Gary Keller: It’s A Do-Or-Die Housing Market For Real Estate Agents

Gary Keller: It’s A Do-Or-Die Housing Market For Real Estate Agents

In these times, double down — on your skills, on your knowledge, on you. Join us Aug. 8-10 at Inman Connect Las Vegas to lean into the shift and learn from the best. Get your ticket now for the best price.

Four months ago, Keller Williams co-founder and Executive Chairman Gary Keller stood before thousands of real estate agents, dumbfounded by a rapidly shifting real estate market influenced by several public health emergencies, rising mortgage rates, slowing home sales, worsening affordability, and increasing recession fears.

“I would say this is the most confusing market I’ve ever seen in my entire 40-plus years in our industry,” Keller said during August’s Mega Camp training conference. “It’s confusing, and it’s only confusing because you have mixed signals. Normally, you would expect all the signals to aim in one direction. And that’s not what’s happening.”

While all of those market factors still linger, Keller had a better read of the tea leaves and a clear message for the 10,000 agents watching his State of the Housing Market address on Sunday  — step up or step aside.

Gary Keller | Credit: KW

“I truly believe that 2023 will be a really tough year. It will be very, very hard,” he said on Sunday beside KW execs Jay Papasan and Jason Abrams and KW Chief Economist Ruben Gonzalez. “And if you don’t work hard to match the hard, your year is gonna suck. It will.”

“I said it yesterday, but I’ve been through this seven times,” he added. “And what I noticed is that there are people that don’t do anything different than they were doing during the good times. You can’t do that. When times get hard, you have to ramp it up.”

Putting home sales in context

While the past 12 months have felt like some of the worst ones on record, Keller said the historical data proves that we’re nowhere near the valleys of previous market cycles that saw annual home sales fall to the 3 to 4 million range — a rate we last saw in the years after the great recession.

“You’re sitting there thinking oh my gosh, we’re going to go back to production levels of 2009 and 2010 based on numbers of transactions,” he said while pulling up a slide of annual home sales data ranging back to 1990. “But here’s the gift of appreciation, and that is the volume of business that is predicted to occur this year would be the third highest in recorded history. Oh, by the way, the other two highest were the previous two years.”

Keller said part of the whiplash real estate agents experienced in 2022 was simply from how fast the market shifted, with home sales dropping from 6.1 million to 5.0 million in one year. “If it felt like you were falling off a cliff, news for you — You did, ” he said. “You fell off the second-highest cliff in recorded history.”

Although sales have slowed, Keller said 2023 is on pace to be the third-greatest year in recorded real estate history with $2.13 trillion in total market volume, even as home price appreciation is expected to decline 1.0 percent.

“You hear the ‘Oh my gosh, the sky’s falling, the sky’s falling,’” he said. “No. Look up. You’re most likely going to be in the neighborhood of the third greatest year in the history of real estate in terms of total volume.”

Before the crowd could get too excited, Keller said it would be harder than ever for real estate agents to get their “unfair share” of the market, thanks to the booming interest in the real estate market that saw the National Association of Realtors experience record membership gains in 2021.

“Okay, this is where you go boo, boo, boo,” he said to a wave of laughs from the audience. “Because you look up and you see in 2022 it was 6.3 transaction sides per agent, which is the lowest recorded. It’s never been lower in the number of sides.”

“Why? Because NAR, coming out of the Great Recession, added 580,000 agents, and average transaction sides dropped from 9.8 to 6.3. The historic average is around 10,” he added. “Notice how over time, it always finds its way back to that. Why does it do that? Well, we wrote about that in the book SHIFT. It’s called the law of equilibrium.”

Abrams said the industry is currently overrun with agents who joined when the market was hot and saw the opportunity to potentially get rich quickly. Right now, many of those agents are still hanging on; however, he expects them to quit over the upcoming year.

“We’re seeing lots of headlines about people who jumped into real estate right? Because of COVID, they were looking for another way to make money and are realizing this is a pretty tough industry, right?” Papasan added. “You have to be committed and they’re going back to their day jobs. So we will see this number go down.”

Keller and Abrams said a shrinking pool of competition leaves plenty of opportunity for experienced agents and dedicated newer agents to be successful in the coming year, especially if they’re willing to fight back against the negative narratives they and consumers hear about the market.

“Just because there are less opportunities, does not mean that anyone’s opportunity is less,” Abrams said.

The issue with fixating on mortgage rates

Keller, Abrams, Papasan and Gonzalez said the greatest challenge real estate agents and consumers will have to overcome is the Federal Reserve’s battle to curb inflation, which has in turn, caused mortgage rates to balloon by more than 400 basis points in the course of a year.

“It’s kind of still gonna be a rocky ride in ’23 because ’23 will be a full year of the federal government trying to get control of inflation [because] they don’t want to send the economy into a full-blown recession,” Keller said. “The odds are, you’re going to have one — my definition is that we had one last year, but no one talked about it because all the numbers were good.”

When it comes to inflation, inflation is most severe in the medical and education industries with costs for hospital services (+227.2 percent), college and tuition fees (+181.2 percent), college textbooks (+163.7 percent), medical care services (+132.2 percent) and childcare (123.1 percent) increasing by the triple digits since 2000. However, housing costs have increased by 87.1 percent, he said.

Although 87 percent is a staggering number, Papasan said it’s not as bad as it seems when you calculate the real change in prices when adjusted for inflation. Keller Williams compared the real change in prices from 1989 to 2022, which saw the monthly mortgage for a median-priced home only rise 2 percent.

“The takeaway here is that housing isn’t changed as much as people thought,” Papasan said. “Your mortgage is only 2 percent higher in real dollars than it was in 1989. That’s crazy, it is crazy.”

Keller admitted the impact of inflation varies across generations and personal life circumstances, with millennials and Gen-Zers battling the cost of college educations and baby boomers feeling the weight of staggering medical bills.

Even with that, Keller said most Americans would be smart to purchase a home and secure steady housing costs.

“When I got in real estate in 1979, interest rates were below 10 percent and interest rates within like a year period when they actually peaked at 18 percent,” he said. “Why would you buy a house at that interest rate? Well, a lot of people did.

“And by the way, those who bought houses at 18 percent 10 years later had the last laugh,” he added. “Why? Two things, real estate appreciated and interest rates came down and they refinanced.”

All four panelists acknowledged homeowners who secured record-low rates in 2020 and 2021 will only place their homes on the market if they absolutely need to since it’ll be impossible to get that kind of rate again. “You’re not gonna see three in your lifetime. My guess is you will never see four in your lifetime,” Keller said. “But that’s OK.”

Even though it won’t match the two-percent rates seen in 2020, Keller said today’s homebuyers who lock in a rate at the seven percent range will likely have an opportunity to refinance at the five to six percent level as the Fed gets a hold on inflation.

But even if they don’t, he said real estate is an investment that always pays off in the long run, especially since today’s homeowners and homebuyers are in a more secure financial position than one or two decades ago.

“[Purchasing real estate] has been proven to be the best long-term plan to build wealth because the second that prices go up on the houses, people that can’t afford to buy and they go rent and every greedy landlord in the room today will raise the rent on those suckers. Yes or no? Yes, yes, you will. Of course, you will. So rent never does it.”

“Even if owning a home takes up 60 percent of your income, do it,” he said while noting the average homeowner puts around 36 percent of their pre-tax income toward a monthly mortgage. “Why? Because you’re trying to lock in your cost of living.”

Debt ceilings, Ukraine and climate change

Although the first half of 2023 will be rough, Keller said the back half of the year will most likely yield calmer seas if domestic and global politics don’t get in the way.

“Well, if we look ahead this year and say, ‘Okay, what could derail us? What would be the things that we just need to keep an eye on?’ Number one would be any further escalation in Ukraine,” he said. “That could destabilize so much from oil and gas to wheat, you name it. I mean, there there are products coming out of that region that make a difference.”

The second-biggest threat comes from the Fed as they continue to battle inflation. So far they’ve been relatively successful, Keller said, but there is a chance that inflation takes a turn for the worse and throws us into a recession.

“In fact, if something weird happens and instead of getting it under control this year, it goes up, all bets are off,” he said matter of factly. “All bets are off.”

Keller said the partisan battle over how to handle the federal debt ceiling will have a major impact on the third and fourth quarters of 2023, while the increasing risks associated with climate change will guide the market for the foreseeable future.

“Look, I don’t care who caused it, but there is climate change,” he said. “Just come to my house and look at all the trees that are freezing. I mean, it’s unreal. Climate change is very real. By the way, it’s going to destabilize cities and it can destabilize a government overnight.”

Abrams and Papasan nodded in agreement, with Abrams telling agents to dial into environmental issues as they’ll become a greater factor in homeowners’ and homebuyers’ real estate decisions. “You can also have an immediate disaster, which changes the economic future in a moment,” he said. “Those [disasters] are happening more and more often. So we have to be cognizant of it.”

Thriving in a consolidating market

Beyond political and macroeconomic issues, Keller said real estate agents and companies must pay attention to a converging industry where everyone is battling to disrupt the traditional homebuying and homeselling experience and create the ultimate all-in-one tool that consumers will come to count on in the future.

“People forget that we tend to overestimate the short term, and then we completely underestimate the long term,” he said. “What you see happening again is a convergence. When you hear firms like Zillow talk about The Great App or The Super App…”

“What they’re talking about is pulling all of this into one experience,” he said. “It’s going to keep and it’s going to keep this is going to keep happening.”

However, Keller said the current market shift is showing who’s actually got the proof in the pudding, with the downfall of iBuyers being the prime cautionary tale of rushing to invest in the next shiny, new thing.

“You would have thought that the iBuyers two years ago, were the smartest, most brilliant people in the entire industry, right? They got the front stage. I remember Eric Wu, who is no longer running [Opendoor],” he said. (Note: Wu has taken on another executive role with Opendoor.) “I remember Eric came to Austin and we were a group of us met with him. At one point I asked him, ‘What are you going to do when we go into a downturn?’”

“He gave a really sophisticated algorithmic answer of how they knew how to figure that out,” he added. “He didn’t know what he was talking about. In the short term, people that sound good can make you look stupid. But truths are truths. They don’t change over time.”

Keller said real estate companies who own their tech are in the best position to lead the industry and support agents in their journey to serve agents and create solid, long-lasting businesses.

“You’re the number one source that people use,” he said. “So even if they’ve looked at real estate online or they start their journey and all these different ways, who do they end up going to? The real estate agent.”

Email Marian McPherson

Housing market correction just took a new turn

Housing market correction just took a new turn

“Depending on sector dynamics and backlog stages in each and every neighborhood, we are receiving more intense with our pricing ahead of the spring offering year, in order to deliver new orders,” KB Dwelling told investors back again in January after posting its disappointing fourth-quarter final result.

Rapidly-ahead to February, and it appears to be like like we’re previously looking at the housing industry correction—which noticed new- and existing-home revenue agreement at virtually document speed in the next 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of previous year—move into a new phase. What’s heading on? Aggressive builder rate cuts coupled with incentives, like mortgage rate purchase-downs, are assisting builders get profits transferring up once more.

This uptick in new-home product sales could mean the household selling price correction on the new-building side is losing steam. Or at the very least shedding steam for now.

“Builders have taken their medicine for the most section proper now on pricing. And we feel nationally, dwelling prices—on the new-household aspect, web of incentives—are down about 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from peak,” Rick Palacios Jr., head of investigation at John Burns Real Estate Consulting, reported in a video clip posted on Saturday. “There’s almost certainly not a ton of runway there left.”

Let us be obvious: Palacios is speaking about the residence price tag correction on the new-house facet. On the present or “resale” facet, he thinks the household cost correction has a way yet to go.

“We however consider that there’s more [home] value correction to appear on the resale facet, while. And the resale marketplace is constantly stickier to the draw back when it comes to [home] selling prices,” Palacios suggests.

Unlike homebuilders, who have to have to reduce price ranges in get to move unsold stock, existing property owners are normally additional resistant to these kinds of cuts. That resistance is why current-household rates generally bottom out past in a housing market place downturn.

Let us get a closer glimpse at the ongoing correction on the present side. Here’s the data.

For 124 consecutive months, spanning the bottom of the previous housing bust in February 2012 by means of the best of the Pandemic Housing Increase in June 2022, the price of U.S. present solitary-family houses, as measured by the seasonally altered Situation-Shiller Nationwide Residence Rate Index, posted constructive month-more than-month house selling price development.

That streak is about now.

By the latest examining in November 2022, present one-family residence charges are down 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from that June 2022 all-time superior. On the 1 hand, that drop marks the 2nd-biggest house value correction of the post–World War II era. On the other hand, it is really a mild correction as opposed to the 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} peak-to-trough home value drop among 2007 and 2012.

It will be yet another six weeks until the Scenario-Shiller reading for January is released. Nonetheless, preliminary knowledge displays that the residence cost correction on the present-home aspect may possibly also be shedding some steam in 2023.

An examination of Zillow Residence Price Index data by Fortune (see chart above), finds that 79{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the nation’s 200 premier housing markets saw a month-about-thirty day period home price drop in September. That determine has since been dropping, gradually but surely.

In Oct, 76{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of those main markets saw a residence price tag drop. In November and December, it was down to 64{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. Nonetheless, in January, just 47{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the nation’s 200 largest housing markets registered a thirty day period-around-thirty day period home rate decline.

Last year’s mortgage loan fee shock, which saw the common 30-yr fixed home finance loan charge spike from 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to around 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, has in fact established off a dwelling price tag correction. That explained, the correction carries on to be bifurcated: Some markets are observing a sharp correction, while other markets have not seen considerably of something.

“If you happen to be any where in Texas or west of Texas, you might be in all probability down much more. If you’re any place east of Texas, you are almost certainly not down that substantially, if at all,” Palacios claims.

That bifurcated housing correction is why KB Property, which has a large concentration of organization in rapidly-correcting West Coast and Mountain West markets, noticed a cancellation level that exceeded those people of its friends, which do extra enterprise in the Midwest and Northeast.

When it arrives to the house cost correction, there does continue to be 1 large wild card: property finance loan rates.

“Before cost cuts that now put together with significant fee invest in-downs are supporting on the new-property price tag balance facet [in some markets]. If [mortgage] prices adhere all over 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or split earlier mentioned, deeper [new and existing] price cuts may possibly be essential,” Palacios explained to Fortune.

Want to remain updated on the housing market correction? Comply with me on Twitter at @NewsLambert.

Discover how to navigate and reinforce trust in your enterprise with The Belief Variable, a weekly e-newsletter inspecting what leaders need to be successful. Sign up below.

Home Depot sees home-improvement market declining if consumer demand keeps shifting to services from goods

Home Depot sees home-improvement market declining if consumer demand keeps shifting to services from goods

House Depot Inc. stated Tuesday the home-improvement sector could weaken this year, if client expending retains shifting toward companies from goods, and if inflation carries on to influence demand.

The house-enhancement big
High definition,
-7.06{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
expects fiscal 2023 internet income and exact-retail outlet gross sales to be about flat with previous yr, however, due to the fact it will take market share from its competition.

Sales could be harm additional if lumber price ranges, which have presently fallen by extra than 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a 12 months back, go on to decrease.

The ordinary analyst estimate compiled by FactSet for revenue at the time Home Depot reported effects was $158 billion, which implied .4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} progress, while the FactSet consensus for identical-shop product sales was for a increase of .2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Main Money Officer Richard McPhail said on the submit-earnings conference connect with with analysts that for about the very first five quarters postpandemic, the corporation observed important growth in the price of the ordinary ticket and selection of transactions, for the reason that property owners took on extra do-it-oneself tasks as they invested far more time at home.

Since about the fiscal second quarter of 2021, McPhail stated product sales ongoing to increase thanks to ticket development, but the range of transactions “steadily normalized” towards prepandemic levels, “as the broader customer economy shifted” from merchandise back to products and services.

“We think that if this change proceeds at its existing pace, the residence-improvement market would be down lower-solitary-digits [percentages],” McPhail explained, according to a transcript offered by AlphaSense.

In the meantime, earnings per share for the 12 months are forecast to decrease in the “mid-one-digit” percentage assortment, as a increased anticipated tax rate and an expense in staff payment weighs on functioning margins.

That was a shock for Wall Road analysts, as the FactSet EPS consensus for the latest fiscal calendar year was $16.70, which was a penny extra than EPS for previous calendar year.

Dwelling Depot’s inventory slid 5.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in morning investing, sufficient to make it the worst performer amid the Dow Jones Industrial Average’s
DJIA,
-2.06{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
elements. The stock’s $17.26 rate decrease was reducing about 114 details off the Dow’s rate, while the Dow fell 487 details, or 1.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

The organization also documented just before the open fiscal fourth-quarter EPS that topped expectations, net product sales that arrived up a bit shy and same-store profits that incredibly declined.

Chief Govt Officer Ted Decker mentioned on the article-earnings phone with analysts that by most of fiscal 2022, the company’s “resilient” buyers have been much less selling price delicate that expected in the reality of persistent inflation.

“In the 3rd quarter, we famous some deceleration in selected products and categories which was far more pronounced in the fourth quarter,” Decker claimed, in accordance to an AlphaSense transcript. “This, along with the damaging impact from lumber deflation, led to fourth-quarter comps [same-store sales] that have been somewhat softer than predicted.”

Home Depot’s inventory has slumped 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the past three months and declined 13.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} about the earlier 12 months, even though the Dow has eased 1.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} the past three months and slipped 2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} the previous calendar year.

Homewares Market to register a CAGR 5.20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} across | CAGR of 5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021 to 2028 | Arc International SA, SEB , Ikea

Homewares Market to register a CAGR 5.20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} across | CAGR of 5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021 to 2028 | Arc International SA, SEB , Ikea

homeware-amr

homeware-amr

Homewares market size was valued at $1,395.73 billion in 2020, and is estimated to reach $2,028.68 billion by 2028

PORTLAND, 5933 NE WIN SIVERS DRIVE, #205, UNITED STATE, February 17, 2023 /EINPresswire.com/ — Growing demand for advanced, smart and elegant home appliances and furniture are expected to escalate the demand for homewares products. Increase in spending for home decoration and improvement practices owing to growing disposable income specially in emerging economies including China, India and Brazil, are anticipated to contribute toward the homewares market growth during the forecast period. According to a new report published by Allied Market Research, titled, “Homewares Market by Type and Distribution Channel: Global Opportunity Analysis and Industry Forecast, 2021–2028,”The global homewares market size is expected to reach $2,028.68 billion by 2028 at a CAGR of 5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021 to 2028.

Asia-Pacific is projected to grow at the highest CAGR, owing to constantly expanding infrastructure and real estate sector

Request For Sample : – https://www.alliedmarketresearch.com/request-sample/11005

Homewares market is made up of various markets such as furniture, home appliances, home décor, lighting and bathroom accessories. Homewares market is majorly driven by surge in number of residential homes, increase in disposable income, and rise in adoption of smart and advanced home appliances. Changing lifestyles owing to rapid urbanization and increasing purchasing power of the developing countries including China, Taiwan, India, and Brazil, is fueling the demand for various homewares products including microwave oven, dishwashers, sofa, bed and refrigerator. In addition, manufacturers are introducing localized products based on the need of the consumers from a particular region or country. For instance, in March 2019, Robert Bosch GmbH announced the launch of India-specific dishwashers that will incorporate the Kadhai feature, which is an essential utensil for Indian consumers.

IMPACT OF COVID-19 pandemic :-
Due to the COVID-19 pandemic, supply chain has been adversely affected, thereby resulting in the whole consumer goods industry incurring losses. Government is frequently practicing total lockdown in order to limit the spread of corona virus, in which retail stores including specialty shops are strictly suggested to remain closed. Manufacturing units are also temporarily closed, which is expected to decrease the production of furniture, home appliances and lighting products, which in turn adversely impacts the homewares market.

According to the homewares market analysis, the homewares market segmented on the basis of type, distribution channel, and region.

On the basis of type, the market is categorized into home decoration, furniture, kitchenware, home appliances, soft furnishings, lighting, bathroom accessories and others.
According to distribution channel, it is divided into homewares stores, franchised stores, departmental stores, online stores and specialty stores.
Region wise, it is analyzed across North America (the U.S., Canada, and Mexico), Europe (Germany, France, UK, Italy, Spain, Russia, Rest of Europe), Asia-Pacific (China, Japan, India, Australia, South Korea and Rest of Asia-Pacific), and LAMEA (Latin America, The Middle East and Africa).

Get detailed COVID-19 impact analysis on the Homewares Market :- https://www.alliedmarketresearch.com/request-for-customization/11005?reqfor=covid

Market trends, Segmentation, Growth Prospects, Demand ,Opportunities And Forecast 2021-2026 :-

According to the homewares market opportunities, on the basis of type, furniture segment was valued at $370.17 billion in 2020, and is projected to reach $500.47 billion by 2028, registering a CAGR of 4.30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021 to 2028. Owing to space constraints faced in urban areas, multifunctional furniture is gaining popularity among urban consumers, as this furniture aids in space saving, which fuels the growth of the furniture segment. In addition, rise in awareness regarding environment safety among consumers has led to surge in demand for eco-friendly furniture. Furthermore, with increase in disposable income and willingness of customers to invest in furniture significantly contribute toward the growth of the market. Moreover, rapid urbanization coupled with increase in concept of nuclear family structure drives the growth of the furniture market. In addition, development of the real estate industry coupled with surge in penetration of e-commerce platform is expected to provide significant opportunities to the furniture market.

Reginal Analysis 2021-2026 :-

Region wise, Europe was valued at $360.94 billion in 2020, and is expected to reach $490.13 billion by 2028, registering a CAGR of 4.40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021 to 2028. In Europe, a considerable growth rate is anticipated for new advanced & smart home appliances and elegant & multifunctional furniture. In addition, there has been a huge increase in demand from the major countries in Europe such as France, Spain, the UK and Russia. Increasing preference for hustle free lifestyle, people are increasing demanding air conditioners, vacuum cleaner and dishwashers, are supporting the growth of home appliances and furniture market in the region. Thus contributing to increase in the sales of homewares products in Europe.

The key players profiled in this report include
Arc International SA,
Conair Corporation,
Ikea Systems,
International Cookware SAS,
Lock & Lock Co., Ltd.,
Pacific Market International,
SEB SA,
Tempur Sealy International, Inc.,
The Oneida Group and Tupperware.

Buy Now :- https://www.alliedmarketresearch.com/checkout-final/f3e218c48754a6b9374db2eed7e6c700

Key findings of the study

In 2020, the Homewares market was valued at $1,395.73 billion, and is estimated to reach $2,028.68 billion by 2028, growing at a CAGR of 5.20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} during the forecast period.
In 2020, depending on type, the home decor segment was valued at $351.58 billion, accounting for 25.19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the global homewares market share.
In 2020, depending on distribution channel, the franchised stores segment was valued at $274.29 billion, accounting for 19.65{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the global Homewares market share.
In 2020, the U.S. was the most prominent market in North America, and is projected to reach $ 428.5 billion by 2028, growing at a CAGR of 4.80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} during the forecast period.

Similar Report :-
o Carpet Spot Remover Market
https://www.alliedmarketresearch.com/carpet-spot-remover-market-A09413

o Carpet Cleaning Products
https://www.alliedmarketresearch.com/carpet-cleaning-products-market-A09398

David Correa
Allied Analytics LLP
+ +1 503-894-6022
email us here
Visit us on social media:
Facebook
Twitter
LinkedIn

The Real Estate Market Is In The Freezer, But Billionaire Grant Cardone Says Investors Will ‘Save The Day’

The Real Estate Market Is In The Freezer, But Billionaire Grant Cardone Says Investors Will ‘Save The Day’

Economists have been contacting for a housing crash for quite a few months. Some even predicted that residence price ranges would drop by as substantially as 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023. Whilst these statements are understandable considering that mounting mortgage premiums have priced a lot of would-be potential buyers out of the market place, it appears that a distinctive state of affairs is beginning to perform out.

Ideal-selling writer and serious estate fund supervisor Grant Cardone agrees that the housing current market is in problems, but details out that buyers will make adequate demand from customers to retain the industry from crashing.

“Banks never have confidence in borrowers, and all those they do trust will have to shell out. This will shift house owners to the sidelines and bit by bit decrease property selling prices,” Cardone claimed. “Investors will stage in to pick up solitary-family members properties at lower costs with considerably less competitors. That getting mentioned, there will be no housing crash! Traders, like myself, will help you save the working day and stage in to acquire the households, place renters in position and appreciate them for the hard cash circulation, not the kitchens and cabinets.”

Cardone’s actual estate expense organization Cardone Money has elevated about $1 billion from accredited and nonaccredited traders throughout 22 resources due to the fact its inception in 2016. The company’s actual estate portfolio is valued at roughly $4 billion and is composed of virtually 12,000 apartment models throughout 36 attributes and in excess of 500,000 sq. toes of professional place of work house.

Cardone isn’t the only significant trader who sees an possibility in the recent housing marketplace. J.P. Morgan declared in November that it strategies to get $1 billion well worth of single-household rentals. Other institutional buyers like BlackRock Inc. and Norges Bank improved their positions in solitary-relatives housing real estate financial commitment trusts (REITs) Invitation Houses and American Residences 4 Hire all through the final quarter.

Amazon Founder Jeff Bezos even staked a claim in the one-family rental industry by investing in the seed and collection A rounds of the investment system Arrived Homes, which makes it possible for retail investors to obtain shares of unique rental houses with as small as $100. The platform has presently funded over 200 houses worth additional than $75 million.

There is also a expanding demand from customers from international traders for U.S. true estate. Chad Gallagher, co-founder of the residence administration organization House 365, informed Benzinga very last thirty day period that his company has viewed a significant uptick in overseas buyers from economically risky nations looking for residence management products and services for their purchases of multifamily houses.

“U.S. authentic estate truly has a greater cap fee than most countries. For instance, the typical one-relatives dwelling in Israel expenses five times what a identical property below would price tag,” he stated. “So investing in a rental home in nations around the world like that and building them income-move optimistic doesn’t do the job for them.”

Examine future:

You should not pass up serious-time alerts on your shares – sign up for Benzinga Professional for free of charge! Check out the device that will assistance you invest smarter, speedier, and far better.

This report The Real Estate Current market Is In The Freezer, But Billionaire Grant Cardone Says Investors Will ‘Save The Day’ originally appeared on Benzinga.com

.

© 2023 Benzinga.com. Benzinga does not deliver expense assistance. All rights reserved.

Investors are pulling back from the housing market, Redfin says

Investors are pulling back from the housing market, Redfin says

Traders are slinking away from the serious-estate current market as property-selling price growth slows and the possibility of value drops seems on the horizon.

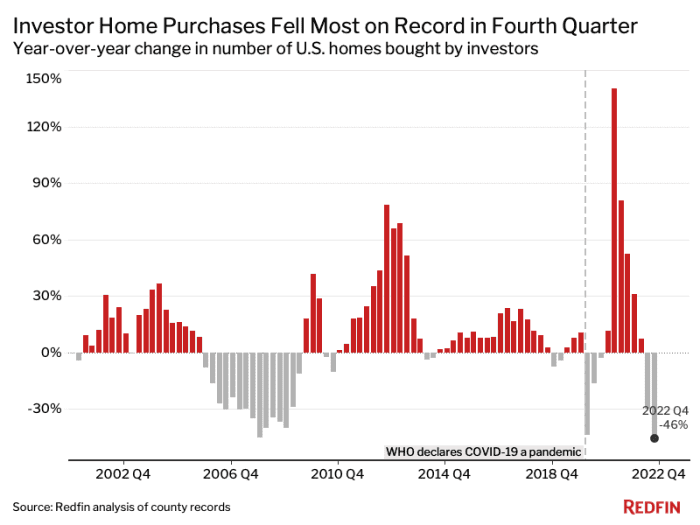
The last time trader purchases dropped so considerably was in 2008, throughout the subprime house loan crisis, when they fell 45.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Redfin explained.

In the fourth quarter of 2021, buyers acquired 89,396 houses in metropolitan regions tracked by Redfin. In the fourth quarter of 2022, investors only acquired 48,445 properties in those regions.

The overall drop in mortgage charges and a feasible bottoming-out of home prices may lure investors back again into the industry, but “it’s unlikely that investors will return with the exact same vigor they had in 2021,” said Sheharyar Bokhari, senior economist at Redfin.

“That’s fantastic information for personal consumers, who are nevertheless grappling with high housing fees but no more time shedding bidding war soon after bidding war to traders,” he extra.

Throughout the pandemic, many property purchasers were being outbid and overshadowed by traders who were being equipped to scoop up houses with all-income features. The issue above the plight of initially-time household customers prompted Democratic lawmakers to convene a panel to seem into achievable predatory actions by institutional investors.

In its study, Redfin appeared at residence income amongst January 2000 and December 2022.

Residence purchases by investors fell in 2022. The last time such purchases dropped as drastically was in 2008.


Redfin

For the study, an investor was described as a purchaser whose identify incorporated at the very least a person of these search phrases: LLC, Inc., Have faith in or Houses. Buyers were being also viewed as to be buyers if their possession code on a house deed integrated key terms like “association,” “corporate trustee” or “company.”

Though buyers have pulled back on purchasing homes, it does not imply their market share has dropped, due to the fact person household prospective buyers have also slowed their action. Home loan costs are nevertheless elevated and house charges have not however dropped drastically, which means that lots of men and women are acquiring it challenging to find the money for to buy a dwelling ideal now.

According to Redfin, investors’ share of the industry in all the metropolitan places tracked by Redfin was 17.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fourth quarter.

In other terms, traders acquired that proportion of all households bought in the 40 most populous U.S. metro locations, as tracked by Redfin. Past yr, buyers bought 19.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all homes in all those locations.

The cost of a usual property ordered by an investor was all around $425,926.

Investors flee pandemic boomtowns

In pandemic boomtowns like Las Vegas, Nev., and Phoenix, Ariz., buyers are operating for the hills, the info clearly show.

In accordance to Redfin, household purchases by buyers fell the most in Las Vegas, dropping 67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fourth quarter about the exact period of time of the past calendar year.

Las Vegas is also the metropolis that saw residence values fall the most amongst the prime 50 marketplaces tracked by Zillow Group
Z,
+.86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9},
another true-estate tech enterprise. Household values there fell 1.23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January as opposed with December.

Traders also hit the brakes in Phoenix, in which house purchases by investors dropped 66.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nassau County, N.Y., where they fell 63{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Atlanta, where they fell 62.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and Charlotte, N.C., exactly where they dropped 61.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

“A large amount of traders are on hold since they even now see residence costs declining,” claimed Elena Fleck, a Redfin agent based mostly in Palm Beach, Fla.

The only metro place amid these analyzed by Redfin that observed an boost in trader purchases was Baltimore, Md.

Buyers still experienced the highest sector share in Miami Jacksonville, Fla. Atlanta Anaheim, Calif. and Charlotte, Redfin noted.

Home loan costs have crept again up as the current market weighs extra fascination-rate hikes from the U.S. Federal Reserve, which proceeds its struggle against inflation. In consequence, potential buyers have also pulled back again.