Top Picks For 2023 – Part 2: Investment Property Stocks

Top Picks For 2023 – Part 2: Investment Property Stocks

Townhomes

AnthonyRosenberg/iStock via Getty Images
Introduction

Part 1 focused on “Home Stocks,” meaning those that I would be happy to buy now and hold indefinitely, like a home. They were Brookfield Corporation (BN), Brookfield Asset Management (BAM), DreamOTCPK:DRUNFOTCPK:TOITFOTCQX:SECUF

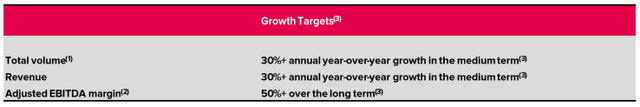
Nuvei Growth Targets

Nuvei’s growth outlook (Nuvei’s Q3 Earnings Report)
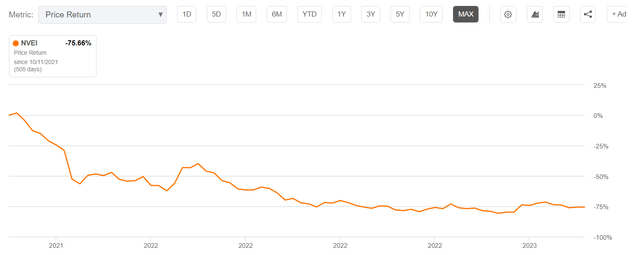
Return

Nuvei’s return since its IPS – Not pretty! (Seeking Alpha)
Margins

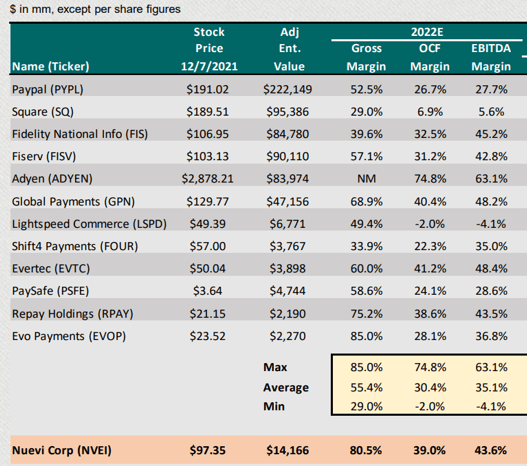
Note to Canadian investors, Lightspeed gets more press than Nuvei, but isn’t even profitable. (Short Seller’s Report)
Table

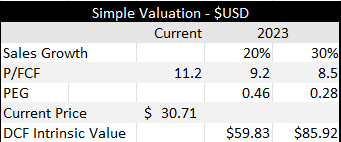
Two different growth scenarios and their impact on the valuation of Nuvei. Both suggest Nuvei is substantially undervalued (Author’s Calculations)
Moat

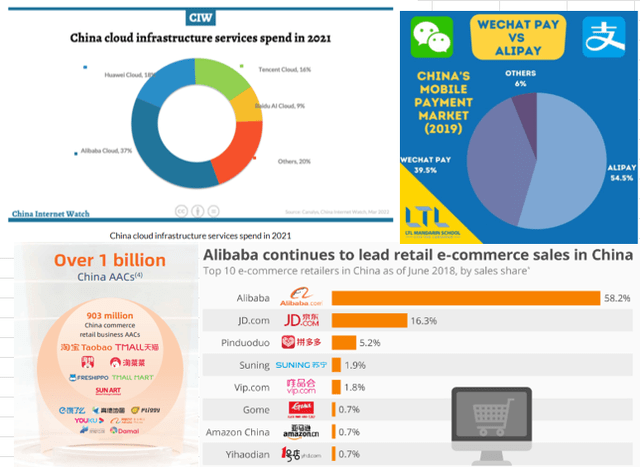
Visuals to aid readers in understanding Alibaba’s moat (China Internet Watch, Mandarin School, Alibaba 2022 Annual report)
Graphical user interface, chart, application, line chart Description automatically generated

Alibaba’s return since its IPO (Seeking Alpha)
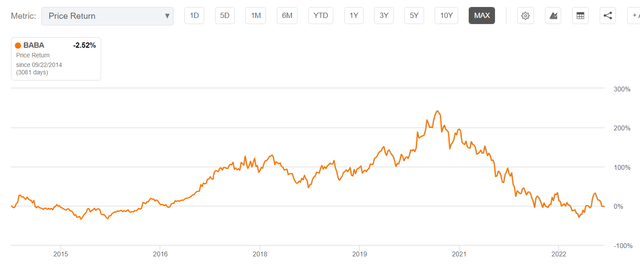
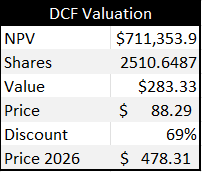
Table Description automatically generated

Valuation of Alibaba assuming its free cash flow margins and multiples paid for that FCF returns to historic averages (Author’s Calculation)
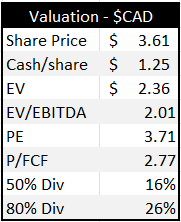
Table

Remarkably undervalued. Priced like it’s going bankrupt again (Author’s Calculations)
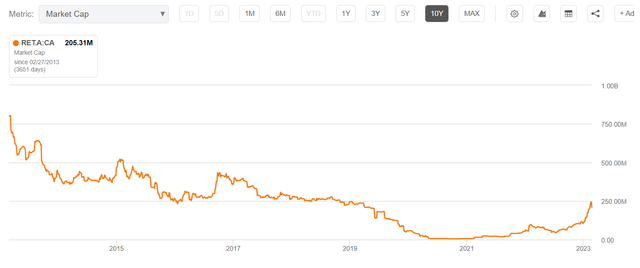
Table

Long-term holder are likely non-existent (Seeking Alpha)
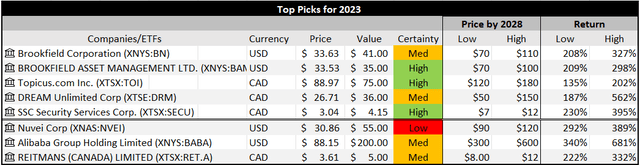
Table

Summary of top picks in the last two articles, including fair values and return potential (Author’s Calculation)
3 Home Improvement Stocks to Spruce up Your Portfolio Now

3 Home Improvement Stocks to Spruce up Your Portfolio Now

Demand for home improvement products and services increased during the COVID-19 pandemic, with people spending more time in their homes. With people becoming homebound and continuing their hybrid lifestyles, demand remained stable even after the restrictions were eased.

Nearly 76{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of American homeowners did a home improvement project in 2020. Last year, Americans spent approximately $538 billion at home improvement stores. This trend is projected to continue in the upcoming years, driven by rapid urbanization, a growing transition toward energy-efficient living spaces, and the continuation of hybrid working models across various organizations.

Furthermore, easing inflation data for October is expected to bode well for the industry. According to a report by Allied Market Research, the home improvement services market is expected to reach $585.30 billion by 2030, growing at a CAGR of 6.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Given the backdrop, adding fundamentally strong home improvement stocks The Sherwin-Williams Company (SHW), La-Z-Boy Incorporated (LZB), and Bassett Furniture Industries, Incorporated (BSET) to your portfolio could be wise.

The Sherwin-Williams Company (SHW) 

SHW develops, distributes, and sells paints, coatings, and related products to professional, industrial, commercial, and retail customers. It works through three segments: The Americas Bunch; Consumer Brands Group; and Performance Coatings Group.

On November 8, 2022, SHW announced a deal to acquire Specialized Industrial Coatings Holding (SIC Holding), a venture of Peter Möhrle Holding and GP Capital UG that includes Oskar Nolte GmbH and Klumpp Coatings GmbH. Through this acquisition, SHW will have the chance to grow profitably in the international industrial wood market.

Additionally, the company will gain from the excellent technical and commercial teams at Oskar Nolte and Klumpp Coatings and their connections to local and international clients, all of which SHW can further exploit across Europe and beyond.

On November 11, SHW announced the acquisition of Industria Chimica Adriatica S.p.A. (ICA), an Italian designer, manufacturer, and distributor of industrial wood coatings used for kitchen cabinets, furniture and décor, building products, flooring, and other specialty applications.

In addition to having cutting-edge waterborne and solvent liquid coatings technology, ICA has several product specifications and approval positions, strategically positioned manufacturing, and solid technical ties with local and international clients. With this cooperation, SHW might quicken lucrative expansion in the area and outside.

SHW’s net sales increased 17.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $6.05 billion in the fiscal 2022 third quarter ended September 30, 2022. Its gross profit grew 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $2.59 billion. Its adjusted EBITDA came in at $1.12 billion, up 34.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year.

Furthermore, the company’s net income and net income per share grew 36.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 39.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $685.10 million and $2.62, respectively.

The company’s Board of Directors declared a regular quarterly dividend of $0.60 per common share to shareholders of record on November 18, 2022, payable on December 2, 2022. The company has increased its dividend for 44 consecutive years. Its dividend payouts have grown at a 16.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} CAGR over the past five years, and the current dividend yields 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Analysts expect SHW’s revenue to increase 11.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $22.16 billion in fiscal 2022. The company’s EPS for the current fiscal year is expected to increase 6.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $8.71. Over the past month, the stock has gained 15.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close the last trading session at $243.45.

SHW’s strong fundamentals are reflected in its POWR Ratings. The stock has an overall rating of B, which equates to a Buy in our proprietary rating system. The POWR Ratings are calculated by considering 118 different factors, each weighted to an optimal degree.

The stock has a B grade for Growth and Quality. Within the Home Improvement & Goods industry, it is ranked #11 among 60 stocks.

Beyond what we stated above, we also have SHW’s ratings for Value, Sentiment, Stability, and Momentum. Get all SHW ratings here.

La-Z-Boy Incorporated (LZB)       

LZB produces, markets, imports, exports, distributes, and retails accessories and case goods furniture products in the United States, Canada, and internationally. The company operates through Wholesale; Retail; Corporate; and Other segments.

On August 23, Melinda D. Whittington, LZB’s President and Chief Executive Officer said, “We delivered excellent results for the quarter amidst challenging trends for the global economy and the furniture industry. We are focused on navigating the near-term volatile environment with agility while strengthening our business for the long term with our Century Vision strategy.”

“This quarter, we further built our iconic La-Z-Boy brand with the acquisition of five La-Z-Boy Furniture Galleries® stores in the Denver market and our Joybird brand with the opening of two new Joybird retail stores,” he added.

LZB’s sales increased 15.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $604.09 million in the fiscal 2023 first quarter ended July 30, 2022. Its non-GAAP operating income increased 55.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $53.82 million. Non-GAAP net income attributable to LZB grew 58.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the prior-year period to $39.42 million, while non-GAAP EPS came in at $0.91, up 65.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year.

LZB pays a $0.66 per share dividend annually, which translates to a 2.57{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield on the current price. Its dividend payouts have grown at a CAGR of 8.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the past five years.

Analysts expect LZB’s revenue to increase 0.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $2.37 billion in the fiscal year ending April 2023. The company’s EPS for the ongoing year is expected to increase 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $3.30. It has surpassed the consensus EPS estimates in three of the trailing four quarters. 

The stock has gained 12.32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the past month and 10.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the past six months to close the last trading session at $26.20.

LZB’s POWR Ratings reflect its strong outlook. The stock has an overall rating of B, which equates to a Buy in our proprietary rating system. 

The stock has a B grade for Value and Quality. Within the Home Improvement & Goods industry, it is ranked #6 among 60 stocks.

Beyond what we stated above, we also have LZB’s ratings for Growth, Stability, Sentiment, and Momentum. Get all LZB ratings here.

Bassett Furniture Industries, Incorporated (BSET) 

BSET develops, manufactures, sources, sells, and distributes home furnishings internationally. It operates in three segments: Wholesale; Retail company-owned stores; and Logistical services. The company operates a network of more than 63 company-owned and 34 licensee-owned stores.

On September 6, the company acquired the capital stock of Noa Home Inc., a mid-priced e-commerce furniture retailer based in Montreal, Canada. Noa operates in Canada, Australia, Singapore, and the United Kingdom and has had net revenues of C$2 million ($1.49 million) for its most recent fiscal year.

The acquisition might give BSET a stronger online presence and allow the company to attract more digitally native customers.

For the third quarter of fiscal 2022 ended August 27, 2022, BSET’s net sales of furniture and accessories increased 12.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $118.01 million, and its gross profit grew 15.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $60.77 million. The company’s income from operations was $10.67 million, up 114.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year.

In addition, the company’s net income and EPS increased 152.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 164.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $7.63 million and $0.82, respectively.

BSET’s annual dividend of $0.64 per share yields 3.34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the current price. Its four-year dividend yield is 5.35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The company’s dividend payments have grown at a 6.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} CAGR over the past three years and a 7.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} CAGR over the past five years.

Analysts expect BSET’s EPS for the current fiscal year (ending November 2022) to increase 23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the previous year to $2.27. Moreover, the company has surpassed the consensus EPS in three of the trailing four quarters.

Over the past month, the stock has gained 14.45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close the last trading session at $19.13.

BSET’s POWR Ratings reflect its promising outlook. The stock has an overall rating of A, which equates to a Strong Buy in our proprietary rating system. 

The stock has an A grade for Quality and Sentiment and a B for Value. Within the Home Improvement & Goods industry, it is ranked #3 among 60 stocks.

Click here to see additional ratings of BSET for Growth, Momentum, and Stability.


SHW shares were trading at $249.33 per share on Wednesday afternoon, up $5.88 (+2.42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Year-to-date, SHW has declined -28.52{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, versus a -14.34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise in the benchmark S&P 500 index during the same period.

About the Author: Mangeet Kaur Bouns

Mangeet’s keen interest in the stock market led her to become an investment researcher and financial journalist. Using her fundamental approach to analyzing stocks, Mangeet’s looks to help retail investors understand the underlying factors before making investment decisions. More…

More Resources for the Stocks in this Article

China property stocks surged amid warnings of weak reality, high expectations

China property stocks surged amid warnings of weak reality, high expectations

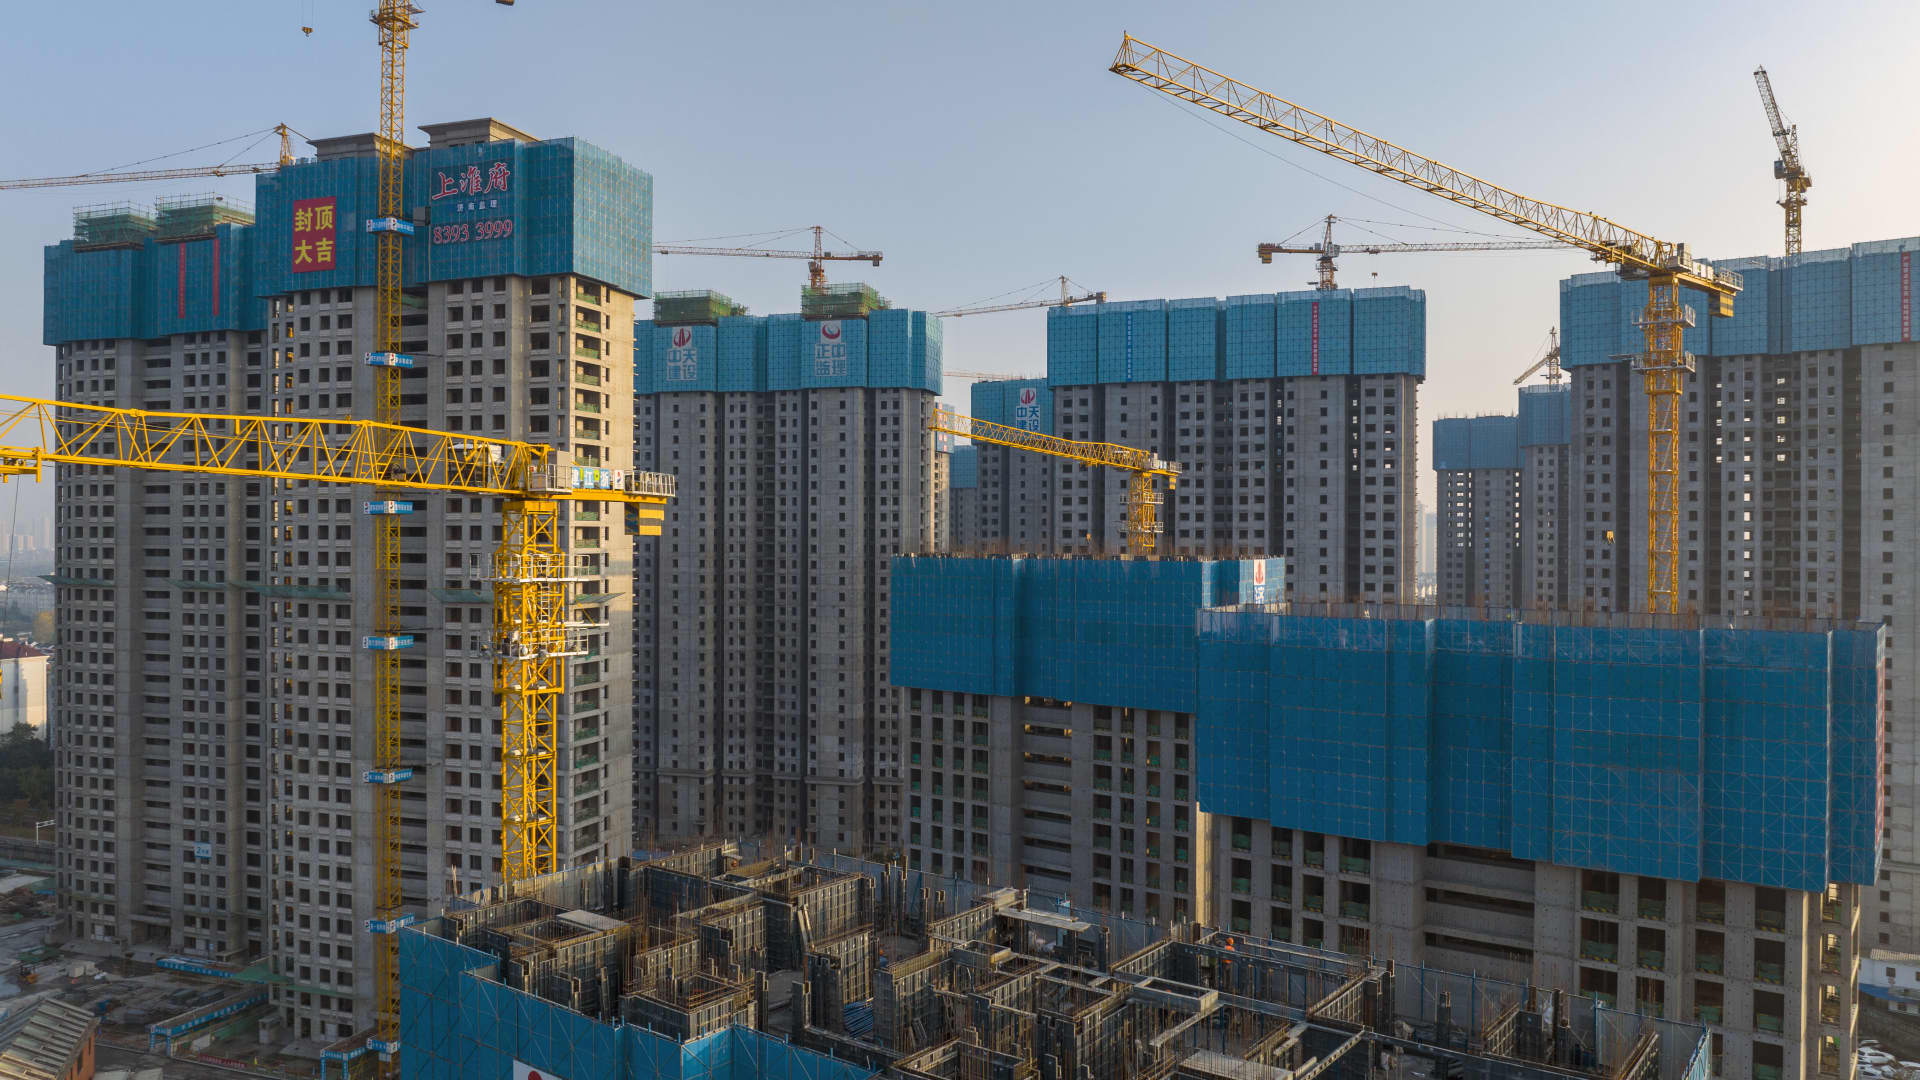
China’s housing charges fell in Oct owing mainly to slipping costs in a lot less developed, so-named Tier-3 cities, in accordance to Goldman Sachs examination of official info.

Potential Publishing | Foreseeable future Publishing | Getty Visuals

BEIJING — China’s real estate sector is just not however poised for a brief restoration, even with a rally this month in stocks of significant home developers.

That is simply because current assist by Beijing you should not specifically take care of the main challenge of falling household income and price ranges, analysts say.

associated investing news

Stocks could rally as much as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, predicts Wharton's Jeremy Siegel

CNBC Pro
Stocks could rally as substantially as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, predicts Wharton’s Jeremy Siegel

Last week, residence developer shares surged just after information the central lender and banking regulator issued actions that encouraged banking companies to assistance the actual estate sector. It arrives together with other support measures earlier this month.

Shares of Country Backyard, the most significant Chinese developer by profits, have far more than doubled in November, and all those of Longfor have surged by about 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The shares have by now offered back again some of this month’s gains.

Meanwhile, iron ore futures surged by about 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this thirty day period — Morgan Stanley analysts say about 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of China’s steel consumption is utilized in residence construction.

The predicament is one of “potent anticipations, but weak reality,” and current market rates have deviated from the fundamentals, Sheng Mingxing, ferrous metals analyst at Nanhua Analysis Institute, explained in Chinese translated by CNBC.

Sheng stated it really is significant to look at whether or not apartments can be done and delivered throughout the peak building period of March and April.

This seriously is a non permanent reduction in phrases of the developers possessing to fulfill considerably less credit card debt repayment wants in the close to long run…

The new steps, greatly claimed in China but not officially introduced, stipulate mortgage extensions, connect with for treating builders the exact same no matter whether they are point out-owned or not and aid bond issuance. Neither regulator responded to CNBC’s ask for for comment.

“This actually is a momentary relief in terms of the developers having to fulfill less financial debt compensation wants in the around upcoming — a temporary liquidity relief relatively than a fundamental turnaround,” Hong Kong-based analyst Samuel Hui, director, Asia-Pacific corporates, Fitch Rankings, said Wednesday.

“The essential is that we however need the elementary fundamental property profits market to improve,” he said, noting homebuyer assurance depends on whether builders can end creating and delivering residences.

Earlier this calendar year, many homebuyers refused to carry on having to pay mortgages on flats when design was delayed. Residences in China are typically offered in advance of completion, generating a major source of dollars movement for builders.

A drawn-out restoration

Analysts vary on when China’s house market place can recuperate.

Fitch explained a timeline “stays really uncertain,” when S&P World wide Ratings’ Senior Director Lawrence Lu expects a restoration could happen in the 2nd 50 percent of up coming 12 months.

“If this plan is applied instantly, this will prevent the downward spiral to the developers, this will support to restore the investors’ assurance [in] the developers,” he mentioned.

Household housing profits for the 1st 10 months of the calendar year dropped by 28.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a calendar year ago, the Nationwide Bureau of Statistics reported previous week. S&P Worldwide Ratings claimed in July it expects a 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} plunge in profits for 2022, even worse than in 2008 when gross sales fell by about 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

A slowdown in economic advancement, uncertainty about ongoing Covid controls and worries about long term income have dampened hunger for getting households.

Much burden is on China despite its rules-based system: World Bank

Incorporating to all those concerns are falling charges.

Housing rates throughout 70 metropolitan areas fell by 1.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Oct from a yr ago, according to Goldman Sachs assessment of knowledge introduced Wednesday.

“Even with more area housing easing steps in current months,” the analysts claimed, “we believe the house marketplaces in decreased-tier cities however facial area robust headwinds from weaker advancement fundamentals than significant cities, which includes net populace outflows and likely oversupply complications.”

The report reported housing costs in the premier, tier-1 cities rose by 3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in October from September, though Tier-3 cities noticed a 3.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} fall through that time.

About two decades back, Beijing started to crack down on developers’ superior reliance on credit card debt for advancement. The country’s most indebted developer, Evergrande, defaulted late last calendar year in a higher-profile financial debt crisis that rattled trader self esteem.

Worries about other authentic estate companies’ means to repay their debt have considering the fact that unfold to as soon as-nutritious developers.

Buying and selling in shares of Evergrande, Kaisa and Shimao is however suspended.

Examine a lot more about China from CNBC Professional

While Covid controls have dragged down China’s advancement this calendar year, the actual estate market’s struggles have also contributed significantly.

The house sector, together with relevant industries, accounts for about a quarter of China’s GDP, according to analyst estimates.

“I consider the authentic estate sector will turn into lesser of a drag to the financial state in 2023,” Tommy Wu, senior China economist at Commerzbank AG, said Wednesday.

“It is too early to notify whether the actions rolled out so much will be more than enough to rescue the actual estate sector,” he explained. “But it feels much more assuring now because it seems extra very likely that much more forceful steps will be rolled out if the genuine estate downturn nonetheless does not convert all-around meaningful in the coming months.”

A longer-time period transformation

Ultimately, China’s serious estate business is going through a condition-directed transformation — to a lesser section of the financial system and a enterprise product significantly considerably less reliant on offering apartments right before they are concluded.

The property sector has shrunk by roughly one-3rd compared to previous yr, and will very likely stay the same measurement following yr, S&P’s Lu mentioned.

State-owned developers have fared superior during the downturn, he pointed out.

In the initial 3 quarters of the calendar year, Lu explained profits by state-owned builders fell by 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, when compared to the 58{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} sales drop for builders not owned by the condition.

And in spite of new policy moves, Beijing’s stance remains firm in dissuading dwelling purchases at scale.

No matter whether it can be messaging from the Countrywide Bureau of Statistics or the People’s Lender of China, official bulletins this thirty day period reiterated that residences are for living in, not speculation — the mantra that marked the early beginnings of the real estate current market slump.

Chinese property giant Evergrande has a huge debt problem – here's why you should care
‘Load Up,’ Says Jim Cramer About These 2 Real Estate Stocks

‘Load Up,’ Says Jim Cramer About These 2 Real Estate Stocks

There was no good information in the August inflation numbers. Though the annualized rate did drop marginally from July, from 8.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 8.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, it came in higher than envisioned – and even worse, the main CPI fee, instead than dropping, elevated to 6.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Customers are struggling, and their soreness is genuine.

But it’s not only shoppers who are getting strike hard by inflation. Vendors are also emotion the pressure, and they’re experience it twice – from buyers, whose wallets are pinched and so are buying a lot less, and from their individual suppliers, who have been increasing charges by themselves. There is no quick way out of this, as the Federal Reserve’s main anti-inflationary go, increasing desire costs, will automatically drive up the charge of credit history, creating products additional pricey – again – for the two consumers and suppliers, though also escalating the hazard of a major economic downturn.

Investors can be forgiven if they just really don’t know the place to put their cash in an atmosphere like this. On this conclusion, Jim Cramer, the nicely-acknowledged host of CNBC’s ‘Mad Money’ plan, has some assistance.

“While most retail shares are terrible ideal now, the corporations that personal the finest retail true estate are performing just fantastic.” Cramer mentioned.

Cramer elaborated with some more element on the typical situation of industrial real estate organizations: “Not lots of [retail] chains are in risk of likely below, or even falling guiding on their lease payments. We’re not looking at mass shop closures, both… As extended as their tenants remain in enterprise, [real estate companies] will not consider considerably of a strike monetarily. To me, that appears like an option.”

Now let’s just take a search at two serious estate stocks on Cramer’s acquire record. We’ve made use of the TipRanks databases to pull up the newest data on both equally, and we can look at them out in conjunction with new commentary from the Wall Avenue analysts.

Kimco Realty (KIM)

The to start with Cramer choose we’re seeking at is Kimco Realty, a true estate financial commitment rely on (REIT) focused on commercial place. In fact, this enterprise, based mostly in Jericho, New York, is the premier proprietor and manager of grocery-anchored, open-air retail shopping facilities. The company’s portfolio of properties focuses on the initially-ring suburbs of important city places, specially in the Northeast, on the West Coast, and in the Southeast and Sunlight Belt regions. As of the conclusion of 2Q22, Kimco owned pursuits in 533 these kinds of shopping centers with a complete of 92 million leasable sq. feet.

Some crucial metrics from the company’s 2Q22 earnings launch present both equally the high-quality of the portfolio and the ongoing demand from customers for superior-stop retail area. To start with, Kimco observed its occupancy level enhance by 40 foundation points to 95.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the quarter. On a 12 months-about-12 months basis, Kimco’s occupancy rate has enhanced by 120 basis factors.

Substantial occupancy has led to a great deal of funds generation, and Kimco noticed its resources from operations (FFO) mature by 17.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} y/y to get to $246.6 million or 40 cents for every diluted share. This metric is of especial curiosity for dividend traders, as FFO normally supports a REIT’s div payments. Kimco’s recent dividend, declared in July for a September 23 payout, was set at 22 cents for every popular share. This annualizes to 88 cents, and gives a yield of 4.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Kimco has been progressively boosting the dividend over the previous two a long time.

In addition to Cramer, this inventory has caught the eye of Baird’s 5-star analyst Wesley Golladay, who writes of Kimco, “The core enterprise continues to increase with income basis tenants again to ordinary concentrations and SS base rents accelerating. Tenant need remains resilient and retention is substantial inspite of the softening financial state. The enterprise continues to be active on the exterior development front with structured investments, acquisitions and acquiring JV pursuits in 2Q and 3Q. KIM is also getting means to generate worth via acquiring again debt and preferred fairness, getting out current floor leases, and entitling land for household units.”

In addition to his upbeat comments, Golladay premiums this stock ab Outperform (i.e. Buy) and his value goal, at $27, implies a 1-calendar year upside potential of ~30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. (To watch Golladay’s track file, click on in this article)

Total, there have been 16 analyst testimonials set in current months, like 11 to Purchase and 5 to Maintain for a consensus rating of Reasonable Get on the inventory. The normal cost focus on of $24.45 implies an upside of 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the investing price tag of $20.82. (See Kimco inventory forecast on TipRanks)

Federal Realty (FRT)

Up coming up is Federal Realty, a REIT primarily based in Rockville, Maryland. FRT’s aim is on buying center qualities – particularly superior-finish retail properties – in the Mid-Atlantic and Northeast locations of the US. The company also has a existence in Florida, in the Great Lakes spot, and in the Southwest, particularly in California. FRT observed $951 million in overall earnings in 2021.

The company’s strong efficiency has ongoing this calendar year. In its 2Q22 report, FRT mentioned a higher occupancy rate of 92{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for its portfolio qualities, and a 94.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lease fee. Year-around-12 months, these numbers signify improves of 240 and 140 basis factors, respectively. Little shop leasing has verified specifically resilient considering the fact that the top of the COVID crisis, and has risen 580 basis points given that its pandemic reduced issue. In the recent Q2, small store leasing was up 360 foundation stage y/y to 89.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

FRT has also been relocating to expand its footprint, and in Q2 used some $434 million on 3 new browsing heart property. These new qualities deal with 93 acres of land and involve extra than 1 million square toes of leasable house. The organization signed 132 new leases for the duration of the quarter, covering 562,111 square toes of its full house, producing 2Q22 its ‘most active quarter on history.’

Federal Realty has 1 of the REIT industry’s strongest dividends, and has not missed a single payment considering the fact that it begun shelling out out 55 a long time back. The corporation has lifted its dividend in every single one particular of people 55 several years. The present-day dividend is $1.08 per popular share, or $4.32 annualized, and yields 4.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

All of this details to a business with a sound footing in its niche, and that prompted Raymond James’ 5-star analyst RJ Milligan to amount FRT a Powerful Buy alongside with a $140 value focus on. That figure signifies a possible for ~30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} share growth in the coming year. (To enjoy Milligan’s track document, click in this article.)

Backing his bullish stance, Milligan writes: “The major essential takeaway is that the leasing pipeline is as strong as it has at any time been – which need to push significant growth by means of 2023/2024… FRT (and the broader sector) has had a challenging couple of months of trading as buyers priced in a economic downturn and retreated into additional defensive REIT sub-sectors (such as web lease). With shares investing at just 17x the midpoint of 2022 direction much of our thesis remains intact: shares continue on to trade at a historic discount even though the essential backdrop has hardly ever been better…”

All in all, the 16 modern analyst critiques on this just one are evenly split, with 8 just about every Buys and Holds. This tends to make the consensus view a Moderate Get. FRT shares are investing for $100.60, and their $117.78 normal cost concentrate on implies ~17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} upside on the one particular-12 months horizon. (See FRT stock forecast on TipRanks)

To discover superior thoughts for shares buying and selling at desirable valuations, go to TipRanks’ Best Shares to Acquire, a recently launched device that unites all of TipRanks’ equity insights.

Disclaimer: The views expressed in this short article are only those people of the highlighted analysts. The information is intended to be utilised for informational functions only. It is quite vital to do your very own assessment in advance of making any expenditure.

5 Stocks to Win in a Thriving Retail Building Products Industry

5 Stocks to Win in a Thriving Retail Building Products Industry

The Zacks Building Products – Retail industry is poised to gain from the continued strong consumer demand trends for home renovation and maintenance activities amid rising interest rates and home prices. Rapid urbanization and favorable trends in the housing market are added advantages. The industry players are expected to gain from investments in digital and omni-channel capabilities for meeting demand, executing strategies, and acquisitions.

Continued innovation and e-commerce expansion, and strong demand are likely to benefit industry participants like The Home Depot Inc. HD, Lowe’s Companies Inc. LOW, Builders FirstSource, Inc. BLDR, Beacon Roofing Supply BECN and GMS Inc. GMS.

About the Industry

The Zacks Building Products – Retail industry mainly comprises U.S. home improvement retailers, manufacturers of industrial and construction materials, and distributors of wallboard and ceilings systems. Some industry participants offer products and services for home decoration, repair and remodeling, and in-home delivery and installation services. A few industry players provide construction products, ranging from cement or concrete foundation materials to roofing boards and shingles. The companies also sell lumber, insulation materials, drywall, plumbing fixtures, hard-surface flooring, and lawn and garden decor products. Some players also deal in threaded fastener products, and manufactured and natural stone tiles. In addition to general consumers, the industry players cater to professional builders, sub-contractors, remodelers and retailers.

3 Trends Shaping the Future of Building Products – Retail Industry

Adherence to Home Refurbishing Activities: With rising inflation, interest rates, and increased construction costs and home prices, consumers are inclined toward renovating their homes instead of buying one. Consumers continue to invest in making homes enjoyable and comfortable. Industry experts opine that consumers’ discretionary spending on homes will continue, as interests in keeping houses well-maintained are here to stay. Revamping interiors to facilitate work-from-home and entertainment needs continues to remain a major trend. Do-it-yourself (DIY) projects for decorating and maintaining furniture and fixtures are being widely undertaken. There is a higher demand for gardening tools, as well as products related to at-home activities such as paint and tool kits. This, along with rapid urbanization, should keep aiding the top-line performances of the industry participants. Additionally, consumers are open to hiring Professional (Pro) help to complete their home renovations, resulting in rising demand for Pro projects. This is likely to aid companies in the home improvement space, with a focus on building Pro offerings.

Digitization in Focus: Retail Building Products industry participants have been witnessing a surge in online business transactions, owing to consumers’ growing digital dependency. Companies have, therefore, been bolstering their digital presence by expanding the availability of online assortments and bolstering omni-channel capabilities. Such prudent measures have been aiding the companies to meet the accelerated demand. Companies are also ramping up their delivery operations in order to provide safe and swift services, especially to Pro customers. The digital transaction boom should continue to drive the top line of key industry players.

Rising Costs: Some home improvement retailers have been incurring additional costs to provide enhanced payments and other benefits to employees amid the pandemic. A few players have been witnessing inflationary pressure across product categories, as well as higher transportation costs. Such increased costs are likely to put pressure on margins. Nevertheless, companies are adopting prudent saving measures to cushion the impacts of such costs.

Zacks Industry Rank Indicates Solid Prospects

The Building Products – Retail industry is housed within the broader Zacks Retail-Wholesale sector. The industry currently carries a Zacks Industry Rank #25, which places it in the top 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of more than 250 Zacks industries.

The group’s Zacks Industry Rank, which is basically the average of the Zacks Rank of all the member stocks, indicates bright near-term prospects. Our research shows that the top 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the Zacks-ranked industries outperforms the bottom 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} by a factor of more than 2 to 1.

The industry’s position in the top 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the Zacks-ranked industries is a result of a positive earnings outlook for the constituent companies in aggregate. Looking at the aggregate earnings estimate revisions, it appears that analysts are gradually gaining confidence in this group’s earnings growth potential. In the past year, the industry’s earnings estimates for the current fiscal year have increased 20.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Given the industry’s encouraging prospects, we present a few stocks that you may want to consider buying for your portfolio. But before that, it is worth taking a look at the industry’s stock-market performance and current valuation.

Industry Vs. Broader Market

The Zacks Building Products – Retail industry has outperformed the broader Zacks Retail-Wholesale sector and the Zacks S&P 500 over the past year.

The industry declined 8.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past year, whereas the broader sector declined 31.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Meanwhile, the S&P 500 has registered fall of 12.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past year.

One-Year Price Performance

Industry’s Current Valuation

On the basis of forward 12-month price-to-earnings (P/E) ratio, which is the commonly used multiple for valuing Retail-Wholesale stocks, the industry is currently trading at 14.71X compared with the S&P 500’s 16.53X. Further, the sector’s forward-12-month P/E stands at 20.69X.

Over the last five years, the industry traded as high as 23.43X and as low as 14.19X, with the median at 19.54X, as the chart below shows.

Price-to-Earnings Ratio (Past 5 Years)

5 Building Products Stocks to Buy

Builders FirstSource: The Dallas, TX-based company manufactures and supplies building materials. The company has been benefiting from its focus on cost synergies, strategic acquisition, and robust demand from solid housing and repair and remodeling activities. Robust demand for single-family housing, R&R and other activities have been tailwinds for the company’s products and services. Builders FirstSource continues to focus on investing in innovations and enhancing digital solutions for its customers.

Acquisitions are important for Builders FirstSource’s growth strategy to supplement its organic growth and expand extensively across vast geographic boundaries. The Zacks Rank #1 (Strong Buy) company has been active on the acquisition front, which is supporting the top line. It is also focusing on cost-management practices. The stock has surged 49{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for BLDR’s current fiscal-year sales and earnings indicates growth of 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 18.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively, from the prior-year period’s reported figures. The consensus estimate for the current fiscal-year earnings has moved up 0.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.

You can see the complete list of today’s Zacks #1 Rank stocks here.

Price and Consensus: BLDR

Beacon Roofing: The company is the largest publicly-traded distributor of residential and non-residential roofing materials, along with complementary building products in the United States and Canada. The company has been benefiting from strategic initiatives and the successful execution of its technology initiative in the growing e-commerce platform. The company is also on track with its Ambition 2025 targets, which emphasize operational excellence, above-market growth trajectory and accelerated stockholder value creation. Beacon has been focusing on business expansion through bolt-on acquisitions, thereby expanding its reach.

Beacon is expanding its digital platform in value-added ways. It remains on track with the long-term target of generating $1 billion in annual digital sales. Disciplined pricing in a volatile, supply-constrained marketplace, and effective and timely sourcing have been aiding margins. Cost-saving efforts and productivity initiatives are expected to go a long way in bringing down the Zacks Rank #1 company’s operating expenses, thereby driving margins. The stock has risen 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for BECN’s current fiscal-year sales and earnings indicates growth of 23.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 36.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has been unchanged in the past 30 days.

Price and Consensus: BECN

Home Depot: The Atlanta, GA-based company is the world’s largest home improvement specialty retailer, based on net sales. Home Depot has been benefiting from strong demand for home-improvement projects, robust housing market trends and ongoing investments. Continued strength in both Pro and DIY categories, and digital momentum have been key drivers. Its interconnected retail strategy and underlying technology infrastructure have helped consistently boost web traffic for the past few quarters, aiding digital sales.

Home Depot is witnessing significant benefits from the execution of its One Home Depot plan, which focuses on expanding the supply chain, technology investments and digital enhancements. The Zacks Rank #2 (Buy) company has created the fastest, most efficient delivery network in home improvement through options like buy online pick up in store with convenient pickup lockers, buy online deliver from store with express car and van delivery, and curbside pickup. The HD stock has declined 10.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for its current fiscal-year sales and earnings indicate growth of 3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has been unchanged in the past 30 days.

Price and Consensus: HD

Lowe’s Companies: The Mooresville, NC-based leading home improvements retailer has been gaining from strong growth in its Pro business. The company has been enhancing the experience of its pro customers by upgrading pro-focused brands and revamping the pro-service business website. The company also remains well-positioned to capitalize on the demand for the home improvement market, backed by investments in the technology and merchandise category. Gains from the Total Home strategy and the execution of the Perpetual Productivity Improvement initiative are likely to drive the company’s results in the near and long terms. The Total Home strategy has been resonating well with Pro and DIY customers for a while.

Lowe’s has been progressing well with advancements in the digital channel. The company is investing in enhancing omni-channel retailing capabilities. Management is also committed to enhancing the Pro offerings, expanding the company’s market share and driving the operating margin. Shares of the Zacks Rank #2 company have declined 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for its current fiscal year’s sales and earnings indicates growth of 1.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 12.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has improved 0.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.

Price and Consensus: LOW

GMS: The Tucker, GA-based leading North American specialty building product distributor has been gaining from the robust customer service in a solid residential market, coupled with an inflationary pricing environment and successful platform expansion activities. Inflationary pricing, healthy residential end markets, strong performance from complementary products and the recent acquisitions have been sales drivers for GMS.

The Zacks Rank #2 company has risen 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for GMS’ current fiscal year’s sales and earnings indicates growth of 8.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 2.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has moved up 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.

Price and Consensus: GMS

Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
 
The Home Depot, Inc. (HD) : Free Stock Analysis Report
 
Lowe’s Companies, Inc. (LOW) : Free Stock Analysis Report
 
Beacon Roofing Supply, Inc. (BECN) : Free Stock Analysis Report
 
Builders FirstSource, Inc. (BLDR) : Free Stock Analysis Report
 
GMS Inc. (GMS) : Free Stock Analysis Report
 
To read this article on Zacks.com click here.
 
Zacks Investment Research

5 Beaten-Down Home Improvement Stocks to Scoop Up Now

5 Beaten-Down Home Improvement Stocks to Scoop Up Now

Home improvement companies benefited significantly from surging consumer interest in renovation and remodeling activities amid the pandemic-led remote lifestyles. However, sowing home sales this year with soaring mortgage rates amid the multi-decade high inflation is hurting the industry’s growth. Many home improvement companies have witnessed sales declines lately.

However, since many economists believe inflation has peaked, the demand for homes and home improvement should rebound soon with declining mortgage rates. Moreover, soaring DIY décor trends should help home improvement companies to stay afloat. The global do-it-yourself (DIY) home improvement retailing market is expected to grow at a 4.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} CAGR to $1.28 trillion by 2030. The global home improvement market is expected to grow at a 6.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} CAGR to reach $514.90 billion by 2028.

Therefore, it could be wise to invest in beaten-down home improvement stocks Arhaus, Inc. (ARHS), Tile Shop Holdings, Inc. (TTSH), Kingfisher plc (KGFHY), Haverty Furniture Companies, Inc. (HVT), and Builders FirstSource, Inc. (BLDR), which possess sound fundamentals and solid growth prospects.

Arhaus, Inc. (ARHS)

ARHS operates as a lifestyle brand and premium retailer in the home furnishings market, providing merchandise assortments across various categories, including furniture, lighting, textiles, décor, and outdoor. The company offers its products through an omnichannel model comprising showrooms, an e-commerce platform, a catalog, and in-home designer services. As of December 31, 2021, it operated through a network of 71 traditional showrooms, 5 Design Studios, and 3 Outlets, as well as 58 showrooms with in-home interior designers.

For its fiscal 2022 first quarter ended March 31, 2022, ARHS’ net revenue increased 43.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $246.30 million. The company’s gross profit came in at $97.72 million, representing a 38.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year improvement. Its income from operations came in at $22.87 million for the quarter, indicating a 102.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise from the prior-year period. As of March 31, 2022, the company had $148.84 million in cash and cash equivalents.

ARHS surpassed Street EPS estimates in the trailing three quarters. The consensus revenue estimate of $1.17 billion for fiscal 2022 ending December 31, 2022, represents a 47.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise from the prior-year period. The company’s EPS is expected to grow at a rate of 7.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} per annum over the next five years.

The stock’s 0.82x forward EV/Sales is 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 1.11x industry average. In terms of forward Price/Sales, ARHS is currently trading at 0.68x, which is 28.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 0.95x industry average. Over the past week, the stock has lost 5.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close yesterday’s trading session at $5.57, down 61.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its 52-week high of $14.95.

ARHS’ POWR Ratings reflect this promising outlook. The stock has an overall B rating, which equates to Buy in our proprietary rating system. The POWR Ratings are calculated by considering 118 distinct factors, with each factor weighted to an optimal degree.

It has an A grade for Sentiment and a B grade for Quality. Click here to see the additional ratings for ARHS’ Growth, Stability, Value, and Momentum. ARHS is ranked #15 of 63 stocks in the Home Improvement & Goods industry.

Tile Shop Holdings, Inc. (TTSH)

TTSH is a specialty retailer of manufactured and natural stone tiles, setting and maintenance materials, and related accessories. The company offers marble, travertine, granite, quartz, sandstone, porcelain, glass, cement, wood, and metal tiles. It sells its products through its website and offers delivery services through third-party freight providers.

For its fiscal 2022 first quarter ended March 31, 2022, TTSH’s net sales increased 11.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $102.47 million. The company’s gross profit came in at $66.85 million, indicating a 4.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise from the prior-year period. It had $13.46 million in cash and cash equivalents as of March 31, 2022.

Analysts expect the company’s revenue to improve 5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $389.97 million for fiscal 2022, ending December 31, 2022. TTSH’s EPS is expected to grow at a rate of 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} per annum over the next five years.

The stock’s 0.90x forward EV/Sales is 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 1.11x industry average. In terms of forward Price/Sales, TTSH is currently trading at 0.58x, which is 39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 0.95x industry average. Over the past week, the stock has lost 4.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close yesterday’s trading session at $4.37, down 50.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its 52-week high of $8.90.

TTSH’s POWR Ratings reflect this promising outlook. The stock has an overall B rating, which equates to Buy in our proprietary rating system.

It has an A grade for Sentiment and Quality. Click here to see the additional ratings for TTSH’s Stability, Value, Growth, and Momentum. TTSH is ranked #4 in the same industry.

Kingfisher plc (KGFHY)

Headquartered in London, the U.K., KGFHY supplies home improvement products and services through home improvement specialist stores and e-commerce internationally. Also, the company offers property investment, finance, digital, sourcing and franchising, and IT services. It operates approximately 1,470 stores in eight countries across Europe under the B&Q, Castorama, Brico Dépôt, Screwfix, TradePoint, and Koctas brands.

On May 16, 2022, KGFHY’s Screwfix business, a multi-channel retailer of trade tools, accessories, and hardware products, announced to open its 800th store in June and expand its footprint through 80 new stores across the UK and the Republic of Ireland by the end of its fiscal 2023. This expansion will help Screwfix witness rising demand in the coming months.

For its fiscal 2022 full year ended January 31, 2022, KGFHY’s sales increased 6.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to £13.18 billion ($16.45 billion). The company’s gross profit came in at £4.94 billion ($6.16 billion), up 7.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the prior-year period. Its operating profit came in at £1.14 billion ($1.43 billion) for the quarter, representing a 24.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise from the year-ago period. KGFHY’s adjusted net earnings came in at £737 million ($919.65 million) for the quarter, indicating a 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year improvement. Its adjusted EPS came in at 35.2 pence, representing a 22.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise from the year-ago period.

The stock’s 0.52x forward EV/Sales is 53{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 1.11x industry average. In terms of forward Price/Sales, KGFHY is currently trading at 0.40x, 57.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 0.95x industry average. Over the past week, the stock has lost 5.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close yesterday’s trading session at $6.19, down 40.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its 52-week high of $10.47.

KGFHY’s POWR Ratings reflect its solid prospects. The stock has an overall B rating, equating to Buy in our proprietary rating system.

It has an A grade for Value and a B grade for Stability and Quality. In addition to the POWR Ratings grades we have just highlighted, one can see the ratings for KGFHY’s Momentum, Growth, and Sentiment here. KGFHY is ranked #14 in the same industry.

Haverty Furniture Companies, Inc. (HVT)

HVT is a specialty retailer of residential furniture and accessories, custom upholstery products, eclectic looks, and mattress product lines. The company also offers financing through a third-party finance company and an internal revolving charge credit plan. It distributes primarily through retail stores and websites.

HVT’s net sales for its fiscal 2022 first quarter ended March 31, 2022, increased 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $238.95 million. The company’s gross profit came in at $140.96 million, representing a 4.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year improvement. Its pre-tax income came in at $25.72 million for the quarter, up 1.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the year-ago period. HVT’s EPS increased 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $1.11. The company had $162.34 million in cash and cash equivalents as of March 31, 2022.

The company surpassed Street EPS estimates in each of the trailing four quarters, which is impressive. Its EPS is expected to grow at a 13.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate per annum over the next five years.

HVT’s 0.54x forward EV/Sales is 51.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 1.11x industry average. In terms of forward Price/Sales, the stock is currently trading at 0.47x, 50.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 0.95x industry average. Over the past three months, the stock has lost 3.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close yesterday’s session at $27.73, down 42.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its 52-week high of $48.54.

HVT’s strong fundamentals are reflected in its POWR Ratings. It has an overall rating of B, which equates to Buy in our proprietary rating system.

The stock has an A grade for Value and Quality and a B for Sentiment. Click here to see the additional ratings for HVT (Momentum, Stability, and Growth). The stock is ranked #3 in the same industry.

Builders FirstSource, Inc. (BLDR)

BLDR manufactures and supplies building materials, manufactured components, and construction services to professional homebuilders, sub-contractors, remodelers, and consumers. The company also distributes dimensional lumber and lumber sheet goods, millwork, windows, interior and exterior doors, and other building products. It offers a range of construction-related services, including professional installation, turn-key framing, and shell construction, spanning all its product categories.

On January 5, 2022, BLDR acquired National Lumber, the largest independent building materials supplier in New England. National Lumber’s diverse building materials and service offerings, including prefabricated millwork components and a robust R&R mix, will add even more depth to the value-added solutions BLDR customers rely on. This acquisition should strengthen BLDR’s presence in New England.

BLDR’s fiscal 2022 first-quarter net sales increased 36.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $5.68 billion. The company’s gross profit came in at $1.83 billion, indicating a 71.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year improvement. Its income from operations came in at $863.81 million for the quarter, representing a 248.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise from the year-ago period. While its adjusted net income increased 136.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year to $700.80 million, its adjusted EPS grew 174.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to $3.90. As of March 31, 2022, the company had $281.80 million in cash and cash equivalents.

Analysts expect BLDR’s EPS to be $12.17 for fiscal 2022 ending December 31, 2022, representing a 17.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year improvement. It surpassed Street EPS estimates in each of the trailing four quarters, which is impressive. The consensus revenue estimate of $21.65 billion in the same fiscal year represents an 8.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year improvement. The company’s EPS is expected to grow at an 18.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate per annum over the next five years.

The stock’s 0.69x forward EV/Sales is 58{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 1.65x industry average. In terms of forward Price/Sales, BLDR is currently trading at 0.53x, which is 61.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than the 1.36x industry average. Over the past week, the stock has lost 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to close yesterday’s trading session at $27.73, down 24.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its 52-week high of $86.48.

BLDR’s strong fundamentals are reflected in its POWR Ratings. The stock has an overall B rating, which equates to Buy in our proprietary rating system.

It has a B grade for Value, Growth, Momentum, Sentiment, and Quality. Click here to see the additional ratings for BLDR’s Stability. BLDR is ranked #2 in the same industry.


ARHS shares closed at $5.53 on Friday, down $-0.04 (-0.72{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Year-to-date, ARHS has declined -58.26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, versus a -17.67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rise in the benchmark S&P 500 index during the same period.

About the Author: Sweta Vijayan

Sweta is an investment analyst and journalist with a special interest in finding market inefficiencies. She’s passionate about educating investors, so that they may find success in the stock market. More…

More Resources for the Stocks in this Article