A lady is suing a genuine-estate agency who she stated tricked her into shopping for a penthouse without a total-time doorman.Google Maps
A lady said she was deceived into believing a penthouse she obtained experienced a entire-time doorman.
The unnamed girl is suing The Corcoran Team, just one of its agents, and the vendor of the residence.
She reported the agency experimented with to cover the actuality that there was a virtual doorman in the evenings.
A female is suing a New York Metropolis genuine-estate company that she mentioned tricked her into getting a $19 million penthouse without a entire-time doorman, the New York Write-up at first documented.
In a grievance submitted Wednesday with the Manhattan Supreme Courtroom and acquired by Insider, a authorized agent for the unnamed woman claimed she ordered the penthouse at 37 Warren Avenue, Tribeca, in March.
The customer — who is explained in the legal doc as a one mom of three — terminated the contract in August and demanded a refund of her $1.9 million deposit following mastering that the vendor and brokers had concealed that there was a part-time doorman and digital doorman in the evenings, according to the criticism. Now, the complaint says, she’s searching for punitive damages in excess of $2.5 million as properly as the reimbursement of her legal expenses.
The grievance was filed by Kara Dille, an accountant who runs the unidentified woman’s estate, according to the New York Article. It names The Corcoran Team, Catherine L Juraciah (an agent at the real-estate company), and Zoelle LLC (the seller of the home).
According to the complaint, The Corcoran Group and Zoelle LLC represented the doorman in an “deliberately wrong” way with the apparent intention to “fraudulently induce” the girl into obtaining the household.
The grievance claims The Corcoran Team misrepresented the house by crafting that there was a doorman in the on the net listing and on many other internet websites that printed the info. It adds that the agency and its reps “went so significantly as to place themselves in front of the virtual doorman interface” all through viewings of the property so she could not question issues about what it was and why it would be expected if there was a complete-time doorman.
The customer would under no circumstances have bought the house had she known there was no entire-time doorman, according to the complaint. “Right after all, the settlor-beneficiary sought a residence wherever she, a one mother with a few kids, could reside in ease and comfort and stability realizing that there was a fulltime doorman,” the document reads.
Howard M. Brickner, an legal professional for Zoelle LLC, wrote in a letter to the court docket that the vendor is not liable for the alleged actions or published statements of the serious-estate company, the New York Put up studies.
“The Vendor is not liable or sure in any way by any verbal or prepared statements, representations, true estate broker ‘set-ups’ or info pertaining to the higher than premises furnished by a true estate broker nor by any agent, staff, servant or other human being,” the letter states, according to the New York Write-up.
Howard M. Brickner, Catherine L Juraciah (the agent at The Corcoran Team named in the complaint), and Steven I. Fox, an lawyer at New York-dependent legislation firm Wrobel Markham LLP representing Dille, did not straight away respond to Insider’s ask for for remark.
When Keyan Sanai moved to Manhattan and started working as a real estate broker in 2014, he was eating 12 to 15 cans of tuna a week to keep costs low. “I said to my friend, ‘My mouth tastes like a fistful of old pennies all the time,’” he says. After a doctor’s visit, he found out he had mercury poisoning.
His first few years as a broker were rough. Working at a “boiler room” brokerage, he got acquainted with what he calls the “dark underbelly” of the industry. “The script is basically to lie to people: ‘Put up [an ad] that says ‘no fee’, and once you get ’em in, say, ‘Oh, that’s rented, but I have something else,’” he recalls managers telling him. He says they insisted their employees “just get [the client] out to the appointment, then pump the fear and pressure them into making a decision.”
“I was like, ‘Ahh, I can’t do that,’” Sanai says. After three years of scraping by as a broker, he personalized a more ethical approach to renting, switched agencies, and became Douglas Elliman’s top-ranked New York rental agent in 2019.
But less than a year later, he watched the pandemic drive a mass exodus from the city. Brokers like Sanai, who are typically unsalaried and work on a 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} commission basis, saw their incomes evaporate. In August of 2020, he left a showing when his client wasn’t showing up. “She emailed me, ‘You should come back,’” he recalls. “I don’t need you at this time, you need me.’” It took him four weeks to rent the one-bedroom on West 37th Street, even with a “great deal”.
Today, a one-bedroom in the same building rents sight unseen in days, and the power dynamic between brokers and renters has flipped. In contrast to 2020’s renter’s market, this is an owner’s market, which, in New York City, means it’s a landlord’s market, and, by extension, a broker’s market. Last month, the average rent for an apartment in Manhattan hit a record high of $5,000, up 29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over last year with demand and prices expected to keep surging into the fall. Meanwhile, the supply of available apartments is nearing record lows, with a vacancy rate in Manhattan of 1.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, down 46{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021.
Advertisements for luxury apartments and homes in the window of a Douglas Elliman Real Estate business in Manhattan’s Upper East Side. Photograph: Mike Segar/Reuters
For renters who make less than $160,000 a year – the minimum required to secure a $4,000 rental – the housing crisis can mean spending months searching for an affordable apartment, or being priced out of a neighborhood long called home. But for many rental agents, it’s been a boon for business. Bidding wars have become routine. Certain apartments rent sight unseen. In July, 45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of apartments citywide required broker fees, compared with just 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2021.
A hotter market often means some brokers and landlords can get away with more unethical behavior, from posting bait-and-switch BS apartment listings to starting “broker fee bidding wars”. even for rent-stabilized apartments. (There are no legal limits on how much a broker can charge in fees, but it is typically 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of annual rent, or one month’s rent.)
“People are more desperate. There’s very little regulation,” Sanai says. “I’ve heard stories of people saying, ‘We really wanted this place, but we’re pretty sure the broker took cash on the side from someone’” – a practice that’s illegal, but difficult to regulate.
Aside from struggling with guilt, possibly, this may seem entirely like a win for brokers, but Sanai now finds himself fielding hundreds of inquiries a day, presiding over packed open houses, and listening to “sob stories” from desperate apartment-hunters. “It was difficult to navigate when you were praying that someone would show up to your open house during Covid,” he says. “But it’s just as difficult to navigate when you have multiple people who want the same product.”
Other brokers are indeed taking it all in stride. “The rental market is crazy right now in New York City, and so I have a treat for you guys,” Anthony Park announced to his 179,000 TikTok followers in a video last month. “We have a one-bedroom in the West Village that’s going to be coming on to the market very soon. But I wanted to give you a first look and see if any of you wanted to take this place before it goes live.”
Park enters a fourth-floor walkup near the Waverly Inn, a sceney bistro that serves $29 cheeseburgers. The bedroom can’t fit much more than a full bed, and the kitchen has an “eating counter” but no room for a table.
“If you’re willing to take it sight unseen, [and] to put in more than $4,250 a month, which is what it’s going to be listed for, then shoot me an email,” says Park, 29, who started working at Brown Harris Stevens in March 2021 and now runs a popular “Real Estate TikTok” account, posting housing porn of $135m penthouses and river views from “Billionaire’s Row”.
Although his videos – and those of other NYC brokers who have taken to posting listings on TikTok – are sometimes met with hostile comments (“Looks like a torture chamber,” said one user of the West Village apartment; “Scammy af,” said another), Park is unfazed, knowing this place will fly off the market.
When Park started his TikTok in 2020, he says, “I wanted someone to look at my channel and think, ‘This guy does not look like a broker.’ I intentionally don’t wear suits.”What a broker looks like, according to Park: “Someone who is not cool, someone who comes off way too aggressive, too much oil in their hair, talking about themselves all the time.”
Whether he looks like one or not, he’s living a broker’s dream when $4,250 is considered low for a one-bedroom in Manhattan. While TikTok ultimately yielded no takers on Park’s proposal, the “torture chamber” did rent for $200 per month above asking price, to a tenant who beat out several other above-ask applications at an appointment-only open house.
“People were like, ‘How are you demanding so much? That’s ridiculous,’” says Park. His response: “New York is expensive. You can easily go to some other city and find very affordable housing. If you struggle, then it’s like, well, you chose to be here.”
Between January 2021 and 2022, jobseekers flocked to the real estate industry. The top job-related Google search was “how to become a real estate agent”, and a record number of real estate licenses were issued nationwide.
Many new brokers find the work more stressful and less lucrative than expected. The rental market “can be brutal, depending on if you have a soul”, says Anna Klenkar, a broker with Compass whose TikTok bio reads: “Housing is a human right”. “I’m on a call at 8am every Monday with agents who are like, ‘I feel fucking horrible, I feel so guilty. We got 12 applications, people are offering way more than the rent. What are these people going to do?’”
Allow TikTok content?
This article includes content provided by TikTok. We ask for your permission before anything is loaded, as they may be using cookies and other technologies. To view this content, click ‘Allow and continue’.
About 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} percent of brokers don’t renew their licenses after one year. “It’s really hard to be a rental agent long term,” says Klenkar, who worked in rentals for years before switching to sales full-time. “You can work 80 hours a week and make zero dollars. I worked so much my first two years and barely made ends meet. We’re 1099 [tax forms], we don’t have salaries. I have to pay like $800 a month out of pocket for health insurance. We expect that half the industry will leave in the next 18 months, because whenever there’s a recession, people want to go back to W-2 jobs.”
Estimates of the average income – made entirely by broker’s fees either paid by the landlord, or, in an owner’s market, by the potential renter – of a broker in New York City range between $36,000 and $47,000 a year, meaning the average agent can’t afford the average monthly rent of $5,000 themselves.
Kai Dailey, 27, an agent with Compass since 2020, says that in the past month he reduced the number of rental clients he represents and shifted his focus to sales. He describes an atmosphere of stiff competition, burnout, and strained relationships with clients in the rental market.
“I’m working from 7AM until 9pm every day. The emails, texts, phone calls, they don’t stop. And to some people, you’re an incredible agent. [But] to a majority, you might not be able to get back in contact. The rental market moves faster than you can keep up.”
Some agents describe feeling guilty watching renters pay staggering rates for tiny spaces. “When you see people paying such large fees up front for these units, it does make you gulp. Deep,” says Dailey.
On a recent Sunday afternoon, 25 people stood sweating in a narrow stairwell on West 11th Street, waiting to see a one-bedroom apartment Sanai was showing for $4,195 a month. He ushered them quickly through the small rooms, fielding questions like “Why is the lamp in the bathroom super hot?” (“It’s a heat lamp”) and “What happens if someone lies in their application?” (“Then we’ll get the documentation that shows they’re lying and move on to the next applicant”). He had been showing apartments since 10am.
“In general, people hate brokers. And if you thought people hated us before, now it’s just another level of dislike,” says Sanai. “I wish my calling was being a surgeon or something that helped society, but this is it.”
Visitors to the open house included a 32-year-old construction manager who said being a broker was a “cheap job” – “like, ‘Wham, bam, thank you ma’am.’”
“It feels like we’re doing all the legwork and just giving them a fee,” said Lucy Malone, a 26-year-old fashion designer. “It feels like they don’t add that much value.”
At one point during the showing, Sanai reminded the crowd that he would have zero say in whose application the landlord greenlit: “It’s not up to me,” he said. While he wields more leverage today than in 2020, he notes that many overestimate brokers’ power, conflating their position in the housing market with that of landlords and developers.
“We’re middlemen. We’re basically puppets. If the owner says, ‘We want $4,000 for this apartment,’ I don’t have a say in pricing. I’ll say, ‘That number is a little high,’ and they’ll say, ‘If anyone can get this number, it’s you. Good luck.’ And then someone won’t get chosen and they’ll send a nasty email, like, ‘This is bullshit,’ but we really have no say. It’s tough, because I don’t want to disappoint someone.”
He adds: “I really do sympathize with how difficult it is to get an apartment.”
The perks of being a broker in New York City today are not lost on him, but he doesn’t forget where he started, or how quickly the market can reverse course. He says: “Every now and then I’ll have a can of tuna just to remember how it tastes.”
In New York Metropolis, luxury serious estate is as significantly a car to disguise one’s prosperity as it is to flaunt it. Not long ago, these kinds of properties have come less than new scrutiny as town officers connect with for seizing the flats of acknowledged Russian oligarchs. “For a long time, Manhattan has been a single of the most preferred secure harbors for Russian oligarchs to park their cash, specifically via extremely-significant-stop apartments,” Manhattan Borough President Mark Levine tweeted on Monday.
And with the “ultra-superior-end” market arrives a corresponding phenomenon: the extremely-large-end renovation. These jobs, like the entrepreneurs — or proudly owning entities — are normally shrouded in secrecy. The architects, contractors, and carpenters sign NDAs and develop out homes that may well never ever home an genuine tenant. But when it arrives to provider, what do these consumers ask for? Do you even meet your manager?
Curbed spoke to a contractor who does luxurious wooden and metal architectural perform to get a sense of the occupation (“Sometimes you have received to shut down Fifth Avenue and hire a crane”) and the clientele (“bad style but tons of money”).
This job interview has been edited and condensed.
On insane-large jobs, you indication NDAs, and they are truly restrictive about obtain. I’ve labored on two or 3 penthouses and major skyscrapers, and there are insane safety protocols. If you are a subcontractor of a subcontractor, you do not ever get any where in close proximity to any individual, and you only see construction people today. I’ve worked on job sites where aspect of the NDA is that you just cannot choose photos — I have seen a carpenter get caught taking pictures and then straight away get escorted out of the constructing by safety.
With stars, you may possibly know it is their area — it is rumored — but you really don’t ever see them. But for oligarchs owning authentic estate completed through shell providers, you would by no means know who it is. These sorts of build-outs or investments are just parking income someplace. Perhaps the developers them selves will have a marriage with the conclude client, but I really don’t know. I have been in households and labored on tasks that are worth tens of thousands and thousands of bucks, and if I actually desired to come across out who they belonged to in the finish, I’m not even positive who I’d chat to.
For a more compact $7 million challenge we did not get, I had to indicator an NDA just to seem at the architectural drawings. The precise customers came to my shop, which was extremely unconventional. But if you Google them or Google that property to figure out who you’re really operating for, you really don’t know. There ended up no past names, and that house is in a keeping organization.
It is seriously wildly demanding. People with that form of cash skirt building codes and get about items like metropolis ordinances on how much you can operate and how much sound you can make. If they make your mind up they actually want to go quick, they’ll set it in the agreement, and you’ll function until finally shit will get performed. There are insane deadlines exactly where you get 130-web site contracts and it is like, If you fuck this up, a team of attorneys will litigate you out of existence.
A not uncommon exercise is making things that will move inspection only to be removed just after it’s given a certification of occupancy. For illustration, there’s loads of policies about stairs, like code all-around open up gaps concerning balusters on railings. Often, they want a significant huge-open up railing, so we’ll build a railing that is crammed in, and following inspection, it will come out.
Occasionally you have received to shut down Fifth Avenue and hire a crane to haul all this stuff into a setting up, which is insane. Just so they can get all their home furniture into their apartment!
When I’m operating on smaller sized-scale initiatives right with the shopper, there is the general shit that comes about with wealthy folks: They wanna be over your shoulder and change their intellect all the time. They’ll want to make modifications and not fork out for them, and there’s a sort of services they assume to be offered.
It would truly be more pleasurable if they preferred crazier issues, but what finishes up taking place is that architects design and style these seriously appealing factors and a great deal of that will get pushed out in the method. The consumer will see some shit they want in a journal and know that other people today like it, so in its place of carrying out something intriguing, they shell out insane piles of cash on elements and hiding the workmanship. Given that they really do not want to see how it is created or held jointly, you get truly medical areas that are value tens or hundreds of countless numbers of pounds for a concluded product that is relatively bland most of the time. It normally sticks out how a great deal dollars they commit for the stuff to arrive out so regular.
A person challenge I worked on had an 1,800-pound doorway, and they just required it to get the job done a particular way. So we had to purchase tailor made-created $6,000 hinges to make it go. There’s a whole lot of energy, time, and cash that’s set into coming up with tailored methods to solving logistical and engineering complications that eventually fit a quite tedious aesthetic. Or it is actually odd stuff, like a usual McMansion but anything is gold plated or imported stone from strange quarries in Spain. They have undesirable style but tons of cash and buy all this really highly-priced stuff that ends up on the lookout like shit.
FOX Business’ Madison Alworth stories on the city’s attempts on ‘Varney & Co.’
New York Metropolis real estate brokers have been inundated with Russian consumers on the lookout to privately promote off multimillion-greenback homes by so-referred to as “whisper listings” in a rush to liquidate property amid fears a lot more U.S. sanctions will appear against any person believed to be tied to Russian President Vladimir Putin.
Dolly Lenz, a luxury true estate agent who’s been in the organization in New York City much more than 35 many years, explained to FOX Business enterprise her agency acquired phone calls from Russian clients on the lookout to probably “whisper listing” among 50 and 70 homes, largely in Manhattan, within the final week.
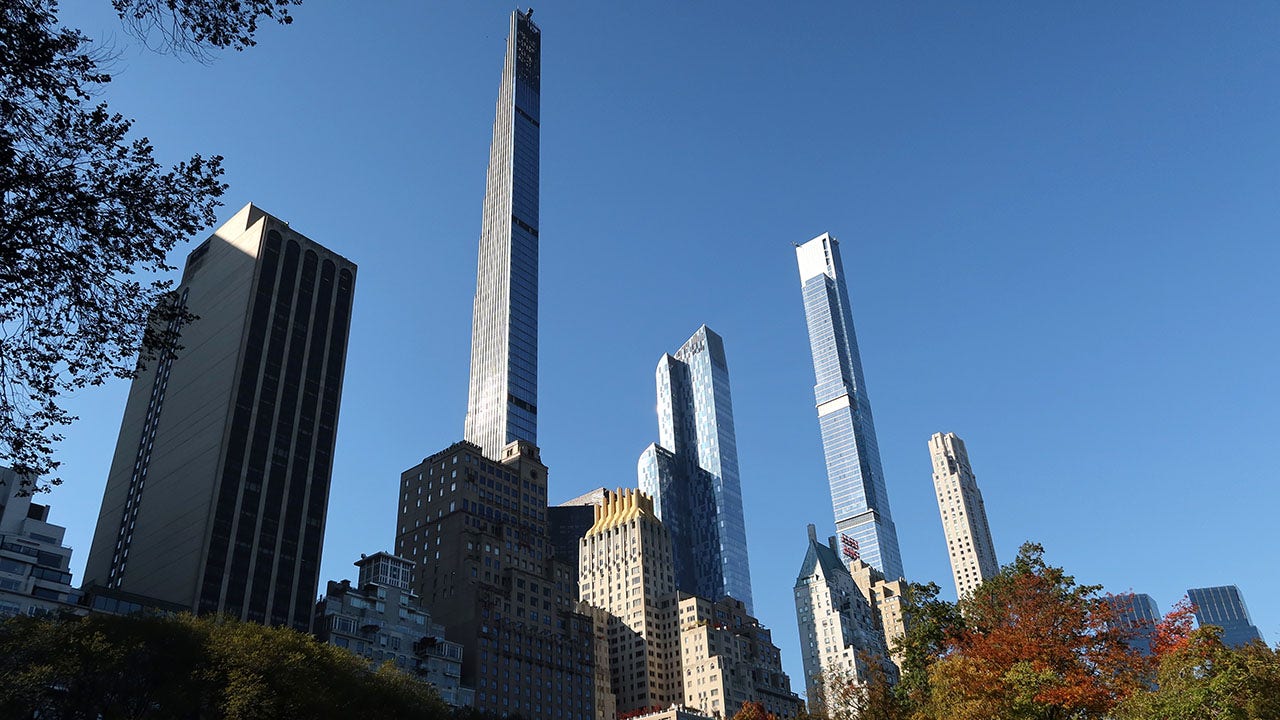
Of the Manhattan properties that could be offered beneath the radar, the majority are on Billionaires’ Row, a set of ultra-luxury residential skyscrapers alongside the southern end of Central Park. There are other folks in the West Village, as perfectly as some luxury condominiums on Park Avenue and Fifth Avenue.
The attributes range in value from $5 million to $45-50 million in inquiring value, but income could be rushed for far much less relying on how distressed sellers turn into.
The Steinway Tower and Central Park Tower on Billionaires’ Row rise earlier mentioned Central Park, Nov. 9, 2021, in New York Metropolis. (Getty Illustrations or photos / Getty Illustrations or photos)
‘Depending on sanctions’
“Everybody’s placing feelers out there. They are not pulling the trigger still. They’re having all set to pull the set off. Indicating, ‘Yes, I am going to consider no matter what the best providing can get me’,” Lenz informed FOX Enterprise this week. “That could be what comes down the pike. So genuinely, based on sanctions, and you know exactly where we are with almost everything, that is all we see perhaps is actively playing out.”
RUSSIA-UKRAINE WAR: CANADIAN Premier Desires TO REVIVE TRUMP-BACKED KEYSTONE-XL PIPELINE TO Substitute RUSSIAN OIL
Lenz explained other Russian entrepreneurs arrived at out to her from states outside the house of New York, like California and Florida, wherever likely sellers are in North Miami and Fisher’s Island, acknowledged for its personal enclaves that turned preferred among the Russian uber-rich all around the slide of the Soviet Union.
Billionaires’ Row is a extend of extremely-luxurious properties on and all around West 57th St. (FOX Business )
As Putin continues his invasion of Ukraine, President Biden’s Justice Section released a new process drive, KleptoCapture, which has been functioning considering that previous 7 days to enforce sanctions versus Russian felony actors and potentially seize belongings in the U.S. belonging to Russian oligarchs, which include luxurious authentic estate, yachts and personal jets well worth hundreds of thousands and thousands of bucks.
Loopholes in laws
Last 7 days, Manhattan Borough President Mark Levine termed on the U.S. Treasury Department to add names to the U.S. sanctions record so much more authentic estate in New York Town connected to Russian oligarchs can be seized. By means of present-day loopholes in legislation, these oligarchs are allowed to transfer prosperity to households and good friends devoid of retribution. It’s approximated that there is at least $12 trillion tucked away in offshore accounts, in accordance to human legal rights group World Witness. In New York Metropolis alone, a total accounting of the serious estate holdings exceeds $1 billion in price, Levine said.
There is also issue far too among the Russian elites about access to cash in their bank accounts as major Wall Road money institutions slash ties to Moscow.
The famous Plaza Resort, a landmark 20-tale luxurious hotel and condominium apartment developing, in 2019. (Getty Illustrations or photos / Getty Photographs)
In neighboring New Jersey, Democratic Gov. Phil Murphy signed bipartisan laws Wednesday clearing the state treasury to develop a record of persons and companies with investments in Russia or Belarus as a way to stop Putin’s “cronies” from securing contracts, tax abatements or performing additional company with the condition.
A so-termed whisper listing, Lenz defined, means owners speak to realtors to make contact with opportunity purchasers in their rolodex privately and gage how much they would be inclined to pay back. Alternatively of formally listing their house for sale, accomplishing the paperwork and publicly disclosing inquiring price tag, whisper listings give sellers an added perception of privacy by averting acquiring pictures of their property on-line.
“It is really much extra challenging, time-consuming, and leaves an odd flavor in purchasers’ mouths as to why are we doing it this way? Why is this whisper mentioned?” Lenz reported of dealing with listings under the radar. “Specially in these periods, anyone wants a offer, but they’re so reticent to jump in.”
US Officers AND NYC LAWMAKERS Call ON RUSSIAN OLIGARCHS’ True ESTATE TO BE SEIZED
Lenz claimed she can only converse with respect to the 50 to 70 Russian-owned attributes her organization is handling, but these aren’t the only luxurious qualities out of the blue hitting the Manhattan market.
61 attributes
At least 61 houses have been place up for sale or have had a cost update or some other transform in Central Park South within the last 7 days, a next real estate resource told FOX Organization.
Central Park South, a micro-neighborhood just a few blocks along 59th Street, amongst Fifth Avenue and Columbus Circle, has prolonged attracted rich Russians and other global buyers. At One particular Central Park South, the constructing famously recognized as The Plaza, there have been at minimum 16 new or up-to-date listings considering that the invasion of Ukraine began Feb. 24.
These qualities usually variety in rate from $1 million to $28 million.
That does not necessarily mean all the new or updated listings are owned by Russians. If a Russian proprietor is putting a residence up at a noticeably better benefit to make certain faster than typical motion, that can prompt other sellers to fall in line and compete with the new pricing, the resource said.
Manhattan’s luxurious actual estate market place has prolonged relied on international expense. Due to the fact she’s been in the small business, Lenz reported, it was initial the Japanese who arrived in the 1980s searching to obtain up luxury properties. Even the Financial institution of Japan obtained houses around the Museum Tower area, she reported.
Then, about 10 to 15 a long time in the past, wealthy Russians flooded New York City soon after the Soviet Union fell and largely acquired houses all over Billionaire’s Row and more mature luxury properties in the same neighborhood.
Then Russians became a significantly less frequent clientele in New York City’s luxurious true estate market place. And, in recent several years, there’s been much more of an influx of rich buyers from China, Taiwan and Hong Kong.
“They variety of went peaceful,” Lenz reported of the influx of wealthy Russian customers. “And they are only out there now simply because they want to liquidate forward of a disaster.”
“If you talk to me to guess since naturally not everybody’s telling you almost everything they’re considering, nor ought to they,” she extra. “I feel that they’re extra afraid of what is actually coming in the long term than it is any absolute knowledge of what is coming in the upcoming. They are hoping to get forward of it.”
‘Secretive patterns’
At the state amount in New York, two Democratic state lawmakers, Sen. Brad Hoylman and Assemblywoman Emily Gallagher, who symbolize Manhattan and Brooklyn, respectively, released legislation previous 7 days aimed at combating “secretive patterns of actual estate expense in New York Town among international elites as a result of anonymous LLCs and the use of New York LLCs by rich Russian nationals in New York point out to obtain luxurious households.”
The invoice would have to have LLCs to disclose their entrepreneurs to the New York Office of Point out and would build a community databases of which LLCs share widespread possession. It asserts that nameless LLC landlords have brought about code violations for decades in the Hudson Valley, prompting a 2019 point out senate investigation, as very well as tens of thousands of pandemic-era rental assistance programs to be unnecessarily delayed.
GET FOX Business enterprise ON THE GO BY CLICKING Right here
But the use of LLCs to invest in large-conclude true estate is a common practice, so it is really unclear if the proposed laws will achieve any traction.
“Each individual one purchaser we’ve at any time had established a new LLC for just about every and every home. I imagine the majority of rich persons invest in an LLC for every single rationale in the entire world,” Lenz stated. “We would welcome any transparency to every transaction. We individually go the further lawn to make certain we know who we’re dealing with. Even even though we do not have (know-your-shopper) procedures in genuine estate like they do in banking – have to vet everybody they talked to – we really do not have to, but we do.”
“We will not want to chat to any person we think is unsavory,” she extra. “It’s not simply because they’re unsavory, it’s because they’re scared of becoming tied to this circumstance.”
FOX Business’ Sumner Park contributed to this report.
Vladimir Putin (Getty/Illustration by Kevin Rebong for The True Offer)
Russian President Vladimir Putin’s invasion of Ukraine has established the phase for international economic turmoil and sanctions whose impacts will stretch to the U.S. serious estate marketplace.
The invasion has led the U.S. federal government to join its allies in shifting to freeze the assets of Russian elites near to Putin, and will probable gradual real estate expenditure from each international locations.
The full extent of the sanctions is continue to currently being established. Russian and Ukrainian buyers represent a smaller section of the all round U.S. true estate current market, but authorities agree that it will turn out to be extra challenging for numerous Russians to do company in the U.S. People complications will rely on the way in which the global community pursues more sanctions, but bank loan approvals and residence income could be delayed as the crisis intensifies.
Any transaction involving Russian oligarchs — who have ordered some of the priciest qualities in Manhattan and Miami — will grow to be significantly a lot more tough, specialists say.
“If there is will need for a payment to or from a Russian oligarch in the U.S. or the EU, that will be massively problematic,” claimed Ross Delston, an lawyer and independent anti-funds laundering skilled.
Russians’ serious estate freeze
The belongings of Russian officials discovered by the U.S. as getting ties to or supporting the invasion will be blocked and frozen, in accordance to attorney Harold E. Patricoff Jr. This could signify just about anything from actual estate to cars and trucks, yachts or jewellery.
The Treasury Department’s Office of Foreign Belongings Manage (OFAC) is compiling a listing of Specifically Selected Nationals of Russia and Belarus who will be focused by sanctions.
The Magnitsky Act — named for tax attorney Sergei Magnitsky, who died in a Russian jail in 2009 right after alleging popular corruption by government officials — authorizes the U.S. authorities to impose sanctions on individuals it perceives to be human legal rights offenders, together with freezing the American belongings of persons on the SDN record.
“There are a good deal of rich Russians and wealthy Ukrainians and their names are on the Magnitsky record and their belongings are blocked in the U.S.,” explained Patricoff, a Duane Morris legal professional focusing on intercontinental disputes. “If the asset is blocked by OFAC … it are unable to be bought, mortgaged and it is topic to forfeiture, which signifies the govt could speedily just take it absent and the federal government could offer it.”
In 2019, the Trump administration froze Venezuelan point out-owned assets in a thrust to oust socialist President Nicolás Maduro.
An asset freeze only applies to all those near to Putin, probably a tiny subset of Russian traders in the U.S., but financial institutions are possible to position any bargains with Russian organizations or buyers less than a microscope.
“In any form of transaction, standard thanks diligence is going to be heightened,” reported Andrew Ittleman, an anti-funds laundering professional and founding companion of the Miami legislation company Fuerst Ittleman David & Joseph.
The U.S. is also imposing sanctions on Russian point out-owned banking institutions, which include the country’s major, Sberbank, as perfectly as its subsidiaries, forcing American banking institutions to sever ties in just 30 days in an energy to cripple the Russian monetary system and force it into backing out of the invasion.
“Apparently, a lot of the money held in Sberbank is held in U.S. bucks, but in order to process it, it would have to go by means of a U.S. account,” claimed lawyer Aleksey Shtivelman of Shutts & Bowen, who focuses on international disputes. “That is what the authorities is seeking to cease.”
The deterioration of U.S.-Russian relations could also guide to Russia acquiring kicked out of the Society for Globally Interbank Fiscal Telecommunication, or SWIFT, a messaging community that facilitates monetary transactions concerning banking institutions about the entire world. President Joe Biden has hence significantly resisted slicing Russia off from the network, citing apprehension from European allies.
“If SWIFT will be taken absent from them, and with any luck , that happens these days, that would complicate any kind of transaction,” reported Natalia Raphael, a Moscow-born actual estate agent with the Keyes Organization who caters to Russian and Ukrainian customers in South Florida. “If they cannot use wires, if they are not able to transfer funds freely as they have been so significantly, that complicates business fairly a little bit.”
Future sanctions could also make it far more complicated for Russians to make payments, Ittleman added.
“There is a serious credit history risk that you didn’t have prior to,” he claimed. “The sanctions condition is so fluid. You could be non-sanctioned right now, but that could change tomorrow.”
From Sunny Isles to Manhattan
Russia’s annexation of Crimea in 2014 “crippled the Russian market” in Miami, stated Craig Studnicky, CEO of Aventura, Florida-primarily based brokerage ISG.
“Since then, the populace of Russian purchasers in Sunny Isles is about 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} what it used to be,” Studnicky explained.
Russian investment and interest has fallen dramatically in recent several years. Between August 2017 and July 2018, it represented just 2 percent of the overseas investment decision current market in Miami, in accordance to a National Association of Realtors report.
The invasion of Ukraine has by now prompted some specials to be put on keep in South Florida, brokers said. 1 consumer of an $870,000 condominium, concerned about the conflict’s result on the stock current market, canceled their give, explained Mike Pappas, proprietor of the Keyes Enterprise, a single of the most significant brokerages in South Florida.
“I consider sure people today will hesitate. There is more than just the war,” Pappas claimed. “It’s the complexity of the war, the interest rate increase and the stock market adjustment.”
In New York, Russian consumers have designed some eye-popping household buys.
Billionaire Roman Abramovich paid $96 million in between 2015 and 2017 for four qualities on Manhattan’s East 75th Avenue, with plans to make a mega-residence right before marketing the properties to his ex-spouse in 2018 for $91 million.
Oligarchs’ buys drew the ire of previous mayor Monthly bill de Blasio all through the investigation into Russian interference in the 2016 U.S. presidential election. De Blasio complained that these oligarchs had basically stolen their country’s prosperity and funneled it into New York City real estate, but he experienced minimal recourse to do everything about it.
“It manifests in this article as individuals with a good deal of sick-gotten gains getting a ton of property — I don’t like it a person little bit,” De Blasio claimed in 2017.
And on Friday, Manhattan Borough President instructed in a tweet that oligarchs who have invested in New York Town real estate must have their property expropriated.
“For years Manhattan has been one of the most well known harmless harbors for Russian oligarchs to park their money, in particular by means of extremely-higher-conclusion residences,” he wrote. “It’s time to begin seizing their attributes. #SupportUkraine.”
A getting chance?
In addition to sanctions, there will be some logistical difficulties for Russians wanting to spend in The united states.
Lawyer Galina Urman, who focuses on immigration and EB-5 matters, claimed she is hearing from U.S. shoppers who want to deliver their household customers in Russia and Ukraine to The us.
Urman, who was born in the previous U.S.S.R., stated a slowdown in financial commitment has resulted because the pandemic began. “I do anticipate that the slowdown will proceed thanks to what is going on in Ukraine,” she claimed.
“It’s just the logistics of dollars transfers and traveling here that will be additional challenging for them to pick homes,” mentioned Raphael, of the Keyes Corporation. “They can absolutely obtain homes in excess of FaceTime, but not everybody would like to do that.”
Others say that Russians and Ukrainians looking for a secure spot to park their cash could be drawn to U.S. serious estate. Overseas curiosity in American property tends to maximize in situations of political instability overseas.
“We’ve been viewing a considerably better degree of fascination in offers from Ukraine and Russia in anticipation of the war” more than the previous two months, mentioned South Florida broker Mariana Shulga, who is also Ukrainian. “Between Covid and now the war, they realize the time is now.”
Cindy Scholz, a broker with Compass, explained that such conflicts have triggered additional fascination in attributes in New York and — more just lately, as Covid-19 set a spotlight on the location — in the Hamptons.
“These investors are likely to want to get their dollars out of their nations around the world and bring it in excess of to what’s identified as 1 of the safest investments, which is investing in the Hamptons and in New York City,” Scholz reported. “New York Town is generally seen as a seriously secure parking spot for funds.”
Ashkenazy Acquisition Corporation’s Ben Ashkenazy; Clipper Equity’s David Bistricer; Fetner’s Hal Fetner; L+M Development Partners’s Ron Moelis (Google Maps, Ashkenazy Acquisition Corporation, Fetner, Clipper Equity, L+M Development Partners)
From Ashkenazy Acquisition to ZG Capital, property investors raced to beat the clock and close on investment deals before the calendar flipped to 2022.
The bevy of sales helped breathe life into Manhattan’s investment sales market, which accounted for the most deals for the third straight week in the $10 million to $40 million range. The borough recorded 11 sales last week. Brooklyn saw six deals, Queens two and the Bronx one.
Twenty mid-market sales fetched a total of $370 million, outpacing even the prior week’s larger-than-usual $320 million.
Below are more details of the buzzer-beating deals recorded in late December, which hit city property records last week:
1. Ben Ashkenazy’s Ashkenazy Acquisition Corp. bought a 200,000-square-foot shopping center at 92-59 59th Avenue in Elmhurst, Queens, for $40.5 million. The purchase brings the property out of tenant JC Penney’s bankruptcy, during which trustee Glas Trust bought the building in April 2021 for $18.1 million
2. Fetner Properties bought a 2,850-square-foot lot at 270 West 96th Street on the Upper West Side from the NAACP for $16.8 million, and PGIM Real Estate bought the 2,500-square-foot parcel next door from the Salvation Army for $16.1 million. Fetner plans to develop a 150,000-square-foot, mixed-use building on West 96th Street, for which it received a $108 million loan from Wells Fargo.
The developer was also recently revealed as the seller of 625 residential units to Empire State Realty Trust as part of that firm’s pivot to the multifamily sector.
3. David Bistricer’s Clipper Equity bought a 23,000-square-foot development parcel at 1050 Pacific Street in Crown Heights, Brooklyn, for $26 million. The developer has yet to file construction plans for the site. Harry Daskal was the seller.
4. L+M Development Partners bought a 48,500-square-foot parcel at 888 Fountain Avenue in East New York, Brooklyn, for $25 million. The affordable housing developer plans to build a 15-story, mixed-use building at the site spanning 386,000 square feet. Empire State Development sold the land.
5. California-based IRA Capital bought a 12,600-square-foot medical building at 3417 Kings Highway in Flatlands, Brooklyn, for $22.7 million. The seller was Fieber Group. The NewYork-Presbyterian Medical Group Brooklyn leases the building.
6. Steve Croman sold a 17-unit, 19,700-square-foot apartment building at 182-184 Stanton Street on the Lower East Side for $21.3 million. The buyer was Targo Capital Partners. A notorious landlord and ex-convict, Croman is seeking around $120 million for 14 of his apartment buildings in and around the East Village.
7. Manuel Glas’s GLAS Architects bought a 9,350-square-foot, mixed-use building and a 10,500-square-foot warehouse at 88 and 90 White Street, respectively, in Chinatown for $20.5 million. The O’Kane family of Hugh O’Kane Electric Company sold the buildings.
8. Chicago-based private equity firm L3 Capital bought mixed-use buildings spanning a combined 8,700 square feet at 200 and 202 Bedford Avenue in Williamsburg, Brooklyn, for $20.5 million. Robert Li was the seller.
9. Houston-based Crest Investment bought a 14,855-square-foot commercial condo unit at 100 East 53rd Street in Midtown for $20.1 million. Vanke U.S., a subsidiary of China’s largest residential development firm, was the seller. Aby Rosen and Michael Fuchs’s RFR has battled Vanke U.S. over financing at the building.
10. Craig Policastro sold a 15,000-square-foot warehouse at 444 West 36th Street in Hudson Yards for $15 million. Limited liability company EX ZDJ 36 was the buyer.
11. Morris Weinberg bought an 86,000-square-foot apartment building with 84 units at 100 East 21st Street in Flatbush, Brooklyn, for $14.8 million. Jacob Hager was the seller.
12. Alma Realty Corp bought a 60,000-square-foot apartment building with 79 units at 165 Bennett Avenue in Washington Heights for $14.6 million. Lee Krantzow was the seller.
13. Jason Fishkind bought a 10,500-square-foot retail building at 2535 Webster Avenue in Fordham, the Bronx, for $13.8 million. Transworld Equities was the buyer.
14. David Kaye and Joe Listhaus’s Rockledge, in partnership with PH Realty Capital and L3C Capital Partners, bought three apartment buildings spanning 96,060-square-feet with a combined 100 units at 617, 623 and 629 West 170th Street in Washington Heights for $13.2 million. The seller was Adrian Longo. Justin Conway of Besen Partners brokered the sale.
15. Daniel Kroll bought a 19,250-square-foot condo building at 1027-1035 Cortelyou Road in Ditmas Park, Brooklyn, for $12.8 million through limited liability company MKFIT1. The seller was Daniel Cohen through two limited liability companies.
16. Kaled Management bought a 3,500-square-foot, mixed-use building at 54 Third Avenue in the East Village for $12 million. The Hyun family sold the building.
17. Norse Realty bought a 10,200-square-foot retail building at 37-60 82nd Street in Jackson Heights, Queens, for $11.8 million. Ponce Bank was the seller.
20. Benjamin Shaoul’s Magnum Real Estate Group sold a 4,000-square-foot residential building at 81 Charles Street in the West Village for $10.2 million. Houston-based Northern Trust was the buyer.