Real estate housing market in 2023 could lead to drop in home prices

Real estate housing market in 2023 could lead to drop in home prices

Goldman Sachs makes a bold housing market call

Goldman Sachs makes a bold housing market call

The U.S. housing market might finally be nearing the bottom. At least that’s according to Goldman Sachs.

Just two weeks after Goldman Sachs downgraded its outlook for the U.S. housing market in a paper titled Getting Worse Before Getting Better, the investment bank reversed course on Jan. 23 in a paper titled 2023 Housing Outlook: Finding a Trough.

Instead of U.S. home prices falling 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, which was their Jan. 10 prediction, researchers at the investment bank now expect national home prices to end 2023 down just 2.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

By the time U.S. home prices bottom out this summer, Goldman Sachs says, national home prices will be down around 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its June 2022 peak. Previously, Goldman Sachs researchers were expecting that peak-to-trough decline to come in closer to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

“We expect a peak-to-trough decline in national home prices of roughly 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and for prices to stop declining around midyear. On a regional basis, we project larger declines across the Pacific Coast and Southwest regions—which have seen the largest increases in inventory on average—and more modest declines across the Mid-Atlantic and Midwest—which have maintained greater affordability over the past couple years,” wrote the researchers.

Why the upward revision? Recent data, Goldman Sachs says, points to an uptick in homebuyer demand.

“Home sales appear set to turn higher. Mortgage purchase applications have averaged 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} above their October trough so far in January, and survey-based measures of purchasing intentions have rebounded sharply,” wrote Goldman Sachs researchers.

To get a better idea of where both national and regional home prices might be headed, Fortune asked Goldman Sachs to provide us with its full forecast.

Let’s take a look.

Unlike KPMG, Goldman Sachs does not expect a double-digit home price correction. The investment bank says there are three reasons why a steeper correction won’t happen this cycle.

“First, the rapid buildup of untapped home equity over the last couple years means that even if prices declined more sharply than we expect, only a small share of mortgage borrowers would be underwater,” wrote Goldman Sachs researchers. “Second, over 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of outstanding mortgages are fixed rate, meaning that the rise in interest rates will not lead to a spike in debt service costs for most homeowners. And third, household balance sheets remain strong, with low aggregate leverage and considerable remaining pent-up savings from the COVID-19 pandemic.”

Those three factors, Goldman Sachs says, should prevent the potential “for the cascading defaults that contributed to the post-GFC drawdown.” That previous correction—after the 2007–2008 Global Financial Crisis (GFC), which saw U.S. home prices fall 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} between 2007 and 2012—is four times greater than the 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} peak-to-trough decline Goldman Sachs is predicting this time around.

While Goldman Sachs expects national home prices to fall 2.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, not every market will be so lucky.

In 2023, Goldman Sachs expects double-digit home price declines only in overheated markets like Austin (-16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Francisco (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Diego (-13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Phoenix (-13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Denver (-11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Seattle (-11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Tampa (-11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Las Vegas (-11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). On the positive side, Goldman Sachs expects home prices will rise in markets like Baltimore (+0.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Miami (+0.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

“Metro-level trends will be dictated by a tug-of-war between housing demand and supply. MSAs [metros] with stronger affordability like Chicago and Philadelphia—for which payments on new mortgages only cost roughly a quarter of monthly income—should see smaller home price declines than metros with poor affordability like many cities in the West—some of which are seeing mortgage payments claim three-quarters of monthly income,” wrote Goldman Sachs researchers in their latest note.

On the mortgage rate front, Goldman Sachs says buyers shouldn’t expect much relief. By the end of 2023, the investment bank expects the average 30-year fixed mortgage rate will tick back up to 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. As of Thursday, the average 30-year fixed mortgage rate sits at 6.09{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Newsletter-Gold-Line

Looking for more housing predictions? Follow me on Twitter at @NewsLambert.

Learn how to navigate and strengthen trust in your business with The Trust Factor, a weekly newsletter examining what leaders need to succeed. Sign up here.

6 leading real estate economists and pros on what to expect from the housing market this winter

6 leading real estate economists and pros on what to expect from the housing market this winter


Getty Photos

Some aspiring homebuyers are in for some substantially-essential reduction. “Right now may well appear additional desirable to some prospective buyers mainly because, not too long ago, the housing market place has been cooling. Charges are dropping in a lot of locations, housing offer is increasing, sellers are featuring more concessions and property finance loan charges are falling,” suggests Jacob Channel, senior economist at LendingTree. (See the greatest property finance loan charges you may perhaps get now listed here.)

But no doubt, following swift escalations in household price ranges and mortgage loan fees in the past couple yrs (though both of those have eased just lately), numerous purchasers are cautious of what is to appear. So we questioned economists and true estate execs for their housing marketplace predictions this winter. 

Prediction 1: Property finance loan costs will “continue their downward trek”

“With the Fed switching to a smaller sized charge hike in February, house loan prices will go on their downward trek and a decrease home finance loan rate enhances affordability, bringing far more prospective buyers back to the sector,” suggests Nadia Evangelou, senior economist and director of real estate exploration at the Nationwide Affiliation of Realtors (NAR).

For his section, Channel also says decrease fees also may provide at least some consumers again. “There may possibly be additional purchaser demand from customers assuming prices go on to fall, or at the really the very least really do not get started climbing once again, but it does not seem like there’s a high chance that demand will dramatically rise back again to wherever it was at the begin of final 12 months. All in all, February’s housing sector will probable remain far more pleasant to purchasers than it was just a handful of months in the past,” suggests Channel.

Kate Wooden, household qualified at NerdWallet, gives a comparable sentiment: “Buyers might be additional determined if fees show up to stabilize and people who ended up priced out when premiums rapidly elevated final fall might be keen to give dwelling acquiring an additional shot.”

Prediction 2: Household value gains will sluggish even further more

Realtor.com facts reveals that the expansion of median inquiring selling prices for residences nationwide eased again into solitary-digits in December for the to start with time in 12 months and just about held that speed shifting into January.

“The milestone of single-digit rate development is genuinely a continuation of the moderation that began in the summer season when rates had been increasing at a rate of 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months more than yr,” suggests Danielle Hale, chief economist at Realtor.com. The report reveals that the median rate of homes for sale has increased by 8.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} each year in January, which is somewhat fewer than December’s expansion rate with the national median record value remaining stable at $400,000 in January, down from a history high of $449,000 in June.

Hope even slower progress this month, suggests Evangelou. “Home cost gains will slow even more in February. Home loan prices are last but not least relocating down, easing affordability, but several purchasers continue on to be priced out of the current market, particularly initially time potential buyers,” says Evangelou.

That mentioned, rate alterations will change involving markets. “Markets with the greatest imbalance amongst supply and desire will see increased softness in prices, even though for the majority of other folks it is far more a leveling out in price ranges,” states Greg McBride, chief financial analyst at Bankrate. 

Prediction 3: Buyers have a lot more place to negotiate

Hale suggests: “It will not be all annoyance for purchasers. A surging selection of houses for sale might not signify falling  household costs, but it is enabling potential buyers to acquire back a evaluate of negotiating ability and together with a extended time on market place compared to a year ago, prospective buyers are additional likely to see homes with a record price tag that has been decreased down below original inquiring value,” says Hale.

Prediction 4: The market place is on a sluggish route to normalcy

“The housing sector is continuing its return back to a extra regular-on the lookout industry following the pandemic-fueled frenzy. We are far from out of the woods with the affordability disaster that has been weighing heavily on dwelling product sales, but we are beginning to see some green shoots pushing up as price ranges and mortgage loan costs have fallen. That dip in mortgage loan costs has started to entice renewed desire from customers and gross sales are climbing again when compared to very last year, but need stays considerably reduced than the past two years,” states Nicole Bachaud, senior economist at Zillow.

The guidance, suggestions or rankings expressed in this post are individuals of MarketWatch Picks, and have not been reviewed or endorsed by our business associates.

Is the housing market about to crash? Here’s what experts say

Is the housing market about to crash? Here’s what experts say

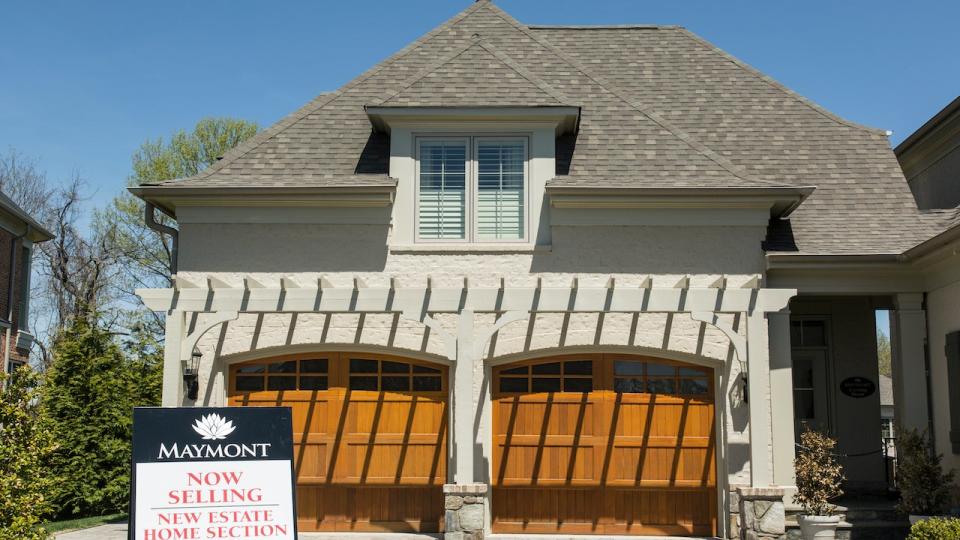
is the housing market about to crash? - the two-car garage and front door of a suburban home, with a maymont

Benjamin C. Tankersley/For The Washington Post via Getty Images

After a record-breaking run that saw mortgage rates plunge to all-time lows and home prices soar to new highs, the U.S. housing market is finally slowing. Home sales had declined for 11 consecutive months as of December 2022, and home values seem to have peaked.

While demand and price gains are cooling, any correction is likely to be a modest one, housing economists and analysts say. No one expects price drops on the scale of the declines experienced during the Great Recession.

Rob Dietz, chief economist at the National Association of Home Builders, sums up the consensus among housing experts: “We’re thinking this is going to be a moderate downturn,” he says.

The real estate party raged on longer than anyone expected. The National Association of Realtors reported that median prices in the spring of 2022 topped $400,000 for the first time ever. Even after a recent retreat, prices are up a robust 32 percent since the coronavirus pandemic began in March 2020, according to NAR data.

Now, bidding wars have largely faded, inventories are loosening and the feeling of frothiness is gone. “The market is clearly turning,” says NAR chief economist Lawrence Yun.

Is the housing market going to crash?

The last time the U.S. housing market looked so frothy was back in 2005 to 2007. Then home values crashed, with disastrous consequences. When the real estate bubble burst, the global economy plunged into the deepest downturn since the Great Depression.

Now that the housing boom is threatened by soaring mortgage rates and a potential recession, buyers and homeowners are asking a familiar question: Is the housing market so hot that it’s about to crash?

Housing economists agree that prices could fall, but the decline won’t be as severe as the one homeowners experienced during the Great Recession. One obvious difference between now and then is that homeowners’ personal balance sheets are much stronger today than they were 15 years ago. The typical homeowner with a mortgage has stellar credit, a ton of equity and a fixed-rate mortgage locked in at a rate well below 5 percent. So no foreclosure crisis looms.

“The wild ride known as the U.S. housing market slowed dramatically in the fall of 2022, as mortgage rates surged and home prices remained high,” says Molly Boesel, principal economist at CoreLogic. “Home sales started strong in early 2022 but took a nosedive later in the year. On the plus side, generous amounts of home equity will protect many borrowers from experiencing the type of foreclosure activity seen during the Great Recession.”

What’s more, builders remember the Great Recession all too well, and they’ve been cautious about their pace of construction. The result is an ongoing shortage of homes for sale.

“We simply don’t have enough inventory,” Yun says. “Will some markets see a price decline? Yes,” he says. “[But] with the supply not being there, the repeat of a 30 percent price decline is highly, highly unlikely.”

Lightbulb

Key housing market statistics

  • A total of 30,822 U.S. homes had foreclosure filings — default notices, scheduled auctions or bank repossessions — as of December 2022, according to ATTOM Data Solutions.

  • South Carolina had the highest foreclosure rate of any state in December, at one foreclosure filing for every 2,301 housing units, according to ATTOM. It was followed by New Jersey, where one in every 2,378 homes were in some stage of foreclosure.

  • Lenders repossessed 3,663 U.S. properties through completed foreclosures — known as “real estate owned,” or REO — in December 2022. Altogether, 42,854 properties were repossessed in 2022, according to ATTOM.

  • Home sales fell 34 percent from December 2021 to December 2022, the National Association of Realtors says. The median sale price in December 2022 was $366,900.

  • Existing home sales for 2022 totaled just over 5 million, per NAR — down 17.8 percent from 2021.

Existing home prices

For many months, economists have been predicting that the housing market would eventually cool as home values become a victim of their own success. Home prices have risen far more quickly than incomes, creating an affordability squeeze, and mortgage rates doubled since August 2021, before starting to retreat a bit.

Experts say home prices could fall

“Most markets are going to experience price declines in the high single digits,” Dietz predicts. Home price declines of 8 to 9 percent would create some economic pain, to be sure. But this correction will be nothing like the utter collapse of property prices during the Great Recession, when some housing markets experienced a 50 percent cratering of values.

Rick Sharga, executive VP of market intelligence at ATTOM Data Solutions, expects declines of 5 percent. “It’s almost inevitable we’re going to see home prices drop,” he says.

Yun says high-priced regions such as California are most vulnerable to a downturn in prices. The Midwest, on the other hand, is unlikely to see a decline in home prices. Overall, he expects national prices to remain flat next year.

5 reasons the housing market is not about to crash

Housing economists point to five compelling reasons that no crash is imminent.

  1. Inventories are still very low: The National Association of Realtors says there was a 2.9-month supply of homes for sale in December. In February, that figure was as low as a tiny 2.0-month supply. This ongoing lack of inventory explains why many buyers still have little choice but to bid up prices. And it also indicates that the supply-and-demand equation simply won’t allow a price crash in the near future.

  2. Builders didn’t build quickly enough to meet demand: Homebuilders pulled way back after the last crash, and they never fully ramped up to pre-2007 levels. Now, there’s no way for them to buy land and win regulatory approvals quickly enough to quench demand. While they are building as much as they can, a repeat of the overbuilding of 15 years ago looks unlikely. “The fundamental reason for the run-up in price is heightened demand and a lack of supply,” says Greg McBride, CFA, Bankrate’s chief financial analyst. “As builders bring more available homes to market, more homeowners decide to sell and prospective buyers get priced out of the market, supply and demand can come back into balance. It won’t happen overnight.”

  3. Demographic trends are creating new buyers: There’s strong demand for homes on many fronts. Many Americans who already owned homes decided during the pandemic that they needed bigger places, especially with the rise of working from home. Millennials are a huge group and in their prime buying years. And Hispanics are a young, growing demographic keen on homeownership.

  4. Lending standards remain strict: In 2007, “liar loans,” in which borrowers didn’t need to document their income, were common. Lenders offered mortgages to just about anyone, regardless of credit history or down payment size. Today, lenders impose tough standards on borrowers — and those who are getting a mortgage overwhelmingly have excellent credit. The typical credit score for mortgage borrowers in the the third quarter of 2022 was a high 768, the Federal Reserve Bank of New York says. “If lending standards loosen and we go back to the wild, wild west days of 2004-2006, then that is a whole different animal,” says McBride. “If we start to see prices being bid up by the artificial buying power of loose lending standards, that’s when we worry about a crash.”

  5. Foreclosure activity is muted: In the years after the housing crash, millions of foreclosures flooded the housing market, depressing prices. That’s not the case now. Most homeowners have a comfortable equity cushion in their homes. Lenders weren’t filing default notices during the height of the pandemic, pushing foreclosures to record lows in 2020.

All of that adds up to a consensus: Yes, home prices are still pushing the bounds of affordability. But no, this boom shouldn’t end in bust.

FAQs

  • Actually, economists do not think it will. Housing economists point to five main reasons that the market will not crash anytime soon: low inventory, lack of new-construction housing, large amounts of new buyers, strict lending standards and a drop in foreclosures.

  • Home prices rose sharply for years. And while the heated market has cooled down, it’s not likely to experience an equally sharp drop soon. Greg McBride, CFA, Bankrate’s chief financial analyst, says a plateauing of prices is more likely than a steep fall. Matthew Pointon, senior property economist at Capital Economics, also expects a slowdown rather than a freefall, predicting a 5 percent drop by mid-2023.

  • It depends on how much money you earn versus how much you pay out in debts and expenses each month. Many financial advisors recommend the 28/36 percent rule of home affordability, which states that you should spend no more than 28 percent of your gross monthly income on housing expenses, and no more than 36 percent on total debt. Bankrate’s home affordability calculator can help you crunch the numbers.

  • Different minimum credit scores are required by lenders for different types of mortgages. However, a score of at least 620 is typically required for a conventional loan — and if it’s as high as 740, all the better. Successful borrowers today tend to have outstanding credit, with a median score of 768.

[sc code=”alpine_collapse”]
China’s real estate crisis isn’t over yet, IMF says

China’s real estate crisis isn’t over yet, IMF says

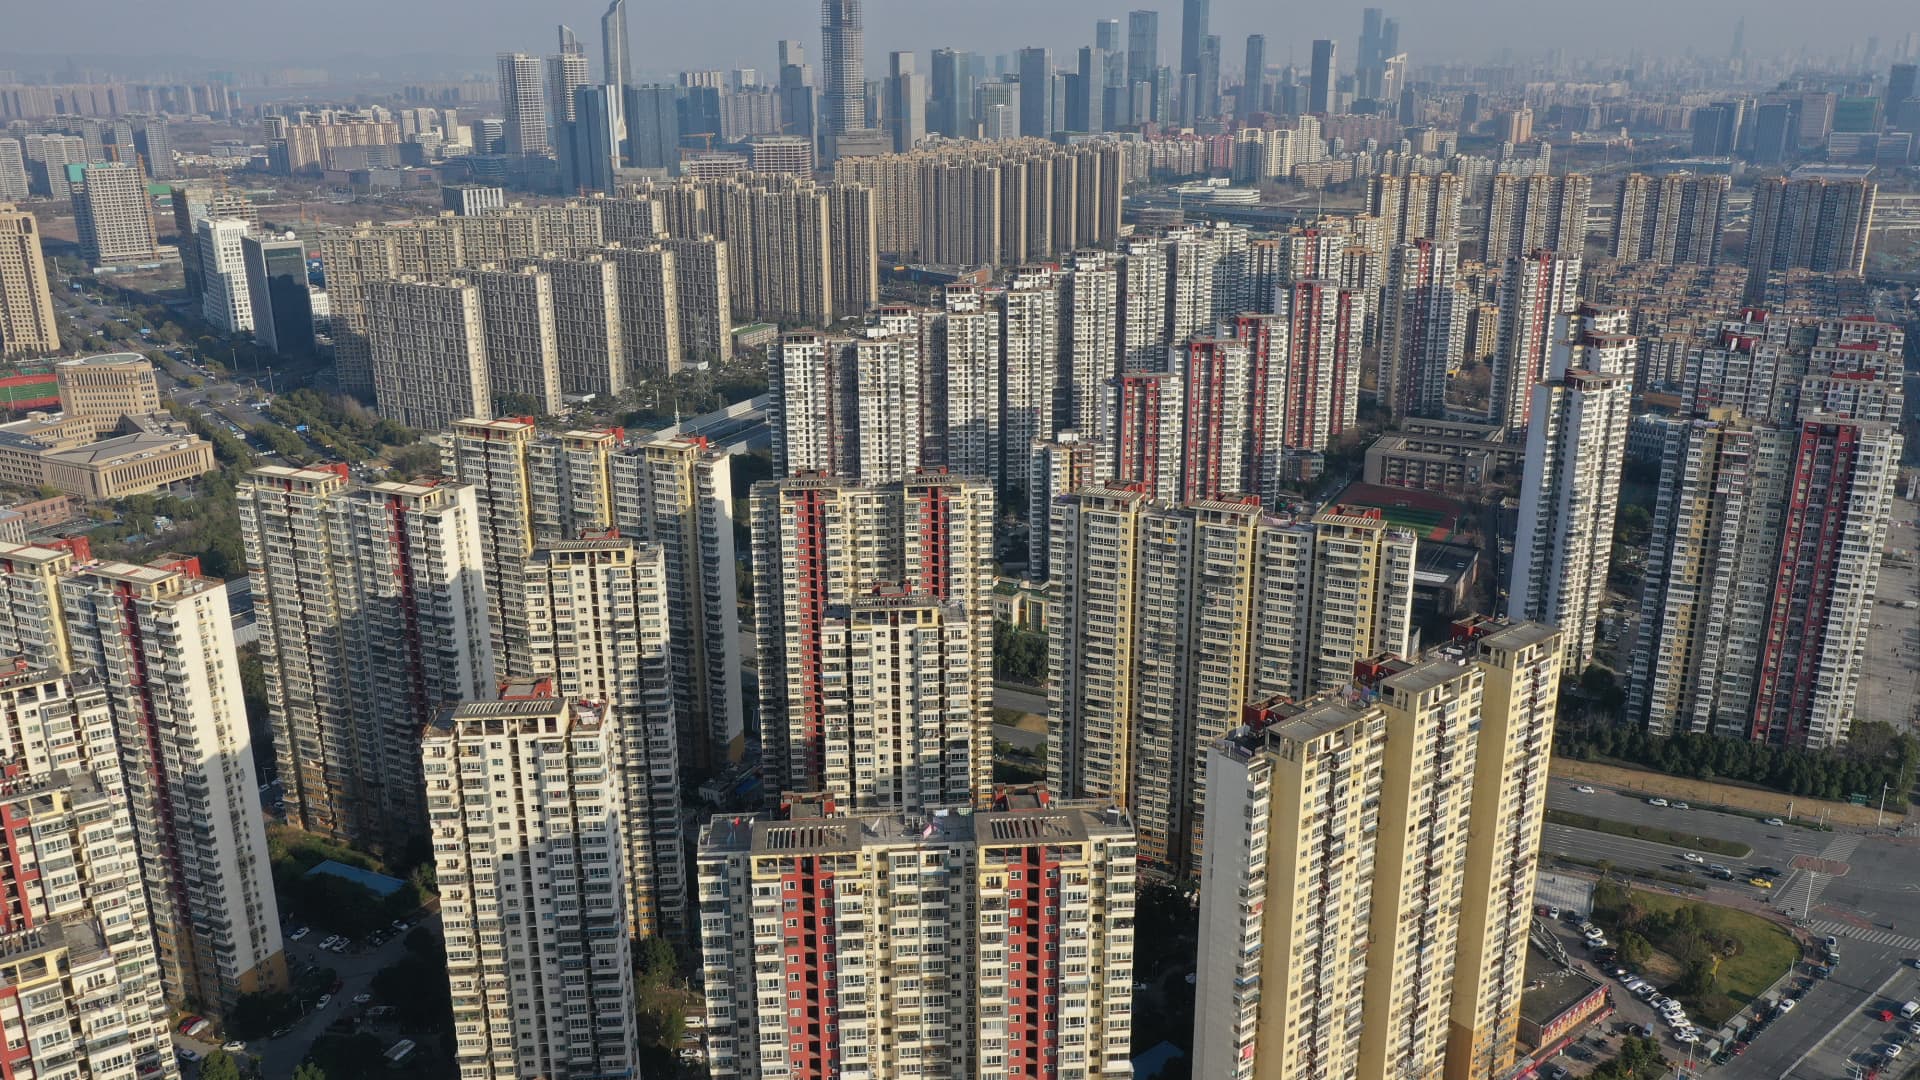
China’s serious estate current market has slumped in the past two years after Beijing cracked down on developers’ substantial reliance on financial debt for progress.

Long run Publishing | Foreseeable future Publishing | Getty Pictures

BEIJING — China demands to do extra in buy to correct its true estate issues, the Global Monetary Fund stated Friday.

The assets market place contributes to about a quarter of China’s GDP and has been a drag on expansion, particularly considering that Beijing cracked down on developers’ substantial reliance on personal debt in 2020.

Chinese authorities commenced to relieve constraints on funding for the sector in excess of the previous several months.

“Authorities’ the latest coverage actions are welcome, but in our look at extra action will be wanted in purchase to conclusion the real estate crisis,” Thomas Helbling, deputy director in the IMF’s Asia Pacific Office, stated in a briefing.

“If you glance at the actions, a good deal of them handle funding problems for the developers that are still in reasonably superior economical health, so that will aid,” he added in an job interview with CNBC. “But the difficulties of the property developers’ dealing with severe economic difficulties are not however dealt with. The issue of the large inventory of unfinished housing more broadly is not but addressed.”

China is slowly coming back, Dassault Systemes CEO says

Flats in China are generally bought to homebuyers just before completion. Covid and economic issues slowed construction so significantly that some homebuyers halted their home loan payments final summertime in protest.

Chinese authorities subsequently emphasized the will need to assistance builders complete developing these pre-bought apartments. Still, household ground area offered in China dropped by practically 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} past calendar year, though true estate investment fell by 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, according to formal figures.

“I assume it would be practical to point to a way out and … how the restructuring could be accomplished and who will soak up losses if there are any losses,” Helbling stated. He also called for more steps to address the large stock of unfinished residences.

Read more about China from CNBC Professional

“If not the sector will go on to slump and remain a threat and also constrain homes that are overexposed to the property sector, and will have dollars tied up and their discounts tied up which will be a handicap for the broader financial restoration,” he stated.

Helbling declined to name a particular timeframe in just which authorities necessary to act prior to the circumstance bought a great deal worse.

“The faster you deal with draw back challenges the improved.”

China claims it truly is not a crisis

The IMF assessment was aspect of the organization’s most current report on China, subsequent yearly conversations with Chinese officers that finished in November.

The officials pushed back on the IMF’s serious estate evaluation, according to a assertion in the IMF report by Zhengxin Zhang, govt director for People’s Republic of China, and Xuefei Bai, senior advisor to the government director, dated Jan. 12.

China’s assets market place has typically operated effortlessly and “is not in a ‘crisis’ condition,” the assertion explained, casting the sector’s problem as “a natural evolution of ‘deleveraging and destocking’ in the past couple of many years.”

“The relevant pitfalls are nearby and only issue personal corporations, and their influence on the relaxation of the earth has been somewhat compact,” the central lender associates claimed. Hunting in advance, the Chinese aspect explained they would get the job done towards guaranteeing the delivery of accomplished residences, and merging developers.

Examine more about China from CNBC Professional

“The sector’s contraction is also primary to strains in nearby governments. Slipping land sale revenues have diminished their fiscal capacity at the same time as community federal government financing vehicles (LGFVs) have also substantially amplified land buys.”

The IMF on Monday lifted its worldwide progress anticipations for the year thanks to greater-than-envisioned growth in big international locations late final 12 months, softening inflationary pressures and the stop of China’s Covid controls.

The new 2.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} forecast for the globe is .2 proportion points better than anticipated in Oct. But it truly is nonetheless a slowdown from 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} progress in 2022.

For China, the IMF projects advancement of 5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this calendar year, more quickly than the 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} speed in 2022.

— CNBC’s Silvia Amaro contributed to this report.

Zillow ranks Cleveland second hottest real estate market in the U.S. for 2023

Zillow ranks Cleveland second hottest real estate market in the U.S. for 2023

CLEVELAND — It is no mystery that Cleveland rocks.

Just talk to anybody who life right here.

But our hometown is in the nationwide spotlight earning major marks when it will come to the actual estate market and people today wanting to purchase a residence.

Serious estate site “Zillow” just named the CLE a single of the hottest housing marketplaces in the United States.

Cleveland ranked range 2 in the top 10.

Charlotte nabbed the range 1 location.

Pittsburgh took 3rd location (Check out out the comprehensive listing listed here: https://www.zillow.com/exploration/2023-most popular-marketplace-31982/).

In accordance to Zillow, the things behind the rankings consist of anticipated property price progress, projected change in operator-occupied households and task growth compared to new construction.

Nearby serious estate professionals say just obtaining the word out on a countrywide scale entices possible dwelling prospective buyers to invest and plant roots in Northeast Ohio.

Cleveland is also having main notice due to the fact the city presents all the facilities at a fraction of the cost of other big Metropolitan towns, according to gurus.

Generate around any Cleveland community, and you’ll most likely place just one “For Sale” signal after the following.

Even with financial uncertainty, the housing industry in Northeast Ohio carries on to entice prospective buyers.

Zillow appeared at purchaser demand from customers, envisioned home worth advancement and affordability when it compiled the 2023 rankings.

“I guess that is great for Cleveland, suitable?” Matt Stevens mentioned.

Berkshire Hathaway Stouffer Realty agent Sarah Halsey states the marketplace has definitely absent through a changeover time period, but the last 8 many years have been continually chaotic, whether you’re a initially-time purchaser, transient or looking to downsize your space as a retiree.

“I feel that people are continue to intrigued in the Cleveland marketplace for a couple distinctive factors. A single becoming the charge of living. Two, the position prospects. And three, the new housing developments.”

Halsey claims the market place has progressed and designed additional of an even, good enjoying discipline for everyone more than the very last year.

It’s not like it was in the course of peak pandemic, exactly where realtors ended up getting a number of features $50 thousand pounds around asking cost and waiving house inspections, Halsey said.

Halsey states curiosity costs have also adjusted the match.

“Fees a calendar year or so in the past, even fewer than a year back ended up about 2-3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. We have not witnessed low fees like that at any time, really. And now fees are about 5-6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9},” Halsey explained.

And as for why so quite a few men and women are hunting to settle down listed here as opposed to a additional year-spherical hotter climate–

“I comprehend men and women require affordability, and I would live some place with my spouse and children that was like this,” Barbara Cossey explained.

Halsey says despite the fact that rent selling prices are high just about everywhere–they’re manageable right here.

And if you obtain a house, your mortgage—will likely be much less expensive.

“The expense of living in Cleveland is drastically fewer than other spots. It is really 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} under the national common, and rentals are 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down below the Ohio common, getting a massive city by a large physique of water,” Halsey reported.

The median listing selling price for a property in Cleveland is all-around $110-$115 thousand dollars.

Serious estate officers say it is engaging to initially-time residence prospective buyers.

As for the coolest or worst marketplaces to get a home– Zillow ranked San Jose, Minneapolis and Sacramento.