Is Real Estate a Good Career? a Laid Off, Houston Anchor Closed  Million As a New Realtor

Is Real Estate a Good Career? a Laid Off, Houston Anchor Closed $28 Million As a New Realtor

  • Lily Jang grew to become a authentic-estate agent in 2017 following performing typically as a broadcast-news anchor.
  • She obtained into authentic estate for the reason that she’d experienced lousy ordeals with brokers and preferred adaptable several hours.
  • To stand out to her customers, she presents social-media promotion, household staging, and Tv set placement.

In advance of she was a effective genuine-estate agent closing on just about $28 million in discounts in 2022, Lily Jang was a news anchor for KHOU-Television set in Houston.

She never would’ve still left the broadcasting world, she explained to Insider, had the Television set station not gone through a management improve and subsequent layoffs.

“You generally know in the back of your head this could come about: New management arrives in, and they’re going to thoroughly clean house, and you could be a casualty — and that is exactly what took place to me,” she stated.

The blow was primarily difficult for her since a person of the key factors she moved to Houston was to choose treatment of her growing old moms and dads, particularly her father, who has Parkinson’s sickness. Contrary to other broadcasters who could select up and move to one more metropolis for a career, Jang wanted to continue to be and get treatment of her family members.

“That was the most devastating time in my everyday living. Anybody else would’ve springboarded to Chicago, New York, LA, or Miami, but I couldn’t,” Jang, who experienced labored in other states in advance of shifting to Texas, stated. “I sat in a corner and cried for two months, but I claimed to myself, ‘I’m going to have to pivot. I have to determine this out.'”

And determine it out she did — by the conclusion of her to start with 12 months at Keller Williams, she’d closed $8 million in serious-estate transactions and surpassed her income as a news anchor. In 2021, four several years soon after she received her begin, she made approximately $900,000 in gross earnings.

“I took my job as a information anchor, my advertising and marketing techniques, and leveraged anything I experienced and who I was, and I applied that in genuine estate,” Jang reported. “I created my journalism career on relationships, communication, and integrity, and I parlayed all that into my new vocation pretty seamlessly.”

Here is how she crafted a enterprise that’s thrived by social media and organic and natural advertising.

Earning the pivot

Jang’s fascination in true estate was spurred by her activities searching for homes.

“I experienced bought and bought residences in the previous, and I understood how very little my Realtor did for me,” Jang claimed. “I was like, ‘I can do this improved than you, and you’re not even advocating for me.'”

A different benefit, she extra, was the possibility to be her have boss and established her personal work several hours.

In 2017, immediately after paying out roughly a month accomplishing a six-portion on-line system with the Champions Faculty of Authentic Estate, Jang declared her career change on Facebook and immediately began receiving messages from outdated high-university mates and colleagues inquiring irrespective of whether she would choose on their listings. 3 months later, she had 3 houses in her portfolio — two of which ended up luxury properties priced at additional than $750,000.

Jang worked 80-hour months for the to start with six months.

“I bear in mind crying at the conclusion of some months from pure exhaustion,” she stated. “I realized that my company was entirely dependent on me acquiring a way to sector myself differently and on a greater system when there ended up tens of hundreds of other Realtors out there.”

Nowadays, Jang has discovered a better perform-lifetime harmony and has outsourced numerous features of her company, which include selecting a transaction coordinator to handle paperwork and a comprehensive-time certified assistant to assist in a variety of tasks.

Making use of social media and Tv to entice shoppers

Jang mentioned her exclusive strategy to offering assisted her establish a company entirely from referrals and organic queries from sellers, prospective buyers, buyers, renters, and fellow real-estate agents. For her shoppers, Jang supplies videos, residence staging, and Instagram exposure on her account, which has 35,000 followers.

“I have hardly ever created a one cold phone, and I’ve hardly ever knocked on any doors. My business is 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} referral from working day 1 and 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} social media,” she said. “My Tv set history gave me an organic and natural system of men and women who felt they realized me, trustworthy me, and required to operate with me.”

On social media, Jang walks by way of several of the wonderful, glossy features of a household but also points to instructional information that possible customers would want to pay focus to, like ceilings that have experienced former repair service get the job done, wall corners that give clues to the issue of a home’s basis, and other issues that indicate the structural integrity of a home.

Jang also shares on social media what she does off the clock, like her overseas travel and great eating. She reported this is underrated among real-estate agents, primarily when they want to do the job with luxurious clients, lots of of whom probable want enter on great eating places and journey locations.

“It reveals men and women all the levels of who I am, how I journey, what my hobbies are, and what authentic estate seems to be like in other areas of the globe,” she claimed. “People function with persons they like and sense most linked to.”

Jang has also been equipped to use her broadcasting background to her advantage, initially with a nearby phase identified as “Lily’s Listing” on KPRC, then, immediately after that was canceled since of Hurricane Harvey, a 30-moment genuine-estate demonstrate named “Property 2 Household with Lily Jang,” where by she functions house listings as very well as interviews with loan providers, builders, inside designers, and other true-estate gurus.

Jang’s connections and knowledge in the broadcasting planet served her url up with Jerry Martin, the now retired common supervisor of KPRC. He brainstormed several authentic-estate-display strategies with Jang in advance of landing on the principle for “Lily’s Checklist” following Jang showed him a video clip sample of what she had in mind.

“I believe I closed a few transactions in the limited six months we had been on the air,” she stated. “‘Lily’s List’ was just as important as social media for me in reaching prospective consumers.”

Promoting properties in the recent marketplace

When fluctuating fascination fees and slowing demand may make other true-estate brokers anxious, Jang is not much too worried about the alter of rate. She mentioned that even though stock is lower, she’s continue to looking at numerous offers on properties with essential features, these types of as great neighborhoods and the ideal value place. Jang’s tips to those purchasing in Houston is to often order a house zoned to dependable, effectively-rated faculties.

As for her confidence in how she’ll accomplish in a tighter, a lot more-aggressive marketplace, Jang mentioned she’s happy to flip a page on the wildness that 2021 and early 2022 introduced. She stated there was an inflow of “tens of hundreds of new” serious-estate brokers who benefited from historically lower curiosity fees, which created true-estate transactions more rapidly, simpler, and additional lucrative, but now periods are a lot harder.

“When the sector shifts like this and normalizes, there is certainly a systemic exodus of brokers for the reason that not all agents are making product sales they are employed to in get to make a living,” she reported. “The Realtors who benefited from a sturdy industry are now not making as much.

“They have dues to pay out without closings, so our industry has normalized and new brokers who received into the video game through the surge of document residence gross sales failed to automatically have to have resourceful advertising and marketing abilities, business enterprise setting up, and putting in the do the job and hustle to make profits, and quite a few have to switch to a salaried job with a lot more protection.”

Jang stated she believes the authentic-estate brokers who will thrive are the ones totally invested and integrated in the industry, as opposed to all those with no a “pulse on the marketplace each and every single day.”

Gary Keller: It’s A Do-Or-Die Housing Market For Real Estate Agents

Gary Keller: It’s A Do-Or-Die Housing Market For Real Estate Agents

In these times, double down — on your skills, on your knowledge, on you. Join us Aug. 8-10 at Inman Connect Las Vegas to lean into the shift and learn from the best. Get your ticket now for the best price.

Four months ago, Keller Williams co-founder and Executive Chairman Gary Keller stood before thousands of real estate agents, dumbfounded by a rapidly shifting real estate market influenced by several public health emergencies, rising mortgage rates, slowing home sales, worsening affordability, and increasing recession fears.

“I would say this is the most confusing market I’ve ever seen in my entire 40-plus years in our industry,” Keller said during August’s Mega Camp training conference. “It’s confusing, and it’s only confusing because you have mixed signals. Normally, you would expect all the signals to aim in one direction. And that’s not what’s happening.”

While all of those market factors still linger, Keller had a better read of the tea leaves and a clear message for the 10,000 agents watching his State of the Housing Market address on Sunday  — step up or step aside.

Gary Keller | Credit: KW

“I truly believe that 2023 will be a really tough year. It will be very, very hard,” he said on Sunday beside KW execs Jay Papasan and Jason Abrams and KW Chief Economist Ruben Gonzalez. “And if you don’t work hard to match the hard, your year is gonna suck. It will.”

“I said it yesterday, but I’ve been through this seven times,” he added. “And what I noticed is that there are people that don’t do anything different than they were doing during the good times. You can’t do that. When times get hard, you have to ramp it up.”

Putting home sales in context

While the past 12 months have felt like some of the worst ones on record, Keller said the historical data proves that we’re nowhere near the valleys of previous market cycles that saw annual home sales fall to the 3 to 4 million range — a rate we last saw in the years after the great recession.

“You’re sitting there thinking oh my gosh, we’re going to go back to production levels of 2009 and 2010 based on numbers of transactions,” he said while pulling up a slide of annual home sales data ranging back to 1990. “But here’s the gift of appreciation, and that is the volume of business that is predicted to occur this year would be the third highest in recorded history. Oh, by the way, the other two highest were the previous two years.”

Keller said part of the whiplash real estate agents experienced in 2022 was simply from how fast the market shifted, with home sales dropping from 6.1 million to 5.0 million in one year. “If it felt like you were falling off a cliff, news for you — You did, ” he said. “You fell off the second-highest cliff in recorded history.”

Although sales have slowed, Keller said 2023 is on pace to be the third-greatest year in recorded real estate history with $2.13 trillion in total market volume, even as home price appreciation is expected to decline 1.0 percent.

“You hear the ‘Oh my gosh, the sky’s falling, the sky’s falling,’” he said. “No. Look up. You’re most likely going to be in the neighborhood of the third greatest year in the history of real estate in terms of total volume.”

Before the crowd could get too excited, Keller said it would be harder than ever for real estate agents to get their “unfair share” of the market, thanks to the booming interest in the real estate market that saw the National Association of Realtors experience record membership gains in 2021.

“Okay, this is where you go boo, boo, boo,” he said to a wave of laughs from the audience. “Because you look up and you see in 2022 it was 6.3 transaction sides per agent, which is the lowest recorded. It’s never been lower in the number of sides.”

“Why? Because NAR, coming out of the Great Recession, added 580,000 agents, and average transaction sides dropped from 9.8 to 6.3. The historic average is around 10,” he added. “Notice how over time, it always finds its way back to that. Why does it do that? Well, we wrote about that in the book SHIFT. It’s called the law of equilibrium.”

Abrams said the industry is currently overrun with agents who joined when the market was hot and saw the opportunity to potentially get rich quickly. Right now, many of those agents are still hanging on; however, he expects them to quit over the upcoming year.

“We’re seeing lots of headlines about people who jumped into real estate right? Because of COVID, they were looking for another way to make money and are realizing this is a pretty tough industry, right?” Papasan added. “You have to be committed and they’re going back to their day jobs. So we will see this number go down.”

Keller and Abrams said a shrinking pool of competition leaves plenty of opportunity for experienced agents and dedicated newer agents to be successful in the coming year, especially if they’re willing to fight back against the negative narratives they and consumers hear about the market.

“Just because there are less opportunities, does not mean that anyone’s opportunity is less,” Abrams said.

The issue with fixating on mortgage rates

Keller, Abrams, Papasan and Gonzalez said the greatest challenge real estate agents and consumers will have to overcome is the Federal Reserve’s battle to curb inflation, which has in turn, caused mortgage rates to balloon by more than 400 basis points in the course of a year.

“It’s kind of still gonna be a rocky ride in ’23 because ’23 will be a full year of the federal government trying to get control of inflation [because] they don’t want to send the economy into a full-blown recession,” Keller said. “The odds are, you’re going to have one — my definition is that we had one last year, but no one talked about it because all the numbers were good.”

When it comes to inflation, inflation is most severe in the medical and education industries with costs for hospital services (+227.2 percent), college and tuition fees (+181.2 percent), college textbooks (+163.7 percent), medical care services (+132.2 percent) and childcare (123.1 percent) increasing by the triple digits since 2000. However, housing costs have increased by 87.1 percent, he said.

Although 87 percent is a staggering number, Papasan said it’s not as bad as it seems when you calculate the real change in prices when adjusted for inflation. Keller Williams compared the real change in prices from 1989 to 2022, which saw the monthly mortgage for a median-priced home only rise 2 percent.

“The takeaway here is that housing isn’t changed as much as people thought,” Papasan said. “Your mortgage is only 2 percent higher in real dollars than it was in 1989. That’s crazy, it is crazy.”

Keller admitted the impact of inflation varies across generations and personal life circumstances, with millennials and Gen-Zers battling the cost of college educations and baby boomers feeling the weight of staggering medical bills.

Even with that, Keller said most Americans would be smart to purchase a home and secure steady housing costs.

“When I got in real estate in 1979, interest rates were below 10 percent and interest rates within like a year period when they actually peaked at 18 percent,” he said. “Why would you buy a house at that interest rate? Well, a lot of people did.

“And by the way, those who bought houses at 18 percent 10 years later had the last laugh,” he added. “Why? Two things, real estate appreciated and interest rates came down and they refinanced.”

All four panelists acknowledged homeowners who secured record-low rates in 2020 and 2021 will only place their homes on the market if they absolutely need to since it’ll be impossible to get that kind of rate again. “You’re not gonna see three in your lifetime. My guess is you will never see four in your lifetime,” Keller said. “But that’s OK.”

Even though it won’t match the two-percent rates seen in 2020, Keller said today’s homebuyers who lock in a rate at the seven percent range will likely have an opportunity to refinance at the five to six percent level as the Fed gets a hold on inflation.

But even if they don’t, he said real estate is an investment that always pays off in the long run, especially since today’s homeowners and homebuyers are in a more secure financial position than one or two decades ago.

“[Purchasing real estate] has been proven to be the best long-term plan to build wealth because the second that prices go up on the houses, people that can’t afford to buy and they go rent and every greedy landlord in the room today will raise the rent on those suckers. Yes or no? Yes, yes, you will. Of course, you will. So rent never does it.”

“Even if owning a home takes up 60 percent of your income, do it,” he said while noting the average homeowner puts around 36 percent of their pre-tax income toward a monthly mortgage. “Why? Because you’re trying to lock in your cost of living.”

Debt ceilings, Ukraine and climate change

Although the first half of 2023 will be rough, Keller said the back half of the year will most likely yield calmer seas if domestic and global politics don’t get in the way.

“Well, if we look ahead this year and say, ‘Okay, what could derail us? What would be the things that we just need to keep an eye on?’ Number one would be any further escalation in Ukraine,” he said. “That could destabilize so much from oil and gas to wheat, you name it. I mean, there there are products coming out of that region that make a difference.”

The second-biggest threat comes from the Fed as they continue to battle inflation. So far they’ve been relatively successful, Keller said, but there is a chance that inflation takes a turn for the worse and throws us into a recession.

“In fact, if something weird happens and instead of getting it under control this year, it goes up, all bets are off,” he said matter of factly. “All bets are off.”

Keller said the partisan battle over how to handle the federal debt ceiling will have a major impact on the third and fourth quarters of 2023, while the increasing risks associated with climate change will guide the market for the foreseeable future.

“Look, I don’t care who caused it, but there is climate change,” he said. “Just come to my house and look at all the trees that are freezing. I mean, it’s unreal. Climate change is very real. By the way, it’s going to destabilize cities and it can destabilize a government overnight.”

Abrams and Papasan nodded in agreement, with Abrams telling agents to dial into environmental issues as they’ll become a greater factor in homeowners’ and homebuyers’ real estate decisions. “You can also have an immediate disaster, which changes the economic future in a moment,” he said. “Those [disasters] are happening more and more often. So we have to be cognizant of it.”

Thriving in a consolidating market

Beyond political and macroeconomic issues, Keller said real estate agents and companies must pay attention to a converging industry where everyone is battling to disrupt the traditional homebuying and homeselling experience and create the ultimate all-in-one tool that consumers will come to count on in the future.

“People forget that we tend to overestimate the short term, and then we completely underestimate the long term,” he said. “What you see happening again is a convergence. When you hear firms like Zillow talk about The Great App or The Super App…”

“What they’re talking about is pulling all of this into one experience,” he said. “It’s going to keep and it’s going to keep this is going to keep happening.”

However, Keller said the current market shift is showing who’s actually got the proof in the pudding, with the downfall of iBuyers being the prime cautionary tale of rushing to invest in the next shiny, new thing.

“You would have thought that the iBuyers two years ago, were the smartest, most brilliant people in the entire industry, right? They got the front stage. I remember Eric Wu, who is no longer running [Opendoor],” he said. (Note: Wu has taken on another executive role with Opendoor.) “I remember Eric came to Austin and we were a group of us met with him. At one point I asked him, ‘What are you going to do when we go into a downturn?’”

“He gave a really sophisticated algorithmic answer of how they knew how to figure that out,” he added. “He didn’t know what he was talking about. In the short term, people that sound good can make you look stupid. But truths are truths. They don’t change over time.”

Keller said real estate companies who own their tech are in the best position to lead the industry and support agents in their journey to serve agents and create solid, long-lasting businesses.

“You’re the number one source that people use,” he said. “So even if they’ve looked at real estate online or they start their journey and all these different ways, who do they end up going to? The real estate agent.”

Email Marian McPherson

Housing market correction just took a new turn

Housing market correction just took a new turn

“Depending on sector dynamics and backlog stages in each and every neighborhood, we are receiving more intense with our pricing ahead of the spring offering year, in order to deliver new orders,” KB Dwelling told investors back again in January after posting its disappointing fourth-quarter final result.

Rapidly-ahead to February, and it appears to be like like we’re previously looking at the housing industry correction—which noticed new- and existing-home revenue agreement at virtually document speed in the next 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of previous year—move into a new phase. What’s heading on? Aggressive builder rate cuts coupled with incentives, like mortgage rate purchase-downs, are assisting builders get profits transferring up once more.

This uptick in new-home product sales could mean the household selling price correction on the new-building side is losing steam. Or at the very least shedding steam for now.

“Builders have taken their medicine for the most section proper now on pricing. And we feel nationally, dwelling prices—on the new-household aspect, web of incentives—are down about 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from peak,” Rick Palacios Jr., head of investigation at John Burns Real Estate Consulting, reported in a video clip posted on Saturday. “There’s almost certainly not a ton of runway there left.”

Let us be obvious: Palacios is speaking about the residence price tag correction on the new-house facet. On the present or “resale” facet, he thinks the household cost correction has a way yet to go.

“We however consider that there’s more [home] value correction to appear on the resale facet, while. And the resale marketplace is constantly stickier to the draw back when it comes to [home] selling prices,” Palacios suggests.

Unlike homebuilders, who have to have to reduce price ranges in get to move unsold stock, existing property owners are normally additional resistant to these kinds of cuts. That resistance is why current-household rates generally bottom out past in a housing market place downturn.

Let us get a closer glimpse at the ongoing correction on the present side. Here’s the data.

For 124 consecutive months, spanning the bottom of the previous housing bust in February 2012 by means of the best of the Pandemic Housing Increase in June 2022, the price of U.S. present solitary-family houses, as measured by the seasonally altered Situation-Shiller Nationwide Residence Rate Index, posted constructive month-more than-month house selling price development.

That streak is about now.

By the latest examining in November 2022, present one-family residence charges are down 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from that June 2022 all-time superior. On the 1 hand, that drop marks the 2nd-biggest house value correction of the post–World War II era. On the other hand, it is really a mild correction as opposed to the 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} peak-to-trough home value drop among 2007 and 2012.

It will be yet another six weeks until the Scenario-Shiller reading for January is released. Nonetheless, preliminary knowledge displays that the residence cost correction on the present-home aspect may possibly also be shedding some steam in 2023.

An examination of Zillow Residence Price Index data by Fortune (see chart above), finds that 79{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the nation’s 200 premier housing markets saw a month-about-thirty day period home price drop in September. That determine has since been dropping, gradually but surely.

In Oct, 76{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of those main markets saw a residence price tag drop. In November and December, it was down to 64{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. Nonetheless, in January, just 47{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the nation’s 200 largest housing markets registered a thirty day period-around-thirty day period home rate decline.

Last year’s mortgage loan fee shock, which saw the common 30-yr fixed home finance loan charge spike from 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to around 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, has in fact established off a dwelling price tag correction. That explained, the correction carries on to be bifurcated: Some markets are observing a sharp correction, while other markets have not seen considerably of something.

“If you happen to be any where in Texas or west of Texas, you might be in all probability down much more. If you’re any place east of Texas, you are almost certainly not down that substantially, if at all,” Palacios claims.

That bifurcated housing correction is why KB Property, which has a large concentration of organization in rapidly-correcting West Coast and Mountain West markets, noticed a cancellation level that exceeded those people of its friends, which do extra enterprise in the Midwest and Northeast.

When it arrives to the house cost correction, there does continue to be 1 large wild card: property finance loan rates.

“Before cost cuts that now put together with significant fee invest in-downs are supporting on the new-property price tag balance facet [in some markets]. If [mortgage] prices adhere all over 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or split earlier mentioned, deeper [new and existing] price cuts may possibly be essential,” Palacios explained to Fortune.

Want to remain updated on the housing market correction? Comply with me on Twitter at @NewsLambert.

Discover how to navigate and reinforce trust in your enterprise with The Belief Variable, a weekly e-newsletter inspecting what leaders need to be successful. Sign up below.

How to know when housing bottom is in

How to know when housing bottom is in

New homes at the Cielo at Sand Creek by Century Communities housing development in Antioch, California, U.S., on Thursday, March 31, 2022.

David Paul Morris | Bloomberg | Getty Images

Chicago realtor Jeremy Fisher headed to Florida after Christmas counting on five mostly-relaxed weeks, after a slow second half of 2022 left him with a bunch of unsold listings exiting the year.

Instead, the Compass broker ended up flying back to the Windy City three times during his low season, as seven homes went into contract and his husband ended up driving their baby home from Florida alone. The great real estate bust, it seems, has found something like a floor.

“For somebody, it’s always the right time to buy a house,” Fisher said. “People for the most part have come to terms with interest rates.”

After only a few months in the tank, is the U.S. housing market close enough to a bottom that it’s time for those on the sidelines to at least start thinking about buying as spring shopping season nears?

Signs are accumulating that the big price bust — and mortgage-rate relief — that buyers wanted isn’t materializing, at least not soon.

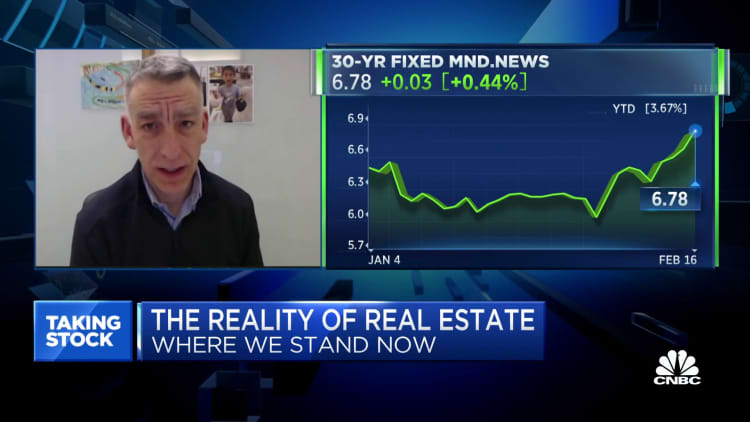
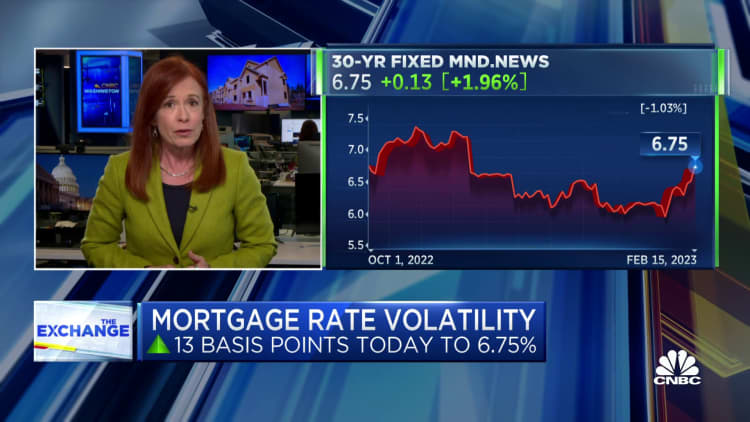
Goldman Sachs trimmed its estimate of peak-to-trough declines in nationwide home prices to 6 percent from 10 percent in late January. Online housing marketplace Zillow now expects prices to rise slightly in 2023. Existing home sales, which were running at a 6.5 million annual pace in early 2021, have begun to stabilize around 4 million, with the National Association of Realtors forecasting 4.8 million for the year. Meanwhile, mortgage rates, which dipped under a 6 percent national average on Feb. 2 after more than doubling since mid-2021 to almost 7.4 percent, have jumped back to 6.75 percent, driven by a scorching January jobs report.

No bust, but a standoff between buyers and sellers

Instead of a price bust a la the one after the mid-2000s housing bubble, what’s developing is a standoff, says Logan Mohtashami, lead analyst for HousingWire in Irvine, Calif. On the one hand are buyers who would like homes to be as affordable as in 2019. But a big share of them either have to move or can afford to despite higher prices and rates. On the other are sellers, under no pressure to move since they have cheap mortgages and plenty of equity for now. So far, sellers are hanging tough in most cities. Even small increases in demand can keep prices firm, or move them higher, because inventory is so tight, Mohtashami said.

The recipe for 2023’s housing market is shaping up as prices that are roughly stable nationally, but with ongoing drops in some regional markets, interest rates that decline but not hugely, and buyers’ incomes that rise. Experts think they will combine to make affordability improve, maybe to near-normal historical levels, but still fall well short of where home buyers stood when mortgage rates were 3 percent or even lower.

“Households have two incomes, and you have to earn about $100,000 to buy a house,” Mohtashami said. “There are lots of dual-income couples that can do that. It gives you more buying power than people know about.” 

No return of 2008, or 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} mortgage rate

The biggest reason why housing prices aren’t plunging like they did after 2008? Because the market isn’t being flooded with homes that drive down prices, as happened then.

Capital-rich banks aren’t under pressure as they were then, with foreclosure rates less than a tenth of those from the housing bust. Neither are households, with debt payment burdens near historic lows and few homeowners owing more on their mortgage than the house is worth. Serious delinquency rates, which skyrocketed after 2006 and led to 6 million foreclosures, have fallen by nearly half in the last year, to less than 0.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of mortgages, according to Fannie Mae. Unemployment is the lowest in 54 years, letting homeowners either trade up or hang on to their current homes easily – and if they are among the 85 percent of owners whose mortgages carry interest rates below 5 percent, many will stay put rather than buy a more expensive house with a costlier loan. 

All that means the supply of homes for sale is likely to stay tight, which limits price declines.

We're still at half the housing inventory of 2016 through 2019, says Redfin's Glenn Kelman

Affordability is bad now, after rate hikes and Covid-driven price increases, but it has been worse. And we’ve all been spoiled by recent history: After the financial crisis, housing affordability nationally literally doubled as interest rates collapsed and prices fell, reaching all-time highs. It had retained most of those gains up until the Covid price surge, even as home values recovered.

“Rates will be dropping in the second quarter, but we don’t see a drastic drop that should make people wait,” said Nadia Evangelou, director of real estate research at the NAR. She predicted that 30-year mortgages will decline to around 5.75 percent. “Buyers realize 3 percent rates are not coming back.”

Housing affordability is stretched

The NAR’s closely-watched affordability index, which considers prices, rates and buyers’ incomes, is much lower than in 2019, but is still in line with the late 1980s and early 1990s. At current levels, the Housing Affordability Index says the median buyer can afford the median U.S. home — but barely. In 2020, the median buyer could afford the median home with a 70 percent cushion, which was the product of 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} loans, Covid-driven income support and the residual impact of big home price drops between 2006 and 2011. Since 1980, the average is that median home buyers have about 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more income than they need for the median home, Evangelou said.

So why is anyone buying homes that are suddenly less affordable?

For Maggie Neuder, a client of Fisher’s in Chicago, the answer boiled down to wanting a new place and being able to afford one. Having seen 6 percent interest rates when she bought her first place in 2007, she’s not daunted by today’s rates, she said. The 41-year old finance executive bought a bigger home than she needed during Covid to ride out quarantines, and now wants a smaller place in the city’s Lincoln Park neighborhood, so she executed a flip.

To calm her buyer’s interest rate fears, she is giving a closing credit big enough to buy down the mortgage rate on the buyer’s loan for the first two years, by two percentage points in year one and one percentage point in year two – a move many builders are also using to sell new homes. To make back the money, she extracted a similar concession from the seller of the home she expects to buy in April.

“People look at refinancing like it’s a bad thing,” she said, figuring she can likely lower her payment within a couple of years. “I don’t think we’re going back to the sub-threes, but somewhere in the fours. Even if rates don’t fall below 6, I’m in a comfortable place with my mortgage.” 

Mortgage rates move higher, along with homebuilder sentiment

Fisher says his recent buyers fall into three camps. At either end are first-time buyers who have never had a 3 percent loan, and older buyers who are paying cash. Neither is much bothered by rates around 6 percent, he said. In the middle are move-up buyers who initially worried about rates more. But they are making work-arounds like Neuder’s to get what they want, Fisher said. These buyers likely drove the increase in applications for new mortgages that happened as rates fell earlier this winter.

“People have wrapped their heads around where interest rates are, and they have adapted,” Fisher said. 

Indeed, combining the wage gains of the last few years with the deflation that has begun to show in market-based housing data in the last six months, and the most flagrant cases of distorted regional markets have begun to correct already. Another boost comes from solid rates of new household formation, said Daryl Fairweather, chief economist at Redfin.

Where home prices are now

The average house price is down 6 percent since the June peak, according to the S&P Case-Shiller index of prices in 20 major metro areas, and 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the index for the whole country. 

Recently-hot markets have taken bigger hits, as expected. In San Francisco, the Case-Shiller index is down 12 percent, in Phoenix 8 percent. In Sacramento, home prices have given back almost half of their Covid-era gains, said Ryan Lundquist, a local appraiser who blogs about the market in California’s capital. In metro Tampa, where prices rose 69 percent during Covid, according to Case-Shiller, prices are down only 3 percent.

Add in wage growth — wages rose about 5 percent last year, according to data from Zillow — and the effective price of housing has come down sharply in some places, while remaining well above pre-Covid levels, Zillow chief economist Skylar Olsen said. 

“Even with values down a bit since August, if you bought the average house in February 2020 you have annual gains of 11 percent,” Olsen said.

Wage growth is one reason why even in some recently-hot markets, buyers are still out there, said St. Petersburg, Fla. broker Jeffrey Clarke. Indeed, he recently talked one client with a home in another city out of selling their place in St. Petersburg, convincing them that the crash they feared was not coming.

By the NAR’s numbers, affordability is now poor in metro Tampa, with the median buyer only earning 80 percent of what’s needed to buy the median home. But Tampa is close enough to equilibrium that Clarke doesn’t see anything coming like 2008-2011, when the average Tampa house lost half of its value.

“With nothing falling yet, no one is freaking out,” he said. 

The math on mortgage rates and wage growth

The big flaw in the thesis that only minor price drops are coming is that so many large regional markets like Tampa remain out of line with local incomes, and many of them were in much better balance as recently as two years ago. Another is that San Francisco, Phoenix and Las Vegas all saw more than a 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} price drop in January alone, according to Zillow, making forecasts for relatively-stable prices look shakier.

Much of Florida and Texas, and markets like Asheville N.C. and Denver, had relatively-affordable housing until 2020 but median homes are now 20 percent to 30 percent too expensive for median local incomes, according to NAR data released in October. In much of California, NAR affordability indexes are at 50 or below, indicating homes cost twice as much as local incomes can support. But much of California has always been less affordable.

Nationally, to get back to the average affordability since 1980, meaning median houses are about 20 percent cheaper than the median family can afford, mortgage rates would have to come down to about 4.6 percent, while wages would need to rise 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and prices stay stable, the NAR’s Evangelou said. Wage growth has recently cooled a little, but remains above 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — in the recent nonfarm payrolls report, wages were up 4.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a year ago, though a bit below the December gain of 4.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Mortgage rates remain volatile, and the market hopes that began 2023 — that the Fed would be cutting its benchmark interest rates before year-end — have recently dimmed as the labor market and consumer remain too strong to provide confidence that the current rates hikes are doing enough to slow inflation. After falling for five weeks, the average contract interest rate for 30-year fixed-rate mortgages increased to 6.39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 6.18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} last week, and was as high as 6.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on Friday. The rate was 4.05{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} one year ago.

How fast could affordability get better? On a $300,000 loan, a drop in fixed rates to 4.5 percent from today’s 6.75 percent, with no change in prices, would change the monthly payment by about $425 on a 30-year loan, about a 23 percent drop. Going to 6 percent cuts a payment by about $150, or 8 percent. A 5 percent income gain this year for the median buyer would add about another $400 a month.

“If rates come down to 5 percent, it gets radically better very fast,” Olsen said.

In a place like Tampa where prices grew rapidly during Covid, the affordability fix will probably blend near-stagnant prices for a year or two, pay raises and lower interest rates, Clarke said. But hotter markets like Tampa may need more price cuts to get affordability all the way back to historical averages, Evangelou said.

The market’s standstill is likely to last for months, at least, because its main underpinnings aren’t going anywhere. Sellers will continue to have the advantage of being equity-rich and sitting on a low interest rate from 2021 or before, Mohtashami says. Some buyers will remain priced out of the market, or able to afford less house than they want. And some will use work-arounds like mortgage buydowns or parental support to buy houses until affordability recovers. Sellers of new homes will do buydowns and have been using incentives since last summer to limit cuts to list prices. 

“It has become kind of the norm,” Neuder said. 

In some markets, affordability is likely to remain a problem for long enough that policy solutions will be needed, Olsen said. She mentioned solutions like building more dense housing, or letting more homeowners add additional dwelling units such as basement or attic apartments to let families share costs. 

In most places, the likely outcome is affordability that falls somewhere between today’s market, where many prospective buyers are stretched and demand is light, and the buyer’s delight that prevailed for close to a decade. The path to that is rising wages, declining inflation that lets interest rates fall, and home prices that give back a still-to-be-determined chunk of the 2021-22 gains – a share that so far is small in most places.

“I want it to be flat the next two years,” said Clarke, the Florida broker. “You can’t rise 20 percent a year for a decade. You end up with a $5 million dollar two-bedroom, two-bath.”

The Real Estate Market Is In The Freezer, But Billionaire Grant Cardone Says Investors Will ‘Save The Day’

The Real Estate Market Is In The Freezer, But Billionaire Grant Cardone Says Investors Will ‘Save The Day’

Economists have been contacting for a housing crash for quite a few months. Some even predicted that residence price ranges would drop by as substantially as 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023. Whilst these statements are understandable considering that mounting mortgage premiums have priced a lot of would-be potential buyers out of the market place, it appears that a distinctive state of affairs is beginning to perform out.

Ideal-selling writer and serious estate fund supervisor Grant Cardone agrees that the housing current market is in problems, but details out that buyers will make adequate demand from customers to retain the industry from crashing.

“Banks never have confidence in borrowers, and all those they do trust will have to shell out. This will shift house owners to the sidelines and bit by bit decrease property selling prices,” Cardone claimed. “Investors will stage in to pick up solitary-family members properties at lower costs with considerably less competitors. That getting mentioned, there will be no housing crash! Traders, like myself, will help you save the working day and stage in to acquire the households, place renters in position and appreciate them for the hard cash circulation, not the kitchens and cabinets.”

Cardone’s actual estate expense organization Cardone Money has elevated about $1 billion from accredited and nonaccredited traders throughout 22 resources due to the fact its inception in 2016. The company’s actual estate portfolio is valued at roughly $4 billion and is composed of virtually 12,000 apartment models throughout 36 attributes and in excess of 500,000 sq. toes of professional place of work house.

Cardone isn’t the only significant trader who sees an possibility in the recent housing marketplace. J.P. Morgan declared in November that it strategies to get $1 billion well worth of single-household rentals. Other institutional buyers like BlackRock Inc. and Norges Bank improved their positions in solitary-relatives housing real estate financial commitment trusts (REITs) Invitation Houses and American Residences 4 Hire all through the final quarter.

Amazon Founder Jeff Bezos even staked a claim in the one-family rental industry by investing in the seed and collection A rounds of the investment system Arrived Homes, which makes it possible for retail investors to obtain shares of unique rental houses with as small as $100. The platform has presently funded over 200 houses worth additional than $75 million.

There is also a expanding demand from customers from international traders for U.S. true estate. Chad Gallagher, co-founder of the residence administration organization House 365, informed Benzinga very last thirty day period that his company has viewed a significant uptick in overseas buyers from economically risky nations looking for residence management products and services for their purchases of multifamily houses.

“U.S. authentic estate truly has a greater cap fee than most countries. For instance, the typical one-relatives dwelling in Israel expenses five times what a identical property below would price tag,” he stated. “So investing in a rental home in nations around the world like that and building them income-move optimistic doesn’t do the job for them.”

Examine future:

You should not pass up serious-time alerts on your shares – sign up for Benzinga Professional for free of charge! Check out the device that will assistance you invest smarter, speedier, and far better.

This report The Real Estate Current market Is In The Freezer, But Billionaire Grant Cardone Says Investors Will ‘Save The Day’ originally appeared on Benzinga.com

.

© 2023 Benzinga.com. Benzinga does not deliver expense assistance. All rights reserved.

Investors are pulling back from the housing market, Redfin says

Investors are pulling back from the housing market, Redfin says

Traders are slinking away from the serious-estate current market as property-selling price growth slows and the possibility of value drops seems on the horizon.

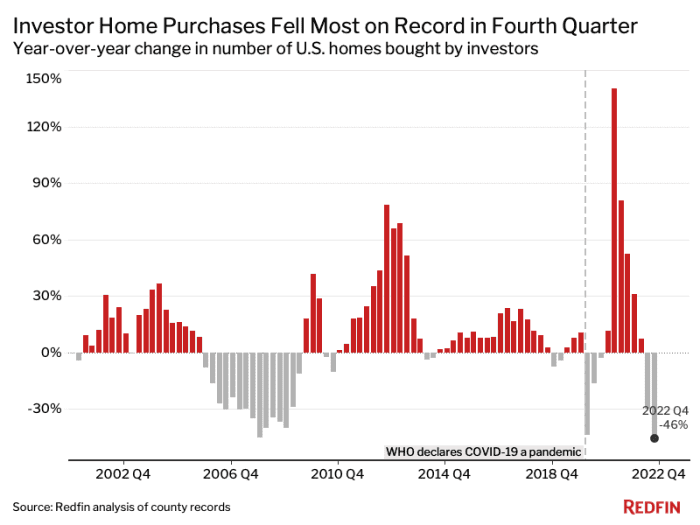
The last time trader purchases dropped so considerably was in 2008, throughout the subprime house loan crisis, when they fell 45.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Redfin explained.

In the fourth quarter of 2021, buyers acquired 89,396 houses in metropolitan regions tracked by Redfin. In the fourth quarter of 2022, investors only acquired 48,445 properties in those regions.

The overall drop in mortgage charges and a feasible bottoming-out of home prices may lure investors back again into the industry, but “it’s unlikely that investors will return with the exact same vigor they had in 2021,” said Sheharyar Bokhari, senior economist at Redfin.

“That’s fantastic information for personal consumers, who are nevertheless grappling with high housing fees but no more time shedding bidding war soon after bidding war to traders,” he extra.

Throughout the pandemic, many property purchasers were being outbid and overshadowed by traders who were being equipped to scoop up houses with all-income features. The issue above the plight of initially-time household customers prompted Democratic lawmakers to convene a panel to seem into achievable predatory actions by institutional investors.

In its study, Redfin appeared at residence income amongst January 2000 and December 2022.

Residence purchases by investors fell in 2022. The last time such purchases dropped as drastically was in 2008.


Redfin

For the study, an investor was described as a purchaser whose identify incorporated at the very least a person of these search phrases: LLC, Inc., Have faith in or Houses. Buyers were being also viewed as to be buyers if their possession code on a house deed integrated key terms like “association,” “corporate trustee” or “company.”

Though buyers have pulled back on purchasing homes, it does not imply their market share has dropped, due to the fact person household prospective buyers have also slowed their action. Home loan costs are nevertheless elevated and house charges have not however dropped drastically, which means that lots of men and women are acquiring it challenging to find the money for to buy a dwelling ideal now.

According to Redfin, investors’ share of the industry in all the metropolitan places tracked by Redfin was 17.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fourth quarter.

In other terms, traders acquired that proportion of all households bought in the 40 most populous U.S. metro locations, as tracked by Redfin. Past yr, buyers bought 19.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all homes in all those locations.

The cost of a usual property ordered by an investor was all around $425,926.

Investors flee pandemic boomtowns

In pandemic boomtowns like Las Vegas, Nev., and Phoenix, Ariz., buyers are operating for the hills, the info clearly show.

In accordance to Redfin, household purchases by buyers fell the most in Las Vegas, dropping 67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fourth quarter about the exact period of time of the past calendar year.

Las Vegas is also the metropolis that saw residence values fall the most amongst the prime 50 marketplaces tracked by Zillow Group
Z,
+.86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9},
another true-estate tech enterprise. Household values there fell 1.23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January as opposed with December.

Traders also hit the brakes in Phoenix, in which house purchases by investors dropped 66.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nassau County, N.Y., where they fell 63{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Atlanta, where they fell 62.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and Charlotte, N.C., exactly where they dropped 61.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

“A large amount of traders are on hold since they even now see residence costs declining,” claimed Elena Fleck, a Redfin agent based mostly in Palm Beach, Fla.

The only metro place amid these analyzed by Redfin that observed an boost in trader purchases was Baltimore, Md.

Buyers still experienced the highest sector share in Miami Jacksonville, Fla. Atlanta Anaheim, Calif. and Charlotte, Redfin noted.

Home loan costs have crept again up as the current market weighs extra fascination-rate hikes from the U.S. Federal Reserve, which proceeds its struggle against inflation. In consequence, potential buyers have also pulled back again.