AI Won’t Spell The End Of Real Estate Agents. A Court Decision Will

AI Won’t Spell The End Of Real Estate Agents. A Court Decision Will

While many agents fear the replacement potential of AI, it may end up allowing the industry to continue working if the worst happens.

In these times, double down — on your skills, on your knowledge, on you. Join us Aug. 8-10 at Inman Connect Las Vegas to lean into the shift and learn from the best. Get your ticket now for the best price.

A growing threat looms on the horizon, shaking the real estate industry to its very core. Inevitable changes seem to be coming sooner than later. 

Is this a worst-case scenario? Perhaps. Is there enough truth and data to be plausible? Yup. I believe reality lies somewhere in the middle of our risk spectrum — and no, the real threat is not AI.

An exemption problem

There’s a legal battle (based on several cases, actually) that’s been brewing for years in court. The TL;DR — Real estate agents are currently 1099/independent contractors and not W2 employees. Many in leadership believe that will change when the government forces Realtors to become W2 employees.

Currently, the industry has been riding on an “exemption” for the classification of the industry, brought about by the mighty and long-lasting power of the National Association of Realtors (NAR) lobby in Washington, which is second only to the NRA in size. (Good work, Team RPAC.)

Cutting costs (Read: Agent and staff reductions)

Not all Realtors are 1099, but about 87 percent (according to NAR’s 2021 data) are independent contractors. When the government “asks” that the designation change to W2, agents will have to be paid minimum wage. Federal minimum wage is currently $7.25 per hour or $15,000 per year.

However, most believe that due to a number of factors this will increase significantly soon. So consider the living wage for the sake of this discussion since few of us in the industry could (or would) live on the minimum wage of $15,000 per year.

According to Just Capital and MIT, “For one full-time working adult with no children in 2022, the national average living wage is $17.46 per hour – or $36,311 annually.”

In this livable wage future, each agent would be paid by the broker a base rate of $36,000  per year. Friends, there is no 1099 brokerage that will keep all its agents if this happens. The cost is simply too great. 

Agents vs. math

What would it take for an agent to keep their job at a brokerage? How many transactions would be acceptable?

Using national averages according to Zillow, the average home value is $329,000 as of this writing. The average total sales commission for both buyer and seller sides of the transaction is 5.37 percent. Divided by two, that equals 2.68 percent per sale ($8817.20 per side). Based on this math, the average agent needs to sell five transaction sides per year to pass break-even for the cost of the base.

Assuming the industry is in business for profit, in my estimation, agents would need to do around 12 transaction sides per year on average to remain employed. Making matters more difficult, with a hovering recession, we are not in a 2021 boom economy, either. 

There are too many agents. The number of agents exploded nationwide in the last two years. Estimates are that there are currently over two million licensed real estate agents in the US and that there will be roughly 4.5 million housing transactions — thus, 2.25 transactions per agent “available” with this number of agents.

The imbalance in the number of agents and lack of proceeds to support so many agents will create massive layoffs of crummy agents who entered the market during the boom and don’t have the necessary skills to survive these conditions. Even middle-of-the-road producers who are content selling six homes a year will be removed from office.

The new problem will be staffing desks and phones and getting repetitive tasks done that were previously taken care of by entry-level 1099 agents. 

The AI answer

Real estate brands, teams and brokers will have to reduce costs and will inevitably turn to real estate AI to do more of the tedious, monotonous work, just as they have with VAs (virtual assistants). In addition, the easy lead qualifying and simple Q and A solutions are a far more dependable, accurate and inexpensive alternative to 1099 desk, chat and phone staff. 

The huge industry trade shows (if they still exist) will be jammed with new, untested AI tools that promise to be the all-in-one printer. Caveat emptor: Failure is always an option, but ChatGPT has a winning model on their hands. 

For example, I asked ChatGPT the type of question an entry-level Realtor might be asked: “Will I need a septic tank inspection before selling my house?” Here is its very on-point and scarily impressive answer. Chat GPT gave me good advice.

The end will be swift

AI may be viewed as the executioner; however, in this case, it’s likely that a judge will mean the death of hundreds of thousands of real estate agents’ jobs. With the stroke of a pen and the bang of a gavel, the end of the 1099 exemption for Realtors will signal a new era in real estate.

There are a few companies today, such as Redfin, that are already built for this model and will likely thrive during the transition. However, the bulk of today’s massive brokerages like eXp, Keller WIlliams and RE/MAX will be forced to legally comply or die. 

Companies like to make money. So that they won’t die, they will pivot and look for the most cost-effective method to continue making money. That solution has been handed to them in the form of ChatGPT and other AI to help them survive and become vastly more efficient in the future.

Chris Drayer is co-founder of Revaluate which segments consumers for marketers by propensity to move.
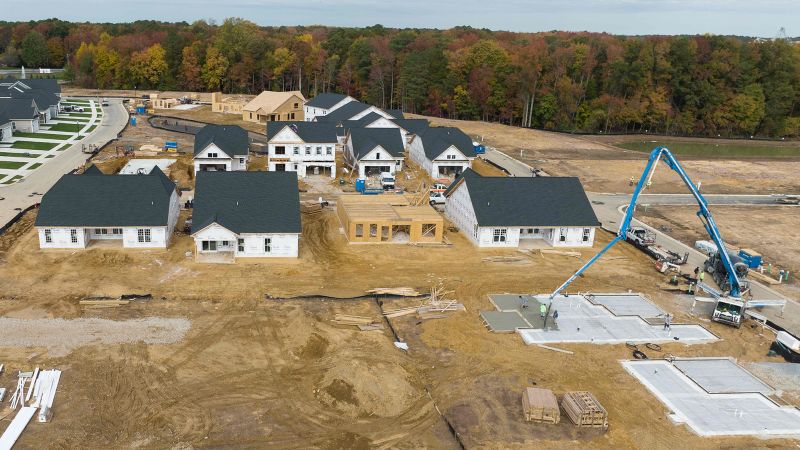
This real estate developer is happy that new home construction is falling

This real estate developer is happy that new home construction is falling

A version of this story first appeared in CNN Business’ Before the Bell newsletter. Not a subscriber? You can sign up right here. You can listen to an audio version of the newsletter by clicking the same link.


New York
CNN
 — 

Recent headlines point to a slumping US housing market — as mortgage rates average near 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an increasing number of potential homebuyers are finding it difficult to finance homes.

Mortgage applications fell in late February to a 28-year low, according to the Mortgage Bankers Association. But some of the country’s largest homebuilders are undeterred.

David O’Reilly, CEO of the real estate developer Howard Hughes Corp., told CNN that he’s “cautiously optimistic” that the residential housing market is rebounding after a downturn in the second half of 2022.

Before the Bell spoke with O’Reilly about Howard Hughes Corp

(HHC)
. and his outlook for the market.

This interview has been edited for clarity.

Recent data point to doom and gloom for the housing market. What are you seeing?

O’Reilly: I hear the headlines and they generate a lot of clicks, but I don’t see the death and destruction or anything close to what we saw during the global financial crisis. This, in my estimation, will be a very modest downturn. First, as a country, we’re short between four and five million homes. We just haven’t built enough to keep up with household formation since the global financial crisis. In most markets, we’re close to record lows in terms of inventory for homebuilders.

Sure, home prices are down but we’re just giving back some of the gains we saw in 2020. We’re still making an outsized profit relative to historical norms. When you hear about homebuilders buying down mortgage rates [contributing part of the purchase price upfront], they’re doing the things that they should do to help move inventory and they’re doing it very profitably.

David O' Reilly, CEO of the real estate developer Howard Hughes Corp. This real estate developer is happy that new home construction is falling.

Are you having issues attracting new buyers because of higher mortgage rates?

The mortgage rate is less impactful to homebuyers than the volatility of interest rates.

When interest rates are moving, rising or falling quickly, they create a pause amongst buyers because they want to know where it settles out. No one wants to lock in if they think the mortgage could be cheaper in a month. I think homebuilders have, to a large extent over the past several months, tried to take some of the volatility out of the market. Some of the volatility has come out naturally as the rate increases have been consistent with expectations and mortgage rates have behaved normally, but some of the risk and uncertainty has been taken out because home builders are saying we’re gonna lock in your rate at, you know, 4.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, for a year or two.

Even though that 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate is much higher than the 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate a couple of years ago, it gives the consumer confidence to act without the uncertainty of rate volatility.

Are we in a housing recession?

In the second half of 2022 we saw a meaningful downturn in home sales nationally. We saw meaningful reductions across the board. But I’m cautiously optimistic that we’re starting to see a turn. I find it encouraging that home sales for the past several months have increased.

But what about new housing starts? Construction is falling.

New housing starts continue to fall — to me, that’s great news. During the second half of 2022 we saw the cancellation rate on new home sales surge. Those cancellations left a lot of standing inventory — home builders with homes that they were building for someone that canceled sitting on them.

The fact that they’re selling more but building less tells me that they’re eating through that inventory. And that is a great sign for the rest of this year.

▸ It’s all about the labor market this week as a slew of jobs data for February is set to be released.

Last month’s massive surprise — 517,000 jobs were added to the US economy when economists were expecting 185,000 — sent the stock market reeling. Investors are hoping that numbers fall back down to earth to help cool the economy and inflation along with it. If they don’t, expect market swings as the Fed will face more pressure to hike interest rates to keep prices in check.

ADP’s private payroll report for February and the JOLTS job openings, hires and quits report for January are expected Wednesday. On Thursday, Challenger, Gray & Christmas is set to release its job cuts numbers for February, and Friday brings the main show — the US jobs report for February.

Analysts expect that the economy added 200,000 jobs in February and the unemployment rate is expected to remain at a historically low 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

▸ Speaking of the Fed, Chairman Jerome Powell will be on the hot seat this week as he testifies before the Senate on Tuesday and the House of Representatives on Wednesday. In his semi-annual report to lawmakers, Powell will likely stress that the Fed will need to take more action to get inflation back down to its 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} target. Investors will watch lawmakers question Powell, and he’ll likely be asked to defend his fight to cool the economy, which could hurt wage growth.

▸ President Joe Biden is also expected to unveil his Federal budget proposal for the next year. He’s promised that it will include tax hikes for the wealthy — something that Wall Street typically doesn’t like to hear. While the president’s budget proposal is just that — a proposal — it will likely guide Democratic policy initiatives for the year to come. That means we’ll likely hear more about increasing capital gains taxes and taxes on controversial corporate stock buybacks, two policy proposals that also rattle investors.

Amazon made two recent announcements that don’t sound very good for the company — at least at face value.

The company is pausing construction on its second headquarters in northern Virginia, the company confirmed in a statement to CNN on Friday. Bloomberg first reported news of the pause.

John Schoettler, Amazon’s real estate chief, said the company is pushing back the new headquarters’ second-phase groundbreaking. The first phase is still under construction and expected to open in June.

The company’s decision to pause construction comes just two months after Amazon CEO Andy Jassy confirmed the company would be eliminating more than 18,000 jobs, the largest cut in its history. Amazon hired rapidly in the early years of the pandemic and it is cutting costs as consumers shift their behavior.

But Wall Street applauded the news on Friday. Amazon

(AMZN)
stock surged 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher.

That’s because investors want the company to reduce its expenses as revenue slows and the economic forecast remains dour. Jassy said during Amazon’s fourth quarter earnings report that he plans to do just that.

Amazon also announced on Friday that it will close eight cashier-less brick and mortar stores in Seattle, New York and San Francisco.

The Real Estate Market Has Officially Closed on Opendoor

The Real Estate Market Has Officially Closed on Opendoor

The COVID-19 pandemic delivered a generational catalyst for the U.S. housing sector. Median dwelling prices soared over 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in significantly less than two yrs as document-low fascination prices drove the price of financing a home to new lows and work-from-any place guidelines permitted extra younger adults to transfer absent from downtown city areas. Now home loan premiums are soaring, creating housing charges to stagnate and even decrease in many regions around the region.

A person business experience the brunt of this slowdown is Opendoor (Open -3.92{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), an online property flipper. The firm’s gain margins are deteriorating owing to declining house rates and weak acquisition choices more than the very last couple many years, causing traders to get particularly pessimistic about its future prospects. Here’s why the worst is yet to occur from this disaster of a serious estate disrupter.  

Q4 earnings: From negative to worse

Opendoor’s Q4 2022 earnings ended up ugly.  Profits declined 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months around 12 months to $2.86 billion, with gross margins sliding from 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That gave Opendoor a whopping $71 million in gross income final quarter, which wasn’t even plenty of to address the $113 million in fascination charges from the credit card debt it works by using to finance residence buys.

And it is not as if the organization is frugal with its running bills. Opendoor invested $194 million on gross sales/internet marketing, $23 million on corporate fees, and $48 million on know-how/merchandise enhancement fees in the fourth quarter. Insert it all up, and Opendoor posted a internet loss of $399 million just in Q4. For all of 2022, the enterprise misplaced $1.35 billion though creating only $667 million in gross gain. 

A bad organization strategy

Opendoor requires to scale its gross financial gain to substantially bigger heights in get to turn web revenue positive. For a residence flipper, there is a rather very simple system for creating this happen: Provide your housing inventory for extra than you acquired it for, net of funding fees. This is an effortless undertaking when property selling prices are soaring and the Federal Reserve has fascination charges at zero. It is a great deal much more challenging when curiosity prices start off climbing at the speediest pace in history, rising your curiosity expenses and making housing affordability the worst it has at any time been for people, such as the peak of the 2006 housing bubble. To simplify it, home flippers are tied to the housing market, placing it at the mercy of macroeconomic factors and the Federal Reserve.

Introducing on to these woes, it would seem Opendoor is basically very bad at house flipping. For illustration, in August of 2022 it is believed that the corporation missing dollars on 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its transactions. This was in the third quarter of final calendar year, when the median property value in the United States was nonetheless rising. In Q4 of 2022, housing rates went into a slight drop, leading to Opendoor’s gross margin deterioration. If house prices stagnate further more or even go into a cyclical downturn for an extended period, Opendoor is likely to be in a globe of harm fiscally.

Wherever does the firm go from right here?

Opendoor needs to look by itself in the mirror and comprehend it is managing on a flawed business product. Flipping households as an online market still indicates acquiring physical property financed with financial debt, possessing them sit on your harmony sheet, and (with any luck ,) advertising them at a better selling price a handful of months later on.

The only route forward for Opendoor is to pivot its company product. It has over $1 billion in cash on its stability sheet and $4.5 billion in property stock it can liquidate. At a industry cap of below $1 billion, it would not have to create a gigantic new business in order to get started developing benefit for shareholders. But if it carries on down this household-flipping path in an economy with declining residence values, it will only continue on to damage shareholder worth.

Brett Schafer has no position in any of the stocks outlined. The Motley Fool has positions in and suggests Opendoor Technologies. The Motley Idiot has a disclosure plan.

Commercial real estate continues to get pummeled

Commercial real estate continues to get pummeled

Industrial serious estate continued to acquire it on the chin previous 7 days, and brokerages are preparing for even rougher instances ahead. 

CBRE, JLL, Colliers and Cushman Wakefield, among others, are shifting forward with value-cutting steps, which includes layoffs as house gross sales and leasing consume into their earnings.

Symbolic of the rough situations, the iconic — but vacant — Flatiron Creating is heading to auction scheduled by a New York state judge for March 22. 

Sorgente Group, Jeffrey Gural’s GFP Genuine Estate and Abdominal muscles Serious Estate Associates, which owns 75 p.c of the constructing at 175 Fifth Avenue, sued in 2021 to seek a partition sale just after the entrepreneurs stated they could not see eye to eye with the 25 per cent proprietor, Nathan Silverstein. The choose issued an get in January permitting the sale to go ahead. 

It is not the only significant-increase perhaps poised to strike auction. A subsidiary of M&T Lender asked a court docket to approve the foreclosure on 29 West 35th Avenue so it can market the making at auction. The lender received two judgments towards entrepreneurs Paul Sohayegh and Roni Movahedia in December over their default on a $41 million bank loan.

The Brooklyn business market seems to be similarly bleak. When the vacancy amount held at about 21 per cent in 2022, web absorption in the fourth quarter crashed from all-around 279,500 sq. toes in 2021, down to 950 sq. ft at the shut of 2022 (while which is a important improvement from the third quarter). 

Meanwhile, in Queens, for the 2nd time in 3 months, the Chetrit Team — squeezed by occupancy struggles and a floating fee loan manufactured costly by the Fed’s amount will increase — fell driving on a $225 million financial loan covering 640 multifamily models in Jamaica. That mortgage comes due in July.

In further evidence of professional distress in Los Angeles, Laguna Place Attributes is delinquent on a $329 million bank loan it utilised to acquire a portfolio of a lot more than 1,000 L.A. residences significantly less than a 12 months after securing the financial debt. 

In addition, Grant King is viewing his share of tricky moments, as Pertinent Team, which he co-launched, lost the Tommie and Thompson inns to mezzanine loan providers by means of foreclosures.

Somewhere else, LaSalle Financial investment Administration marketed the office environment creating at 4 Hutton Centre Drive in Orange County for 55 percent fewer ($24.9 million) than what the company acquired it for in 2019 ($55.4 million).

In San Francisco, the Chronicle claimed the city has misplaced approximately 150,000 every day place of work personnel considering the fact that the commence of the pandemic in early 2020 throughout a change to remote get the job done and on line procuring.

Not every person is emotion the pinch similarly. The Chicago space retained its No. 1 place (for the 10th calendar year managing) as the nation’s foremost metropolis for professional real estate investment decision. This despite getting rid of Boeing, Citadel and Caterpillar headquarters to other municipalities. 

Texas, in the meantime, noticed commercial development jobs overall $70 billion — or 20 per cent of the business genuine estate investing in the country — last year,  the Dallas Early morning Information claimed, based mostly on an annual analyze by the Nationwide Affiliation of Industrial and Place of work Parks. 

Hitting dwelling

The professional sector isn’t the only one having blows. Big household brokerages, which includes Any place, Refin and Compass, reported huge losses. Previous week, Compass declared it posted a $158 million loss in the fourth quarter of 2022, main some analysts to doubt that the firm will split even by 2025. 

South Florida — as a consequence of the lethal Surfside rental collapse — is seeing spiking insurance policies charges and much less insurers crafting insurance policies, which could guide to apartment owners selling their models at substantial bargains. 

If we’re hunting for some good news, the Manhattan and Brooklyn housing marketplaces observed an uptick in action that was over and above seasonal. Continue to, even there, the information was coated in 2023 truth.

“This is the calendar year of disappointment,” stated Miller Samuel CEO Jonathan Miller. “Sellers are not likely to get their selling price of 2021 and customers are not going to see substantial charge price savings.”

Read a lot more

Single-digit millionaires are ‘basically middle class,’ argues real estate mogul. Here’s why he’s wrong

Single-digit millionaires are ‘basically middle class,’ argues real estate mogul. Here’s why he’s wrong

Currently being a millionaire could not have the identical cache it at the time did. So argues actual estate mogul Grant Cardone in a recent online video on his YouTube channel in which he details five techniques to starting to be a millionaire.

A lot more from Fortune:

“Everybody’s like ‘Oh my god, the iconic millionaire, you are wealthy,’” he stated. “You’re not wealthy…you’re anxious.”

In the video clip, Cardone stands in a bleak workplace and yells a great deal in an effort to demonstrate that remaining a one-digit millionaire will not get you incredibly considerably these days (which, if you just take his word for it, states a whole lot about the relaxation of us contemplating the normal web value of a family members in U.S. is $121,700). He broke down some math to validate his place: If a 30-calendar year-previous with $1 million and zero revenue used $4,000 a month, equivalent to $48,000 a year, they would be broke by the time they attained 51.

“Millionaires are generally center-course individuals who are concerned about dollars,” Cardone reported.

The self-built millionaire, who’s CEO of assets financial investment enterprise Cardone Money, author of quite a few small business publications, and a scientologist, is acknowledged for his warm takes—in the previous, he said he’d be ashamed if he only manufactured $400,000 a 12 months. And his polarizing comments really do not end with revenue advice—he just lately came beneath hearth for tweets to his almost 1 million followers about anti-trans regulations. Becoming controversial is component of his model: As he not long ago tweeted, “You you should not have to like every thing I say. The emotion is mutual.”

Quite a few men and women may not like his choose on single-digit millionaires possibly (Cardone did not answer to Fortune’s request for remark). Following all, netting $1 million doesn’t happen right away for most individuals. It’s a challenging internet worth to realize when you’re in the actual center class, which the Pew Study Centre defines as a single individual earning in between $30,003 and $90,010 or a family members of four getting home $60,000 to $180,000.

Now, the hypothetical 30-12 months-aged millionaire Cardone speaks of does fall into that middle course bracket if they are dwelling off $48,000 for the up coming 21 several years. But the example is really unlikely: Most folks aren’t striving to retire at this age, until you’re section of a smaller subset aiming to sign up for the Hearth motion, and people who do frequently rely on passive earnings, which Cardone did not account for.

One million bucks is quite out of arrive at for the common joe the normal American household has a median financial savings of $5,300 (the normal, which is skewed by higher earners, is a bit improved at $41,600). When one’s internet truly worth also contains assets like actual estate and motor vehicle possession, both equally of these investments have develop into significantly less attainable to the middle course the past number of years many thanks to a blend of rising inflation, aggressive marketplaces, and significant interest costs.

Although the center course was ready to sock away some significant money through the pandemic, their golden period has given that light as the economic climate rebounded and 40-calendar year-high inflation took above. About 8 in 10 center class households in America report chipping absent at their financial savings to retain up with a higher charge of living, according to a Primerica survey. Whilst lots of higher-course homes bought raises to preserve up with the rate of inflation, middle class people didn’t see the exact same wage boosts—contributing to the previously shrinking center course.

Sure, the wealthy are worried—but that does not make them middle course

Sure, even the rich have been feeling a minor uneasy thanks to inflation and a rocky inventory marketplace. Much less than fifty percent (44{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) of all millionaires feel “very comfortable” about their finances (despite the fact that which is nevertheless twice as many as all respondents), according to a study from Edelman Economic Engines. And 29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of millionaires say they really don’t come to feel rich.

Which is possibly since today’s overall economy is obtaining a destructive impact on typical fiscal benchmarks take into consideration that much more than 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Us residents raking in about $100,000 every year sense they are dwelling paycheck to paycheck. And $1 million is no lengthier generally sufficient for a at ease retirement.

“While it is even now an excellent level of achievement, it is questionable irrespective of whether that amount is sustainable as a resource of life time income, supplied enhanced longevity and large inflation,” Michele Lee Wonderful, founder and CEO of Cornerstone Wealth Advisory, told Fortune’s Alicia Adamczyk of retiring on $1 million.

But it can continue to be done with good budgeting. “A million dollars is not what it utilized to be, but it can nonetheless supply a relaxed retirement if performed proper,” Gates Tiny, president and CEO at the Southern Financial institution Organization, explained to Adamczyk. Even if Cardone’s aforementioned case in point was applied to another person who retired at the entire retirement age of 66, it would previous them till they’re 87—maybe not the complete duration of retirement for some, but yet again, that illustration does not include passive money or Social Safety advantages.

Of class, becoming a solitary digit millionaire usually means various points in different cities it probably will not give another person as substantially economical protection in large-expense metropolitan areas like New York City or San Francisco as it may possibly in a non-metro area. Although Individuals consider it requires a $2.2 million internet well worth to be wealthy, their normal for remaining economically comfortable—which just one could possibly equate with the middle class—is $774,000.

But just for the reason that the benefit of $1 million has depreciated doesn’t imply it’s not a lot of income, as Cardone implies. A net truly worth of $1 million that’s well invested is almost nothing to sniff at.

This tale was initially showcased on Fortune.com

Extra from Fortune:

Median home price in metro Denver down in February

Median home price in metro Denver down in February

Metro Denver one-family members house prices, just after dancing in between an once-a-year reduction and attain in January, crossed more than to the dim aspect with equally ft in February.

The median price of a solitary-family property offered in metro Denver very last month was $600,000, down 5.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the identical month a year before, in accordance to a monthly update from the Denver Metro Association of Realtors. That drop happened irrespective of far more strong action in February, which includes a .8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} leap in median rates from January.

The once-a-year drop in median revenue charges for condos and townhomes was not as huge at 1.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and the month to month obtain was much more strong at 1.14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Normal rental price ranges had been still in good territory at 3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the year. The median cost of a condominium sold was $400,000.

In January, the median revenue selling price of a solitary-loved ones property was down .68{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} but the typical profits selling price was up 1.94{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, making it way too shut to phone a slipping marketplace. But in February, the regular selling price was down 1.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Metro Denver is again in the depreciation zone, and it is not alone.

Before on Thursday, the genuine estate brokerage Redfin introduced that U.S. property price ranges fell on an annual foundation for the initially time considering the fact that February 2012, a reversal it attributed to 30-calendar year house loan rates rising back higher than 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} soon after rates closer to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} breathed some lifestyle back into the industry at the start off of the calendar year.

“Prices falling from a 12 months in the past is a milestone simply because it hasn’t occurred given that the housing sector was recovering from the 2008 subprime property finance loan crisis. But it’s not shocking and in quite a few techniques, it is welcome,” explained Redfin Deputy Chief Economist Taylor Marr in a launch. “Home prices skyrocketed so substantially around the very last several yrs that they had been most likely to arrive down when charges rose from historic lows.”

Selling prices peaked late very last spring in metro Denver and the strong gains captured early in 2022 are earning for some tricky comparisons. Metro Denver saw a drop in home charges in Might 2020 in the course of the pandemic, but that speedily reversed right after the financial system reopened. The final time home revenue costs had been negative was in 2011, when the sector was even now recovering from the housing bust and Fantastic Recession.

While value declines build extra favorable conditions for purchasers by strengthening affordability, they are not superior information for anybody who stretched to get anything in the initial 50 percent of past yr with a tiny down payment.

The variety of closings for each homes and condos rose by 22.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from January to 2,661 in February, but activity continues to be down by nearly a quarter from the exercise observed in February 2022. The quantity of lively listings fell 8.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the month to 3,778, the second-premier fall on file. But it is up 208.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a 12 months before when the stock of properties for sale was at history lows.

In other signals of a strengthening market place in terms of exercise, new listings ended up up 20.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from January and pending gross sales, a measure of upcoming exercise, rose 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, indicating momentum heading into March. And listings have been turning over a lot quicker, paying out a median of 25 days prior to finding a buyer in comparison to 34 days in January. 

“Buyers are viewing charges carefully and patiently waiting around for new stock to strike the marketplace,” mentioned Libby Levinson-Kataz, head of the DMAR Sector Developments Committee, in opinions accompanying the group’s report. “They are much more discerning about house selling prices, a lot less keen to contend and will only leap into a bidding war if the house is go-in prepared and satisfies their needs.”