The property advancement market place is bracing for a bumpy highway.
Two of the major house improvement vendors, Property Depot (Hd) and Lowe’s (Lower), warned of softness in the market in the latest earnings reviews, indicating the year in advance is probable to be a tricky 1 as inflation weighs on shoppers.
“In 2023, residential expenditure will be underneath some strain, provided elevated concentrations of inflation, greater interest charges and a a lot more careful client,” Lowe’s CFO Brandon Sink told analysts on the earnings call on Wednesday. “We are forecasting a slight decline in the house-improvement current market.”
“We do assume moderation in dwelling enhancement demand,” House Depot CEO Ted Decker told analysts on the company’s earnings meeting phone very last week. “Persons are also setting up to change shell out extra in the direction of companies. And as we have said, we see some a lot more value sensitivity,” he additional.
The warning comes as Lowe’s (Lower) posted a blended quarter on Wednesday prior to the industry open up.
The retailer documented adjusted earnings for every share of $2.28, topping over analysts expectations for $2.21. Profits missed estimates, coming in at $22.4 billion against anticipations for $22.7 billion, according to facts compiled by Bloomberg.
“The slower start off to the quarter was owing in section to slower gift buying demand in the course of the holiday break period, about just one-third of product or service combine is discretionary in nature,” Bobby Griffin, an analyst at Raymond James, wrote in a be aware to clients next the outcomes.
For 2023, Lowe’s is forecasting sales to be between $88-$90 billion, though similar-retail outlet-revenue are believed to be flat or down 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year. Executives see the pullback in Diy demand from customers as transitory, and other experts in the marketplace see a “historic boom” coming for residence transforming.
Nick Teichtmann (R,) with the help of Lowe’s personnel Jaime Solis, purchases lumber to renovate his residence by incorporating a gazebo on best of a deck and repairing his garage at Lowe’s residence improvement retailer on April 11, 2011 in Burbank, California. (Picture by Kevork Djansezian/Getty Illustrations or photos)
“Disposable own earnings, which I pointed out, is about $1.5 trillion in cost savings earlier mentioned pre-pandemic amounts,” CEO Marvin Ellison explained to analysts on the earnings simply call.
Ellison pointed out the regular equity for residences in the U.S. is about $330,000, and anticipations of growing older housing inventory could place to continued desire for home upgrades.
“Two-thirds of every little thing we market is non discretionary. And there are other tailwinds, millennial household development trend, little one boomers ageing in location and additional widespread sustainable remote work, so all of these matters give us some self-assurance that the backdrop remains supportive,” Ellison additional.
Shares of both equally Residence Depot and Lowe’s are down over 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the very last month.
Lumber deflation
The times of pricier lumber could be more than.
The housing slump has triggered a crisis in lumber, with lumber futures falling 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the earlier calendar year. And homebuilders are using observe.
Pulte Group (PHM) introduced in their hottest earnings get in touch with the company is picking up their pace of design amid elevated lumber stock and more inexpensive pricing.
A be aware from analysts at UBS published very last month claimed some authorities in the homebuilding room see kitchen cabinetry and home windows, fairly than larger framing or roofing initiatives, driving desire for lumber.
And however lumber selling prices have fallen sharply, the firm pointed out for quite a few “main” housing solutions charges “have reverted to ‘reasonable levels,’ but [builders] are not witnessing any authentic rate reductions from sellers.”
As just one expert explained to the company, most solutions are “in no way going [to] pre-Covid rates once again.”
Dani Romero is a reporter for Yahoo Finance. Follow her on Twitter @daniromerotv
As significant home rates and home loan fees force many property owners to stay place rather than trade-up, a whopping 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners are hunting to make their current dwelling space more comfy this yr, in accordance to a new survey.
But as inflation continues to drive up material expenses, many are turning to Do-it-yourself initiatives to preserve funds.
For occasion, even though the consumer-price tag index, a measure of inflation, moderated to 6.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January from a year before, the value of flooring coverings rose 13.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and the selling prices of resources, hardware and materials went up by 11.8 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, in accordance to info introduced before this week by the Labor Division.
How are house owners handling increasing fees of home enhancement assignments?
In a survey of nearly 3,700 American property owners by Today’s Homeowner, almost 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of respondents stated they have been arranging to commit “significantly” a lot less as opposed to very last calendar year, 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homeowners mentioned they were being preparing to tackle at the very least just one home renovation project this yr.
“If you preferred to get new furnishings or if you preferred to paint your residence, or if you preferred to set new siding up outdoors, if you required to make a deck, seriously everything linked to enhancing your residence, we uncovered that this category, was about 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a lot more expensive,” Hailey Neff, a researcher on the study explained to United states of america These days. “For a large amount of home owners, DIY challenge has develop into a extra extra economical way of accomplishing it.”
Property owners in some states are tightening their purse strings much more than other folks. A lot more than 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners in four states (Connecticut, Wisconsin, New Mexico, and Nebraska), 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} reported they system to minimize their investing on home improvement projects in 2023.
With these assignments, lots of property owners are frequently on the lookout to enhance their residing room. Approximately 69{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of respondents listing this as a main rationale for seeking to full their prepared property enhancement projects in 2023. The future-most common cause for seeking to full one particular or much more renovations is to repair a little something damaged (53.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of respondents).
Only about 13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of house owners listing renovations prior to listing a residence for sale as a person of their key factors for using on improvement assignments.
How are house owners paying out for home enhancement tasks?
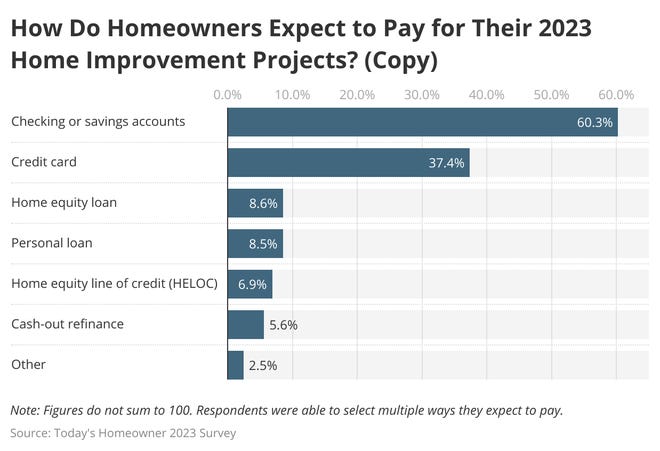
Around 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of respondents stated they expect to pay out for initiatives applying cash from examining and cost savings accounts (60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). On top of that, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners cite credit rating playing cards as a single of the means they will spend for enhancement initiatives.
Less property owners anticipate to switch to financing solutions, and of these, practically 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} report residence equity and personal loansas their most popular selections.
Owing to volatile and elevated mortgage charges, fewer home owners are intrigued in a residence equity line of credit history (HELOC) or hard cash-out refinancing as means to fund their residence enhancement. In a HELOC, desire costs are normally variable, that means that homeowners may perhaps be on the hook to shell out a higher fee if curiosity costs keep on to rise. In the meantime, a funds-out refinance is only advantageous when existing mortgage rates are lower than the existing fee, which may well not be the case for several owners these days, in accordance to Today’s Home-owner.
Do it yourself your property enhancement job?
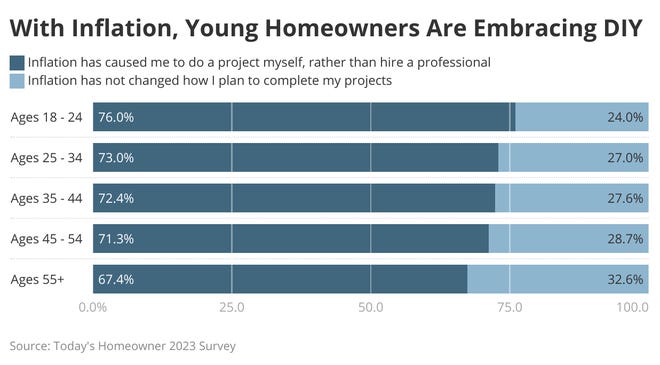
About 71{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of home owners say that inflation has caused them to do a challenge by themselves rather than use a experienced.
The craze is even more pronounced for Gen Z and Millennials. Around 76{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homeowners amongst the ages of 18 and 24 are performing a job on their own alternatively than selecting a contractor due to inflation. For people under 44, that selection is shut to 73{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
The survey also found that property owners in distant parts appear to be to desire Do it yourself, possibly indicating a trouble in discovering nearby industry experts. 8 of the top 10 states with the most Diy-leaning owners in this analyze have a population of five million or significantly less.
Swapna Venugopal Ramaswamy is a housing and financial system correspondent for United states Now. You can follow her on Twitter @SwapnaVenugopal and signal up for our Daily Money newsletter here.
Though it does not impact our views of goods, we could receive compensation from companions whose offers look in this article. We’re on your facet, generally. See our whole advertiser disclosure.
Dwelling costs hit all-time highs in 2022, with the median price escalating by 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from January 2020. Superior property finance loan rates have slowed down the housing market place noticeably, with Redfin predicting that the median U.S. residence rate could fall by shut to 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, publishing the very first 12 months-in excess of-calendar year drop in a decade. House profits will also drop, falling to the least expensive amount considering the fact that 2011, a drop of 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2021. When lots of places are presently experiencing a decrease in prices, some are predicted to be even a lot more costly this 12 months.
Places in which rates will fall the most
Pandemic migration hotspots like coastal metropolitan areas and those in the Sunlight Belt noticed the major raises in the housing market place frenzy in the aftermath of COVID-19. Home charges in Malibu, California surged by 82{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the 1st quarter of 2021 to 2022. The East Coastline also saw history gains, with the regular dwelling cost of the Hamptons in New York escalating by 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and the variety of houses readily available slipping to a history small.
Residence costs went up the most in metropolitan areas these types of as Austin, Boise, and Phoenix, locations that were being prime places during the initial period of the pandemic. These spots are envisioned to see the most unstable charges considering the fact that there is a ton more room for selling prices to fall when compared to parts that failed to see as a lot growth.
Costs that will see costs go up
Local weather-dangerous areas like the hills of California and oceanfront house in Florida will see costs proceed to go up mainly because of to significant coverage expenditures. According to Redfin’s information, disaster coverage premium premiums will go on to increase, offsetting any price tag declines in these spots. Insurance policy premiums in Florida enhanced by 33{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} past calendar year, and are expected to go up even a lot more because of to Hurricane Ian, the deadliest hurricane to strike the point out of Florida due to the fact 1935. The hurricane was also the costliest in Florida’s background, triggering $113 billion in damages.
Numerous insurers have stopped issuing procedures on large-fire-danger properties in California. This means that the only insurance plan businesses house owners in these spots have to access are two to three instances additional high-priced. Even FEMA flood insurance rates have absent up. With disaster insurance plan essential for a home loan in these high-risk spots, the vast majority of individuals who can pay for these varieties of residences are the wealthy all-hard cash buyers.
Obtaining a residence is the most pricey obtain a lot of individuals will ever make in their lives. When using into thing to consider the complete expenses of homeownership, make positive you just take into account coverage, residence taxes, and maintenance fees prior to you pull the trigger on purchasing a home. The remarkable enhance of insurance coverage rates will offset any dwelling selling price decreases noticed in some locations. Getting a household need to be based mostly on your particular economic circumstance and it is significant to funds all the fees you can count on to incur.
We are firm believers in the Golden Rule, which is why editorial thoughts are ours alone and have not been previously reviewed, permitted, or endorsed by involved advertisers. The Ascent does not cover all provides on the marketplace. Editorial information from The Ascent is separate from The Motley Idiot editorial material and is created by a diverse analyst crew.The Motley Fool has a disclosure plan.
The Motley Idiot is a Usa Currently content husband or wife supplying financial information, investigation and commentary designed to help persons acquire regulate of their economic lives. Its content is developed independently of United states of america Nowadays.
Our picks for the very best credit score cards
Offer you from the Motley Fool: Our experts vetted the most popular delivers to land on the choose picks that are worthy of a spot in your wallet. These ideal-in-class cards pack in loaded perks, these kinds of as significant signal-up bonuses, extended {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} intro APR features, and robust benefits. Get started today with our suggested credit cards.
The California housing market
continues to cool
from the pandemic buying frenzy, with some areas seeing home prices decline for seven months in a row.
Among the factors fueling the decline have been inflation, economic uncertainty and soaring interest rates, experts say. The average monthly mortgage rate was 6.15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the week ending Jan. 19, up 73{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a year ago.
Even so, home value growth in some California outlier neighborhoods has bucked the trend, continuing to rise even as parts of San Francisco and Los Angeles push further into the red, according to the latest data from real estate listings site Zillow.
While the increases in the hottest ZIP codes over the past six months don’t match the torrid pace of the early pandemic months, experts say they are encouraging signals for the market as a whole.
Largest increases in Southern California
Six Southern California ZIP codes made the top 10 for highest home value growth from June-December 2022. Five of those were in Imperial County, at the southeastern tip of the state.
At No. 1 statewide was the 92250 ZIP code in the Imperial County city of Holtville. The typical home value there was $316,377 in December 2022, up 10.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, from $287,049 in June 2022, according to Zillow. At No. 2 was 92274 in Thermal in Riverside County with 8.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth, followed by three more Imperial County ZIP codes.
The 92251 ZIP code in the city of Imperial was third on the list, with home values jumping 7.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from $385,318 in June to $414,327 in December. Right behind it at No. 4 was 92231 in Calexico, with a 7.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} bump from $344,659 in June to $369,307 in December. In fifth place was El Centro, where home values rose 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the six-month period. Also in the top 10 was Brawley in Imperial County, at No. 7, with a 5.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase.
Zillow’s estimates for typical home value are based not only on the prices of recently sold homes, but also on the estimated value of all homes within a ZIP code based on the selling price trends of similar homes in the area.
Home values for the six months ending in December 2022 increased 5.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in six ZIP codes in Imperial County, including in Calexico where this home is located, according to data from Zillow.
Courtesy of Carla Ramos
Carla Ramos, a real estate agent in Imperial, said she wasn’t surprised that ZIP codes there were among the hottest in the state for real estate value.
“Right now inventory is low,” she said, and available homes are snapped up quickly. “A lot of investors from San Diego and L.A. come to buy cheaper properties, and lease for a great amount of money.”
She said there are a lot of renters in the area, and available units are hard to come by. While the city of Imperial is seeing housing growth, she added, new construction is rare in the rest of the county, which has further constrained supply.
According to the U.S. census, the median age in Imperial County is 32.8 and the population is 86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Hispanic, with a median household income of $51,809.
Residents of Imperial County, which borders Mexico and is home to two state prisons, typically include corrections officers, teachers, law enforcement — including many who work for U.S. Border Patrol — and health care workers. Farms, meat processing plants, the solar panel industry and construction companies are also major employers, but many of their workers live in Mexico and cross the border daily because it has become too expensive for them to live in Imperial County, Ramos said.
Home buyers include younger people who have stable jobs and are looking for starter homes, as well as families, many living in multigenerational households.
Ramos said she doesn’t see the demand stopping anytime soon, “unless they build 1,000 homes … but nothing is being built” in Imperial County, she said.
Coastal towns see positive growth
Over on California’s coast, ZIP codes in the cities of San Luis Obispo, Santa Cruz and Santa Barbara also landed in the top 15 for home value growth in the past six months.
The ocean remains a perennial draw, including for many who can’t or don’t want to pay tip-top prices, real estate experts said.
“There is demand from people who want a coastal lifestyle and are looking for places relatively less expensive,” said Matt Kreamer, director of brand communications for Zillow. “You wouldn’t necessarily think of Santa Cruz as a bargain, but compared to some of the nearby coastal areas, there are bargains to be found.”
The 93110 ZIP code on the west side of Santa Barbara saw home values increase 2.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, from $1.88 million to $1.93 million, from June to December 2022.
According to the U.S. census, the ZIP code has a median age of 43.4, a median household income of $99,261 and a population that is 63{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} white and 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Hispanic.
Home values in the 93110 ZIP code in Santa Barbara increased 2.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the six-month period ending in December 2022, according to Zillow.
Randy Solakian Estates Group
The ZIP code includes the high-end oceanfront community of Hope Ranch. Randy Solakian of Randy Solakian Estates Group, who has current listings in the community, called it “a little bit of utopia” because it is safe and private, while still offering activities, good schools and cultural amenities.
“Many families with school-aged kids are very determined to buy a home in Hope Ranch,” he said. “A lot of people come in without families too, mature adults with grown kids and grandkids who want a place for family gatherings and holidays.”
Properties in Hope Ranch range from a minimum of 1 to 2½ acres, all the way up to 50 acres, Solakian said. He added that it’s not a gated community, but it has private roads and beach access, and also offers equestrian trails dating back to the community’s founding in the 1920s.
No highways or railroads run through the community, and oceanfront views are unimpeded, making it especially unique and desirable, he added.
Hope Ranch also encompasses a private school, golf club and country club, and while those amenities aren’t free, many join as members, Solakian said.
The community was also untouched by the devastating 2017 Thomas Fire
— the eighth-largest
wildfire in state history — making it more attractive to home buyers, he said.
While buyer demand has cooled slightly “coast to coast” in the past six months, Solakian said Hope Ranch in 93110 is among the exceptions. He cited low inventory as a contributing factor.
“There’s not a lot of sellers,” he said, “so if somebody qualified comes in and wants a property, there’s very few options, which helps maintain price stability.”
Bay Area, L.A. see big declines
San Francisco and Los Angeles counties dominated the list of California ZIP codes with the biggest home value declines in the past six months.
The biggest drop from June to December, 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, was in the 91108 ZIP code encompassing San Marino, a wealthy enclave near Pasadena.
Neighboring 91030, which includes South Pasadena, saw the second-biggest home value decline of 12.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past six months.
The third-biggest decline was the 94116 ZIP code on the west side of San Francisco, encompassing the Sunset, Inner Parkside and Forest Hill neighborhoods, as well as part of West Portal. Home values there declined 10.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Home values in the San Francisco metro area — which includes Alameda, Contra Costa, San Francisco, San Mateo and Marin counties — have taken the biggest hit among all large U.S. metros since mid-2022, declining 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} since the start of May, according to Zillow data.
However, despite the declines, already-pricey Bay Area real estate soared into the stratosphere during the first half of the pandemic — and as a result, it remains
among the most expensive in the country, and home values are still elevated compared with a year ago in many ZIP codes.
While some people living in these areas may worry about their overall home values and what that means for their investments, Kreamer said he sees no cause for concern.
“Even in the three ZIPs that have seen the sharpest downturn, home values are still up between nearly 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and more than 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} since 2019,” he said. “It wasn’t possible for home values to continue to skyrocket 15-20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} like they did in late 2020 through 2021, and this correction is putting the market back toward something more normal and balanced.”
He added that those looking to buy in the areas with the most significant declines are at an advantage, as they “have more time to shop and make decisions, and are less likely to face a bidding war.”
Over the next few months, Kreamer said he expects “more of the same, as the market continues to rebalance from the pandemic surge.”
“The places that are the most expensive — and the ones where prices grew the most during the pandemic — will continue to cool the fastest,” he said, “and the less expensive markets will continue to stay the hottest, relatively.”
Kellie Hwang is a San Francisco Chronicle staff writer. Email: kellie.hwang@sfchronicle.com Twitter: @KellieHwang
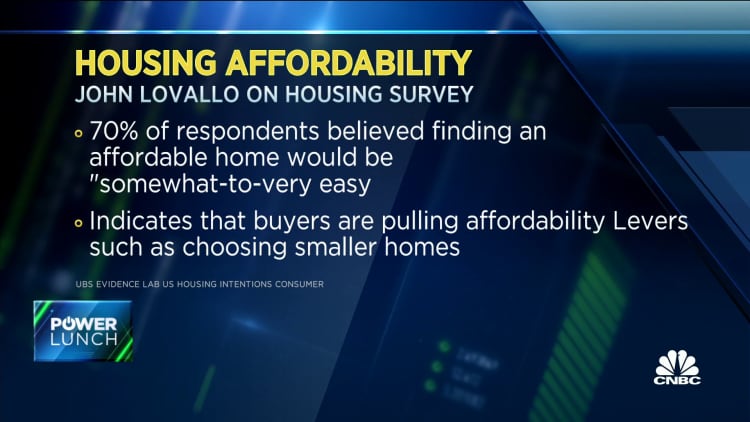
Mortgage charges are still 2 times what they have been a calendar year in the past, but household selling prices have been falling considering that June, and which is finally producing people feel far better about what experienced been an overheated, extremely aggressive housing market place.
A every month housing sentiment index from Fannie Mae confirmed sentiment increasing from November to December. The index is continue to reduced than it was a year ago and just a bit off its file reduced established in October and November.
related investing information
The share of respondents stating now is a very good time to invest in a home was nevertheless low, at just 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, but it was up from 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in October. The share saying now is a negative time lowered.
On advertising, on the other hand, sentiment ongoing to fall. The share of respondents indicating now is a excellent time to offer dropped to 51{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 54{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, while the share indicating now is a terrible time to promote elevated.
Future purchasers watch a true estate showing.
Carline Jean | Sunshine Sentinel | Tribune Information Service | Getty Pictures
Much more individuals now believe household rates will drop in the next 12 months, and additional also claimed they believe property finance loan costs will arrive down.
Prices in November, the most the latest measurement, ended up 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} reduced than the spring 2022 peak, in accordance to CoreLogic. They ended up however over 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} larger yr more than calendar year, but that once-a-year comparison is now half of what it was in June.
The regular price on the popular 30-calendar year preset house loan hit a the latest large of 7.37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in October but then fell back again into the mid-6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} vary in the course of November and into December. As of last Friday it had dropped to 6.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, in accordance to Mortgage News Day-to-day.
“As we enter 2023, we hope affordability to keep on being the best challenge for prospective homebuyers, as even small declines in costs and residence prices — from the point of view of the consumer — may well not develop adequate acquiring electrical power,” explained Doug Duncan, Fannie Mae’s senior vice president and main economist, in a launch. “At the very same time, existing owners may perhaps keep on to hold out to listing their properties, considering that a lot of have already locked in lessen home finance loan fees, creating negligible incentive to promote and buy once again until premiums are a lot more favorable.”
That pressure will go on to travel household profits decreased in the coming months, Duncan explained.
Introducing to the confidence in housing, the share of customers who mentioned they have been involved about getting rid of their work in the upcoming 12 months dropped from 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Much less, nevertheless, explained their domestic profits is significantly greater than it was a year ago.
With the housing current market now in its traditionally slow winter season, some brokers are reporting action is “frozen.” Pending home revenue, which symbolize signed contracts on existing houses, dropped much more than anticipated in November, suggesting that closed product sales in January will be decreased as perfectly.
Those sellers who are braving the housing chill are supplying extra concessions: About 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of sellers did so in the fourth quarter, the best share in modern several years, in accordance to Redfin, a authentic estate brokerage. That is up from just above 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in both the previous quarter and the fourth quarter of 2021, and is better than the previous large of 40.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, notched throughout the three months ending July 2020, at the start off of the Covid pandemic.
Even though it is quite distinct that pressurized housing affordability has brought on some deflation in the U.S. housing current market, sector insiders remain divided on what the ongoing household price correction will look like in 2023. The reason? Desire and provide are sending blended indicators.
On the housing desire entrance, things continue being slumped with mortgage loan invest in purposes (down 38{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-above-12 months) presently just down below their cheapest place for the duration of the 2000s housing crash. On just one hand, if financial problems ease and mortgage charges drop in 2023, homebuyer demand from customers would increase. On the other hand, the pandemic’s housing need growth could’ve had a pull-ahead influence that results in a slower than envisioned article-pandemic housing market.
On the housing supply front, things continue to be fairly limited nationally. Whilst spiked home finance loan fees corresponded with a big decrease in demand, it hasn’t brought on sellers to hurry for the exits. In point, new listings on Real estate agent.com are down 17.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on a 12 months-more than-yr foundation. A lot of purchasers who would generally be seeking to move up to a greater residence have postponed the change mainly because they don’t want to give up their preset 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} house loan rates they have for their latest household.
So do consumers (for whom very low desire is a probable tailwind) or sellers (for whom limited source is a likely tailwind) have the higher hand? One particular of the ideal indications could be the route of inventory—and its velocity of improve. At initial look, it may be uncomplicated to think that stock (i.e. active listings for sale) is only a measurement of supply, however, it’s also a measurement of need. If homebuyers pull back again, and properties sit on the marketplace for a longer period, that can boost inventory degrees (at present up 46.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months-about-yr) even if new listings (at present down 17.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} calendar year-above-calendar year) decrease.
Let’s choose a nearer look at inventory information in the nation’s 400 major markets.
Soon just after home finance loan rates spiked this spring, the overheated U.S. housing current market cooled. That swift pullback in purchaser need ultimately gave stock breathing area to rise.
Although national stock stages on Real estate agent.com are up 46.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yr-above-year, the photo may differ noticeably by sector. Towns like Austin and Phoenix have witnessed their respective inventory concentrations soar 160.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 176{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In the meantime, markets like Chicago and New York City continue being effectively unchanged.
Why are inventory ranges spiking in some markets and flat in others? Very well, for starters, fundamentals.
Each quarter, Moody’s Analytics assesses whether community fundamentals, such as local income degrees, can aid neighborhood residence charges. If a regional housing marketplace is “overvalued” by much more than 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Moody’s Analytics deems it “considerably overvalued.” The Pandemic Housing Increase noticed the “considerably overvalued” camp skyrocketed from 3 markets in the next quarter of 2019 to 210 markets by the 2nd quarter of 2022. These frothy marketplaces include things like places like Boise (“overvalued” by 74{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Austin (“overvalued” by 61{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
Quick-ahead to now, and those “substantially overvalued” marketplaces, on combination, are shifting faster. The inflow of higher-earning remote personnel saw residence costs in boomtowns, like Boise and Idaho Falls, detach from local incomes. Of system, that becomes a trouble when both equally remote employee migration slows and a 1981-stage mortgage loan level shock leads to quite a few area would-be borrowers—who ought to meet up with lenders’ rigorous debt-to-revenue ratios—to eliminate their home finance loan eligibility. Cue falling home prices.
In complete, there were 751,544 lively listings on Real estate agent.com in November 2022. That is up from 511,899 listings in November 2021 and 683,606 energetic listings in November 2020. Having said that, the number still continues to be considerably down below the pre-pandemic active listing count of 1.14 million in November 2019.
Some companies, like CoreLogic and Residence.LLC, question that U.S. property selling prices will fall in 2023 with inventory remaining this restricted. Researchers at Morgan Stanley say individuals housing bulls must rethink their stance.
“The truth that we count on residence rates to begin slipping on an yearly basis in March 2023 irrespective of restricted inventory reflects how unparalleled this affordability predicament is in the U.S. housing sector,” writes Morgan Stanley researchers who expect U.S. residence prices to decrease by close to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from peak-to-trough even though provide stays down below 6 months of inventory.
How can residence prices drop even if inventory stages continue being down below pre-pandemic stages?
“When demand from customers abruptly falls off a cliff, the complete amount of supply isn’t really as suitable. This is in which viewing the level of change on equally offer and desire separately is critical,” Rick Palacios Jr., director of investigation at John Burns True Estate Consulting, tells Fortune. “Investors accounted for the optimum share of prospective buyers ever this [housing] cycle in numerous markets. The lion’s share of individuals buyers are now on the sidelines, with some needing to provide provided overleveraged and genuinely had been just using a flyer on house price tag appreciation continuing to rip better. These days are now about, and these sellers don’t show [the] identical psychological/behavioral features connected with classic operator-occupiers, which traditionally retains property price ranges fairly sticky on the downside. Builders also account for around two times their historic current market share norm when it comes to for sale housing source in the system (denominator there is resale offer additionally new dwelling supply below construction and finished stock). Builders fulfill the market place on price tag while traditional entrepreneurs are not as swift to fall selling prices.”
“It really is pretty probable we see offer rise arrive spring, which is standard. New household offer in particular ought to rise, as we know concluded homes (completions) are now growing and builders have a large amount a lot more unsold households nonetheless beneath development doing work by way of the procedure,” Palacios tells Fortune. “This will be the 1st spring promoting period because 2008 the place property finance loan fees are ~6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, so we’re expecting a bumpy experience in common for sellers, specially if the overall economy is officially in a economic downturn.”
Anytime a team like Morgan Stanley or John Burns Real Estate Consulting suggests U.S. home costs, they are chatting about a countrywide aggregate. What ever comes upcoming will undoubtedly differ by current market.
Amongst the country’s 400 largest housing markets, 36 marketplaces are back again to pre-pandemic housing concentrations. The searchable chart (in alphabetical order) over shows all those 36 markets.
In idea, better stock stages could depress dwelling costs in individuals marketplaces.
Among the the country’s 400 biggest housing marketplaces, 364 marketplaces continue to be underneath pre-pandemic inventory degrees. The searchable chart (in alphabetical purchase) over displays those people 364 marketplaces.
Though Morgan Stanley scientists you should not feel restricted stock will avoid house costs declines, they do imagine limited stock concentrations will reduce a 2008-style crash.
“Whilst provide isn’t going to preserve household value growth floored at zero, we do imagine it prevents residence rate declines from getting also huge” writes Morgan Stanley scientists.
Want to remain current on the housing downturn? Abide by me on Twitter at @NewsLambert.
Our new weekly Impression Report publication examines how ESG information and tendencies are shaping the roles and obligations of today’s executives. Subscribe listed here.