Dubai, Miami top list of best luxury real estate markets for 2023

Dubai, Miami top list of best luxury real estate markets for 2023

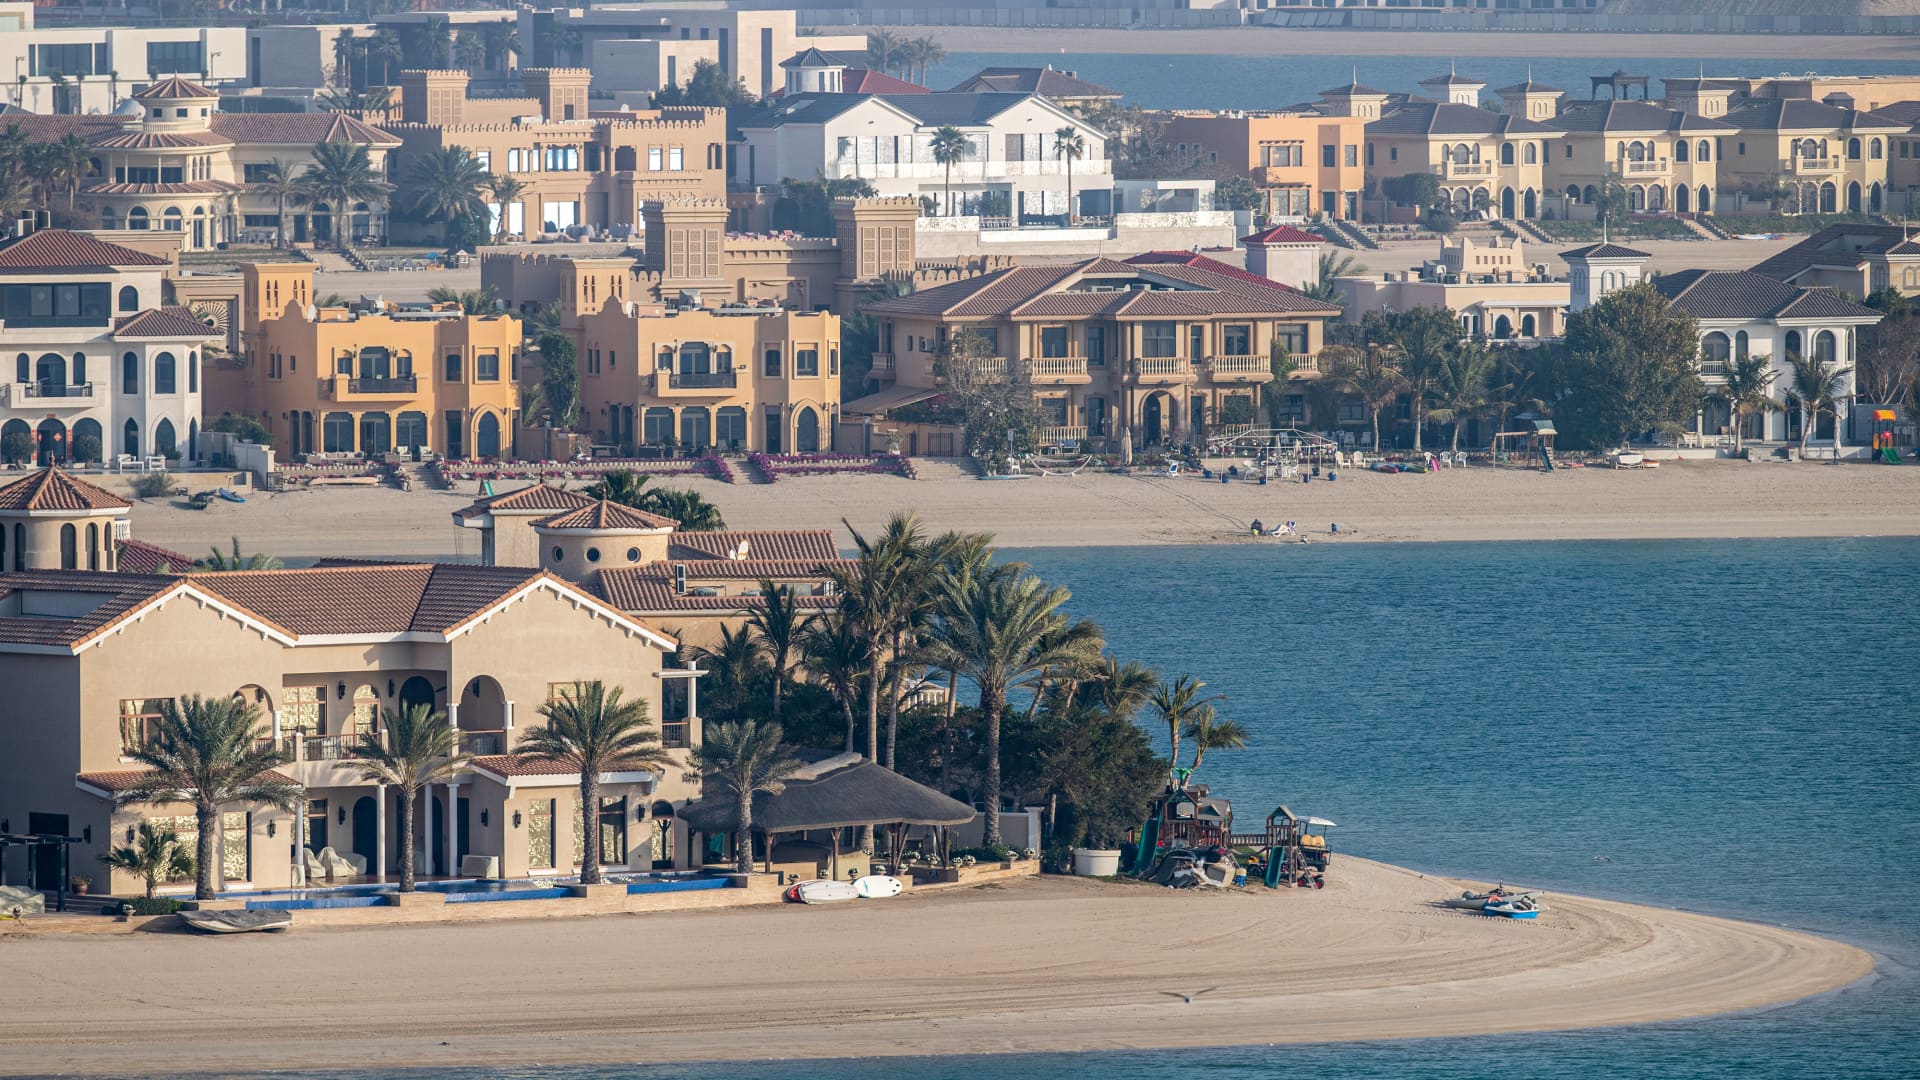
Residential villas on the waterside of the Palm Jumeirah in Dubai on Feb. 24, 2022. Russians were normally amongst the top 10 nationalities investing in Dubai house, according to Tahir Majithia, managing lover at Dubai-primarily based Primary Money genuine estate.

Christopher Pike/Bloomberg by using Getty Photographs

Wealthy buyers betting on luxurious real estate would do ideal by putting their dollars in Dubai or Miami subsequent 12 months, according to a new report.

In a rating 25 of the world’s major luxury, or “key,” authentic estate marketplaces, Dubai topped the listing, with selling prices predicted to enhance 13.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, in accordance to genuine estate consultancy Knight Frank. Miami ranked second, with selling prices envisioned to increase 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Dublin, Lisbon and Los Angeles adopted, with 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} anticipated boosts.

The worst performers upcoming calendar year are anticipated to be Seoul and London, with costs predicted to drop 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for equally. New York rated in the middle of the pack, at 13, with prices predicted to increase 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} following calendar year.

However, even the strongest luxurious marketplaces are expected to great subsequent year, as desire premiums increase and economies gradual down, according to Knight Frank. Across the 25 cities, Knight Frank expects prices to rise by an common of 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, revised down from the 2.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Knight Frank projected 6 months back.

The revision implies that the world rich, seemingly immune from inflation and economic slowdowns, are keeping off on large actual-estate buys or turning into much more discerning on price tag presented mounting interest fees.

“Though key marketplaces are far more insulated to the fallout from better home loan expenditures, they are not immune,” the report claimed. “The transition from a seller’s to a buyer’s industry is previously underway throughout most key residential markets.”

Dubai observed rates soar by 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022, so the selling price increases for 2023 mark a considerable slowdown. Dubai has found a surge in rich people in excess of the past yr, pushed mostly by Russians seeking for a risk-free harbor for their prosperity, yachts and real estate amidst Western sanctions over the war in Ukraine.

Selling prices for Dubai one family residences rose 13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in October, although over-all sales volume jumped 73{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in excess of the prior calendar year.

Miami also remains a preferred haven for the rich, given its reduced tax fees and escalating variety of economic firms finding their headquarters or offices in South Florida.

Even though New York’s predicted 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} enhance upcoming year is down from 2022, many brokers forecast declining rates upcoming calendar year, primarily in Manhattan. Knight Frank mentioned New York will benefit from abroad consumers who are “in search of additional, somewhat than fewer, publicity to the U.S. dollar as the Federal Reserve ramps up charges.”

Singapore is the only Asian town in the top 10 and one of only four metropolitan areas whose forecast has climbed in the previous 6 months, in accordance to the report. Singapore is benefitting from prosperity flight from China, as abundant Chinese citizens move their income – and usually their family members – to the island to stay clear of strict Covid lockdowns and a slowing economic climate.

Funds will be king across the 25 marketplaces, as customers keen to pay out all-money will be additional attractive to sellers, Knight Frank mentioned. Political and economic volatility in numerous nations will also guide to a flight to protection in genuine estate, “pushing buyers to experienced and transparent luxury marketplaces.”

The Real Estate Markets Seeing The Biggest Downturns In Home Prices And Property Values

The Real Estate Markets Seeing The Biggest Downturns In Home Prices And Property Values

The only lousy factor about the very best functions is that no make any difference how fantastic they have been, the excellent situations just cannot go on forever.

Investing is normally cyclical and even investments like authentic estate which have performed above time will have undesirable cycles. It absolutely seems as if the Federal Reserve’s conclusion to raise curiosity rates has finished the increase interval of strong gains that buyers savored after the 2008 crash.

It’s impossible to stay away from the truth that several true estate marketplaces that had been scalding hot as a short while ago as a year in the past have gone ice cold. This time last calendar year, the “seller auction” was almost commonplace. A seller would listing a residence for sale in a sizzling market, and a flood of gives would appear in over the inquiring price.

Consumers had been bidding versus each other, and it obtained so extreme that some purchasers were being sending photographs of their family members and customized letters to the seller. A lot of major U.S. cities noticed the typical dwelling price tag strike the million-dollar mark, and even fixer-uppers had been providing in the higher $800,000 variety. Sellers and authentic estate brokers were being pretty much having the time of their lives. Then the Federal Reserve stepped in.

Rate improves grew to become an unofficial “curfew,” sending just about all the partygoers dwelling early. But even in that framework, there will be marketplaces that really don’t experience as significant a drop as some others. Benzinga takes a glimpse at some of the authentic estate markets that are observing the major downturns and what that implies for the authentic estate match.

The Solar Belt

Potentially no real estate marketplace in the place heated up speedier during the COVID crisis than the Sunlight Belt. Lured by the low costs and heat weather, individuals streamed into the Sun Belt, which led to a substantial leap in home charges. That development has certainly reversed itself.

In accordance to details from Realtor.com, Austin, Texas, observed a whopping 10.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop in property selling prices from June to September. The superior news for sellers is the typical property selling price is even now $558,275, which is up 2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the same time final calendar year.

Phoenix is another Solar Belt town that was appealing to consumers in the course of the pandemic. It, too, has experienced of late. The common value of a household in Phoenix is down 9.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from three months back. If you are searching to get there, the common value is now $493,500.

In Florida, Orlando, Tampa Bay and Palm Bay had been well-liked Sunlight Belt places. When you take into consideration that Florida presents year-round sunshine and no state taxes, it only would make sense that its real estate market place would hit a growth cycle write-up-COVID. Palm Bay undoubtedly did, but the worm has turned. There has been an 8.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop in sale price ranges to $379,995 from June to Oct.

The Tech Drop and the Mountain West

It is not just the Sunlight Belt that has been encountering what Fed Chairman Jerome Powell identified as a “correction” in household price ranges considering the fact that interest charges went up. During the pandemic, Mountain West marketplaces like Boise, Idaho, were abruptly pink warm.

Even so, a new research by SmartAsset identified that homes in Boise have been staying on the sector for an ordinary of 20 times, which is 186{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} longer than a yr back. That stated, 20 times is not an specially extensive time for a property to be on the market. Redfin reviews that 55{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of residence sellers in Denver and 51.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of property sellers in Salt Lake City have experienced to decreased their inquiring costs to shut offers.

Through the tech boom, marketplaces like Sunnyvale and San Jose, California, actually became ground zero for America’s housing affordability crisis. As the COVID pandemic brought distant function into the public consciousness, instantly not every person in tech wanted a household around their company’s respective mothership in Silicon Valley. That has resulted in a cooldown of these notoriously sizzling markets.

Moody’s observed that San Jose’s home selling prices have dropped by 7.88{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} due to the fact the Fed referred to as time on very low interest fees. San Francisco experienced an even a lot more precipitous fall of 10.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. However for customers in these markets, the house charges were presently so superior that even drops this considerable have not introduced homes back within their access, specially when the better desire premiums are accounted for.

It’s Not Just Home Charges

Solitary-household house rates are often viewed as to be the greatest indicator of a real estate market’s relative strength. But household rents in multifamily condominium communities are a further vital metric for the performance of a presented market. This is why so several true estate investment trusts (REITs) have so numerous institutional-high-quality multifamily property in the exact markets wherever dwelling selling prices are superior.

After all, a deficiency of affordability in one-family members houses means a large amount of men and women will close up remaining forced into the rental marketplace irrespective of whether they want to or not. For buyers, the news is tricky right here, way too. Orlando, Phoenix, Las Vegas and Dallas/Forth Really worth have all witnessed typical rents drop concerning .07{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the previous a number of months.

That is unquestionably not superior news for REIT investors mainly because many of them responded to the increase in all those towns by breaking floor on new developments. By some estimates, an additional 200,000 units are set to come on-line in these markets, which will put even far more downward force on rents.

The Rumors of the Dying of the Genuine Estate Industry are Greatly Exaggerated

Obviously, lots of information factors present that the real estate current market is in a hard stage. With that reported, the resilience of the true estate industry is famous. In much the exact way a palm tree can be bent nearly all the way about on its aspect when it is hit by hurricane-drive winds, the tree virtually often straightens itself out and stands tall after the storm clears. The present-day storm is not over, but it will ultimately go.

Even now, investors are on the lookout for home values to go down so they can obtain them at very low costs and take gain of the upside that pretty much usually accompanies genuine estate investments. For homebuyers, the falling charges have been mostly offset by the mounting interest rates. Even now, any one seeking at all this details and imagining that the genuine estate sector is useless and gone will probably be established incorrect.

Real estate is however a finite asset. Homeownership is even now a cornerstone of the American desire. Indeed, curiosity rates are at a 20-year higher. But persons were being nonetheless buying homes 20 decades back, too. Finally, potential buyers will reappear and a lot of of these marketplaces that are in distress will be strong all over again. Timing is nevertheless anything in authentic estate.

Interested in incorporating passive true estate investments to your portfolio? You can devote in rental properties with as very little as $100. Benzinga will demonstrate you how, verify it out!

See a lot more on serious estate investing from Benzinga:

Not financial commitment guidance. For educational needs only.

Do not pass up actual-time alerts on your stocks – sign up for Benzinga Pro for free! Attempt the resource that will aid you make investments smarter, a lot quicker, and much better.

© 2022 Benzinga.com. Benzinga does not deliver investment tips. All rights reserved.

10 U.S. cities where housing markets are cooling the fastest

10 U.S. cities where housing markets are cooling the fastest

The housing industry is in flux appropriate now, thanks to higher house loan fees, persistent inflation, and financial uncertainty, in accordance to Redfin’s 2022 report.

The know-how-powered authentic estate brokerage ranked 100 of the most populous metropolitan spots in the United States employing the adhering to metrics:

  • charges
  • price tag drops
  • source
  • pending revenue
  • sale-to-record ratio
  • speed of dwelling income

The review located that the marketplaces cooling off the speediest from February 2022 to August 2022 had been pretty much all on the West Coastline.

No. 1 metropolis in which the housing market is cooling the speediest: Seattle, WA

Top 10 towns in which housing marketplaces are cooling the fastest in 2022

  1. Seattle, WA
  2. Las Vegas, NV
  3. San Jose, CA
  4. San Diego, CA
  5. Sacramento, CA and Denver, CO (tie)
  6. —
  7. Phoenix, AZ
  8. Oakland, CA
  9. North Port, FL
  10. Tacoma, WA

Las Vegas, Nevada rated next on the checklist — dwelling rates in the metropolis ended up down 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in August from the month prior to and about 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} less houses sold inside of two months than a 12 months earlier.

Coming in third is San Jose, CA, exactly where according to Redfin’s report, the housing sector has most likely cooled off due to the fact the Fed’s price hikes and growing home loan premiums have produced it far more tricky to find the money for a house there.

“These are all locations where by homebuyers are feeling the sting of rising residence prices, higher property finance loan fees, and inflation really sharply. They are slowing down partly since so numerous persons have been priced out and partly simply because past year’s file-minimal costs manufactured them unsustainably hot,” Redfin Chief Economist Daryl Fairweather mentioned in the report.

“The fantastic information is that the slowdown is dampening competition and giving these who can nonetheless find the money for to acquire additional negotiating ability.”

Indicator up now: Get smarter about your dollars and job with our weekly publication

Never pass up:

These are the major 5 most high priced states to acquire a property in 2022

These are the 10 lowest priced states to obtain a property in 2022—and Florida isn’t just one of them

These 210 housing markets are now vulnerable to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}-25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} home price declines, finds latest Moody’s downgrade

These 210 housing markets are now vulnerable to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}-25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} home price declines, finds latest Moody’s downgrade

Favorable millennial demographics. Limited housing inventory. Lower unemployment. Which is why housing bulls stated the Pandemic Housing Boom experienced much more home to operate.

Moody’s Analytics main economist Mark Zandi, of study course, disagreed. Back again in May, Zandi arrived to Fortune with a daring proclamation: The Pandemic Housing Boom experienced peaked and we were entering into a “housing correction.” A housing correction getting a period of time wherever the housing market—which received priced to 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} home finance loan rates—would work to equilibrium. It’d see house gross sales volumes slide sharply. It’d also, Zandi explained, set much of the country at risk of a house price tag corrections.

Fast forward to September, and it looks like Zandi’s housing correction call was place-on. Not only is housing exercise declining across the board, but some marketplaces, like Austin and Boise, are by now observing falling home prices. This week, Fed Chair Jerome Powell acknowledged that the U.S. housing sector is moving into into a “difficult correction.”

That said, Zandi’s views are shifting—downward. In August, Moody’s Analytics downgraded their U.S. housing sector outlook. Peak-to-trough, Moody’s Analytics expected U.S. house rates to fall among {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and tumble amongst 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in drastically “overvalued” housing markets. That August forecast assumed no recession. If an financial downturn manifested, Moody’s Analytics predicted U.S. home rates to tumble involving 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Whilst drastically “overvalued” housing markets would drop 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Just a month later, Moody’s Analytics is by now revising that bearish housing current market outlook downward.

Peak-to-trough, Moody’s Analytics now expects U.S. property rates to fall among 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In drastically “overvalued” housing markets, that forecasted drop is now involving 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If a economic downturn hits, Moody’s Analytics expects that U.S. household price tag decline to widen to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and the drop in drastically “overvalued” housing marketplaces to variety between 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Let us say that U.S. property costs decrease 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That hypothetical drop would not completely erase the staggering 43{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} jump in U.S. dwelling selling prices we saw in the course of the Pandemic Housing Growth. Even so, it would be the second largest household price tag decrease of the put up-Earth War II era. Only the bursting housing bubble, which observed U.S. dwelling prices decrease 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} concerning 2006 and 2012, would have it conquer.

If U.S. dwelling prices do in fact drop by a double-digit quantity, Fortune would relabel the Pandemic Housing Boom to the Pandemic Housing Bubble.

In which can we find these noticeably “overvalued” housing markets? Effectively, just about everywhere you go.

Each quarter, Moody’s Analytics assesses regardless of whether regional financial fundamentals, which include regional revenue levels, can guidance area property charges.* If a housing market is “overvalued” by extra than 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Moody’s Analytics deems it “significantly overvalued.” By the first quarter of the 12 months, 183 of the nation’s 413 greatest regional housing markets have been overvalued by additional than 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In the 2nd quarter of 2022, that determine grew to 210 regional housing marketplaces.

In the course of the early section of the Pandemic Housing Growth these frothy marketplaces were being closely concentrated in Sunlight Belt and Mountain West boomtowns. Having said that, as the housing growth carried above into 2022, several marketplaces on the West Coastline, Midwest, and Northeast also started to get to frothy valuations.

Traditionally talking, frothy housing marketplaces (i.e. substantially “overvalued” marketplaces) are at the highest hazard of home price tag declines through a housing industry correction. Immediately after all, that is why Moody’s Analytics updates the evaluation just about every quarter.

If this housing correction—which was spurred by a 3 share point leap in house loan rates—had transpired two yrs ago, far less housing markets would’ve been at threat of property cost declines. Back again in the next quarter of 2019 (see chart previously mentioned), just three significant regional housing marketplaces have been viewed as drastically “overvalued.”

Simply just set: In just under a few several years, the U.S. housing market went from a historically reasonably priced housing industry (see chart beneath) to a historically unaffordable housing market.

This house rate correction, of system, has currently started out. It is hitting two groups the most difficult.

The to start with group includes frothy markets like Austin (the place property values fell 7.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} between May and August), Boise (down 5.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Denver (down 4.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Phoenix (down 4.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Those people marketplaces noticed deep-pocketed WFH buyers from cities like San Francisco and New York travel property costs much beyond what area incomes would traditionally support. These are exactly the varieties of sites Moody’s Analytics deems substantial hazard.

The second team are higher-price tag tech hubs like Settle (where household values fell 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} between Might and August), San Francisco (down 7.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and San Jose (10.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Relative to nearby incomes, those marketplaces are not appreciably “overvalued.” Those tech hubs are, however, hit by a double whammy. Not only are their significant-end genuine estate marketplaces far more charge-delicate, but so are their tech sectors.

When will these housing marketplaces bottom out? According to Zandi, it could consider another 12 to 18 months right before this property cost correction concludes.

Want to keep up-to-date on the housing correction? Adhere to me on Twitter at @NewsLambert.

*”The Moody’s Analytics housing valuation evaluate is the p.c big difference concerning precise home costs and house prices traditionally regular with wages and salaries for each capita and building expenditures. The cost of a property is eventually established by the benefit of the land on which it resides which is tied to the possibility charge of the land as calculated by wages and salaries, and the cost to build the household. Nationwide, roughly one particular-half of a home’s worth is the land and the other 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} the framework, but this differs significantly across the nation.  In San Francisco, for example, the land is significantly and away the biggest part of the home’s price, though in Des Moines, Iowa, it is the opposite. Our housing valuation measure accounts for these variances,” writes Moody’s Analytics chief economist Mark Zandi.

Dominant List of Vulnerable Housing Markets

Dominant List of Vulnerable Housing Markets

Chicago and New York City Areas Remain Most Exposed to Potential Downturns in Second Quarter of 2022; Other More-At-Risk Markets Scattered Around Nation; South Region Continues to be Less Vulnerable

IRVINE, Calif. — Sept. 15, 2022 — ATTOM, a leading curator of real estate data nationwide for land and property data, today released a Special Housing Risk Report spotlighting county-level housing markets around the United States that are more or less vulnerable to declines, based on home affordability, unemployment and other measures in the second quarter of 2022. The report shows that New Jersey, Illinois and inland California continued to have the highest concentrations of the most-at-risk markets in the second quarter – with the biggest clusters in the New York City and Chicago areas. Southern and midwestern states remained less exposed.

The second-quarter patterns – based on gaps in home affordability, underwater mortgages, foreclosures and unemployment – revealed that New Jersey, Illinois and California had 33 of the 50 counties most vulnerable to potential declines. The 50 most at-risk included nine in and around New York City, six in the Chicago metropolitan area, and 13 spread through northern, central and southern California. The rest of the top 50 counties were scattered across the U.S., including three in the Philadelphia, PA, metro area. At the other end of the risk spectrum, the South and Midwest had the highest concentration of markets considered least vulnerable to falling housing markets.

“The Federal Reserve has promised to be as aggressive as it needs to be in order to get inflation under control, even if its actions lead to a recession,” said Rick Sharga, executive vice president of market intelligence at ATTOM. “Given how little progress has been made reducing inflation so far, the Fed’s actions seem more and more likely to drive the economy into a recession, and some housing markets are going to be more vulnerable than others if that happens.”

Counties were considered more or less at risk based on the percentage of homes facing possible foreclosure, the portion with mortgage balances that exceeded estimated property values, the percentage of average local wages required to pay for major home ownership expenses on median-priced single-family homes, and local unemployment rates. The conclusions were drawn from an analysis of the most recent home affordability, equity and foreclosure reports prepared by ATTOM. Unemployment rates came from federal government data. Rankings were based on a combination of those four categories in 575 counties around the United States with sufficient data to analyze in the second quarter of 2022. Counties were ranked in each category, from lowest to highest, with the overall conclusion based on a combination of the four ranks. See below for the full methodology.

The ongoing wide disparities in risks throughout the country comes during a time when the U.S. housing market faces headwinds that threaten to slow down or end an 11-year surge in home prices.

Sales of both existing and new homes have declined as mortgage rates have almost doubled to 6 percent over the past year, and inflation remains near a 40-year high. However the most recent risk gaps do not suggest an imminent fall in housing markets anywhere in the nation. Home prices have risen more than 10 percent in most of the country over the past year, with new highs hit in the vast majority of metropolitan-area markets. That has kept homeowner equity and home-seller profits rising.

Those numbers have continued to improve as demand, buoyed by increasing household formation by young adults and rising wages has continued to outpace an historically tight supply of properties for sale.

Amid that mixed scenario, home affordability is worsening, lender foreclosures on delinquent mortgages are up and the number of home sales is slowing, with local housing markets heading into that uncertain future facing significant differences in risk measures.

Most-vulnerable counties clustered in the Chicago, New York City and Philadelphia areas, along with sections of California

Thirty-one of the 50 U.S. counties considered most vulnerable in the second quarter of 2022 to housing market troubles (from among 575 counties with enough data to be included in the report) were in the metropolitan areas around Chicago, IL; New York, NY; and Philadelphia, PA, as well as in California. California markets on the list were mostly inland, away from the coast.

The top 50 counties included two in New York City (Kings and Richmond counties, which cover Brooklyn and Staten Island), seven in the New York City suburbs (Bergen, Essex, Ocean, Passaic, Sussex and Union counties in New Jersey and Rockland County in New York) and six in the Chicago metropolitan area (Cook, Kane, Kendall, McHenry and Will counties in Illinois and Lake County, IN). The three in the Philadelphia, PA, metro area that were among the top 50 most at-risk in the second quarter were Philadelphia County, along with Camden and Gloucester counties in New Jersey.

Elsewhere, California had 13 counties in the top 50 list: Butte County (Chico), Humboldt County (Eureka), Shasta County (Redding) and Solano County (outside Sacramento) in the northern part of the state; Fresno County, Kings County (outside Fresno), Madera County (outside Fresno), Merced County (outside Modesto), San Joaquin County (Stockton) and Tulare County (outside Fresno) in central California, and Kern County (Bakersfield), Riverside County and San Bernardino County in the southern part of the state.

Counties most at-risk continue to have higher levels of unaffordable housing, underwater mortgages, foreclosures and unemployment

Major home ownership costs (mortgage payments, property taxes and insurance) on median-priced single-family homes consumed more than one-third of average local wages in 35 of the 50 counties that were most vulnerable to market problems in the second quarter of 2022. The highest percentages in those markets were in Kings County (Brooklyn), NY (102.9 percent of average local wages needed for major ownership costs); Riverside County, CA (67.6 percent); Rockland County, NY (outside New York City) (66.2 percent); Richmond County (Staten Island), NY (61.8 percent) and San Joaquin County (Stockton), CA (58.7 percent). Nationwide, major expenses on typical homes sold in the second quarter required 31.5 percent of average local wages.

At least 7 percent of residential mortgages were underwater in the second quarter of 2022 in 23 of the 50 most at-risk counties. Nationwide, 5.9 percent of mortgages fell into that category. Those with the highest underwater rates among the 50 most at-risk counties were Rockland County, NY (outside New York City) (19.2 percent of mortgages were underwater); Lake County, IN (outside Chicago, IL) (18.9 percent); Peoria County, IL (17.6 percent); Philadelphia County, PA (16.1 percent) and Saint Clair County, IL (outside St. Louis, MO) (16.1 percent).

More than one in 1,000 residential properties faced a foreclosure action in the second quarter of 2022 in 40 of the 50 most at-risk counties. Nationwide, one in 1,559 homes were in that position. Foreclosure actions have risen since the expiration last July of a federal moratorium on lenders taking back properties from homeowners who fell behind on their mortgages during the early part of the Coronavirus pandemic that hit in 2020. They are expected to continue increasing over the coming year. The highest rates in the top 50 counties were in Cuyahoga County (Cleveland), OH (one in 365 residential properties facing possible foreclosure; Cumberland County, NJ (outside Philadelphia, PA) (one in 373); Warren County, NJ (outside Allentown, PA) (one in 455); Camden County, NJ (outside Philadelphia, PA) (one in 462) and Saint Clair County, IL (outside St. Louis, MO) (one in 470).

The June 2022 unemployment rate was at least 7 percent in 35 of the 50 most at-risk counties, while the nationwide figure stood at 3.5 percent. The highest levels among the top 50 counties were in Tulare County, CA (outside Fresno) (11.7 percent); Merced County, CA (outside Modesto) (11.5 percent); Kern County (Bakersfield), CA (11.3 percent); Kings County, CA (outside Fresno) (10.9 percent) and Kings County (Brooklyn), NY (10.8 percent).

Counties less at-risk concentrated in South and Midwest

Twenty-five of the 50 counties least vulnerable to housing-market problems from among the 575 included in the second-quarter report were in the South, while another 14 were in the Midwest. Just five were in the West and six in the Northeast.

Tennessee had six of the 50 least at-risk counties, including three in the Nashville metropolitan area (Davidson, Rutherford and Williamson counties), while Wisconsin had five – Brown County (Green Bay), Dane County (Madison), Eau Claire County, La Crosse County and Winnebago County (Oshkosh). Another four were in Arkansas: Benton County (Rogers), Craighead County (Jonesboro), Sebastian County (Fort Smith) and Washington County (Fayetteville).

Counties with a population of at least 500,000 that were among the 50 least at-risk included King County (Seattle), WA; Travis County (Austin), TX; Salt Lake County (Salt Lake City), UT; Wake County (Raleigh), NC, and Cobb County (Marietta), GA.

Least-vulnerable counties have more-affordable homes along with lower levels of underwater mortgages, foreclosure activity and unemployment

Major home ownership costs (mortgage payments, property taxes and insurance) on median-priced single-family homes consumed more than one-third of average local wages in just 24 of the 50 counties that were least vulnerable to market problems in the second quarter of 2022. The lowest percentages in those markets were in Sebastian County (Fort Smith), AR (16.5 percent of average local wages needed for major ownership costs); Potter County (Amarillo), TX (16.5 percent); Sullivan County (Kingsport), TN (21.5 percent); Winnebago County (Oshkosh), WI (22.8 percent) and Craighead County (Jonesboro), AR (23.3 percent).

Less than 5 percent of residential mortgages were underwater in the second quarter of 2022 (with owners owing more than their properties are worth) in 30 of the 50 least-at-risk counties. Those with the lowest rates among those counties were Chittenden County (Burlington), VT (1.3 percent of mortgages were underwater); Williamson County, TX (outside Austin) (1.4 percent); Williamson County, TN (outside Nashville) (1.5 percent); Travis County (Austin), TX (1.8 percent) and Wake County (Raleigh), NC (1.9 percent).

More than one in 1,000 residential properties faced a foreclosure action during the second quarter of 2022 in none of the 50 least at-risk counties. Those with the lowest rates in those counties were Fayette County (Lexington), KY (one in 48,714 residential properties facing possible foreclosure); Chittenden County (Burlington), VT (one in 36,543); Missoula County, MT (one in 27,271); Johnson County (Overland Park), KS (one in 20,973) and Williamson County, TN (outside Nashville) (one in 15,189).

The June 2022 unemployment rate was more than 5 percent in just two of the 50 least-at-risk counties. The lowest rates among the top 50 counties were in Cache County (Logan), UT (2.4 percent); Sarpy County, NE (outside Omaha) (2.8 percent); Hamilton County, IN (outside Indianapolis) (2.8 percent); Shelby County, AL (outside Birmingham) (2.8 percent) and Forsyth County, GA (outside Atlanta) (2.9 percent).

###

Report methodology

The ATTOM Special Coronavirus Market Impact Report is based on ATTOM’s second-quarter 2022 residential foreclosure, home affordability and underwater property reports, plus June 2022 unemployment figures from the U.S. Bureau of Labor Statistics. (Press releases for affordability, foreclosure and underwater-property reports show the methodology for each.) Counties with sufficient data to analyze were ranked based on the second-quarter percentage of residential properties with a foreclosure filing, the percentage of average local wages needed to afford the major expenses of owning a median-priced home and the percentage of properties with outstanding mortgage balances that exceeded their estimated market values, along with June 2022 county unemployment rates. Ranks then were added up to develop a composite ranking across all three categories. Equal weight was given to each category. Counties with the lowest composite rank were considered most vulnerable to housing market problems. Those with the highest composite rank were considered least vulnerable.

About ATTOM

ATTOM provides premium property data to power products that improve transparency, innovation, efficiency and disruption in a data-driven economy. ATTOM multi-sources property tax, deed, mortgage, foreclosure, environmental risk, natural hazard, and neighborhood data for more than 155 million U.S. residential and commercial properties covering 99 percent of the nation’s population. A rigorous data management process involving more than 20 steps validates, standardizes, and enhances the real estate data collected by ATTOM, assigning each property record with a persistent, unique ID — the ATTOM ID. The 30TB ATTOM Data Warehouse fuels innovation in many industries including mortgage, real estate, insurance, marketing, government and more through flexible data delivery solutions that include bulk file licenses, property data APIs, real estate market trends, property reports and more. Also, introducing our newest innovative solution, that offers immediate access and streamlines data management – ATTOM Cloud.

Media Contact:

Christine Stricker

949.748.8428

[email protected]

Data and Report Licensing:

949.502.8313

[email protected]
Map: How fast sellers are slashing home prices in America’s 97 biggest housing markets

Map: How fast sellers are slashing home prices in America’s 97 biggest housing markets

The Pandemic Housing Increase noticed U.S. household charges spike an unprecedented 43{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in just in excess of two yrs. But that is about now: Spiked property finance loan prices have pushed the U.S. housing marketplace into a sharp slowdown that could threaten some of people gains.

Some firms—including John Burns Genuine Estate Consulting, Zonda, and Zelman & Associates—are currently predicting that U.S. dwelling prices in 2023 will post their first calendar year-in excess of-yr decline of the put up-Terrific Monetary Disaster era. In a sharp housing downturn circumstance, Fitch Ratings thinks a 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} countrywide dwelling price tag drop is possible. Not every person agrees. Goldman Sachs and Zillow forecast that U.S. property charges will rise a different 1.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 2.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively, more than the coming calendar year.

Although business insiders are even now debating irrespective of whether nationwide household prices will publish 12 months-in excess of-12 months declines, there is a consensus that some regional marketplaces will see selling price declines.

To get a much better notion of which regional housing marketplaces could first see 12 months-above-year household value declines, let us glimpse at checklist costs. Although a spike in slashed record costs doesn’t promise a sector will post calendar year-around-calendar year home price declines, it does mark a trajectory modify. Lengthy before a market place essentially posts a calendar year-above-calendar year price decline, it would’ve witnessed a spike in record value cuts.

Amid 97 regional housing marketplaces calculated by Redfin, the common industry observed 34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of house listings get a price tag slice in July. Which is the maximum at any time looking at on Redfin. It’s also very well over the 25.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in May possibly 2022, and 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in July 2021.

“Nationwide, the share of households for sale with selling price drops arrived at a history large in July. Sellers experienced to slash their price ranges mainly because they were catching up with customers, who had come to be expecting lessen prices amid a cooling industry. Mounting property finance loan premiums and the prospect of slipping residence values also created purchasers hesitant to fork out sky-high prices, and an uptick in provide gave them a lot more to pick from. Rate drops are possible to flatten out as sellers arrive to conditions with the shifting market place,” compose Redfin scientists.

The regional housing marketplaces viewing the optimum share of price tag cuts are in the pretty sites that observed the most significant cost gains for the duration of the pandemic. Just look at Boise. All through the Pandemic Housing Boom, selling prices in Boise soared in excess of 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. But as the sector shifted, Boise received hit the toughest. In July, 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of property listings in Boise noticed a price lower. Which is up from 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in July 2021.

In accordance to data gathered by John Burns True Estate Consulting, residence rates are presently falling in Boise. People thirty day period-over-thirty day period Boise price drops can already be observed in Zillow information. Before the conclusion of the calendar year, John Burns True Estate Consulting predicts that Boise will be the to start with U.S. sector to submit a 12 months-around-year selling price decline.

It isn’t just Boise. The West—the epicenter of the Pandemic Housing Boom—has shifted really quick. Just guiding Boise are Denver (in which 58{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of listings saw a value slash in July), Salt Lake Metropolis (56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Tacoma (55{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Marketplaces like Phoenix (where 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of listings observed a price tag cut), San Diego (50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Stockton (47{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) also rank around the prime.

Why are Mountain West and West Coastline markets shifting so quick?

“The solid need over the earlier two decades drove up dwelling charges throughout the country, and it appears the West strike the pricing ceiling more rapidly than other marketplaces offered the unique provide constraints,” Ali Wolf, main economist at Zonda, instructed Fortune.

Just set: The powerful bidding wars out West—which have been exacerbated by limited inventory—pushed home selling prices to buyers’ breaking stage.

The info seems to agree with Wolf.

Regional housing marketplaces that became the most detached from underlying financial fundamentals are now cooling the fastest. Spots like Boise and Austin observed residence rates increase to bubbly degrees amid the Pandemic Housing Boom. Once traditionally minimal mortgage prices disappeared previously this yr, would-be potential buyers in people markets started to really feel the complete brunt of report household rate appreciation. Which is why this summertime several buyers, in areas like Boise and Austin, referred to as off their research.

Heading ahead, these bubbly housing markets are at the optimum possibility of sharp selling price corrections. Peak-to-trough, Moody’s Analytics expects countrywide dwelling price ranges to drop involving {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} amid this housing slowdown. Having said that, in significantly “overvalued” markets like Boise and Austin, Moody’s Analytics expects 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} house rate drops. That’s assuming no economic downturn. If a economic downturn hits, Moody’s Analytics expects a 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} national dwelling selling price decrease and 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} declines in the nation’s 187 drastically “overvalued” markets.

Want to continue to be up to date on the housing correction? Follow me on Twitter at @NewsLambert.

Sign up for the Fortune Characteristics e mail checklist so you do not pass up our greatest attributes, exclusive interviews, and investigations.