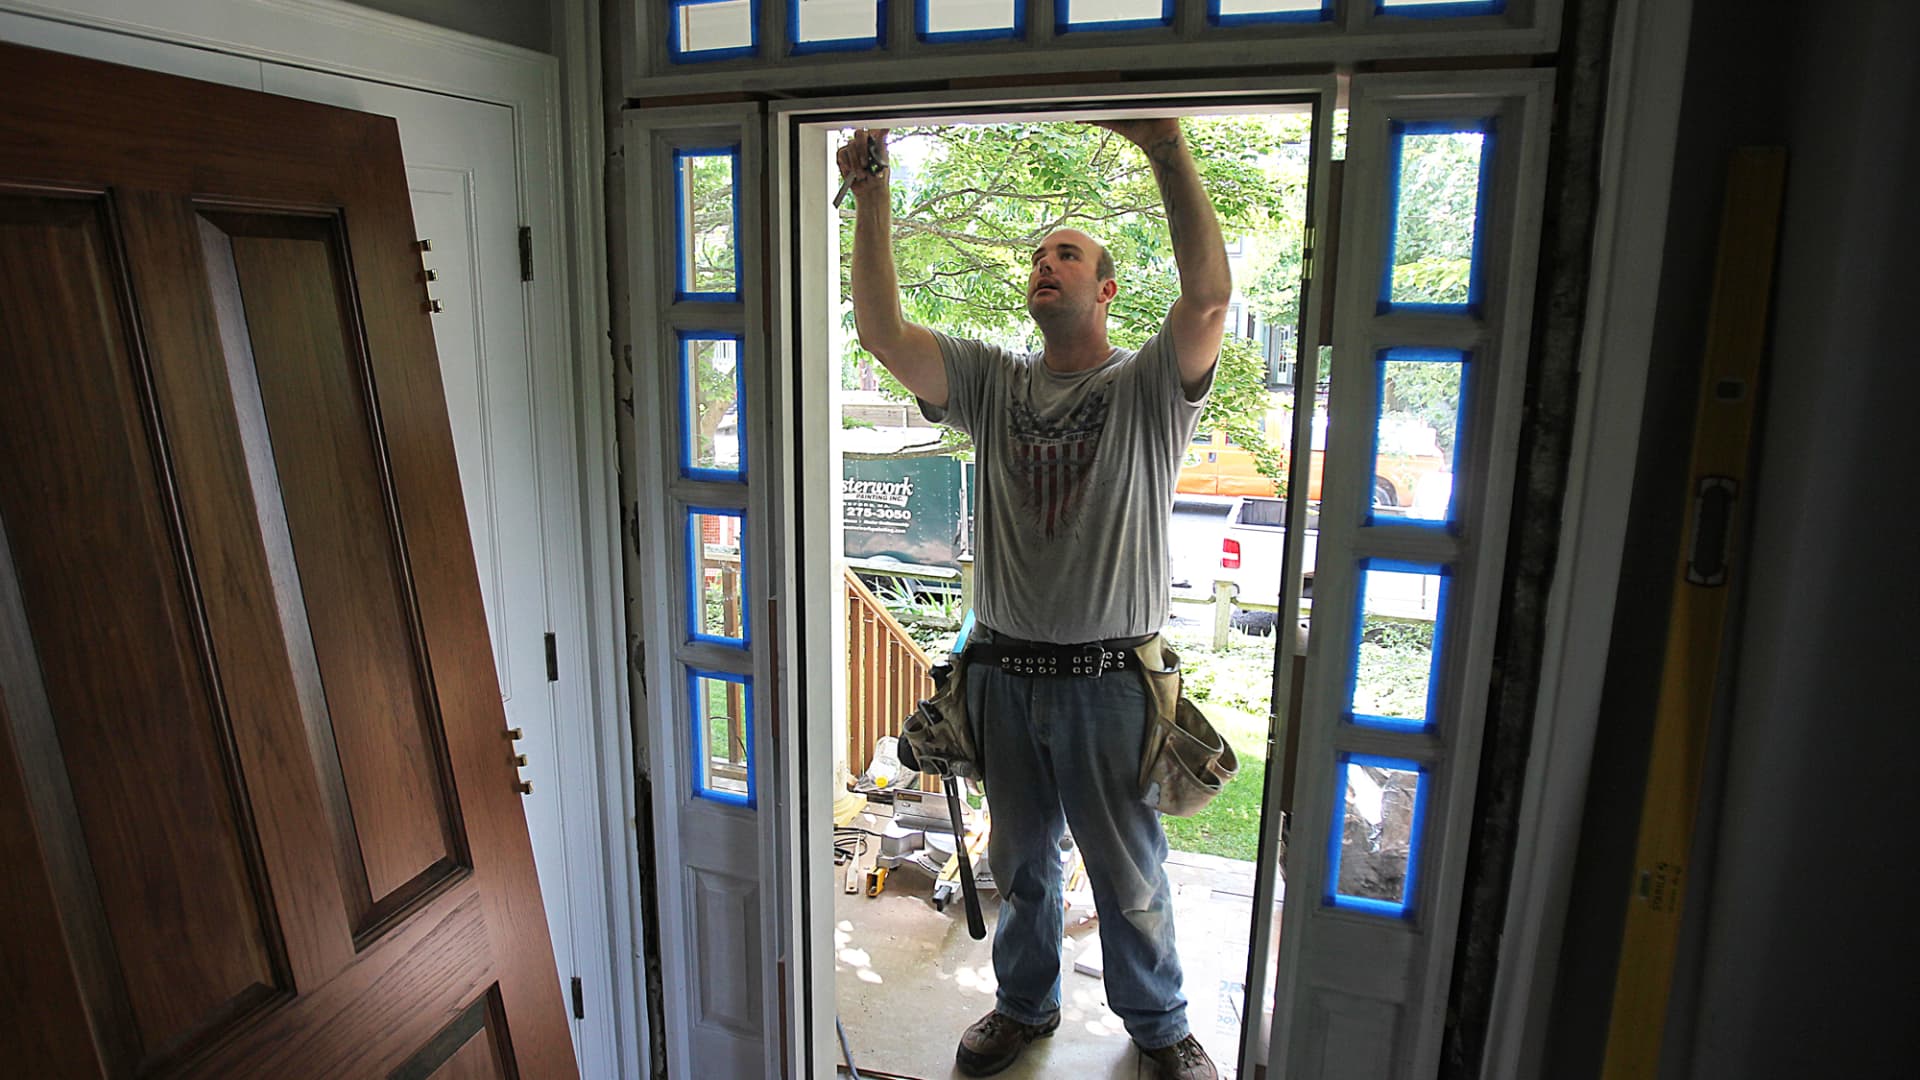
A household enhancement contractor operates on a residence in Cambridge, Massachusetts.
Suzanne Kreiter | The Boston World | Getty Illustrations or photos
As the U.S. housing marketplace falls challenging from its pandemic-pushed highs, house enhancement vendors like Dwelling Depot and Lowe’s really don’t appear to be to be sensation the very same agony. In fact, they’re faring improved than expected.
When homebuilding and home reworking are integrally linked, the industry forces guiding each and every can be diverse, and that is what is happening now.
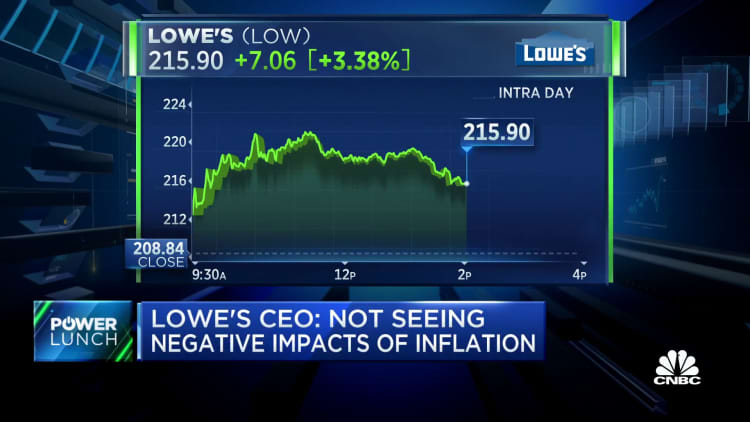
House Depot and Lowe’s documented sturdy quarterly earnings Tuesday and Wednesday, respectively. Lowe’s stock rose 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Wednesday. Executives at both corporations spoke bullishly about the prospects for their organization in 2023. This comes as residence sales, charges and building are all weakening appreciably thanks to a massive soar in home finance loan prices.
Residence Depot financial main Richard McPhail pointed to an “boost in place” mentality among recent owners, who may have required to offer but adjusted their minds due to the fact they could no longer command top dollar.
“All we can do at this place is repeat what our shoppers are telling us,” McPhail stated. “There is a dynamic we do not see a lot in the marketplace. With climbing house loan costs, homeowners are keeping in place.”
With increasing mortgage fees, homeowners are being in place.
Richard McPhail
Residence Depot CFO
Home costs are nevertheless 11.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} better in Oct than they were being in Oct 2021, in accordance to CoreLogic, but that yearly comparison has been shrinking for quite a few months. Costs are falling thirty day period-to-month at a considerably speedier pace than standard seasonal tendencies.
However, the unparalleled operate-up in home costs throughout the 1st years of the pandemic, fueled by file reduced property finance loan fees and a drive for lots of People in america to shift to more substantial houses in suburban locations, gave householders sizeable amounts of equity. Charges jumped extra than 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in just two several years.
By the close of the initially quarter of this 12 months, prior to the steep runup in home loan premiums prompted the housing sector to falter, house owners experienced a collective $11 trillion dollars in so-identified as tappable equity, according to Black Knight. That is the quantity a borrower can get out of their home while nevertheless leaving 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity in it. That fairness grew by an unparalleled $1.2 trillion in the to start with quarter of this yr by itself. For every property owner, it quantities to about $207,000 in tappable equity.
That equity is aspect of a three-pronged driver of property advancement, in accordance to the CEO of Lowe’s, Marvin Ellison. He pointed to dwelling price tag appreciation, the age of the U.S. housing stock — which is roughly 40 several years outdated, the oldest considering the fact that Globe War II — as perfectly as significant levels of personalized disposable earnings.
“So when you seem at all people elements, individuals matters bode properly for house improvement, and we come to feel genuinely fantastic about our present-day tendencies,” explained Ellison in an interview Wednesday on CNBC’s “Squawk Box.”
The NAHB, nonetheless, is forecasting that the remodeling sector will fare the best between the household construction submarkets during this existing housing contraction.
“The development level for advancement investing will gradual because of to declines for existing property income,” said Robert Dietz, NAHB’s chief economist. “However, an aging housing inventory, function from household developments and a decline for domestic mobility all favor transforming investing.”
Dietz also factors to the “curiosity fee lock-in results,” meaning folks will not want to offer a dwelling where they may possibly be spending a 2.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} property finance loan fascination price and trade up to another home wherever the price would probably be all-around 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} currently.
Harvard’s Joint Center for Housing predicts that the annual gains in home advancement and maintenance shelling out will drop “sharply” by the center of future year, but only to a 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} development amount from an unusually superior 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate.
“Housing and reworking markets are without doubt slowing from the exceptionally high and unsustainable growth costs that adopted in the wake of the pandemic-induced economic downturn,” states Carlos Martín, venture director of the Reworking Futures Plan at the Middle. “Paying for dwelling advancements will carry on to face headwinds from declining dwelling income, mounting interest fees and the increasing charges of contractor labor and building components.”
Regardless of inflation in just about every thing in the financial system, consumers do feel to want to commit far more on their homes. Both equally Lowe’s and Household Depot showed a drop in the number of sales but a soar in the dollar amount of money of all those gross sales. That led to their increases in profits.
“There is inflation in the market and elasticity, but not to the degree that we predicted, and the shopper reveals us they are resilient,” reported Home Depot’s McPhail.
A new study of nearly 4,000 home owners by Houzz, a house improvement and structure web-site, discovered that only 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners documented acquiring canceled a house improvement job in 2022. In the meantime, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} accomplished a undertaking in 2022 and just about a single-quarter mentioned they were being setting up to start off a home enhancement challenge in the next 12 months.
“Moreover, much more than fifty percent of the owners we surveyed have no intention of marketing or relocating out of their existing residences in the following 20 a long time or ever,” said Maritime Sargsyan, Houzz personnel economist.
Enfield is a town in north London and has experienced a great deal of growth in recent years. If you’re thinking of selling your house in Enfield, you might be wondering when the best time to do so is. After all, timing is everything when it comes to real estate. The answer, unfortunately, is that there is no one-size-fits-all answer to this question. The best time to sell your house in Enfield depends on a number of factors, including the current state of the housing market and your personal circumstances.
It is better to take the assistance of a conveyancer to sell your house without any issue. AVRillo conveyancing lawyer in Enfield with several years experience. They will help you in the process of selling your house in an easy way.
The Current State of the Housing Market
One of the most important factors to consider when trying to time the sale of your house is the current state of the housing market. If prices in your area are on the rise, it might be a good idea to sell sooner rather than later. On the other hand, if prices are stagnant or dropping, you might want to wait a bit longer before putting your house on the market.
Your Personal Circumstances
Another important factor to consider is your personal circumstances. If you’re in a hurry to sell, you might not be able to wait for the perfect time to put your house on the market. On the other hand, if you’re not in a hurry, you might be able to afford to wait for a better market.
How’s the Market in Enfield?
Right now, the market in Enfield is bustling. Prices have been rising steadily for the past few years, and there is no sign of them slowing down anytime soon. This is mainly influenced by the fact that Enfield is a commuter town with good transport links to central London. If you’re thinking of selling your house in Enfield, now might be a good time to do so.
Once you have an asking price, it is time to start marketing your property. This can be done through online portals such as Rightmove and Zoopla, as well as through traditional methods such as newspapers and flyers. It is important to ensure that your property is advertised in as many places as possible to have the best chance of finding a buyer.
Once you have found a buyer for your property, getting the sale agreed upon as quickly as possible is important. This is because the longer a property is on the market, the more likely the price will drop. Once the sale has been agreed upon, you will need to instruct a solicitor to draw up the contract of sale. This legally binding document sets out the terms of the sale, and it is important to ensure that you understand everything that is included in it before signing.
Your solicitor will also deal with the transfer of ownership of the property and will liaise with the buyer’s solicitor to ensure that everything goes smoothly. Once the sale has been completed, you will receive the proceeds minus any estate agent or solicitor fees.
The Bottom Line
As you can see, there are a lot of factors to consider when deciding when to sell your house in Enfield. The best time to sell depends on your circumstances and the housing market’s current state. If you need help deciding the best decision for you, we recommend speaking with a real estate agent who can give you expert advice based on your unique situation.
Seattle’s cooling housing marketplace is impacting more than just consumers and sellers. With less transactions and reduced rates on the horizon, essential town revenues are envisioned to slide.
Town officers had to rework the spending plan this month immediately after new forecasts showed Seattle will most likely provide in tens of tens of millions of bucks less than beforehand expected around the up coming two years, like a important drop in actual estate-linked tax income.
As inflation persists, desire charges keep on being superior and quite a few persons come across on their own locked out of obtaining a residence, forecasters anticipate “a spectacular decrease in the variety of homes offered and a modest decline in costs,” Ben Noble, director of the Seattle Workplace of Financial and Revenue Forecasts, instructed council users in early November.
That issues to the metropolis funds since of a tax billed on every sale, named the authentic estate excise tax, or REET. The metropolis now expects REET revenue to be $64 million decreased than as soon as expected involving now and 2024.
Forecasters also count on a slowdown in new development. That will possible signify fewer income from profits and business taxes.
The downturn underscores how the city’s finances depends on the ups and downs of the housing market place. It could also preview the fallout from a slowdown in the setting up increase that has outlined the metropolis for the past ten years.
On Monday, Seattle Town Council price range chair Teresa Mosqueda unveiled her balancing package, incorporating requests from the mayor and council as very well as the grim new earnings projections. The proposal trims jobs funded by REET and, in some situations, swaps in other revenues. The spending budget was the result, she mentioned, of “tough choices.”
Marketplace drives gloomy outlook
Seattle’s $7 billion funds relies on an array of earnings sources, not all of them linked to the authentic estate sector. But many important taxes observe intently to home profits and cranes on the skyline.
Seattle and several other towns across the point out charge a .5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} REET on all assets income, centered on the sale value. The revenues can only be employed for specific capital jobs, these types of as libraries, roadways, sidewalks and, not too long ago, economical housing, and are often committed to pay back again personal debt on people projects. (The condition expenses its own REET, which differs dependent on the sale rate.)
Skyrocketing dwelling prices and a rush of revenue have greater those people revenues in current several years. In 2021, Seattle introduced in far more than $112 million from the REET, up from $101 million in 2019.
Some decrease was not a shock. In previously forecasts, the town envisioned to deliver in $106.6 million in REET revenues this calendar year and practically $95 million each and every calendar year in 2023 and 2024. Having said that, now the town expects about $95.3 million this yr, just $68.1 million in 2023 and $68.6 million in 2024.
Mosqueda’s proposal would lessen proposed paying on parks upkeep, sidewalk and bridge-painting projects and planning for seismic retrofits at libraries established to be funded by REET, amid other budget shifts.
At the identical time, revenue taxes and small business and occupation taxes are anticipated to slide small by about $22 million about a few yrs. New construction accounts for approximately a quarter of the city’s sales tax revenues.
Residence tax revenue, by contrast, is much more steady for the reason that of point out law that limitations yearly residence tax increases to 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, besides for voter-approved actions. That means community governments didn’t see a huge influx when house values climbed in the latest years and do not expect to see a dramatic fall as the market slumps, Noble mentioned. Seattle expects people revenues to fall short of earlier expectations by about $3.4 million around 3 a long time.
The REET will battle not only for the reason that house prices are anticipated to drop somewhat but due to the fact the quantity of income has by now started to slow noticeably.
Property price ranges “don’t go down as speedily as they go up, normally. What occurs is individuals just don’t sell,” said Steven Bourassa, chair of the College of Washington’s Runstad Section of True Estate.
“On pause”
Business genuine estate investors are facing very similar headwinds. Better interest rates signify it is more high priced for investors to borrow.
“Everyone is sort of on pause,” claimed Katie Parsons, a Seattle-primarily based controlling director in valuations for JLL, a commercial authentic estate business.
The forms of residence nevertheless drawing considerable investor fascination are not a big aspect of the landscape in Seattle. Industrial land and storage services are interesting for buyers, Parsons stated.
As for the office environment market, tech layoffs and distant function position to a possible decrease in need for place of work towers like those in downtown Seattle. About 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of downtown business room was vacant in the 3rd quarter of this calendar year, according to a JLL report.
Even so, massive traders “still have rather a little bit of capital” they will commit somewhere, Parsons claimed. She expects traders to remain interested in “trophy belongings,” these as the most recent workplace towers, although scaled-down and more mature office environment properties could grow to be a lot less precious.
Apartment properties are probable to remain eye-catching for buyers, Parsons and Noble claimed.
Seattle’s funds struggles spotlight the hyperlink between the cooling sector and the excise tax made use of by numerous towns throughout the state to fund essential jobs.
If regional governments “rely intensely on taxes that rely on authentic estate transactions in a single way or yet another,” Bourassa stated, “they are dependent on the housing cycle.”
For Seattle, taxes on new construction and authentic estate transactions are not the biggest revenues, but they are “significant,” Noble said in an interview.
Which is specifically true simply because of the city’s development. When compared to scaled-down cities these types of as Shoreline, Seattle “is most likely far more vulnerable than its municipal neighbors mainly because we have been the target of a sizeable growth in construction,” Noble mentioned.
What’s future
How extensive will Seattle’s bleak outlook past? That is dependent largely on interest fees, Noble stated. The forecasts the city employs count on the housing current market to recuperate if interest prices decrease in 2024 or 2025.
“If fascination premiums continue to be large,” Bourassa stated, “then the marketplace is heading to continue to be weak.”
Goldman Sachs predicts dwelling rates will fall by 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from their peak and begin to rebound in late 2024.
Windermere economist Matthew Gardner predicted Monday that whilst residence costs may well decrease, “it will not be enough” to make residences reasonably priced for very first-time buyers.
Mosqueda claimed in an interview she sees the volatility as an additional argument for upzoning to draw in more advancement and, in transform, tax earnings. Townhomes, flats and condos can assist relieve the housing scarcity, she said. “It is also excellent for the bottom line for metropolitan areas.”
In a matter of months, the pandemic housing boom has turned into a rapidly spreading bust. Incredibly, recent reporting shows that home prices are now falling faster than they did during the run-up to the 2008 financial crisis.
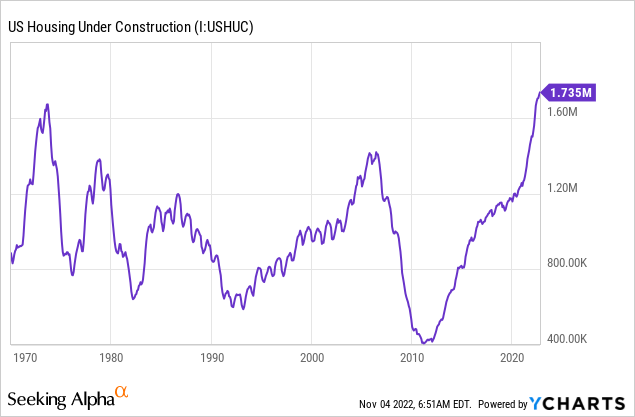
Decreased demand comes just as a tsunami of new supply is about to hit the market, with over 1.7 million privately owned homes currently under construction. This smashes the all-time record set in 2006.
The housing market was very overheated for a couple of years after the pandemic, as demand increased and rates were low. The market needs to get back into a balance between supply and demand (emphasis mine).
–Jerome Powell, Nov. 2 FOMC Meeting.
The developing crash in housing prices has profound implications for anyone looking to buy a house, as well as for investors in housing stocks. The iShares Home Construction ETF (BATS:ITB) is down a bit more than 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year, but if the situation on the ground is as bad as it appears, then it might be headed a lot lower. ITB is the worst of the worst when it comes to this kind of interest rate shock, because homebuilders borrow a lot of money to build, and in turn, they sell to their customers who borrow a lot of money to buy. This crash has been a long time coming as prices got further and further from fair value. Now that huge declines are rolling down the tracks, there’s not much that can stop it. If you already own a house with a low mortgage rate and didn’t buy it during the bubble, then no worries. But if you’re looking to buy a house now, think twice!
A Tidal Wave Of Housing Supply Is Coming
1.7 million homes are presently under construction in the US, the highest level ever. The peak in 2006 was around 1.4 million homes in various stages of construction. This obscures the fact that the US population was growing by nearly 3 million people per year in 2006, whereas the population now is only growing by somewhere between 500,000 and 1 million people per year.
At the average of roughly 2.5 people per household, that implies a need for nearly 1.2 million housing units built in 2006, but only 400,000 units in 2022 if we assume we gained a million people in population. There are reasons to believe that population growth could be even lower going forward, as declining inflation-adjusted wages and declining life expectancy (coronavirus, opiates, general malaise, etc.) take their toll. With mortgages over 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} now and population growth flatlining, who is going to buy all of these homes?
Of course, there’s a continual toll of obsolescence for homes (mostly homes in rural areas and the Rust Belt where people abandon them and move to greener pastures). This is thought to be about 300,000 homes per year. All-in, demographics imply the need for around 700,000 housing starts per year. We’re adding about twice as many houses as demographics imply we need to the construction pipeline on an annualized basis.
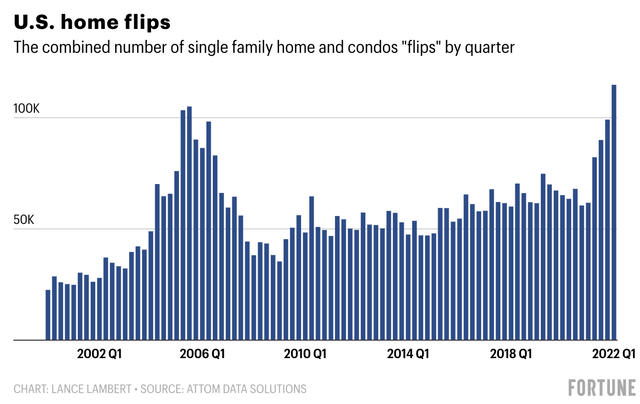
By contrast to the changing demographic picture, house flipping has been at an all-time high, with investors often selling to other investors.
Flip or Flop? (Fortune)
The Rental Market Is Reversing
Interestingly, a much higher percentage of units under construction than in the last cycle are multifamily units, either as condos for sale or apartments for rent (about 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Rents went crazy during COVID, but there’s actually a simple explanation for why they did, and why things may be about to reverse.
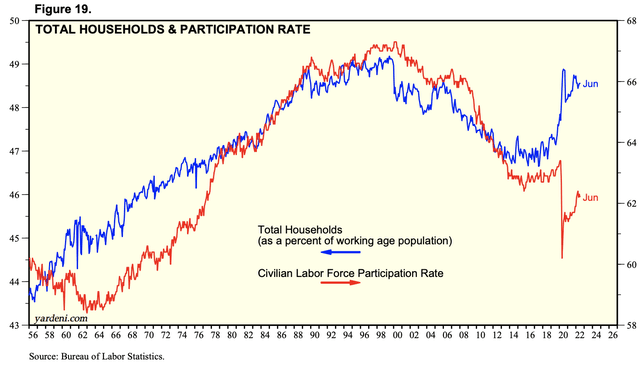
The eviction and foreclosure moratoriums allowed millions of people to live rent-free, massively choking the supply of housing while they were in effect. As I’ve written previously, the pandemic was the first time in the post-WW II era when fewer people worked but more people were occupying housing. Not normal! This is bound to revert to the mean, either millions more people are going to have to start working, or they’re not going to be able to pay rent/mortgage payments. In the vast majority of cases, people with insufficient income to support their current housing situation will just ride out their current leases and then not renew. They’ll move in with family, get roommates, or move to cheaper accommodation until supply and demand are balanced. When this data is updated next, I expect to see a lot of demand destruction.
Labor Force Participation Vs. Occupied Housing (Yardeni Research)
2. Price-fixing in the rental market. What’s not widely known is the effect that software used by large landlords may have had on the pandemic rental market. A recent class-action lawsuit alleges that a ubiquitous leasing software called YieldStar allowed large landlords to effectively form a cartel by letting a common algorithm set rental and lease renewal prices for all users. The software essentially used an algorithm to automatically coordinate pricing with thousands of other landlords, largely to avoid competing on price. Of course, the founder of YieldStar previously was forced to settle a case with the Justice Department for creating illegal price-fixing software for airlines. You can’t make this stuff up!
The evidence presented in the lawsuit is quite damning, and the fact that the main class action is being filed in Southern California means that this has the potential to be one of the largest class action payouts in US history. It’s very fashionable for people and politicians to blame rising prices on “greedy corporations,” and in many cases, it’s off-base. Here though, there’s evidence that using this software truly gave large landlords sufficient control over certain rental markets to extract monopolistic profits from tenants.
However, the theory will tell you that the free market will eventually respond to this sort of oligopoly, which is why we’re now seeing a huge boom in multifamily construction to cover for this artificial shortage. With some antitrust enforcement and letting the free market work, rents shouldactuallyfall over the next few years, which will help cool runaway inflation, albeit not nearly enough to bring inflation back to 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} by itself. In fact, asking rents have already begun falling.
The Demographic-Driven Housing Shortage Was Mostly A Myth
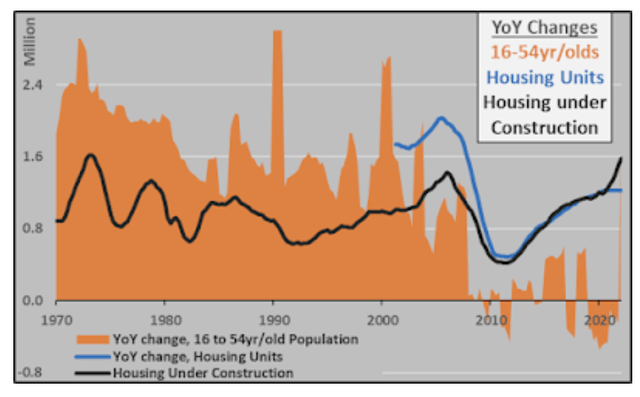
Though prices have skyrocketed, housing units per capita exceed the levels seen in 2008 in many markets. This doesn’t mean that housing isn’t scarce due to booming demand or too expensive, but what it does mean is that supply has easily kept up with demographics, albeit not speculative demand from investors, flippers, and second/third homeowners. The big spikes here below every 10 years are from one-off census adjustments, but the data shows that the US population aged 16-54 is actually falling.
Demographic Problems With Housing (Economica)
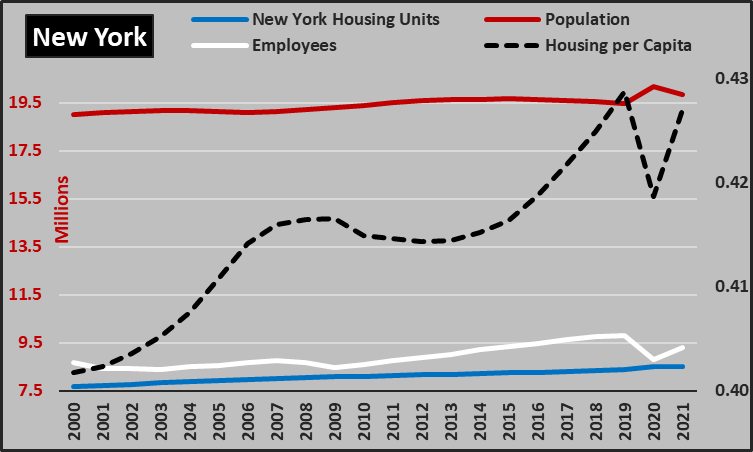
We see this when comparing the housing stock to the population. For example, construction in New York has continually increased the amount of housing stock available per capita (again note that the jagged lines in 2021 are from a census adjustment). This is the free market at work.
New York Housing Market (Economica)
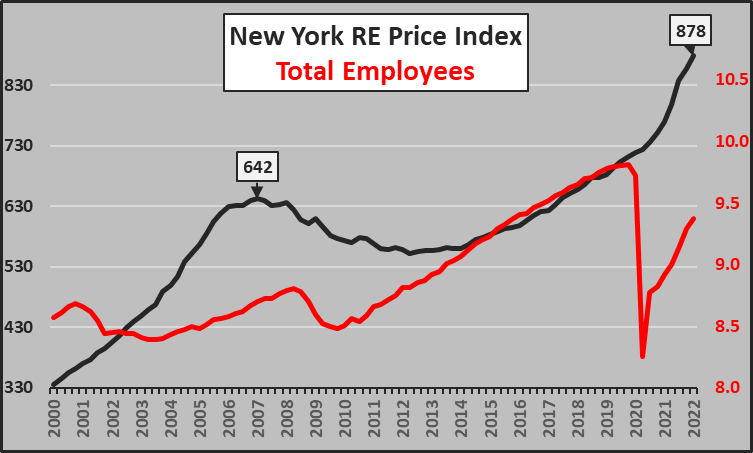
However, prices have surged, even while employment remains well below pre-pandemic levels. This is not the free market since 2019, instead, it was from interest rate suppression. Now that rates are skyrocketing, this is a huge shoe to drop.
New York Housing Market (Economica)
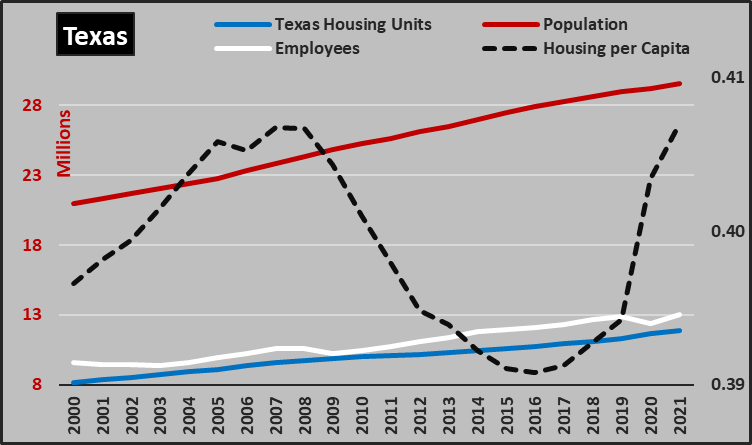
Texas also is an extremely interesting housing market to look at, because a lot of people are moving there, fueling the narrative that prices should automatically surge. But contrary to popular belief, construction in Texas has kept pace with migration trends, yet prices have skyrocketed. The most recent real-time data from Realtor.com shows that the Texas market is now among the leaders of the deepening housing market correction that started on the West Coast.
Texas Housing Market (Economica)
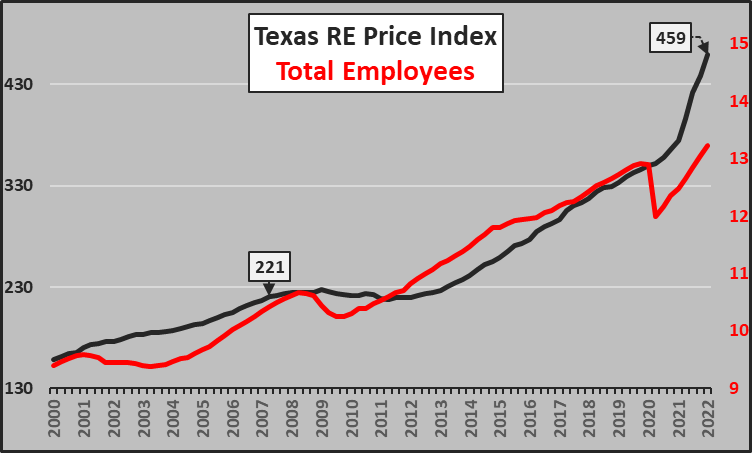
Surely prices should rise in line with supply and demand, but the degree of price rises while construction keeps pace with demographics should not happen. Note that while employment superficially looks better in Texas than in New York, median salaries are much lower while housing prices have surged far more.
Texas Housing Market (Economica)
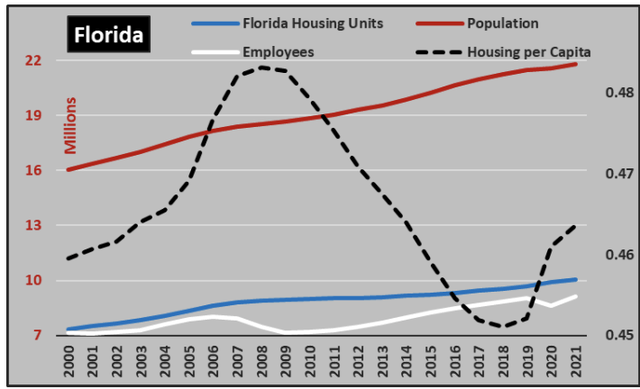
Construction hasn’t yet kept pace with migration in all markets. The author of the Economica blog noted that states like Florida, Nevada, and Washington had underlying demographic demand that could soak up homes if prices were to fall from their presently overvalued state. Still though, as hot as the real estate market is, Florida’s median income has increased something like 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} post-pandemic, while housing prices increased about 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Debt, debt, and more debt! Florida’s housing per capita has actually increased since bottoming in 2018 though when prices were almost half of where they are now. Also, a disproportionate amount of new housing supply will be coming online in sunbelt markets like Florida.
Florida Housing Market (Economica)
Demographic reality (i.e. wages) doesn’t square with the enormous boom in home prices, which is why many economists believe home prices are substantially overvalued. What’s really at play here is that housing prices have done nothing but go up because interest rates have done nothing but go down, fueling round after round of speculative buying.
But with an ongoing construction boom well in excess of population growth, the question is who will live in all these homes – five years from now, 10 years from now, and 30 years from now? 2008 showed that even markets with good long-term fundamentals tend to see crashes just the same because they receive a disproportionate amount of speculative investment flows. Tarrant County, in the Dallas-Fort Worth metro area, saw 52{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all home sales go to investors in 2021! That’s the height of insanity.
These figures imply that in a county with over 2 million people, less than half of homebuyers actually intended to live in the houses they were buying. This is after in the last 10 years, median income in Texas rose 29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, while the median mortgage payment on a new home purchase rose 280{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Home price gains of this magnitude are created by borrowing, not actual wealth. And while this article focuses on the US, I’d be remiss not to mention the other enormous housing bubbles globally, chiefly in Canada, Australia, and New Zealand.
The 20th Century housing market was boosted by steady population growth and a steady pace of urbanization, so prices went up. But with the process of urbanization complete in Western countries and population growth effectively at zero, continually adding supply should continually lower prices. This already has happened in parts of Europe where prices are well below 2007 inflation-adjusted peaks. In the long run, this can actually be a good thing because it means consumers get more for less, but it’s bad if you went all-in on housing with debt too early.
And Mortgage Demand Is Tanking
In the 2000s housing market bubble, America and much of the world had a cultural moment where real estate was praised as the only real way to build wealth. And after the 2008 crash, many of these same people got disillusioned and decided the juice of being a homeowner wasn’t worth the squeeze. From late 2019 to early 2022, a similar frenzy took hold. Now, demand is truly tanking again.
With mortgage rates over 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and prices up substantially since the pandemic, this is perhaps the worst time to buy a house in our lifetimes. This comes 10 years after the best time to buy a house in our lifetimes, and likely 2-3 years before a similar time may come again. Mortgage applications are down 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year over year. That’s simply stunning, considering how people were getting into bidding wars mere months ago.
There’s a famous economics paper from 2007 called Housing IS The Business Cycle. In it, the author argues that by setting interest rates to manage inflation and unemployment, the Federal Reserve had inadvertently inflated a housing bubble and would be forced to cause a housing bust to keep inflation from spiraling out of control. Instead, the argument is that the Fed should start hiking rates earlier in the business cycle to keep the housing market from becoming speculative chaos. Does this sound familiar at all? The key idea here: The later the Fed is in hiking interest rates (or doing quantitative tightening) during the boom, the less ability they have to help during the inevitable downturn.
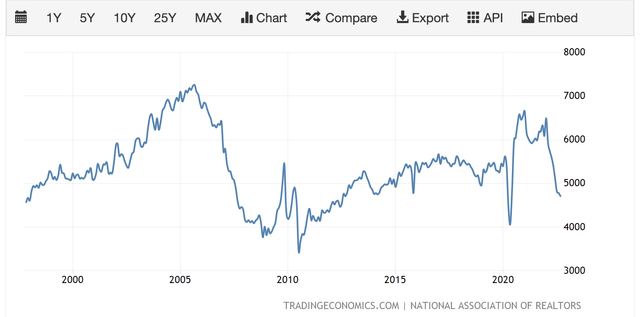
Notably, the paper was written in the middle of the 2000s crash at a point where buyers and sellers were in a similar standoff to today where sellers refused to sell and buyers could not or would not buy, so there also was a very interesting (wrong) prediction in the paper that prices would not crash but transactions would grind to a halt. Of course, prices went on shortly after to crash the most since the Great Depression. Here we are again, with leading indicators for future sales falling off a cliff.
US Existing Home Sales (Trading Economics)
One reason for this is – if I sell a house to buy another one, that’s not net housing supply. But if someone passes away and their kids put the house up for sale, or if a couple gets divorced and rents, or if investors sell because they realize that they’re not going to make money- that’s net supply. Unemployment is a huge driver of net supply over time, so if the unemployment rate begins to rise in the US, foreclosures and short sales hitting the market could have an unprecedented impact on the state of speculative demand.
The Fed May Need The Housing Market To Fall
The key difference between 2007 and now is that the Fed was far more behind the curve this time. In contrast to 2007-2008 when the government actively tried to help stabilize the housing market, the Fed is likely unable or unwilling to put a floor under housing prices, because they’re overpriced and they can’t waste money fighting the market. To this point, in light of the amount of arbitrary redistribution of wealth that the current housing boom has created, the housing market crashing from dizzying heights may be an intended feature of Fed policy, not a bug.
This isn’t my lifelong crusade. If housing prices fall 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and you can get a mortgage under 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (i.e. to historical norms vs. wages), I’d tell you that buying a house is a solid long-term investment. Similarly, if the stock market retreats to a more attractive valuation, you should buy it. If someone bought a house in 2017 and ends up being breakeven in price appreciation seven years later after the market crashes, that’s fine because they bought at fair prices and saved rent along the way in a similar fashion to investors getting dividends. But if someone bought a house in 2021 or 2022 for far above the house’s fundamental value, they’re in a ton of trouble, especially new construction buyers who locked in purchase prices at signing but had to wait to lock bank financing at completion (when mortgages soared from 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or more). New buyers likely had no idea what they were getting into.
Buyers who are taking sellers’ asking prices right now are dramatically overpaying based on market fundamentals. This is why so few people are buying homes right now compared with the recent past, and why so many homebuyers are canceling their contracts with builders. Like it or not, the 21st Century real estate market has been a wild carnival ride – redistributing years and years of salary income to winners from losers. If you make a bad decision regarding housing, it can negate the earnings from a six-figure salary for a decade or longer. The market is speaking right now if you’re willing to listen, and what it’s telling you is that the unhealthy US housing market is in a twice-in-a-lifetime amount of trouble. Investors in housing-sensitive stocks like homebuilders should pay attention to the macro picture with the real estate market and consider selling their positions as well.
Bottom Line
Will this housing market crash outdo 2008? It’s yet to be seen. A key reason behind the 2008 housing crash was a rise in the rate of unemployment. If unemployment stays relatively low, then home prices may just grind downward. But if unemployment rises to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, or more, millions of motivated sellers will hit the market with relatively few takers due to the changing demographic reality of America and the amount of demand that was already pulled forward during the pandemic. And in 2008, houses were objectively cheap, drawing capital in from institutional investors. If home prices were to fall something 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}-20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from here, valuations would still be higher than fundamentals suggest they should be. Those declines would only take us back to 2021 prices, with rates dramatically higher. For these reasons, it’s very possible for this crash in housing prices to exceed 2008’s in magnitude.
As the U.S. housing sector states goodbye to very low mortgage rates—and residence sales slump as a result— this is the big problem: Is it now time to invest in residential real estate?
“For buyers like us (it) is an possibility, essentially, to scoop up some new stock and master system communities at, I believe, rates that will be effectively-down below what we could have seen very last yr,” Nuveen True Estate World wide CIO Carly Tripp advised Yahoo Finance Are living (movie higher than).
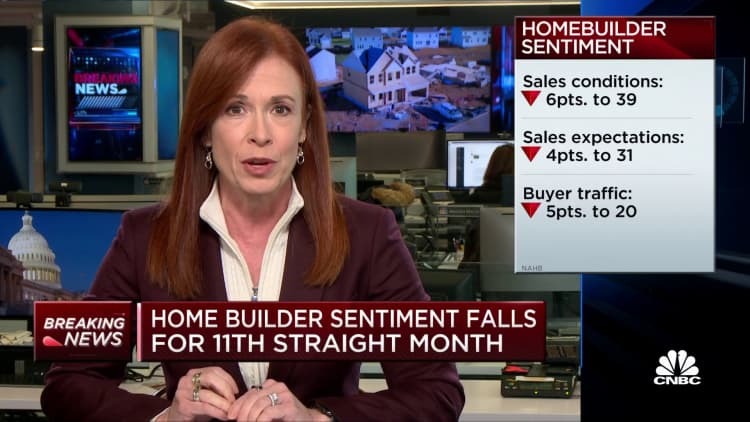
There’s no denying that the real estate market place has been hideous. U.S. property charges were pushed down in August. A measure of selling prices in 20 substantial U.S. cities fell 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on a thirty day period-in excess of-thirty day period foundation, according to the S&P CoreLogic Situation-Shiller index. In October, homebuilder self-assurance slipped for the tenth consecutive month, hitting the least expensive level since the onset of the pandemic, according to the Nationwide Association of Home Builders/Wells Fargo Housing Marketplace Index.
And, homebuilders and customers alike are contending with the maximum mortgage loan costs in two decades on prime of rampant inflation.
“I do not hope homebuilder self-confidence to arrive back again any time shortly. As you saw, it’s plummeted. And it is really envisioned to proceed to plummet,” Tripp added.
But some savvy investors imagine that real estate has been, and will carry on to be, a constant hedge in opposition to inflation. In other words and phrases: it may possibly be time to acquire as others pull back.
According to Tripp, rental qualities could be an option for customers. Rental house homeowners, for illustration, can increase rents as demand from customers soars— a final result of possible homebuyers emotion to the sidelines.
There is heading to be “continued force on the capacity to buy and offer a residence. And so what that’s gonna do is increase the demand for rental housing,” Tripp mentioned.
Multifamily investment decision can also provide as a hedge against inflation by providing the chance to reset lease rates as commonly as each and every 12 months, as opposed to 3 to 10 yrs for other property kinds. This presents buyers with the versatility to reset pricing to fulfill demand from customers or in a way offset increasing operational expenses.
New multi-family apartment creating
“But, I would say that if you glimpse across your rental solutions, solitary relatives rental, we’re seriously looking at a great deal of tempering in new commences and under design compared to multifamily, which is continuing to outdo historical numbers,” stated Tripp.
Dani Romero is a reporter for Yahoo Finance. Observe her on Twitter @daniromerotv
Examine the most current economical and small business information from Yahoo Finance
Learn what your options are as a potential investor in Canadian real estate
Photo by StackCommerce
Reviews and recommendations are unbiased and products are independently selected. Postmedia may earn an affiliate commission from purchases made through links on this page.
Article content
This article was created by StackCommerce. Postmedia may earn an affiliate commission from purchases made through our links on this page.
Advertisement 2
This advertisement has not loaded yet, but your article continues below.
Article content
In the Canadian real estate market, home prices have been rising for years. Many potential homeowners are moving away from cities toward small towns and rural opportunities, and a lot of prospective buyers have been priced out with a critical scarcity of affordable housing. This adds up to mean unsavvy investors are at risk of losing money on their properties, though that doesn’t mean there aren’t opportunities. For beginners, investing in real estate in Canada right now means doing more research and planning more carefully before taking any action.
Financial Post Top Stories
Sign up to receive the daily top stories from the Financial Post, a division of Postmedia Network Inc.
By clicking on the sign up button you consent to receive the above newsletter from Postmedia Network Inc. You may unsubscribe any time by clicking on the unsubscribe link at the bottom of our emails. Postmedia Network Inc. | 365 Bloor Street East, Toronto, Ontario, M4W 3L4 | 416-383-2300
Thanks for signing up!
A welcome email is on its way. If you don’t see it, please check your junk folder.
The next issue of Financial Post Top Stories will soon be in your inbox.
We encountered an issue signing you up. Please try again
Article content
Article content
One way to get started is with online research, but that can be overwhelming. Alternatively, curated online training programs, like the Fundamentals of Real Estate Investment Bundle, can be a more manageable jumping-off point. This 17-hour series of real estate investment training courses can help build your foundational knowledge and gain confidence for investing in residential or commercial properties. There’s no sure thing when you’re investing, whether in the real estate or stock market, but preparing well may mitigate some risk, and the five-course e-learning bundle is a good place to start.
Advertisement 3
This advertisement has not loaded yet, but your article continues below.
Article content
In a time of flux, learning the basics of real estate investment may be intimidating. There’s more to it than finding an attractive property, throwing money at it, and waiting for your ROI. Learning to calculate a property’s value over time is complicated. You have to consider what the property will be used for in the long and short term, whether it will generate consistent revenue or be sold when it has appreciated in value, and how your property fits in the context of the greater Canadian real estate market, among other things. For beginner investors, there’s a lot to learn.
Growing your foundation as a real estate investor
Good news: You don’t have to be a millionaire to start investing. There are many types of real estate investments, and the right one could act as a continuous supplement to your income as you build up the capital to invest more. Cash-flow investing, purchasing an asset that provides income at regular intervals, is a popular approach to rental properties. You can collect rent — ideally covering all the costs of the property and then some — while holding the investment long-term. If your asset appreciates in value over time, you could sell it for a profit that’ll provide more capital for higher-value investments.
Advertisement 4
This advertisement has not loaded yet, but your article continues below.
Article content
One method for managing a cash-flow investment property is to turn it into an Airbnb. Who better to learn about rentals from than Symon He? He is one of the authors behind Airbnb for Dummies, and he is a co-founder of LearnAirbnb, a consultancy and education blog for the home-sharing economy.
Finding the right property for your first investment can be a challenge, but the lessons included in the bundle can point you in the right direction. In Pre-Investing: Before Investing in Real Estate, he discusses identifying the value of a property, understanding the market in which you’re investing, and how to value a property. You’ll also get to see an example of rental income property analysis for real-world application.
Advertisement 5
This advertisement has not loaded yet, but your article continues below.
Article content
How to be realistic about making money in real estate
Real estate is not the lottery, and you probably won’t make money overnight. Current predictions are that Canadian home prices may fall up to 25 per cent in 2025 as inflation returns to normal levels. Online courses like Fundamentals of Real Estate Investment Analysis may help you get a sense of making good investments and avoiding bad ones. As you learn more about your investment goals, that change over time could drive you to plan for cash-flow investments less impacted by changes in market prices, or it could tell you that you’ll have to hold onto your appreciating assets longer.
The shifting of the market or your own financial shifts may indicate it’s time to work with an investment partner. If you can identify a lucrative investment, then a split profit is still a profit, so it would be wise to learn the practicalities of working with a team, as presented in How to Invest with Partners in Real Estate.
Advertisement 6
This advertisement has not loaded yet, but your article continues below.
Article content
Other experts feel that the expensive Canadian housing market will remain until there is large-scale government intervention. If that proves true, you may want to learn more about finding or creating wholesale deals, which is also covered in these online courses. Buying and selling on a wholesale deal — one of the only viable short-term investment models in real estate — could help you build capital fast. Guidance on pitching a property to investors and understanding a property’s repair value are all covered in He’s lectures.
Canadian investment properties are waiting for you
For beginner real estate investors, the stakes are high. Whether you’ve arranged a wholesale deal, worked with investment partners, or secured your ideal cash-flow property, there’s no guarantee that you will make a profit. However, you can increase your chances of earning money by making sure you’re informed about the investment process, staying in the know about recent and current real estate happenings, and being ready to jump on a great deal when you find one. For $32.99, the Fundamentals of Real Estate Investment Bundle can provide you with essential tools for becoming a savvier real estate investor.
Prices subject to change.
Share this article in your social network
Advertisement
This advertisement has not loaded yet, but your article continues below.