The property advancement market place is bracing for a bumpy highway.
Two of the major house improvement vendors, Property Depot (Hd) and Lowe’s (Lower), warned of softness in the market in the latest earnings reviews, indicating the year in advance is probable to be a tricky 1 as inflation weighs on shoppers.
“In 2023, residential expenditure will be underneath some strain, provided elevated concentrations of inflation, greater interest charges and a a lot more careful client,” Lowe’s CFO Brandon Sink told analysts on the earnings call on Wednesday. “We are forecasting a slight decline in the house-improvement current market.”
“We do assume moderation in dwelling enhancement demand,” House Depot CEO Ted Decker told analysts on the company’s earnings meeting phone very last week. “Persons are also setting up to change shell out extra in the direction of companies. And as we have said, we see some a lot more value sensitivity,” he additional.
The warning comes as Lowe’s (Lower) posted a blended quarter on Wednesday prior to the industry open up.
The retailer documented adjusted earnings for every share of $2.28, topping over analysts expectations for $2.21. Profits missed estimates, coming in at $22.4 billion against anticipations for $22.7 billion, according to facts compiled by Bloomberg.
“The slower start off to the quarter was owing in section to slower gift buying demand in the course of the holiday break period, about just one-third of product or service combine is discretionary in nature,” Bobby Griffin, an analyst at Raymond James, wrote in a be aware to clients next the outcomes.
For 2023, Lowe’s is forecasting sales to be between $88-$90 billion, though similar-retail outlet-revenue are believed to be flat or down 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year. Executives see the pullback in Diy demand from customers as transitory, and other experts in the marketplace see a “historic boom” coming for residence transforming.
Nick Teichtmann (R,) with the help of Lowe’s personnel Jaime Solis, purchases lumber to renovate his residence by incorporating a gazebo on best of a deck and repairing his garage at Lowe’s residence improvement retailer on April 11, 2011 in Burbank, California. (Picture by Kevork Djansezian/Getty Illustrations or photos)
“Disposable own earnings, which I pointed out, is about $1.5 trillion in cost savings earlier mentioned pre-pandemic amounts,” CEO Marvin Ellison explained to analysts on the earnings simply call.
Ellison pointed out the regular equity for residences in the U.S. is about $330,000, and anticipations of growing older housing inventory could place to continued desire for home upgrades.
“Two-thirds of every little thing we market is non discretionary. And there are other tailwinds, millennial household development trend, little one boomers ageing in location and additional widespread sustainable remote work, so all of these matters give us some self-assurance that the backdrop remains supportive,” Ellison additional.
Shares of both equally Residence Depot and Lowe’s are down over 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the very last month.
Lumber deflation
The times of pricier lumber could be more than.
The housing slump has triggered a crisis in lumber, with lumber futures falling 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the earlier calendar year. And homebuilders are using observe.
Pulte Group (PHM) introduced in their hottest earnings get in touch with the company is picking up their pace of design amid elevated lumber stock and more inexpensive pricing.
A be aware from analysts at UBS published very last month claimed some authorities in the homebuilding room see kitchen cabinetry and home windows, fairly than larger framing or roofing initiatives, driving desire for lumber.
And however lumber selling prices have fallen sharply, the firm pointed out for quite a few “main” housing solutions charges “have reverted to ‘reasonable levels,’ but [builders] are not witnessing any authentic rate reductions from sellers.”
As just one expert explained to the company, most solutions are “in no way going [to] pre-Covid rates once again.”
Dani Romero is a reporter for Yahoo Finance. Follow her on Twitter @daniromerotv
Dear Readers, do note that most of the data here were generated between 22 and 25 December 2022, and the rest from 26 to 30 December 2022. Also, any “Buy” rating in this article is a “Conditional buy” which comes with having certain conditions being met. You will need to assess if an asset is a “buy” based on your expected returns from that asset which is a very personal decision.
Happy New Year, everyone! May your 2023 be far better than 2022 in every imaginable way.
An Introduction to Home Depot and Lowe’s
Anyone familiar with the home improvement scene in the United States will know that the two largest listed companies in this space are Home Depot (NYSE: NYSE:HD) and Lowe’s (NYSE: NYSE:LOW).
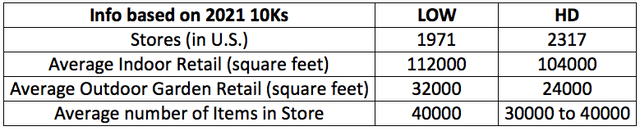
They are similar in many ways, with almost the same number of stores, having outlets of similar size, etc.
Author’s compilation of info from 10Ks and transcripts
Both companies target essentially the same profile of customers, the DIY (do-it-yourself), DIFM (do-it-for-me), and Pros Customers (professional contractors in two broad categories, those in the construction trades like renovators/remodelers and general contractors, and those in maintenance, repair and operations like building managers, handymen and specialty tradesmen such as electricians, carpenters and plumbers).
Both companies essentially sell similar products and services. They have to make the extra effort to differentiate themselves with their respective house brands, “unique” product offerings, and through their service quality. For instance, Sherwin-Williams paints are sold exclusively at Lowe’s while Ryobi are sold at Home Depot but not at Lowe’s. Home Depot sells its own proprietary products (HDX, Husky, Hampton Bay, Home Decorators Collection, Glacier Bay, Vigoro, Everbilt and Lifeproof), but Lowe’s has its Allen+, Roth, and more recently Origin21.
As mentioned in the LOW’s 10K,
We have many competitors who could take sales and market share from us if we fail to execute our merchandising, marketing and distributionstrategies effectively, or if they develop a substantially more effective or lower cost means of meeting customer needs, resulting in a negative impact on our business and results of operations.
Other than each other, these two companies also compete with traditional hardware, plumbing, electrical, home supply retailers, and maintenance and repair organizations, as well as with general merchandise retailers, warehouse clubs, online retailers, other specialty retailers, providers of equipment and tool rental, as well as service providers that install home improvement products. Other than selling products at different price points to target different demographics, having locations in all the states, and reducing friction in the transaction process to make the process convenient for their customers, service quality will be the other key differentiating factor. More on service quality later.
Both are Great Companies to Hold Long-Term
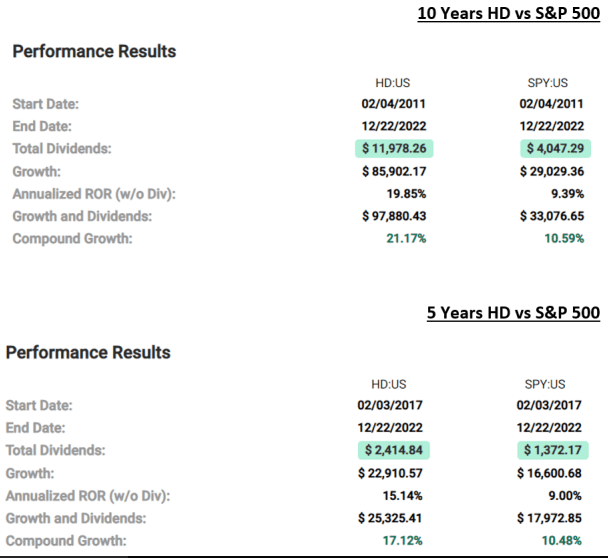
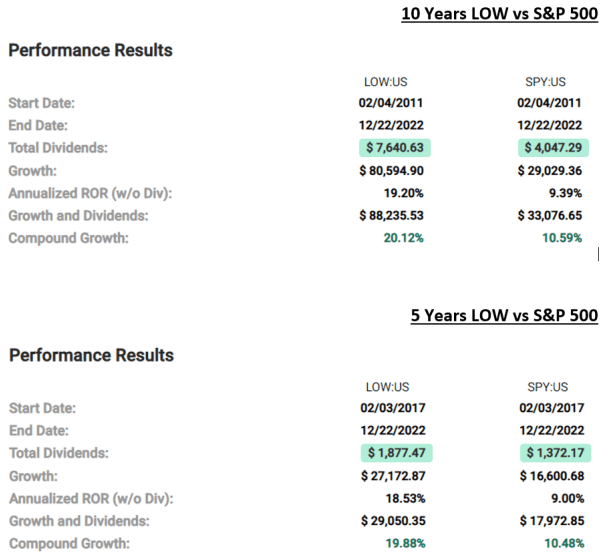
It is not surprising to find many shareholders of Home Depot also owning shares of Lowe’s as both companies have been performing well, trouncing the S&P 500 over a longer 10-year as well as a shorter 5-year period.
Fast Graph HD
Fast Graph LOW
Note: I chose these time frames to (1) exclude the worst of the Great Financial Crisis and (2) to factor in technological improvements that happened during the last 10 years that both companies could have leveraged such as better visibility of data via cloud computing, the use of touch screens interfaces to improve productivity, greater automation and use of robotics in the distribution centers, etc. This is important when I cover the section on “The Case for Lowe’s to Outperform Home Depot”.
Both Face Similar Headwinds and Benefit from Similar Tailwinds
A common concern that industry watchers and analysts have regarding the home improvement industry is the impact a slower housing market has on the future earnings of both companies, especially for Lowe’s since the majority of their customers are homeowners, they are likely to defer or reduce their budget for home improvement works.
This may be true but the impact should not be dire. Lowe’s CEO Marvin Ellison pointed out what he believes to be a myth regarding a positive correlation between a decline in housing with sales in home improvement, and posited three compelling arguments for a sustained tailwind in this industry
…demand drivers for home improvement are distinctly different from those that drive home building. So it’s important not to confuse the two. And as a reminder, at Lowe’s, the three highest correlating factors of home improvement demand are home price appreciation, age of housing stock and disposable personal income.
So let’s start with home price appreciation. Even if there is a broad-based decline in home prices, homeowners currently have a record amount of equity in their homes, nearly $330,000 on average, which remains supportive of home improvement investment. And even in the select U.S. markets where home prices have declined after a particularly steep run-up during the pandemic, we are not seeing any impact to sales.
Second, the average age of homes in the U.S. is over 40 years old and roughly 3 million more homes built during the housing boom in the mid-2000s, will be entering prime remodeling years by which is a key inflection point for big-ticket repairs. This is one of the key reasons why 2/3 of home improvement spend is nondiscretionary on repair or maintenance projects that cannot be delayed.
Third, consumer savings are near record highs, while disposable personal income remained strong. And more than 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homeowners either own or home or are locked into a low fixed mortgage insulating them from rising rates.The facts are that we have more personal disposable income today than we had before the pandemic, and that’s primarily in the bank accounts of homeowners… it was still 1.5 million to 2 million homes under current demand .
On top of these three factors, there is a persistent 1.5 million to 2 million undersupply of homes because of the lack of home building coming out of the financial crisis in 2008 and 2009, and 250000 first-time millennial homebuyers are expected per year through 2025. These factors lead homeowners to choose an investment in repairs and renovations to make their current homes meet their families’ evolving needs rather than buying a new home at record-high prices. In other words, this period of high inflation and rising interest rates actually drives greater demand for the home improvement industry.
Home Depot’s CEO Ted Decker agrees with CEO Marvin that sales can continue to be strong in 2023. In his response to an analyst who was concerned about the negative impact of a slower housing market on sales, he said,
There is a lot of noise around housing and home improvement. And you’ve heard some of this before, but if I can just step back a minute and lay out the environment the way we see it. I mean, we still feel very good, Michael, about our business. We just reported another strong quarter and reaffirmed our guidance for the year… From our core customer, we think our customer is still healthy. I mean, our customer tends to have a good job, growing wages, strong balance sheets. They own their home and have seen increased home equity.
Both CEOs also shared feedback from their Pro customers that most of them are expecting a robust backlog of projects pushing forward to 2023. Does this mean both stocks are a buy since the demand for home improvement will continue to be “strong and robust”?
So, after this brief introduction to what they do, some similarities, how they had performed, some of the industry-relevant tailwinds and headwinds, and the stance of the CEOs on the state of affairs, which is the better company to own?
The Obvious Winner is Home Depot
Home Depot has the largest market share, 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the $900 million to $1 trillion estimated total addressable home improvement market to be exact. That is a clear lead over second place Lowe’s 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the market share.
Home Depot is expected to do better than Lowe’s in an inflationary and recessionary environment that is compounded by a slower housing market scenario. The rationale goes like this: 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Lowe’s revenue comes from the DIY and DIFM crowd and if they choose to prioritize more immediate bread-and-butter spending needs over home improvement works, Lowe’s will take a bigger hit. On the other hand, 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Home Depot comes from professionals that include maintenance, repair and operations which are expected to have ongoing works in 2023, Home Depot is not expected to be hurt as much.
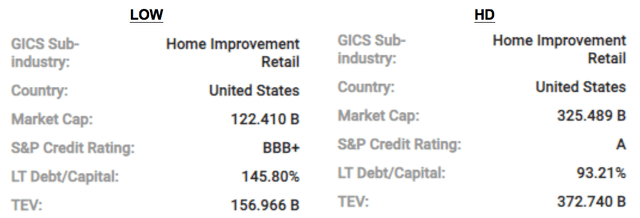
Both companies are investment grade but Home Depot is better with an A credit rating compared to Lowe’s BBB+. HD is also less leveraged than LOW, which has a higher long-term debt-to-capitalization ratio of 145.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Fast Graph comparing LOW and HD
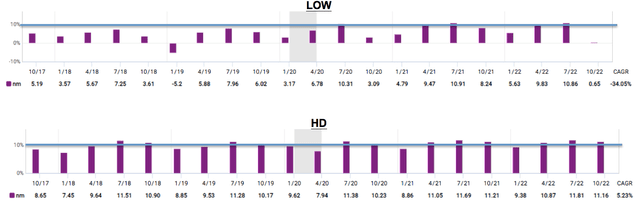
Bottom line matters and net margin affects that directly. Over the past 21 quarters, Home Depot’s net margin was consistently in the 9-10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} range. Lowe’s net margin however fluctuated much more from -5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10.91{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Fast Graph comparing LOW and HD
Those stable and consistently higher margins translate to higher sales per square foot for Home Depot. In the fiscal year 2021, Home Depot generated $604.74 in sales per square foot. In comparison, Lowe’s managed a respectable but much lower $463 in sales per square foot.
Finally, income investors will find Home Depot’s 2.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield more appealing than Lowe’s 1.86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Case closed? Not so fast. Reality is always more nuanced. I believe there is a strong bull case for Lowe’s.
The Case for Lowe’s to Outperform Home Depot
In the earlier segment under “The Obvious Choice is Home Depot“, I laid out comparisons of the fundamentals of both companies to show that Home Depot is a better choice. Yet, you may be surprised to know that an investment in Lowe’s 40 years ago would have been almost 400{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} better than an investment in Home Depot.
Historically, Lowe’s Had Massively Outperformed Home Depot
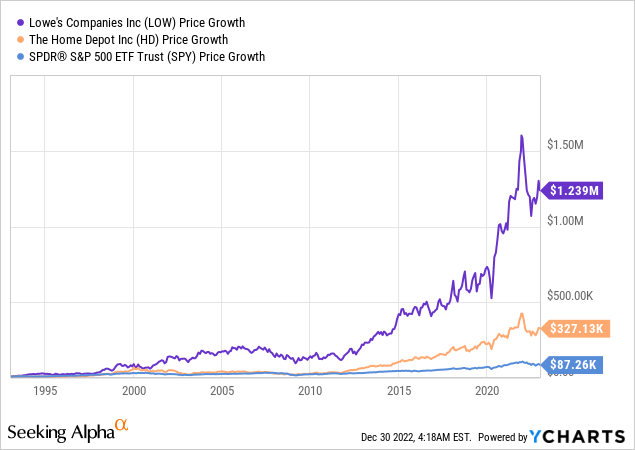
Previously, when comparing both companies over a 5-year and 10-year period, Lowe’s actually performed slightly better than Home Depot. To show that I did not cherry-pick the timeframe to get a favorable result for Lowe’s, I extended the comparison period to exactly 40 years, from 30 December 1982 to 30 December 2022.
A $10,000 investment in SPY would have become $87 thousand. The same amount in Home Depot would have increased to $327 thousand. But $10 thousand invested in Lowe’s would have turned into an envious $1.2 million dollars.
Past performance is definitely no guarantee of the future but it does give an indication of the possibility and the potential so let’s turn to examine the future earnings growth rate of both companies.
Based on Earnings Projections, Lowe’s Is A Better “Buy”
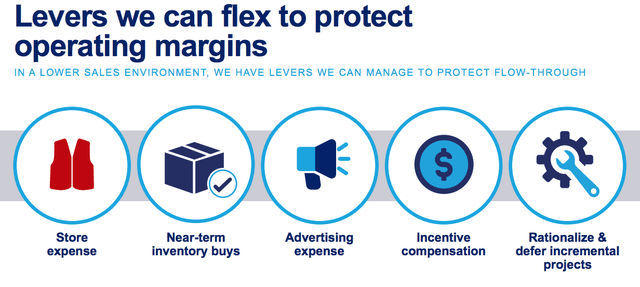
As both companies are huge, with a combined market share of 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the entire home improvement industry in the United States, there are levers for them to pull to improve operating margins, lower costs by ordering in bulk, pass costs on to their customers, and improve the bottom line. For instance, during the 7 December 2022 Investor Day presentation, Lowe’s CFO shared the following levers for improving their operating margins.
Lowe’s Investor Presentation Slides by CFO
Home Depot has not shared its guidance for 2023 as its investor day will be in the middle of next year but I will not be surprised to see the company do likewise if they need to squeeze out positive earnings.
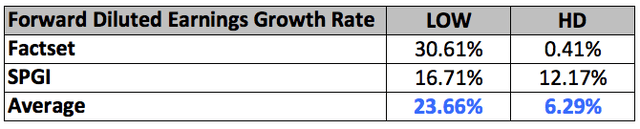
Analysts modeled the earnings growth rate and the results are tabulated below.
Author’s collation of analysts’ forecast
The disparity between these two sets of earnings growth estimates is great but believable. Morningstar analyst Jaime M. Katz wrote a memo on 15 December 2022 saying,
With continued focus on retail fundamentals (merchandising excellence, operational efficiency, supply chain improvements, and customer engagement), Lowe’s has been able to better leverage costs while maintaining its low-cost position. The firm retains some of the cost savings it achieves and passes the rest on to its customers through everyday low prices. These competitive advantages support our wide economic moat rating.
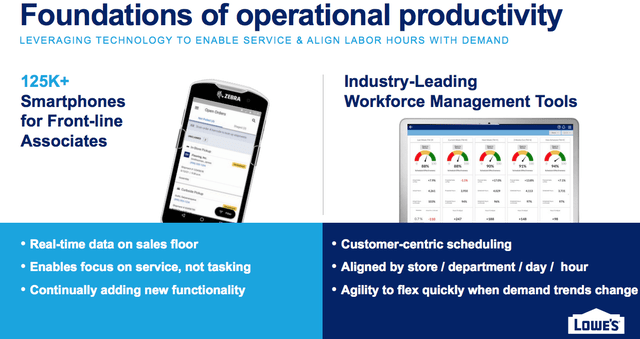
Lowe’s has been undergoing a multi-year technological and logistical transformation to improve productivity. It developed a customer-centric scheduling system to allow it to predict customer demands and align its labor with peak customer traffic for each store, each department, by each day, and even by each hour of the day to maintain its consistent and strong customer service and reduce payroll expenses. More on how Lowe’s is able to cut more expenses and improve margins to a greater degree later.
Based on Valuations, Lowe’s Is Cheaper
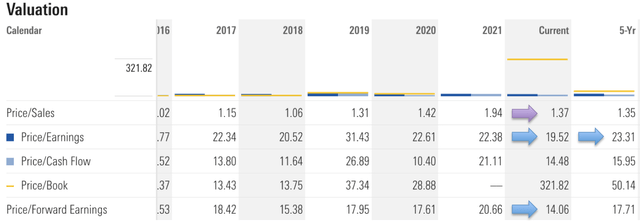
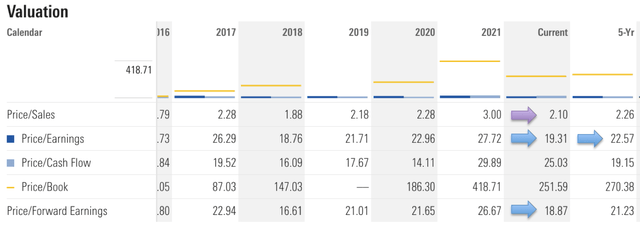
Both are trading at P/E and forward P/E valuations below their respective 5-year averages.
Lowe’s Valuation from Morningstar
Home Depot’s Valuation from Morningstar
I would like to draw your attention to the forward P/E; Lowe’s much lower price/forward earnings of 14.06 compared to Home Depot’s 18.87 is a reflection of both the better-expected future earnings for Lowe’s as well as worse-expected future earnings for Home Depot.
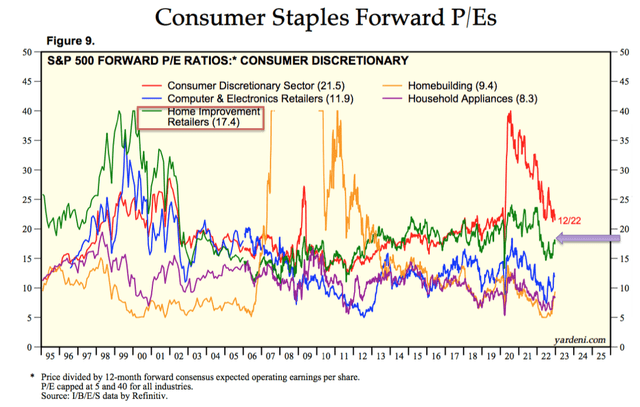
Yardeni Research
That also means that Home Depot is expected to continue to trade at a premium in 2023 relative to the stocks in the Consumer Discretionary category while Lowe’s is expected to trade at a much better valuation which will offer a much preferable entry point and a higher margin of safety.
Lowe’s Has Higher Average Ticket Than Home Depot
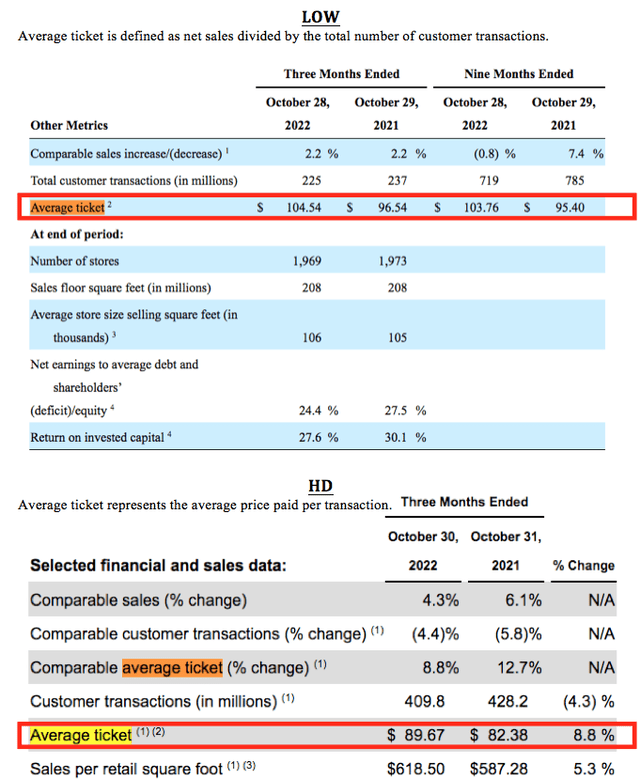
Home Depot can boast of having a higher revenue per square foot than Lowe’s but that is not everything. Another key metric management of both companies uses to monitor the performance of the Company is “Average Ticket” as it represents a primary driver in measuring sales performance. “Average Ticket” represents the average price paid per transaction.
Comparison of The Latest Q3 2022 Average Ticket
Although Home Depot consistently chalks up a higher sales per retail square foot figure than Lowe’s, the average Lowe’s customer consistently outspends Home Depot’s customer.
Dividend Growth Investors Would Love Lowe’s
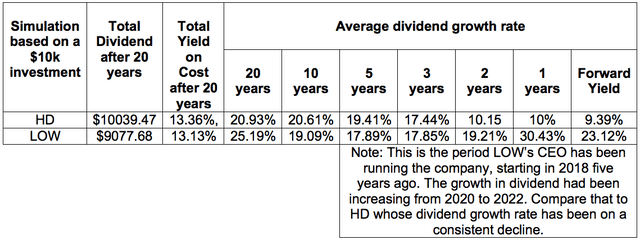
I will be remiss if I fail to mention that Lowe’s is a Dividend Aristocrat that has risen dividends for 49 consecutive years compared to just 13 consecutive years of dividend growth for Home Depot. Although Home Depot provides a higher yield than Lowe’s, an investor with a longer investment horizon should give Lowe’s a second look. Over a 20-year period, because of Lowe’s higher dividend growth rate of 25.19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an investor could have gotten back $9077.68 which is close to HD’s $10k of dividends.
Author’s compilation of data taken from Fast Graph and Seeking Alpha
And looking forward, one can also see the disparity in the average dividend growth rate. While Home Depot is decreasing its rate of dividend growth to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this year and an expected 9.39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth in 2023, Lowe’s never fell below 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In fact, under CEO Marvin from 2018, the dividend increased for three consecutive years, and it is still expected to grow the yield at a lip-smacking rate of 23.12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fiscal year 2023.
With that, I will move on to the final bull-case argument for Lowe’s – management.
Lowe’s Management Knows What They Are Doing, And Knows What Their Competitor Is Doing
In the most recent earnings call, CEO Marvin Ellison said,
As I said in my prepared comments, we’ve got a lot of experience sitting around this table. There’s very few things that we have not seen.
Usually, we might have interpreted this casually as “we are a bunch of people who have worked for many years in the home improvement industry, so trust us to do the right thing“, and therefore dismiss the importance of his characterization. There is more to what he meant.
You see, three of the current leadership team at Lowe’s had prior experience working in various executive roles at Home Depot and one of them worked at another large competitor for almost 2 decades. They knew first-hand what had worked at Home Depot and Walmart and could adapt the relevant processes and strategies to Lowe’s. I will mention them briefly below while putting the focus on the CEO.
Joe McFarland, Executive vice president of Operations, served at Home Depot as President from 1994 to 2015. During his time at Home Depot, he led improvements in customer service and productivity so frontline staff could spend more time providing customer service and making sales.
William Boltz, Executive vice president of Merchandizing, served in different merchandising roles at Home Depot.
Donald Frieson, Executive Vice President of Supply Chain, was not a Home Depot veteran but he has more than 30 years of operations and supply chain experience, including 19 years at Walmart, joined Lowe’s in 2018. He is widely recognized as a cost containment expert.
CEO Marvin Ellison
He was brought on board at Lowe’s in 2018. Prior to that, he worked at Home Depot for 12 years from 2002 to 2014. He served as executive vice president of Home Depot’s U.S. stores from 2008 to 2014, “dramatically improving customer service and efficiency across the organization, as he oversaw U.S. sales, operations, installation services, tool rental and pro-strategic initiatives“.
And upon joining Lowe’s he had taken a hard look at his company. At the 7 December Investor Presentation Day, CEO Marvin was brutally candid about Lowe’s shortcomings,
One critical step in our evolution is moving away from a store delivery model which was terribly inefficient. With our old store-centric system, each store served as its own distribution centre for big and bulky products. We were holding the appliances in our back rooms, and storage containers behind our stores and using our store trucks to deliver them to customers. That meant customers can only purchase inventory from that single store. They didn’t have visibilityinto the inventory we had to offer and neither do our associates. And because or store-based trucks didn’t have delivery or routing software, customers did not have visibility into the delivery process. They didn’t know when their appliances will arrive so to say this was a poor customer experience would be an absolute understatement.
That kind of honesty was simply mind-blowing to me. And that was definitely what a leader needs to meet the challenges posed by its largest competitor with a market share that is more than twice as large.
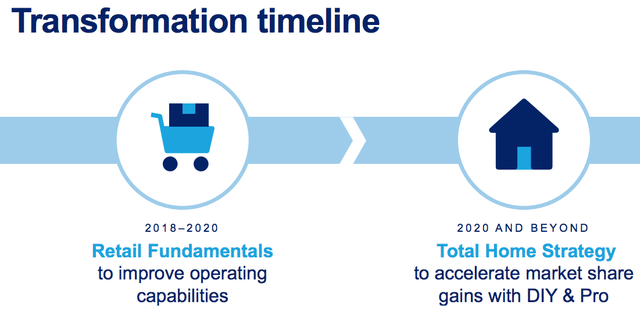
Under his leadership, he set Lowe’s on a two-stage transformation. Part one is on improving the fundamentals of the business to address the numerous issues which he had highlighted, to transit Lowe’s from a store-centric system into a more efficient customer-centric market-delivery model.
Investor Day 2022 Presentation by CEO
Part one is the low-hanging fruit, which when achieved will boost margins and earnings quickly and Lowe’s is on track; the full rollout is expected to complete by the end of 2023.
Investor Day 2022 Presentation by CEO
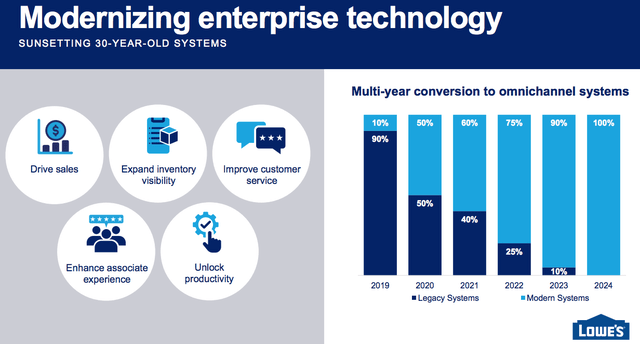
Likewise, Lowe’s modernization efforts are already paying off. Some examples: frontline associates in the backrooms and distribution centers are using their own smartphones to access inventory and complete fulfillment for online orders; more self-checkout stations are installed; cashiers are working with touch-screen terminals that make training new associates easier.
Investor Day 2022 Presentation by Joe McFarland
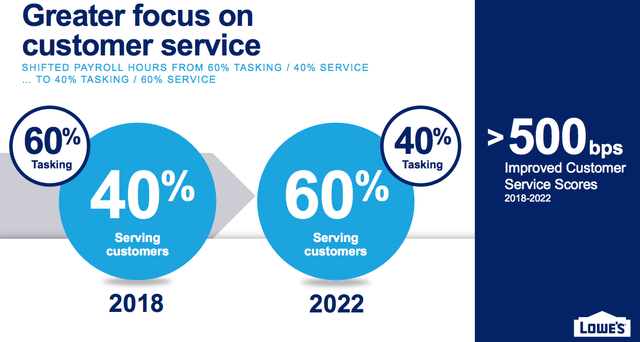
By the end of 2023, 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Lowe’s archaic systems will be modernized. With improved productivity and better visibility across inventory and labor, frontline associates are now able to spend 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their time serving customers and improving sales, compared to just 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 4 years ago. That is a massive 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase in the time associates have to help customers find the best solutions for their home improvement needs. In a space that to me is very commoditized, where price matters a lot to customers and the differentiation between the supplies at different home improvement retailers is minimal, what brings a customer back, again and again, is the customer service.
Investor Day 2022 Presentation by Joe McFarland
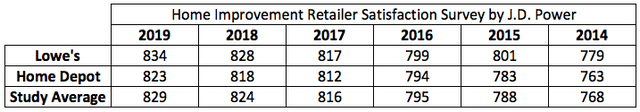
J.D. Power, a global leader in consumer insights, advisory services and data and analytics and a pioneer in the use of big data, artificial intelligence and algorithmic modeling capabilities to understand consumer behavior, has been conducting this “Home Improvement Retailer Satisfaction Survey” for the past 8 years.
J.D. Power. Data for 2020-2022 is not presented as those require payment
The two takeaways from the survey are clear: Lowe’s has consistently received a better consumer satisfaction score than Home Depot, and Lowe’s has consistently received above-industry average scores while Home Depot received scores below the industry’s average.
The transformations at Lowe’s also received acknowledgment at the national and international levels.
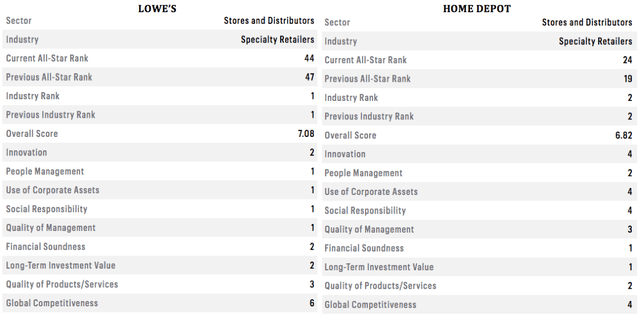
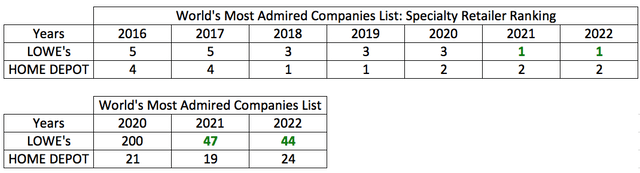
Lowe’s topped Fortune’s list under theWorld’s Most Admired Companies List in the Speciality Retailer category.
Fortune Ranking Comparison of Lowe’s and Home Depot
From the period when CEO Marvin took over in 2018, the multi-year improvements and innovations he and his team have been introducing are bearing fruit, and Lowe’s has been moving up this list.
It is no wonder CEO Marvin just received the National Retail Federation Visionary Award for 2023.
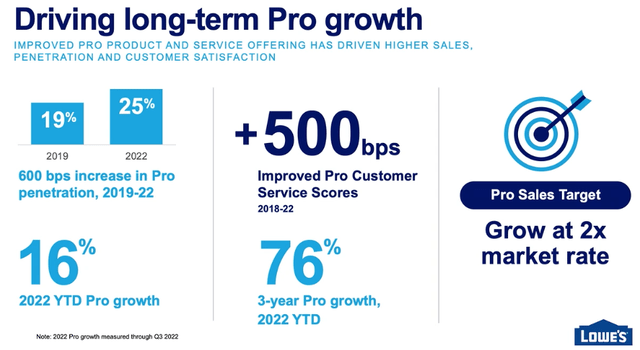
And he is far from done. He has been positioning Lowe’s to enter into Home Depot’s traditional domain in a strong way – the Pro Customer space. While it remains focused on the DIY business, Lowe’s recognizes the opportunities in the Pros section and is expanding its market share there, aiming to have 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the revenue from this segment.
He shared the following at the recent investor day,
It wouldn’t be difficult to overstate how broken the pro service model was when we arrived at the company, but we are up to the challenge and we have completely overhauled the Pro Offering. I know some of our pro customers, suppliers and many shareholders and people in this room were originally skeptical about whether we had the commitment, and also the tenacity to succeed in this important area of the business. After 10 consecutively quarters of double-digit growth at Pro, we have demonstrated our commitment to this business.
The increasing emphasis on the Pro business is not just a strategy envisioned but it is one that has been put in place. Lowe’s Pro customers in the MVP program spend three times more than pros not in the program and that has resulted in impressive double-digit growth for 10 consecutive quarters. Revenue contribution from the Pros has increased from 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2019 to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022.
CEO Investor Day slides
And with the other initiatives that are coming to fruition in 2023 and 2024, it is not difficult to see Lowe’s reaching the targeted 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Pro sales revenue, and for the sales from the Pro customers to continue to grow at two times the market rate.
Risks in Investing in Both Companies: Based Only On Revenue Projections, Both Are A “Hold”
The CEOs of both companies expressed confidence in the strength of the business and downplayed the effects a slower housing market has on the business. While we should take note of the very reasonable explanations and reassurances by both CEOs, investors should also be mindful that CEOs are the spokesperson (cough… salespersons… cough) for their companies. Phrases such as “strongandrobust sales” have to be qualified; actual projected numbers tell a more complete story.
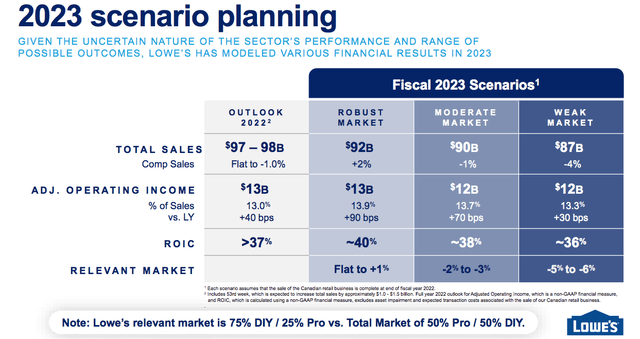
Lowe’s CFO Brandon Sink shared the following on the 7 December 2022 investor day. He projected three outlooks for the company. In the most bullish scenario of a “robust market”, sales are expected to grow 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-on-year. In a moderate market situation, sales are expected to drop to -1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. And if the market is really weak, sales may fall as much as -4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Lowe’s Investor Day slides
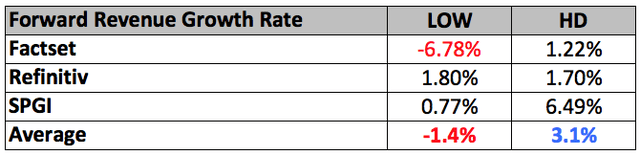
Analysts are likewise lukewarm on both companies as they are not convinced that a weaker housing market does not affect the growth prospects of these two companies. Analysts across the board are forecasting slower revenue growth rates for in next fiscal year for Lowe’s and Home Depot.
Author’s compilation of data taken from Seeking Alpha, Fast Graph and Yahoo Finance
None of these revenue growth figures are particularly encouraging or promising for investors.
Conclusion
Both Home Depot (HD) and Lowe’s (LOW) are great companies. The rivalry between them drives each other forward to be their better selves. Just as Lowe’s is improving by leaps and bounds, Home Depot is not resting on its laurels either. Home Depot recently announced the Path to Pro platform, connecting skilled tradespeople with hiring trades professionals for free for its Pro extra members. This unique and proprietary platform contains thousands of candidates and Pros have begun posting their open jobs. This serves to deepen the Pro value proposition and make the platform more “sticky” for its pro customers.
Both have generated outstanding returns over the long term, both in terms of capital appreciation as well as dividends.
The difference, however, is Lowe’s has more room for improvements than Home Depot, and hence is poised to show better results at least in 2023. The majority of the changes put in place by Lowe’s management are nearing fruition and many are bearing fruit.
Being number two is not always bad. Lowe’s is often described as playing second fiddle to Home Depot, often characterized as “playing catch-up”. Well, playing catch-up is not as bad as it sounds because it means learning from the mistakes made by the trailblazers. Playing catchup also means Lowe’s gets to install newer and faster equipment, and a newer and better inventory management system than its competitors.
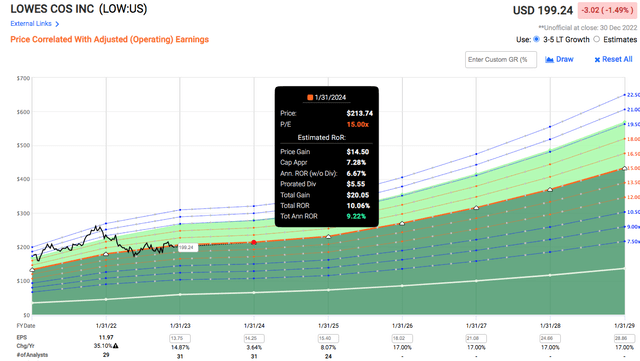
In terms of valuation Lowe’s is much cheaper than Home Depot, and with that margin of safety, it potentially offers a 9.22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} return by the end of the fiscal year 2023.
Fast Graph Lowe’s
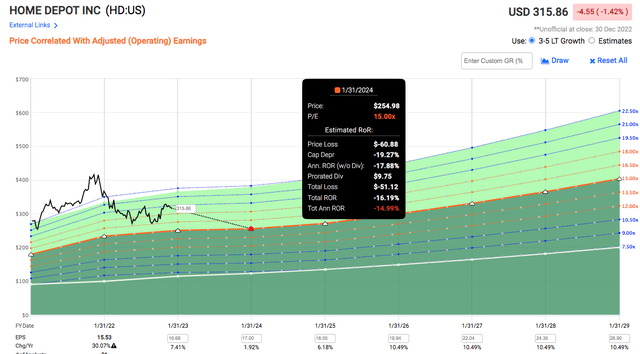
In contrast, despite the market correction in 2022, Home Depot is still priced at a premium. As the expected earnings growth rate for the next two years is only in the low to mid-single digits, it will be unrealistic to expect Home Depot to trade at its past normal P/E of 19-20. If the company were to trade down to just a P/E of 15 to reflect the new normal, there is potential for a loss even with a multi-year holding period.
Fast Graph Home Depot
And with Lowe’s higher dividend growth rate, thrice that of Home Depot’s in 2022 and more than twice of Home Depot’s in 2023, it will not be long before Lowe’s yield catches up to Home Depot’s. Already, that yield difference has narrowed, from Lowe’s current 1.83{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to Home Depot’s 2.37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, to an expected 2.08{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for Lowe’s to Home Depot’s 2.37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fiscal year 2023.
Lastly, having a proven management team with a depth of relevant experience, much of which was gained working at its major competitor, who had seen firsthand what had worked is definitely a plus. Lowe’s combination of cost management, margin improvements (like selling the less profitable Canadian division), productivity initiatives, technological advancements, operational and logistical enhancement to improve customer experience, and strategic realignment to focus more on the pros, is finally bearing fruit.
To reiterate, both are fantastic companies to own. However, at their current valuation and looking at their potential in the next 1-2 years, as well as taking other factors into consideration, on a risk-reward basis it is my opinion that Lowe’s is a reasonable buy while Home Depot is a hold.
A household enhancement contractor operates on a residence in Cambridge, Massachusetts.
Suzanne Kreiter | The Boston World | Getty Illustrations or photos
As the U.S. housing marketplace falls challenging from its pandemic-pushed highs, house enhancement vendors like Dwelling Depot and Lowe’s really don’t appear to be to be sensation the very same agony. In fact, they’re faring improved than expected.
When homebuilding and home reworking are integrally linked, the industry forces guiding each and every can be diverse, and that is what is happening now.
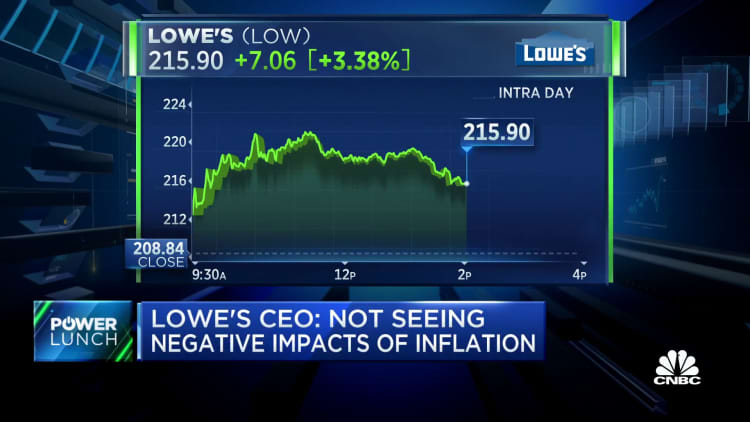
House Depot and Lowe’s documented sturdy quarterly earnings Tuesday and Wednesday, respectively. Lowe’s stock rose 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Wednesday. Executives at both corporations spoke bullishly about the prospects for their organization in 2023. This comes as residence sales, charges and building are all weakening appreciably thanks to a massive soar in home finance loan prices.
Residence Depot financial main Richard McPhail pointed to an “boost in place” mentality among recent owners, who may have required to offer but adjusted their minds due to the fact they could no longer command top dollar.
“All we can do at this place is repeat what our shoppers are telling us,” McPhail stated. “There is a dynamic we do not see a lot in the marketplace. With climbing house loan costs, homeowners are keeping in place.”
With increasing mortgage fees, homeowners are being in place.
Richard McPhail
Residence Depot CFO
Home costs are nevertheless 11.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} better in Oct than they were being in Oct 2021, in accordance to CoreLogic, but that yearly comparison has been shrinking for quite a few months. Costs are falling thirty day period-to-month at a considerably speedier pace than standard seasonal tendencies.
However, the unparalleled operate-up in home costs throughout the 1st years of the pandemic, fueled by file reduced property finance loan fees and a drive for lots of People in america to shift to more substantial houses in suburban locations, gave householders sizeable amounts of equity. Charges jumped extra than 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in just two several years.
By the close of the initially quarter of this 12 months, prior to the steep runup in home loan premiums prompted the housing sector to falter, house owners experienced a collective $11 trillion dollars in so-identified as tappable equity, according to Black Knight. That is the quantity a borrower can get out of their home while nevertheless leaving 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity in it. That fairness grew by an unparalleled $1.2 trillion in the to start with quarter of this yr by itself. For every property owner, it quantities to about $207,000 in tappable equity.
That equity is aspect of a three-pronged driver of property advancement, in accordance to the CEO of Lowe’s, Marvin Ellison. He pointed to dwelling price tag appreciation, the age of the U.S. housing stock — which is roughly 40 several years outdated, the oldest considering the fact that Globe War II — as perfectly as significant levels of personalized disposable earnings.
“So when you seem at all people elements, individuals matters bode properly for house improvement, and we come to feel genuinely fantastic about our present-day tendencies,” explained Ellison in an interview Wednesday on CNBC’s “Squawk Box.”
The NAHB, nonetheless, is forecasting that the remodeling sector will fare the best between the household construction submarkets during this existing housing contraction.
“The development level for advancement investing will gradual because of to declines for existing property income,” said Robert Dietz, NAHB’s chief economist. “However, an aging housing inventory, function from household developments and a decline for domestic mobility all favor transforming investing.”
Dietz also factors to the “curiosity fee lock-in results,” meaning folks will not want to offer a dwelling where they may possibly be spending a 2.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} property finance loan fascination price and trade up to another home wherever the price would probably be all-around 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} currently.
Harvard’s Joint Center for Housing predicts that the annual gains in home advancement and maintenance shelling out will drop “sharply” by the center of future year, but only to a 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} development amount from an unusually superior 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate.
“Housing and reworking markets are without doubt slowing from the exceptionally high and unsustainable growth costs that adopted in the wake of the pandemic-induced economic downturn,” states Carlos Martín, venture director of the Reworking Futures Plan at the Middle. “Paying for dwelling advancements will carry on to face headwinds from declining dwelling income, mounting interest fees and the increasing charges of contractor labor and building components.”
Regardless of inflation in just about every thing in the financial system, consumers do feel to want to commit far more on their homes. Both equally Lowe’s and Household Depot showed a drop in the number of sales but a soar in the dollar amount of money of all those gross sales. That led to their increases in profits.
“There is inflation in the market and elasticity, but not to the degree that we predicted, and the shopper reveals us they are resilient,” reported Home Depot’s McPhail.
A new study of nearly 4,000 home owners by Houzz, a house improvement and structure web-site, discovered that only 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners documented acquiring canceled a house improvement job in 2022. In the meantime, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} accomplished a undertaking in 2022 and just about a single-quarter mentioned they were being setting up to start off a home enhancement challenge in the next 12 months.
“Moreover, much more than fifty percent of the owners we surveyed have no intention of marketing or relocating out of their existing residences in the following 20 a long time or ever,” said Maritime Sargsyan, Houzz personnel economist.
The nation’s next-greatest chain of hardware shops stated Wednesday (Nov. 16) that its business or “Pro” small business grew 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} previous quarter, as individuals carry on to make investments in property remodeling assignments somewhat than face the turbulence and large mortgage loan fees that are at the moment crimping housing income.
In asserting its 3rd-quarter earnings results, the CEO of the North Carolina-based mostly operator of virtually 2,000 shops said that contrary to popular misperception about the property advancement enterprise, Lowe’s latest and extensive-expression potential customers keep on being sturdy.
“Even in the U.S. market in which home selling prices have declined following a especially steep run-up during the pandemic, we are not seeing any impact to profits,” Lowe’s CEO Marvin Ellison instructed analysts, noting ongoing strength in the 3 largest factors that impression the category’s demand, specifically elevated household prices, age of housing inventory and disposable own earnings.
When financial gloom and fears about inflation crimping home shelling out and sentiment have roiled vendors and markets all calendar year, Ellison explained it was critical to “not confuse” the difference in demand from customers motorists for home improvement compared to home developing.
“This one of a kind mixture of aspects is causing owners to trade-up in area, preferring to devote in repairs and renovations to make their present-day properties fulfill their family’s evolving requires, relatively than acquiring a new residence,” explained Ellison, who’s led Lowe’s for 5 many years and whose 35-yr retail business resume also includes stints at JCPenney, Home Depot and Focus on.
“This is why we’re so assured about the outlook for the residence improvement business even in a time period of significant inflation and climbing fascination premiums for the reason that the important drivers of our enterprise continue being supportive,” he additional.
A Pocket of Power
Ellison’s insights appear in the wake of related remarks designed by greater rival Household Depot, which claimed its individual established of defiant final results Tuesday pushed by the toughness of its Pro income.
In detailing the company’s bullishness that underpins its projected uptrend in dwelling enhancement, Ellison mentioned that despite a broad foundation decline in home price ranges this 12 months, the average property owner continue to has a document $300,000 in household fairness to support investments, as perfectly as the simple fact that the typical dwelling is now in excess of 40 decades outdated and that tens of millions of other residences crafted in the mid-2000s are now moving into peak transforming a long time.
“Two-thirds of Household Enhancement invest is non-discretionary on repair or upkeep tasks that can not be delayed,” he observed.
In addition, he claimed, extra than 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homeowners both individual their dwelling outright or are locked into a minimal, fastened house loan that insulates them from soaring charges.
Insert in what Ellison claimed was “a persistent 1.5 to 2 million below supply of homes,” as well as an believed 250,000 initially-time millennial homebuyers coming into the housing industry yearly, and the situation for resilience and optimism gets to be apparent.
Calling All Pros
Presented this backdrop and the 6x outperformance of Lowe’s Professional business past quarter, it is understandable what it and Residence Depot are equally aggressively pursuing and positioning themselves to capture this forthcoming wave of big-ticket purchases.
In the case of Lowe’s, the retailer is continuing its initiatives to hire extra installation services companies although also expanding the positive aspects and benefits it presents to experienced shoppers by means of its MVP application.
“Over 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} [of Pros] mentioned that they hope even more function in 2023 than they experienced in 2022. This is just one more evidence stage of the resilience of Residence Enhancement need, even in this uncertain macro environment,” Ellison reported on the earnings contact.
For all PYMNTS retail protection, subscribe to the daily Retail E-newsletter.
We’re generally on the lookout for possibilities to companion with innovators and disruptors.
A buyer enters a House Depot shop on August 16, 2022 in San Rafael, California.
Justin Sullivan | Getty Photographs
Paying out on residence improvement isn’t going to appear to have taken a significant hit with the slowdown in the U.S. housing marketplace, but analysts say the power may not past.
House Depot and Lowe’s this 7 days cited solid next-quarter gross sales from professionals this sort of as contractors, plumbers and electricians. The stores explained all those consumers have a wholesome backlog of assignments and loads of pent-up demand for house improvement.
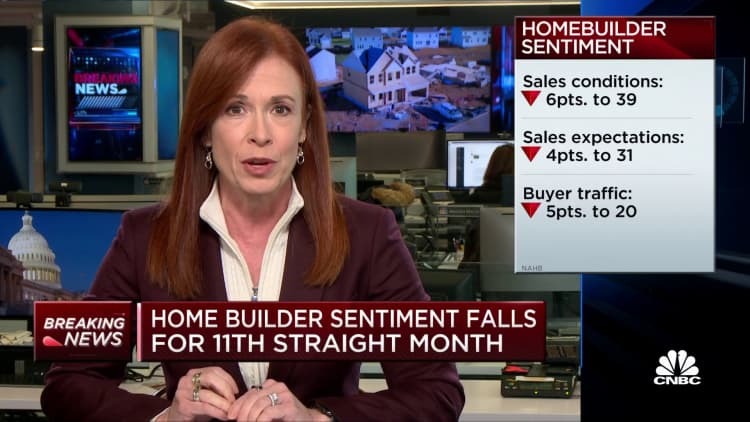
The businesses are chalking up the ongoing strength coming out of the top of the pandemic to housing sector situations for the reason that, they say, individuals remaining set in their homes more time could spur renovations. Considering the fact that the commence of this year, the ordinary price on the 30-year fastened home loan has practically doubled and housing commences have declined significantly. This thirty day period, the Countrywide Affiliation of Homebuilders/Wells Fargo Housing Marketplace Index dropped into the negative territory for the initially time since early in the pandemic.
“Quite often, what is negative for the house builder is not necessarily bad for the home advancement,” Lowe’s CEO Marvin Ellison advised CNBC.
Ellison stated reduced housing starts and large property finance loan prices could incentivize homeowners to continue to be exactly where they are and select to renovate their present-day properties. He observed much more than half of U.S. homes are above 40 yrs previous.
Dwelling Depot’s main financial officer, Richard McPhail, also noted that the rise in household prices is “almost certainly the strongest underpinning” of property advancement demand from customers.
“We have viewed dwelling charges respect by practically 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more than the very last two years, which has truly transformed the equilibrium sheet of the North American home owner,” McPhail explained to CNBC. “When you see your residence raise in price, you are much more probable to commit far more in it.”
Appreciating dwelling price ranges can also let for much larger household fairness financial loans, which owners use to fund renovations. KeyBanc analyst Bradley B. Thomas noted that Home Depot cites property prices as “one of the most significant top indicators of residence advancement demand.” The median rate for a household sold in July was $403,800, which is approximately 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} greater than through the similar thirty day period a calendar year earlier.
But with curiosity fees now bigger, residence equity financial loans are falling just after hitting their highest degree due to the fact 2007 in the very first quarter of the year, explained Piper Sandler analyst Peter Keith.
“There’s a bit of a lag effect,” Keith advised CNBC. “We do imagine this drop off in house fairness extraction will sooner or later show up in the pro investing.”
Keith explained the fall off could strike contractors and other residence improvement pros by the conclude of this calendar year or the beginning of up coming.
Bobby Griffin, an analyst from Raymond James, sees the danger to residence equity extraction, but similarly has most of his target on household price ranges.
“Premiums go up, it is really not as appealing to acquire income out of your household any longer,” Griffin advised CNBC. “But you however have that fairness, so it is nonetheless eye-catching to invest.”
Chicago, IL – July 14, 2022 – Today, Zacks Equity Research discusses The Home Depot Inc. HD, Lowe’s Companies Inc. LOW, Builders FirstSource, Inc. BLDR, Beacon Roofing Supply BECN and GMS Inc. GMS.
The Zacks Building Products – Retail industry is poised to gain from the continued strong consumer demand trends for home renovation and maintenance activities amid rising interest rates and home prices. Rapid urbanization and favorable trends in the housing market are added advantages. The industry players are expected to gain from investments in digital and omni-channel capabilities for meeting demand, executing strategies, and acquisitions.
Continued innovation and e-commerce expansion, and strong demand are likely to benefit industry participants like The Home Depot Inc., Lowe’s Companies Inc., Builders FirstSource, Inc., Beacon Roofing Supply and GMS Inc..
About the Industry
The Zacks Building Products – Retail industry mainly comprises U.S. home improvement retailers, manufacturers of industrial and construction materials, and distributors of wallboard and ceilings systems. Some industry participants offer products and services for home decoration, repair and remodeling, and in-home delivery and installation services.
A few industry players provide construction products, ranging from cement or concrete foundation materials to roofing boards and shingles. The companies also sell lumber, insulation materials, drywall, plumbing fixtures, hard-surface flooring, and lawn and garden decor products. Some players also deal in threaded fastener products, and manufactured and natural stone tiles. In addition to general consumers, the industry players cater to professional builders, sub-contractors, remodelers and retailers.
3 Trends Shaping the Future of Building Products – Retail Industry
Adherence to Home Refurbishing Activities: With rising inflation, interest rates, and increased construction costs and home prices, consumers are inclined toward renovating their homes instead of buying one. Consumers continue to invest in making homes enjoyable and comfortable. Industry experts opine that consumers’ discretionary spending on homes will continue, as interests in keeping houses well-maintained are here to stay.
Revamping interiors to facilitate work-from-home and entertainment needs continues to remain a major trend. Do-it-yourself (DIY) projects for decorating and maintaining furniture and fixtures are being widely undertaken. There is a higher demand for gardening tools, as well as products related to at-home activities such as paint and tool kits. This, along with rapid urbanization, should keep aiding the top-line performances of the industry participants.
Additionally, consumers are open to hiring Professional (Pro) help to complete their home renovations, resulting in rising demand for Pro projects. This is likely to aid companies in the home improvement space, with a focus on building Pro offerings.
Digitization in Focus: Retail Building Products industry participants have been witnessing a surge in online business transactions, owing to consumers’ growing digital dependency. Companies have, therefore, been bolstering their digital presence by expanding the availability of online assortments and bolstering omni-channel capabilities.
Such prudent measures have been aiding the companies to meet the accelerated demand. Companies are also ramping up their delivery operations in order to provide safe and swift services, especially to Pro customers. The digital transaction boom should continue to drive the top line of key industry players.
Rising Costs: Some home improvement retailers have been incurring additional costs to provide enhanced payments and other benefits to employees amid the pandemic. A few players have been witnessing inflationary pressure across product categories, as well as higher transportation costs. Such increased costs are likely to put pressure on margins. Nevertheless, companies are adopting prudent saving measures to cushion the impacts of such costs.
Zacks Industry Rank Indicates Solid Prospects
The Building Products – Retail industry is housed within the broader Zacks Retail-Wholesale sector. The industry currently carries a Zacks Industry Rank #25, which places it in the top 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of more than 250 Zacks industries.
The group’s Zacks Industry Rank, which is basically the average of the Zacks Rank of all the member stocks, indicates bright near-term prospects. Our research shows that the top 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the Zacks-ranked industries outperforms the bottom 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} by a factor of more than 2 to 1.
The industry’s position in the top 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the Zacks-ranked industries is a result of a positive earnings outlook for the constituent companies in aggregate. Looking at the aggregate earnings estimate revisions, it appears that analysts are gradually gaining confidence in this group’s earnings growth potential. In the past year, the industry’s earnings estimates for the current fiscal year have increased 20.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Given the industry’s encouraging prospects, we present a few stocks that you may want to consider buying for your portfolio. But before that, it is worth taking a look at the industry’s stock-market performance and current valuation.
Industry vs. Broader Market
The Zacks Building Products – Retail industry has outperformed the broader Zacks Retail-Wholesale sector and the Zacks S&P 500 over the past year.
The industry declined 8.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past year, whereas the broader sector declined 31.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Meanwhile, the S&P 500 has registered a fall of 12.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past year.
Industry’s Current Valuation
On the basis of forward 12-month price-to-earnings (P/E) ratio, which is the commonly used multiple for valuing Retail-Wholesale stocks, the industry is currently trading at 14.71X compared with the S&P 500’s 16.53X. Further, the sector’s forward-12-month P/E stands at 20.69X.
Over the last five years, the industry traded as high as 23.43X and as low as 14.19X, with the median at 19.54X.
5 Building Products Stocks to Buy
Builders FirstSource: The Dallas, TX-based company manufactures and supplies building materials. The company has been benefiting from its focus on cost synergies, strategic acquisition, and robust demand from solid housing and repair and remodeling activities.
Robust demand for single-family housing, R&R and other activities have been tailwinds for the company’s products and services. Builders FirstSource continues to focus on investing in innovations and enhancing digital solutions for its customers.
Acquisitions are important for Builders FirstSource’s growth strategy to supplement its organic growth and expand extensively across vast geographic boundaries. The Zacks Rank #1 (Strong Buy) company has been active on the acquisition front, which is supporting the top line. It is also focusing on cost-management practices. The stock has surged 49{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year.
The Zacks Consensus Estimate for BLDR’s current fiscal-year sales and earnings indicates growth of 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 18.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively, from the prior-year period’s reported figures. The consensus estimate for the current fiscal-year earnings has moved up 0.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Beacon Roofing: The company is the largest publicly-traded distributor of residential and non-residential roofing materials, along with complementary building products in the United States and Canada. The company has been benefiting from strategic initiatives and the successful execution of its technology initiative in the growing e-commerce platform.
The company is also on track with its Ambition 2025 targets, which emphasize operational excellence, above-market growth trajectory and accelerated stockholder value creation. Beacon has been focusing on business expansion through bolt-on acquisitions, thereby expanding its reach.
Beacon is expanding its digital platform in value-added ways. It remains on track with the long-term target of generating $1 billion in annual digital sales. Disciplined pricing in a volatile, supply-constrained marketplace, and effective and timely sourcing have been aiding margins.
Cost-saving efforts and productivity initiatives are expected to go a long way in bringing down the Zacks Rank #1 company’s operating expenses, thereby driving margins. The stock has risen 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for BECN’s current fiscal-year sales and earnings indicates growth of 23.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 36.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has been unchanged in the past 30 days.
Home Depot: The Atlanta, GA-based company is the world’s largest home improvement specialty retailer, based on net sales. Home Depot has been benefiting from strong demand for home-improvement projects, robust housing market trends and ongoing investments.
Continued strength in both Pro and DIY categories, and digital momentum have been key drivers. Its interconnected retail strategy and underlying technology infrastructure have helped consistently boost web traffic for the past few quarters, aiding digital sales.
Home Depot is witnessing significant benefits from the execution of its One Home Depot plan, which focuses on expanding the supply chain, technology investments and digital enhancements. The Zacks Rank #2 (Buy) company has created the fastest, most efficient delivery network in home improvement through options like buy online pick up in store with convenient pickup lockers, buy online delivery from store with express car and van delivery, and curbside pickup.
The HD stock has declined 10.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for its current fiscal-year sales and earnings indicate growth of 3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has been unchanged in the past 30 days.
Lowe’s Companies: The Mooresville, NC-based leading home improvements retailer has been gaining from strong growth in its Pro business. The company has been enhancing the experience of its pro customers by upgrading pro-focused brands and revamping the pro-service business website.
The company also remains well-positioned to capitalize on the demand for the home improvement market, backed by investments in the technology and merchandise category. Gains from the Total Home strategy and the execution of the Perpetual Productivity Improvement initiative are likely to drive the company’s results in the near and long terms. The Total Home strategy has been resonating well with Pro and DIY customers for a while.
Lowe’s has been progressing well with advancements in the digital channel. The company is investing in enhancing omni-channel retailing capabilities. Management is also committed to enhancing the Pro offerings, expanding the company’s market share and driving the operating margin.
Shares of the Zacks Rank #2 company have declined 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for its current fiscal year’s sales and earnings indicates growth of 1.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 12.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has improved 0.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.
GMS: The Tucker, GA-based leading North American specialty building product distributor has been gaining from the robust customer service in a solid residential market, coupled with an inflationary pricing environment and successful platform expansion activities. Inflationary pricing, healthy residential end markets, strong performance from complementary products and the recent acquisitions have been sales drivers for GMS.
The Zacks Rank #2 company has risen 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for GMS’ current fiscal year’s sales and earnings indicates growth of 8.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 2.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has moved up 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.
Why Haven’t You Looked at Zacks’ Top Stocks?
Our 5 best-performing strategies have blown away the S&P’s impressive +28.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} gain in 2021. Amazingly, they soared +40.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, +48.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, +67.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, +94.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and +95.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Today you can access their live picks without cost or obligation.
See Stocks Free >>
Join us on Facebook: https://www.facebook.com/ZacksInvestmentResearch/
Zacks Investment Research is under common control with affiliated entities (including a broker-dealer and an investment adviser), which may engage in transactions involving the foregoing securities for the clients of such affiliates.
Media Contact
Zacks Investment Research
800-767-3771 ext. 9339
support@zacks.com
https://www.zacks.com
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss. This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. No recommendation or advice is being given as to whether any investment is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole. Zacks Investment Research does not engage in investment banking, market making or asset management activities of any securities. These returns are from hypothetical portfolios consisting of stocks with Zacks Rank = 1 that were rebalanced monthly with zero transaction costs. These are not the returns of actual portfolios of stocks. The S&P 500 is an unmanaged index. Visit https://www.zacks.com/performance for information about the performance numbers displayed in this press release.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report