Zoned Properties, Inc.ZDPY has acquired an financial investment house in Nice Ridge, Michigan and entered into a very long-term, complete-net lease agreement with NOXX Cannabis to operate a retail dispensary.
“We are thrilled to announce this sizeable transaction, which marks our entry into Michigan as an investor in serious estate. This deal has offered us the possibility to add a sturdy, established operator in a appealing sector, when diversifying our portfolio. This is an illustration of Zoned Properties including a excellent asset and tenant lover to our residence financial commitment portfolio by using our value-insert financial investment solution and injecting immediate-to-buyer genuine estate targets into our pipeline,” stated Bryan McLaren, CEO of Zoned Attributes. “We are enthusiastic to reinforce our partnership with NOXX Cannabis and their govt crew.”
Transaction Highlights


Zoned Properties has acquired the investment assets in Pleasurable Ridge, Michigan that has been entitled and permitted as a hashish retail dispensary.


The investment residence was obtained for $4.3 million, such as $1.85 million in seller financing, which allowed Zoned Homes to additional leverage its funds stack at beautiful costs.


The financial commitment residence is leased to NOXX Hashish less than a lengthy-term, absolute-net lease arrangement, which will generate an approximate 13.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} cap rate when straight-lined above the term of the lease arrangement. The lease contains 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} once-a-year increases in foundation rent above the existence of the lease phrase, yielding approximately $580,000 in yearly base rental income when straight-lined more than the lifetime of the lease phrase.


Benzinga’s Hashish Funds Conference Is Back again
The most effective cannabis small business party in the entire world, the Benzinga Cannabis Funds Meeting, returns to Miami for its 16th edition. This is the put exactly where Bargains GET Completed, in which cash is elevated, M&A begins, and companies meet buyers and essential associates. Join us at the Fontainebleau Miami Beach Hotel in Florida on April 11-12. Do not miss out on out. Safe your tickets now. Prices will surge incredibly soon.
Picture: Benzinga edit with images by geralt and lindsayfox on Pixabay
Meet the most important cannabis industry gamers and make deals that will thrust the sector ahead.
Showcasing reside corporation presentations, insider panels, and unmatched entry to networking, the Benzinga Cannabis Funds Meeting is the place cannabis executives and entrepreneurs fulfill.
Join us April 11-12, 2023 at Fontainebleau Miami Seashore in sunny Florida.
Desire rates across the board have absent up and the financial gain buyers make from a multifamily outweighs a more compact 1-4 device setting up. With costs raising, an trader is better off securing additional units at a increased level, instead than just a solitary-family members expense at an fascination charge at this time previously mentioned 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Just just one multifamily investment home can turnaround a struggling, underperforming portfolio. Investors that have skipped out on various qualities throughout past yr can also make up for that decline of opportunity with only a person multifamily property. Desire prices are also tipping the scales toward multifamily investing for the reason that in a market place in which rates are scaring absent anyone, an investor with a multifamily financial investment assets with several models for lease just located by themselves in a high leverage predicament. In an article discovered on wealthmanagement.com, this sentiment is echoed, “As households become more high priced to acquire, and new merchandise a lot more costly to create, the present inventory of rental housing results in being extra important and in-need.”
Multifamily financial investment qualities are essential for a selection of explanations but mostly for investors the most beautiful factor is the scalability chance it results in for them. The funds generated from a rental house, occasionally referred to as passive income, is amplified tremendously by possessing a multifamily property. With this money coming in due to quantity of units, it is less difficult for traders to extend and make down payments on investments. Any investor will acquire you as a result of their journey that typically commences with modest resolve and flip initiatives, shifts to owing solitary family rentals and jumps to owning multifamily properties. Buyers are normally wanting for the following problem and a probability to receive the greatest ROI. With multifamily financial commitment properties, the route to financial liberty has under no circumstances been a lot easier. With a companion or two and a several trusted property professionals, traders can cross the 50–100-unit threshold with ease.
Liquidity equals flexibility
Liquidity is a further beautiful reason why buyers want multifamily expense qualities in their portfolio. As opposed to stocks and bonds, a multifamily expense residence holds its worth at a significantly extra reputable price than an expenditure in the stock sector. That value will make these investment decision homes significantly far more captivating and offers flexibility to an financial investment portfolio. If a new house arrives on the sector and an investor needs to liquidate before long to totally free up some cash to make a down payment, a multifamily investment is just the asset they would need to have. Whether it is marketing off a selected selection of units to make it worthwhile or unloading the multifamily house fully, an trader can come up with that down payment money. Inventory sector situations could lead to an investor to miss out on an possibility if the market place is down, so having that multifamily home can demonstrate to be considerably a lot more reputable.
Part 1 focused on “Home Stocks,” meaning those that I would be happy to buy now and hold indefinitely, like a home. They were Brookfield Corporation (BN), Brookfield Asset Management (BAM), Dream Unlimited Corp. (DRM)(OTCPK:DRUNF), Topicus (OTCPK:TOITF), and SSC Security Services Corp. (SECU)(OTCQX:SECUF). These are stocks commonly referred to as “compounders,” meaning they grow reliably, profitably, and over long periods of time. If the stock market were to close for ten years, Home Stocks I would not worry about.
Like those stocks, “Investment Property Stocks” are growing profitably, but have some sort of drawback and that make them less attractive over the long term. This drawback is made up for by a large, temporary dislocation between price and value, providing an attractive risk/reward that could result in a large return over a relatively short period, anywhere from one to five years. When the stock’s price gets close to its value, I’ll consider selling for a nice gain. Thus, they are Investment Property Stocks, not Home Stocks.
Currently, I find Nuvei Corp. (NVEI), a Canadian mid-sized e-commerce payments company, Alibaba (BABA), China’s pre-eminent internet stock, and Reitmans (RET)(RET.A)(OTCPK:RTMAF), a Canadian women’s fashion retailer, to be attractive Investment Property Stocks. All have something going against them which dissuades me from holding over the long term, but enough going for them and a large enough margin of safety that I believe they can make very nice gains in the next one to five years.
Investment Property Stocks
Nuvei Corp.
Nuvei Corp. is a mid-size Canadian fintech (~$4-5B market-cap) specializing in merchant services; it essentially has a top-of-the-line modular “everything platform” for merchants. I go into greater detail here but a shorter version follows.
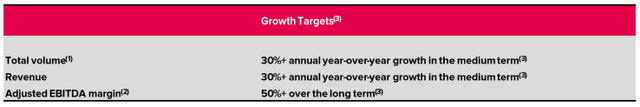
Nuvei specializes in payment solutions for online regulated gaming (gambling and sports betting), a fast-growing segment as Canadian provinces and US states legalize the industry, and e-commerce generally, which represents almost 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their revenue. Nuvei is quickly diversifying however, most recently they acquired Paya Payments, a B2B payments provider, the details of which I cover here. In addition, the CEO owns 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of shares, and upon its IPO employees each received a stake in the company worth $100,000, creating significant insider-ownership. Management projects sales to grow at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually over the next few years with adjusted EBITDA margins increasing up to 40-50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, a call that was recently reiterated in a press release. Nuvei has competitive technology, huge growth in sales and margins, and owner-operators; it meets my normal qualifications of a quality stock.
Nuvei’s growth outlook (Nuvei’s Q3 Earnings Report)
Despite these positives, Nuvei trades at 11x trailing free cash flow. The reasons for this are not perfectly clear, but here are a few possibilities.
Payments companies generally are down huge due to recession fears caused by interest rate hikes and inflation. Companies operating in cyclical sectors like e-commerce and online gaming are even more affected. Nuvei was also exposed to crypto payments, which crashed hard in 2021, bringing Nuvei’s share price with it. The exposure is not huge, but the mere association was enough to hurt the stock.
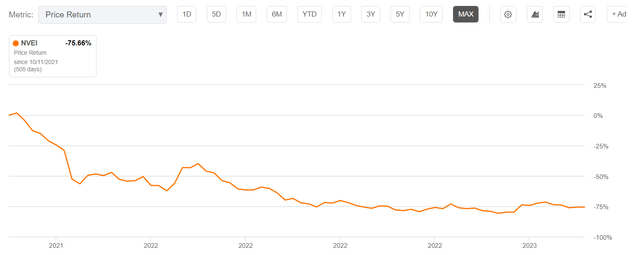
Additionally, Nuvei was one of the prime beneficiaries on the pandemic bubble, a lot of its growth was brought forward, and its share price skyrocketed beyond what anybody could consider reasonable, and thus became the target of a short seller’s report. Many of the allegations were rebutted, but the share price didn’t recover. More concerning is the CEO’s relative youth, reflected in how much he pays himself (a lot), and that Nuvei pays presumably large amounts to sponsor an F1 team. I fail to see how such a sponsorship benefits shareholders, but doesn’t break my thesis on the company, though it is inconvenient.
Nuvei’s return since its IPS – Not pretty! (Seeking Alpha)
Lastly, bringing forward growth also had the effect of creating impossible comps year over year, indeed Nuvei’s sales this year are up only single digits over last year. Considering they doubled sales in 2021, simple staying flat is quite the feat, and puts management’s forecasted 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} medium-term sales growth seem far less ambitious than it appears. It also probably didn’t help that they converted their net cash position to a net debt position to acquire a company; it isn’t the market for that. Overall, I view most of these factors as temporary impairments to the stock, and therefore signify a potential opportunity.
Most importantly for me, and why this stock is not a long-term hold, is competition. In the payment services world, a company is only as good as its technology developers and sales team; there is no moat, or even picket fence, keeping others out of the business castle. Nuvei’s peers are Stripe (STRIP), Block (SQ), Europe-based Adyen (OTCPK:ADYEY) and to a lesser extent online payments companies like PayPal (PYPL). All are worth 10s of billions and with significant resources; competition is clearly formidable.
That said, Nuvei is currently much smaller than they are so need to take less market share to see gains, has competitive technology, is building a direct sales team with a former Mastercard exec at its head, has a niche and early movers advantage in online gaming payments, and is priced for the apocalypse, while its competitors are priced for a recession. The lack of durable competitive advantage is made up for by these redeeming factors, but especially by valuation.
A cursory glance at the stock suggests it is expensive because it has a high PE ratio, but if we skip to the cash flow statement, we see that Nuvei gushes free cash flow. Gross margin is above 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, operating cash flow margin is regularly above 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and free cash flow around 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Due to operating leverage, where little capital is required to provide more services, margins even have room for expansion. These are levels are profitability beyond even Microsoft.
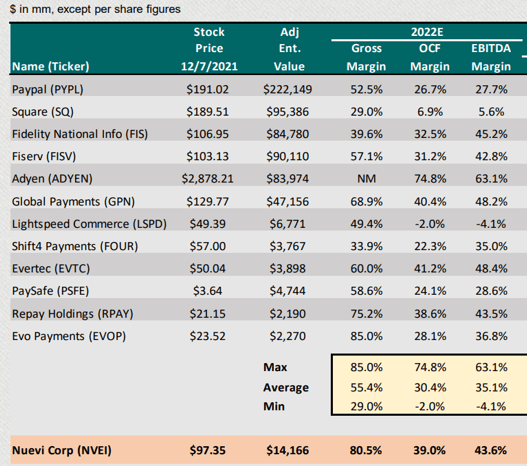
To be honest, my “too-good-to-be-true” sense is tingling, and I’m not the only one. In the short seller’s report, they made a list of comparable fintechs and their profitability. Most of the report was, from my perspective, ad hominem hearsay, but the following breakdown was useful:
Note to Canadian investors, Lightspeed gets more press than Nuvei, but isn’t even profitable. (Short Seller’s Report)
A close look will reveal that Nuvei is about as profitable as a fintech can be and far above average. This could be concerning, but comfortingly for me, there are other companies that are similarly profitable so Nuvei is not a clear outlier. Adyen for example, its closest peer, has operating cash flow and EBITDA margins much higher. This chart is useful for industry comparisons as well, which I’ll leave to the reader to peruse. In my opinion, the probability that Nuvei is cooking the books is low, though I am wary.
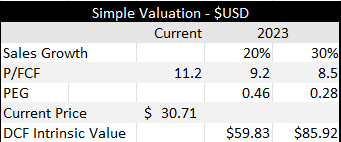
Nuvei is tremendously profitable, and, as the table below shows, the market is strongly discounting this fact, assigning it an 8-9x forward P/FCF multiple, half the average of information technology stocks according to Seeking Alpha. Nuvei should perhaps demand even more than average as it is a quickly growing fintech stock with huge margins and operating leverage.
Two different growth scenarios and their impact on the valuation of Nuvei. Both suggest Nuvei is substantially undervalued (Author’s Calculations)
As we can see, the stock is at least 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} discounted from conservative fair value, assuming management’s medium-term outlook of 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual sales growth is high by 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a year. If it’s not, and Nuvei does manage to grow sales at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually while maintaining or growing current margins, the stock is potentially 66{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} undervalued. Furthermore, a PEG ratio of 1 is generally considered a fair price to pay, and Nuvei trades at half or a quarter of that, lending further support to our DCF values. Should the market get bullish and payment stocks demand higher multiples (the current model assumes 20), upside is even greater.
Nuvei is certainly not a Home Stock, in that it doesn’t have a moat and there are some smaller concerns, but the price and business model are far too discounted; a disaster is being priced in. If business doesn’t flop and/or the Great Depression doesn’t happen, Nuvei is going upwards. The main catalyst is lapping 2021’s financials making for easier comps, and new customer wins.
I’m a buyer at $30-$35 USD and would consider selling at $90-$120, though I wouldn’t make this an out-sized position as the company hasn’t been public long so it’s hard to get a sense of its track record.
Alibaba (BABA)
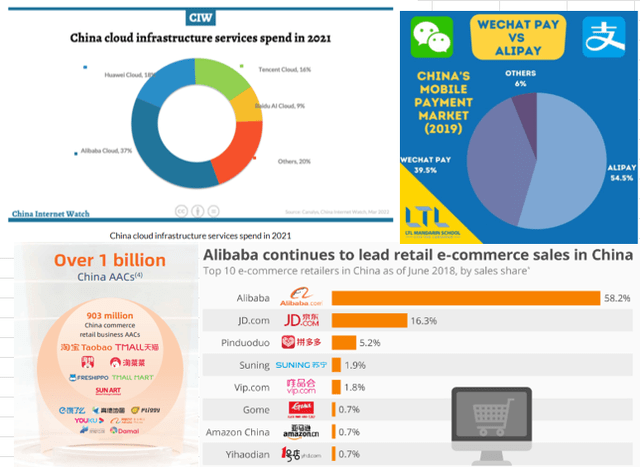
Alibaba is the pre-eminent Chinese internet stock. 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese e-commerce goes through one of its platforms, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the fast growing cloud market is captured by Alibaba, almost every single Chinese person (and 300M outside China) are annual active consumers on its platforms, and, through its one third stake in Ant Financial, BABA owns Alipay, the payment platform through which 56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese payments flow (with more volume than Visa, Mastercard and Amex combined) and Yu’e Bao, the second largest money-market fund in the world with over $170B under management. Alibaba has an ocean for a moat.
In addition, they have fast growing segments, like international e-commerce and domestic groceries, both of which alone could be bringing in more annual sales by 2033 than the entirety of Alibaba generated in the last twelve months. Alibaba is more than just the Microsoft (MSFT) or Apple (AAPL) or Amazon (AMZN) of China, it’s all of them, combined.
Visuals to aid readers in understanding Alibaba’s moat (China Internet Watch, Mandarin School, Alibaba 2022 Annual report)
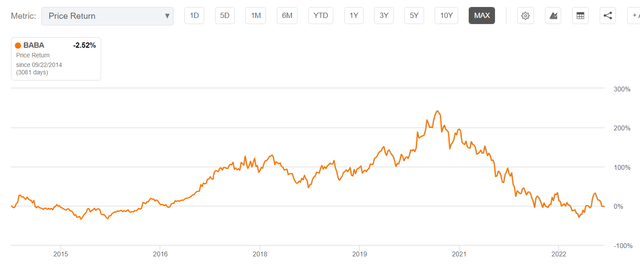
Since it IPO’d in 2014 at $92.70 a share, Alibaba has 15x the revenue, 5x the EBITDA, 4.5x the free cash flow, and 3.5x the operating income. Somehow, we can buy it at IPO prices; Alibaba is tremendously undervalued. Tom Hayes describes it as a submerged balloon, waiting to rocket to the surface.
Alibaba’s return since its IPO (Seeking Alpha)
The dislocation of price to value is caused by the Chinese government locking down the economy in an attempt to prevent Covid from spreading and cracking down on its tech companies, which it deemed were becoming too powerful (perhaps justifiably). Things have changed recently however, the CCP bought shares in BABA, has re-opened the economy, is stimulating the consumer, and generally seems to be working with and through its tech companies as China’s leaders’ personal and national self-preservation instinct has kicked in. Headwinds have shifted to tailwinds.
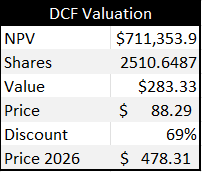
I’m putting up my sails to catch that wind, as Alibaba, were it to return to normalized multiples on normalized earnings, is worth at least $500-$600 a share three years from now. This plan appears to be on track. In their most recent earnings, Alibaba bought back significant amounts of stock well below intrinsic value, somehow grew revenue 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} despite the most recent quarter being under lockdown, and, significantly, increased free cash flow 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year over year despite sales staying flat. This means that Alibaba found a way to become much more profitable in a very short amount of time. Once sales growth starts to kick back in, combined with increased profitability, BABA shareholders could see results well beyond normalized earnings, and therefore have much more upside.
Valuation of Alibaba assuming its free cash flow margins and multiples paid for that FCF returns to historic averages (Author’s Calculation)
Moreover, Chinese savings are twice the historic average, so if they can spend at normal levels, upside could be even higher, considering the market currently expects a conservative 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual growth of sales over the next few years for BABA. Shareholders of Alibaba have a significant margin of safety at current prices, and massive upside should anything go right.
I’m an active buyer and will continue to accumulate under $100 a share for as long as the market lets me. I’ll consider selling when it reaches that $500-$600 mark but will reassess when we get there. If international expansion is going well, BABA might turn into a long-term hold.
I did a longer article on Alibaba here.
Reitmans (OTCPK:RTMAF)(RET.A:CA)(RET:CA)
Reitmans is a century-old Canadian women’s fashion retailer, including the brand’s Reitmans, Pennington’s, and RW & Co. The Reitmans family still owns most voting shares (RET:CA), and senior management positions. Donville-Kent, a Canadian small-cap investing firm whose newsletter, the ROE Reporter, alerted me to the opportunity here. Their treatment is in-depth and can be read here.
Reitmans historically was a reliable dividend payer with sluggish growth in the Canadian retail space, like Canadian Tire in this respect. After years of deterioration however, Reitmans almost didn’t survive the pandemic and was forced to enter bankruptcy to survive. In so doing they laid off thousands of employees, renegotiated better lease terms, paid off creditors at 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the dollar, shut down unprofitable locations and brands, and re-listed from the TSX to the TSXV.
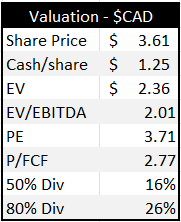
Re-emerging from bankruptcy, the company looks remarkably different, financially. Returns on equity are over 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, debt is paid off and they have $1.25 of cash/share (a quarter of the company’s market cap is cash). In the last nine months alone, Reitmans has generated $67M in free cash flow on $588M of sales, for a margin of 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an excellent number for a retailer. Using just the last nine months numbers, they currently trade at around 2x EV/EBITDA, 4x net income and 3x free cash flow, well below historical averages for their own company specifically and retail generally.
Remarkably undervalued. Priced like it’s going bankrupt again (Author’s Calculations)
If Reitmans were to pay out 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of that free cash flow as a dividend (which they have historically), the stock would yield 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If that isn’t enough, the headquarters and distribution centre owned by Reitmans are worth more than the market cap of the company. The value is clear.
Like BABA, there is a large overhang on the stock causing its price to be severely depressed, but the facts are pointing to this overhang being temporary.
The new Reitmans could continue to be the dog it was in the 2010s, but if its last fiscal year is anything to go by, this doesn’t appear to be the case. Indeed, the current overhang from bankruptcy and Reitmans reputation is providing a margin of safety and likely an opportunity. Shareholders will need catalysts to continue gains though.
Reitmans has several potential catalysts. First, the company could buy back a significant amount of stock with just the cash on the balance sheet. Second, it could reinstate the dividend, which I’m sure the Reitman family are eager to do as it’s been a few years since they got the cheque they’ve been receiving for almost a century. Third, they could list back onto the TSX proper, where fund managers can buy their stock. Fourth, the family could buy the land under their headquarters and fulfilment centre and lease it back to the company, unlocking a pile of cash. Fifth, when earnings are reported in April, we get our first full year of financials for the new Reitmans, and potential announcements regarding any of the first four points made here. Reitmans is already up significantly, but there are more catalysts that could cause it to go even higher.
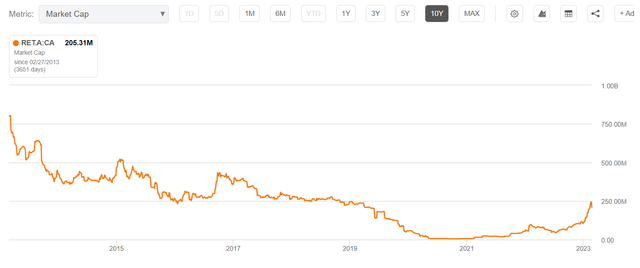
Long-term holder are likely non-existent (Seeking Alpha)
Over the last 10 years, Reitmans was a value trap, with slowing sales and decreasing margins and thus traded at very low multiples, around 7-8x free cash flow (which is still twice as expensive as today). However, sales are not slowing anymore, its brands are proving resilient, and margins have expanded significantly coming out of bankruptcy. 8-10x EV/EBITDA and/or 8-10x FCF are perhaps more appropriate conservative expectations of multiples going forward, compared to the current 2.3x EV/EBITDA and 3x FCF. This suggests that Reitmans is likely a double from ~$3.50-$4.00 on valuation alone, with more potential should the catalysts mentioned earlier happen. Donville-Kent expects the price to reach around $8 if the company doesn’t sell the land to the family, and $12 if they do.
If the outlook remains rosy, the company proves quality and the dividend is reinstated, I might find myself a long-term holder. To put it in perspective, with an 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} payout ratio, I’ll be receiving upwards of 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield on my current cost-basis; a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual cash return is hard to say no to. This should result in price upside as well, as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield from a quality company will not last long; I could see a more justifiable yield of around 6-8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, implying the price could increase another two or three times, like Donville-Kent suggested.
In any case, I see a double minimum with potential for RET.A to triple or quadruple, while I eventually collect a significant dividend yield that I could choose to hold for the longer term. Reitmans is an ideal Investment Property Stock.
Conclusion
Reitmans, Alibaba, and Nuvei are all promising stocks into the medium-term. Though they have long-term drawbacks, namely low growth at Reitmans, ageing demographics and an autocratic home government for Alibaba, and no durable competitive advantage for Nuvei, the market is pricing their stocks at unreasonably low levels. To re-value their stocks, Reitmans could reinstate the dividend and go back up to the TSX, Alibaba could benefit hugely from government stimulus and domestic cloud growth, and Nuvei will be lapping tough 2021 financials, leading to some pleasing year of year numbers. All are quality businesses down for temporary reasons, and have catalysts to revive investor interest.
If worst-case scenarios don’t happen, all these stocks could be doubles in a relatively short period (a couple years or less), and perhaps more into the medium-term (3-5 years). I’m in all of them at allocations I feel are appropriate and am excited to see what the future brings. I would love to become a long-term holder but will reassess later. For now, these make for great Investment Property Stocks.
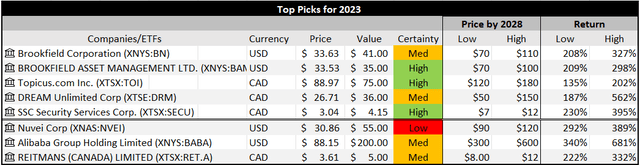
Below is a final summary for all the Top Picks for 2023:
Summary of top picks in the last two articles, including fair values and return potential (Author’s Calculation)
Please feel free to comment, especially dissenting thoughts.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
North Texas Residence Administration is very pleased to announce new articles aiding buyers fully grasp the positive aspects of qualified administration services.
FRISCO, TX, February 26, 2023 /24-7PressRelease/ — North Texas Residence Administration, a ideal-in-class financial investment property management business based in Plano, Texas, and serving Collin County is proud to announce new informational information targeted on the key communities of Richardson, Allen, and Plano, Texas. One family members property home investors could need to have the assistance of a regional qualified to juggle the everyday facts essential for handling rentals.
“Big assets investors can evidently realize the duties of handling financial commitment rentals in Texas. More compact traders, both these new to the rental industry or those people who have inherited a house and want to lease it out, may not realize all the ins and outs of residence administration,” explained Jason Marascio, North Texas Assets Management CEO. “We do and we can assistance them by having more than every day and every month perform necessary to thoroughly handle a property rental. We are only centered on the house management of financial investment properties.”
The new informational submit can be located at https://www.ntxpm.com/2023/01/14/when-you-need-expenditure-assets-management-employ the service of-the-best/. Little traders searching for facts on financial investment house administration in Richardson, Allen, and Plano, Texas, can study solutions in the new submit as effectively as on location-distinct pages these kinds of as https://www.ntxpm.com/richardson/. NTXPM can support entrepreneurs of one-family members dwelling rentals. The local rental administration staff can deal with duties these kinds of as the following: advertising and marketing a household for rent, residence inspections, scheduling tenant interviews, running renter background checks, and even eviction companies (https://www.ntxpm.com/eviction-company/). The firm’s workers can gather lease, agenda household repairs and offer a monthly economic statement to the assets investor.
The Most effective Financial investment Home Management Services Presents Hassle-cost-free Aid
Listed here is the track record on this release. Lots of newbie traders may well be tempted to “go it alone” when it will come to investment decision assets management. This could not, having said that, be the most effective decision. Utilizing a residence administration service for a single family members household rental home can present numerous benefits in excess of taking care of the property oneself. House management corporations can deliver a range of solutions, including marketing the assets to future tenants, screening tenants, gathering lease, handling maintenance and repairs, and implementing lease agreements. These services can help save residence house owners time and exertion and can guarantee that the house is very well-taken care of and in compliance with community polices. Residence management corporations in Plano and close by communities also have experience in the nearby rental market place, letting them to set competitive rental charges and industry the home proficiently. Additionally, residence administration organizations can provide a buffer in between the assets operator and the tenant, dealing with any disputes or conflicts that may arise and cutting down the anxiety and workload for the home operator.
ABOUT NORTH TEXAS Residence Administration
North Texas House Management Business is a top rated-rated home administration firm servicing rental residence owners’ desires in the North Dallas spot of North Texas. The firm’s residence professionals manage residential rental homes in McKinney, Richardson, and Allen, Texas. NTXPM also handles single-loved ones house property administration for Frisco, Plano, Carrollton, Garland, and Princeton, Texas. The team supports each the wants of renters and landlords in the North Dallas suburbs.
Multifamily is the most well-known asset course that buyers go after in industrial true estate.
Some multifamily traders opt for properties that already have a secure money stream, have much less embedded danger, and are favored by much more conservative investors. Other investors opt for benefit-incorporate homes that may have vacancy or maintenance challenges, or may possibly require renovations, but with time ought to yield better returns.
There are several rewards to multifamily investments. Very first, these qualities are a lot more resilient through recessions as folks will always will need a put to dwell. Next, considering that rentals can be adjusted annually, house owners can enhance rents to hold up with sector rents and offset inflation.
Another major gain is the means to reduce tax legal responsibility by means of depreciation and create off house loan desire, assets taxes and running charges.
Ultimately, there is great upside opportunity in purchasing a multifamily with zoning that lets for bigger density and opportunity for redevelopment of additional housing units.
Fernando Echeverri.
When getting a multifamily, you really should analyze the home, its location and its financials.
1st, assure that all operate has been carried out with permits and adopted regional constructing codes. Seek the services of a residence inspector to verify that the constructing is in good ailment. In older properties, validate that the 40-12 months recertification has been accomplished and all significant components – this kind of as roof, electrical, structural, plumbing – are in audio issue.
2nd, evaluate the area, as it is just as crucial as assessing the residence.
Push by the place at distinct occasions of working day to get a truly feel of the community. Also ask your authentic estate agent to look at the area’s demographics to recognize its development, crime fee, college district ranking, and future assignments prepared for the location that may influence the house.
Third, review the financials and request the most recent hire roll, profits and price experiences to discover any disruption of income or boost in any cost.
Multifamily house in Coral Gables, Florida.
Joe L from Pexels
Never ever assume the financials presented on the featuring memorandum. Do your operate and corroborate that the expenses are accurate. Insurance policies do not transfer to new prospective buyers. Ask for a estimate to make certain assets can be insured at a reasonable amount of money. Also estimate the residence taxes primarily based on the invest in price, as the tax invoice will adjust every single yr. Eventually, ensure that the rents are constant with the marketplace and check similar rents in just a a person-mile radius.
Is this the ideal time to get? It relies upon on just about every investor and their time horizon.
The rise in fascination rates have positioned quite a few investors on the facet lines and as a outcome revenue have slowed this may set some pressure on sellers but generate chances for prospective buyers. We are at an inflection place, presented the rapid increase in interest prices have thrown the multifamily financial commitment market into a period of time of rate discovery, where sellers and purchasers need to concur on the worth of multifamily.
Whether it is a purchase-and-keep tactic or rehab, make sure the property’s properties suit with your financial strength, objectives, and encounter. Opt for the suitable experts starting with a real estate agent who has knowledge, understands the dynamic of the market, and can find outlined and off-industry qualities.
Fernando Echeverri, is a broker specializing in professional investments houses, and functions with Great Properties International on Essential Biscayne.
Carry out thorough industry research right before beginning the negotiation system to realize costs and tendencies in the community spot.
Fully grasp your funds and generate a spending plan that variables in more expenditures this kind of as closing fees, legal expenses, and renovations.
Know which loan goods are available and which kinds satisfy your economical demands.
Spouse with a house loan loan provider who can present help in evaluating possible offers.
Have tolerance and be persistent through the negotiation approach.
Investing in true estate can be incredibly worthwhile, but it is not with no dangers. No matter if you are hunting to obtain a rental house or flip a household, there are various ways you can choose to maximize your return on financial investment. Negotiating the fantastic offer starts off with knowing the industry and honing your negotiation competencies. Right here are some of the crucial methods to negotiating the finest price tag and terms on a authentic estate investment decision assets.
Perform Comprehensive Current market Exploration
Prior to you even start out searching for potential properties to spend in, it is critical that you perform extensive market study so that you understand selling prices and traits in the nearby location. This will aid you comprehend what type of deal you should really be wanting for and give you an concept of how a lot place there is for negotiation.
It is also critical that you are acquainted with any community laws or limits that may well have an impact on your ability to rent out or sell the property at its full possible. For occasion, some areas will have zoning guidelines that limit the range of rental units in a supplied area or call for precise types of renovations right before you can hire or provide.
Knowing these limits forward of time will support you avoid any expensive surprises in the course of negotiations. Also, a very good knowledge of the nearby competitiveness will assistance you ascertain what variety of deal is achievable.
Comprehend Your Finances
It is essential that you know specifically how much revenue you have readily available for investing and what funding alternatives are offered to you if needed. Being aware of this information in advance of time will empower you to negotiate confidently and confidently stroll absent from bargains that do not make economical perception for your scenario. Here are some guidelines for knowing your finances:
Have a Apparent Funds and Adhere To It
You really should be very clear about the utmost amount you are prepared to pay out for a residence before negotiations even get started. Make certain to variable in any additional costs, these kinds of as closing expenses, lawful service fees, and prospective renovations, if applicable. It can also be beneficial to map quite a few unique cost factors out in scenario the seller is open to negotiation.
Know What Forms of Loan Products and solutions Are Available
It is vital to be acquainted with the distinct bank loan solutions available to you and what type of terms they appear with. Some financial loans may perhaps provide improved terms than others, so make absolutely sure to exploration these selections comprehensively in advance of creating any decisions.
Associate with Home loan Loan providers
Owning a trusted home finance loan loan company on your side for the duration of the negotiation method can be amazingly helpful. They can suggest you on which promotions make perception and assistance you obtain the best funding possibilities available. Operating intently with a loan company will enable them to comprehend your demands, so they can recommend viable methods that in shape inside of your budget.
Be Ready to Wander Away
From time to time, the finest deal is no offer at all. If negotiations are not heading in your favor and you do not sense relaxed with the conditions that are becoming presented, it is significant to be organized to wander absent from a offer. This will reveal to the vendor or landlord that you are serious about acquiring the best deal, and they might be prepared to renegotiate. This can also protect against you from receiving caught in a bad deal that could charge you income in the extensive run.
Be Persistent and Patient
When negotiating, it is vital to be persistent and affected individual. You should often test to get the very best deal that you can and in no way agree to a price tag you are not comfortable with.
On the other hand, it is also essential that you do not hurry into any conclusions, as this could direct to high-priced errors down the line. For instance, if a seller is pushing for a brief sale, you should really still choose the time to do your due diligence in advance of signing any contracts.
Negotiating can take some time, but if completed correctly, it will be worth the hard work in the stop. Also, do not be concerned to talk to for assistance if wanted. There are specialists who focus in genuine estate investing and can offer priceless tips throughout the negotiation system.
Negotiating the greatest feasible offer on an expenditure residence usually takes preparing and confidence—but it doesn’t have to be overwhelming. With stable industry investigation, an knowledge of your finances, and a willingness to stand up for your self, everyone can efficiently negotiate on their behalf when investing in real estate. Performing so could conveniently conserve thousands of bucks above time, creating it perfectly worth having the further time upfront to be certain achievements.