The property advancement market place is bracing for a bumpy highway.
Two of the major house improvement vendors, Property Depot (Hd) and Lowe’s (Lower), warned of softness in the market in the latest earnings reviews, indicating the year in advance is probable to be a tricky 1 as inflation weighs on shoppers.
“In 2023, residential expenditure will be underneath some strain, provided elevated concentrations of inflation, greater interest charges and a a lot more careful client,” Lowe’s CFO Brandon Sink told analysts on the earnings call on Wednesday. “We are forecasting a slight decline in the house-improvement current market.”
“We do assume moderation in dwelling enhancement demand,” House Depot CEO Ted Decker told analysts on the company’s earnings meeting phone very last week. “Persons are also setting up to change shell out extra in the direction of companies. And as we have said, we see some a lot more value sensitivity,” he additional.
The warning comes as Lowe’s (Lower) posted a blended quarter on Wednesday prior to the industry open up.
The retailer documented adjusted earnings for every share of $2.28, topping over analysts expectations for $2.21. Profits missed estimates, coming in at $22.4 billion against anticipations for $22.7 billion, according to facts compiled by Bloomberg.
“The slower start off to the quarter was owing in section to slower gift buying demand in the course of the holiday break period, about just one-third of product or service combine is discretionary in nature,” Bobby Griffin, an analyst at Raymond James, wrote in a be aware to clients next the outcomes.
For 2023, Lowe’s is forecasting sales to be between $88-$90 billion, though similar-retail outlet-revenue are believed to be flat or down 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year. Executives see the pullback in Diy demand from customers as transitory, and other experts in the marketplace see a “historic boom” coming for residence transforming.
Nick Teichtmann (R,) with the help of Lowe’s personnel Jaime Solis, purchases lumber to renovate his residence by incorporating a gazebo on best of a deck and repairing his garage at Lowe’s residence improvement retailer on April 11, 2011 in Burbank, California. (Picture by Kevork Djansezian/Getty Illustrations or photos)
“Disposable own earnings, which I pointed out, is about $1.5 trillion in cost savings earlier mentioned pre-pandemic amounts,” CEO Marvin Ellison explained to analysts on the earnings simply call.
Ellison pointed out the regular equity for residences in the U.S. is about $330,000, and anticipations of growing older housing inventory could place to continued desire for home upgrades.
“Two-thirds of every little thing we market is non discretionary. And there are other tailwinds, millennial household development trend, little one boomers ageing in location and additional widespread sustainable remote work, so all of these matters give us some self-assurance that the backdrop remains supportive,” Ellison additional.
Shares of both equally Residence Depot and Lowe’s are down over 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the very last month.
Lumber deflation
The times of pricier lumber could be more than.
The housing slump has triggered a crisis in lumber, with lumber futures falling 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the earlier calendar year. And homebuilders are using observe.
Pulte Group (PHM) introduced in their hottest earnings get in touch with the company is picking up their pace of design amid elevated lumber stock and more inexpensive pricing.
A be aware from analysts at UBS published very last month claimed some authorities in the homebuilding room see kitchen cabinetry and home windows, fairly than larger framing or roofing initiatives, driving desire for lumber.
And however lumber selling prices have fallen sharply, the firm pointed out for quite a few “main” housing solutions charges “have reverted to ‘reasonable levels,’ but [builders] are not witnessing any authentic rate reductions from sellers.”
As just one expert explained to the company, most solutions are “in no way going [to] pre-Covid rates once again.”
Dani Romero is a reporter for Yahoo Finance. Follow her on Twitter @daniromerotv
Dwelling Depot (NYSE:High definition) is set to post its earnings final results prior to the market place open on Tuesday, with macro things in emphasis as the retailer tries to keep gross sales momentum immediately after a pandemic-driven increase.
Analysts hope the enterprise to report $3.29 in earnings for every share for the fourth quarter $36B in profits. The Atlanta-dependent retailer has crushed both equally revenue and EPS estimates in each and every report due to the fact May 2020 in the depths of the early pandemic. Even though shares have risen sharply from that position amid strong pandemic remodeling demand, shares have trended flat above the previous calendar year and stay notably down below their late-2021 peak.
In 2023, the vital considerations about the stock’s trajectory involve the likely for soaring desire prices to damage housing demand, lingering offer chain risks, still-elevated labor charges, a general slowdown in residence reworking submit-pandemic, and greater level of competition from Lowe’s (Very low), particularly in the essential Professional section. By distinction, upside motorists incorporate rebounding homebuilder sentiment and prospective for the housing industry to continue to be resilient, continued dominance in the Pro segment, and the probable for much better than predicted reworking devote amid customers.
“We figure out lapping the pandemic energy signifies risks, but we however perspective High definition as a significant-cap, retail current market share chief to have,” Citi analyst Steven Zaccone stated. “Housing industry indicators are powerful and place to ongoing strength in home improvement, HD’s greater positioning with pros (45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of company), and recent acquisition of High definition Source need to insulate the retailer from important declines on more durable comparisons, and management’s determination to continual opex leverage presents clarity on returning to leverage post a multi-yr financial investment cycle.”
He currently retains a Get-equal rating on the stock, in-line with the analyst consensus.
Analysts also broadly see upside for Home Depot (Hd) via its expense-slicing efforts and channel checks that counsel strong similar-store revenue. In accordance to Placer.ai, a knowledge analytics company tracking foot website traffic to main stores, visits to Residence Depot and Lowe’s have fallen double-digits from the pandemic increase, but have stabilized near 2019 stages.
For each the details, foot website traffic into House Depot destinations slumped by an typical of 11.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months about yr for the months of October 2022 by January 2023. Nonetheless, visits trended only 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} beneath 2019 degrees around the exact same span.
“Although the warm property-shopping for sector is cooling off, year-in excess of-a few-calendar year foot visitors continues to be shut to pre-pandemic stages thanks to a change in direction of projects aimed at sprucing up a present-day residing place,” the analysis explained. “Demand for projects related with moving drove dwelling enhancement foot targeted traffic when residence gross sales had been surging, but it seems that jobs that enhance the prospect of being in position also have the ability to drive visits.”
That said, direction into 2023 is likely to confirm pivotal for the inventory reaction on Tuesday, more so than income trends into the near of the fiscal 12 months. Analysts are not hopeful for the retailer to offer a comprehensive forecast. Financial institution of The united states analyst Eliazbeth Suzuki observed that 2022 guidance integrated a projection of “slightly positive” comps, “flattish” EBIT margin, and “low-single digit growth” in EPS relatively than precise figures. She does not foresee far more granular depth in the forthcoming report.
In terms of ahead-seeking surveys, Keybanc analyst Bradley Thomas instructed purchasers that “a continued slowdown in in the vicinity of-phrase progress for home improvement professionals” is probable. While Residence Depot (High definition) is very likely to keep a dominant placement in the Professional segment, the business enterprise could be choppy into 2023.
“As we have composed in the past, the latest pipeline of work should really hold transforming developments constructive for the future a person to two quarters, which is encouraging, albeit at progress prices that are probable to decelerate,” Thomas wrote in advance of the success.
House Depot Inc. stated Tuesday the home-improvement sector could weaken this year, if client expending retains shifting toward companies from goods, and if inflation carries on to influence demand.
The house-enhancement big
High definition, -7.06{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
expects fiscal 2023 internet income and exact-retail outlet gross sales to be about flat with previous yr, however, due to the fact it will take market share from its competition.
Sales could be harm additional if lumber price ranges, which have presently fallen by extra than 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a 12 months back, go on to decrease.
The ordinary analyst estimate compiled by FactSet for revenue at the time Home Depot reported effects was $158 billion, which implied .4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} progress, while the FactSet consensus for identical-shop product sales was for a increase of .2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Main Money Officer Richard McPhail said on the submit-earnings conference connect with with analysts that for about the very first five quarters postpandemic, the corporation observed important growth in the price of the ordinary ticket and selection of transactions, for the reason that property owners took on extra do-it-oneself tasks as they invested far more time at home.
Since about the fiscal second quarter of 2021, McPhail stated product sales ongoing to increase thanks to ticket development, but the range of transactions “steadily normalized” towards prepandemic levels, “as the broader customer economy shifted” from merchandise back to products and services.
“We think that if this change proceeds at its existing pace, the residence-improvement market would be down lower-solitary-digits [percentages],” McPhail explained, according to a transcript offered by AlphaSense.
In the meantime, earnings per share for the 12 months are forecast to decrease in the “mid-one-digit” percentage assortment, as a increased anticipated tax rate and an expense in staff payment weighs on functioning margins.
That was a shock for Wall Road analysts, as the FactSet EPS consensus for the latest fiscal calendar year was $16.70, which was a penny extra than EPS for previous calendar year.
Dwelling Depot’s inventory slid 5.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in morning investing, sufficient to make it the worst performer amid the Dow Jones Industrial Average’s
DJIA, -2.06{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
elements. The stock’s $17.26 rate decrease was reducing about 114 details off the Dow’s rate, while the Dow fell 487 details, or 1.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
The organization also documented just before the open fiscal fourth-quarter EPS that topped expectations, net product sales that arrived up a bit shy and same-store profits that incredibly declined.
Chief Govt Officer Ted Decker mentioned on the article-earnings phone with analysts that by most of fiscal 2022, the company’s “resilient” buyers have been much less selling price delicate that expected in the reality of persistent inflation.
“In the 3rd quarter, we famous some deceleration in selected products and categories which was far more pronounced in the fourth quarter,” Decker claimed, in accordance to an AlphaSense transcript. “This, along with the damaging impact from lumber deflation, led to fourth-quarter comps [same-store sales] that have been somewhat softer than predicted.”
Home Depot’s inventory has slumped 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the past three months and declined 13.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} about the earlier 12 months, even though the Dow has eased 1.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} the past three months and slipped 2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} the previous calendar year.
Dwelling advancement retailer Residence Depot is making a nationwide modify to how it pays hourly staff upcoming 7 days.
“As legislation, know-how and office practices proceed to evolve, we’re transforming our follow nationwide effective Jan. 16, 2023, to shell out hourly associates to the nearest moment based mostly on correct time punches,” a House Depot spokesperson confirmed to FOX Business enterprise.
The new coverage will mark a change from its existing apply, which the spokesperson mentioned “has been to spherical full shift time up or down to the nearest 15 minutes.” That “has been a typical business practice for a lot of a long time,” according to the spokesperson.
House Depot retailer in West Berlin, N.J. with rental vehicles parked outside, Dec 25, 2022.
The transfer was first claimed Wednesday by Small business Insider.
The exercise of rounding is permitted in the Reasonable Labor Criteria Act (FLSA), with the legislation noting some industries tend to round to the “closest 5 minutes, or to the closest a single-tenth or quarter of an hour.” It have to be “utilized in such a fashion that it will not outcome, more than a time period of time, in failure to compensate the staff correctly for all the time they have actually worked,” it states.
A couple staff manufactured allegations about compensation in relationship to House Depot’s rounding tactics in previous lawsuits, Company Insider also noted.
Shares of retailer House Depot jumped early past 7 days right after posting superior-than-expected income.
Ralph Polk (L) and Fred James operate in the paint section at a Household Depot store Feb. 21, 2006 in Chicago, Illinois.
Home Depot had more than 2,300 shops and some 500,000 staff as of the conclusion of October, the firm reported a couple months in the past.
In November, the company stated its 3rd-quarter net gross sales amplified 5.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the similar interval very last calendar year, coming in at $38.87 billion. Its internet earnings were $4.34 billion, up 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in contrast to $4.13 billion in past year’s 3rd quarter.
As for its fiscal 2022 steering, Home Depot claimed it envisioned “comparable revenue advancement of roughly 3. p.c” and “diluted earnings-per-share-per cent-growth to be mid-one digits,” according to the earnings launch.
Dear Readers, do note that most of the data here were generated between 22 and 25 December 2022, and the rest from 26 to 30 December 2022. Also, any “Buy” rating in this article is a “Conditional buy” which comes with having certain conditions being met. You will need to assess if an asset is a “buy” based on your expected returns from that asset which is a very personal decision.
Happy New Year, everyone! May your 2023 be far better than 2022 in every imaginable way.
An Introduction to Home Depot and Lowe’s
Anyone familiar with the home improvement scene in the United States will know that the two largest listed companies in this space are Home Depot (NYSE: NYSE:HD) and Lowe’s (NYSE: NYSE:LOW).
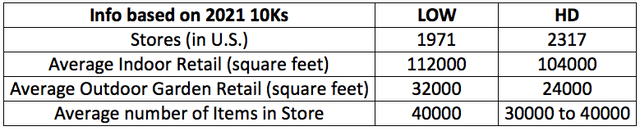
They are similar in many ways, with almost the same number of stores, having outlets of similar size, etc.
Author’s compilation of info from 10Ks and transcripts
Both companies target essentially the same profile of customers, the DIY (do-it-yourself), DIFM (do-it-for-me), and Pros Customers (professional contractors in two broad categories, those in the construction trades like renovators/remodelers and general contractors, and those in maintenance, repair and operations like building managers, handymen and specialty tradesmen such as electricians, carpenters and plumbers).
Both companies essentially sell similar products and services. They have to make the extra effort to differentiate themselves with their respective house brands, “unique” product offerings, and through their service quality. For instance, Sherwin-Williams paints are sold exclusively at Lowe’s while Ryobi are sold at Home Depot but not at Lowe’s. Home Depot sells its own proprietary products (HDX, Husky, Hampton Bay, Home Decorators Collection, Glacier Bay, Vigoro, Everbilt and Lifeproof), but Lowe’s has its Allen+, Roth, and more recently Origin21.
As mentioned in the LOW’s 10K,
We have many competitors who could take sales and market share from us if we fail to execute our merchandising, marketing and distributionstrategies effectively, or if they develop a substantially more effective or lower cost means of meeting customer needs, resulting in a negative impact on our business and results of operations.
Other than each other, these two companies also compete with traditional hardware, plumbing, electrical, home supply retailers, and maintenance and repair organizations, as well as with general merchandise retailers, warehouse clubs, online retailers, other specialty retailers, providers of equipment and tool rental, as well as service providers that install home improvement products. Other than selling products at different price points to target different demographics, having locations in all the states, and reducing friction in the transaction process to make the process convenient for their customers, service quality will be the other key differentiating factor. More on service quality later.
Both are Great Companies to Hold Long-Term
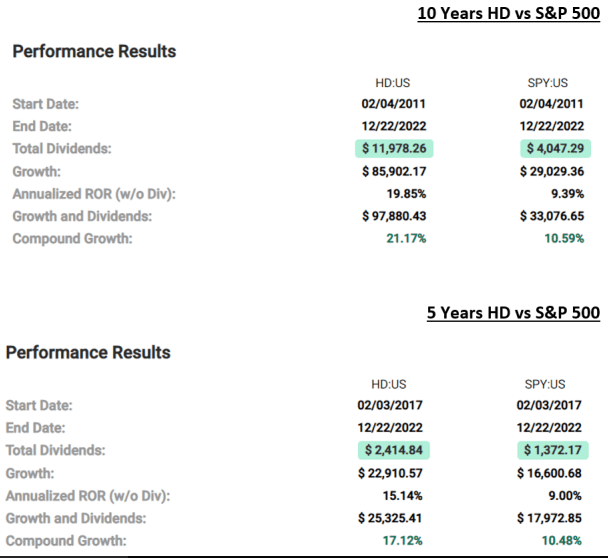
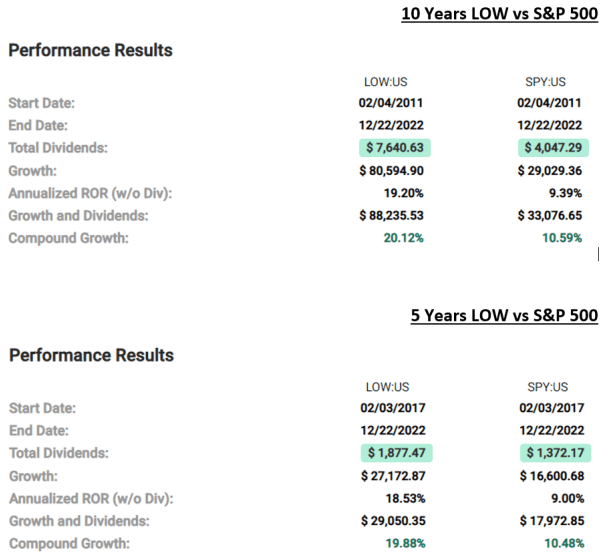
It is not surprising to find many shareholders of Home Depot also owning shares of Lowe’s as both companies have been performing well, trouncing the S&P 500 over a longer 10-year as well as a shorter 5-year period.
Fast Graph HD
Fast Graph LOW
Note: I chose these time frames to (1) exclude the worst of the Great Financial Crisis and (2) to factor in technological improvements that happened during the last 10 years that both companies could have leveraged such as better visibility of data via cloud computing, the use of touch screens interfaces to improve productivity, greater automation and use of robotics in the distribution centers, etc. This is important when I cover the section on “The Case for Lowe’s to Outperform Home Depot”.
Both Face Similar Headwinds and Benefit from Similar Tailwinds
A common concern that industry watchers and analysts have regarding the home improvement industry is the impact a slower housing market has on the future earnings of both companies, especially for Lowe’s since the majority of their customers are homeowners, they are likely to defer or reduce their budget for home improvement works.
This may be true but the impact should not be dire. Lowe’s CEO Marvin Ellison pointed out what he believes to be a myth regarding a positive correlation between a decline in housing with sales in home improvement, and posited three compelling arguments for a sustained tailwind in this industry
…demand drivers for home improvement are distinctly different from those that drive home building. So it’s important not to confuse the two. And as a reminder, at Lowe’s, the three highest correlating factors of home improvement demand are home price appreciation, age of housing stock and disposable personal income.
So let’s start with home price appreciation. Even if there is a broad-based decline in home prices, homeowners currently have a record amount of equity in their homes, nearly $330,000 on average, which remains supportive of home improvement investment. And even in the select U.S. markets where home prices have declined after a particularly steep run-up during the pandemic, we are not seeing any impact to sales.
Second, the average age of homes in the U.S. is over 40 years old and roughly 3 million more homes built during the housing boom in the mid-2000s, will be entering prime remodeling years by which is a key inflection point for big-ticket repairs. This is one of the key reasons why 2/3 of home improvement spend is nondiscretionary on repair or maintenance projects that cannot be delayed.
Third, consumer savings are near record highs, while disposable personal income remained strong. And more than 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homeowners either own or home or are locked into a low fixed mortgage insulating them from rising rates.The facts are that we have more personal disposable income today than we had before the pandemic, and that’s primarily in the bank accounts of homeowners… it was still 1.5 million to 2 million homes under current demand .
On top of these three factors, there is a persistent 1.5 million to 2 million undersupply of homes because of the lack of home building coming out of the financial crisis in 2008 and 2009, and 250000 first-time millennial homebuyers are expected per year through 2025. These factors lead homeowners to choose an investment in repairs and renovations to make their current homes meet their families’ evolving needs rather than buying a new home at record-high prices. In other words, this period of high inflation and rising interest rates actually drives greater demand for the home improvement industry.
Home Depot’s CEO Ted Decker agrees with CEO Marvin that sales can continue to be strong in 2023. In his response to an analyst who was concerned about the negative impact of a slower housing market on sales, he said,
There is a lot of noise around housing and home improvement. And you’ve heard some of this before, but if I can just step back a minute and lay out the environment the way we see it. I mean, we still feel very good, Michael, about our business. We just reported another strong quarter and reaffirmed our guidance for the year… From our core customer, we think our customer is still healthy. I mean, our customer tends to have a good job, growing wages, strong balance sheets. They own their home and have seen increased home equity.
Both CEOs also shared feedback from their Pro customers that most of them are expecting a robust backlog of projects pushing forward to 2023. Does this mean both stocks are a buy since the demand for home improvement will continue to be “strong and robust”?
So, after this brief introduction to what they do, some similarities, how they had performed, some of the industry-relevant tailwinds and headwinds, and the stance of the CEOs on the state of affairs, which is the better company to own?
The Obvious Winner is Home Depot
Home Depot has the largest market share, 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the $900 million to $1 trillion estimated total addressable home improvement market to be exact. That is a clear lead over second place Lowe’s 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the market share.
Home Depot is expected to do better than Lowe’s in an inflationary and recessionary environment that is compounded by a slower housing market scenario. The rationale goes like this: 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Lowe’s revenue comes from the DIY and DIFM crowd and if they choose to prioritize more immediate bread-and-butter spending needs over home improvement works, Lowe’s will take a bigger hit. On the other hand, 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Home Depot comes from professionals that include maintenance, repair and operations which are expected to have ongoing works in 2023, Home Depot is not expected to be hurt as much.
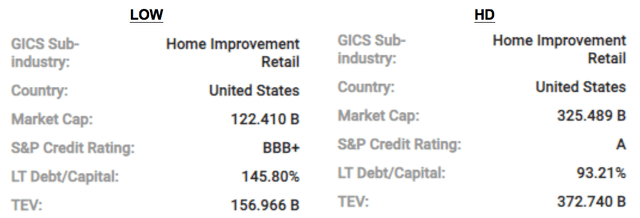
Both companies are investment grade but Home Depot is better with an A credit rating compared to Lowe’s BBB+. HD is also less leveraged than LOW, which has a higher long-term debt-to-capitalization ratio of 145.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
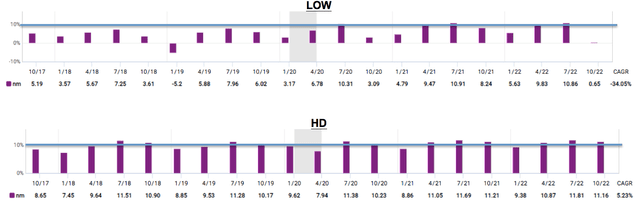
Fast Graph comparing LOW and HD
Bottom line matters and net margin affects that directly. Over the past 21 quarters, Home Depot’s net margin was consistently in the 9-10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} range. Lowe’s net margin however fluctuated much more from -5.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10.91{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Fast Graph comparing LOW and HD
Those stable and consistently higher margins translate to higher sales per square foot for Home Depot. In the fiscal year 2021, Home Depot generated $604.74 in sales per square foot. In comparison, Lowe’s managed a respectable but much lower $463 in sales per square foot.
Finally, income investors will find Home Depot’s 2.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield more appealing than Lowe’s 1.86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Case closed? Not so fast. Reality is always more nuanced. I believe there is a strong bull case for Lowe’s.
The Case for Lowe’s to Outperform Home Depot
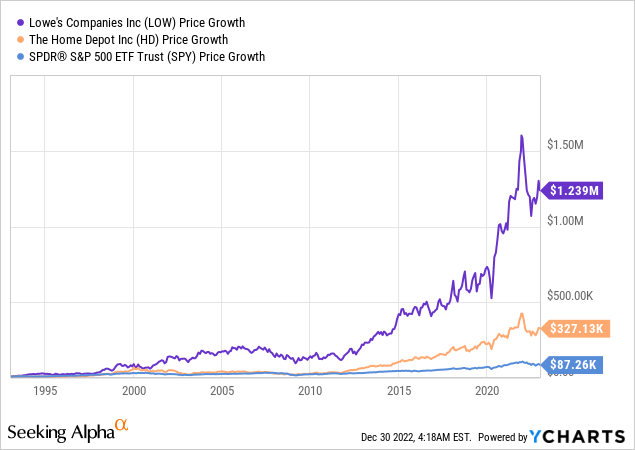
In the earlier segment under “The Obvious Choice is Home Depot“, I laid out comparisons of the fundamentals of both companies to show that Home Depot is a better choice. Yet, you may be surprised to know that an investment in Lowe’s 40 years ago would have been almost 400{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} better than an investment in Home Depot.
Historically, Lowe’s Had Massively Outperformed Home Depot
Previously, when comparing both companies over a 5-year and 10-year period, Lowe’s actually performed slightly better than Home Depot. To show that I did not cherry-pick the timeframe to get a favorable result for Lowe’s, I extended the comparison period to exactly 40 years, from 30 December 1982 to 30 December 2022.
A $10,000 investment in SPY would have become $87 thousand. The same amount in Home Depot would have increased to $327 thousand. But $10 thousand invested in Lowe’s would have turned into an envious $1.2 million dollars.
Past performance is definitely no guarantee of the future but it does give an indication of the possibility and the potential so let’s turn to examine the future earnings growth rate of both companies.
Based on Earnings Projections, Lowe’s Is A Better “Buy”
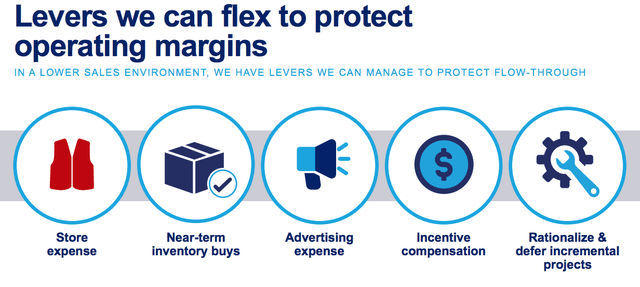
As both companies are huge, with a combined market share of 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the entire home improvement industry in the United States, there are levers for them to pull to improve operating margins, lower costs by ordering in bulk, pass costs on to their customers, and improve the bottom line. For instance, during the 7 December 2022 Investor Day presentation, Lowe’s CFO shared the following levers for improving their operating margins.
Lowe’s Investor Presentation Slides by CFO
Home Depot has not shared its guidance for 2023 as its investor day will be in the middle of next year but I will not be surprised to see the company do likewise if they need to squeeze out positive earnings.
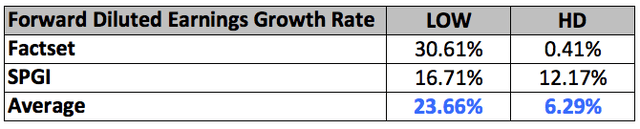
Analysts modeled the earnings growth rate and the results are tabulated below.
Author’s collation of analysts’ forecast
The disparity between these two sets of earnings growth estimates is great but believable. Morningstar analyst Jaime M. Katz wrote a memo on 15 December 2022 saying,
With continued focus on retail fundamentals (merchandising excellence, operational efficiency, supply chain improvements, and customer engagement), Lowe’s has been able to better leverage costs while maintaining its low-cost position. The firm retains some of the cost savings it achieves and passes the rest on to its customers through everyday low prices. These competitive advantages support our wide economic moat rating.
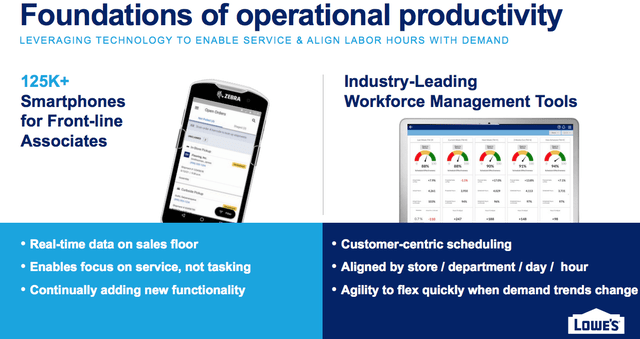
Lowe’s has been undergoing a multi-year technological and logistical transformation to improve productivity. It developed a customer-centric scheduling system to allow it to predict customer demands and align its labor with peak customer traffic for each store, each department, by each day, and even by each hour of the day to maintain its consistent and strong customer service and reduce payroll expenses. More on how Lowe’s is able to cut more expenses and improve margins to a greater degree later.
Based on Valuations, Lowe’s Is Cheaper
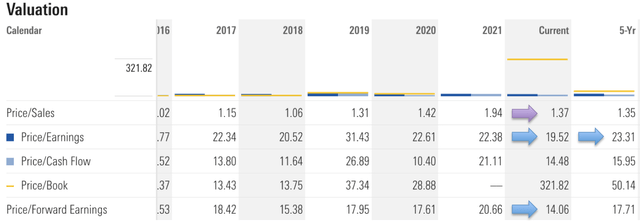
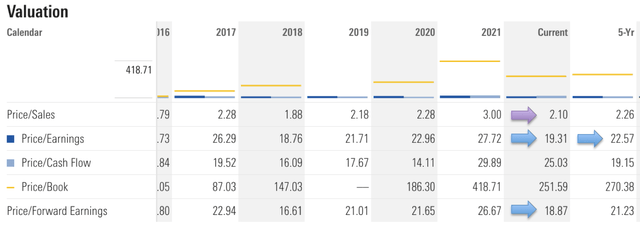
Both are trading at P/E and forward P/E valuations below their respective 5-year averages.
Lowe’s Valuation from Morningstar
Home Depot’s Valuation from Morningstar
I would like to draw your attention to the forward P/E; Lowe’s much lower price/forward earnings of 14.06 compared to Home Depot’s 18.87 is a reflection of both the better-expected future earnings for Lowe’s as well as worse-expected future earnings for Home Depot.
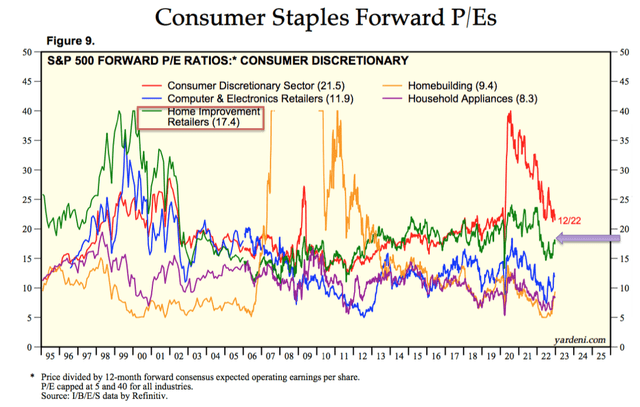
Yardeni Research
That also means that Home Depot is expected to continue to trade at a premium in 2023 relative to the stocks in the Consumer Discretionary category while Lowe’s is expected to trade at a much better valuation which will offer a much preferable entry point and a higher margin of safety.
Lowe’s Has Higher Average Ticket Than Home Depot
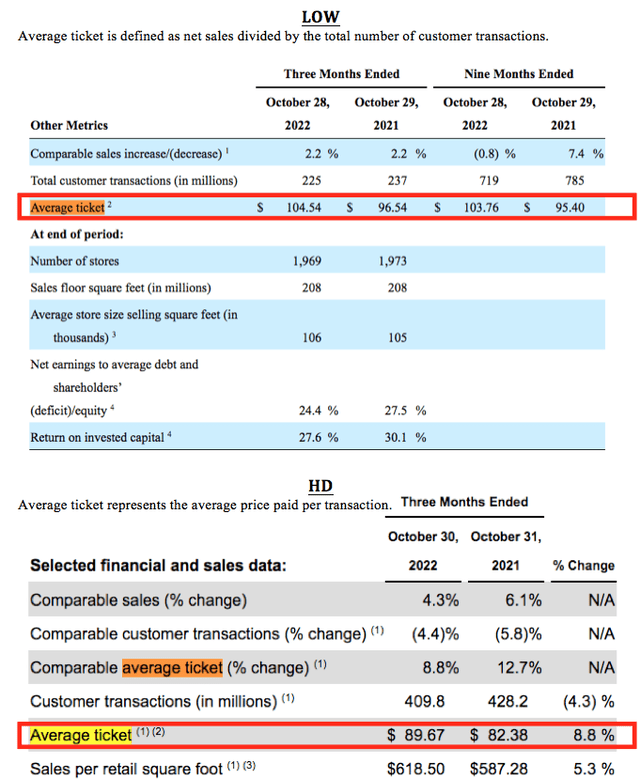
Home Depot can boast of having a higher revenue per square foot than Lowe’s but that is not everything. Another key metric management of both companies uses to monitor the performance of the Company is “Average Ticket” as it represents a primary driver in measuring sales performance. “Average Ticket” represents the average price paid per transaction.
Comparison of The Latest Q3 2022 Average Ticket
Although Home Depot consistently chalks up a higher sales per retail square foot figure than Lowe’s, the average Lowe’s customer consistently outspends Home Depot’s customer.
Dividend Growth Investors Would Love Lowe’s
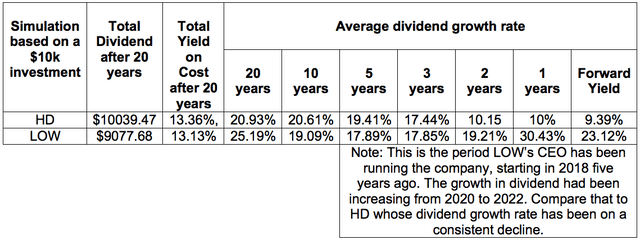
I will be remiss if I fail to mention that Lowe’s is a Dividend Aristocrat that has risen dividends for 49 consecutive years compared to just 13 consecutive years of dividend growth for Home Depot. Although Home Depot provides a higher yield than Lowe’s, an investor with a longer investment horizon should give Lowe’s a second look. Over a 20-year period, because of Lowe’s higher dividend growth rate of 25.19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an investor could have gotten back $9077.68 which is close to HD’s $10k of dividends.
Author’s compilation of data taken from Fast Graph and Seeking Alpha
And looking forward, one can also see the disparity in the average dividend growth rate. While Home Depot is decreasing its rate of dividend growth to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this year and an expected 9.39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth in 2023, Lowe’s never fell below 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In fact, under CEO Marvin from 2018, the dividend increased for three consecutive years, and it is still expected to grow the yield at a lip-smacking rate of 23.12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fiscal year 2023.
With that, I will move on to the final bull-case argument for Lowe’s – management.
Lowe’s Management Knows What They Are Doing, And Knows What Their Competitor Is Doing
In the most recent earnings call, CEO Marvin Ellison said,
As I said in my prepared comments, we’ve got a lot of experience sitting around this table. There’s very few things that we have not seen.
Usually, we might have interpreted this casually as “we are a bunch of people who have worked for many years in the home improvement industry, so trust us to do the right thing“, and therefore dismiss the importance of his characterization. There is more to what he meant.
You see, three of the current leadership team at Lowe’s had prior experience working in various executive roles at Home Depot and one of them worked at another large competitor for almost 2 decades. They knew first-hand what had worked at Home Depot and Walmart and could adapt the relevant processes and strategies to Lowe’s. I will mention them briefly below while putting the focus on the CEO.
Joe McFarland, Executive vice president of Operations, served at Home Depot as President from 1994 to 2015. During his time at Home Depot, he led improvements in customer service and productivity so frontline staff could spend more time providing customer service and making sales.
William Boltz, Executive vice president of Merchandizing, served in different merchandising roles at Home Depot.
Donald Frieson, Executive Vice President of Supply Chain, was not a Home Depot veteran but he has more than 30 years of operations and supply chain experience, including 19 years at Walmart, joined Lowe’s in 2018. He is widely recognized as a cost containment expert.
CEO Marvin Ellison
He was brought on board at Lowe’s in 2018. Prior to that, he worked at Home Depot for 12 years from 2002 to 2014. He served as executive vice president of Home Depot’s U.S. stores from 2008 to 2014, “dramatically improving customer service and efficiency across the organization, as he oversaw U.S. sales, operations, installation services, tool rental and pro-strategic initiatives“.
And upon joining Lowe’s he had taken a hard look at his company. At the 7 December Investor Presentation Day, CEO Marvin was brutally candid about Lowe’s shortcomings,
One critical step in our evolution is moving away from a store delivery model which was terribly inefficient. With our old store-centric system, each store served as its own distribution centre for big and bulky products. We were holding the appliances in our back rooms, and storage containers behind our stores and using our store trucks to deliver them to customers. That meant customers can only purchase inventory from that single store. They didn’t have visibilityinto the inventory we had to offer and neither do our associates. And because or store-based trucks didn’t have delivery or routing software, customers did not have visibility into the delivery process. They didn’t know when their appliances will arrive so to say this was a poor customer experience would be an absolute understatement.
That kind of honesty was simply mind-blowing to me. And that was definitely what a leader needs to meet the challenges posed by its largest competitor with a market share that is more than twice as large.
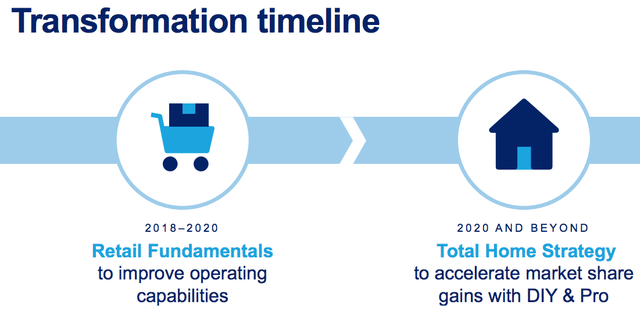
Under his leadership, he set Lowe’s on a two-stage transformation. Part one is on improving the fundamentals of the business to address the numerous issues which he had highlighted, to transit Lowe’s from a store-centric system into a more efficient customer-centric market-delivery model.
Investor Day 2022 Presentation by CEO
Part one is the low-hanging fruit, which when achieved will boost margins and earnings quickly and Lowe’s is on track; the full rollout is expected to complete by the end of 2023.
Investor Day 2022 Presentation by CEO
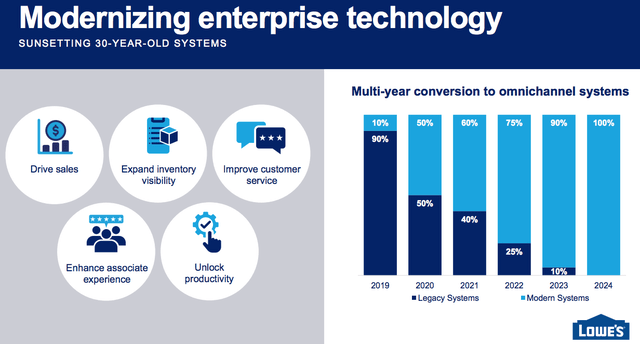
Likewise, Lowe’s modernization efforts are already paying off. Some examples: frontline associates in the backrooms and distribution centers are using their own smartphones to access inventory and complete fulfillment for online orders; more self-checkout stations are installed; cashiers are working with touch-screen terminals that make training new associates easier.
Investor Day 2022 Presentation by Joe McFarland
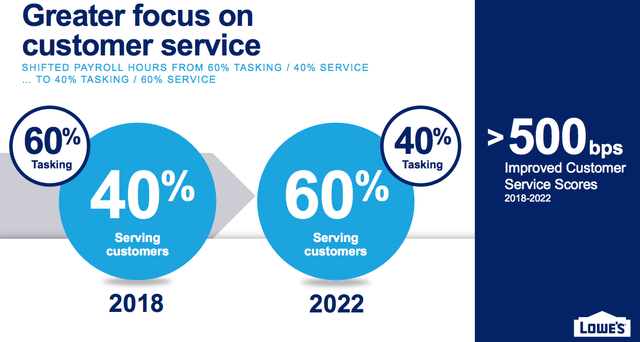
By the end of 2023, 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Lowe’s archaic systems will be modernized. With improved productivity and better visibility across inventory and labor, frontline associates are now able to spend 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their time serving customers and improving sales, compared to just 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 4 years ago. That is a massive 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase in the time associates have to help customers find the best solutions for their home improvement needs. In a space that to me is very commoditized, where price matters a lot to customers and the differentiation between the supplies at different home improvement retailers is minimal, what brings a customer back, again and again, is the customer service.
Investor Day 2022 Presentation by Joe McFarland
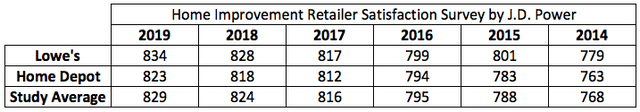
J.D. Power, a global leader in consumer insights, advisory services and data and analytics and a pioneer in the use of big data, artificial intelligence and algorithmic modeling capabilities to understand consumer behavior, has been conducting this “Home Improvement Retailer Satisfaction Survey” for the past 8 years.
J.D. Power. Data for 2020-2022 is not presented as those require payment
The two takeaways from the survey are clear: Lowe’s has consistently received a better consumer satisfaction score than Home Depot, and Lowe’s has consistently received above-industry average scores while Home Depot received scores below the industry’s average.
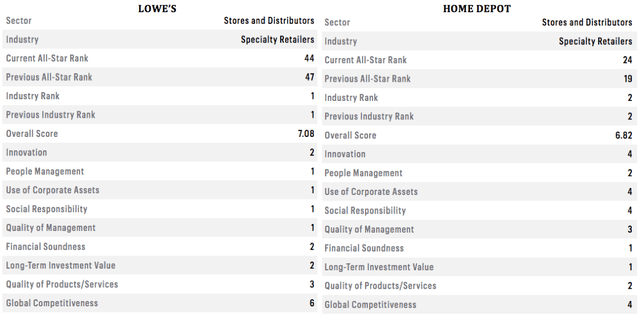
The transformations at Lowe’s also received acknowledgment at the national and international levels.
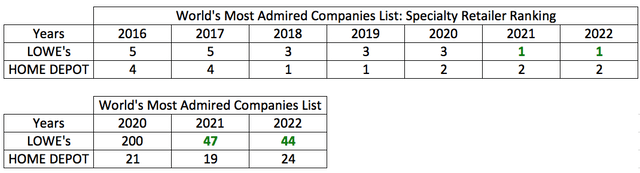
Lowe’s topped Fortune’s list under theWorld’s Most Admired Companies List in the Speciality Retailer category.
Fortune Ranking Comparison of Lowe’s and Home Depot
From the period when CEO Marvin took over in 2018, the multi-year improvements and innovations he and his team have been introducing are bearing fruit, and Lowe’s has been moving up this list.
It is no wonder CEO Marvin just received the National Retail Federation Visionary Award for 2023.
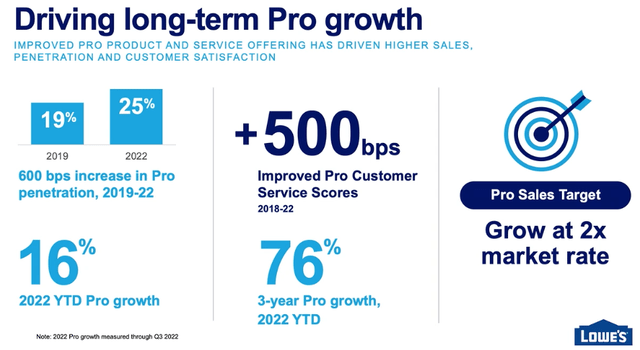
And he is far from done. He has been positioning Lowe’s to enter into Home Depot’s traditional domain in a strong way – the Pro Customer space. While it remains focused on the DIY business, Lowe’s recognizes the opportunities in the Pros section and is expanding its market share there, aiming to have 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the revenue from this segment.
He shared the following at the recent investor day,
It wouldn’t be difficult to overstate how broken the pro service model was when we arrived at the company, but we are up to the challenge and we have completely overhauled the Pro Offering. I know some of our pro customers, suppliers and many shareholders and people in this room were originally skeptical about whether we had the commitment, and also the tenacity to succeed in this important area of the business. After 10 consecutively quarters of double-digit growth at Pro, we have demonstrated our commitment to this business.
The increasing emphasis on the Pro business is not just a strategy envisioned but it is one that has been put in place. Lowe’s Pro customers in the MVP program spend three times more than pros not in the program and that has resulted in impressive double-digit growth for 10 consecutive quarters. Revenue contribution from the Pros has increased from 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2019 to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022.
CEO Investor Day slides
And with the other initiatives that are coming to fruition in 2023 and 2024, it is not difficult to see Lowe’s reaching the targeted 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Pro sales revenue, and for the sales from the Pro customers to continue to grow at two times the market rate.
Risks in Investing in Both Companies: Based Only On Revenue Projections, Both Are A “Hold”
The CEOs of both companies expressed confidence in the strength of the business and downplayed the effects a slower housing market has on the business. While we should take note of the very reasonable explanations and reassurances by both CEOs, investors should also be mindful that CEOs are the spokesperson (cough… salespersons… cough) for their companies. Phrases such as “strongandrobust sales” have to be qualified; actual projected numbers tell a more complete story.
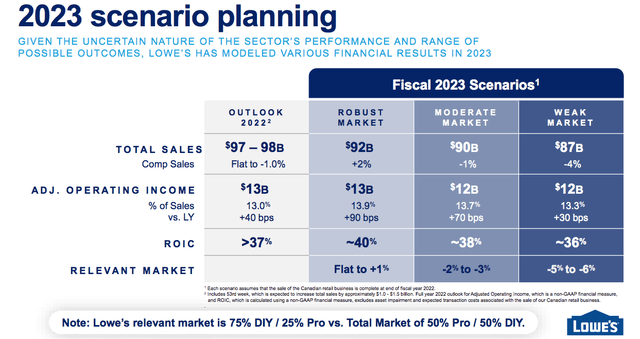
Lowe’s CFO Brandon Sink shared the following on the 7 December 2022 investor day. He projected three outlooks for the company. In the most bullish scenario of a “robust market”, sales are expected to grow 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-on-year. In a moderate market situation, sales are expected to drop to -1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. And if the market is really weak, sales may fall as much as -4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Lowe’s Investor Day slides
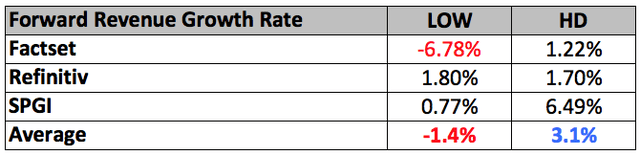
Analysts are likewise lukewarm on both companies as they are not convinced that a weaker housing market does not affect the growth prospects of these two companies. Analysts across the board are forecasting slower revenue growth rates for in next fiscal year for Lowe’s and Home Depot.
Author’s compilation of data taken from Seeking Alpha, Fast Graph and Yahoo Finance
None of these revenue growth figures are particularly encouraging or promising for investors.
Conclusion
Both Home Depot (HD) and Lowe’s (LOW) are great companies. The rivalry between them drives each other forward to be their better selves. Just as Lowe’s is improving by leaps and bounds, Home Depot is not resting on its laurels either. Home Depot recently announced the Path to Pro platform, connecting skilled tradespeople with hiring trades professionals for free for its Pro extra members. This unique and proprietary platform contains thousands of candidates and Pros have begun posting their open jobs. This serves to deepen the Pro value proposition and make the platform more “sticky” for its pro customers.
Both have generated outstanding returns over the long term, both in terms of capital appreciation as well as dividends.
The difference, however, is Lowe’s has more room for improvements than Home Depot, and hence is poised to show better results at least in 2023. The majority of the changes put in place by Lowe’s management are nearing fruition and many are bearing fruit.
Being number two is not always bad. Lowe’s is often described as playing second fiddle to Home Depot, often characterized as “playing catch-up”. Well, playing catch-up is not as bad as it sounds because it means learning from the mistakes made by the trailblazers. Playing catchup also means Lowe’s gets to install newer and faster equipment, and a newer and better inventory management system than its competitors.
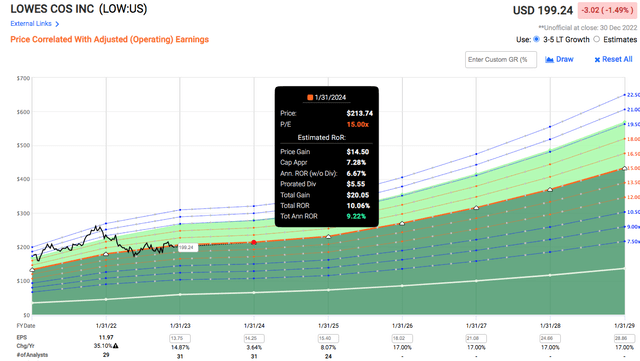
In terms of valuation Lowe’s is much cheaper than Home Depot, and with that margin of safety, it potentially offers a 9.22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} return by the end of the fiscal year 2023.
Fast Graph Lowe’s
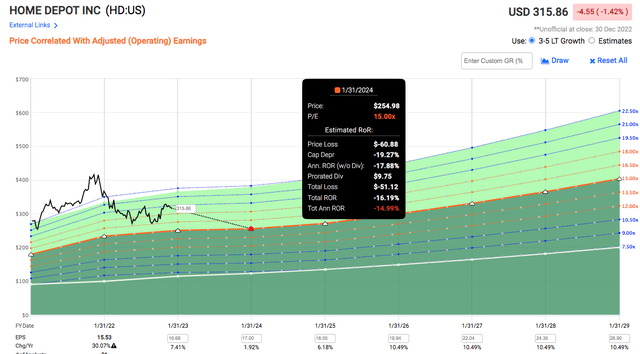
In contrast, despite the market correction in 2022, Home Depot is still priced at a premium. As the expected earnings growth rate for the next two years is only in the low to mid-single digits, it will be unrealistic to expect Home Depot to trade at its past normal P/E of 19-20. If the company were to trade down to just a P/E of 15 to reflect the new normal, there is potential for a loss even with a multi-year holding period.
Fast Graph Home Depot
And with Lowe’s higher dividend growth rate, thrice that of Home Depot’s in 2022 and more than twice of Home Depot’s in 2023, it will not be long before Lowe’s yield catches up to Home Depot’s. Already, that yield difference has narrowed, from Lowe’s current 1.83{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to Home Depot’s 2.37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, to an expected 2.08{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for Lowe’s to Home Depot’s 2.37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fiscal year 2023.
Lastly, having a proven management team with a depth of relevant experience, much of which was gained working at its major competitor, who had seen firsthand what had worked is definitely a plus. Lowe’s combination of cost management, margin improvements (like selling the less profitable Canadian division), productivity initiatives, technological advancements, operational and logistical enhancement to improve customer experience, and strategic realignment to focus more on the pros, is finally bearing fruit.
To reiterate, both are fantastic companies to own. However, at their current valuation and looking at their potential in the next 1-2 years, as well as taking other factors into consideration, on a risk-reward basis it is my opinion that Lowe’s is a reasonable buy while Home Depot is a hold.
A household enhancement contractor operates on a residence in Cambridge, Massachusetts.
Suzanne Kreiter | The Boston World | Getty Illustrations or photos
As the U.S. housing marketplace falls challenging from its pandemic-pushed highs, house enhancement vendors like Dwelling Depot and Lowe’s really don’t appear to be to be sensation the very same agony. In fact, they’re faring improved than expected.
When homebuilding and home reworking are integrally linked, the industry forces guiding each and every can be diverse, and that is what is happening now.
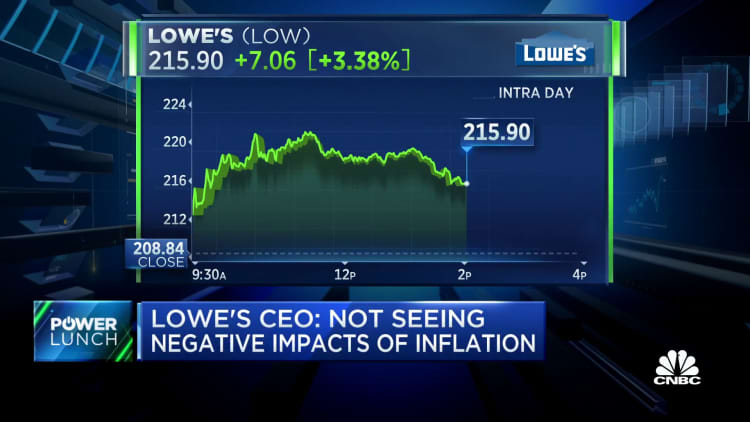
House Depot and Lowe’s documented sturdy quarterly earnings Tuesday and Wednesday, respectively. Lowe’s stock rose 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Wednesday. Executives at both corporations spoke bullishly about the prospects for their organization in 2023. This comes as residence sales, charges and building are all weakening appreciably thanks to a massive soar in home finance loan prices.
Residence Depot financial main Richard McPhail pointed to an “boost in place” mentality among recent owners, who may have required to offer but adjusted their minds due to the fact they could no longer command top dollar.
“All we can do at this place is repeat what our shoppers are telling us,” McPhail stated. “There is a dynamic we do not see a lot in the marketplace. With climbing house loan costs, homeowners are keeping in place.”
With increasing mortgage fees, homeowners are being in place.
Richard McPhail
Residence Depot CFO
Home costs are nevertheless 11.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} better in Oct than they were being in Oct 2021, in accordance to CoreLogic, but that yearly comparison has been shrinking for quite a few months. Costs are falling thirty day period-to-month at a considerably speedier pace than standard seasonal tendencies.
However, the unparalleled operate-up in home costs throughout the 1st years of the pandemic, fueled by file reduced property finance loan fees and a drive for lots of People in america to shift to more substantial houses in suburban locations, gave householders sizeable amounts of equity. Charges jumped extra than 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in just two several years.
By the close of the initially quarter of this 12 months, prior to the steep runup in home loan premiums prompted the housing sector to falter, house owners experienced a collective $11 trillion dollars in so-identified as tappable equity, according to Black Knight. That is the quantity a borrower can get out of their home while nevertheless leaving 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity in it. That fairness grew by an unparalleled $1.2 trillion in the to start with quarter of this yr by itself. For every property owner, it quantities to about $207,000 in tappable equity.
That equity is aspect of a three-pronged driver of property advancement, in accordance to the CEO of Lowe’s, Marvin Ellison. He pointed to dwelling price tag appreciation, the age of the U.S. housing stock — which is roughly 40 several years outdated, the oldest considering the fact that Globe War II — as perfectly as significant levels of personalized disposable earnings.
“So when you seem at all people elements, individuals matters bode properly for house improvement, and we come to feel genuinely fantastic about our present-day tendencies,” explained Ellison in an interview Wednesday on CNBC’s “Squawk Box.”
The NAHB, nonetheless, is forecasting that the remodeling sector will fare the best between the household construction submarkets during this existing housing contraction.
“The development level for advancement investing will gradual because of to declines for existing property income,” said Robert Dietz, NAHB’s chief economist. “However, an aging housing inventory, function from household developments and a decline for domestic mobility all favor transforming investing.”
Dietz also factors to the “curiosity fee lock-in results,” meaning folks will not want to offer a dwelling where they may possibly be spending a 2.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} property finance loan fascination price and trade up to another home wherever the price would probably be all-around 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} currently.
Harvard’s Joint Center for Housing predicts that the annual gains in home advancement and maintenance shelling out will drop “sharply” by the center of future year, but only to a 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} development amount from an unusually superior 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate.
“Housing and reworking markets are without doubt slowing from the exceptionally high and unsustainable growth costs that adopted in the wake of the pandemic-induced economic downturn,” states Carlos Martín, venture director of the Reworking Futures Plan at the Middle. “Paying for dwelling advancements will carry on to face headwinds from declining dwelling income, mounting interest fees and the increasing charges of contractor labor and building components.”
Regardless of inflation in just about every thing in the financial system, consumers do feel to want to commit far more on their homes. Both equally Lowe’s and Household Depot showed a drop in the number of sales but a soar in the dollar amount of money of all those gross sales. That led to their increases in profits.
“There is inflation in the market and elasticity, but not to the degree that we predicted, and the shopper reveals us they are resilient,” reported Home Depot’s McPhail.
A new study of nearly 4,000 home owners by Houzz, a house improvement and structure web-site, discovered that only 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners documented acquiring canceled a house improvement job in 2022. In the meantime, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} accomplished a undertaking in 2022 and just about a single-quarter mentioned they were being setting up to start off a home enhancement challenge in the next 12 months.
“Moreover, much more than fifty percent of the owners we surveyed have no intention of marketing or relocating out of their existing residences in the following 20 a long time or ever,” said Maritime Sargsyan, Houzz personnel economist.