Luxury real estate to get special tax status under ‘blight’ statute

Luxury real estate to get special tax status under ‘blight’ statute

Council moves to create $277 million infrastructure fund and grant special tax treatment to lakefront properties

The Austin City Council took steps Monday to create a special tax zone to subsidize infrastructure development in a 118-acre area along Lady Bird Lake known as the South Central Waterfront.

Plans for the zone call for the creation of amenities including a waterfront boardwalk, streetside rain gardens, commercial plazas, sculptures, amphitheater, and a disc golf course, as well as sidewalks, trails, and a revamped street network, at a cost of $277 million.

A proportion of property taxes collected in the district would go to fund just those improvements, rather than the general fund. A draft ordinance posted with Monday’s council agenda put the proportion at 46 percent, though the council delayed a final decision on the exact increment.

The subsidies could supercharge the development of an area that already includes some of the most valuable real estate in Austin, including a stretch of the famed South Congress Avenue, the long-time Austin-American Statesman office and bat observation center, and the lakeside Hyatt Regency hotel.

Behind the plan is the Endeavor Real Estate Group, which built some of the city’s best-known luxury developments. One of them was The Domain, a high-end shopping center that got a sales-tax and property tax breaks worth an estimated $57 million to $65 million over two decades. Civic activist Brian Rodgers sued the City and Endeavor over that deal and in 2004 reached a settlement that stated the city wasn’t required to pay the Domain incentives, but could continue to do so voluntarily, which it did.

Endeavor has partnered with the Atlanta-based Cox family, owners of the 18.9-acre Statesman property, to develop that site and to lobby for a broader South Central Waterfront plan, including public financing.

The Cox family, which has a net worth of about $35 billion, according to Forbes, sold the Statesman in 2018 but held on to the newspaper’s property at 305 South Congress, next to the Congress Avenue Bridge. The property is the largest in the new South Central Waterfront zone, representing about a sixth of its total area.

Endeavor hopes to put as many as six high rises on the property, including at least one that would be taller than Austin’s iconic Frost Bank Tower (the “owl building”). Many of the amenities proposed under the South Central Waterfront plan would lie in the shadow of these buildings.

Additionally, Endeavor itself owns at least two other properties in the district, a 1.5-acre, six-story apartment building on South First Street, which offers “modern luxury living,” and a 1.8-acre waterfront property on Riverside Drive that’s currently rented by the bar and game arcade Cidercade Austin.

‘Unproductive, underdeveloped, or blighted’

To authorize the infrastructure subsidies, the council invoked the Tax Increment Financing Act, which allows a city to create a Tax Increment Reinvestment Zone (TIRZ) in an area where development “would not occur solely through private investment in the reasonably foreseeable future.”

That law is authorized under a constitutional provision allowing cities to create reinvestment zones “to finance the development or redevelopment of an unproductive, underdeveloped, or blighted area.”

According to the tax law, the TIRZ area must constitute “a menace to the public health, safety, morals, or welfare,” or an impediment to “the sound growth of the municipality” because of the presence of deteriorating structures, a slum, unsanitary conditions, or certain other criteria.

In its ordinance creating the TIRZ, the council cited two such criteria: “faulty lot layout” and “defective or inadequate sidewalk and street layout.” Because of those conditions, the growth of the waterfront district is substantially impaired, the council stated in a list of findings.

‘Crony capitalism’

Critics of the plan say that it violates the law and represents a handout to developers. Attorneys Fred Lewis, Bill Aleshire, and Bill Bunch wrote a letter to the mayor and council saying the proposed TIRZ was “a gross abuse of the Texas Tax Code provisions for subsidizing development of blighted areas that would not otherwise develop on their own.”

“The subject property is the most prime development land in the entire city of Austin…Unless the plain language of the statute is meaningless, this property is nowhere near lacking in development potential as required.”
The lawyers pointed out that developers normally have to pay for new sidewalks, parks, and utility infrastructure in new developments. The new South Central Waterfront TIRZ therefore represents a departure from that practice that will pad the pockets of the developers behind the proposal. “This proposal is corporate crony capitalism at its worst and is the epitome of TIRZ abuse by wealthy developers,” they wrote.

Aleshire, Bunch, and Lewis recommended that the tax dollars instead be spent on “public improvements that benefit average Austinites or in reducing their heavy property tax burden.” (Disclosure: Attorney Bill Aleshire represents The Austin Bulldog in obtaining information through public information requests and assists in other legal matters).
Ora Houston

Similarly, former Council Member Ora Houston issued a call-to-action to her followers, in which she mocked the idea that prime downtown real estate was “blighted” and wouldn’t develop without incentives.

The proposal was “welfare for the rich,” she wrote. “Remember, every dollar Endeavor Real Estate Group doesn’t pay in property taxes, is a dollar that will be made up through increases to your property taxes.”

During the public input portion of the council meeting, attorney Bunch pointed to the hundreds of cranes stretching across the downtown skyline, saying these threw into question the council’s justification for the TIRZ.

“There’s three words for this deal,” he said: “stink, stank, stunk.”

Public-private partnership
Steve Adler

On the other hand, backers of the TIRZ contend that the area would not develop to the same extent without the new public amenities and infrastructure. Mayor Steve Adler said, “We have land that’s undoubtedly going to develop on the South Waterfront, but unless we put in a grid system of roads, it’s not going to develop the way that it should.”

Likewise, an analysis prepared for the city in September by Capitol Market Research stated, “Without the implementation of the district plan and supporting infrastructure investment, the area will develop in a fragmented manner at significantly lower densities and taxable value.”

The total taxable value of property in the district could explode from about $1 billion today to $7.9 billion by 2040, the study said.

Much of that growth, however, would be attributable to upzoning, not the TIRZ, said attorney Lewis.

“Your own data, your own plan, is legally insufficient, and you really are subjecting yourself to the prospect of property taxpayer… litigation,” he told the council.
Richard Suttle

Yet the developers say that the full value of the area can’t be unlocked without looking at the zone comprehensively, including through public investments in a smarter street grid and public green spaces.

“I’ll tell you what, we won’t build the plan if there’s no TIRZ. It just doesn’t work. It all fits together,” said lobbyist Richard Suttle at a December 14th hearing of the Planning Commission.

Suttle, who represents Endeavor Real Estate Group and the Cox family, is seeking approval from the Planning Commission for an upzone of the old Statesman site. His clients want to build six high-rise buildings containing 3.5 million square feet of space, including 1.5 million square feet of office space, ground-floor retail, a 275-room hotel, and 1,378 residences.

Four percent of the rental units would be affordable housing.
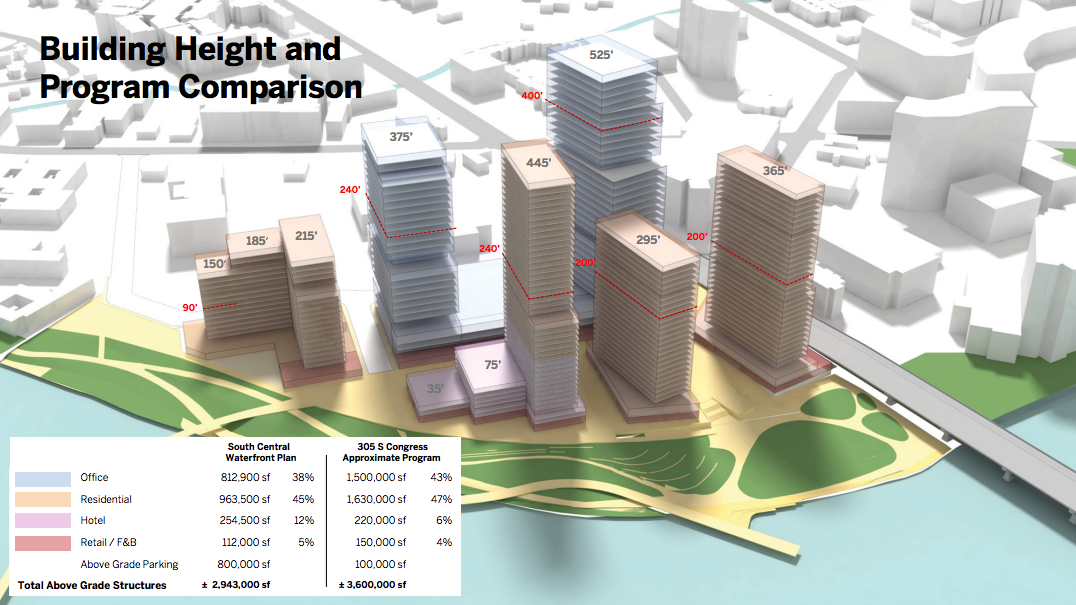
Proposed high rises at 305 S. Congress. Comparisons are to an earlier plan that called for shorter buildings.

Suttle said that his clients were prepared to donate 3.7 acres of the Statesman property for right-of-way, 6.6 acres for parks, and 1.6 acres for parkland easement. However, a prospective Blue Line rail stop at the site could reduce the amount of usable parkland, he noted.

Austin’s famous bat observation area next to the South Congress bridge would become parkland under the proposal. That site is already effectively open to the public, but only because the current owner allows it to be.

Unlike the current Statesman structure, which is surrounded by acres of surface parking, the new development would have almost no surface parking. Ninety-five percent of parking would be underground—an arrangement that city zoning chief Jerry Rusthoven called “very, very expensive.”

Rusthoven recommended that the Planning Commission approve the Endeavor proposal, noting that the developer was willing to donate about a third of its property for parkland.
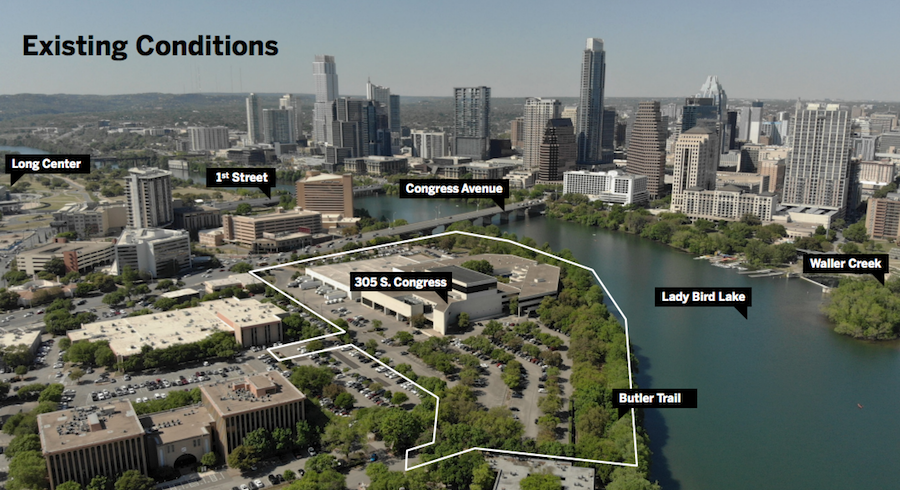
Aerial view of the current conditions at 305 S. Congress, from a developer presentation.

Buying influence

Suttle’s lobby firm, Armbrust & Brown, is a big donor to council members, as is Endeavor. As reported previously by the Bulldog, employees of those firms donated heavily to council candidates in the 2020 election cycle.

Although the city charter prohibits corporate contributions and limits campaign contributions from registered lobbyists to $25, Armbrust & Brown found a workaround by having dozens of non-registered attorneys and their spouses donate the maximum of $400 each.

A separate and subsequent analysis by the Austinites for Democracy PAC, which used a similar methodology but relied on a fuller dataset, found that “ten of the top 39 council contributors…worked for Austin’s leading developer lobby firm: Armbrust & Brown.”

Tallied together, employees of Armbrust & Brown and Endeavor contributed $92,814 to 2020 council candidates, including to winning candidates Greg Casar and Leslie Pool. Likewise, in 2018, Adler received several thousand dollars from employees of those two firms, as did Council Members Kathie Tovo and Sabino “Pio” Renteria.

This means that some of the same council members who are making decisions about the new tax zone have already benefitted substantially from campaign contributions from the firms that are lobbying for it.

Density boost

But council members may be supporting the new plan for other reasons too. The TIRZ is connected with a years-long planning process that culminated in a 114-page vision document adopted in 2016.

That document, the Austin South Central Waterfront Vision Framework Plan, reflects long-running council priorities, including a desire to boost mixed-use, pedestrian-friendly development. The area is one where significant density can be added without major pushback from nearby residents, of whom there are relatively few—in part because of the number of government and commercial buildings in the vicinity.
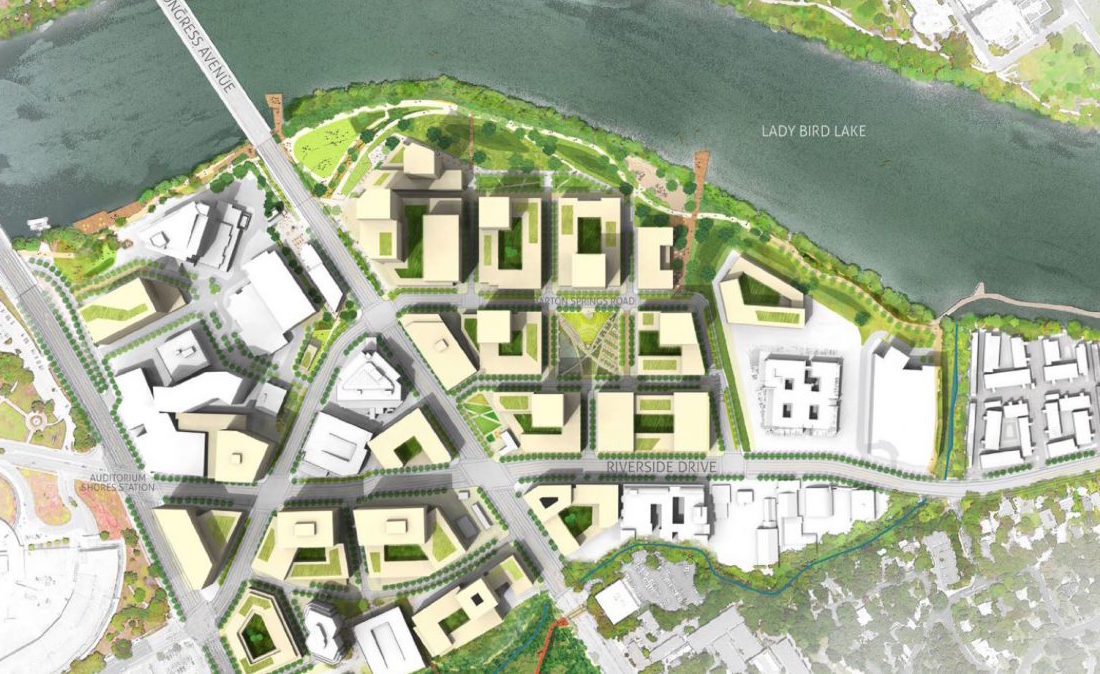
Illustrative rendering of the South Central Waterfront Framework Vision, 2016, an area that generally corresponds to the boundaries of the TIRZ (CMG Landscape Architecture).

The Framework Plan calls for a “district-wide green infrastructure system paired with quality urban design and an interconnected network of public spaces.” Key components of that would be the existing Ann and Roy Butler Trail, which runs through the district along the lakeside, and new streets that would break up the current blocks.

The plan says, “The 118 acres of the South Central Waterfront covers the equivalent of 33 downtown blocks but are only divided into a handful of superblocks… The lack of a street grid hinders an orderly development of buildings within a patchwork of private parcels.”

“Over time, the existing superblocks will be broken up into a district of pedestrian-scaled blocks.”

During his presentation to the Planning Commission, Suttle played a polished promotional video produced for the occasion. A narrator in the video touts the site as a “multi-modal hub” accessible by trail, train, road, and bike: “We’re creating a new environment for people to walk, stroll, and hang out in a vibrant, diverse, and welcoming public space that embraces our city’s culture and honors the spirit of Austin.”

Potentially, the redevelopment could eventually even include a connection to the Rainey Street District via a pedestrian bridge across Lady Bird Lake, according to planning documents. The documents did not indicate how such a bridge would be financed.

As the area develops, it is likely to draw tenants who work in the Central Business District, the University of Texas at Austin, and the Capitol complex, according to the study by Capitol Market Research.

“It is also likely that a number of tenants or condominium buyers will be downsizing empty nester households from central and west Austin, and out of town, second home buyers,” the study said.

Background on TIRZ law

The general idea behind a TIRZ is that it creates a special benefit for a particular area. Unlike taxpayers in other parts of the city, whose taxes benefit the city at large, the TIRZ taxpayers effectively get to ensure that their tax dollars are spent locally.

On account of this preferential treatment, Texas’ first TIRZ statute was found unconstitutional in an attorney general opinion in 1979, because it violated the “equal and uniform” tax provision of the state constitution.

Rather than accept this, the legislature decided to offer a constitutional amendment that would expressly authorize the zones.

Ratified by voters in 1981, and still part of the constitution today, the amendment said that the legislature could authorize cities to create tax exemptions and bond taxes in reinvestment zones “to finance the development or redevelopment of an unproductive, underdeveloped, or blighted area.”

The Office of the Attorney General has interpreted this to mean that “a city may not designate an area as a reinvestment zone…unless the area is ‘unproductive, underdeveloped, or blighted’ within the meaning of article VIII, section l-g(b) of the Texas Constitution,” according to an on opinion issued under then-Attorney General John Cornyn in 1999 and reaffirmed subsequently.

Therefore, to ensure compliance with this requirement, Austin’s new TIRZ ordinance and the accompanying project plan emphasize that the South Central Waterfront zone is “underdeveloped” and “unproductive.”

The preliminary project plan states, “Portions of the property substantially impair and arrest the sound growth of the city because it is predominately unproductive or underdeveloped due to factors such as the lack and aging of public infrastructure.”

Likewise, the South Central Waterfront Vision Framework, which dates to 2016 but is included as an appendix to the project plan, mentions the need for “findings of blight” in order to authorize the TIRZ. 

Both ‘luxury’ and ‘underdeveloped’

For an “underdeveloped” area, the South Central Waterfront is remarkably expensive for those who live and work there. For example, two-bedroom apartment at 422 at the Lake, a “luxury community” on South Congress, costs from $2,800 to $3,350, compared to a citywide average of about $1,500, according to listings on Apartments.com.

A studio apartment costs $1,922, more than some two-bedroom or even three-bedroom apartments elsewhere in the city. Similarly, a studio at The Catherine, a “luxury green apartment community” on Barton Springs Road, costs $2,520, according to listings on its website.
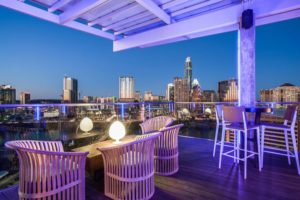
Marketing photo showing the view from The Catherine, a residential tower that would benefit from TIRZ subsidies.

One-bedroom apartments at The Catherine Tower go for about $3,000 per month, and two-bedrooms cost about $5,500, according to its website.

In terms of property values, several properties in the district are appraised in the tens of millions, including The Catherine, which is valued at $122 million, and the Embassy Suites off Barton Springs Road, which is worth $39 million, according to appraisal district records.

Even small commercial properties in the TIRZ fetch a premium. For example, a two-story, 8,500 square foot property on South Congress built in 1936, which houses the flagship YETI store, is appraised at $8.9 million.

What’s next

The council’s vote Monday was unanimous, with Council Members Greg Casar and Leslie Pool off the dais. The action establishes the TIRZ, adopts a preliminary project plan and financing plan, and creates a fund to capture property tax from the zone.

But because the council didn’t set a capture rate, the new fund will be an empty shell until the council amends the financing plan to set a rate.
Kathie Tovo

Tovo, the council member who represents the South Central Waterfront, said she wants to see action on the matter early next year. She suggested work sessions February 1st and February 17th, as needed, with final action March 2nd. “I think we should be scheduled for action,” she said.

Asked about the council’s decision to delay setting a capture rate, attorney Bill Bunch said that was likely only a temporary hold-up. “It’s never over until it’s over, but it’s likely over unless there’s an outpouring of outrage from taxpayer voters. And if there was ever a reason for voter outrage, this stinker is it.”

For his part, Adler stressed that Monday’s vote was not a final decision, saying, “We can certainly decide early next year whether or not to do a TIRZ at all, and if so, what that TIRZ should look like and include or not include.” But the mayor also said he was committed to “getting this question resolved, one way or another, as early as we can next year.”

At a previous work session in October, Adler had voiced urgency around the need to pass the TIRZ ordinance before the end of the year, saying that if council didn’t do so, the TIRZ would miss out on revenue capture until 2023. Hence why the council voted to create the zone before reaching consensus about the exact increment rate or the final project plan.

Further highlighting the political importance of the issue is the fact that the TIRZ was the only issue on the council’s agenda at the special called meeting December 20th, the final meeting of the year.

Administratively, the TIRZ will be run by staff of the Austin Economic Development Corporation. Their role now involves helping finalize the TIRZ project plan and financing plan to be approved by the council, according to Q&A posted with the council agenda. The board will consist of each of the sitting council members.

One matter they’ll have to attend to is finding a way to incorporate some funding for affordable housing into the final project plan. That’s required under an amendment to the TIRZ ordinance proposed by Tovo and adopted without objection. New housing could be set up at One Texas Center on Barton Springs Road, the only city-owned property in the TIRZ, according to council discussions, but there aren’t yet any firm plans around the idea.

The amount of available funding for projects will depend on the final capture rate. Once that rate is set, it will remain in place until 2042, or until all debt service issued by the city in connection with the TIRZ is fully satisfied. In other words, the subsidies for the South Central Waterfront could continue for a period of up to 20 years.

Law advice ignored

One outstanding issue that was tentatively resolved Monday was whether to include in the TIRZ a property known as the “Snoopy PUD,” so-called because it was formerly owned by Charles Schulz, creator of the “Peanuts” comic strip. The 1.3-acre plot on South 1st Street was home to a Hooters until 2019, when it was torn down to make room for a 15-story office tower.

Council members discussed the property extensively at a work session December 7th. At that meeting, Assistant City Attorney Leela Fireside cautioned the council against including the property because it was already recently redeveloped. Doing so might strain the legal analysis required to defend the TIRZ in court and to secure approval for bond issuance, which need to be approved by the attorney general.

“Part of the challenge with adding the Snoopy PUD…is if we can’t make the ‘but for’ analysis then we can’t use that to support the bonds,” she said.

Fireside was referring to the legal analysis required to show that development in the area would not take place “but for” the public infrastructure investments under the TIRZ.

“The attorney general’s office will look very carefully if the bonds and the improvements we’re putting in meet that ‘but for’ test. And the Snoopy PUD is already developing, so it’s very difficult to make that analysis. So that is why the economics of it and the legal analysis resulted in that exclusion.”
Alison Alter

Likewise, Council Member Alison Alter opposed inclusion of the Snoopy PUD in the zone, saying, “I don’t really understand the argument of the ‘but for’. It’s built. It’s there.” Including it “may call into question the whole TIRZ and create other hassles,” she said.

The council Monday ignored these warnings. Council staff had posted to the agenda two options for the TIRZ: one that included the new office tower, and another that didn’t. On Adler’s motion, the council voted to include the new redevelopment within the proposed TIRZ.

The development, now known as RiverSouth, is owned by Dallas-based Stream Realty Partners. During its recent redevelopment process, it was represented by Richard Suttle of Ambrust & Brown.
Trust indicators: Bulldog reporter Daniel Van Oudenaren is a journalist with 13 years experience in local, state, and international reporting.

Who funds this work? This report was made possible by contributions to The Austin Bulldog, which operates as a 501(c)(3) nonprofit for investigative reporting in the public interest. You can help support this independent coverage by making a tax-deductible contribution. Contributions made by December 31, 2021, will the TRIPLED by matching national and local partners.

Related documents

Draft council ordinance establishing TIRZ, December 20, 2021

Amendment to TIRZ ordinance, December 20, 2021

TIRZ draft preliminary plan, December 20, 2021

South Central Waterfront Vision Framework Plan, June 15, 2016
Property Logistics Specialist GLP Plans IPO for Investment Arm

Property Logistics Specialist GLP Plans IPO for Investment Arm

GLP Pte. Ltd., the world-wide professional in logistics authentic estate, is gearing up for a U.S. first general public featuring of its investment decision arm subsequent 12 months, a particular person common with the matter claimed.

GLP has employed underwriters for a probable listing of its fund-management business and could file IPO paperwork confidentially with the U.S. Securities and Trade Fee shortly, this individual stated, incorporating that the community enterprise is probably to handle about $100 billion of belongings when it launches.

Providers this kind of as carefully held GLP are benefiting from shifting world-wide intake, as buyers store far more online, driving desire for the warehouses in which shops shop and form products. The globe will include about 1.485 billion square feet of logistics area from 2020 to 2025, as worldwide e-commerce sales surge, the actual estate team

CBRE Team Inc.

CBRE 2.14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}

estimated before this year.

The listing will adhere to a reorganization combining the financial investment company with a individual, U.S.-based entity identified as GLP Capital Partners LP, or GCP, whose holdings will grow to be the U.S. portfolio of the enlarged group.

Alan Yang, who was chief financial investment officer of GLP before founding and getting to be main executive of GCP, is set to serve as chief executive of the new community company, the man or woman common with the matter explained. Ming Mei, co-founder and CEO of GLP, is established to be chairman.

Although GLP has specialised primarily in logistics genuine estate, these kinds of as industrial warehouses, the new company will also emphasis on two other progress parts, data facilities and renewable-strength infrastructure, the particular person explained.

In 2019, GLP sold a community of U.S. industrial warehouses to Blackstone Team, now recognised as Blackstone Inc., for $18.7 billion, in what was then the greatest personal actual estate transaction at any time, as well as a significant wager on the ongoing explosion of e-commerce.

GLP claimed in a firm report in August that it has 67 real estate and non-public-fairness money, and extra than $100 billion of assets less than management. Its logistics true-estate enterprise managed $61 billion of property, spanning 731 million sq. feet of area, the equal of far more than 110 Pentagon structures.

The stock supplying would mark a partial return to the public marketplaces for GLP, which delisted from the Singapore inventory trade in early 2018. It was taken private in a deal well worth about $11.6 billion excluding debt by a bidding consortium that bundled Mr. Mei and the investment teams Hillhouse Money Group and Hopu Expenditure Administration Co.

Rival Prologis Inc., which was outbid in 2019 by Blackstone for GLP’s U.S. community, has some $177 billion of property beneath management, in accordance to its web-site.

Publish to Liz Hoffman at liz.hoffman@wsj.com and Quentin Webb at quentin.webb@wsj.com

Copyright ©2021 Dow Jones & Corporation, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8

Appeared in the December 22, 2021, print edition as ‘Property-Logistics Specialist Options IPO.’

Stay Safe During the Holidays

Stay Safe During the Holidays

The holiday break period delivers to the surface area the items that issue most and it is essential to consider the techniques to safeguard them. Emergency Administration and law enforcement specialists from the Division of Public Basic safety share some tips to assist you and your loved ones continue being safe throughout the holiday seasons, new technology.

Safeguard from house fire dangers

Stay Safe During the HolidaysCandles can make for stunning decorations but can pose a fire possibility when not monitored. A lot more than fifty percent of household decoration fires in December are commenced by candles. Retain burning candles away from anything at all flammable (at least 12 inches) and never depart a candle burning in another area or when you go away dwelling. Battery-operated flameless candles are a safe choice for decorations.

Examine your smoke detectors and carbon monoxide alarms on each flooring, especially if you are expecting company. Make certain practically nothing is obstructing exits in situation of an crisis.

Heat your home safely and securely. Keep everything that can melt away (that involves Christmas trees) at minimum a few ft away from fireplaces, wooden stoves, moveable heaters and radiators. When you leave a place or go to bed, transform heaters off or unplug them.

If you have a Christmas tree, make guaranteed you water it each day. A dry tree can be a fireplace hazard.

Be safe when making ready your vacation meal

Cooking is the key cause of residence fires each year, so retain these strategies in head though whipping up your vacation feast.

  • Stand by your pan – if you leave your kitchen area, transform the burner off.
  • Watch what you’re cooking.
  • Flip pot handles towards the again of the stove to stop them from being bumped or pulled off the stove.
  • Keep a pan lid or baking sheet nearby to set out pan fires.

Typical house security

Quit deliveries
Piles of newspapers in the driveway or an overflowing mailbox is a guaranteed sign no a single is home. Quit deliveries and mail even though you are absent. It is also a excellent observe to have a trustworthy neighbor or friend test on your property while you are out. They can decide up something that could be sent and wander all over your dwelling for a swift stability verify.

Make your residence seem occupied
Use wise dwelling products to program your lights to change on when you are not at home. You can also use them to flip on a Television or to participate in new music. Sounds is a excellent deterrent for likely burglars to imagine you are at property.

Social Media Basic safety
Whilst absent on holidays or prolonged periods of time, restrict postings on social media of your absence. You may well want to keep away from “check- ins” or wait until your return right before submitting shots from your excursion.

Agenda security checks
Contact your community law enforcement office or sheriff’s workplace. Several present a dwelling security verify program for people who may possibly be absent from their households for prolonged intervals of time.

Maintain new buys out of simple look at
The getaway year provides new goodies to your household. Don’t provide focus to new buys by placing them in close proximity to home windows and inviting thieves. Also, try out to split bins down to in shape into recycling bins. By hiding the bins in the bins, no a person can see what new buys you have in your residence.

Safe and sound anywhere you are

Be harmless shopping
Although browsing Always be aware of your surroundings and check out our weblog for much more suggestions on keeping safe while shopping in-person and on the net.

Remain healthier
According to the North Carolina Office of Overall health and Human Solutions (NCDHHS), attending out of doors or digital gatherings presents a decrease danger for spreading COVID-19 than situations that are
in-individual and indoors. Due to the very contagious Omicron variant, look at staying away from huge in-human being social gatherings with people outside of your family.Vaccinating and boosting towards COVID-19 stay the most powerful techniques for folks to shield by themselves. Travel is not suggested if you are not totally vaccinated or boosted. Get examined 1-2 days prior to and 3-5 days just after traveling, and be completely vaccinated towards COVID-19, such as boosters and towards flu.

Extra Resources:

Visit : https://stpetewaterfrontrentals.com/

Home and Garden Products B2C E-commerce Market is set to Experience a Revolutionary growth by 2026

Home and Garden Products B2C E-commerce Market is set to Experience a Revolutionary growth by 2026

Industry Intellix’s newest study analyze, Residence and Yard Solutions B2C E-commerce, evaluates the market threat side assessment, highlights chances, and offers strategic and tactical determination-earning assist. The report offers info on sector developments and development, growth motorists, systems, and the modifying House and Back garden Goods B2C E-commerce marketplace . Some of the key players profiled in the study are Giardineria, Bricofer, Brico Io, Amazon, Kingfisher plc, Cfadda, Brcoman, Leroy Merlin, Flubit, e-Bay, OnBuy, Fruugo.

Get totally free entry to sample report @ https://www.marketintellix.com/sample-request/world wide-household-and-back garden-items-b2c-e-commerce-market-149241

Dwelling and Backyard Products B2C E-commerce Industry Overview:

The review gives a comprehensive outlook critical to retain industry understanding up to day segmented by Professional, House, House Decor, Back garden Products and solutions and 18+ countries across the world together with insights on emerging & significant gamers. If you want to assess unique businesses included in the Home and Yard Goods B2C E-commerce business according to your focused objective or geography we offer customization in accordance to needs.

Household and Backyard Items B2C E-commerce Industry: Need Investigation & Option Outlook 2026

Property and Backyard garden Items B2C E-commerce research examine defines the market dimensions of a variety of segments & nations by historical decades and forecasts the values for the following 6 a long time. The report is assembled to comprise qualitative and quantitative things of Household and Garden Products B2C E-commerce market which includes sector share, sector sizing (benefit and quantity 2016-2020, and forecast to 2026) that admires each individual region concerned in the aggressive market. Further more, the study also caters to and provides in-depth statistics about the important factors of Home and Backyard garden Merchandise B2C E-commerce which includes motorists & restraining things that assist estimate the potential expansion outlook of the industry.

The segments and sub-part of House and Yard Goods B2C E-commerce marketplace is demonstrated below:

The Examine is segmented by the subsequent Products/Company Sort:

  • Property Decor
  • Backyard Merchandise

Main applications/conclude-customers market are as follows:

Some of the vital gamers concerned in the Market are:

  • Giardineria
  • Bricofer
  • Brico Io
  • Amazon
  • Kingfisher plc
  • Cfadda
  • Brcoman
  • Leroy Merlin
  • Flubit
  • e-Bay
  • OnBuy
  • Fruugo

Enquire for customization in Report @ https://www.marketintellix.com/enquiry-prior to-get/world-dwelling-and-garden-solutions-b2c-e-commerce-market place-149241

Important years viewed as in the Home and Backyard garden Solutions B2C E-commerce study:

Historical year – 2016-2020 Base year – 2020 Forecast period of time** – 2021 to 2026 [** unless otherwise stated]


If opting for the Global variation of Property and Yard Products B2C E-commerce Current market then beneath state evaluation would be integrated:

  • North The usa (United states of america, Canada and Mexico)
  • Europe (Germany, France, the United Kingdom, Netherlands, Italy, Nordic Nations, Spain, Switzerland and Relaxation of Europe)
  • Asia-Pacific (China, Japan, Australia, New Zealand, South Korea, India, Southeast Asia and Relaxation of APAC)
  • South The usa (Brazil, Argentina, Chile, Colombia, Relaxation of countries etc.)
  • Center East and Africa (Saudi Arabia, United Arab Emirates, Israel, Egypt, Turkey, Nigeria, South Africa, Relaxation of MEA)

Obtain Property and Back garden Items B2C E-commerce analysis report @ https://www.marketintellix.com/buyReport?report=149241&structure=1

Essential Queries Answered with this Analyze

1) What helps make Dwelling and Backyard Goods B2C E-commerce Market possible for very long-time period financial commitment?

2) Know benefit chain regions wherever players can produce worth?

3) Teritorry that may well see a steep increase in CAGR & Y-O-Y development?

4) What geographic area would have greater demand for solutions/products and services?

5) What opportunity rising territory would give to recognized and new entrants in Property and Back garden Products and solutions B2C E-commerce marketplace?

6) Chance aspect evaluation connected with services suppliers?

7) How influencing components driving the demand from customers of Home and Backyard garden Solutions B2C E-commerce in the future couple decades?

8) What is the impression examination of numerous aspects in the Home and Backyard garden Goods B2C E-commerce industry expansion?

9) What methods of significant players assist them receive a share in a mature market place?

10) How Technological innovation and Purchaser-Centric Innovation is bringing large Transform in Property and Backyard Products B2C E-commerce Market?

Search Executive Summary and Entire Table of Articles @ https://www.marketintellix.com/report/international-residence-and-back garden-solutions-b2c-e-commerce-industry-149241

There are 15 Chapters to display the Household and Back garden Items B2C E-commerce Marketplace

Chapter 1, Overview to describe Definition, Specs and Classification of House and Backyard Items B2C E-commerce market place, Apps [Commercial, Household], Market Phase by Kinds House Decor, Garden Products and solutions

Chapter 2, objective of the examine.

Chapter 3, Exploration methodology, actions, assumptions and analytical resources

Chapter 4 and 5, Household and Garden Products and solutions B2C E-commerce Current market Craze Analysis, Drivers, Worries by buyer actions, Advertising and marketing Channels, Price Chain Analysis

Chapter 6 and 7, to show the Household and Yard Products and solutions B2C E-commerce Market Examination, segmentation assessment, characteristics

Chapter 8 and 9, to present 5 forces (bargaining power of purchasers/suppliers), Threats to new entrants and market ailment

Chapter 10 and 11, to exhibit investigation by regional segmentation [Asia-Pacific (Vietnam, China, Malaysia, Japan, Philippines, South Korea, Thailand, India, Indonesia, Australia and Others), Europe (Germany, Russia, the UK, Italy, France, Spain, Belgium, Netherlands, Switzerland, Nordic Nations, Rest of Europe.), North America (the United States, Mexico, and Canada), South America (Brazil, Argentina, Chile, Rest of South America), Middle East and Africa (GCC Countries, Turkey, Israel, South Africa, Egypt and Rest of MEA)], comparison, major countries and alternatives Customer Behaviour

Chapter 12, to establish significant choice framework gathered via Field industry experts and strategic decision-makers

Chapter 13 and 14, about competitors landscape (classification and Market place Ranking)

Chapter 15, bargains with Dwelling and Back garden Merchandise B2C E-commerce Industry profits channel, study conclusions and summary, appendix and data source.

Thanks for exhibiting interest in Home and Backyard garden Merchandise B2C E-commerce Sector Analysis Publication you can also get particular person chapter smart segment or region clever report edition like North The united states, LATAM, United States, GCC, Southeast Asia, Europe, APAC, United Kingdom, India or China and so forth

About Sector Intellix

Marketplace Intellix is an specialist in the location of worldwide sector investigate consulting. With the support of our ingenious database crafted by experts, we supply our purchasers a broad array of personalized Marketing and Business enterprise Analysis Remedies to opt for from. We assist our clients in gaining a superior knowledge of the strengths and weaknesses of many markets, as properly as how to capitalize on possibilities. Covering a vast selection of marketplace apps, We are your one-cease remedy for nearly anything from knowledge assortment to investment decision information, masking a broad wide variety of sector scopes from electronic products to the foods market.

Call Us

Sector Intellix LLP

Steven Jones

Media & Internet marketing Supervisor

Address: S.N 87/2,  Kashid Park, Close to Tresor Park, Pune, Maharashtra – 411027, India

Contact: +1 (350) 908 1001

E-mail: income@marketintellix.com

Site: www.marketintellix.com

The Best Home Improvement Loans of 2021

The Best Home Improvement Loans of 2021

The Best Home Improvement Loans of 2021

Photo: istockphoto.com

If you’re looking to perform some renovations or need to make repairs, a home improvement loan could provide the financing you need to pay for the project. However, finding the best way to finance home improvements takes a little time and research. It’s crucial to compare factors like minimum credit score requirements, maximum loan limits, and interest rates to make sure you find the best home improvement loans for your situation and needs.

The loans listed here are personal home improvement loans, so it’s important to compare any origination fees, late fees, prepayment fees, and other fees associated with each loan before applying. While a loan may look good based on the loan amount and interest rate, you don’t want to pay too much in fees. Here, we’ll break down the best home improvement loans and how to make the best decision that will pay off in the long run.

  1. BEST OVERALL: SoFi
  2. RUNNER-UP: LightStream
  3. BEST FOR SMALL PROJECTS: Marcus by Goldman Sachs
  4. BEST BANK: Wells Fargo
  5. BEST FOR FAIR CREDIT: Upgrade

The Best Home Improvement Loans Options

Photo: istockphoto.com

What to Consider When Choosing Home Improvement Loans

When reviewing the best loan for home improvement, make sure to compare the key features of each loan. These include the interest rate, loan amount, minimum credit score, and loan term. You want to compare apples to apples to ensure you find the best way to pay for home improvements. Comparing the fees to obtain the loan is crucial when shopping for the best home renovation loans.

Prequalification and Application

Some, but not all, lenders allow borrowers to prequalify for a home improvement loan, which could give them an idea of how much they may qualify to receive, how much their monthly payment could be, and what the repayment terms might be. To do so, borrowers will need to provide such personal information as name, address, birth date, Social Security number, and income. They also may be asked how they plan to use the loan funds. Prequalification may take a few minutes or possibly longer. If borrowers are prequalified, the lender will use their prequalification information as part of the application.

When prequalifying for a loan, it’s essential to know if the lender will complete a soft or hard credit check. Soft credit checks won’t affect a borrower’s credit score, but a hard check will. Mortgages typically involve a hard credit check, but smaller personal loans like home improvement loans often only require a soft check.

The loan application will contain much of the same information a borrower would provide to prequalify. This includes the personal information listed above, as well as proof of identity, bank statements, and pay stubs. Reviewing and approving your application may take longer than prequalification.

Credit Score

Every lender has its own benchmark for the minimum credit score required to qualify for the best loans for home improvement. While many lenders prefer a minimum credit score of 660, especially if you want a mortgage-backed loan, some companies will accept a lower credit score. The trade-off is that interest rates may be higher than for borrowers with a higher credit score. A general rule is that the higher a borrower’s credit score, the lower their interest rate.

Suppose a borrower is seeking a home improvement loan that is unsecured, such as a personal loan. In that case, lenders also prefer borrowers with higher credit scores because those borrowers appear to be more likely to repay the loan as agreed.

Loan Amount

Not all home loan lenders offer the same loan amounts. Therefore, borrowers need to determine how much the project will cost so they have a firm amount on how much they need in a home improvement loan. Once they have this information in hand, they will need to shop around to find lenders willing to match the amount they need. Eliminating lenders who are unable or unwilling to offer the loan amount they need will help narrow down the selection of lenders, which can be helpful when they are shopping for the best home improvement loans.

Rates and Fees

When reviewing the terms of a home improvement loan, one key feature to look at is the annual percentage rate (APR). The APR is the amount someone pays for borrowing the money. It includes the interest rate as well as all additional fees.

Origination fees are associated with opening a new account with a bank or broker. Borrowers can incur prepayment fees if they attempt to pay off the entire loan amount before the loan terms are over. Lenders want to keep collecting interest for as long as possible, so longer loan terms are more favorable for them. Other fees can include those for loan processing, late payments, or insufficient funds.

The lower the APR is on a loan, the less the borrower will pay over the life of the loan. The APR is based on several factors, most notably credit score and income. Typically, the higher a borrower’s credit score, the lower the APR. Also, a higher income can result in a lower APR because it shows someone has the means to repay the loan as agreed.

Repayment Terms

When it comes to repaying a home improvement loan, term lengths vary based on the lender as well as a borrower’s creditworthiness. The typical repayment term for a home improvement loan is between 1 and 7 years with monthly payments. The better a borrower’s credit score, the better their repayment terms typically will be.

It’s essential to check the repayment terms to see if the borrower will incur a prepayment penalty if they decide to pay off the loan early. The amount of a prepayment penalty may be more costly than if they just pay off the loan as agreed.

Discounts

Although not all lenders offer discounts, some do when a borrower takes out a home improvement loan. For instance, some lenders will offer a discount if they sign up for its autopay service to automatically pay the monthly loan payment. If a borrower is a current customer with a bank or lender, they also may qualify for a loyalty discount. It’s important to ask any lender what discounts are available. Often, this information is not readily available, so it’s important to be proactive and ask directly about discounts. Otherwise, a borrower could miss out on additional savings, even on the best home improvement loans.

Our Top Picks

To help you find the best home improvement loans, we compared loan terms and other factors to find the best way to finance home improvements.

The Best Home Improvement Loan Option: SoFi

Photo: sofi.com

Why It Made the Cut: Unlike many other traditional financial institutions, SoFi offers borrowers the option for prequalification, boasts competitive interest rates, and eliminates late fees, prepayment fees, and origination fees.

There’s a lot to like about a home improvement loan from SoFi. The company offers loans with limits as high as $100,000 with no late, prepayment, or origination fees. Unlike many other lenders, SoFi offers prequalification without a hard inquiry so you can get an idea of what loan amount you could receive as well as possible loan terms without hurting your credit score.

While SoFi offers competitive interest rates, a borrower likely will need a good credit score to receive a home improvement loan at reasonable rates. Currently, SoFi requires a minimum credit score of 680, which could be a lofty goal for some borrowers. That being said, SoFi is still a top lender to consider for home improvement loans.

Specs

  • Prequalification offered: Yes
  • Minimum credit score: 680
  • Loan amount: $5,000 to $100,000
  • APR: 4.99 to 19.63{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Term: 2 to 7 years

Pros

  • No late, prepayment, or origination fees
  • Borrowers can prequalify with a soft credit check
  • Unemployment protection for borrowers
  • Competitive interest rates

Cons

  • Higher minimum credit score of 680 required
The Best Home Improvement Loan Option: LightStream

Photo: lightstream.com

Why It Made the Cut: LightStream prides itself on offering loans to borrowers with a strong history of financial responsibility and good credit across multiple account types.

LightStream offers a variety of loan products, including home improvement loans, with competitive interest rates. Borrowers have the option to apply online or use the app and could receive their funds the same day if their loan application is approved before 2:30 p.m. EST. If a borrower signs up for autopay before receiving the loan, they could receive a 0.5 percent discount on the loan. Also, through its Rate Beat Program, LightStream will offer a rate .10 percentage points lower than a competitor’s rate provided certain conditions are met.

However, it could be hard for some borrowers without an extensive credit history to qualify for a LightStream home improvement loan. The lender looks at credit history to see if the borrower has various accounts, including credit cards, installment loans (such as a car or student loan), and a mortgage loan. For borrowers who meet these requirements, though, LightStream is a great option to consider.

Specs

  • Prequalification offered: No
  • Minimum credit score: 660
  • Loan amount: $5,000 to $100,000
  • APR: 4.49 to 20.49{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Term: 2 to 7 years

Pros

  • Borrowers receive a 0.5 percent discount for using autopay
  • Same-day funding available for loans approved before 2:30 p.m. EST
  • Rate-matching program for eligible borrowers

Cons

  • Loan approval requires several years of credit history with multiple account types
The Best Home Improvement Loan Option: Marcus by Goldman Sachs

Photo: marcus.com

Why It Made the Cut: Marcus by Goldman Sachs offers decent loan terms to borrowers with a minimum credit score of 660 and even provides prequalification with a soft check, so a borrower’s credit doesn’t get dinged.

If a homeowner is planning a small-scale home renovation, Marcus’s $40,000 loan limit may be more than enough to finance the project. Marcus by Goldman Sachs does offer prequalification with a soft credit check, so they can see what a borrower’s loan terms may be without hurting their credit score. And if a borrower makes 12 consecutive payments, the lender allows them to defer one payment, which could be helpful if money gets tight during the life of the loan. The company will also allow borrowers to consolidate debt with third-party creditors—a unique feature among financial institutions.

Marcus by Goldman Sachs also doesn’t offer the option of having multiple borrowers on one loan, so homeowners may not benefit from a cosigner with a great credit score. However, if the loan terms work for the home improvement a borrower is planning, Marcus by Goldman Sachs is a worthy lender.

Specs

  • Prequalification offered: Yes
  • Minimum credit score: 660
  • Loan amount: $3,500 to $40,000
  • APR: 6.99 to 19.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Term: 3 to 6 years

Pros

  • Direct payments to third-party creditors for debt consolidation available
  • Borrowers can prequalify with a soft credit check
  • Borrowers can defer one payment if they make 12 consecutive payments

Cons

  • Multiple borrowers are not allowed on one loan
The Best Home Improvement Loan Option: Wells Fargo

Photo: wellsfargo.com

Why It Made the Cut: For those who want to bank with an established financial institution, Wells Fargo offers a lot of flexibility for borrowers looking for a home improvement loan—and existing customers may benefit even more.

When shopping with Wells Fargo for a home improvement loan, expect a lot of flexibility in loan terms and limits, with a minimum loan amount of $3,000, a maximum loan amount of $100,000, and a minimum 1-year repayment window. In addition, borrowers who already do business with Wells Fargo may receive discounts on their loans.

Currently, only existing customers can apply for a home improvement loan online. All others will need to visit a brick-and-mortar location to complete an application, which may not be convenient for all borrowers. Of course, many borrowers like the option of meeting face-to-face with Wells Fargo associates, which many other lenders don’t offer.

Specs

  • Prequalification offered: No
  • Minimum credit score: Not specified
  • Loan amount: $3,000 to $100,000
  • APR: 5.74 to 19.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Term: 1 to 7 years

Pros

  • Flexible loan amounts and lending terms available
  • Borrowers can visit brick-and-mortar bank locations
  • Discounts available for existing customers

Cons

  • Online application is only available for existing customers
The Best Home Improvement Loan Option: Upgrade

Photo: upgrade.com

Why It Made the Cut: If a borrower’s credit history is not in the best shape and they have a lower credit score, Upgrade could be the right lender to provide them with a home improvement loan.

A new player in the lending industry—Upgrade was founded in 2017—Upgrade seeks to offer affordable and responsible loans, including home improvement loans. For borrowers with lower credit scores, this could be especially beneficial given they need a minimum credit score of only 560 to qualify. If they already have an Upgrade checking account, they also could qualify for a discount on their home improvement loan.

Upgrade offers a wide APR range that tops out at 35.47 percent, which could negatively impact borrowers with a low credit score. In addition, Upgrade loans also may include several fees, including origination fees, late fees, and insufficient funds fees. However, Upgrade is still a great choice that opens the door for more borrowers to make improvements to their homes.

Specs

  • Prequalification offered: No
  • Minimum credit score: 560
  • Loan amount: $1,000 to $50,000
  • APR: 5.94 to 35.47{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Term: 2 to 7 years

Pros

  • Borrowers need a minimum credit score of 560
  • Small loan amounts available
  • Discount available for borrowers with Upgrade checking accounts

Cons

  • Wide APR range
  • Borrowers may incur origination, late, and insufficient funds fees

Our Verdict

When shopping for the best home improvement loans, SoFi comes out on top because it doesn’t charge a lot of fees and offers competitive interest rates. LightStream is our runner-up thanks to its rate-matching program and the possibility of same-day funding if approved.

How We Chose the Best Home Improvement Loans

To determine the best home improvement loans, we reviewed several factors for each lender, including minimum credit score requirements, available loan amounts, APRs offered, loan terms, and whether prequalification was offered. We also checked to see what, if any, fees were charged as well as possible available discounts. In addition, we looked to see if lenders offered added benefits to borrowers, such as unemployment protection, same-day funding, and online servicing. Each lender also was reviewed based on its brand reputation. This curated list was developed from extensive research, but your individual loan experience may vary from the information shared here.

Before You Choose One of the Best Home Improvement Loans

The most straightforward avenue is to pay cash if you’re starting a home improvement project. However, not everyone has the money in hand to pay for a large bill, or paying for the project up front might jeopardize a homeowner’s quality of life for a period. That’s where home improvement loans can be helpful tools.

When trying to decide what type of loan is best for home improvements, it’s important to note that not all home improvement loans fit every borrower’s needs or financial situation. In fact, a home improvement loan may not even be the right choice to pay for home renovations. For instance, if a homeowner doesn’t need a considerable loan amount, they may do better by finding the best credit card for home renovation. Credit cards are simpler to obtain, but they may incur higher interest rates, even with one of the best credit cards for home improvement. And since monthly expenses can, using a credit card can result in ongoing debt that might be difficult to pay off.

On the other hand, if a homeowner needs a large loan amount, a home equity loan or home equity line of credit might offer them a better interest rate and longer loan term than even the best home improvement loan. Home equity loans are secured, though, meaning the lender has collateral if a borrower defaults on payments. This means that the stakes are higher, and if a borrower runs into a situation where they can’t make their payments, the lender could levy their home.

Cost of Using One of the Best Home Improvement Loans

Before signing on the dotted line for one of the best home improvement loans, it’s important to review the costs of the loan. In addition to the interest rate on the loan, many lenders also charge hefty fees that add to the cost of the loan. For instance, some lenders charge origination fees ranging between 1 and 8 percent of the loan amount. Other expenses could include late payment fees, insufficient funds fees, prepayment penalties, and additional fees that will add to the cost of the loan. The total amount of these fees could make one of the best home improvement loans more costly than other financing options available to pay for home improvements.

The Advantages of Using One of the Best Home Improvement Loans

Using one of the best home improvement loans could be the most affordable option for paying for the improvements or repairs a home needs without having to pay a daunting amount of money up front. There are some benefits to choosing a home improvement loan, including:

  • Repairs and upgrades can increase a home’s value. Remodeling the kitchen, refinishing hardwood floors, and adding landscaping have some of the best returns on investment.
  • Homeowners don’t have to wait to save up money to make repairs, causing the situation to worsen and become costlier the longer it’s left untreated.
  • Personal home improvement loans have fixed monthly payments, so homeowners can budget accordingly and know exactly how much they’re paying.

FAQs

When shopping for the best home improvement loans, it’s essential to know exactly what you are shopping for regarding interest rates, loan amounts, loan terms, and minimum credit score requirements. Having this knowledge beforehand could save you valuable time when talking to lenders. It also could provide insight on how to improve your financial situation before applying for any loan.

Q. What kind of loan should I get for home improvements?

A personal home improvement loan could provide the best way to pay for home improvements. But the type of loan a borrower opts for will ultimately depend on the extent of the renovations. For example, an FHA 203(k) rehab loan might be better if a borrower is buying a fixer-upper and needs to complete extensive, whole-home remodeling. Borrowers might benefit from one of the best home improvement credit card options for small-scale projects.

Q. What credit score do I need to qualify for a home improvement loan?

Many lenders require a minimum credit score of 660 to qualify for a home improvement loan, although some lenders may have lower or higher minimum requirements.

Q. Are home improvement loans tax-deductible?

If your home improvement loan is secured by your home, such as with a home equity loan or home equity line of credit, the interest and fees on the loan could be tax-deductible.

Q. Do banks offer home improvement loans?

Yes, many banks like Wells Fargo offer home improvement loans. Some banks offer discounts for existing bank customers, and some borrowers may prefer consolidating their loans and accounts to one financial institution. However, borrowers should compare the rates and terms of bank loans against other lenders to ensure they’re getting the best deal.

Should renters get first dibs in Bay Area real estate deals?

Should renters get first dibs in Bay Area real estate deals?

As the Bay Area grasps for new ways to quell its affordable housing scarcity, a number of towns are contemplating controversial guidelines that would give some tenants a shot at acquiring their houses — a go that is sharply dividing house homeowners and renters.

To avoid massive-pocketed buyers from scooping up houses, increasing rents and forcing tenants out, East Palo Alto, San Jose, Oakland and Berkeley are eyeing ordinances that would give renters, nonprofits or the city very first dibs on some gross sales. Acknowledged as prospect to order acts, the ordinances have been heralded by tenant legal rights advocates as a way to give renters a leg up in the overheated housing industry. But the thought faces solid opposition from some landlords and actual estate groups who argue they characterize an unconscionable interference in the rights of house house owners.

“It’s heading to be a battle,” stated Sandy Perry, a board member of the South Bay Local community Land Trust, which seeks to invest in residential structures and transform them to affordable housing. “We’re battling against the genuine estate marketplace, which does not want this to occur. But I assume it is a excellent option. It’s an chance to do something incredibly concrete in opposition to this wave of displacement that is however likely on in San Jose and in Silicon Valley.”

SAN JOSE, CA – DECEMBER 15: Community associates just take component in a rally for a San Jose Local community Chance to Purchase Act or “COPA” at town corridor on Wednesday, Dec.15, 2021, in San Jose, Calif. (Aric Crabb/Bay Location Information Team) 

The proposals range, but commonly they require homeowners of multi-device rental homes to notify the tenants in their developing, capable economical housing nonprofits and/or the metropolis if they intend to sell. If none of those groups develop an present the vendor finds suitable, the seller can list the property on the open current market. Immediately after selecting the ideal give, the seller then requires to give the tenants, nonprofits or the city the chance to match it. If that takes place, less than East Palo Alto’s proposed ordinance, the operator would have to sell to whoever matches the give. The buyer would be prohibited from increasing rents past a sure stage.

Underneath the design San Jose is workshopping, the proprietor would get the final say in deciding on the consumer.

The San Francisco Group Land Trust is in the process of acquiring its initially two buildings underneath the city’s two-calendar year-aged purchase act — 40 models in the Tenderloin and four in Russian Hill. But even though the city’s ordinance gave the land rely on an unprecedented opportunity to contend with company investors, it is hard for nonprofits to locate the cash to close discounts, reported Keith Cooley, director of asset administration for the land have confidence in. Other towns weighing opportunity to invest in functions are contemplating coupling them with town resources.

At an East Palo Alto Town Council meeting earlier this thirty day period, heated debate over the city’s proposed order act lasted right up until midnight, forcing council members to postpone their vote. Opponents called the proposed ordinance unconstitutional and reported it amounted to a “hostile takeover” of people’s residences, even though supporters said it might be their only suggests of at any time obtaining home. The City Council is established to revisit the item Wednesday.

EAST PALO ALTO, CA – DECEMBER 19: Group member Caroline Tang, centre, usually takes component in a rally opposed to “Opportunity to Purchase” or “OPA” ordinances at city corridor on Sunday, Dec. 19, 2021, in East Palo Alto, Calif. (Aric Crabb/Bay Area Information Group) 

Jennifer Liu, vice president of the homeowner-concentrated Small business and Housing Community, problems that East Palo Alto’s plan will prevent house owners from marketing to tech providers or their personnel and obtaining the very best price tag achievable. She also concerns the ordinance will lavatory down revenue in months of purple tape.

“Those are my life time personal savings for my retirement,” Liu claimed of her actual estate investments. “So my issue is that later when I require the dollars and I require to offer it, I cannot provide it. And the cost would be discounted because of this plan. I am deeply anxious.”

The ordinance wouldn’t impression a substantial amount of product sales in East Palo Alto, in accordance to a town analysis. Owner-occupied solitary-relatives houses, duplexes and triplexes would be exempt. Based on historic income information, less than 23 solitary-family properties and 7 multi-device buildings would be matter to the ordinance just about every year.

In Oakland, a team of tenants final week convinced their landlord to sell their Fruitvale setting up for $3.3 million. The Oakland Community Land Believe in is poised to obtain it and support the tenants turn out to be partial proprietors. But the process took more than two a long time of rent strikes and protests, which includes a current procession to the landlord’s dwelling.

ALAMEDA, CA – DECEMBER 16: Dressed as Joseph, Leonard Miller, of Boulder Creek, and his donkey Sally put together to sign up for a procession of apartment tenants, touring to the home of their building’s proprietor in Alameda, Calif., on Thursday, Dec. 16, 2021. With the help of a land rely on, the tenants have been trying to obtain their apartment developing in Oakland for the previous couple yrs. Organized by the Alliance of Californians for Community Empowerment, the procession replicated a standard “posada,” which commemorates the journey of Joseph and Mary from Nazareth to Bethlehem in search of a harmless refuge. (Ray Chavez/Bay Location Information Group) 

Advocates say an chance to purchase ordinance could have made the system less difficult. And if one particular is passed, it could open up up the prospect to purchase for additional tenants.

“This is anything that more than a 10-12 months period, I assume it could have a radical effect,” said Leah Simon-Weisberg, authorized director for the Alliance of Californians for Community Empowerment.

Oakland has been toying with the thought of an option to order act given that early very last year, spurred by the activist group Moms 4 Housing, which skyrocketed to countrywide fame when customers began squatting in a vacant house with their kids. Progress stalled through the pandemic, but Councilwoman Carroll Fife programs to bring the notion back for a vote subsequent slide.

In Berkeley, Mayor Jesse Arreguín set discussions all-around a proposed tenant possibility to invest in act on keep, immediately after major pushback. The town expects to existing an up-to-date version early following 12 months.

SAN JOSE, CA – DECEMBER 15: Community members just take section in a rally for a San Jose Local community Prospect to Obtain Act or “COPA” at metropolis corridor on Wednesday, Dec.15, 2021, in San Jose, Calif. (Aric Crabb/Bay Location Information Group) 

San Jose housing officers also are performing on an ordinance and be expecting to carry it ahead of City Council following spring.