South Florida has extended been a magnet for New York real estate gamers. And when most New Yorkers make a move on the regional market place, they do it in design: With loads of ballyhoo in hopes that even the smallest promotions and tasks turn into the talk of the town.
The Damaghis are not most New Yorkers.
The Great Neck family members has amassed developable sites across South Florida. Even though some of its investments have surpassed people of New York’s real estate royalty, the family’s bargains have remained clandestine.
“They have got some genuinely phenomenal property,” a resource reported. “But some folks just want to preserve it peaceful.”
The Damaghis — designed up of husband-and-wife Nasser and Shahnaz Damaghi and their kids Nader, Kambiz and Babak Damaghi — aren’t complete-time authentic estate players. Nasser and his sons founded paper products and individual care items maker Initially Excellent Enterprises in 1988, which has grown to employ much more than 4,000 employees at minimum 7 services across the U.S. and Canada.
True estate is extra of a aspect gig. The Damaghis have paid out $182.2 million across 15 bargains for developable land according to a information investigation by The Actual Deal.
TRD discovered the household in November as the buyers who dropped $50.8 million on 2.7 acres south of Brightline’s MiamiCentral downtown passenger prepare station as a result of sources acquainted with the deal. State documents for the limited legal responsibility company that produced the obtain really do not explicitly tie the Damaghis to the offer. Neither the family’s identify nor addresses for 1st Quality’s offices or a person of the family’s Excellent Neck properties are shown in the filings. But the documents do record 1 human being of interest: Moshe Oppenheim.
Turns out, Oppenheim is the clue to the Damaghis’ other holdings.
Muzzled
9 entities registered to Oppenheim — the family’s longtime attorney — bought the bulk of the homes from 2019 to 2022.
The Damaghis are powering the bargains, according to numerous sources, nevertheless no a person wanted to converse on the report or even at all, citing the family’s demanding instructions to continue to keep them off the radar. ”Real tough” to communicate about the loved ones, just one source stated they are “very personal,” other individuals held repeating.
Though unwilling, some did budge, presented they continue to be nameless. They explained the family’s true estate perform as a “long-term generational investment.” A different supply revealed that the purchases ended up all hard cash — in fact, no mortgages are recorded on the serious estate. And other individuals stated the Damaghis have searched for additional South Florida investments as not too long ago as last calendar year.
In Fort Lauderdale’s booming Flagler Village community, the spouse and children owns nearly 5 acres on 3 websites: land on the northeast corner of Northwest Flagler Push and Next Avenue, on the southeast corner of Next Street and Northwest Initially Avenue, and straight away west of the federal courthouse at 299 East Broward Boulevard.
South of there, they have amassed the block fronting the New River on the northeast corner of South Andrews Avenue and Southeast Fifth Avenue. They also own nearby parking heaps and tiny industrial buildings, which are likely candidates for redevelopment.
But the family’s to start with investment decision was in Miami in 2013 when they bought a complete metropolis block of land in Edgewater, involving Northeast 32nd and 33rd streets, together the east aspect of Biscayne Boulevard. This is the only non-concealed offer, as the getting entity lists Kambiz Damaghi in state data.
Their other Miami site is the downtown land south of the Brightline station, which has approval for a pair of combined-use household towers with 2,007 models and spanning 4 million square toes.
The family has selected several parcels for growth and are “assessing the opportunities” but can’t share far more specifics until eventually the assignments are released, Oppenheim wrote in an emailed reaction to a record of concerns.
For the Damaghis, stealth method is nothing new, as they have been opaque about their private life. Very first Quality’s website and LinkedIn say loads about the company’s heritage but make no point out of its house owners. In its place, tying the loved ones to the organization is additional effortlessly carried out by reading
posts published in 2019 and past year by Pennsylvania’s The Specific Lock Haven about Kambiz Damaghi’s speeches to the neighborhood chamber of commerce.
Temple Israel of Wonderful Neck’s annals also clearly show the Damaghis have been embedded in the region’s Jewish local community. In 2012, the temple’s The Voice publication declared a bar mitzvah for Nader and Mitra Damaghi’s son. Kambiz Damaghi has also been shown on the board of trustees for the Sephardic Heritage Alliance for 2017-18. As a result of Oppenheim, the family members agreed to present a minimal about its history for this story, and stated they are accomplishing it expressly for the sake of precision. In 1978, Nasser and Shahnaz remaining Iran for the duration of the revolution with their sons to escape persecution. Even though information show the Damaghi spouse and children includes a lot of cousins, uncles and other kinfolk, it’s Nader, 61, Kambiz, 59, and Babak, 53, who guide 1st High-quality as co-CEOs — and who are buying up South Florida authentic estate
Just one issue the loved ones hasn’t concealed so nicely is its penchant for palatial homes in Fantastic Neck’s affluent Kings Place.
In 2004, Babak and his spouse, Farhnaz, paid $12.8 million for the late comedian Alan King’s dwelling at 40 Shore Push, in accordance to records. Fronting Manhasset Bay, the home was built in 1926 in a combination of Tudor and gothic styles, and by 2012, the couple experienced replaced it with a Colonial-model châteauan measuring extra than 15,000 square toes. They marketed it in 2017 for $22 million, documents show.
Nader and Mitra have been nearby neighbors. They paid $7.1 million in 2002 for the 10 Shore Push manse, which four a long time afterwards they changed, also with a Colonial-type castle that spans a lot more than 10,000 sq. feet on 2 bayfront acres. The pair bought it in 2017 for $20 million, record demonstrate.
As for Kambiz and Haleh’s abode at 26 Dock Lane, they sold it in 2017 for $14 million,
but not just before litigation gave a glimpse of their way of living in the house totaling a lot more than 14,000 square toes.
The couple experienced a 14-person employees of housekeepers, groundskeepers, cooks, personalized assistants and security, according to a 2013 lawsuit filed towards them by previous estate supervisor Christopher Marconi.
Marconi claimed he was illegally fired four months in on the occupation partly in excess of increasing problem with Haleh’s personal assistant’s allegedly racist remarks to household employees. In a non-public meeting, Kambiz advised Marconi to “back off” his thrust to get the assistant fired, insinuating that Kambiz and the assistant had been “sexually intimate” and she had texts that “‘could be perceived’ as inappropriate by Haleh,” in accordance to the lawsuit. Marconi, who could not be achieved for remark, missing, however his implication of an extramarital affair struck a chord with Kambiz.
“That is pretty, extremely erroneous and inappropriate to even suggest,” Kambiz reported for the duration of a deposition, contacting the allegation “shameful,” “despicable” and saying it places his “honor in question”.
New M.O.?
When Miki Naftali and a husband or wife dropped $40.5 million for a Miami Worldcenter development web page final March, information releases flooded journalists’ inboxes with announcements for a pair of supertall residential towers. Namdar Team, also based mostly in New York, also did not shy absent from announcements about its prepare for a 41-tale and a 43-story condominium towers, also in downtown, last August.
But when TRD attained out to the Damaghis in November about their purchase of the improvement web site south of Brightline’s station, a member of the loved ones vehemently denied they ended up the customers and did not want to deliver his first name.
No matter whether the Damaghis’ growing existence in South Florida, in which producing excitement over genuine estate promotions is just as much part of the activity as the precise expense, will push them to abandon their mysterious means continues to be to be observed.
They have, even so, proven signals that they could be rethinking their lengthy-held modus operandi.
In a stick to up get in touch with with Oppenheim, he explained the Damaghis’ arrangement to respond to TRD’s queries in an e mail as “a 1st.”
Part 1 focused on “Home Stocks,” meaning those that I would be happy to buy now and hold indefinitely, like a home. They were Brookfield Corporation (BN), Brookfield Asset Management (BAM), Dream Unlimited Corp. (DRM)(OTCPK:DRUNF), Topicus (OTCPK:TOITF), and SSC Security Services Corp. (SECU)(OTCQX:SECUF). These are stocks commonly referred to as “compounders,” meaning they grow reliably, profitably, and over long periods of time. If the stock market were to close for ten years, Home Stocks I would not worry about.
Like those stocks, “Investment Property Stocks” are growing profitably, but have some sort of drawback and that make them less attractive over the long term. This drawback is made up for by a large, temporary dislocation between price and value, providing an attractive risk/reward that could result in a large return over a relatively short period, anywhere from one to five years. When the stock’s price gets close to its value, I’ll consider selling for a nice gain. Thus, they are Investment Property Stocks, not Home Stocks.
Currently, I find Nuvei Corp. (NVEI), a Canadian mid-sized e-commerce payments company, Alibaba (BABA), China’s pre-eminent internet stock, and Reitmans (RET)(RET.A)(OTCPK:RTMAF), a Canadian women’s fashion retailer, to be attractive Investment Property Stocks. All have something going against them which dissuades me from holding over the long term, but enough going for them and a large enough margin of safety that I believe they can make very nice gains in the next one to five years.
Investment Property Stocks
Nuvei Corp.
Nuvei Corp. is a mid-size Canadian fintech (~$4-5B market-cap) specializing in merchant services; it essentially has a top-of-the-line modular “everything platform” for merchants. I go into greater detail here but a shorter version follows.
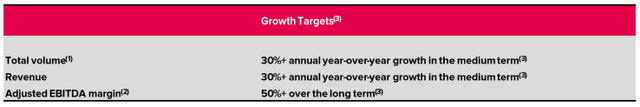
Nuvei specializes in payment solutions for online regulated gaming (gambling and sports betting), a fast-growing segment as Canadian provinces and US states legalize the industry, and e-commerce generally, which represents almost 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their revenue. Nuvei is quickly diversifying however, most recently they acquired Paya Payments, a B2B payments provider, the details of which I cover here. In addition, the CEO owns 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of shares, and upon its IPO employees each received a stake in the company worth $100,000, creating significant insider-ownership. Management projects sales to grow at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually over the next few years with adjusted EBITDA margins increasing up to 40-50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, a call that was recently reiterated in a press release. Nuvei has competitive technology, huge growth in sales and margins, and owner-operators; it meets my normal qualifications of a quality stock.
Nuvei’s growth outlook (Nuvei’s Q3 Earnings Report)
Despite these positives, Nuvei trades at 11x trailing free cash flow. The reasons for this are not perfectly clear, but here are a few possibilities.
Payments companies generally are down huge due to recession fears caused by interest rate hikes and inflation. Companies operating in cyclical sectors like e-commerce and online gaming are even more affected. Nuvei was also exposed to crypto payments, which crashed hard in 2021, bringing Nuvei’s share price with it. The exposure is not huge, but the mere association was enough to hurt the stock.
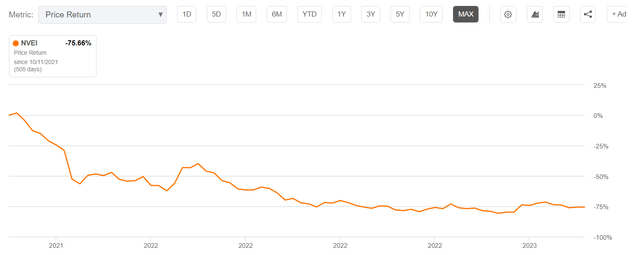
Additionally, Nuvei was one of the prime beneficiaries on the pandemic bubble, a lot of its growth was brought forward, and its share price skyrocketed beyond what anybody could consider reasonable, and thus became the target of a short seller’s report. Many of the allegations were rebutted, but the share price didn’t recover. More concerning is the CEO’s relative youth, reflected in how much he pays himself (a lot), and that Nuvei pays presumably large amounts to sponsor an F1 team. I fail to see how such a sponsorship benefits shareholders, but doesn’t break my thesis on the company, though it is inconvenient.
Nuvei’s return since its IPS – Not pretty! (Seeking Alpha)
Lastly, bringing forward growth also had the effect of creating impossible comps year over year, indeed Nuvei’s sales this year are up only single digits over last year. Considering they doubled sales in 2021, simple staying flat is quite the feat, and puts management’s forecasted 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} medium-term sales growth seem far less ambitious than it appears. It also probably didn’t help that they converted their net cash position to a net debt position to acquire a company; it isn’t the market for that. Overall, I view most of these factors as temporary impairments to the stock, and therefore signify a potential opportunity.
Most importantly for me, and why this stock is not a long-term hold, is competition. In the payment services world, a company is only as good as its technology developers and sales team; there is no moat, or even picket fence, keeping others out of the business castle. Nuvei’s peers are Stripe (STRIP), Block (SQ), Europe-based Adyen (OTCPK:ADYEY) and to a lesser extent online payments companies like PayPal (PYPL). All are worth 10s of billions and with significant resources; competition is clearly formidable.
That said, Nuvei is currently much smaller than they are so need to take less market share to see gains, has competitive technology, is building a direct sales team with a former Mastercard exec at its head, has a niche and early movers advantage in online gaming payments, and is priced for the apocalypse, while its competitors are priced for a recession. The lack of durable competitive advantage is made up for by these redeeming factors, but especially by valuation.
A cursory glance at the stock suggests it is expensive because it has a high PE ratio, but if we skip to the cash flow statement, we see that Nuvei gushes free cash flow. Gross margin is above 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, operating cash flow margin is regularly above 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and free cash flow around 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Due to operating leverage, where little capital is required to provide more services, margins even have room for expansion. These are levels are profitability beyond even Microsoft.
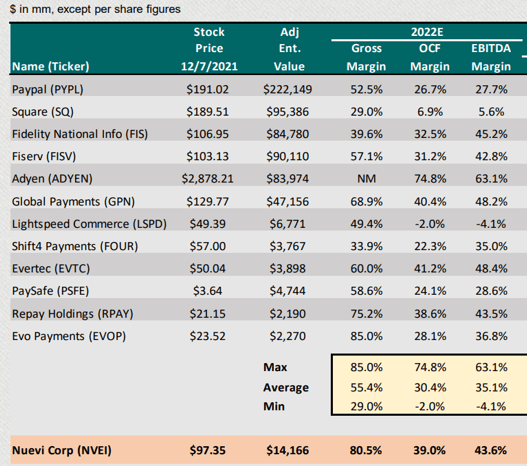
To be honest, my “too-good-to-be-true” sense is tingling, and I’m not the only one. In the short seller’s report, they made a list of comparable fintechs and their profitability. Most of the report was, from my perspective, ad hominem hearsay, but the following breakdown was useful:
Note to Canadian investors, Lightspeed gets more press than Nuvei, but isn’t even profitable. (Short Seller’s Report)
A close look will reveal that Nuvei is about as profitable as a fintech can be and far above average. This could be concerning, but comfortingly for me, there are other companies that are similarly profitable so Nuvei is not a clear outlier. Adyen for example, its closest peer, has operating cash flow and EBITDA margins much higher. This chart is useful for industry comparisons as well, which I’ll leave to the reader to peruse. In my opinion, the probability that Nuvei is cooking the books is low, though I am wary.
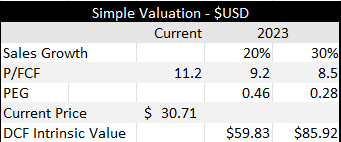
Nuvei is tremendously profitable, and, as the table below shows, the market is strongly discounting this fact, assigning it an 8-9x forward P/FCF multiple, half the average of information technology stocks according to Seeking Alpha. Nuvei should perhaps demand even more than average as it is a quickly growing fintech stock with huge margins and operating leverage.
Two different growth scenarios and their impact on the valuation of Nuvei. Both suggest Nuvei is substantially undervalued (Author’s Calculations)
As we can see, the stock is at least 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} discounted from conservative fair value, assuming management’s medium-term outlook of 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual sales growth is high by 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a year. If it’s not, and Nuvei does manage to grow sales at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually while maintaining or growing current margins, the stock is potentially 66{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} undervalued. Furthermore, a PEG ratio of 1 is generally considered a fair price to pay, and Nuvei trades at half or a quarter of that, lending further support to our DCF values. Should the market get bullish and payment stocks demand higher multiples (the current model assumes 20), upside is even greater.
Nuvei is certainly not a Home Stock, in that it doesn’t have a moat and there are some smaller concerns, but the price and business model are far too discounted; a disaster is being priced in. If business doesn’t flop and/or the Great Depression doesn’t happen, Nuvei is going upwards. The main catalyst is lapping 2021’s financials making for easier comps, and new customer wins.
I’m a buyer at $30-$35 USD and would consider selling at $90-$120, though I wouldn’t make this an out-sized position as the company hasn’t been public long so it’s hard to get a sense of its track record.
Alibaba (BABA)
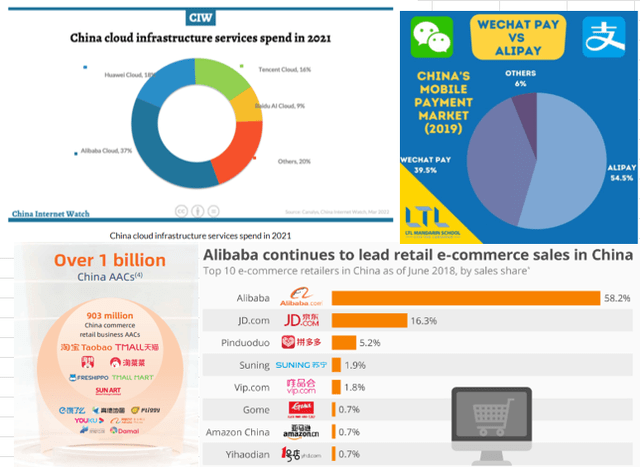
Alibaba is the pre-eminent Chinese internet stock. 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese e-commerce goes through one of its platforms, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the fast growing cloud market is captured by Alibaba, almost every single Chinese person (and 300M outside China) are annual active consumers on its platforms, and, through its one third stake in Ant Financial, BABA owns Alipay, the payment platform through which 56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese payments flow (with more volume than Visa, Mastercard and Amex combined) and Yu’e Bao, the second largest money-market fund in the world with over $170B under management. Alibaba has an ocean for a moat.
In addition, they have fast growing segments, like international e-commerce and domestic groceries, both of which alone could be bringing in more annual sales by 2033 than the entirety of Alibaba generated in the last twelve months. Alibaba is more than just the Microsoft (MSFT) or Apple (AAPL) or Amazon (AMZN) of China, it’s all of them, combined.
Visuals to aid readers in understanding Alibaba’s moat (China Internet Watch, Mandarin School, Alibaba 2022 Annual report)
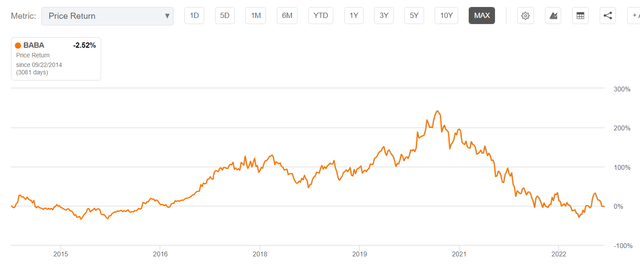
Since it IPO’d in 2014 at $92.70 a share, Alibaba has 15x the revenue, 5x the EBITDA, 4.5x the free cash flow, and 3.5x the operating income. Somehow, we can buy it at IPO prices; Alibaba is tremendously undervalued. Tom Hayes describes it as a submerged balloon, waiting to rocket to the surface.
Alibaba’s return since its IPO (Seeking Alpha)
The dislocation of price to value is caused by the Chinese government locking down the economy in an attempt to prevent Covid from spreading and cracking down on its tech companies, which it deemed were becoming too powerful (perhaps justifiably). Things have changed recently however, the CCP bought shares in BABA, has re-opened the economy, is stimulating the consumer, and generally seems to be working with and through its tech companies as China’s leaders’ personal and national self-preservation instinct has kicked in. Headwinds have shifted to tailwinds.
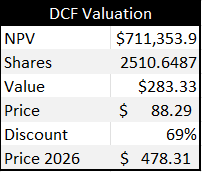
I’m putting up my sails to catch that wind, as Alibaba, were it to return to normalized multiples on normalized earnings, is worth at least $500-$600 a share three years from now. This plan appears to be on track. In their most recent earnings, Alibaba bought back significant amounts of stock well below intrinsic value, somehow grew revenue 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} despite the most recent quarter being under lockdown, and, significantly, increased free cash flow 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year over year despite sales staying flat. This means that Alibaba found a way to become much more profitable in a very short amount of time. Once sales growth starts to kick back in, combined with increased profitability, BABA shareholders could see results well beyond normalized earnings, and therefore have much more upside.
Valuation of Alibaba assuming its free cash flow margins and multiples paid for that FCF returns to historic averages (Author’s Calculation)
Moreover, Chinese savings are twice the historic average, so if they can spend at normal levels, upside could be even higher, considering the market currently expects a conservative 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual growth of sales over the next few years for BABA. Shareholders of Alibaba have a significant margin of safety at current prices, and massive upside should anything go right.
I’m an active buyer and will continue to accumulate under $100 a share for as long as the market lets me. I’ll consider selling when it reaches that $500-$600 mark but will reassess when we get there. If international expansion is going well, BABA might turn into a long-term hold.
I did a longer article on Alibaba here.
Reitmans (OTCPK:RTMAF)(RET.A:CA)(RET:CA)
Reitmans is a century-old Canadian women’s fashion retailer, including the brand’s Reitmans, Pennington’s, and RW & Co. The Reitmans family still owns most voting shares (RET:CA), and senior management positions. Donville-Kent, a Canadian small-cap investing firm whose newsletter, the ROE Reporter, alerted me to the opportunity here. Their treatment is in-depth and can be read here.
Reitmans historically was a reliable dividend payer with sluggish growth in the Canadian retail space, like Canadian Tire in this respect. After years of deterioration however, Reitmans almost didn’t survive the pandemic and was forced to enter bankruptcy to survive. In so doing they laid off thousands of employees, renegotiated better lease terms, paid off creditors at 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the dollar, shut down unprofitable locations and brands, and re-listed from the TSX to the TSXV.
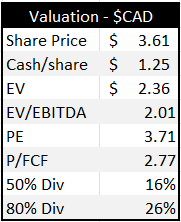
Re-emerging from bankruptcy, the company looks remarkably different, financially. Returns on equity are over 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, debt is paid off and they have $1.25 of cash/share (a quarter of the company’s market cap is cash). In the last nine months alone, Reitmans has generated $67M in free cash flow on $588M of sales, for a margin of 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an excellent number for a retailer. Using just the last nine months numbers, they currently trade at around 2x EV/EBITDA, 4x net income and 3x free cash flow, well below historical averages for their own company specifically and retail generally.
Remarkably undervalued. Priced like it’s going bankrupt again (Author’s Calculations)
If Reitmans were to pay out 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of that free cash flow as a dividend (which they have historically), the stock would yield 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If that isn’t enough, the headquarters and distribution centre owned by Reitmans are worth more than the market cap of the company. The value is clear.
Like BABA, there is a large overhang on the stock causing its price to be severely depressed, but the facts are pointing to this overhang being temporary.
The new Reitmans could continue to be the dog it was in the 2010s, but if its last fiscal year is anything to go by, this doesn’t appear to be the case. Indeed, the current overhang from bankruptcy and Reitmans reputation is providing a margin of safety and likely an opportunity. Shareholders will need catalysts to continue gains though.
Reitmans has several potential catalysts. First, the company could buy back a significant amount of stock with just the cash on the balance sheet. Second, it could reinstate the dividend, which I’m sure the Reitman family are eager to do as it’s been a few years since they got the cheque they’ve been receiving for almost a century. Third, they could list back onto the TSX proper, where fund managers can buy their stock. Fourth, the family could buy the land under their headquarters and fulfilment centre and lease it back to the company, unlocking a pile of cash. Fifth, when earnings are reported in April, we get our first full year of financials for the new Reitmans, and potential announcements regarding any of the first four points made here. Reitmans is already up significantly, but there are more catalysts that could cause it to go even higher.
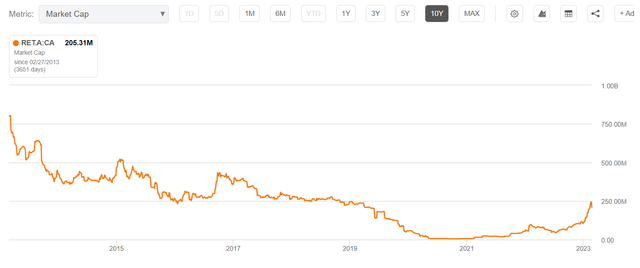
Long-term holder are likely non-existent (Seeking Alpha)
Over the last 10 years, Reitmans was a value trap, with slowing sales and decreasing margins and thus traded at very low multiples, around 7-8x free cash flow (which is still twice as expensive as today). However, sales are not slowing anymore, its brands are proving resilient, and margins have expanded significantly coming out of bankruptcy. 8-10x EV/EBITDA and/or 8-10x FCF are perhaps more appropriate conservative expectations of multiples going forward, compared to the current 2.3x EV/EBITDA and 3x FCF. This suggests that Reitmans is likely a double from ~$3.50-$4.00 on valuation alone, with more potential should the catalysts mentioned earlier happen. Donville-Kent expects the price to reach around $8 if the company doesn’t sell the land to the family, and $12 if they do.
If the outlook remains rosy, the company proves quality and the dividend is reinstated, I might find myself a long-term holder. To put it in perspective, with an 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} payout ratio, I’ll be receiving upwards of 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield on my current cost-basis; a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual cash return is hard to say no to. This should result in price upside as well, as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield from a quality company will not last long; I could see a more justifiable yield of around 6-8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, implying the price could increase another two or three times, like Donville-Kent suggested.
In any case, I see a double minimum with potential for RET.A to triple or quadruple, while I eventually collect a significant dividend yield that I could choose to hold for the longer term. Reitmans is an ideal Investment Property Stock.
Conclusion
Reitmans, Alibaba, and Nuvei are all promising stocks into the medium-term. Though they have long-term drawbacks, namely low growth at Reitmans, ageing demographics and an autocratic home government for Alibaba, and no durable competitive advantage for Nuvei, the market is pricing their stocks at unreasonably low levels. To re-value their stocks, Reitmans could reinstate the dividend and go back up to the TSX, Alibaba could benefit hugely from government stimulus and domestic cloud growth, and Nuvei will be lapping tough 2021 financials, leading to some pleasing year of year numbers. All are quality businesses down for temporary reasons, and have catalysts to revive investor interest.
If worst-case scenarios don’t happen, all these stocks could be doubles in a relatively short period (a couple years or less), and perhaps more into the medium-term (3-5 years). I’m in all of them at allocations I feel are appropriate and am excited to see what the future brings. I would love to become a long-term holder but will reassess later. For now, these make for great Investment Property Stocks.
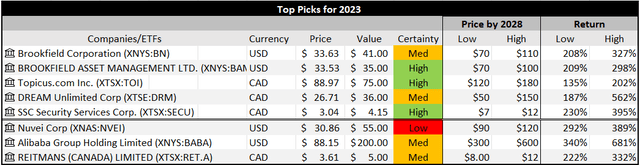
Below is a final summary for all the Top Picks for 2023:
Summary of top picks in the last two articles, including fair values and return potential (Author’s Calculation)
Please feel free to comment, especially dissenting thoughts.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Dear Aggie: Are there any distinctive tips to escalating asparagus in the north country?
Just one of my favored treats in Might is fresh asparagus, picked from our yard and steamed minutes later on. Sweet and tender, asparagus is a nutritious vegetable that grows pretty nicely in the north region. Offered that demand from customers for nearby asparagus usually outstrips out there source at neighborhood farmstands, the best approach to be certain a continuous offer is to improve it you.
Planting asparagus is easy. The initial stage is to choose a web site with well-draining soil and entire sun. Prevent are damp or h2o-logged areas. Asparagus also needs total sunshine — so stay away from the north-facet of residences or spots underneath trees. Recall that asparagus is perennial. With appropriate treatment, asparagus plants can reside for 20 decades. Experienced crops also transplant poorly — so pick out a area where the vegetation can be left for yrs to occur. Luckily, asparagus tolerates a extensive array of soil pH and will execute effectively in the alkaline soils common all over Watertown. It’s deep root process can make it tolerant of dry soils and areas without having irrigation (although watering is recommended in the first calendar year). Hardy to an outstanding Zone 2, it is chilly-hardy everywhere you go in the north country (Zone 4). Simply because it is indigenous to seaside destinations in the Mediterranean, asparagus will even tolerate street-salt, making it possible for it to be planted near sidewalks and roadways.
Even though asparagus can be grown from seed, gardeners will have the best results by paying for crowns — bareroot asparagus roots delivered in dormancy. These can frequently be observed at backyard garden centers and nurseries. Specially when you system to invest in a much larger amount of crowns, we advise buying from a catalog and getting them delivered mail-get in early spring. That way, they will be in cold-storage ideal up until the day they are delivered (as opposed to sitting down in on the shelf of a retailer, which tends to dry them out). A wide variety that I recommend for Northern New York is Millennium, which is seldom available at community vendors but widespread in mail get catalogs. This wide variety performs nicely even in weighty clay soils. An exciting novelty range for our place is Purple Passion.
To plant asparagus crowns, start out by digging a trench about 10 inches deep and 12 inches huge. Unfold a 2-inch layer of compost or properly-rotted manure into the bottom of the trench and turn it into the soil with a spade. This will assist increase the soil fertility and endorse nutritious roots. As soon as the trench is all set, it is time to plant the crowns. Place the crowns in the trench, spacing them about 18 to 24 inches apart. Gently address the crowns with soil, and organization the soil with your hands. Drinking water the asparagus mattress generously, and then include the bed with a 2-inch layer of mulch. The mulch will help retain moisture and hold the weeds down — critically crucial throughout the to start with year or two as plants become established.
Asparagus vegetation need to have time to come to be recognized in advance of they can be harvested. The first yr, chorus from any harvest by any means. I advocate preventing harvest in the second calendar year, although some growers do decide on lightly from their plantings at that time.
In the 3rd 12 months, you can start out harvesting spears from about May well by way of June. Choose the spears when they attain about 7 inches tall. End picking in about mid-June to permit some of the spears to produce into fronds. This fern-like foliage can then acquire and store strength for the duration of the summer for upcoming year’s harvest. Nevertheless set up plantings can endure drought, water them during dry intervals to assure a superior harvest. To lower weeds, increase a 2-inch layer of mulch every spring. Be sure to take away any weeds from the patch, specially perennial weeds, as these will faucet electricity from your vegetation.
Composed by Mike Nuckols, Cornell Cooperative Extension, agriculture and natural methods crew leader.
As an Amazon Associate I get paid from qualifying buys.
Given that the Covid-19 pandemic started approximately three many years back, housing current market traits have been pushed in aspect by home finance loan premiums.
Patrick T. Fallon/Getty Photos
The normally-chaotic spring dwelling getting season is in its early days—but what lies in the coming months will appear considerably different than past spring. A raft of current housing info offers traders clues on what could happen future, but the selection to observe is nevertheless property finance loan premiums.
Housing marketplace details launched this thirty day period confirmed hopeful symptoms of purchaser need buying up ahead of the commonly active spring time. Then home finance loan fees rose.
Initially, builder confidence calculated by the Countrywide Association of Property Builders elevated for the 2nd thirty day period in a row. Up coming, the Countrywide Affiliation of Realtors claimed seasonally-modified existing-property revenue in January fell by .7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}—a more compact decrease than modern drops that “may be suggesting that the home income are bottoming out,” Lawrence Yun, the trade group’s chief economist, stated on a Tuesday meeting simply call. Finally, the Census Bureau explained the seasonally-altered annual level of new dwelling gross sales, a evaluate of deal signings, improved in January by 7.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
These types of details would paint an optimistic picture of the housing marketplace gearing up for the spring dwelling buying season—if not for the latest gains in property finance loan fees, which weekly information exhibit may well have weighed on property customers in recent months.
The average charge on a preset 30-calendar year home loan this week was 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, in accordance to
Freddie Mac ,
representing an maximize of .41 percentage stage from the to start with reading through in February. House loan rates this month have gained on the back again of more powerful-than-predicted financial knowledge. “Interest charges are repricing to account for the more robust than expected development, restricted labor current market and the threat of sticky inflation,” Sam Khater, Freddie Mac’s chief economist, said in a Wednesday assertion.
There is reason to spend attention—even as indicators of deal signings, this kind of as Friday’s new property sales report, present gains. “Even though new dwelling gross sales edged higher in January, the current uptick in home loan premiums would imply continued weakness in the coming months,” Danushka Nanayakkara-Skillington, the National Affiliation of Household Builders’ assistant vice president for forecasting and evaluation said in a Friday assertion.
Due to the fact the Covid-19 pandemic began practically a few years in the past, housing market place trends have been driven in section by house loan rates. In 2021, a 12 months marked by traditionally-lower costs, buyers obtained 6.12 million current-homes, the major yearly overall considering that 2006, according to the Nationwide Association of Realtors.
In 2022, the pendulum swung back again: House loan charges attained via considerably of the yr, topping 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and cooling the housing sector: current-residence sales dropped a lot more than 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} very last 12 months, to the least expensive once-a-year total considering the fact that 2014, in accordance to Nationwide Affiliation of Realtors info.
1 early knowledge issue shows symptoms of higher prices weighing on purchaser demand. The Mortgage Bankers Association’s seasonally-modified measurement of home purchase mortgage applications dropped 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} during the week ending Feb. 17, the most new time frame for which the data is accessible. It was the metric’s 2nd decline in a row and the sharpest 7 days-more than-7 days fall since Oct 2015.
The drop came as property finance loan fees rose for the duration of a typically fast paced 7 days as the spring household buying period begins. “Given the styles that we have found a short while ago, there is definitely fantastic evidence that obtain activity is even now extremely delicate to amount movements,” explained Joel Kan, the trade group’s deputy main economist, who claimed seasonal adjustment intensified the downward drop.
On an unadjusted foundation, the metric dropped 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, in accordance to the trade group. When the affiliation expects demand to pick up in the center of the spring, “how premiums behave above the upcoming thirty day period or so seriously is heading to decide how much of that pickup we’re likely to get,” Kan states.
Investors will have to wait to see how Friday’s main PCE examining impacts weekly rates and purchaser demand—Freddie Mac’s property finance loan level gauge is launched on Thursdays, whilst the Mortgage Bankers Association releases their obtain mortgage application gauge the next Wednesday—but early indications stage to larger charges. Rocket House loan, a large dwelling bank loan originator, quoted interest charges on 30-calendar year fixed-charge loans at 6.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on Friday afternoon, when Property finance loan News Daily’s study pegged Friday’s level at 6.88{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Larger prices do not automatically mean prospective buyers will flee the market. Luxurious builder
Toll Brothers
(ticker: TOL), observed deposits boost even as mortgage loan rates rose, CEO Douglas Yearley reported on Wednesday on the company’s very first-quarter earnings convention contact.
Whatever the impact, it will acquire time for the enhance in costs to reflect in regular monthly knowledge. A person of the remaining housing knowledge releases for this month, the National Affiliation of Realtors’ pending house profits index for January, is envisioned to display its next maximize in a row just after a number of months of declines, in accordance to FactSet.
Create to Shaina Mishkin at shaina.mishkin@dowjones.com
Thinking of investing in real estate? Before acquiring an expense residence, you want to make positive that it will generate at least more than enough funds to address your monthly carrying charges — and, ideally, extra. Which is where the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule will come into play. This true estate rule of thumb can help investors determine irrespective of whether a specific home will be worthwhile for them, centered on its acquire price tag and every month rent. Here’s how it works.
What is the 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule in serious estate?
The 1 p.c rule is a true estate investment guideline that allows traders immediately estimate the minimal month to month lease they have to cost to break even (at minimal) on a particular home. Exclusively, the rule indicates that the rent on an financial investment assets need to be equivalent to or greater than 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the property’s sale rate.
Here’s another way of seeking at it: When viewing possible rental attributes, buyers can use the 1 percent rule to assist choose no matter whether the purchase price is worthy of the profits it is probable to create.
It is crucial to mention that the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule is merely a guideline, not a tricky-and-quickly rule. It doesn’t take into account all the variables that could influence no matter if or not a opportunity assets is really worth the investment decision at the time. It is a practical (albeit imperfect) shortcut to calculate the approximate amount you’ll need to have to cost in monthly rent in purchase to make a earnings.
How it is effective and how to estimate it
To work out regular monthly rent employing the 1 per cent rule, just multiply the home’s obtain price tag by 1 p.c. If repairs are essential, incorporate the repair service fees in with the buy price tag.
Calculator
Order Price tag (Together with Fix Charges) x .01 = Least Month to month Hire
For illustration, let’s say you are looking at a duplex household outlined at $250,000 which is in great problem and doesn’t need any instant repairs. Employing the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule, you’d need to have to bring in at minimum $2,500 for every month complete, or $1,250 for every unit, to address your fees.
Now, let’s say you’re wanting at a $150,000 single-family members residence that demands $25,000 well worth of repairs. In that case, you would multiply $175,000 by 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to get a minimal regular hire of $1,750.
You can also apply the 1 per cent rule to gauge no matter if or not a home may be a great financial commitment based on its historic hire. For instance, if a household is shown for $200,000 and the most latest tenants paid $1,500 for each thirty day period, which is a lot less than 1 per cent — and, as a result, most likely not an interesting expense. But if the tenants were being shelling out $2,500 for each month, the property would move the 1 percent rule.
What it doesn’t take into account
There are some limits to the 1 p.c rule. For case in point, although it does component in any original repairs that the property needs, it does not contemplate the ongoing expenditures of homeownership. House entrepreneurs normally bundle these costs into their tenants’ lease, but if you use the 1 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule, these expenses will not be reflected in the every month hire full.
Property finance loan fees
The every month value of a house loan depends, of study course, on the mortgage’s interest price. The same $200,000 residence might be a superior expenditure at 5 percent but not so a lot at, say 6.5 per cent. Be confident to variable in your bank loan terms and what your every month property finance loan payment will be right before investing in any residence.
Routine maintenance and repairs
As a home owner, you’ll have ongoing upkeep expenditures like garden treatment, HVAC upkeep and pest handle. Some of these expenses can be unpredictable, which can make it complicated to prepare for them, so budget correctly.
Property taxes and insurance coverage premiums
You are dependable for shelling out your home’s once-a-year assets taxes, which change extensively by state and municipality. The median property tax bill in the U.S. is $2,375, according to World Population Overview. In addition, you’ll have to have to invest in coverage for your residence — especially landlord insurance, which is generally much more pricey than normal property owners insurance.
Property owners affiliation charges
If the property is in a community managed by an HOA, you’ll will need to pay out standard dues. These can variety very a little bit relying on the features and products and services available, so make certain you know accurately how significantly you will have to tack on to your every month expenses to protect them.
Atypical markets
The 1 p.c rule might not apply in specifically dear marketplaces, like San Francisco and New York Metropolis. For case in point, the median sale rate of a house in San Francisco was $1,385,000 in January 2023, according to the California Association of Realtors. Working with the 1 percent rule, you’d require to cost more than $13,800 per month in lease just to split even, which is simply just unrealistic for most rental homes.
Other authentic estate principles to know
There are quite a few common real estate tips centered on percentages. In this article are a few some others that might be useful:
The 2 per cent rule: The same plan as the 1 per cent rule, just a little bit stricter. It suggests that any residence ought to make at the very least 2 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its order rate in every month hire.
The 28 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule: This guideline recommends that you commit, at most, 28 p.c of your gross month-to-month money on your home loan payment. A lot of loan providers think about this when examining your software.
The 70 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule: The 70 per cent rule assists home flippers identify how much they can expend on a house centered on its following-mend price (ARV) — the home’s expected value right after renovations are comprehensive.
Base line
If you’re in the early stages of assessing rental qualities to commit in, the 1 p.c rule is a speedy and quick way to estimate the minimum sum you’d have to cost in hire to make a earnings. Hold in thoughts, nonetheless, that it is just a common rule of thumb, so you shouldn’t depend on it to offer a specific determine.
Disreputable contractors who botch renovations or, worse but, get a homeowner’s cash and operate are all way too common—and a new HGTV demonstrate highlights the drama and some substantially-essential remedies.
On “Rico to the Rescue,” Denver-dependent real estate agent and construction restoration guide Rico León helps homeowners rectify half-done renovation careers, while also chasing down the contractors who’ve carried out the shoddy get the job done.
“I take care of conflicts concerning property owners and homebuilders,” states León. “Years ago, my moms and dads received taken edge of by a contractor. That is why I’m these kinds of an advocate for home owners.”
In the episode “Ranch Residence Redo,” León performs with Chris and Katie, who acquired a ’70s ranch residence with 4 bedrooms and a significant basement that desired a total renovation from leading to base.
They interviewed at least 10 contractors and picked the a single they considered would do the very best work. However, six months later on, pretty very little had been performed, and what was carried out was accomplished poorly—so badly, in point, that León and his crew have to rip a large amount of it out and commence in excess of again.
Katie and Chris had currently paid out the contractor $230,000, and the occupation was not even near to staying entire. León and his crew try to end the dwelling speedily and economically, and they also reach out to the contractor to see if he will make things proper. In the method, we get a must have ideas for dealing with contractors on our very own initiatives. Read through on to discover out what we discovered this 7 days.
The cheapest bid may not be the very best
Rico León and his workforce of specialists talk about what the renovation will genuinely price.
(HGTV)
The contractor at first hired experienced given a very minimal bid for the couple’s task. Even though this is unquestionably tempting to dollars-strapped house owners, it is also a red flag that the contractor may possibly not know what he’s accomplishing.
“The largest oversight the contractor did was not bidding it properly,” León says soon after inspecting the unprofessional workmanship and looking at that pretty much absolutely nothing was finished. “He experienced it at close to $200,000. This really should have been at least a $350,000 renovation.”
Owners must generally be suspicious of a very low bid.
House enhancement financial loans have their benefits
León and the householders in the residence the way the contractor still left it.
(HGTV)
Though most have extensive read that it’s best and most secure to fork out with funds, León will come up with a decent explanation for taking out a dwelling enhancement financial loan.
“Did you fellas consider out a bank loan, or was this cash that you saved?” asks León.
“We experienced been conserving for a extensive time,” suggests Chris.
“It was income,” confirms Katie.
“That’s fantastic and poor,” responds León. “Because when you do a mortgage, the home loan corporation will be on top rated of the contractor as well.” Now which is a thing to feel about.
Make sure your contractor is licensed and insured
León’s dog observes the renovation perform.
(HGTV)
One more prerequisite for any contractor is to make guaranteed he (or she) is certified and insured—that way, if anything at all goes incorrect, the contractor’s insurance policies company will deal with numerous of the expenses.
In this case, “The few has made statements versus the contractor with his insurance business,” clarifies León. “Now it is in their hands.”
Though working with an insurance enterprise is rarely pleasant, it is improved than making an attempt to offer with a disappearing contractor who will no longer acquire your calls.
Come across out if there are further elements waiting to be shipped
Empty basement left with no finishes
(HGTV)
When León and his crew initial walk into the home, they see only partial building perform. There are no resources in bins waiting around to be utilized or put in. They never know if the previous contractor ordered any cupboards, flooring, appliances, fixtures, countertops, etcetera. And if they have, the place are they? Is there any way they can get and use them?
“The major worry that I have is, out of the $230,000 that they gave him, how a lot of that was put in on materials and the place they are,” claims León.
If the unique contractor did not spend the couple’s money on products, the completed renovation project would be considerably extra highly-priced.
When they locate out that nothing more has been purchased, León’s designer, Poonam, arrives to the rescue. She informs Katie and Chris that the distributors she will work with will donate flooring resources, cabinetry for kitchens and loos, counter tops, some of the lights, and all of the tiles. What a generous windfall!
Finished basement with generously donated supplies
(HGTV)
Ask to hear the contractor’s side
León speaks with the contractor.
(HGTV)
León receives the option to converse with Mike, the initial contractor, each in particular person and on the phone.
“Mike and I had a quite extended conversation,” he stories. “I always want to hear the contractor’s aspect of items.”
The contractor admits he has about $30,000 that he had planned to use on labor and that he would be ready to return that.
But later, when León speaks to Mike on the phone and reminds him of the $30,000, Mike accuses León of bullying him and says he’ll have to talk to his law firm. Then he hangs up.
The discussions have been legally recorded and can afterwards provide as evidence.
How does this renovation transform out?
Newly renovated kitchen
(HGTV)
When León is attempting to kind items out with the contractor, his crew is doing work on a excellent rework. With their donated materials and exceptional abilities, they switch these raw, ruined rooms into stunning dwelling spaces.
Katie and Chris are surprised.
“Rico, this is so gangster!” Chris exclaims. His attractive new house is far extra attractive than he at any time dreamed it could be.
“We weren’t guaranteed if we were going to be content in the space just after the trauma that we went via,” adds Katie.
And as for the sketchy contractor? “Unfortunately, we’re not completed with our aged contractor,” describes Katie. “We have building defect statements, we have breach of agreement and overpayment difficulties that we’re likely to test and get back again. It’s heading to be a journey from right here, but at the very least we can do it from dwelling, from a much improved location.”