An investor needs to make investments a big total of revenue when it will come to real estate financial commitment, which is composed of quite a few hazards. These components make it vital to think more than all the elements of the financial commitment thoroughly ahead of making the remaining conclusion. Deficiency of awareness of the market and similar procedures and polices may well lead to a erroneous conclusion. The inclination to very own a residence has improved owing to the pandemic induced insecurities. With this tendency, the worth of the info linked to the complexities of expense in realty has also risen. The significant factors 1 need to consider are right here-
RERA registration
RERA is framed and implemented to control the malpractices in the sector and guarantee security to buyers. It has produced actual estate transactions clear. The trader ought to test the project registration with RERA. It can be verified online through RERA Internet site. It would be really effective to review the assets on the parameters of RERA.
Spot
Area is an significant issue to contemplate ahead of investing in property as it decides connectivity. Accessibility to roads, general public transport, health care facilities, academic institutions and other significant infrastructure relies upon on the location. Residence ought to be analysed to fully grasp the probable of the site. A close look at the structure of the house is also crucial to comprehend the total process produced at the web page.
Stability and facilities
Protection is a principal problem now for all. Stability from the unsocial things as very well as organic threats these types of as viruses has grow to be essential. An particular person searching for investment decision in real estate must examine all the safety capabilities at the web page. One more critical place to contemplate is the features provided by the developer. Routine maintenance prices, electrical energy offer, drinking water costs and other these types of extra rates have to be thought of ahead of finalising the offer.
Title
Understanding the title of the property is incredibly vital when it arrives to investing in realty sector. Lawful information from a reputed law firm should be taken to recognize this elaborate challenge much better. It is additional essential in case of secondary gross sales. In some cases, unpaid thanks or some expenses are hidden from the potential buyers in house agreements by the broker or seller. It need to be supplied owing focus.
Evaluate sector costs
Traders should really look at the price ranges in the market place ahead of making the ultimate decision about expenditure. It will guarantee the ideal present. Moreover, it is fantastic to know the brand name worth of the developer for upcoming valuation.
Serious estate investment decision is a extremely big determination as it includes a whopping sum of funds. This is the rationale why a person really should look at all the necessary element right before investing. It is also critical to steer clear of future disputes. 1 should investigate every facet in element and then only make an financial commitment in home. It tends to make the information of reputed consulting organizations vital. A lawful assistant will also help in building the purchasing system easier.
Housing variations took a sharp flip away from common kinds with the introduction of Artwork Deco design and style, and a new age in residence architecture came on the scene. Gerard Splendore spells out what you must know about houses from this time period.
Wanting for far more tips? Check out Inman’s New Agent Necessities.
American housing types have adjusted, and continue to modify, in the course of the state and as homeowners’ preferences and life have evolved. As the region has undergone industrial and financial changes, the two very good and not so fantastic, housing variations have tailored out of necessity.
In this new collection, I will wander you through the predominant housing types of the earlier 12 many years, commencing in 1900. A essential being familiar with of every single architectural model that defines a decade will posture you as a experienced agent with your clients and make browsing for a home with your prospective buyers easier for absolutely everyone.
From the vantage stage of 100+ a long time, chatting about “the fashionable age” may well feel comical, but that is how the 1920s are known.Housing kinds took a sharp turn away from common designs and, with the introduction of the Artwork Deco structure fashion from France, a new age in residence architecture came on the scene.
Artwork Deco was initial observed generally in commercial properties in New York, these as the Chrysler Developing. In 1922, Chicago’s Tribune Headquarters was an additional instance of the Artwork Deco type on a grand scale.
Glamour and sophistication are the feelings most involved with Artwork Deco.Interiors were being characterised by geometric lines, bold colours and statement mirrors. Metals, specially chrome and aluminum, are witnessed equally within and outside the house properties in the 1920s as opposed to wooden and brick. Neo-Gothic structures, that includes the pointed Gothic arch, ended up characterised by decorative finials, patterns on interiors and exteriors, and scallops in brickwork and woodwork.
The so-termed “Roaring Twenties,” a time period of rebellious assumed, and the avant-garde motion in artwork and style, bolstered the introduction of Artwork Deco. New systems in supplies, plumbing and heating ended up included into the Art Deco-type household.
Eclectic, not pure, style and design incorporated each modern and classical style factors, intentionally breaking with traditions that existed prior to Globe War I. Beaux-Arts facets of Artwork Deco included neoclassical French and Italian variations.
Artwork Deco can be identified as a pastiche of designs in its determination to stay away from direct historical references. It is just one of the most influential ornamental kinds of the initial 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the twentieth century. Functionalism and purified architectural sorts exhibiting radical extremes are components of the Art Deco vocabulary.
Coinciding with Art Deco, introduced by Walter Gropius in Germany circa 1919, is the Bauhaus Motion. Purity of variety and the reality of nature are other aspects of the Art Deco Style.
Even though the 1920s Art Deco style brings together numerousaesthetics, what does the genuine 1920s property appear like? Servants and various generations dwelling in 1 residence turned less and a lot less commonplace. Streamlined interiors that were being quick to care for became a precedence and contemporary kitchens with newer streamlined appliances, such as washing devices, were in evidence.
Properties now had telephones, and “nooks” to home a cellphone, some with crafted-in seating, were being factors in new properties. Generally situated concerning the bedrooms and the bathroom, phone nooks were being niches in the wall with a box beneath the compact shelf to hold the mobile phone.
The to start with residential telephones were much too smaller to house the phone’s ringer and other electronic sections, so these parts ended up housed in a separate box, which was screwed into the back of the lessen compartment. A cord connected the two parts of the cell phone and the shelf conveniently held the telephone book and pencil and paper for messages. A phone nook is a sure indicator of a 1920s dwelling.
Garages were almost never witnessed in Artwork Deco residences, inspite of autos setting up to turn into readily available. Householders who owned automobiles parked on the street around their houses.
Realtors who can recognize historical components of households from unique durations can quickly converse with their clientele about why residences are configured or created as they are. If historical types are significant to prospective buyers, the Real estate agent who can examine them has an edge. If buyers are on the lookout for additional present-day or up-to-day homes with modern-day amenities, the educated Real estate agent only has to look at the age of the dwelling to figure out if it will do the job for their buyer.
One particular can by no means forget about the allure of Miami for much too extensive since The Magic Town often pulls anything interesting out of its hat of tips. Famed for its unpredictable fauna and undeniably gripping coastline, the Florida metropolis has come to be the deal with of selection for those who have genuinely arrived in everyday living. The modern inaugural Formula 1 race added 1 of the most embellished feathers on the proverbial hat.
Developed on the pillars of its actual-estate increase that keeps inflammation with regular tempest, luxurious dwelling is staying redefined below by three prestigious jobs that are all established to carry the warmth to Miami.
Baccarat Residences in Brickell Led by Associated Team, the major apartment builders in Miami, the resort-esque properties in Baccarat Residences in Brickell provide the very best life for its people. Brickell delivers unmatched connectivity to the culture, commerce, and amusement hubs of the metropolis. The challenge is located a quick push absent from the town heart, the heavily frequented Bayfront Park and Museum Park, the Pérez Artwork Museum, and numerous leading eating places and procuring havens.
The Baccarat Residences are made up of a trio of towers that comprise a assortment of 324 tower residences that are accessible from 1-bed room to 4-bedroom configurations, 8 penthouses, and 28 riverfront flats and duplexes.
The entire elaborate is a perform of art, thanks to the vision of Arquitectonica’s structure sensibilities. Meyer Davis has intended the interiors of each and every of the condos, which include things like shared facilities these types of as a heated pool, a little ones pool, a clubroom, a conditioning middle, a hammam spa, a wine cellar, and tasting salon, and a gourmet sector, amid other comforts. Inhabitants can also avail on their own of the amenities from the company heart and even lease out boats for a weekend getaway with mates and family members.
Each individual individual device will be geared up with private vital elevator entry, ceilings up to 10 ft substantial, cupboards by Italkraft, induction ovens by Wolf, stone backsplashes to add to the opulence, wine storage, a sub-zero fridge, huge wood doorways, a few of wander-in closets in the learn bedrooms (in case of several bedrooms), and laundry rooms.
People can get gain of the children’s playroom that helps the children unwind and meet new mates, a 24/7 valet parking assistance, and a whole lot extra to enrich their common of living and give them an unadulterated taste of pure luxurious.
The completion date of the challenge is set at the stop of 2025. The developer has also opened up a effortless payment model to bring in extra aspiring purchasers.
Waldorf Astoria Residences in Downtown Miami Below is a monument in the making. Situated in Downtown Miami, Waldorf Astoria Residences in Miami are established to declare the title of getting the tallest mega-composition in all of Miami. Measuring a whopping 1,049 toes previously mentioned the ground, the household complex will develop into the most coveted handle in the location. Just a short travel from Miami Planet Heart, found at Biscayne Boulevard, Waldorf Astoria Residences will characteristic a 100-tale superior-rise that is established to dominate the Miami skyline.
The tower will be a work of artwork from the studio of famed architects Carlos Ott and Sieger Suarez, who have devised the distinctive structural form of the tower. The developer of the project is House Marketplaces Team and Greybrook Realty Companions. The entire challenge will include a whopping 800,000 square ft of land and will offer you a direct watch of Biscayne Bay, Brickell Avenue, Downtown Miami, Critical Biscayne, and South Seaside.
A person would agree that the Waldorf Astoria challenge is situated in the finest doable spot of Miami, supplying customers a vantage level into the important landmarks of Downtown Miami. Even all those who are driving by this phenomenal composition would want it in their frame, with the stacked cubes-like composition employed in the design and style. It is a sight to marvel at and an architectural circumstance study for those who intention skywards.
The interiors are fashioned by BAMO, a San Francisco-centered interior structure firm that prides alone on groundbreaking luxurious residence jobs for in excess of three decades. The residences will boast floor-to-ceiling windows of up to 12 toes superior, giving vistas of Miami’s stunning landscape, private and semi-private elevators, charming views of the ocean and Downtown Miami, and summer months kitchen area balconies so that you can enthrall your visitors with a BBQ with a see, and a good deal a lot more.
The amenities offered for citizens will be no different than that of a 5-star lodge. People will be able to avail of a spa, exercise heart, pool deck, a café, a signature restaurant, ballrooms to host their activities, and far more. Shortly, it will be commonplace to measure any declare of luxury in opposition to this absolute benchmark.
The developer also delivers a versatile payment scheme for possible purchasers and is committed to the completion of the job by 2026. Standing just before the glass facades on the top rated floor of the Waldorf Astoria will give just one the feeling of remaining a god on the lookout down upon their stunning development that is Miami.
The Perigon at Miami Beach Beachside attributes are far more eye-catching than people that are not. And then there are people, like The Perigon in Miami Beach front, that make all the some others turn their heads covetously. The constructing boldly claims that it provides a new standpoint on luxury living, and to a excellent measure. Miami’s sea-struggling with condos supply the most beautiful vistas into the ocean waves and excited tourists on the shorelines. But legitimate luxurious commences with what’s on the other aspect of the glass façade that overlooks these picturesque expanses – some thing that you can be definitely positive to take pleasure in with The Perigon undertaking.
The really form of the Perigon tower is what sets it apart on the Miami skyline, particularly among the the other beachfront residences. The project has been made by Mast Funds, a Miami-primarily based real estate development business that has a agency grip on the lay of the land. The condominium project is set to be all set for possession by 2025.
1 are unable to harp more than enough about the key place of The Perigon. It is surrounded by the gorgeous Miami shoreline, overlooking some of the very best shorelines along the full coastline, the finest pools, numerous artwork tasks, the finest boutiques, and important nightlife hotspots. If you’re not engulfed in the surreal cloud protect that the higher condos promised, then you will be treated to the bustling sights, many toes under you. The architecture of the tower is motivated by OMA, even though the interior style is led by London-based mostly designer Tara Bernerd who has labored on many houses, resorts (which include Four Seasons and Conrad), and yachts.
The Perigon will be a solitary tower with 82 ultra-high-class residences unfold throughout 17 stages. The configurations of the homes range from 2-bedroom (2,100 square ft) to 4-bed room (6,700 sq. feet). Inhabitants will have the luxury of 183 parking spaces with almost 15,000 square feet focused to recreation, wellness, and other amenities. 1 of the highlights is the cafe with an Instagram-deserving beachside swimming pool, with sunbeds and cabanas. They can also delight in a poolside and beachside food and beverage provider. Youwouldn’t need to step out for a exclusive dinner butrather invite some visitors in excess of to the cafe for a perspective of a life span.
Another standout feature is the outside spa and wellness middle that is accompanied by an intimate yard and meditation lounge for quieter moments. The Perigon offers its extremely very own 200 linear feet of personal shoreline that is easy to accessibility for inhabitants.
Just one would wonder why they want a seaside trip any place else.
Nir Meir, Ziel Feldman, and Helene Feldman. Photo-Illustration: Curbed; Photos: Shutterstock/Getty Images
This article was featured in One Great Story, New York’s reading recommendation newsletter. Sign up here to get it nightly.
Ziel Feldman is in good company. At least that’s what the real-estate developer at the center of one of the most spectacular meltdowns in recent memory has been telling himself. The Manhattan real-estate industry is a game of winners and losers, Feldman says, and even titans lose big sometimes. Over the past 18 months, Feldman’s firm, HFZ Capital Group, has been obliterated by foreclosures and investor lawsuits, a collapse that has dredged up unflattering details about the company’s inner workings. Which is why Feldman, on a cloudy afternoon earlier this year, ticked off the names of prominent developers who have, at one point or another, stared down the barrel of bankruptcy. Stephen Ross, Arthur Zeckendorf Sr., Harry Macklowe.
“Every single one — bar none — has run into potentially career-ending roadblocks,” Feldman says, sitting at a coffee table in his corner office, which, despite the imperiled state of his business, overlooks the Plaza Hotel and Central Park beyond. “It’s not for the faint of heart,” he says. “Most successful ones have been bankrupt.”
Though the tabloids and real-estate journals have covered HFZ’s fall with a journalistic fervor usually reserved for war and the Kardashians, this is the first time Feldman has spoken to the press about his company’s implosion. He’s clean shaven and his hair, a jet-black bouffant before the pandemic, is trimmed short and gray.
That Feldman can so easily string together a list of billionaires who have bounced back from financial ruin probably says more about the ludicrous nature of the Manhattan real-estate business than it does Feldman’s own circumstances. In truth, it’s hard to compare any other builder’s misfortunes with the enormous pile of rubble through which Feldman is presently wading. In addition to losing its portfolio, HFZ has been sued by a slew of contractors, lenders, and investors. Lawsuits are to be expected during bankruptcy proceedings, but the allegations of impropriety within some of the suits — including accusations that Feldman and his partner skimmed millions to fund their extravagant lifestyles — are not.
To make matters worse, last year, one of HFZ’s key investors, an Israeli diamond magnate, was convicted of bribery and sentenced to five years in a Swiss prison. And the company’s former managing director of development — someone Feldman employed for more than 20 years — was arrested and sentenced to prison for awarding contracts to the Mafia. Last year, the New York State attorney general confirmed her office was reviewing a fraud complaint against HFZ, though to date, nothing seems to have come of that investigation.
Manhattan has always been a playground for the rich, and the decade-long all-they-can-eat asset buffet that followed the Great Recession nurtured a fresh crop of luxury developers including HFZ, who soaked the city with units that advertised floor-to-ceiling windows and hotel-quality amenities. The boom was fueled in part by overseas buyers — from Russia, China, Latin America, and the Middle East — who stashed their money in those units, investments that offered stability and, thanks to the city’s tolerance of LLC property owners, anonymity. That influx of extreme wealth transformed New York. In little more than a decade, the city’s median sale price nearly doubled, driven by luxury condos in neighborhoods essentially invented by property developers and their marketing teams: West Chelsea along the High Line and Billionaires’ Row, a neighborhood with a boundary primarily defined by its being above everyone else.
Luxury developers raced to keep up with demand, and HFZ was among the splashiest of the bunch. By the mid-2010s, the firm was responsible for a significant percentage of the luxury condos coming to market. By 2015, HFZ’s two top executives, Feldman and managing director Nir Meir, were appearing on lists of the most powerful developers in the city. Their rise culminated with HFZ’s announcement that it was building the XI, a $2 billion megadevelopment along the High Line. The XI, which Feldman called his “shining star” during our conversation, should have bumped Feldman and Meir into the highest echelon of builders, masters of the most recognizable skyline on the planet. Instead, over the course of a single real-estate cycle, their company went from being the industry’s darling to its biggest bust.
Insiders and former employees say there is no one reason HFZ imploded, pointing to an array of issues — poor decision-making, a chaotic work culture, extravagant spending, spreadsheets that said whatever the bosses wanted to hear. Even those who didn’t have a front seat to the turbulence sensed something was awry.
“I would never in a million years do a deal with Ziel,” said one major developer. “He had too many deals, too much leverage, too much razzle-dazzle.There was always a sense that things weren’t what they seemed to be. The pandemic was like that Warren Buffett line: Only when the tide goes out do you see who’s swimming naked.”
For a time, Feldman also blamed the pandemic for HFZ’s woes. In December 2020, HFZ filed a notice with the New York State Department of Labor indicating it had laid off 31 people, almost its entire staff, because of “unforeseeable business circumstances prompted by Covid-19.” But sitting in his office, the 63-year-old trains his ire on one person: his former partner, Meir.
Feldman and Meir worked together for 20 years and, according to former colleagues and friends, never seemed to have any issues until everything came crashing down. Since then, the two have been engaged in an ugly, very public divorce.
“We were like his family. I always said I have three children and that I gave them an older brother, Nir,” says Feldman’s wife, Helene, who is sitting beside him in his office. A former prosecutor in the Brooklyn district attorney’s office, Helene served as HFZ’s “design and creative” principal. She has blue eyes and platinum-blonde hair and wears black leather platform shoes she designed herself. “Ziel really took him in as a son.”
In August, Feldman filed a lawsuit against Meir accusing him of engineering a “Machiavellian scheme to enrich himself through theft, deception and ‘charm.’” Feldman alleged that Meir diverted millions away from HFZ accounts into his own pockets. The lawsuit seeks $688 million in damages. (Meir would not speak to me on the record for this story.)
“With Nir at the helm, we were doomed from the beginning,” Feldman says when he’s done listing formerly bankrupt billionaires. “I’m not aware of any other developer who relied so heavily on a person who turned out to be a very talented sociopath.”
The XI in April 2022. Photo: Gary Hershorn/Getty Images
A Queens native, Feldman started his career as a real-estate attorney in the mid-1980s, a time when, as the journalist Jerry Adler observed, “real estate replaced sex as the venue for the everyday fantasies of most Americans.” Sex never reclaimed the top slot, and in the wake of the 1987 stock-market crash, Feldman sensed there was more money to be made as a developer than as a developer’s attorney.
Eventually, Feldman co-founded a development firm, Property Markets Group, with a banker named Kevin Maloney. There was no shortage of opportunity in the early ’90s. PMG went after SROs, troubled walk-ups, and neglected buildings it could afford to buy and refurbish before raising rents. As a young start-up, PMG’s partners prided themselves on keeping overhead low, stuffing employees into a cramped office with space heaters. Everyone except Feldman worked off cheap folding tables.
“At one end, there was Ziel with his leather-topped partner’s desk, and at the other end, there was me with my card table,” said Maloney. “Ziel liked to have a higher standard of living than I did. That was important to him.”
In 1994, Maloney and Feldman partnered with Gary Barnett, who today runs Extell Development, one of the most successful luxury-condo developers in the city, to purchase the Belnord, a sumptuous Beaux-Arts building on the Upper West Side. The building had been neglected, and its tenants were locked in a bitter fight with their landlord. Barnett and PMG paid $15 million for the building, funded largely by the secretive Israeli diamond dealer Beny Steinmetz, and promised tenants they would spend $5 million on renovations in exchange for the right to increase rents. The project would serve as a blueprint for Feldman for two decades.
Feldman earned a small fortune at PMG. He and Helene built a mansion in Englewood inspired by a Fontainebleau chateau they’d toured on their honeymoon. But by the early aughts, Maloney, who continues to run PMG, wanted to spend more time concentrating on deals in Florida, while Feldman was eager to expand in Manhattan.
People who knew and worked with Feldman say he seemed to be driven by an unspoken desire to reach the penthouse of Manhattan real estate: the dynastic families — Durst, Zeckendorf, Speyer, LeFrak, Rose, et al. Feldman liked to talk about what made a successful developer, and more than anything, he thought of himself as a tastemaker attuned to the city’s trends and needs. In 2005, Feldman started HFZ (Helene, Feldman, Ziel) and brought with him a few PMG employees including Meir, whom Feldman tapped to be HFZ’s managing principal. In his 20s at the time, Meir was younger than Feldman. He had short, dark hair and the chiseled jaw of an action figure. He’d grown up between Israel and Paris, and he told people he served in the Israel Defense Forces before moving to New York in the early aughts.
In Meir, Feldman found someone whose skill and ambition matched Feldman’s own desire to grow HFZ. Meir was excitable, a fast-talking bulldog who dug into the minutiae of every project. During the day, he pored over spreadsheets, adjusting projections and timetables, and at night, he’d hit the town to develop relationships with lenders and investors. In that way, Meir complemented Feldman, who increasingly enjoyed playing the part of the elder statesman, providing big-picture strategy.
After the real-estate bubble burst in the late ’80s, Feldman learned a frustrating truth about postrecession markets: While there was no better time to buy real estate, there was also no harder time to find investors and lenders. To Feldman’s great satisfaction, Meir proved to be particularly adept at raising money from both institutional lenders and overseas investors. “JPMorgan loved him,” Feldman says.
According to Feldman and former colleagues, Meir had a magnetism that drew in wealthy investors, people he would wine and dine at Carbone or La Esquina before taking them to clubs. With their backing, HFZ went on a buying spree that resembled deals Feldman made in the ’90s with PMG, snatching up distressed buildings other developers wouldn’t touch. The press took notice. “Developer turns flops to gold,” read a 2013 Crain’s headline that referred to Feldman as the “man of the hour.” The Observer published a feature on Feldman, saying he’d “emerged out of nowhere” to rescue One Madison Park, the all-glass residential tower with a penthouse that would serve as Rupert Murdoch’s postdivorce bachelor pad. The Daily News called him the “modern-day John Jacob Astor” for his renovation of prewar apartments on the Upper West Side.
“These guys were magicians about playing the capital markets. They knew there was so much capital in the world and that banks and bankers were hungry to put that money to work,” said someone who worked with Feldman and Meir. “But they were the step-kids trying to get into the world of the big families controlling real estate. They were successful, but they were doing it in a shady way.”
Historically, the families haven’t needed to rely on foreign money to fund their projects. They are so obscenely rich that they can, for the most part, afford to play the game on their own. But if Feldman’s goal was to establish a dynasty, he needed to do so with other people’s cash.
By the late aughts, Steinmetz’s fortune had ballooned to make him one of the richest people in Israel, and he was pumping hundreds of millions of dollars into real-estate projects around the globe. It was an open secret among HFZ employees that Steinmetz, who is intensely private about his business and personal life, was a major HFZ backer. But when a reporter from The Real Deal asked HFZ about its relationship with the diamond dealer in 2016, a spokesperson emphatically denied any personal or professional connection to him.
Emails, text messages, and interviews with former HFZ employees show Steinmetz was intimately involved with HFZ. In fact, at one point, Steinmetz had employees based inside HFZ’s office. Multiple former HFZ employees recalled Meir taking last-minute trips to the Mediterranean to meet with Steinmetz. According to emails made public in court proceedings, Steinmetz would email Meir to discuss details of deals. Once, Steinmetz’s lawyer emailed Meir to ask him to scrub the diamond dealer’s name from an investment organization chart. Meir dutifully agreed.
Feldman denies ever lying about his connection to Steinmetz. He claims Meir erected a firewall between Feldman and the diamond dealer, as he did with most foreign investors. But HFZ and Steinmetz had good reasons to conceal their relationship. In 2009, Steinmetz’s company won the rights to mine the Simandou mountains in Guinea, one of the most prized mining contracts in the world. A year later, Steinmetz sold half of those rights to the Brazilian mining firm Vale for $2.5 billion. Then, in 2014, the Guinean government revoked Steinmetz’s rights, alleging his company had bribed the youngest of the late Guinean president’s four wives to secure the deal. In 2021, a Swiss criminal court found Steinmetz guilty of corruption and forgery related to the Simandou deal, sentencing him to five years in prison. (Steinmetz, who lives in Israel, has indicated he intends to appeal the decision. Last year, Steinmetz was briefly detained in Greece on an Interpol red notice related to a 2020 bribery case in Romania in which he was found guilty and sentenced to five years in prison.)
For years now, Vale has been trying to recoup its initial $1.25 billion payment to Steinmetz. As part of that action, Vale’s attorneys have traced money from the Simandou deal to investments Steinmetz made in HFZ projects including the XI. (HFZ isn’t the only developer Vale’s attorneys are interested in; they’ve also subpoenaed Aby Rosen’s RFR Holding.)
Helene, the daughter of a Holocaust survivor, and Ziel, whose father ran a family textile business, often talk about their humble roots in Queens. But as HFZ’s portfolio grew, so did the Feldmans’ presence in watermarked photos taken at New York society parties. They attended galas from Palm Beach to Antibes, were staples at Art Basel in Miami, and hosted charity fundraisers at their 8,000-square-foot home on Dune Road in Bridgehampton, where guests mingled between an infinity pool and a pool-size infinity hot tub. They chipped in $25,000 for Donald Trump’s 2016 presidential campaign and sat on the board of directors of a hospital in Israel. Acknowledging a connection to Steinmetz, a controversial figure by Feldman’s own admission, may have put his success in a new light.
“Ziel is a very high-flying guy, but he was never in the families,” said a former colleague. “He wanted to establish that for his family. He wanted a generational business. But Rob Speyer is not in bed with Steinmetz.”
The opening of the XI gallery on April 25, 2018. Photo: Craig Barritt/Getty Images for XI Gallery
In 2015, HFZ made its most aggressive move yet, purchasing the empty 1.75-acre lot at 17th Street and 11th Avenue with a plan to build a large luxury condo and hotel. Before the sale, the lot had an unremarkable history, hosting a few houses, a string of gasworks facilities, a rail yard, and Edison Properties parking lots. But in 2009, the neighborhood around the lot started to change. Thanks to a Bloomberg-era rezoning and the reinvention of the High Line, West Chelsea very quickly became an Eden for high-profile architects looking to leave a mark on Manhattan. In little more than a decade, Frank Gehry, Thomas Heatherwick, Renzo Piano, Jean Nouvel, Zaha Hadid, and others planted expensive buildings that crisscrossed the High Line with shadows. Property values skyrocketed, and by the time Edison put the lot at 76 11th Avenue on the market in 2014, it was a very valuable tract of land. When the dust settled, HFZ had the highest bid: $870 million. It remains one of the largest residential-land sales in New York City history.
“Everybody gasped. No one could believe the price they paid for the land,” said Andrew Gerringer, a veteran real-estate marketer who has worked with HFZ on a number of projects. “Everybody thought it was a good area, but those of us in the development business were like, Jeez, this is a really high number.”
Feldman’s willingness to pay stemmed, in part, from his vision for the building he planned to erect there. Feldman believed the XI (variously pronounced ex-eye, eleven, eleventh, zee, or shee, like the general secretary of the Chinese Communist Party, depending on whom you ask) would be so spectacular that it would woo one-percenters away from the Upper East Side and Billionaires’ Row. The XI would embody what Feldman believed to be the ultimate 21st-century fantasy: a self-contained urban-resort life with spaces and amenities that made residents feel as if they were living in a hotel — a 75-foot swimming pool, a sauna, a wine-tasting room, and an art gallery.
Luxury-condo sales were booming in 2015, but even the most data-driven developers were rolling the dice. By spending $870 million just for the land, HFZ was starting in a very deep hole, and it would need to sell the XI’s 576,551 square feet of residential units for roughly $4,000 per square foot, a price rarely secured in neighborhoods that don’t abut Central Park. And that was assuming the market kept apace.
“Very few people in the office thought that the XI was a smart deal,” said a former employee. “There was no ability for any of us below Ziel and Nir to influence this decision. My guess is that Ziel liked the idea of it. He liked the attention it brought him, and Nir needed to grow the company and get big deals and keep money coming in the door.”
Developers are by nature optimists, and Feldman was no exception. When The Real Deal’s Hiten Samtani asked Feldman about criticism of the $870 million price tag, Feldman balked at the question, saying he had too much experience to let naysayers influence him. “It meant nothing to me,” Feldman replied. “It was actually kind of humorous.”
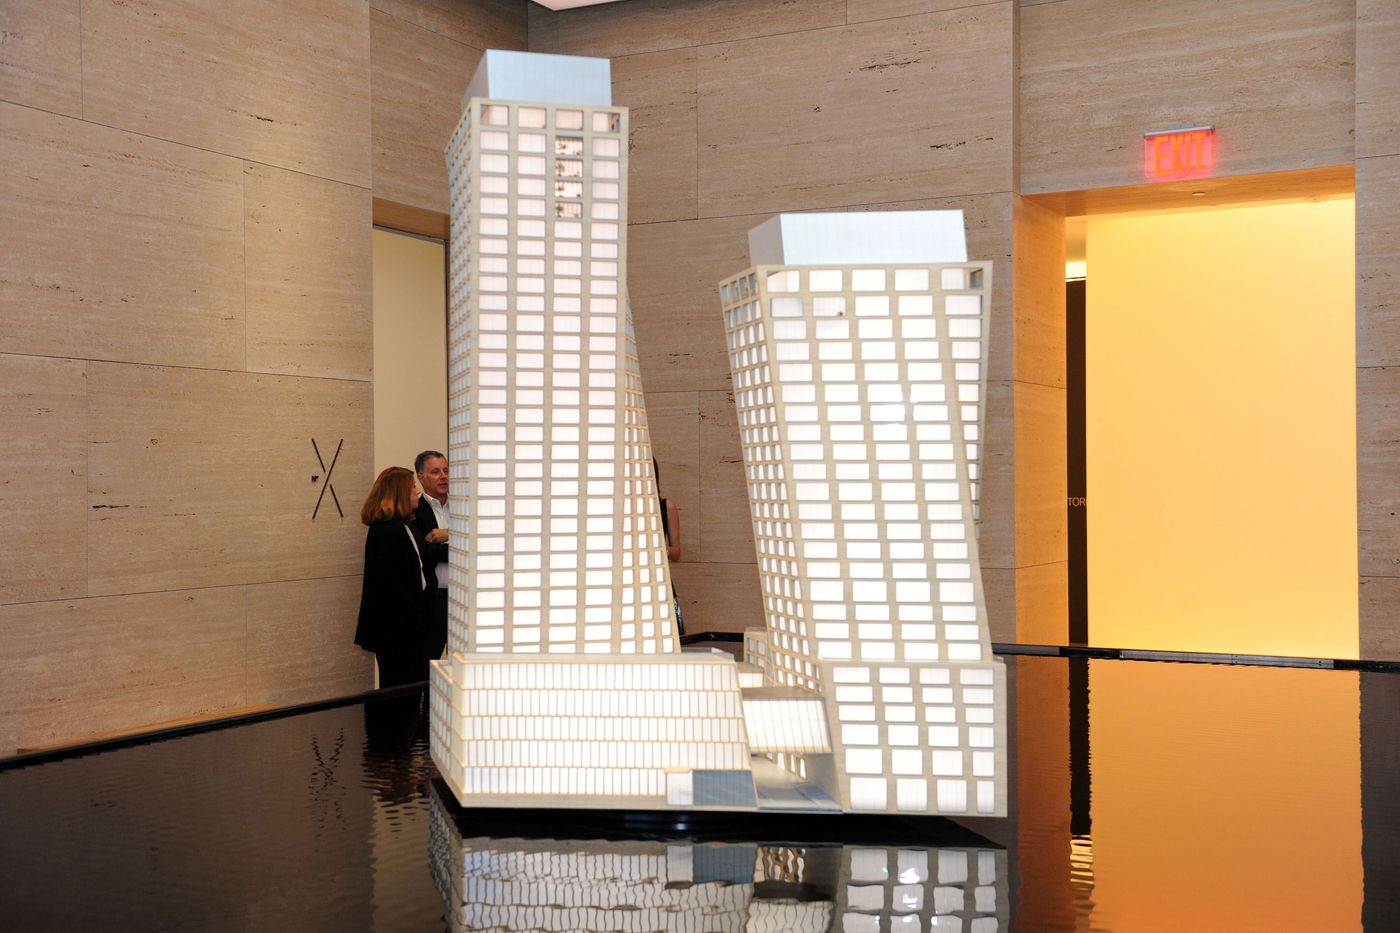
One reason Feldman shrugged off naysayers was because he had bagged Bjarke Ingels, one of the most sought-after architects in the world, to design the XI. Starchitects can charge as much as 25 to 30 percent more than their lesser-known colleagues, and Ingels was all but guaranteed to deliver a complicated, expensive design, but that didn’t matter to Feldman. Partnering with the young, swaggering Dane would send a message to the entire industry: HFZ was ready to leave its mark on the Manhattan skyline. The final plans called for the top floors of the XI’s two towers to cantilever over the shared base by 50 feet, so they seemed to be leaning, unnervingly, like the Tower of Pisa. Engineering reports talked of “torsional irregularity” and “gravity load induced lean,” which added to the “inter-story seismic drift.”
By January 2018, some 800 workers were employed at the site. Rebar shot out of the ground like fingers poised to pull the rest of the building up behind it. After the concrete was poured, Ingles’s design took shape, and the first of the building’s 11,000 travertine panels, imported from a quarry in Tivoli, was put in place. Someone called 311 to report “a building that is leaning south.”
From the start, some HFZ employees expressed apprehension about bringing Ingels onto the project. They knew Ingels would deliver a complicated — and expensive — design that would have a greater likelihood of hitting snags than a conventional building. And when the XI’s concrete settled, it did so in such an unpredictable way that the initial batch of windows didn’t fit into their frames, triggering one of a number of costly delays that befell the project.
“The true risk to a developer is the time and the cost of funds. That’s for the good developers who estimate everything properly and don’t take too much for granted,” said Barnett, who partnered with Feldman on the Belnord in the early ’90s and whose company, Extell, is responsible for two of the twiglike towers swaying over Billionaires’ Row. “There are cautious developers and there are ultracautious developers, and Ziel has never been either.”
Es Devlin’s “Egg” on display in the XI gallery in 2018. Photo: Johannes Schmitt-Tegge/picture alliance via Getty Image
By 2016, HFZ had grown to employ more than 100 people, and its Madison Avenue offices reflected the company’s fast success, looking more like a modern-art gallery than a real-estate development firm. Feldman regularly talked about the connection between art and real estate. “Artists tend to be frustrated developers,” he told Artnet in 2018. “Architects think they’re artists. Developers, we think we’re all of those things.” (He and Helene say some version of this to me again during our interview.) Employees and visitors alike rolled their eyes at some of the over-the-top pieces from the Feldmans’ collection on display at the office — including Patricia Piccinini’s The Student, a hyperrealistic pig-baby made with actual human hair, a Gimhongsok dog made of stuffed garbage bags cast in bronze, and the George Condo portrait Girl With Green Hair, which was auctioned at Christie’s for $437,500 after HFZ’s downfall.
Former employees’ descriptions of the art ranged from “zany” to “so, so, so terrible.” Everyone believed the art was an extension of their bosses’ approach to development. Feldman’s obsession with art, and the status his proximity to the art world conferred upon him, frustrated some. “Ziel was always focused on stuff that didn’t matter,” said a former employee. “He thought he was an arbiter of design, style, and taste. He’d sit in architecture meetings and bring his wife in and think that that was the important part of the business.”
The art wasn’t the only disconcerting presence in HFZ’s offices. Feldman and Meir, employees say, ran HFZ as a diarchy in which they shared total power. Employees who expressed professional opinions — or, several claimed, facts that contradicted the leaders’ points of view — were disregarded or ridiculed. One former employee, talking about her experience on a recent wellness podcast, described HFZ’s atmosphere as “icky,” “Wolf of Wall Street-y,” and “Machiavellian.”
Former employees said it was Meir, more than Feldman, who set the tone. By the time HFZ broke ground on the XI, Feldman was hardly involved in his own company’s day-to-day operations. Meir floated around the hallways, popping into people’s offices to grill them about HFZ projects. In addition to his talent for raising capital, Meir had a gift for numbers. At times, former employees said, it was as if the company’s true ledger existed only in Meir’s head. HFZ proposals were not submitted to investors until Meir looked over the numbers. Sometimes, Meir would ask employees to juice spreadsheets so projects looked better on paper. Occasionally, if an employee refused to alter a projection, Meir would ask the employee to send him the Excel spreadsheet, presumably so he could make the adjustment.
In the spring of 2018, HFZ opened the XI Visionaries Gallery, a 12,000-square-foot salesroom located in a storefront a few blocks from the XI. The space was unlike any sales gallery anyone in the industry had ever seen before. At its center were “multi-sensory installations” by Es Devlin, a British artist known for designing elaborate stage sets for Kanye West, Lady Gaga, and the Weeknd. At the gallery’s opening, men in black suits poured complimentary glasses of Macallan 25, which retails at $1,999 a bottle. One former employee estimated the total cost of the sales gallery to be at least $25 million. Units went on sale in the fall of 2018. Jeff Bezos reportedly showed interest in a penthouse before opting for a Madison Avenue spread. Graeme Hart, the richest person in New Zealand, snatched up one of the XI’s penthouses for $34 million.
Then the luxury-condo market started to strain under the weight of excess inventory. A 2019 analysis by StreetEasyestimated that a quarter of all new luxury apartments built after 2013 had not found buyers, an inauspicious indicator for a developer that had recently brought 236 glistening units to market. (Filings would later show that just 38 of those units, or 16 percent, were sold by the time HFZ went bust.) Feldman remained optimistic that his brand of luxury was strong enough to buck market trends. “It’s about the buildings — you can’t broad-stroke an entire market,” he told the New York Times.
Yet HFZ was already showing signs of distress. In October 2019, HFZ failed to pay an $8.2 million invoice to Pioneer Window, which had a $98 million contract for work on the XI. Initially, executives at Omnibuild, the construction firm overseeing the XI, weren’t surprised by the unpaid invoice. “We knew through the industry that they may be a little bit of a crazy bunch, but I guess everybody’s crazy in this business,” Omnibuild COO John Mingione told Crain’s. But not all of HFZ’s contractors could afford to be so patient. “GUYS — CABINETS ARE READY — I NEED ‘my’ MONEY,” Jan Efraimsen wrote in an email in November. Efraimsen’s company had been producing millwork for an HFZ building on the Upper West Side, and Efraimsen was trying to collect an outstanding balance of $163,652.90, a lot of money for his small operation. “I am desperate for money right now–anything will work,” he wrote in a follow-up email. “Unfortunately we just don’t have answers,” David Szczapa, a project manager at HFZ, wrote back to Efraimsen, who was later forced to lay off three of his carpenters. Szczapa’s hands were tied. By the end of 2019, it seemed as if all payments depended on Meir’s approval. According to three former HFZ employees, project managers would tell Meir that some contractor was complaining because they hadn’t been paid only to be told that he would handle it.
The unpaid invoices were the first flutters of HFZ’s tailspin. At the end of 2019, the FBI arrested John Simonlacaj, HFZ’s managing director of development, for offering lucrative XI contracts to Gambino associates in exchange for free work on his Westchester home. (He eventually pleaded guilty to filing a false tax return and was sentenced to four months in prison last summer.) This wasn’t Simonlacaj’s first arrest. In 2015, he had spent three months in prison for tax fraud. Simonlacaj had worked for Feldman going all the way back to PMG, and when he finished his prison sentence, Feldman allowed him to return to work, a decision Feldman now calls “a big mistake.”
“They just let him show back up. It was mind-blowing that they never acknowledged it,” one former HFZ employee said. “Why would they let a convicted criminal come back?”
Then COVID-19 hit, and a wave of existential dread swept through the real-estate industry. “We were overleveraged even before COVID,” said a former HFZ employee in the accounting department. “They were depending on acquisitions to pay the payroll, insurance, everything. So there was suddenly no money.” HFZ’s foreign investors were getting agitated. Yoav Harlap, an Israeli car importer and art collector who had given HFZ more than $20 million for a development on the Upper East Side and a $10 million investment in the XI, began pestering Feldman and Meir about repayment. Meanwhile, the Los Angeles–based hedge fund CIM Group, which had loaned HFZ $90 million to convert four prewar buildings on the Upper East Side, was pestering Meir about a late payment. “What’s the latest? Running out of time,” wrote Adam Gibbons, a managing director at CIM, one afternoon in July. “On it. 2 min,” Meir wrote back. Four hours later, Meir sent Gibbons a confirmation code showing he’d initiated a payment. The code turned out to be fake, according to CIM, as The Real Dealwould later report.
In the early days of the pandemic, Meir and his family, like many Manhattanites, decamped to the Hamptons. In 2013, Meir had knocked down a ten-bedroom beachfront “cottage” on Southampton’s Meadow Lane and built a modern 6,600-square-foot mansion. The home had been a gathering place for friends, family, and the occasional HFZ employee. Meir and his wife, Ranee Bartolacci, regularly hosted omakase nights, bringing a sushi chef from Manhattan for private dinners. Sometimes omakase nights would be followed on Sundays with pizza catered by Nolita’s Pasquale Jones.
“Nir spent more money than God,” said a former HFZ employee. “No one was clear where the money was coming from. What success had the company realized that we were unaware of?” Feldman’s complaint against Meir alleges that Meir’s monthly American Express bill often exceeded $400,000. Meir spent hundreds of thousands on wine and kept a stable of luxury cars including five Mercedes G-Class wagons and a 1996 Porsche 911 Turbo valued at $300,000.
Back at the office, I ask the Feldmans why they never questioned Meir’s spending. In retrospect, Feldman says, he knew very little about Meir’s personal life. He and his wife claim they’d assumed the money had come from Bartolacci’s grandfather, not from HFZ. That assumption might be plausible if Meir had merely been someone they occasionally bumped into at Hamptons parties and not someone with whom Feldman had entrusted his multibillion-dollar business or someone whom Helene, minutes earlier, called an adopted son.
“It’s hard to describe,” Helene pleads. “You have to start with the mind-set that there was no reason not to trust him.”
According to Feldman, a series of incidents in the fall of 2020 tipped him off to how bad things had gotten at his company. One day at the office, Feldman said he checked in on a group of accountants carrying out an audit for an HFZ investor. When Feldman asked if they had everything they needed, the accountants told him Meir had instructed them not to bother Feldman because he’d recently had open-heart surgery. (He had not.) Then Feldman said he was alerted to documents bearing his signature, which he alleges Meir forged. Feldman also found out about a term sheet that he claims Meir doctored to look as if HFZ had received a $900 million loan from JPMorgan Chase in 2020. (HFZ had received the loan in 2019.) The final straw came when Feldman spoke to an investor who said Meir had fabricated a Korean investor, even enlisting someone with a Korean accent to dial into a phone meeting, according to Feldman’s complaint. Feldman fired Meir in December 2020. It was the last time the two spoke.
Former HFZ employees were quick to cast Meir as a rogue, but their descriptions of Feldman were more complex. He was aloof or asleep at the wheel. No one could say how much Feldman did or didn’t know about the way Meir was handling HFZ’s business. But they agreed that Feldman reveled in the success Meir brought to HFZ, and they blamed him for the company’s downfall just as much as they blamed Meir.
“You get complacent. Of course I’m to blame,” Feldman says, admitting for the first time that he made mistakes beyond trusting Meir. “But there really is no scenario, if you really study it, where it turns out to say that Ziel may have known, should have known, or was involved with it.”
That line of defense hasn’t played well in court. In March, the Appellate Division of the New York State Supreme Court said Feldman was fully aware of Meir’s role and authority at HFZ, ruling that he was liable for the claims brought by Harlap, the Israeli car importer. “For several months, Feldman had notice of all the underlying transactions, as well as the default thereunder and negotiations to resolve it,” the court wrote. “He then received actual copies of the allegedly unauthorized agreements, signed by Meir and one bearing his own ostensible signature, but conducted no investigation and made no objection for three months prior to being sued.”
Because Feldman offered personal guarantees on HFZ projects — risking his net worth, some $110 million — the company’s collapse has come at considerable personal cost. A year ago, the Feldmans sold their mansion in the Hamptons for $50 million, and they recently reduced the asking price for their 6,100-square-foot, black-marbled penthouse at the Marquand, an HFZ building on 68th Street and Madison Avenue.* They’ve sold off most of their art collection as well.
“People tell you all the clichés: ‘Oh, your family will be so much better off.’ Yeah, it’s very sweet and very nice. You read The Daily Stoic, it’s wonderful,” Helene says, rolling her blue eyes back. “I think, for us, it has really given us a chance to reset. It has changed our life drastically, certainly from a lifestyle perspective. No, we don’t have the house in the Hamptons anymore, and we don’t know what tomorrow’s going to bring. But as a family, and speaking as a mother, I’ve seen my family and children rise to the occasion and then some.”
When Meir listed his Southampton home last year, Feldman filed a lawsuit claiming the beachfront mansion had been HFZ’s property all along. Feldman accused Meir of forging his signature — again — to gain control of the house. In May, New England Patriots owner Robert Kraft bought the home for nearly $43 million. (The vast majority of the proceeds ultimately went to Bartolacci, under whose name it was registered. In a deposition, Bartolacci claimed the house was a birthday present but was unsure who had actually put up the money to purchase the property, per The Real Deal.) According to Feldman’s suit, Meir continues to spend like a Saudi prince, blowing hundreds of thousands on fine wine, strip clubs, private jets, and yachts. He and Bartolacci also spent $1.5 million on gold coins and bullion.
Meir is still on the hook for a $19 million judgment Harlap won against him. Harlap has alleged that, in order to avoid payment, Meir transferred his assets to Bartolacci and fled New York. At least part of this is true: Last summer, Meir and his family rented a modern bayside home in Miami Beach for $150,000 a month. In September, the landlord sued Bartolacci, whose name is on the lease, saying she had made some unauthorized modifications to the rental, which included the installation of a new dock, the replacement of the natural grass with synthetic turf, and the construction of a cage for the family’s bearded dragon.
Of the half-dozen major developers interviewed for this story and many more real-estate insiders, none would predict the end of either Meir’s or Feldman’s careers. That’s because their futures depend on whether they will be able to raise money, and as one former HFZ employee put it, the market’s blind hunger for New York real estate is insatiable.
“People are so hot for New York real estate — private investors are so eager to put money into New York real estate — that they don’t even pay much attention to the people they’re investing in,” the former employee said. “They just gave HFZ hundreds of millions of dollars because they trusted Nir or Ziel? It all kind of made me see how unsophisticated private-lender capital was. Banks were lending and then turning a blind eye for years. HFZ borrowed billions on what? A personal guarantee? A one-page balance sheet Ziel had?”
In the meantime, the luxury real-estate market has moved on without HFZ — sales of high-end units remain more than 50 percent higher on a monthly basis than they were in 2015. As for Feldman’s shining star, the XI, work on the building stopped in 2020, and the construction site has been eerily quiet for the better part of two years. In December, the Witkoff Group partnered with billionaire Len Blavatnik to purchase HFZ’s stake in the project for $900 million at a debt auction. Witkoff found a new contractor to oversee the site, and in the past few weeks, there have been signs that construction is restarting. Scaffolding has been repositioned, and the cladding is again creeping up the sides of the towers, securing the XI’s place in Manhattan’s skyline one travertine panel at a time.
*A previous version of this article said the Marquand, an HFZ building on 68th St. and Madison Avenue, is mired in litigation. In fact, HFZ is not involved in litigation over the Marquand and the story has been updated to reflect that.

Genuine estate tendencies are setting up to shift, and it can be really hard for would-be prospective buyers and sellers to continue to keep up.

When most stories target on authentic estate for the common house owner, the luxurious market place is also staying impacted.

CTV News spoke to a Realtor about what individuals included in serious estate at that stage need to know before they get started procuring.

Her solutions will most likely be useful to individuals at all levels of the marketplace, not just those people working in qualities well worth hundreds of thousands.

 Dilemma: What developments have you seen in the luxury sector around the last several months?

In the previous handful of months and to day, we are going through a layering of matters that have an impact on genuine estate marketplaces – provide chain issues, inflation and interest level hikes for instance.

The luxurious current market can be an $8-million residence or a $50-million household, and there are probable variances in how they fluctuate.

The homes have to be priced strategically to mirror the current sector disorders and in anticipation of how we imagine the current market will enjoy out.

Men and women still want to negotiate irrespective of the cost level every person wishes to really feel like they have won.

We at present see tighter movement in the mid-tier of the luxurious genuine estate current market, around $6 million to $8 million. The bigger ends of $10 million-as well as and $20 million-as well as go on to see identical degrees of exercise relative to former months prior to the curiosity charge hikes.

 Problem: Do you expect to see income reducing or escalating in the coming months?

 Remedy: Realtors who are actively functioning in the marketplace will start out to see market shifts prior to the stats coming out that bear fruit to what they are suffering from.

We are seeing a tiny sluggish-down in revenue, and this softening will possible proceed in the coming months.

When new procedures are applied, and also getting occur off a stellar preceding calendar year of (exponential) raise in profits points, it stands to motive that there may be a “hold out and see” mindset among the purchasers and sellers alike as they try to make sense of a altering market place.

Offer and demand from customers are generally critical things, and at the moment, the source is nonetheless low.

The source/demand ratio needs to be understood from a granular neighbourhood perspective and from the property style (condominiums, hooked up properties and single-relatives residences). It is apparent that areas and neighbourhoods and property sorts really don’t respond the identical way across the board.

 Concern: Luxurious households are usually on the market for some time (for example, this mansion has been for sale for two yrs, and the value recently dropped. Why is this the situation?

 Respond to: Just place, the extra costly a home is, the variety of customers that can afford to pay for that home diminishes.

An critical note is that the number of days on the industry is, to a particular diploma, correlated with worth and pricing – whilst it is intriguing that you can have an astounding assets that you put on the industry, and if the ideal customer is there, it sells speedily.

 Problem: What can you tell us about the customers of luxury houses, and have you identified the overseas buyers tax a deterrent?

 Solution: B.C.’s luxury potential buyers can come from any place, but there are several area potential buyers.

Of system, as Canada has constantly had a big immigrant populace and is identified for its range, persons often want to shift to Canada. When they search at the place in Canada they want to relocate, B.C. stands out with its scenic pure mountain and h2o landscape, excellent schools and cultural range.

Our buyers are coming globally, although most surface to have Canadian citizenship or long term residency.

(The tax) is an significant matter and a single we should really be spending close interest to, but queries about it are far better directed to provincial and federal genuine estate associations.

What I can inform you is we will not anticipate the international buyers’ tax will have an affect on our luxurious assets listings, as several prospective buyers we are observing are from the Reduced Mainland, Okanagan and Canada in standard.

 Some of Wilson’s solutions have been edited for clarity and duration.
North Miami Mayor Philippe Bien-Aime added $148,000 last month to his commanding lead in the race to be the next Miami-Dade County Commissioner representing District 2. As was the case in months prior, the majority of his gains came from the real estate industry.
Bien-Aime has raised more than $525,000 since he filed in December 2020 to run for the seat Commissioner Jean Monestime must vacate in November due to term limits. That’s just $3,000 shy of what his five competitors — educator Wallace Aristide, nonprofit executive Marleine Bastien, teacher turned firefighter William Clark, former North Miami Mayor Josaphat “Joe” Celestin and Monique Nicole Barley-Mayo — have raised combined.
As of April 30, he still held about $431,000 between his campaign account and political committee, Progressive Advocates for Change, which took in the preponderance of his donations last month.
More than 30 people donated to Bien-Aime in April, with checks ranging from $25 to $15,000.
Stanley Tate Builders, a construction company located in Miami, gave $7,000. So did two companies that shared an Aventura addresson Bien-Aime’s donations ledger — “Downtown Realty Investments LLC” and “Bird Bowl Ocean,” — for which the Florida Division of Corporations has no record.
Outside the real estate sector, Bien Aime received $10,000 apiece from Coral Gables-based physician and rehab specialist Carolina Ramirez, commercial litigator Benjamin Brodsky, and Kevin Adler, the founder and CEO of Miracle Messages, a nonprofit that assists homeless people.
Bien-Aime spent more than $27,000 in April. More than half that, $16,000, went to Plantation-based Democratic consulting firm MDW Communications.
He paid $5,000 to Zafe Pa Nou, a Haitian-language radio show, for “communications.” Citing the same reason, he paid $1,000 apiece to Jean Sony Zulerion, the founder of Haitian TV and radio station Bpx TV Reseau, and Bernard Gotchen, whom Gazette Haiti said is a journalist.
The remainder of Bien-Aime’s spending, roughly $3,300, covered general upkeep costs, including accounting and fee processing.
Aristide, a former principal at Miami Northwestern Senior High School, raised $14,000 in April, all of it through his political committee, Miami District 2 United. That brought his total collections since filing to run in December 2020 to about $260,000.
Of that, he has about $201,000 remaining.
Like Bien-Aime, most of Aristide’s haul in April — $11,000 — came from real estate businesses. His largest contribution, $5,000, came from a pair of companies belonging to lawyer, political fundraiser and real estate developer Chris Korge, who is also the elected finance chair of the Democratic National Committee.
Aristide spent about $1,500. Nearly all of that covered a donation to Restart Community Services, a nonprofit that benefits homeless individuals and families.
Pulling up third in April gains, as well as in overall fundraising, was Bastien, a licensed clinical social worker who runs the Family Action Network Movement in Miami, a low-income community advocacy organization.
Since filing to run in September 2019, Bastien has amassed about $221,000. She had more than $180,000 of that left by the end of April.
Last month, her campaign reported taking in $11,500. Roughly half that came through individual donations.
Twenty-five people gave Bastien checks of between $50 and $1,000 in April.
Bastien also gained $5,000 from IMG Equity Group, a commercial real estate firm that gave to her campaign through five subsidiaries.
Of the $2,000 Bastien spent, half went to Sinal Consulting Group in Miami. The remainder covered office rent, a cell phone payment and a headphone purchase.
Clark, who worked as a teacher in Miami-Dade Public Schools before becoming a county firefighter, added more than $6,000 to his campaign coffers in April. While he may not have raised as much as the race’s three fundraising front-runners, he worked hard for what he got.
More than 90 people gave to Clark last month. Checks ranged from $3 to $500. Most were for less than $50.
He’s raised $46,000 since filing to run in March 2020. Of that, he has $25,000 remaining.
Clark didn’t entirely eschew corporate and organizational contributions. He accepted $1,000 apiece from Development Services Solutions, a Miami-based construction consulting business, and a subsidiary of nonprofit Jubilee Community Development Corporation, a public charity that provides affordable housing to low-income families in Miami-Dade.
He spent $3,600, almost all of it on campaigning, including flyers, banners, fundraiser food, postage, gas, an event tent and website fees.
Celestin filed to run for District 2 in November 2019. Since then, he’s only added funds to his campaign accountin four months total. April was not one of those months.
He did, however, spend $3,400, bringing his campaign balance down to $17,000. All the money was for office rent.
Barley-Mayo again raised nothing. She also spent nothing, balancing her campaign accountout neatly at zero funds raised and spent since she filed for the race last July.
District 2 spans portions of Miami, North Miami, North Miami Beach, Opa-locka, Hialeah and the unincorporated neighborhoods of Liberty City, North Dade Central and Biscayne Gardens.
Candidates faced a May 10 deadline to report all campaign finance activities through the end of April.