How the Tax Code Can Help Investors Keep Their Real Estate Wealth Stable During Retirement

How the Tax Code Can Help Investors Keep Their Real Estate Wealth Stable During Retirement

By David Wieland.

Due to the fact unique buyers (not corporate entities) own additional than 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of household rental authentic estate, you most likely have some customers who hold house assets and act as landlords for people attributes. With rising fascination costs and costs, clientele with expense homes may be sensation a pinch in income.

In my working experience, these pressures, along with a myriad of other reasons which include a desire to get out of the landlord small business, are top quite a few authentic estate traders to take into consideration promoting. No matter of the motive for wanting to unload assets, they all very likely have just one popular intention – to guard as considerably of their wealth as doable when they provide by lowering the taxes thanks when they market an expenditure residence.

If you have clientele (significantly all those nearing retirement age) who are seeking to offload some genuine estate investments to fund their golden many years, there are possibilities for supporting them access residual earnings devoid of shedding price to money gains taxes. To keep away from that 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} strike from the cash gains tax when your clientele provide real estate financial commitment attributes, you can display them how to consider benefit of a tax shelter that’s been all-around for 100 decades: §1031 of the U.S. Tax Code.

Comprehending 1031 exchanges

1031 exchanges (also referred to as like-kind exchanges) are accessible to any individual who has owned real house held for business or expense purposes, for at least two several years. A 1031 exchange allows traders to defer some, or even all, of their gains from the sale of these qualities. To leverage a 1031 trade, an investor has to guarantee the money from a authentic estate financial commitment home sale is reinvested (or “exchanged”) in like-sort assets, which the IRS broadly defines as in the same way valued serious estate held for expense or business reasons.

1031 exchanges also provide possibilities for your clients to protect generational prosperity. For example, your customer can market an investment decision property at a earnings, then reinvest that income in like-sort real estate in an hard work to hold growing wealth for generations to appear. 

The U.S. Tax Code delivers for beneficiaries to acquire belongings from an estate on a stepped-up foundation, which usually means the asset is permitted its sector value at the time the benefactor dies. Normally that means the stepped-up basis will be bigger than the cost at which the benefactor acquired the asset. Due to the fact taxable cash-gain money is figured centered on the advertising rate minus the foundation, that superior stepped-up foundation can drastically minimize the beneficiary’s taxable funds-acquire revenue if they pick out to sell the inherited asset.

So each time your customer conducts a 1031 trade, they’re locking in benefit and deferring taxes. Their foundation is going to be decrease or even zero, but they’ll also have advancement in the relinquished price of the previous property. This permits your consumers to steer clear of tax casualty or devastation and permits their investment’s benefit to potentially expand for many years to arrive.

How serious estate can create options for passive actual estate financial commitment income

Numerous real estate investors could be on the lookout to drop some of the duties of currently being a direct trader. You may possibly, for case in point, have clientele who are exhausted of staying landlords and residence professionals as they enter retirement, in particular just after the tough yrs quite a few may perhaps have confronted for the duration of the pandemic when the countrywide moratorium on evictions gave tenants reduction from rent payments. That ate into investor hard cash flow and even turned it detrimental in some scenarios. These encounters have led some investors to shift their watch of authentic estate as an asset class to keep in their retirement several years.

Below is where by investors can be released to a genuine estate asset course they don’t have to control: a Delaware Statutory Believe in (DST), which is a authentic estate expenditure vehicle that gives folks fractional obtain to a commercial real estate home. (You do not have to are living in Delaware to take part in a DST.) A DST can present many possible advantages for clientele in a phase of everyday living when they want to drop liability and threat.

A DST presents an investor entry to real estate financial investment possibilities comparable to these owned by significant institutional buyers like insurance plan organizations, pension resources and actual estate expense trusts (REITs). In addition to permitting for passive serious estate financial investment, these options can also give your client obtain to much larger house investments than they could very likely afford to pay for on their own, since buyers share possession of the belief with other buyers.

Given that DSTs let for minimum amount investment decision quantities ($25,000 for a hard cash investor and $100,000 for a 1031 trade investor), your clients can build their possess passively managed, custom-made and diversified portfolio of real estate homes — like university student housing, industrial, multifamily, retail and warehouses — without having acquiring to play landlord. Your shopper can also commit in house anywhere in the nation, potentially steering clear of the will need to spend cash flow taxes in states that really don’t levy them. With a DST, the residence is owned and operated by a sponsor who is accountable for keeping the assets, securing buyers, revenue distribution for traders and far more.

By using a 1031 trade to devote in a DST, your client can transfer from a one asset class (say multifamily housing) to just one that is much more diversified. This is an specially excellent move for a person in or approaching retirement. You really do not want to see your client going back to function or suffering from a reduction in way of living since a genuine estate investment decision starts getting rid of value and cash flow opportunity. Variety is crucial. Investing in distinctive real estate sectors in unique regions of the nation can assistance secure price.

Comprehension the risks 

DSTs are not right for absolutely everyone, however. They have their possess unique hazards to consider right before earning an investment.

A Delaware Statutory Have confidence in is essentially a serious estate portfolio in an expenditure safety wrapper. Investments never always fulfill return expectations, and at times tasks really do not expand as substantially as predicted. Your consumers can assistance control individuals challenges by doing work with an seasoned sponsor who duly evaluates alternatives before releasing choices.

An additional possible draw back to DST investment is that authentic estate is not quick to liquidate. A DST won’t in good shape the bill for clients who want an investment decision they can turn into money quickly as needed. Most DST choices will have essential keeping intervals of 5 to 10 several years.

And DSTs will also carry a variety of expenses, which include administration expenses, presenting bills and acquisition fees, that immediate investment decision properties will not. Your customer will will need to get these expenses of expenditure, or “load,” into account when looking at irrespective of whether they can regain and/or multiply the fairness they devote.

So, if you’re wanting to help true estate trader shoppers preserve and develop property even though also sheltering them from key tax liabilities, leveraging a 1031 trade and investing in a DST may perhaps offer a option to aid safeguard funds, crank out revenue and lower publicity to industry volatility.

Whole disclosure. The info supplied below is not expenditure, tax or fiscal assistance. You really should talk to with a certified skilled for advice relating to your precise condition.

======

David Wieland is founder and CEO of Understood, a serious estate wealthtech agency that gives Investment decision Property Wealth Administration for investors.


How to invest 0,000: Best ways to grow your wealth

How to invest $100,000: Best ways to grow your wealth

Acquiring $100,000 at your disposal can current a wide variety of financial investment alternatives. Dependent on your financial needs and plans, the income can be put to do the job to create passive cash flow, enrich your retirement readiness and even start a new business that can offer higher prosperity in the several years to come.

How to commit $100,000 

The initially action when you have any total of money to make investments, irrespective of whether it is $100,000 or some other sum, is to think about your short- and very long-term money strategies and objectives. It is also essential to imagine about when you could possibly want to obtain the money and assess your stage of  danger tolerance.

“While undoubtedly more dollars give you perhaps far more flexibility to divide the belongings and use them for various functions, thoughtful conclusion-generating ought to stay continuous,” says  Heather Winston, licensed fiscal planner, CWS, and director of merchandise, tips, and organizing at Principal Money Group.

As you’re sorting via these things to consider, bear in head that diversification is constantly a superior approach, each inside of and throughout asset types, to decrease volatility. 

You can devote in the inventory market place

There are a number of means to spend in the stock market which include making use of a regular brokerage account to obtain shares in expansion industries that can assist your income develop even more or by obtaining dividend-paying stocks and bonds that can deliver continuous, ongoing, passive cash flow. Bonds are a different useful alternative, says Jason Escamilla, CFA, founder, and chief financial investment officer for the wealth management business Affect Advisor. 

“Bond yields have not been this substantial in above a 10 years. This implies you get a respectable return with reduced-risk, specifically shorter-expression, govt bonds ideal now, even for long-term retirement savings,” states Escamilla.

Exchange traded funds (ETFs), which are commonly a blend of stocks and bonds can also include diversification to your portfolio.

Or save for retirement

Putting revenue into a tax-advantaged individual retirement account (IRA) is another wise option if you have $100,000 to spend. Using this action can offer the gain of decreasing your yearly cash flow and consequently your tax load.

“Work with your economical advisor and tax qualified to determine which sort of retirement account—such as a classic IRA or a Roth IRA —might make the most perception primarily based on your recent and expected tax bracket,” claims Scott Thoma, accredited economical planner with Principal.

You can construct your crisis fund and pay out off credit card debt, way too

Getting six months of dwelling expenses in an crisis fund is also an crucial rule of thumb. With $100,000 at your disposal, location aside some cash to greatly enhance your wet working day reserves is a good preference. And in the present-day significant-curiosity rate environment, paying down personal debt is yet another savvy move.

“It’s important to focus on money steadiness and stability, and that could get started with making certain you have a steady personal debt place such as addressing substantial-fascination, non-deductible credit card debt initially and functioning towards creating or replenishing an crisis fund,” suggests Thoma.

Make investments in genuine estate 

With $100,000 at your disposal, you may also want to take into consideration more substantial-image contemplating in terms of your investments and contain actual estate choices.

Actual estate financial investment trusts or REITS are an financial commitment automobile that contains income-developing qualities these kinds of as business office buildings, malls, apartment buildings, and a lot more.

“REITs give go-through profits to person traders. They can be beneficial for people on the lookout to acquire obtain without the need of getting the know-how or time to handle a significant range of homes,” states Sameer Samana, CFA and senior global Sector strategist for Wells Fargo Expense Institute.  

Possessing assets right, such as getting your first household or an financial investment property this kind of as a single family household or apartments to rent out and make passive earnings, is an additional way to improve your dollars around the long time period. 

Not only does real estate commonly respect about time but it also arrives with some tax benefits. The expenses related with owning a rental property can be deducted like residence taxes, mortgage desire and even management service fees if you use a assets manager.

Look at peer-to-peer lending 

Peer-to-peer (P2P) lending provides a range of positive aspects including potent historic returns and the capability to produce an ongoing source of passive income. This form of investing usually involves lending revenue to persons by way of an online platform this kind of as Prosper, Upstart, Kiva,  or equivalent businesses. The revenue you lend is then repaid with fascination.

“P2P lending performs finest for compact traders who also like to roll up their sleeves and do extra function and who get pleasure from remaining element of P2P lending possibly from an affect or social betterment perspective,” states Escamilla. 

There are some downsides to maintain in thoughts even so. When taking part in P2P lending, your income is not obtainable should really you have to have it immediately or for any unexpected causes. There may perhaps also be risks when lending this way.

“P2P lending lacks liquidity or ‘resale value’ if you have to have your money again faster,” continues Escamilla. There may well also be credit risks related with the borrowers or possible dangers tied to the lending system itself should really it fail or go out of business enterprise unexpectedly. The base line is due diligence is very significant in advance of investing.

Start off a side hustle or small business

Starting up a side hustle or compact business enterprise can be a excellent way to create an further supply of income to supplement your salary or even exam no matter if a organization thought has the possible to increase. But here much too, there are hazards, including that the small business will not thrive. 

With this in brain, it is a excellent thought to seek advice from specialists before investing much too significantly and restrict the volume of money you devote to this sort of a approach.

“If the side-gig [or business] is too significantly outdoors your lane, feel really hard about pouring methods into it,” says Escamilla.

How a teacher and real estate agent built wealth with passive income

How a teacher and real estate agent built wealth with passive income

The world wide web is flooded with tales of men and women applying some variety of so-identified as passive money scheme to get wealthy swift, irrespective of whether they are cashing in on straightforward YouTube ad dollars or investing in the most recent meme stock. It’s tricky not to get suckered into the guarantee of earning massive bucks without having functioning a classic working day position.

Numerous periods, these procedures aim on actual estate. But most genuine estate traders will explain to you that you can’t make cash just putting in negligible energy as the world wide web would have you believe that. Just ask Tiffanie Vendryes. 

Courtesy of Tiffanie Vendryes

Lured by the thought that she could make income from obtaining up rental houses in 2015, Vendryes, now 37, purchased 3 units in Florida that housed up to 7 tenants. 

But Vendryes rapidly realized the tricky way that passive cash flow isn’t all it’s cracked up to be often. “I was blinded by how a great deal revenue [I could earn], and I didn’t notice all of that would go into retaining the home,” she claims candidly. 

Vendryes states she selected properties that were being more mature, wanted perform, and were being in low-cash flow regions. As a substitute of sitting back again and raking in the revenue, she was overwhelmed dealing with late lease payments, evictions, and expensive repairs, which includes fixing a leaky roof and replacing the water heater and air conditioning models. “I failed, and I lost funds,” she admits. 

But Vendryes suggests the practical experience, whilst harrowing, taught her vital lessons that helped her make up her existing web worthy of of approximately $565,000. Here’s how she bounced back again. 

Playing the true estate match in Florida

Following graduating from Stevens Institute of Engineering in 2006, Vendryes experienced about $25,000 in university student loan personal debt, mostly thanks to grants and scholarships. She landed a high-having to pay work in tech sales—earning amongst $70,000 and $130,000 in excess of 3 years—and lived frugally, at periods getting up to a few roommates. Slowly but surely Vendryes was able to begin setting up her prosperity, and by the time she turned 25, she suggests she experienced saved up about $100,000.

But then the 2008 monetary crisis hit, and Vendryes was laid off, prompting her to move South and shake up her profession. “I moved to Florida and got into training,” she states, including the shift from tech sales to instructing meant having a key pay back lower from $100,000 to about $40,000. 

Yet with her price savings, Vendryes was ready to acquire a dwelling in 2010 in Palm Seaside County. Five yrs later, the worth enhanced by far more than 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}—jumping from $118,000 when Vendryes acquired it to $190,000 when she bought it. 

With section of the proceeds from her household sale, Vendryes bought into the serious estate sport in a huge way, acquiring 3 investment decision attributes more than the training course of 2015 and into early 2016. But the luck did not maintain. 

The fixer-uppers were being within just her spending plan, but they came with a host of routine maintenance challenges and promptly became money pits. Not to mention the men and women complications: Vendryes suggests she had tenants fighting with each individual other, contacting the cops on every single other, and calling her about their quarrels—and currently being a landlord became a substantial time suck and an emotional drain. 

“I made a decision that this in all probability wasn’t the greatest financial investment method for me,” Vendryes says. In just six months, she unloaded the properties, advertising at least a person at a reduction.

Developing assorted earnings streams 

While Vendryes struggled to get it proper in rental genuine estate, she never ever stop her working day career in instructing. And obtaining a whole-time job helped her remain afloat when this other money stream wasn’t functioning.

That is just one of the major takeaways she suggests: have many gigs. Vendryes, now the mother of a 2-year-previous, received back again into the rental home match in 2019, and she opened up her very own actual estate brokerage. But she also retains her training work.

It turns out that buying the rental qualities sparked Vendryes’s curiosity in being additional than an proprietor. “When I was buying all those three attributes, I would often come to feel poor asking my real estate agent far too a lot or likely to see too numerous points,” Vendryes claims, including she received her very own license in 2016. That way, she could go glance at all the homes she preferred to right before building an offer—guilt-free. Not only that, it had the added advantage of conserving her cash as both equally a purchaser and a seller. 

Immediately after taking some time to regroup, Vendryes acquired a two-bed room condominium in 2018 situated in a nicer community with the plan that she’d finally lease it out. A 12 months afterwards, it started out making revenue. This time, with secure tenants and negligible drama, she earns about $6,000 in once-a-year rental income. Additionally, Vendryes doesn’t contact the vast majority of the earnings. As an alternative, it goes into an account so if there’s some routine maintenance challenge with the condo, the price tag isn’t coming out of her everyday funds. She at the moment has 1 rental residence and a townhouse that she owns and life in. 

Previous year, Vendryes also opened her own authentic estate brokerage, Grace Realty Team. She has 1 agent functioning for her. So significantly this yr, they’ve bought $2 million in serious estate, which Vendryes suggests interprets into approximately $38,000 in commissions for her. 

And thanks to tenure and buying up more responsibilities, Vendryes has boosted her educating income to about $79,000 a yr as she operates as an interim assistant principal and remote higher school math teacher.

The early setbacks aside, Vendryes suggests she seriously likes actual estate and enjoys on the lookout at homes and displaying homes. “It’s essential to do a thing that you like so that it doesn’t come to feel like you’re doing a ton of do the job,” she states, including that while her educating task is flexible, she even now depends on her mom for babysitting in get to juggle the authentic estate company, her training, and the obligations of a landlord. 

All reported, Vendryes calculates she’s on observe to make about $123,000 this year. With her present-day home value (she bought a townhouse in 2021 that’s valued at above $400,000), retirement personal savings, and investments, she’s wanting at a internet worth north of $500,000. And she does not have any outstanding credit card debt.

But she’s the initially to admit it’s been a good deal of hard do the job. “My story has not been one of effortless results. I got laid off from my initial work. I went into education and learning at much less than 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of what I was building in advance of. I manufactured bad possibilities in genuine estate,” she states, noting that by way of it all, she’s been capable to accumulate wealth. “It’s via self-discipline, and it is really hard work, and it’s through discovering from my blunders.” 

Perhaps the most important lesson? It can take hustle. “It’s not genuinely passive—everything usually takes get the job done,” Vendryes suggests.

Young Buyers Focus on Investment Properties to Build Wealth

Young Buyers Focus on Investment Properties to Build Wealth

A growing amount of youthful grown ups are charting a unique path toward making prosperity as a result of homeownership, prioritizing getting an expenditure house before a major home, in accordance to a new survey by Mynd, a firm that leverages technologies instruments to assist traders acquire, finance and regulate one-family rental qualities.

Forty-a few p.c of people younger than 40 say they are thinking about becoming “rentvestors,” who continue to rent their have home even though shoring up income from an financial investment residence, Mynd’s 2022 Buyer Insights Report exhibits. That compares to just 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of toddler boomers and 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Gen Xers who are utilizing the exact same prosperity-setting up technique. Some to start with-time buyers see this as an prospect to make more money and much better afford a life-style in larger sized, extra high-priced markets, the report notes.

“Young folks are discovering that shopping for an financial investment house offers them the best of equally worlds: They can live where ever they want, which includes towns the place they can not yet afford to pay for to obtain, and continue to turn into home owners, which, as we realized in our survey, is still viewed as an significant portion of their American desire,” states Mynd founder and CEO Doug Brien. “Buying an financial commitment assets usually means they can go in which their everyday living, their work and their feeling of purpose usually takes them without the need of getting tied down, and they can even now profit from the diversification, appreciation and tax benefits of authentic estate investing.”

As the economic climate teeters on the brink of economic downturn, diversifying a portfolio might become a bigger priority for future consumers. Brien notes that numerous millennials, who came of age for the duration of the Wonderful Recession in 2008, viewed their moms and dads and other folks confront wonderful economic loss simply because they were overleveraged on their home loans. “This cohort is also extra skeptical of the stock and bonds market place,” Brien states.

But young grown ups look optimistic about real estate’s long-time period likely. Brien suggests he thinks quite a few of the younger folks getting financial commitment houses do not necessarily see it as a move toward buying a key home but as an investment decision that will dwell alongside their home one day.

The Distant Investor

Distant investing is one more pattern aiding far more very first-time investors get the leap. A lot more than 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the qualities Mynd manages are owned by out-of-state traders. The business has predicted that number to mature as technologies makes it less difficult to get and manage financial investment homes from afar. That doesn’t seem to be a frightening considered to people: Seventy-two per cent of the extra than 1,000 survey respondents say they’d take into consideration shopping for an investment residence in a distinctive town or state than wherever they live.

“For many years, the serious estate expenditure course was seen as way too complicated and scary for quite a few consumers,” Brien claims. “Fast forward to currently: Individuals now have entry to a slew of applications and platforms that demystify the real estate financial commitment system.” He included that Mynd’s mission has been to support encourage a new crop of investors “who have been formerly as well intimidated by serious estate or had been constrained to investments inside commuting distance.”

Tech residence administration firms have been introducing applications to assistance amateur and skilled traders alike locate, finance, buy and handle properties remotely.

As recession fears mount, solitary-loved ones rental investments could increase into an even far more interesting asset course, Brien says. “As inflation rises, rents are certain to increase, which increases possible cashflow for residence owners.”

20-8 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of study respondents say they’re taking into consideration buying an financial investment property now, regardless of the present financial weather. “As the Federal Reserve increases curiosity prices in an effort and hard work to tamp down inflation, that can impression demand for rental houses, as well,” Brien suggests. “If it becomes extra pricey for possible consumers to finance a buy, less will be in a position to afford to pay for it. This will maximize need for single-family members residences and develop additional upward stress on rental price ranges.”

Homeowners lose wealth as rising interest rates weigh on home values

Homeowners lose wealth as rising interest rates weigh on home values

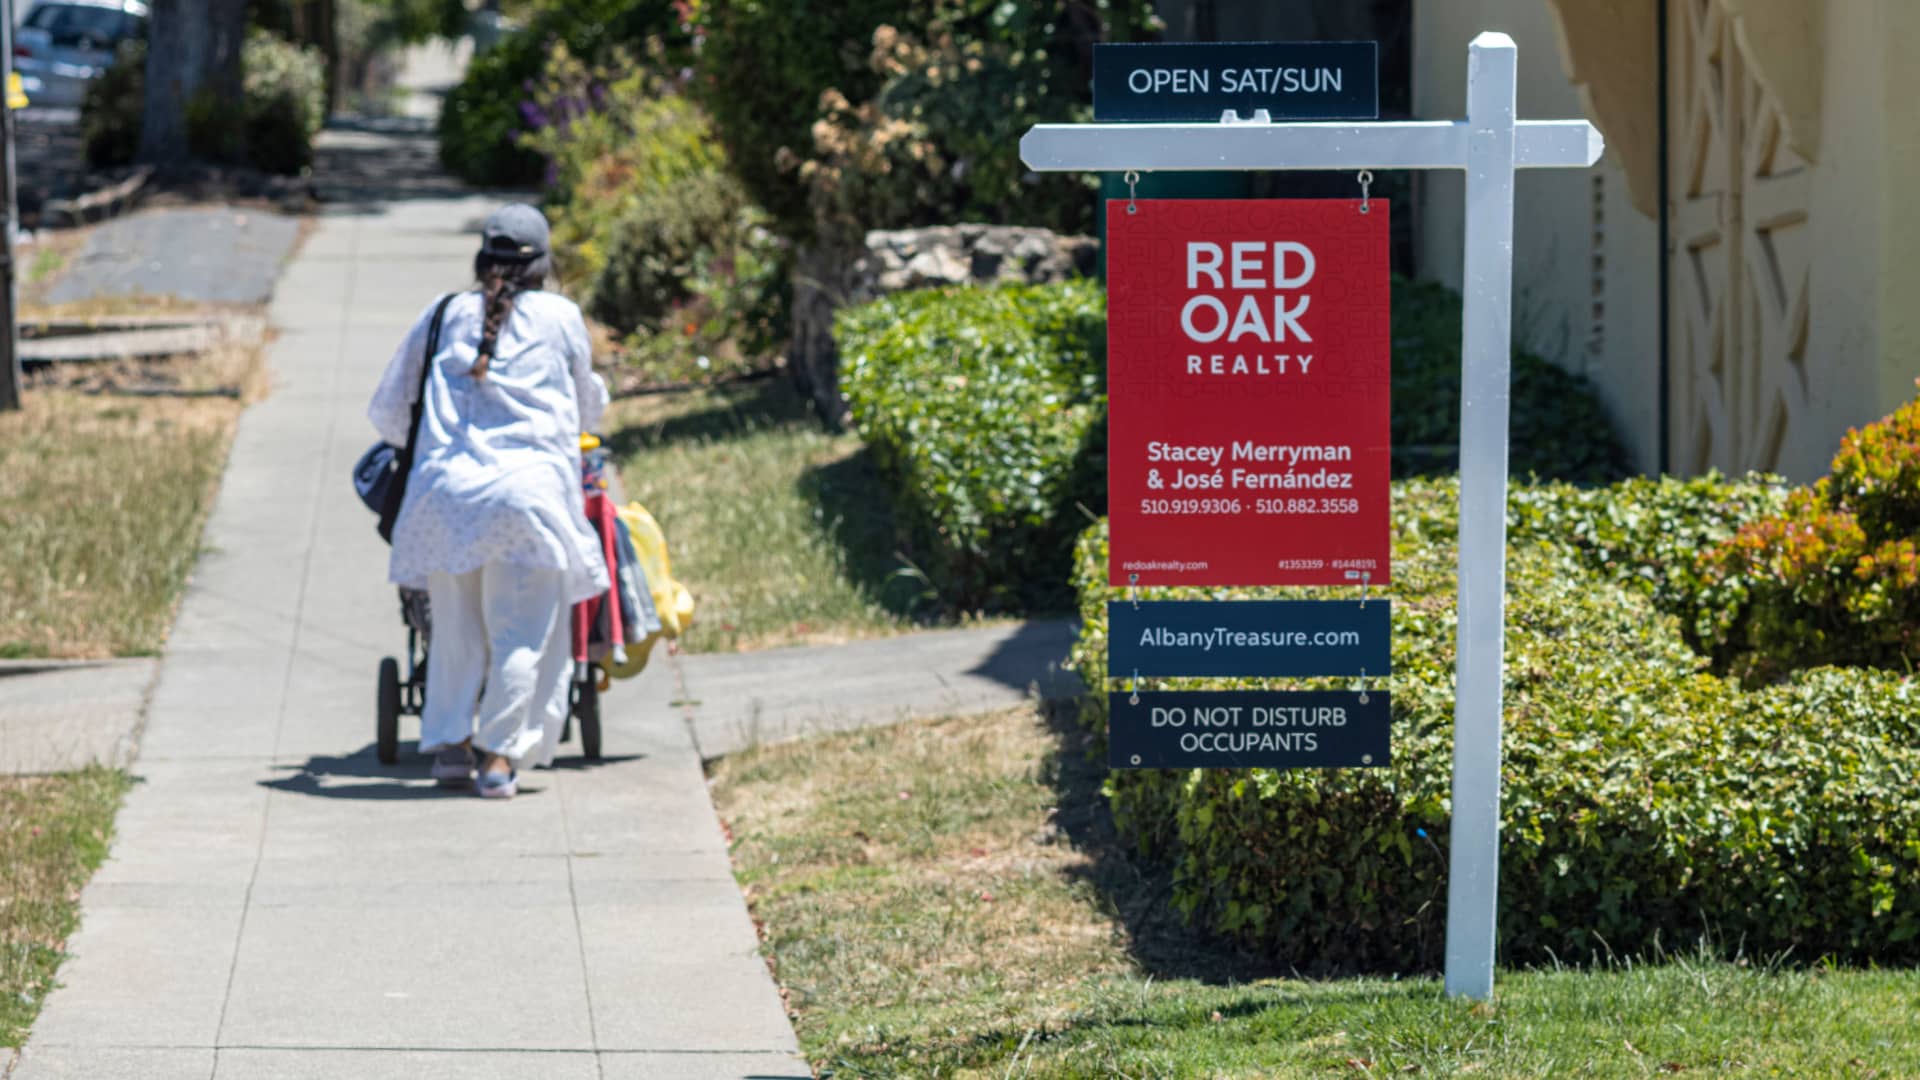
A “For Sale” sign outside a home in Albany, California, on Tuesday, May perhaps 31, 2022.

David Paul Morris | Bloomberg | Getty Visuals

Some householders are dropping wealth as significant property finance loan prices weigh on property values, at least on paper, as the once pink-sizzling housing sector cools promptly.

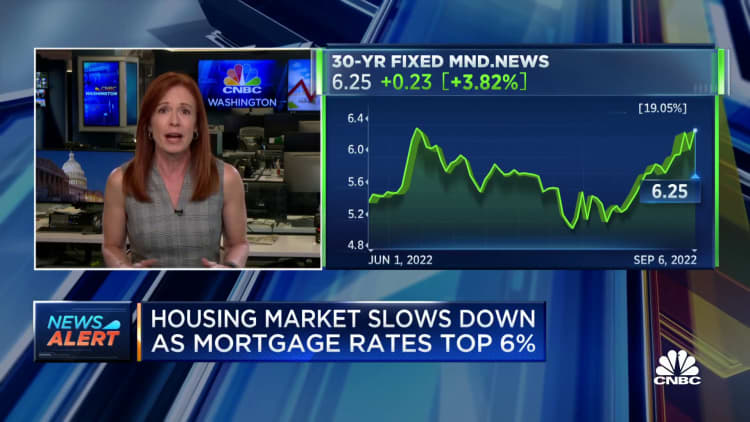
Revenue have been slowing down for numerous months, with house loan costs now double what they ended up at the start of this 12 months.

House charges, similarly, dropped .77{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from June to July, according to a recent report from Black Knight, a computer software, details and analytics corporation. Although that may perhaps not sound like a ton, it was the major regular monthly drop because January 2011 and the very first regular monthly fall of any dimensions in 32 months.

Housing market slows as mortgage rates hit 6.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}

“Yearly dwelling rate appreciation even now arrived in at about 14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, but in a sector characterized by as much volatility and quick improve as present day, this sort of backward-on the lookout metrics can be deceptive as they can mask far more existing, pressing realities,” wrote Ben Graboske, president of Black Knight Knowledge & Analytics.

Around 85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of major marketplaces have noticed selling prices come off peaks by means of July, with just one-third coming down a lot more than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and about 1 in 10 falling by 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or far more. As a final result, soon after gaining trillions of bucks in property equity collectively through the to start with two several years of the Covid pandemic, some house owners are now shedding fairness.

So-identified as tappable fairness, which Black Knight defines as the sum a homeowner can borrow versus even though trying to keep a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity stake in the assets, strike its 10th consecutive quarterly document high in the second quarter of this yr at $11.5 trillion. But data suggests it may well have peaked in May possibly.

Declining house values in June and July introduced the complete quantity of tappable equity down 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and offered the weakening in the housing market considering the fact that then, the third quarter of this calendar year will demonstrate a a lot more sizeable decrease.

“Some of the nation’s most equity-rich markets have viewed considerable pullbacks, most notably amid vital West Coast metros,” pointed out Graboske.

From April by way of July, San Jose, California, shed 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its tappable equity, followed by Seattle (-18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Diego (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Francisco (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Los Angeles (-10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

House owners are nonetheless considerably a lot more flush than they have been the previous time the housing industry went by way of a big correction. All through the subprime mortgage crash, which began in 2007, and the subsequent Excellent Recession, dwelling values plummeted by virtually half in some significant marketplaces. Hundreds of thousands of debtors went underwater on their mortgages, owing a lot more than their households have been worthy of.

That is not the scenario right now. Latest debtors, on normal, owe just 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their home’s value on the two first and 2nd home loans. It is the most affordable leverage on record. Shedding some value on paper should not impact all those entrepreneurs at all.

There are, nonetheless, about 275,000 debtors who would tumble underwater if their households ended up to get rid of 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their current benefit. A lot more than 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all those borrowers acquired their properties in the 1st six months of this calendar year, which was the top of the market.

Even with a common 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop in charges, destructive equity costs would continue to be nowhere close to the concentrations noticed throughout the monetary crisis, according to the report.

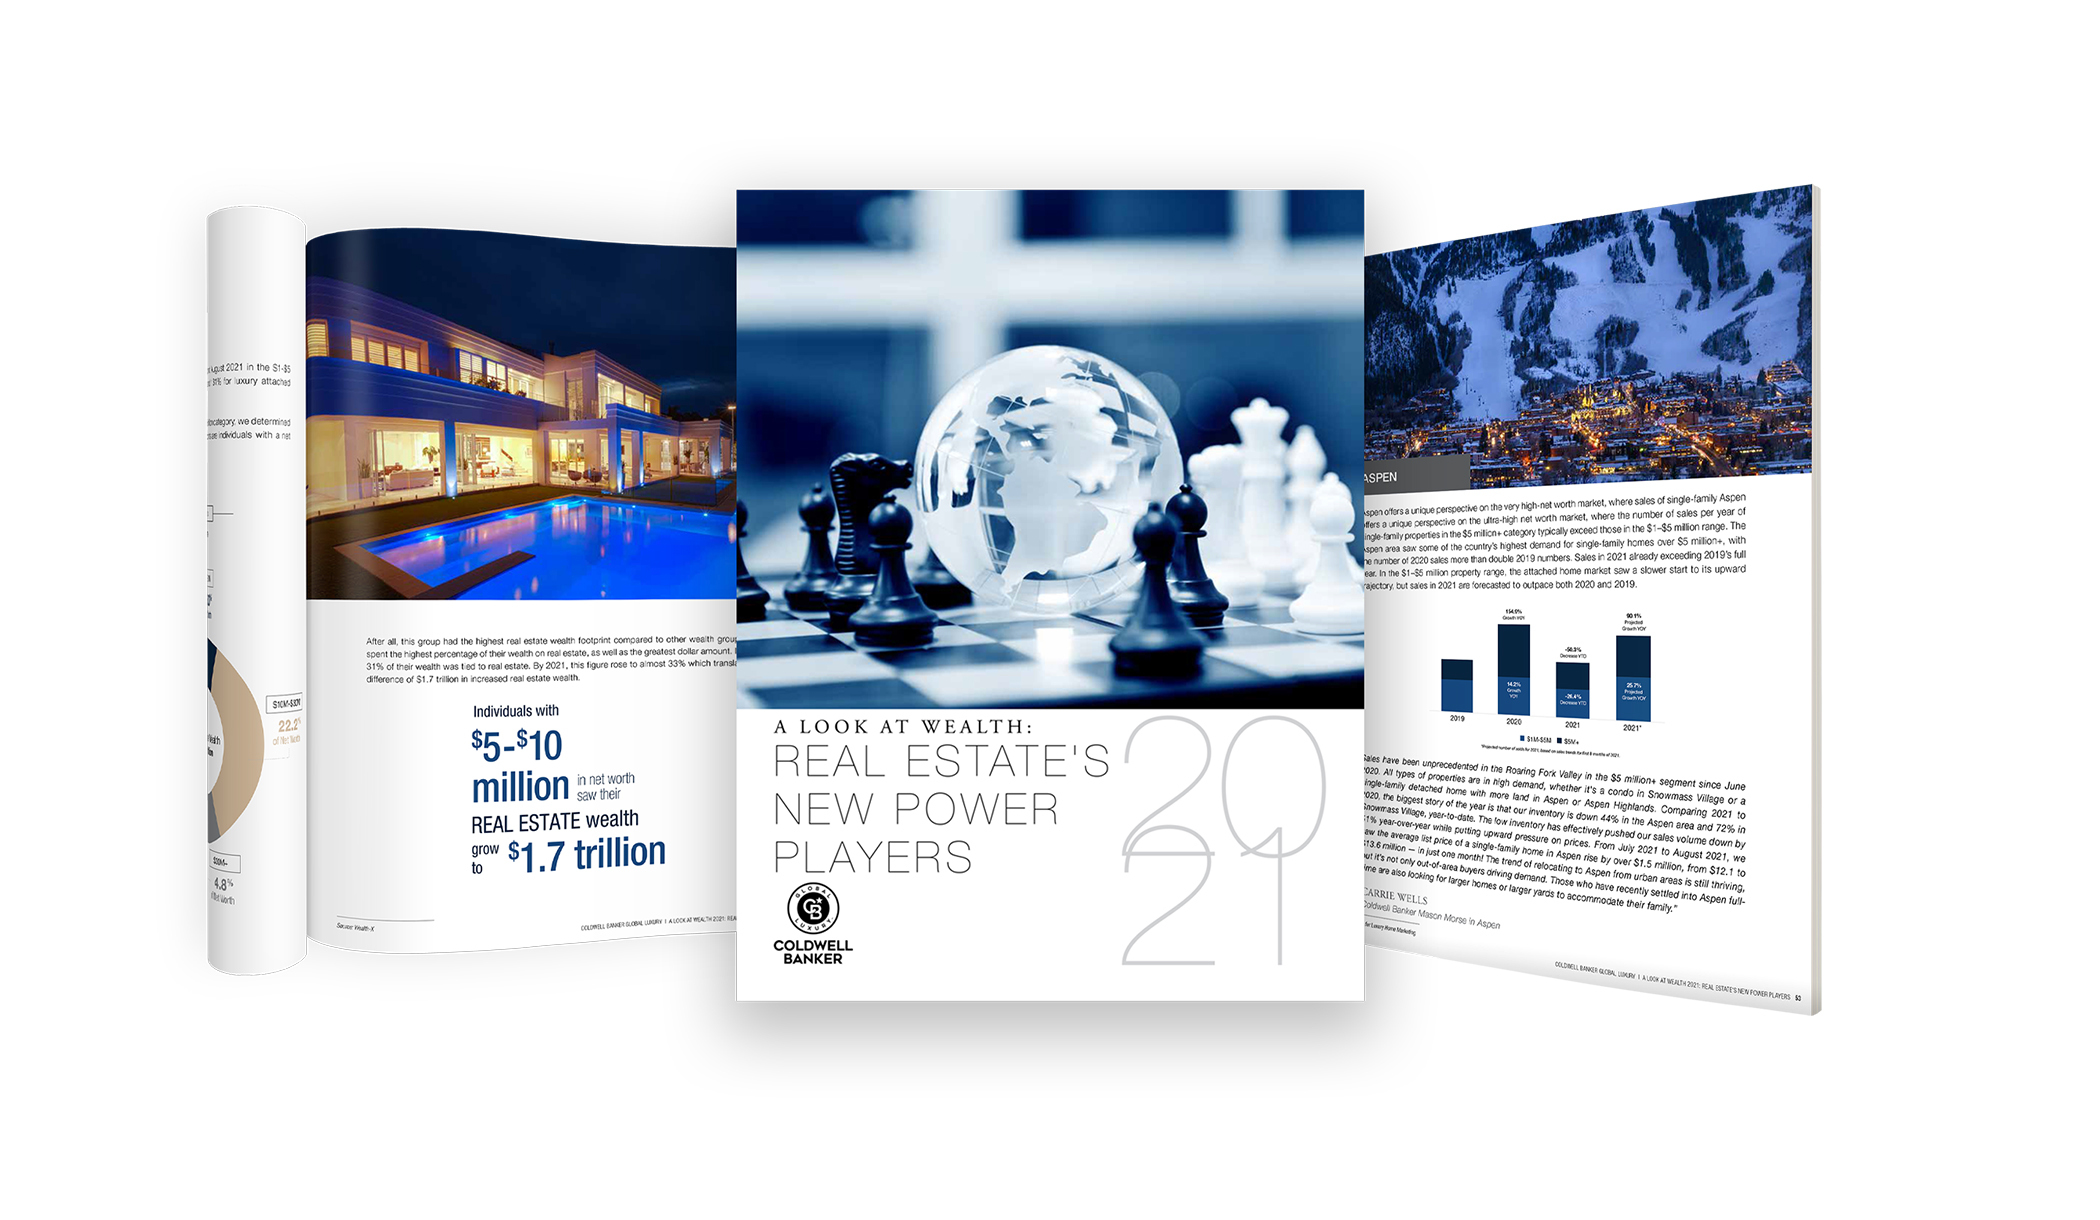
Staggering new report: ‘A Look at Wealth 2021: Real Estate’s New Power Players’

Staggering new report: ‘A Look at Wealth 2021: Real Estate’s New Power Players’

Today, nearly three times as many individuals with a $5 million+ net worth own $1–$5 million in real estate, compared to the numbers in 2019 — that’s a 180{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase in luxury property ownership.

How did we reach such unprecedented growth in a three-year period? What power groups drive this demand, how do they redefine luxury and what should luxury real estate professionals know as they seek to serve clients in this new buying climate?

Our team at Coldwell Banker Global Luxury® once again looked to WealthEngine, Wealth-X, and The Institute for Luxury Home Marketing to compile the data for “A Look at Wealth 2021: Real Estate’s New Power Players.” What we found was staggering.

Behind the luxury housing boom

Two main factors drive the luxury real estate market today. Cryptocurrency gains, rising stock markets, and 401(k)s have combined with soaring home prices and low-interest rates, allowing consumers to borrow and save more while reinvesting cash. This new wealth allowed affluent individuals to buy more expensive homes — and more of them. People also continue to make life-changing moves, choosing to live out their values or embrace a FOMO-meets-YOLO mindset following the pandemic.

This has put the 2021 luxury real estate market on course to surpass 2020, which was already considered a record year. The volume of wealth spent on luxury real estate rose by over 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} between 2019 and 2020 — but when you compare January to August 2021 to the same eight months in 2019, it jumped by 79{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Stats on August 31, 2021, already show real estate wealth in the luxury property market is now greater than 2019 and 2020 combined, with four months left to go.

Additionally, the number of properties purchased January-August 2021 in the $1–$5 million range jumped an incredible 142{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for luxury single-family homes and 129{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for luxury attached properties, compared to the same period in 2019. About 71{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of luxury properties owned by those with a net worth over $5 million are now valued in the $1–$5 million range. We dubbed these folks the new “power players” because of their outsized influence on the luxury real estate market over the last 18 months.

The New Power Players

Suburban settings, resort markets, and secondary cities are still booming, while major metropolises are surging back, according to 2021 data to date. Four core groups are driving demand in these places: Baby Boomers, Golden Millennials, Second Homeowners and Urban Repatriates.

1. Baby Boomers represent 51{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of power players. Speeding up retirement plans, they’re buying dream homes in places like Park City, Utah, where they can build family compounds near outdoor recreation, or Sarasota, Florida, where there’s sunny weather and a friendly tax environment. Boomers show greater affinity for second-home ownership, as well; there are 2,020,854 Boomers owning more than three properties, the most out of any age group.

2. Golden Millennials own 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of millennial-owned properties priced $1–$5 million. Golden Millennials have reached the life stage (35–40) where they are getting married and having children. This, combined with shifting psychologies during the pandemic and inability to travel, pushed them toward suburban locations, like the Greater Chicagoland area, and hot secondary cities like Atlanta, where they can get more house for their money. The influence of Golden Millennials will be important to watch as their wealth and real estate portfolios grow.

3. Second Homeowners still drive the 2021 market. This power group gobbled up inventory and drove up prices in resort enclaves like Coeur D’Alene and Monterey. Their influence on the overall luxury property market is one to watch; nearly 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of those with a net worth of $5 million+ own two or more properties.

4. Urban Repatriates pump up cities again. Luxury attached property values in 2021 increased an average 14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to 2020 and 2019, and the number of sales in the first eight months has already increased by over 45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to the full year of sales in 2019 and 59{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to 2020. Investors capitalizing on low-interest rates and higher inventory in cities like San Francisco and New York are behind the uptick, as are newcomers flocking to the city and former residents who fled in 2020 and are now on the hunt for more square footage and outdoor space.

As these New Power Players continue to make moves in the high-end housing landscape, we will see new definitions of luxury emerge as they refine how and where their wealth is spent. Luxury professionals who want to stay on top of their rising influence and upward pressure on demand and prices are encouraged to read the complete ALAW report on the Coldwell Banker Global Luxury blog.

Michael Altneu is the vice president of luxury for Coldwell Banker Global Luxury.