Peter Petrakis, a Seaford-primarily based industrial genuine estate investor, obtained three retail qualities in Indiana and North Carolina for a overall of $3.965 million.
The purchaser obtained an 18,000-sq.-foot retail creating on 1.3 acres at 8905 E. 10th St. in Indianapolis, Ind. for $1.3 million. The residence is web-leased to Walgreens and the sale price tag equates to a 7 p.c cap amount.
Petrakis also obtained a 5,472-sq.-foot restaurant developing on .91 acres at 4383 Countrywide Road in Richmond, Ind. for $1.54 million. The assets is net-leased to Chili’s and the sale value equates to a 4 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} cap amount.
The third house acquired by Petrakis is a 2,979-square-foot cafe setting up on 1.94 acres at 16 New Clyde Freeway in Canton, N.C. for $1.125 million. The assets is web-leased to Hardee’s.
The a few acquisitions were part of a 1031 exchange in which Petrakis offered an 11,183-square-foot retail developing on .68 acres at 2846 Mahoning Ave. in Youngstown, Ohio for $1.945 million. The house is net-leased to CVS and the sale value equates to a 5.7 p.c cap price.
Peter Petrakis and Adam Silber / Courtesy of Silber Expense Attributes
All of the transactions ended up brokered by Plainview-based mostly Silber Financial investment Houses, with Adam Silber symbolizing Petrakis on the four bargains. Stuart Frankel of Silber Financial investment Houses represented the purchaser of the Youngstown property, Vincent Garrow, and Frankel also represented the seller, Ingram G7 Partners LP, in the Richmond, Ind. revenue transaction.
Michael Turkowitz of Silber Investment decision Houses represented the vendor, Sharon Thomas, in the Indianapolis transaction and his colleague Nicolas Anzalone represented the seller, Rocking C Investments LLC, in the Canton, N.C. deal.
Silber’s brokerage firm has facilitated effectively around 300 discounts with Petrakis over the last two a long time. Petrakis got his start in business in the early 1990s, when he opened his to start with 1 Stop Smoke Shop benefit retailer in Copiague. The business soon grew to about a dozen places throughout Extensive Island.
Immediately after working the convenience retailers for a couple decades, Petrakis started buying commercial real estate. Today, his organization and its affiliates individual very well over 100 commercial properties all over the region, concentrated on belongings that have essential firms as tenants, these kinds of as 7-Eleven, CVS, Walgreens and swift services places to eat.
Zoned Properties, Inc.ZDPY has acquired an financial investment house in Nice Ridge, Michigan and entered into a very long-term, complete-net lease agreement with NOXX Cannabis to operate a retail dispensary.
“We are thrilled to announce this sizeable transaction, which marks our entry into Michigan as an investor in serious estate. This deal has offered us the possibility to add a sturdy, established operator in a appealing sector, when diversifying our portfolio. This is an illustration of Zoned Properties including a excellent asset and tenant lover to our residence financial commitment portfolio by using our value-insert financial investment solution and injecting immediate-to-buyer genuine estate targets into our pipeline,” stated Bryan McLaren, CEO of Zoned Attributes. “We are enthusiastic to reinforce our partnership with NOXX Cannabis and their govt crew.”
Transaction Highlights


Zoned Properties has acquired the investment assets in Pleasurable Ridge, Michigan that has been entitled and permitted as a hashish retail dispensary.


The investment residence was obtained for $4.3 million, such as $1.85 million in seller financing, which allowed Zoned Homes to additional leverage its funds stack at beautiful costs.


The financial commitment residence is leased to NOXX Hashish less than a lengthy-term, absolute-net lease arrangement, which will generate an approximate 13.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} cap rate when straight-lined above the term of the lease arrangement. The lease contains 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} once-a-year increases in foundation rent above the existence of the lease phrase, yielding approximately $580,000 in yearly base rental income when straight-lined more than the lifetime of the lease phrase.


Benzinga’s Hashish Funds Conference Is Back again
The most effective cannabis small business party in the entire world, the Benzinga Cannabis Funds Meeting, returns to Miami for its 16th edition. This is the put exactly where Bargains GET Completed, in which cash is elevated, M&A begins, and companies meet buyers and essential associates. Join us at the Fontainebleau Miami Beach Hotel in Florida on April 11-12. Do not miss out on out. Safe your tickets now. Prices will surge incredibly soon.
Picture: Benzinga edit with images by geralt and lindsayfox on Pixabay
Meet the most important cannabis industry gamers and make deals that will thrust the sector ahead.
Showcasing reside corporation presentations, insider panels, and unmatched entry to networking, the Benzinga Cannabis Funds Meeting is the place cannabis executives and entrepreneurs fulfill.
Join us April 11-12, 2023 at Fontainebleau Miami Seashore in sunny Florida.
Floor & Decor (NYSE:FND) is a hard surface flooring retailer and commercial flooring distributor with 191 warehouse-format stores and six small design studios across 33 states. With an experienced management team, the company lays out an expansion plan to drive future store base growth at 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually. It gives FND a runway to grow to become the next home improvement retail giant.
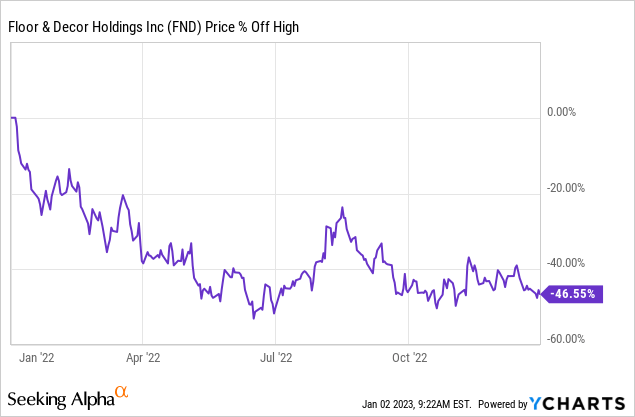
FND also has performed well financially over the past few years. Revenue per share rose 64{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and EPS surged 83{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2019 to 2021. However, FND declined over 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its all-time high in December 2021 and had a disappointing performance in 2022 due to the depressing housing market. This allows investors to buy this incredible growth company at a significantly discounted price in my opinion. Thus, I rate FND as a “Strong Buy”.
A team of experienced executives, including Chief Executive Officer Tom Taylor, manages FND. He had 23 years of experience at The Home Depot (HD) and assisted in expanding the store base from 15 stores to over 2,000 stores. FND is in the early growing stages. His valuable experience provides excellent guidance for FND to scale.
FND’s warehouse-format stores provide one-stop services for their customers to shop for hard surface flooring materials and associated tools and materials. The company offers products from over 60 proprietary brands and approximately 4200 stock keeping units (“SKU”) in each store, far greater than other flooring retailers. As a customer, an integrated store like FND is something I have longed for. It saves considerable time from traveling between stores to search for flooring materials of different styles and brands.
Floor & Decor
Besides, the focus on Pro customers provides a competitive edge for the company. Although the Pros are only accountable for 40.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of total sales, they are likely to make more frequent store visits, and their professional opinions often affect homeowners’ choices. Thus, FND offers a dedicated Pro sales force at each store to help the Pros shop more efficiently. Also, to improve their loyalty to FND and engage new Pros customers, the company launched a Pro loyalty rewards program. In the latest earnings call, the management provided some encouraging numbers related to Pros:
Pro transactions were up 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} during the quarter, and the top 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of our PPR members spent 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more than they did a year ago. If you think about that’s 185 stores in a really difficult macro to be able to sign up another 29,000 Pros during the quarter, that’s all good for the long term.
E-commerce is relatively less important to a hard surface floor material retailer as customers may wish to have first-hand experiences to feel the textures and materials of the flooring materials. Only 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the total sales are from e-commerce channels. But FND is still eager to develop its online platform as it assists customers in exploring design options and enriches the whole shopping experience.
With a great variety of products, a professional sales team and an experienced management team, the company achieved a remarkable 14.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} comparable store sales growth per year over a thirteen-year period (2009 – 2021) and a 12.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth from 2017 – 2021.
The Next Home Depot?
FND operates in a large but fragmented U.S. floor coverings market, estimated to have an addressable market size of $30 billion. Hard surface flooring material has recently gained popularity, partly because of better hygiene and higher durability. The market size is approximately $41 billion if associated tools and materials are included.
Currently, FND only has 197 stores and studios, which is only less than one-tenth of Home Depot’s store count. As the floor covering market in the U.S. is highly fragmented, FND still has a wide and long runway to grow as one of the largest home improvement retailers in the U.S. The management estimated that FND represented only 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the total addressable market.
To gain market share, the hard floor covering retailer has an expansion plan to grow its store base by 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually for the next several years in new and underserved markets. Expansion to at least 500 stores nationwide over the next 8 to 10 years is anticipated. The company demonstrated that the aggressive plan is achievable this year. They opened 32 new warehouse stores across the U.S., a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase from last year’s store count.
Performances of the newly opened stores have been promising already. All new stores are profitable in their first year and achieve better comparable store sales growth than existing stores.
Other than FND’s expansion plan to acquire market share from this fragmented sector, a pending 2023 recession may also be an excellent opportunity to grow market share. Small and heavily indebted floor covering companies may be forced to shut down under a challenging economic backdrop. The balance sheet of FND should be healthy enough to survive the recessionary environment. And it will likely be able to gulp the released market share from those unable to get through tough times.
The company is on a runway to expand its business to 500 stores this decade. The hard surface floor covering industry is growing at 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually. With its fragmented nature, it will not be surprising if this well-managed company continues to gain market share and becomes the next home improvement retail giant like Home Depot.
Solid Balance Sheet
Acquisition activities and the aggressive store expansion plan may pressure the company’s balance sheet as the latter incurs significant pre-opening expenses (e.g., construction cost, training cost, advertisement cost). Especially the capital expenditure of the company has been on an increasing trend over recent years.
However, I found the balance sheet of FND fairly solid, and its expansion plan would unlikely impact its financial performance adversely. FND now owns $374 million in debt in Q3 2022, where the majority of debt will be matured post-2026. The amount of debt is just slightly more than its equity value. A summary of financial strength ratios is tabled below for easy reference.
Debt-to-Equity Ratio
1.05
Debt-to-Asset Ratio
0.39
Equity-to-Asset Ratio
0.37
(Source: Author, data from Gurufocus)
Potential Risks
Styles of tiles and hard flooring materials are like clothes in your closet. They will change seasonally. Thus, the increasing inventory level is my concern, as old-fashioned floor covering materials could become outdated. There is a risk that the company will mark down the prices to clear the excessive and out-of-style inventories. The inventory level doubled from $654 million in 2020 to $1,320 million in TTM. The high level of inventory also brought the operating cash flow down sharply in the first three quarters of 2022. At the same time, free cash flow dropped to a negative level in the same period.
However, the sharp growth in inventory level to some extent reflected the frequent opening of new stores and new in-store products. As explained in the latest earnings call:
The inventory growth was in line with our expectations and reflected our new store growth. We have been making to improve our in-stock inventory, inflation and the addition of new innovative SKUs.
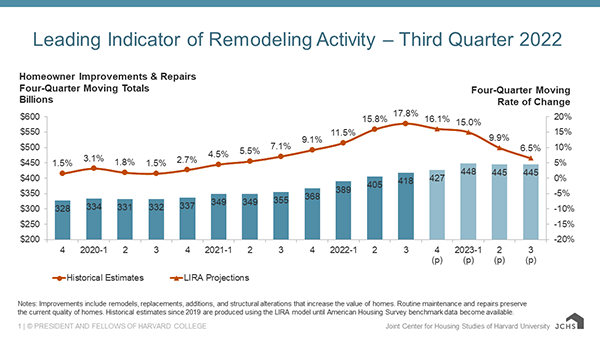
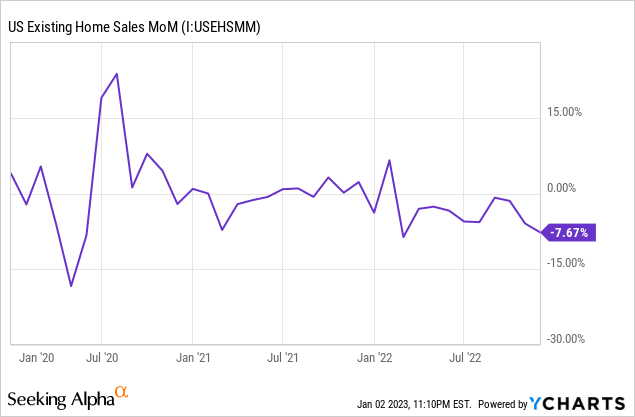
The second concern will be the declining existing home sales and home improvement incentives. Existing home sales data fell for eleven consecutive months (since February 2022). And The Leading Indicator of Remodeling Activity expected home improvement and maintenance expenditures would peak in the second quarter of 2023, and its growth rate would also slow sharply in 2023. We may conclude that the disappointing housing data will likely lower hard surface flooring material demand in 2023.
Some may argue the weakening housing market will severely affect home improvement retailers like FND. However, even during tough times, FND still delivered strong financial results. Total sales and EPS grew 25.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 16.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} YoY in Q3 2022, respectively. The management team is also confident in achieving 14 consecutive years of comparable store sales growth.
Valuation and Conclusion
FND has a great business model and management team to scale itself in the highly fragmented hard surface floor covering industry to become the upcoming home improvement retail giant. In previous years, the stock has demonstrated robust financial performance.
The stock is now significantly discounted. FND has a P/E ratio of 27.09 currently, which is 43{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower than its 5-year average P/E ratio. The company’s 5-year average P/E ratio is reasonable as it matches its 5-year average EPS growth (42.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} CAGR).
However, the average P/E ratio will likely decline as the Street anticipates a slower growth rate in the next few years. Below are my bullish and bearish cases of valuation, assuming the stock returns to a P/E ratio of 33.6 (70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the current 5-year average P/E ratio).
Bullish Case (EPS Growth {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9})
Bearish Case (EPS Growth {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9})
One extra reason to own FND is that Berkshire Hathaway (BRK.A) (BRK.B) established their position of FND in Q3 2021 and increased their position at ranges between $81 to $130. Entry at current prices will provide investors with a discount over Mr. Warren Buffett.
Please kindly note that all data in this article is abstracted from FND’s conference call transcript in 2022 Q3 and 2021 annual report, unless otherwise specified.
Written by Nick Ackerman. This article was originally published to members of Cash Builder Opportunities on August 11th, 2022.
Alpine Income Property Trust, Inc. (NYSE:PINE) immediately caught my attention when it appeared on our latest monthly dividend screening piece. Several interesting names show up with that screening article, and it gets some of the most readership. So, a good reason why I continue to produce that monthly piece.
For PINE, more specifically, the higher yield of nearly 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} at this time plus a growth trend initially stood out. After looking into it a bit more, some red flags should be addressed. All in all, though, it is an interesting name that is worth being put on the watchlist, or even perhaps a small initial position.
They describe themselves as:
“a publicly traded real estate investment trust that acquires, owns and operates a portfolio of high-quality net leased properties. The Company’s portfolio consists of 143 properties located in 35 states.”
They were considered a diversified real estate investment trust (“REIT”), but after selling off their Wells Fargo offices earlier this year, they have become a more pure-play retail REIT.
A Look At The Tenants And Size
There are risks to all investing. Some investments have additional risks that should be considered. I believe that PINE is one of those.
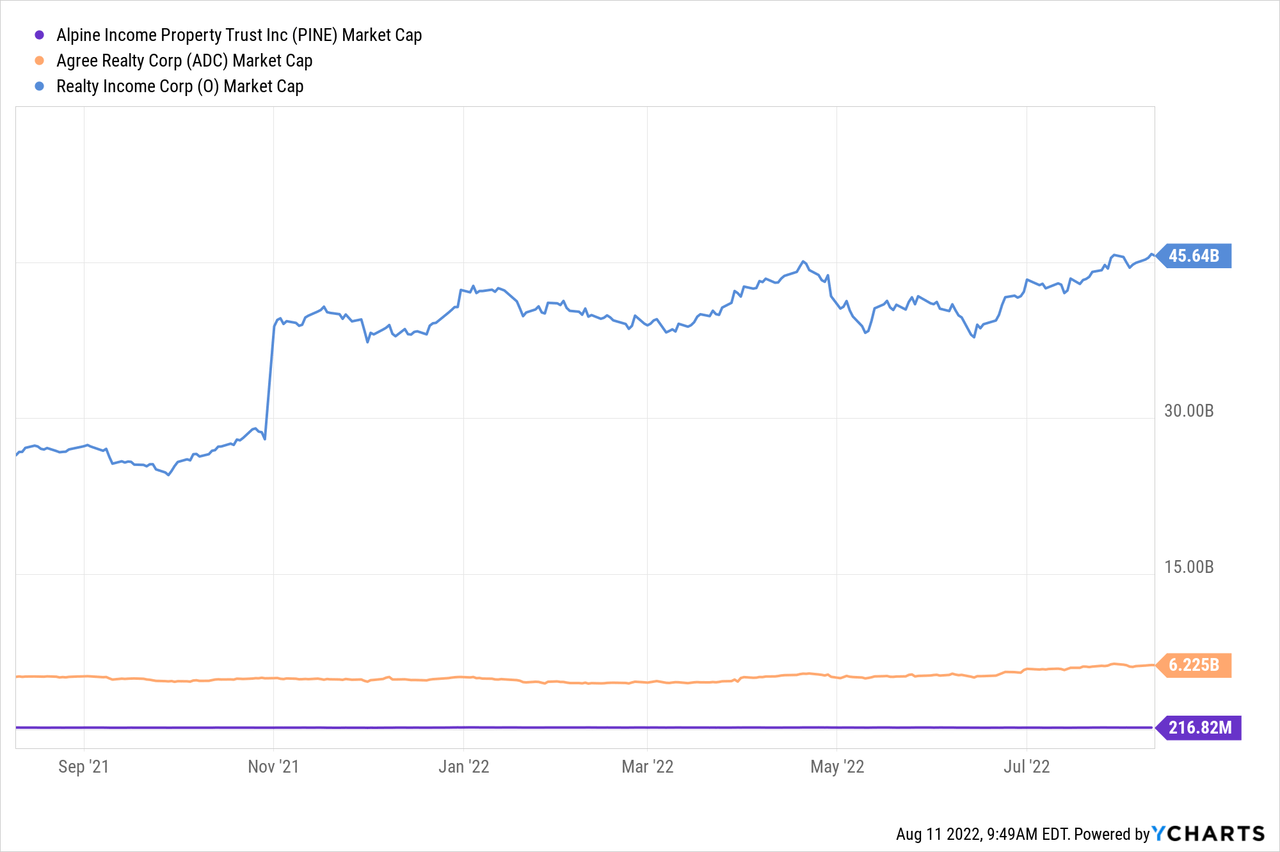
The first caution that I saw was the market cap and, subsequently, the size of the REIT. At only around a $217 million market cap, we are looking at a microcap. In total, they only have 143 properties. With only a few years of operation, that isn’t necessarily unexpected as they look to become bigger over time.
Other retail REITs such as Realty Income (O) and Agree Realty (ADC) weren’t built in a day.
Speaking of those names, here’s a comparison of those market caps for some context. Note how O had a spike in market cap after its merger with VAREIT.
YCharts
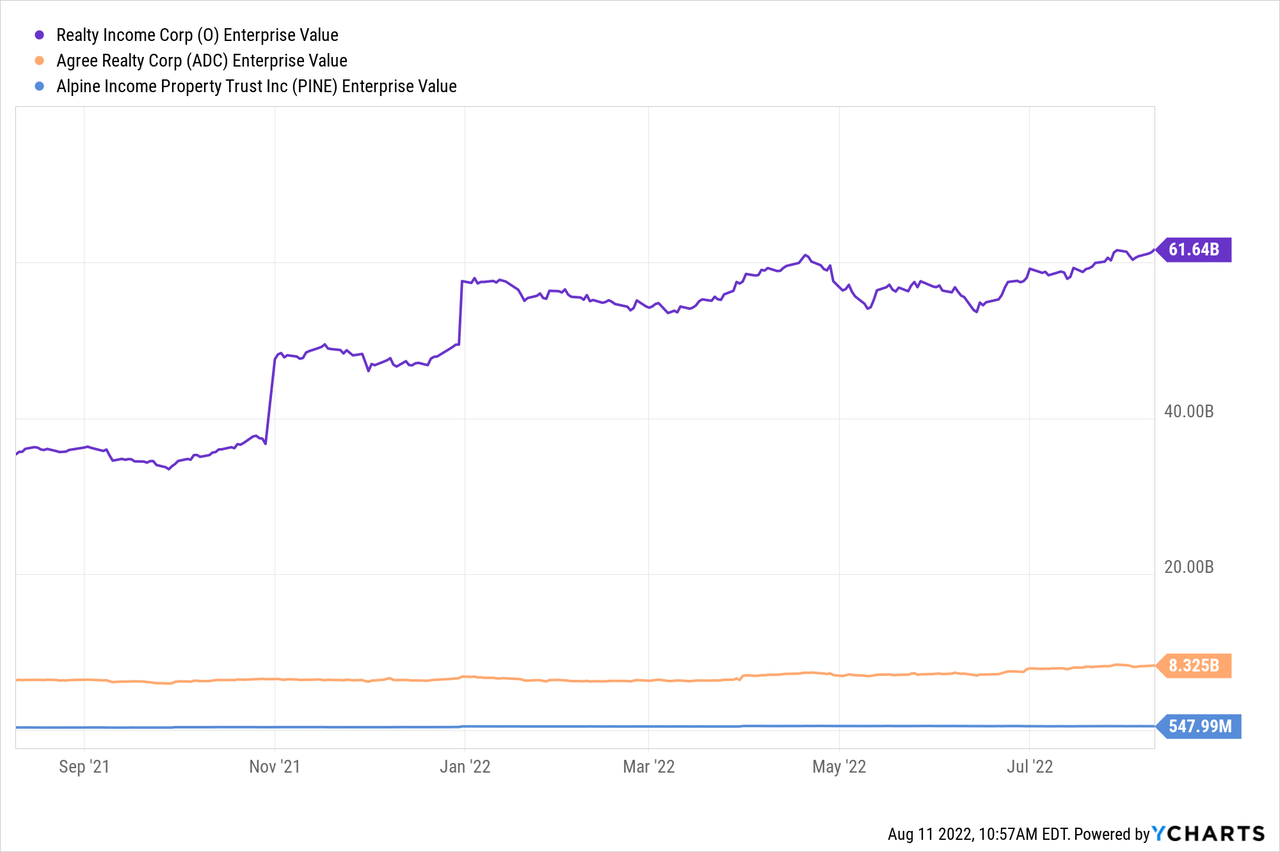
Enterprise value is often considered a better sizing metric for REITs, but we will obviously see a similar trend here too.
YCharts
A small company, or in this case, REIT, can offer higher growth potential going forward. However, it also means that a small speed bump in the economy could send things off track. Looking at the portfolio, despite being a small number of properties, it seems they hold some top-quality names for tenants.
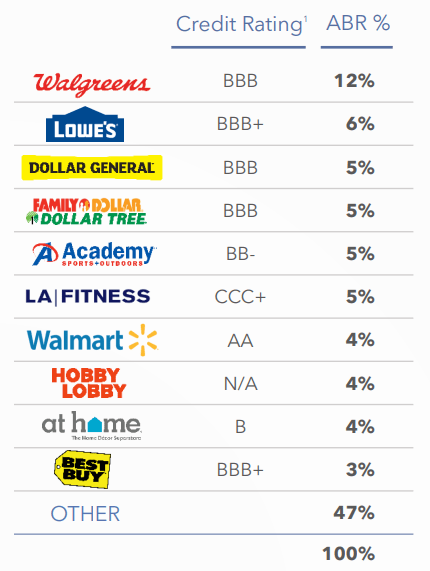
There are several recession-resistant names that won’t be impacted too considerably, such as Walgreens (WBA), Lowe’s (LOW), Dollar General (DG), Family Dollar/Dollar Tree (DLTR) and Walmart (WMT). That’s reinforced by the strong credit ratings of investment grades that these positions receive.
PINE Top Tenants (PINE Investor Presentation)
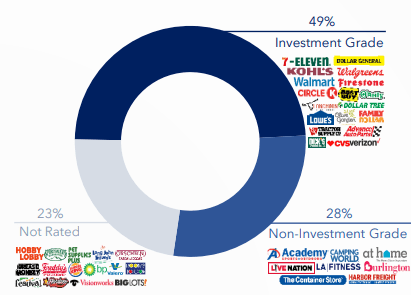
In fact, half their tenants are considered investment-grade. That should bode well during the next economic slowdown.
PINE Tenant Quality (PINE Investor Presentation)
That’s where we go back to the size discussion, though. These top tenants make up half of their annualized base rent (“ABR”). That’s a fairly narrow selection of individual companies that can have their own individual issues pop up.
I’d also look back at their geographic exposure. Having a fairly small number of properties means that you will be fairly concentrated. In this case, 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their portfolio is in Houston, TX alone. They highlight that 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of ABR comes from metropolitan statistical areas with more than one million people.
They also highlight that 39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of ABR comes from the high-growth states of Texas, Florida, North Caroline, Arizona and Georgia. That highlights a strength while those places are growing. However, I view it as more of a concentration risk, too, having so much ABR tied up to a relatively limited number of cities within these states.
The Company has no employees and is externally managed by Alpine Income Property Manager, LLC, a Delaware limited liability company and a wholly owned subsidiary of CTO Realty Growth, Inc. (our “Manager”). CTO Realty Growth, Inc. (NYSE: CTO) is a Maryland corporation that is a publicly traded diversified real estate investment trust (“REIT”) and the sole member of our Manager (“CTO”).
That can create some potential conflicts of interest or values that don’t necessarily align with current shareholders. In their coverage of CTO, On The Pulse noted that they own a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} stake in PINE itself. That should help align the managers with shareholders.
As of the latest quarterly release from PINE, they continue to pick up shares in the open market. That continues to align their interest with current holders of PINE.
We are externally managed by the Manager, a wholly owned subsidiary of CTO. Subsequent to the IPO, CTO purchased an aggregate 107,866 shares of PINE common stock in the open market including (i) 99,778 shares purchased during the six months ended June 30, 2022 for $1.8 million, or an average price per share of $17.99 and (ii) 8,088 shares purchased during the year ended December 31, 2021 for $0.1 million, or an average price per share of $17.65. As of June 30, 2022, CTO owns, in the aggregate, 1,223,854 OP Units and 923,656 shares of PINE common stock, inclusive of (i) 394,737 shares of common stock totaling $7.5 million issued in connection with the CTO Private Placement, (ii) 421,053 shares of common stock totaling $8.0 million issued in connection with the IPO, and (iii) 107,866 shares of common stock totaling $1.9 million purchased by CTO subsequent to the IPO. The aggregate 1,223,854 OP Units and 923,656 shares of PINE common stock held by CTO represent an investment totaling $38.5 million, or 15.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of PINE’s outstanding equity, as of June 30, 2022.
Additionally, they intend to internalize the management of PINE. Their latest investor relation simply stated, “internalization of management for PINE is anticipated in the future when the Company approaches or exceeds critical mass.” That suggests they want to be a larger operation before internally taking a team. It, unfortunately, does not give us any solid metric to watch to see how close we may be to such a transition.
Growth Potential And Dividend
I believe those are the main risks that stood out to me, but now on why PINE can be quite attractive. The latest funds from operation (“FFO”) they provided for last quarter was $0.47. That was an increase from 2021’s $0.38 of 23.68{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That’s quite the leap. AFFO also increased 20.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the prior quarter.
ADC recently had its own earnings release. The results were fantastic, in my opinion. However, their FFO increased by 9.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and AFFO was up 10.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Fantastic results, but helps provide context on what size can do to the figures. That was after they invested $430 million on 121 properties. That’s nearly as many properties that PINE has combined.
Analysts expect that they will report $1.68 in FFO for the full year. Though that’s only a relatively smaller 6.24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth potential for the year, they have a history of easily beating analysts’ expectations thus far.
For the full 2022 year, they expect AFFO to come in at $1.58 to $1.63. That was a raise from their own prior guidance of $1.53 to $1.58. That was after they raised their guidance in the earlier quarter too. So at this point, it’s becoming a bit of a regular thing for PINE to beat and raise, which means that their expectations could still potentially be lower than what we ultimately see.
That’s part of why microcap stocks and REITs can have some strong appeal-being able to grow by larger percentages since they are growing from a smaller size in the first place. When they add 19 properties as they did in the latest quarter, that actually really adds up.
Though, net, it was a 14 property addition due to disposing of 5 office properties. Still, another 14 properties in the next quarter off of 143 properties is an almost 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} add to their portfolio. That can really contribute significantly to the FFO and AFFO growth through acquisitions alone.
For 2022 overall, they are expecting acquisitions of $215 million to $235 million. Dispositions for the year are anticipated to be $125 million to $175 million.
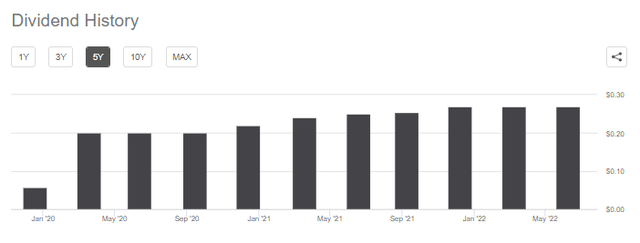
This all translates into the potential growth of the dividends for investors. Which is exactly what has been experienced so far. So far, it appears they haven’t had a predictable growth in the dividend. Instead, they appear to be raising rather sporadically but raising nonetheless. That doesn’t seem to be a bad thing until they have matured a bit more.
PINE Dividend History (Seeking Alpha)
The latest $0.27 quarterly was a raise over last year’s $0.25 of 7.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That also worked out to an increase of 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the 2020 $0.20 quarterly payout.
Conclusion
I consider ADC to be “O-lite.” With PINE coming on my radar now, it would appear that a fitting description could be something like “O-ultra-lite” if I wanted to put a moniker on it. There is potential here, but due to its newness and being a small operation at this point, I think it would only be appropriate for a very high-risk portion of one’s portfolio. With the size can come the potential for a lot of growth. Even the potential to be an acquisition target. However, it also means that their economic sensitivity and lack of diversification leave them more vulnerable.
The Zacks Building Products – Retail industry is poised to gain from the continued strong consumer demand trends for home renovation and maintenance activities amid rising interest rates and home prices. Rapid urbanization and favorable trends in the housing market are added advantages. The industry players are expected to gain from investments in digital and omni-channel capabilities for meeting demand, executing strategies, and acquisitions.
Continued innovation and e-commerce expansion, and strong demand are likely to benefit industry participants like The Home Depot Inc. HD, Lowe’s Companies Inc. LOW, Builders FirstSource, Inc. BLDR, Beacon Roofing Supply BECN and GMS Inc. GMS.
About the Industry
The Zacks Building Products – Retail industry mainly comprises U.S. home improvement retailers, manufacturers of industrial and construction materials, and distributors of wallboard and ceilings systems. Some industry participants offer products and services for home decoration, repair and remodeling, and in-home delivery and installation services. A few industry players provide construction products, ranging from cement or concrete foundation materials to roofing boards and shingles. The companies also sell lumber, insulation materials, drywall, plumbing fixtures, hard-surface flooring, and lawn and garden decor products. Some players also deal in threaded fastener products, and manufactured and natural stone tiles. In addition to general consumers, the industry players cater to professional builders, sub-contractors, remodelers and retailers.
3 Trends Shaping the Future of Building Products – Retail Industry
Adherence to Home Refurbishing Activities: With rising inflation, interest rates, and increased construction costs and home prices, consumers are inclined toward renovating their homes instead of buying one. Consumers continue to invest in making homes enjoyable and comfortable. Industry experts opine that consumers’ discretionary spending on homes will continue, as interests in keeping houses well-maintained are here to stay. Revamping interiors to facilitate work-from-home and entertainment needs continues to remain a major trend. Do-it-yourself (DIY) projects for decorating and maintaining furniture and fixtures are being widely undertaken. There is a higher demand for gardening tools, as well as products related to at-home activities such as paint and tool kits. This, along with rapid urbanization, should keep aiding the top-line performances of the industry participants. Additionally, consumers are open to hiring Professional (Pro) help to complete their home renovations, resulting in rising demand for Pro projects. This is likely to aid companies in the home improvement space, with a focus on building Pro offerings.
Digitization in Focus: Retail Building Products industry participants have been witnessing a surge in online business transactions, owing to consumers’ growing digital dependency. Companies have, therefore, been bolstering their digital presence by expanding the availability of online assortments and bolstering omni-channel capabilities. Such prudent measures have been aiding the companies to meet the accelerated demand. Companies are also ramping up their delivery operations in order to provide safe and swift services, especially to Pro customers. The digital transaction boom should continue to drive the top line of key industry players.
Rising Costs: Some home improvement retailers have been incurring additional costs to provide enhanced payments and other benefits to employees amid the pandemic. A few players have been witnessing inflationary pressure across product categories, as well as higher transportation costs. Such increased costs are likely to put pressure on margins. Nevertheless, companies are adopting prudent saving measures to cushion the impacts of such costs.
Zacks Industry Rank Indicates Solid Prospects
The Building Products – Retail industry is housed within the broader Zacks Retail-Wholesale sector. The industry currently carries a Zacks Industry Rank #25, which places it in the top 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of more than 250 Zacks industries.
The group’s Zacks Industry Rank, which is basically the average of the Zacks Rank of all the member stocks, indicates bright near-term prospects. Our research shows that the top 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the Zacks-ranked industries outperforms the bottom 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} by a factor of more than 2 to 1.
The industry’s position in the top 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the Zacks-ranked industries is a result of a positive earnings outlook for the constituent companies in aggregate. Looking at the aggregate earnings estimate revisions, it appears that analysts are gradually gaining confidence in this group’s earnings growth potential. In the past year, the industry’s earnings estimates for the current fiscal year have increased 20.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Given the industry’s encouraging prospects, we present a few stocks that you may want to consider buying for your portfolio. But before that, it is worth taking a look at the industry’s stock-market performance and current valuation.
Industry Vs. Broader Market
The Zacks Building Products – Retail industry has outperformed the broader Zacks Retail-Wholesale sector and the Zacks S&P 500 over the past year.
The industry declined 8.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past year, whereas the broader sector declined 31.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Meanwhile, the S&P 500 has registered fall of 12.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past year.
One-Year Price Performance
Industry’s Current Valuation
On the basis of forward 12-month price-to-earnings (P/E) ratio, which is the commonly used multiple for valuing Retail-Wholesale stocks, the industry is currently trading at 14.71X compared with the S&P 500’s 16.53X. Further, the sector’s forward-12-month P/E stands at 20.69X.
Over the last five years, the industry traded as high as 23.43X and as low as 14.19X, with the median at 19.54X, as the chart below shows.
Price-to-Earnings Ratio (Past 5 Years)
5 Building Products Stocks to Buy
Builders FirstSource: The Dallas, TX-based company manufactures and supplies building materials. The company has been benefiting from its focus on cost synergies, strategic acquisition, and robust demand from solid housing and repair and remodeling activities. Robust demand for single-family housing, R&R and other activities have been tailwinds for the company’s products and services. Builders FirstSource continues to focus on investing in innovations and enhancing digital solutions for its customers.
Acquisitions are important for Builders FirstSource’s growth strategy to supplement its organic growth and expand extensively across vast geographic boundaries. The Zacks Rank #1 (Strong Buy) company has been active on the acquisition front, which is supporting the top line. It is also focusing on cost-management practices. The stock has surged 49{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for BLDR’s current fiscal-year sales and earnings indicates growth of 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 18.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively, from the prior-year period’s reported figures. The consensus estimate for the current fiscal-year earnings has moved up 0.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Price and Consensus: BLDR
Beacon Roofing: The company is the largest publicly-traded distributor of residential and non-residential roofing materials, along with complementary building products in the United States and Canada. The company has been benefiting from strategic initiatives and the successful execution of its technology initiative in the growing e-commerce platform. The company is also on track with its Ambition 2025 targets, which emphasize operational excellence, above-market growth trajectory and accelerated stockholder value creation. Beacon has been focusing on business expansion through bolt-on acquisitions, thereby expanding its reach.
Beacon is expanding its digital platform in value-added ways. It remains on track with the long-term target of generating $1 billion in annual digital sales. Disciplined pricing in a volatile, supply-constrained marketplace, and effective and timely sourcing have been aiding margins. Cost-saving efforts and productivity initiatives are expected to go a long way in bringing down the Zacks Rank #1 company’s operating expenses, thereby driving margins. The stock has risen 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for BECN’s current fiscal-year sales and earnings indicates growth of 23.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 36.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has been unchanged in the past 30 days.
Price and Consensus: BECN
Home Depot: The Atlanta, GA-based company is the world’s largest home improvement specialty retailer, based on net sales. Home Depot has been benefiting from strong demand for home-improvement projects, robust housing market trends and ongoing investments. Continued strength in both Pro and DIY categories, and digital momentum have been key drivers. Its interconnected retail strategy and underlying technology infrastructure have helped consistently boost web traffic for the past few quarters, aiding digital sales.
Home Depot is witnessing significant benefits from the execution of its One Home Depot plan, which focuses on expanding the supply chain, technology investments and digital enhancements. The Zacks Rank #2 (Buy) company has created the fastest, most efficient delivery network in home improvement through options like buy online pick up in store with convenient pickup lockers, buy online deliver from store with express car and van delivery, and curbside pickup. The HD stock has declined 10.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for its current fiscal-year sales and earnings indicate growth of 3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has been unchanged in the past 30 days.
Price and Consensus: HD
Lowe’s Companies: The Mooresville, NC-based leading home improvements retailer has been gaining from strong growth in its Pro business. The company has been enhancing the experience of its pro customers by upgrading pro-focused brands and revamping the pro-service business website. The company also remains well-positioned to capitalize on the demand for the home improvement market, backed by investments in the technology and merchandise category. Gains from the Total Home strategy and the execution of the Perpetual Productivity Improvement initiative are likely to drive the company’s results in the near and long terms. The Total Home strategy has been resonating well with Pro and DIY customers for a while.
Lowe’s has been progressing well with advancements in the digital channel. The company is investing in enhancing omni-channel retailing capabilities. Management is also committed to enhancing the Pro offerings, expanding the company’s market share and driving the operating margin. Shares of the Zacks Rank #2 company have declined 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for its current fiscal year’s sales and earnings indicates growth of 1.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 12.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has improved 0.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.
Price and Consensus: LOW
GMS: The Tucker, GA-based leading North American specialty building product distributor has been gaining from the robust customer service in a solid residential market, coupled with an inflationary pricing environment and successful platform expansion activities. Inflationary pricing, healthy residential end markets, strong performance from complementary products and the recent acquisitions have been sales drivers for GMS.
The Zacks Rank #2 company has risen 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in a year. The Zacks Consensus Estimate for GMS’ current fiscal year’s sales and earnings indicates growth of 8.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 2.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively. The consensus estimate for current fiscal-year earnings has moved up 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the past 30 days.
Price and Consensus: GMS
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
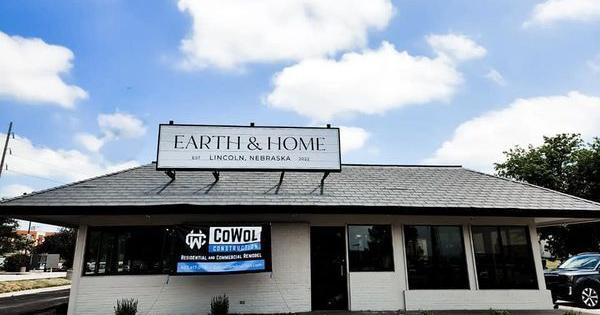
The story of how Megan Connealy came to open up a plant and home decor store across the street from the Nebraska State Penitentiary revolves heavily around two events in February.
First, her husband, Devan, was completing remodeling work on a space in the former Burger King location at 14th Street and Pioneers Boulevard for a coffee shop. He told her he had always had the feeling that they should open some kind of business in the other side.
The second event was a trip to Texas after her husband finished the job in which they visited Magnolia, the company formed by Chip and Joanna Gaines of “Fixer Upper” fame.
One of the things Connealy saw at Magnolia was a propagation wall, where plants were growing. The plants were just for decoration, but she thought it would be cool to have a wall like that with plants people could buy.
“I thought that would be really fun to create,” she said. “It’s an experience.”
A propagation wall is one of the main features of Connealy’s new store, Earth & Home.
People are also reading…
The store, which opened Saturday, offers houseplants and plant accessories, home decor, candles and soaps.
Connealy, who doesn’t have any formal background or experience in botany, said she comes from a family of green thumbs and has always had an interest in plants, something that really “bloomed” during the pandemic.
“Because of COVID, I took the time to really learn about them,” she said.
Connealy also said she has lots of friends who are intimidated by houseplants, and she wanted to find a way to help them.
The store’s “pot your own plant” feature, which allows customers to choose a cutting from the propagation wall that Connealy and her staff will put into a pot along with soil and nutrients, is perfect for those who want a plant, but don’t really know how to go about buying one.
Earth & Home will be open Monday through Friday, 10 a.m. to 6 p.m., and Saturdays, 10 a.m. to 2 p.m.
Husker attire now at SouthPointe
Alumni Hall Stores, the company that bought Husker Headquarters, has opened up a location at SouthPointe Pavilions.
The location that opened June 29 in a space next to Barnes & Noble is technically a relocation of the store that was in the Edgewood shopping center at 56th Street and Nebraska 2.
Alumni Hall, which is based in Knoxville, Tennessee, specializes in selling college athletic apparel. It bought Husker Headquarters a year ago. In addition to the SouthPointe store, it has a store downtown at 1120 P St.
New store at Gateway
A women’s clothing store called Daily Thread opened last month at Gateway Mall.
Minnesota-based Daily Thread describes itself as offering “affordable fashion everyday” for women in sizes ranging from extra small to 3X.
The company, which has stores almost exclusively in the Midwest, has been expanding rapidly, with the Lincoln store one of more than a dozen that’s opened just in the past couple of months.
12 Nebraska shops to check out
Suite Child
Suite Child at 2304 Central Ave. in downtown Kearney has the latest baby and toddler fashions as well as helpful products for families with new babies. There is also a store in Elkhorn.
Mike Konz, Kearney Hub
York Boot ‘N Repair
Tammy and Randy Obermier own York Boot ‘N Repair on the east side of the town square for 100 years. The business is a full-service leather repair store that also builds custom orthotics and sells boots and shoes.
Melanie Wilkinson, News-Times
Platte River Outdoors
Platte River Outdoors in Loup City sells a variety of hunting, fishing and archery gear and accessories. The store is open Monday-Saturday from 8 a.m. to 6 p.m.
Grace McDonald, Kearney Hub
Marah’s Treasures
Marah’s Treasures is at 304 Broadway St. in Taylor in Loup County. The shop carries gift items and fragrances, plus life-sized plywood figures made to order, and is open Thursday and Friday afternoons.
Marah’s Treasures Facebook page
The Most Unlikely Place
The Most Unlikely Place, 205 Main St. in Lewellen, is just a short drive from Lake McConaughy and is open Wednesday-Saturday 9 a.m. to 2 p.m. It closes for the season from mid-November to mid-March.
The combination bistro/gallery serves breakfast and lunch as well as offering a wide variety of fine art. Sculptures, jewelry, paintings and more are available.
VICTORIA AYOTTE BROWN, Journal Star
Fort Cody Trading Post
The Fort Cody Trading Post, 221 Halligan Drive in North Platte, has a variety of merchandise. The store is open from 9 a.m. to 5:30 p.m. “We have one of the best selection of western books anywhere, handmade Native American jewelry and arts, T-shirts, toys, Minnetonka Moccasins, retro soda pop, candy, hot sauces, cook books, Nebraska-made items and food, stuffed animals, souvenirs, cards and much, much more,” the store’s Facebook page boasts.
Nebraska Tourism
Hollywood Candy
Hollywood Candy is in Omaha’s Old Market at 1209 Jackson St. The store specializes in “hard-to-find retro and nostalgic candies of the past” and has modern-era candy as well. It has a large collection of PEZ dispensers and retro toys and novelties.
Rick Neibel/Nebraska Tourism
Brown Sheep Co. Mill Store
The Brown Sheep Co. Mill Store, located at 100662 County Road 16 in Mitchell, is attached to the mill and sells the company’s yarn “seconds” and other crocheting/knitting supplies. The company’s yarn is known and sold worldwide. One benefit of the mill store is “seeing all the wonderful handpaints that our handpainter tries out when developing new color ways. Because these hanks are one of a kind and generally not reproduced, they are not offered to our retail customers for purchase,” according to the company’s website.
Nebraska Tourism
Master’s Hand Candle Co.
Master’s Hand Candle Co. in Tekamah, 3599 County Road F, has more than candles — delectable chocolates, flowers, home decor, shopping, gifts, jewelry, purses and diva wear. The shop’s website declares it “every woman’s dream store.” The store is open Monday through Saturday from 9 a.m. to 5:30 p.m.
Nebraska Tourism
North Platte Art And Gift Gallery
The North Platte Art and Gift Gallery, 516 N. Dewey, is open Tuesday through Saturday and has local contemporary art in a variety of mediums. The enterprise began in 1987 when a group of local artists rented a vintage downtown storefront. One of the five galleries hosts monthly competitive art shows.
Rick Neibel/Nebraska Tourism
Park Avenue Antiques
Park Avenue Antiques, 515 N. Park Ave. in Fremont, has furniture, dishes, linens, home decor and books, as well as a multitude of signs. The shop is open from 9 a.m. to 5 p.m. Monday-Saturday and noon to 5 p.m. Sunday.
Emilie Bouvier/Nebraska Tourism
The Keeping Room
Its website describes The Keeping Room as “a fusion of stylish antiques, unique holiday and home decor, unique fashion, food and drink and a friendly atmosphere.” The Nebraska City store is at 717 Central Ave. and is open Monday-Wednesday 10 a.m.-6 p.m., Thursday-Saturday 10-7 and Sunday 1-4 p.m.
Rick Neibel/Nebraska Tourism
Marshall Custom Hats
Marshall Custom Hats, 214 Staples St., in Arthur features handmade hats made by James Marshall. “It’s amazing that about 42 percent of my customers are repeat customers,” Marshall told Tri-State Livestock News last year. “Once I get them in once, they’re usually back for another one.”