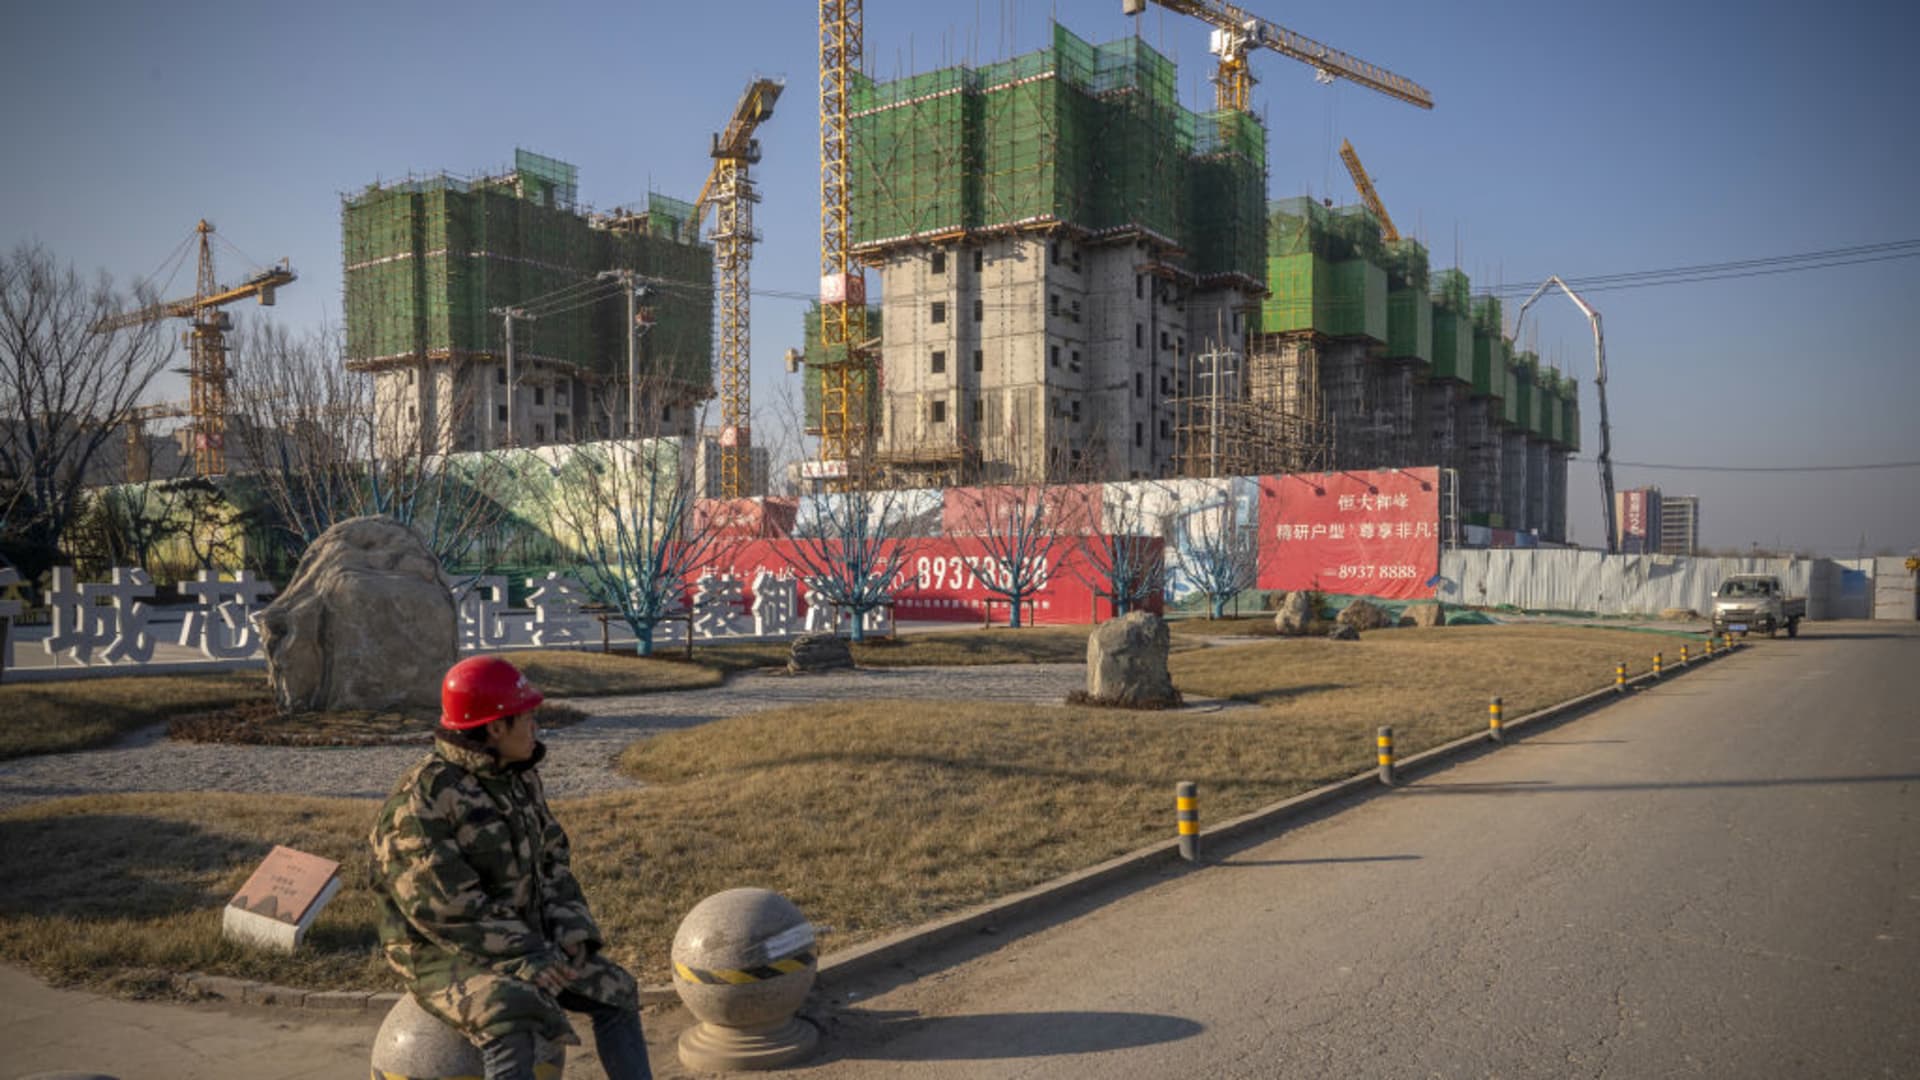
Chinese true estate developers, together with very indebted Evergrande, have operated a business enterprise that relied on marketing flats in advance of they ended up concluded. Pictured below is an Evergrande development in Beijing on Jan. 6, 2022.
Bloomberg | Bloomberg | Getty Images
BEIJING — China’s genuine estate market desperately requires a enhance in self confidence, analysts explained, after studies of homebuyers halting home finance loan payments rocked financial institution stocks and elevated problems of a systemic crisis.
The sizing of the mortgages is not as worrisome as the impact of the newest events on need and rates for just one of the major economic belongings in China: residential housing.
“It is essential for policymakers to restore self-confidence in the sector immediately and to circuit-break a prospective detrimental feed-back loop,” Goldman Sachs chief China economist Hui Shan and a group reported in a report Sunday.
Previous 7 days, a spike in reported figures of homebuyers halting mortgage loan payments prompted lots of Chinese financial institutions to announce their low exposure to these loans. But the bank stocks fell. The homebuyers had been protesting design delays for the apartments they’d paid out for forward of completion, as is regular in China.
“If remaining on its personal, much more homebuyers could stop spending mortgages, [further] straining property developers’ income flows, which in flip could guide to a lot more development delays and project halts,” the Goldman report reported.
Uncertainty “dampens households’ motivation to acquire homes from these builders who arguably need the profits the most,” the analysts mentioned.
Right after two a long time of huge advancement, China’s home developers have observed it more durable to keep afloat beneath Beijing’s crackdown on the companies’ substantial reliance on personal debt for progress. Extremely indebted builders like Evergrande Group defaulted late final year.
Developers’ persistent financial troubles alongside with Covid limitations have delayed development tasks, pushing homebuyers to put their have economical credit rating at threat by suspending their mortgage loan payments.
The variety of assets assignments associated much more than tripled in a couple days to additional than 100 as of July 13, in accordance to Jefferies.
That’s a little 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the whole house loan harmony in China, the analysts stated.
Throughout banking companies protected by Goldman Sachs, ordinary publicity to assets together with mortgages was just 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, the firm’s fiscal products and services analysts wrote in a report very last 7 days.
“We look at this mortgage threat to be a lot more about households’ willingness, fairly than capability, to make home finance loan payments,” the report reported, “as builders have dragged out the development of properties given the problems of refinancing.”
But if additional homebuyers refuse to fork out their home loans, the bad sentiment would minimize demand — and theoretically price ranges — in a vicious cycle.
That is prompted phone calls to boost self esteem.
“In the 2nd 50 percent of 2022, there is no hope for a swift rebound in the serious estate sector, and it will proceed to drag financial advancement,” reported Gary Ng, senior economist, Natixis CIB Asia Pacific. “The antidote is to raise the self confidence of homebuyers and developers when again, but it has established to be a difficult activity.”
Halting home finance loan payments is an intense measure that shouldn’t grow to be a prevalent observe, specially since there are authorized procedures to address delays in completing flats, said Qin Gang, deputy director of China authentic estate exploration institute ICR.
He cited discussions with sector executives in indicating experiences of stopped payments are pretty unfavorable for preserving the real estate sector’s restoration.
Normally, if developers are unsuccessful to supply flats inside of the agreed period, homebuyers can utilize to terminate their obtain contracts, Goldman Sachs serious estate analysts said in a report very last 7 days.
The analysts mentioned acceptance generally usually takes a few months and the developer will have to have to return the down payment and finished mortgage loan payments to the homebuyer, like fascination. The remaining mortgage payment should go to banks, the report claimed.
A 6-yr very low in home buy programs
Need for new houses has presently fallen.
A People’s Financial institution of China quarterly survey identified in June that only 16.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of people system to acquire a residence in the future a few months, the most affordable due to the fact 16.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 3rd quarter of 2016.
Earlier this year, the central bank took a substantial move toward boosting the serious estate market place by decreasing the home loan charge. Quite a few metropolitan areas have peaceful procedures in the final numerous months to aid residence purchases.
But since April, actual estate gross sales have fallen 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or a lot more from very last year’s ranges, in accordance to Wind Information and facts knowledge.
The ordinary selling price throughout 100 Chinese cities has scarcely risen around the previous 12 months, though price ranges in massive metropolitan areas like Beijing and Shanghai have surged by double-digits, reflecting divergence in demand, according to Wind Facts.
Phone calls to full and deliver flats
Any plan that can assure the shipping and delivery of households would be valuable, mentioned Bruce Pang, chief economist and head of exploration, Bigger China, JLL. He claimed banking companies have confined exposure to uncompleted construction projects and have the means to restore market self esteem.
Dai Xianglong, previous head of the People’s Financial institution of China, mentioned Saturday that China would not knowledge anything like the 2007 U.S. “subprime home finance loan disaster,” and suggested actions to improve self esteem in the true estate marketplace and stabilize housing costs. That is according to a state media report.
But even condition-backed Securities Situations very last week elevated the specter of systemic money chance in an report that inspired nearby governments and developers to provide houses on time.
“Credit history losses relating to home loan loans are minimum and the influenced balances are modest at most Chinese countrywide banking companies at the moment,” Harry Hu, senior director at S&P Worldwide Ratings, claimed in a statement.
“But draw back stress could make if the latest suspension in mortgage repayments by some resident teams in China is not managed nicely and manifest into program dangers,” Hu mentioned.
The formal newspaper for China’s banking and insurance coverage regulator on Sunday revealed comparable admonitions and pushed to support shipping and delivery of apartments and funding for the serious estate business.
Without having the assets sector’s drag, China’s GDP could have developed by 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 2nd quarter compared to the .4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} development claimed Friday, according to Goldman Sachs’ evaluation.
