When is housing market truly down? When sellers lose money

When is housing market truly down? When sellers lose money

When

Charges are coming down, but that does not mean sellers are losing out. Unless of course they ordered their residences inside of, say, the previous 12 months, sellers aren’t taking losses — instead, they are having considerably less income. Earlier mentioned: Exterior the gated home of a home in Southwest Ranches, just one of the most well-liked solitary-family members dwelling communities in Broward.

cjuste@miamiherald.com

It is that time of yr when all people tends to make daring predictions about what lies forward in 2023. Just very last thirty day period, the California Association of Realtors projected the regular selling price of houses in the Golden Condition would fall almost 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} upcoming 12 months.

But I have my own concept. Sure, rates are coming down, but that doesn’t mean sellers are shedding out. Except they acquired their households inside, say, the very last 12 months, sellers are not using losses — relatively, they are getting a lot less income. To me, rates don’t genuinely “fall” right up until owners offer for fewer than they compensated.

Properties now may perhaps sell for much less than they would have, say, six months in the past, but nonetheless for a lot more than what sellers paid. You just cannot get rid of what you under no circumstances had, which, in this situation, is the fairness you make up about time as residence values increase and drop.

The only way to cash in on fairness is to provide your put or borrow towards it. Except if you do a person or the other, “equity” is a nebulous term for some thing you know is there, but you can’t contact.

To assist my hypothesis, I give you the most current profits report from facts services organization ATTOM: The earnings margin on the median one-family members house slipped from 57.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the next quarter to 54.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 3rd. There’s however a large amount of earnings to be eaten away right before sellers essentially shed dollars.

HOUSING SLUMP

Housing is by now in a recession, and the Federal Reserve Board is not possible to just take its foot off the brakes until finally 2024, in accordance to Robert Dietz, the main economist at the Countrywide Association of Home Builders. Dietz believes the sector will rebound in 2024, but till then, the slowdown will only exacerbate the shortage of new properties.

“We’ve been underneath-developing considering that 2008,” he states, noting that the sector is shorter about 1 million homes nationwide. This year’s drop in homebuilding is the very first due to the fact 2011. “We finally bought to 1.1 million starts” final 12 months, Dietz reported. “That’s in line with what we think we want to satisfy demand from customers. And by 2025, we must be again to that stage.”

Created Houses

Manufactured residences, aka mobile homes, are a less high-priced substitute to web site-crafted houses. Last calendar year, the median selling price of a manufacturing facility-designed home was just $61,400 — that is $220,000 much less than that of a common single-relatives residence.

A person of the knocks versus manufactured homes is that they shed benefit, relatively than value. But according to LendingTree, that has not been the circumstance over the previous 5 several years. Among 2016 and 2021, the median worth of a manufactured household enhanced by an average of 34.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Single-spouse and children properties increased just hardly additional — by 35.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — about the exact same time period.

GOLDEN Several years

Spectacular: According to the Nationwide Reverse Mortgage loan Loan providers Affiliation, homeowners aged 62 and older noticed their merged housing wealth reach a file $11.6 trillion in the second quarter.

Much more Signals of the Apocalypse:

▪ Thanks to a title business error, a lady who assumed she was acquiring a dwelling outside of Reno wound up with the full neighborhood: 84 properties in addition two common regions. It would seem the title enterprise slice-and-pasted the legal description for the full shebang on to her deed.

▪ In Texas, a retired few is remaining sued by their householders association for $250,000. Their crime: feeding ducks. In accordance to the suit, neighbors claim the ducks defecated on their residence and destroyed their gardens.

▪ How would you like to dwell in a $1.7 million house in San Ramon, California, for free of charge? Anita and Mahesh Khurana did just that for several years: The few built 6 payments on their financial loan and then stopped chilly, in some way preventing foreclosures due to the fact 2009. They were finally evicted this summer months. But they may possibly not keep the document: In accordance to one particular resource, another person in New York fended off foreclosure for far more than two decades.

▪ Extra customers of recently crafted houses compensated hard cash in the 3rd quarter than those people who financed their buys by way of the Federal Housing Administration. According to Census Bureau data, 7.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all the new houses bought in the course of the period of time were being backed by the FHA. Which is the smallest share considering that the fourth quarter of 2007, economist David Logan of the Countrywide Affiliation of Property Builders factors out.

On the other hand, 9.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} went to all-income customers. Which is a 20-12 months substantial, Logan notes. Typically, funds potential buyers are people who sold their homes in expensive markets and moved to a lot less pricey locations. Loaded with a pocketful of moolah, they can fork out whichever a seller is inquiring, and then some. And that drives rates higher.

Census details also exhibits that 78{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the new spots sold in the third quarter have been financed with common financial loans, even even though FHA-insured home loans are somewhat less complicated to qualify for. In the current-house industry, meanwhile, 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the resale properties sold in September went for dollars, NAHB experiences.

Lew Sichelman has been covering true estate for additional than 50 yrs. He is a normal contributor to various shelter publications and housing and housing-finance market publications. Readers can get in touch with him at lsichelman@aol.com.
Million-dollar homes lose luxury status as buyers get less space

Million-dollar homes lose luxury status as buyers get less space

A for-sale indicator in entrance of a house mentioned for more than $1 million on April 29, 2022 in San Francisco.

Justin Sullivan | Getty Pictures

Grocery shoppers aren’t the only kinds who have to contend with the phenomenon acknowledged as “shrinkflation,” which is what happens when the price tag of one thing stays the same or gets increased even as the product gets smaller.

Dwelling customers have to be concerned about “shrinkflation,” much too. The development is hitting houses, particularly people in the $1 million assortment, exactly where the size of the homes that potential buyers are receiving for their dollars is shrinking, in accordance to new exploration from authentic estate web page Zillow.

It can be one way inflation is hitting the housing market, in accordance to Skylar Olsen, main economist at Zillow.

Additional from Personal Finance:
Reduced credit score scores may well direct to $104,000 additional in house loan fees
Rents are high in these 5 towns. Less expensive parts have concealed charges
What to know about backing out of a home acquire below agreement

Dollars will not go as significantly for properties at any selling price position, she claimed. But the $1 million threshold is specifically eye-catching for the reason that of the expectations customers generally location upon it.

“A million bucks isn’t as magnificent as it at the time was,” Olsen stated.

The plan that $1 million is only sufficient to acquire a normal household has been about for awhile in California. Now far more and far more markets are also suffering from that exact same sentiment, Olsen said.

A lot more than two times as a lot of $1 million-as well as residences were being marketed this spring when compared to two many years in the past, according to Zillow. The largest will increase took place in Austin, Texas Portland, Oregon and Riverside, California.

Yet $1 million properties are having lesser, in accordance to Zillow listings flooring system information. People properties peaked at 3,021 sq. feet in mid-2020 and ended up down to 2,530 early this 12 months.

However, property dimensions at that price tag level has now risen to 2,624 square ft, which is still 397 square feet less than from the 2020 high.

Lesser million-dollar houses have much less loos

Considering that 2019, the usual residence promoting for about $1 million has shrunk in practically every key metropolitan place, Zillow’s assessment identified. Today’s $1 million properties are inclined to have fewer bathrooms and are usually older, the report notes.

The largest declines in measurement of properties at this value place occurred in Phoenix, where by they fell about 1,116 square feet, and Nashville, Tennessee, the place they observed a 1,019-sq.-foot decrease.

Just two metropolitan areas saw the measurement of their flooring strategies improve for $1 million-furthermore homes in that time. That features Minneapolis, with an raise of about 36 sq. toes, or about the dimension of a closet, and St. Louis, by about 406 square ft, or somewhere around a home and a fifty percent.

Future property buyers searching in the $1 million selection may well get the most for their dollars in Hartford, Connecticut, exactly where the value for each sq. foot is $205, in accordance to Zillow.

That was followed by other towns in the middle of the country which include Indianapolis, with $209 for each square foot Oklahoma Town, at $214 Kansas Town, Missouri, $221 and Cincinnati, $222.

The maximum price tag for each sq. foot in all the important metropolitan places tracked by Zillow was San Jose, with about $715. A normal solitary benefit household in that city price a lot more than $1.5 million as of July.

Zillow defines $1 million properties as solitary-household dwellings that marketed concerning $950,000 and $1.05 million, when $1 million furthermore houses sold for $1 million or much more. The information excludes condominiums.

How the cooling market may perhaps have an effect on shrinkflation

The current scorching true estate marketplace has led to 72{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the latest homebuyers possessing regrets about their residence buys, a new study from Intelligent Genuine Estate discovered. Spending too much money was the most popular motive for buyer’s regret, with 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of respondents.

On the other hand, as the sector cools, there are indicators price ranges are coming down, with 1 in 5 sellers dropping their inquiring selling prices in August, in accordance to Realtor.com. That may possibly give prospective buyers more chance to store all around and get the most value — and square footage — for their income.

“Encompass you with experts who actually treatment about your targets and your goals and also are proficient of the local location,” Danetha Doe, economist at Intelligent Authentic Estate, not long ago told CNBC.

Homeowners lose wealth as rising interest rates weigh on home values

Homeowners lose wealth as rising interest rates weigh on home values

A “For Sale” sign outside a home in Albany, California, on Tuesday, May perhaps 31, 2022.

David Paul Morris | Bloomberg | Getty Visuals

Some householders are dropping wealth as significant property finance loan prices weigh on property values, at least on paper, as the once pink-sizzling housing sector cools promptly.

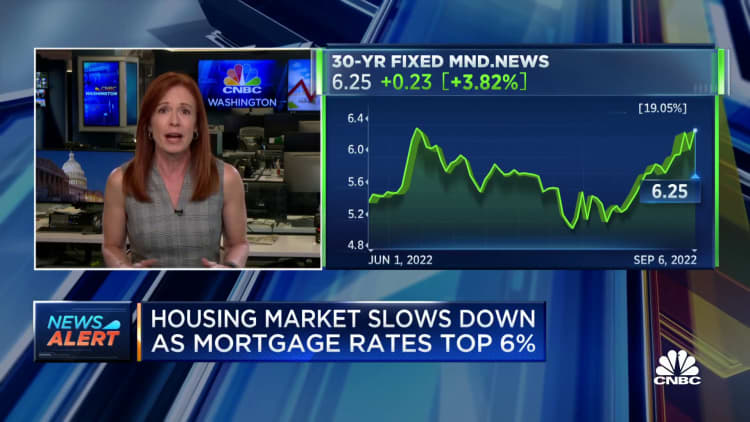
Revenue have been slowing down for numerous months, with house loan costs now double what they ended up at the start of this 12 months.

House charges, similarly, dropped .77{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from June to July, according to a recent report from Black Knight, a computer software, details and analytics corporation. Although that may perhaps not sound like a ton, it was the major regular monthly drop because January 2011 and the very first regular monthly fall of any dimensions in 32 months.

Housing market slows as mortgage rates hit 6.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}

“Yearly dwelling rate appreciation even now arrived in at about 14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, but in a sector characterized by as much volatility and quick improve as present day, this sort of backward-on the lookout metrics can be deceptive as they can mask far more existing, pressing realities,” wrote Ben Graboske, president of Black Knight Knowledge & Analytics.

Around 85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of major marketplaces have noticed selling prices come off peaks by means of July, with just one-third coming down a lot more than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and about 1 in 10 falling by 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or far more. As a final result, soon after gaining trillions of bucks in property equity collectively through the to start with two several years of the Covid pandemic, some house owners are now shedding fairness.

So-identified as tappable fairness, which Black Knight defines as the sum a homeowner can borrow versus even though trying to keep a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity stake in the assets, strike its 10th consecutive quarterly document high in the second quarter of this yr at $11.5 trillion. But data suggests it may well have peaked in May possibly.

Declining house values in June and July introduced the complete quantity of tappable equity down 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and offered the weakening in the housing market considering the fact that then, the third quarter of this calendar year will demonstrate a a lot more sizeable decrease.

“Some of the nation’s most equity-rich markets have viewed considerable pullbacks, most notably amid vital West Coast metros,” pointed out Graboske.

From April by way of July, San Jose, California, shed 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its tappable equity, followed by Seattle (-18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Diego (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Francisco (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Los Angeles (-10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

House owners are nonetheless considerably a lot more flush than they have been the previous time the housing industry went by way of a big correction. All through the subprime mortgage crash, which began in 2007, and the subsequent Excellent Recession, dwelling values plummeted by virtually half in some significant marketplaces. Hundreds of thousands of debtors went underwater on their mortgages, owing a lot more than their households have been worthy of.

That is not the scenario right now. Latest debtors, on normal, owe just 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their home’s value on the two first and 2nd home loans. It is the most affordable leverage on record. Shedding some value on paper should not impact all those entrepreneurs at all.

There are, nonetheless, about 275,000 debtors who would tumble underwater if their households ended up to get rid of 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their current benefit. A lot more than 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all those borrowers acquired their properties in the 1st six months of this calendar year, which was the top of the market.

Even with a common 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop in charges, destructive equity costs would continue to be nowhere close to the concentrations noticed throughout the monetary crisis, according to the report.