‘A real estate bottom?’ More homebuyers jump back in as the year kicks off

‘A real estate bottom?’ More homebuyers jump back in as the year kicks off

Authentic estate agents verify what housing details is starting to exhibit: Much more homebuyers are rising from their self-imposed hibernation.

The volume of mortgage loan apps for dwelling buys rose 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} week over week, the House loan Bankers Affiliation (MBA) survey for the week ending Jan. 13 identified. Housing sentiment ticked bigger at the finish of last year, for each Fannie Mae. And household builders are reporting an raise in consumer website traffic in January, the first uptick since December 2021, according to an market survey.

These buyers are hoping to enjoy the benefits from a a lot more favorable market place, bagging vendor incentives along with a marginally lessen mortgage loan price, ahead of the spring-shopping for season draws in a lot more level of competition.

“I experienced one particular of my consumers at Meta and yet another from Microsoft who have been active up until September of previous yr access out to me past weekend,” Jeff Reynolds, a broker at Compass and founder of UrbanCondoSpaces.com, explained to Yahoo Finance. “They had wanted to see what the current market would do, and because it looks to have stabilized and costs are down, they are hoping to get a move ahead of what would inevitably be a true estate bottom.”

Home sellers are more likely to offer buyers concessions, a Redfin report found. At least 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homes sold during the fourth quarter of 2022 included an incentive. (Credit: Getty Creative).

Dwelling sellers are extra likely to offer potential buyers concessions, a Redfin report observed. At minimum 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of households sold through the fourth quarter of 2022 provided an incentive. (Credit history: Getty Artistic).

‘Bringing people back again in’

The dip in home loan fees in recent weeks has taken some of the edge off of the document-setting ascent costs clocked in previous year. Past 7 days, the ordinary rate on the 30-year fastened mortgage — the most generally applied property personal loan for a invest in — settled closer to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} than 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, fitting into extra buyers’ budgets.

“Interest costs are greater for initially-time customers. I consider naturally it’s just bringing folks back again in,” John Downs, senior vice president at Vellum Property finance loan, instructed Yahoo Finance.

At the similar time, dwelling selling prices have also softened, with the median record rate falling to $400,000 in December, in accordance to Redfin, down 11.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from June’s peak of $449,000.

“The vast majority of exercise is from new purchasers,” Reynolds said. “In our microclimate in downtown Seattle, the the vast majority of action has strike definitely reasonably priced cost details. That’s pushed primarily by that millennial buyer, that younger consumer, or initial-time purchaser eventually taking benefit of market place disorders — probably for the to start with time.”

‘Picking for deals’

The buyers who are coming back again are also finding gutsy, knowing that the sellers who continue being in the sector are open to negotiation.

“In 2022, prospective buyers set the market by bidding up, which led to escalating price ranges and primarily possessing to spend to acquire,” Downs reported. “Now, rather of waiting for listing rates to drop, customers submit features with major bargains and make the vendor make a selection. And that seems to be performing.”

At the very least 16.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homes bought in December experienced a selling price slice, Real estate agent.com info found, an increase from 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a 12 months ago. Even home builders are squishy on cost.

A person of Monte Miner’s shoppers obtained $15,000 off a recently created household initially priced at $409,000, in accordance to the serious estate agent at Ironwood Fantastic Homes in Arizona.

Rick Nazarro of Colonial Manor Realty talks with a pair of interested buyers in the driveway as a couple waits to enter a property he is trying to sell during an open house in Revere, MA. (Credit: Blake Nissen for The Boston Globe via Getty Images)

Rick Nazarro of Colonial Manor Realty talks with a pair of interested customers in the driveway as a few waits to enter a residence he is hoping to provide in the course of an open up residence in Revere, MA. (Credit: Blake Nissen for The Boston World by using Getty Pictures)

“Buyers are coming back again, but they are choosing for offers. Let’s say a household is listed for $400,000 — a whole lot of the provides coming in are below that range,” Miner mentioned. “Some sellers’ pricing anticipations are trapped in the earlier, like three months in the past. It’s various now.”

Not only are some people receiving large cost reductions, they are also snagging vendor concessions to further ease the stress of nevertheless-significant residence prices.

For instance, at least 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders reduced their dwelling rates in December, information from the Countrywide Affiliation of Homebuilders identified. A further 62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders continued to use incentives to catch the attention of customers, like charge invest in-downs and shelling out factors. According to Redfin, about 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of properties marketed in the closing three months of 2022 incorporated a vendor concession, these types of as funds for repairs or closing expenditures.

“If you don’t have not enough dollars for closing expenses,” Downs said, “sellers are supplying to fork out it for you,”

A sign is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit: Mario Tama/Getty Images)

A indication is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit: Mario Tama/Getty Images)

Timing is anything

With rates finally inching down, now could be an opportune time to invest in a property prior to the spring season is in entire swing, Downs explained. But you need to be well prepared. Having a pre-qualification completely ready, setting a spending budget, and conversing to a authentic estate specialist can raise your chances of negotiating a far better deal at closing.

According to Miner, stepping into the marketplace just before it will get flooded by competitiveness could be a excellent go if you want to negotiate terms.

“From what I’m looking at,” Miner explained, “I sense like the bottom is right here.”

Gabriella is a personalized finance reporter at Yahoo Finance. Stick to her on Twitter @__gabriellacruz.

Click right here for the newest financial news and economic indicators to assistance you in your investing decisions

Examine the most current economical and company news from Yahoo Finance

Download the Yahoo Finance application for Apple or Android

Comply with Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, and YouTube.

Realtor.com Site Visitor Survey Results: Homebuyers Respond to Challenges from the Market and the Economy at Large

Realtor.com Site Visitor Survey Results: Homebuyers Respond to Challenges from the Market and the Economy at Large

Highlights

  • High listing prices and high mortgage rates lead 34.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of buyers to report budget challenges in their homebuying experience.
  • The share of buyers who report being overbid on a home has decreased as the market has begun to correct itself.
  • Buyers are increasingly targeting homes in other states and smaller towns in a search for affordability.
  • 40.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all buyers and 45.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of first-time buyers believe the US is currently in a recession, and recession perception is increasingly affecting when buyers are looking to make a purchase.


Background and Context

In order to better understand the sentiment and experiences of buyers, sellers, and renters currently on the market for homes, the Realtor.com Economics team conducts a randomized survey of visitors to listing and search result pages on the site. Respondents are asked about the reasons they’re visiting the site, how they’ve been engaged with the housing market, and how they feel that current market conditions are impacting their behavior. These data series stretch back as far as late 2017, providing the opportunity to evaluate a pre-pandemic baseline as well as constant monitoring throughout the tumultuous two-year COVID-19 housing market. In recent months, we can track how market players are responding to the current real estate refresh and see the ways in which the market has and has not reverted to “normal” conditions. Responses are weighted based on respondents’ reported ages, ensuring that the survey captures an accurate picture of the demographic breakdown of online real estate marketplace visitors, and are aggregated to three-month rolling averages to preserve significant sample sizes. This piece focuses on survey respondents who report being active or prospective buyers, and incorporates findings from other Realtor.com research to provide context to their responses.


Buyer Challenges

There has been no shortage of adversity for homebuyers in 2022. For 36 consecutive weeks, year-over-year listing price growth has been in the double digits and mortgage rates have hovered around or above 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} since April. The alternative hasn’t been much more appealing, as nationwide rent has reached new record levels for 17 months in a row. It’s no wonder that 34.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all buyers and 40.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of first-time homebuyers in our survey report that their budget has been a challenge to their homebuying experience. Access to financing is also a concern. 9.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all buyers and 19.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of first-time buyers report credit score issues interfering with their plans to buy a home. Uncertainty has made its way into the minds of buyers, as 31.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} now don’t know when they want to buy.


Table 1: How soon do you think you will buy a property?

Share of responses
Response July 2022 July 2021 July 2020 July 2019
Within the next 6 months 45.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 49.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 45.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 43.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
Within 7-12 months 14.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 14.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 16.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
More than a year 7.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 8.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 9.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 11.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
Don’t know / Not sure 31.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 30.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 30.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 27.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}


One way in which homebuying has gotten easier is in the level of competition buyers face. Just 9.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of buyers report being overbid, down from the peak of 12.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in April and back in line with the responses from early 2021. Again, though, first-timers are having more problems on this front, as 12.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} report being overbid. These responses are consistent with changes we see in the market at large. The share of listings that have seen their price reduced has almost doubled year-over-year, and the number of days a listing spends on market has started to rebound from an all-time low a few months ago. Even though this issue is on the decline, it remains much more prevalent than it was prior to the pandemic, when the share of respondents reporting being overbid hovered around 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Adding fuel to the competitive fire is buying activity by large investors, who constituted a larger portion of home sales and made more all cash purchases during the same pandemic period that survey respondents reported being overbid the most often.


Buyer Targets

Budget challenges have home shoppers searching for smaller homes. 8.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} are looking for condos or apartments to buy, the highest share since January of 2019. We showed in our most recent quarterly cross-market demand report that the share of shoppers searching for listings in other states has reached an all-time high, and our survey suggests that trend will continue. 33.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of buyers are looking to buy in another state this July, the highest in survey history. Compare this to 25.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in July 2021 and 23.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in July 2020.


Not only are home shoppers more likely to search cross-country, they’re more likely than ever to be looking at smaller markets. 49.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} report that they are looking to buy a home in a small town or rural area, back in line with the peak levels of August and September 2020. This coincides with our research into the top emerging housing markets in the first half of 2022, where we found that a search for affordability is leading homebuyers to heat up the markets in places like Elkhart-Goshen, IN, which came in as the top market on our list and is a mainstay in our hottest markets as well. Just 12.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of buyers are targeting urban areas, down from 15.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in February; and just 32.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} are targeting suburban areas, down from 36.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in March.


Buyer Economic Perceptions

Economic research, the news, and casual conversations are full of speculation about whether or not the US economy is currently in a recession or if one is on its way. Despite strong employment reports in recent months, inflation has a strong grip on American consumers and wage growth has not kept up, leaving millions in a tighter financial position than they have been in years. Our survey attempts to quantify this effect by asking questions about the timing of the next economic downturn and the decisions related to homebuying that it will impact. As a baseline, in December 2019, 46.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} said a recession was a year or more off, while 14.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} said that we were currently in a recession. COVID-19 changed this drastically, and in June 2020 just 10.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} thought that a recession was more than a year away while 53.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} thought that one was underway. A year ago, the recovery moderated these responses, with 27.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} responding that a recession was more than a year off and 31.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} responding that the economy was currently in a recession. Recent months have seen a re-souring of economic outlook. In July 2022, just 12.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the buyers surveyed said that the next recession would not happen for at least another year, while 40.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} said that a recession was already upon us. June and July saw the two biggest month-to-month jumps in the share of respondents indicating their belief that the US economy was in a recession since May 2020. First-time homebuyers are slightly more pessimistic, with 45.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} saying they believe a recession is underway.


What does this mean for the housing market? It appears that buyer behavior is becoming more sensitive to perceptions about the state of the economy. Just 42.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of respondents report that an economic downturn will have no effect on their decision to buy a home, down from 46.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} last year and 51.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in December 2021. Buyers are more likely to respond to the state of the economy, but the direction of their response is mixed. The share of surveyed buyers saying that a recession will make them more likely to purchase a home is up to 27.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 24.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} last year, and the share responding that it will make them a lot less likely to purchase a home is up from 5.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year. Respondents’ current perceptions of the economy also impact their response to it. Among those who say we are currently in a recession, 45.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} say it will have no effect on their decision to purchase a home and 24.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} say it will make them more likely to purchase a home. Compare this to the respondents who think a recession is more than a year off: 33.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} report that it will have no effect on their homebuying, while 36.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} report that it will make them more likely to purchase. Those who are more bullish on the current economic conditions are more likely to be positioning themselves to buy the eventual dip. No matter how recession concerns ultimately impact decision making, there are moves that consumers can make to prepare to weather a potential recession.


Methodology

Surveys are conducted via Qualtrics and are administered randomly to visitors on Realtor.com. For this report, we consider only respondents who indicate that they are active or prospective homebuyers. Weights are calculated by computing the share of survey respondents falling into categories based on age and adjusting these proportions to match the share of all visitors to Realtor.com and similar online real estate marketplaces segmented by age. Sample sizes and response totals are calculated as 3-month rolling totals. Consequently, effects and trends may be lagged. Sample size for July 2022 is 928.


Joel Berner

China’s homebuyers are running out of patience with the real estate slump

China’s homebuyers are running out of patience with the real estate slump

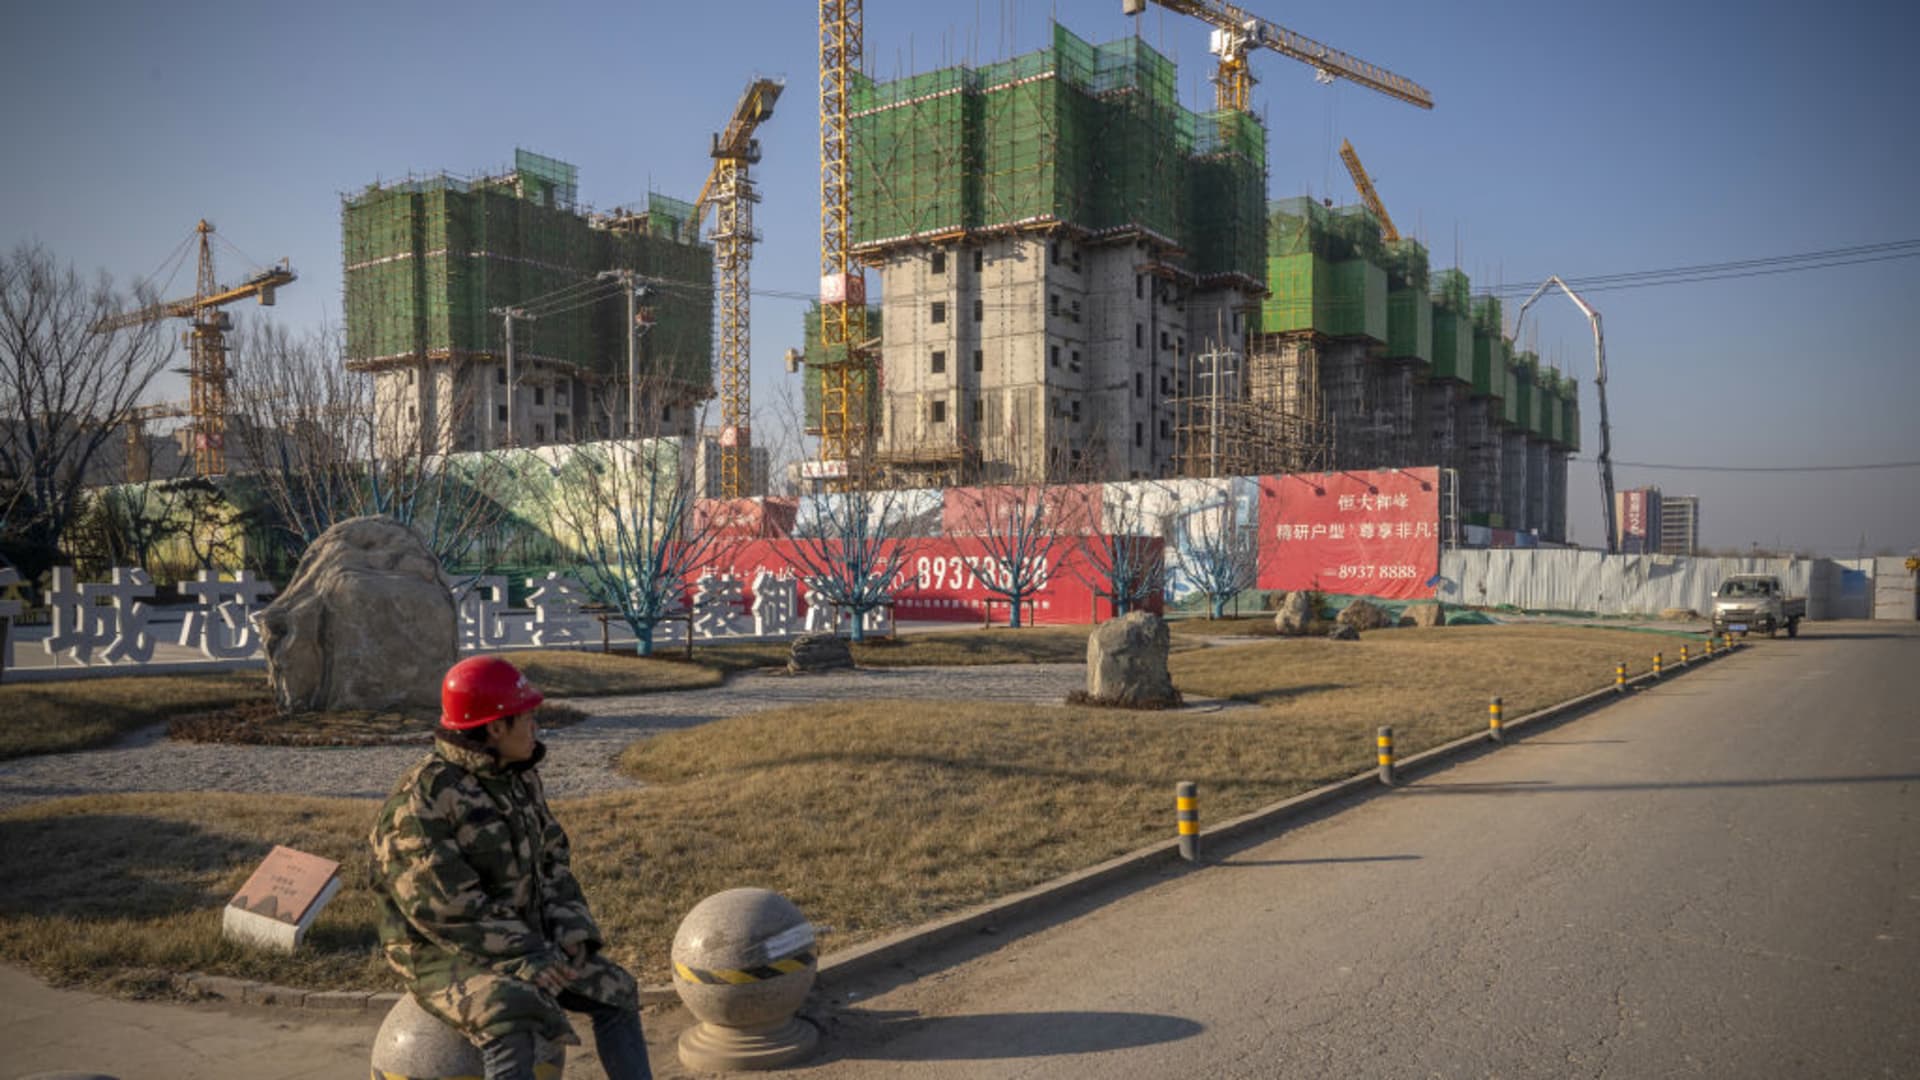
Chinese true estate developers, together with very indebted Evergrande, have operated a business enterprise that relied on marketing flats in advance of they ended up concluded. Pictured below is an Evergrande development in Beijing on Jan. 6, 2022.

Bloomberg | Bloomberg | Getty Images

BEIJING — China’s genuine estate market desperately requires a enhance in self confidence, analysts explained, after studies of homebuyers halting home finance loan payments rocked financial institution stocks and elevated problems of a systemic crisis.

The sizing of the mortgages is not as worrisome as the impact of the newest events on need and rates for just one of the major economic belongings in China: residential housing.

“It is essential for policymakers to restore self-confidence in the sector immediately and to circuit-break a prospective detrimental feed-back loop,” Goldman Sachs chief China economist Hui Shan and a group reported in a report Sunday.

Previous 7 days, a spike in reported figures of homebuyers halting mortgage loan payments prompted lots of Chinese financial institutions to announce their low exposure to these loans. But the bank stocks fell. The homebuyers had been protesting design delays for the apartments they’d paid out for forward of completion, as is regular in China.

“If remaining on its personal, much more homebuyers could stop spending mortgages, [further] straining property developers’ income flows, which in flip could guide to a lot more development delays and project halts,” the Goldman report reported.

Uncertainty “dampens households’ motivation to acquire homes from these builders who arguably need the profits the most,” the analysts mentioned.

Right after two a long time of huge advancement, China’s home developers have observed it more durable to keep afloat beneath Beijing’s crackdown on the companies’ substantial reliance on personal debt for progress. Extremely indebted builders like Evergrande Group defaulted late final year.

Developers’ persistent financial troubles alongside with Covid limitations have delayed development tasks, pushing homebuyers to put their have economical credit rating at threat by suspending their mortgage loan payments.

The variety of assets assignments associated much more than tripled in a couple days to additional than 100 as of July 13, in accordance to Jefferies.

That’s a little 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the whole house loan harmony in China, the analysts stated.

Throughout banking companies protected by Goldman Sachs, ordinary publicity to assets together with mortgages was just 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, the firm’s fiscal products and services analysts wrote in a report very last 7 days.

“We look at this mortgage threat to be a lot more about households’ willingness, fairly than capability, to make home finance loan payments,” the report reported, “as builders have dragged out the development of properties given the problems of refinancing.”

But if additional homebuyers refuse to fork out their home loans, the bad sentiment would minimize demand — and theoretically price ranges — in a vicious cycle.

That is prompted phone calls to boost self esteem.

“In the 2nd 50 percent of 2022, there is no hope for a swift rebound in the serious estate sector, and it will proceed to drag financial advancement,” reported Gary Ng, senior economist, Natixis CIB Asia Pacific. “The antidote is to raise the self confidence of homebuyers and developers when again, but it has established to be a difficult activity.”

Study extra about China from CNBC Pro

Halting home finance loan payments is an intense measure that shouldn’t grow to be a prevalent observe, specially since there are authorized procedures to address delays in completing flats, said Qin Gang, deputy director of China authentic estate exploration institute ICR.

He cited discussions with sector executives in indicating experiences of stopped payments are pretty unfavorable for preserving the real estate sector’s restoration.

Normally, if developers are unsuccessful to supply flats inside of the agreed period, homebuyers can utilize to terminate their obtain contracts, Goldman Sachs serious estate analysts said in a report very last 7 days.

The analysts mentioned acceptance generally usually takes a few months and the developer will have to have to return the down payment and finished mortgage loan payments to the homebuyer, like fascination. The remaining mortgage payment should go to banks, the report claimed.

A 6-yr very low in home buy programs

Need for new houses has presently fallen.

A People’s Financial institution of China quarterly survey identified in June that only 16.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of people system to acquire a residence in the future a few months, the most affordable due to the fact 16.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 3rd quarter of 2016.

Earlier this year, the central bank took a substantial move toward boosting the serious estate market place by decreasing the home loan charge. Quite a few metropolitan areas have peaceful procedures in the final numerous months to aid residence purchases.

But since April, actual estate gross sales have fallen 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or a lot more from very last year’s ranges, in accordance to Wind Information and facts knowledge.

The ordinary selling price throughout 100 Chinese cities has scarcely risen around the previous 12 months, though price ranges in massive metropolitan areas like Beijing and Shanghai have surged by double-digits, reflecting divergence in demand, according to Wind Facts.

Phone calls to full and deliver flats

Any plan that can assure the shipping and delivery of households would be valuable, mentioned Bruce Pang, chief economist and head of exploration, Bigger China, JLL. He claimed banking companies have confined exposure to uncompleted construction projects and have the means to restore market self esteem.

Dai Xianglong, previous head of the People’s Financial institution of China, mentioned Saturday that China would not knowledge anything like the 2007 U.S. “subprime home finance loan disaster,” and suggested actions to improve self esteem in the true estate marketplace and stabilize housing costs. That is according to a state media report.

But even condition-backed Securities Situations very last week elevated the specter of systemic money chance in an report that inspired nearby governments and developers to provide houses on time.

“Credit history losses relating to home loan loans are minimum and the influenced balances are modest at most Chinese countrywide banking companies at the moment,” Harry Hu, senior director at S&P Worldwide Ratings, claimed in a statement.

“But draw back stress could make if the latest suspension in mortgage repayments by some resident teams in China is not managed nicely and manifest into program dangers,” Hu mentioned.

The formal newspaper for China’s banking and insurance coverage regulator on Sunday revealed comparable admonitions and pushed to support shipping and delivery of apartments and funding for the serious estate business.

Without having the assets sector’s drag, China’s GDP could have developed by 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 2nd quarter compared to the .4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} development claimed Friday, according to Goldman Sachs’ evaluation.

Why the Spring Housing Market Will Be ‘Miserable’ for Homebuyers

Why the Spring Housing Market Will Be ‘Miserable’ for Homebuyers

Homebuyers experienced better be completely ready to match up for battle.

Any buyers—or wannabe buyers—who thought final year’s meteoric jump in residence prices was tough need to be ready for this spring to be even worse. A hellish trifecta of quick-rising housing prices, raising home finance loan prices, and record-very low stock of houses for sale is very likely to present a brutal spring real estate sector for people searching to invest in a new dwelling.

“For the prospective buyers, it is heading to be depressing,” predicts Mark Zandi, chief economist at Moody’s Analytics. “We’re likely to see a great deal much less home revenue this spring. … In several communities, they [just] never have a thing to offer.”

The nation has been mired in a housing scarcity for decades, but it’s now grappling with the fewest households for sale at any time. The absence of inventory is taking place at the worst probable time as a lot more People in america are hitting their primary residence-purchasing years—and not discovering everything on the industry. The COVID-19 pandemic has only accelerated the dilemma as customers sought out more roomy households.

“It’s heading to be a rough marketplace for consumers,” claims Gay Cororaton, a senior economist at the National Affiliation of Realtors®. “There are much more bidders than homes out there.”

Consumers really should expect to spend more for housing as selling prices go on accelerating by double digits. Last 12 months, all-time-minimal house loan premiums served to offset the increased prices. But prospective buyers will not locate that reduction this spring now that costs are at the brink of cracking 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}—adding probably hundreds of dollars every single thirty day period to a borrower’s house loan payment.

That doesn’t imply it will be difficult to correctly acquire a home—it just will not be easy.

The competition from other purchasers could slim out a little bit as far more individuals are priced out of homeownership. If there is a lot less demand, it could suggest much less (or at least significantly less heated) bidding wars that do not outcome in head-boggling gives around the asking cost.

“We’re going to see a little bit far more stock and rather less dwelling customers,” suggests Real estate agent.com® Main Economist Danielle Hale. She anticipates far more residences will go up for sale as the temperature warms up. “But that could possibly not be until finally the afterwards portion of the spring.”

Will property prices slow down or proceed increasing this spring?

It would make perception that, as home loan costs increase, property charges would fall or at minimum stabilize. Logic would propose that there has to be some limit on how considerably potential buyers can manage to commit on housing. Right? Even so, in the shorter time period, rather of rates chilling out, they’ve been capturing up at a faster clip as house consumers rushed into the sector hoping to lock in a house at a minimal property finance loan level prior to charges rise even even further.

As a consequence, previously large price ranges leaped 12.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a yr earlier in the week ending Feb. 19, in accordance to the most recent Realtor.com data.

“What’s unclear: Is this the past gasp?” claims Len Kiefer, deputy main economist at Freddie Mac. Price tag development was cooling, but then costs commenced climbing. “Six months down the line … the market may well soften a minimal bit.”

That doesn’t signify selling prices will drop. It would have to have a tsunami of recently built residences heading up for sale for rates to end their seemingly inexorable increase. And that doesn’t seem possible as builders have struggled to ramp up building and the desire for housing just keeps escalating.

Kiefer expects it will just take involving 4 and five yrs for it to ramp up ample to meet up with demand. Builders are however contending with a major scarcity of personnel, offer chain difficulties creating it harder—and more expensive—to protected setting up products and appliances, and inflation even further boosting costs.

Usually, much more homes start off to trickle onto the marketplace soon after the vacations. But extremely minor of the earlier two years has been “normal.” In 2021, additional properties did not come onto the industry until finally April, suggests Hale.

“We will sooner or later see an increase in listings, but it may be a little bit later this yr,” suggests Hale. The selection of properties for sale was down 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January in comparison with the exact same time previous 12 months, in accordance to Real estate agent.com facts.

Mortgage loan prices are poised to hold heading up

Dwelling prices are likely to hog the highlight as buyers and sellers are normally more worried with the sticker cost than the mortgage loan desire price. But not concentrating on the home loan desire rate arrives with some peril, as even a portion of a share position can translate into some very large bucks above the life of the personal loan.

Purchasers who ended up pre-authorized for home loans might come across that they now qualify for much less. Other folks will be priced out of the market place or pressured to decide on more compact households, fixer-uppers, or attributes in considerably less desirable spots.

For illustration, surging premiums will tack on somewhere around $220 a thirty day period, or $2,640 a calendar year, onto buyers’ regular monthly payments as costs leaped from a minimal of all around 2.67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in December 2020 to about 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in February. Some specialists predict they’ll proceed inching up. Though that may perhaps not sound drastic, it can include nearly $80,000 about the lifetime of a 30-year preset-level bank loan. Those people with greater home loans will pay out noticeably much more.

(This assumes potential buyers ordered a $375,000 residence, the nationwide median property record price, with 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down.)

Home loan curiosity fees shot up to 3.92{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for 30-calendar year mounted-fee loans in the week ending Feb. 17, in accordance to the most current Freddie Mac data. Which is a little greater than it was in the runup to the start off of the pandemic in March 2020.

“People who are just at the margins of becoming ready to afford to pay for a house will assume two times about buying,” says NAR’s Cororaton. “The higher-profits brackets will be the types leaping into the marketplace. It just would make it all the more difficult for the decreased-profits folks.”

The larger prices are most likely to make the inventory crunch even even worse. Homeowners who locked in ultralow charges may perhaps be reluctant to market their houses and purchase new types if their regular housing payments will be bigger thanks to those people soaring charges.

“If they have an fascination amount below 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} … that can be a major increase in their payment—even if they are downsizing,” says Kiefer. “When inventory is so restricted, each individual possible household vendor has an outsize effects on the marketplace.”

Inspite of the will increase, costs are nevertheless historically minimal. Three several years in the past, premiums have been in the mid-4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} assortment. 20 a long time ago, they ended up hovering in the superior 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and minimal 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} arena. Forty a long time in the past, they had been in the mid-17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} array.

The one particular dazzling place for prospective buyers will be if sellers commence to slash costs as mortgage loan rates slash into the budgets of buyers. This could take place in some of the best housing marketplaces that observed the greatest selling price raises. But the jury’s nonetheless out on if and when this sort of correction may materialize.

“Mortgage premiums will be both equally good friend and foe to consumers this calendar year,” claims Hale of Real estate agent.com. “Monthly property finance loan payments will be larger. On the other hand, individuals bigger regular monthly home finance loan payments are possible to knock some homebuyers out of the market place. You may perhaps see to some degree significantly less levels of competition.”

Greater home loan rates is not superior news for house sellers

Though it’s a wonderful time to list a household, mounting house loan fees are predicted to curtail what could have been an even larger payday for residence sellers.

Dwelling sellers expecting “10 prospective buyers lined up at the door” might be let down as much less individuals can afford to pay for the “stratospheric” dwelling rates, states Moody’s Zandi. That usually means there may not be as several feverish bidding wars and potential buyers may not have the funds to go rather so higher about the inquiring rate.

Sellers will “get a fantastic rate, no question about it,” says Zandi. “They’re just not heading to get the fortunes they assumed they were being heading to get, mainly because the buyers just can’t afford it.”

Most sellers are also homebuyers, hunting to go, get more substantial abodes, or downsize. So though they may well make a tidy sum offering their residences, they nevertheless have to have to discover a household and compete in the bidding wars about it just like every single other customer.

“It’s a grind and it is heading to remain a grind,” Keifer suggests of this year’s true estate market. “The reduction will come, but it will be gradual.”

Fannie Mae’s economist, and real estate pros, give advice to aspiring homebuyers

Fannie Mae’s economist, and real estate pros, give advice to aspiring homebuyers


Getty Illustrations or photos

The housing marketplace isn’t an uncomplicated matter to pin down — and you’re not alone if you are feeling like you’re acquiring blended messages on the issue. On the a person hand, property finance loan costs are in the vicinity of historic lows — some 15-year premiums are in the vicinity of 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and some 30-12 months charges are below 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, as you can see here — and quite a few industry experts predict they will increase in the coming calendar year. But on the other, housing price ranges are on the increase, and in a lot of areas have turn into unaffordable for quite a few regional families. Those things are creating some possible homebuyers ponder: Ought to I purchase now?  So we asked Doug Duncan, Fannie Mae’s senior vice president and main economist, and some other authentic estate execs, their ideas on what is heading on with the housing market place and irrespective of whether now is the time to buy.


Property finance loan rates stay minimal, but industry experts forecast they will rise

A latest study of housing gurus revealed by Zillow exposed that execs expect curiosity premiums to increase to 3.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} at the conclude of 2022, and for its section, Fannie Mae predicts that desire prices will average approximately 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022, up a bit from this calendar year. Authorities we spoke to claimed the identical: Kate Wooden, property and house loan skilled at NerdWallet, states we may perhaps see a “long-long lasting upward trend” in home finance loan costs, and Greg McBride, chief money analyst at Bankrate, notes that appear 2022, the basic development will be toward larger costs.

It is nevertheless an particularly aggressive sector, but “things aren’t as frenetic as before in the year”

Residence selling prices have risen approximately 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the earlier 12 months — and most experts consider they will continue to increase, albiet at a slower pace — but demand from customers for properties is however large: “While economic uncertainty could likely dampen home loan desire over the for a longer time expression, we believe latest market place problems continue being conducive to house acquire exercise, as demand from customers for houses carries on to far outstrip the source accessible for sale,” Fannie Mae’s Duncan claims. 

There are symptoms that the marketplace is moderating, if only a little little bit. “There’s been a little bit extra inventory of houses accessible for sale to arrive on the sector and items are not as frenetic as earlier in the year, but this is nonetheless a extremely incredibly hot housing marketplace the place demand far exceeds provide in most markets,” claims McBride. 

End striving to time the marketplace wanting for the excellent time to get, instead concentration on your particular conditions

Fannie Mae’s deputy main economist Mark Palim suggests timing house loan costs and the housing market place is really hard, and in its place suggests potential buyers appear at their have would like and requires. “They need to concentrate on private existence situation and how lengthy they consider they’ll be in the location,” suggests Palim. If you have locational security and prepare to be in the property for 5 many years or additional, Palim suggests getting in its place of renting very likely would make the most feeling. But comprehend what you can genuinely manage, and do not get caught up in the genuine estate frenzy: “Making the largest economical determination of your everyday living under duress is not a recipe for success,” says McBride.

Also see: The very best month to invest in a home

Climate change and real estate: The new calculus for homebuyers

Climate change and real estate: The new calculus for homebuyers

This tale is portion of The Cost of Local weather Adjust, CNET’s protection of how the shifting local weather impacts a assortment of money concerns.

There is certainly a new wild card in the housing market place that is providing some future prospective buyers pause: the expenses of local weather change. 

When Aditi Shekar flew from New York City to San Francisco four a long time in the past to launch Zeta, a economic tech business servicing people, she was drawn to the robust fintech group and obtain to traders and engineers. (Disclosure: I am an trader in Zeta.)

Now, with her corporation entirely remote and her husband’s operate also completely online, they’re accelerating ideas to go. This time, acquiring a “tech-pleasant” community is not the priority. 

“Local weather is our best standards,” says Shekar, who has now lived through quite a few cycles of droughts and wildfires in Northern California. “We want our dwelling to be some thing we hand over to our kids.” They have their eyes set on Bozeman, Montana, an more and more well known desired destination for Millennial professionals trying to get a laidback-but-connected life style. Though Montana is not immune to weather modify, the few thinks living there will be more sustainable. “We see longevity there,” claims Shekar, who spoke at size about her go on the So Dollars podcast.

In Cedar City, Utah, 29-calendar year-aged Elise Grant shares very similar sentiments about the relationship concerning local climate and homebuying. As a married mother of 3 young small children, she and her husband decided not to get a property in her childhood town of St. George, Utah thanks to the increasing threat of drought. Instead, they bought a dwelling one particular hour absent, bigger up in the mountains. “The inhabitants of St. George is exploding — and there is no program to preserve h2o,” she claims. “We can not see a extensive-term very affordable long run there.”

Across the state in Kalamazoo, Michigan, “Maya,” who most popular to keep her id anonymous, turned down a desire job educating at a university in California because of to concerns about a host of climate risks. “I was worried about drought, mudslides and fires,” claims the 47-yr-aged. “Not just the threat — but also the disruption to every day lifestyle and the added environmental worry.” Inspite of close spouse and children customers dwelling in the vicinity of the coast, she eventually failed to make the shift.

These homes may possibly be ahead of the curve, as the housing market place — even in spots specifically susceptible to local weather alter — proceeds its sizzling streak. As of September, 86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of US homes set on sale were purchased in less than 30 days. “So considerably the market won’t look to be impacted [by climate change] in the combination.” suggests Lawrence Yun, main economist with the Countrywide Affiliation of Realtors. “Possibly consumers are short-sighted or they believe that in the course of the time they will be dwelling in the household, they will not be impacted.”

But shopping for a house is typically the most considerable money transaction several of us will make — and it really is widely noticed as a stage towards very long-time period wealth-creating. As a prospective buyer, it truly is worth taking into consideration the ways local weather adjust may possibly threaten your acquire. Here are some market place insights that may perhaps enable you make a additional educated final decision.

Sustainability: A new selling point

“Place, place, spot.” This authentic estate cliche about buyer priorities has the ring of truth of the matter. But specialists imagine that above time, “sustainability” — a similar but distinct trait — could turn into the most sought-following aspect. With out it, a home’s selling price could go through. “As insurance policies fees increase, a household in the outer banks of North Carolina may come to be unsellable — and the household price tag could go way down,” says Eddie Seiler, government director at the Investigation Institute for Housing The united states.

If you’re wanting to get in present day marketplace, this should really give you pause. “There are much more consumers who are a lot more intrigued in the environmental capabilities of a residence and whether or not it is subject to weather adjust threat,” says Yun. Distance from soaring sea ranges could ever more be witnessed as a gain — as will upgrades like photo voltaic paneling and storm-proof windows. “With just about every passing yr, buyers will be a lot more conscious [of such things],” he says.

Coverage: The sudden deal-breaker 

Before this calendar year, a good friend of mine backed out of acquiring a home in Miami immediately after insurance coverage organizations refused to protect the residence, which was in a substantial-risk flood zone. Prospective insurers demanded pricey updates — and even continue to, the policy would have price tens of thousands for every calendar year. This is just one instance of how insurance policy issues are throwing an surprising wrench in buyers’ plans. “Residence insurance prices have risen and that has led to a minimize back on some demand from customers,” says Yun of the NAR. 

Strategies for possible buyers: In advance of generating an supply, connect with a couple of insurance organizations for a rapid analysis. Though proximity to hearth hydrants is a bonus, exterior construction is vital. If you live in a hotter local weather, a brick home — as opposed to one particular made of wood or other additional flammable elements — will normally yield a decreased quality. If you prepare to live in a flood-susceptible space, you can order flood insurance policies even if FEMA has not technically declared it an formal flood zone. 

Home loans: Higher premiums for some?

And the creditors are using cues from the insurance companies. If an insurance coverage organization will not supply a policy above local climate issues, mortgage loan companies might follow match. 

In accordance to Seiler, who is also AVP of the Property finance loan Bankers Affiliation, the industry is not however pricing the foreseeable future effects of climate modify — generally because underwriters aren’t positive how (or if) it components into the likelihood of a default. Could an excessive temperature function depart the borrower out of do the job? What if the house is wrecked by a storm? In principle, with the correct insurance policy, repairs are coated. But what if an insurance company drops a policyholder, as is now going on in some parts of the nation? “We you should not have a apparent picture, as an industry, what climate adjust will do to the chance of default,” states Seiler. “All I can say is underwriters have a dearth of data and it is a perform in progress.”

As a potential buyer, your chance tolerance will enjoy a position in this calculation. If you take a mortgage on a coastal residence close to mounting seas, acknowledge that your loan provider may possibly not have taken long term serious climate gatherings into account — yet. But they may do it sooner rather than later on.

Real estate brokers: Disclosures run the gamut

That house you might be eyeing: Has it at any time flooded? What climate-relevant destruction has the location skilled in current yrs? As a future customer anxious about local weather danger, these are great inquiries. But sellers might be reluctant to share that kind of data — and your agent may not be organized to check with for it. In actuality, dependent on the point out, your real estate agent may possibly not be required to share significantly, as disclosure rules range throughout the country.

By and huge, the broker field is still ramping up on how to tutorial prospective buyers by the implications of weather on a property. “We’re concentrated on closing promotions and earning cash. [Realtors] really don’t look ahead or backward. They search right there and then. So when purchasers are expressing concerns about what a shifting clime implies for their house — it has the probable to toss an agent off guard,” states Craig Foley, a realtor and main sustainability officer at LAER Realty Partners in Melrose, Massachusetts.

At the countrywide level, loan companies are needed to disclose if a household is located in a flood zone. “Brokers and brokers are conscious of this, but this just isn’t aspect of a formal disclosure approach. Disclosure legislation change drastically,” states Foley.

Clever homebuyers will do their homework: Evaluation flood maps, discuss to locals, lookup information stories related to weather and contact a regional coverage agent to discover about climate-associated claims. You can also get a free of charge local climate danger evaluation at ClimateCheck.com. When I typed in our New Jersey address, I learned storms are an “severe” climate threat listed here — which is backed up by my firsthand encounter. 

Local weather modify is only now commencing to critically influence the serious estate current market, but it can be likely to grow to be an significantly key issue. Finally, repeated bouts of extreme temperature will have an effect on all the things from property finance loan curiosity charges to insurance coverage premiums. And because realtors are lagging at the rear of on informing buyers about local climate challenges, you want to be your very own largest advocate. Press for responses and figure out your threat tolerance.