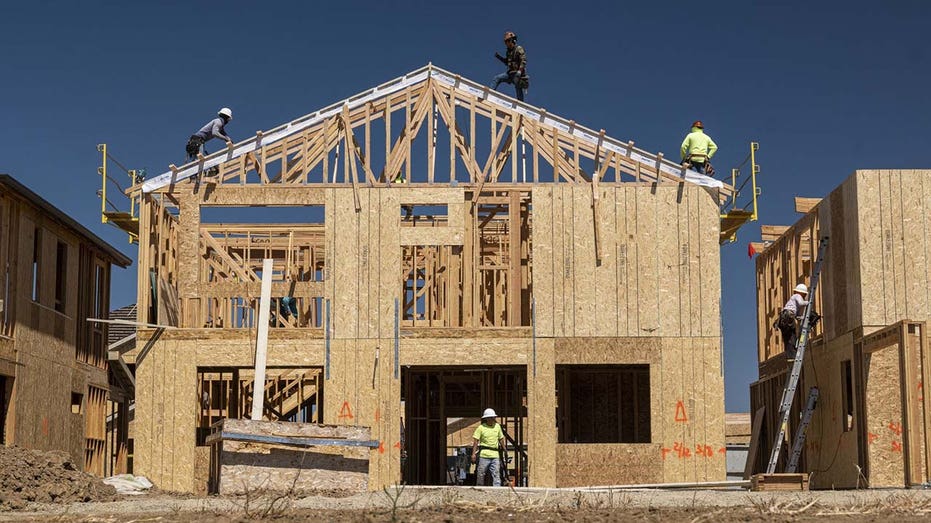
Benjamin C. Tankersley/For The Washington Post via Getty Images
After a record-breaking run that saw mortgage rates plunge to all-time lows and home prices soar to new highs, the U.S. housing market is finally slowing. Home sales had declined for 11 consecutive months as of December 2022, and home values seem to have peaked.
While demand and price gains are cooling, any correction is likely to be a modest one, housing economists and analysts say. No one expects price drops on the scale of the declines experienced during the Great Recession.
Rob Dietz, chief economist at the National Association of Home Builders, sums up the consensus among housing experts: “We’re thinking this is going to be a moderate downturn,” he says.
The real estate party raged on longer than anyone expected. The National Association of Realtors reported that median prices in the spring of 2022 topped $400,000 for the first time ever. Even after a recent retreat, prices are up a robust 32 percent since the coronavirus pandemic began in March 2020, according to NAR data.
Now, bidding wars have largely faded, inventories are loosening and the feeling of frothiness is gone. “The market is clearly turning,” says NAR chief economist Lawrence Yun.
Is the housing market going to crash?
The last time the U.S. housing market looked so frothy was back in 2005 to 2007. Then home values crashed, with disastrous consequences. When the real estate bubble burst, the global economy plunged into the deepest downturn since the Great Depression.
Now that the housing boom is threatened by soaring mortgage rates and a potential recession, buyers and homeowners are asking a familiar question: Is the housing market so hot that it’s about to crash?
Housing economists agree that prices could fall, but the decline won’t be as severe as the one homeowners experienced during the Great Recession. One obvious difference between now and then is that homeowners’ personal balance sheets are much stronger today than they were 15 years ago. The typical homeowner with a mortgage has stellar credit, a ton of equity and a fixed-rate mortgage locked in at a rate well below 5 percent. So no foreclosure crisis looms.
“The wild ride known as the U.S. housing market slowed dramatically in the fall of 2022, as mortgage rates surged and home prices remained high,” says Molly Boesel, principal economist at CoreLogic. “Home sales started strong in early 2022 but took a nosedive later in the year. On the plus side, generous amounts of home equity will protect many borrowers from experiencing the type of foreclosure activity seen during the Great Recession.”
What’s more, builders remember the Great Recession all too well, and they’ve been cautious about their pace of construction. The result is an ongoing shortage of homes for sale.
“We simply don’t have enough inventory,” Yun says. “Will some markets see a price decline? Yes,” he says. “[But] with the supply not being there, the repeat of a 30 percent price decline is highly, highly unlikely.”
Lightbulb
Key housing market statistics
A total of 30,822 U.S. homes had foreclosure filings — default notices, scheduled auctions or bank repossessions — as of December 2022, according to ATTOM Data Solutions.
South Carolina had the highest foreclosure rate of any state in December, at one foreclosure filing for every 2,301 housing units, according to ATTOM. It was followed by New Jersey, where one in every 2,378 homes were in some stage of foreclosure.
Lenders repossessed 3,663 U.S. properties through completed foreclosures — known as “real estate owned,” or REO — in December 2022. Altogether, 42,854 properties were repossessed in 2022, according to ATTOM.
Home sales fell 34 percent from December 2021 to December 2022, the National Association of Realtors says. The median sale price in December 2022 was $366,900.
Existing home sales for 2022 totaled just over 5 million, per NAR — down 17.8 percent from 2021.
Existing home prices
For many months, economists have been predicting that the housing market would eventually cool as home values become a victim of their own success. Home prices have risen far more quickly than incomes, creating an affordability squeeze, and mortgage rates doubled since August 2021, before starting to retreat a bit.
Experts say home prices could fall
“Most markets are going to experience price declines in the high single digits,” Dietz predicts. Home price declines of 8 to 9 percent would create some economic pain, to be sure. But this correction will be nothing like the utter collapse of property prices during the Great Recession, when some housing markets experienced a 50 percent cratering of values.
Rick Sharga, executive VP of market intelligence at ATTOM Data Solutions, expects declines of 5 percent. “It’s almost inevitable we’re going to see home prices drop,” he says.
Yun says high-priced regions such as California are most vulnerable to a downturn in prices. The Midwest, on the other hand, is unlikely to see a decline in home prices. Overall, he expects national prices to remain flat next year.
5 reasons the housing market is not about to crash
Housing economists point to five compelling reasons that no crash is imminent.
Inventories are still very low: The National Association of Realtors says there was a 2.9-month supply of homes for sale in December. In February, that figure was as low as a tiny 2.0-month supply. This ongoing lack of inventory explains why many buyers still have little choice but to bid up prices. And it also indicates that the supply-and-demand equation simply won’t allow a price crash in the near future.
Builders didn’t build quickly enough to meet demand: Homebuilders pulled way back after the last crash, and they never fully ramped up to pre-2007 levels. Now, there’s no way for them to buy land and win regulatory approvals quickly enough to quench demand. While they are building as much as they can, a repeat of the overbuilding of 15 years ago looks unlikely. “The fundamental reason for the run-up in price is heightened demand and a lack of supply,” says Greg McBride, CFA, Bankrate’s chief financial analyst. “As builders bring more available homes to market, more homeowners decide to sell and prospective buyers get priced out of the market, supply and demand can come back into balance. It won’t happen overnight.”
Demographic trends are creating new buyers: There’s strong demand for homes on many fronts. Many Americans who already owned homes decided during the pandemic that they needed bigger places, especially with the rise of working from home. Millennials are a huge group and in their prime buying years. And Hispanics are a young, growing demographic keen on homeownership.
Lending standards remain strict: In 2007, “liar loans,” in which borrowers didn’t need to document their income, were common. Lenders offered mortgages to just about anyone, regardless of credit history or down payment size. Today, lenders impose tough standards on borrowers — and those who are getting a mortgage overwhelmingly have excellent credit. The typical credit score for mortgage borrowers in the the third quarter of 2022 was a high 768, the Federal Reserve Bank of New York says. “If lending standards loosen and we go back to the wild, wild west days of 2004-2006, then that is a whole different animal,” says McBride. “If we start to see prices being bid up by the artificial buying power of loose lending standards, that’s when we worry about a crash.”
Foreclosure activity is muted: In the years after the housing crash, millions of foreclosures flooded the housing market, depressing prices. That’s not the case now. Most homeowners have a comfortable equity cushion in their homes. Lenders weren’t filing default notices during the height of the pandemic, pushing foreclosures to record lows in 2020.
All of that adds up to a consensus: Yes, home prices are still pushing the bounds of affordability. But no, this boom shouldn’t end in bust.
FAQs
When will the housing market crash?
Caret Down
Actually, economists do not think it will. Housing economists point to five main reasons that the market will not crash anytime soon: low inventory, lack of new-construction housing, large amounts of new buyers, strict lending standards and a drop in foreclosures.
When will housing prices drop?
Caret Down
Home prices rose sharply for years. And while the heated market has cooled down, it’s not likely to experience an equally sharp drop soon. Greg McBride, CFA, Bankrate’s chief financial analyst, says a plateauing of prices is more likely than a steep fall. Matthew Pointon, senior property economist at Capital Economics, also expects a slowdown rather than a freefall, predicting a 5 percent drop by mid-2023.
How much house can I afford?
Caret Down
It depends on how much money you earn versus how much you pay out in debts and expenses each month. Many financial advisors recommend the 28/36 percent rule of home affordability, which states that you should spend no more than 28 percent of your gross monthly income on housing expenses, and no more than 36 percent on total debt. Bankrate’s home affordability calculator can help you crunch the numbers.
What is a good credit score to buy a house?
Caret Down
Different minimum credit scores are required by lenders for different types of mortgages. However, a score of at least 620 is typically required for a conventional loan — and if it’s as high as 740, all the better. Successful borrowers today tend to have outstanding credit, with a median score of 768.
New home and multifamily construction projects slated for delivery in 2024 and 2025 are expected to … [+] be delayed.
getty
The housing market is sending clearer signals that historically low mortgage rates and the home-buying frenzy have come to an end. As we near the end of 2022, here’s a look at the expectations of real estate experts for 2023.
Danielle Hale, Realtor.com chief economist: After several years of an unambiguous sellers’ market, the 2023 housing market could feel more like a nobody’s market. We expect to see some buyer advantages in the form of 22.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more homes for sale, however, the increase will result largely from homes taking longer to sell amid challenging affordability conditions. For-sale homes will remain high-priced with the national annual median price for 2023 expected to advance another 5.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}—less than half the pace observed in 2022. Still high prices mean that homeowners are likely to walk away from a home sale with significant equity if they decide to venture into the market and can find a buyer. On the whole, however, we expect home sales to be dramatically lower, down 14.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to 2022 as both buyers and sellers pull back from a housing market and economy in transition. We expect the annual tally for 2023 to be roughly in line with the recent pace of home sales in late 2022.
For many potential first-time home buyers, 2023 will herald a delayed dream rather than a celebration as home costs exceed what’s possible on their budget and income. As fewer households make the jump to homeownership, increased rental demand could help keep rents moving higher. Nationwide, the median rental is projected to increase 6.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in price, even as an influx of new multifamily housing helps to better meet rental demand. Renters looking to save in the year ahead may consider moving further out to the suburbs.
A still strong jobs market will keep incomes growing at a faster than historically average pace (3.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), but they will not exceed expected inflation (4.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) which means that many households will continue to make tough budget tradeoffs. After years of high-flying tech cities dominating real estate who’s-who lists, this year’s top performers are expected to be modest, mid-sized domestic industry hubs in the Northeast, South, and Midwest. The slow and steady real estate markets in these areas where homes continue to be affordable will be the stars in 2023, better weathering the affordability challenges that loom ahead.
Affordable rental housing is essential to improving overall affordability and household stability in … [+] the housing market.
getty
Bob Pinnegar, president and chief executive officer of the National Apartment Association: Pursuing sustainable and responsible solutions to address our nation’s housing affordability crisis will remain a steadfast priority in the new year. Our nation’s affordability challenges stem from an alarming supply/demand imbalance, and to properly address this we must build 4.3 million new apartments by 2035.
On the economic side, supply chain issues have begun to ease and will hopefully continue to in the year ahead. While jobs are steady, the labor market faces challenges in areas like construction, where workers are needed. Inflation is starting to show signs of easing, but any of those impacts are unlikely to be seen until the end of 2023.
State and local lawmakers continue to consider damaging policies like rent control, which more than 40 years of academic research and real-life case studies consistently reiterate is ineffective in addressing affordability. Rent control distorts the housing market by acting as a deterrent and disincentive for rental housing development and expedites the deterioration of existing housing stock. As these policies continue to be discussed, the rental housing industry will continue to advocate for responsible solutions – like revitalizing Section 8 and removing barriers to apartment development – that will improve affordability challenges long-term.
Nick Bailey, president and CEO of RE/MAX, LLC: One thing I can say for certain about the housing market in 2023 is that no matter the macro-economic conditions, Americans will continue to buy and sell millions of homes. Generally speaking, when we’re talking about the overall health of the housing market, most people are approaching that conversation from the lens of an investor. Will the market bottom out or have we hit the top? That’s an important conversation, but the truth is, people are getting married, divorced, moving to care for aging family members, relocating for career opportunities and so on, every single day. And for those people, it’s less about the interest rate or mortgage rates that week and more about their present situation and whether they can afford a house that fits their needs.
I’m optimistic that 2023’s spring selling season will be a bright spot as levels of inflation get more under control. There will still be extreme demand as new construction just can’t get out of the ground fast enough, and the Millennial home buyers, who make up a huge demographic, are primed to make their move. According to a recent survey conducted by RE/MAX in partnership with SWNS Media Group, 84{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Gen Z, 79{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Millennials and 61{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of survey respondents 77 or older plan to buy a house or condo in the next few years. In my opinion, 2023 will be a better year for housing than many people think, especially because we’ll no longer have year-over-year comparisons to 2021 – an historic outlier that made 2022 seem less than what it really was.
Jacob Channel,senior economist for LendingTree: The housing market will remain tough for many would-be buyers. While mortgage rates might stabilize, prices could decline, and buyers may be able to negotiate with sellers more in 2023 than they were able to over the height of the pandemic, that doesn’t mean that buying a home is suddenly going to become a walk in the park. On the contrary, affordability challenges will likely persist for many, owing to rates remaining steep and supply remaining limited.
Borrowers shouldn’t expect rates to fall to anywhere near their record 2021 lows, or even to as low as they were at the start of 2022. Home prices won’t necessarily fall everywhere, but a combination of relatively high rates and weak home buyer demand will probably push prices down nationwide this year. Although a 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop may seem steep, it’s important to keep in mind that because home values rose so much over the height of the pandemic, declines this year are unlikely to totally wipe out the gains that many homeowners saw over the past few years.
Atlanta is expected to be a top real estate market to watch in 2023 and beyond.
getty
Lawrence Yun, chief economist for the National Association of Realtors and senior vice president of research: 4.78 million existing homes will be sold, prices will remain stable and Atlanta will be the top real estate market to watch in 2023 and beyond. Home sales will decline by 6.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to 2022 (5.13 million) and the median home price will reach $385,800 – an increase of just 0.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from this year ($384,500).
Half of the country may experience small price gains, while the other half may see slight price declines. However, markets in California may be the exception, with San Francisco, for example, likely to register price drops of 10–15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Rent prices will rise 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, following a 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase in 2022. Foreclosure rates will remain at historically low levels in 2023, comprising less than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all mortgages. The gross domestic product will grow by 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, roughly half the typical historical pace of 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. After eclipsing 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in late 2022, the 30-year fixed mortgage rate will settle at 5.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as the Fed slows the pace of rate hikes to control inflation. That is lower than the pre-pandemic historical rate of 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Consumer spending will remain supported by a tight labor market.
getty
Taylor Marr, Redfin deputy chief economist: Slowing inflation and the hope of the Fed easing rate hikes in the new year are likely to bring mortgage rates down further and thereby improve homebuying demand. But don’t call it a comeback or even a recovery yet; demand is still way down from its peak. We’re keeping a close eye on the labor market for confirmation that inflation will continue slowing. A strong job market like the one we have now contributes to inflation because it pushes up wages and leads to higher prices. Though it seems counterintuitive, a slight uptick in unemployment and/or slower economic growth would likely help bring mortgage rates down further. If that happens, the increase we’re seeing in early-stage demand could translate to an uptick in pending sales in early 2023.
Selma Hepp, interim lead of the Office of The Chief Economist at CoreLogic: Following the recent mortgage rate surge above 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, real estate activity and consumer sentiment regarding the housing market took a nosedive. Home price growth continued to approach single digits in October, and it will move in that direction for the rest of the year and into 2023. However, while some housing markets have seen significant recalibration since the spring price peak and are likely to post losses in 2023, further deteriorating for-sale inventory, some relief in mortgage rate increases and relatively positive economic news may help eventually stabilize home prices.
Jeff Tucker, Zillow senior economist: The rental market is cooling, but to this point it hasn’t brought any real relief for renters. However, there are signs affordability may improve in the coming months. Annual rent growth has fallen from a record 17.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual growth in February to 8.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year growth in November.
Renters looking to sign a new lease in 2023 should feel encouraged about this data, but still need to keep a close eye on the market and act quickly when they find a rental that fits their needs and budget. Rents are still higher than they were pre-pandemic, so tradeoffs and flexibility will still be necessary into next year. Renters facing a renewal should know that they’ve got more bargaining power this year and should carefully consider the prices of other nearby rental options when negotiating a lease renewal.
Many real estate brokerages are expected to consolidate.
getty
Kuba Jewgieniew, CEO and founder of Realty ONE Group: Homeowners will stay in homes due to locked-in lower interest rates. Regarding Realtors, 300,000 to 400,000 new licensees entered the real estate market over the past couple of years (similar to the relative percentage growth of NAR members between 2005-07).
Many top-producing professionals and teams that have been closing $100 million per year in transaction sales, chose this career path during real estate’s hot markets (2012-2020). So, they haven’t experienced a severe downward cycle like this since 2008. There are more than 90,000 real estate brokerages in America. Of these, many will consolidate, and others will get wiped out. Their Plan B funding source for access to capital, just to stay afloat, are friends and family.
The average interest rate on a credit card is now at a high of over 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and expected to be in the 20’s soon. Home equity lines of credit are increasingly popular during high inflationary times.
Lisa Sturtevant, chief economist for Bright MLS: Over the past year, the housing market underwent an about-face as rapidly rising mortgage rates dramatically slowed home sales activity. In 2023, the housing market is expected to continue its correction and the housing market will start to look more normal, though we may need to reconsider what normal means. Mortgage rates will decline slowly in 2023, though will remain above 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for most of the year. While not high by historic standards, 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} mortgage rates along with fast-rising prices will also keep some prospective buyers out of the market. Bright MLS’ forecast suggests that there will only be 4.87 million home sales in 2023, down 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to 2022, and the lowest level of sales activity in nine years.
The median home price is expected to be relatively flat in 2023, rising just 0.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year. But the national figure does not tell the whole story. Local markets that are more affordable and where the local economy is strong will see stronger price growth in the year ahead. In contrast, higher-cost metros, where housing affordability is a challenge, are at greater risk of price drops. In addition, pandemic boom towns where demand surged will also see greater price corrections in 2023. The frenzied pace of home sales activity during the pandemic was not typical or sustainable, nor is it good for a healthy, stable housing market. A return to a slower market with more modest price growth is a good place to be headed in 2023.
L.D. Salmanson, CEO of Cherre, a data integration and insights platform: Looking at the current market, we are seeing fewer transactions and increasing days on market. Low absorption rates indicate a price gap between buyers and sellers. Historically, this environment had been temporary — people lost their jobs while still carrying mortgages at variable rates. This will likely force sellers to have a reality check in 2023, needing to lower prices to make the sale. As interest rates continue to rise, the housing market is less appealing to potential buyers and mortgage applications are extremely low. Though a few very specific markets have sustained demand, most markets will see large corrections, and some markets, like South Florida, will even experience 20-30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} price drops.
Any time there is a hot housing market with a sharp increase in the median home price, there is the possibility of a housing bubble. After home prices hit their peak in June, we saw the first decline in home price growth in 10 years, with the lagging Case-Shiller Index showing price increases falling 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Black Knight also reported that U.S. home equity dropped 7.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Q3, marking the largest drop since 2009. Though we are not technically currently in a housing bubble or experiencing a major market crash, declining prices coupled with interest rates climbing higher than 7.14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} indicates that we are experiencing a market downturn that will continue into 2023.
Major economic or geopolitical changes could, as they did this past year, upend interest rate … [+] forecasts.
Getty Images
Kate Wood, home expert at NerdWallet: After three years of a wildly unbalanced housing market, it’s tempting to hope 2023 will at last bring normalization. But the market remains far from normal, even if it’s no longer going to extremes. Rates have fallen from the peaks of October and November, but with continued upward pressure from the Federal Reserve the lows we’re seeing now could just be the eye of the hurricane. And major economic or geopolitical changes could, as they did this past year, totally upend rate forecasts. Home prices will likely continue dropping next year, but this won’t be a bubble bursting. These price drops will be more like a balloon slowly deflating — no longer headed skyward, but still hovering out of reach for many. Markets seeing the most significant drops will be those where home values grew the most rapidly, so even with prices dropping, home values will probably still be up year-over-year. Even with higher interest rates forcing some buyers out of the market, demand will likely continue to outstrip supply because the supply just isn’t there.
Many would-be sellers will likely be unwilling to give up the historically-low interest rates they purchased at or refinanced to for a rate that could be double. We may see an increase in homeowners moving without selling. Instead of giving up the low payment on their previous homes, they’re keeping them and converting them into single-family rentals. With a tenant’s rent covering the mortgage while the owner’s equity continues to grow, this can be a win-win for the seller. For home buyers, though, these are more potentially affordable homes that won’t go on the market. Nonetheless, buyers will probably continue to gain traction in 2023.
Jamison Manwaring, CEO and co-founder of Neighborhood Ventures: 2023 will be the first normal year for housing since 2019. After big run ups in housing costs in 2020 and 2021 followed by 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase in interest rates to slow the market in 2022, 2023 is set up to be a more normal year as interest rates stabilize and more newly constructed housing units are added. The supply of new units will be offset by the number of homeowners not moving because their interest rate is much lower than a new loan.
New home and multifamily construction projects slated for delivery in 2024 and 2025 will be delayed because the run-up in interest rates have made these ventures less profitable. Housing costs will remain flat and may even decline in some Sun Belt markets. Additional supply of new construction multifamily units will be delivered throughout 2023, mostly in Sun Belt states helping to ease housing costs. These high growth areas have suffered from housing shortages and new supply has been slow due to materials and labor shortages and Covid-related delays. But many of these projects will be delivered during 2023 adding thousands of additional units.
Jack Macdowell, chief investment officer at Palisades Group: Our base case shows housing activity dropping significantly in 2023 due to lower levels of purchase demand and limited housing inventory. At least through the first half of 2023, persistent labor market imbalances created in part by an undersupplied labor force will likely keep inflation elevated and policy rates restrictive. Barring unforeseen events, geopolitical or otherwise, we would expect volatility to subside alongside the Fed reaching the zenith of rate hikes, leaving room for mortgage rates to drop below 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and easing the debt service burden for would-be home buyers.
We expect mortgage delinquencies to rise as disposable income levels and consumer savings diminish. However, given the default management toolkit and large amounts of home equity, we are unlikely to see a material increase in foreclosure activity that leads to distressed property sales. 2022 and 2023 will likely be remembered as the years where the housing market sowed the seeds for future pent-up demand as would-be home buyers continue to get forced into the rental market due to affordability pressures. In the absence of new supply added to the housing stock, the release of this pent-up demand could come as soon as 2024.
Federal Reserve chairman Jerome Powell at a news conference on interest rate policy.
Getty Images
Lazer Sternhell, CEO of Cignature Realty: The federal fund’s target rate is projected to hit 4.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023, which makes it extremely difficult for investors to evaluate multifamily deals: what will interest rates be at closing, what refinancing events will be available down the line, and what will an exit strategy look like? Investor preference will continue to be focused on free market buildings in prime locations.
Instability in the capital markets and rising interest rates have significantly curtailed multifamily investment activity and higher commercial mortgage rates are sending buyers to the sidelines. Private buyer tolerance for volatility keeps investment activity afloat. If rates stabilize in 2023, institutional investors will provide a further tailwind to the multifamily investment market.
Multifamily’s underlying solid fundamentals over the last 10 years delivered an average annual total return of over 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. We expect multifamily to perform above average in 2023 despite economic headwinds and ongoing capital market disruptions. Multifamily real estate is one of the best asset classes for hedging inflation. Investors will wait for the multifamily market to stabilize.
Marc Minor, CEO and co-founder of Higharc: 2023 will see the continuation of the suburban migration. Smaller cities will be winners in 2023. As the tussle over remote versus in-office work calms down, Millennials who were previously waiting on the sidelines will settle in — likely not in the major cities they started the pandemic in. More than 900,000 new homes have been built every year for the last 60 years, on average. Most of the new homes being built today are in smaller metro areas. Expect this dynamic to drive housing in 2023 and 2024. New construction homes are going to be brought to market in line with the sturdy pace we were seeing pre-pandemic. It is no secret, the U.S. has a deficit of 3.8 million homes. The strength of demand is there and the need for the construction of new homes has never been higher.
The cost of construction and labor, and delays due to permitting and regulations, continue to impede … [+] the creation of badly needed housing.
getty
Doug Bibby, president of the National Multifamily Housing Council: Over the coming year, we expect rents to continue to decrease from the heights of the last couple of years, but that demand for apartment homes to remain strong. Indeed, we can be reasonably confident, as research commissioned by NMHC and the National Apartment Association found that as a country we need to build 4.3 million new apartments by 2035. And that, of those 4.3 million apartment homes needed, we already are facing an existing 600,000 apartment home deficit because of underbuilding due in large part to the 2008 financial crisis. Even more worrisome, the number of affordable units (those with rents less than $1,000 per month) declined by 4.7 million from 2015 to 2020. A recent NMHC survey found that while market conditions may be beginning to normalize, the cost of construction and labor, and delays due to permitting and regulations, continue to impede the creation of badly needed housing. Simply put, over the course of 2023 and beyond we need to build and renovate more housing of all types and at all price points in communities across the country.
One trend of particular concern that will unfortunately continue is that lawmakers at the city, state and even federal levels continue to pursue failed policies like rent control to deal with housing affordability challenges. Again and again, rent control has been shown to actually hurt housing affordability – not improve it. As Swedish economist Assar Lindbeck described it, “In many cases rent control appears to be the most efficient technique presently known to destroy a city—except for bombing.” Looking ahead, we need real solutions that will actually lower housing costs and spread opportunity. That starts with expanding housing supply. NMHC was encouraged when the White House announced their Housing Supply Action Plan earlier this year and we look forward to continuing to work with the Biden administration and lawmakers in both parties in Congress to implement policies that allow for the development of desperately needed housing.
Rick Goldberg, vice president of sales atArize: Over the last few years, the multifamily industry has seen record demand and surging rental rates. In a recent survey conducted by Yardi Matrix, the average asking rent rose 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-over-year, while the national occupancy rate remained strong at 95.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this past October. There is no doubt that multifamily investors and employees are facing ongoing pressures including but not limited to record-breaking inflation, ongoing supply chain constraints, interest rates increasing and resident concerns.
If “hot” was the overused word to explain the U.S. housing maret in 2021, then lukewarm to outright freezing might best explain how the market fared general this yr.
The pandemic housing sector growth, which noticed home rates go up by 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} about a two-calendar year interval, began slowing down in the 2nd half of the yr as mortgage loan charges doubled in contrast to the beginning of the 12 months.
As the Federal Reserve sought to tamp down a long time-higher inflation with rate hikes all through the 12 months, rising property finance loan fees contributed to the rising mismatched anticipations concerning customers and sellers. Households sat on the market place for months as sellers continued to price tag homes at rates prospective buyers could no extended pay for. Contracts ended up canceled, asking price ranges were being slashed and stock stages dropped.
Right after crossing 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in October, mortgage rates have been slipping steadily above the very last five weeks, which could give some reduction to prospective buyers but could possibly not offset still-high inquiring price ranges.
So, what’s ahead for the housing market in 2023? We spoke to six experts for their predictions:
The Federal Reserve and mortgage prices
The Fed elevated its vital limited-time period curiosity amount by half a share level Wednesday, a smaller hike than its former 4, as inflation confirmed indicators of easing.
The Fed also indicated that the financial state would be grappling with slower advancement, bigger unemployment and higher inflation in 2023.
Weaker growth typically potential customers to decrease long-phrase fascination rates, like mortgage costs, claims Mike Fratantoni, main economist for the Mortgage loan Bankers Association.
“The housing sector has definitely welcomed the modern drop in home finance loan charges,” he explained. “This decline is reflecting sector anticipations of staying in the vicinity of the peak for limited-expression rates, as well as greater indications that the U.S. is headed for a recession subsequent 12 months.”
Improvements in property finance loan finance
Housing finance has reached an inflection issue, claims Janneke Ratcliffe, vice president of the Housing Finance Plan Middle at the Urban Institute.
She expects to see innovation speed up with loan providers, startups, advocates, scientists, and policymakers actively pushing the envelope all over what is feasible in mortgage finance.
“We’re seeing pilots and new packages about alternatives in credit rating scoring, synthetic intelligence, weather adaptation, created housing, and a lot more,” she claims. “Not only does the field see the problems of inequality, but quite a few players are also actively voicing their commitments to near the racial homeownership gap.”
Ratcliffe also expects to see elevated use of adjustable-rate home loans, which made up 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of full programs in November, up from 3.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in November 2021.
“Would-be homebuyers really should not worry this fiscal instrument,” she suggests. “Their use has often been prevalent, and regulatory reforms instituted right after the Excellent Economic downturn have significantly mitigated their danger.”
Foreclosure is the consequence of two simultaneous triggers: the deficiency of means to pay out, which results in delinquency and the absence of equity in a household, suggests Odeta Kushi, deputy main economist for Very first American Financial Corp..
With ample equity, a property owner has the selection of providing the household or tapping into that equity to climate a short term financial setback. The inverse – a deficiency of fairness in the house without a financial setback that qualified prospects to delinquency – will yet again not conclusion in foreclosure.
House owners have very high amounts of tappable house equity now, providing a cushion to stand up to probable price declines, but also preventing housing distress from turning into a foreclosures, states Kushi.
“In fact, if distressed house owners are necessary to take care of delinquency, provided their fairness buffers, involuntary income are considerably much more most likely than foreclosures,” she states. “While we can hope the amount of foreclosures to drift bigger as the labor marketplace slows and house rates tumble from their peak, the end result will likely be much more of a foreclosures trickle.”
Housing stock will remain low
The persistent absence of listing inventory has been the important driver of price tag gains during the pandemic-period housing boom, and it will be the key underpinning of price ranges all through 2023, says genuine estate appraiser Jonathan Miller, who prepares the monthly Douglas Elliman Actual Estate report for New York Town.
“Listing stock was piled to the sky in past housing downturns,” states Miller. “Consumers are wedded to the minimal charges they refinanced into or procured residences for the duration of the increase. Extra source is not the story for 2023 simply because, even with modest listing stock growth, price declines need to be saved to a bare minimum.”
Redfin forecasts about 4.3 million residence product sales in 2023, which is much less household profits than in any 12 months considering that 2011 and a lower of 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} calendar year about 12 months.
Declining house price ranges
While there will be no wave of foreclosures, household selling prices will drop in 2023, says Taylor Marr, deputy main economist for Redfin.
Marr expects the median U.S. house-sale rate to drop by approximately 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2023. Even with selling prices falling 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} calendar year around yr, residences will be substantially a lot less very affordable in 2023 than they had been just before the pandemic homebuying growth, he suggests.
“Taking subsequent year’s projected prices and mortgage loan costs into account, the standard homebuyer’s regular monthly payment will be about 63{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increased in 2023 than it was in 2019, just just before the pandemic commenced.”
Dwelling costs will decline the most in pandemic boomtowns when markets in the Midwest and Northeast will maintain up best, claims Marr.
Price ranges are expected to drop most in pandemic migration hotspots like Austin, Texas, Boise, Idaho, and Phoenix, as well as high-priced West Coastline cities. Meanwhile, housing markets in fairly very affordable Midwest and East Coastline metros, primarily in the Chicago spot and components of Connecticut and upstate New York, will maintain up somewhat perfectly.
“Those places tend to be far more steady than high-priced coastal parts, and they didn’t heat up as considerably during the pandemic homebuying frenzy, meaning they also really don’t have as far to slide,” he states.
New household construction outlook
One-family housing begins are established to publish a calendar decrease in 2022, the initial these types of fall in 11 many years, inspite of a persistent structural deficit of housing in the U.S., in accordance to the Nationwide Association of Residence Builders.
House builder sentiment, as measured by the NAHB/Wells Fargo HMI, has declined for 11 straight months, signaling an ongoing contraction for house creating in 2023.
“Single-family house making will in the long run direct a rebound for housing and the overall economic system in 2024 as curiosity prices drop again on sustained basis, bringing need back to the for-sale housing market place,” says Robert Dietz, main economist for the National Association of Residence Builders.
Dietz also expects multifamily design quantity will slide back in 2023, just after a really potent year in 2022. Multifamily home developing, which is extra than 95{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} constructed-for-lease, experienced toughness in 2022 as mortgage fascination premiums elevated and for-sale housing affordability ailments declined.
“However, there are just about 930,000 residences under building, the optimum complete given that January 1974,” he states. “A climbing unemployment charge, elevated apartment provide, rising emptiness rates and slowing lease development will gradual multifamily construction next year.”
Creating conversions?
Commercial to residential conversions will remain more speak than action, according to Marc Norman, affiliate dean of the New York College College of Specialist Studies’ Schack Institute of Actual Estate.
“We’ve lived with the pandemic for just about a few decades, but that nonetheless is not adequate time to shift possession, financing, and regulatory systems for conversion of underutilized business area,” he says. “We could see the beginnings of conversions, but most properties will keep in limbo thanks to extensive-phrase industrial leases and the continuing high value of funding.”
Swapna Venugopal Ramaswamy is a housing and overall economy correspondent for United states of america Today. You can follow her on Twitter @SwapnaVenugopal and signal up for our Daily Cash newsletter here.
Air fryers are a household essential for energy-efficient, quick meals and oven-free lunches, whipping up crispy, delicious results without any added oil. The best air fryers come in a variety of sizes with lots of handy features to try, so there is an option for every family.
Some offer dual baskets, so you can cook a meal in one drawer and a separate side dish or even dessert in the other. Air frying aside, many models come equipped to bake, roast, reheat, and even dehydrate. The best air fryers have easily adjustable timers and temperatures, and if cooking wasn’t easy enough, clean-up is quick thanks to dishwasher-safe baskets or inserts.
A couple of my picks also feature in my list of the best toaster ovens, and have multiple cooking levels to allow you to cook all the different elements of a meal in one go. We’ve also included one or two multi-cookers that can be used to pressure cook and slow cook as well as air fry.
All of the products below went through standardised tests but some will be better for certain users than others. You can find all the details you need to know, like the cooking modes, dimensions, and temperature range, listed with each item to make your decision as straightforward as possible. If you’d like to know more, you can click straight through to read our complete reviews.
Black Friday air fryer deals
Why you can trust Homes & Gardens Our expert reviewers spend hours testing and comparing products and services so you can choose the best for you. Find out more about how we test.
This year’s Black Friday home deals are offering some of the lowest prices I’ve ever seen on many of our top tested air fryers, so there’s no better time to get on the bandwagon.
Best air fryers 2022
(Image credit: Instant)
Best air fryer you can buy
Specifications
Dimensions: 17.1 x 15 x 13.9 inches
Capacity: 6-quart
Settings: Air fry, roast, broil, bake, reheat, and dehydrate
Cleaning: Nonstick tray and basket, dishwasher-safe insert
Temperature range: 95-400°F
RRP: $169.99/ £149.99
Reasons to buy
+
Quiet and odor-free
+
Even cooking at all temperatures
+
Innovative viewing panel in basket
+
Crisped up fries perfectly
+
Pre-heat and reminder to turn included
Reasons to avoid
–
Hand-clean basket
–
Only goes up to 400°F
Why you should buy it: Perfect size for families; made the best fries; prevents cooking odors.
The Instant Pot Vortex Plus 6-Quart 6-in-1 Air Fryer made the best homemade fries of any air fryer I tested. They had a fluffy interior and crispy exterior, with evenly browned edges and consistent cooking throughout.
Because there is a removable air fry insert, you can also use the Instant Pot Vortex Plus 6-Quart 6-in-1 Air Fryer to reheat things such as rice or pasta, which would usually fall through the slots in the air fryer tray.
The six-quart capacity is perfect for families, and it will easily cook for 5 or 6 people. My bacon was rendered perfectly, and the innovative OdorErase technology really did help in preventing cooking odors in the kitchen. This is also one of the quietest air fryers I’ve tried, and I found that the control panel is sleek and attractive, just be prepared to wipe away finger smudges.
My Instant Vortex Plus 6-in-1 Air Fryer with ClearCook and OdorErase review has more details
(Image credit: Ninja )
Best air fryer with two drawers
Specifications
Dimensions: 15.63 L x 13.86 W x 12.4 H
Capacity: 8 Quarts
Settings: Air broil, air fry, roast, reheat, dehydrate, and bake
Cleaning: Removable parts are dishwasher-safe
Temperature range: 105°F–450°F
RRP: $199.99/ £199.99
Reasons to buy
+
Easy to use and clean
+
Cook two dishes at once
+
Generous capacity
Reasons to avoid
–
The controls are a little fiddly
–
No pre-heat
Why you should buy it: Two baskets for cooking two recipes at once; one of the fastest and hottest; easy to clean.
What’s better than one air fryer? Two, in one. The Ninja Foodi 6-in-1 XL 2-Basket Air Fryer is incredibly versatile, so prepare for it to replace your oven.
There are six modes: air broil, air fry, roast, reheat, dehydrate and bake. I found that the air fry mode is great, especially when you use the removable crisper plates, and you can use one in one drawer to air fry chicken while baking or roasting vegetables in the other drawer to make fajitas or simply a balanced meal.
I enjoyed the fact that you can sync the two drawers so every element of your meal will finish together. When you’re done you can place both drawers and the crisper insert into the dishwasher, so not only is it easy to use, but it’s easy to clean, too.
You can choose between smart finish, which allows you to cook at two different modes simultaneously with them finishing at the same time, or match cook, where the settings in drawer 1 are automatically applied to drawer 2.
This air fryer was a consistent performer, with a high-temperature limit which meant it was one of the fastest air fryers I tested when cooking bacon and frozen chicken. There is no pre-heat though, so it loses heat for precision.
My Ninja Foodi DZ401 6-in-1 XL 2-Basket Air Fryer review has more details
(Image credit: Beautiful Kitchenware)
Best looking air fryer for your kitchen
Specifications
Dimensions: 15.11 x 12.1 x 13.07 inches
Capacity: 6 quarts
Settings: Air fry, roast, reheat, and dehydrate
Cleaning: Dishwasher-safe drawer
Temperature range: 90-400°F
RRP: $89.99
Reasons to buy
+
Under $100
+
Attractive design
+
Large basket
+
Dishwasher-safe features
Why you should buy it: Looks gorgeous on your counter; compact design but big enough for families; smart touchscreen controls.
When Drew Barrymore came out with her own line of appliances, we were first in line to review them. The Beautiful 6-Quart Digital Air Fryer looked just as, well, beautiful in our kitchen as it did online, with a Sage Green finish (it also comes in black, white, blue, and other shades) and a matte exterior that won’t mark easily.
The Beautiful 6-Quart Digital Air Fryer has modes for dehydrating, roasting, air frying, and reheating food. It’s got a smart touchscreen control panel that increases the temperature in 5-degree increments, up to an impressive 400 degrees Fahrenheit.
Expert tester Camryn Rabideau found that the materials felt a little cheap, but bear in mind that this is true of most air fryers, as they’re largely made of plastic. The six-quart basket is great for families, but it also worked well on smaller servings of snacks. In her tests, Camryn baked bagels, made French fries, and dehydrated slices of apple, and everything came out well-cooked and evenly crisped. For the price, this is a brilliant and stylish pick.
Camryn’s Beautiful 6-Quart Digital Air Fryer review has more details
(Image credit: Ninja Foodi)
Best Ninja air fryer
Specifications
Dimensions: 8.5 x 12.1 x 11 inches
Capacity: 5.5 Quarts
Settings: Max Crisp, Air Fry, Roast, Air Broil, Bake, Reheat, and Dehydrate
Cleaning: Removable parts are dishwasher-safe
Temperature range: 105°F–450°F
RRP: $169.99/ £129.99
Reasons to buy
+
Dishwasher-safe
+
Compact enough for families
+
Sturdy build
+
Cooked frozen food in record time
Reasons to avoid
–
Max Crisp mode is not adjustable
–
Less effective at lower temperatures
Why you should buy it: Perfect size for couples; lightweight and easy to move; lots of modes.
Despite being one of Ninja’s smaller air fryers, the Max XL really impressed me when I put it to the test. For a start, it’s lightweight and easy to move around the kitchen, and its small frame won’t dominate the kitchen counter.
The 5.5-quart capacity is smaller than some, but it’s perfectly sized to make two portions of homemade fries or a platter of snacks for easy entertaining. Everything I made at higher temperatures crisped up beautifully, from bacon to roasted vegetables, and the cooking time sped up significantly because of the circular, more compact basket. However, I found that it wasn’t as strong when cooking at lower temperatures.
The control unit has modes for max crisp, air frying, roasting, baking, reheating, air broiling, and dehydrating, and there are also easy controls for temperature and timing to toggle as your food cooks. There is also a pause button, which I really like. However, unlike air fryers from Instant which will pre-heat before telling you to add your food, this one has a countdown timer from the beginning.
My Ninja Max XL Air Fryer review has more details
(Image credit: Instant)
Best air fryer for large servings
Specifications
Dimensions: 17.8 x 17.5 x 14.8 inches
Capacity: 8 Quarts
Settings: Air fry, roast, broil, bake, reheat, and dehydrate
Cleaning: Nonstick tray and basket, dishwasher-safe insert
Temperature range: 95-400°F
RRP: $199.95/ £219.99
Reasons to buy
+
Transparent doors
+
Speedy cooking
+
Straightforward cleaning
+
Family-friendly
+
Simple to use
Why you should buy it: Large capacity and two zones for cooking family meals; even cooking; great fries.
With an 8-quart capacity that’s split across two drawers, this Instant Vortex Plus Dual Basket Air Fryer is a brand-new model that’s designed for families and those who want to cook a whole meal in one appliance
The fries I made in this air fryer were amazing, and they were well-browned after just 10 minutes of cooking. We did need to shake them up to get an even finish, but they were some of the crispiest fries we’ve made in just 22 minutes.
In the other basket, I made breaded fish, which also came out deliciously crisp. The two baskets are 4 quarts each, which is perfect for cooking an entire meal for two people or a batch of fries or roasted vegetables for an entire family split across the two baskets. Of course, if you’re only cooking something small for a lunchtime salad topper, you can just use one drawer at a time.
Choose SyncFinish mode to cook your meal at two different times, modes or temperatures, but to finish at the same time. SyncCook will take the settings you’ve applied to one drawer and copy them across to the second drawer. Both are easy to use, and the touch controls will make adjusting your timings mid-cook easy.
My Instant Vortex Plus Dual Basket Air Fryer review has more details
(Image credit: Ninja)
Best air fryer toaster oven
Specifications
Dimensions: 19.72 x 7.56 x 14.96 inches
Capacity: 4-lbs air fryer basket
Settings: Cooker unit, crumb tray, air fry basket, sheet pan, wire rack
Cleaning: Diswasher-safe removable parts
RRP: $199.99/ £199.99
Reasons to buy
+
Very versatile
+
Easy to store
+
Inner light for easy viewing
+
Quick pre-heat
Why you should buy it: Toaster oven too; great internal capacity; easy to see food cooking.
The Ninja Foodi 8-in-1 Flip Mini Oven is one of my favorite toaster ovens. It has a compact profile that folds up and away to maximize counter space when not in use.
When air frying in the Ninja Foodi 8-in-1 Flip Mini Oven I really enjoyed the size of the tray, which is more generous than many drawer-style air fryers. It made distributing meat or french fries across the oven easy, which in turn sped along the cooking time.
The air frying insert is dishwasher-safe, but you need to put a tray underneath it to prevent any liquids from dropping onto the bottom heating element and burning.
You can easily illuminate the Ninja Foodi 8-in-1 Flip Mini Oven from the inside using a button on the main control panel, which means you can check on your food as it cooks without opening the fryer.
As well as air frying, the Ninja Foodi 8-in-1 Flip Mini Oven can air broil, air roast, bake, dehydrate, toast, toast bagels, and switch over to a keep-warm setting. The bottom of the oven opens up for easier cleaning access, but there are still some areas that are tough to clean by hand.
My Ninja Foodi 8-in-1 Flip Mini Oven review has more details.
(Image credit: Philips)
Best air fryer for pre-set cooking
Specifications
Dimensions: 15.1 x 15.1 x 14.2 inches
Capacity: 6.5lb
Settings: Frozen snacks, french fries, meat, fish, chicken, cake, veggies
Cleaning: Nonstick trays and basket, dishwasher-safe
Temperature range: Up to 400° F
RRP: $199.99/ £179.99
Reasons to buy
+
Excellent air circulation
+
Simple to clean
+
Preset cooking modes for convenience
+
Well-made
+
Fat drains away easily
Reasons to avoid
–
Modes are a little confusing
–
Basket is a little clunky
Why you should buy it: Quick and even cooking; good for small spaces; smart presets if you want to cook to specific times.
I was impressed by the air frying in the Philips Essential Airfryer XL. It has a unique ‘starfish’ base that makes sure the air circulates around the entire basket, for even results.
I found that the Philips Essential Airfryer XL had a lot of smart preset cooking modes, but they were a little confusing. They all have specific timings, when you may well be cooking very different sizes of cuts of meat in one mode.
Our homemade fries came out very crispy and evenly cooked, and they finished about 10 minutes ahead of when we’d usually expect them to be ready. The bacon was cooked in just five minutes, and the vegetables came out with the crispiest finish of all the air fryers I tested alongside the Essential Airfryer XL.
Smaller households or those with less kitchen space to spare will love the Philips Essential Airfryer XL, but it is expensive for its capacity and the facade is a little cluttered. This option seriously impressed me with its cooking ability, but I found that it was one of the noisier options I tested at 72dB.
My Philips Essential Air Fryer XL review has more details
Why you should buy it: Budget-friendly; easy to use and Wifi enabled; basket lifts right out and is dishwasher safe.
The COSORI Pro Smart Air Fryer only air fries, so it’s great for those who want a budget-friendly investment without the add-ons of reheating and baking that you’ll find from Ninja and Instant air fryers.
The 13 cooking presets make it easy to get the process started. Choose from steak, seafood, fries, frozen food, veggies, and even cake and bread settings. You can also opt for a keep-warm setting that switches on once your food is finished cooking, so if your side dish isn’t finished yet, you won’t have to worry about your chicken wings getting cold. The Cosori Pro is also Wifi-enabled to be compatible with your smartphone via an app or with a voice assistant to program your device from a distance.
The drawer and basket can go through the dishwasher, and the basket lifts right out, so you can pour out your food onto your plate as soon as it’s finished cooking. This does mean you can only cook dry foods in the COSORI Smart Air Fryer because it doesn’t have the option of removing the air fry insert.
75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} less fat
Why you should buy it: Does everything from pressure cook to air fry and sear; large capacity for one pot meals; can cook a whole chicken.
With a newer take on multi-cooking, the Ninja Foodi 14-in-1 8-qt XL Pressure Cooker makes it easier than ever to air fry in your instant pot. The lid has a slider that will allow you to adjust the lid for all different cooking modes, including a new one: steam air fry.
The controls are intuitive and modern, and the air fryer basket is large enough to fit a whole chicken (although it struggled with a very large one I tried).
The basket has handles that mean you can shake up potatoes or vegetables as they’re air frying, and the dials to the right and left of the display will allow you to increase the temperature or the timer.
There are 14 cooking modes: Pressure Cook, Steam & Crisp, Steam & Bake, Air Fry, Broil, Bake/Roast, Dehydrate, Sear/Sauté, Steam, Sous Vide, Slow Cook, Yogurt, Keep Warm & Proof. You can even proof and then bake a loaf of bread in the one cooking pot.
Steamcrisp cooking is a new feature: it will cook potatoes, vegetables, and even cakes with steam and then crisp them up using the air fry mode.
My Ninja Foodi 14-in-1 8-qt XL review has more details.
(Image credit: Instant Pot)
Best Instant Pot air fryer
Specifications
Dimensions: 15.35 x 12.57 x 14.78 inches
Capacity: 8 Quarts
Settings: Pressure Cook, Sauté, Slow Cook, Steam, Sous Vide, Warm, Air Fry, Roast, Bake, Broil, Dehydrate
Cleaning: Dishwasher-safe removable parts
Temperature range: 95-450°F
RRP: $269.99 / £249.99
Reasons to buy
+
Air fryer basket fits a whole chicken
+
Smart and easy controls
+
I love the sleek black finish
Reasons to avoid
–
An expensive choice when compared to standalone models
Why you should buy it: Very large basket means lots of recipe choice; can also cook a whole chicken; multifunctional and does both air fryer and slow cooking to the level of dedicated appliances.
If you want to double down on functions (or, multiply them by 14) the Instant Pot Pro Crisp is a genius device and comes out on top as our first pick of the many Instant Pot variations. It has 14 presets in total and can be used as one of the best slow cookers when it’s not making delicious homemade fries as an air fryer.
I was able to air fry things we’d never tried before in the Pro Crisp. It has a very generous basket that slots into the stainless steel pot, and we were able to use this to pressure cook a chicken for just 20 minutes before air frying until crisp. All we needed to do was switch the lid midway through.
Cleaning is easy, too, because most of the parts are dishwasher-safe. The air fryer lid cannot go in the dishwasher, but the pressure cooker lid actually can. I found that having an extra lid that’s constantly spare can take up additional space in your kitchen, so this is the best air fryer for those who want to replace numerous appliances in one machine. Overall, it takes up far less space than an air fryer and slow cooker would separately.
The basket is round, and the lid is quite high, so there is a lot you can cook in this device. Note that the capacity is related to the stainless steel pot, though, and while you can air fry without the air fryer basket, the air circulation won’t give you the best results.
You do need oven gloves to lift the air fryer basket out of its cooking pot. It’s great for giving your food a shake-up midway through the cooking mode though, and the display shows your progress on a handy chart. See our guide to the best Instant Pots for more options.
Our Instant Pot Pro Crisp review has more details
How did I choose the best air fryer?
(Image credit: Future / Millie Fender)
When testing, Homes & Gardens took into account the following factors:
Noise: The noise of an air fryer can impact your ability to use it. Perhaps you like to cook while listening to the TV, or you live in a smaller home and the noise of an air fryer running would distract you as you work. If an air fryer is noisy, I make a note of it.
Speed: Air fryers promise to speed up cooking times, so when testing them I used standardized recipes to see how long they will take to cook classic recipes. While potato fries would typically take around 25 minutes in the air fryer, the speediest air fryers we tested have taken as little as 12 minutes to make crisp, evenly-cooked fries.
Looks: It’s going on your kitchen counters, so it has to look the part. You might not mind a less attractive air fryer as much as some other users, but any bulky features or unattractive elements such as smudging or busy display panels were noted during testing.
Cleaning: Cleaning an air fryer should be easy. Most have baskets that can go in the dishwasher, and it’s rare to find one without a non-stick interior. If I ran into any difficulties cleaning, I marked it down.
Some of the air fryers in our guide have been reviewed on other Future Homes websites, but they have all been reviewed by me, so I can still bring you all my inside knowledge even if you can’t click through to read the full review on Homes & Gardens.
For more insight, our review guidelines explain more about our product review process.
Our reviewers
(Image credit: Future)
Most of the air fryers in our best air fryer guide have been tested by our resident testing genius and Head of Reviews, Millie Fender. Millie tested these air fryers for weeks in her own kitchen, so she can directly compare taste, user experience, cooking times, and ease of cleaning.
Millie used standardized recipes across all the machines she tested, cooking streaky bacon to see how fast it and evenly it would crisp, and cooking homemade potato fries to see how well the air fryers can handle large servings. She also cooked an assortment of home recipes while working from home, just as you would in your own kitchen.
‘My favorite air fryer I’ve tried is the Instant Pot Vortex Plus 6-Quart 6-in-1 Air Fryer – hence why I’ve put it in first place!’
Camryn Rabideau
Camryn has been reviewing kitchen appliances for years, and she has reviewed everything from bread makers to juicers for Homes & Gardens.
From her home in Rhode Island, Camryn reviewed the Beautiful 6-Quart Digital Air Fryer, and noted that it’s ‘a great entry-level air fryer for anyone who wants a more attractive appliance’.
How much does an air fryer cost?
You can typically expect to pay between $80 and $150 for an air fryer, but a few of our top picks come in at under $80, and some of the smarter options go up to $200. As a general rule, as you go up in budget you’ll find that the options become smarter and larger. The best value air fryers I’ve tested come with one large-capacity basket and a drawer-style design that is easy to use and clean.
How big of an air fryer do I need?
For the average buyer, I suggest buying a five-quart air fryer. The basket is large enough to not be crammed when cooking for your family, but won’t take up too much space on the counter.
For two-person households, between two and four quarts of capacity will serve your day-to-day air frying needs. However, if you want to cook for more than two people or you plan on cooking two elements of your meal at once, some of the top dual-drawer air fryers offer up to nine quarts of cooking space.
What are the features of an air fryer?
Many air fryers come with multiple cooking modes. Opting for something that will allow you to also bake, roast, dehydrate, reheat, and even slow cook will add real versatility to your kitchen counters.
What is the best air fryer brand?
As you can see, we think that the best air fryer brand is Instant. We rated its Instant Pot Vortex Plus 6-Quart Air Fryer the best on the market when we tested it in our review kitchen, but Ninja came a close second with its Ninja Foodi DZ401 6-in-1 XL 2-Basket Air Fryer. This comes with two cooking baskets and an XL capacity for feasting.
Another brand that really impressed us when it came to cooking quality is Philips, and if you want the best value air fryer brand, take a look at Cosori air fryers.
Is air frying healthy?
Many love the best air fryers for how well they work with a low-fat diet. Unlike deep fryers, which require you to immerse your potato chips in oil, air fryers make the most of even a tablespoon of oil to circulate it around the fries, and if you cook bacon or chicken, fat will render and drip away from the meat and stop it from making its way onto your plate.
So while air fryers don’t necessarily make your diet healthy, because it depends on what you cook in them, they really can help.
Different types of air fryers
There are a few different types of air fryers to choose from, but all of them work in a similar way. You can choose between two main types:
Drawer air fryers have inserts with handles that can be easily lifted out of the cooking unit and shaken up to evenly cook your fries or chicken without having to turn using a spatula.
They are a very popular design because they often have an insert that elevates your food to allow air to circulate inside the air fryer basket as it cooks. You can sometimes even lift this filter out of the main basket, which contains oil and juices as they drip away from your food, to make sure none of it ends up on your plate.
(Image credit: Future)
Toaster oven air fryers are the second and less common type. We feature many of them in our guide to toaster ovens because they come with layered designs that can be used to bake and roast as well as air fry.
Some even come with rotisserie functions that can be used to cook kebabs or whole chickens, but because they don’t have a drawer that can be easily pulled out, they can be more fiddly to operate, but they most closely resemble a smaller-scale oven in our experience.
Completely ready to take Halloween to the future level? We have information — and shots — from severe decorators.
October 13, 2022 at 8:00 a.m. EDT
(Paul Blow/Illustration for The Washington Submit)
Remark
Prior to you haul the same pretend cobwebs and skeletons out of storage for an additional spooky time of suitable-but-absolutely nothing-exclusive Halloween decor, allow us to nudge you towards some self-reflection: What if this yr, you went all in?
What if this 12 months, your home turned “the outrageous Halloween house?”
Pandora Rose’s residence in Aurora, Colo., has carried that honorific considering the fact that 2009, when she 1st transformed the modest 1980s home into Darkrose Manor, festooned, based on the yr, with the trappings of a haunted forest or a “dark carnivale.” Normally a lover of Halloween, she and her spouse married on the holiday. One particular year, after a costume contest fell as a result of, she determined to surprise him with “super cheesy” decorations. “We did not have a single trick-or-treater, but boy, we experienced so a lot exciting just sitting there and savoring the atmosphere.” They have since developed a business enterprise out of spooky output and artwork layout.
Attracting trick-or-treaters is no for a longer time a trouble. Rose suggests her ghoulish adornments have supplied neighbors some thing to bond above: “We are quite a great deal a tightknit local community that now comes together basically simply because of Halloween.” In truth, the social positive aspects of all this All Hallows’ Eve pleasurable are absolutely just one motive Americans are projected to invest additional than $3 billion decorating this calendar year, in accordance to the Countrywide Retail Federation.
If you are prepared to freak out (but also delight) your neighbors, heed this haunted advice from Halloween superfans.
Substantial skeletons are just aspect of how we are living now
Qualified haunted sights often guide you by way of vignettes — for instance, an alien come across followed by an eerie circus, which qualified prospects to an undead Viking feast. Even though you can unquestionably consider a equivalent technique at property, several aficionados suggest choosing 1 topic to manual you.
Colleen Delawder, who has lived in and decorated the Historic Herndon Halloween Property in Herndon, Va., since 2005, suggests themes make decorating easier and much more pleasurable. Receiving her individual dwelling prepared for the major working day typically starts on Labor Working day.
This calendar year, she’s basing her motif on the film “The Nightmare Prior to Christmas,” which means she’ll get to use her Xmas decorations, much too. Prior Halloweens have featured clowns and haunted pirates. (This is why she continue to consists of a pirate ship. “We have it, so why not use it?”)
Delawder also suggests incorporating your hobbies, which can help save money. If you are into kayaking, for instance, set out your kayak and toss some skeletons in it.
Rose modifications her concept annually, way too, frequently using wherever from a single to a few months to put it all jointly. (Her longest setup took more than a calendar year.) This 12 months, she drew inspiration from the late Polish artist Zdzisław Beksiński, whose surrealist operate often depicted his nightmares. (Who states Halloween cannot be highbrow?) “We want [people] to feel like they have both entered into one more earth or they are viewing the portal to yet another entire world,” Rose states.
Paul Brubacher, director of functions at Markoff’s Haunted Forest, an once-a-year attraction in Dickerson, Md., states his team’s thoughts are likely to occur from “our very own issues that creep us out and what we get the shivers about.” Inspiration also can strike unexpectedly, such as whilst shopping at Home Depot: “I’ll just see a little something in the plumbing aisle and go: ‘Oh, wow, that right there looks like an intriguing fitting. I could likely use a very little paint, … perhaps place a small latex on it, and I could make that into an alien feeding tube.’ ”
Don’t traumatize the neighbors
Whilst commercial points of interest this sort of as Markoff’s are intended to scare you silly, you must most likely avoid severe horror at residence, specifically if you have youthful kids all-around.
To delight instead than traumatize, Brubacher suggests concentrating on atmosphere in excess of blood and guts. “There’s terrifying, and then there’s just gross, proper? If I’m searching at a pile of dismembered bodies, I’m not scared, I’m disgusted.” He suggests utilizing fog devices and eerie lighting to establish secret, no gore required.
Continue to, if you experienced your heart established on dismembered physique components, there are strategies to be playful about like them, Delawder suggests. A recurring aspect at her Historic Herndon Halloween Property is a haunted grill, which has faux parts above the flame. “But it is not disgusting in any way. It just type of seems enjoyment and whimsical,” she states.
Indeed, throughout the board, realistic blood and guts were seen as no-nos. So, way too, have been real looking references: The professional decorators we talked with cautioned in opposition to featuring just about anything also topical. “We’re not touching on subjects that could be touchy for other individuals or probably disrespectful of someone’s perception systems,” Rose states.
Get frightening-superior offers on provides
As with most holiday getaway goodies, the least-high priced time to store for Halloween decorations is ideal immediately after the unholy day, when you will discover goods on clearance. But that is not the only strategy for scoring bargains.
Character can be a excellent (and cost-free) resource: “The additional organic factors you can convey in, the extra convincing your environment gets to be,” says Rose, who collects tree limbs, sticks and leaves for her graveyard set up and other macabre shows. “There is almost nothing extra fall and Halloween than the seem of crunching leaves underneath your ft.”
Halloween is also a recycling option. Francisco Santos, operations director at the Horrorland, a haunted attraction in Miami, finds props at flea marketplaces and scours curbs on evenings when people set out undesirable furnishings and other goods for metropolis pickup. “We observed a definitely nice outdated classic desk that we remodeled into a rotting desk wherever somebody’s feeding on somebody else,” he says.
When renovating his bathroom, Thomas Hall of Richmond — who has been making intricate jack-o’-lantern shows for 16 many years — saved the old bathroom. He saved it for the adhering to Halloween, when he staged a person of his pumpkins throwing up into it.
Maybe you are not prepared to grow to be the hardest-main Halloween home on the block. (There’s always next 12 months.) But there are toddler actions you can acquire to give your regular decor additional oomph.
Start out with retail outlet-bought skeletons. Even so, really do not they search a little bit sterile to be human stays? Brubacher endorses coating them in liquid latex for texture, followed by a layer of wood stain to age them. (Or, you know, you could just roll them around in filth.)
Resist carving pumpkins until eventually a couple of times right before Halloween to keep away from rot. Then take into account swapping that orange plastic carving knife for a drywall knife as an alternative. Lou Cantolupo, a large-scale pumpkin sculptor in D.C., claims drywall knives are sharper and direct to more specific styles. He enlists a range of power instruments, far too, but those people could possibly be a tiny sophisticated for an beginner.
Feel about other senses. Last but not least, assume of your decorations as more than just a thing to glance at. “What do you odor? What do you style?” Rose claims. “If you assume about people issues in your thoughts as you’re making your haunt, it is likely to make for an astounding experience.” She provides a seasonal scent — these as a campfire scent — to her fog machine: “We just really want it to be a little something of a sensory overload.”
Check out out what is actually clicking on FoxBusiness.com
Prospective property owners who need to have to go now are not completely out of luck, even with elevated house costs and soaring house loan fees, which just lately topped 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the 1st time in two decades.
Authentic estate professionals told FOX Business enterprise that there are nonetheless some gains to leaping into the sector right now.
For one, with levels of competition waning, “prospective buyers don’t have to make a selection pretty so swiftly,” according to Clare Trapasso, govt news editor of Real estate agent.com.
US Property finance loan Curiosity Charges Jump TO 7.16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Maximum Because 2001
“There is also substantially less opposition now that fewer prospective buyers can qualify for mortgages and can manage the households they want,” Trapasso mentioned. “So, prospective buyers are fewer most likely to get entangled in highly-priced, emotionally draining bidding wars.”
A diminished value signal sits in entrance of a household Nov. 27, 2007 in Glendale, California. (David McNew/Getty Photos / Getty Visuals)
For the duration of the red-warm housing sector, competition was getting so stiff that property owners had been featuring over-inquiring costs, dropping contingencies for inspections and appraisals, and closing on the residence in a month, FOX Enterprise earlier claimed.
Now, it is a buyer’s current market, according to Lauren Cangiano, an associate broker with New York Town-centered Brown Harris Stevens.
“They really don’t have to jump as a result of hoops in 5 seconds any longer,” mentioned Cangiano. “They can make an informed, clever selection simply because things are staying on the industry extended.”
Ultimately, consumers now have an “option to do far more investigate,” which was not the scenario in 2021, when residences ended up “traveling off the shelf,” according to Cangiano.
US Household Rates COULD PLUNGE 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Upcoming Year AS Property finance loan Rates SURGE
Trapasso claimed she is also encouraging consumers to negotiate as considerably as attainable and incorporate appraisal and residence inspection contingencies to their offers.
A “Dwelling for Sale” indicator factors to an current single-family members residence for sale Oct. 4, 2006 in Park Ridge, Illinois. (Photograph by Tim Boyle/Getty Illustrations or photos)
This provides customers the capability to renegotiate in the party that a home does not appraise for as much as the customer provided, Trapasso explained.
“If a qualified household inspection uncovers some dear troubles, they can also go back again to the bargaining table,” she additional.
GET FOX Enterprise ON THE GO BY CLICKING In this article
Trapasso also observed that customers can even attempt to post bids less than the asking value if a home has been sitting on the current market for a though.
Contractors operate on a house under construction in Antioch, California, on Tuesday, June 14, 2022. (David Paul Morris/Bloomberg by using Getty Illustrations or photos / Getty Pictures)
In the same way, Cangiano stated sellers have an understanding of what is going on in the world and will be far more negotiable in cost mainly because of it.
“In my feeling, this is when you should really be… deep diving into a get and receiving by yourself the most effective deal,” she reported.
If it is a new building, potential buyers can even check with the seller or the builder to add to their closing fees or even make some improvements to the house, which in transform “can conserve them a fairly penny,” Trapasso explained.