Florida real estate firm accused of ‘equity theft’ by St. Louis homeowners

Florida real estate firm accused of ‘equity theft’ by St. Louis homeowners

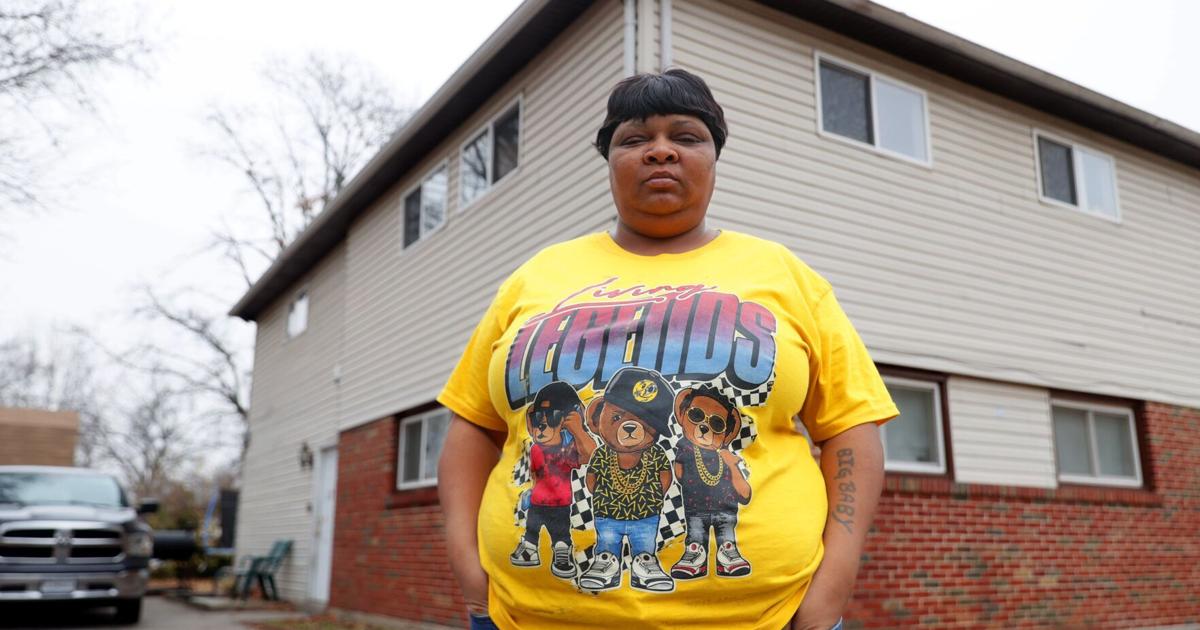
ST. LOUIS — Dianne Allen experienced been ignoring the calls from a range she did not figure out. But after so lots of, she last but not least relented. 

The female on the other stop requested if she was the operator of 8441 Midwood Avenue in Berkeley. “What is this about?” Allen asked. “You could be eligible for up to $2,000 in upfront cash if you agree to use our true estate service,” the female said.

Allen desired some cash to catch up on her truck payments. And just before the conclusion of that working day in August, a notary was at her home, thumbing by means of papers for her to indicator. They gave her a test for $500. 

“I held stating, ‘what’s the catch?’” Allen stated. “If I understood there was gonna be a lien on my dwelling I would have in no way signed.”

But the firm, MV Realty, did file a lien in opposition to the household, stability for the 40-12 months agreement Allen signed to use the Florida authentic estate brokerage business if she at any time sells.

Persons are also reading…

Now, Allen cannot get out the dwelling equity mortgage she was hoping to use to remodel her kitchen area because of the excess lien on her assets. Banking companies are most likely to balk at refinancing. And up to 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of her home’s value — a benefit identified by MV Realty — is now due to MV Realty, possibly from a brokerage commission or a termination price beneath a clause that looks pretty much created to be triggered, stated Rob Swearingen, a lawyer with nonprofit regulation business Legal Services of Eastern Missouri representing Allen.

MV Realty states its contracts are only built to dedicate owners to use its brokers if they at any time provide the household, and their 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} fee is in line with market standards. A deal reviewed by the Put up-Dispatch has a provision spelling out a lien will be recorded towards the assets.

But, in addition to triggering a penalty well worth 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the home’s worth if the dwelling is sold applying a non-MV Realty broker, the 40-12 months agreement consists of an early termination clause induced if the household is transferred to heirs and they really don’t recommit to the agreement in a couple times.

“It’s like a hidden grenade that everyone’s gonna forget about and the heirs won’t know about,” said Swearingen, who is planning a lawsuit versus MV Realty above its methods. “It’s an equity theft gadget, is what this is.”

Lawful Products and services estimates MV Realty has entered contracts with at the very least 100 home owners in Missouri, about 40 of them in the St. Louis location, in accordance to home information.

The enterprise has lately attracted consideration from point out attorneys standard and users of Congress. 

In late November, Ashley Moody, the attorney typical of Florida, where by the company is centered, was the 1st to file match from the enterprise, alleging misleading small business tactics and telemarketing legislation violations. The Florida Attorney Common lawsuit cites documents from just one telemarketing support indicating MV Realty still left around 6.8 million voicemails advertising their “homeowner profit agreements.”

“For a enterprise to prey on unsuspecting owners in a way that locks them into a 40-yr obligation created to siphon away equity from the property is disgraceful,” Moody explained in a Nov. 29 news launch asserting the lawsuit. 

Last week, both of those Pennsylvania Lawyer Typical Josh Shapiro and Massachusetts Legal professional General Maura Healey submitted a related lawsuits versus the firm. Shapiro’s business office says MV Realty statements it has executed some 32,000 “homeowner advantage agreements” nationwide, up from pretty much 7,800 in 2021. 

“MV Realty is a scam that exploits Pennsylvanians in susceptible fiscal situations,” Shapiro reported in a statement final 7 days. 

In a statement, MV Realty spokeswoman Diana London reported it is “committed to operating with policymakers, regulators, and lawyers basic in which needed” and that “we are assured that soon after a complete airing of the specifics, these conversations will strengthen how MV Realty’s organization transactions are lawful and moral and that our workforce operates in total compliance with condition and federal laws.”

“New and progressive enterprise products, like the (Home-owner Gain Arrangement), can completely transform established industries and can from time to time attract inquiries from critics or outright hostility from individuals whose present small business design is threatened,” London stated in a statement. “However, to recommend that MV Realty has engaged in unfair or deceptive methods is simply just fake.”

On Wednesday, U.S. Sens. Sherrod Brown, D-Ohio, Ron Wyden, D-Oregon, and Tina Smith, D-Minn., sent a letter to the Federal Trade Fee and the U.S. Shopper Fiscal Defense Bureau citing the latest media stories about MV Realty. It urged the regulatory companies to operate with condition attorneys basic to examine MV Realty’s business enterprise techniques and any equivalent real estate broker listing agreements.

R. Wilson Freyermuth, a real estate legislation professor at the College of Missouri-Columbia, questions whether the underlying liens are legitimate if the home-owner has no obligation to promote their property or fork out back again the upfront funds. The American Land Title Association is currently drafting design legislation, he stated, to bar tying service contracts of all styles, not just actual estate brokers, to assets titles. 

‘Securitization scheme’

Quite a few of the headlines in the latest weeks — which includes a person from superstar news internet site TMZ — have targeted on the deal with of the enterprise, Amanda Zachman, a contestant (who went by Amanda Zuckerman) in the 2013 season of the “Big Brother” CBS truth Television set clearly show. 

But the impetus for the strategy to use long term listing contracts may perhaps have arrive from a New York financial investment business hunting for ways to securitize assets tied to house values and two Florida fiscal expert services veterans who led a enterprise that a ten years ago faced federal prosecution over monetary goods tied to life insurance plan. 

MV Realty’s CEO is Antony Mitchell, who at the time served as CEO of Florida economical products and services corporation Imperial Holdings. He led Imperial Holdings a ten years ago with Jonathan Neuman, a minority trader in MV Realty. Neuman stepped down as Imperial Holdings’ president and chief working officer in 2012 after the FBI raided Imperial Holdings’ Boca Raton business and it was disclosed he was under investigation. 

The Justice Office in April 2012 arrived at a nonprosecution settlement with Imperial Holdings over its advertising and marketing of economic merchandise tied to lifetime insurance contracts. The Justice Department agreed to not prosecute the enterprise, citing its cooperation, the termination of the daily life insurance product or service organization and the departure of workforce involved in the carry out. Mitchell, who took about as Imperial’s president following Neuman stepped down, resigned as chairman a couple of months after the DOJ settlement.

According to court paperwork, New York expenditure firm Innovatus Funds claimed it brought the concept for MV Realty’s listing agreements to Mitchell and Neuman. Innovatus CEO David Schiff approached the two, believing they controlled MV Realty, about a way to crank out long term broker listing agreements as a financial product tied to the value of actual estate. The two had “extensive experience originating and securitizing asset courses that experienced not formerly been securitized,” MV Realty statements in its possess lawsuit from Innovatus.

The two providers have been in litigation considering that 2018 around nondisclosure agreements and MV Realty’s use of the broker listing agreements. They settled very last week, days following the Pennsylvania and Massachusetts lawyer normal lawsuits.

A spokesman for Innovatus Funds did not reply to a request for remark.

MV Realty claimed Neumann is a minority spouse in MV and has not been an worker or officer of the business. The lawsuit has been solved “amicably,” London mentioned.

“It appears as while you are striving to hook up past lawsuits that have been fixed with this ongoing dialogue MV is possessing with lawmakers,” she stated in an electronic mail. “They have very little to do with every other. The enterprise would value if you stick to present points and not what it (sic) quite obvious you are becoming fed.”

London stated MV Realty is not securitizing any of its upcoming listing agreements. The Florida lawyer normal lawsuit says the company’s main running officer, David Manchester, is “responsible for securitizing MV Realty’s interests in contracts with customers.” 

The involvement of Innovatus Capital in the notion reveals MV’s promises of serving to property owners with some upfront income is just a entrance for fiscal engineers seeking to create yet another Wall Road merchandise, Swearingen mentioned. 

“It has very little to do with any advantage to home owners,” Swearingen reported. “It was a securitization scheme.” 


Homeowners targeted with suspect loans

Marcella Jackson poses for a portrait within her St. Louis household on Wednesday, Dec. 21, 2022. Jackson signed an agreement with a Florida-primarily based true estate company, MV Realty, about the property that she owns on Miami Avenue, which could have resulted in a lien versus her residence.


Again in south St. Louis, Marcella Jackson may be a single of the blessed ones. She picked up a cold connect with from an MV Realty agent though she was at do the job and was informed she could be owed money for agreeing to use MV to list her house. She didn’t have an understanding of what the funds was for, but she could use the income. So she did not dangle up. They moved quickly. 

“I spoke with them that Friday, she sent me the contract that Friday, and 10 o’clock Monday early morning the notary was there,” Jackson explained. 

She signed an settlement with MV Realty for her two-bed room, a person-lavatory Tower Grove South property, but she felt one thing was not suitable. She under no circumstances cashed the $629 check they gave her. MV has not recorded a lien towards her dwelling. 

“It felt like one thing was wrong the complete time,” Jackson claimed, “but I couldn’t put my finger on it.”

&#13

DEMOGRAPHIC Challenge: St. Louis was just one of the nation’s slowest-escalating metro parts around the previous decade. Jim Gallagher argues that we should fear much more about high quality of life, but David Nicklaus counters that the place can not prosper without expansion.

&#13

&#13

Can You Take Out a Home Equity Loan on a Rental Property?

Can You Take Out a Home Equity Loan on a Rental Property?

If you individual a lot more than 1 residence, you can borrow towards any equity you have constructed up to fund a substantial expenditure.

When you acquire out a property equity personal loan and use your household as collateral, it’s important to be conscious of the gains and drawbacks, however. For a residence equity loan, an financial investment assets and rental property are handled the same you can borrow from the equity in possibly. 

Here’s what you should know about borrowing towards your fairness in a rental residence (or other non-most important home) and why other kinds of funding may perhaps be a safer bet. 

What is property equity?

Your property fairness is the variance in between what you owe on your property finance loan and the present-day price of your residence. You establish fairness in your household by constantly producing mortgage loan payments about the a long time. Most loan companies will anticipate you to have at minimum 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity in order to approve you to borrow dollars from your most important home. When it will come to a rental property, even so, loan companies usually require larger degrees of equity for acceptance due to the fact it is a riskier loan for them.  

Challenges of making use of dwelling fairness to finance a second home

Using a residence equity financial loan or HELOC to borrow against an expenditure home is a dangerous shift. It signifies you are going to be on the hook for a few mortgage loan payments a thirty day period, which is a significant economic motivation even if you can comfortably pay for the payments. 

The use of dwelling fairness financial loans and property equity traces of credit rating, or HELOCs, strike file highs during the pandemic thanks to soaring home values and small curiosity charges that manufactured borrowing funds inexpensive. Nevertheless, as the Federal Reserve ratcheted up fees by 2022, borrowing versus a dwelling, whether or not it is a major residence or not, has come to be radically additional high priced.

“Household fairness rates are the optimum they have been in 15 years, and it really is likely to price tag you even much more on a little something other than a principal residence,” suggests Greg McBride, main fiscal analyst for CNET’s sister website Bankrate. “Individuals typically look at home equity as observed revenue. But it’s no more time a affordable source of borrowing with the way fees have long gone up this yr.”

What is a residence fairness personal loan?

A residence fairness financial loan lets you borrow money from your current equity and presents you with a lump sum of money at a fixed fascination rate and a set repayment routine. Your monthly payments will normally be regular and your interest level will never ever transform. 

What is a HELOC?

A HELOC is a revolving line of credit history that works far more like a credit card. You you should not obtain your funds all at when and as a substitute you can make as several withdrawals as you will need more than an extended interval of time. HELOCs have variable fascination fees, so your month-to-month payments will fluctuate, as opposed to household fairness personal loan payments which keep regular.

What is a rental assets?

A rental assets is any assets you acquire with the intention of generating earnings by renting it to tenants. Any rental house you use to make income can also be referred to as an financial investment home. 

How to get a dwelling equity financial loan or HELOC on a rental property

As with any financial loan or home finance loan, you may want to have all of your economical ducks in a row right before applying. Though property appraisals might now be carried out nearly, it can be likely your loan provider will involve one particular or two in-human being appraisals to affirm your home’s  benefit. 

Calculate your loan-to-benefit ratio

Determine your personal loan-to-benefit, or LTV, ratio, which is simply just the recent appraised value of your dwelling divided by the remaining harmony. Most loan providers prefer an LTV of 85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or considerably less for key residences, but will possible demand an even decreased LTV for an expenditure residence. 

Critique your credit score historical past

In addition to your accessible equity, lenders normally have to have a credit rating score of 700 or greater to make this type of bank loan. The increased your score, the greater costs and terms lenders will provide you. Prior to you use, review your credit report for accuracy. For a major home, loan providers typically want you to have a personal debt-to-revenue or DTI, ratio among 36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 43{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. For a rental household, the threshold may possibly be lessen.

Get your money paperwork together

You can expect to want to exhibit you can pay out back again your personal loan more than time by furnishing evidence of profits and work with tax returns, shell out stubs and W-2s. You can expect to also be needed to exhibit present-day house loan statements for the homes you by now possess to display that you’ve got been building on-time payments. For a rental assets, you will have to demonstrate proof of rental insurance policy, and also probably be demanded to present copies of your tenants leases’ to exhibit that the property is occupied and building money. 

Evaluate loan providers

Not all creditors provide property fairness loans or HELOCs for financial investment properties because they are inclined to be riskier. The a lot more loan companies you job interview, the much better your possibilities of obtaining the most favorable costs and terms. Some creditors may perhaps present decrease fascination prices that seem less pricey, but consist of larger charges that could terminate out any likely price savings. Make positive you realize the complete price concerned, together with any added loan company and 3rd-bash costs. 

Solutions to a house fairness mortgage or HELOC when financing a rental assets

There are other varieties of financing that you should not have to have you to acquire a 2nd home finance loan out on your rental household. And at existing curiosity premiums, you could not conserve all that substantially with a household equity bank loan or HELOC compared to an additional form of personal loan.

“There is certainly a whole lot of property equity rates that have attained double digits and they’re still heading up because the Fed is nonetheless increasing premiums,” claims McBride. “You are not going to get a discount by tapping into equity on a rental residence or an expense property.” 

Personalized financial loan: A private mortgage is an unsecured bank loan so it will have a greater fascination level and lessen credit score limit than a house fairness bank loan, but it won’t require you to set your rental up for collateral. The average own bank loan rate is numerous share details higher than a HELOC, according to Bankrate.

Dollars-out refinance: A cash-out refi replaces your latest house loan with a new house loan that has far more favorable fees and phrases. The fairness you borrow is included again onto the equilibrium of your new house loan and you fork out it off above your bank loan expression. But with fascination premiums close to their best concentrations in two a long time, this possibility almost certainly will not make sense for most householders who’ve now locked in a reduce amount. 

Credit history playing cards: A credit score card is also unsecured personal debt that will have a increased desire charge than a property fairness financial loan, but you will not likely be at risk of foreclosures and you may well benefit from credit card rewards courses, also.

The bottom line

You can just take out a house equity financial loan on a rental property, but accomplishing so means you may have to pay a few mortgages every single month. When you borrow towards your dwelling equity you are utilizing the property as collateral to protected the personal loan, so if you default for any rationale your loan provider can repossess the property. With fascination prices continuing to increase and household fairness premiums at a 15-year superior, it is really not value the danger of foreclosure to borrow from an investment residence if you have access to other forms of financing.

Home Equity Loan On Investment Property

Home Equity Loan On Investment Property

heerful family toasting drinks during a party

Klaus Vedfelt/Getty Illustrations or photos

A household fairness financial loan enables you to tap the fairness in a residence to acquire a one particular-time lump sum you can use for any function. You may possibly be ready to get a household fairness loan on a rental property, although the procedure can be far more complicated, and you could commit extra with a higher interest amount.

The quick remedy: Sure, it’s achievable to get a property equity mortgage on an expenditure or rental house. It’s also achievable to use a dwelling equity financial loan to assistance buy this kind of property.

Even so, in the eyes of a home equity lender, investment decision houses are riskier compared to key residences. This is because you most likely really do not depend on the rental to serve as the roof around your head, so there is much less at stake if you somehow become unable to repay the dwelling equity mortgage.Because of this hazard, it could possibly be harder for you to find a lender inclined to tie a home fairness loan to an financial commitment assets. If you do locate a single, you will probably shell out extra in interest to compensate for that danger.

Necessities for a home equity loan on expense house

The necessities for a home fairness personal loan on an investment decision or rental property change by lender. In common, you can count on to want:

  • Minimum amount credit score score: 700 or higher
  • Optimum debt-to-earnings (DTI) ratio: 43 per cent (from time to time up to 50 percent)
  • Most bank loan-to-price (LTV) ratio: 80 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Reserves: Six months’ to 15 months’ worthy of of dwelling fairness financial loan payments

Aside from the chance the financial institution usually takes on, you’ll be having on some possibility, as well. Identical to a home loan, when you borrow against a home’s equity, you could eliminate the home if you fall short to preserve up with payments.In addition, if the property’s value decreases, you could uncover you underwater on the bank loan. This tends to make it much more challenging to offload the dwelling if you choose or need to sell.

“If a economic downturn begins, you operate the possibility of taking out far more than the house is worth, and you could have a quite hard time offering it,” states Dick Lepre of CrossCountry Home finance loan. “If curiosity prices are higher, that depresses house values.”

Can You Use a Home Equity Loan for Investment Property?

Can You Use a Home Equity Loan for Investment Property?

Investment decision qualities can be a terrific way to build passive profits and diversify your expenditure portfolio, but breaking into authentic estate investing takes a massive chunk of alter. If you really don’t have hard cash lying around and don’t want to wait until eventually you’ve saved it, can you use a house fairness mortgage on an expenditure property?

Crucial Takeaways

  • Higher curiosity rates have led to a slight slowing of the housing marketplace.
  • A house fairness loan challenges your house if you can not shell out it back.
  • You can make income in true estate in a slower market place, but it normally takes talent.
  • Know the threats just before you borrow in opposition to your dwelling. 

Working with a Home Fairness Personal loan to Spend in Serious Estate

Household equity bank loan proceeds can be made use of on anything at all you choose, which include investing in serious estate. To use a household equity personal loan to make investments in authentic estate, you will need to have some equity in your present home, first rate credit score, and proof of profits adequate to pay back back the mortgage.

When your dwelling equity financial loan has shut and you have picked out an investment decision property, you can use the proceeds from your household equity mortgage in any way you pick out on your financial investment home, or everything else. The dollars is yours to use as you wish following the personal loan closes, but just simply because you can use your residence fairness loan to make investments in genuine estate does not suggest you really should.

Risks of Utilizing a Dwelling Fairness Financial loan to Spend in Actual Estate

Working with a home equity bank loan for an financial investment house carries risks that you need to look at right before signing up for 1.

Property Equity Loan Risks

Home equity financial loans are loans that enable you to borrow from your home’s fairness for a lump sum payout that you fork out back more than time with a set fascination fee and mounted regular payments. They carry two major risks 

  • You could default on your bank loan and eliminate your property if you just cannot retain up with payments.
  • Your home’s worth could decrease and you could come to be underwater on your financial loans, meaning that you can not transfer or provide your house with no having to pay funds to your loan providers.

Actual Estate Financial investment Challenges

No person can predict the foreseeable future of the housing market place with 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} precision but it does seem that the wild advancement amount of the last several several years is starting up to sluggish down as fascination rates are climbing promptly. Investing in serious estate as the sector is slowing signifies it could be challenging for you to make income in the around foreseeable future immediately after accounting for closing expenses, high desire payments, and any renovation fees you might have.

Even though real estate investing has been a fairly simple way for folks with even minimum knowledge to have wonderful gains in excess of the past numerous a long time, do not confuse an individual else’s luck investing in a scorching market place with true success. Discovering to review true estate markets, rental marketplaces, and opportunity return on financial commitment will take talent and specialized expertise a lot of spend a long time developing. 

If you are hunting to make investments so you can flip homes, that may possibly be far more hard to make a revenue with at present. If you’re intrigued in getting investment decision assets to lease out to tenants, then you want to be extremely comprehensive in your investigation on the rental marketplace and the principles and rules in the area you are investing in. You ought to specially familiarize oneself with some of the eviction moratoriums released because of to the coronavirus pandemic. 

Request you how extensive you can afford to pay out the house loan and home fairness loan on your major home in addition to any loans you may well have on the expenditure residence. If you simply cannot find the money for to retain people payments with out any rental cash flow for in excess of a calendar year, then having out a dwelling equity financial loan to devote in rental authentic estate could cause you to get rid of your dwelling. Make sure you’re relaxed with that stage of chance for the potential reward of passive money just before you acquire out a household equity personal loan.

Can I Get a Tax Deduction for My Property Fairness Bank loan?

You can only get a tax deduction on the fascination portion of your home equity financial loan on the quantity utilized to invest in, create, or significantly make improvements to the borrower’s house the property equity financial loan is based on. If you’re utilizing a home equity financial loan to devote in a individual home, you can not get a tax deduction.

Is Investing in Genuine Estate Risky?

All investing is risky, but serious estate investing carries its very own pitfalls. The home you’ve invested in could minimize in value about time. If you are investing in property and leasing it out, your property could be harmed by tenants or you could confront lengthy intervals of nonpayment even though you go by the pricey procedure of evicting anyone.

Can I Use a Dwelling Fairness Financial loan to Spend in a REIT?

You can use your residence fairness loan’s proceeds on anything you like, which includes investing in a authentic estate investment decision have faith in (REIT). Investing in a REIT can be a way to mitigate some of the dangers of particular person actual estate investing, but they have occur underneath latest fireplace for shopping for up attributes in parts and contributing to the housing crisis. In addition, eroding your home’s fairness to invest carries the danger of foreclosures if you just cannot find the money for to fork out again your home fairness financial loan.

Which Is Improved for Investing, a Household Equity Bank loan or a HELOC?

That depends. If you only intend to devote in a single residence and you know the correct amount necessary, a home fairness personal loan will most probable have a reduced desire fee in excess of time than a house equity line of credit rating (HELOC). If you intend to devote in several properties over time, a HELOC enables you to pull fairness and pay it off a number of moments with just one product and is much more hassle-free than taking out and having to pay off numerous residence equity loans above the similar time time period.

The Base Line

Investing in real estate was a lot easier to earnings from more than the very last few a long time than it is very likely to be in the potential. Though a person on TikTok could have doubled their cash flipping properties in the previous two years, any person who invested all through the housing crisis of the early aughts will notify you it is not simple in a slower marketplace. Master as a great deal as you can about genuine estate investing and make absolutely sure you have the cash to deal with downturns or very long durations of zero rental income. If you simply cannot, really do not threat the roof about your head with a household equity bank loan to invest in actual estate.

Vesta Equity launches real estate-backed NFT platform on Algorand

Vesta Equity launches real estate-backed NFT platform on Algorand

Today marks the launch of Vesta Equity, a true estate financial investment corporation with a twist. 

The platform charges itself as the world’s very first peer-to-peer market for serious estate-backed NFT belongings. 

It permits homeowners who have bought their residence outright to provide off a part of it as a tokenized, fractionalised, NFT — which is packaged as a security. 

CEO Michael Carpentier, who started performing on the concept a very little more than two a long time back, states the advantage of the product is that you can accessibility the price of your household without getting to remortgage it or offer it. 

This also indicates an trader anywhere in the world can theoretically reward from the appreciating worth of true estate if charges increase. 

Two frenzies in a person

The platform’s start will come at a frenzied moment in the true estate sector. In accordance to the Nationwide Affiliation of Realtors, as individuals seemed to move amid pandemic lockdowns, the median home sale price for a US residence was $346,900 in 2021, up 16.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2020. This was the highest on report going again to 1999. Property sales experienced the strongest calendar year given that 2006, with 6.12 million houses bought, up 8.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the 12 months in advance of.

“Investors can take part by purchasing into the foreseeable future appreciation of the house and establish a portfolio of real estate belongings like they do with stocks,” says Carpentier. 

People interested in investing can browse a searchable marketplace, make features for wished-for belongings, and “leverage liquidity” on the secondary market, or in the party of the standard sale of the assets. 

Vesta argues that this building democratizes prosperity development by furnishing unhindered accessibility to the value locked into the actual estate market. 

Comparable arguments have been built right before by crowdfunding players in serious estate, on the other hand the use of NFTs has been introduced into enjoy right here due to the velocity of execution on Vesta’s blockchain of alternative, Algorand. 

Carpentier suggests the choice arrived down to the reality that Algorand is immune to forks, offers instant finality on profits, which typically distinct inside four seconds, as very well as having reduced costs. 

The system is hunting into potential styles where by an NFT could be employed to obtain an proprietor out of their home loan or constructions for initially-time consumers looking for choices other than credit card debt financing. 

“The model will evolve and adapt to scale-up to other use case purposes,” Carpentier said. 

Vesta expects to have unfold across the US inside of 12 months, just after an initial start in California. Houses in a range of other states will also be readily available on the platform on start. 

“There will be an training method with owners in which we will have to clarify to them the proposition,” mentioned Carpentier. 

The proposition for proprietors

A single these home owner, who has listed his Las Vegas household on the system, is Mike Pitcher. As another person who experienced dabbled in genuine estate investments in the earlier, Pitcher had been on the lookout for a blockchain resolution.

He argues that from a buyer’s stage of see, this composition is effective mainly because you can get smaller sized parts of the asset, which is not attainable beneath ordinary instances in authentic estate. 

So far, NFTs have been concentrated mainly on tokenizing electronic property, nonetheless a modern wave of initiatives have set their sights on true-environment applications. 

Before in February, Propy, a genuine estate blockchain enterprise, offered its first assets in the United States. 

The sale drew interest for the simple fact that, as section of the offer, the owner gets a non-fungible token as electronic evidence-of-ownership. 

As observed by the Tampa Bay Instances, the condominium was beforehand owned by Leslie Alessandra, founder of a crypto company named DeFi Minimal. Amongst other homes, the sale of a apartment in Florida less than related conditions is forthcoming.

Carpentier states that he would not want to exclude potential buyers or persons interested in the marketplace by only pushing the blockchain angle of the solution. It has to be obtainable and usable initially, he reported. 

“You don’t care about the technology in your cell phone — regardless of whether it is 5G or 4G, you don’t care how the digicam works,” he mentioned. “You just want to know that it operates, and that is particularly the approach we’ve taken.”

© 2022 The Block Crypto, Inc. All Legal rights Reserved. This article is furnished for informational applications only. It is not provided or meant to be made use of as authorized, tax, expense, monetary, or other information.

Considering a Cash-Out? Now is a Great Time as Equity Skyrockets!

Considering a Cash-Out? Now is a Great Time as Equity Skyrockets!

Record home price appreciation in the last few years has pushed tappable home equity to new heights!

According to a report published by data vendor Black Knight this week, the third quarter of 2021 saw a nearly $250 billion increase in tappable equity—a record. With record high tappable home equity, now is a great time to consider a cash out refinance to fund those projects or repairs around the house, start an addition, consolidate high interest debts, or whatever you need the extra cash for.

The report from Black Knight also sheds light on the fact that the aggregate total of $9.4 trillion is up an astonishing 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the same time last year and nearly 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher than the pre-great recession peak in ’06.

That works out to roughly $178,000 available to the average homeowner in tappable equity!

Did you know you can use a cash-out refinance as a way to put a down payment on an investment property? With Griffin Funding Bayside’s DSCR no income investment property loan, you don’t have to show your personal income or tax returns. Qualify simply off the rental income of the investment property.

Considering a Cash-Out? Now is a Great Time as Equity Skyrockets!

Overall, mortgage holders withdrew more than $70 billion in equity in the third quarter, equivalent to just 0.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of available equity entering the quarter, the report said. Year-over-year, more than a million cash-out refis were originated. It’s also notable the the share of cash-out refinances is poised to rise further if mortgage rates continue to trend upward in the next few quarters.

Some cities with the highest concentration of tappable equity in the nation are Los Angeles, San Francisco, San Jose and Seattle. Additionally, the report by Black Knight said that the monthly principle and interest payment to purchase an average-priced home with 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down increased by close to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} since the start of 2021.

The shortage of housing inventory continues to put pressure on home prices, and they will likely continue to rise in the foreseeable future. Even if home prices hold steady, a rise in 30-year rates to 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} will result in the tightest affordability since 2009.

Here are just a few ways to utilize a cash-out refinance:

  1. Build emergency savings
    Having emergency funds can turn a potential disaster into an inconvenience. Emergency examples include an unexpected job loss, car repairs, medical emergencies, or home repairs. Many experts recommend having at least three to six months of living expenses in an emergency fund. Having this amount avoids the stress of scrambling for funds or borrowing money.
  2. Pay off high-interest debt
    With a cashout refinance, you can get funds to pay off your high interest debts. Target the debts with the highest interest rate. The more equity you have, the more cashout you can use. The earlier you pay off debt, the less interest paid over the long run. See how inexpensive it could be to take cash out below.
  3. Increase retirement contributions
    The longer retirement funds are in the market, the more they will compound and grow. So the sooner and more you contribute, the better. By using the equity in your home to take cash out at a low interest rate, you can then invest that money in faster, higher returning investments.
  4. Invest in education
    Getting additional training, education, and professional licenses could make you a strong candidate for getting that next big promotion or raise. You can also use the cash to save or pay for your children’s education. Education isn’t inexpensive, but it’s highly valuable.
  5. Home improvements
    Strategic renovations and upgrades can increase the value of a home. Maybe you have been waiting to start that kitchen remodel or adding on an addition- now is a great time to use the equity you have while rates are still low. Start those much needed renovations or repairs today.
  6. Buy an investment property
    You could use cash from refinancing your primary residence to buy more real estate, such as a rental or investment property. As an asset class, real estate can build wealth quickly because you can leverage your purchase. This is a great way to expand your real estate portfolio. In many cases, homeowners take a cash-out loan on their home and buy a rental property with cash.  When they want to invest again, they do a cash-out refinance on their existing investment property to buy another one. The result is a robust collection of rentals that produce ongoing income and tend to hold their value historically.

If you haven’t already considered a cash-out refinance, now is a great time while rates are historically still very low.

Griffin Funding Bayside is licensed in: Arizona, California, Colorado, Florida, Georgia, Hawaii, Idaho, Maryland, Michigan, Montana, Tennessee, Texas, Virginia, and Washington!

Specializing in VA and Non-QM loans, we have access to wholesale rates and offer to beat or match any rate on the market! Want to learn more? Contact us online or call us at 619-393-8458 to receive your no-obligation consultation.