Midwest is ‘last regional bastion of affordability’ for homebuying, economist says

Midwest is ‘last regional bastion of affordability’ for homebuying, economist says

Zillow Senior Economist Jeff Tucker breaks down the outlook of the housing sector and property finance loan charges subsequent the Fed’s hottest charge hike, including regional household pricing developments in advance of 2023.

Online video Transcript

[AUDIO LOGO]

DAVID BRIGGS: Fed Chair Jerome Powell stating inflation in the housing market place could commence to great by the center of 2023. But will a different 50 stage hike further punish the housing sector? Becoming a member of us now is Zillow Senior Economist Jeff Tucker. Jeff, good to see you. How will today’s decision by the Fed impression the housing sector that the Fed chair stated, quote, “had weakened considerably?”

JEFF TUCKER: Yeah, you know, modern announcement was not a surprise in terms of the true 50 foundation stage hike. So I think that information of a little bit getting his foot off the brakes experienced been priced in for mortgages and 10-year treasuries presently. So it even now would seem like a small action in the ideal path. We have found that 10-12 months Treasury operating its way down from more than 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 3 and 1/2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

And critically for housing, that has introduced the property finance loan amount down on a 30-yr home loan from about 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} back down to about 6 and 1/3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That’s genuinely important progress in conditions of improving upon affordability for homebuyers. And this– it truly is a prolonged road for us to get back again from this high-inflation, large-level setting to a extra gradual and continuous minimal-inflation, significantly less-high-priced atmosphere. And we are generating progress in that way at this moment.

SEANA SMITH: Jeff, you described the development that we’re making, the drop in mortgage premiums. Do you assume that decline to continue on? And the place do you believe premiums are headed then if, in point, we do see that drop go on?

JEFF TUCKER: I consider that is the foundation circumstance state of affairs proper now. We are viewing a ton of products inflation kind of turning the corner. And we have a whole lot of motive to count on shelter inflation also to convert the corner in the new year. The Zillow lease index year-over-calendar year expansion peaked again in February. That can take time to move by means of to the CPI lease index.

So we hope sometime in the first or next quarter to essentially see that commence to decelerate on a 12 months-in excess of-12 months basis. Which is the one major part in providers in the CPI. So placing that all together, I imagine the base circumstance has to be that inflation form of proceeds on this trajectory downward.

So what does that do to mortgages? I assume that does convey us back into the 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} variety about the program of 2023. The far more optimistic situation is that we make a ton of progress towards the lower close of that assortment. The fewer optimistic scenario is that we conclusion up stalling in the higher 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}– upper 5-stage some thing p.c selection for home loans.

DAVID BRIGGS: Yeah, it seriously is tough to visualize rates receiving substantially below 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In phrases of housing rates, what is your prediction for ’23?

JEFF TUCKER: Yeah, our forecast correct now seeking a calendar year ahead is for charges to slide by probably fifty percent to 1 percentage place from now, 12 months forward. Both way, it is really about flat. I know there are a lot more bearish forecasts out there of much more substantial price tag declines.

I assume the amount a single element in our product halting us from that prediction is the very low inventory. Inventory has not constructed up in a massive way. A lot of sellers are just remaining place in their residences. So it basically indicates out there in the market, you you should not see a glut of properties for sale. That has sort of assisted preserve a lid on some of individuals procedures the place rates actually begin to fall swiftly.

There is definitely regional color to this, of system, wherever West Coastline markets and some of the Inland West, like Phoenix and Las Vegas, they’ve already fallen perhaps near to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a peak again in about May well or June. And I feel they nonetheless have a tiny bit of home to occur down. But at a countrywide amount, we just really don’t see this type of inventory tension of forced sellers or actually inspired sellers. If anything at all, sellers are determined, type of continue to be set, hunker down, and keep warm by their 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} house loan that they locked in back again in 2021.

SEANA SMITH: Jeff, what does all this indicate then for the rental sector since value is even now significantly larger year-about-12 months? I guess, on a month-in excess of-thirty day period foundation, you happen to be starting up– the info that Zillow put alongside one another starting off to see some enhancement. So what does that imply in phrases of rental charges? And how very long until we see that reflected in the CPI details?

JEFF TUCKER: Yeah, we have viewed rents– asking rents actually start out to decrease month-around-thirty day period in the very last– fundamentally this wintertime, even over and above the standard seasonal trend. So it appears to be like like there is certainly a little bit of suggest reversion the place that rent advancement is cooling down seriously sharply. That is good information for renters. It’s good information for the inflation steps.

But it really is actually at least a 12-month lag from that slowdown in our asking lease index filtering by to CPI for lease and owners’ equivalent hire. It is challenging to say, but I assume possibly the finest-situation state of affairs is that February could transform out to be the peak for 12 months-more than-yr CPI hire advancement. That would just be 12 months following our hire index peaked. There could be a little bit of a lag, maybe it really is sometime in the spring. But we do know this is presently bringing reduction to renters both getting renewal– renewal letters or going out there contemplating a new condominium to shift into this winter season.

DAVID BRIGGS: Yeah, fascinating, truly, to see where by they are slipping the quickest. New York and Seattle among the the best 5, not exactly where you usually expect it. Speaking of regions, the Midwest seems to be the ideal put for 1st-time homebuyers, according to Zillow information. Why so?

JEFF TUCKER: It is really all about affordability. Affordability has been holding again the housing industry, particularly keeping again property income quantity all close to the place. That 1-two punch of value appreciation and higher mortgage prices usually means that sites like Seattle, New York, Miami, that house loan is just out of access for a significant swath of homebuyers at the second.

So we seemed about the region and in which is the previous type of regional bastion of affordability? It truly is the Midwest. These are places wherever center-class families’ cash flow is nevertheless more than enough to qualify to invest in a good relatives-sized dwelling. Nobody likes having to pay bigger curiosity, even in the Midwest, but there is a ton much more people who can qualify to get a home there and where it really is even now seeking like they’re just in a very good posture to obtain in individuals marketplaces.

I considered it was putting, also, that people had been some of the exact markets you just highlighted exactly where lease is now increasing the quickest. These are the markets in which younger folks environment out searching for a area of their individual, regardless of whether renting or obtaining, they’re acquiring a lot more opportunity sort of in the heartland, in the Midwest, and the Great Lakes regions. So in phrases of housing industry action, that is in which we assume it to be the busiest in the calendar year in advance.

SEANA SMITH: Jeff, what about the traits of purchasing with household and buddies? That’s one thing that stuck out to me. A great deal of us questioned it, irrespective of whether or not which is a sensible financial thought. I will not want you to weigh in on that. But that momentum seriously, I consider, just alerts particularly what is actually heading on in the housing industry right now and the truth that so many very first-time homebuyers basically are unable to afford it no matter the place they are in the nation.

JEFF TUCKER: Which is certainly correct. It comes again to affordability. And this is a technology of People in america getting into their mid-30s now. The core of the millennial era is pretty several. There are numerous million added individuals in their early 30s and late 20s ideal now, and they are just as decided as preceding generations to get into homeownership, but they are working into the greatest affordability obstacle in a generation, maybe that we have at any time seen, thanks to that a person-two punch of selling prices and property finance loan charges.

So people are having inventive. They’re contemplating of other techniques to get into homeownership. We have seen some other type of life milestones are delayed for the millennial technology, issues like relationship and possessing young children. So that type of creates this circumstance in which there are folks in their early 30s or late 20s who may well assume, Alright, how about if my dad and mom go in on a home with me?

How about if my good friends and I go in on a home with each other? We’ve acquired a location to are living. We know that the price tag– you know, that our month to month rent just isn’t heading to keep heading up like if we continue to be in the rental market place. So it’s form of folks searching for methods to get into homeownership.

And I’m unquestionably reassured that the way that they are accomplishing it is not what we did in 2005 and 2006 with ninja loans and no underwriting and balloon payments. Home finance loan underwriting is still rock reliable and pretty strict, frankly, for homebuyers. Which is why men and women are seeking at these strategies of just considering, Ok, who can I invest in a property with if I can not just do it by itself correct now?

SEANA SMITH: I never know. It however sounds a little bit dangerous to me just in conditions of proudly owning a household with close friends or other household customers. I will not know. It’s possible I am an outlier there. Jeff Tucker, wonderful to have you. Many thanks so substantially for becoming a member of us this afternoon.
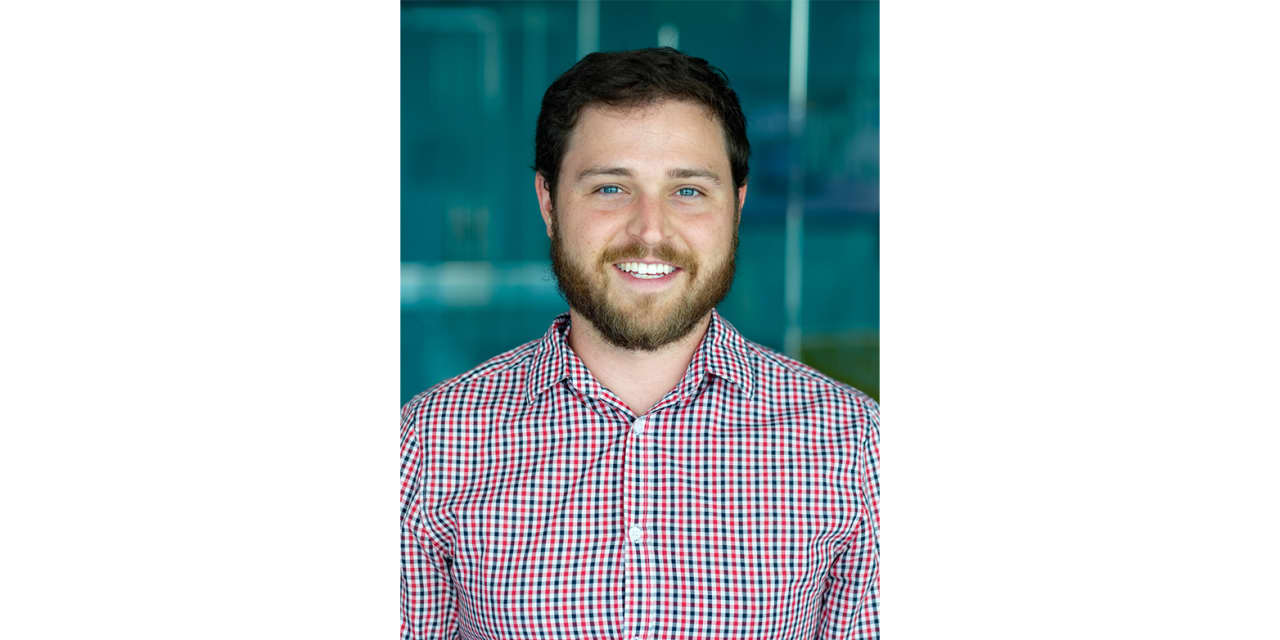
I’m a senior economist at Zillow. Here are 3 things home buyers should know about the housing market now

I’m a senior economist at Zillow. Here are 3 things home buyers should know about the housing market now

In this sequence, we ask a assortment of authentic estate economists what they assume potential buyers and sellers should really know about the housing sector now.


Jeff Tucker

House charges have been on a continuous climb upward, as have property finance loan premiums (you can find the cheapest fees you might qualify for listed here), and several People who are pondering about shopping for are no doubt wondering: What ought to I anticipate? So, as portion of our sequence the place we communicate to genuine estate economists about the housing marketplace now, we requested Zillow’s senior economist, Jeff Tucker — who has put in the the past 10 years studying the forces shaping the American housing market, like domestic formation, homeownership and housing offer — to share his perspective.

Prospective buyers need to put together for higher month-to-month expenses

There’s no question that home finance loan prices are climbing immediately just after hitting a file small in 2020 and remaining around 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for a 30-12 months home loan for substantially of the earlier two yrs, holding payments in examine. But 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} mortgages are a detail of the earlier. “Now the normal 30-yr level is over 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, which usually means much bigger month to month costs for any provided acquire value. Browsing around for a home loan to come across the finest fee can bring sizeable price savings and employing a property finance loan calculator can assistance a buyer keep up to date on what they can afford,” suggests Tucker. (You can find the cheapest home loan rates you may qualify for in this article.)

Even with growing charges, there is nevertheless a large amount of levels of competition in the current market

Certainly, need is still sky superior. The median vendor is accepting a acquire offer you considerably less than one particular 7 days just after listing their home for sale, says Tucker. “There will be a place when the charge of acquiring a dwelling deters adequate prospective buyers to carry price tag expansion back again down to Earth, but for now there’s lots of fuel in the tank,” states Tucker. 

What’s far more, need should continue being significant thanks to generational demographics, he says. “There’s a significant wave of millennials ageing into their prime residence-getting many years and newborn boomers are additional energetic in the housing market than earlier generations. And stock has a extensive way to capture up from a lot more than a ten years of less than-creating next the mid-2000s housing crash, which means source and desire realities will keep pressure on charges for the foreseeable long run,” suggests Tucker.

He provides that even even though the spring home buying time is here and extra households are staying detailed, inventory is continue to exceptionally low. The lengthy-awaited seasonal inventory increase at last arrived in March just after six consecutive months of slipping inventory, he claims: “But inventory was much less than 50 percent what it was in March 2019.”

For the reason that it’s still a seller’s market, purchasers should really anticipate level of competition for residences they’re intrigued in. “Being well prepared with financing and ideally receiving pre-accepted from a loan company not only can give a purchaser additional certainty about what they can find the money for but it presents sellers more self-confidence in the offer which can thrust that offer you above the major in a competitive condition,” suggests Tucker. (You can obtain the least expensive home finance loan fees you might qualify for here.)

Property selling prices may possibly amazing, but they probably won’t fall

Nonetheless, he states this is not a bubble and he does not assume residence costs will drop. “The mix of more new residences becoming developed, bigger rates and rising home loan prices should really assist toss chilly h2o on the market in the around foreseeable future.” claims Tucker. This will direct to a cooldown in rate expansion, but not a selling price drop, he predicts.

If you are seeking to acquire now, Tucker claims it is important to determine out a funds for the utmost total you ready to shell out on a residence. “The the greater part of residences are now offering previously mentioned checklist cost, so customers really should give on their own some area to escalate from competing gives if required. Usually, they threat getting shut out repeatedly, losing valuable weeks of difficult property browsing hard work,” states Tucker.

I’m the chief economist of Redfin. 5 things to know about the housing market now

I’m the chief economist of Redfin. 5 things to know about the housing market now

Redfin main economist Daryl Fairweather shares her feelings and predictions on the housing industry.

Peak dwelling-obtaining period is in full swing, and lots of aspiring consumers are asking yourself: What need to I know about the housing market place if want to buy? After all, interest fees have been soaring, with some pros declaring that pattern will go on (see the cheapest home loan fees you can qualify for below) household prices preserve climbing and there are not plenty of properties on the sector to meet buyers’ need. So we questioned Daryl Fairweather — Redfin’s main economist, who also labored at the Boston Fed studying why householders enter foreclosure — to share her projections and feelings for what potential buyers and sellers can count on in the coming months.

There are early symptoms that the sector, in some sites, is cooling a bit

Fairweather says we’re viewing early symptoms that the housing market place is setting up to neat, at the very least in pricey coastal metros. “Buyers in marketplaces like Los Angeles, San Francisco, Boston and Seattle who have missing out on many bidding wars may possibly find they’re experiencing a lot less level of competition from other purchasers than they had been a month or two in the past,” claims Fairweather.

Also see: This story is element of a series where we ask popular true-estate economists about the housing sector. Here’s what the senior economist for Real estate agent.com informed us about the housing current market now.

For this cause, if you’re a nearby property hunter in a well-known migration spot like Nashville, Tenn. Atlanta or Miami, you must expect levels of competition from California and New York buyers who are likely to have greater housing budgets. “In Nashville, the ordinary out-of-towner has a housing funds that is practically 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher than the ordinary spending budget for neighborhood customers,” states Fairweather.

Mortgage loan premiums could proceed to rise in the near expression

It’s no key that interest rates are climbing quickly — and, thanks to soaring premiums as effectively as increasing property charges, regular property finance loan payments are up 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a yr ago. “I hope fees will proceed to rise in the close to time period so potential buyers who never however have a home loan rate locked with a lender must variable that into their budget,” states Fairweather. (See the lowest home finance loan premiums you can qualify for below.)

House-selling price development could slow before long

As for residence-value expansion, she expects a slowdown shortly, provided growing property finance loan fees. “I really do not believe household charges will go down, but purchasers may be relieved to know that the double-digit yr about calendar year rate expansion we have been suffering from is very likely to fall into the one digits in the coming months,” suggests Fairweather.

But this will not be universal in every single market place: Preferred Solar Belt migration places are likely to be the most resilient, meaning value development will likely keep on, but, in common, house-rate progress will start off to harmony out, according to Fairweather

Rents are also quite superior, so this could possibly not be the most effective time to shift

Buyers who are at present renting must also beware that rental asking price ranges are soaring. “They were being up 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} nationwide in March and as substantially as about 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in places like Austin, Texas, and Portland, Ore. If you make your mind up to pause your residence lookup for any purpose, keeping in your present lease could be a much better choice than going to a new rental residence,” claims Fairweather. This is due to the fact, she says, landlords are usually much less likely to increase rents as aggressively for present tenants as they do on freshly vacant models.

Emphasis on what matters when shopping for a dwelling

In this difficult marketplace, Fairweather suggests household potential buyers not get hung up on beauty particulars that are comparatively simple to replace or repair like paint color, cabinet hardware, out-of-date appliances and mild fixtures. “It can guide to a lowball offer you on a residence that would otherwise check out all your boxes, and, in a market where about two-thirds of gives confront bidding wars, it can value you the property,” says Fairweather. Instead, focus on the matters that subject more, like spot, square footage and layout — you can make cosmetic improvements at any time as soon as you possess the household. 

I’m the senior economist for Realtor.com. 5 things to know about the housing market

I’m the senior economist for Realtor.com. 5 things to know about the housing market

George Ratiu is the senior economist and supervisor of economic research at Realtor.com.


Real estate agent.com

For a lot more than 15 a long time, George Ratiu has been researching the housing current market. He’s the senior economist and manager of financial investigate at Real estate agent.com, the place he focuses on trends in global economies and real estate markets. He’s also a previous supervisor of investigation courses at the National Association of Realtors, where by he specialized in housing figures, global and industrial real estate current market general performance and additional. (Realtor.com is owned by the identical father or mother organization as MarketWatch.)

So we questioned Ratiu: What do buyers have to have to know about the actual estate market place now? (See the lowest mortgage loan fees you could possibly qualify for in this article.)

1. Home loan rates will likely continue on to increase

“The surge in rates pushed the monthly mortgage payment for a median-priced house $550 increased than a yr ago, a substantial enhance thinking of that most households are also emotion the squeeze of higher rates for food items, gasoline, cars and trucks and garments. Just as importantly, prices are envisioned to go on rising as the Federal Reserve tightens credit history movement,” says Ratiu, who predicts that if the tempo of improves continues, we could before long see a 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} charge on 30-12 months loans. 

2. There aren’t enough houses for sale — which tends to make your alternatives far more restricted

One thing to continue to keep in mind is that inventory remains limited as the range of homes for sale is still down below last yr when customers were competing intensely. “The principal explanation for this scarcity is the truth that builders have not matched the tempo of development to populace and residence development more than the previous ten years,” states Ratiu. In point, there’s a shortfall of virtually 6 million houses, according to investigation from Real estate agent.com, and that helps make it tough to come across more than enough homes for all the customers wanting for a residence.

3. House prices will possible keep likely up in a lot of markets, but not practically as rapid

Ratiu predicts that costs will also continue to improve thanks to the point that there are even now more purchasers than houses for sale. “In quite a few marketplaces across the state, potential buyers are obtaining that they might nevertheless be outbid by somebody with a money give or a larger down payment,” claims Ratiu. 

But owing to sharp improves in curiosity prices and inflation, he says we’re nearing the major of the selling price progress curve. “In some markets, sellers are acquiring that buyers are commencing to commit more time seeking and are considerably less inclined to waive contingencies, insisting on house inspections and asking owners to deal with a property’s shortcomings,” claims Ratiu. What’s additional, he says in about a dozen cities across the region charges have declined above the earlier few months, an sign that the market place is beginning to return toward far more stability.

“We can count on price ranges to carry on soaring in the months forward. For individuals, the base line is that larger expenditures are leaving a lot less dollars in their pocket at the stop of each individual thirty day period, just as rents and property prices proceed mounting at double-digit costs,” claims Ratiu. 

See the cheapest mortgage loan charges you might qualify for right here.

4. Sellers will nevertheless have an benefit, but it won’t be pretty so excessive

Sellers are probably to retain the upper hand in most marketplaces throughout the place. On the other hand, their gain is setting up to wane supplied the mix of high selling prices and better fascination fees — which are pricing thousands and thousands of buyers out of the market. Ratiu claims the slowdown in need is recognizable as gross sales of both new and existing households have been declining above the past couple months. “Twenty per cent of home owners indicated that they prepare to shift forward with pandemic-delayed options this year and list their qualities for sale. The enhance in source will guide to more competitiveness amid sellers, shifting the market place additional in the direction of buyers,” states Ratiu.

5. Don’t permit FOMO land you in a dwelling you do not love

The principal takeaway for prospective buyers this yr is that housing markets are currently in a apparent transition from the frenzied tempo of 2021. With economical and economic pressures mounting, Ratiu says it is essential not to allow the worry of missing out direct you into hurrying what’s the greatest buy of most people’s lives. “The rate of new design is buying up, more property owners will be completely ready to checklist their homes and with mounting fascination charges, costs are by now adjusting to the slowdown in demand from customers. Patience is generally viewed as a advantage and may perhaps also be a critical component in this year’s search for a property,” suggests Ratiu.

Fannie Mae’s economist, and real estate pros, give advice to aspiring homebuyers

Fannie Mae’s economist, and real estate pros, give advice to aspiring homebuyers


Getty Illustrations or photos

The housing marketplace isn’t an uncomplicated matter to pin down — and you’re not alone if you are feeling like you’re acquiring blended messages on the issue. On the a person hand, property finance loan costs are in the vicinity of historic lows — some 15-year premiums are in the vicinity of 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and some 30-12 months charges are below 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, as you can see here — and quite a few industry experts predict they will increase in the coming calendar year. But on the other, housing price ranges are on the increase, and in a lot of areas have turn into unaffordable for quite a few regional families. Those things are creating some possible homebuyers ponder: Ought to I purchase now?  So we asked Doug Duncan, Fannie Mae’s senior vice president and main economist, and some other authentic estate execs, their ideas on what is heading on with the housing market place and irrespective of whether now is the time to buy.


Property finance loan rates stay minimal, but industry experts forecast they will rise

A latest study of housing gurus revealed by Zillow exposed that execs expect curiosity premiums to increase to 3.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} at the conclude of 2022, and for its section, Fannie Mae predicts that desire prices will average approximately 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022, up a bit from this calendar year. Authorities we spoke to claimed the identical: Kate Wooden, property and house loan skilled at NerdWallet, states we may perhaps see a “long-long lasting upward trend” in home finance loan costs, and Greg McBride, chief money analyst at Bankrate, notes that appear 2022, the basic development will be toward larger costs.

It is nevertheless an particularly aggressive sector, but “things aren’t as frenetic as before in the year”

Residence selling prices have risen approximately 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the earlier 12 months — and most experts consider they will continue to increase, albiet at a slower pace — but demand from customers for properties is however large: “While economic uncertainty could likely dampen home loan desire over the for a longer time expression, we believe latest market place problems continue being conducive to house acquire exercise, as demand from customers for houses carries on to far outstrip the source accessible for sale,” Fannie Mae’s Duncan claims. 

There are symptoms that the marketplace is moderating, if only a little little bit. “There’s been a little bit extra inventory of houses accessible for sale to arrive on the sector and items are not as frenetic as earlier in the year, but this is nonetheless a extremely incredibly hot housing marketplace the place demand far exceeds provide in most markets,” claims McBride. 

End striving to time the marketplace wanting for the excellent time to get, instead concentration on your particular conditions

Fannie Mae’s deputy main economist Mark Palim suggests timing house loan costs and the housing market place is really hard, and in its place suggests potential buyers appear at their have would like and requires. “They need to concentrate on private existence situation and how lengthy they consider they’ll be in the location,” suggests Palim. If you have locational security and prepare to be in the property for 5 many years or additional, Palim suggests getting in its place of renting very likely would make the most feeling. But comprehend what you can genuinely manage, and do not get caught up in the genuine estate frenzy: “Making the largest economical determination of your everyday living under duress is not a recipe for success,” says McBride.

Also see: The very best month to invest in a home