U.S. genuine estate has gone through a extraordinary slowdown in transaction activity in the months considering that the Federal Reserve began jacking up desire fees.
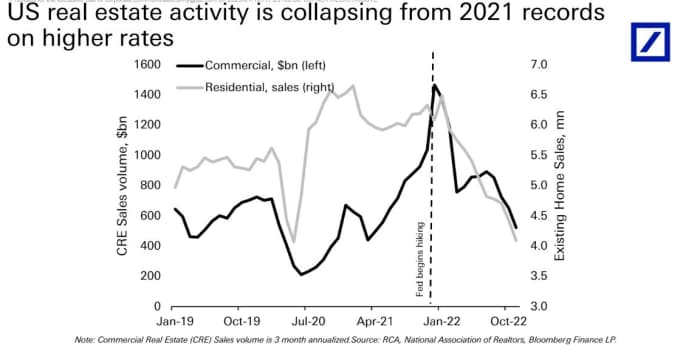
Income of present residences plunged from peak pandemic stages to about 4.1 million in November (see chart) from over 6 million units offered per calendar year in 2021 as the Fed has radically raised desire charges to tame inflation.
U.S. genuine estate transaction quantity has collapse with higher prices
Deutsche Lender, RCA, Nationwide Association of Realtors, Bloomberg Finance
Likewise, the chart demonstrates industrial real estate transactions dropping off a cliff after they rose 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increased than their prior peak in 2019, according to a new shopper be aware from Deutsche Bank investigation.
“Real estate is one particular of the crucial levers the Fed can use to slow the overall economy higher costs are significantly cutting down US authentic estate exercise,” a Deutsche analysis team led by Ed Reardon wrote in a weekly market place briefing.
They also mentioned that property finance loan premiums of about 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in both sectors will let the Fed “to unwind some exuberance” in the housing marketplace, exactly where charges climbed about 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} considering the fact that March 2020 and around 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in commercial actual estate.
Connected: The occasion is more than in professional genuine estate. Here’s what to expect in 2023.
The Fed started fast increasing its plan desire price from in close proximity to-zero in March to assist convey inflation that peaked above a 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yearly rate this summer time nearer to its 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} goal. Its federal cash level was increased to a 4.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 4.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} vary in December, the optimum given that 2007, with yet another level bump envisioned in February.
Before this week, San Francisco Fed President Mary Daly claimed she expects the central bank to raise desire costs earlier mentioned 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to get inflation down. A new monthly update on consumer inflation due Thursday is envisioned to clearly show inflation slipping for 6 months in a row to a 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yearly amount.
U.S. stocks have staged a modest rally to commence 2023 as some investors interpret retreating price pressures and moderating wage gains as indicators that the economic system may possibly nevertheless keep away from a economic downturn, even though central bankers hold expressing to hope high prices until finally inflation deeply recedes.
Examine: Inflation is slowing, CPI to show. But is it slowing quick sufficient for the Fed?
The S&P 500 index
SPX, +.34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
was up .7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on Wednesday ahead of Thursday’s inflation reading through, when the Dow Jones Industrial Ordinary
DJIA, +.64{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
was up .4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and the rate-delicate Nasdaq Composite Index
COMP, +8.98{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
was 1.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher, in accordance to FactSet.
“Las Vegas is 1 of the major indicators for [home] selling price motion in the housing market, like we observed in 2008 and the new frenzy. We are completely sensation the warmth here. The consumer pool has, for the most portion, dried up,” Kristen Riffle, a genuine estate agent in Las Vegas, tells Fortune.
But it’s not just bubbly markets like Las Vegas and Boise that are emotion the suffering: This housing downturn is selecting up steam nationwide. In point, as of past 7 days, home loan invest in apps are down 38{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on a calendar year-above-12 months foundation. That marks the most affordable looking through since 2014.
Simply set: Housing activity is crashing.
Let us be apparent, although: This “crash” in housing activity—or as Fed Chair Jerome Powell phone calls it a “difficult correction”—didn’t show up out of slender air. It is by design. The Federal Reserve flipped into inflation-preventing mode this spring with hopes that elevated fascination charges would lead to action to slump in fee-sensitive sectors like housing.
The Fed’s reasoning for slowing the housing market boils down to two words: demand from customers destruction. Historically speaking, property finance loan prices spike as before long as central financial institutions go into inflation-fighting manner. That home loan level shock brings about profits for equally current and new properties to drop. As builders lower back, desire for each commodities (like lumber) and resilient merchandise (like fridges) then declines. It also results in true estate and building layoffs. Those economic contractions then immediately distribute all over the rest of the economy and, in theory, assistance to weaken the labor sector and tame high inflation.
“The most frequent way we enter into economic downturn is the Fed raises rates to battle inflation. The top indicator for this type of economic downturn is housing,” Bill McBride, writer of the economics blog site Calculated Danger, told Fortune this summer. “It [housing] is not the target, but it [housing] is basically the target.”
Of system, we’re by now viewing these housing-spurred financial contractions. Homebuilders are chopping back again. Serious estate companies are trimming headcounts. And some regional housing marketplaces, like Boise and Seattle, have now slipped into a home selling price correction.
“Realtors are feeling it massive-time, as very well. I put in a call to the Bigger Las Vegas Affiliation of Realtors, and the staff I spoke with mentioned that they were averaging about 300 new customers every thirty day period. This month she experienced believed 120 nonetheless, she has been processing about 30 realtor withdrawals a day,” Riffle states. That implies each individual day around 30 genuine estate brokers in Las Vegas by yourself are calling it quits.
Now let us rewind back to the intro of this short article. When analysts say “the Fed will push right until one thing breaks,” they’re implying the Fed’s inflation campaign is going to keep on until finally possibly inflation abates or a little something pushes the financial state into a economic downturn. That “anything” could be distress in the bond sector, or probably liquidity troubles at important economical firms. But there is also expanding worry that the “anything” could be the housing sector.
1981 and 2008
You will find almost nothing unusual about a housing downturn aiding to cause a economic downturn. Search no further than economist Edward Leamer’s 2007 paper titled “Housing Is the Business Cycle.” Leamer observed that 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of post–World War II recessions arrived right after a “substantial” housing slowdown.
But when analysts discuss about housing currently being what “breaks,” they’re talking about a housing downturn not just helping to bring about the recession but becoming the fundamental trigger. The most infamous historical illustrations of this are 1981 and 2008.
Again in the early 1980s, Fed Chair Paul Volcker famously tackled the inflationary run that had commenced in the ’70s. The central bank attained its objective but only following spiking home finance loan rates—which climbed to 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 1981—established a housing downturn so sharp that it drove the overall financial state into recession. Although residence revenue and building degrees both equally cratered, house price ranges really remained fairly stable all through the 1981 housing downturn.
The 2008 housing crash, of system, was a various story. Compared with 1981, the 2000s housing downturn was brought on by a housing bubble. That slowdown began in 2005 right after a collection of Fed level hikes. More than the subsequent many years, it would escalate into a whole-blown housing bust that introduced on the Terrific Economic downturn. Contrary to 1981, the 2000s housing crash was underpinned by a ideal storm of rampant overbuilding, deteriorating household funds, historic amounts of overvaluation, and harmful subprime home loans.
Though the 2022 housing marketplace downturn doesn’t in shape squarely into possibly the 1981 nor 2008 camp, it does share features from every. Just as in 1981, the 2022 housing marketplace has deteriorated in the encounter of a historic mortgage loan price shock. And similar to 2008, the 2022 housing market has after yet again come to be detached from underlying economic fundamentals.
A historic affordability shock. That’s the very best way to explain why the housing market place may be the “something” that breaks.
Every time home loan premiums rise, some would-be borrowers—who will have to fulfill lenders’ strict debt-to-profits ratios—lose their property finance loan eligibility. When mortgage charges spike from 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, it translates into millions dropping their potential to order.
There is certainly no doubt about it: The housing current market entered into a downturn back again in the summer time. That explained, the economic contractions aren’t yet at the degree you would assume to see ahead of a Fed-induced economic downturn.
Something stands in the way: homebuilding.
On a person hand, single-household housing begins are down 18.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on a calendar year-about-12 months basis. On the other hand, homebuilders stay active. A mix of provide-chain constraints and an eagerness to money in on the Pandemic Housing Boom led homebuilders to massively ramp up generation more than the earlier two decades. That backlog is so big, they are however doing work via it. And as extended as builders and contractors continue to be active, it will sluggish down the spike in construction position cuts that commonly occur in advance of a Fed-induced economic downturn.
Heading forward, economists and analysts alike think the housing industry will go on to deteriorate.
This yr, Wells Fargo tasks sharp declines in new-residence profits (-10.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), current-residence income (-7.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), one-spouse and children housing starts off (-7.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and housing GDP (-10.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). Then, in 2023, Wells Fargo expects yet another fall in new-household revenue (-6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), current-house sales (-13.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), single-loved ones housing commences (-12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and housing GDP (16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
If Wells Fargo’s forecast—which also predicts a 5.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop in U.S. house selling prices in 2023—comes to fruition, it would suggest that the housing marketplace downturn reaches a stage that historically occurs only for the duration of economic downturn.
Though the housing downturn appears to be on a trajectory that could press the U.S. financial system into recession, almost nothing is particular. If inflation eases, the Fed could pivot coverage in advance of a economic downturn becomes locked in. There’s also the concept that a significant fall in household investment—which makes up 4.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of GDP—wouldn’t be as impactful on modern significantly less housing-dependent financial state. Although it’s correct that private expense topped out at a much bigger share of GDP in 2005 (6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), we’re truly slightly over the share seen in 1981 (4.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). In other words and phrases, never undervalue housing.
But “recession” or “no recession,” the housing marketplace is plainly experience the pinch of the tightening cycle. It is really tough to see that transforming anytime before long.
“I have literally absolutely nothing underneath contract. I am a long-hauler, but I’d be lying if I claimed I was not anxious,” Kira Mason, a authentic estate agent in Philadelphia, tells Fortune.
Want to remain updated on the housing downturn? Stick to me on Twitter at @NewsLambert.
An economist recognized 7 major threats and threats that could hamper action and growth across residential and commercial residence segments.
In a a short while ago revealed whitepaper, CreditorWatch chief economist Anneke Thompson claimed there are huge photo threats and business unique threats hounding the all round assets industry.
“The hazard for landlords is becoming amplified by the existing financial disorders,” she said.
“As inflation continues to rise, so will the mounting charge-of-residing pressures. The detrimental housing prosperity impact from residence rates slipping will likely signify that demand for discretionary items wanes additional and building and household desire will also weaken as costs rise.”
1. Soaring prices
Ms Thompson reported soaring charges have an clear immediate influence to residential assets.
“The impact to industrial normally takes much more time to expose alone but a different impact will be to business enterprise assurance,” she reported.
“When enterprises feel much less self-assured, they are inclined to pause any huge choices or commitments all around business moves or expense.”
2. Function from household pattern
The most significant effects of the do the job from home pattern on a residential assets standpoint is the exodus of individuals from bigger towns in research of more spacious and laid-back again lifestyle markets in the regions.
On a professional house standpoint, Ms Thompson claimed commercial tenants are progressively becoming hesitant to indication 10-calendar year leases or leases with annual improves joined to inflation.
Central company districts, which are closely dependent on workers, travelers, and intercontinental college students, might take some time in advance of showing signs of restoration.
However, retail strips and local centres could likely reward from this get the job done from residence development.
3. Inflation
Inflation will have various impacts across assets segments, with homes getting far more careful about their shelling out significantly on housing.
Meanwhile, this will have a direct impression on suppliers and landlords in the commercial area.
4. Strength prices
Ms Thompson reported soaring electrical power fees will have a far more sizeable effects on the professional area.
“Rising vitality charges will also be hitting the outgoings bills of workplace, industrial and retail properties,” she stated.
“It is likely that when yearly outgoings budgets are currently being drawn up, a huge improve to vitality fees will will need to be factored in.”
5. Prolonged emptiness
Prolonged emptiness is a person of the marketplace-unique issues buyers confront, significantly in the business phase.
“Current financial ailments expose landlords to far more prolonged durations of vacancy if they have a tenant that defaults or wants to vacate,” Ms Thompson explained.
“Particularly for landlords of CBD retail premises, there will now be less firms that are keen to appear in and occupy area, particularly on recent passing rents.”
On the household entrance, rental source stays limited, which may possibly be much more of a problem for tenants.
6. Tighter credit controls
Credit controls will also pose threats if financial uncertainties persists and triggers main shocks.
“While commercial house is in a monetarily considerably more healthy state now than it was heading in to the GFC, the threat continues to be that financial institutions improve their lending hurdles on industrial landlords if the financial state carries on to worsen,” Ms Thompson claimed.
7. Altering occupancy developments
Occupancy developments will effects the place of work sector the most but any transform to the means tenants lease room would affect the industry step by step.
“Flexibility is the essential term and supplying this in leases will be a major obstacle for the market, as certainty of revenue has been one of the vital causes why traders, and financiers, have favored the sector,” Ms Thompson explained.
“If we do transfer into a environment of, say, shorter leases or a lot more break clauses, this would signify additional threat handed on to landlords.”
Winter PARK, Fla., Jan. 05, 2022 (World NEWSWIRE) — Alpine Income Residence Have faith in, Inc. (NYSE: PINE) (the “Company”) now furnished a portfolio update and announced its record 2021 acquisition and disposition things to do.
2021 Acquisition Highlights
All through the yr ended December 31, 2021, the Corporation obtained 68 web lease retail attributes for a full acquisition quantity of $260.3 million, symbolizing a weighted-regular heading-in cash cap fee of 6.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Acquisitions concluded for the duration of the calendar year experienced a weighted-ordinary remaining lease phrase of 8.2 decades and roughly 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of annualized base rents are from a tenant or the guardian of a tenant with an investment decision grade credit history rating.
All through the fourth quarter of 2021, the Company obtained 26 internet lease retail qualities for whole acquisition quantity of $101.6 million, symbolizing a weighted-ordinary going-in cash cap charge of 6.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Acquisitions concluded in the course of the fourth quarter experienced a weighted-common remaining lease expression of 8.1 decades and roughly 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of annualized base rents are from a tenant or the parent of a tenant with an investment decision grade credit rating ranking.
The fourth quarter 2021 acquisitions are located in 11 states, net leased to tenants operating in 10 various retail sectors, which include the home improvement, sporting merchandise, property furnishings, informal eating, greenback store, ease retail outlet and farm & rural supply sectors, and around 34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of annualized foundation rents are from floor leased homes.
2021 Disposition Highlights
In the course of the yr ended December 31, 2021, the Business marketed 3 web lease properties for complete disposition volume of $28.3 million, at a weighted common exit cap amount of 7.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The sale of the houses created aggregate gains of $9.7 million.
For the duration of the fourth quarter of 2021, the Firm offered its one tenant office homes positioned in Orlando, Florida internet leased to Hilton Grand Vacations for $24.5 million, representing an exit cap amount of 7.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Yr-Stop 2021 Portfolio Update
As of December 31, 2021, the Company owned 113 net lease attributes that ended up 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} occupied and produced $36.9 million of annualized based hire.
The Company’s portfolio at yr-close 2021 had a weighted-ordinary remaining lease time period of 7.8 yrs, somewhere around 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of annualized foundation rents are from floor leased attributes and about 45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of annualized foundation rents are from a tenant or the mum or dad of a tenant with an investment decision grade credit score.
“I’m very pleased with our robust end to a very productive year,” explained John P. Albright, President and Main Executive Officer of Alpine Profits Property Believe in. “The fourth quarter signifies our major quarter of acquisition quantity to-date and associated a selection of beautiful prospects, such as a floor lease portfolio that created up more than just one 3rd of our overall volume. We’re encouraged by the power of our pipeline and confident our portfolio’s solid demographics, very well-executing and defensive retail sectors and interesting actual estate fundamentals placement us for balance and growth as we head into 2022.”
About Alpine Income Property Belief, Inc.
Alpine Profits Assets Have faith in, Inc. (NYSE: PINE) is a publicly traded authentic estate financial commitment belief that acquires, owns and operates a portfolio of higher-excellent net leased homes. For extra data on the Enterprise, be sure to check out www.alpinereit.com.
Harmless Harbor
This press launch could consist of “forward-on the lookout statements.” Forward-seeking statements contain statements that may well be determined by text these types of as “could,” “may,” “might,” “will,” “likely,” “anticipates,” “intends,” “plans,” “seeks,” “believes,” “estimates,” “expects,” “continues,” “projects” and identical references to long run periods, or by the inclusion of forecasts or projections. Ahead-hunting statements are based mostly on the Company’s recent anticipations and assumptions pertaining to capital industry conditions, the Company’s enterprise, the economic system and other upcoming circumstances. Since ahead-seeking statements relate to the long term, by their mother nature, they are subject to inherent uncertainties, threats and improvements in circumstances that are difficult to predict. As a result, the Company’s genuine outcomes may well vary materially from individuals contemplated by the forward-searching statements. Significant factors that could induce real success to differ materially from those people in the forward-hunting statements consist of typical enterprise and economic conditions, continued volatility and uncertainty in the credit rating markets and broader economical markets, challenges inherent in the true estate small business, such as tenant defaults, possible liability relating to environmental matters, illiquidity of serious estate investments and opportunity damages from all-natural disasters, the impact of the COVID-19 Pandemic and its variants on the Company’s enterprise and the business enterprise of its tenants and the influence on the U.S. financial state and market place disorders commonly, other things impacting the Company’s business enterprise or the company of its tenants that are outside of the manage of the Firm or its tenants, and the elements established forth underneath “Risk Factors” in the Company’s Once-a-year Report on Sort 10-K for the yr ended December 31, 2020 and other risks and uncertainties discussed from time to time in the Company’s filings with the U.S. Securities and Exchange Fee. Any forward-looking assertion made in this press launch speaks only as of the date on which it is designed. The Business undertakes no obligation to publicly update or revise any forward-on the lookout assertion, no matter if as a consequence of new info, future developments or normally.
The Company defines “annualized base rent” as the annualized straight-line in-area base hire demanded by the tenant’s lease as of December 31, 2021. ABR is a non-GAAP fiscal measure. We imagine this non-GAAP financial measure is practical to traders since it is a extensively accepted field measure utilised by analysts and investors to compare the real estate portfolios and running general performance of serious estate investment trusts.
Call:
Matthew M. Partridge Senior Vice President, Main Money Officer & Treasurer (386) 944-5643 mpartridge@alpinereit.com