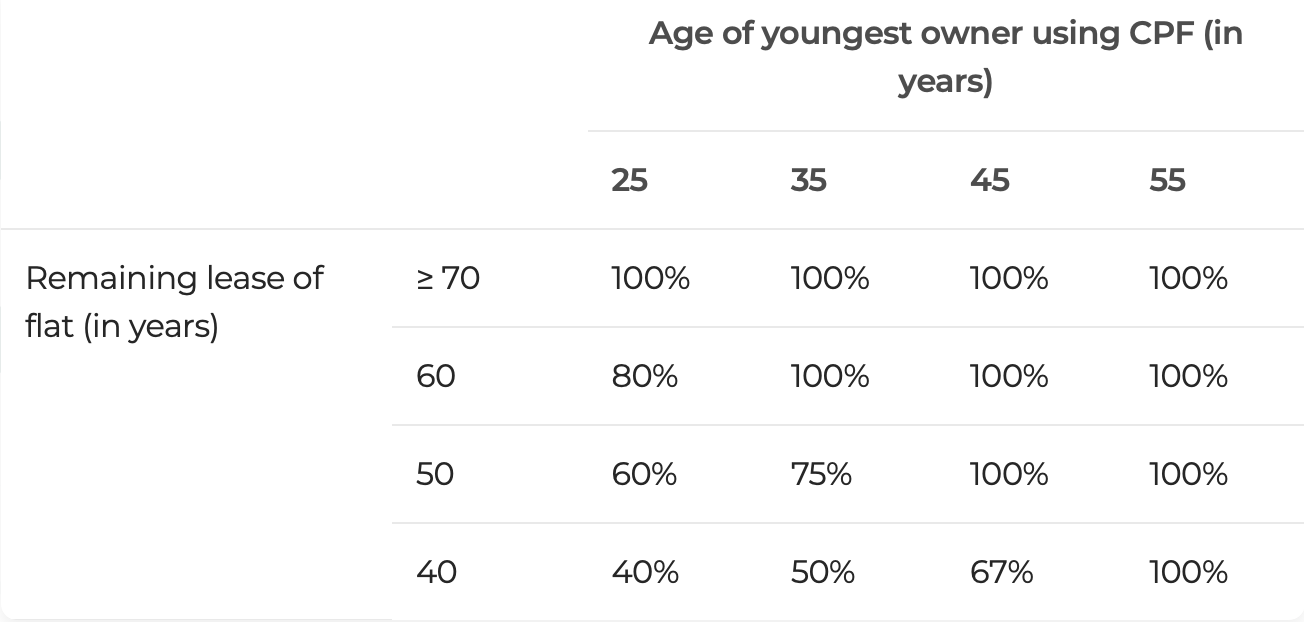Best real estate markets to buy a home in 2023

Best real estate markets to buy a home in 2023

Even with climbing homeownership prices squeezing out customers, some authentic estate markets will continue being sizzling in 2023, primarily due to their relative affordability when compared with the rest of the U.S., a new forecast finds.

The leading places have something else in frequent, also: They are all situated in the South.

Based on a variety of components, which includes residence affordability, job advancement, migration gains and housing provide, the National Affiliation of Realtors (NAR) analyzed 179 markets to decide which will offer the most price to buyers. The facts looks back one yr from Oct 2022 and demonstrates predicted demand from customers from consumers in 2023.

The median rate of properties in some of these markets is not more cost-effective than the countrywide median of $398,500. On the other hand, these cities scored higher on other metrics this sort of as position development or housing source.

Below are the 10 very best places to buy a residence in 2023, in accordance to NAR:

1. Atlanta-Sandy Springs-Marietta, Ga

Median dwelling value: $371,200 

With important tech businesses these as Apple, Microsoft and Visa opening Atlanta workplaces in current a long time, the town has a sturdy occupation sector. 

The Atlanta metro place continues to be rather affordable compared with other regions in the state. About 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of renters can afford to pay for to invest in a median-priced property in the location, based mostly on a calculation that contains a 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment. The nationwide typical is 15.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

2. Raleigh, North Carolina

3. Dallas-Fort Value-Arlington, Texas

4. Fayetteville-Springdale-Rogers, Arkansas-Missouri

Median residence price: $328,400

House to 3 Fortune 500 organizations — Walmart, Tyson Foodstuff and J.B. Hunt Transportation Products and services — this metro location is next amid NAR’s top rated 10 rankings in phrases of housing affordability.

It truly is a escalating market place, as well, with yearly inhabitants expansion of 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — perfectly higher than the national regular of .01{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Properties are also low-cost, with prices 2nd only to Huntsville, Alabama, amid this listing. The share of renters that can pay for the common residence is approximately double the countrywide ordinary. 

5. Greenville-Anderson-Mauldin, South Carolina

Median dwelling price: $335,400

Although housing affordability is on par with the nationwide ordinary, career advancement in this spot is strong, in particular for substantial-shelling out information technological know-how employment like computer programming or world-wide-web advancement. 

There are far more properties to choose from, far too, as the offer of homes in 2022 was extra than two times the national regular. 

6. Charleston-North Charleston, South Carolina

Median house cost: $416,800

Of the top 10 rankings, the Charleston region is 2nd only to Raleigh for the greatest median value for houses. It truly is also down below the national normal when it will come to affordability.

On the other hand, this quickly-expanding marketplace has strong migration gains and work development that is just about 2 times the nationwide regular.

7. Huntsville, Alabama 

Median dwelling cost: $327,500

Alabama’s most populous city is the most reasonably priced location for houses amongst this checklist. Just below 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of renters can afford a typical home with a 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment, which is pretty much twice the national common.

Increasing work opportunities and lower expense of living will go on to appeal to even much more movers in 2023, in accordance to NAR.

8. Jacksonville, Florida

Median home value: $398,000

As with lots of metropolitan areas in Florida, Jacksonville became a migration hotspot during the pandemic, with residence prices soaring by virtually 58{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} considering the fact that the starting of 2020.

Jacksonville’s property costs are practically on par with the median price in the U.S., but it is really extra reasonably priced than other spots statewide, in accordance to NAR.

The qualifying income to order a median-priced residence with a 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment is about $98,000. Which is much less than most big metro regions across the point out, like Miami, the place the qualifying profits with a 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment is $140,000.

Jacksonville also has a powerful occupation current market and a fantastic supply of homes in comparison with the rest of the place. 

9. San Antonio-New Braunfels, Texas

Median dwelling cost: $342,700

San Antonio became a migration hotspot during the pandemic, specially from California, where by home costs and the price of dwelling are inclined to be more expensive.

The city has become a destination within just the state of Texas, far too. Numerous prospective homebuyers have migrated to San Antonio from close by Austin, mainly due to much less expensive dwelling selling prices.

In San Antonio, citizens earning $85,000 qualify for a median priced home, such as a 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment, considerably much less than $130,000 demanded in Austin. Job growth is also more robust than the national ordinary.

10. Knoxville, Tennessee

Why rent in NYC is out of control right now
We make 0k per year and live in a 3-room HDB flat. Should we save to buy an investment property, upgrade to a condo, or larger flat?, Lifestyle News

We make $180k per year and live in a 3-room HDB flat. Should we save to buy an investment property, upgrade to a condo, or larger flat?, Lifestyle News

Hello,

We’ve read with interest on your advice columns, and we especially appreciate the effort and detail put into the responses.

My wife and I are in a bit of a dilemma. 

We live in a 3-room HDB flat in Clementi Ridges which we bought for close to $400k. Our MOP is up in April this year. We’re in our mid-30s and together we make $15,000 gross a month, with no debts other than our HDB loan. We don’t plan to have kids.

Our goal is to have a retirement nest egg; the question is how best to go about building it. We’re not sure if our next move should be to:

(1) Upgrade to a freehold condo – we’re only interested in one located in Districts 9, 10, 11, 20, or 21;

(2) Save up to buy an additional investment property; or

(3) Upgrade to a larger HDB through resale/2nd BTO.

Sincerely hoping you could share some insights to help in our decision-making. Thank you very much!

1) Outstanding loan – $238,000

2) CPF used plus accrued interest – $128,000 from me + $36,000 from my wife

Hi there!

Thanks for reaching out to us!

It’s always good to start the retirement planning process early, as there is a lot you can do to build that nest egg from now till then. With so many possible pathways to take, it can be difficult to decide on the best option.

We will do our best to shed some light on the possibilities and hopefully, it will make your decision-making process a little easier. Let’s start by looking at affordability.

Affordability

These are some of the recent 3-room transactions for Clementi Ridges:


Date Block Level Size (sqm) Price
Oct 2022 312B 19 to 21 69 $615,000
Sep 2022 312A 19 to 21 69 $660,000
Sep 2022 312B 16 to 18 69 $660,000
Aug 2022 312A 13 to 15 69 $608,000
Jul 2022 312A 13 to 15 69 $565,000
Jul 2022 312A 13 to 15 69 $638,000
Jul 2022 312A 22 to 24 69 $642,800

Source: HDB

We will use the average selling price of $626,971 for calculation purposes.


Description Amount
Selling price $626,971
Outstanding loan $238,000
CPF used plus accrued interest $164,000
Cash proceeds $224,971

Affordability (For a private property)


Description Amount
Maximum loan based on a fixed monthly income of $15K and ages 35 $1,728,055 (30 years tenure)
CPF funds $164,000
Cash $224,971
Maximum affordability based on CPF and cash of $388,971 $1,555,884
BSD based on $1,555,884 $46,835
Estimated affordability $1,509,049

Due to the available amount of CPF and cash that make up the 25per cent downpayment, you will not be able to take the maximum loan

Affordability (For an HDB)


Description Amount
Maximum loan based on a fixed monthly income of $15K and ages 35 $852,536 (25 years tenure)
CPF funds $164,000
Cash $224,971
Total loan + CPF + Cash $1,241,507
BSD based on $34,260
Estimated affordability $1,207,247

Option 1: Upgrade to a freehold condo in D9, 10, 11, 20 or 21

With a budget of $1.5 million, you’ll most likely be looking at a 1 + Study or a two-bedder in these locations. As you do not plan to have children, this should suffice but as most of these units are rather compact, it may take some getting used to from a 3-room HDB flat which is typically bigger in comparison.

If you were to do a quick search online, you’ll see that the current pickings are rather slim, and the majority of the developments that fall within this price range are boutique projects.

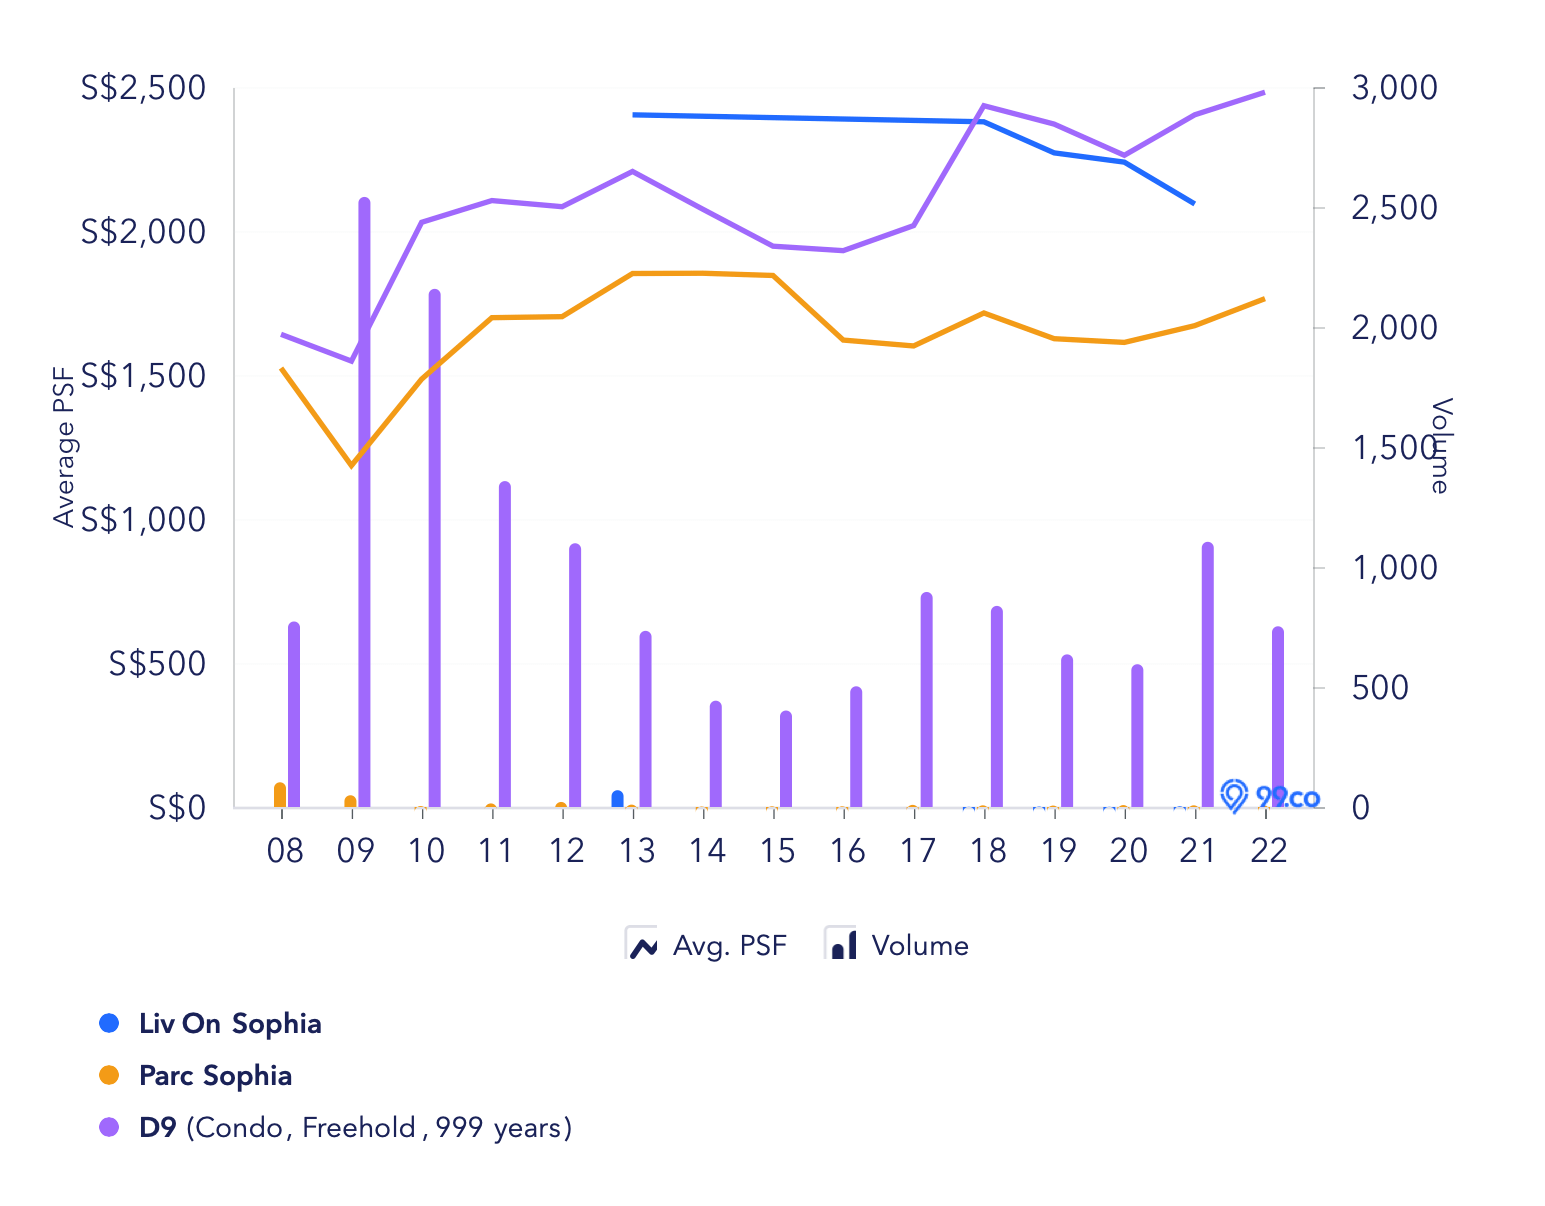
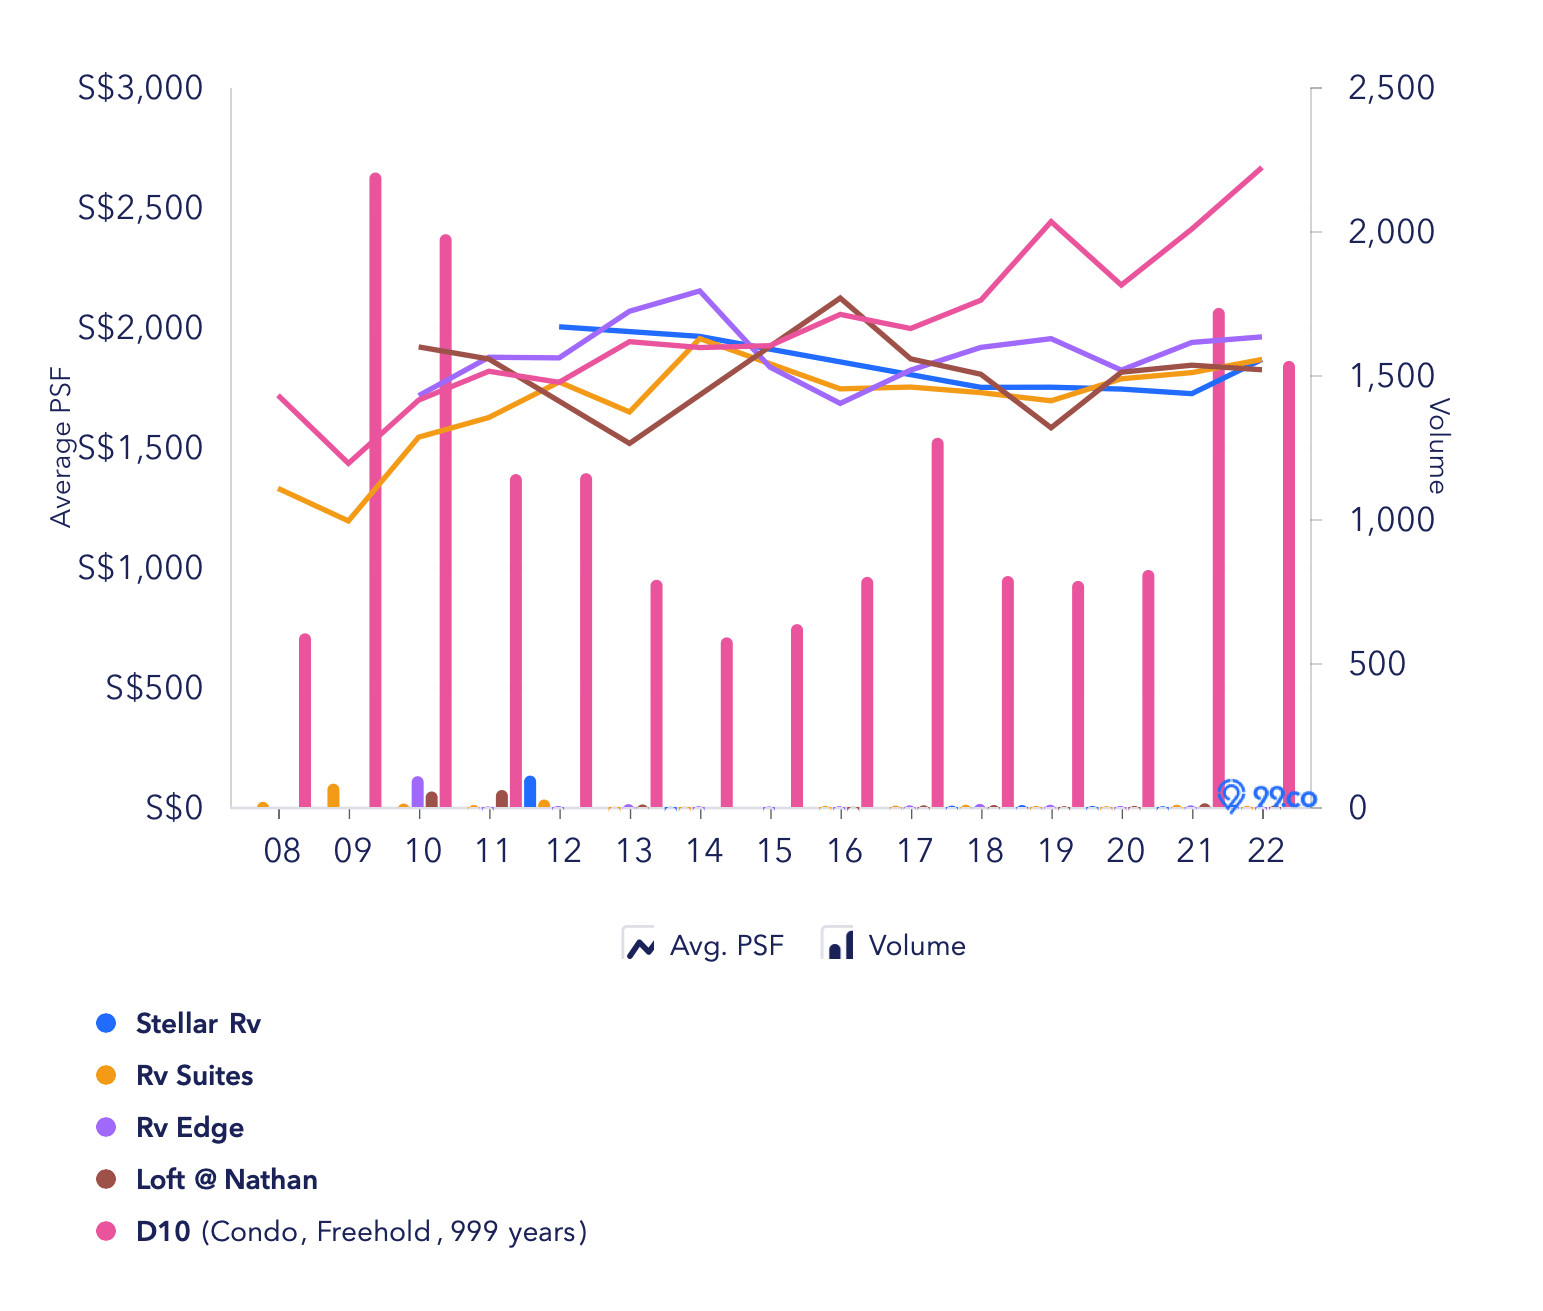
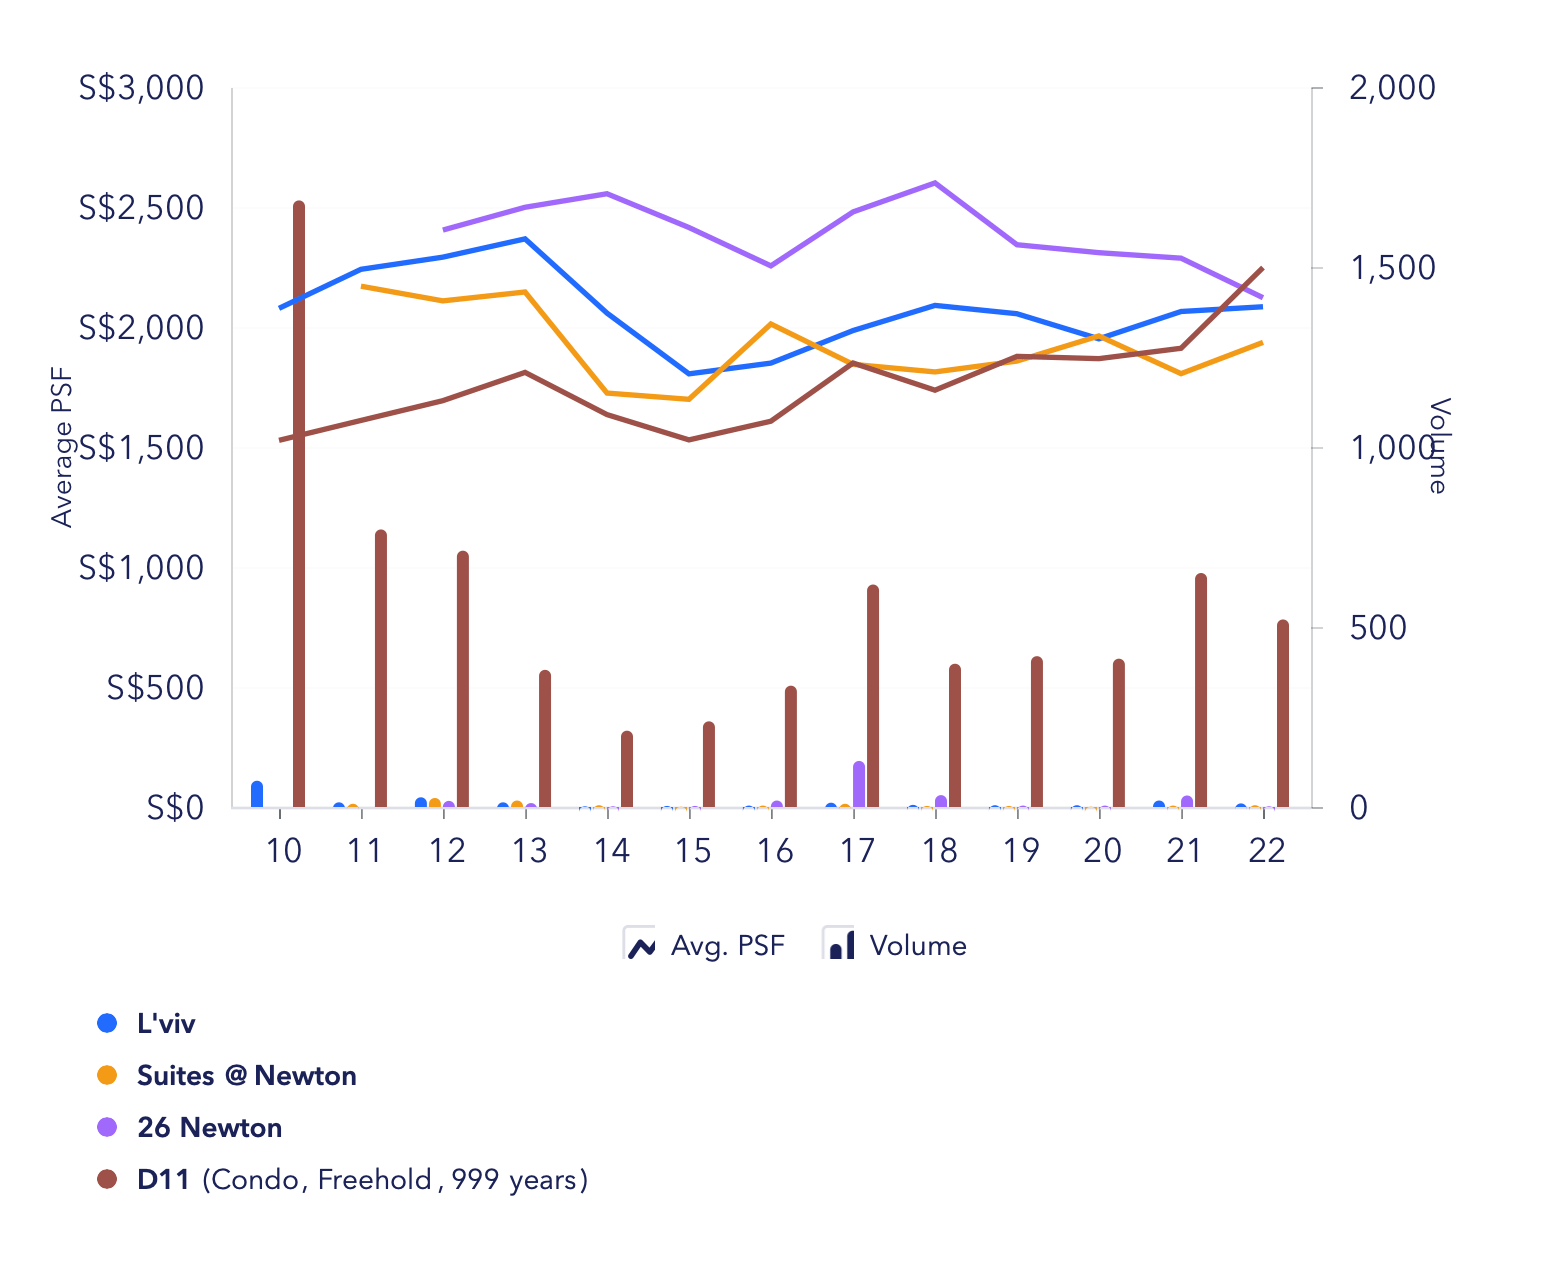
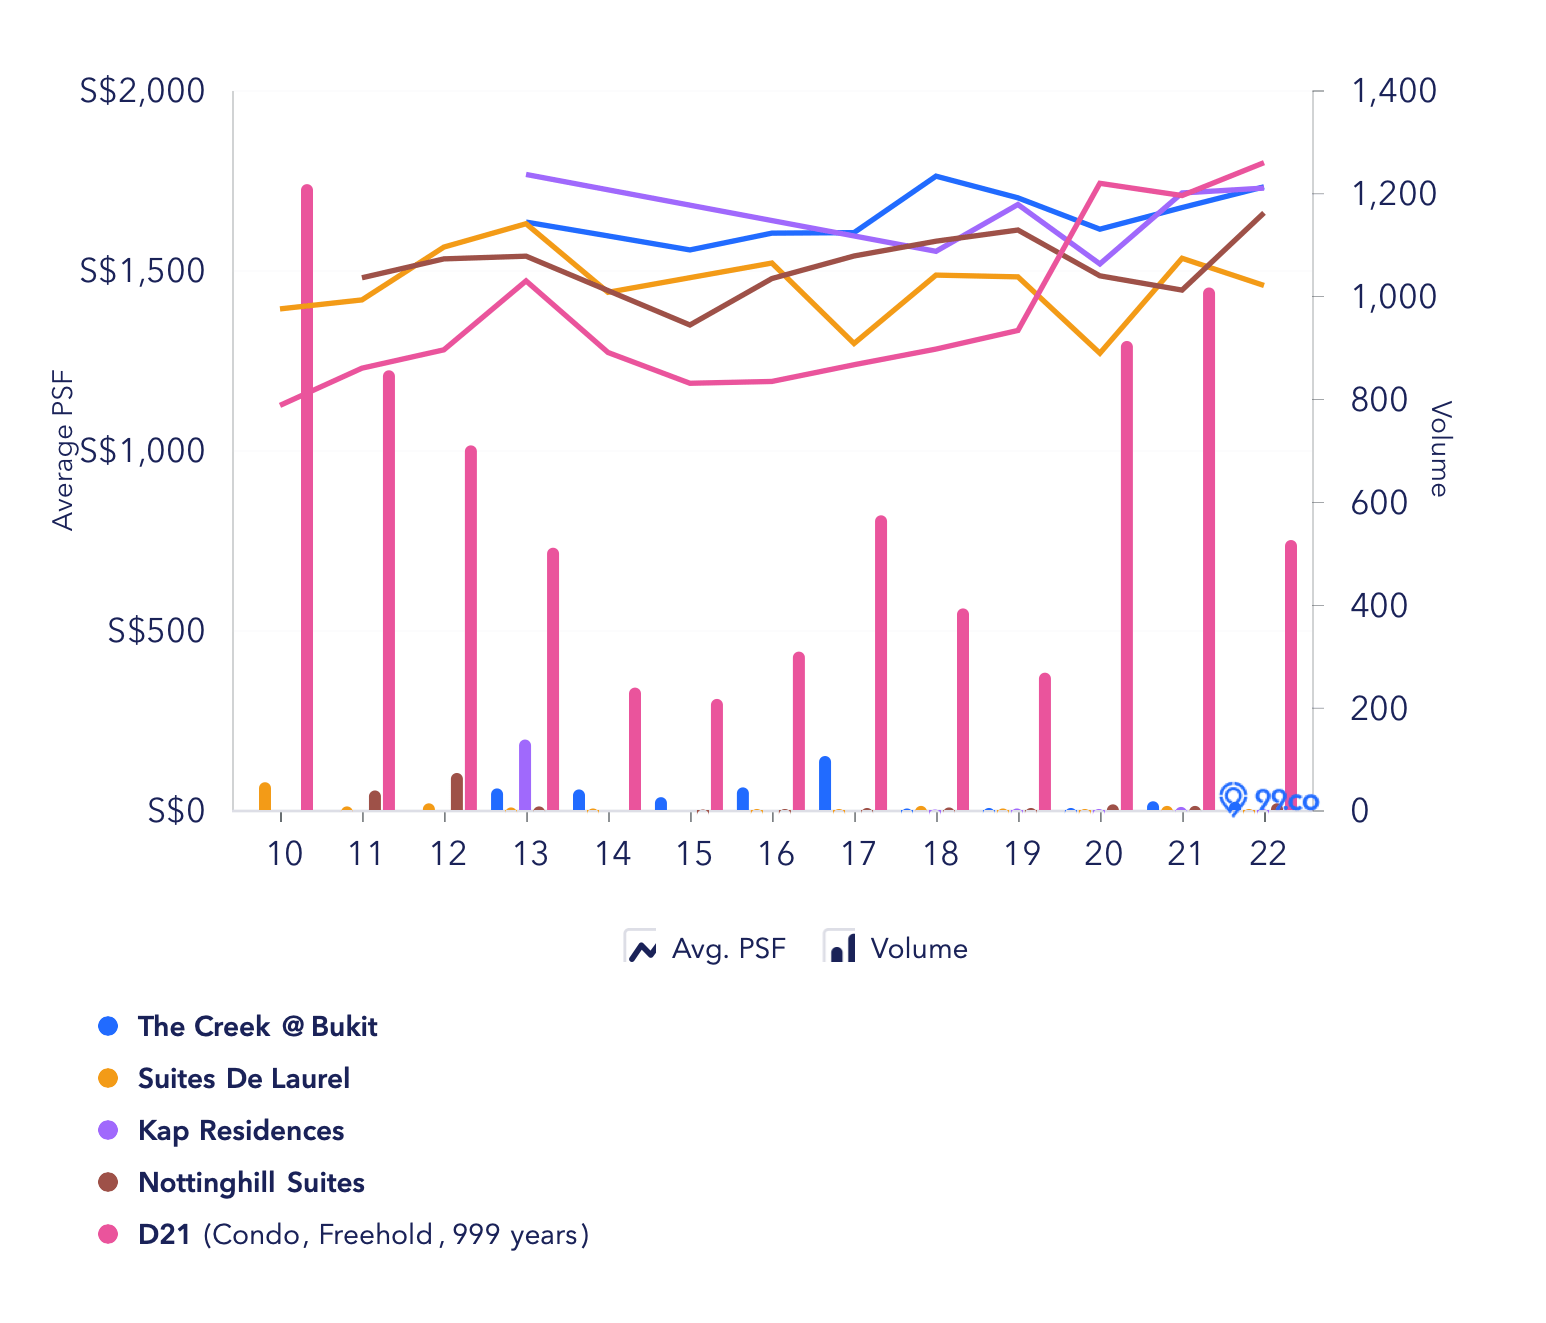
District 9 District 10 District 11 District 21

The developments shown above are those with available units that match your affordability. You’ll notice that after the launch, their transaction volumes are generally low, resulting in the trend lines appearing somewhat volatile. This is a usual concern with boutique developments because if the turnover rates are low, it is difficult for prices to move since banks value a property based on recent transactions. You can see from the graphs that prices are relatively stagnant for most of the projects, as compared to other freehold condos in the same district.

Also, many of these developments are made up of predominantly one and two- bedders which are catered more towards investors since the barriers to entry are lower. This is another issue as investors usually go wherever the money is, so if they find a better investment opportunity, they are less hesitant to let go of their units (even at a loss). This differs from genuine homeowners, who may be emotionally attached to their properties. It is advisable to get a development with a good unit mix, which caters to both homeowners as well as investors as prices are generally more protected.

Compared to an HDB flat, these projects are usually a better potential store of value. This is especially so in the long run as there is no lease decay issue. But if you’re looking for capital appreciation in the short to medium term, these may not be the best options.

That being said, we do believe there is potential for growth in the CCR provided you select the right properties.

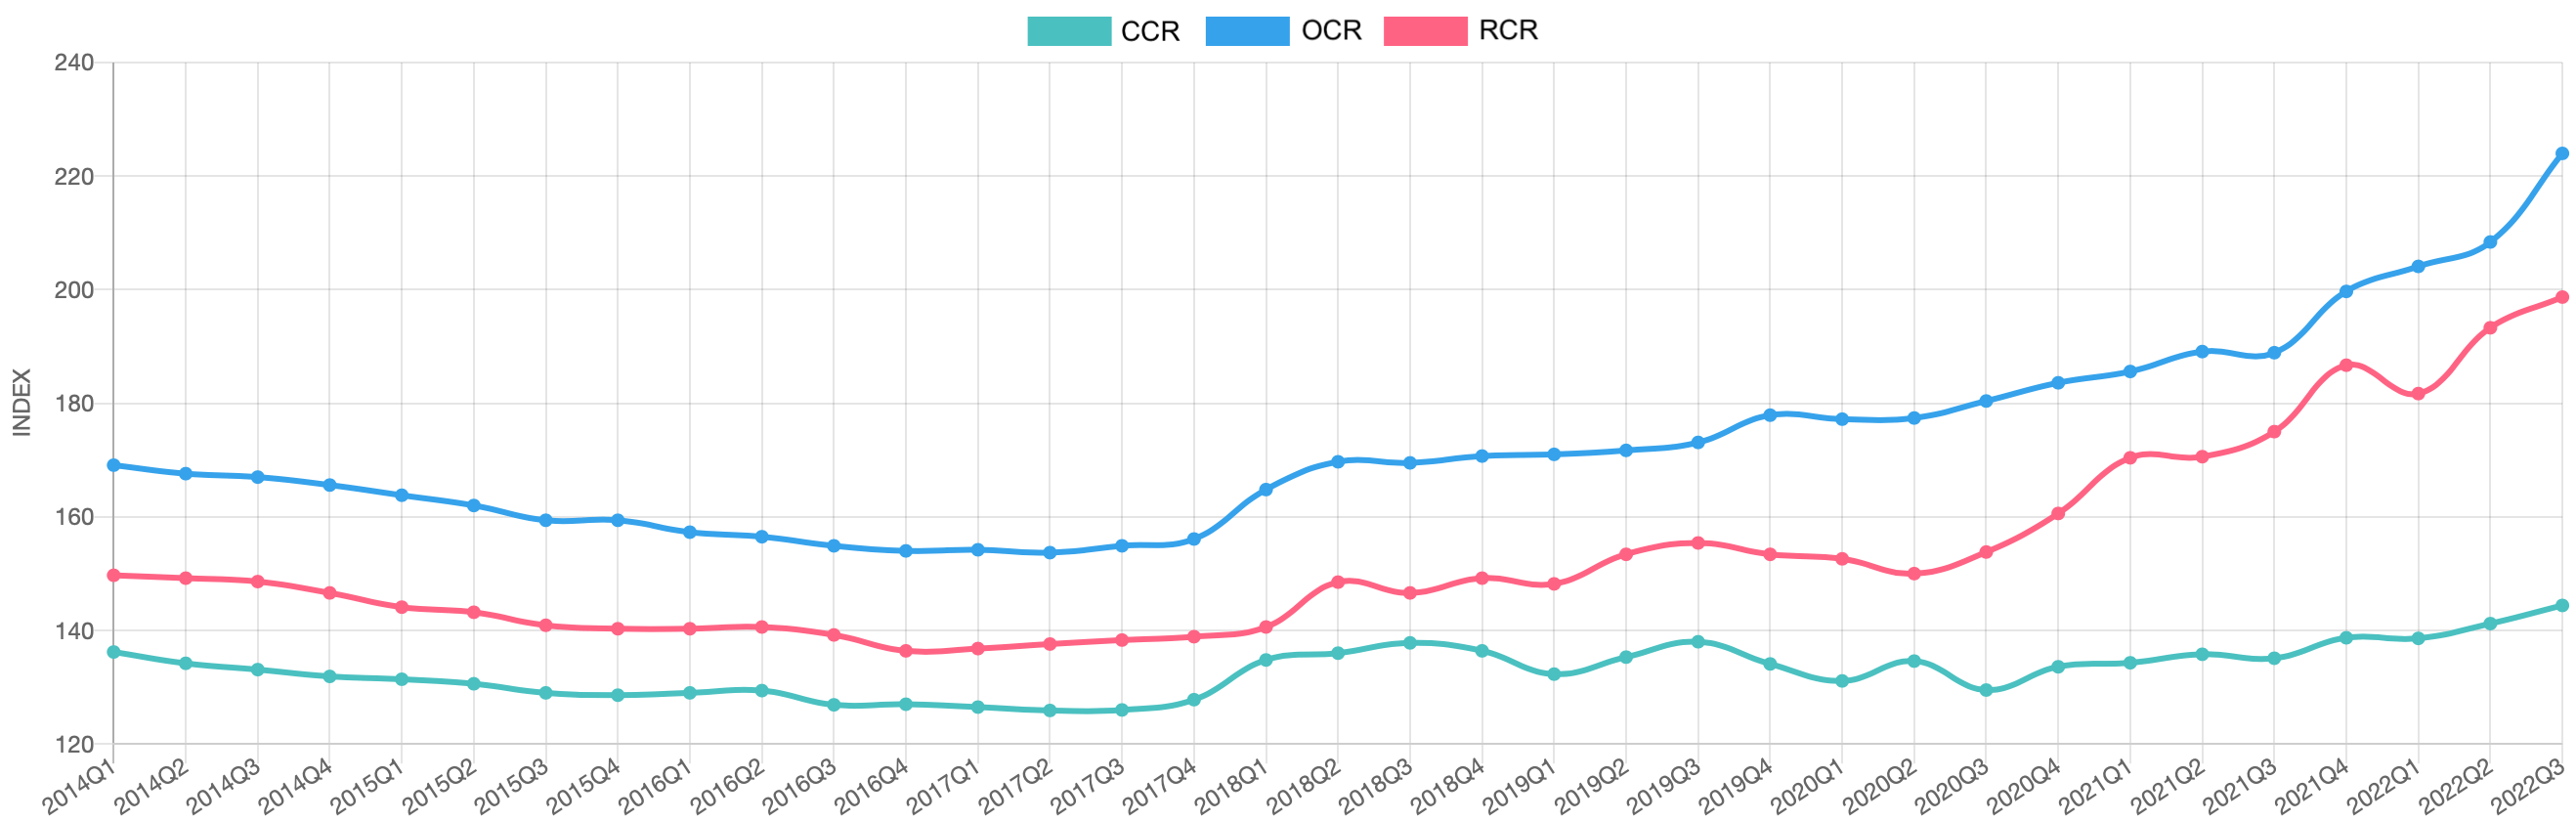
Property Price Index (PPI) of non-landed residential properties in the different regions


Price Indices Q1 2021 Q2 2021 Q3 2021 Q4 2021 2021 Q1 2022 Q2 2022 Q3 2022 Q4 2022 2022 (Flash)
  QoQper cent change QoQper cent change QoQper cent change QoQper cent change YoY per cent change QoQper cent change QoQper cent change QoQper cent change QoQper cent change YoY per cent change
Overall PPI 3.3 0.8 1.1 5.0 10.6 0.7 3.5 3.8 0.2 8.4
Landed 6.7 -0.3 2.6 3.9 13.3 4.2 2.9 1.6 0.5 9.5
Non-landed 2.5 1.1 0.7 5.3 9.8 -0.3 3.6 4.4 0.1 8.0
CCR 0.5 1.1 -0.5 2.7 3.8 -0.1 1.9 2.3 0.5 4.6
RCR 6.1 0.1 2.6 6.7 16.3 -2.7 6.4 2.8 2.6 9.2
OCR 1.1 1.9 -0.1 5.7 8.8 2.2 2.1 7.5 -2.6 9.3

Source: URA, Propnex Research

Drawing from the Property Price Index (PPI) in the different regions, we can see that prices in the RCR and OCR have appreciated significantly more than in the CCR in recent years. We do expect that prices in the CCR will eventually right themselves and the growth rate will catch up. We have recently also written a piece about the narrowing gap between prices of new RCR and CCR projects, which you can read here.

If CCR prices pick up can we expect prices of these boutique developments to pick up too?

Option 2: Save up to buy an additional investment property

Given that you currently own a flat, which we assume is under both your names, and have an outstanding housing loan, there are several things to take into consideration when purchasing a second property.

Loan-To-Value ratio (LTV)

When purchasing your first property, depending on your income, you may be eligible to loan up to a maximum of 75 per cent of the property value (for a bank loan). However, if you’re purchasing a second property while still repaying an existing mortgage loan for the first one, the LTV drops to 45 per cent of the property value.

Higher downpayment

As the LTV for a second property is reduced, naturally the downpayment increases. The downpayment is split into two portions; minimally 25 per cent needs to be paid in cash and the remaining 30 per cent can be paid using your CPF should you have sufficient funds.

Additional Buyer Stamp Duty (ABSD)

The current ABSD rate for Singaporeans buying a second property is 17 per cent which is on top of the regular BSD. Do note that when purchasing a private property, the stamp duty has to be paid in cash first, as this has to be done within 14 days after you have exercised the Option to Purchase (which isn’t enough time to apply for the withdrawal from CPF), and if you have sufficient funds in your CPF to pay for it, the cash will be reimbursed to you afterward.

CPF requirements

When buying a second property, you will need to set aside the following before you can utilise your CPF funds for the purchase:

  • The latest Basic Retirement Sum (BRS) if you have at least one property bought using CPF or the property that you are buying can cover you till age 95*
  • The latest Full Retirement Sum (FRS) if you do not have any property that can cover you till age 95

* If you subsequently sell the property that can cover you till age 95, you will need to set aside the FRS instead.

Also, the maximum amount of CPF that can be used for your second property depends on whether the remaining lease of this property can cover the youngest owner up to the age of 95.

Source: CPF

Let’s say you were to purchase a second property at $1 million for the sake of simple calculations:


Description Amount
Purchase price $1,000,000
25per cent cash downpayment $250,000
30per cent CPF/cash downpayment $300,000
BSD $24,600
ABSD of 17per cent $170,000

As we can see from the calculations above, the cash outlay required in order to purchase a second property is pretty substantial and it will likely take a long time to save up.

We’ve written a detailed piece on the merits of paying for the ABSD for an investment property, but in short, it’s not what we’d typically recommend.

Option 3: Upgrade to a larger flat (resale/BTO)

Being able to buy a BTO is a Singaporean privilege, and since we have two chances at it, most individuals/households will try for the second time if they are eligible. Of course, it’s much tougher the second time around given that only two to five per cent of BTO launches are set aside for second-timers. Also, the income ceiling to apply for a BTO is $14,000 which your household has unfortunately (or fortunately) exceeded so you are no longer eligible.

As you’ve mentioned you’re looking to build your retirement nest, buying a flat may not be the best investment choice. It is no doubt a good stepping stone for buyers looking to upgrade since you’d likely make some profits if you bought a BTO, or if you purchased a resale and managed to gain from the CPF Housing Grants.

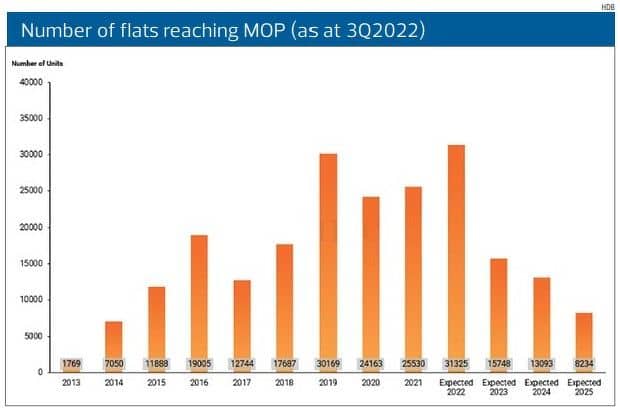
Source: Edgeprop

Given the reduced supply of newer MOP flats coming onto the resale market in the next couple of years, prices of HDB prices could still hold up in the short term. But even so, it is public housing after all; prices are regulated by the government in order to keep them affordable for the masses.

Alternative option

We’ve said this many times before, but a freehold property does not necessarily mean it’s better than a leasehold, and there are many other factors that contribute to the performance of a property besides its tenure. Perhaps instead of looking at freehold options in the districts you’ve identified, you can look at leasehold options instead, which will give you more choices to choose from. And if you were to open up to other locations, you’d have even more options.

These are some available 99-year leasehold units on the market that is within your affordability:


Project District Completion year Unit type Size Asking price
Sophia Hills 09 2018 2b2b 689 $1,482,000
The Panorama 20 2019 2b2b 797 $1,488,888
Thomson Impressions 20 2019 2b2b 764 $1,500,000
Sky Vue 20 2017 2b2b 678 $1,380,000
Daintree Residences 21 2023 2b2b 679 $1,399,999

These projects are picked out based on the fact that they are in your preferred districts, and for their age, so they may or may not be the most suitable for you. We would suggest you consult with an agent for further analysis.

In the ideal situation, you’ll stay in this property for the short to medium term and if it does appreciate well over the next few year, you can then upgrade again; perhaps to a bigger unit or a freehold development, which you can then live in for the longer term. You can eventually cash out for your retirement while you right size to a smaller unit.

Conclusion

Let’s do a quick recap of the options:

For the first option of buying a freehold condominium in District 9, 10, 11, 20, or 21, your choices are rather limited and the available developments are mostly boutique projects (which as mentioned, we do have some concerns over). You will have to pick carefully, as a freehold property definitely doesn’t always mean it will be a good investment.

The second option of saving up to purchase a second property for investment will require a huge cash outlay, which may take a considerable amount of time to save up for.

As for the last option of upgrading to a bigger HDB, unfortunately, your household is no longer eligible to apply for a second BTO due to your income. Regardless, buying an HDB is not the best investment tool given that it is after all a regulated market.

We will suggest looking at some younger leasehold developments that still have the potential for growth which will open you up to more choices. You can stay in this property while you wait for it to appreciate and from there, move on to a bigger unit or a freehold development where you can stay for the long term. As you’re only in your mid-30s, you’re able to maximise the loan tenure. We get that moving might be a pain, but it’s inevitable if you wish to cash out on your property which will go towards building your retirement nest.

ALSO READ: We make $15k per month and live in a 4-room HDB flat. Should we upgrade to a condo now once interest rates drop?

How to Pay for a Home Renovation

How to Pay for a Home Renovation

Home renovations can be exciting, but paying for them requires a lot of planning. If you aren’t careful you could end up with unnecessary debt.

The best way to pay for a home improvement, be it a kitchen refresh or emergency roof repair, is to use cash savings—it costs nothing in interest and leaves you owing no one. But if you have that kind of financial wiggle room, you should consider yourself lucky.

Most of us will have to think about borrowing. Your first thought might be a credit card, since these offer the fastest, easiest route to extra cash. But unless you can pay off the balance in full, there are smarter, and potentially cheaper, ways to borrow money for home renovations—for example: a home equity loan, a home equity line of credit, or a rehab loan backed by the federal government.

With the help of personal finance and mortgage experts, we’ll walk you through the options for financing a home renovation.

What to know about paying for home improvements

Home improvement projects come in all shapes and sizes, from fixing the water heater to knocking out walls and expanding your home’s footprint. They’re generally one of two flavors: a-nice-to-have or a need-to-have. 

Figure out which category your project falls into before you decide how to pay for it, says Taylor Kovar, founder of Kovar Wealth Management in Lufkin, Texas, because not all projects justify taking on debt.

Need-to-have

Emergencies happen—pipes burst, roofs rot and appliances need replacing. If you have to make a repair to maintain the condition or comfortability of your home and you’re short on cash, debt might be your only lifeline. Still, aim to not to sacrifice cost for convenience. Think about when you need the money—as it happens, the quickest way to get cash will likely cost the most in the long run. 

Ideally, you should aim to budget for need-to-have projects ahead of time, says Jenna Biancavilla, a Phoenix, financial planner.

“You should be planning for maintenance and repair, especially if you didn’t buy a new build,” Biancavilla says. As a rule of thumb, you can expect those costs to equal about 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your home’s value each year, she says. For a $300,000 home, that means having up to $6,000 ready to go in a savings or checking account. 

Nice-to-have

The motivation behind these projects is often cosmetic or luxury. They usually aren’t urgent and therefore may be something to save up for instead of financing. 

There are exceptions, though, like if you’re making improvements to increase the value of your home to sell it soon. In these cases, taking on debt may be justified. Just bear in mind the data: While improving curb appeal and upgrading highly-trafficked areas such as kitchens and bathrooms will often boost a home’s value, it’s unlikely you’ll recoup 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the money you put into a remodel. 

With a purpose and a timeline for your project in mind, here are several financing options to consider.

Home equity loan

Pros: 

  • Fixed monthly payments
  • Lower interest rate than a credit card
  • Repayment periods from five to 30 years
  • Interest payments may be tax deductible

Cons:

  • Approval to funding can take up to two months
  • Fixed loan amount
  • May have prepayment penalties
  • Need significant home equity
  • House is collateral

How it works & when it’s best: If you own a large portion of your home, a home equity loan is a great, low-cost way to borrow money. You’ll encounter less red tape than you would with some other options like FHA-backed loans, and you may be able to borrow more.

Your home equity is the difference between the home’s appraised value and what you owe on your mortgage. Home equity loans, also called second mortgages, let you borrow a fixed amount of money from that equity pot and use it however you want. 

If your home is worth $500,000, for example, and your mortgage balance is $200,000, then your equity is $300,000. The bank will evaluate your credit score and debt obligations, decide how much you can borrow and give you a cash lump sum. (Lenders typically require homeowners to keep at least 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity.) 

Repaying a home equity loan is straightforward: Monthly payments are made up of interest—which may be tax deductible—and principal, and begin almost immediately after you receive the cash.

The fact that the loan is for a fixed amount makes it a smart tool for staying on budget, says Kovar, unlike using credit cards or a home equity line of credit (more on that later).

Home equity loan interest rates are fixed and tend to be slightly higher than primary mortgage rates, yet still far below credit card rates, particularly for borrowers with good to excellent credit. In January 2023, average rates on home equity loans ranged from 6.93{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 9.44{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, while average credit card rates hovered around 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. 

“If you have the equity in your house, you’re gonna get the best interest rates because your house is being put up as collateral,” Biancavilla says. But that’s also a risk. If you fail to repay what you owe on the loan, the bank can take your home. (The same rules apply to your primary mortgage).

Home equity line of credit

Pros: 

  • Ability to borrow what you need, when you need it
  • Initial payments are interest-only
  • Potential for a lower interest rate in the future
  • Interest payments may be tax deductible

Cons:

  • Approval to funding can take up to six weeks
  • Floating interest rates mean payments can go up
  • Lower initial payments can lead to overborrowing
  • Need significant home equity
  • House is collateral

How it works and when it’s best: A home equity line of credit, or Heloc, is a way to set up a “revolving” line of credit, which lets you pull money from the equity in your home whenever you need it, up to a certain limit. It’s like a credit card, except it’s backed by the value of your home.

Helocs can be a good method for financing home improvement projects with unpredictable costs, saving you from borrowing too much, or more likely, too little. “Everyone underestimates what they’re going to need,” says Biancavilla. They may also be appealing if interest rates are expected to drop soon, since you don’t lock in a fixed rate with a Heloc (more on that in a moment).

Most Helocs give you access to a line of credit for 10 years, known as the draw period. During that time you only have to make interest payments on what you actually borrow (and you may be able to deduct those payments on your taxes).

This interest-only payment scheme means you’re paying a lot less in the beginning than you would with a home equity loan to borrow the same amount of money—but that can sometimes be a “trap,” says Kovar. Eventually, both interest and principal payments will come due. “If you can’t afford to pay that loan back while you’re doing it, then what are you leaning on to be able to pay it back after the fact?” he says.

As Biancavilla puts it, “If someone can only pay the interest, [they’re] gonna end up home broke and that’s not a good long-term financial strategy.” Ideally the homeowner will make an effort to repay what they borrow in full along the way to keep interest costs down and replenish the line of credit, she says.

One more thing: Like credit cards, Helocs have floating interest rates, where your rate changes based on prevailing market rates, sometimes as often as every month. When your rate moves up or down, so does your payment.

FHA-backed loan

Pros: 

  • Little home equity needed
  • Down payment can be as low as 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • No minimum credit score requirement (depends on individual lender)
  • Loan terms range from six months to 20 years

Cons:

  • Least spending flexibility
  • Maximum borrowing amount may be lower than non-government-backed loans

How it works and when it’s best: You might think of the Federal Housing Administration as mainly helping first-time home buyers get mortgages. But the government agency also backs home improvement loans for certain types of projects.

With a so-called Title I loan, you can get up to $25,000 to spend on projects that make your home “more livable and useful.” That includes things like adding built-in appliances, widening doorways or remodeling your kitchen for a disabled person, and installing solar panels. If you hire a contractor, you may be able to use the loan to cover labor and materials, but if you do the work yourself, you can only cover the cost of materials.

Pools, outdoor fireplaces and other luxury projects are not eligible for financing with a Title I loan, so if you want full spending flexibility, this loan isn’t for you.

You don’t need to have an FHA mortgage to qualify for a Title I loan, but you need to apply for the loan through an FHA-approved lender and meet their individual lending requirements. You can expect interest rates to be similar to typical rates on FHA mortgages, but the rate you get is determined by the lender.

It’s also worth noting that, due to FHA guidelines, Title I loans between $7,500 and $25,000 are secured by your home. Loans for less than $7,500 don’t require collateral.

Another government-backed option, the FHA 203(k) rehab loan, is for new buyers or homeowners who are refinancing. It lets you combine a home improvement loan of at least $5,000 with a new mortgage or refinanced mortgage. For example, say the purchase price for a home is $300,000 and your down payment is $30,000, your mortgage would ordinarily be $270,000. 

With a rehab loan, you can take out more than you need for the mortgage, say $290,000, and use the remaining funds for home repairs. It’s similar to a cash-out refinance, but you don’t need significant equity to qualify. The loans can have either fixed or adjustable rates.

Biancavilla recommends doing your own research on government loan and grant programs before turning to a mortgage loan officer at your local bank. Not all lenders have access to or training for those programs, she says, so they might not present it as an option if you’re looking for home renovation financing. 


Personal loan

Pros: 

  • Quicker funding than a home equity loan or Heloc
  • Fixed interest rates
  • Straightforward repayment
  • Loan funds can be used for anything
  • No collateral required
  • Significant home equity not required

Cons:

  • Need strong credit to qualify for lowest interest rates
  • May have origination fees or closing costs of 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the loan amount
  • Shorter repayment period than home equity loans, usually between one and five years

How it works and when it’s best: As far as its structure, you can think of a personal loan like a home equity loan—you get a fixed amount for a fixed interest rate and start making monthly payments immediately. This can be a good option if you know exactly how much you need to complete a project, or you at least have some cash to cover any shortfall.

The big difference is that personal loans for home improvement projects don’t use your house as collateral. This means they’re quicker to obtain than a home equity loan or a Heloc. But no collateral often translates to a higher interest rate for some borrowers, since it means there’s more risk for the lender, and closing costs.

“That’s where having a really good credit score comes into play,” Kovar says. Without strong credit (or a cosigner), you’ll probably be offered an interest rate that’s closer to what you’d get with a credit card. In that case, it’s better to turn to a home equity loan, provided you have enough equity to qualify.

If a personal loan is your best option, be sure to compare offers from several lenders, not just your go-to bank or credit union, Kovar urges. Online banks, for example, tend to offer comparatively better rates than traditional brick-and-mortars.

Cash-out refinance

Pros: 

  • Single loan may keep financing costs down
  • Potential for a lower interest rate than a new home equity loan or line of credit
  • Cash can be used for anything

Cons:

  • Approval to funding can take up to two months
  • Closing costs apply to the entire new mortgage amount
  • Not advantageous if today’s mortgage rates are higher than your current rate

How it works and when it’s best: A cash-out refinance is yet another way to tap your home equity for cash, but the process is more involved than other options. It requires taking out a new loan that’s larger than your existing mortgage and pocketing the difference. 

Say you have a $250,000 mortgage and $200,000 in equity. With a cash-out refinance, you could get a new mortgage for $300,000, shifting $50,000 from your equity into the new loan. That $50,000 would come back to you in cash.

A cash-out refinance leaves you with a single loan, which could lower the cost of financing a home improvement project. That’s because you’re only paying interest on one loan balance, rather than two, such as a primary mortgage and a home equity loan. 

But a cash-out refinance is only advantageous if the mortgage rate you can get today is lower than what you’re paying. In the current rate environment, a cash-out refinance would likely mean taking your entire loan balance and setting it at a new, higher interest rate, Biancavilla says, plus you’ll have to pay closing costs on the new loan. “That’s gonna be way too costly. You don’t need to do that,” she says.


Family loans

Pros: 

  • Potentially lower interest rate than Helocs, credit cards or personal loans
  • Interest payments may be tax deductible
  • No formal lender requirements, like a credit check
  • Fixed repayment term

Cons:

  • Requires a willing family member with available cash
  • Loan holder must use federal market rate benchmark to avoid additional tax consequences

How it works and when it’s best: Borrowing money from family may seem like a last resort, if it’s even available to you. But “sometimes utilizing your parents as your loan holders could be a really great idea,” Biancavilla says. 

Say your parents are retired and holding onto a significant amount of cash in a high-yield savings account, rather than the stock market, and earning around 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} interest. Meanwhile, you’re considering a Heloc with an 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} interest rate to remodel your master bathroom. What about, instead, a loan from the bank of Mom and Dad? 

Ideally they charge an interest rate that pays them more than any savings account is yielding, and you get financing that’s cheaper than a traditional bank loan. “That spread between what the parents are getting and what the kids are willing to pay—if you can meet in the middle, both parties would be better off,” Biancavilla says.

The key is treating it like a “real loan,” she adds, to avoid unnecessary income tax consequences. That means the loan holder needs to use the applicable federal rates tables to set the interest rate. The minimum required interest rate on family loans in January 2023 ranged from about 3.85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 4.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, depending on the repayment term.

The loan holder also needs to abide by a few other IRS rules: setting up a fixed repayment schedule, reporting the interest income on their tax return and putting everything in writing.


Credit cards

Pros: 

  • Quick access to cash
  • Borrow what you need, when you need it
  • Possibility of avoiding interest with a balance transfer credit card

Cons:

  • Higher interest rates than home equity loans
  • Need very good or excellent credit to qualify for a balance transfer card

How it works and when it’s best: In a pinch, credit cards are an easy way to pay for small home improvement projects—you can instantly borrow the amount you need and spend it on whatever you want. The major downside is that credit cards charge higher interest rates than most other borrowing options, and the rate you pay can fluctuate as often as monthly based on prevailing market rates. It’s easy to get into financial trouble if you don’t pay off your balance in full each month.

Say you charge $1,000 to a credit card with a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} APR. If you can only afford to pay $50 toward the balance each month, it’ll take two years to pay off the debt and you will have spent more than $1,220 on repayment.

If you have a very good or excellent credit score (around 670 or higher), you may be able to avoid steep interest charges by applying for a balance transfer credit card. This allows you to move your balance from one card to another that has a temporary 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} APR. This grace period can last anywhere from six to 24 months, but afterward your interest rate will jump back up. 
The advice, recommendations or rankings expressed in this article are those of the Buy Side from WSJ editorial team, and have not been reviewed or endorsed by our commercial partners.

10 questions with home and garden shop Manor Mercantile

10 questions with home and garden shop Manor Mercantile

You have in all probability heard of farm-to-desk places to eat, but what about field-to-vase farms? Working day Dream Manor is a flower farm in Zachary that specializes in just this thought, but before this year, it prolonged its offerings into an online retail outlet for property and yard components: Manor Mercantile. In this article, you can discover handmade planters for your fresh new-picked bouquets, as effectively as trays, ring dishes and additional, typically made of hand-poured concrete in several hues and styles.

We achieved out to owner Dawn Saucier to master far more about what’s in retail outlet.


1. What is a usual day like for you and your workforce?

Juggling a full-time work that includes the flower farm and the mercantile means remaining tremendous structured and possessing a really very good calendar/planner! Most times you will discover me in the workshop in advance of the sunshine arrives up, hand-creating orders. We have had to restructure our approach with the development we are looking at in order to be a lot more productive. That suggests in the evenings we compile our record of orders, different them into sound colours or colour combo requests, and lay out our pigments, molds and mixing resources so I’m completely ready to pour when I get into the workshop.

Dawn Saucier, owner of Manor Mercantile

2. What is your qualified history? How did you get into this discipline?

If you have ever absent down the rabbit hole on the world-wide-web, you will discover with how I received into performing with concrete. Early past 12 months I was looking for some exceptional modest vessels that I could use for our succulents we develop on the farm, and I couldn’t discover nearly anything that spoke to me. Late one night time I stumbled upon a random put up that had a planter in the qualifications, and I despatched a information to that individual. Very well, that individual connected with one more person who then linked me with a team, and soon after months of research and testing, listed here we are.

3. What sets your store aside?

Commencing everything new is terrifying and fascinating at the very same time, let alone an on line retail store. I perform seriously really hard to make a feeling of group with my prospects. I price every and each consumer who orders from us, and I allow them know.

Valet Trays

4. What is a person issue you feel customers should really know about your shop that they might not be aware of?

I’m pouring little batches in a room that I carved out in my seed-starting off workshop. It isn’t glamorous, but it’s functional. I have also taken around our guest space for delivery and photographing products and solutions. We make it work, and now we are transferring into providing wholesale pricing with desires of possessing our solutions in neighborhood boutiques.

5. How do you maintain your store’s inventory fresh and up to date?

I am often experimenting with new molds and pigment mixtures to see what will work and what does not. I have a trustworthy group of good friends that I use for feedback on hues and models.

Propagation Stations

6. Can you share a trace about what buyers will see in your retail outlet following period?

I am launching a Louisiana collection with our valet trays, then will be introducing planters, candle vessels, trays and pattern weights to the assortment. I’m truly enthusiastic to create this selection with a touch of whimsy and Southern aptitude.

7. What was your reason for opening the shop? When did it open up, and how has it grown or transformed because then?

We loaded our initial get in November 2022, and it was a really big a person. The buyer preferred one of a kind, handmade, regional gifts for her overall staff. I never imagine I slept properly until eventually the buy was in her arms. It was these types of an remarkable feeling of accomplishment when I sent those trays to her, though. That order gave me the self-assurance to spend in additional supplies and to start off setting up out the Manor Mercantile.

Serena Planters

8. What are a handful of of your favorite things in the store appropriate now? 

I have two favorites that I’m presently doing the job on. A single is a new lamp mould that screams midcentury modern, and the other is a plate mold that would make an remarkable charger or centerpiece to include to a tablescape.

9. What are a several need to-have things for spring?

Should-haves this spring have to be our planters and propagation stations! You simply cannot go completely wrong with the Serena planter or the strong colors of our planters. I really like lining up our lesser planters in my kitchen window sill following to a propagation station.

10. What are some of your greatest-providing merchandise?

Our valet trays are our best-sellers, with the Serena planter a near next. Surprisingly, our pattern weights are getting traction with sewers and quilters.


For a lot more data, go to daydreammanor.com/manor-mercantile or adhere to @manormercantile on Instagram. 

Home sales plunge in Miami in 2022, strong sign of housing market slowdown

Home sales plunge in Miami in 2022, strong sign of housing market slowdown

Home

Despite falling home sales last year, South Florida’s median prices for houses and condos increased as people competed for homes to buy. This is an aerial view of North Bay Village, near housing hotbed Miami Beach.

mocner@miamiherald.com

Home sales in Miami-Dade County plummeted in 2022 compared to the prior year, the strongest indication the frenetic homebuying spree that defined South Florida during the ongoing coronavirus pandemic finally has ended.

The county recorded 32,627 single-family house and condominium sales last year, a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop from 39,394 sales in 2021, according to the Miami Association of Realtors housing sales report released late Friday.

The median prices in December for houses and condos provided further evidence of a slowing residential real estate market. The midpoint prices were $530,900 for houses and $374,500 for condos, only slightly higher than year-ago prices and the second-lowest monthly figures in 2022. This easing of pricing momentum as home inventory remains tight indicated the pandemic-fueled market was weakening as the year closed.

To be sure, Miami-Dade finished another year in which the monthly median prices showed sellers had the upper hand. The average midpoint price for 2022 settled at $555,013 for single-family homes and $388,586 for condos, up from $495,333 and $325,649, respectively.

Housing market trends were similar in Broward County, where there were 32,573 sales last year, down 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 40,423 in 2021. In December, median prices of houses and condos in Broward also rose moderately compared to the previous year.

Over the past 12 months, Broward’s average monthly midpoint price of $553,125 for single-family homes mirrored Miami-Dade. But the condo slice of the market was cheaper with a $254,083 average condo in 2022, compared to $217,871 in 2021.

READ MORE: Want to stay informed with the Miami Herald’s real estate coverage? Sign up here for RE|source, our free weekly real estate newsletter.

As the South Florida housing market slowed in the final months of last year from its breakneck speed, a disconnect developed between buyers and sellers. Looking ahead, there’s a chance by midyear that homebuyers could be on equal footing with sellers in a balanced housing market. Expert say don’t, however, expect monthly home prices to fall below the prior year, because there’s still strong demand to relocate here from the Northeast, other parts of the country and Latin America.

Buyers and sellers are on different wavelengths here and in many parts of the United States, said Mariya Letdin, a business professor at Florida State University. The high prices and annual slowdown in sales volume exemplify their disconnect.

“If a seller is patient, they will not transact at prices that fall below their expectations. If sellers see the reality doesn’t match expectations, they will wait,” Letdin said, noting that the higher median prices in South Florida are the result of “sellers refusing to list at lower prices. … They can do that for a few months, before reality sinks in.”

The Federal Reserve’s push all of last year to boost its benchmark interest rates to thwart inflation, led to higher mortgage rates, which eventually took the steam out of South Florida’s overheated housing market. As of Friday, Freddie Mac, the government-sponsored mortgage lender and secondary market buyer, reported an average 30-year mortgage rate of 6.15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, nearly double the 3.56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate from a year ago.

Looking back on 2022, the region enjoyed a robust housing market, but one in which the affordability gap widened more than perhaps anywhere in the nation. The continued population growth in South Florida kept home sales activity and price tags on a steady upward trajectory during the first half of last year, reaching a record median price of $579,000 for a house in Miami-Dade in June.

Many wealthy people relocated to the Miami area last year to take advantage of remote work, low taxes, loose COVID-19 restrictions and warm weather. Companies also expanded and relocated to South Florida, drawing middle- and working-class employees from elsewhere in the country.

“What we’re seeing is that the demand is still strong,” Alyssa Brody, head of New York real estate brokerage and marketing firm Development Marketing Team, said of the desire to live in Miami and South Florida overall.

The emergence of a technology sector and growing financial hub in Miami, Brody said, has brought global financial services giants like Citadel to the city. In perhaps the most high-profile relocation, the Chicago-based hedge fund operator run by billionaire Ken Griffin said last year it’s moving Citadel’s corporate home and securities trading operations to Miami. That corporate move alone will bring thousands more workers here over the next few years. Despite global cryptocurrency markets hitting headwinds that rattled Miami, area residents for the large part have more diverse job opportunities than in the past.

The well-paid newcomers bid up houses and condos in Miami-Dade in 2022, with many paying cash to get the homes they wanted. In December, just over 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of home sales were cash deals, sharply higher than the 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} national average.

“The challenge that Miami had over the years is there was no industry here to work in,” Brody said. “Now that these industries are opening up,” the labor market will continue to become diversified.

Despite Miami emphatically putting itself on the world stage in business and finance, it came with a high price and exacted a toll. The housing market and broader cost of living kept many longtime residents and natives from buying homes and made it extremely difficult to maintain apartments as rents soared.

Take Jackson Health System physician resident Dr. Onome Oboh. After being handed a 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} monthly rent hike — to $2,700 per month from $2,050 per month — to live in Miami’s Overtown section downtown, Oboh moved north to Broward.

“I caught a wave of overcharging,” she said. “At that time, they began charging $200 more for rent and would not let me sign a new lease six months before my rent went up.”

Last year’s torrid pace of home sales activity and overheated residential rental market forced many to flee the region, leaving small business owners floundering to find essential workers — especially in hospitality and personal services jobs.

Most area real estate experts predict a less competitive housing market in 2023, one that will enable buyers and renters to avoid nerve-wracking surprises.

“I don’t have a crystal ball with interest rates. We’ve all been surprised with how high they’ve gone up,” Florida State’s Letdin said. “I expect to see continued increases in (home) inventory, especially in less established markets.”

Profile Image of Rebecca San Juan

Rebecca San Juan writes about the real estate industry, covering news about industrial, commercial, office projects, construction contracts and the intersection of real estate and law for industry professionals. She studied at Mount Holyoke College and is proud to be reporting on her hometown.
Support my work with a digital subscription

Profile Image of Michael Butler

Michael Butler writes about the residential and commercial real estate industry and trends in the local housing market. Just like Miami’s diverse population, Butler, a Temple University graduate, has both local roots and a Panamanian heritage.

Buying an investment property in Canada: Risks, taxes, regulations and lower-cost alternatives

Buying an investment property in Canada: Risks, taxes, regulations and lower-cost alternatives

Serious estate is its individual asset course, featuring various characteristics from equities and fastened profits. As these kinds of, it can enable diversify prosperity. Investing in real estate does not call for specialised knowledge most Canadians have an understanding of the principles of holding property by means of dwelling possession. Numerous have accomplished pretty well due to residence selling price appreciation about the earlier two a long time.

The inflation-altered returns for real estate over the previous 50 several years in Canada are pretty equivalent to that of equities. But individuals returns came with much a lot less volatility than stock marketplaces. In addition, income varieties a even bigger part of its total return when compared to stocks, which are additional about money gains. So genuine estate may possibly be a extra acceptable financial commitment for cash flow-oriented buyers this sort of as retirees. But younger investors, also, can consider benefit of the leverage uniquely out there to serious-estate buyers banking institutions will readily lend you up to 4 situations your money at favourable prices to get true estate, wherever they won’t do that if you are buying stocks or bonds.

“As the property appreciates, the return on first expense for your down payment can be much increased thanks to the leveraged total,” reported Sabine Ghali, managing director of Buttonwood Assets Administration in Toronto. Of study course, as many landlords are finding this calendar year, leverage performs the other way, way too when assets values arrive down, the mortgage principal owed continues to be just as complicated.

What are the threats of investing in authentic estate?

As opposed to other assets, authentic estate is illiquid. It takes time to locate a suited house to acquire or a ready buyer for a assets you’re promoting. When you do, the expenditures of the transaction are significant, normally upward of 5 for every cent of the price tag for the seller. That features agent commissions, legal expenses, inspections and other 3rd-bash bills, but not your personal time.

Simply because investment decision attributes begin at about $100,000 in Canada, and most cost several instances that, it’s a tough sector to wade into incrementally. Even with mortgage loan financing, you have to have at the very least a middling internet really worth to participate. (See a list of decreased-cost different approaches of getting authentic estate publicity underneath.)

While much less volatile than the stock marketplace, assets markets fluctuate. Ought to fascination costs increase though you personal the property, its benefit could minimize even as you facial area higher mortgage loan payments on renewal. Economic and work prospective buyers in the community subject, too, as does excellent of daily life. There are individual challenges to your house of hearth, destruction and all-natural disasters. You can get insurance policy for that.

What’s more challenging to handle is the romantic relationship with your tenants. An exacting process to screen prospective tenants, including a credit score check out and interviewing employers and past landlords, can go a long way toward reducing potential complications, in accordance to Ms. Ghali. Provincial laws lays out a process for dealing with disputes in between tenants and landlords, nevertheless rental tenancy laws and tribunals tend to err on the aspect of the previous. Ally Ballam, a genuine-estate adviser with Engel & Volkers in Vancouver, suggests entrepreneurs maintain a few to six months’ lease in a individual account just in scenario there’s a dispute and you go a couple of months devoid of receiving profits from the home.

Last but not least, there is a hazard of emptiness, whether or not resulting from tenant churn or adverse industry conditions. This chance can hardly ever be removed entirely but can be minimized by possessing higher-top quality properties in favourable areas.

“Buying a home for investment decision functions that can be your main home if the marketplace turns seriously terrible is generally a awesome insurance policies plan,” Ms. Ghali stated.


What taxes and laws apply to financial investment assets?

Compared with a principal home in Canada, investment decision home is issue to funds gains tax when you offer it. You ought to also pay out profits tax on the rental cash flow even though you individual the property. Each will consume into your returns. Having said that, these taxable amounts can be partially offset by costs incurred from financing, protecting, handling and strengthening the residence. It is worth consulting a tax adviser to decrease your taxes payable, at the very least when it comes time to sell.

The pros and disadvantages – and tax implications – of proudly owning cash flow home

Also make oneself conscious of provincial, municipal and apartment corporation regulations relevant to any house you’re taking into consideration buying. Some provinces and municipalities have controls on hire, which may constrain your potential to increase it to the market rate. British Columbia and Ontario have both equally launched taxes on properties ordered by overseas consumers (not Canadian citizens or permanent residents). Vancouver and Toronto both have levied property surtaxes on houses considered to be vacant, and other towns are contemplating adopting related measures as a way to increase the housing provide.

Many Canadian municipalities restrict or totally ban shorter-time period rentals in specified housing kinds. Additional, apartment organizations may undertake limits, for case in point on brief-time period rentals or the proportion of models in a creating that can be rented out.


Is now a great time to commit in actual estate?

The good information for future customers: Right after big selling price appreciation in modern many years, most Canadian marketplaces are going through a flip and selling prices are coming down.

The bad information: The major element pushing prices down is the maximize in borrowing prices. So for most customers, the drop in selling prices will be offset by greater house loan payments.

Is your mortgage leaving you dwelling poor? Use our True Lifestyle Ratio calculator

The takeaway: This is a potentially perilous time for buyers with only a 20-for each-cent down payment (the minimum expected by creditors on investment decision houses) to get into the market. If you are in that predicament, you’d far better be confident you are paying underneath industry price. It may possibly be an opportune time, even so, for men and women who possess their residence outright, have some further income and really do not have to have to borrow enormous sums to get into the expenditure property marketplace. If financing is not a massive be concerned, your dollar will go even more these days than it has in a although.

Preserve in mind that serious-estate marketplaces are notoriously area. Different dynamics will be at play in Sudbury and suburban Montreal. Time and once again, income trends immediately after the actuality propose there’s virtually constantly a variety of house somewhere in Canada that is a steal suitable now. The challenge is obtaining it (or them).


How do I invest in authentic estate?

You research for an financial investment property to buy the same way you may possibly do your have house: search at listings, interact a true estate agent and/or research on commission-free revenue platforms. The most extensive general public database of Canadian households for sale can be identified at realtor.ca.

But there are other avenues to uncover the greatest deal. Ms. Ballam and income associate Amy Leong focus in working with builders to give their purchasers pre-sale condos at charges commonly reserved for insiders in advance of they are offered to the normal public.

“Make absolutely sure when you are looking to buy an financial investment house that you are working with an agent who specializes in financial investment qualities,” Ms. Ballam advises. They will, for instance, run pro forma income movement projections for your rental money and bills below distinctive property finance loan-price scenarios so you have a far better plan of what you’re finding into.

In addition to an agent, you will probable require other company suppliers, this sort of as a lawyer, assets inspector and home finance loan broker, to get the transaction finalized.


What do I need to have to do immediately after I get an expense residence?

If you have the time and inclination, you can reduce your expenditures and likely improve your returns by taking care of the residence oneself. That entails locating and dealing with tenants, amassing lease, observing to upkeep and repairs (together with soon after-hrs emergencies), and shelling out residence taxes as well as relevant utility and other charges. You will have to have property insurance plan it will be to some degree higher than for an operator-occupied space. Conventional lease files can be downloaded from most provincial internet sites that will assist lower the chance of authorized disputes, which can probably drag out for months, interrupt your rental profits and incur main expenditures.

Alternatively, you can employ the service of a house-administration company, which will do most or all of the jobs listed earlier mentioned for 8 to 10 for every cent of rental profits on prolonged-time period rentals and 12 to 15 for every cent on quick-term kinds. Your serious-estate agent can refer you to these kinds of a agency in your region, but like something else, it’s worth buying close to. Some serious-estate revenue and finance providers have their own property-administration products and services arms.

Like any important investment, you really should have a system. Do you intend to flip the assets in a rapidly-rising market place? Maintain it lengthy-expression? Renovate it in the hope of raising the rent? For traders committed to the asset class, Ms. Ghali recommends banking rental money with the aim of acquiring a further house each individual 3 to 5 yrs: “This electrical power of compounding extra on top of the leverage aspect of authentic estate investing can make probably substantial gains above a extended interval of time.”


There are a amount of means for traders of modest usually means to attain publicity to genuine estate without getting a second dwelling or the headache of managing the house.jhorrocks/iStockPhoto / Getty Photos

Are there decreased-charge techniques to get publicity to serious estate?

The millennial lament about shopping for a house, epitomized by the hashtag #donthaveamillion, is also a major hurdle for would-be investors. The good thing is there are a selection of techniques for buyers of modest suggests to get exposure to true estate with no acquiring a 2nd home or the trouble of handling the home.

REITs

Real-estate investment trusts are securities that trade on stock marketplaces. They are designed to maintain and take care of a basket of qualities and pass on cash flow through distributions (related to company dividends) to investors. With REIT units or an exchange-traded fund (ETF) invested in them, you can profit from both of those land worth and lease will increase in the genuine-estate marketplace for as little as $100. Becoming traded on stock marketplaces, they nonetheless are inclined to be remarkably correlated to equities.

Fintech

For the previous decade or so, economical know-how startups have been trying to arrive up with means for tiny buyers to get crowdfunded attributes fractionally for as little as a number of thousand bucks for each investor. Canadian illustrations include Addy Engineering Corp., BuyProperly, NexusCrowd and Willow Serious Estate Technologies. On the moreover side, these platforms promise to be genuine diversifiers, in which your investment’s value is tied to serious property. Even now, they have a small observe report and are competing with very well capitalized landholding firms owned by pension funds, REITs, personal-pooled money and wealthy households and men and women.

Serious-estate pooled money

For a minimum financial commitment as high as $100,000 and a lock-in period, non-public genuine-estate investment resources permit investors to participate in possessing (and sometimes establishing) rental homes all over North America. Adhere to typical companions with a heritage and great track record there are some shady operators in this niche. Beware promotions promising suspiciously substantial or “guaranteed” returns and usually demand to see fiscal statements prior to putting your dollars down.

Investing in your possess household

Owners in Canada’s expensive, major-metropolis marketplaces presently know about “mortgage helpers” these kinds of as basement suites. Adding or improving a rental suite in your own home or constructing a laneway residence represents a way to leverage your present principal home to deliver additional income and increase the fairness in your residence. It is basically an investment decision property tacked onto your residence.

As these kinds of, be conscious of charges that can erode your fee of return. Even though little, new laneway properties even now require the most high-priced elements of any residence, particularly kitchens, loos and HVAC units. But it need to nonetheless be much less expensive than purchasing a separate residence.

No space for a independent suite? Now that COVID-similar journey constraints have been lifted, international college students are coming again to Canada. You can produce revenue by renting out a spare space. There are numerous organizations that match pupils to host homes below a assortment of phrases.