With its relaxing natural tones and minimalist aesthetic, it is no shock that eucalyptus is placing traits in the structure field. But its power stretches much beyond its style. Industry experts recommend employing the preferred plant to hold insects out of your household, and their tips is correct on time.
The hotter months see bugs arise from hibernation and develop several generations of offspring in the course of the summer season. So, if you’re seeking for a natural way to continue to keep insects out of the household, then this is just one of the best indoor plants for the career.
How does eucalyptus retain bugs out of the household?
(Picture credit history: GettyImages)
Yard pro Jeremy Yamaguchi of Garden Like points out that insects are deterred by eucalyptus’ sturdy smell. So, if you’re looking for the most powerful way to use eucalyptus, he suggests pure eucalyptus oil [such as time one from Amazon] that is conveniently spreadable about your property.
‘Pests are alarmed by solid smells, and eucalyptus is generally not a scent that is native to the location, so its unfamiliarity blended with its potency results in pests to perceive it as a menace,’ Jeremy says.
On the other hand, you can use all the all-natural deterrents you want, but if you have holes or areas for pests to enter your house, they will – so repair those places very first. If, for some reason, you are unable to seal people entry points, make those details the aim of your eucalyptus placement for maximum deterrent performance.
It is important to be aware, however, that this oil can be harmful to animals, so it is finest to use it with caution if you have a pet.
How to use eucalyptus to maintain bugs out of the house
(Picture credit: GettyImages)
As Jeremy indicates, you can use eucalyptus oil to discourage insects this summer months, but you can also incorporate eucalyptus into your indoor (and outdoor) back garden concepts with eucalyptus trees as well. Here’s what you need to have to know.
1. Use eucalyptus oil in a diffuser
Lindsey Hyland, the gardening specialist and the founder of City Natural Generate, suggests filling a diffuser with eucalyptus oil to preserve insects out of the property. This scent will ‘help to repel insects and retain them absent from your residence.’
2. Make a handmade spray
You can also blend h2o and eucalyptus oil to produce a do-it-yourself bug spray, which Lindsey implies will prevent bugs from coming into your residence. It is very best to spray the combination in problematic areas in which the insects are very likely to enter your home.
(Impression credit: GettyImages)
3. Make investments in eucalyptus trees
Eucalyptus is at the peak of interior and garden tendencies this year, so it is only natural that you will want to appreciate the plant by itself. And although the scent is not as impressive as the oil, these plants will however enable preserve insects at bay. Lindsey suggests that eucalyptus trees can assistance retain insects away as they will generate a ‘barrier concerning your household and the insects.’
Now you have every motive you may well require to take pleasure in the positive aspects of eucalyptus – the only thing remaining to do is make the investment
Using cash is the least expensive option for paying for home improvements.
Borrowing against the equity you have in your home with a loan or line of credit is also cost efficient.
Unsecured loans will have higher rates, but you won’t risk losing your home if you’re unable to pay.
There are many reasons you may want to renovate your home. Besides the added value they might bring,
home renovations
may be necessary to fix safety issues, provide additional comfort, or add space for new living situations.
Any successful home-improvement project starts with a good plan, a key part of which is how much it’s going to cost and how you’re going to pay for it. As of mid-2022, the average remodel or renovation project was just under $47,000, with most falling in the range of about $18,00 to $77,000, according to data compiled by the digital home-improvement marketplace HomeAdvisor.
Start with the basics
The way you pay for a home-improvement project will depend on your individual situation.
“When financing home improvements or dipping into cash reserves, there is never a one-size-fits-all answer,” says J.R. George, senior vice president at Trustco Bank. “There are just too many variables involved to be able to price each method accurately.”
Before you begin, George recommends you ask yourself these basic questions:
How much money do you need and how long will it take to pay that amount back?
Are current loan interest rates favorable?
If you have cash reserves, how much are you earning on that cash versus how much it will cost to borrow?
Having answers to these questions can help you figure out which method of paying for home improvements will work best for you.
10 ways to pay for your home-improvement project
1. Save the money and pay cash
Cash is the least expensive way to pay for home improvements. There are no interest charges, origination fees, or repayment periods. A 2021 Bank of America survey found that 62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homeowners making significant changes to their homes planned to use savings to pay for them.
However, as ideal as this sounds, the large cost of renovations can put this option out of reach when your home needs a lot of repairs or an extensive remodel.
“While this can be an effective way to finance some smaller projects, it might not be feasible for homeowners who are doing big projects such as a complete kitchen makeover,” says Franco Terrango, retail sales executive at Bank of America. “Pairing savings with other financing options can give you the funds you need to accomplish your goals.”
Pros: No interest costs; no credit check or loan qualification
Cons: Ties up a large amount of money that could be used for other purposes
When it makes sense: When you have the funds to pay in cash and when the scope of your project is smaller
2. Home-improvement loan
A home-improvement loan has a fixed interest rate and doesn’t use your home as collateral. Amounts can vary from $3,000 to $100,000. You can find home-improvement loans at banks,
credit unions
, online lenders, and private lenders. They’re structured similarly to personal loans.
“A homeowner is approved based on creditworthiness, like with a credit card,” says Vince Passione, founder and CEO of digital-lending platform LendKey. “There’s never a lien on their home, and the entire process is almost instant.”
Pros: Not secured with your home; quick approval process; fixed interest rates
Cons: Higher interest rates than a home-equity loan or line of credit; shorter repayment period
When it makes sense: If you don’t have equity in your home or don’t want to use your home to secure the loan
3. Home-equity line of credit
A home-equity line of credit (or HELOC) offers a relatively low-cost borrowing option with a lot of flexibility when it comes to home renovations. It is secured by your home. If you aren’t able to repay it, the lending institution can foreclose. Banks, credit unions, and other lending institutions may offer HELOCs.
“As homeowners are accumulating equity at a faster rate, a home equity line of credit lets them borrow against the available equity in the home up to their credit limit,” Terrango says. “Additionally, home-equity lines of credit give homeowners the flexibility of a revolving credit line that can be accessed as needed, and it tends to offer more attractive interest rates than other financing options – which will save money in the long run.”
How it works: A home equity line of credit works similarly to a revolving line of credit such as a credit card. There’s a maximum amount you can borrow, and you make installment payments with interest. Lenders generally won’t approve you for more than 85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your home’s value, minus the amount you owe on your mortgage.
Your credit limit will also depend on how much you’re able to qualify for. If, for example, the amount that can be borrowed against your home is $140,000, but your income and
credit score
don’t qualify you for that amount, the limit will be lower.
Money from a HELOC can be paid directly to the contractor in the form of a check or debit transaction.
Pros: Low rates; convenient access
Cons: Uses your home as collateral on the loan; may have some closing costs
When it makes sense: If your home has a lot of equity and if you’re unsure of what your remodeling costs are going to be
4. Home-equity loan
A home-equity loan is like a HELOC in that your home is used as collateral for the loan. However, with a home-equity loan, the entire amount is borrowed up front, and repayments begin immediately. The interest rates are low and funds can be dispersed at the homeowner’s discretion.
The amount that you can borrow depends on your income, credit report, and the market value of your home, but generally follows the same guidelines as a HELOC. The main difference is a homeowner borrows a fixed amount with a fixed interest rate on a home-equity loan. There may also be additional costs.
“Borrowers need to keep in mind when borrowing against your house is that it is a mortgage transaction,” George says. “This often results in some form of closing costs which can equate to thousands of dollars.”
Pros: Low interest rates; set amount of money financed
Cons: Full amount must be applied for up front; uses home as collateral on your loan; possible closing costs
When it makes sense: If you have a larger renovation with a solid bid from a contractor
5. Cash-out refinancing
If you have a lot of equity in your home, you can use a cash-out refinancing to replace your old mortgage with a new one and receive the difference in your bank account. With a cash-out refinancing, you take out a loan larger than the amount you still owe and receive a portion of your home’s gained value in cash.
It’s a new mortgage, so you’ll qualify based on income and credit history. A cash-out refinancing generally has a maximum loan-to-value (LTV) ratio of 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, meaning, you can only cash out up to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your home’s value.
For example, if you owe $200,000 on your house and it’s worth $350,000, you can refinance up to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of $350,000, which is $280,000. The $200,000 mortgage is paid off and you’re left with $80,000 in cash.
Pros: Costs of renovations wrapped into your new mortgage; lower interest rate
Cons: Renovation financed along with your mortgage over the entire term of loan; full mortgage application and approval process
When it makes sense: If you have a lot of equity and borrowing conditions are favorable for a new mortgage
6. FHA 203(k) renovation loan
An FHA 203(k) loan combines the purchase of a property and needed renovations into one mortgage. Funds for the renovation are placed in escrow and are paid out as projects are completed. The cost of the renovation must be at least $5,000, but not more than the FHA mortgage limit for the area.
Applicants will need to apply through an FHA-approved lender and be able to find contractors who can bid for the work that needs to be completed before the loan closes. Once the loan closes, the work can commence and contractors will be paid with renovation funds held in escrow.
Pros: One loan for both the purchase of a property and the renovation; lower credit score and
down payment
requirements
Cons: More hoops to jump through to get work approved, scheduled, and paid for
When it makes sense: If you have less income or a lower credit score, or would like to combine the costs of a renovation with the purchase of property
7. Fannie Mae HomeStyle renovation loan
A HomeStyle Renovation loan covers the purchase of a property and renovations. Before the loan closes, the borrower must work with a contractor to submit plans for approval. The LTV ratio is calculated by taking the project into account. As the work is completed, the contractor can request the funds held in a custodial account.
It’s similar to an FHA 203(k) loan, but the Fannie Mae program bears the hallmarks of a conventional mortgage, such as cancellable mortgage insurance. You do have to find an approved HomeStyle Renovation mortgage lender.
Pros: Low rates; one loan for both the purchase and renovation of a property
Cons: Not as flexible as other options
When it makes sense: If you want one loan for the purchase and renovation of a property and are able to get a solid bid from a contractor who can meet the timelines required by the loan
8. Government-backed renovation loans
For those who qualify, a government-backed renovation loan could be a low-cost option for a home improvement project. Here are some lesser-known options.
HUD Title I property improvement. Amounts can be as much as $25,000 with terms as long as 20 years. To qualify, the project must substantially improve the safety and liveability of the property.
VA cash-out refinance. Terms and conditions are similar to conventional cash-out refinancings but with the added VA benefits, such as lower fees and credit requirements.
USDA single-family housing repair loans and grants. This program offers loans up to $40,000 to very low-income households in eligible rural areas. Grants are also available for borrowers over age 62. The money can be used to repair, improve, or modernize your home. Loans are for 20 years at a 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} interest rate.
9. Personal loan
Applying for a personal loan is similar to what you would experience with a home-improvement loan. Your home is not used as collateral, so you’ll pay a higher rate than you would with a secured loan. But personal loans also have fewer strings attached than other types of
home-renovation
financing, giving you more flexibility in how you can use the money.
Most banks, credit unions, and other lenders offer personal loans. They will examine your creditworthiness in determining how much you qualify for.
Pros: Doesn’t use your home as collateral; often has lower interest rate than a credit card; flexibility in what it’s used for
Cons: Shorter repayment period and higher payments than a home equity loan or HELOC; may not qualify for as much as you would with a HELOC or home equity loan
When it makes sense: When you don’t have enough equity for a HELOC or home equity loan or do not want to use your home as collateral on a loan
10. Credit card
Using a credit card is one of the most expensive ways to fund home improvements. Nevertheless, Bank of America’s survey found 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of households planned to do so.
While this method is convenient and may make sense with a smaller project, most other options will come with a lower cost. One exception might be a new credit card with an introductory 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} interest rate. If you can pay for the renovations within the introductory time period, the cost will be low. The ability to dispute charges for dissatisfactory work or materials could also be a benefit of using a credit card.
However, with APRs ranging anywhere from 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to more than 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, carrying a large amount of debt on a credit card becomes very costly. It also can affect your ability to qualify for other, lower-interest loans. When your credit utilization becomes high due to the amount of renovation charges you’re putting on the card, your credit score goes down significantly.
Pros: Easy, no paperwork to have your loan or renovation plans approved; funds immediately available; doesn’t use your home as collateral
Cons: High interest rates; may lower your credit score if your credit utilization gets too high
When it makes sense: With smaller projects or projects on a shorter timeline
George Ratiu is the senior economist and supervisor of economic research at Realtor.com.
Real estate agent.com
For a lot more than 15 a long time, George Ratiu has been researching the housing current market. He’s the senior economist and manager of financial investigate at Real estate agent.com, the place he focuses on trends in global economies and real estate markets. He’s also a previous supervisor of investigation courses at the National Association of Realtors, where by he specialized in housing figures, global and industrial real estate current market general performance and additional. (Realtor.com is owned by the identical father or mother organization as MarketWatch.)
1. Home loan rates will likely continue on to increase
“The surge in rates pushed the monthly mortgage payment for a median-priced house $550 increased than a yr ago, a substantial enhance thinking of that most households are also emotion the squeeze of higher rates for food items, gasoline, cars and trucks and garments. Just as importantly, prices are envisioned to go on rising as the Federal Reserve tightens credit history movement,” says Ratiu, who predicts that if the tempo of improves continues, we could before long see a 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} charge on 30-12 months loans.
2. There aren’t enough houses for sale — which tends to make your alternatives far more restricted
One thing to continue to keep in mind is that inventory remains limited as the range of homes for sale is still down below last yr when customers were competing intensely. “The principal explanation for this scarcity is the truth that builders have not matched the tempo of development to populace and residence development more than the previous ten years,” states Ratiu. In point, there’s a shortfall of virtually 6 million houses, according to investigation from Real estate agent.com, and that helps make it tough to come across more than enough homes for all the customers wanting for a residence.
3. House prices will possible keep likely up in a lot of markets, but not practically as rapid
Ratiu predicts that costs will also continue to improve thanks to the point that there are even now more purchasers than houses for sale. “In quite a few marketplaces across the state, potential buyers are obtaining that they might nevertheless be outbid by somebody with a money give or a larger down payment,” claims Ratiu.
But owing to sharp improves in curiosity prices and inflation, he says we’re nearing the major of the selling price progress curve. “In some markets, sellers are acquiring that buyers are commencing to commit more time seeking and are considerably less inclined to waive contingencies, insisting on house inspections and asking owners to deal with a property’s shortcomings,” claims Ratiu. What’s additional, he says in about a dozen cities across the region charges have declined above the earlier few months, an sign that the market place is beginning to return toward far more stability.
“We can count on price ranges to carry on soaring in the months forward. For individuals, the base line is that larger expenditures are leaving a lot less dollars in their pocket at the stop of each individual thirty day period, just as rents and property prices proceed mounting at double-digit costs,” claims Ratiu.
4. Sellers will nevertheless have an benefit, but it won’t be pretty so excessive
Sellers are probably to retain the upper hand in most marketplaces throughout the place. On the other hand, their gain is setting up to wane supplied the mix of high selling prices and better fascination fees — which are pricing thousands and thousands of buyers out of the market. Ratiu claims the slowdown in need is recognizable as gross sales of both new and existing households have been declining above the past couple months. “Twenty per cent of home owners indicated that they prepare to shift forward with pandemic-delayed options this year and list their qualities for sale. The enhance in source will guide to more competitiveness amid sellers, shifting the market place additional in the direction of buyers,” states Ratiu.
5. Don’t permit FOMO land you in a dwelling you do not love
The principal takeaway for prospective buyers this yr is that housing markets are currently in a apparent transition from the frenzied tempo of 2021. With economical and economic pressures mounting, Ratiu says it is essential not to allow the worry of missing out direct you into hurrying what’s the greatest buy of most people’s lives. “The rate of new design is buying up, more property owners will be completely ready to checklist their homes and with mounting fascination charges, costs are by now adjusting to the slowdown in demand from customers. Patience is generally viewed as a advantage and may perhaps also be a critical component in this year’s search for a property,” suggests Ratiu.
This is in all probability the most abnormal marketplace in the history of real estate: inventory is at document lows, consumers are at report highs (at the very least in Texas), and there are a lot more agents out selling and shopping for properties on behalf of purchasers.
In fact, in accordance to the Affiliation of Serious Estate License Law Officers, there have never ever been more serious estate brokers in the U.S.: there are now additional than 3 million energetic authentic estate licenses, in accordance to NAR.
In 2006, there had been 1.35 million. In 2012, there wasn’t even 1 million.
You know the Fantastic Resignation? The place is every person? Many are selling serious estate!
Hence, it is not just needed, it is Vital for agents to keep ahead of the activity and keep encouraged. Like the best athletes, they will need to strategize intensely and assume otherwise.
Consider like a billionaire, with a billionaire’s attitude.
Study straight from the authorities: brokers with a billionaire’s attitude who wake up each working day hyper-concentrated on the million-dollar-moreover listing they will be marketing. And not just advertising it, but how they will be Marketing and advertising it.
1st you will be influenced by Josh Altman, star of Bravo’s Million Greenback Listing Los Angeles. You will be mesmerized by Frank McKinney’s story: Frank is a philanthro-capitalist, writer, and self-described Actual Estate Artist who eats, sleeps, and bleeds true estate from creating ocean-entrance mansions in South Seaside — exactly where he frequently drops in by helicopter — to writing inspirational authentic estate tomes in his Florida tree-household.
And his advertising strategies? Frank has some resourceful genius methods that I cannot wait to listen to him share.
In the afternoon, I will reasonable a lively panel discussion with top rated-tier luxury income execs — the prime-generating brokers in North Texas.
It all occurs on June 13 at the Renaissance Dallas Resort at Plano/Legacy: a day-very long symposium referred to as Following Gen Luxury. Visitor speakers include Michael Valdes, Janie Coffey, Shaun Patrickus, and Alicia Chmielewski … you know Alicia, she is the actual estate auction pro who has sold scores of multi-million dollar mansions across the state, such as 1 just down the avenue from me.
This occasion is broker agnostic: speakers and panelists hail from all brokerages, income, and cash flow concentrations. The widespread denominator is Luxurious. We at CandysDirt.com have lengthy desired to move into Luxury True ESTATE conferences, but a very little point called COVID place designs on maintain. Now we are off and running.
Twenty decades back an mysterious variety popped up on my quite new, quite amazing and then outstanding little device identified as a mobile cellular phone. I answered — neighborhood quantities had been constantly local, and spam calls weren’t a point.
Introducing himself, the caller had a peculiar proposition. “I read through your piece in the [Business Journal’s sister publication the Colorado Springs] Independent about the Burns [Theatre],” he reported, “and I have one thing you really should have.”
Sounded appealing — so I gave him my tackle and he showed up a several several hours later on. He experienced a gigantic, dilapidated hanging lamp that experienced been produced from a stained glass indicator that had hung more than the ticket booth at the Burns.
“I assumed probably you could restore it as a indicator, or correct it up and hang it up in your home,” he explained. “I don’t have any place for it.”
So I took it with thanks, set it in the basement and there it sat for practically 20 several years — until eventually we embarked on one more try to declutter our ancient home.
Honoring my type-of dedication two decades before, I hauled the when-and-upcoming sign to Linda “The Glassy Lady” for restoration. She did an incredible task — it was breathtakingly lovely. We thought about hanging it on our cluttered partitions, but it was major, fragile and way too vulnerable to our leaping, roughhousing young canine. It was normally destined for the Pioneers Museum, so I schlepped it more than previously this 7 days.
They had been delighted to have it, and I was delighted to give it. Our city-owned historical past museum is an remarkable asset to the local community, absolutely free to all comers, unpretentious, exciting and endlessly attention-grabbing. The museum’s main goal: to build a lasting connection to the Pikes Peak area by preserving and sharing our cultural history.
The resplendent Burns turned the beloved Chief Theater. It retained its remarkable architecture and inside decoration, delighting generations of moviegoers until it was gracelessly demolished in 1973. You can blame the shortsighted entrepreneurs of the developing, who refused to fund an substantial renovation, or the similarly shortsighted elected officers who stood passively by, but there’s a further unacknowledged perpetrator.
Our city has thrived for 15 a long time since it was conceived and focused to the premise that (practically) all advancement is superior. If you have a creating, you have the ideal to tear it down, replace it or leave it vacant. Non-public property is just that. As opposed to Denver, our metropolis govt cannot adversely landmark a making — in reality, the owner of a setting up can not check with the city for landmark status. That indicates that each privately owned developing in the metropolis is prospective bulldozer bait. Area, state or national historic sign up listings may confirm historic standing, but this sort of listings do not avoid present or potential proprietors from tearing them down. Properties in the North Stop Historic District are perfectly protected, but related households on the Westside are not.
The inherent dynamism, optimism and generally explosive nature of progress in Colorado Springs signifies that no buildings are sacrosanct. Take into consideration the Town Auditorium, which town officers refused to preserve or renovate for many years. In spite of our community’s passion for the stunning old pile, it may well have finally fallen to the wrecker’s ball without the Colorado Springs Conservatory’s Linda Weise and her ongoing restoration initiatives. Look at also the Union Printer’s House, acquired by a benevolent coalition of rich area citizens who purpose to protect and revivify that wonderful campus.
Our philanthropic and organization communities have grow to be much much more attuned to preservation in latest decades, but we require a landmark ordinance that empowers assets entrepreneurs. And yeah, I’ve obtained a puppy in this combat — our 1899 Westside home. Landmarking it would maintain and defend it, even nevertheless it might diminish its worth for potential house owners.
Those people of us who bear in mind the Burns, The Antlers lodge (the 1 torn down in 1964), and dozens of other structures that fell in the city’s mid-20th century Demolition Derby (AKA Urban Renewal) are dying off, and hope that foreseeable future generations will treasure the developed landscape of the past.
Just now, sitting down at my desk at home seeking to determine out a good stroll-off for this column, a good friend posted the plan for the opening of the new County Courthouse (now household to the Pioneers Museum), dated Could 16, 1903. It’s in the museum’s assortment.
The 1st speaker outlined was Judge Louis Cunningham of the Criminal Court, who had probably taken the trolley Downtown from his spacious new Westside property exactly where I now sit. Do I feel in ghosts? It’s possible now…
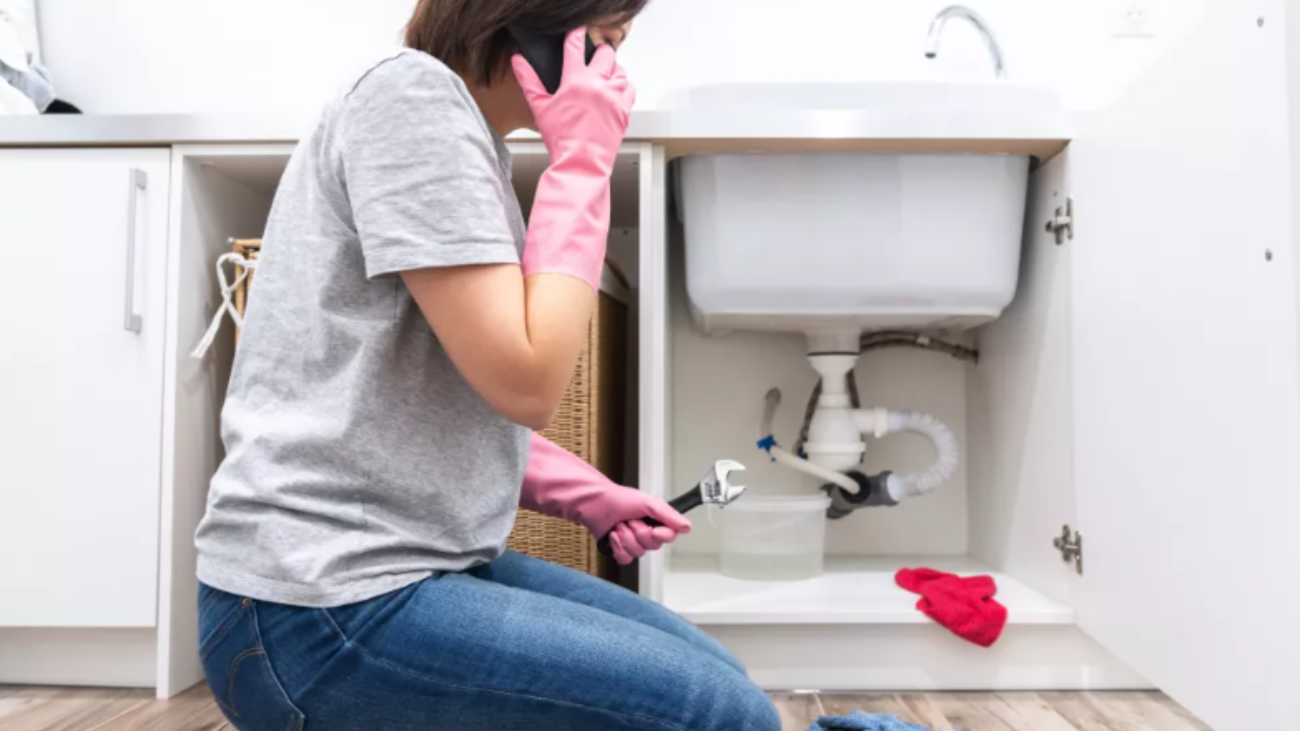
Various issues might arise with your plumbing system at any time. When this happens, it’s recommended to open your search engines and type ‘plumbing services near me’ rather than try to fix it yourself.
IDENTIFY THE ORIGINAL CAUSE.
Drain clogs and plumbing problems aren’t always caused by food particles and debris caught in the pipes. The pipe itself might sometimes be the source of the problem. In the event of sewage line damage or waste backup, calling in a plumbing firm is your best bet at getting the job done right. Professional plumbers can assess the situation thoroughly and quickly provide solutions to get to the bottom of the problem.
SAFETY
An ordinary homeowner would lack the expertise needed to do plumbing repairs. The right tools and equipment are available to plumbers to complete the job correctly and efficiently. It’s not just more practical to hire a professional, but it’s also safer for everyone involved.
ENSURE THERE ARE NO FUTURE ISSUES
Professional plumbers have dealt with numerous similar problems in the past. Once the problem is solved, the work is done for good. An example of an emergency plumbing scenario can be a broken sewer line, which would need expert attention since it is potentially hazardous.
TIME SAVINGS AND COMFORTABLE LIVING
You may need a permit from the city if you need to excavate to fix your plumbing problems. In some cases, you’ll have to notify your insurance carrier. If you’re taking on all of these chores, it might be daunting. With the aid of a professional plumber, you can avoid any unnecessary hassles.
Having the Proper Equipment
Having to wait for a plumber to arrive to discover that they don’t have the proper tools for the job is one of the most frustrating things. As a result, you’ll have to wait for them to return with the necessary tools before they can begin work. That seldom occurs with a plumber. To guarantee that your plumbers meet the high standards for client service, they stress the need to have all the necessary tools in the van.
To get the job done, they will have a wide range of equipment, including the latest in high-tech instruments like drills and video cameras and more basic ones like tube cutters and wrenches.
Provides a Variety of Services
A wide range of plumbing services is offered by plumbing firms. When you look up ‘plumbing services near me’ in your search engines, you can see the type of services each firm has to offer.
There is extensive training for every plumber. As a result, a single phone call might request various services to bring your plumbing system back in working condition. Certain plumbing firms specialise in only one service, such as drain unclogging. You can count on their services to help you with everything from installing water heaters to unclogging, repairing or replacing your pipes.
Let the agency know if you need a dishwasher or trash disposal installed the next time you have a plumbing issue.
Accomplish an Improved Ending
Hiring an experienced plumbing company gives you access to a team of well-versed experts in their field. For decades, professionals have been working in this field. They are experienced in dealing with plumbing systems in brand-new homes and decade-old homes.
If you’re remodelling your house and need assistance integrating new plumbing systems with your existing plumbing, there are many agencies there to help you. Inexperienced plumbers and DIY-minded householders can cause more harm than benefit inadvertently. Because of the poisonous waste in your pipes, you run the risk of injury and unhealthy living circumstances if you don’t use the correct equipment and protective clothing.
SAFETY
An ordinary homeowner would lack the expertise needed to do plumbing repairs. The right tools and equipment are available to plumbers to complete the job correctly and efficiently. It’s not just more practical to hire a licensed Columbus OH plumber (or a similar professional in your area), but it’s also safer for everyone involved.