Considering a 1031 Exchange? The Rules You Need to Know

Considering a 1031 Exchange? The Rules You Need to Know

Investing in real estate can be a highly profitable enterprise. Unfortunately, real estate investors know that it comes with the same cost as most other forms of investment: taxes. Fortunately, unless Congress changes the 1031 rules, which have been in existence for more than 100 years, there is a way for savvy real estate investors to defer payment of capital gains taxes indefinitely: the 1031 exchange.

Named after the section of the Internal Revenue Code that defines its many rules and regulations, the 1031 exchange permits an investor to defer tax payment by following a series of strict rules. What follows is a list of what you need to know in order to take full advantage of a 1031 exchange.

1. 1031 Exchanges Are Also Known as ‘Like-Kind’ Exchanges, and That Matters.

Want to Invest in the Housing Market? Try This REIT.

Want to Invest in the Housing Market? Try This REIT.

Owning a rental residence isn’t as quick as it could audio, even if you employ the service of a property supervisor. But which is not the only way to commit in the housing market.

One more choice to contemplate is obtaining shares in AMH (AMH 1.35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), formerly known as American Homes 4 Lease. This real estate expenditure trust (REIT) owns a huge and diversified portfolio of solitary-spouse and children residences. It’s not specifically like proudly owning your own rental property, but it gets you quite a few of the most critical gains whilst preserving you stress and danger. Here are some key info to take into account.

1. Diversification matters

Most little serious estate traders will only personal a several qualities, possibly only a single, in addition to their most important home. That indicates a vacancy at a one home can have a large affect on your income movement. Similarly, an surprising value at a property (like changing a broken furnace) will be a weighty load. AMH owns extra than 59,000 solitary-family members houses. No single house will have a discernible affect on its in general results or the revenue you acquire from the REIT’s dividends.

A sign in front of a home that says house for rent.

Image source: Getty Visuals.

On prime of that, with only a handful of belongings, most tiny serious estate traders are uncovered to just just one or two markets. AMH’s portfolio is spread across the Southeast, Midwest, Southwest, and Mountain West locations of the United States. It would be almost impossible for most scaled-down landlords to realize that type of diversification.

2. Responsible dividend

To be honest, AMH’s 2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} dividend yield is just not specifically massive. That mentioned, it is notably larger than what you would get from an S&P 500 index exchange-traded fund (ETF), at this time all-around 1.65{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. But the true vital is that the dividend has been held constant or increased each and every 12 months due to the fact AMH commenced paying out dividends in 2014, the REIT’s 1st complete yr of daily life as a public company. In the meantime, in the third quarter of 2022, AMH’s altered funds from operations (FFO) was $.33 per share as opposed to a dividend of $.18 for each share. That prospects to an adjusted FFO payout ratio of all over 55{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, which is very conservative. 

3. Hire and appreciation

When it comes to REITs, dividends are a essential issue. On that score, lease advancement more than the previous pair of yrs has authorized AMH to maximize its quarterly payment to $.18 for each share for every quarter from $.05 for each share per quarter in 2020. In other words, buyers are benefiting specifically from the business’ powerful operating outcomes. 

Even so, that’s not the only story here. AMH began developing its portfolio in the aftermath of the Great Economic downturn, which was driven by a housing downturn. It was opportunistically purchasing residences on the inexpensive. The inventory has doubled due to the fact its IPO, reflecting the reality that housing price ranges have gone up because that place. Massive gains like that aren’t likely to come about again, but if home price ranges raise in excess of time, the improve is probable to be mirrored in a bigger stock cost just the same. In other phrases, if you are observing housing costs go up, AMH is an prospect to get in on.

Virtually like carrying out it you

AMH’s inventory rate has pulled back approximately 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} since the begin of 2022 as desire prices have headed better. So there is probable to be far more price volatility here than if you bought a rental assets on your own. And however, that fall has pushed the generate towards traditionally high stages. And you get the benefit of specialist management and diversification. AMH isn’t really an specific substitute for obtaining a rental residence, but if you are conservative, it could be worth a deep dive when you consider the complications and hazards of getting a landlord.

12 Tax Deductions Available to Rental Property Investors by Dave Sweyer

12 Tax Deductions Available to Rental Property Investors by Dave Sweyer


&#13
Oh, January – it truly is the time of the 12 months for contemporary begins, new resolutions, and… taxes. But if you’re a rental house operator, we have acquired some fantastic information – you may possibly be eligible for some good tax deductions! In this weblog put up, we will examine the major 12 tax deductions that are offered to you. Don’t forget that everyone’s problem is various, so make sure you seek the advice of with a tax skilled to decide what deductions are out there to you.
&#13
 &#13

    &#13

  1. Home finance loan fascination: You can frequently deduct the property finance loan desire you fork out on a personal loan utilised to purchase or make improvements to your rental house.
  2. &#13

  3. Assets taxes: Property taxes paid out on a rental residence are usually tax deductible.
  4. &#13

  5. Depreciation: The value of rental residence (excluding the land) is considered to drop more than time, and this decline in value can be deducted every single 12 months as a depreciation expense.
  6. &#13

  7. Repairs and maintenance: Expenses linked to keeping and restoring a rental property, this kind of as painting, repairing a leaky roof, or changing a broken window, are frequently tax deductible.
  8. &#13

  9. Insurance policy: Insurance rates paid for a rental assets are frequently tax deductible.
  10. &#13

  11. Skilled expenses: Fees paid out to a assets supervisor, bookkeeper, or other professionals for providers connected to the rental house are normally tax deductible.
  12. &#13

  13. Travel costs: If you need to have to journey to your rental residence for enterprise functions (e.g., to make repairs, meet up with with tenants), you could be in a position to deduct some of your vacation costs.
  14. &#13

  15. Operating Expenses:  Purchases designed for provides or subscriptions for taking care of your rental homes are tax deductible.  This can include things like workplace supplies like pens, paper, ink, authorized types, or management publications.  And also subscription-based expert services like phone expenses or world wide web-dependent house management computer software.
  16. &#13

  17. Home Updates: You can spruce up your investment decision residence by portray shutters, electrical power washing, or undertaking some landscaping. Did you know that all these beauty advancements are also tax deductible in the latest year? So why not refresh that paint, trim people shrubs, and give this area a new lease on lifetime (see what we did there?)?
  18. &#13

  19. Promotion: Any funds you devote marketing your assets for rent is deductible, irrespective of whether on the web, print, or radio.
  20. &#13

  21. If you’re a landlord, your deductions have an higher limit – but the good thing is, it is quite generous! You can generally subtract up to $25,000 from your rental home revenue.
  22. &#13

  23. Preserve receipts and information of payments in case the IRS has thoughts (and we all know they enjoy to ask questions). Hold out, you have to continue to keep up with receipts for the complete yr? That appears like a lot. Fortunately, at Sweyer Property Management, we keep observe of all rental residence expenditure expenditures and give conclude-of-yr statements for consumers. That way, when tax time rolls all around, you don’t have to go looking for a pile of receipts.
  24. &#13

 
It is vital to be aware that to declare these deductions, you ought to be able to display that the expenses are instantly connected to your rental assets and are not personalized expenses. Moreover, you should retain good documents of all your financial commitment assets expenditures, as you will have to have to deliver documentation to aid your deductions.
 
In summary, it is truly worth investigating the several tax deductions obtainable to landlords. Even even though the fiscal responsibilities of proudly owning a rental house can be challenging, any accountable landlord will consider advantage of all the legal deductions they are allowed to make. It truly is significant for rental home owners to seek advice from their tax specialists as eligibility for these deductions differs from situation to case. With the proper advice, landlords can function towards developing predictable money movement and guarding their investments from overpayment of taxes. The process is ongoing and necessitates regular diligence, but with persistence and tricky function, maximizing your earnings as a landlord whilst lessening your tax load is possible.
 
As a primary residence management firm in the Cape Worry region, Sweyer Residence Management suggests that assets homeowners strongly take into account doing work with a trustworthy and skilled house management business. Irrespective of whether it pertains to the eviction approach or an additional location of dealing with your expenditure properties, we want to make certain house proprietors and investors recognize the marriage they are entering into when choosing to perform with a home administration business. 
If you have expenditure houses and do not use a professional management firm, we hope you contemplate accomplishing so. The specialists at Sweyer Home Management will be happy to provide you with a no cost rental analysis or, if you like, give us a simply call at 910-239-1338. 
 
Sweyer Residence Administration is a whole-service expert residence administration organization specializing in all areas of rental administration. If you might be an investor or home operator searching to learn a lot more about our companies and what a qualified home supervisor can do for you, achieve out to us right now at 910.256.3031 or by using our website. Sweyer Property Administration has exhibited ongoing development in the course of the Wilmington, Leland, and Hampstead places though preserving an excellent Google+ rating for client service. 

How Can a Property Management Company Help with Your Rental Property?

How Can a Property Management Company Help with Your Rental Property?

Provided by Freedom Assets Management and Revenue

Having rental properties can be an fantastic financial commitment and a dream appear actuality for numerous house house owners. Some proprietors choose the Do-it-yourself landlord solution to controlling their rentals.

Listed here are a number of good reasons why sensible landlords pick instead to perform with a skilled to lease and manage their rentals.

#1 The Authorized Factor

Each individual course of action of renting will come with problems and ramifications, equally for a landlord, and for a tenant. As a Do-it-yourself landlord, do you know which is which?  The lawful aspect is the most typical significant pitfall and in this article is why.

  • How do you know that your leases are authorized?
  • Is the accurate language involved in your lease?
  • Do you have to have a smoke alarm certification?
  • Have state and federal Honest Housing Rules been adhered to?  

In many cases, landlords unintentionally violate rules and regulations during the application, screening, leasing and handling of their financial investment assets.

For instance, what is the right way to gather lease and what is the suitable way to react if the tenant will not pay back hire? How does a landlord handle an uncooperative tenant?

Perhaps changing the locks and locking the tenant out seems like a good idea. But it’s not legal. There is a appropriate course of action to observe.

Listed here are other procedures that all have a authorized method and ensuing ramifications:

  • Tenant application and screening
  • Lease delinquency
  • Lease violations
  • Routine maintenance and repairs
  • Terminating tenancy
  • Protection deposit processing

In lots of states, a qualified residence manager has to be accredited, they want to take continuing schooling, continue to be on top of altering regulations, and they are held to a greater common by the Realtors’ Code of Ethics and DPOR License Restrictions.

Extra Methods at Your Fingertips

House Management organizations have access to a wide range of assets. Interactions with local Realtors will assistance to get the assets rented sooner, high-quality and perfectly-priced contractors will quickly address repairs and remove all those problems. Moreover, most have authorized sources by way of countrywide and community trade associations, boards and affiliations for covering thanks process that is necessary.

Fewer Complications

An professional property manager is heading to choose the load of managing your assets off your shoulders by getting devices in place to competently collect rent, tackle program upkeep phone calls, decrease emergencies, stay on major of transforming landlord and tenant rules and enforce leases.

Your Rental is a Organization

Did you know that independent escrow accounts are vital? That you need to have to maintain in-depth records to safeguard oneself if a tenant would ever file a declare against you? That educating you with switching legislation is a need to? Typical downfalls of Do it yourself landlording include things like not retaining accurate documents and payment histories, which includes reporting profits on tax returns.  Property Management Organizations continue to keep detailed information and supply stop of yr statements to their landlords, moreover relevant IRS reporting.

Plan Inspections

To affirm tenant lease compliance and remain on major of vital routine maintenance, assets administrators perform routine inspections. Inspecting the rental residence also helps in holding emptiness time small by determining turnover servicing perfectly in advance of a tenant move-out.

What Can Your Dwelling Hire For?

Assets management companies have obtain to online information and business companies which will give present-day market prices for setting rental quantities. You could have a extensive-expression tenant in spot that you will need to carry your amount volume to latest. Residence management companies can navigate these nuances and secure the landlord’s fascination. Now, rental properties are in significant demand from customers and there is limited rental housing stock. It is very vital to know what your property can feasibly hire for in this market place.

Total, there are infinite benefits to performing with a area pro in the marketplace, a specialist assets management corporation. Make sure you connect with 703-330-1776 to established up a time to chat to Freedom’s house manager to get all of your concerns answered.

About Liberty Assets Management & Product sales

Freedom House Management & Sales is a Manassas-dependent true estate firm that can assistance you to lease your residence or acquire or promote this yr. From armed forces and govt moves, to financial commitment buys and rightsizing, they can solution your real estate inquiries. Call whenever at 703-330-1776 to explore the market place and issues you have with your house. Led by Broker Tiffany Izenour, Liberty Home Management & Product sales provides an great full staff to fulfill your authentic estate requires.

Property Investment Startup, Dashdot Wins Spot 14 of Deloitte Tech Fast 50 Awards

Property Investment Startup, Dashdot Wins Spot 14 of Deloitte Tech Fast 50 Awards

Sydney, Australia–(Newsfile Corp. – January 23, 2023) – Dashdot, a residence expense organization that will help Australians own houses, lands at location 14 of the 2022 Deloitte Tech Fast 50 Awards Australia.

Dashdot

The Deloitte Quickly 50 Awards recognises public or non-public Australian technological know-how organizations that have achieved the swiftest yearly income growth premiums around the previous three a long time. The award recognises Dashdot’s 800{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} progress above the past a few a long time, a notable expansion for a bootstrapped startup that has only been operational for much less than 4 many years.

Dashdot characteristics the milestone to its ground breaking data science and know-how development crew, which has manufactured two proprietary prediction products that don’t exist anywhere else in the earth. These have authorized traders to get applicable insights about development hotspots.

Dashdot utilizes its proprietary technological know-how, real-time knowledge, and verified system with the aim of making sure customers are shopping for the suitable investments at the suitable time for their personal targets.

“Affordability and apprehension in direction of residence investing, especially from youthful generations, is just one that is rooted in concern and lack of education. We are in this article to transform that mind body and lead the way, with a demonstrated system, backed by data and proprietary tech,” suggests Goose McGrath, Co-founder and CEO.

“House investing is full of misinformation, with a whole lot of contradictory information and projected concern for youthful men and women to navigate. With every little thing we create, the intention is for it to be usable by all. A lot of our innovation has been formulated from the intention of building assets investing approachable and basic to fully grasp,” says Gabi Billing, Co-founder.

Dashdot also will take satisfaction in its special “coronary heart + details approach.” The business places equivalent price on its technological innovation and services and an great consumer working experience.

As a ‘assets portfolio growth companion‘, Dashdot does all the tough operate for its client’s expenditure assets portfolio. “From sourcing, securing by to settlement, we tackle all the grunt get the job done that persons just don’t want to deal with,” clarifies Jason D’Silva, Head of Client Success.

“We are living in a globe where by individuals anticipate convenience, curation, and concise communication. From your relationship app recognizing your kind, to having a person else develop your flat-pack household furniture. Seamlessness is in all places, but the property field is nevertheless dusty, and not to point out particularly fragmented, so we’re enthusiastic to double down on how we can make home investing just as clever as our people are,” states Jess Norton, Head of Marketing and advertising.

In 2023, Dashdot is positioned for continued success with its new application and other merchandise choices that will make assets expense a lot more attainable in Australia.

About Dashdot

Dashdot is a home portfolio growth spouse that champions financial flexibility for Australians by assisting them make the wisest selections about home investments. It pioneers improvements in the Australian authentic estate industry by aiding clientele build a scalable and lucrative assets portfolio.

Dashdot supplies a absolutely distinctive approach to the standard residence financial investment support, presenting finish-to-conclusion administration for their clientele and a myriad of info and tech tools. The Dashdot approach streamlines anything, saving men and women the trouble of coordinating all the transferring items of securing expenditure homes and evaluating their functionality.

Speak to Particulars:

Call Particular person: Nat Griffiths
Email: hello there@dashdot.com.au
Web page: https://dashdot.com.au/

To look at the resource version of this push release, make sure you take a look at https://www.newsfilecorp.com/release/152141

We make 0k per year and live in a 3-room HDB flat. Should we save to buy an investment property, upgrade to a condo, or larger flat?, Lifestyle News

We make $180k per year and live in a 3-room HDB flat. Should we save to buy an investment property, upgrade to a condo, or larger flat?, Lifestyle News

Hello,

We’ve read with interest on your advice columns, and we especially appreciate the effort and detail put into the responses.

My wife and I are in a bit of a dilemma. 

We live in a 3-room HDB flat in Clementi Ridges which we bought for close to $400k. Our MOP is up in April this year. We’re in our mid-30s and together we make $15,000 gross a month, with no debts other than our HDB loan. We don’t plan to have kids.

Our goal is to have a retirement nest egg; the question is how best to go about building it. We’re not sure if our next move should be to:

(1) Upgrade to a freehold condo – we’re only interested in one located in Districts 9, 10, 11, 20, or 21;

(2) Save up to buy an additional investment property; or

(3) Upgrade to a larger HDB through resale/2nd BTO.

Sincerely hoping you could share some insights to help in our decision-making. Thank you very much!

1) Outstanding loan – $238,000

2) CPF used plus accrued interest – $128,000 from me + $36,000 from my wife

Hi there!

Thanks for reaching out to us!

It’s always good to start the retirement planning process early, as there is a lot you can do to build that nest egg from now till then. With so many possible pathways to take, it can be difficult to decide on the best option.

We will do our best to shed some light on the possibilities and hopefully, it will make your decision-making process a little easier. Let’s start by looking at affordability.

Affordability

These are some of the recent 3-room transactions for Clementi Ridges:


Date Block Level Size (sqm) Price
Oct 2022 312B 19 to 21 69 $615,000
Sep 2022 312A 19 to 21 69 $660,000
Sep 2022 312B 16 to 18 69 $660,000
Aug 2022 312A 13 to 15 69 $608,000
Jul 2022 312A 13 to 15 69 $565,000
Jul 2022 312A 13 to 15 69 $638,000
Jul 2022 312A 22 to 24 69 $642,800

Source: HDB

We will use the average selling price of $626,971 for calculation purposes.


Description Amount
Selling price $626,971
Outstanding loan $238,000
CPF used plus accrued interest $164,000
Cash proceeds $224,971

Affordability (For a private property)


Description Amount
Maximum loan based on a fixed monthly income of $15K and ages 35 $1,728,055 (30 years tenure)
CPF funds $164,000
Cash $224,971
Maximum affordability based on CPF and cash of $388,971 $1,555,884
BSD based on $1,555,884 $46,835
Estimated affordability $1,509,049

Due to the available amount of CPF and cash that make up the 25per cent downpayment, you will not be able to take the maximum loan

Affordability (For an HDB)


Description Amount
Maximum loan based on a fixed monthly income of $15K and ages 35 $852,536 (25 years tenure)
CPF funds $164,000
Cash $224,971
Total loan + CPF + Cash $1,241,507
BSD based on $34,260
Estimated affordability $1,207,247

Option 1: Upgrade to a freehold condo in D9, 10, 11, 20 or 21

With a budget of $1.5 million, you’ll most likely be looking at a 1 + Study or a two-bedder in these locations. As you do not plan to have children, this should suffice but as most of these units are rather compact, it may take some getting used to from a 3-room HDB flat which is typically bigger in comparison.

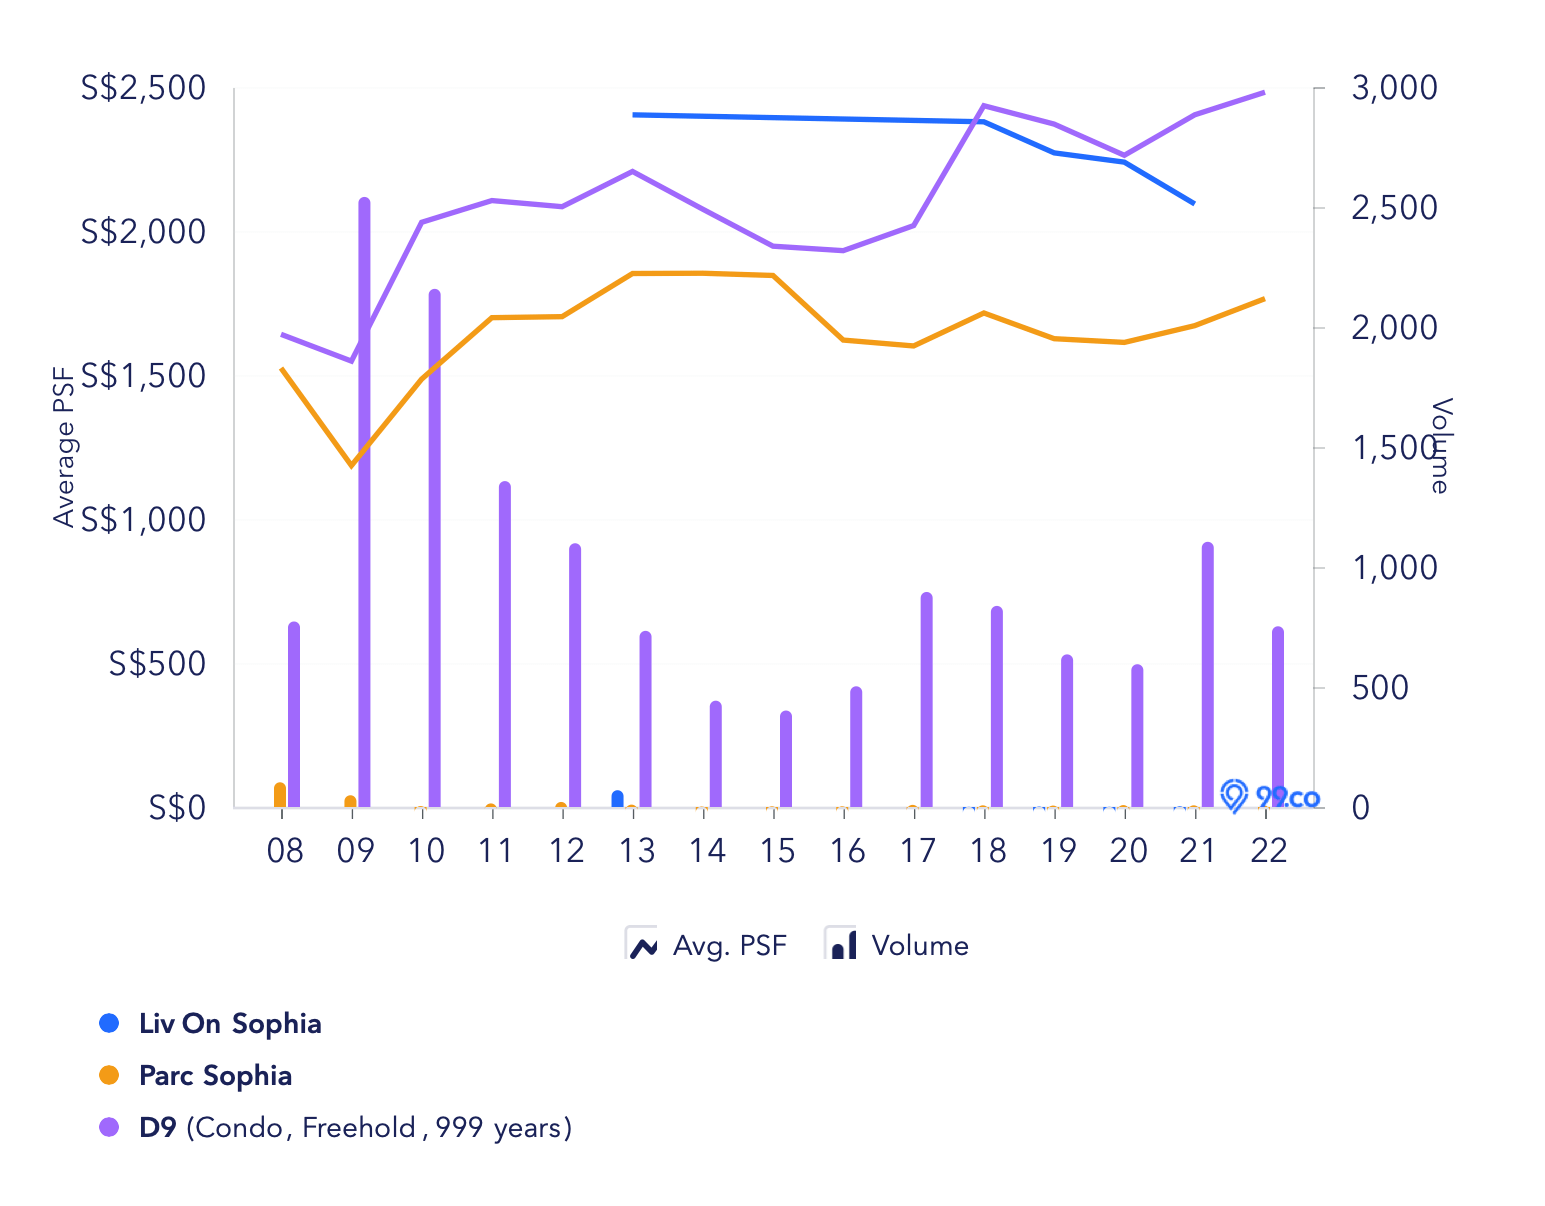
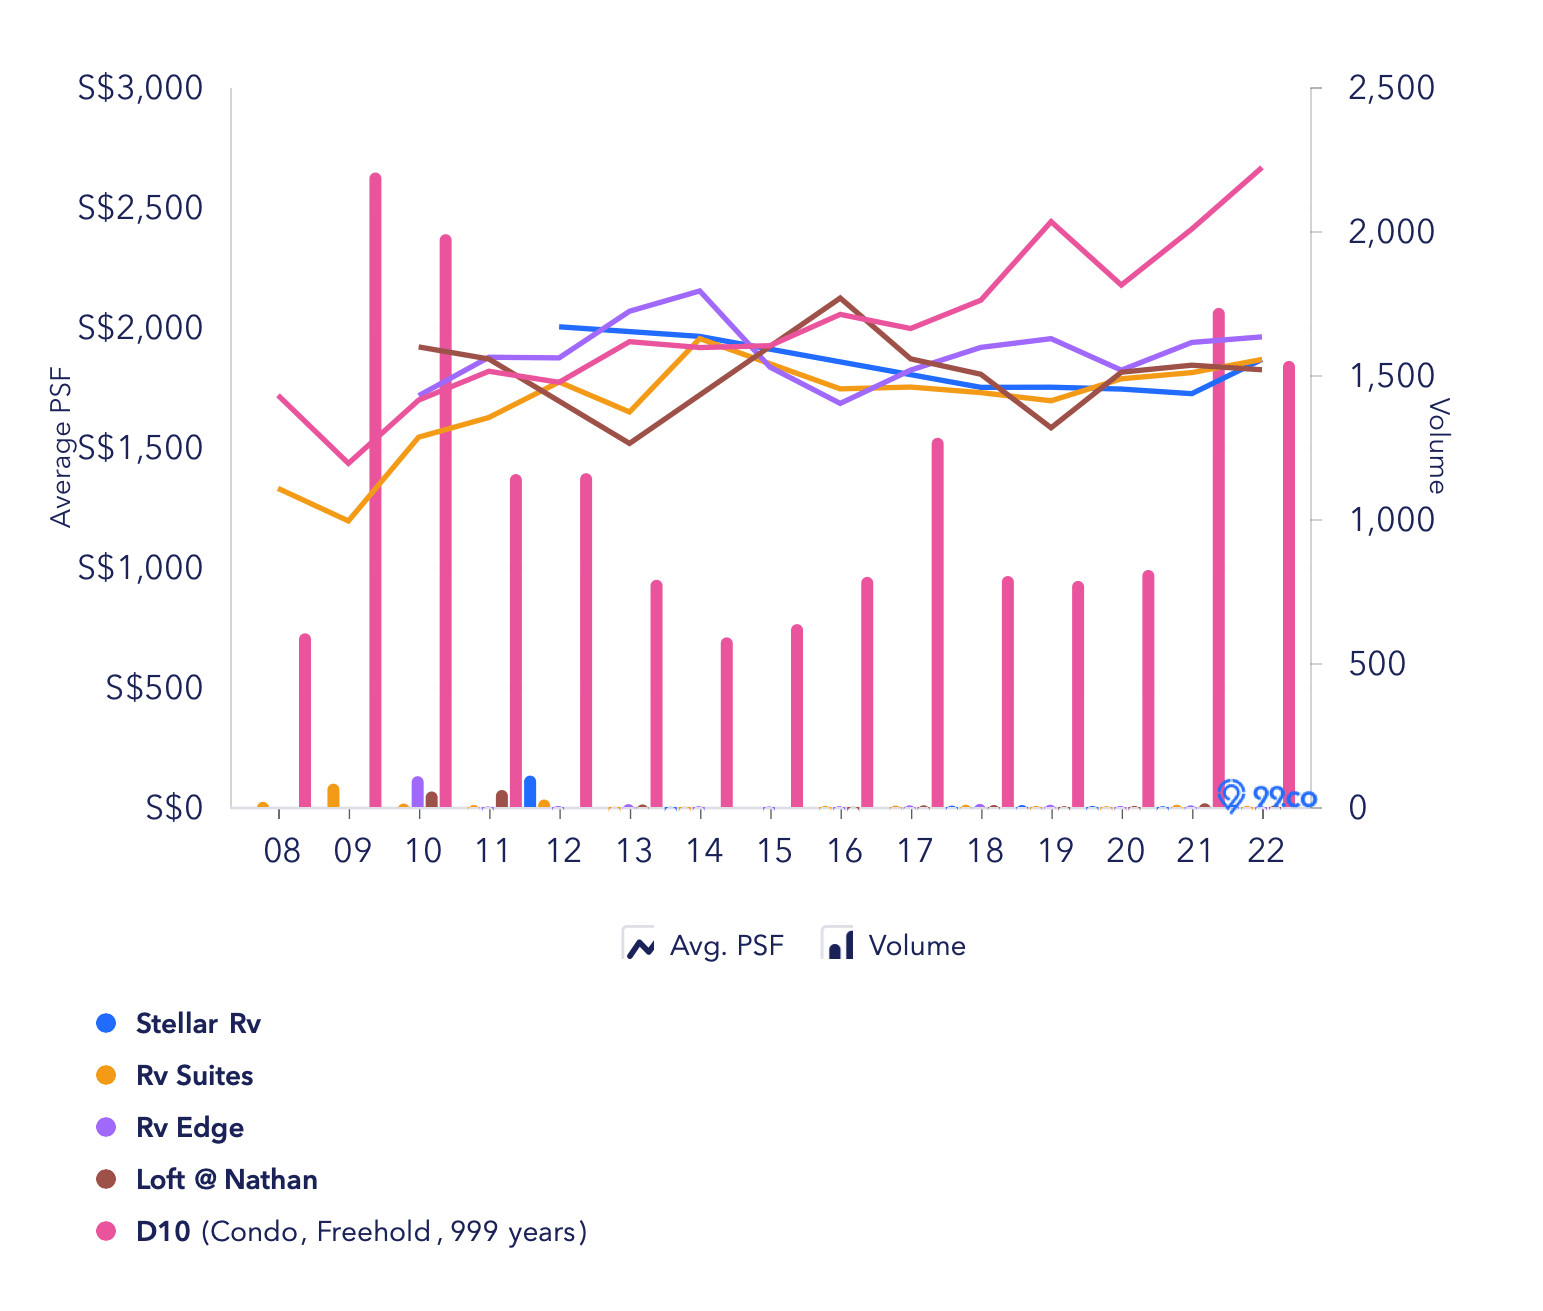
If you were to do a quick search online, you’ll see that the current pickings are rather slim, and the majority of the developments that fall within this price range are boutique projects.

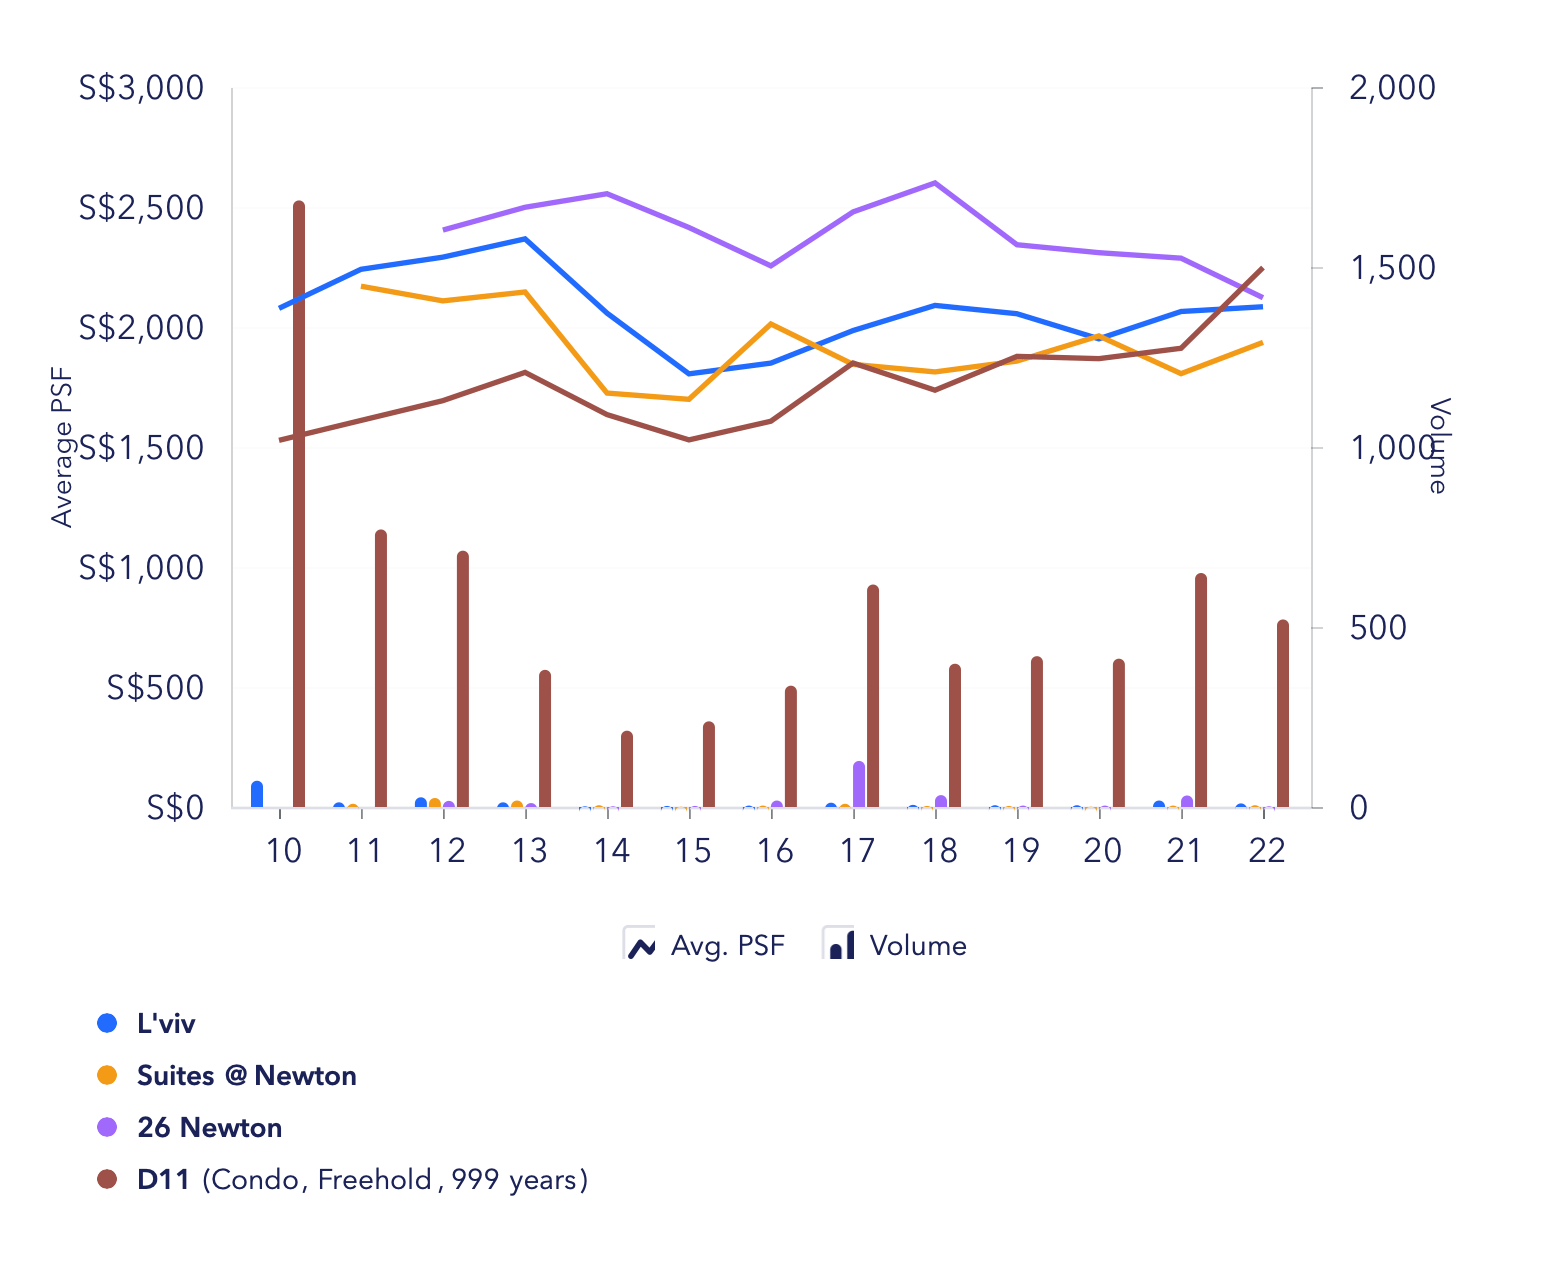
District 9 District 10 District 11 District 21
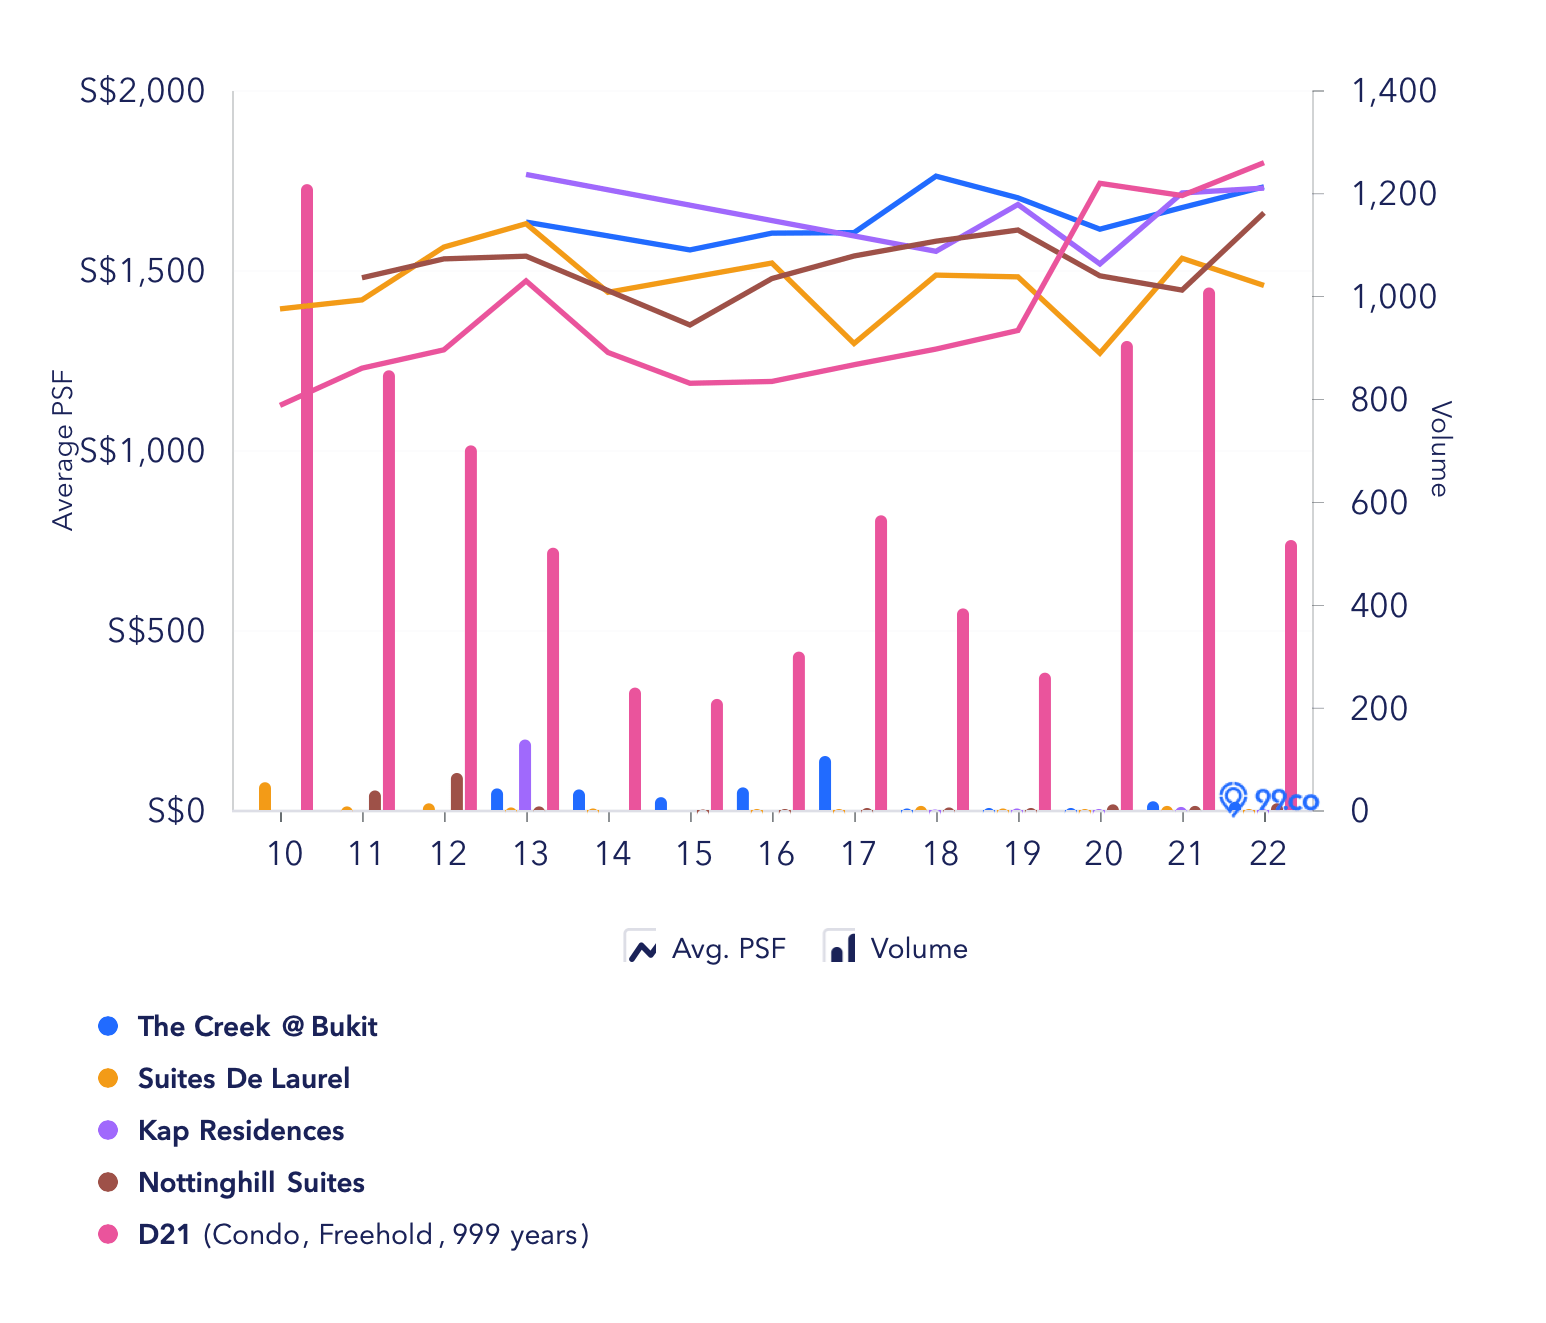
The developments shown above are those with available units that match your affordability. You’ll notice that after the launch, their transaction volumes are generally low, resulting in the trend lines appearing somewhat volatile. This is a usual concern with boutique developments because if the turnover rates are low, it is difficult for prices to move since banks value a property based on recent transactions. You can see from the graphs that prices are relatively stagnant for most of the projects, as compared to other freehold condos in the same district.

Also, many of these developments are made up of predominantly one and two- bedders which are catered more towards investors since the barriers to entry are lower. This is another issue as investors usually go wherever the money is, so if they find a better investment opportunity, they are less hesitant to let go of their units (even at a loss). This differs from genuine homeowners, who may be emotionally attached to their properties. It is advisable to get a development with a good unit mix, which caters to both homeowners as well as investors as prices are generally more protected.

Compared to an HDB flat, these projects are usually a better potential store of value. This is especially so in the long run as there is no lease decay issue. But if you’re looking for capital appreciation in the short to medium term, these may not be the best options.

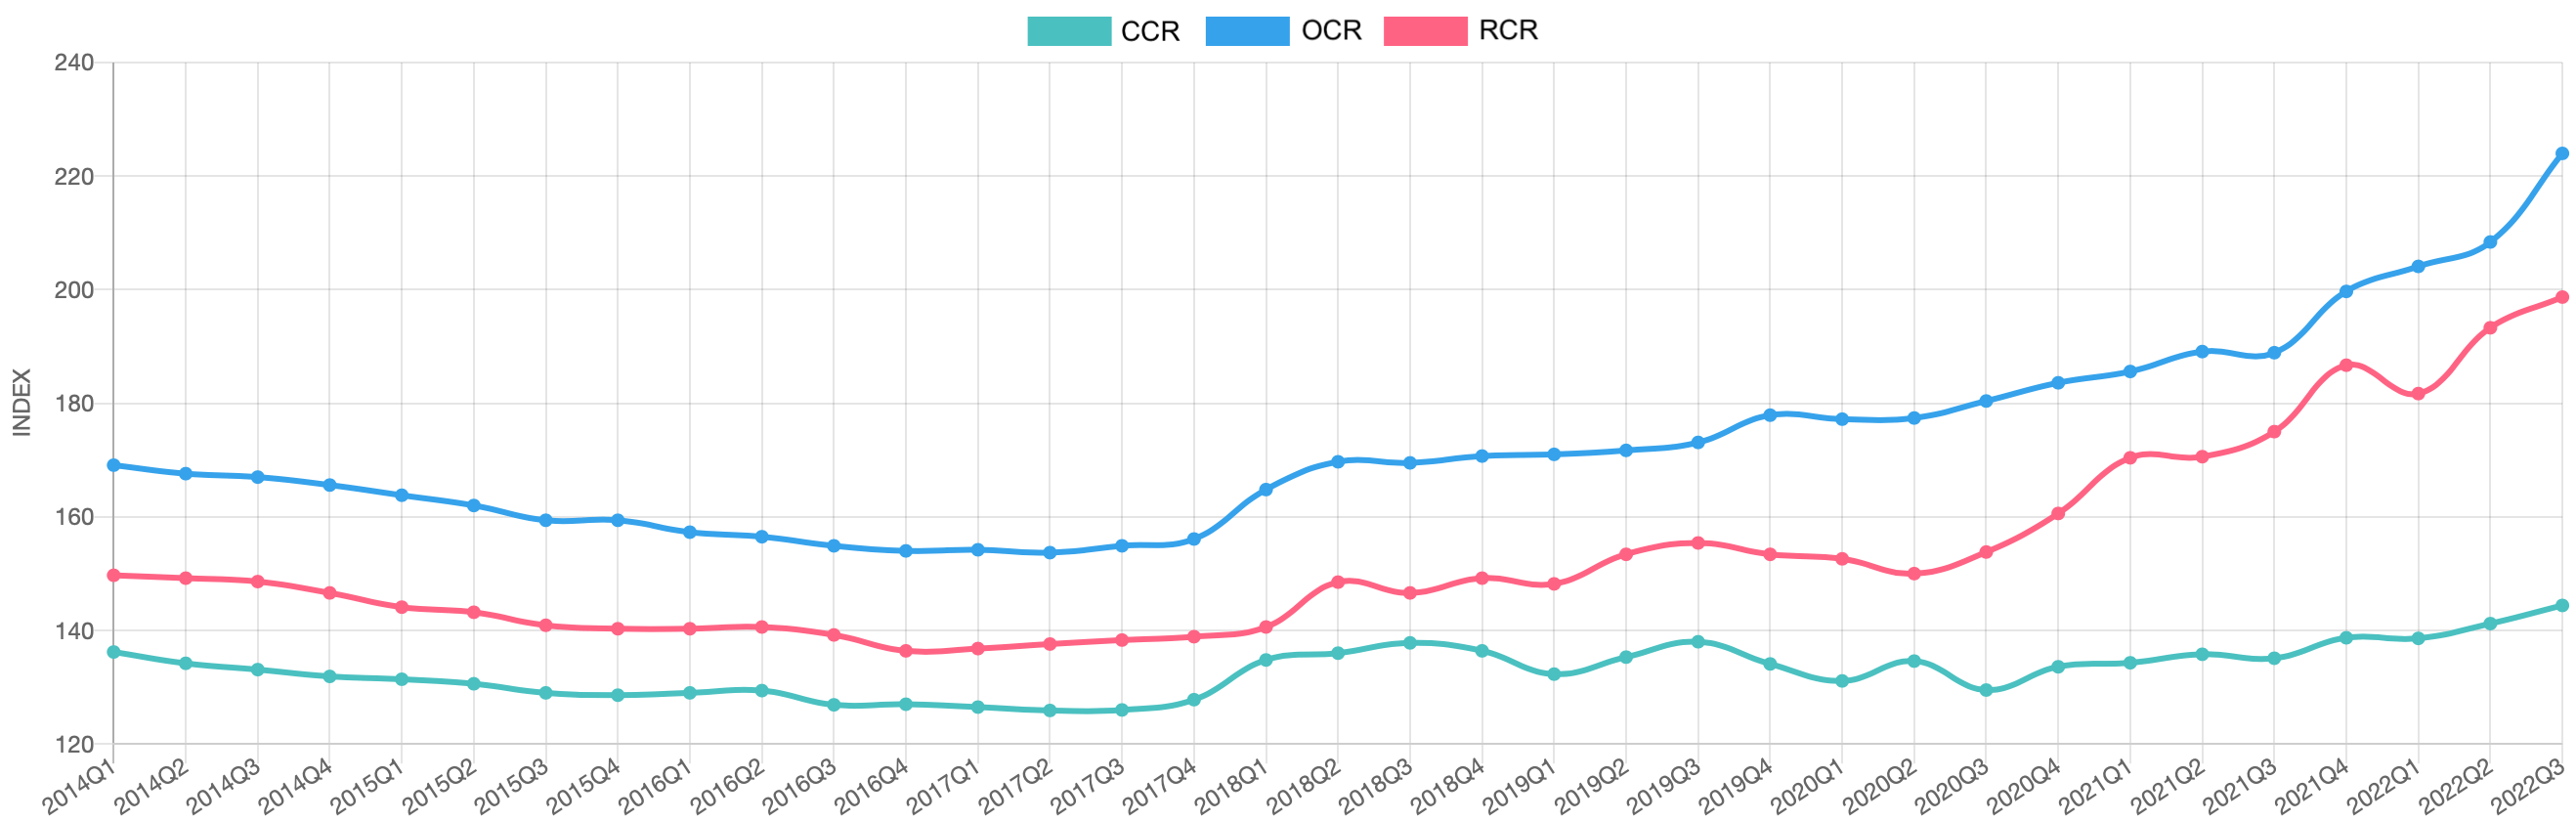
That being said, we do believe there is potential for growth in the CCR provided you select the right properties.

Property Price Index (PPI) of non-landed residential properties in the different regions
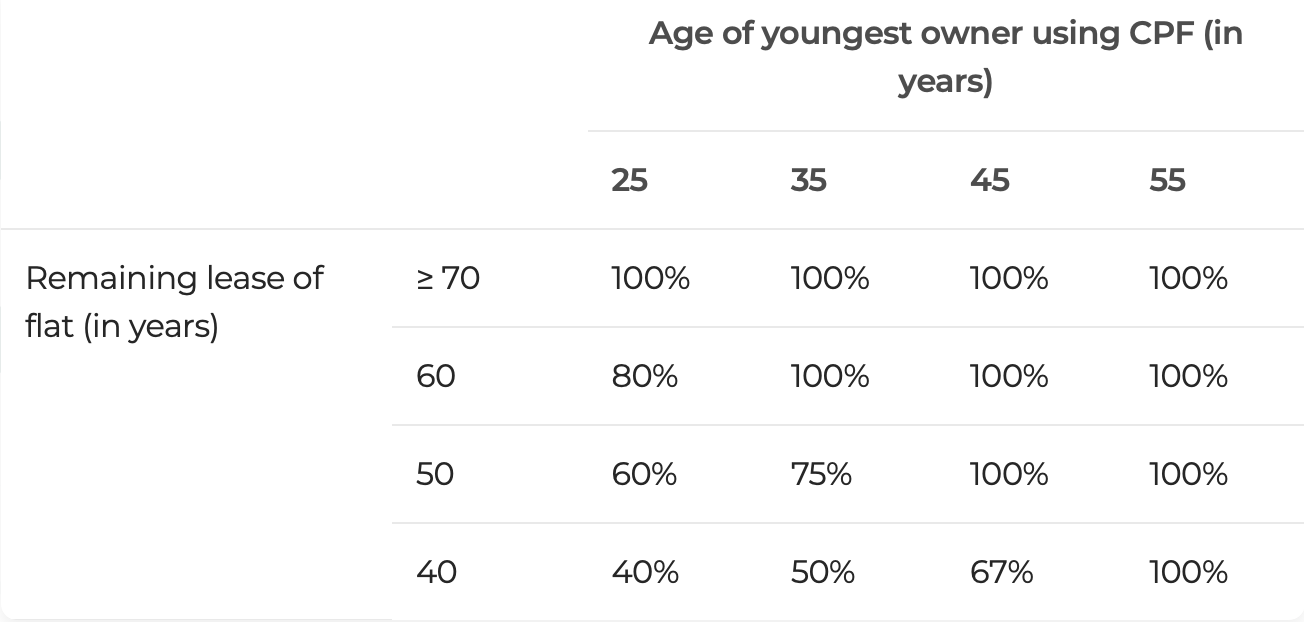


Price Indices Q1 2021 Q2 2021 Q3 2021 Q4 2021 2021 Q1 2022 Q2 2022 Q3 2022 Q4 2022 2022 (Flash)
  QoQper cent change QoQper cent change QoQper cent change QoQper cent change YoY per cent change QoQper cent change QoQper cent change QoQper cent change QoQper cent change YoY per cent change
Overall PPI 3.3 0.8 1.1 5.0 10.6 0.7 3.5 3.8 0.2 8.4
Landed 6.7 -0.3 2.6 3.9 13.3 4.2 2.9 1.6 0.5 9.5
Non-landed 2.5 1.1 0.7 5.3 9.8 -0.3 3.6 4.4 0.1 8.0
CCR 0.5 1.1 -0.5 2.7 3.8 -0.1 1.9 2.3 0.5 4.6
RCR 6.1 0.1 2.6 6.7 16.3 -2.7 6.4 2.8 2.6 9.2
OCR 1.1 1.9 -0.1 5.7 8.8 2.2 2.1 7.5 -2.6 9.3

Source: URA, Propnex Research

Drawing from the Property Price Index (PPI) in the different regions, we can see that prices in the RCR and OCR have appreciated significantly more than in the CCR in recent years. We do expect that prices in the CCR will eventually right themselves and the growth rate will catch up. We have recently also written a piece about the narrowing gap between prices of new RCR and CCR projects, which you can read here.

If CCR prices pick up can we expect prices of these boutique developments to pick up too?

Option 2: Save up to buy an additional investment property

Given that you currently own a flat, which we assume is under both your names, and have an outstanding housing loan, there are several things to take into consideration when purchasing a second property.

Loan-To-Value ratio (LTV)

When purchasing your first property, depending on your income, you may be eligible to loan up to a maximum of 75 per cent of the property value (for a bank loan). However, if you’re purchasing a second property while still repaying an existing mortgage loan for the first one, the LTV drops to 45 per cent of the property value.

Higher downpayment

As the LTV for a second property is reduced, naturally the downpayment increases. The downpayment is split into two portions; minimally 25 per cent needs to be paid in cash and the remaining 30 per cent can be paid using your CPF should you have sufficient funds.

Additional Buyer Stamp Duty (ABSD)

The current ABSD rate for Singaporeans buying a second property is 17 per cent which is on top of the regular BSD. Do note that when purchasing a private property, the stamp duty has to be paid in cash first, as this has to be done within 14 days after you have exercised the Option to Purchase (which isn’t enough time to apply for the withdrawal from CPF), and if you have sufficient funds in your CPF to pay for it, the cash will be reimbursed to you afterward.

CPF requirements

When buying a second property, you will need to set aside the following before you can utilise your CPF funds for the purchase:

  • The latest Basic Retirement Sum (BRS) if you have at least one property bought using CPF or the property that you are buying can cover you till age 95*
  • The latest Full Retirement Sum (FRS) if you do not have any property that can cover you till age 95

* If you subsequently sell the property that can cover you till age 95, you will need to set aside the FRS instead.

Also, the maximum amount of CPF that can be used for your second property depends on whether the remaining lease of this property can cover the youngest owner up to the age of 95.

Source: CPF

Let’s say you were to purchase a second property at $1 million for the sake of simple calculations:


Description Amount
Purchase price $1,000,000
25per cent cash downpayment $250,000
30per cent CPF/cash downpayment $300,000
BSD $24,600
ABSD of 17per cent $170,000

As we can see from the calculations above, the cash outlay required in order to purchase a second property is pretty substantial and it will likely take a long time to save up.

We’ve written a detailed piece on the merits of paying for the ABSD for an investment property, but in short, it’s not what we’d typically recommend.

Option 3: Upgrade to a larger flat (resale/BTO)

Being able to buy a BTO is a Singaporean privilege, and since we have two chances at it, most individuals/households will try for the second time if they are eligible. Of course, it’s much tougher the second time around given that only two to five per cent of BTO launches are set aside for second-timers. Also, the income ceiling to apply for a BTO is $14,000 which your household has unfortunately (or fortunately) exceeded so you are no longer eligible.

As you’ve mentioned you’re looking to build your retirement nest, buying a flat may not be the best investment choice. It is no doubt a good stepping stone for buyers looking to upgrade since you’d likely make some profits if you bought a BTO, or if you purchased a resale and managed to gain from the CPF Housing Grants.

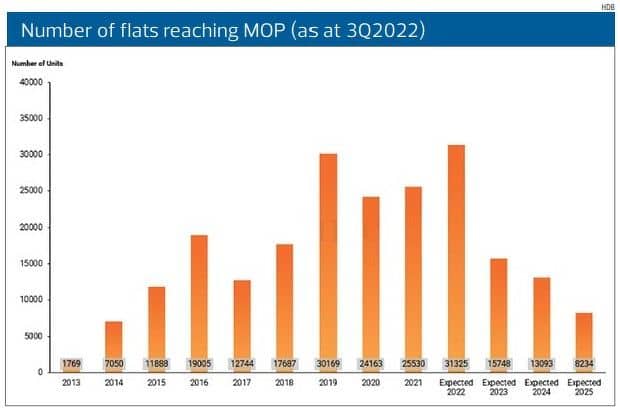
Source: Edgeprop

Given the reduced supply of newer MOP flats coming onto the resale market in the next couple of years, prices of HDB prices could still hold up in the short term. But even so, it is public housing after all; prices are regulated by the government in order to keep them affordable for the masses.

Alternative option

We’ve said this many times before, but a freehold property does not necessarily mean it’s better than a leasehold, and there are many other factors that contribute to the performance of a property besides its tenure. Perhaps instead of looking at freehold options in the districts you’ve identified, you can look at leasehold options instead, which will give you more choices to choose from. And if you were to open up to other locations, you’d have even more options.

These are some available 99-year leasehold units on the market that is within your affordability:


Project District Completion year Unit type Size Asking price
Sophia Hills 09 2018 2b2b 689 $1,482,000
The Panorama 20 2019 2b2b 797 $1,488,888
Thomson Impressions 20 2019 2b2b 764 $1,500,000
Sky Vue 20 2017 2b2b 678 $1,380,000
Daintree Residences 21 2023 2b2b 679 $1,399,999

These projects are picked out based on the fact that they are in your preferred districts, and for their age, so they may or may not be the most suitable for you. We would suggest you consult with an agent for further analysis.

In the ideal situation, you’ll stay in this property for the short to medium term and if it does appreciate well over the next few year, you can then upgrade again; perhaps to a bigger unit or a freehold development, which you can then live in for the longer term. You can eventually cash out for your retirement while you right size to a smaller unit.

Conclusion

Let’s do a quick recap of the options:

For the first option of buying a freehold condominium in District 9, 10, 11, 20, or 21, your choices are rather limited and the available developments are mostly boutique projects (which as mentioned, we do have some concerns over). You will have to pick carefully, as a freehold property definitely doesn’t always mean it will be a good investment.

The second option of saving up to purchase a second property for investment will require a huge cash outlay, which may take a considerable amount of time to save up for.

As for the last option of upgrading to a bigger HDB, unfortunately, your household is no longer eligible to apply for a second BTO due to your income. Regardless, buying an HDB is not the best investment tool given that it is after all a regulated market.

We will suggest looking at some younger leasehold developments that still have the potential for growth which will open you up to more choices. You can stay in this property while you wait for it to appreciate and from there, move on to a bigger unit or a freehold development where you can stay for the long term. As you’re only in your mid-30s, you’re able to maximise the loan tenure. We get that moving might be a pain, but it’s inevitable if you wish to cash out on your property which will go towards building your retirement nest.

ALSO READ: We make $15k per month and live in a 4-room HDB flat. Should we upgrade to a condo now once interest rates drop?