How Much Will Capital Gains Tax on Real Estate Investment Property

How Much Will Capital Gains Tax on Real Estate Investment Property

SmartAsset: Capital gains tax on real estate investment property

SmartAsset: Capital gains tax on real estate investment property

Real estate investments can be lucrative assets. However, they can also incur capital gains taxes that weaken your profits. Fortunately, you can implement tactics that reduce capital gains taxes so you can keep more of your money. Although the IRS taxes short-term and long-term gains differently, you can combat high tax rates on both. We’ll explain short-term and long-term capital gains and how to keep the associated taxes from costing you an arm and a leg.

A financial advisor can help you tax-optimize your investment portfolio. Find a financial advisor today.

What Are Capital Gains Taxes?

You pay capital gains taxes when you profit from selling assets. You can incur two types of capital gains taxes: short-term and long-term. Short-term capital gains are from selling assets you’ve held for less than a year. On the other hand, long-term capital gains come from selling assets after holding them for a year or more. So, if you sell an investment property, the time you owned it before selling it will determine what kind of capital gains taxes you pay.

How Are Capital Gains Taxed?

The IRS taxes short-term capital gains as standard income, meaning your income tax bracket will determine your tax rate. Income tax brackets are as follows: 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Your income determines your capital gains tax rates.

For example, say you make $85,000 from your day job. You sell an investment property nine months after purchasing it and make a $30,000 profit. The sale results in a short-term capital gain, and your income is $115,000 when you file taxes. In addition, you’re a single filer, putting a portion of your income in the 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} tax bracket.

Conversely, long-term capital gains have different tax rates than short-term gains: 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, depending on your income level and filing status. For 2023, single filers making up to $44,625 receive the 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate. Single filers with income between $44,626 and $492,300 will pay 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Finally, single filers with income above $492,300 will pay 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} long-term capital gains taxes. In addition, single filers making $125,000 or more annually will pay a net investment income tax of 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on capital gains from real estate.

A married couple filing 2023 taxes jointly will pay 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} if they earn up to $89,250. The 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate applies if the couple earns $89,251 to $553,850. The 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate applies if they earn more than $553,850.

How to Limit Capital Gains on Real Estate Investment Properties

SmartAsset: Capital gains tax on real estate investment property

SmartAsset: Capital gains tax on real estate investment property

You can use a variety of strategies to avoid capital gains on real estate properties:

Use Tax-Deferred Funds

You don’t have to invest in real estate with dollars from your bank account. Instead, you can use your individual retirement account (IRA) or 401(k). Depositing investment profits in your investment account allows your money to grow tax-free. Plus, your IRA contributions can garner you another tax deduction.

Make the Property Your Primary Residence

The internal revenue service (IRS) exempts primary residence sales from capital gains taxes up to $500,000 for married joint filers and $250,000 for single filers. You can also avoid paying taxes on depreciation deductions this way. Using this option means fulfilling the following requirements:

  • Owning the home for two or more of the last five years

  • Living in the home as the primary residence for two or more of the last five years

  • You haven’t taken a primary residence exemption in two years

Tax-Loss Harvesting

Tax-loss harvesting means deliberately selling an asset for a loss to mitigate profits from another asset. Therefore, you can sell a property for less than you bought it, reducing your taxes.

For instance, say you sell one property and make $30,000. You don’t want to pay taxes on this gain, so you sell another property for $25,000 less than what you paid. As a result, you pay taxes on $5,000 of capital gains.

1031 Exchange

The depreciation deduction for rental properties has one major drawback: when you sell a rental property, you owe taxes on the depreciation amount (if you received any). Fortunately, the 1031 exchange allows you to circumvent this rule.

The 1031 exchange means using the income from the sale of an investment property to purchase another investment property of equal or greater value. Then, you don’t have to pay taxes on prior depreciation deductions. This caveat allows you to avoid income taxes on depreciation into perpetuity if you buy another property of equal or greater value.

How to Minimize Your Capital Gains Tax

Even if you can’t altogether avoid capital gains taxes, the following tactics will minimize your capital gains taxes:

Depreciation Deduction

The IRS allows rental property owners to deduct an annual depreciation amount from their income. The deduction comes from the expected lifespan of rental property, which the IRS defines as 27.5 years. As a result, you can calculate your depreciation deduction by dividing your rental property value by 27.5 (commercial real estate uses the lifespan figure of 39 years).

For instance, say you have a $250,000 residential investment property. Dividing this figure by the depreciation deduction lifespan of 27.5 gives you an annual deduction of $9,090.

Itemized Deductions

Generally, you can deduct the costs of managing property, lowering your tax burden. Running your real estate investment business incurs costs such as travel, legal fees, and business equipment. These expenses can add up – but instead of hurting your wallet, they can create a tax benefit.

In addition, you can deduct mortgage interest and the costs of repairing or maintaining a property. Therefore, keeping detailed records and saving every receipt is vital to claiming as many deductions as possible.

Methods to Boost Property Basis

SmartAsset: Capital gains tax on real estate investment property

SmartAsset: Capital gains tax on real estate investment property

Improving your property gives two financial advantages: the costs of doing so can shrink your capital gains taxes, and the improvements can bolster your property value. Here’s how you can boost property basis:

  • New windows and doors

  • Updated appliances, roofing, and flooring

  • Renovate plumbing, electrical, and HVAC systems

  • Paying commissions to real estate agents

  • Expenses for the appraisal, inspection, and legal services

  • Closing costs, including title search, escrow, and taxes

Bottom Line

Capital gains taxes can curb your profits from real estate investments. Fortunately, multiple deductions and tax strategies can lower your tax burden. For example, you can deduct depreciation and make a home your primary residence before you sell it. In addition, upgrading your home can boost your property basis and lower your capital gains taxes. So, it’s essential to be thorough in your research and record keeping to ensure you minimize capital gains taxes on real estate investments.

Tips on Capital Gains Tax on Real Estate Investment Property

  • You can make the most of your real estate investments by familiarizing yourself with relevant tax laws. A financial advisor can help you understand your financial position and make the most of your tax return. Finding a qualified financial advisor doesn’t have to be hard. SmartAsset’s free tool matches you with up to three vetted financial advisors who serve your area, and you can interview your advisor matches at no cost to decide which one is right for you. If you’re ready to find an advisor who can help you achieve your financial goals, get started now.

  • Check out our free capital gains capital gains tax calculator for a quick estimate of what you’ll owe.

  • If you’re considering starting a real estate venture, it’s wise to do your homework first. Use this guide for how to buy investment property.

Photo credit: ©iStock.com/Perawit Boonchu, ©iStock.com/ArLawKa AungTun, ©iStock.com/ArLawKa AungTun

The post Capital Gains Tax on Real Estate Investment Property appeared first on SmartAsset Blog.

Residential real estate investors and investment properties in 2020

Residential real estate investors and investment properties in 2020

Overview

For the first time, the Canadian Housing Statistics Program (CHSP) is publishing data on investors. This article presents a profile of these owners and the residential properties they owned in the provinces of Nova Scotia, New Brunswick, Ontario, Manitoba and British Columbia in 2020.

Key findings

  • The proportion of investors among owners varied from 20.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Ontario to 31.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nova Scotia.
  • Among houses and condominium apartments, just under one in five properties was used as an investment in British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia combined.
  • Condominium apartments were used as an investment more often than houses (single-detached houses, semi-detached houses, row houses, and mobile homes). Ontario topped the list with the highest rate of condominium apartments used as an investment, at 41.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
  • Houses used as an investment were mainly owned by individuals living in the same province as the property.

Introduction

Residential properties can be owned for several reasons: for use as a primary place of residence, but also for occasional use as a secondary residence, to generate income or other investment purposes. When properties are owned by investors, they can contribute to the rental housing supply—and therefore meet the population’s need for rental housing—but that can also limit the number of properties available to buyers who intend to use it as a primary place of residence. Data from the 2021 Census showed that the proportion of Canadian households who owned their home fell from 69.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2011 to 66.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2021. This article distinguishes between investors and other types of owners to better understand the profile of investors, what they own, and the role they play in the market.

This topic is especially important since, in the United States, the study by Haughwout et al. (2011) showed an increase in the proportion of investors among buyers from 2000 to 2007, when a housing bubble emerged. These borrowers then contributed considerably to the rise in delinquency rates during the 2007/2008 housing crisis. Analyzing the subsequent period in the United States (2009 to 2013), the study by Allen et al. (2018) also found that an increase in the percentage of houses purchased by investors in a given area led to higher prices in that market.

North of the border, the Bank of Canada (2022) analyzed the importance of investors—defined as buyers who own multiple mortgaged properties—and found an increase in the proportion of purchases by investors in Canada in the first half of 2021. Teranet (2022) made a similar observation in an analysis of transactions carried out by owners of multiple properties in Ontario. The Canada Mortgage and Housing Corporation (2016) also investigated investors — defined as households who own a primary residence and at least one secondary condominium unit — using a survey of condominium owner households in Toronto and Vancouver. They found that 48.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of investors in 2015 stated that their secondary unit was rented out while 42.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} stated that they or a family member were using the unit.

In this release, the CHSP follows a different approach by identifying properties owned by investors among the entire stock of residential properties in Nova Scotia, New Brunswick, Ontario, Manitoba and British Columbia for the reference year 2020.Note The findings provide a snapshot of the situation in these provinces before the COVID-19 pandemic and can therefore be used as a point of comparison to determine the effects of the public health crisis when examining subsequent years.

What is an investor?

In this analysis, owners are divided into three categories: investors, investor-occupants, and non-investors.

An investor is defined as an owner who owns at least one residential property that is not used as their primary place of residence. Individual owners who own a single property in the same province as where they reside are not considered investors, so long as it is not a property with multiple units.

Specifically, the following owners are considered to be investors:

  • A business or government that owns at least one residential property, excluding Canadian non-profit organizations.Note Given the predominance of businesses in this category, they will simply be referred to as “business” in what follows.
  • An individual owner who is not resident in Canada, referred to as a “non-resident investor” below.
  • An individual owner who lives outside the province where they own residential property, referred to as an “out-of-province investor” in the province of the non-principal residence.
  • An individual owner who lives in the province and owns two or more residential properties, or owns a property with multiple residential units who does not occupy that property. These individuals will be referred to as “in-province investors”.

The investor category thus can include, among others, secondary residence owners, landlords, short-term rental owners, developers, for-profit businesses and speculators.

An owner is classified as an investor-occupant if they own a single property with multiple residential units, one of which is their primary place of residence. For example, this category includes owners of a house with a laneway unit or basement suite and owners of a duplex who live in one of the units. In all cases, at least one of the units must be occupied by one of the owners.

An owner is classified as a non-investor when they are not an investor or an investor-occupant. This category primarily includes owners who live in the province where the property is located, who own a single property, and this property does not have multiple residential units. Canadian non-profit businesses are also included in this category.Note

More than one in five owners is an investor

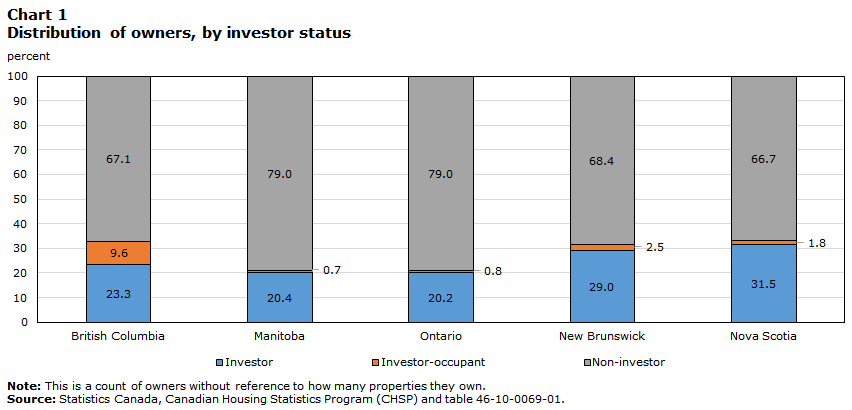
For British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia combined, CHSP data show that a total of 21.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners were investors in 2020. The proportion of investors was higher in Nova Scotia (31.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and New Brunswick (29.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) than in British Columbia (23.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Manitoba (20.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Ontario (20.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
Residential real estate investors and investment properties in 2020

Data table for Chart 1


Data table for chart 1

Table summary

This table displays the results of Data table for chart 1 British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia, calculated using percent units of measure (appearing as column headers).

British Columbia Manitoba Ontario New Brunswick Nova Scotia
percent
Investor 23.3 20.4 20.2 29.0 31.5
Investor-occupant 9.6 0.7 0.8 2.5 1.8
Non-investor 67.1 79.0 79.0 68.4 66.7


This difference is largely due to a higher proportion of vacant land in the two Atlantic provinces, which is a type of property often owned in addition to the primary place of residence. The proportion of investors who live in the province and own one or two pieces of vacant land in addition to their primary place of residence was 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nova Scotia and 7.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in New Brunswick. If we remove this type of investor, the rate of investors falls to 24.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nova Scotia and 21.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in New Brunswick. The proportions of investors are then more comparable to those of the other provinces.

Given that the stock of vacant land is proportionally lower and more expensive in British Columbia and Ontario, less than 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners in these provinces were in-province investors who owned one or two pieces of vacant land in addition to their primary place of residence. In Manitoba, the proportion of homeowners in this situation was also low, at 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Investor-occupants are more common in British Columbia, where they made up 9.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of owners. This higher proportion is mostly due to the composition of the housing stock. In this province, properties with multiple residential units represented 11.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the stock, a higher proportion than in the other provinces, where it varied from 2.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Ontario to 5.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nova Scotia. This higher percentage in British Columbia was mostly attributable to many residences with a laneway unit or a basement suite among properties with multiple residential units. These kinds of properties were more likely to be occupied by the owner when compared to apartment buildings in British Columbia and elsewhere.

How is the investment status of the property defined?

An analysis of properties used as an investment helps clarify the role that investors play in the housing market. The investment status of the property is determined by analyzing the investor status of the owner and the use of the property. Properties are divided into one of the following three categories: an investment property, an owner-occupied investment property, and a non-investment property.Note

An investment property is defined as a property owned by at least one investor that is not the primary place of residence of any of the owners. This can include, for example, a rented property with one or more units, a cottage or a property owned for speculative purposes.

If the property is not included in the previous category, it can be considered an owner-occupied investment property if it is a property with multiple residential units where at least one of the owners occupies a unit.Note

Finally, the non-investment property category includes properties owned only by non-investors or those used as a primary place of residence by at least one of the owners.

The proportion of investment properties varies greatly by the type of property analyzed. Vacant land and properties with multiple residential units are used more for investment than single-detached houses, semi-detached houses, row houses, and mobile homes — which we refer to as “houses” in this article — and condominium apartments.

In all the provinces analyzed in this study combined, more than 9 in 10 vacant lots were investment properties or were owned by a non-profit organization. The remainder were owned by individuals residing in the province where they owned a single vacant lot. Similarly, for all these provinces, 96.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of properties with multiple residential units were either investment properties (45.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) or owner-occupied investment properties (51.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), while the rest were owned by non-profit organizations. However, these proportions varied from one province to another. In British Columbia, 73.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of properties with multiple dwellings were owner-occupied investment properties. By contrast, in the other provinces, the majority of properties with multiple dwellings were investment properties, with the proportion reaching 72.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Manitoba.

As a result, provinces with a large stock of vacant land, such as New Brunswick and Nova Scotia, and those with a high proportion of properties with multiple residential units, such as British Columbia, had high rates of investors or investor-occupants. The portrait shifts when the focus is on houses and condominium apartments, which are more likely to be owner-occupied, and therefore not used for investment purposes. In the following sections, the analysis of properties focuses exclusively on houses and condominium apartments, and excludes properties with multiple dwellings and vacant land.

In Nova Scotia, more than 1 in 20 houses is used as an investment by a person living outside the province or the country

The analysis by property type found that investors were drawn more to condominium apartments than houses. The share of houses used as an investment varied from 14.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in New Brunswick to 20.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nova Scotia, with an overall average of 15.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for all five provinces. By comparison, this same statistic for condominium apartments was 39.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. For the five provinces, a total of 918,695 houses were used as an investment, 584,615 of which were in Ontario. A regional analysis found that the proportion of houses used as an investment was generally higher in more touristic regions, where there may be more cottages.

In-province investors owned, as investment properties, between 8.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the houses in New Brunswick and 12.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nova Scotia, and, as such, they owned more houses used as an investment than all the other types of investors combined.
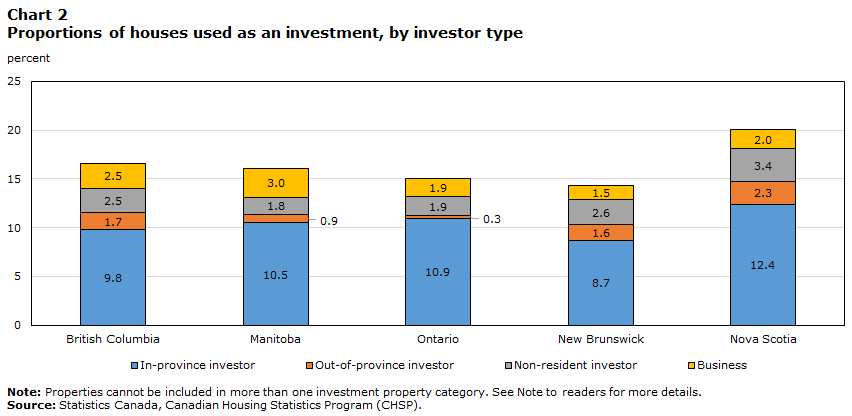
Chart 2: Proportions of houses used as an investment, by investor type

Data table for Chart 2


Data table for chart 2

Table summary

This table displays the results of Data table for chart 2 British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia, calculated using percent units of measure (appearing as column headers).

British Columbia Manitoba Ontario New Brunswick Nova Scotia
percent
In-province investor 9.8 10.5 10.9 8.7 12.4
Out-of-province investor 1.7 0.9 0.3 1.6 2.3
Non-resident investor 2.5 1.8 1.9 2.6 3.4
Business 2.5 3.0 1.9 1.5 2.0


Out-of-province investors owned proportionally fewer houses used as an investment in Ontario (0.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) than out-of-province investors in the other provinces, which is likely partly due to higher real estate prices in Ontario than most of the provinces. Nova Scotia, New Brunswick and British Columbia seemed more popular with out-of-province investors, who owned, as investments, 2.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 1.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 1.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of houses, respectively. New Brunswick and Nova Scotia may have attracted residents from other provinces with lower average housing prices than in other provinces. As for British Columbia, the number of out-of-province investors was particularly high in the areas near the Alberta border. In British Columbia, non-residents and out-of-province investors owned 43,890 houses used as an investment.

Condominium apartments are more popular with investors than houses

The share of condominium apartments used as an investment was higher than for houses, varying from 22.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in New Brunswick to 41.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Ontario and totalling 39.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for all five provinces. Although this share was higher in Ontario and British Columbia (36.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) than in Manitoba (29.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and New Brunswick, this does not appear to be attributable to the large census metropolitan areas (CMAs) in those provinces. In fact, the rate of condominium apartments used as investment was lower in the CMAs of Toronto (36.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Vancouver (34.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) than the rate in the rest of their respective provinces.
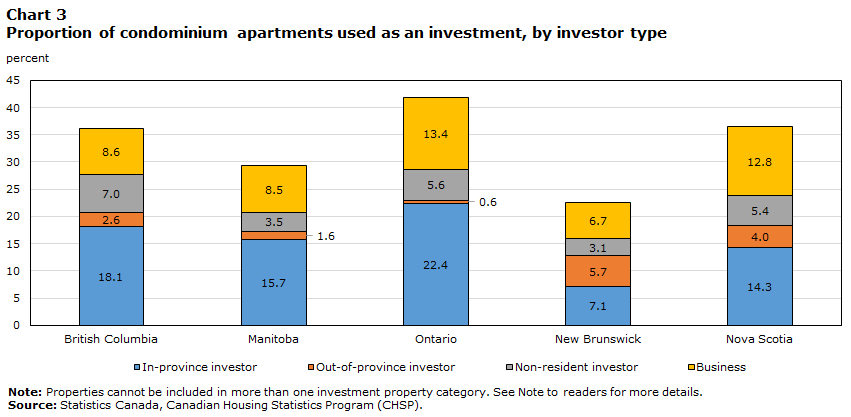
Chart 1: Proportion of condominium apartments used as an investment, by investor type

Data table for Chart 3


Data table for chart 3

Table summary

This table displays the results of Data table for chart 3 British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia, calculated using percent units of measure (appearing as column headers).

British Columbia Manitoba Ontario New Brunswick Nova Scotia
percent
In-province investor 18.1 15.7 22.4 7.1 14.3
Out-of-province investor 2.6 1.6 0.6 5.7 4.0
Non-resident investor 7.0 3.5 5.6 3.1 5.4
Business 8.6 8.5 13.4 6.7 12.8


There was a higher rate of business-owned investment properties among the condominium apartment stock than in the stock of houses. In Ontario, businesses owned 74,485 condominium apartments for investment purposes, or 13.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all properties of this type, which is the highest share among the provinces analyzed. Nevertheless, most condominium apartments used as an investment in both Ontario and Manitoba were owned by in-province investors. In the other jurisdictions, this was not the case.

The proportion of condominium apartments owned for investment purposes by non-resident investors was the highest in British Columbia (7.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), followed by Ontario (5.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

More investment properties outside CMAs and census agglomerations (CAs) seem to be used as a secondary residence

While some investors rent out their investment property, others may use it as a secondary residence. Properties located outside CMAs and CAs are more likely to be used as secondary or recreational properties, such as cottages, when the owners are residents of the province and only own one additional property outside the region of their primary residence.Note These properties may or may not be rented.

Outside the major centres, this type of investment made up between 3.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of houses and condominium apartments in New Brunswick and 11.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Ontario. In the latter, this amounted to 70,610 properties, or 1.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all houses and condominium apartments in the province. Of these, more than 99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} were houses, while condominium apartments, which are less common outside major centres, represented less than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the investment properties of this type.

In British Columbia and, to a lesser extent, Nova Scotia, the share of potential secondary residences owned by out-of-province investors was higher than in the other jurisdictions. In British Columbia, investment properties owned by out-of-province residents represented 6.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the houses and condominium apartments outside CMAs and CAs, while the figure for Nova Scotia was 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
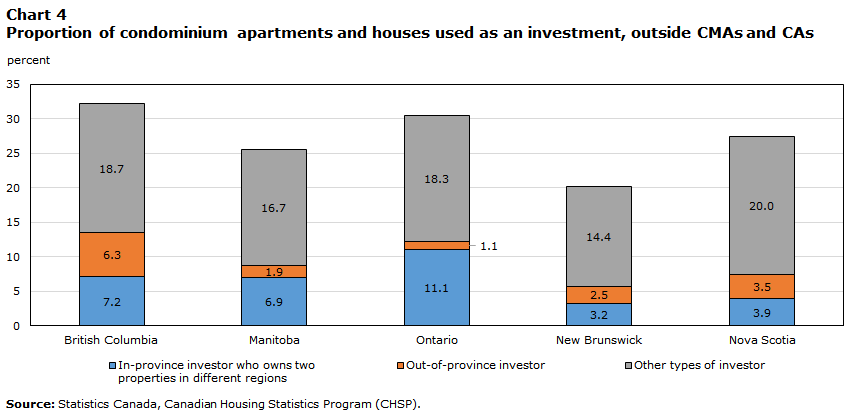
Chart 4: Proportion of investment properties outside CMAs and CAs among condominium apartments and houses

Data table for Chart 4


Data table for chart 4

Table summary

This table displays the results of Data table for chart 4 British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia, calculated using percent units of measure (appearing as column headers).

British Columbia Manitoba Ontario New Brunswick Nova Scotia
percent
In-province investor who owns two properties in different regions 7.2 6.9 11.1 3.2 3.9
Out-of-province investor 6.3 1.9 1.1 2.5 3.5
Other types of investor 18.7 16.7 18.3 14.4 20.0


Although a secondary residence could also be a pied-à-terre in the city, this seemed less common. In large urban centres, the proportion of houses and condominium apartments used as an investment owned by residents from outside the region or the province was lower than in areas outside CMAs or CAs. This proportion was highest in the CAs and CMAs in Nova Scotia (2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and British Columbia (2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). In CMAs and CAs of the five provinces, the second property of in-province investors living in a different region was more often a condominium (23.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of cases) than was the case outside major centres.
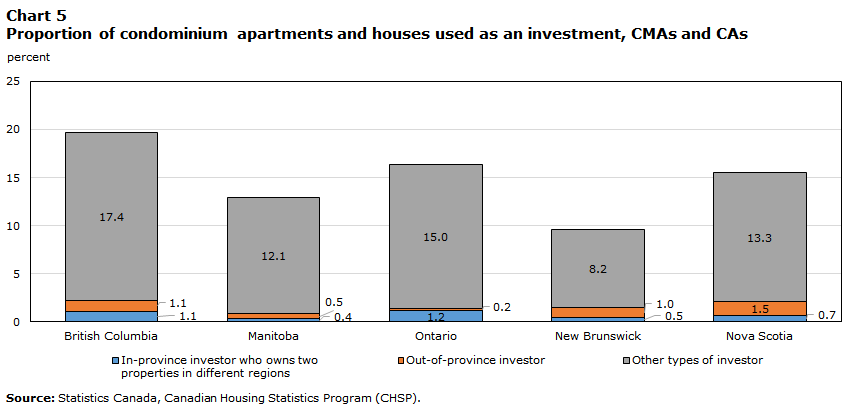
Chart 5: Proportion of investment properties among condominium apartments and houses, CMAs and CAs

Data table for Chart 5


Data table for chart 5

Table summary

This table displays the results of Data table for chart 5 British Columbia, Manitoba, Ontario, New Brunswick and Nova Scotia, calculated using percent units of measure (appearing as column headers).

British Columbia Manitoba Ontario New Brunswick Nova Scotia
percent
In-province investor who owns two properties in different regions 1.1 0.4 1.2 0.5 0.7
Out-of-province investor 1.1 0.5 0.2 1.0 1.5
Other types of investor 17.4 12.1 15.0 8.2 13.3


In the Toronto and Vancouver CMAs, investment properties were concentrated in the downtown core

In both Toronto and Vancouver CMAs, there was a higher proportion of investment properties in the core census subdivisions (CSDs). In the Vancouver CMA, the Greater Vancouver ANote CSD was the one exception, with a higher proportion of houses and condominium apartments used as an investment (42.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) than in the other CSDs in the region. This is consistent with other trends observed for Greater Vancouver A. According to the 2021 Census, this CSD had a higher proportion of renters (57.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of households) than in the rest of the CMA. This difference is partially due to the students who attend the University of British Columbia, which is located in this area. Students are more likely to be renters, but they could also be owners, or they could live in a second property owned by a family member. In addition, this CSD had the highest non-resident ownership rate (14.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) in the CMA in 2020.

In the City of Vancouver, which is the core CSD, the proportion of houses and condominium apartments used as an investment was 32.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, the second highest proportion in the Vancouver CMA, which had an overall rate of 21.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The higher share of investment properties in the core CSD is partly due to a greater concentration of condominium apartments, which are more often used as an investment. However, even considering condominium apartments and single detached houses separately, both had a higher rate of properties used as an investment in the Vancouver CSD than in the rest of the CMA.
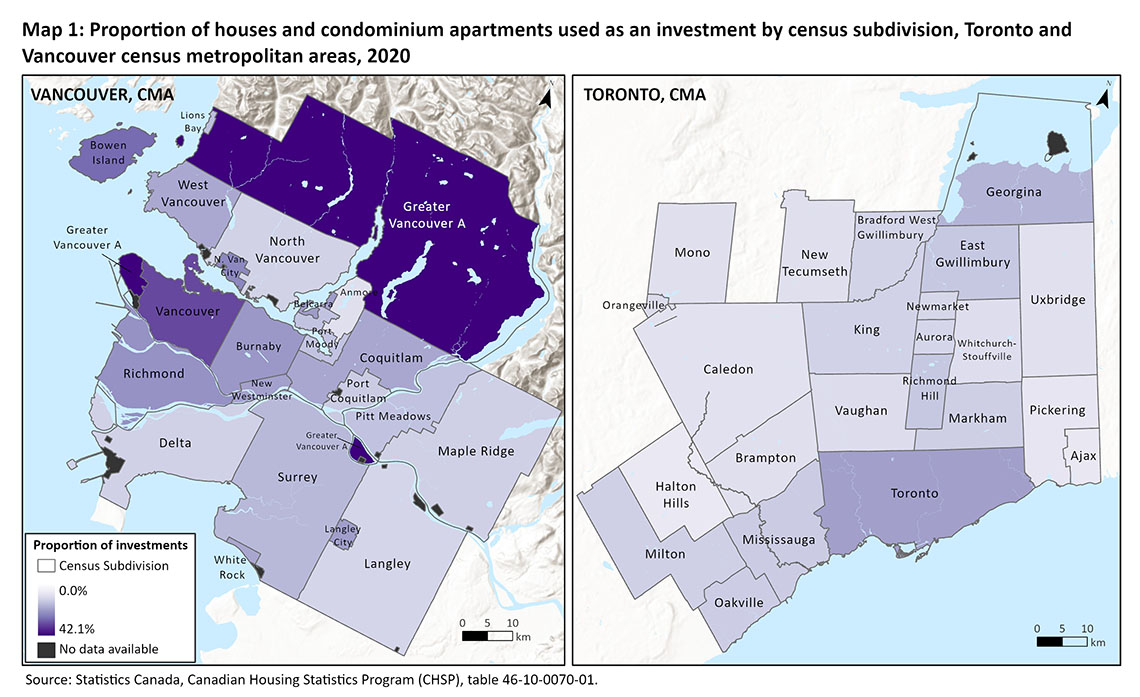
Map 1: Proportion of houses and condominium apartments used as an investment by census subdivision. Toronto and Vancouver census metropolitan areas, 2020

Description for Map 1


The title of the map is: “Proportion of houses and condominium apartments used as an investment by census subdivision, Toronto and Vancouver census metropolitan areas, 2020.” This figure displays two maps of the CSDs in the Vancouver CMA (left side) and the Toronto CMA (right side). 


Each CSD is shaded from light to dark purple based on the proportion of houses and condominium apartments used as an investment. The darker the shade, the higher the proportion of houses and condominium apartments used as an investment in that CSD. The map shows that the proportion of houses and condominium apartments used as an investment is generally higher in CSDs near the core of the Vancouver and Toronto CMAs. A continuous scale is used and ranges from 0.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 42.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.


Proportion of houses and condominium apartments used as an investment by census subdivision, Toronto and Vancouver census metropolitan areas, 2020

Table summary

This table displays the results of Proportion of houses and condominium apartments used as an investment by census subdivision. The information is grouped by Census subdivision name (appearing as row headers), Proportion of houses and condominium apartments used as an investment (percent) (appearing as column headers).
Census subdivision name Proportion of houses and condominium apartments used as an investment (percent)
Toronto CMA
Ajax, Town 7.4
Aurora, Town 12.1
Bradford West Gwillimbury, Town 12.6
Brampton, City 9.8
Caledon, Town 9.2
East Gwillimbury, Town 15.1
Georgina, Town 18.4
Halton Hills, Town 7.1
King, Township 12.9
Markham, City 13.7
Milton, Town 13.2
Mississauga, City 14.2
Mono, Town 9.6
New Tecumseth, Town 9.8
Newmarket, Town 12.1
Oakville, Town 13.9
Orangeville, Town 11.5
Pickering, City 8.0
Richmond Hill, Town 15.0
Toronto, City 21.7
Uxbridge, Township 9.5
Vaughan, City 10.6
Whitchurch-Stouffville, Town 10.2
Vancouver
Anmore, Village 9.2
Belcarra, Village 20.9
Bowen Island, Island municipality 28.3
Burnaby, City 21.6
Coquitlam, City 19.1
Delta, District municipality 12.1
Greater Vancouver A, Regional district electoral area 42.1
Langley, City 20.6
Langley, District municipality 11.4
Lions Bay, Village 16.0
Maple Ridge, City 12.3
New Westminster, City 20.2
North Vancouver, City 24.3
North Vancouver, District municipality 11.8
Pitt Meadows, City 14.8
Port Coquitlam, City 13.3
Port Moody, City 14.8
Richmond, City 22.4
Surrey, City 16.5
Vancouver, City 32.5
West Vancouver, District municipality 19.0
White Rock, City 19.2


The finding was similar in Toronto, where the proportion of investment properties was higher in the core CSD of the City of Toronto (21.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) than in the CMA as a whole (16.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}). For the CSD, this amounts to 112,220 condominium apartments and 52,935 houses used as an investment.

Note to readers

The Canadian Housing Statistics Program (CHSP) is an innovative data project that leverages existing data sources and transforms them into new and timely indicators on Canadian housing.

The data in this study are compiled from the CHSP for the reference year 2020. Complete information about the reference years of the property stock, by province and territory, are available here.

Methodology

Investor status and investment status of the residential property take into consideration the type of property as obtained by our data providers. Certain properties may have secondary units that are not known to the authorities. As a result, we cannot account for them. The counts and distribution of properties are calculated based on the property classifications established by the CHSP. These may differ from the ones used by local authorities.

Once the property is categorized as an investment property, a subcategory is created to determine the type of investment property. This is based on the type of investor who owns it. The order of priority is as follows:

  1. Investment property owned by at least one business or one government;
  2. Investment property owned by at least one non-resident individual;
  3. Investment property owned by at least one out-of-province individual;
  4. Investment property owned by an individual living in the province.

Properties cannot be included in more than one investment property category. If the property has multiple owners with various profiles, once an owner fits in one of the categories, by order of priority, then the property is included in that category.

Geographical boundaries

In CHSP releases, data are based on the geographical boundaries from the Standard Geographical Classification 2016.

The CHSP database does not contain information about residential properties on Indian reserves.

Definitions

A property owner refers to an individual or an entity included in the classification of ‘business and government’ (such as corporations, governments, sole proprietorships and partnerships, and other legal types) that has property title transferred to, recorded in, registered in, or otherwise carried in their name.

A property may have more than one owner or an owner may have more than one property, therefore the count of owners and properties can differ.

An individual is considered a non-resident if their primary dwelling is outside the economic territory of Canada.

The core of a geographic area, for the purposes of this release, refers to the census subdivision (CSD) within a census metropolitan area (CMA) with the highest number of residential properties.

An investor is defined as an owner who owns at least one residential property that is not used as their primary place of residence, excluding Canadian non-profit organizations. An individual owner who owns a single property in the same province as where they reside is not considered an investor, so long as it is not a property with multiple residential units. This category excludes investor-occupants.

An investor-occupant is defined as an owner who possesses a single property with multiple residential units and who occupies that property.

A non-investor is defined as an owner who is not an investor or an investor-occupant. An owner who lives in the same province as where the property is owned and owns a single property is included in this category, so long as it is not a property with multiple residential units.

An investment property refers to a residential property owned by at least one investor and is not used as a primary place of residence by any of the owners. This category excludes owner-occupied investment properties.

An owner-occupied investment property refers to a property with multiple residential units where at least one of the owners occupies a unit.

A non-investment property refers to a property held solely by non-investors or a property being used as a primary place of residence by at least one of the owners and that is not an owner-occupied investment property.

The term unspecified investment property status refers to properties whose owner is unknown, and therefore the investment status of the property cannot be determined.

A property with multiple residential units refers to a property containing more than one set of living quarters owned by the same owner(s), as is the case for an apartment building or a duplex or a property with two houses on the same lot.

A condominium apartment refers to a set of living quarters that is owned individually, while land and common elements are held in joint ownership with others.

Bibliography

Allen, Marcus T., Rutherford, J., Rutherford, R., Yavas, A. (2018). Impact of Investors in Distressed Housing Markets. The Journal of Real Estate Finance and Economics. 56. 622-652.

Canada Mortgage and Housing Corporation (2016). “Condominium owners report – Toronto and Vancouver”. April 2016. https://publications.gc.ca/collections/collection_2016/schl-cmhc/NH21-3-2016-eng.pdf

Haughwout, A., D. Lee, J. Tracy, and van der Klaauw, W. (2011). Real estate investors, the leverage cycle, and the housing market crisis. Staff Reports 514, Federal Reserve Bank of New York.

Khan, M., Xu, Y. (2022). Housing demand in Canada: A novel approach to classifying mortgaged homebuyers. Staff Analytical Note 2022-1, Bank of Canada.

Statistics Canada. (2021). “Canadian Housing Statistics Program, 2020.” The Daily. September 17, Statistics Canada Catalogue no. 11-001-X. https://www150.statcan.gc.ca/n1/daily-quotidien/210917/dq210917b-eng.htm

Statistics Canada. (2022). “To buy or to rent: The housing market continues to be reshaped by several factors as Canadians search for an affordable place to call home.” The Daily. September 21. Statistics Canada Catalogue no. 11-001-X. https://www150.statcan.gc.ca/n1/daily-quotidien/220921/dq220921b-eng.htm

Statistic Canada. (2022). “Canadian Housing Statistics Program, 2019 and 2020.” The daily. November 11. Statistics Canada no.11-001-X. https://www150.statcan.gc.ca/n1/daily-quotidien/221110/dq221110c-eng.htm

Statistics Canada. (2022). Census Profile, 2021 Census. Statistics Canada Catalogue no. 98-316-X2021001. Last updated on September 21, 2022. https://www12.statcan.gc.ca/census-recensement/2021/dp-pd/prof/index.cfm?Lang=E

Teranet. (2022). Market Insight – The Canadian Source for Housing Information – Q2 2022, https://www.teranet.ca/wp-content/uploads/2022/06/Teranet-Market-Insight-Quarterly-Report-Q2-2022.pdf (accessed September 12, 2022).
Capital Gains Tax on Real Estate Investment Property

Capital Gains Tax on Real Estate Investment Property

SmartAsset: Capital gains tax on real estate investment property

Real estate investments can be lucrative assets. However, they can also incur capital gains taxes that weaken your profits. Fortunately, you can implement tactics that reduce capital gains taxes so you can keep more of your money. Although the IRS taxes short-term and long-term gains differently, you can combat high tax rates on both. We’ll explain short-term and long-term capital gains and how to keep the associated taxes from costing you an arm and a leg.

A financial advisor can help you tax-optimize your investment portfolio. Find a financial advisor today.

What Are Capital Gains Taxes?

You pay capital gains taxes when you profit from selling assets. You can incur two types of capital gains taxes: short-term and long-term. Short-term capital gains are from selling assets you’ve held for less than a year. On the other hand, long-term capital gains come from selling assets after holding them for a year or more. So, if you sell an investment property, the time you owned it before selling it will determine what kind of capital gains taxes you pay.

How Are Capital Gains Taxed?

The IRS taxes short-term capital gains as standard income, meaning your income tax bracket will determine your tax rate. Income tax brackets are as follows: 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Your income determines your capital gains tax rates.

For example, say you make $85,000 from your day job. You sell an investment property nine months after purchasing it and make a $30,000 profit. The sale results in a short-term capital gain, and your income is $115,000 when you file taxes. In addition, you’re a single filer, putting a portion of your income in the 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} tax bracket.

Conversely, long-term capital gains have different tax rates than short-term gains: 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, depending on your income level and filing status. For 2023, single filers making up to $44,625 receive the 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate. Single filers with income between $44,626 and $492,300 will pay 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Finally, single filers with income above $492,300 will pay 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} long-term capital gains taxes. In addition, single filers making $125,000 or more annually will pay a net investment income tax of 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on capital gains from real estate.

A married couple filing 2023 taxes jointly will pay 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} if they earn up to $89,250. The 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate applies if the couple earns $89,251 to $553,850. The 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate applies if they earn more than $553,850.

How to Limit Capital Gains on Real Estate Investment Properties

SmartAsset: Capital gains tax on real estate investment property

You can use a variety of strategies to avoid capital gains on real estate properties:

Use Tax-Deferred Funds

You don’t have to invest in real estate with dollars from your bank account. Instead, you can use your individual retirement account (IRA) or 401(k). Depositing investment profits in your investment account allows your money to grow tax-free. Plus, your IRA contributions can garner you another tax deduction.

Make the Property Your Primary Residence

The internal revenue service (IRS) exempts primary residence sales from capital gains taxes up to $500,000 for married joint filers and $250,000 for single filers. You can also avoid paying taxes on depreciation deductions this way. Using this option means fulfilling the following requirements:

  • Owning the home for two or more of the last five years
  • Living in the home as the primary residence for two or more of the last five years
  • You haven’t taken a primary residence exemption in two years

Tax-Loss Harvesting

Tax-loss harvesting means deliberately selling an asset for a loss to mitigate profits from another asset. Therefore, you can sell a property for less than you bought it, reducing your taxes.

For instance, say you sell one property and make $30,000. You don’t want to pay taxes on this gain, so you sell another property for $25,000 less than what you paid. As a result, you pay taxes on $5,000 of capital gains.

1031 Exchange

The depreciation deduction for rental properties has one major drawback: when you sell a rental property, you owe taxes on the depreciation amount (if you received any). Fortunately, the 1031 exchange allows you to circumvent this rule.

The 1031 exchange means using the income from the sale of an investment property to purchase another investment property of equal or greater value. Then, you don’t have to pay taxes on prior depreciation deductions. This caveat allows you to avoid income taxes on depreciation into perpetuity if you buy another property of equal or greater value.

How to Minimize Your Capital Gains Tax

Even if you can’t altogether avoid capital gains taxes, the following tactics will minimize your capital gains taxes:

Depreciation Deduction

The IRS allows rental property owners to deduct an annual depreciation amount from their income. The deduction comes from the expected lifespan of rental property, which the IRS defines as 27.5 years. As a result, you can calculate your depreciation deduction by dividing your rental property value by 27.5 (commercial real estate uses the lifespan figure of 39 years).

For instance, say you have a $250,000 residential investment property. Dividing this figure by the depreciation deduction lifespan of 27.5 gives you an annual deduction of $9,090.

Itemized Deductions

Generally, you can deduct the costs of managing property, lowering your tax burden. Running your real estate investment business incurs costs such as travel, legal fees, and business equipment. These expenses can add up – but instead of hurting your wallet, they can create a tax benefit.

In addition, you can deduct mortgage interest and the costs of repairing or maintaining a property. Therefore, keeping detailed records and saving every receipt is vital to claiming as many deductions as possible.

Methods to Boost Property Basis

SmartAsset: Capital gains tax on real estate investment property

Improving your property gives two financial advantages: the costs of doing so can shrink your capital gains taxes, and the improvements can bolster your property value. Here’s how you can boost property basis:

  • New windows and doors
  • Updated appliances, roofing, and flooring
  • Renovate plumbing, electrical, and HVAC systems
  • Paying commissions to real estate agents
  • Expenses for the appraisal, inspection, and legal services
  • Closing costs, including title search, escrow, and taxes

Bottom Line

Capital gains taxes can curb your profits from real estate investments. Fortunately, multiple deductions and tax strategies can lower your tax burden. For example, you can deduct depreciation and make a home your primary residence before you sell it. In addition, upgrading your home can boost your property basis and lower your capital gains taxes. So, it’s essential to be thorough in your research and record keeping to ensure you minimize capital gains taxes on real estate investments.

Tips on Capital Gains Tax on Real Estate Investment Property

  • You can make the most of your real estate investments by familiarizing yourself with relevant tax laws. A financial advisor can help you understand your financial position and make the most of your tax return. Finding a qualified financial advisor doesn’t have to be hard. SmartAsset’s free tool matches you with up to three vetted financial advisors who serve your area, and you can interview your advisor matches at no cost to decide which one is right for you. If you’re ready to find an advisor who can help you achieve your financial goals, get started now.
  • Check out our free capital gains capital gains tax calculator for a quick estimate of what you’ll owe.
  • If you’re considering starting a real estate venture, it’s wise to do your homework first. Use this guide for how to buy investment property.

Photo credit: ©iStock.com/Perawit Boonchu, ©iStock.com/ArLawKa AungTun, ©iStock.com/ArLawKa AungTun

The post Capital Gains Tax on Real Estate Investment Property appeared first on SmartAsset Blog.

The views and opinions expressed herein are the views and opinions of the author and do not necessarily reflect those of Nasdaq, Inc.

5 Reasons Not to Own a House in Your Name

5 Reasons Not to Own a House in Your Name

iStock-626540754 why not to own a house in your name signing real estate documents

Photograph: istockphoto.com

Homeownership is an aspiration for lots of men and women, but not all house owners truly own a house in their identify. There are two main strategies someone can have a home with no attaching their title, such as placing it in a trust and transferring it to a limited liability corporation (LLC).

A have confidence in is generally a very good plan for a residence purchaser who wants to leave their dwelling to a beneficiary upon their dying but desires to prevent a potential authorized struggle the moment they die. If you want to place your home in a rely on, it’s advisable to get the job done with an estate scheduling attorney who can make absolutely sure your needs are included in the rely on, making certain almost everything will go smoothly after your death.

LLCs are usually improved suited for expenditure and rental qualities. To start an LLC, you are going to require to arrive up with a small business name and fill out numerous varieties (which can differ from state to condition). Again, it could be recommended to consult with an legal professional to assure that you fill in all the sorts appropriately, which can assistance keep away from inconvenience down the highway.

There are quite a few gains to placing a property in a trust or LLC. This guideline will go over five of the major causes not to possess a household in your name.

Connected: A Phase-By-Step Guide on What to Do Just after Inheriting a Residence

1. Putting your house in a have faith in can help stay away from probate.

Not a lot of persons like to assume about their have loss of life, but it’s smart to prepare as a lot as attainable for when the inescapable takes place. If you own your dwelling in your identify and go away it to an heir in your will, it will go via a system known as probate. Probate is the method your assets go by upon your dying in order to ensure all your money owed and taxes are compensated off. Only then will your remaining property be distributed to your decided on heirs.

Probate can be a prolonged and tense process, even for comparatively compact estates. There are also several expenses affiliated with probate, which will probable fall on your beneficiaries to manage before they acquire their inheritance. These charges can include things like court docket charges, administrative service fees, and lawful expenditures.

If you put your household into a trust fairly than trying to keep it in your name, you can bypass probate when you die. That suggests your beneficiaries will get their inheritance without needing to go by the courts. When you set up a trust, you are going to have to have to designate a trustee and one particular or a lot more beneficiaries.

The trustee will be responsible for taking care of the have confidence in after you die and making certain that your assets are passed together to your beneficiaries. You can identify any one as the trustee, but make guaranteed the particular person is reputable and dependable. For this cause, quite a few people decide on to identify an attorney or have faith in organization as their trustee.

iStock-181887864 why not to own a house in your name probate court

Photo: istockphoto.com

2. A serious estate LLC guards from private liability.

Owning a rental or investment decision house can be dangerous. If a tenant or guest information a lawsuit, your particular assets won’t be at risk if the residence is owned by an LLC. If it’s owned by you personally, although, the lawsuit will title you in the assert and you may perhaps drop your personal property in get to settle.

For example, if a tenant falls down the stairs and breaks a bone, they may possibly involve various professional medical techniques to tackle the crack. They may possibly make a decision to sue the property owner for damages to aid pay out for their healthcare bills, decline of income, etc. If you very own the assets individually, you’ll be on the hook to shell out for any judgment issued. Having said that, if the property is owned by an LLC, you will not want to stress about getting rid of your household or individual objects to assist pay out the essential expenses.

Associated: 5 Financing Solutions to Kick-Start out Your Authentic Estate Investing Profession

3. Possessing a home as an LLC shields your privateness. 

The identify of a property owner is community document, indicating that everyone could find out who owns a household with a couple very simple on the web lookups. But if the assets is owned by an LLC, the owner’s title will remain personal. This can be in particular interesting for anyone who is famed or normally properly known, or for any one who basically desires to keep their private business private.

Linked: 9 Blunders Not to Make When Promoting Your Residence

iStock-158734256 why not to own a house in your name LLC operation agreement paperwork

Photo: istockphoto.com

4. LLCs appear with tax benefits for rental residence entrepreneurs.

If you have a rental assets, there are tax rewards that come with LLC possession. A sole proprietor of an LLC will report the business’s profits and losses on a personal tax return instead than a enterprise tax return—this is known as move-via taxation.

Even so, if you form a company to handle the rental business enterprise, you’ll will need to report the company’s financials on equally the business enterprise tax return and your personal tax return, which can guide to double taxation.

Similar: Solved! Really should I Get a Household Warranty for a Rental Home?

5. An LLC will make the transfer of possession less complicated.

Providing a house can be a very long and drawn-out process—and that continues to be accurate for a rental or financial commitment assets. If the home is owned by an LLC, you can simply just provide or transfer the ownership of that LLC to the new owner without having truly selling the home. This can also make it much easier to present a house to a family member without having needing to draw up a new deed.

Associated: How to Decide on a Home loan Loan company Which is Appropriate for You

iStock-1131335531 why not to own a house in your name handing keys to a house to someone

Picture: istockphoto.com

The Downsides of Not Proudly owning a Dwelling in Your Identify

Even though there are numerous advantages to not owning a assets in your personal name, there are also some down sides.

Disadvantages of a Belief

Living in a believe in-owned dwelling can be an inconvenience if you want to refinance your mortgage loan. Even though not difficult, you may well require to shop about to multiple lenders to come across a single that will refinance your financial loan if your household is belief-owned.

In addition, your beneficiaries may possibly uncover that it is far more do the job on their section to claim their belongings if they are held in a rely on. Alternatively than inheriting the property on your death, the beneficiaries will have to depend on the man or woman you named as trustee. If you named a reliable person, this sort of as an legal professional, this will most likely not be a concern.

Drawbacks of an LLC

Though an LLC is a excellent possibility for an expenditure or rental property, it is not advised for a main residence. Creating an LLC to presume ownership of your key home can impact your means to get funding in the long run. In addition, purchasing a dwelling below an LLC can end result in increased closing fees and higher insurance policies premiums.

An LLC can also limit eligible tax breaks. Proudly owning a principal home individually comes with many tax strengths which can vanish if the household is owned by an LLC. In basic, it is a fantastic strategy to converse with an legal professional or a economical advisor prior to transferring ownership of any residence—primary or rental—to an LLC.

Women represent only 1 in 4 property investors

Women represent only 1 in 4 property investors

&#13

women-in-property-investment.jpg

The present housing sector problems present options for ladies to commit and make improvements to their economic conditions, professionals mentioned.

According to new investigation by Assets Expense Pros of Australia (PIPA), only 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of buyers ended up ladies.

Recommended home purchaser Kate Hill said decreased premiums of feminine property expenditure was yet another economical headwind women are experiencing.

“Throughout their doing work life, ladies have to navigate the gender pay out hole, significantly reduced superannuation balances, and poorer economical outcomes publish-divorce – all of which will indicate they will have inferior fiscal results all over their life and in retirement,” she claimed.

A latest report from the Monash University and Monash Overall health uncovered that at current premiums, it would take women 70 yrs to get to whole-time work equality with signify and additional than 200 yrs to obtain fairness on earnings.

There was nearly a $24,000 cash flow gap amongst guys and girls in 2020, with the latter’s labour drive absence alone costing $72bn in shed GDP on a yearly basis, according to the report.

“The simple fact that girls only depict a smidge in excess of a quarter of all home buyers is a different element that exhibits ladies are just not on the same economical footing as gentlemen in this place,” Ms Hill explained.

Ms Hill reported sufficient options are presently out there for girls that would assistance them get a household or expenditure property to shore up their fiscal futures.

“Market disorders are hugely supportive at present given softer property prices and lower consumer need,” she stated.

“The following six months will produce excellent market ailments for any lady who would like to strengthen their financial situation by way of strategic assets ownership.”

PIPA chairperson Nicola McDougall claimed quite a few women may have been anxious about buying a home both as a home or an financial investment in several years that absent by.

“Society has modified noticeably since the times when females stayed at house to glimpse soon after their little ones though their husbands ended up the primary breadwinners,” she claimed.

“However, extra and additional research and lived encounters are proving that the financial outcomes for girls are commonly heading to be poorer than guys – and especially for all those who independent or divorce.”

Nonetheless, there are reports that counsel that gals are using up area in the residence scene.

A report by ME Financial institution in March previous 12 months showed that the range of solitary female house bank loan application amplified amid the housing boom.

Also, women are also borrowing additional, with the typical financial loan dimensions growing 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2021.

In the meantime, CoreLogic’s 2022 Gals & Residence report showed that 28.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of property purchases in 2021 ended up built by females — up from 27.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2020.

Ms McDougall pressured the significance of women’s economic independence and how possessing a house can make a sizeable distinction.

“I obtained three attributes as a single lady and retained economical

independence from my husband,” she said.

“This signifies that if our partnership ends, we can transfer on with our lives comparatively seamlessly specified we have financial independence from every single other and are hence not likely to ever wind up in Loved ones Courtroom for months or even years on stop.”

—

Image by RODNAE Productions from Pexels.

&#13

Shanghai Property Investment Fell 23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022

Shanghai Property Investment Fell 23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022

Shanghai Property Investment Fell 23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022

China’s commercial funds saw investment decision decide on up in the fourth quarter of 2022 (Getty Pictures)

Major trades of expenditure attributes in Shanghai fell by far more than a person-fifth in phrases of value from 2021 to 2022, in accordance to experiences by home brokerages, as COVID-19 limitations and financial weak spot derailed bargains during the second and 3rd quarters in the mainland monetary hub.

China’s industrial capital confirmed symptoms of a rebound in the fourth quarter of past yr, nonetheless, with a pickup in action as guidelines to help the authentic estate sector kicked in. Transaction quantity in the course of the quarter totalled RMB 26.4 billion ($3.8 billion), symbolizing 31.6 percent of the year’s full and soaring 36.8 p.c when compared to the fourth quarter of 2021, JLL identified in its most up-to-date sector report.

While the influence of COVID-19 continued to sluggish signing of new leases and drag on other spots of Shanghai’s commercial home industry in the fourth quarter, the brokerage expects that continued supportive steps and the lifting of pandemic constraints may well strengthen trader sentiment in 2023.

“As the ‘exit wave’ of COVID passes, we anticipate everyday lifetime and enterprise to normalize, setting the stage for a recovery in self-confidence and current market general performance later on in the 12 months,” said Anny Zhang, handling director for JLL East China, who also heads the company’s industrial leasing organization nationwide.

Abroad Consumers Appear Back again

JLL counted 74 significant true estate financial investment transactions in Shanghai totalling RMB 83.64 billion throughout 2022,  – a sum which was down 22.8 percent from the prior year’s tally of RMB 108.3 billion. Portray a equivalent photograph, rival brokerage Cushman & Wakefield reported 71 en-bloc transactions in the mega-town totalling RMB 88.5 billion for the duration of the year, dropping 17 per cent from 2021.

Buyers chalked up 13 new en-bloc transactions in Shanghai totalling RMB 24.9 billion in the course of the fourth quarter, Cushman & Wakefield uncovered, with business office and enterprise park qualities accounting for far more than 90 p.c of deals recorded for the duration of the quarter. The assets consultancy additional that the proportion of financial investment by overseas consumers slowly greater in the second 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the year.

Anny Zhang JLL

JLL head of japanese China Anny Zhang

Notable offers through the fourth quarter incorporated Hong Kong-based mostly insurance plan giant AIA’s order of a 90 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} stake in the SIIC Heart, an office environment-retail complicated in Hongkou district, for RMB 8.7 billion in December.

Singapore’s CapitaLand notched a different key transaction by buying The Springs Heart, an business office sophisticated in Yangpu district, from Tishman Speyer for RMB 7.6 billion, even though Singaporean sovereign wealth fund GIC acquired a 70 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} stake in Baijiatong Park, a organization park in the Zhangjiang submarket, for RMB 2.8 billion, according to Cushman & Wakefield.

Place of work assets accounted for 82 per cent of transaction volume in the fourth quarter, followed by business parks at 11 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Senior housing, industrial and hotel promotions built up 5 per cent, 2 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 1 per cent, respectively.

The brokerage located that business office property in Shanghai’s central organization districts supplied cap costs of 4.5 percent, while these in non-CBD spots averaged 4.8 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Small business park qualities experienced regular cap fees of 5 percent.

Rental Housing on the Rise

Shanghai’s virus outbreak and months-extended lockdown in the first 50 percent of the 12 months dampened need for business space, with net absorption of grade A places of work totalling just 94,851 sq. metres (1 million square toes) in the fourth quarter, a plunge of more than 74 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the similar quarter of 2021, in accordance to JLL.

CBD rents declined .9 percent quarter-on-quarter in the fourth quarter, offsetting rental gains before in the calendar year, even though decentralized rents declined 1.3 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} quarter-on-quarter and 1.6 percent yr-on-year, pushed by sluggish leasing and lease terminations by compact and medium-sized enterprises.

A report by Colliers, even so, found that grade A office market efficiency picked up in the fourth quarter, with general leasing need mounting 37.7 p.c quarter-on-quarter to 166,000 sq. metres. Vacancy tightened by .5 share points to 17.9 p.c through the quarter thanks to just take-up in decentralized enterprise districts and a scarcity of new source.

Even though place of work assets accounted for around 64 p.c of complete transaction quantity in 2022, in accordance to JLL, rental housing rated as the 2nd most popular asset course for the duration of the year with 15 transactions. Buyers also sought out other different asset courses such as organization parks, lodges, and senior living services.

“The investment decision industry is being bolstered by a range of procedures these kinds of as the the latest resumption of financing for outlined actual estate providers, as nicely as personal equity becoming permitted to build private genuine estate expense cash,” observed Ling Sunshine, head of funds marketplaces for JLL East China in a assertion. “The marketplace also is benefiting from the accelerated broadening of the scope for REITs and broader official steps to revive China’s residence sector.”