Friday the 13th was an unlucky working day for three billed by Arlington law enforcement in a residence-enhancement fraud.
Arrested following police posed as prospects have been Peter Gilheney, 21, of Quincy Richard Gilheney, 18, of Randolph and Patrick Gilheney, 18, of Quincy.
On Tuesday, Jan. 10, an elderly Arlington resident notified law enforcement of a likely fraud just after a few males billed him an abnormal quantity of dollars for house-advancement operate and damaged his house.
Minimal quotation, then injury
A news launch termed this “a popular rip-off” that normally targets seniors for different residence-improvement tasks. The specific properties are normally in want of authentic repairs. Having said that, the suspect often estimate a quite small value for a insignificant task and then problems a chimney, front methods, retaining wall, roof or a further section of the home, without having authorization from the homeowner.
The suspect will then estimate a much bigger cost and encourage the target to spend a substantial sum upfront, promising to full the function, but later using the payment with out finishing the get the job done.
The target claimed to police that 3, later determined as those arrested, quoted him $200 to fix a smaller crack in his entrance methods, the information launch mentioned.
The trio returned a few times afterwards and allegedly ripped out the entrance actions with out the victim’s authorization and quoted the target $6,000 for repairs. The sufferer in the end wrote a examine for a part of the full amount of money, which was allegedly cashed by the suspects. The target tried to get his check out again, but was unsuccessful.
Police pose as prospects
On Jan. 13, Arlington police detectives posed as probable buyers and contacted the suspects. When the 3 arrived to a predetermined site, approached them.
The 3 ended up positively discovered as all those who allegedly harmed the victim’s home and took his look at, and all 3 were arrested with out incident.
Although at the scene, law enforcement also decided that Peter Gilheney was allegedly driving with no a license, and that the vehicle’s registration plates were being affiliated with a various car or truck.
Peter was charged with unlicensed operation of a motor auto, quantity plate violation to conceal identification. He, Richard and Patrick ended up billed with malicious destruction of home of additional than $1,200 and larceny by phony pretenses of much more than $250.
All three, arraigned in Cambridge District Court Jan. 13, have been introduced on private recognizance.
Scammers generally strategy probable victims for property enhancement frauds by telephone, e mail or by traveling door-to-door, and may possibly declare they’ve been executing operate domestically and have surplus materials.

Scammers routinely provide their providers at a quite very low price.

Look at to make certain the contractor is registered with the Workplace of Consumer Affairs and Business Regulation by using its household-improvement contractor registration lookup assistance. Ask for a business enterprise card or web page address for the contractor’s organization.

Be wary if the specific is driving an unmarked motor auto.

Ask for a duplicate of the company’s normal deal.

Inquire about no matter if the corporation will deliver a warranty and how very long that warranty will past.

Never ever pay back far more than 1-third the complete price of a support upfront, in hard cash, and only do so at the time you have verified that this man or woman is a registered property improvement contractor and you have a agreement.

Any individual who thinks they have fallen target to any kind of scam is encouraged to get hold of the Arlington Police Section at 781-643-1212
Jan. 12, 2023: Court proceeding reset for March for Arlington person charged in intercourse sting
This news summary was printed Saturday, Jan. 14, 2023, primarily based on information and facts from a news release by Ashley Fairchild of John Guilfoil General public Relations.
Dwelling advancement retailer Residence Depot is making a nationwide modify to how it pays hourly staff upcoming 7 days.
“As legislation, know-how and office practices proceed to evolve, we’re transforming our follow nationwide effective Jan. 16, 2023, to shell out hourly associates to the nearest moment based mostly on correct time punches,” a House Depot spokesperson confirmed to FOX Business enterprise.
The new coverage will mark a change from its existing apply, which the spokesperson mentioned “has been to spherical full shift time up or down to the nearest 15 minutes.” That “has been a typical business practice for a lot of a long time,” according to the spokesperson.
House Depot retailer in West Berlin, N.J. with rental vehicles parked outside, Dec 25, 2022.
The transfer was first claimed Wednesday by Small business Insider.
The exercise of rounding is permitted in the Reasonable Labor Criteria Act (FLSA), with the legislation noting some industries tend to round to the “closest 5 minutes, or to the closest a single-tenth or quarter of an hour.” It have to be “utilized in such a fashion that it will not outcome, more than a time period of time, in failure to compensate the staff correctly for all the time they have actually worked,” it states.
A couple staff manufactured allegations about compensation in relationship to House Depot’s rounding tactics in previous lawsuits, Company Insider also noted.
Shares of retailer House Depot jumped early past 7 days right after posting superior-than-expected income.
Ralph Polk (L) and Fred James operate in the paint section at a Household Depot store Feb. 21, 2006 in Chicago, Illinois.
Home Depot had more than 2,300 shops and some 500,000 staff as of the conclusion of October, the firm reported a couple months in the past.
In November, the company stated its 3rd-quarter net gross sales amplified 5.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the similar interval very last calendar year, coming in at $38.87 billion. Its internet earnings were $4.34 billion, up 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in contrast to $4.13 billion in past year’s 3rd quarter.
As for its fiscal 2022 steering, Home Depot claimed it envisioned “comparable revenue advancement of roughly 3. p.c” and “diluted earnings-per-share-per cent-growth to be mid-one digits,” according to the earnings launch.
Homeownership arrives with a extended checklist of costs, together with the cost of generating enhancements from time to time. When part of the pleasure of proudly owning a home is the skill to create a area that reflects you and your character, having to pay for renovations ought to always be taken care of properly.
It can absolutely be tempting to use a credit score card or two to finance your renovation dreams. But if you program to shell out for assignments this way, the crucial is to pick the appropriate type of card, using into thing to consider such elements as fascination rate and benefits program features.
Advantages of using a credit score card to fund house improvements
A lot of credit cards give substantive welcome bonuses to persons who meet specific paying necessities or thresholds inside of the first months or months of opening the account. This signifies if you open a credit score card particularly to fund home improvements, you could get paid a massive quantity of hard cash again, factors, miles, or other important benefits.
“For those who have accounted for their complete renovation price range, considering a new account or credit score card may possibly be a wonderful way to seize a helpful welcome bonus and added rewards—in the variety of money or points—that can be utilized to offset the cost of house enhancements,” states Chris Fred, head of U.S. credit playing cards and unsecured lending for TD Bank.
If this is your approach, be confident to do your research on the card issuer and its reward application ahead of applying for a new card. You are going to want to make guaranteed you fully grasp all the ins and outs of qualifying for the bonus to ensure that you will most likely be equipped to meet up with the prerequisites.
Additionally, it’s vital to be certain that you have the capacity to simply redeem the benefits provided by the system, whether they are dollars again or a gift card to a dwelling enhancement store.
Yet one more popular credit history card element is introductory {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} funding that lasts everywhere from six months to 21 months. When you decide on a {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} introductory price credit score card, you are basically getting cost-free financing on the fees of improvement.
“Introductory premiums are well known between quite a few card issuers and can be a practical tool if you might be hunting for small-price financing,” suggests Fred. “But be sure to pay back the credit rating card stability in comprehensive and spending plan accordingly to steer clear of the desire charge resetting just after the introductory period of time ends.”
Credit playing cards linked with distinct shops or retailers, specially property advancement merchants, are identified for featuring deferred desire applications to enable entice house owners to pursue their renovation ambitions. But listed here, too, the crucial is spending notice to the system particulars in buy to make the offer operate for you.
“These features allow far more of the payment to go towards the principal, and you can pay out off the financial debt quicker. But know the period of the supply time period and estimate the every month payments desired to shell out off the harmony in complete right before the offer expires,” says LaDonna Cook of the nonprofit financial debt counseling organization GreenPath Economical Wellness.
Convenient when procuring
Nevertheless yet another upside when utilizing credit cards to spend for dwelling enhancements is the relieve of use. This is particularly legitimate if you are going to be relying on a number of distinctive retailers to finish your venture. Working with credit to pay out several sellers is considerably easier than employing individual loans for just about every acquire or provider, for occasion.
“Using a credit rating card is certainly just one of the most practical and protected kinds of payment,” states Fred. “It can be additional hassle-free to swipe your card as opposed to making use of for a bank loan that then needs to strike your financial institution account, which you then require to withdraw or create a test for. Making use of a credit history card could also have a smaller sized impression on your credit score rating in comparison to getting out a mortgage.”
Guarantee protection
It’s prevalent practice amid credit card issuers these days to give extended warranties on objects bought with the card. If your renovations incorporate purchasing huge appliances or other expensive merchandise, this can be a significantly useful attribute.
“This is unquestionably a central thing to consider when applying a card, significantly if you believe that the goods might not previous extended than the size of the guarantee or if you would want not to budget in a replacement or prolonged guarantee,” states Fred.
Disadvantages of working with a credit history card
Whilst there are certainly some gains to applying a credit rating card to fund household enhancements, there are a several most effective techniques that are critical to observe to make this strategy pay back off and not induce you monetary heartache.
Prospective to overspend
With inflation, the value of everything has been increasing, such as residence advancements. It can be effortless and tempting to overspend, eventually finding in over your head with personal debt on your home undertaking.
“Practice spending restraint, stick with your expending system, and try not to overspend to earn rewards,” states Cook dinner. “Where possible, strategy forward and save for house improvements so that you never want to entirely rely on credit rating to finance them.”
In point, you should really prevent employing a credit score card completely if you are not sure of your means to make payments on time or you have a tendency to spend further than your usually means when working with a card. Creating and sticking intently to a residence renovation spending plan is an additional important very best follow.
You need to also frequently review your credit history card statements to make sure you are being within the finances you recognized at the outset of your venture.
“Remember that benefits are a helpful instrument when renovating, in particular when many expenses have risen in new a long time, but first look at your finances and stick to it,” claims Fred.
Failing to repay credit card debt just before introductory amount expires
Credit score card introductory premiums eventually conclusion. So you’ll require to be disciplined about keeping your eye on the advertising timeline and repaying the personal debt on time.
“If you are not in a position to pay back off the equilibrium before the offer period expires, it is significant to determine and funds for payments at the larger desire fee that requires outcome when the present period ends,” suggests Cook dinner.
There may possibly be less costly solutions
It’s worth noting that some sellers or retailers present discounts to shoppers who shell out in dollars and will tack on an additional advantage cost when you spend with a credit history card. This may make credit rating playing cards a far more highly-priced proposition in some instances.
If you have a excellent deal of equity in your house, it might be fewer pricey about the extensive term to use a residence equity personal loan or residence fairness line of credit rating (HELOC), specially as interest prices on numerous credit rating playing cards soar amid the present-day high-fascination environment. But HELOCs come with hazards of their individual.
“Consumers should really continue to keep in brain that fascination prices range in excess of the life of the (HELOC) credit line and are identified by current market prices,” says Fred. Moreover, remember that your house is staying utilized as collateral in this financial loan situation, so speak with a fiscal professional irrespective of your home renovation size to make sure your funding system ideal matches the scale and requirements of your renovation undertaking.”
Selecting if utilizing a credit rating card is appropriate for you
Applying a credit history card to finance household advancements is unquestionably not the suitable transfer for every person. There are some specific instances and problems under which this can be a valuable method. Utilizing a credit rating card can make sense if:
You are making huge buys that could qualify for a welcome bonus: It tends to make the most perception to use a credit history card to fund a house renovation when you may well have a significant upfront buy to make that can get paid a welcome reward. Despite the fact that as described, don’t forget to make be aware of when the introductory give may close and price range for the overall assertion.
If you can get a {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} intro level: If your credit rating score and payment heritage makes it possible for you to qualify for a {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} credit history card supply, then this solution may well be a good way to finance your property enhancements for no price.
You are disciplined about paying out: It is essential to look at your exclusive own economic behaviors and irrespective of whether you’re disciplined about credit rating card use as properly as pursuing a finances. If the remedy is of course, then using a credit history card could be a safe and sound and beneficial strategy to spending for dwelling renovations.
Utilizing a credit score card to finance renovations may not make feeling if:
You by now have a high personal debt-to-cash flow ratio: If you previously have a substantial financial debt-to-income ratio, making use of a credit history card might not be the finest option. It could negatively have an affect on your credit score rating, and you may possibly not qualify for the most favorable desire costs or credit score card programs.
You have a lower credit score rating presently: Identical to acquiring a high personal debt-to-money ratio, if your credit rating is subprime, you may well not qualify for a competitive credit rating card supply or even a credit score limit that is large enough to cover the entire charge of your job. That may possibly force you to use other types of funding in addition to a credit rating card, in order to fork out for the full charge of renovations. In this scenario, it might be finest to skip the credit rating card altogether.
The takeaway
There are a wide range of advantages to using credit history cards to shell out for property advancements, including earning useful welcome bonuses or program rewards and getting {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} financing on your renovation task. But before choosing to use a credit card to cover these kinds of expenses, be certain you absolutely fully grasp the software principles if you hope to qualify for rewards.
And if you’re not a disciplined budgeter and spender, it’s in all probability best to think about other alternatives to spend for your property renovation plans. In such cases, a home fairness personal loan or even a personalized personal loan can be a beneficial solution.
You’ve probably spent more time at home than usual during the coronavirus pandemic, so all of those little things about your space that didn’t really bother you before have probably driven you crazy by now. If your home is in need of a refresh, you might not want to spend thousands on a full kitchen remodel or bathroom renovation, but there are plenty of home improvements you can make without spending a fortune. All of these home makeover projects can be done on a budget.
You can boost your home’s curb appeal at a small cost by painting your front door. “With a good coat of primer and a couple coats of exterior paint, your door will look new and striking at first glance,” said Dina Gibbons, home and garden design expert at RubberMulch, a company that makes environmentally responsible mulch from rubber.
Research shows that a home’s value can increase as much as $8,000 just by updating the front door, said Gibbons. The primer should cost between $30 and $40, and paint costs between $25 and $50 for a gallon. Then, you can install a door knocker for less than $50 to add a decorative touch.
Another way to improve the look of your garage door without blowing your budget is to paint it. “People tend to underestimate just how big a garage door is,” said Connor Roberson of A Plus Garage Doors in Charlotte, North Carolina. “Once it is painted, no one will miss the difference.”
Homeowners can also attach decorative hardware such as handles or faux hinges to their doors. All of these upgrades can be done with a little elbow grease and for less than $100, he said.
kitzcorner / Getty Images/iStockphoto
3. Add a Fresh Coat of Paint to a Room
The walls in your home likely have dings, marks and paint that has lost its luster or is an outdated color. “For just about $35 per gallon, you can transform those interior walls into a bright, new color that has some fresh sheen,” said Geoff Sharp, founder of Sharper Impressions Painting Company. Or for about $350, you can get an average-sized bedroom for a child painted by a professional, he said.
Sean Juneja, the co-founder of interior design firm Décor Aid, recommends using neutral grays or creams that freshen and brighten a room and appeal to a mass market. “Avoid anything that is too bold or dramatic,” he said.
KatarzynaBialasiewicz / Getty Images/iStockphoto
4. Use Wallpaper To Create a Bold Accent Wall
Adding wallpaper immediately transforms the look of any room, whether it’s a bathroom, bedroom, dining room or living room. The cost for this makeover project will depend on the size of the wall and the type of wallpaper you choose, but if you choose a smaller wall and less expensive paper, you can likely keep costs under $500. According to HomeAdvisor, adding wallpaper to a room ranges from $310 to $790, so doing a single wall would cost less.
You can save on costs by putting it up yourself. Peel-and-stick wallpaper makes this an easy home improvement to DIY.
iStock.com
5. Add New Textiles
Change the vibe of your living room or bedroom by switching out the textiles. Kimberly Ward, an interior designer and blogger at PinkEggshell.com, told The Nest that she recommends starting with a rug — ideally for $300 or less — and then selecting a throw blanket or throw pillows to match.
Eduard Militaru / Unsplash
6. Change Out Your Window Treatments
Installing new windows can be pricey, but a cheaper alternative is to simply switch out your window treatments. A new set of curtains or drapes should cost well under $500.
FollowTheFlow / Getty Images/iStockphoto
7. Add Some New Art
The art you have on your walls can give new personality to a room — and you don’t have to spend a lot on wall art. You can find both art and frames on Etsy for less than what you’d pay elsewhere.
KatarzynaBialasiewicz / Getty Images/iStockphoto
8. Upgrade Your Nightstand
You don’t need to splurge on a whole new furniture set to give your bedroom a refreshed look. Simply swapping out your nightstand for one that makes a statement — and ideally has ample storage — will upgrade the look of your room. Expect to spend around $80 on the lower end and $300 on the higher end.
svetikd / Getty Images/iStockphoto
9. Make Your Bed Hotel-Quality
Bring the feeling of a luxurious hotel bed into your own home by upgrading your bedding. You can find down duvet inserts and feather beds for less than $100 each. Use your remaining budget to invest in high-quality, high-thread-count sheets, and your bed will feel like a cozy retreat.
ESB Professional / Shutterstock.com
10. Add New Flooring
Replacing wall-to-wall carpeting and other outdated flooring will provide a great return on your investment. Juneja recommends using Pergo, a laminate wood that fits tongue-in-groove and is easy to install. An average-sized room would cost about $400, he said.
Shutterstock.com
11. Replace Dated Brass Fixtures
Back in the 1980s, shiny brass fixtures were popular, but now they just make homes look dated. Replacing these fixtures with brushed nickel or oil-rubbed bronze fixtures can instantly update your home, said Mindy Jensen, community manager for BiggerPockets, an online real estate investing resource.
It won’t cost a lot, either, to replace the ’80s brass in your home. For example, cabinet knobs start at about $1 each and drawer handles start at $2, Jensen said. You can get modern door knobs for $20 and up, and plumbing fixtures cost $50 and up, she said.
Jaskaran Kooner / Getty Images/iStockphoto
12. Make Brass Fixtures Look More Modern
There’s a cheaper alternative to updating brass fixtures in your home. You can buy a bottle of brass darkening solution online or from a craft or home improvement store for less than $10 to give your fixtures an antique brass look, which is trendy now.
“Put it on everything brass, and bring your home into the 21st century,” said Sam Perks, a real estate broker with Re/Max House of Real Estate in Fort Lauderdale, Florida. It will give your fixtures a more modern appearance and add appeal to your interior, he said.
Shutterstock.com
13. Install New Light Fixtures
Lighting is one of the most important things you can update in a home, Juneja said. And it won’t set you back too much to install updated overhead fixtures and add both floor and table lamps to a room.
You should budget about $100 to $200 per fixture and $10 to $20 for enough light bulbs for each room, Juneja said. Be sure to avoid fluorescent lighting, which can cast a harsh glow, he said. When showing your house for sale, switch LED bulbs for incandescent lights, which create a softer light.
Tomsmith585 / Getty Images/iStockphoto
14. Change Light Switches to Dimmer Switches
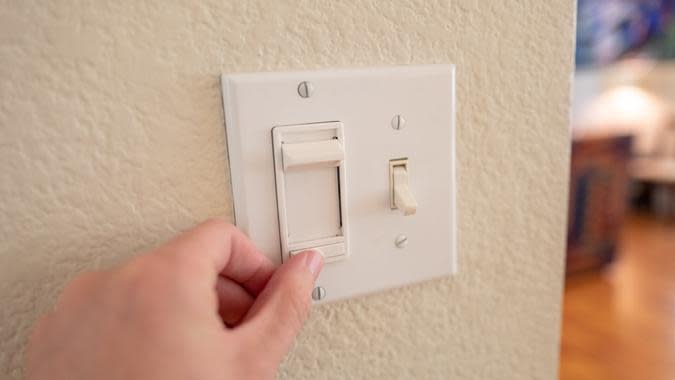
As you update the light fixtures in your home, don’t neglect the light switches. Perks recommends replacing standard light switches with dimmer switches — ideally models that have motion sensors that turn lights on when a person enters a room and off when there’s no activity for a certain amount of time.
“Buyers today want energy efficient homes,” Perks said. “In low-traffic areas, a motion sensor switch can save a lot of energy that would otherwise be wasted when lights are left on.”
You can get dimmers for as little as $13 and light switches with motion sensors for about $25 and up.
FollowTheFlow / Getty Images/iStockphoto
15. Add More Reflective Surfaces
In addition to upgrading your lighting, you can amplify the lighting you already have by adding more reflective surfaces and strategically placed mirrors around a room. You can find a wide variety of wall mirrors, floor mirrors and mirror sets for less than $250 on sites like Wayfair.
funeyes / Pixabay
16. Install a Ceiling Fan
Improve airflow in an especially stuffy room by installing a ceiling fan. The average cost of a unit plus labor is $247, according to HomeAdvisor.
gilaxia / Getty Images
17. Revamp Kitchen Cabinets
Kitchen updates can be the key to maximizing your home’s value. But you don’t have to start from scratch to remodel your kitchen. A relatively inexpensive way to give your kitchen an updated look is to paint — rather than replace — cabinets and add new knobs, Juneja said. Expect to spend about $35 per gallon of paint and $10 to $12 per knob.
Or, you could replace a couple of cabinet doors with glass doors to instantly modernize them and bounce light throughout the space, Juneja said. It will cost about $500 to add two glass cabinet doors.
iStock.com
18. Update Your Kitchen Tile
Your tile could be making your kitchen look outdated. Swap it out for classic subway tile or mosaic tile, which Jensen said is popular and affordable. Jensen said she bought mosaic tile for her kitchen from Costco, which cost $5 per square foot.
You can also take a class at a home improvement store to learn how to install tile. “Take your time, and you will be amazed at how easy it can be,” she said.
Another alternative is to clean your existing tile and grout, which will instantly refresh the look of your kitchen. It typically costs between $282 to $665 per room to have this done by a professional, according to HomeAdvisor.
jodiejohnson / Getty Images/iStockphoto
19. Revamp Your Kitchen Counters
Some big-box stores offer kitchen countertop revamp packages, which include the cost of the counters and installation, for less than $500. The cost will depend on the size of your counter and the material you use. There are now lots of great-looking laminates that work as a cost-saving alternative to granite.
contrastaddict / Getty Images
20. Freshen Up a Bathroom
In addition to the kitchen, the bathroom is one of the rooms that benefits the most from small improvements, according to HGTV. And you can update it for less than $500.
Juneja said lighting is the most important feature in a bathroom to upgrade. You can add new overhead lights and wall sconces near a mirror for about $400.
Shutterstock.com
21. Add New Bathroom Accessories
If you don’t want to undertake the project of installing new lighting, buying a new rug, shower curtain and towels will freshen up the room. Give your bathroom a spa-like feel with a plush or bamboo-style bath mat, a fabric shower curtain and extra-soft bath towels.
Shutterstock.com
22. Install Floating Shelves in Your Bathroom
Cut down on clutter and add more storage to your bathroom by installing floating shelves. Or, invest in an aesthetically pleasing standing unit if you don’t want to deal with the hassle of installation. You can find high-quality ladder floor storage units for less than $250.
Jodi Jacobson / Getty Images
23. Clean Your House’s Exterior
Realtors suggest that a good, thorough cleaning of the front of your home can increase the value by several thousand dollars, Gibbons said. But the cost of making this improvement is low. You can rent a pressure washer for less than $100 to clean the dirt and mildew from your home. Or, you can hire someone to do it for you for about $200, Sharp said.
MCCAIG / Getty Images/iStockphoto
24. Spruce Up Your Yard
Improving your property’s curb appeal can be as simple as cleaning up your current landscaping. Janine Acquafredda, an associate broker with House-n-Key Realty in Brooklyn, New York, said you can pay about $150 for a lawn care professional to spruce up your front yard by trimming bushes and removing weeds. A clean yard — along with a clean exterior — can attract more eyes to your property and get you offers that are as much as 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher than offers for homes that haven’t made these simple improvements, Acquafredda said.
Shutterstock.com
25. Plant Evergreen Trees
Planting a screen of evergreen trees can create year-long privacy and a natural property line that can give a home seller an edge over competing properties, Perks said. A 4-foot tree can cost around $50 or so.
“While it’s unlikely to add much dollar volume to a sale, it can easily create a perception of completeness that will make a sale happen,” Perks said.
RyanJLane / Getty Images
26. Buy Indoor Plants
Even if you don’t have outdoor space, you can bring some green into your life by purchasing some indoor plants. You can even grow an herb garden inside. There are many indoor herb garden kits available for around $100 or less.
More From GOBankingRates
Gabrielle Olya contributed to the reporting for this article.
Florida owners trying to get up to $10,000 in state funding for windstorm protection enhancements are presently becoming notified that they’ve been accepted for the matching grant.
An approval implies that house owners who expend $15,000 on advancements are qualified to get $10,000 and cut down their challenge value to $5,000.
There is a recently disclosed catch: To get reimbursed, property owners will have to spend their contractor in comprehensive for the position and post a reimbursement bill along with evidence of whole payment to the contractor. Which is various than what application officials said a couple of months in the past.
But {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} small-expression financing selections are out there that will protect the price right until the reimbursement check out arrives, contractors say.
The My Harmless Florida Property system, funded by the state Legislature final May, commenced accepting programs for windstorm mitigation inspections on Nov. 18. With $115 million earmarked for grants, the program approximated that 11,000 to 12,000 owners would be authorised for up to $10,000 each.
Homeowners can get started the grant application procedure by requesting an inspection at www.mysafeflhome.com or calling 1-866-513-6734.
Grant funding is getting made obtainable on a initial-arrive, very first-provide foundation, and 13,840 inspection applications have been in some “form of status” as of Jan. 4, according to a method official.
Florida home owners in search of up to $10,000 in state funding for windstorm mitigation enhancements can download this guide by going to mysafeflhome.com and clicking the “Means” tab at the best of the homepage. (Florida Section of Monetary Services)
Windstorm mitigation inspections to establish enhancements required to provide properties up to modern-day development codes have been immediately scheduled for earliest candidates, and inspection reviews determining qualifying advancements commenced likely out a 7 days or two later on.
Upon receiving inspection experiences, applicants were being invited to use for grants of up to $10,000 each, and this 7 days, the system began notifying earliest applicants that they have been authorized.
As of Jan. 4, about 5,160 inspections have been finished, and 213 grant purposes have been submitted. The very low variety of grant applications indicates that a greater part of applicants are however awaiting their inspection studies.
The software features $2 in point out funding for each and every $1 house owners add for improvements that involve impression-resistant home windows, exterior doorways and garage doors that fulfill existing windstorm codes, new roof coverings, upgraded roof-to-wall connections and other roof upgrades.
The advancements will improved safeguard houses versus harming winds and qualify individuals houses for insurance plan quality savings.
Jeff Torrey, a Deerfield Seashore retiree who utilized for an inspection on the working day the software portal opened, located out on Thursday that he is authorized for a grant.
“I’m finding 13 affect home windows and a new front doorway,” Torrey reported by phone. “On two jalousie windows at the gable finishes of my residence, I’m likely to set accordion shutters.”
Torrey experienced been on the lookout into the program’s necessities even right before it commenced accepting applications. He arrived at out to a community contractor and urged him to participate in the program, and so now he’s completely ready to commence function.
The email notifying him of his grant approval provided a website link to a list of collaborating contractors. As of Friday, 44 contractors had registered to do the job on residences in Broward, Palm Beach and Miami-Dade counties. Most of the contractors are registered to function in all 3 counties, in accordance to the list, which can be accessed at https://www.neighborlysoftware.com/dashboard/mysafefloridaprogram/.
[ RELATED: After latest insurance reforms, what rights do policyholders have left? ]
A guidebook obtainable for download at the My Safe Florida Household website spells out necessary techniques that owners will have to adhere to to be suitable for reimbursement. To find the tutorial, go to www.mysafeflhome.com and simply click the Methods tab at the top rated of the website page.
They involve:
Original windstorm mitigation inspections will have to be coordinated as a result of the plan.
Only single-family members, proprietor-occupied, site-created properties with insured alternative value of $500,000 or significantly less are eligible. Constructing permits for the properties ought to have been issued right before July 1, 2008. House owners of condos, townhouses, mobile houses, multi-household dwellings, flats, rental attributes, trip residences and uninsured attributes require not utilize.
Eligibility is limited to households located within the “wind-borne particles region” as outlined in the Florida Building Code. That is a U-shaped location of the point out that covers all of southern Florida, the Panhandle and considerably of the remaining coastlines. It excludes several northern and central counties.
Only advancements determined the inspection report are suitable for reimbursement. In other phrases, the plan will not shell out for a new garage doorway if an applicant’s recent garage door presently meets present constructing codes.
Contractors ought to be registered participants of the plan. Home owners are urged to receive 3 competing estimates, even though that is not necessary.
Home owners can deal for operate that expenses much more than $15,000, but $10,000 is the optimum that the condition will reimburse.
Following the get the job done is complete, it need to be inspected by the homeowner’s community developing section. Contractors really should be paid in entire right after the perform passes inspection.
Property owners should submit several files, such as programs for the initial windstorm mitigation inspection and matching grant, and the inspection report. These should really by now be in the homeowner’s My Safe and sound Florida Home account dashboard.
Other needed documents involve the contractor’s estimate (or estimate), the contractor’s bill, proof of payment to the contractor (can be a cancelled look at or receipt of payment from the contractor), and a document from the homeowner’s insurance firm or agent demonstrating the quality discounts secured as a end result of the advancements.
Following the system started getting programs for windstorm mitigation inspections in late November, officers of the point out Section of Economical Expert services, which oversees the program, did not instantly specify no matter if homeowners would have to pay back for the enhancements upfront ahead of obtaining the $10,000 grant.
Office spokesman Devin Galetta in December advised that householders might only have to give a down payment to their contractor and then wait until the grant test arrives just after get the job done is done to fork out the stability. But the latest posted assistance clarifies that house owners should deliver proof that contractors have been totally paid out in advance of reimbursements could be received.
“After further evaluate, the [program] has identified that it is in the finest interest of the property owners and plan-authorized contractors for home owners to spend for mitigation enhancements when finished and then post this documentation for reimbursement,” Galetta explained in an electronic mail on Friday.
The necessity could be a burden for candidates who never have $15,000 to shell out. But, numerous have options to defray the whole upfront price.
[ RELATED: You can now apply by phone for up to $10,000 for home-hardening improvements ]
Numerous contractors authorised to participate in the application reported they can assist buyers protected shorter-time period {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} financing so they will not have to prepay the $10,000 they expect to get from the state.
Not all contractors will supply funding for their tasks. But numerous do, and candidates really should request contractors what solutions are obtainable.
Luke Amorseano, proprietor of Fort Lauderdale-primarily based Luke Skybuilder LLC, mentioned his enterprise can assist home owners get hold of a limited-time period house advancement home finance loan that would be payable when the house owner gets the $10,000 reimbursement. Price to the property owner would be a 1.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} financial loan servicing cost ($150 if financing $10,000) as well as a $75 county recording price.
Although desire charges would start out to accrue everyday at 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} APR if the customer defaults, “The upside to this is that the home-owner will have a compensated-in-comprehensive receipt for having their rebate because Luke Skybuilder will be demonstrated as paid,” Amorseano stated. “The house loan be aware will be beneath the loan servicing firm.”
Matias Colombo, manager of All Weather conditions Protective Programs in Pompano Seaside, said his enterprise features various funding programs that will not accrue desire for 6 months to 18 months that will also enable home owners to present proof of comprehensive payment when they use for reimbursement.
A further possibility, Amorseano said, is for owners to sign up for Speed (Home Assessed Thoroughly clean Electricity) funding. Tempo financing calls for no upfront cost, no credit history verify, and can be repaid at any time, all at the moment or over a interval of many years at a preset desire fee. But debtors are charged program fees that include up to $2,000 to the principal.
Ron Hurtibise covers enterprise and shopper issues for the South Florida Sunlight Sentinel. He can be achieved by telephone at 954-356-4071, on Twitter @ronhurtibise or by e mail at rhurtibise@sunsentinel.com.
Whether you’ve recently bought a house and want to make some adjustments or have been a homeowner for quite some time and think you’re long overdue for some renovations, you’ll want to make sure you have the financial means to take on such project.
Home improvement costs can vary depending on what part of the home you’re fixing, but according to Rocket Mortgage, Americans spend an average of $15,000 on a single home improvement project.
If you don’t have the savings to float your entire improvement project, you might consider applying for a personal loan since it can be used for a variety of expenses and typically carry lower interest rates compared to credit cards. Personal loans must be paid back in regular increments over a set period of time. The longer your loan term, the lower your monthly payments will be but the more you’ll pay in interest charges over that duration.
Select rounded up six of the best personal loan lenders to consider if you need to finance a home improvement project. When compiling our list of the best personal loans, Select evaluated dozens of lenders. We looked at key factors like interest rates, fees, loan amounts and term lengths offered, plus other features including how your funds are distributed, autopay discounts, customer service and how fast you can get your funds. (Read more about our methodology below.)
5.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 23.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}* when you sign up for autopay
Loan purpose
Debt consolidation, home improvement, auto financing, medical expenses, wedding and others
Loan amounts
Terms
Credit needed
Origination fee
Early payoff penalty
Late fee
Pros
Same-day funding available through ACH or wire transfer
Loan amounts up to $100,000
No origination fees, no early payoff fees, no late fees
LightStream plants a tree for every loan
Cons
Requires several years of credit history
No option to pay your creditors directly
Not available for student loans or business loans
No option for pre-approval on website (but pre-qualification is available on some third-party lending platforms)
Who’s this for? LightStream stands out for offering loans with some of the lowest interest rates and providing loans for nearly every purposeexcept for higher education and small business. In other words, home improvements are fair game for the use of these funds.
It offers the longest-term option among the lenders on this list, which typically means lower monthly payments, and less pressure when repaying debt. On the flip side, a longer term also means you’ll accrue more interest charges over the long run.
LightStream does not charge any origination fees, administration fees or early payoff fees. All these points make this lender an appealing option for those who want to score an interest rate that’s as low as possible and achieve a monthly payment that’s as low as possible.
Debt consolidation, home improvement, medical expenses, auto financing and more
Loan amounts
Terms
Credit needed
Origination fee
Early payoff penalty
Late fee
Pros
Credit union membership available to anyone
Loans as low as $600
Can pick up a physical at a branch
May apply with a co-borrower
Cons
Funds come as a physical check
Must be a member to get funds (no membership needed to apply)
Must pay for expedited shipping to get your funds next day
Maximum loan amount of $50,000
Late fee of $29
Who’s this for?PenFed offers loans of as little as $600, making it ideal for those who may not necessarily need a massive home improvement undertaking but just need a little extra cash for a smaller fix.
Note that this lender is a credit union. While you don’t need to be a member to apply, you will need to sign up for a PenFed membership and keep $5 in a qualifying savings account to receive your funds.
Also, PenFed provides its funds in the form of a paper check. If you live near a PenFed location, you can pick up your check at any time directly from the bank. Otherwise, you can receive your funds as early as the next day if you pay for expedited shipping.
Debt consolidation, credit card refinancing, home improvement, wedding, moving or medical
Loan amounts
Terms
Credit needed
Credit score of 300 on at least one credit report (but will accept applicants whose credit history is so insufficient they don’t have a credit score)
Origination fee
0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the target amount
Early payoff penalty
Late fee
The greater of 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of last amount due or $15, whichever is greater
Pros
Open to borrowers with fair credit (minimum 300 score)
Will accept applicants who have insufficient credit history and don’t have a credit score
No early payoff fees
99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of personal loan funds are sent the next business day after completing required paperwork before 5 p.m. Monday through Friday
Cons
High late fees
Origination fee of 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the target amount (automatically withheld from the loan before it’s delivered to you)
$10 fee to request paper copies of loan agreement (no fee for eSigned virtual copies)
Must have a Social Security number
Who’s this for? If you need to make home improvements but worry that a low credit score would disqualify you from many loans, the good news is thatUpstart offers you an option for funding. This lender is ideal for individuals with a low credit score or even no credit history. It considers factors like education, employment, credit history and work experience.
Term lengths are a bit limited, though, compared to other more flexible options; you can choose either a three-year or five-year loan. Borrowers can apply for as little as $1,000 and as much as $50,000.
There are a few fees to be aware of with this loan. Upstart charges an origination fee of up to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the loan amount, as well as late fees, but no early payoff fee.
6.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 24.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} APR when you sign up for autopay
Loan purpose
Debt consolidation, home improvement, wedding, moving and relocation or vacation
Loan amounts
Terms
Credit needed
Origination fee
Early payoff penalty
Late fee
Pros
No origination fees, no early payoff fees, no late fees
Will send direct payment to up to 10 creditors (for debt consolidation)
Monthly VantageScore updates
Earn a one-month payment vacation (interest-free) after making 12 on-time consecutive payments
Ability to choose your due date when you accept the loan (and again up to two more times after that)
Cons
Does not accept joint applications and/or co-signers
Not the fastest funding (can take a week or 10 business days)
Slightly tougher approval requirements (especially for larger loans/lower interest)
Who’s this for? A Marcus by Goldman Sachs Personal Loan is a good choice if you’re looking for a no-fee personal loan that gives you some flexibility when it comes to making payments. Borrowers can earn a one-month payment vacation (interest-free) after making 12 on-time consecutive payments. This can be a welcomed reprieve for some borrowers.
This lender also gives you the ability to choose your payment due date when you accept the loan (and again up to two more times after that). This way, you can select a due date that works best with your payment schedule and other expenses.
The maximum funding amount is slightly lower than the maximum from some other lenders: Borrowers can apply for up to $40,000. This may not be a dealbreaker for those who have more modest home improvement undertakings, but if you have a renovation project that’s going to cost significantly more, you might want to consider other lenders.
7.99{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 23.43{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} when you sign up for autopay
Loan purpose
Debt consolidation/refinancing, home improvement, relocation assistance or medical expenses
Loan amounts
Terms
Credit needed
Origination fee
Early payoff penalty
Late fee
Pros
No origination fees, no early payoff fees, no late fees
Unemployment protection if you lose your job
DACA recipients can apply with a creditworthy co-borrower who is a U.S. citizen/permanent resident by calling 877-936-2269
Can have more than one SoFi loan at a time (state-permitting)
May accept offer of employment (to start within the next 90 days) as proof of income
Co-applicants may apply
Cons
Applicants who are U.S. visa holders must have more than two years remaining on visa to be eligible
No co-signers allowed (co-applicants only)
Who’s this for?SoFi offers personal loan amounts up to $100,000, making it ideal for those who have more costly, higher-lift home improvement projects to take on. But this lender also offers repayment terms that are longer compared to those of most other lenders: Borrowers have 24 to 84 months to pay back the loan.
Most other personal loans come with a fixed interest rate but SoFi gives borrowers the option to choose between a fixed and variable APR. Variable rates can go up and down over the lifetime of your loan, which means you could potentially save if the APR goes down (but it’s important to remember that the APR can also go up). However, fixed rates guarantee you’ll have the same monthly payment for the duration of the loan’s term, which makes it easier to budget for repayment.
SoFi also provides a 0.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} discount on your APR if you set up automaticelectronic monthly payments.
Debt consolidation, home improvement, wedding or vacation
Loan amounts
Terms
36, 48, 60, 72 and 84 months
Credit needed
Origination fee
Early payoff penalty
Late fee
Pros
No origination fees, no early payoff fees
Same-day decision (in most cases)
Option to pay creditors directly
7 different payment options from mailing a check to pay by phone or app
Cons
Late fee of $39
No autopay discount
No cosigners or joint applications
Who’s this for? If you need funding in a pinch for a home renovation that’s more of an emergency than it is for vanity, Discover Personal Loans is a solid contender since borrowers can receive their funds as early as the next business day. Of course, in order to get your funds in a timely manner, you must submit an application that is complete and doesn’t contain errors (you’ll also want to make sure the loan is funded on a weekday).
While there are no origination fees,Discover does charge a late fee of $39 if you fail to repay your loan on time each month.
Because personal loans are a form of installment credit, borrowers repay the balance in fixed, equal amounts over a set period of time. This period of time is known as the loan’s term. Most loan terms range anywhere from six months to seven years. The longer the term, the lower your monthly payments will be, but this also usually means you’ll pay more in interest charges over the duration of your loan. It’s usually best to choose the shortest term that you can afford.
Once you’re approved for your home improvement personal loan, the cash is usually delivered directly to your checking account. When paying back the loan, be aware of any late fees or early payoff penalties. Your monthly payment will include interest. When your personal loan is paid off, the credit line is closed and you no longer have access to it.
How big of a home improvement loan can I get?
Lenders offer the ability to choose from a wide range of loan amounts, starting from $600 and going up to $100,000. However, before you apply, you should consider how much of a loan you can reasonably afford. Avoid taking on a loan that you cannot afford to pay back since you’ll also be responsible for interest charges and any additional fees should you make a late payment or miss a payment.
Your interest rate is typically based on your credit score, credit history and income, as well as factors like how much of a loan you’re applying for and the loan term. Generally, loans with longer terms have higher interest rates since lenders are giving you a longer runway to pay the balance back in full.
Co-signers: A co-signer agrees to help you qualify for the loan, but they are only responsible for making payments if you are unable to. The co-signer does not receive the loan, nor do they necessarily make decisions about how it is used. However, the co-signers credit will be negatively affected if the main borrower misses payments or defaults.
Co-borrower: Unlike a co-signer, a co-borrower is responsible for paying back the loan and deciding how it is used. Co-borrowers are usually involved in decisions about how the loan is used. Some lenders will only consider two co-borrowers who share a home or business address, as this is a firm indicator that they are sharing the responsibility of money in mutually beneficial ways. Both co-borrowers’ credit scores are on the hook if either one stops making payments or defaults.
Direct payments: Some lenders offer direct payments when you select debt consolidation as the reason for taking out a personal loan. With direct payments, the lender pays your creditors directly, and then deposits any leftover funds into your checking or savings account. Until you see your account balance is fully paid off, it’s best to keep making payments so that you don’t get hit with additional late fees and interest charges.
Early payoff penalty: Before you accept a loan, look to see if the lender charges an early payoff or prepayment penalty. Because lenders expect to get paid interest for the full term of your loan, they could charge you a fee if you make extra payments to pay your debt down quicker. The fees could equal either the remaining interest you would have owed, a percentage of your payoff balance or a flat rate.
Origination fee: An origination fee is a one-time upfront charge that your lender subtracts from your loan to pay for administration and processing costs. It is usually between 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, but sometimes it is charged as a flat-rate fee. For example, if you took out a loan for $20,000 and there was a 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} origination fee, you would only receive $19,000 when you got your funds. Your lender would get $1,000 of the loan off the top, and you’d still have to pay back the full $20,000 plus interest. It’s best to avoid origination fees if possible. Having a good to excellent credit score helps you qualify for loans that don’t have origination or administration fees.
Unsecured versus secured loans: Most personal loans are unsecured, meaning they are not tied to collateral. However, if your credit score is less-than-stellar and you’re finding it hard to qualify for the best loans, you can sometimesuse a car, house or other assets to act as collateral in case you default on your payments. When you put an asset up as collateral, you are giving your lender permission to repossess it if you don’t pay back your debts on time and in full.
Bottom line
A home renovation can be a tremendous financial undertaking, which is why choosing the personal loan that’s right for you can make you feel a little less financially strained. Features like term length, funding timeline and fees are all points to take note of when weighing lenders.
When narrowing down and ranking the best personal loans, we focused on the following features:
No origination or signup fee: None of the lenders on our best-of list charge borrowers an upfront fee for processing your loan.
Fixed-rate APR: Variable rates can go up and down over the lifetime of your loan. With a fixed rate APR, you lock in an interest rate for the duration of the loan’s term, which means your monthly payment won’t vary, making your budget easier to plan.
Flexible minimum and maximum loan amounts/terms: Each lender provides a variety of financing options that you can customize based on your monthly budget and how long you need to pay back your loan.
No early payoff penalties: The lenders on our list do not charge borrowers for paying off loans early.
Streamlined application process: We considered whether lenders offered same-day approval decisions and a fast online application process.
Customer support: Every loan on our list provides customer service available via telephone, email or secure online messaging. We also opted for lenders with an online resource hub or advice center to help you educate yourself about the personal loan process and your finances.
Fund disbursement: The loans on our list deliver funds promptly through either electronic wire transfer to your checking account or in the form of a paper check. Some lenders (which we noted) offer the ability to pay your creditors directly.
Autopay discounts: We noted the lenders that reward you for enrolling in autopay by lowering your APR by 0.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 0.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Creditor payment limits and loan sizes: The above lenders provide loans in an array of sizes, from $500 to $100,000. Each lender advertises its respective payment limits and loan sizes, and completing a preapproval process can give you an idea of what your interest rate and monthly payment would be for such an amount.
After reviewing the above features, we sorted our recommendations by best for overall financing needs, debt consolidation and refinancing, small loans and next-day funding.
Note that the rates and fee structures advertised for personal loans are subject to fluctuate in accordance with the Fed rate. However, once you accept your loan agreement, a fixed-rate APR will guarantee interest rate and monthly payment will remain consistent throughout the entire term of the loan. Your APR, monthly payment and loan amount depend on your credit history and creditworthiness. To take out a loan, lenders will conduct a hard credit inquiry and request a full application, which could require proof of income, identity verification, proof of address and more.
Editorial Note: Opinions, analyses, reviews or recommendations expressed in this article are those of the Select editorial staff’s alone, and have not been reviewed, approved or otherwise endorsed by any third party.