OZ Benefits For HNWIs, An OZ Pitch Day Panel

OZ Benefits For HNWIs, An OZ Pitch Day Panel

In this panel from OZ Pitch Day Spring 2022, a trio of experts discuss the various strategies that investors can use to optimize the tax efficiency of their portfolios.

Webinar Highlights

  • The ongoing disconnect between housing supply and demand that will likely persist for years to come, and how that creates an opportunity for high net worth investors.
  • The relative merits of 1031 exchanges compared to Qualified Opportunity Funds.
  • Scenarios where Opportunity Zones may be particularly attractive — and other scenarios where the clear preference may be for a 1031 exchange.
  • How depreciation can have a major impact on returns realized in OZ investments.
  • Live Q&A with webinar attendees.

Industry Spotlight: Cantor Fitzgerald

Cantor Fitzgerald is a leading global financial services firm, serving clients from over 30 offices around the world. Founded in 1945 as a securities brokerage and investment bank, the firm pioneered computer-based bond trading, built one of the broadest distribution networks in the industry and became the market’s premier dealer of government securities.

Investment Management. Jay is involved in overseeing the day-to-day operations of the business, providing direction and implementing strategic initiatives. 

Visit Cantor.com to learn more.

Industry Spotlight: Realized

Realized is an end-to-end platform that lets investors exchange 1031-eligible properties for diversified portfolios of property interests, customized to your shifting income needs, risk appetite, and investment goals across generations.

In his role as Head of Wealth Management for Realized, Rob is responsible for overseeing the client’s Investment Property Wealth Management (IPWM) experience. In addition, Rob works with Registered Investment Advisors (RIA) and Broker Dealer networks throughout the United States in an effort to increase awareness of the 1031 exchange and Delaware Statutory Trusts (DSTs) to support client financial planning needs.

Visit Realized1031.com to learn more.

Industry Spotlight: MultifamilyInvestor.com

MultifamilyInvestor.com covers trends and opportunities in multifamily real estate investing. We help High Net Worth investors, family offices, RIAs & financial advisors, and industry service providers navigate the ins and outs of the multifamily landscape.

Visit MultifamilyInvestor.com to learn more.

Webinar Transcript

Jimmy: Well, today’s panel is Opportunity Zone investing or Opportunity Zone benefits for high-net-worth investors. My three panelists here today, I’m gonna introduce them very briefly. We only have 20 minutes, so it’s gonna be kind of rapid-fire. But Jay Frank, joining us from Santa Monica, California. He’s president of Cantor Fitzgerald capital and co-head of their real estate investment management business. Scott Hawksworth joining me here today from Chicago, Illinois. He’s co-founder of MultifamilyInvestor.com and host of the “Multifamily Investor” podcast, which is a resource for passive high-net-worth real estate investors. And Rob Johnson also joining us today. He’s here from Austin, Texas. Rob is head of wealth management for Realized. They’re a platform for investment property wealth management, and they specialize in 1031 DSTs and, of course, opportunity zones. So, gentlemen, I wanna start with Scott Hawksworth first.

And Scott, the reason why I wanna start with you is because multifamily is by far and away the most popular sector for Opportunity Zone investing. In fact, 9 of the 12 Qualified Opportunity Funds that are partnering with us on today’s event are multifamily funds, or at least have a very strong multifamily component. So, Scott, why do you like multifamily as an asset class for high-net-worth investors?

Scott: Yeah, thanks, Jimmy. I like multifamily as an asset class for a number of reasons, but I think the biggest reason is we have an ongoing housing shortage in this country. We are underbuilt, and that creates tremendous opportunity for high-net-worth accredited investors. And that kind of underlines what you were just mentioning about the number of funds that have multifamily. And there’s a statistic that I like to point out here, and I have it right here. And this is according to a recent report from the National Association of Realtors. We have an underbuilding gap of 5.5 to 6.8 million housing units. And that has been ongoing since about 2001. So, again, that’s a mismatch between supply and demand. And so there are these funds that are addressing this issue. But even with all of that activity, the demand is not going away, and the supply is just not meeting it. And you see this all over the country. So, I think when we’re talking about the opportunity for return, it’s really tremendous. And that’s why I like multifamily.

Jimmy: Good. Let’s turn to Rob next. A lot of real estate investors traditionally are very familiar with 1031. It’s been a traditional tax advantage vehicle for high-net-worth real estate investors for decades and decades and decades. Can you compare and contrast the section 1031 exchange with Opportunity Zones? What do investors need to know?

Rob: Yeah, no, that’s a great question. So, we get that frequently from clients who could go either way, and they’re gonna evaluate the considerations and upsides of doing one or the other. So, let’s talk about the eligible gains. With a QOZ Fund, any capital gain, regardless of the asset that generated, that gain can go into a QOZ Fund. For a 1031 exchange, it’s limited to gains from real property held for investment or used in a trade or business. So, it’s extremely clear. One is real estate-based. The other one is gonna be any capital gain. The reinvestment of proceeds. What’s nice about the QOZ Fund is you’re only going to reinvest the capital gain. You can reinvest the basis, but it’s not gonna receive the tax benefits. So, quite honestly, we discourage a client from doing that. In the 1031 exchange, you have to reinvest all proceeds, both your basis and the gains. And you have to have the same, or greater amount of debt through the 1031 exchange. So, there are some IRS policies that have to be followed.

The time to reinvestment with the QOZ Fund. You have 180 days, and the gain must be triggered on or before December 31st of 2026. With the 1031 exchange, the time constraints can be very onerous. You’ve got 45 days after the sale of that property to identify what your replacement is gonna be, and then 180 days to reinvest. But you are stuck with what you identify in that 45-day period. So, if you, you know, identify something you don’t close on, it’s gonna blow up your exchange. The replacement asset Qualified Opportunity Zone Funds. You’re gonna invest 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the assets in the QOZ property. Real property must be like-kind. So, the IRS is gonna keep a very close eye on what exactly you use to replace that property, and it has to be the real property designation underneath the IRS.

Location of replacement asset. Obviously, the QOZ is in an Opportunity Zone. It has to be designated by the census. With the 1031 exchange, you could pretty much go in any U.S. state and region that you want. Qualified intermediary, or QI, or an exchange accommodator is gonna be required for 1031 exchange. They have to hold the money. If you don’t pass the proceeds onto them from the sale of the property, you’ll blow up your 1031 exchange. You don’t need a QI in a QOZ transaction. Minimum holding period, the QOZ, at least 10 years to achieve the maximum tax benefit. With the 1031 exchange, it’s really gonna be when… You have to have it for a minimum, in most cases due to IRS policy in terms of a hold. But after that, you can exit when you find a potential buyer for the property. And the tax on the gain generated by the replacement asset for the QOZ, it’s eliminated if held for 10 years, maybe eliminated upon the investor’s death. With the 1031 exchange, it’s due upon the sale of the asset, but they also can qualify with the step-up basis. So, those are the main differences with the QOZ versus the 1031.

Jimmy: Yeah, no, that was a great breakdown, Rob, very, very in-depth, very detailed. Jay, kind of want you to kind of take that and keep going here, comparing and contrasting OZs with 1031s. Jay, Cantor Fitzgerald, I know you have a lot of high-net-worth accredited investors that you advise on this situation all the time as well. And, you know, just like Rob does. How often for you do you find that an Opportunity Zone investment is better than a 1031? And when should investors selling real estate really consider OZs as opposed to…or as a replacement for 1031?

Jay: Yeah. Great. And nice job, Rob. I’m happy to pick up where you left off there. Section 1031 in the tax code has a lot of complexities to it, right? And you should be talking to at first, at a minimum, your CPA or tax attorney, maybe your state planning attorney, and probably a financial advisor. Opportunity Zones to take that complexity to the next level. So, you know, to the nth degree, there should be that team involved in the process because when you are making a decision between one or the other, or don’t forget, you can also invest in both simultaneously. It’s not always opportune, but you can. There’s a lot of different considerations, not just in terms of the investment return, investment time period, horizon, you know, income versus growth when you’re gonna get the returns, etc., like Rob was touching on, but also it has to do with the client’s personal situation. What account that they’re holding it in? The estate planning needs. What tax bracket they’re in? What state do they live in? There’s a whole bunch of, you know, economic considerations, but then there’s a whole bunch of human considerations that go into this.

The general rule that we refer to when you’re kind of comparing a 1031 to an OZ, obviously, only for someone selling investment real estate is when they both are in play. If an OZ tends to be preferred when the client has a basis in the proper they’re selling and/or a little debt. So the more basis they have, the less amount of debt they have, the more the opportunity that it’ll be attractive. So, Jimmy, you bought some land in Dallas, a $ 1 million dollars, it’s land, so you don’t have depreciate it. So, your basis is a $1 million. A few years later, you sell it for a $1.5 million and you have no debt. If you do a 1031 exchange, all $1.5 million would need to go in the exchange to defer a 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your taxes. With an Opportunity Zone, you’d be able to take the million dollars of basis out tax-free, put it in your pocket, diversify it. And only the $500,000 of capital gain would need to go into the Opportunity Zone Fund to defer a 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your tax liability. So, in that situation, I’d say 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} plus of the time, an investor that’s informed and has good advice, would be looking at an Opportunity Zone.

On the flip side, the other bookend where a 1031 tends to be superior is when the lower the amount of basis the client has, often zero basis, and the more debt they have on the real estate property they’re selling tends to be when the 1031 is superior. And the reason why is, example, Jimmy, you bought a rental property in Dallas for a million bucks, you sold it for a $1.5 million. However, you owed it for 30 years, you’ve depreciated it to zero and you have a million-dollar loan on the property. If you were to put your money in 1031, you simply need to take the $1.5 million and complete the exchange. You defer all your taxes. To do an OZ and defer all your taxes, you’d have to first take your $1.5 million and pay off a million-dollar loan to the bank. You’d have a $500,000 left over to invest in the OZ. Then, you’d have to come up with another $1 million out of pocket to invest in the OZ to address your deferred and recapture depreciation tax. So, it really depends on the client situation, both economic considerations, but also human considerations. And it’s a small amount of time, but there are times when you can use a combination of 1031 exchanges and Opportunity Zones on the same transaction.

Jimmy: Great. I think that was an awesome breakdown that both you gentlemen gave. Jay and Rob, thank you so much for that. I think that’s helpful to a lot of investors on the call today who have familiar with 1031s, maybe they’re starting to learn about OZ. Always good to compare and contrast those two programs. I wanna pulse Scott back in, give him another question about multifamily. That’s his area of expertise. So, Scott, you know, just kind of looking at the world at large over the past 24 months or so, we’ve really been in a period of a lot of economic uncertainty with the COVID pandemic and the resulting recession, the imbalance in the labor market. And now the war in Ukraine is kind of making everybody a little jittery, a little bit more uncertain. Do you still like multifamily during this period of economic uncertainty?

Scott: Absolutely. I think it really gets down to the basic fact that everybody needs a home. They need to live somewhere. And multifamily really addresses this need. And then when you look at it at the real estate sector and where it fits traditionally, multifamily has been among the most resilient. So, does well in terms of generating returns in periods of economic expansion and in times of economic uncertainty, or even recession, multifamily has performed well. And I would also say, as you’re kind of looking back through it, we’re coming out of COVID-19, it’s also created a lot of shifts in lifestyle, and work from home, and all of that. And so that really is attractive to a lot of potential renters and has really driven up the need for that housing and for their expectations on amenities and having quality housing and really having folks really reevaluate the four walls that they’re spending their time in. So, I think, for me, even in a climate of economic uncertainty, multifamily is still something I’m very bullish on.

Jimmy: And regularly tying it back into Opportunity Zones and Opportunity Zone investing, multifamily is where it’s at typically for the types of real estate assets that we see, you know, I think, more than half. According to the most recent Novogradac survey, more than half of the capital raised, data’s been going into funds that have, at least some sort of strong residential or multifamily component. And, you know, bringing it into the Opportunity Zone communities really gives investors a chance to do well by doing good, not only are they providing much-needed housing for this country but also they’re doing it in the areas that need it most, these traditionally underserved economically downtrodden communities.

Jay, let’s bring you back in now. Just one more question for Jay and Rob. We gotta wrap things up here pretty quick. But, Jay, why are we seeing more real estate gains from investment properties going into Opportunity Zones? And in your experience, maybe I’m kind of giving away the answer, I’m leading the witness here a little bit, but does the average financial advisor know enough about Opportunity Zones to properly advise high-net-worth investors their clients on that option of OZ investing?

Jay: No, you got it. And it’s not just the financial advisor, it’s fill in the blank advisor, you know, legal advisor, tax advisor, financial advisor, you know, spousal advisor, whatever it is. Many people just are ignorant to the opportunity. I would also add that people miss one of the key elements that make Opportunity Zone viable for real estate changes, which is, it’s not just the capital gain from this sale of an investment property that can be invested in the OZ in realized the tax benefits. It is also the unrealized depreciation expense. At least the straight-line portion of it, is also eligible. And that key element is what… So, if you had, you know, again, a $500,000 gain and $700,000 depreciation recapture expense, most people think, “Well, I can invest a $500,000 million. I have to pay taxes on the $700,000.” They don’t realize that all $1.2 million could go to get all the tax benefits.

Another thing about depreciation is, remember you’re building brand new properties, which means you have a full depreciable schedule. You can be using, you know, multifamily as a shorter depreciable life than most, again, a bonus there. You can be using cost segregation, component depreciation to really accelerate depreciation, and you can be using bonus depreciation, which was also part of the same Tax Cuts and Jobs Act that created the OZ program. Meaning, said in another simple way is there is so much depreciation that can be passed through in the first 7, 10-year useful life of these assets that the amount of taxable rental income, the investors are gonna be received from these things are probably zero or very close to it. So, there’s two ways that people are unaware of how depreciation plays in and can benefit from the OZ program, A, can be invested in the program, but B, all the appreciation from the program is also gonna be tax-free, assuming you hold it for the required period of time.

Jimmy: Terrific. Yeah, no. Great points there, Jay. Thank you. That’s really interesting about the depreciation as well there. Rob, I’m gonna leave you at the final word here. We gotta cut you guys loose here in a couple minutes. I got my next presenter coming on at 35 after the hour here. But Rob, looking at the future here, I’m gonna turn to you. Opportunity Zones in 2022 and beyond. You know, we’ve gone through that expiration of the 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} basis step-up at the end of last year. So, we’re kind of looking forward to the future program over the next, you know, four-plus years when it is scheduled to sunset. How do you view that opportunity today and going forward, and any additional thoughts or insights you have on opportunity zones?

Rob: Yeah, I mean, I would say that it’s taken too long, in my opinion, for investors to make full use of the Qualified Opportunity Zone opportunity. It got off to a little bit of a slow start. We’re seeing a lot of investors utilize it now for the right reasons, not just for deferral but for planning, long-term planning, retirement, estate planning, things that we normally would use with more traditional investments. They’re benefiting from a Qualified Zone Fund and investment in that manner. So, I hope more individuals are aware of the opportunity that this provides. And my hope is also that the government, as the years go on, understands the benefit of reinvesting in challenged communities, challenged areas, and the benefit that can lead to our society, communities, education growth, you know, the ability to live in a community that’s safe and leads to, you know, better society. So, I hope that the opportunity continues from a legislative purpose.

Jimmy: Agreed. And with any hope, fingers crossed, we’ll get this thing extended at some point. Well, I’m gonna end this session there. Hopefully, that was helpful for you as a high-net-worth investor. Some of the options you have and some of the considerations you should make when contemplating an Opportunity Zone investment, especially with you’re comparing it with a section 1031 exchange, and especially if you’re a multifamily investor. This has been Jay Frank with Cantor Fitzgerald, Scott Hawksworth with multifamilyinvestor.com, and Rob Johnson with Realized. I’m gonna cut you gentlemen loose here and demote you to participants again, but thank you for attending today. Appreciate it.

Scott: Thanks, Jimmy.

Rob: Thanks, Jimmy. Thank you, gentlemen.

A TikTok budget-luxury expert who posts viral hacks shares easy home improvement tips she uses in her house

A TikTok budget-luxury expert who posts viral hacks shares easy home improvement tips she uses in her house

Clare McLaughlin, a TikTok home improvement expert, and her living room.

Clare McLaughlin, a TikTok home-advancement qualified, and her residing space.Clare McLaughlin

  • A TikTok household-advancement skilled who gives spending plan-luxurious strategies shared hacks she makes use of in her individual house.

  • Clare McLaughlin instructed Insider she kinds textbooks by color and employs picket dividers in drawers.

  • She also claimed people today ought to think extended-phrase when purchasing household furniture alternatively than adhering to traits.

A spending budget-luxurious expert can make viral TikTok films presenting affordable dwelling decor suggestions to her significant subsequent on the application.

Clare McLaughlin, a budget luxury expert who shares home improvements on TikTok.

Clare McLaughlin, a price range-luxurious specialist who shares house improvements on TikTok.Clare McLaughlin

Clare McLaughlin is a 28-yr-aged information creator with a track record in inside design and style, centered in New York Metropolis. She experimented with creating TikTok movies centered on her artwork in April 2020, ahead of tapping into a rising need for residence interiors hacks.

Considering the fact that then, her TikTok account has grown to a surplus of 998,000 followers, who can ordinarily expect lifestyle and house business hacks, with a “finances-luxury” concentrate. McLaughlin advised Insider that spending plan luxury is all about “being resourceful with your existing residing circumstance.”

“I required my property to come to feel deluxe but I didn’t want to go broke executing it,” McLaughlin said. Here are the minimal-work updates she produced to her dwelling to make it experience far more expensive without the need of breaking the lender.

Purchase much less highly-priced units and boost them with a lot more luxurious facts.

A before and after shot of Clare McLaughlin's modified drawers.

A before and immediately after shot of Clare McLaughlin’s modified drawers.Clare McLaughlin

A prevalent oversight men and women tend to make with residence decoration is that they miscalculation a substantial cost tag or a properly-identified manufacturer for quality, claimed McLaughlin.

“Occasionally the most pricey significant furniture retailers have almost everything made with questionable labor at a stunning portion of the conclude price,” McLaughlin mentioned. Instead, she explained potential buyers ought to break down what they value about a superior-stop piece, whether or not that’s brass components or door handles, and search for out these features for a lot less.

“Hold people matters in mind when searching for a fewer high-priced device,” McLaughlin claimed. “You can often swap out the existing, low cost hardware for nicer pulls and knobs.”

In her personal dwelling, McLaughlin mentioned she changed grey plastic knobs on her drawers with brass ones and it elevated the piece for a portion of the value. She also bought adjustable picket dividers for drawers which make them glance custom made-created.

Use antique indicators rather of modern-day decor with crafting on it.

Signs reading "Screw Room" and "toilet" in TikToker Clare Mclaughlin's home.

Indicators reading through “Screw Space” and “bathroom” in TikToker Clare Mclaughlin’s dwelling.Clare Mclaughlin

Mclaughlin stated that people today must embellish their households in any way that can make them joyful but for these actively trying to get a luxury come to feel, prevent modern decor with words or phrases on.

“I am going to acknowledge that it is really surely uncomplicated to see a ‘French Laundry’ cursive font on a distressed wood signal and feel it’ll adjust the total vibe of your home, but these items cheapen the appear of your room,” she said.

If you’re definitely fully commited to the strategy of producing on homeware, Mclaughlin endorses antique signals as a good compromise due to the fact they assist your household appear curated and superior-conclude.

Mclaughlin has a navy-blue and white antique “bathroom” indicator exterior her toilet. “It really is little, subtle, and authentic — and it was only $5,” she explained. “Why invest in a little something new that is developed to search outdated when you can pay the very same selling price for the antique first?”

Sort guides by coloration or remove their sleeves to include fascination to your shelves.

Colorful bookshelves in TikToker Clare McLaughlin's home.

Vibrant bookshelves in TikToker Clare McLaughlin’s home.Clare McLaughlin

Color-blocking bookshelves is a absolutely free hack that McLaughlin executed in her household to make it sense more coordinated. “If you evaluate all of your books, you’ll probably notice that they tumble into specified shade teams,” she stated. “I removed the e book jackets to expose far more solid spines, and the end final result looked good.”

The content material creator included that she’s viewed trends exactly where purchasers pay out hundreds of bucks for matching textbooks to make their dwelling search cohesive. She claimed she uncovered this fairly “unhappy” and encouraged persons to only decorate with issues they genuinely love as this will also help you save revenue invested on needless buys.

Spend in home furnishings that is timeless so it won’t go out of fashion.

A view of Clare McLaughlin's bedroom interiors.

A view of Clare McLaughlin’s bedroom interiors.Clare McLaughlin

A ultimate idea, and a person that McLaughlin individually life by, is not to observe structure traits and decide for evergreen furnishings. “Prior to you commit $7,o00 on a lime eco-friendly bubble boucle sofa, request you no matter if your 60-12 months-previous self will like it,” she instructed Insider, noting that decor can grow to be a major expenditure if you obtain seasonally.

For merchandise that stand the test of time, McLaughlin advisable shaker door panels on cupboards, home furnishings crafted with bamboo or wooden, and white or beige materials.

She added that most of the items she has gathered will occur with her to long run properties and even go to her little ones a single working day: “My home furniture is just not pricey by any means, but I have sourced items that are very well produced and significant top quality, by way of thrifting and picking out inexpensive things that were being developed with regard to background.”

Read through the unique write-up on Insider

Master Gardeners: Forsythia sage | Home And Garden

Master Gardeners: Forsythia sage | Home And Garden

Last spring, my wife and I were procuring at an Austin nursery that is regarded for marketing indigenous plants and other plants that are drinking water smart. I was searching for purple and purple blooming plants, and the nursery staff directed me to the sage/salvia place. I observed the red Texas sage (Salvia coccinea), and added 6 vegetation to my wagon.

The subsequent early morning, I started picking out planting spots and placing the several crops in open spaces. Turns out, there was a plant labeled Forsythia sage mixed in with the purple Texas sage. The name indicated that it would bloom yellow, but considering that a sage was a sage, I chose a web-site for the plant not totally understanding what to anticipate.

A lengthy wait

As the plant grew, I noticed some discrepancies among this sage and the half dozen other versions I have in my back garden. The plant was quite herbaceous with thick dim inexperienced foliage, sort of like a spinach leaf. It sprawled all more than the put and would not bloom. Then, in November, flower spikes started to variety and what a great shock the plant was.

A minimal qualifications details

Forsythia sage (Salvia madrensis), according to the North Carolina Point out Extension, is a “perennial plant native to Mexico in the Lamiaceae (mint) family.” Its species identify “madrensis” is derived from the locale in which it grows in its indigenous habitat, the Sierra Madre Oriental mountain variety. Wikipedia notes that it grows at “4,000 to 5,000 feet elevation in warm, damp places.”

Increasing circumstances

I planted my Forsythia sage in an space that receives morning shade and afternoon solar. That may clarify its sprawling, floppy advancement. According to the Central Texas Gardener, “morning sun is ideal, or solar all over the working day, but not whole blast all day, specially afternoon.” The report notes that “Forsythia sage is not far too certain about soil ph, but very good drainage would be a advantage.”

Growth habit

The Forsythia sage is similar in condition and behavior to the Amistad sage (Salvia Amistad) that I have experienced in my garden for lots of several years. The stems are ridged and square and the plant can be quite big. The leaves are deep eco-friendly and make a statement on their personal. The Central Texas Gardener states that the plant can be “5-8 feet broad with 3 foot tall bouquets.” I really don’t know if it is my plant’s area or the fact that it was the initially 12 months, but it only grew to about 3 toes significant and 3 feet wide. The Amistad sage does get about 5 toes superior.

Bloom time

Just one of the very best things about the plant is the time of 12 months that it blooms. My plant was expanding effectively, but would not bloom. I had about given up, when I seen bloom spikes were beginning to type at the stop of just about every stem. This development was in late Oct. A fall bloomer. Who knew? To say the minimum, I was both surprised and delighted. The blooms lasted till the very first freeze.

Propagation

The Forsythia sage did die down to the roots through the tough February freeze. The Central Texas Gardener states that it is “generally hardy to zone 7” and that the plant should be “cut to the ground in late winter season/early spring.” The sage is now putting out shoots from the roots and I system on transferring the plant to a far better site. Then I will get started some new plants from the underground shoots.

Winner, winner

Uncomplicated to develop. Attractive dazzling yellow flower spikes. Fall bloomer.

The Gardeners’ Filth is penned by customers of the Victoria County Master Gardener Affiliation, an educational outreach of Texas A&M AgriLife Extension – Victoria County. Mail your questions in care of the Advocate, P.O. Box 1518, Victoria, TX 77901 or vcmga@vicad.com, or remark on this column at VictoriaAdvocate.com.

How to avoid getting scammed by a contractor

How to avoid getting scammed by a contractor

Hunting to make house enhancements? Here is how to keep away from obtaining ripped off by a contractor


Clarifies HOW TO Stay away from Rip-off CONTRACTS.OR BRIAN: ’TIS THE Period FOR Earning Household Advancements AND Alongside WITH IT Comes THE Year FOR Rip-off CONTRACTO.RS Prior to YOU Retain the services of A CONTRACTOR Put IN THE Function AND Effort TO Obtain A REPUTABLCOE NTRACTOR. GET ESTIMATES AND Tips FROM AT Least Three, AND AS Numerous AS Six Unique CONTRACTORS. THAT Need to GIVE YOU A Great Strategy OF A Fair Cost Assortment. Ask FOR REFERENCES AND Photographs OF Employment THEY HAVE Carried out. Call THE People today THEY HAVE Worked FORND A GO Pay a visit to SOME OF THEIR Career Web sites. Terrible CONTRACTORS WILL BE Reluctant STOHARE THIS Information AND SCAMMERS Will not Wait FOR YOU TO DO YOUR Research. BEWARE OF CONTRACTORS WHO HAENPP TO BE IN THE Community AND JUST KNOCK ON YOUR Door. GET A Detailed, Penned Deal. A Commence Date, Selling prices, Products AND LABOR Costs Ought to BE Put IN Composing Alongside WITH ANY OTHER Specifics YOU WANT. People Details Stay clear of Unexpected Concerns THAT Increase THE Value. Term OF MOUTH AND HANDSHAKE Deals ARE One Thing BUT IF YOU Never HAVE IT IN Writing, YOU Really don’t HAVE IT. THE More quickly YOU MAKE A Final decision ON Hiring A CONTRACTOR, THE Far more YOU May possibly Arrive TO REGRET IT. BRIAN ROCHE, ON YOUR Facet, W

Wanting to make residence improvements? Here’s how to stay clear of getting ripped off by a contractor

It truly is the period for creating home improvements and along with it comes the season for fraud contractors.Protect by yourself by placing in the time and energy to discover a trustworthy contractor.Get estimates and concepts from at the very least a few and as several as 6 different contractors. That must give you a superior notion of a truthful value selection.Talk to for references and pics of work they have carried out. Get hold of the people today they have worked for and visit some of their job websites. Negative contractors will be reluctant to share this details, and scammers would not hold out for you to do your homework.Beware of contractors who happen to “be in the neighborhood” and just knock on your door.Get a in depth, created contract. A start out day, selling prices, resources and labor expenditures should be set in creating along with any other particulars you want. All those details steer clear of sudden problems that raise the selling price. Phrase of mouth and handshake offers are 1 point, but if you never have it in composing, you do not have it.The a lot quicker you make a choice on using the services of a contractor, the additional you may well occur to regret it.

It really is the year for making house enhancements and together with it comes the time for scam contractors.

Shield you by placing in the time and hard work to uncover a dependable contractor.

  • Get estimates and ideas from at least 3 and as quite a few as six distinct contractors. That ought to give you a good plan of a good selling price range.
  • Question for references and images of work opportunities they have accomplished. Call the men and women they have worked for and go to some of their position websites. Lousy contractors will be reluctant to share this data, and scammers would not wait around for you to do your homework.
  • Beware of contractors who occur to “be in the neighborhood” and just knock on your door.
  • Get a in-depth, prepared deal. A start date, rates, materials and labor prices must be place in crafting along with any other information you want. Those specifics avoid sudden difficulties that increase the selling price. Term of mouth and handshake bargains are a person issue, but if you really don’t have it in creating, you do not have it.

The faster you make a final decision on employing a contractor, the additional you may possibly appear to regret it.

What is happening in this housing market?

What is happening in this housing market?

1st-time consumers will be priced out

The persistent deficiency of provide in today’s industry merged with surging demand is driving up rates and pushing a lot more potential prospective buyers to the sidelines.

“All the metrics relevant to profits and affordability in housing seem out of sync and the strange motion in the facts is actually caused by absence of supply,” reported Lawrence Yun, main economist at the Nationwide Affiliation of Realtors. “We need to get the inventory up.”

The common house has noticed a 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase in monthly payments in excess of a year ago, claimed Yun, with a about 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} enhance in residence selling prices and a further 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in better home finance loan fees.

“People’s incomes have not risen to the diploma that selling prices have risen and the expense burden of ownership has been drastically amplified,” he reported.

This is not sustainable, Yun explained, and the end result is an significantly inequitable housing industry in which less individuals can very own homes and first-time purchasers are priced out solely.

“Costs climbing this a great deal is not nutritious,” he reported. “Persons associate the American aspiration with doing work challenging and proudly owning a household and it seems ever more out of get to or unattainable.”

Rising fascination charges need to sluggish demand from customers

Housing authorities note that the exuberance in the housing marketplace was also fueled by mortgage costs that had been far too lower for much too lengthy as a outcome of the Federal Reserve Bank’s monetary plan.
As rates rise, they say, demand from customers will fall off.

“Soaring curiosity premiums from 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to almost 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in excess of 4 months, that has aided thrust some competitiveness to the sidelines,” mentioned Mike Maher, co-founder and CEO of Houwzer, a genuine estate brokerage.

What will my monthly mortgage payment be?

Continue to, he included, “it is going to be actually tough for this bubble to burst any time shortly for the reason that demand is outpacing source and even even though prices are growing, funds continues to be low-cost by historical standards.”

A single probable benefit of soaring mortgage premiums, he said, is that the inventory picture could strengthen.

“What I hope occurs is in excess of the subsequent 12 to 24 months is that increasing curiosity prices push some potential buyers to the sidelines to flatten property cost appreciation a bit. Then, potentially, householders would go their homes into the market place,” he mentioned.

Traders might commence to withdraw

A market bubble can occur about when there is a lot of speculation and potential buyers come in with the intent of offering for much more income afterwards. Some housing specialists level to the growing participation of traders in the sector as a signal that a bubble is brewing.

“I’m moderately anxious about a bubble likelihood,” stated Arpit Gupta, an Assistant Professor of Finance at New York University’s Stern College of Business. “My problem in housing is that house flipping is up.”

The number of properties flipped by traders in 2021 rose 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2020 and have been at their highest amounts because 2006, in accordance to ATTOM, a serious estate details firm.

These traders include things like “mom and pop” flippers, as effectively as massive true estate firms in the ibuyer organization and, to a lesser degree, providers in the solitary-relatives rental small business who are betting on soaring rents.

“That basic rise in rents is supporting residence selling prices,” stated Gupta. who added that the lion’s share of dwelling gross sales are even now to people working with the property as a spot to are living.

How much house can I afford?

“Buyers are betting on a potential of increased inequality where by a larger sized portion of People are renters,” claimed Daryl Fairweather, chief economist at Redfin. “They are contributing to that dilemma by competing from to start with-time homebuyers and continuing to dwindle the supply in that entry rate band.”

When traders usually are not automatically producing the dilemma, she claimed, they are profiting from additional than a 10 years of underbuilding in the US, which has developed an surroundings of low provide and high need.

But the enchantment of these investments may well be dwindling.

Even though the number of flipped residences rose very last calendar year, the gross revenue margins on house flips in 2021 sank to their least expensive stage in extra than a decade, according to ATTOM.

“There are a bunch of points that are troubling symptoms that propose that residence charges are having in advance of the capacity of people today to reside in those people properties and pay for them,” said Christopher Mayer, a actual estate professor at Columbia Organization University. “At some place traders have to offer to an individual. They can market to other investors — that’s a bubble. But … finally properties have to be cost-effective for the people today who are living in them.”

Price ranges aren’t possible to go down … yet

Never maintain your breath for dwelling rates to return to “typical.” Selling prices are not probably to head decrease any time before long, in accordance to Fairweather.

“It is tough to picture charges going down,” she stated. “But I consider we are nearing the close of the interval wherever houses are likely for $100,000 over inquiring price tag.”

She was brief to caution that this is not like the previous housing crisis, the place many householders experienced mortgages they could not afford. “We acquired a whole lot past time and we don’t have those people same risks,” Fairweather stated.

New lending laws set in area immediately after the housing crisis ended up designed to superior control the economical sector and secure individuals. Most owners have set rate home loans now, and there are not so many balloon payments to stress about, she stated. Also, lending standards are considerably stricter.

“Existing owners had to clearly show they have lots of belongings to get the home finance loan and they have plenty of fairness,” reported Fairweather. “There has not been much predatory lending the way there was prior to. If nearly anything, there is a lack of entry to credit history for all those who have less-than-perfect credit rating scores.”

Should I rent or buy a home?

Critically, any change in the housing industry is not probable to appreciably affect the broader economy as it did previous time, stated Mayer. “This must not exhibit up in the monetary program, but it will clearly show up in other spots.”

When prices may possibly not appear down any time before long, they probably will at some point, he claimed.

“I you should not believe the hazard is like what we saw from 2008 to 2010 or that selling prices are heading to collapse,” explained Mayer. “But it is flawlessly affordable that they could go up in the future yr, and then go down. I could see price ranges getting 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower three to five decades from now. And you could stop up advertising for a minor significantly less than you bought it for.”

That suggests people seeking to purchase now should really focus on a household they can moderately find the money for and continue to be in for a though, claimed Fairweather.

In the end, customers can tame that “panic of lacking out” experience, reported Fairweather, by acquiring a house they can continue to be in and improve in for the upcoming five yrs or lengthier.

Luxury homes listed for over  million in Canada

Luxury homes listed for over $1 million in Canada

The average price of a home in Canada now stands at an all-time high of $816,720. According to a new report released by real estate company Re/Max, it seems as though a key driver of growth has been the recent boom in Canada’s luxury home market.

Data revealed that 18 of the 19 local markets assessed in the report saw significant year-over-year increases in the sale of luxury homes worth more than $1 million, ranging from detached and attached units, to condominium properties.

The Greater Toronto Area and Metro Vancouver remain red-hot markets, seeing considerable growth in the sale of homes worth more than $3 million, with increases of 112.8 per cent and 75.8 per cent, respectively. Based on data gathered by the Canadian Real Estate Association, the average price of a home in both Ontario and British Columbia has recently exceeded $1 million.

Several other markets also saw notable gains in the sale of luxury homes at over $1 million year-over-year. In Barrie, Ont., 278 units were sold for more than $1 million in 2021, an increase of about 518 per cent compared to the year before. Meanwhile, Saint John reported the sale of 15 units above $1 million each in 2021, an increase of 1,400 per cent when compared to a single sale made in 2020.

Only one market reported a drop in the sale of homes worth more than $1 million; Charlottetown saw a 42.9 per cent decrease in sales from 2020 to 2021.

With considerable demand for luxury homes across the country, CTVNews.ca has compiled a list of Canadian properties currently on the market for at least $1 million.

METRO VANCOUVER

(Lawrence Lu / Jerry Wang, Macdonald Platinum Marketing)

(Lawrence Lu / Jerry Wang, Macdonald Platinum Marketing)

Type: House

Price: $2,888,000

Year Built: 2013

Property Size: 334 sq. m

Lot Size: 0.67 hectares

Located in the Metro Vancouver area, this European-style home welcomes its guests with six-metre ceilings over the foyer, living and family rooms. Floor-to-ceiling windows offer stunning views while allowing natural light to pour in. The luxury property has five bedrooms, six bathrooms, a home office and a private media room. Its 73-foot yard and covered patio are ideal for enjoying outdoor activities all year long.

KELOWNA

(Kevin Arnason / Todd Simpson, Royal LePage Kelowna)

(Kevin Arnason / Todd Simpson, Royal LePage Kelowna)

Type: House

Price: $6,249,000

Year Built: 2010

Property Size: 948.35 sq. m

Lot Size: 0.27 hectares

With its custom-built pool featuring mosaic tiling, an adjacent sports court and a sunken trampoline, this Mediterranean-inspired home is ideal for entertaining. Complete with seven bedrooms and eight bathrooms, the property spans nearly 950 square metres in total. The interior boasts sky-high 6.7-metre ceilings and luxury brand finishes, while an outdoor covered kitchen and pergola give this estate its resort vibe.

CALGARY

(Sona Visual and Zoon Media / Heather Waddell, Sotheby’s International Realty Canada Calgary)

(Sona Visual and Zoon Media / Heather Waddell, Sotheby’s International Realty Canada Calgary)

Type: House

Price: $4,425,000

Year Built: 2009

Property Size: 437.82 sq. m

Lot Size: 0.1 hectares

This luxury home in Calgary is an architectural marvel, with floor-to-ceiling windows that offer stunning views of nearby mountains and valleys. The open-concept kitchen comes with oak plank flooring and a central island. On the upper level is the master bedroom with a private balcony, large dressing room and closet. With three bedrooms and five bathrooms, the home also has a yoga room and wine cellar.

EDMONTON

(Rocco Macri / Trevor Dunn, MaxWell Realty)

(Rocco Macri / Trevor Dunn, MaxWell Polaris Realty)

Type: House

Price: $1,150,000

Year Built: 1925

Property Size: 280.15 sq. m

Lot Size: 0.3 hectares

Initially built in 1925, this Edmonton luxury home has been completely rebuilt for a more contemporary look and feel. Four bedrooms and five bathrooms span across 2.5 storeys, amounting to more than 4,000 square metres of living space. The master bedroom also comes with its own balcony. Meanwhile, a loft and ensuite bathroom occupy the top floor, and a home theatre fills the lower level. The home also has its own wine cellar and vault for tasting.

TORONTO

(Hooman Aliary, The Agency Development Group Toronto)

(Hooman Aliary, The Agency Development Group Toronto)

Type: House

Price: $9,700,000

Year Built: 2006

Property Size: 929 sq. m

Lot Size: 0.42 hectares

Near Toronto’s Bridle Path community is this timeless luxury home with its own grand foyer and piano lounge. The gourmet kitchen comes with chef-grade appliances and a walk-in fridge, while the master ensuite features its own steam shower and boudoir. A wood-panelled grand family room also offers views of a nearby ravine. On the lower level is a wine cellar, billiard room and exercise lounge with direct access to the inground pool.

GREATER MONTREAL

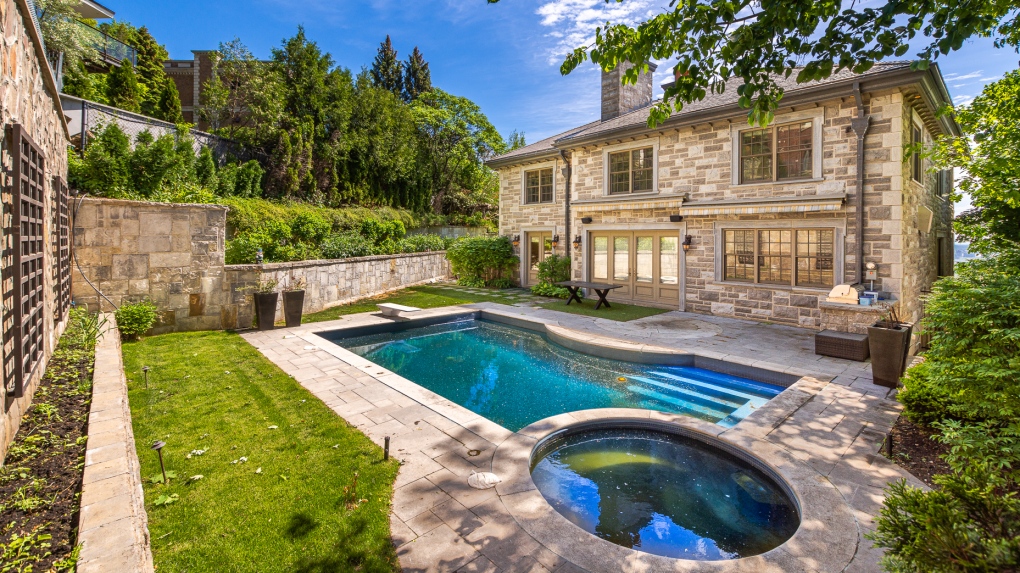
Luxury homes listed for over  million in Canada(Studio Point De Vue / Joseph Montanaro, Re/Max Action Westmount)

(Studio Point De Vue / Joseph Montanaro, Re/Max Action Westmount)

Type: House

Price: $7,900,000

Year Built: 2005

Lot Size: 0.09 hectares

Located in Greater Montreal, this luxury estate with stone exterior sits high on Upper Bellevue, offering extensive views of the metropolitan area below. The custom-built home has five bedrooms, four bathrooms, and a home office. An open-concept chef’s kitchen leads directly into a spacious den for easy access. The property also has an integrated double garage, as well as a landscaped garden surrounding a private pool.

ST. JOHN’S

(Amanda Ryan / Rob Moore, Re/Max Realty Specialists)

(Amanda Ryan / Rob Moore, Re/Max Realty Specialists)

Type: House

Price: $1,695,000

Year Built: 2016

Property Size: 459.87 sq. m

Lot Size: 0.22 hectares

This lakeside property located on a cul-de-sac in St. John’s comes with private access to Virginia Lake. On the main floor is a great room with windows that span from the floor to its cathedral ceilings, maximizing the outdoor view. The gourmet kitchen features a large island with labradorite granite countertops, a gas cooktop and a walk-in pantry. On the top floor is a loft area overlooking the great room, as well as three bedrooms and a spa-inspired master bathroom.

HALIFAX

(Studio Royale / David Dunn, Royal LePage Atlantic)

(Studio Royale / David Dunn, Royal LePage Atlantic)

Type: House

Price: $3,499,000

Year Built: 2011

Property Size: 423.45 sq. m

Lot Size: 0.2 hectares

With four bedrooms and four bathrooms, this Halifax home comes with spectacular views of the Northwest Arm, a key part of Nova Scotia’s coastline. Located lakeside, the property also features its own dock, as well as a putting green. Inside, its kitchen comes with granite countertops, built-in appliances, a breakfast bar and a butler’s pantry. On the top floor is the master bedroom with a walk-in closet and private deck overlooking the water.

CHARLOTTETOWN

(Patty Campbell, Powerhouse Realty PEI)

(Patty Campbell, Powerhouse Realty PEI)

Type: House

Price: $1,149,000

Year Built: 2020

Property Size: 389 sq. m

Lot Size: 0.17 hectares

Just a 14-minute drive from the heart of Charlottetown, this corner lot property has five spacious bedrooms and just as many bathrooms for a total area of nearly 400 square metres. The kitchen features custom cabinets, a stone backsplash, and a double sink, while the living room has a stone propane fireplace. A soaker tub and large glass shower can be found in the master bathroom, while a recreation room is found in the basement.

FREDERICTON

(Matthew Gorveatte / Larry Booker, Re/Max East Coast Elite Realty)

(Matthew Gorveatte / Larry Booker, Re/Max East Coast Elite Realty)

Type: House

Price: $1,195,000

Year Built: 2016

Property Size: 435.62 sq. m

Lot Size: 0.21 hectares

Located in Fredericton, this custom luxury home is as spacious as it is stunning. On the upper floor is the master bedroom, with access to an elevated patio with a hot tub and seating area to view the backyard. The main level features an open-concept living space with a two-sided gas fireplace separating the family room from the kitchen. An oversized sunroom overlooks the backyard, while an entertainment room and exercise area fill the lower level.