March is a great time to dig into our gardens and landscapes. How are our “gardens” and “landscapes” similar? Both equally entail soil, water and vegetation. Equally aid the biodiversity of insects and wildlife. The two can profit from our stewardship.
We frequently believe of gardens as prepared and tended regions to mature greens, flowers, shrubs, and trees. Landscapes, on the other hand, may possibly be larger sized normal regions and viewscapes that are prepared and unplanned, non-public and general public, tended and untended.
So gardens are, effectively, small-scale landscapes.
What does the word “treasure” suggest to you? Something that you worth? Actions that you take to safeguard that valued something — how you “treasure” your “treasure”?
“Treasure” implies the notion of riches. Gardens and landscapes are a form of riches, a unique kind of “green” that’s not purchased and sold for earnings, saved in a lender or jewellery box, or utilized to obtain factors. You can treasure gardens and landscapes outside of their financial price, for their significance to your personal health and quality of everyday living and to your community’s nicely-becoming and sustainability.
Frederick County is fortuitous to be home to lots of gardens and treasured landscapes, “places that stand out … with a lot of inspiring, effective, and in a natural way numerous lands,” in accordance to the Sugarloaf Treasured Landscape Administration Approach. These landscapes “enhance, and in some cases protect, the purely natural, cultural, and historic characteristics” of our property county, for each the Livable Frederick Implementation Plan, and url our communities jointly.
In fact, county land use planners have recognized several locations that can advantage from “focused awareness,” including the Sugarloaf Mountain region, the Middletown Valley and the Catoctin Creek space.
And local weather change is adding urgency to these county attempts to protect and sustain these and other area and regional landscapes, effective lands, and all-natural methods.
Definitely, you know of some gardens and landscapes that can benefit from your personal, focused interest. Early spring is a good time to dig in!
At house: If you have outside place with some soil and sunshine, regardless of whether a balcony or yard, you can plant and sustain your personal back garden — your own treasured landscape — in pots, planters, borders and elevated beds.
Farther afield: If you have space in a local community backyard, or many others need support with theirs, you can prolong your treasured landscape endeavours to include these gardens, as well.
Community: If your neighborhood, college, church or local park has a Inexperienced Crew, pollinator backyard garden or tree-planting task, you can function with other volunteers to plant and care for people shared landscapes.
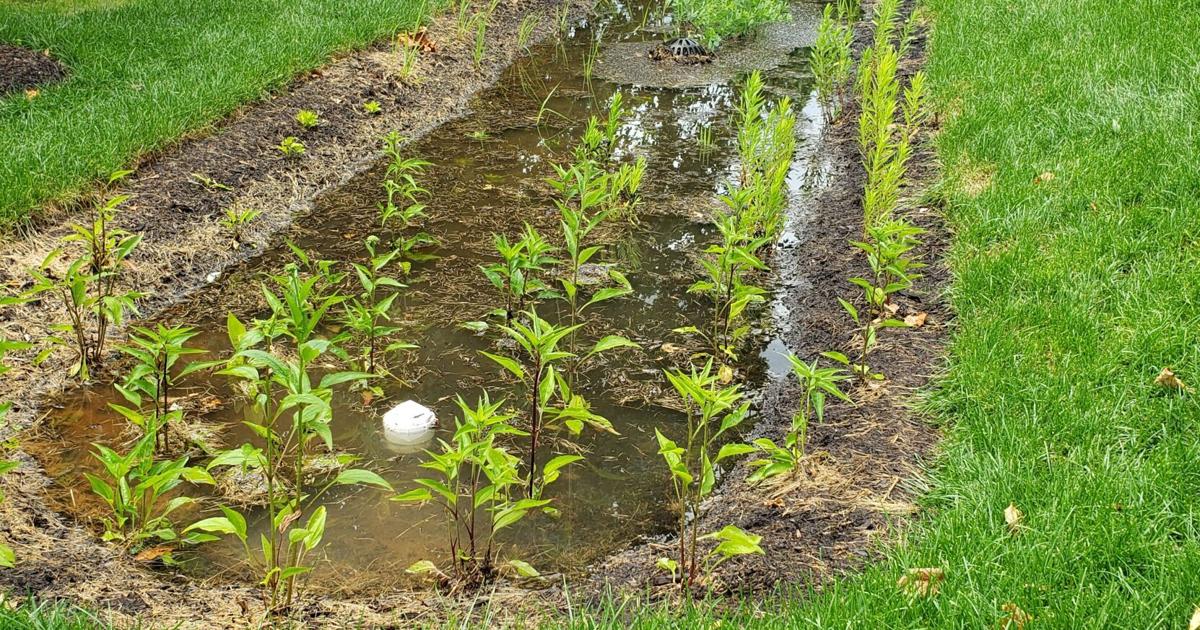
You might be interested to know that in help of these treasured landscapes and gardens, last April, the Maryland senate passed Home Bill 322, which compels homeowners’ associations (HOAs) and other businesses to enable reduced-impact landscaping, such as rain gardens, indigenous plant gardens, pollinator gardens and xeriscaping in subdivisions. The legislation specifically forbids HOAs to call for that cultivated vegetation [in gardens] consist in total or in portion of turf grass, in accordance to an report posted on the Indigenous Plant Society web site.
Blanca Poteat is a Frederick County Learn Gardener.
Desire rates across the board have absent up and the financial gain buyers make from a multifamily outweighs a more compact 1-4 device setting up. With costs raising, an trader is better off securing additional units at a increased level, instead than just a solitary-family members expense at an fascination charge at this time previously mentioned 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Just just one multifamily investment home can turnaround a struggling, underperforming portfolio. Investors that have skipped out on various qualities throughout past yr can also make up for that decline of opportunity with only a person multifamily property. Desire prices are also tipping the scales toward multifamily investing for the reason that in a market place in which rates are scaring absent anyone, an investor with a multifamily financial investment assets with several models for lease just located by themselves in a high leverage predicament. In an article discovered on wealthmanagement.com, this sentiment is echoed, “As households become more high priced to acquire, and new merchandise a lot more costly to create, the present inventory of rental housing results in being extra important and in-need.”
Multifamily financial investment qualities are essential for a selection of explanations but mostly for investors the most beautiful factor is the scalability chance it results in for them. The funds generated from a rental house, occasionally referred to as passive income, is amplified tremendously by possessing a multifamily property. With this money coming in due to quantity of units, it is less difficult for traders to extend and make down payments on investments. Any investor will acquire you as a result of their journey that typically commences with modest resolve and flip initiatives, shifts to owing solitary family rentals and jumps to owning multifamily properties. Buyers are normally wanting for the following problem and a probability to receive the greatest ROI. With multifamily financial commitment properties, the route to financial liberty has under no circumstances been a lot easier. With a companion or two and a several trusted property professionals, traders can cross the 50–100-unit threshold with ease.
Liquidity equals flexibility
Liquidity is a further beautiful reason why buyers want multifamily expense qualities in their portfolio. As opposed to stocks and bonds, a multifamily expense residence holds its worth at a significantly extra reputable price than an expenditure in the stock sector. That value will make these investment decision homes significantly far more captivating and offers flexibility to an financial investment portfolio. If a new house arrives on the sector and an investor needs to liquidate before long to totally free up some cash to make a down payment, a multifamily investment is just the asset they would need to have. Whether it is marketing off a selected selection of units to make it worthwhile or unloading the multifamily house fully, an trader can come up with that down payment money. Inventory sector situations could lead to an investor to miss out on an possibility if the market place is down, so having that multifamily home can demonstrate to be considerably a lot more reputable.
The property advancement market place is bracing for a bumpy highway.
Two of the major house improvement vendors, Property Depot (Hd) and Lowe’s (Lower), warned of softness in the market in the latest earnings reviews, indicating the year in advance is probable to be a tricky 1 as inflation weighs on shoppers.
“In 2023, residential expenditure will be underneath some strain, provided elevated concentrations of inflation, greater interest charges and a a lot more careful client,” Lowe’s CFO Brandon Sink told analysts on the earnings call on Wednesday. “We are forecasting a slight decline in the house-improvement current market.”
“We do assume moderation in dwelling enhancement demand,” House Depot CEO Ted Decker told analysts on the company’s earnings meeting phone very last week. “Persons are also setting up to change shell out extra in the direction of companies. And as we have said, we see some a lot more value sensitivity,” he additional.
The warning comes as Lowe’s (Lower) posted a blended quarter on Wednesday prior to the industry open up.
The retailer documented adjusted earnings for every share of $2.28, topping over analysts expectations for $2.21. Profits missed estimates, coming in at $22.4 billion against anticipations for $22.7 billion, according to facts compiled by Bloomberg.
“The slower start off to the quarter was owing in section to slower gift buying demand in the course of the holiday break period, about just one-third of product or service combine is discretionary in nature,” Bobby Griffin, an analyst at Raymond James, wrote in a be aware to clients next the outcomes.
For 2023, Lowe’s is forecasting sales to be between $88-$90 billion, though similar-retail outlet-revenue are believed to be flat or down 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year. Executives see the pullback in Diy demand from customers as transitory, and other experts in the marketplace see a “historic boom” coming for residence transforming.
Nick Teichtmann (R,) with the help of Lowe’s personnel Jaime Solis, purchases lumber to renovate his residence by incorporating a gazebo on best of a deck and repairing his garage at Lowe’s residence improvement retailer on April 11, 2011 in Burbank, California. (Picture by Kevork Djansezian/Getty Illustrations or photos)
“Disposable own earnings, which I pointed out, is about $1.5 trillion in cost savings earlier mentioned pre-pandemic amounts,” CEO Marvin Ellison explained to analysts on the earnings simply call.
Ellison pointed out the regular equity for residences in the U.S. is about $330,000, and anticipations of growing older housing inventory could place to continued desire for home upgrades.
“Two-thirds of every little thing we market is non discretionary. And there are other tailwinds, millennial household development trend, little one boomers ageing in location and additional widespread sustainable remote work, so all of these matters give us some self-assurance that the backdrop remains supportive,” Ellison additional.
Shares of both equally Residence Depot and Lowe’s are down over 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the very last month.
Lumber deflation
The times of pricier lumber could be more than.
The housing slump has triggered a crisis in lumber, with lumber futures falling 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the earlier calendar year. And homebuilders are using observe.
Pulte Group (PHM) introduced in their hottest earnings get in touch with the company is picking up their pace of design amid elevated lumber stock and more inexpensive pricing.
A be aware from analysts at UBS published very last month claimed some authorities in the homebuilding room see kitchen cabinetry and home windows, fairly than larger framing or roofing initiatives, driving desire for lumber.
And however lumber selling prices have fallen sharply, the firm pointed out for quite a few “main” housing solutions charges “have reverted to ‘reasonable levels,’ but [builders] are not witnessing any authentic rate reductions from sellers.”
As just one expert explained to the company, most solutions are “in no way going [to] pre-Covid rates once again.”
Dani Romero is a reporter for Yahoo Finance. Follow her on Twitter @daniromerotv
From the outside, the David Parr House looks like a typical terraced building in Cambridge, England. Inside, however, the walls of this seemingly unassuming home are adorned with friezes, stained glass, gilded molding and vibrant designs, all crafted by decorative artist David Parr between 1886 and 1927. A representative of the Arts and Crafts movement, which prized handcraftsmanship above mass-produced objects, Parr’s house-turned-heritage siteopened to the public in 2019. Among its visitors was Ella Hawkins, a design historian and author with a unique hobby: creating biscuit art.
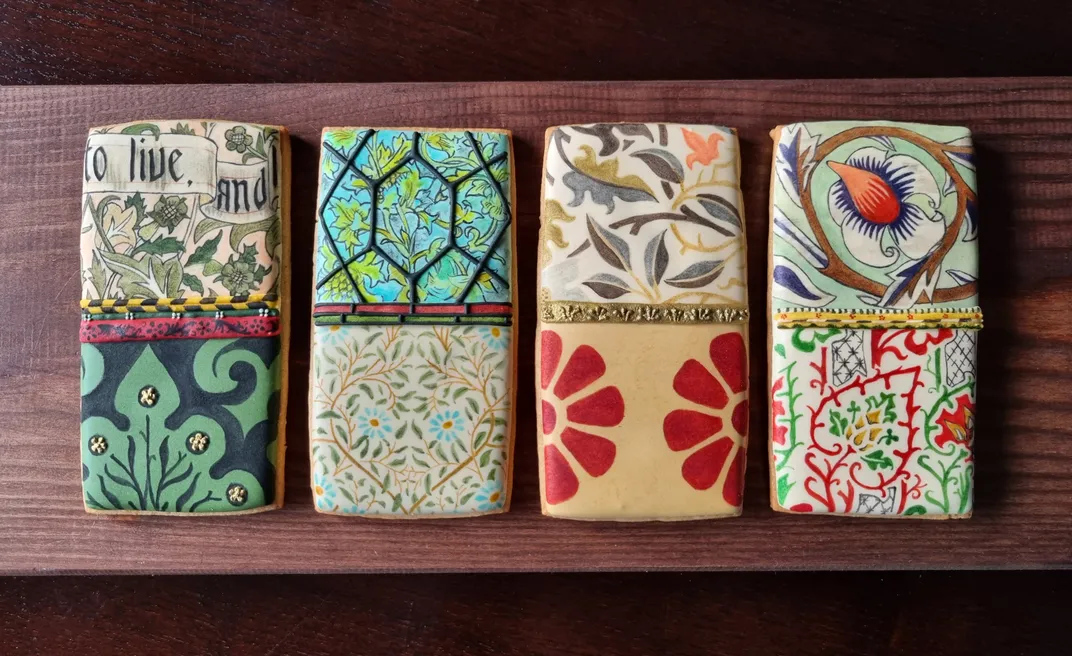
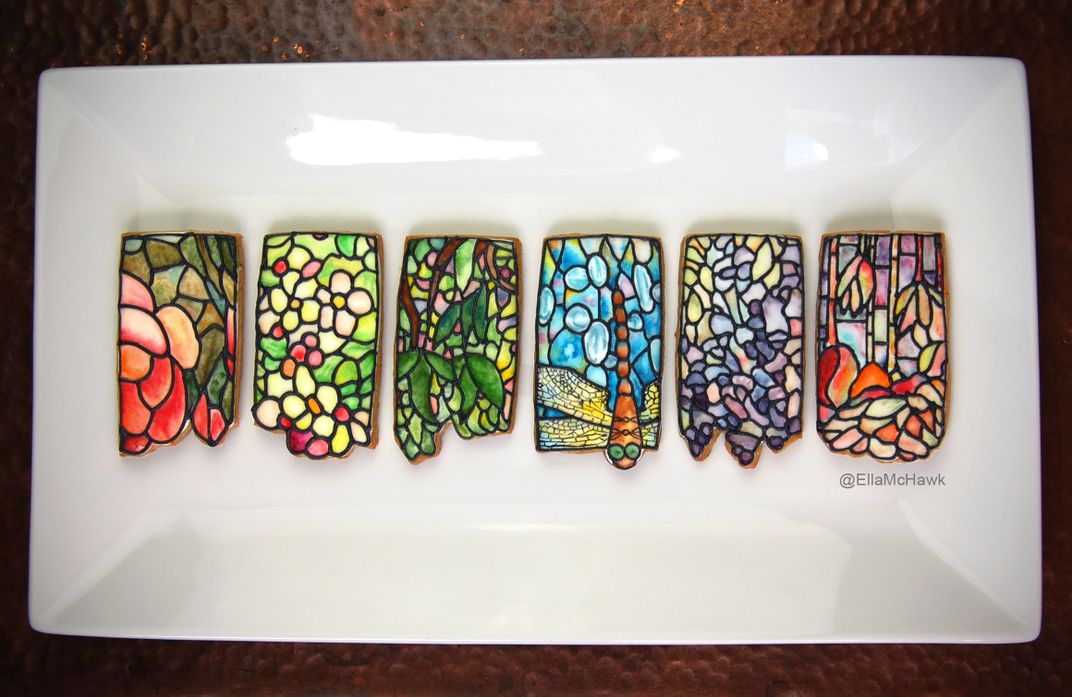
Inspired by her trip to the home, which she describes as “without question, the most beautiful house I’ve ever seen,” Hawkins, 29, decided to decorate a batch of biscuits (better known to Americans as cookies) with Parr’s designs. Flavored with orange, cardamon and vanilla, the rectangular treats served as a canvas for her petite paintings of twisting vines, flowers and Gothic script. She shared snapshots of the finished cookies on social media, where they elicited enthusiasm for both her work and Parr’s.
Cookie art inspired by the David Parr House
Courtesy of Ella Hawkins
“He’s this amazing Arts and Crafts working-class guy who went into stately homes and actually painted the walls with incredible designs,” Hawkins says. Artists like Parr have largely been “lost to history, because they’ve not been documented in as much detail as the people who owned the houses.” But now, because Parr applied the same decorative techniques to his own humble abode, he’s starting to gain recognition.
Reflecting on the response to her post, Hawkins adds, “The comments that came in were like, ‘I had never heard of this. Now I will go.’ Or ‘I had no idea this was in Cambridge.’ It’s a way of signposting something, celebrating it, saying, ‘Aren’t these beautiful? Go see them.’”
A scholar of Early Modern English at the University of Birmingham, Hawkins has always loved baking. “I’ve baked for as long as I can remember,” she says. “Everyone knows someone who bakes, and I’m that person.” But she only took this hobby to the next level during Britain’s Covid-19 lockdown, when she decided to send a set of cookies featuring intricate floral designs to her mother. Heartened by her mother’s reaction to the edible artwork, Hawkins started a new project based on textiles by 19th-century designer William Morris.
“I looked around my office and saw a calendar from the Victoria and Albert Museum of the patterns and thought, ‘Why not?’” she recalls. “It was the first time I realized I could create biscuits inspired by anything I wanted.”
Hawkins posted a photograph of the nature-inspired designs on Twitter on February 23, 2021. “If the academia plan doesn’t work out, I’m taking my material culture interests to the cookie industry,” she captioned the image. After going about her day, she returned to her computer to find the post had garnered thousands of likes. (Currently, it boasts just under 200,000 likes.)
In the two years since her viral tweet, Hawkins has developed a sizable social media following. Fans flock to her accounts for her stunning cookie designs, which emulate book covers, scalloped-edged Tiffany lamps, pottery shards, mosaic tiles, medieval manuscripts, Elizabethan fabrics and more. To make this “biscuit art,” Hawkins covers a gingerbread or sugar cookie-like base with royal icing. She uses food coloring gel and vodka (which acts as a thinning agent) to paint patterns onto the cookies, then adds raised elements by piping on royal icing. Most of her designs are rectangular or square, but she’s experimented with other shapes, too, creating an oval portrait of Jane Austen, a black-and-white fox head and randomly broken cookies patterned after Roman pottery fragments.
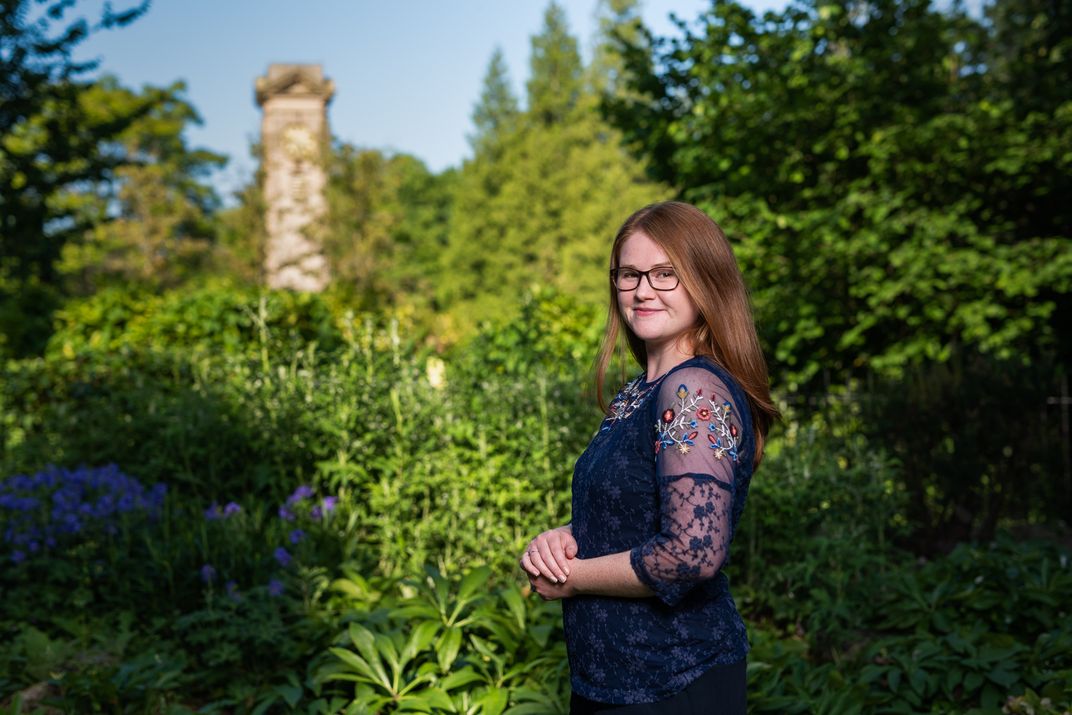
Ella Hawkins
Photo by Rebecca Knowles
For Hawkins, decorating cookies offers a chance to combine her love of design with her love of history and her love of baking. “I’m a very visual person,” she says. “I think it was something to do with how different visual things like colors, shapes and styles come together to create something as a whole that just clicks with my brain. … I realized I can just look at things and turn them into biscuits, and I just sort of carried on experimenting to see what I could do with that.”
Hawkins’ creations are part of a lengthy tradition of baking and decorating cookies. Known by different names around the world, the sweet little treats run the gamut from filled cookies like Hamantaschen to cut-out cookies like gingerbread to commercially produced brands like Oreos. The word “cookie” was first used in 18th-century Scotland, but variations of the dessert date back hundreds of years.
Sharon Hudgins, an author and editor who’s written about cookies for The Oxford Companion to Sugar and Sweets, among other publications, suggests that “picture cookies” (specially shaped, decorated or stamped treats) now popular in Northern Europe trace their roots to the Julfest, a wintertime celebration held by pre-Christian Germanic tribes. Participants who were unable to spare an animal for the traditional Julfest sacrifice instead fashioned dough into animal shapes.
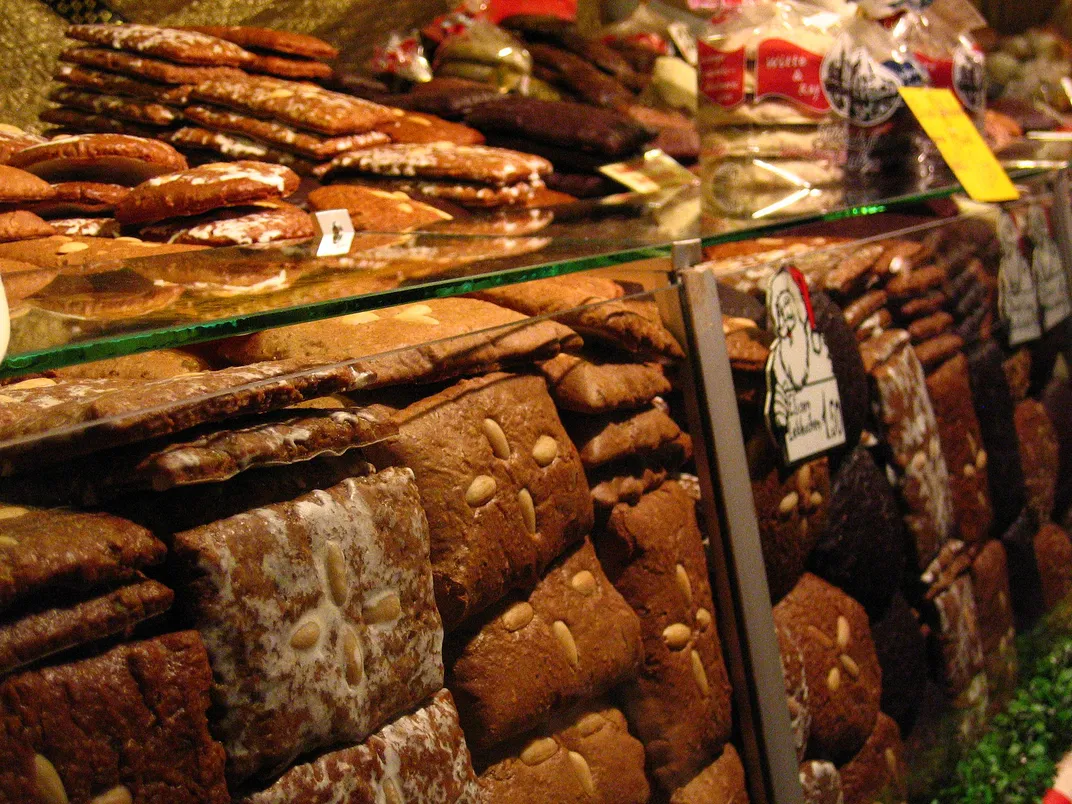
Lebkuchen on sale at the Nuremberg Christmas Market in Germany
“These dough effigieshave been found in archaeological digs,” Hudgins says. “People ate them just as they would the animal sacrifice. [It] was a continuation of the ritual without having the economic loss of a real farm animal.”
Another modern cookie predecessor originated in Persia, where the Sassanids enjoyed khushkananaj, a baked good made by kneading dough with sesame oil and filling it with sugar and almonds, and kulaija, a similar treat made with a mold, as early as the seventh century. At the time, sugar—a central component of many cookies—was a prized commodity introduced to the region by traders from India. Sugar wouldn’t arrive in Europe until the tenth century, when soldiers returning from the Crusades brought it back to their home countries.
Given sugar’s rarity in the Western world at the time, most early European cookies were unsweetened or flavored with alternative ingredients like honey. It was only during the Middle Ages that these treats were “eaten as a form of pleasure and celebration” rather than for the “largely utilitarian purpose” of alleviating hunger, writes Anastasia Edwards in Biscuits and Cookies: A Global History.
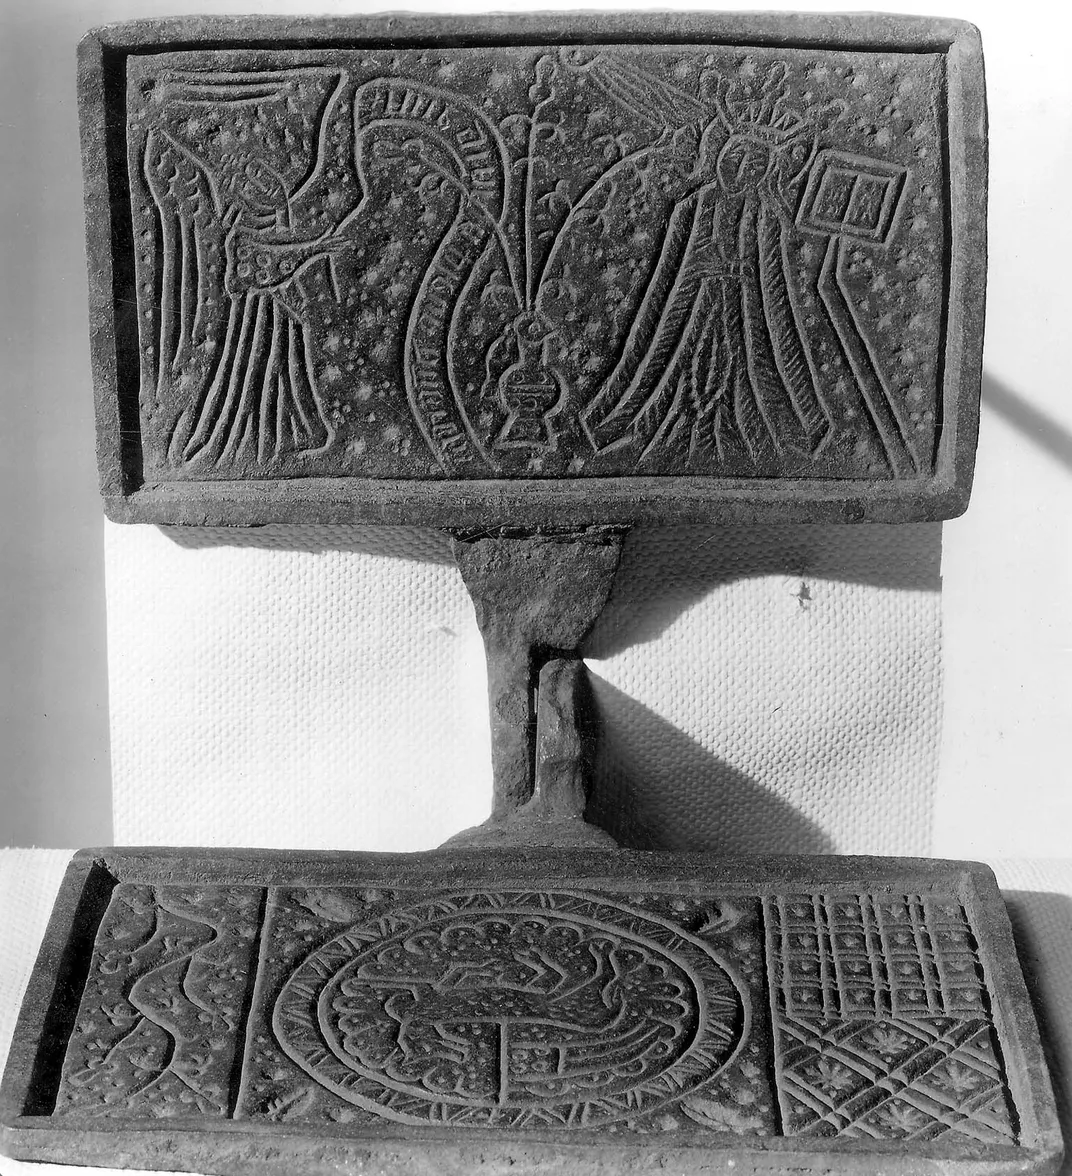
A 16th-century wafer iron depicting the Annunication
Wafers, for instance, evolved from unleavened matzo bread eaten by Jews during Passover. Originally unsweetened, these thin, crisp sheets were stamped with religious imagery and eaten during Christian communion. Medieval clergy used cast-iron tongs imprinted with patterns to hold the dough in place and quickly bake it over a fire. In 1270, a wafer-making guild was established in Paris to help meet the clerical need for wafers; guild members soon branched out, creating secular forms of the cookie that became popular accompaniments to hippocras, a sweet wine served at the end of meals.
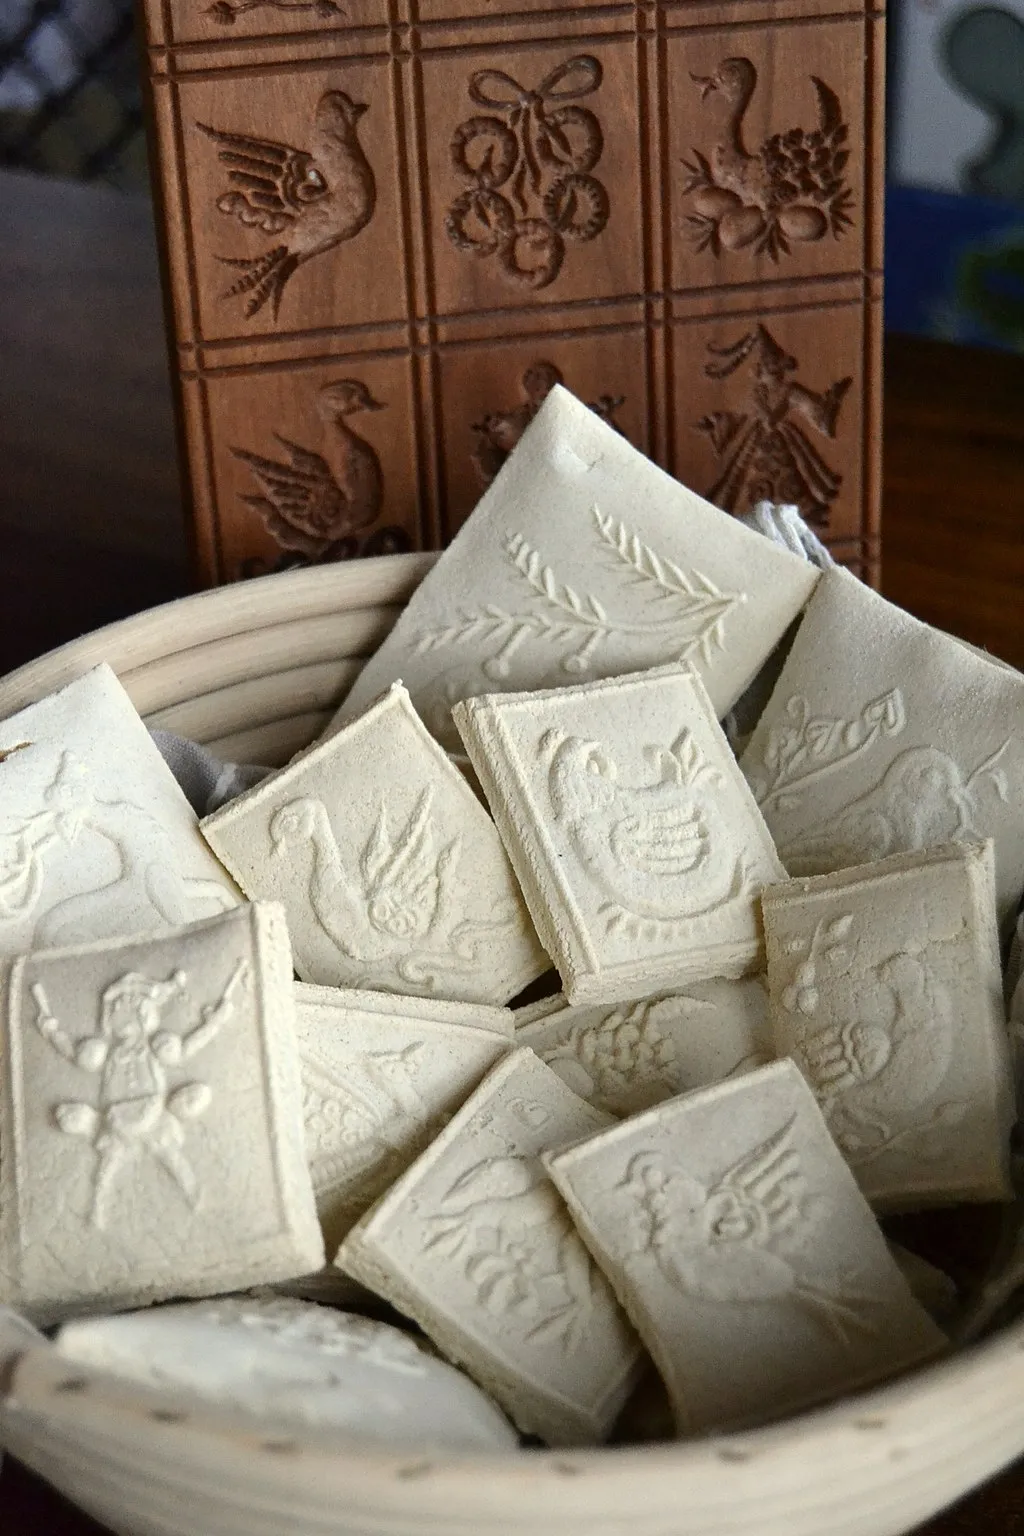
It was in Germany, though, that sweet cookies truly came into their own. During the 16th century, spices flowed from Asia to Nuremberg, a crossroad of key European trade routes. Cooks in the German city combined sugar, cinnamon, nutmeg and other spices with locally produced honey to create lebkuchen, spiced honey cakes comparable to gingerbread. Around this same time, wooden, metal and ceramic cookie molds came into wider use, enabling bakers to imprint elaborate designs on anise-flavored springerle and other picture cookies. Initially decorated with religious images, these molds became increasingly secular in the 17th century, with artisans hand-carving depictions of knights, coats of arms, and activities like ice skating and hunting, among other scenes.
“The embossed designs made by molds”—including wafer irons—“were the first forms of actual decorating beyond just shaping a cookie into a form,” says Hudgins.
Springerle made with Christmas-themed cookie molds
As demand for sugar spiked in the 17th century and onward, European nations established sugar plantations in Brazil and the Caribbean, enslaving millions in their quest to produce so-called white gold. By the early 19th century, sugar was widely available and relatively cheap in both Europe and North America.
The growing middle class could now afford to use sugar as a sweetener instead of honey. It was a handy, versatile ingredient and could be used to make glazes that helped keep cakes moist longer. These glazes soon morphed into frosting, a concoction that became especially popular after it was used to decorate Queen Victoria’s 300-pound wedding cake in 1840. In addition to icing, cooks decorated their cakes and cookies with dried or candied fruits, nuts, and colored sugar.
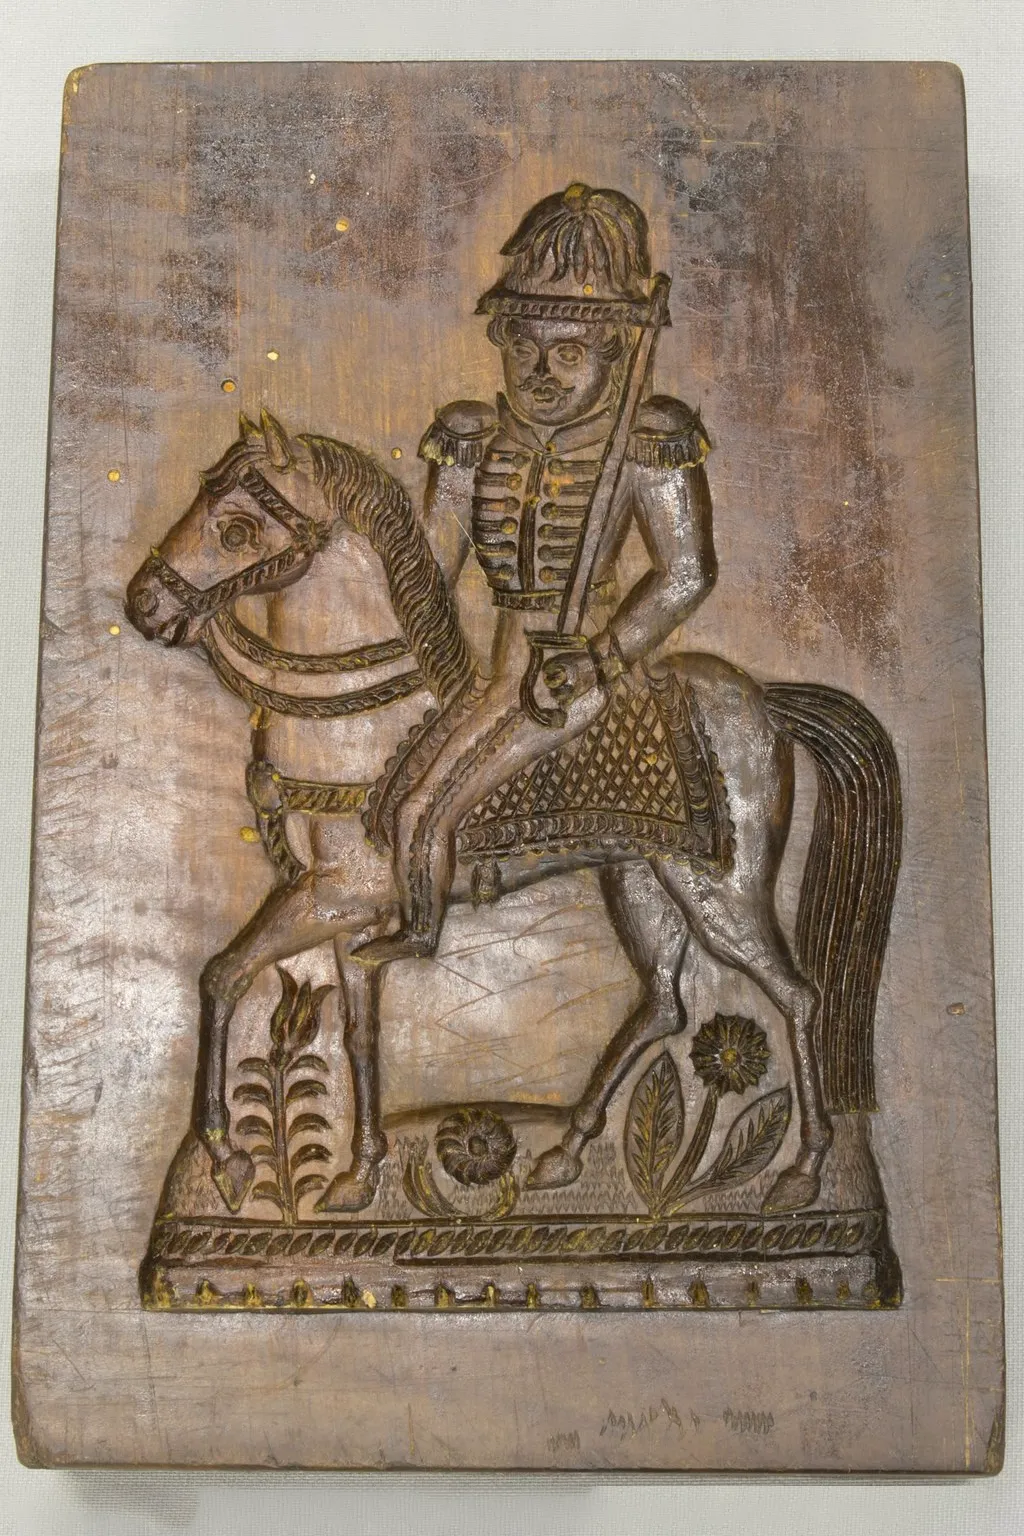
Mass-produced metal cookie cutters similarly gained traction in the mid-19th century. Shaped like people, flowers, animals, hearts or holiday symbols, they presented a playful addition to the dessert menu and were less expensive than handcrafted wooden molds.
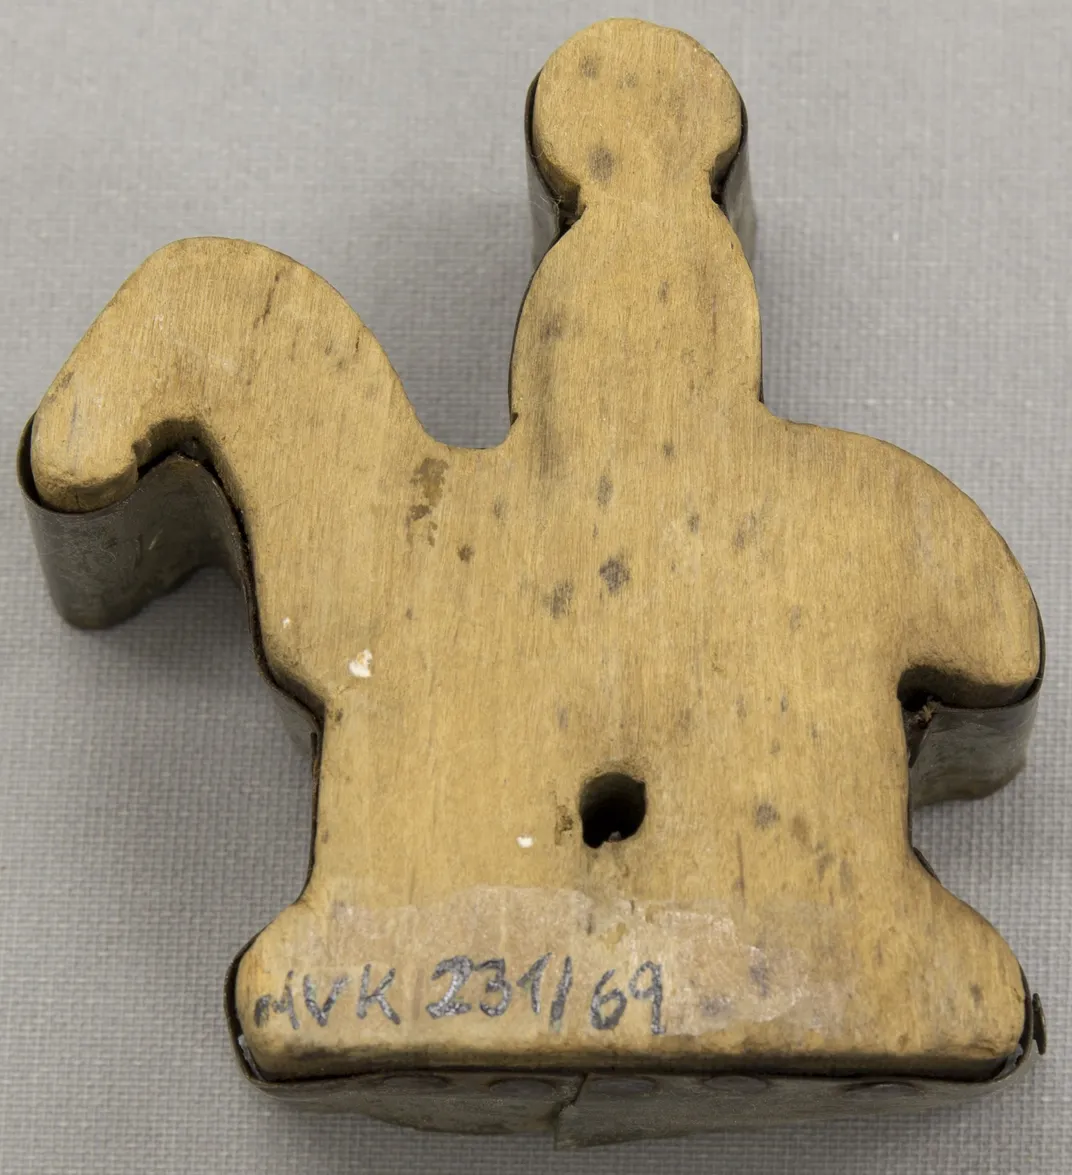
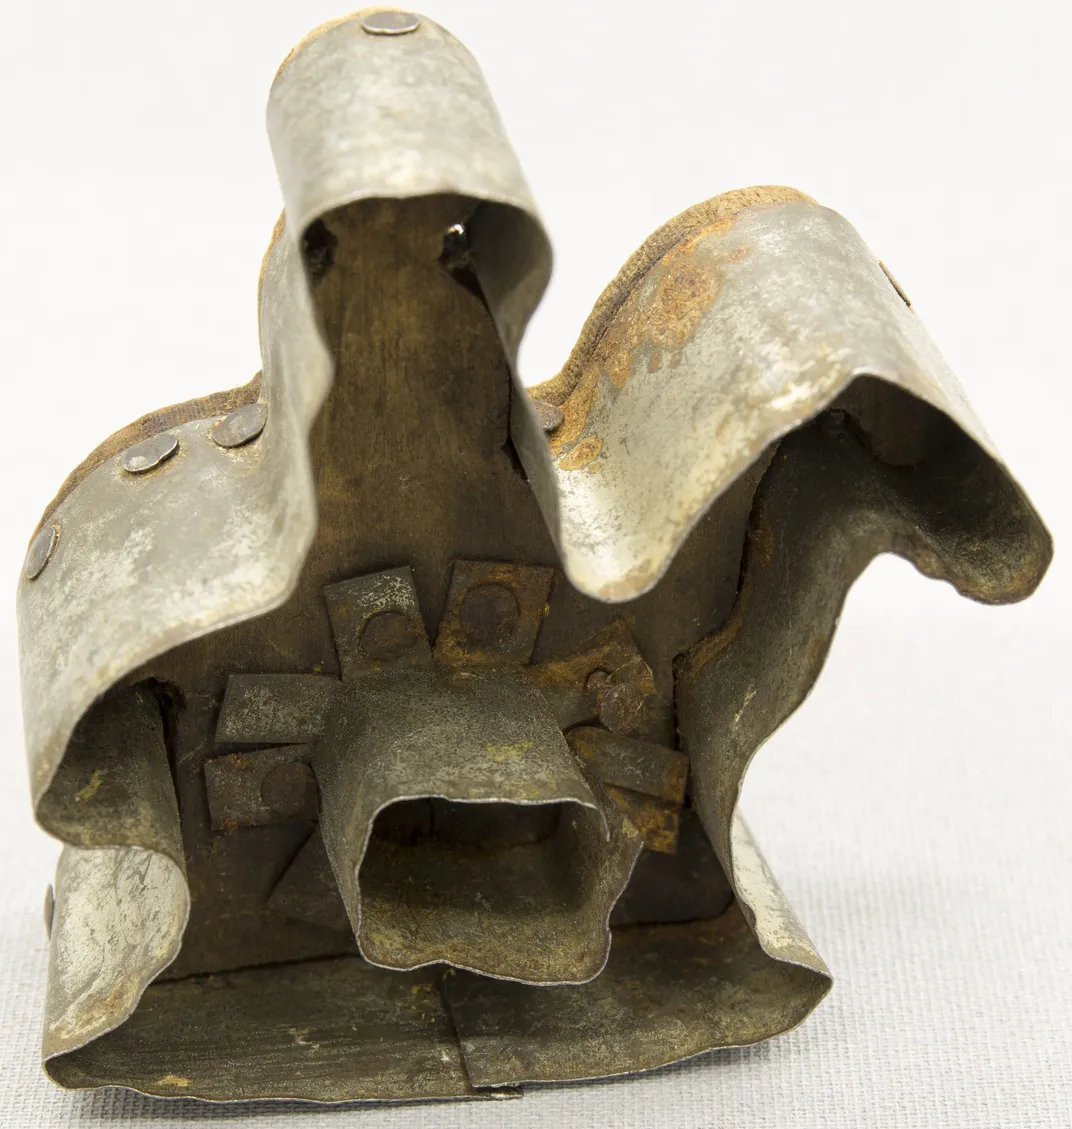
The front of a vintage cookie cutter depicting a person on horseback
“With cookie cutters, people could now make a large amount of something, such as heart-shaped cookies, and [they] wouldn’t have to do a lot of decorating because the shape of the cookie is the decoration itself,” says Hudgins.
As sugar became a pantry staple and ovens a fixture in kitchens, home cooks gained the ability to economically turn out a variety of sweets and desserts, including cookies. At the same time, advances in technology gave rise to mass-produced treats, with companies like Huntley & Palmers and Nabisco (which started making animal crackers in 1902) presenting their products as symbols of home and childhood innocence. Writing in Biscuits and Cookies, Edwards notes that the cookie was meant to be seen as “a quiet antithesis to the industrialization of modern life.”
By the 1940s, baking and decorating cut-out cookies had become a popular holiday tradition in the United States. Entrepreneurs like Nettie Williams McBirney, better known as Aunt Chick, crafted Christmas-themed plastic cookie cutters that now sell as vintage collectibles. The American public’s penchant for baking and decorating was further encouraged by the 1963 publication of Betty Crocker’sCooky Book, which featured more than 450 recipes for treats ranging from satin-glazed date drops to chocolate refrigerator cookies.
“In the 1970s and ’80s, making decorated cookies started coming back into fashion,” says Hudgins. “More women had gone into the workforce in the ’60s and ’70s, so in some families there was less cookie baking at Christmas time. Yet there was also an interest by the hippie generation to return to their roots with activities such as home baking.”
More recently, the internet has transformed the world of cookies, offering bakers a place to connect with each other and share recipes and inspiration alike. New technology has also helped cooks put a modern twist on their baked goods.
Small projectors allow artists like Hawkins to cast their designs onto edible canvases. Airbrushing yields dramatic effects, as do brush sets, stencils, piping bags and food coloring markers. And 3D printers allow decorators to create custom cookie cutters and molds.
“Cookie decorating never gets stale,” says Karen Summers, co-founder of CookieCon, the world’s largest gathering of cookie decorators. “There’s always some new technique, some new tool, some new thing [bakers are] implementing. Every time that I think I’ve seen it all, someone will pull out something new, and I think, ‘Whoa! How’d they do that?’”
Hawkins suggests that decorated cookies’ magic stems in part from their ephemerality.
“I think if they weren’t biscuits, if they were paintings or collages, they wouldn’t have the same reaction,” she says. “Part of what they are is temporary. There’s something really weird about it that’s provocative. I’m happy I have photos of them. They’re preserved in that sense. If I had just a drawer full of them, I don’t know what I’d do with them.”
Cookie art inspired by Tiffany lamp designs
Courtesy of Ella Hawkins
Summers agrees.
“There is some level where people want it to last forever, but I think a lot of people just find it a fun challenge to create this masterpiece that is very, very temporary,” she says. “A common theme is to just eat the cookie.”
South Florida has extended been a magnet for New York real estate gamers. And when most New Yorkers make a move on the regional market place, they do it in design: With loads of ballyhoo in hopes that even the smallest promotions and tasks turn into the talk of the town.
The Damaghis are not most New Yorkers.
The Great Neck family members has amassed developable sites across South Florida. Even though some of its investments have surpassed people of New York’s real estate royalty, the family’s bargains have remained clandestine.
“They have got some genuinely phenomenal property,” a resource reported. “But some folks just want to preserve it peaceful.”
The Damaghis — designed up of husband-and-wife Nasser and Shahnaz Damaghi and their kids Nader, Kambiz and Babak Damaghi — aren’t complete-time authentic estate players. Nasser and his sons founded paper products and individual care items maker Initially Excellent Enterprises in 1988, which has grown to employ much more than 4,000 employees at minimum 7 services across the U.S. and Canada.
True estate is extra of a aspect gig. The Damaghis have paid out $182.2 million across 15 bargains for developable land according to a information investigation by The Actual Deal.
TRD discovered the household in November as the buyers who dropped $50.8 million on 2.7 acres south of Brightline’s MiamiCentral downtown passenger prepare station as a result of sources acquainted with the deal. State documents for the limited legal responsibility company that produced the obtain really do not explicitly tie the Damaghis to the offer. Neither the family’s identify nor addresses for 1st Quality’s offices or a person of the family’s Excellent Neck properties are shown in the filings. But the documents do record 1 human being of interest: Moshe Oppenheim.
Turns out, Oppenheim is the clue to the Damaghis’ other holdings.
Muzzled
9 entities registered to Oppenheim — the family’s longtime attorney — bought the bulk of the homes from 2019 to 2022.
The Damaghis are powering the bargains, according to numerous sources, nevertheless no a person wanted to converse on the report or even at all, citing the family’s demanding instructions to continue to keep them off the radar. ”Real tough” to communicate about the loved ones, just one source stated they are “very personal,” other individuals held repeating.
Though unwilling, some did budge, presented they continue to be nameless. They explained the family’s true estate perform as a “long-term generational investment.” A different supply revealed that the purchases ended up all hard cash — in fact, no mortgages are recorded on the serious estate. And other individuals stated the Damaghis have searched for additional South Florida investments as not too long ago as last calendar year.
In Fort Lauderdale’s booming Flagler Village community, the spouse and children owns nearly 5 acres on 3 websites: land on the northeast corner of Northwest Flagler Push and Next Avenue, on the southeast corner of Next Street and Northwest Initially Avenue, and straight away west of the federal courthouse at 299 East Broward Boulevard.
South of there, they have amassed the block fronting the New River on the northeast corner of South Andrews Avenue and Southeast Fifth Avenue. They also own nearby parking heaps and tiny industrial buildings, which are likely candidates for redevelopment.
But the family’s to start with investment decision was in Miami in 2013 when they bought a complete metropolis block of land in Edgewater, involving Northeast 32nd and 33rd streets, together the east aspect of Biscayne Boulevard. This is the only non-concealed offer, as the getting entity lists Kambiz Damaghi in state data.
Their other Miami site is the downtown land south of the Brightline station, which has approval for a pair of combined-use household towers with 2,007 models and spanning 4 million square toes.
The family has selected several parcels for growth and are “assessing the opportunities” but can’t share far more specifics until eventually the assignments are released, Oppenheim wrote in an emailed reaction to a record of concerns.
For the Damaghis, stealth method is nothing new, as they have been opaque about their private life. Very first Quality’s website and LinkedIn say loads about the company’s heritage but make no point out of its house owners. In its place, tying the loved ones to the organization is additional effortlessly carried out by reading
posts published in 2019 and past year by Pennsylvania’s The Specific Lock Haven about Kambiz Damaghi’s speeches to the neighborhood chamber of commerce.
Temple Israel of Wonderful Neck’s annals also clearly show the Damaghis have been embedded in the region’s Jewish local community. In 2012, the temple’s The Voice publication declared a bar mitzvah for Nader and Mitra Damaghi’s son. Kambiz Damaghi has also been shown on the board of trustees for the Sephardic Heritage Alliance for 2017-18. As a result of Oppenheim, the family members agreed to present a minimal about its history for this story, and stated they are accomplishing it expressly for the sake of precision. In 1978, Nasser and Shahnaz remaining Iran for the duration of the revolution with their sons to escape persecution. Even though information show the Damaghi spouse and children includes a lot of cousins, uncles and other kinfolk, it’s Nader, 61, Kambiz, 59, and Babak, 53, who guide 1st High-quality as co-CEOs — and who are buying up South Florida authentic estate
Just one issue the loved ones hasn’t concealed so nicely is its penchant for palatial homes in Fantastic Neck’s affluent Kings Place.
In 2004, Babak and his spouse, Farhnaz, paid $12.8 million for the late comedian Alan King’s dwelling at 40 Shore Push, in accordance to records. Fronting Manhasset Bay, the home was built in 1926 in a combination of Tudor and gothic styles, and by 2012, the couple experienced replaced it with a Colonial-model châteauan measuring extra than 15,000 square toes. They marketed it in 2017 for $22 million, documents show.
Nader and Mitra have been nearby neighbors. They paid $7.1 million in 2002 for the 10 Shore Push manse, which four a long time afterwards they changed, also with a Colonial-type castle that spans a lot more than 10,000 sq. feet on 2 bayfront acres. The pair bought it in 2017 for $20 million, record demonstrate.
As for Kambiz and Haleh’s abode at 26 Dock Lane, they sold it in 2017 for $14 million,
but not just before litigation gave a glimpse of their way of living in the house totaling a lot more than 14,000 square toes.
The couple experienced a 14-person employees of housekeepers, groundskeepers, cooks, personalized assistants and security, according to a 2013 lawsuit filed towards them by previous estate supervisor Christopher Marconi.
Marconi claimed he was illegally fired four months in on the occupation partly in excess of increasing problem with Haleh’s personal assistant’s allegedly racist remarks to household employees. In a non-public meeting, Kambiz advised Marconi to “back off” his thrust to get the assistant fired, insinuating that Kambiz and the assistant had been “sexually intimate” and she had texts that “‘could be perceived’ as inappropriate by Haleh,” in accordance to the lawsuit. Marconi, who could not be achieved for remark, missing, however his implication of an extramarital affair struck a chord with Kambiz.
“That is pretty, extremely erroneous and inappropriate to even suggest,” Kambiz reported for the duration of a deposition, contacting the allegation “shameful,” “despicable” and saying it places his “honor in question”.
New M.O.?
When Miki Naftali and a husband or wife dropped $40.5 million for a Miami Worldcenter development web page final March, information releases flooded journalists’ inboxes with announcements for a pair of supertall residential towers. Namdar Team, also based mostly in New York, also did not shy absent from announcements about its prepare for a 41-tale and a 43-story condominium towers, also in downtown, last August.
But when TRD attained out to the Damaghis in November about their purchase of the improvement web site south of Brightline’s station, a member of the loved ones vehemently denied they ended up the customers and did not want to deliver his first name.
No matter whether the Damaghis’ growing existence in South Florida, in which producing excitement over genuine estate promotions is just as much part of the activity as the precise expense, will push them to abandon their mysterious means continues to be to be observed.
They have, even so, proven signals that they could be rethinking their lengthy-held modus operandi.
In a stick to up get in touch with with Oppenheim, he explained the Damaghis’ arrangement to respond to TRD’s queries in an e mail as “a 1st.”
Part 1 focused on “Home Stocks,” meaning those that I would be happy to buy now and hold indefinitely, like a home. They were Brookfield Corporation (BN), Brookfield Asset Management (BAM), Dream Unlimited Corp. (DRM)(OTCPK:DRUNF), Topicus (OTCPK:TOITF), and SSC Security Services Corp. (SECU)(OTCQX:SECUF). These are stocks commonly referred to as “compounders,” meaning they grow reliably, profitably, and over long periods of time. If the stock market were to close for ten years, Home Stocks I would not worry about.
Like those stocks, “Investment Property Stocks” are growing profitably, but have some sort of drawback and that make them less attractive over the long term. This drawback is made up for by a large, temporary dislocation between price and value, providing an attractive risk/reward that could result in a large return over a relatively short period, anywhere from one to five years. When the stock’s price gets close to its value, I’ll consider selling for a nice gain. Thus, they are Investment Property Stocks, not Home Stocks.
Currently, I find Nuvei Corp. (NVEI), a Canadian mid-sized e-commerce payments company, Alibaba (BABA), China’s pre-eminent internet stock, and Reitmans (RET)(RET.A)(OTCPK:RTMAF), a Canadian women’s fashion retailer, to be attractive Investment Property Stocks. All have something going against them which dissuades me from holding over the long term, but enough going for them and a large enough margin of safety that I believe they can make very nice gains in the next one to five years.
Investment Property Stocks
Nuvei Corp.
Nuvei Corp. is a mid-size Canadian fintech (~$4-5B market-cap) specializing in merchant services; it essentially has a top-of-the-line modular “everything platform” for merchants. I go into greater detail here but a shorter version follows.
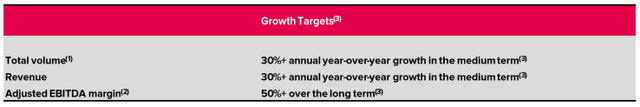
Nuvei specializes in payment solutions for online regulated gaming (gambling and sports betting), a fast-growing segment as Canadian provinces and US states legalize the industry, and e-commerce generally, which represents almost 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their revenue. Nuvei is quickly diversifying however, most recently they acquired Paya Payments, a B2B payments provider, the details of which I cover here. In addition, the CEO owns 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of shares, and upon its IPO employees each received a stake in the company worth $100,000, creating significant insider-ownership. Management projects sales to grow at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually over the next few years with adjusted EBITDA margins increasing up to 40-50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, a call that was recently reiterated in a press release. Nuvei has competitive technology, huge growth in sales and margins, and owner-operators; it meets my normal qualifications of a quality stock.
Nuvei’s growth outlook (Nuvei’s Q3 Earnings Report)
Despite these positives, Nuvei trades at 11x trailing free cash flow. The reasons for this are not perfectly clear, but here are a few possibilities.
Payments companies generally are down huge due to recession fears caused by interest rate hikes and inflation. Companies operating in cyclical sectors like e-commerce and online gaming are even more affected. Nuvei was also exposed to crypto payments, which crashed hard in 2021, bringing Nuvei’s share price with it. The exposure is not huge, but the mere association was enough to hurt the stock.
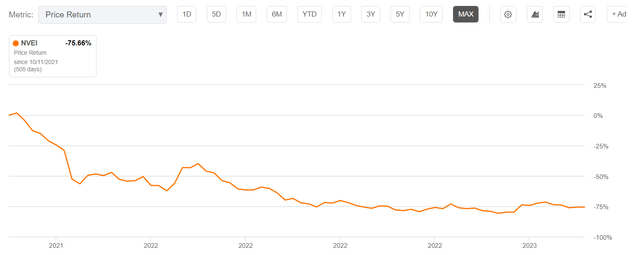
Additionally, Nuvei was one of the prime beneficiaries on the pandemic bubble, a lot of its growth was brought forward, and its share price skyrocketed beyond what anybody could consider reasonable, and thus became the target of a short seller’s report. Many of the allegations were rebutted, but the share price didn’t recover. More concerning is the CEO’s relative youth, reflected in how much he pays himself (a lot), and that Nuvei pays presumably large amounts to sponsor an F1 team. I fail to see how such a sponsorship benefits shareholders, but doesn’t break my thesis on the company, though it is inconvenient.
Nuvei’s return since its IPS – Not pretty! (Seeking Alpha)
Lastly, bringing forward growth also had the effect of creating impossible comps year over year, indeed Nuvei’s sales this year are up only single digits over last year. Considering they doubled sales in 2021, simple staying flat is quite the feat, and puts management’s forecasted 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} medium-term sales growth seem far less ambitious than it appears. It also probably didn’t help that they converted their net cash position to a net debt position to acquire a company; it isn’t the market for that. Overall, I view most of these factors as temporary impairments to the stock, and therefore signify a potential opportunity.
Most importantly for me, and why this stock is not a long-term hold, is competition. In the payment services world, a company is only as good as its technology developers and sales team; there is no moat, or even picket fence, keeping others out of the business castle. Nuvei’s peers are Stripe (STRIP), Block (SQ), Europe-based Adyen (OTCPK:ADYEY) and to a lesser extent online payments companies like PayPal (PYPL). All are worth 10s of billions and with significant resources; competition is clearly formidable.
That said, Nuvei is currently much smaller than they are so need to take less market share to see gains, has competitive technology, is building a direct sales team with a former Mastercard exec at its head, has a niche and early movers advantage in online gaming payments, and is priced for the apocalypse, while its competitors are priced for a recession. The lack of durable competitive advantage is made up for by these redeeming factors, but especially by valuation.
A cursory glance at the stock suggests it is expensive because it has a high PE ratio, but if we skip to the cash flow statement, we see that Nuvei gushes free cash flow. Gross margin is above 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, operating cash flow margin is regularly above 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and free cash flow around 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Due to operating leverage, where little capital is required to provide more services, margins even have room for expansion. These are levels are profitability beyond even Microsoft.
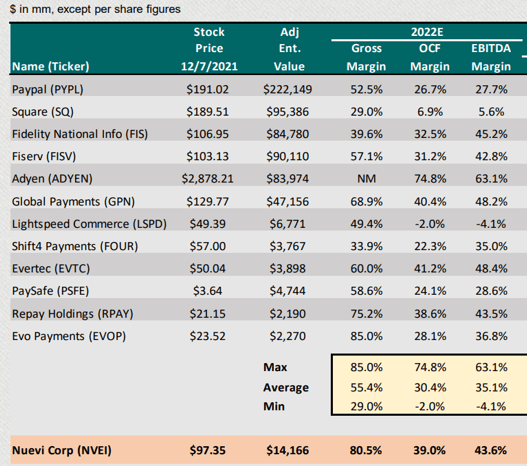
To be honest, my “too-good-to-be-true” sense is tingling, and I’m not the only one. In the short seller’s report, they made a list of comparable fintechs and their profitability. Most of the report was, from my perspective, ad hominem hearsay, but the following breakdown was useful:
Note to Canadian investors, Lightspeed gets more press than Nuvei, but isn’t even profitable. (Short Seller’s Report)
A close look will reveal that Nuvei is about as profitable as a fintech can be and far above average. This could be concerning, but comfortingly for me, there are other companies that are similarly profitable so Nuvei is not a clear outlier. Adyen for example, its closest peer, has operating cash flow and EBITDA margins much higher. This chart is useful for industry comparisons as well, which I’ll leave to the reader to peruse. In my opinion, the probability that Nuvei is cooking the books is low, though I am wary.
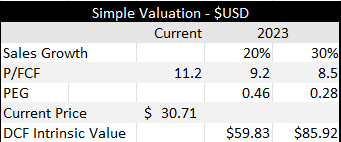
Nuvei is tremendously profitable, and, as the table below shows, the market is strongly discounting this fact, assigning it an 8-9x forward P/FCF multiple, half the average of information technology stocks according to Seeking Alpha. Nuvei should perhaps demand even more than average as it is a quickly growing fintech stock with huge margins and operating leverage.
Two different growth scenarios and their impact on the valuation of Nuvei. Both suggest Nuvei is substantially undervalued (Author’s Calculations)
As we can see, the stock is at least 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} discounted from conservative fair value, assuming management’s medium-term outlook of 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual sales growth is high by 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a year. If it’s not, and Nuvei does manage to grow sales at 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually while maintaining or growing current margins, the stock is potentially 66{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} undervalued. Furthermore, a PEG ratio of 1 is generally considered a fair price to pay, and Nuvei trades at half or a quarter of that, lending further support to our DCF values. Should the market get bullish and payment stocks demand higher multiples (the current model assumes 20), upside is even greater.
Nuvei is certainly not a Home Stock, in that it doesn’t have a moat and there are some smaller concerns, but the price and business model are far too discounted; a disaster is being priced in. If business doesn’t flop and/or the Great Depression doesn’t happen, Nuvei is going upwards. The main catalyst is lapping 2021’s financials making for easier comps, and new customer wins.
I’m a buyer at $30-$35 USD and would consider selling at $90-$120, though I wouldn’t make this an out-sized position as the company hasn’t been public long so it’s hard to get a sense of its track record.
Alibaba (BABA)
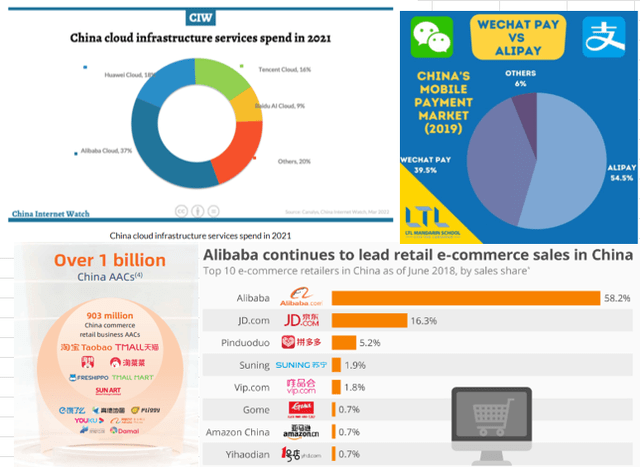
Alibaba is the pre-eminent Chinese internet stock. 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese e-commerce goes through one of its platforms, 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the fast growing cloud market is captured by Alibaba, almost every single Chinese person (and 300M outside China) are annual active consumers on its platforms, and, through its one third stake in Ant Financial, BABA owns Alipay, the payment platform through which 56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Chinese payments flow (with more volume than Visa, Mastercard and Amex combined) and Yu’e Bao, the second largest money-market fund in the world with over $170B under management. Alibaba has an ocean for a moat.
In addition, they have fast growing segments, like international e-commerce and domestic groceries, both of which alone could be bringing in more annual sales by 2033 than the entirety of Alibaba generated in the last twelve months. Alibaba is more than just the Microsoft (MSFT) or Apple (AAPL) or Amazon (AMZN) of China, it’s all of them, combined.
Visuals to aid readers in understanding Alibaba’s moat (China Internet Watch, Mandarin School, Alibaba 2022 Annual report)
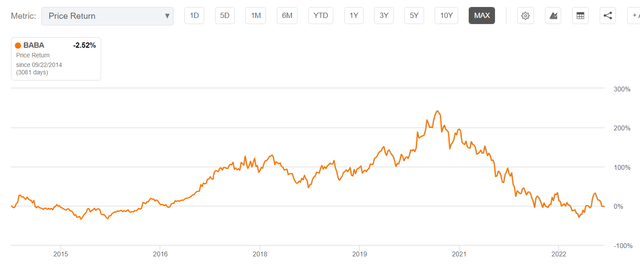
Since it IPO’d in 2014 at $92.70 a share, Alibaba has 15x the revenue, 5x the EBITDA, 4.5x the free cash flow, and 3.5x the operating income. Somehow, we can buy it at IPO prices; Alibaba is tremendously undervalued. Tom Hayes describes it as a submerged balloon, waiting to rocket to the surface.
Alibaba’s return since its IPO (Seeking Alpha)
The dislocation of price to value is caused by the Chinese government locking down the economy in an attempt to prevent Covid from spreading and cracking down on its tech companies, which it deemed were becoming too powerful (perhaps justifiably). Things have changed recently however, the CCP bought shares in BABA, has re-opened the economy, is stimulating the consumer, and generally seems to be working with and through its tech companies as China’s leaders’ personal and national self-preservation instinct has kicked in. Headwinds have shifted to tailwinds.
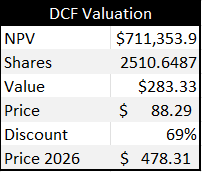
I’m putting up my sails to catch that wind, as Alibaba, were it to return to normalized multiples on normalized earnings, is worth at least $500-$600 a share three years from now. This plan appears to be on track. In their most recent earnings, Alibaba bought back significant amounts of stock well below intrinsic value, somehow grew revenue 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} despite the most recent quarter being under lockdown, and, significantly, increased free cash flow 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year over year despite sales staying flat. This means that Alibaba found a way to become much more profitable in a very short amount of time. Once sales growth starts to kick back in, combined with increased profitability, BABA shareholders could see results well beyond normalized earnings, and therefore have much more upside.
Valuation of Alibaba assuming its free cash flow margins and multiples paid for that FCF returns to historic averages (Author’s Calculation)
Moreover, Chinese savings are twice the historic average, so if they can spend at normal levels, upside could be even higher, considering the market currently expects a conservative 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual growth of sales over the next few years for BABA. Shareholders of Alibaba have a significant margin of safety at current prices, and massive upside should anything go right.
I’m an active buyer and will continue to accumulate under $100 a share for as long as the market lets me. I’ll consider selling when it reaches that $500-$600 mark but will reassess when we get there. If international expansion is going well, BABA might turn into a long-term hold.
I did a longer article on Alibaba here.
Reitmans (OTCPK:RTMAF)(RET.A:CA)(RET:CA)
Reitmans is a century-old Canadian women’s fashion retailer, including the brand’s Reitmans, Pennington’s, and RW & Co. The Reitmans family still owns most voting shares (RET:CA), and senior management positions. Donville-Kent, a Canadian small-cap investing firm whose newsletter, the ROE Reporter, alerted me to the opportunity here. Their treatment is in-depth and can be read here.
Reitmans historically was a reliable dividend payer with sluggish growth in the Canadian retail space, like Canadian Tire in this respect. After years of deterioration however, Reitmans almost didn’t survive the pandemic and was forced to enter bankruptcy to survive. In so doing they laid off thousands of employees, renegotiated better lease terms, paid off creditors at 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the dollar, shut down unprofitable locations and brands, and re-listed from the TSX to the TSXV.
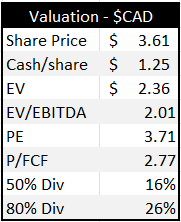
Re-emerging from bankruptcy, the company looks remarkably different, financially. Returns on equity are over 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, debt is paid off and they have $1.25 of cash/share (a quarter of the company’s market cap is cash). In the last nine months alone, Reitmans has generated $67M in free cash flow on $588M of sales, for a margin of 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, an excellent number for a retailer. Using just the last nine months numbers, they currently trade at around 2x EV/EBITDA, 4x net income and 3x free cash flow, well below historical averages for their own company specifically and retail generally.
Remarkably undervalued. Priced like it’s going bankrupt again (Author’s Calculations)
If Reitmans were to pay out 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of that free cash flow as a dividend (which they have historically), the stock would yield 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If that isn’t enough, the headquarters and distribution centre owned by Reitmans are worth more than the market cap of the company. The value is clear.
Like BABA, there is a large overhang on the stock causing its price to be severely depressed, but the facts are pointing to this overhang being temporary.
The new Reitmans could continue to be the dog it was in the 2010s, but if its last fiscal year is anything to go by, this doesn’t appear to be the case. Indeed, the current overhang from bankruptcy and Reitmans reputation is providing a margin of safety and likely an opportunity. Shareholders will need catalysts to continue gains though.
Reitmans has several potential catalysts. First, the company could buy back a significant amount of stock with just the cash on the balance sheet. Second, it could reinstate the dividend, which I’m sure the Reitman family are eager to do as it’s been a few years since they got the cheque they’ve been receiving for almost a century. Third, they could list back onto the TSX proper, where fund managers can buy their stock. Fourth, the family could buy the land under their headquarters and fulfilment centre and lease it back to the company, unlocking a pile of cash. Fifth, when earnings are reported in April, we get our first full year of financials for the new Reitmans, and potential announcements regarding any of the first four points made here. Reitmans is already up significantly, but there are more catalysts that could cause it to go even higher.
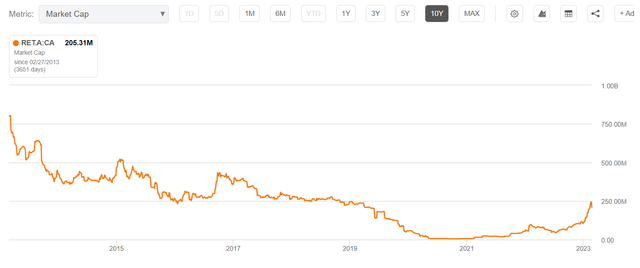
Long-term holder are likely non-existent (Seeking Alpha)
Over the last 10 years, Reitmans was a value trap, with slowing sales and decreasing margins and thus traded at very low multiples, around 7-8x free cash flow (which is still twice as expensive as today). However, sales are not slowing anymore, its brands are proving resilient, and margins have expanded significantly coming out of bankruptcy. 8-10x EV/EBITDA and/or 8-10x FCF are perhaps more appropriate conservative expectations of multiples going forward, compared to the current 2.3x EV/EBITDA and 3x FCF. This suggests that Reitmans is likely a double from ~$3.50-$4.00 on valuation alone, with more potential should the catalysts mentioned earlier happen. Donville-Kent expects the price to reach around $8 if the company doesn’t sell the land to the family, and $12 if they do.
If the outlook remains rosy, the company proves quality and the dividend is reinstated, I might find myself a long-term holder. To put it in perspective, with an 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} payout ratio, I’ll be receiving upwards of 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield on my current cost-basis; a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annual cash return is hard to say no to. This should result in price upside as well, as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yield from a quality company will not last long; I could see a more justifiable yield of around 6-8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, implying the price could increase another two or three times, like Donville-Kent suggested.
In any case, I see a double minimum with potential for RET.A to triple or quadruple, while I eventually collect a significant dividend yield that I could choose to hold for the longer term. Reitmans is an ideal Investment Property Stock.
Conclusion
Reitmans, Alibaba, and Nuvei are all promising stocks into the medium-term. Though they have long-term drawbacks, namely low growth at Reitmans, ageing demographics and an autocratic home government for Alibaba, and no durable competitive advantage for Nuvei, the market is pricing their stocks at unreasonably low levels. To re-value their stocks, Reitmans could reinstate the dividend and go back up to the TSX, Alibaba could benefit hugely from government stimulus and domestic cloud growth, and Nuvei will be lapping tough 2021 financials, leading to some pleasing year of year numbers. All are quality businesses down for temporary reasons, and have catalysts to revive investor interest.
If worst-case scenarios don’t happen, all these stocks could be doubles in a relatively short period (a couple years or less), and perhaps more into the medium-term (3-5 years). I’m in all of them at allocations I feel are appropriate and am excited to see what the future brings. I would love to become a long-term holder but will reassess later. For now, these make for great Investment Property Stocks.
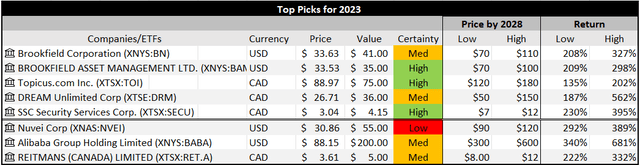
Below is a final summary for all the Top Picks for 2023:
Summary of top picks in the last two articles, including fair values and return potential (Author’s Calculation)
Please feel free to comment, especially dissenting thoughts.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.