Investment Property Loan Guide | 2022 Guidelines and Process

Investment Property Loan Guide | 2022 Guidelines and Process

Guide to investment property loans

Investment property loans are a lot like ‘standard’ mortgages, provided you want to buy a home with 1–4 units.

The application and approval processes work the same way, and mortgage rates are usually less than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher than for a standard mortgage.

However, the rules are a little stricter for an investment property loan than for a mortgage on your primary home. For instance, you likely need 15–20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down instead of 3–5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. And your credit score will need to be in the high 600s or 700s.

If you’re planning to buy an investment property in the near future, here’s what you need to know.


In this article (Skip to…)


What is an investment property?

An investment property is a home that is not your primary residence, and that you buy with the intention to generate rental income or sell for profit. Most commonly, these include one– to four–unit rental homes or houses that you buy to fix and flip. For the purposes of this article, we are not including commercial investment properties like apartments or office buildings.

How are investment properties different from second homes?

It’s important to distinguish between investment properties and second homes because mortgage rules and interest rates are different for each type of property. The biggest difference between the two is that you must occupy a second home for at least part of the year, while you – the owner – don’t live in an investment property.

A second home or vacation home might count as an investment property if you intend to rent it out even for short periods. However, lender policies vary over this.

For example, Fannie Mae lets you rent out a second home provided you occupy it yourself for a period each year, retain exclusive control of the home, and don’t rely on your anticipated rental income when you apply. Lenders will also expect a second home to be in a tourist area for a vacation home or a certain distance from your main house if you plan to use it as an occasional residence.

>Related: Second home vs. investment property mortgage rates

Investment property loan options

There are three main loan types used to finance investment properties:

  • Conforming loans: By far the most common option
  • Jumbo loans: Used when the loan exceeds conforming loan limits
  • Government-backed loans: Used only when you occupy one unit yourself and rent out the others (not for ‘true’ investment properties)

Most of those seeking investment property loans will require conventional mortgages. The majority of these are ‘conforming mortgages,’ meaning they conform to lending rules set by Fannie Mae and Freddie Mac. (More information below.)

It’s a condition of all government–backed loans (FHA, VA, and USDA loans) that the borrower occupies the home as their primary residence. So these are not good sources for investment property loans.

However, there is one exception. You can use a government–backed FHA or VA loan to buy a multifamily dwelling with two, three, or four units. And, provided you live in one of those, you can rent out the other(s).

Other ways to finance an investment property

Many investment property buyers use one of the three mainstream mortgage programs listed above. But other options include:

  • Home equity: A home equity loan or home equity line of credit (HELOC) on your current home
  • Private loans: Real estate investors will sometimes fund a purchase of rental property
  • Seller financing: Occasionally, a seller who owns a home outright may trade the lump sum she would normally receive for a continuing income stream
  • “Hard money loans”: These short–term loans can sometimes work well for house flippers

But most buying investment properties turn to mainstream mortgage lenders, including banks. You can find some through our website using the Request a Quote service. You’ll soon find a question that asks whether you want the loan for investment purposes.

The investment property loan process

If you plan to finance your investment property with a mainstream home loan (likely a conforming loan), the process will look very similar to any other home purchase. You will:

  1. Get preapproved for financing
  2. Find a home and make an offer
  3. Apply for the loan
  4. Lock an interest rate
  5. Go through the underwriting process
  6. Sign final papers on closing day

As when buying a home for yourself, it’s a good idea to get preapproved for a mortgage before you begin house hunting. That way, you’ll know how much home you can afford. And, more importantly, the seller and seller’s real estate agent will know you’re making a serious offer.

Before you settle on a lender, make sure to comparison shop for the very best mortgage rate you can find. Investment property mortgage rates are often 0.50 to 0.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (sometimes 0.875{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) higher than those for standard mortgages. And the lower your rate, the higher your profit margin on the property will be.

Is it hard to find investment property loans?

As a rule, it gets easier to find an investment property mortgage when the economy’s doing well and more difficult when it’s struggling. That’s because lenders see investment property loans as riskier than primary home loans. And they may restrict access to moderate their risk level in tough times.

For example, when the Covid–19 pandemic choked the economy, many lenders made qualifying for one of these loans very tough.

So how easily you’re going to find the loan you want will depend on the economic environment when you apply. But, during normal and good times, there are usually plenty of lenders willing to help out.

Investment property mortgage requirements

Mortgage lenders get to set their own requirements. And the guidelines for investment property loans are usually stricter than for a primary residence.

Though rules vary by lender, here are the broad guidelines you can usually expect to see for an investment property mortgage.

  • Minimum down payment: Often 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of purchase price, though some still require 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Minimum credit score: 680 with a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment; 620 with 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down
  • Maximum DTI: This is your debt–to–income ratio. Typically, your non–housing debts should be no greater than 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your gross monthly income. And your total debts plus housing costs shouldn’t exceed 36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. But some lenders are less strict, often allowing 36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} respectively
  • Cash reserves: Many lenders want you to have cash reserves (or easily liquefied assets) that are sufficient for you to cope for six months without rental income
  • Loan limits: Government–backed mortgages and conforming mortgages have limits on the amount you can borrow. These vary according to local home prices
  • Documentation: Expect lenders to request two years of tax returns, two years of W–2s, and two months of bank statements at a minimum

In addition to your finances, mortgage lenders will also evaluate the property you hope to buy.

Lenders will typically lend on any mainstream property: a condo, apartment, manufactured home, single–family house, or multifamily house. But there may be rules about condition, safeness, year–round habitability, accessibility, and so on. An appraiser will establish whether the home is mortgageable.

Investment property loan rates

Lenders know that investment property loans are riskier than loans for owner–occupied homes. That’s because if a borrower gets into financial trouble, they’ll prioritize paying their main mortgage over their investment property mortgage.

As a result, lenders charge a higher interest rate for investment property loans than for ordinary mortgages as well as setting higher barriers to qualifying.

As we’ve already mentioned, these rates are often 0.50 to 0.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (sometimes 0.875{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) higher. That will vary by lender as well as your down payment, credit score, cash reserves, and DTI.

To find out more, read: Investment and rental property mortgage rates.

Special mortgage rules for investment properties

One of the advantages of buying an investment property is that you can typically add your anticipated rental income to your existing income when you apply. That will help you prove you can comfortably afford your new mortgage payments.

However, don’t assume your lender will count all that extra income, nor that it will take your word for how much it will be. Lenders typically allow 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the future rental income to count toward your qualifying income. And they require a rental schedule, which will use the appraiser’s view of your likely rental income based on local comparisons with similar rental properties.

You’ll likely need that extra income to qualify. Because your lender will want to be sure you can afford payments on your existing mortgage (assuming you have one) as well as your new loan.

When you’re budgeting, also keep in mind that investment properties typically offer much more generous tax breaks than owner–occupied ones. So speak to your professional tax adviser to discover what those might mean to you.

Investment property loan FAQ

Do you need 20 percent down on an investment property loan?

That depends on your lender’s rules and the type of mortgage you want. Often 15 percent down is enough for a conventional loan. And for multifamily dwellings where you occupy one unit, you could put down 3.5 percent (FHA loans), 3 percent (conforming loans), or even 0 percent (VA loans)

Can you put 3 percent down on an investment property?

You cannot put 3 percent down on a ‘true’ investment property. But, as discussed above, a mortgage from Fannie Mae or Freddie Mac has a minimum 3 percent down payment for a multifamily dwelling where you live in one unit. So you can buy with one of these loans and still generate rental income from the additional units in your home.

Can you get a 30-year loan on an investment property?

Absolutely! Most borrowers do.

What bank will loan me money for an investment property? 

Many banks, mortgage lenders, and other lenders are happy to lend on investment properties as long as you meet lending criteria, which are stricter than for your main home. In addition, investment property loans are easier to find when the economy’s doing well. You might have a harder time finding investment property loans during economic downturns, like when the Covid pandemic was at its peak.

Can I use my 401(k) to buy an investment property?

That depends on the rules of the program(s) of which you’re a member. But most financial advisers warn against touching your retirement funds for any investment that’s even a bit risky. A better way to fund your investment property purchase might be with equity from your current home, via a cash–out refinance or second mortgage.

Can I live in an investment property? 

A ‘true’ investment property is one you do not live in. But your home may be considered an investment property if you buy a multifamily property, live in one unit, and rent the other(s) out. Indeed, this can be one of the most affordable ways to buy a rental property and start earning income from it.

How much can I borrow for an investment property? 

That depends on whether your chosen mortgage has loan limits. In theory, you could borrow millions with a jumbo loan, providing you can afford the monthly payments, have a big down payment, and are highly creditworthy.

The information contained on The Mortgage Reports website is for informational purposes only and is not an advertisement for products offered by Full Beaker. The views and opinions expressed herein are those of the author and do not reflect the policy or position of Full Beaker, its officers, parent, or affiliates.

5 Things That You Should Not do When Decorating Your Home

5 Things That You Should Not do When Decorating Your Home

Decorating a room, especially your household, is a quite particular decision. No volume of brochures and Pinterest boards can notify you what you unquestionably should do. Even so, getting inspiration and some guidelines from the suitable resources can make your job less complicated. A single point about household decoration that generally strikes a chord with novices and authorities alike is personalized produced products. These are so common for the reason that they permit you inform your story in your unique language.Also Examine – Thinking How to Make Your Dwelling Christmas All set? Shahnaz Husain Shares Ideas

  • This brings us to the 1st miscalculation that you must stay clear of – subsequent the herd. The social media frenzy that we dwell in right now is driven by Traits. They are almost everywhere, and every person needs to be a portion of it. Nevertheless, it is a confirmed blunder if you observe household decor trends without having incorporating your individualistic flavour. This is mainly because the space that you live in is a representation of your individuality. You will be residing in it each individual day, and you completely must love it. Therefore, although an all-white bohemian concept may well be what the who’s – who are performing, that crimson pink toss or the blush pink tapestry you’ve constantly required could improve the search solely and make you really feel at household. Do what feels suitable to you.
  • Another correlated error that can hamper the decore approach is not owning a finances. Building and placing up a house requires a sizeable investment decision. Transferring into the style system without having an estimate of the probable costs is a large mistake. Figuring out what you can commit on and what you can avoid so that the needs of the complete area are satisfied is essential. Investing in superior-good quality home furnishings and beddings is critical while on the style entrance, investing in customized parts alternatively than off-the-shelf is a terrific concept. But realizing when to end is even additional essential.
  • Litter is your enemy! Though minimalism could possibly not be your type, performing also a lot with your place may possibly hamper its features. If you strike a area each time you transfer, you need to know it is time to make a improve. Understanding your area, having the right measurements and aligning your home furnishings in a way that is desirable to the eye although becoming easy to maintain is the vital.
  • A finish convert-off for any space are open wires. Bundles of cables with nowhere to go can make your home come to feel untidy. For that reason, concealing them ought to be on the major of your listing. Nonetheless, it is also vital that you make preparations for using treatment of this potential hazard in areas about the house that are most inclined to it.
  • Lights is a critical facet of the decor approach. You need to have the right light-weight accenting your most exceptional parts, and you will need more than enough of it around the home. Therefore, it is a must to comprehend the form, type, and tint of the lights, dependent on the space it will be in. A prevalent blunder that individuals make is insufficient lighting. This can make your house really feel cramped and unwelcoming. A further blunder that you really don’t want to make is using much too considerably of it. Acquiring the equilibrium by experimenting with several levels of lighting can be a gamechanger.

Whilst the checklist of pitfalls can carry on to improve, the golden rule for properly decorating your space is to showcase your individuality by way of the pieces accessible to you. And when you just can’t uncover the kinds that you most resonate with, structure them on your own! Also Browse – Diwali 2021 Decor Strategies: Ideal Methods For Do it yourself Styling to Deliver Magic Into Your Property This Festive Year

Also Study – Just Floored: 5 Pro Actions to Choosing an Area Rug

Heidi Uuranniemi Anticipates that the Boca Raton Real Estate Market Will Start to Normalize in 2022

Heidi Uuranniemi Anticipates that the Boca Raton Real Estate Market Will Start to Normalize in 2022

Heidi Uuranniemi Anticipates that the Boca Raton Real Estate Market Will Start to Normalize in 2022

New communities coming to Florida for affordable living indicate a return to normalcy for real estate sales in the greater Boca Raton, Florida region, says Heidi Uuranniemi.

Real Estate Market Recovering in the Wake of COVID-19

As the world slowly starts to recover from the previously unimaginable economic downturn caused by a once-in-a-century pandemic of the novel coronavirus and COVID-19 infections, there is a reason for hope when you look at the real estate market in sunny Boca Raton, Florida, according to Heidi Uuranniemi.

People will start feeling more comfortable making investments in their future, which is especially critical in an industry like real estate, no matter what part of the country you come from. With the economy doing better, more families will be able to focus their sights on homeownership.

Of course, the cost of living will be different in various regions of the United States, which can prompt a lot of activity as individuals and families try to figure out where it would be best to spend their hard-earned dollars. So real estate professionals need to keep close tabs on consumer demographics and how people respond to changes in their communities.

If a region that shut down during quarantines and shelter-in-place orders has not yet picked up much momentum in its economy, people might be motivated to find work and a new living situation in another state where the tax requirements are more favorable, for example. They may also be motivated to make a change if the cost of living is favorable to where they currently live.

Sales of Homes Seen to Continue to Normalizing in Boca Raton

Heidi Uuranniemi (who grew up in Thomasville, GA) lives in Boca Raton, where she works as an attorney at law and real estate broker. She’s a keen observer of the local real estate scene. As reported by Boca Raton Magazine, a return to normal began in 2021, with industry insiders anticipating that the trend should keep growing into next year.

Heidi Uuranniemi Sees Encouraging Signs in Market Demand in Florida Real Estate

Heidi Uuranniemi observes that states with higher tax rates could see more people leaving in droves to come to a community such as Boca Raton. In fact, Boca Raton Magazine points out that a large proportion of home buyers are new to shopping in Florida over the past two years.

What’s more, when you factor in the law of supply and demand, a slowdown and trend of under-building in real estate across the country make housing in greater demand. And for families whose wealth increased over the past few years despite the pandemic-related hit to the economy, this means the real estate market has the potential to heat up more in sunny Boca Raton.

Heidi Uuranniemi Has an Optimistic View of Real Estate in Boca Raton in 2022

There’s good reason to be optimistic when considering the real estate market in the southeast of the United States, with Florida being attractive to newcomers looking to start a fresh life.

With higher prices in other states in the country inspiring people to reexamine their budgets and their choice of where to live, it seems that more families will be interested in coming to places like Boca Raton in Florida, as far as Heidi Uuranniemi is concerned. As more families buy homes and contribute to the local community, it’s safe to say that the living conditions will attract even more newcomers.

Katy Home and Garden Show returns with new larger venue, expanded attractions

Katy Home and Garden Show returns with new larger venue, expanded attractions

The Katy Residence and Yard Show, the biggest display of its kind in the west Houston spot, will be returning this yr on March 26 and 27 at a new much larger location.

The 16th annual show will consider position at the Katy ISD Agricultural Centre, which will present more house for distributors and a much larger show place for outside distributors, said occasion coordinator Robyn Cade. The new place will be practically double the sizing of previous functions, which ended up held at the Merrell Centre.

The present runs Saturday, March 26 from 10:00 a.m. – 6:00 p.m. and Sunday, March 27, from 11:00 a.m. – 5:00 p.m.

With extra than 250 vendors on hand, Cade explained, visitors can join with nearby companies for all their home and yard enhancement requirements. There are also dozens of foods and shopping vendors as very well.

The primary concentrate of the exhibit are the property and backyard garden contractors who provide anything from patios to bathroom renovations.

“One detail I feel that we uncovered from the pandemic is just how essential it is to have a dwelling area that’s definitely tailor-made to you,” Cade explained. “We expended a large amount of time in our residences, and folks are creating much more dwelling improvements than at any time prior to.”

By conference distributors in particular person, she noted, guests looking for a new contractor can get a probability to meet up with the people experience to experience that will be accomplishing the get the job done. “This really gives you an opportunity to make confident you have a link with these corporations so you know you have bought the suitable particular person for the task,” she said.

The party will element several demonstrations, such as headliners The Cheese Chica and The Barndominium Woman. The Cheese Chica is acknowledged for crafting artisanal charcuterie boards. She will be offering charcuterie creating classes for $50, which incorporates every thing needed to make a cheese board, which includes the board itself. Registration for the class is needed.

“You’re going to depart the course with a specialist cheeseboard that serves up to four persons, and you’ll have the information to make your very own,” Cade explained.

Stacee Lynn, the Barndominium Lady, has acquired nationwide acclaim for her craze of developing beautiful luxurious residences out of humble barns. She’ll educate website visitors how to rework a raw barn into a clearly show-halting household.

Other displays involve h2o conservation in gardening and very best horticulture methods for yards. “We’re acquiring far more and additional that persons want to have gardens that really don’t have to have a great deal of water, both equally for expense causes and environmental explanations,” Cade explained.

Even though the major concentration of the demonstrate is property and outside improvement, Cade claimed, this 12 months will carry far more purchasing and meals suppliers than former several years. “People love to store, and this is a great opportunity for that,” she explained. “You can come across on-trend decor merchandise, gifts and definitely exclusive pieces that you will not uncover in a keep.”

The Katy ISD Agricultural Center is positioned at 5801 Katy Hockley Cut Off Highway. Display tickets are $7, and small children 12 and more youthful are absolutely free. Parking is absolutely free. For far more information on the clearly show or to register for the charcuterie course, take a look at www.katyhomeandgardenshow.com.

claire.goodman@chron.com

Home improvement businesses hammered through the pandemic. Will the trend continue? | Home & Garden

Home improvement businesses hammered through the pandemic. Will the trend continue? | Home & Garden

While many people stayed home during the pandemic, Justin Brandt stayed busy.

His business, Custom Scapes, was abuzz those months, when many people opted to focus their time and attention on improving their home.


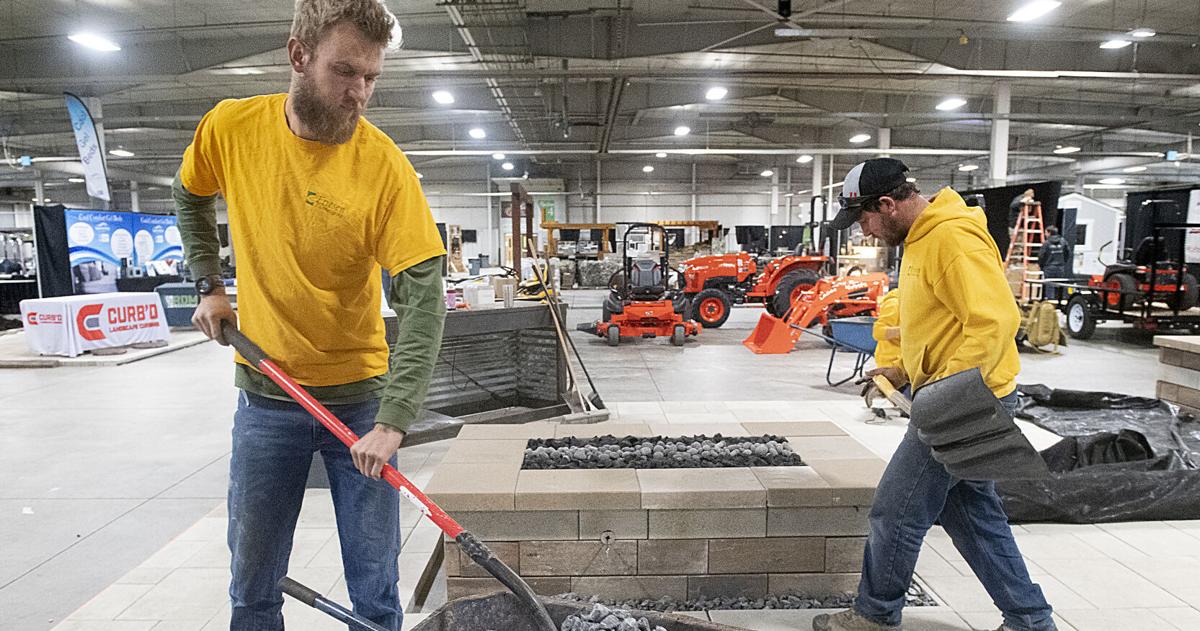
Husker Lawn and Leisure Show setup

Andy Bettenhausen, with Custom Scapes in Lincoln, spreads mulch during set up for the Husker Lawn & Leisure Show on Thursday.


Now with high gas prices leading some to rethink travel, home improvement is likely to remain a hot item.

Brandt, one of dozens of exhibitors at this weekend’s Husker Lawn & Leisure Show, said he expects the increased interest in home improvement to continue for the next few years.

People are also reading…

Now is a good time to invest in landscaping, he said, because he expects prices will continue to rise.

“The sooner you do it, the better,” Brandt said. “Right now everything keeps going up, it seems.”

With COVID-19 cases on the decline and the promise of spring on the horizon, exhibitors at the 20th annual Husker Lawn & Leisure Show are hoping to draw people to the Lancaster Event Center beginning Friday.

The show returns for the first time in three years after COVID-19 concerns led organizers to cancel the event in 2020 and 2021.


Post winter care for your lawn

This year, 125 vendors are promoting everything from landscaping services to iron sculptures.

Paula Widholm, promotions manager of the event, said many local businesses rely on the show to connect with potential customers.

“The face-to-face marketing you get as a business owner trying to sell products or promote your business is very valuable,” Widholm said.

Though she has built long-standing relationships with exhibitors — several have been coming since the show’s first year — Widholm said there are many new faces at this year’s event. About 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the vendors are there for the first time.

Business owners Ken and Jackie Svoboda of Luxury Landscapes were at work Thursday, setting up their exhibit. Forming relationships with customers is their favorite part of the show, which runs through Sunday.

“We absolutely love showcasing what we can do,” Jackie Svoboda said. “Just visiting with customers … and hearing them say, ‘Wow, we love your booth. We want this in our backyard.’”

Future 15: Knock and Pacaso CEOs discuss real estate’s newest homeownership category: co-ownership

Future 15: Knock and Pacaso CEOs discuss real estate’s newest homeownership category: co-ownership

In the most current episode of Potential 15, host and Knock CEO Sean Black sat down with Austin Allison, CEO of Pacaso. The two titans of sector examined the rise in the new category of homeownership, and how it will have an impact on all aspects of the market, from housing affordability to home automation.

Check out the full video clip for their full insights, but below are some important takeaways from Sean and Austin’s dialogue about co-ownership.

Owners get higher overall flexibility and far more accessibility with co-ownership

Sean: What do you believe household obtaining and selling appears to be like like in 10 several years?

Austin: The pattern that I’m closest to is this notion that we, at Pacaso, describe as, “the flexibility of place”, which is this new truth that a lot of people confront: far more adaptability. Versatility to get the job done remotely, possibly portion-time or entire-time. That’s empowering individuals to rethink how and where by they stay and do the job. 10 decades from now, I think there will be a ton extra equally major and secondary house owners in markets that have traditionally been mainly 2nd property places.

Sean: Do you see a future in which the next residence is the property?

Austin: I do. I never assume that to be consultant of how every person life, but I absolutely assume that there is a cohort of people today who now reside nomadically. Envision if you could purchase a quarter of a household in San Francisco and a quarter of a property in 3 other areas and shell out your time in diverse spots in the course of the yr. But I also consider that you’ll see families that carry on to have a key dwelling spot. In point, I believe that will be the norm.

Sean: I want to discuss about how substantially of what you are executing is digitized. How a great deal of the expertise is on your telephone?

Austin: For us, technological innovation permits the overall market. There are lots of factors that excite me a good offer about the potential. A single, in distinct, is the clever property and household automation capabilities. Let’s say you are going for walks into your [Pacaso home], and as you walk in there are digitized family members images of you and your spouse and children on the wall. The temperature on the thermostat is by now established up for the temperature that you and your family prefer. It regarded you as you have been walking up to the residence and it presently unlocked the door securely. That is the style of practical experience that we can create for our homeowners leveraging technological know-how.

Co-ownership benefits housing affordability, community economies, and the planet

Sean: Do you fellas see a long term that is in principal household ownership becoming shared? How much do you see the sharing economic climate version of houses heading?

Austin: The sharing economic system will effect housing in a extremely constructive way due to the fact, frankly, it has to. We’re in the center of a housing affordability disaster and it’s not obtaining any far better. There is way additional demand than supply, and then the housing affordability disaster is most pronounced in 2nd-home destinations simply because you have received this inflow of new 2nd-residence potential buyers that are buying up all the houses at the median value tier, producing it unachievable for locals to find the money for most important homes. Co-ownership is a definitely critical section of the solution there because what co-possession does is it consolidates desire away from the median tier and moves it into the luxurious tier.

The other gain of the sharing economy is to regional economies and to the atmosphere. The common second residence is only utilized 5 months for each year. Each vacant next house means yet another home desires to be built to take in desire, which results in a greater carbon footprint and it starves area companies all through the slower time due to the fact house owners aren’t even in the house supporting the local businesses for all those people months in the course of the calendar year.

With co-ownership on the desk, brokers can include a further dimension to their organization

Sean: Let’s talk a tiny little bit about the marketplace? How, if at all, do agents participate in a position in your universe?

Austin: We assume about brokers like an extension of our crew. We associate with real estate agents on all the actual estate transaction relevant specifics. The point that genuine estate brokers are getting most fascinating about our model is that it’s an additive to their main organization, very first and foremost. It doesn’t contend with their whole-household small business. It’s icing on the cake. It is an accelerant to their business enterprise.

Sean: So you’re allowing for agents to stand for shoppers to purchase a fractional portion of these households like they would a single-loved ones household?

Austin: Certainly. If we can supercharge authentic estate agents’ small business by supplying them an additional kind of solution to sell, a software that allows them to transform men and women who would’ve normally been window customers simply because they didn’t have the spending plan for the total residence they had been dreaming of. Now with Pacaso you can convert all those window shoppers into owners.

Watch the whole episode for extra.