CINCINNATI — The Cincinnati Property and Backyard garden Present is again for its 54th yr.
It is one particular of the most significant home and garden reveals in the Midwest, and the two weekend-prolonged function that will attribute more than 350 exhibitors within the Duke Power and Convention Middle.
Immediately after this weekend, the present will again from March 2 to March 5 with a special visitor showing on March 3 and 4.
“Joe Mazza from HGTV’s House Inspector, so I know it is the time wherever men and women are pondering about obtaining a new dwelling, so he can actually give you the insights of what to look for in a residence inspection,” explained Kelly Scott, one particular of the organizers of the party.
Mazza is a home inspector who has a 20-12 months construction background. He’s the host of HGTV’s “Home Inspector Joe” in which he functions with a design partner to support residence hunters obtain their aspiration house layouts though repairing high priority basic safety concerns.
Attendees will get a single-on-one time with specialists who focus in kitchen area and bathtub, out of doors dwelling and home enhancement.
“We have seven characteristic gardens. They’ve done these types of a excellent occupation, a lot of inspiration for spring, also a pickleball courtroom, some playground sets for the young ones,” Scott claimed.
She said they’ve included two new gardens this calendar year, and one particular of them is with Outdoor Professionals, which is a Cincinnati-based mostly exterior design and style and constructing enterprise.
“We have never ever been to the house and garden exhibit as a firm and desired to see what clients imagined of our work and clearly show off what we had to offer,” explained Zach St. Jean with Out of doors Gurus.
Jim Mild with Weaver Barns stated due to the fact the pandemic additional people today are investing in their backyards.
“We get in touch with it the yard pandemic, which suggests people today are putting revenue in their properties yet again and redesigning their lifestyles to keep at residence to delight in their swimming pools, to appreciate a shade include out back again to have dinners or enjoy playing cards,” Light claimed.
Weaver Barns is a yard building corporation that does every thing from personalized properties to sheds.
“The people today appear from all about,” Light claimed. “This clearly show probably generates 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of our small business in 6 days.”
In the middle of the show is a pickleball court docket made and crafted by Cincinnati Sportscapes.
“The demand for pickleball has just developed immensely. Pickleball has been all the rage. It’s the speediest expanding activity in America,” mentioned Chris Castleman with Cincinnati Sportscapes. “We’re looking at a ton of demand for multi-purpose courts with pickleball bundled, basketball, pickleball, shuffleboard, hopscotch, the will work.”
Castleman extra pickleball courts are small-servicing and final longer than tennis courts.
If you want to check out out the House and Yard display, you can obtain tickets on the net or at the door.
Dear Aggie: Are there any distinctive tips to escalating asparagus in the north country?
Just one of my favored treats in Might is fresh asparagus, picked from our yard and steamed minutes later on. Sweet and tender, asparagus is a nutritious vegetable that grows pretty nicely in the north region. Offered that demand from customers for nearby asparagus usually outstrips out there source at neighborhood farmstands, the best approach to be certain a continuous offer is to improve it you.
Planting asparagus is easy. The initial stage is to choose a web site with well-draining soil and entire sun. Prevent are damp or h2o-logged areas. Asparagus also needs total sunshine — so stay away from the north-facet of residences or spots underneath trees. Recall that asparagus is perennial. With appropriate treatment, asparagus plants can reside for 20 decades. Experienced crops also transplant poorly — so pick out a area where the vegetation can be left for yrs to occur. Luckily, asparagus tolerates a extensive array of soil pH and will execute effectively in the alkaline soils common all over Watertown. It’s deep root process can make it tolerant of dry soils and areas without having irrigation (although watering is recommended in the first calendar year). Hardy to an outstanding Zone 2, it is chilly-hardy everywhere you go in the north country (Zone 4). Simply because it is indigenous to seaside destinations in the Mediterranean, asparagus will even tolerate street-salt, making it possible for it to be planted near sidewalks and roadways.
Even though asparagus can be grown from seed, gardeners will have the best results by paying for crowns — bareroot asparagus roots delivered in dormancy. These can frequently be observed at backyard garden centers and nurseries. Specially when you system to invest in a much larger amount of crowns, we advise buying from a catalog and getting them delivered mail-get in early spring. That way, they will be in cold-storage ideal up until the day they are delivered (as opposed to sitting down in on the shelf of a retailer, which tends to dry them out). A wide variety that I recommend for Northern New York is Millennium, which is seldom available at community vendors but widespread in mail get catalogs. This wide variety performs nicely even in weighty clay soils. An exciting novelty range for our place is Purple Passion.
To plant asparagus crowns, start out by digging a trench about 10 inches deep and 12 inches huge. Unfold a 2-inch layer of compost or properly-rotted manure into the bottom of the trench and turn it into the soil with a spade. This will assist increase the soil fertility and endorse nutritious roots. As soon as the trench is all set, it is time to plant the crowns. Place the crowns in the trench, spacing them about 18 to 24 inches apart. Gently address the crowns with soil, and organization the soil with your hands. Drinking water the asparagus mattress generously, and then include the bed with a 2-inch layer of mulch. The mulch will help retain moisture and hold the weeds down — critically crucial throughout the to start with year or two as plants become established.
Asparagus vegetation need to have time to come to be recognized in advance of they can be harvested. The first yr, chorus from any harvest by any means. I advocate preventing harvest in the second calendar year, although some growers do decide on lightly from their plantings at that time.
In the 3rd 12 months, you can start out harvesting spears from about May well by way of June. Choose the spears when they attain about 7 inches tall. End picking in about mid-June to permit some of the spears to produce into fronds. This fern-like foliage can then acquire and store strength for the duration of the summer for upcoming year’s harvest. Nevertheless set up plantings can endure drought, water them during dry intervals to assure a superior harvest. To lower weeds, increase a 2-inch layer of mulch every spring. Be sure to take away any weeds from the patch, specially perennial weeds, as these will faucet electricity from your vegetation.
Composed by Mike Nuckols, Cornell Cooperative Extension, agriculture and natural methods crew leader.
As an Amazon Associate I get paid from qualifying buys.
Shopping centre leasing activity remains strong, with industry-leading occupancy levels of 98{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Q4 2022, representing a 40 basis point increase as compared to the same period 2021
Same Properties NOI(1) for the quarter increased by $5.1 million or 4.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to Q4 2021, and for the full year increased by $16.5 million or 3.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to 2021
Net rental income and other for the quarter increased by $2.2 million or 1.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to Q4 2021, and for the full year increased by $16.8 million or 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to 2021
Mixed-use Development
In excess of three million square feet of construction activity is currently underway, principally high rise residential on existing shopping centre sites in Toronto, Montreal, and Ottawa
Construction of the Transit City 4 & 5 condominium towers is in the final stages of completion with closings scheduled to commence in March 2023. All 1,026 units have been pre-sold and construction costs are on budget
Construction of the Millway, a 458-unit purpose-built rental apartment building, is also in the final stages of completion, with initial tenants taking occupancy and rent commencement later this month
Financial
FFO(1) with adjustments excluding the impact of the TRS for the quarter increased by $1.0 million or 1.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to Q4 2021, and for the full year increased by $9.6 million or 2.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to 2021
Payout Ratio to ACFO(1) with adjustments excluding the impact of the TRS and other for the year ended December 31, 2022 improved by 3.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 92.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to 2021 and for the quarter improved by 5.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 94.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to Q4 2021
Payout Ratio to cash flows provided by operating activities for the year ended December 31, 2022 increased by 3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 88.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to 2021 and for the quarter increased by 1.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 61.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to Q4 2021
As a result of fair value adjustments to property valuations and condo and townhouse closings that occurred in 2021, net income and comprehensive income for the quarter decreased by $551.8 million or 84.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to Q4 2021, and for the year decreased by $351.7 million or 35.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as compared to 2021
TORONTO, Feb. 08, 2023 (GLOBE NEWSWIRE) — SmartCentres Real Estate Investment Trust (“SmartCentres”, the “Trust” or the “REIT”) (TSX: SRU.UN) is pleased to report its financial and operating results for the quarter and year ended December 31, 2022.
“Walmart is a very strong anchor tenant in good times, and an even stronger one in tough times. Hence, customer traffic to our Walmart-anchored shopping centre portfolio continues to gain momentum which, in turn, is generating steadily increasing levels of leasing activity that began earlier in 2022.” said Mitchell Goldhar, Executive Chairman and CEO of SmartCentres.
“We anticipate this trend will continue into 2023 and that it will have a positive impact on both our occupancy and earnings levels. We are pleased with the noticeable increase in leasing activity in the fourth quarter and the associated improvement in cash collections.”
“We are particularly proud of our progress on the eleven mixed-used development initiatives that are currently under construction. These projects have expected completion dates in 2023 and 2024, upon which they are expected to begin contributing FFO(1). The development initiatives span multiple asset classes, including condos, rental apartments, seniors’ apartments, townhouses, self-storage, industrial, and retirement residences. As at December 31, 2022, the total cumulative amount of capital deployed on these projects was $755.2 million ($304.1 million at the Trust’s share), with approximately $487.8 million remaining until completion ($234.9 million at the Trust’s share),” noted Mr. Goldhar.
“Among these developments are significant projects at our flagship Vaughan Metropolitan Centre. These include two 45-storey and 50-storey condominium towers at Transit City nearing completion after 36 months. These units are sold out and the final stages of construction are rapidly nearing the finish line, on time and on budget. Closings are expected to commence in March 2023. In addition, The Millway, a 458-unit, 36-storey rental apartment tower, is also proceeding on time and on budget with initial occupancy and rent commencement expected to begin later this month. The first phase of our Artwalk condominium project is also sold out and construction is expected to commence in the second half of 2023.”
“We are also pleased to note that, as promised, we published our inaugural ESG report during the fourth quarter of 2022. Our business remains strong and well-positioned for growth in the coming years. Nevertheless, with changing economic conditions, we plan on applying prudent discipline when assessing development and other initiatives. Our focus remains on the long term, including the development of mixed-use projects on our strategically located real estate, which we are confident will extract deeply embedded value for many years to come,” added Mr. Goldhar.
(1) Represents a non-GAAP measure. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release.
Key Business Development, Financial and Operational Highlights for the Year Ended December 31, 2022
Mixed-Use Development and New Growth at SmartVMC
Park Place condo pre-development is underway on the 53.0 acre SmartVMC West lands strategically acquired in December 2021. Pre-sales for this development have commenced. The Trust’s acquisition in December 2021 of a two-thirds interest in the SmartVMC West lands more than doubled the Trust’s holdings in the 105 acre SmartVMC city centre development.
Construction nears completion on the 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} pre-sold Transit City 4 (45 storeys) and 5 (50 storeys) condo towers, representing 1,026 residential units. Concrete, formwork and building envelope have been completed for both towers, with interior finishes ongoing. First closings are expected to commence in March 2023.
Construction of the purpose-built rental project, The Millway (36 storeys), nears completion at SmartVMC. Formwork, concrete and building envelope have been completed, with interior finishes underway. Initial occupancy is expected to commence in February 2023.
ArtWalk condominium sales of 320 released units in Phase 1 are sold out with construction expected to begin in the second half of 2023.
Other Business Development
Occupancy in the completed first phase of the two-phase, purpose-built residential rental project in Laval, Quebec, ended the year with 98{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the 171 units leased. Pre-leasing has commenced on the next phase and construction continues, with a target completion date of Q2 2023.
Initial occupancy in the two purpose-built residential rental towers (238 units) in Mascouche, Quebec began in July 2022, with the final floor opened in November. More than 147 units have been leased and current lease-up activity is in line with initial expectations.
All of the five developed and operating self-storage facilities (Toronto (Leaside), Vaughan NW, Brampton, Oshawa South and Scarborough East) have been very well-received by their local communities, with current occupancy levels ahead of expectations. A sixth facility, Aurora, opened in December 2022.
Three self-storage facilities in Whitby, Markham and Brampton (Kingspoint) are currently under construction, with Brampton (Kingspoint) expected to be completed in early 2023. Additional self-storage facilities have been approved by the Board of Trustees and the Trust is in the process of obtaining municipal approvals in Stoney Creek and two locations in Toronto (Gilbert Ave. and Jane St.). In addition, the municipal approval process is underway in New Westminster and Burnaby, British Columbia.
Construction continues on a new retirement residence and a seniors’ apartment project, totalling 402 units, at the Trust’s Laurentian Place in Ottawa, with completion expected in Q1 2024.
By way of a Minister’s Zoning Order, the Trust has permissions that would allow for the redevelopment of the 73-acre Cambridge retail property (which is subject to a leasehold interest with Penguin) including various forms of residential, retail, office, institutional and commercial uses providing for the creation of a vibrant urban community with the potential for over 12 million square feet of development.
The Trust, together with its partner, Penguin, has also commenced preliminary siteworks for the 215,000 square foot retail project on Laird Drive in Toronto, that is expected to feature a flagship 190,000 square foot Canadian Tire store together with 25,000 square feet of additional retail space. Canadian Tire is expected to take possession in 2024.
Financial
Net income and comprehensive income(1) was $636.0 million in 2022 compared to $987.7 million in 2021, representing a decrease of $351.7 million. This decrease was primarily attributed to: i) $476.8 million decrease in fair value adjustment on revaluation of investment properties; and ii) $20.2 million decrease in net profit on condo and townhome unit closings; and was partially offset by i) $125.5 million increase in fair value adjustments on financial instruments; and ii) $20.6 million increase in net rental income and other mainly due to higher base rent in 2022.
Net income and comprehensive income per Unit(1) in 2022 decreased by $2.14 or 37.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to $3.54 as compared to the same period in 2021, primarily due to the reasons as noted above.
As at December 31, 2022, the Trust increased its unsecured/secured debt ratio(2)(3) to 74{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}/26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (December 31, 2021 – 71{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}/29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
The Trust continues to add to its unencumbered pool of high-quality assets. As at December 31, 2022, this unencumbered portfolio consisted of investment properties was valued at $8.4 billion (December 31, 2021 – $6.6 billion).
The Trust’s fixed rate/variable rate debt ratio(2)(3) was 82{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}/18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as at December 31, 2022 (December 31, 2021 – 89{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}/11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
FFO per Unit with adjustments excluding the impact of ECL, TRS, condominium and townhome closings, and SmartVMC West acquisition(2) was $2.14 (year ended December 31, 2021 – $2.09).
During the quarter, 693,900 additional notional TRS Units were added at a weighted average price of $26.37 per Unit.
For the year ended December 31, 2022, there was a surplus of cash flows provided by operating activities(1) over distributions declared of $41.2 million (year ended December 31, 2021 – surplus of $52.9 million).
The Payout Ratio relating to cash flows provided by operating activities for the year ended December 31, 2022 was 88.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, as compared to 85.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year ended December 31, 2021.
For the year ended December 31, 2022, there was a surplus of ACFO(2) over distributions declared of $10.5 million (year ended December 31, 2021 – surplus of $34.3 million).
The Payout Ratio to ACFO(2) for the year ended December 31, 2022 was 96.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, as compared to 90.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year ended December 31, 2021. Excluding the impact of TRS, condominium and townhome closings, and SmartVMC West acquisition, the Payout Ratio to ACFO(2) for the year ended December 31, 2022 was 92.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, as compared to 96.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year ended December 31, 2021.
Operational
Rentals from investment properties and other(1) was $804.6 million, as compared to $780.8 million in 2021, representing an increase of $23.8 million or 3.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, primarily due to: (i) the acquisition of an additional interest in investment properties in Q1 2022; (ii) higher rental income from Premium Outlets locations in both Toronto and Montreal; and (iii) additional self-storage facility and parking rental revenue.
Same Properties NOI inclusive of ECL(2) increased by $16.5 million or 3.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022 as compared to 2021. Same Properties NOI excluding ECL(2) increased by $9.5 million or 1.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2022 as compared to the prior year.
In-place occupancy rate and occupancy rate with committed deals were 97.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 98.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively, as at December 31, 2022 (December 31, 2021 – 97.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 97.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively).
Subsequent Event
The Trust together with an entity, PCVP, which is classified as investment in associates, entered into an agreement to dispose approximately 6.4 acres of land located in Vaughan, Ontario (VMC) to an unrelated party, which closed in February 2023, for gross proceeds of $95.6 million that was satisfied with cash. The Trust’s share of such proceeds was $58.4 million, comprised of $42.3 million relating to the Trust’s two-thirds share of the 4.3 acres of land on western part of SmartVMC which were previously consolidated in the Trust’s consolidated financial statements and presented as assets held for sale at December 31, 2022, and $16.1 million relating to the Trust’s 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} share of 2.1 acres of land on eastern part of SmartVMC which were previously recorded in equity accounted investments. Proceeds from the sale were primarily used by the Trust to reduce indebtedness.
(1) Represents a GAAP measure. (2) Represents a non-GAAP measure. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release. (3) Net of cash-on-hand of $33.4 million as at December 31, 2022 for the purposes of calculating the applicable ratios.
Selected Consolidated Operational, Mixed-Use Development and Financial Information
Key consolidated operational, mixed-use development and financial information shown in the table below includes the Trust’s proportionate share of equity accounted investments:
(in thousands of dollars, except per Unit and other non-financial data)
December 31, 2022
December 31, 2021
December 31, 2020
Portfolio Information
Number of retail properties
155
155
156
Number of office properties
4
4
4
Number of self-storage properties
6
6
4
Number of residential properties
1
1
1
Number of properties under development
19
17
14
Total number of properties with an ownership interest
185
183
179
Leasing and Operational Information(1)
Gross leasable retail and office area (in thousands of sq. ft.)
34,750
34,119
34,056
Occupied retail and office area (in thousands of sq. ft.)
33,925
33,219
33,039
Vacant retail and office area (in thousands of sq. ft.)
Trust’s share of future development area (in thousands of sq. ft.)
41,200
40,600
32,500
Trust’s share of estimated costs of future projects currently under construction, or for which construction is expected to commence within the next five years (in millions of dollars)
10,000
9,800
7,900
Total number of residential rental projects
110
104
96
Total number of seniors’ housing projects
25
27
40
Total number of self-storage projects
33
36
50
Total number of office buildings / industrial projects
8
8
7
Total number of hotel projects
3
3
4
Total number of condominium developments
88
95
72
Total number of townhome developments
7
10
15
Total number of estimated future projects currently in development planning stage
274
283
284
Financial Information
Total assets – GAAP(2)
11,702,153
11,293,248
10,724,492
Total assets – non-GAAP(3)(4)
12,083,941
11,494,377
10,874,900
Investment properties – GAAP(2)
10,250,392
9,847,078
8,850,390
Investment properties – non-GAAP(3)(4)
11,223,796
10,684,529
9,400,584
Total unencumbered assets(3)
8,415,900
6,640,600
5,835,600
Debt – GAAP(2)
4,983,265
4,854,527
5,210,123
Debt – non-GAAP(3)(4)
5,260,053
4,983,078
5,261,360
Debt to Aggregate Assets ({d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9})(3)(4)(5)
43.6
42.9
44.6
Debt to Gross Book Value ({d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9})(3)(4)(5)
Weighted average interest rate ({d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9})(3)(4)
3.86
3.11
3.28
Weighted average term of debt (in years)
4.0
4.8
5.0
Interest coverage ratio(3)(4)(5)
3.1X
3.4X
3.2X
Equity (book value)(2)
6,163,101
5,841,315
5,166,975
Weighted average number of units outstanding – diluted
179,657,455
173,748,819
172,971,603
(1) Excluding residential and self-storage area. (2) Represents a GAAP measure. (3) Represents a non-GAAP measure. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release. (4) Includes the Trust’s assets held for sale and the Trust’s proportionate share of equity accounted investments. (5) As at December 31, 2022, cash-on-hand of $33.4 million was excluded for the purposes of calculating the applicable ratios (December 31, 2021 – $80.0 million, December 31, 2020 – $754.4 million).
Year-to-Date Comparison to Prior Year
The following table presents key financial, per Unit, and payout ratio information for the year ended December 31, 2022 and December 31, 2021:
(in thousands of dollars, except per Unit information)
2022
2021
Variance
(A)
(B)
(A–B)
Financial Information
Rentals from investment properties and other(1)
804,598
780,796
23,802
Net base rent(1)
508,023
494,992
13,031
Total recoveries(1)
265,281
253,032
12,249
Miscellaneous revenue(1)
15,393
17,891
(2,498)
Service and other revenues(1)
14,652
14,843
(191)
Earnings from other(1)
1,249
38
1,211
Net income and comprehensive income(1)
635,965
987,676
(351,711)
Net income and comprehensive income excluding fair value adjustments(2)(3)
342,261
342,609
(348)
Cash flows provided by operating activities(1)
370,762
371,624
(862)
Net rental income and other(1)
502,604
485,840
16,764
NOI from condominium and townhome closings and other adjustments(2)
FFO sourced from condominium and townhome closings
(680)
(18,747)
18,067
FFO sourced from SmartVMC West acquisition
(984)
—
(984)
FFO with adjustments excluding impact of ECL, TRS, condominium and townhome closings, and SmartVMC West acquisition(2)(3)(4)
372,225
362,613
9,612
FFO with adjustments and Transactional FFO(2)(3)(4)
379,890
385,219
(5,329)
ACFO(2)(3)(4)(5)
340,075
353,055
(12,980)
Other adjustments
656
3,226
(2,570)
ACFO with adjustments(2)(3)(4)
340,731
356,281
(15,550)
Adjusted for:
Loss (gain) on derivative – TRS
4,918
(5,642)
10,560
ACFO sourced from condominium and townhome closings
(305)
(20,471)
20,166
ACFO sourced from SmartVMC West acquisition
(984)
—
(984)
ACFO with adjustments excluding impact of TRS, condominium and townhome closings, and SmartVMC West acquisition(2)(3)(4)
344,360
330,168
14,192
Distributions declared
329,531
318,753
10,778
Surplus of cash flows provided by operating activities over distributions declared(2)
41,231
52,871
(11,640)
Surplus of ACFO over distributions declared(2)
10,544
34,302
(23,758)
Surplus of ACFO with adjustments excluding impact of TRS, condominium and townhome closings, and SmartVMC West acquisition over distributions declared(2)
14,829
11,415
3,414
Units outstanding(6)
178,133,853
178,091,581
42,272
Weighted average – basic
178,121,149
172,447,334
5,673,815
Weighted average – diluted(7)
179,657,455
173,748,819
5,908,636
Per Unit Information (Basic/Diluted)
Net income and comprehensive income(1)
$3.57/$3.54
$5.73/$5.68
$-2.16/$-2.14
Net income and comprehensive income excluding fair value adjustments(2)(3)
$1.92/$1.91
$1.99/$1.97
$-0.07/$-0.06
FFO(2)(3)(4)(5)
$2.09/$2.07
$2.20/$2.19
$-0.11/$-0.12
Other non-recurring adjustments
$0.00/$0.00
$0.02/$0.02
$-0.02/$-0.02
FFO with adjustments(2)(3)(4)
$2.09/$2.07
$2.22/$2.21
$-0.13/$-0.14
FFO with adjustments excluding impact of ECL, TRS, condominium and townhome closings, and SmartVMC West acquisition(2)(3)(4)
$2.16/$2.14
$2.10/$2.09
$0.06/$0.05
FFO with adjustments and Transactional FFO(2)(3)(4)
$2.13/$2.11
$2.23/$2.22
$-0.10/$-0.11
Distributions declared
$1.850
$1.850
$—
Payout Ratio Information
Payout Ratio to cash flows provided by operating activities
(1) Represents a GAAP measure. (2) Represents a non-GAAP measure. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release. (3) Includes the Trust’s proportionate share of equity accounted investments. (4) See “Other Measures of Performance” for a reconciliation of these measures to the nearest consolidated financial statement measure. (5) The calculation of the Trust’s FFO and ACFO and related payout ratios, including comparative amounts, are financial metrics that were determined based on the REALpac White Paper on FFO issued in January 2022 and REALpac White Paper on ACFO issued in February 2019, respectively. Comparison with other reporting issuers may not be appropriate. The payout ratio to FFO and the payout ratio to ACFO are calculated as declared distributions divided by FFO and ACFO, respectively (6) Total Units outstanding include Trust Units and LP Units, including Units classified as liabilities. LP Units classified as equity in the consolidated financial statements are presented as non-controlling interests. (7) The diluted weighted average includes the vested portion of the deferred units issued pursuant to the deferred unit plan.
Operational Highlights For the three months ended December 31, 2022, net income and comprehensive income (as noted in the table above) decreased by $551.8 million as compared to the same period in 2021. This decrease was primarily attributed to the following:
$568.7 million decrease in fair value adjustments on revaluation of investment properties, including adjustments relating to assets held for sale, primarily due to increase in fair value of certain properties under development in Q4 2021 as a result of changes in the market and the progress made on planning entitlements (see details in the “Investment Property” section in the Trust’s MD&A); and
$7.2 million increase in interest expense (see further details in the “Interest Income and Interest Expense” subsection in the Trust’s MD&A);
Partially offset by the following:
$10.9 million increase in fair value adjustment on financial instruments primarily due to fluctuations in the Trust’s Unit price;
$4.1 million increase in interest income mainly due to higher interest rates;
$3.9 million increase in NOI (see further details in the “Net Operating Income” subsection in the Trust’s MD&A);
$2.8 million decrease in acquisition-related costs related to the SmartVMC West acquisition in 2021; and
$1.4 million decrease in general and administrative expenses (net) (see further details in the “General and Administrative Expense” section in the Trust’s MD&A).
For the year ended December 31, 2022, net income and comprehensive income (as noted in the table above) decreased by $351.7 million as compared to the same period in 2021. This decrease was primarily attributed to the following:
$476.8 million decrease in fair value adjustments on revaluation of investment properties primarily due to increase in fair value of certain properties under development in Q4 2021 as a result of changes in the market and the progress made on planning entitlements (see details in the “Investment Property” section in the Trust’s MD&A);
$6.5 million increase in interest expense (see further details in the “Interest Income and Interest Expense” section in the Trust’s MD&A); and
$2.8 million increase in supplemental costs and in general and administrative expenses (net) (see further details in the “General and Administrative Expense” section in the Trust’s MD&A);
Partially offset by the following:
$125.5 million increase in fair value adjustment on financial instruments primarily due to fluctuations in the Trust’s Unit price and increase in fair value adjustments pertaining to interest rate swap agreements due to fluctuation in the interest rate (see further details in the “Debt” subsection in the Trust’s MD&A);
$6.1 million increase in interest income mainly due to higher interest rates; and
$2.5 million decrease in acquisition-related costs related to the SmartVMC West acquisition in 2021.
Development and Intensification Summary The following table summarizes the 274 identified mixed-use, recurring rental income and development income initiatives, which are included in the Trust’s large development pipeline:
Description
Under Construction
Construction expected to commence within next 2 years
Active (Construction expected to commence within next 3–5 years)
Future (Construction expected to commence after 5 years)
Total
Number of projects in which the Trust has an ownership interest
Residential Rental
3
22
24
61
110
Seniors’ Housing
1
3
7
14
25
Self-storage
3
7
8
15
33
Office Buildings / Industrial
1
—
1
6
8
Hotels
—
—
—
3
3
Subtotal – Recurring rental income initiatives
8
32
40
99
179
Condominium developments
2
15
25
46
88
Townhome developments
1
1
2
3
7
Subtotal –Development income initiatives
3
16
27
49
95
Total
11
48
67
148
274
Trust’s share of project area (in thousands of sq. ft.)
Recurring rental income initiatives
1,000
4,450
4,300
12,500
22,250
Development income initiatives
400
3,650
4,700
10,200
18,950
Total Trust’s share of project area (in thousands of sq. ft.)
1,400
8,100
9,000
22,700
41,200
Trust’s share of such estimated costs (in millions of dollars)
550
4,450
5,000
– (1)
10,000
(1) The Trust has not fully determined the costs attributable to future projects expected to commence after five years and as such they are not included in this table.
The following table provides additional details on the Trust’s 11 development initiatives that are currently under construction (in order of estimated initial occupancy/closing date):
Projects under construction (Location/Project Name)
Total Capital Spend To Date at 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (3)
755.2
Estimated Cost to Complete at 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
487.8
Total Expected Capital Spend by Completion at 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (3)
1,243.0
Total Capital Spend To Date at Trust’s share (3)
304.1
Estimated Cost to Complete at Trust’s share
234.9
Total Expected Capital Spend by Completion at Trust’s share (3)
539.0
(1) Figure represents capital spend of both retirement residence and senior apartments projects. (2) GFA represents Gross Floor Area. (3) Total capital spent to date and total expected capital spend by completion include land value.
Reconciliations of Non-GAAP Measures
The following tables reconcile the non-GAAP measures to the most comparable GAAP measures for the three months and year ended December 31, 2022 and the comparable periods in 2021. Such measures do not have a standardized meaning prescribed by IFRS and may not be comparable to similar measures disclosed by other issuers.
Proportionately Consolidated Balance Sheets (including the Trust’s interests in equity accounted investments)
The following table presents the proportionately consolidated balance sheets, which includes a reconciliation of the Trust’s proportionate share of equity accounted investments:
(in thousands of dollars)
Year Ended December 31, 2022
Year Ended December 31, 2021
GAAP Basis
Proportionate Share Reconciliation (1)
Total Proportionate Share(2)
GAAP Basis
Proportionate Share Reconciliation (1)
Total Proportionate Share(2)
Assets
Non-current assets
Investment properties
10,208,071
957,354
11,165,425
9,847,078
837,451
10,684,529
Equity accounted investments
680,999
(680,999
)
—
654,442
(654,442
)
—
Mortgages, loans and notes receivable
238,099
(76,994
)
161,105
345,089
(69,576
)
275,513
Other financial assets
171,807
—
171,807
97,148
—
97,148
Other assets
83,230
8,977
92,207
80,940
7,465
88,405
Intangible assets
43,807
—
43,807
45,139
—
45,139
11,426,013
208,338
11,634,351
11,069,836
120,898
11,190,734
Current assets
Assets held for sale
42,321
16,050
58,371
—
—
—
Residential development inventory
40,373
113,207
153,580
27,399
67,828
95,227
Current portion of mortgages, loans and notes receivable
86,593
—
86,593
71,947
—
71,947
Amounts receivable and other
57,124
(7,033
)
50,091
49,542
(8,637
)
40,905
Prepaid expenses, deposits and deferred financing costs
14,474
15,807
30,281
12,289
13,118
25,407
Cash and cash equivalents
35,255
35,419
70,674
62,235
7,922
70,157
276,140
173,450
449,590
223,412
80,231
303,643
Total assets
11,702,153
381,788
12,083,941
11,293,248
201,129
11,494,377
Liabilities
Non-current liabilities
Debt
4,523,987
212,928
4,736,915
4,176,121
93,465
4,269,586
Other financial liabilities
277,400
—
277,400
326,085
—
326,085
Other payables
17,265
—
17,265
18,243
—
18,243
4,818,652
212,928
5,031,580
4,520,449
93,465
4,613,914
Current liabilities
Current portion of debt
459,278
63,860
523,138
678,406
35,086
713,492
Accounts payable and current portion of other payables
261,122
105,000
366,122
253,078
72,578
325,656
720,400
168,860
889,260
931,484
107,664
1,039,148
Total liabilities
5,539,052
381,788
5,920,840
5,451,933
201,129
5,653,062
Equity
Trust Unit equity
5,126,197
—
5,126,197
4,877,961
—
4,877,961
Non-controlling interests
1,036,904
—
1,036,904
963,354
—
963,354
6,163,101
—
6,163,101
5,841,315
—
5,841,315
Total liabilities and equity
11,702,153
381,788
12,083,941
11,293,248
201,129
11,494,377
(1) Represents the Trust’s proportionate share of assets and liabilities in equity accounted investments. (2) This column contains non-GAAP measures because it includes figures that are recorded in equity accounted investments. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release.
Proportionately Consolidated Statements of Income and Comprehensive Income (including the Trust’s Interests in Equity Accounted Investments) The following tables present the proportionately consolidated statements of income and comprehensive income, which include a reconciliation of the Trust’s proportionate share of equity accounted investments:
Quarterly Comparison to Prior Year
Three Months Ended
Three Months Ended
(in thousands of dollars)
December 31, 2022
December 31, 2021
GAAP Basis
Proportionate Share Reconciliation
Total Proportionate Share(1)
GAAP Basis
Proportionate Share Reconciliation
Total Proportionate Share(1)
Variance of Total Proportionate Share(1)
Net rental income and other
Rentals from investment properties and other
206,223
8,441
214,664
192,850
5,974
198,824
15,840
Property operating costs and other
(77,062)
(3,779)
(80,841)
(65,896)
(3,144)
(69,040)
(11,801)
129,161
4,662
133,823
126,954
2,830
129,784
4,039
Condo and townhome closings revenue and other(2)
—
—
—
—
—
—
—
Condo and townhome cost of sales and other
(10)
(181)
(191)
—
(67)
(67)
(124)
(10)
(181)
(191)
—
(67)
(67)
(124)
NOI
129,151
4,481
133,632
126,954
2,763
129,717
3,915
Other income and expenses
General and administrative expense, net
(7,790)
—
(7,790)
(8,703)
(534)
(9,237)
1,447
Earnings from equity accounted investments
(113)
113
—
160,049
(160,049)
—
—
Fair value adjustment on revaluation of investment properties
13,377
(1,418)
11,959
420,418
160,289
580,707
(568,748)
Gain (loss) on sale of investment properties
531
—
531
(64)
—
(64)
595
Interest expense
(40,342)
(3,846)
(44,188)
(35,654)
(1,355)
(37,009)
(7,179)
Interest income
5,496
1,408
6,904
2,745
11
2,756
4,148
Supplemental costs
—
(738)
(738)
—
(1,125)
(1,125)
387
Fair value adjustment on financial instruments
—
—
—
(10,873)
—
(10,873)
10,873
Acquisition-related costs
—
—
—
(2,791)
—
(2,791)
2,791
Net income and comprehensive income
100,310
—
100,310
652,081
—
652,081
(551,771)
(1) This column contains non-GAAP measures because it includes figures that are recorded in equity accounted investments. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release. (2) Includes additional partnership profit and other revenues.
Year-to-Date Comparison to Prior Year
(in thousands of dollars)
Year Ended December 31, 2022
Year Ended December 31, 2021
GAAP Basis
Proportionate Share Reconciliation
Total Proportionate Share(1)
GAAP Basis
Proportionate Share Reconciliation
Total Proportionate Share(1)
Variance of Total Proportionate Share(1)
Net rental income and other
Rentals from investment properties and other
804,598
28,643
833,241
780,796
21,530
802,326
30,915
Property operating costs and other
(301,559)
(13,467)
(315,026)
(294,956)
(9,719)
(304,675)
(10,351)
503,039
15,176
518,215
485,840
11,811
497,651
20,564
Condo and townhome closings revenue and other(2)
—
4,524
4,524
—
76,837
76,837
(72,313)
Condo and townhome cost of sales and other
(435)
(3,784)
(4,219)
—
(56,366)
(56,366)
52,147
(435)
740
305
—
20,471
20,471
(20,166)
NOI
502,604
15,916
518,520
485,840
32,282
518,122
398
Other income and expenses
General and administrative expense, net
(33,269)
(107)
(33,376)
(31,922)
(610)
(32,532)
(844)
Earnings from equity accounted investments
4,199
(4,199)
—
211,420
(211,420)
—
—
Fair value adjustment on revaluation of investment properties
201,834
624
202,458
491,528
187,728
679,256
(476,798)
Gain (loss) on sale of investment properties
315
(241)
74
27
—
27
47
Interest expense
(148,702)
(7,798)
(156,500)
(144,540)
(5,437)
(149,977)
(6,523)
Interest income
18,036
453
18,489
12,341
75
12,416
6,073
Supplemental costs
—
(4,648)
(4,648)
—
(2,618)
(2,618)
(2,030)
Fair value adjustment on financial instruments
91,246
—
91,246
(34,227)
—
(34,227)
125,473
Acquisition-related costs
(298)
—
(298)
(2,791)
—
(2,791)
2,493
Net income and comprehensive income
635,965
—
635,965
987,676
—
987,676
(351,711)
(1) This column contains non-GAAP measures because it includes figures that are recorded in equity accounted investments. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release. (2) Includes additional partnership profit and other revenues.
FFO, FFO with adjustments, and FFO with adjustments and Transactional FFO
The following tables reconciles net income and comprehensive income to FFO, FFO with adjustments, and FFO with adjustments and Transactional FFO:
Quarterly Comparison to Prior Year
Three Months Ended
Three Months Ended
(in thousands of dollars, except per Unit amounts)
Indirect interest with respect to the development portion(4)
1,935
1,926
9
0.5
Fair value adjustment on revaluation of investment properties
1,418
(160,289
)
161,707
N/R(7)
Adjustment for supplemental costs
738
1,125
(387
)
(34.4
)
FFO(5)
102,471
97,452
5,019
5.2
Other non-recurring adjustments(6)
(1,910
)
660
(2,570
)
N/R(7)
FFO with adjustments(5)
100,561
98,112
2,449
2.5
Transactional FFO – gain on sale of land to co-owners
7,662
336
7,326
N/R(7)
FFO with adjustments and Transactional FFO(5)
108,223
98,448
9,775
9.9
(1) Fair value adjustment on revaluation of investment properties is described in “Investment Properties” in the Trust’s MD&A. (2) Fair value adjustment on financial instruments comprises the following financial instruments: units classified as liabilities, Earnout options, deferred unit plan (“DUP”), equity incentive plan (“EIP”), long term incentive plan (“LTIP”), TRS, interest rate swap agreement(s), and loans receivable and Earnout options recorded in the same period in 2021. The significant assumptions made in determining the fair value and fair value adjustments for these financial instruments are more thoroughly described in the Trust’s consolidated financial statements for the year ended December 31, 2022. For details, please see discussion in “Results of Operations” in the Trust’s MD&A. (3) Salaries and related costs attributed to leasing activities of $1.5 million were incurred in the three months ended December 31, 2022 (three months ended December 31, 2021 – $1.1 million) and were eligible to be added back to FFO based on the definition of FFO, in the REALpac White Paper published in January 2022, which provided for an adjustment to incremental leasing expenses for the cost of salaried staff. This adjustment to FFO results in more comparability between Canadian publicly traded real estate entities that expensed their internal leasing departments and those that capitalized external leasing expenses. (4) Indirect interest is not capitalized to properties under development and residential development inventory of equity accounted investments under IFRS but is a permitted adjustment under REALpac’s definition of FFO. The amount is based on the total cost incurred with respect to the development portion of equity accounted investments multiplied by the Trust’s weighted average cost of debt. (5) Represents a non-GAAP measure. The Trust’s method of calculating non-GAAP measures may differ from other reporting issuers’ methods and, accordingly, may not be comparable. For additional information, please see “Non-GAAP Measures” in this Press Release. (6) Represents adjustments relating to $1.9 million of reversal of costs associated with COVID-19 vaccination centres (three months ended December 31, 2021 – $0.7 million of costs associated with COVID-19 vaccination centres). (7) N/R – Not representative.
Year-to-Date Comparison to Prior Year
(in thousands of dollars, except per Unit amounts)
If you like to observe gardening trends, incorporate the “plants of the year” to your backyard garden. The Nationwide Backyard Bureau (NGB) is a non-income organization with a mission to “Inspire, Connect, Mature,” motivating gardeners and giving inspiration and education. The NGB has named these “Plants of the Year” for 2023.
The Calendar year of the Orchid: The NGB first extra houseplants to its once-a-year record in 2022. Orchids are this year’s houseplant option. They have a status of staying tough, but they definitely are not. The simplest wide range to expand and a fantastic preference for the novice is the moth orchid. Bouquets on moth orchids fluctuate in color and very last a very long time. Orchids favor filtered light-weight and moderate watering.
The 12 months of the Amaryllis: A person of the most recognizable bulbs, the amaryllis is a holiday getaway favorite. Extra than 600 versions, these crops occur in a variety of colours and flower styles. Quite a few amaryllis bulbs come inside of “kits” that involve the bulb, soil, and the pot. If you choose to obtain just a bulb, use a great potting combine and place the bulb with the major third exposed. Drinking water when until there’s development and then drinking water sparingly immediately after that.
The Yr of the Celosia: There are so a lot of unique kinds, heights, and shades, you can use this once-a-year flower any where, even containers. The term “celosia” comes from the Greek term “kelos,” this means “burned” which refers to the bouquets that essentially resemble flames. These bouquets like a sunny location wherever they’ll give your backyard garden the “wow” element for absolutely sure!
The Year of the Spirea: These shrubs have been a staple in the landscape for many years. They boast a range of colorful foliage and beautiful flowers. These quick-growing shrubs are so easy to grow and will tolerate lousy soil, drought, warmth, and chilly. They appear their most effective in full sunshine and prefer nicely-drained soil.
The Year of the Rudbeckia: This perennial, which incorporates the black-eyed Susan, is a need to-have for late summer months shade. It is no question this plant was chosen considering the fact that it is a pollinator magnet and is so quick to grow. These crops require comprehensive sunshine, moderate but consistent soil humidity, and nicely drained soil. They execute their ideal and make the most bouquets if the clumps are divided each individual a few to four several years.
The Yr of the Broccoli: This vegetable will come from the Mediterranean area and has been appreciated considering the fact that Roman instances. It is deemed a super foodstuff simply because it is so substantial in dietary worth. All sections of the plant are edible. It is considered a great season vegetable, escalating the very best in amazing temperatures of spring and slide. Crops desire fantastic drainage and whole sunshine. You can buy transplants for immediate planting in the floor or commence seeds indoors about six months just before the final frost date. Seek the advice of the seed package for more information or take a look at the vegetable gardening segment on our web-site at https://cceoneida.com/property-backyard garden/foods-gardening.
If you would like to read far more about these and other crops suggested by the Nationwide Backyard garden Bureau, check out their web site at ngb.org.
Cornell Cooperative Extension Oneida County responses house and backyard questions which can be emailed to homeandgarden@cornell.edu or simply call 315-736-3394, press 1 and ext. 333. Go away your dilemma, title and cell phone number. Issues are answered weekdays, 8 a.m. to 4 p.m.
Also, visit our web-site at: cceoneida.com or cellular phone 315-736-3394, press 1 and then ext. 100.
Authentic estate agents verify what housing details is starting to exhibit: Much more homebuyers are rising from their self-imposed hibernation.
The volume of mortgage loan apps for dwelling buys rose 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} week over week, the House loan Bankers Affiliation (MBA) survey for the week ending Jan. 13 identified. Housing sentiment ticked bigger at the finish of last year, for each Fannie Mae. And household builders are reporting an raise in consumer website traffic in January, the first uptick since December 2021, according to an market survey.
These buyers are hoping to enjoy the benefits from a a lot more favorable market place, bagging vendor incentives along with a marginally lessen mortgage loan price, ahead of the spring-shopping for season draws in a lot more level of competition.
“I experienced one particular of my consumers at Meta and yet another from Microsoft who have been active up until September of previous yr access out to me past weekend,” Jeff Reynolds, a broker at Compass and founder of UrbanCondoSpaces.com, explained to Yahoo Finance. “They had wanted to see what the current market would do, and because it looks to have stabilized and costs are down, they are hoping to get a move ahead of what would inevitably be a true estate bottom.”
Dwelling sellers are extra likely to offer potential buyers concessions, a Redfin report observed. At minimum 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of households sold through the fourth quarter of 2022 provided an incentive. (Credit history: Getty Artistic).
‘Bringing people back again in’
The dip in home loan fees in recent weeks has taken some of the edge off of the document-setting ascent costs clocked in previous year. Past 7 days, the ordinary rate on the 30-year fastened mortgage — the most generally applied property personal loan for a invest in — settled closer to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} than 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, fitting into extra buyers’ budgets.
“Interest costs are greater for initially-time customers. I consider naturally it’s just bringing folks back again in,” John Downs, senior vice president at Vellum Property finance loan, instructed Yahoo Finance.
At the similar time, dwelling selling prices have also softened, with the median record rate falling to $400,000 in December, in accordance to Redfin, down 11.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from June’s peak of $449,000.
“The vast majority of exercise is from new purchasers,” Reynolds said. “In our microclimate in downtown Seattle, the the vast majority of action has strike definitely reasonably priced cost details. That’s pushed primarily by that millennial buyer, that younger consumer, or initial-time purchaser eventually taking benefit of market place disorders — probably for the to start with time.”
‘Picking for deals’
The buyers who are coming back again are also finding gutsy, knowing that the sellers who continue being in the sector are open to negotiation.
“In 2022, prospective buyers set the market by bidding up, which led to escalating price ranges and primarily possessing to spend to acquire,” Downs reported. “Now, rather of waiting for listing rates to drop, customers submit features with major bargains and make the vendor make a selection. And that seems to be performing.”
At the very least 16.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homes bought in December experienced a selling price slice, Real estate agent.com info found, an increase from 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a 12 months ago. Even home builders are squishy on cost.
A person of Monte Miner’s shoppers obtained $15,000 off a recently created household initially priced at $409,000, in accordance to the serious estate agent at Ironwood Fantastic Homes in Arizona.
Rick Nazarro of Colonial Manor Realty talks with a pair of interested customers in the driveway as a few waits to enter a residence he is hoping to provide in the course of an open up residence in Revere, MA. (Credit: Blake Nissen for The Boston World by using Getty Pictures)
“Buyers are coming back again, but they are choosing for offers. Let’s say a household is listed for $400,000 — a whole lot of the provides coming in are below that range,” Miner mentioned. “Some sellers’ pricing anticipations are trapped in the earlier, like three months in the past. It’s various now.”
Not only are some people receiving large cost reductions, they are also snagging vendor concessions to further ease the stress of nevertheless-significant residence prices.
For instance, at least 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders reduced their dwelling rates in December, information from the Countrywide Affiliation of Homebuilders identified. A further 62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders continued to use incentives to catch the attention of customers, like charge invest in-downs and shelling out factors. According to Redfin, about 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of properties marketed in the closing three months of 2022 incorporated a vendor concession, these types of as funds for repairs or closing expenditures.
“If you don’t have not enough dollars for closing expenses,” Downs said, “sellers are supplying to fork out it for you,”
A indication is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit: Mario Tama/Getty Images)
Timing is anything
With rates finally inching down, now could be an opportune time to invest in a property prior to the spring season is in entire swing, Downs explained. But you need to be well prepared. Having a pre-qualification completely ready, setting a spending budget, and conversing to a authentic estate specialist can raise your chances of negotiating a far better deal at closing.
According to Miner, stepping into the marketplace just before it will get flooded by competitiveness could be a excellent go if you want to negotiate terms.
“From what I’m looking at,” Miner explained, “I sense like the bottom is right here.”
Gabriella is a personalized finance reporter at Yahoo Finance. Stick to her on Twitter @__gabriellacruz.
Click right here for the newest financial news and economic indicators to assistance you in your investing decisions
Examine the most current economical and company news from Yahoo Finance
Download the Yahoo Finance application for Apple or Android
We’ve read with interest on your advice columns, and we especially appreciate the effort and detail put into the responses.
My wife and I are in a bit of a dilemma.
We live in a 3-room HDB flat in Clementi Ridges which we bought for close to $400k. Our MOP is up in April this year. We’re in our mid-30s and together we make $15,000 gross a month, with no debts other than our HDB loan. We don’t plan to have kids.
Our goal is to have a retirement nest egg; the question is how best to go about building it. We’re not sure if our next move should be to:
(1) Upgrade to a freehold condo – we’re only interested in one located in Districts 9, 10, 11, 20, or 21;
(2) Save up to buy an additional investment property; or
(3) Upgrade to a larger HDB through resale/2nd BTO.
Sincerely hoping you could share some insights to help in our decision-making. Thank you very much!
1) Outstanding loan – $238,000
2) CPF used plus accrued interest – $128,000 from me + $36,000 from my wife
Hi there!
Thanks for reaching out to us!
It’s always good to start the retirement planning process early, as there is a lot you can do to build that nest egg from now till then. With so many possible pathways to take, it can be difficult to decide on the best option.
We will do our best to shed some light on the possibilities and hopefully, it will make your decision-making process a little easier. Let’s start by looking at affordability.
Affordability
These are some of the recent 3-room transactions for Clementi Ridges:
Date
Block
Level
Size (sqm)
Price
Oct 2022
312B
19 to 21
69
$615,000
Sep 2022
312A
19 to 21
69
$660,000
Sep 2022
312B
16 to 18
69
$660,000
Aug 2022
312A
13 to 15
69
$608,000
Jul 2022
312A
13 to 15
69
$565,000
Jul 2022
312A
13 to 15
69
$638,000
Jul 2022
312A
22 to 24
69
$642,800
Source: HDB
We will use the average selling price of $626,971 for calculation purposes.
Description
Amount
Selling price
$626,971
Outstanding loan
$238,000
CPF used plus accrued interest
$164,000
Cash proceeds
$224,971
Affordability (For a private property)
Description
Amount
Maximum loan based on a fixed monthly income of $15K and ages 35
$1,728,055 (30 years tenure)
CPF funds
$164,000
Cash
$224,971
Maximum affordability based on CPF and cash of $388,971
$1,555,884
BSD based on $1,555,884
$46,835
Estimated affordability
$1,509,049
Due to the available amount of CPF and cash that make up the 25per cent downpayment, you will not be able to take the maximum loan
Affordability (For an HDB)
Description
Amount
Maximum loan based on a fixed monthly income of $15K and ages 35
$852,536 (25 years tenure)
CPF funds
$164,000
Cash
$224,971
Total loan + CPF + Cash
$1,241,507
BSD based on
$34,260
Estimated affordability
$1,207,247
Option 1: Upgrade to a freehold condo in D9, 10, 11, 20 or 21
With a budget of $1.5 million, you’ll most likely be looking at a 1 + Study or a two-bedder in these locations. As you do not plan to have children, this should suffice but as most of these units are rather compact, it may take some getting used to from a 3-room HDB flat which is typically bigger in comparison.
If you were to do a quick search online, you’ll see that the current pickings are rather slim, and the majority of the developments that fall within this price range are boutique projects.
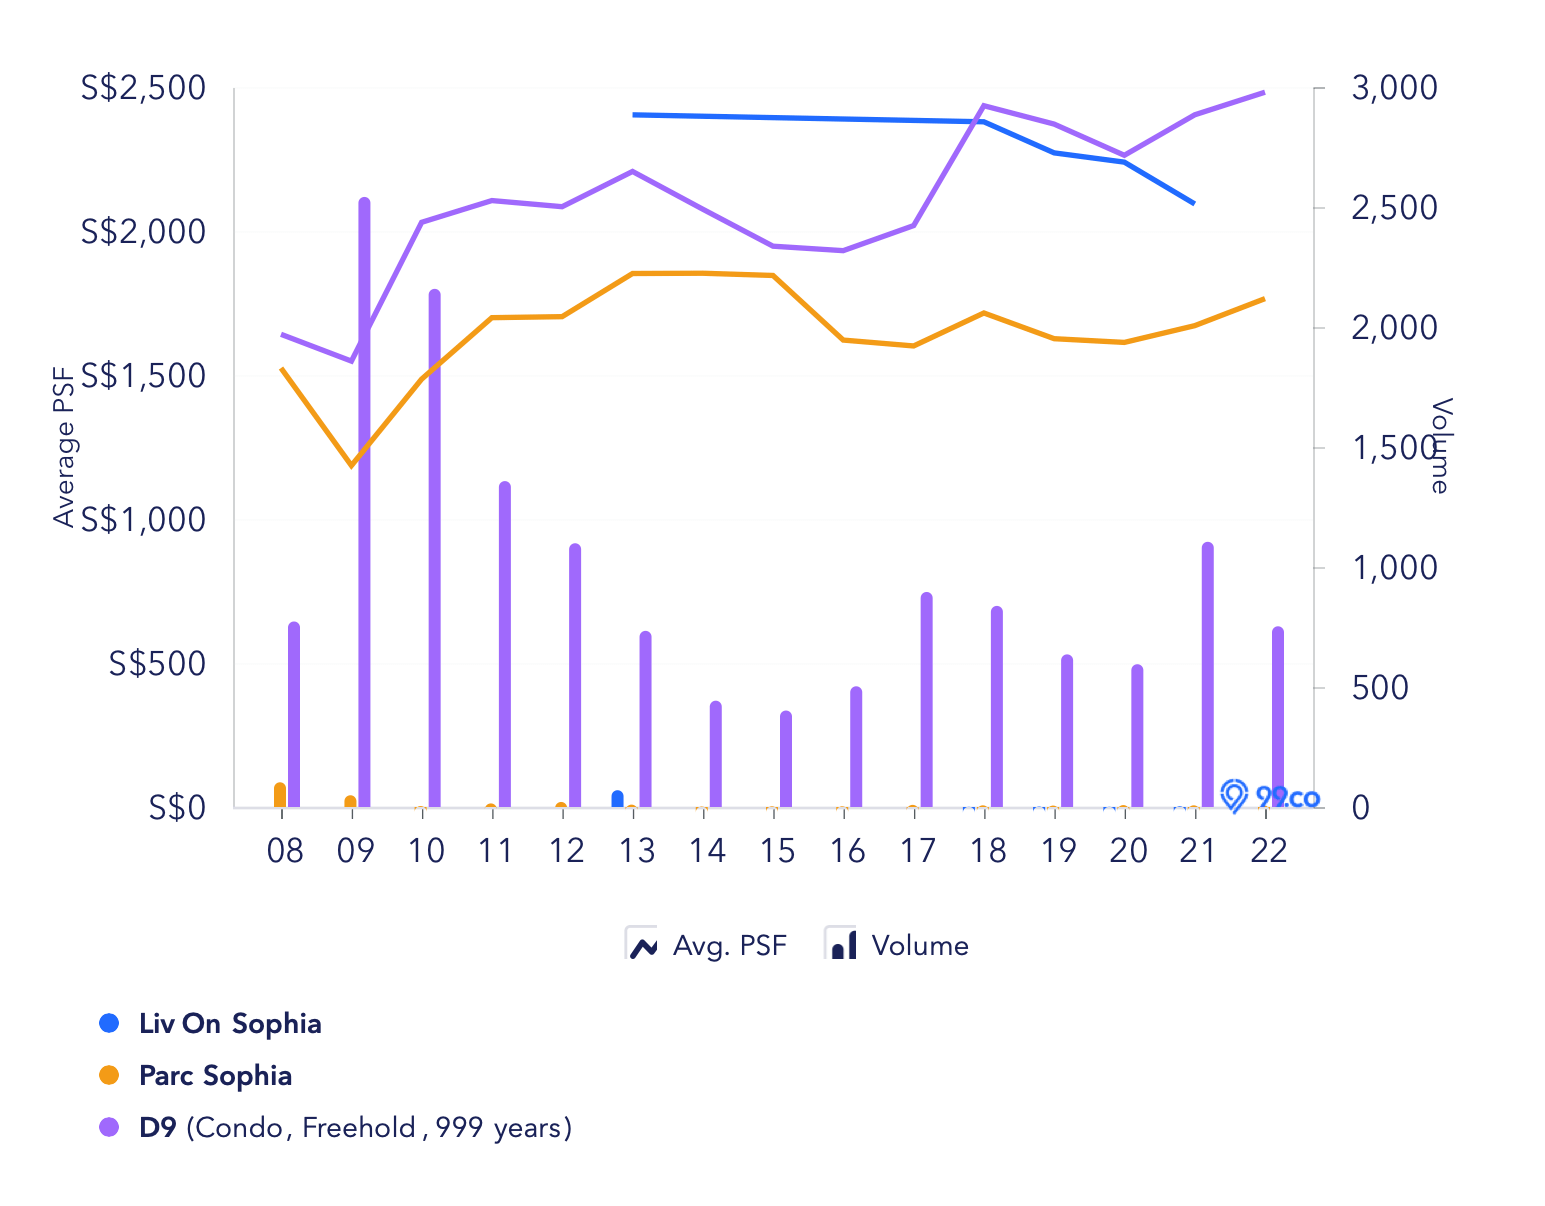
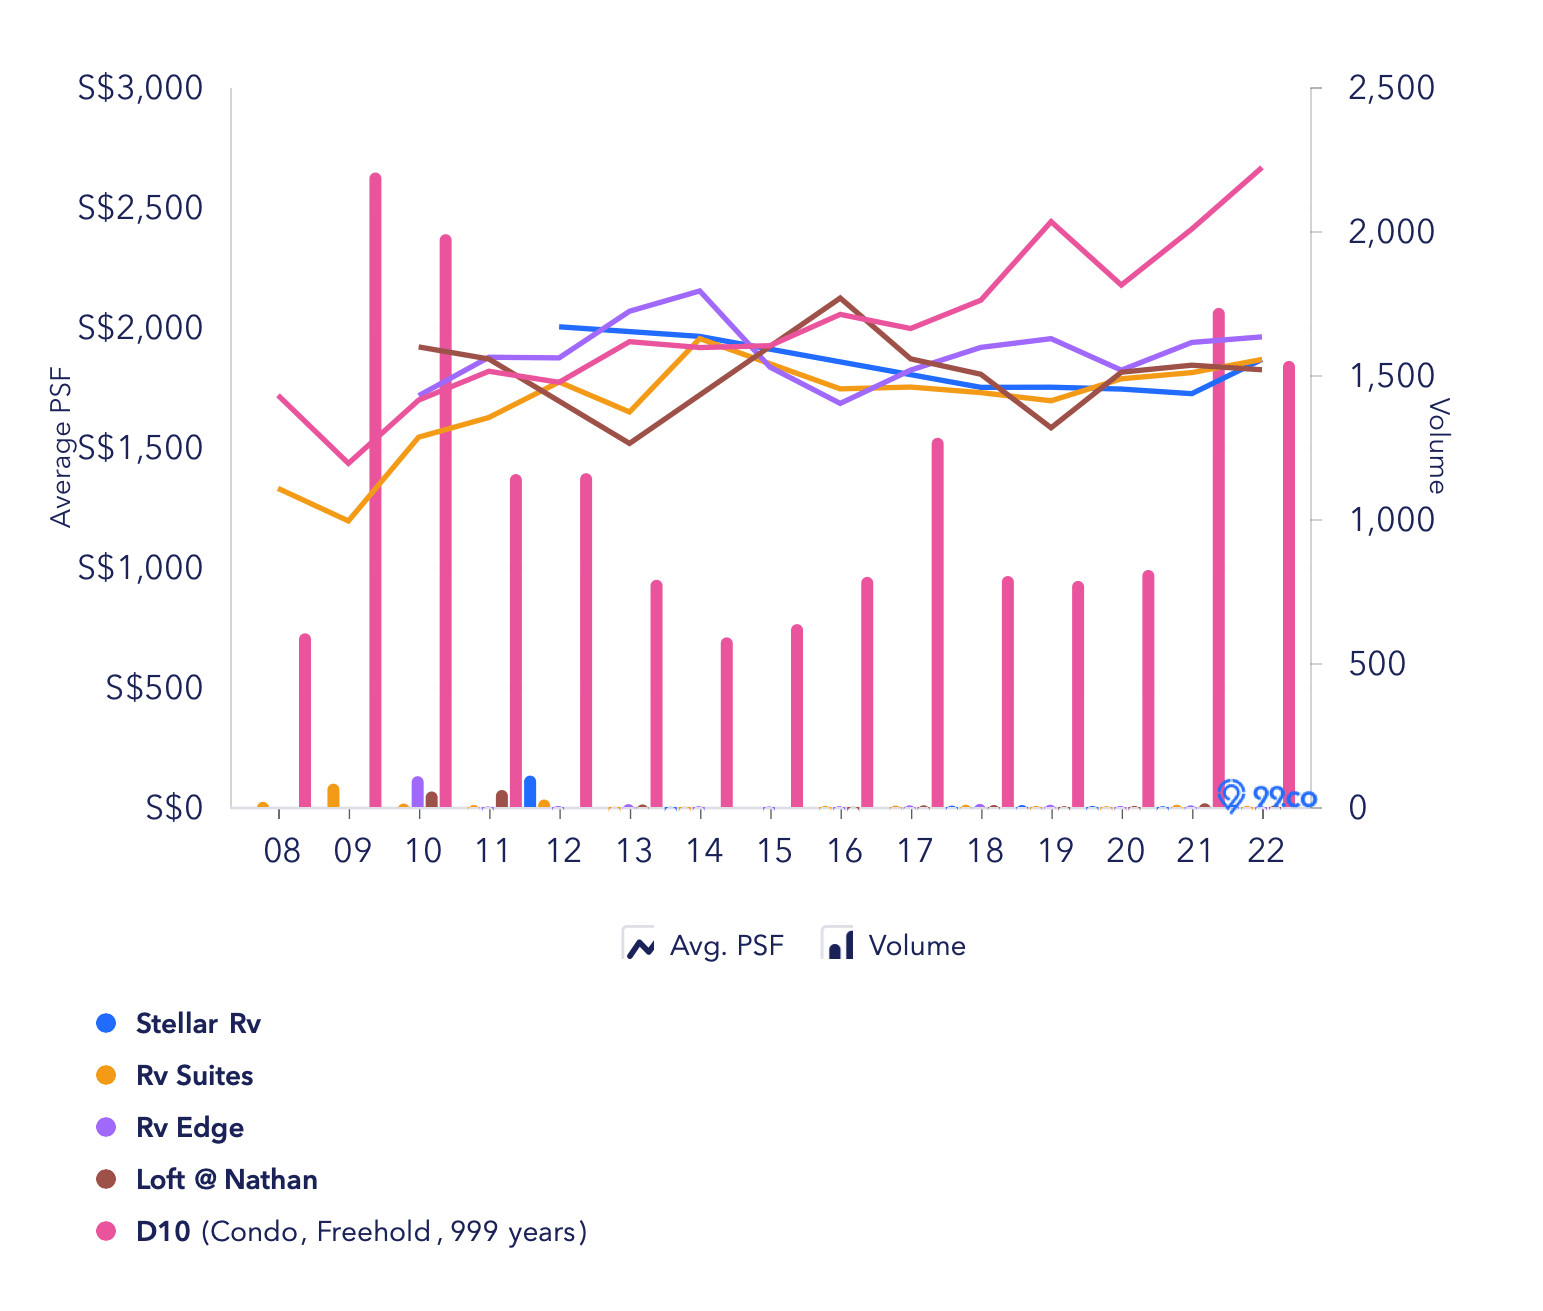
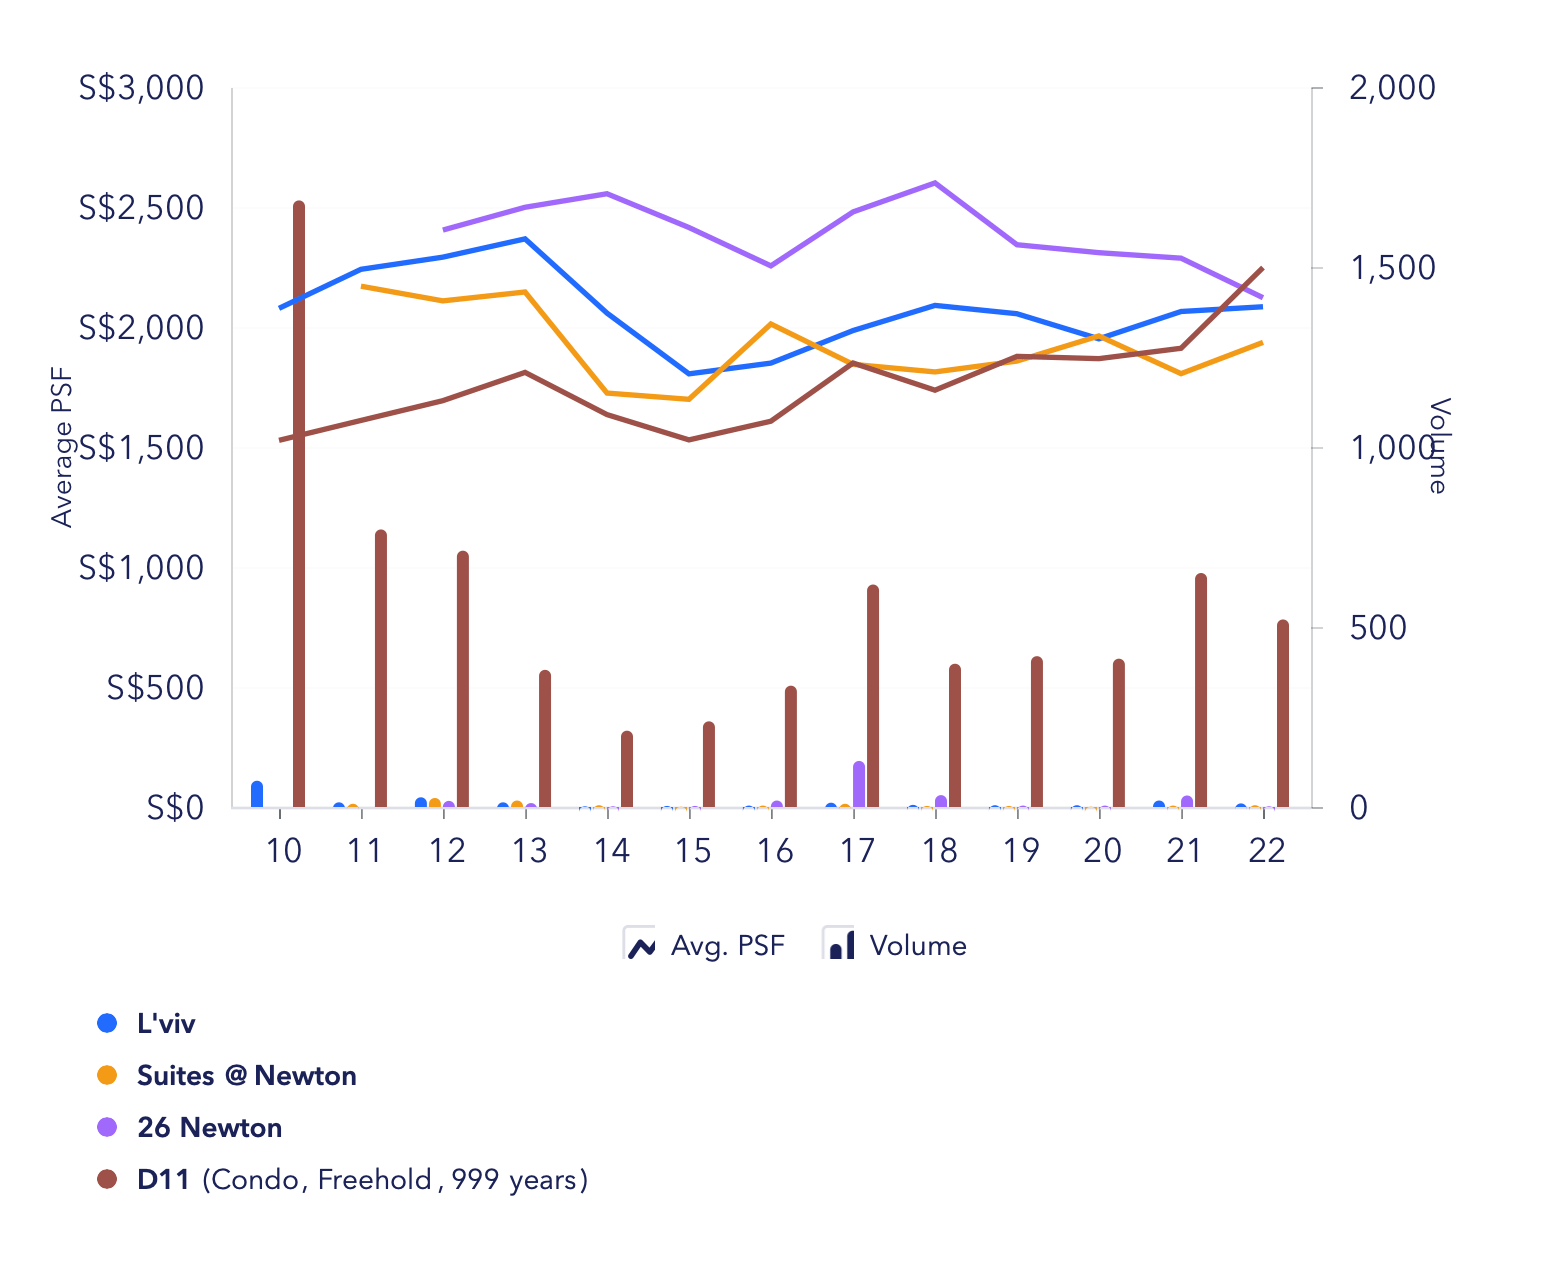
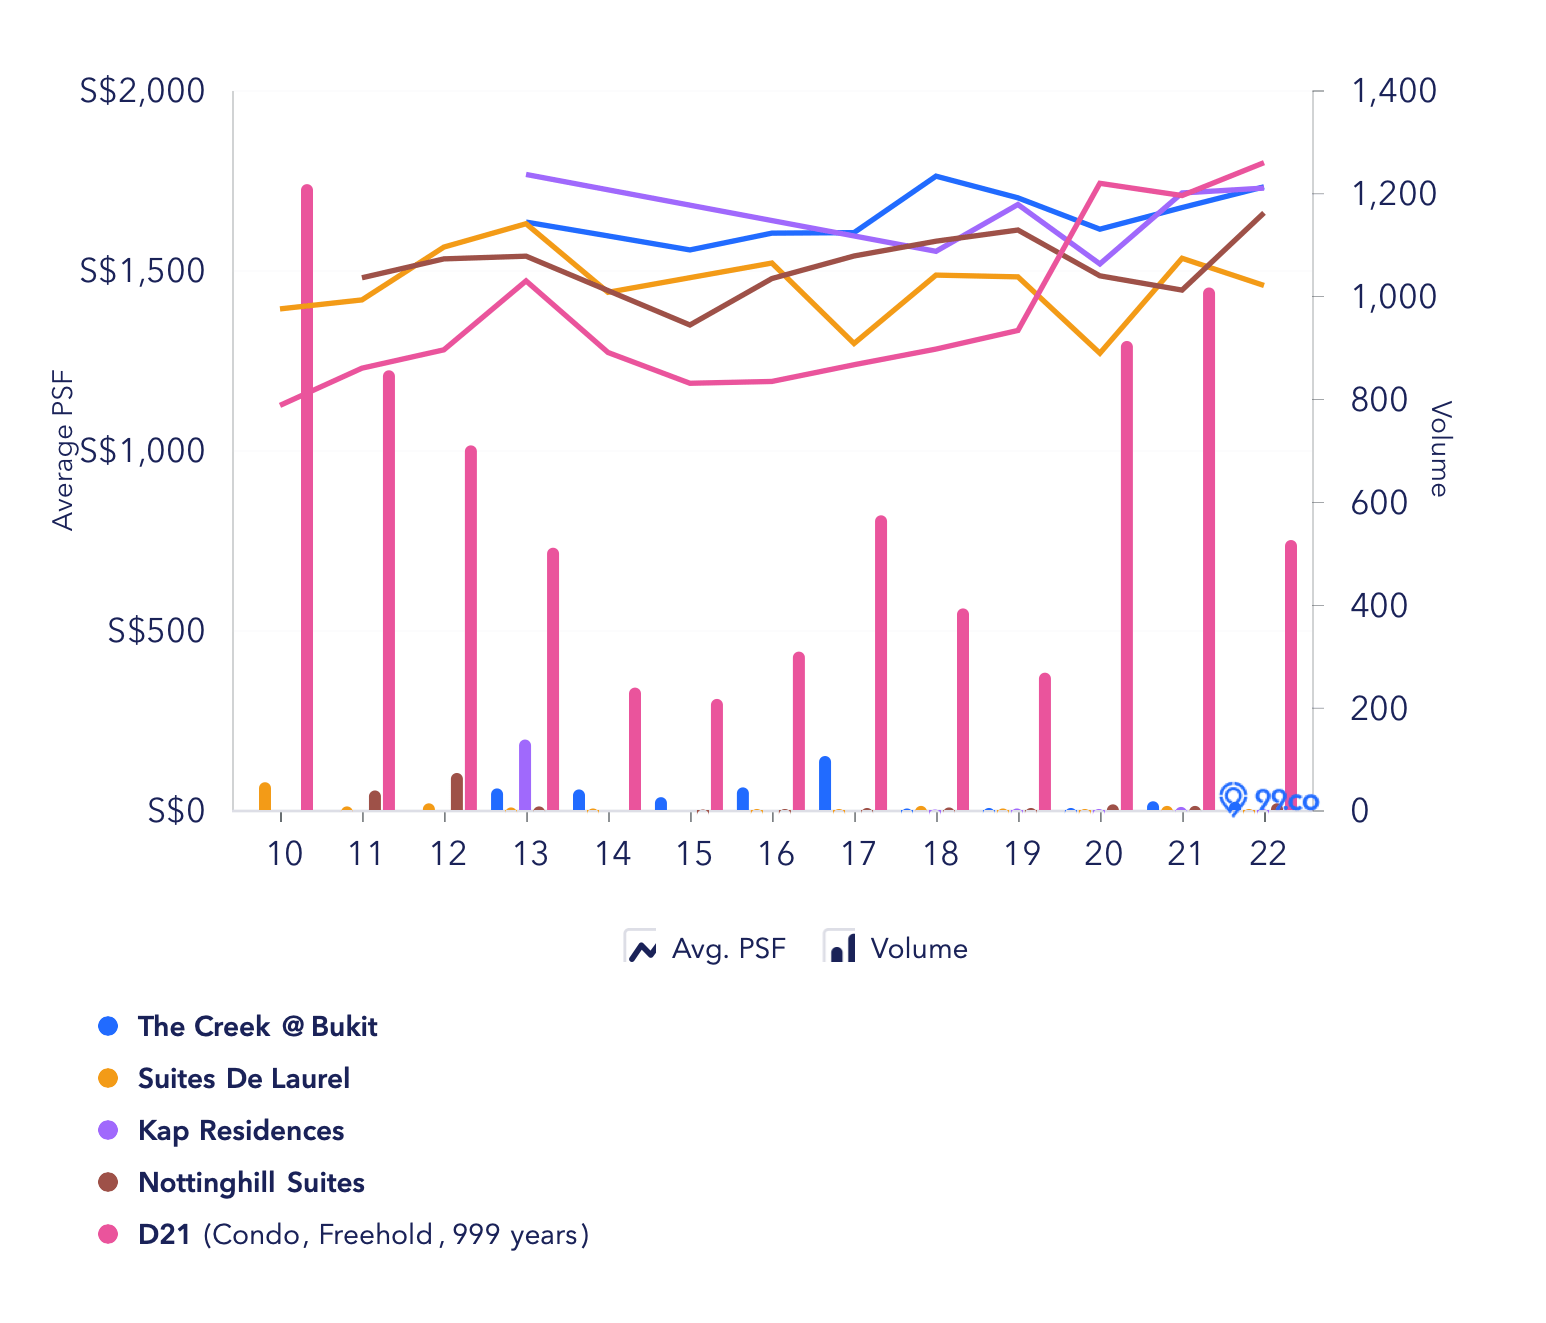
District 9 District 10 District 11 District 21
The developments shown above are those with available units that match your affordability. You’ll notice that after the launch, their transaction volumes are generally low, resulting in the trend lines appearing somewhat volatile. This is a usual concern with boutique developments because if the turnover rates are low, it is difficult for prices to move since banks value a property based on recent transactions. You can see from the graphs that prices are relatively stagnant for most of the projects, as compared to other freehold condos in the same district.
Also, many of these developments are made up of predominantly one and two- bedders which are catered more towards investors since the barriers to entry are lower. This is another issue as investors usually go wherever the money is, so if they find a better investment opportunity, they are less hesitant to let go of their units (even at a loss). This differs from genuine homeowners, who may be emotionally attached to their properties. It is advisable to get a development with a good unit mix, which caters to both homeowners as well as investors as prices are generally more protected.
Compared to an HDB flat, these projects are usually a better potential store of value. This is especially so in the long run as there is no lease decay issue. But if you’re looking for capital appreciation in the short to medium term, these may not be the best options.
That being said, we do believe there is potential for growth in the CCR provided you select the right properties.
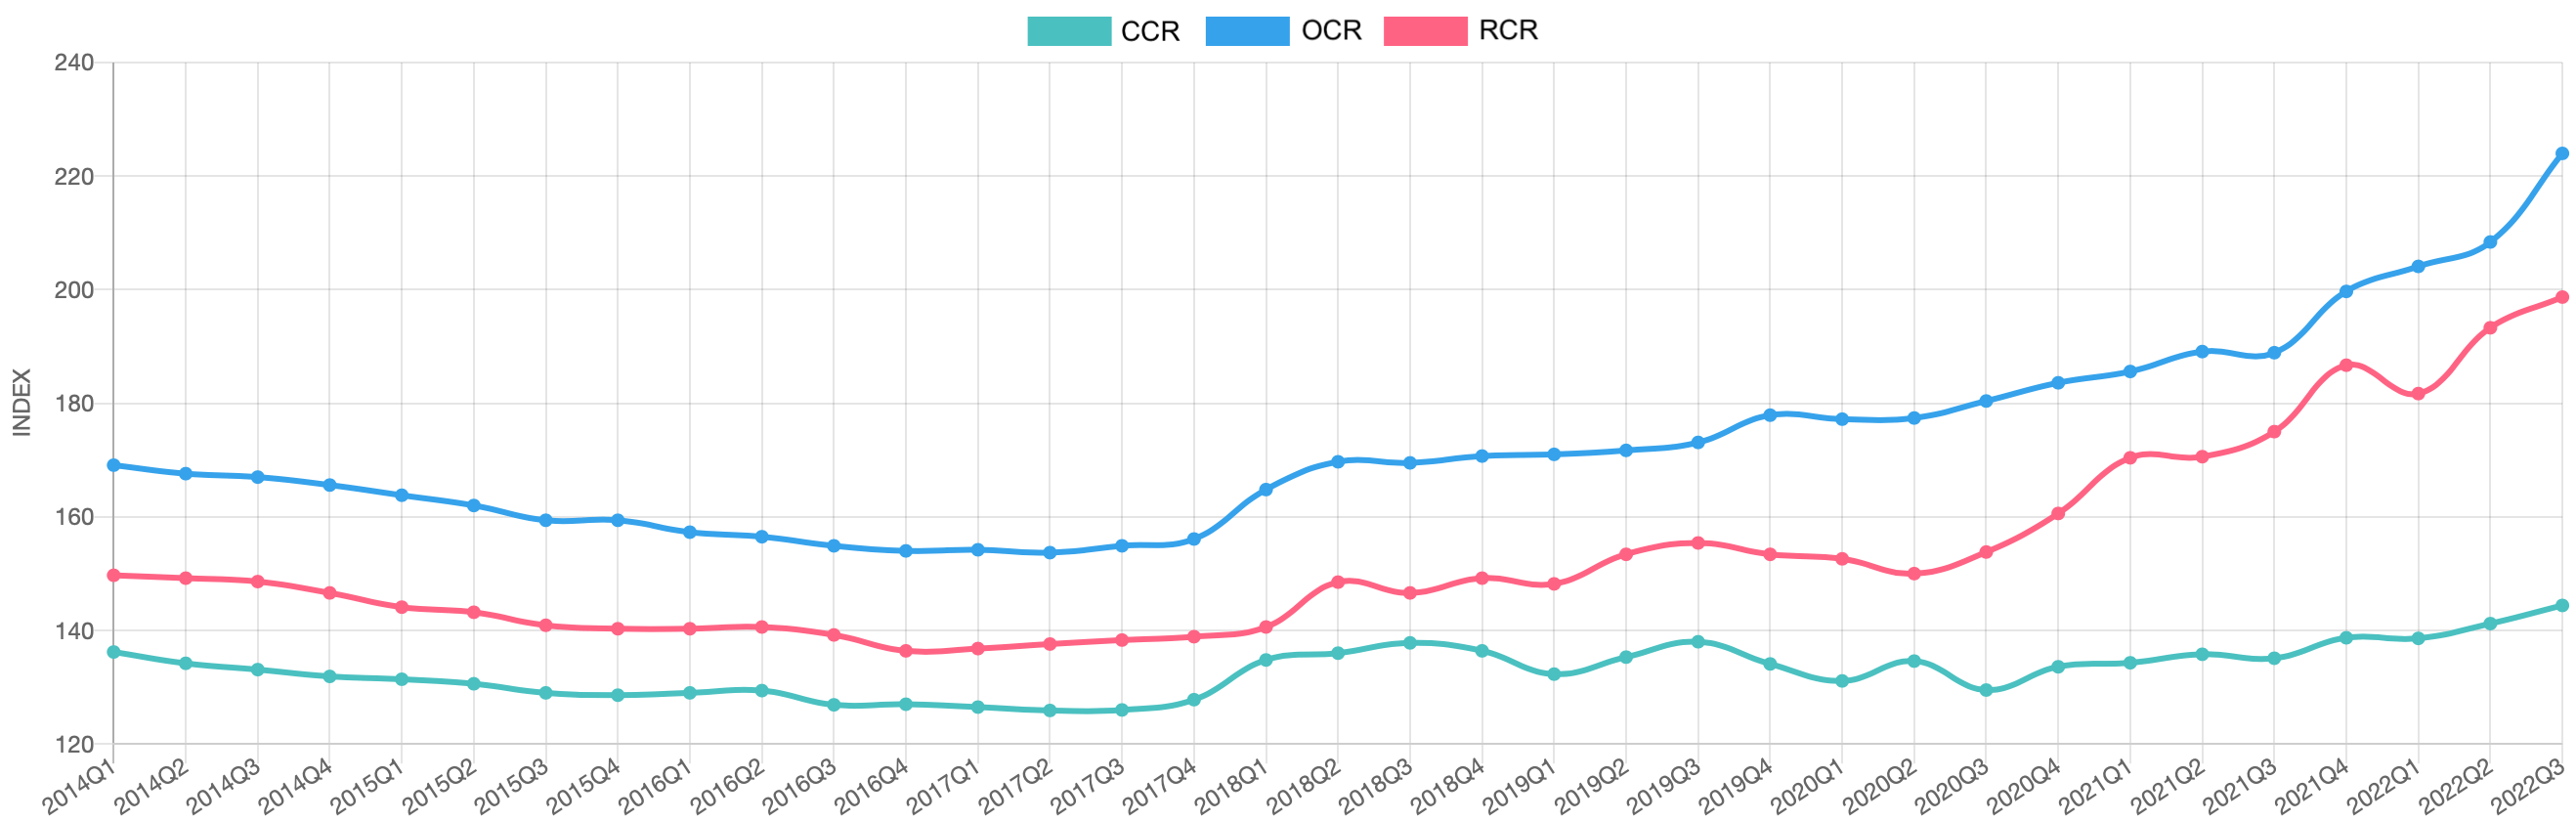
Property Price Index (PPI) of non-landed residential properties in the different regions
Price Indices
Q1 2021
Q2 2021
Q3 2021
Q4 2021
2021
Q1 2022
Q2 2022
Q3 2022
Q4 2022
2022 (Flash)
QoQper cent change
QoQper cent change
QoQper cent change
QoQper cent change
YoY per cent change
QoQper cent change
QoQper cent change
QoQper cent change
QoQper cent change
YoY per cent change
Overall PPI
3.3
0.8
1.1
5.0
10.6
0.7
3.5
3.8
0.2
8.4
Landed
6.7
-0.3
2.6
3.9
13.3
4.2
2.9
1.6
0.5
9.5
Non-landed
2.5
1.1
0.7
5.3
9.8
-0.3
3.6
4.4
0.1
8.0
CCR
0.5
1.1
-0.5
2.7
3.8
-0.1
1.9
2.3
0.5
4.6
RCR
6.1
0.1
2.6
6.7
16.3
-2.7
6.4
2.8
2.6
9.2
OCR
1.1
1.9
-0.1
5.7
8.8
2.2
2.1
7.5
-2.6
9.3
Source: URA, Propnex Research
Drawing from the Property Price Index (PPI) in the different regions, we can see that prices in the RCR and OCR have appreciated significantly more than in the CCR in recent years. We do expect that prices in the CCR will eventually right themselves and the growth rate will catch up. We have recently also written a piece about the narrowing gap between prices of new RCR and CCR projects, which you can read here.
If CCR prices pick up can we expect prices of these boutique developments to pick up too?
Option 2: Save up to buy an additional investment property
Given that you currently own a flat, which we assume is under both your names, and have an outstanding housing loan, there are several things to take into consideration when purchasing a second property.
Loan-To-Value ratio (LTV)
When purchasing your first property, depending on your income, you may be eligible to loan up to a maximum of 75 per cent of the property value (for a bank loan). However, if you’re purchasing a second property while still repaying an existing mortgage loan for the first one, the LTV drops to 45 per cent of the property value.
Higher downpayment
As the LTV for a second property is reduced, naturally the downpayment increases. The downpayment is split into two portions; minimally 25 per cent needs to be paid in cash and the remaining 30 per cent can be paid using your CPF should you have sufficient funds.
Additional Buyer Stamp Duty (ABSD)
The current ABSD rate for Singaporeans buying a second property is 17 per cent which is on top of the regular BSD. Do note that when purchasing a private property, the stamp duty has to be paid in cash first, as this has to be done within 14 days after you have exercised the Option to Purchase (which isn’t enough time to apply for the withdrawal from CPF), and if you have sufficient funds in your CPF to pay for it, the cash will be reimbursed to you afterward.
CPF requirements
When buying a second property, you will need to set aside the following before you can utilise your CPF funds for the purchase:
The latest Basic Retirement Sum (BRS) if you have at least one property bought using CPF or the property that you are buying can cover you till age 95*
The latest Full Retirement Sum (FRS) if you do not have any property that can cover you till age 95
* If you subsequently sell the property that can cover you till age 95, you will need to set aside the FRS instead.
Also, the maximum amount of CPF that can be used for your second property depends on whether the remaining lease of this property can cover the youngest owner up to the age of 95.
Source: CPF
Let’s say you were to purchase a second property at $1 million for the sake of simple calculations:
Description
Amount
Purchase price
$1,000,000
25per cent cash downpayment
$250,000
30per cent CPF/cash downpayment
$300,000
BSD
$24,600
ABSD of 17per cent
$170,000
As we can see from the calculations above, the cash outlay required in order to purchase a second property is pretty substantial and it will likely take a long time to save up.
We’ve written a detailed piece on the merits of paying for the ABSD for an investment property, but in short, it’s not what we’d typically recommend.
Option 3: Upgrade to a larger flat (resale/BTO)
Being able to buy a BTO is a Singaporean privilege, and since we have two chances at it, most individuals/households will try for the second time if they are eligible. Of course, it’s much tougher the second time around given that only two to five per cent of BTO launches are set aside for second-timers. Also, the income ceiling to apply for a BTO is $14,000 which your household has unfortunately (or fortunately) exceeded so you are no longer eligible.
As you’ve mentioned you’re looking to build your retirement nest, buying a flat may not be the best investment choice. It is no doubt a good stepping stone for buyers looking to upgrade since you’d likely make some profits if you bought a BTO, or if you purchased a resale and managed to gain from the CPF Housing Grants.
Source: Edgeprop
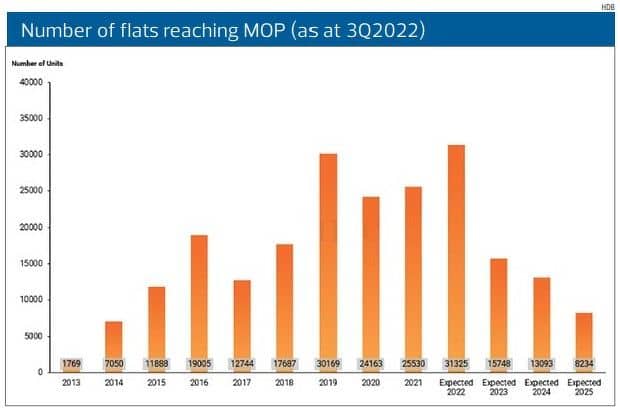
Given the reduced supply of newer MOP flats coming onto the resale market in the next couple of years, prices of HDB prices could still hold up in the short term. But even so, it is public housing after all; prices are regulated by the government in order to keep them affordable for the masses.
Alternative option
We’ve said this many times before, but a freehold property does not necessarily mean it’s better than a leasehold, and there are many other factors that contribute to the performance of a property besides its tenure. Perhaps instead of looking at freehold options in the districts you’ve identified, you can look at leasehold options instead, which will give you more choices to choose from. And if you were to open up to other locations, you’d have even more options.
These are some available 99-year leasehold units on the market that is within your affordability:
Project
District
Completion year
Unit type
Size
Asking price
Sophia Hills
09
2018
2b2b
689
$1,482,000
The Panorama
20
2019
2b2b
797
$1,488,888
Thomson Impressions
20
2019
2b2b
764
$1,500,000
Sky Vue
20
2017
2b2b
678
$1,380,000
Daintree Residences
21
2023
2b2b
679
$1,399,999
These projects are picked out based on the fact that they are in your preferred districts, and for their age, so they may or may not be the most suitable for you. We would suggest you consult with an agent for further analysis.
In the ideal situation, you’ll stay in this property for the short to medium term and if it does appreciate well over the next few year, you can then upgrade again; perhaps to a bigger unit or a freehold development, which you can then live in for the longer term. You can eventually cash out for your retirement while you right size to a smaller unit.
Conclusion
Let’s do a quick recap of the options:
For the first option of buying a freehold condominium in District 9, 10, 11, 20, or 21, your choices are rather limited and the available developments are mostly boutique projects (which as mentioned, we do have some concerns over). You will have to pick carefully, as a freehold property definitely doesn’t always mean it will be a good investment.
The second option of saving up to purchase a second property for investment will require a huge cash outlay, which may take a considerable amount of time to save up for.
As for the last option of upgrading to a bigger HDB, unfortunately, your household is no longer eligible to apply for a second BTO due to your income. Regardless, buying an HDB is not the best investment tool given that it is after all a regulated market.
We will suggest looking at some younger leasehold developments that still have the potential for growth which will open you up to more choices. You can stay in this property while you wait for it to appreciate and from there, move on to a bigger unit or a freehold development where you can stay for the long term. As you’re only in your mid-30s, you’re able to maximise the loan tenure. We get that moving might be a pain, but it’s inevitable if you wish to cash out on your property which will go towards building your retirement nest.
ALSO READ: We make $15k per month and live in a 4-room HDB flat. Should we upgrade to a condo now once interest rates drop?




 District 9
 District 10
 District 11
 District 21
 Property Price Index (PPI) of non-landed residential properties in the different regions
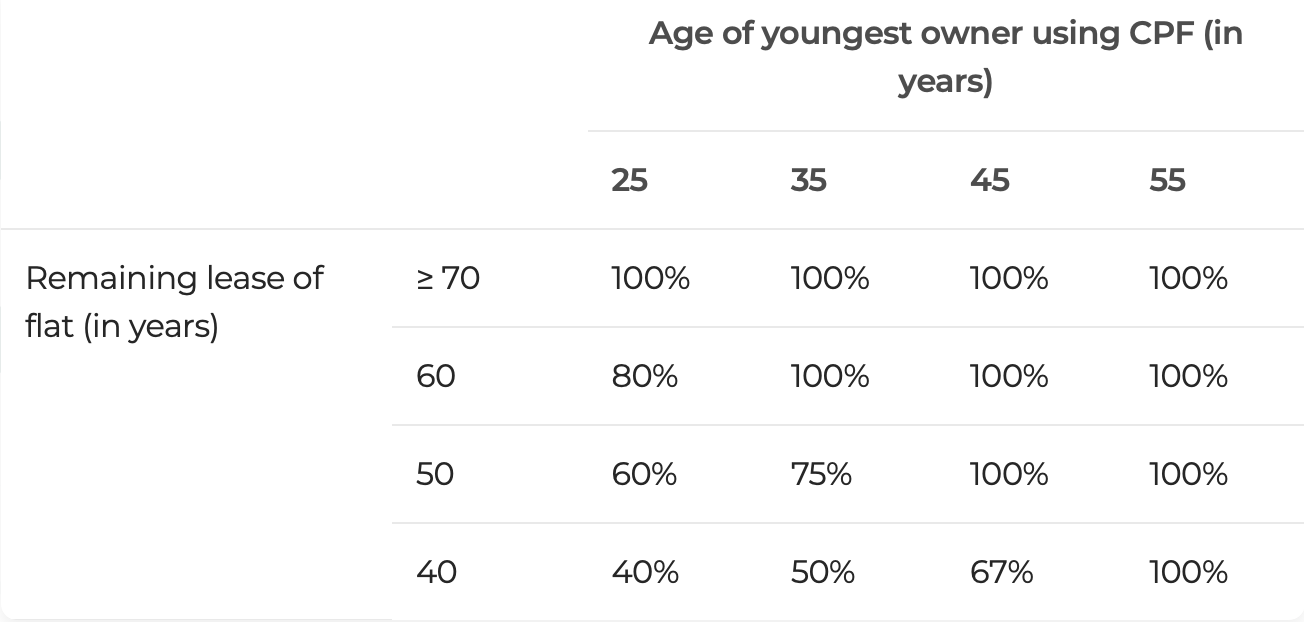 Source: CPF