‘The pandemic boom in home sales is over’: Mortgage rates soar to highest level since 2009 as the Fed pressures the housing market

‘The pandemic boom in home sales is over’: Mortgage rates soar to highest level since 2009 as the Fed pressures the housing market

Home loan rates are skyrocketing thanks to the Fed, but potential buyers who can rough out this tough, altering market will be rewarded.

The 30-year fastened-rate mortgage averaged 5.27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the 7 days ending May possibly 5, in accordance to info unveiled by Freddie Mac 
FMCC,
-1.62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
on Thursday. That’s up 17 basis details from the earlier 7 days — one particular basis level is equal to 1 hundredth of a percentage level, or 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

This represents the maximum level for the benchmark 30-calendar year house loan products given that August 2009. To set that in context: The very last time mortgage loan rates ended up this substantial Barack Obama was just months into his initial phrase as president, the country was in the depths of the Good Recession and Instagram experienced still to be launched.

“The last time mortgage loan charges ended up this higher Barack Obama was just months into his initial phrase as president, the country was in the depths of the Terrific Economic downturn and Instagram had but to be launched.”

The common fee on the 15-12 months fixed-amount home loan rose 12 foundation points about the earlier week to 4.52{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The 5-yr Treasury-indexed hybrid adjustable-rate property finance loan averaged 3.96{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, up 18 foundation details from the prior 7 days.

Home finance loan premiums are roughly benchmarked to the generate on the 10-calendar year Treasury be aware
TMUBMUSD10Y,
3.127{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
But the change among the normal level on the 30-calendar year mortgage and the 10-yr Treasury has widened not long ago.

Considering the fact that the conclude of the Excellent Economic downturn, the spread involving the two has averaged 1.7 share details, but presently it hovers higher than 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If the spread had been closer to historical stages, the 30-calendar year set-fee mortgage loan would however be underneath 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

The Federal Reserve is mostly to blame for the point that mortgage costs enhanced at a more quickly speed than may possibly otherwise be envisioned, according to assessment from Odeta Kushi, deputy main economist at title insurance company Initially American
FAF,
+.29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Investors who purchase property finance loan-backed securities have previously factored in expectations that the Federal Reserve will carry on to raise prices in the course of this 12 months into their view on the mortgage loan current market.

Lenders, therefore, ought to hike the costs they provide customers so that they can carry on to sell their financial loans to traders — people sales are what generates the funds applied to deliver much more home loans.

“While some additional Fed tightening is previously baked into today’s regular house loan premiums, ongoing inflationary tension remains probable to force mortgage loan prices even bigger in the months to come,” Kushi claimed.

Hiking limited-phrase desire charges is not the only way the Fed influences the mortgage marketplace. The central financial institution by itself has been a purchaser of mortgage-backed securities considering that the start out of the pandemic. So now that the Fed will be shrinking its balance sheet of bonds, together with these securities, there could be an influence on liquidity in the mortgage loan market. Lenders would will need to make up the big difference by increasing fees.

Already current housing-market details has proven the massive outcome the surge in rates has experienced on residence prospective buyers. “The pandemic boom in house revenue is around, and exercise is again at pre-pandemic ranges,” Mizuho Securities U.S. economist Alex Pelle and main U.S. economist Steven Ricchiuto wrote in a study be aware.

It’s obvious that the affordability troubles posed by increasing fees and higher charges has cooled demand among property prospective buyers. Nonetheless, house listings continue being several and significantly amongst. That suggests that property selling prices probably will carry on to develop — albeit at a slower pace — due to the fact even with a reduced pool of customers there aren’t plenty of properties to grow all around, analysts say.

And there is the likely that growing interest charges could also put a damper on the provide of properties for sale. “Existing householders are amount locked-in when their existing mortgage rate is beneath the prevailing marketplace home finance loan level, mainly because there is a economical disincentive to offer their residences and purchase a new property at a larger mortgage fee,” Kushi said.

Most economists foresee that the housing market place is balancing out, meaning that bidding wars and contingencies could soon grow to be a issue of the earlier.
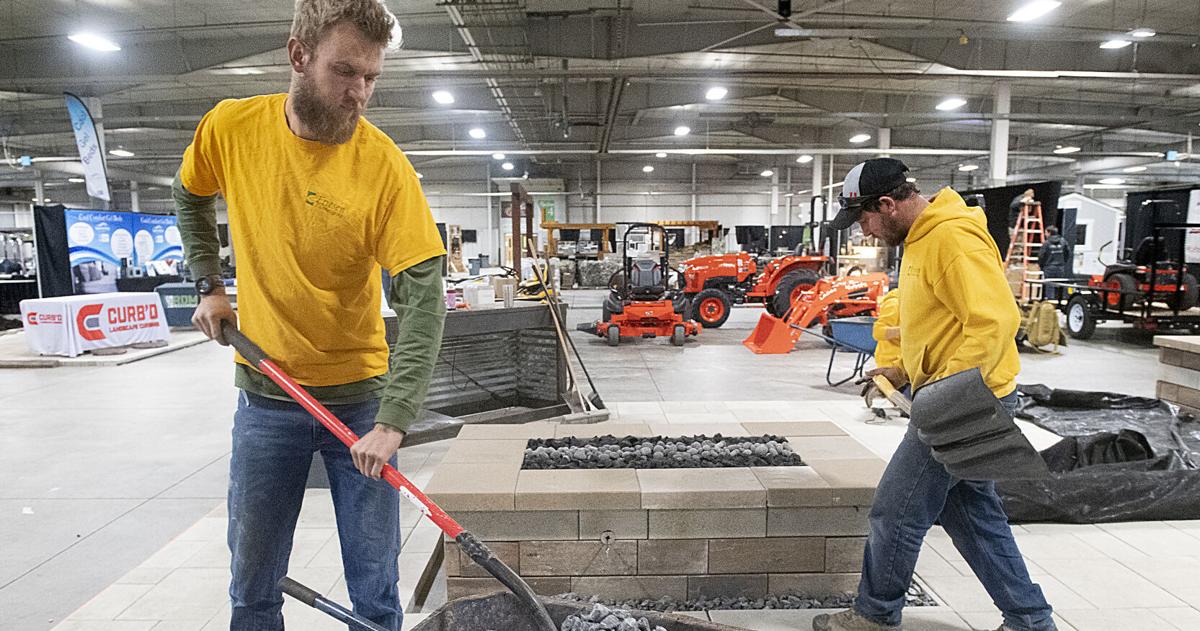
Home improvement businesses hammered through the pandemic. Will the trend continue? | Home & Garden

Home improvement businesses hammered through the pandemic. Will the trend continue? | Home & Garden

While many people stayed home during the pandemic, Justin Brandt stayed busy.

His business, Custom Scapes, was abuzz those months, when many people opted to focus their time and attention on improving their home.


Husker Lawn and Leisure Show setup

Andy Bettenhausen, with Custom Scapes in Lincoln, spreads mulch during set up for the Husker Lawn & Leisure Show on Thursday.


Now with high gas prices leading some to rethink travel, home improvement is likely to remain a hot item.

Brandt, one of dozens of exhibitors at this weekend’s Husker Lawn & Leisure Show, said he expects the increased interest in home improvement to continue for the next few years.

People are also reading…

Now is a good time to invest in landscaping, he said, because he expects prices will continue to rise.

“The sooner you do it, the better,” Brandt said. “Right now everything keeps going up, it seems.”

With COVID-19 cases on the decline and the promise of spring on the horizon, exhibitors at the 20th annual Husker Lawn & Leisure Show are hoping to draw people to the Lancaster Event Center beginning Friday.

The show returns for the first time in three years after COVID-19 concerns led organizers to cancel the event in 2020 and 2021.


Post winter care for your lawn

This year, 125 vendors are promoting everything from landscaping services to iron sculptures.

Paula Widholm, promotions manager of the event, said many local businesses rely on the show to connect with potential customers.

“The face-to-face marketing you get as a business owner trying to sell products or promote your business is very valuable,” Widholm said.

Though she has built long-standing relationships with exhibitors — several have been coming since the show’s first year — Widholm said there are many new faces at this year’s event. About 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the vendors are there for the first time.

Business owners Ken and Jackie Svoboda of Luxury Landscapes were at work Thursday, setting up their exhibit. Forming relationships with customers is their favorite part of the show, which runs through Sunday.

“We absolutely love showcasing what we can do,” Jackie Svoboda said. “Just visiting with customers … and hearing them say, ‘Wow, we love your booth. We want this in our backyard.’”

Why So Many People Became Real Estate Agents in the Pandemic

Why So Many People Became Real Estate Agents in the Pandemic

“Helping persons will make me pleased,” he claimed.

With genuine estate, “I’m serving to households make generational prosperity, especially African-American households and youthful people,” Mr. Cooper mentioned, introducing, “With my nonprofit I assist small income people and youth.”

Like Mr. Cooper, lots of new brokers are holding on to their old professions. Ms. Bieganek stated she’s nevertheless waitressing at a restaurant two or three evenings a week, but hopes to changeover to real estate complete time in a couple of several years. Ms. Gwin reported she proceeds to audition for roles. For her, it’s additional of a companion to her artistic do the job. (Her e mail signature suggests “actress/realtor.”)

Some others are likely all-in. Isaac Teplinsky, 25, graduated from the University of Kansas in 2019 and moved to New York Metropolis to get the job done in experiential internet marketing. He was just 4 months into the task when the pandemic strike. He flew again to go to his mom and dad in Minnesota for what he assumed may well be a week or so. A couple days afterwards he was laid off from his task, together with about 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of his business.

Although residing with his mothers and fathers that summer time and thinking about his following vocation transfer, he began looking at the show, “Million Greenback Listing New York,” and study a ebook created by a single of its stars, Ryan Serhant. He also viewed YouTube videos on receiving into serious estate. “I was having notes,” he claimed. “And at a certain stage I was like, ‘this is 100 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} it.’”

He spent $800 on a Kaplan authentic estate program, acquired his license last spring and joined a community branch of Coldwell Banker in April of 2021. He claimed his father informed him to believe of his to start with three yrs like legislation college — an investment decision in an training without the need of an speedy payoff. “But if you just retain going it will pay off like it would for a health practitioner or somebody in grad faculty,” he stated. He’s considering the fact that sold seven properties and condos and has handled several rentals, hitting his target of $1.5 million in product sales in his 1st six months.

Mike Mogavero, a 54-calendar year-outdated Austin-centered agent with Compass, explained he was producing extra than he predicted inside of his 1st calendar year. When the pandemic strike, he was working remotely in product sales for a Silicon Valley-based mostly tech firm and his job shifted from a staff situation to a agreement work. With his small children, now 10 and 17, attending university remotely and his wife’s occupation as an architect fast paced as ever, he decided to take some time off to figure out his next move. “I looked close to for other jobs and persons stored expressing I was estimate-unquote overqualified, which to me is a very little like a code word for ageism,” he stated.

Immediately after stumbling on a Groupon for serious estate teaching, Mr. Mogavero signed up and obtained his license in 2020. His timing was fortuitous. Austin’s house costs rose practically 40 percent in between 2020 and 2021, earning it a single of the most popular marketplaces in the state. Potential buyers were flooding in from California, in which he’d developed up and used most of his lifetime and occupation before moving to Austin in 2013. He reported he did $30.8 million in income in 2021. “The total of fulfillment you acquired from selling technological know-how to helping individuals obtain and provide actual estate is vastly diverse,” he reported.

They Rushed to Buy in the Pandemic. Here’s What They Would Change.

They Rushed to Buy in the Pandemic. Here’s What They Would Change.

For nearly two years, home buyers have been shopping in conditions ripe for regret. Prices have soared, inventory has plunged and competition has been brutal in markets across the country. With fixer-uppers fetching multiple offers, buyers must make snap decisions about what is often the biggest financial investment of their lives.

Invariably, someone makes a choice they wish they hadn’t.

“There are all kinds of craziness happening,” said Marilyn Wilson, a founding partner of the WAV Group, a consumer research company, who described open houses so crowded they felt like nightclubs, with buyers getting 15 minutes to tour a home. “Sometimes people don’t remember, did it have three bedrooms or four? You might get the house, but it might not be the house you want because you’re just in this desperate state.”

The pandemic has turned out to be a historically miserable time to buy a home. Many buyers entered the market looking for a home to solve some of the problems the pandemic created. They wanted more space for Zoom rooms and home gyms. They wanted bigger and better backyards to entertain outdoors.

These expectations ran headlong into the reality of shopping in a frenzied sellers’ market where the pickings were slim and the prices astronomical. Surveys by the WAV Group and Zillow found about three quarters of recent buyers expressed some regret. In the Zillow survey, released on Feb. 4, the findings paint a picture of homeowners second-guessing the choices they made and wishing they’d had more time, more patience or considered living somewhere else. About a third of respondents regret buying a house that needed more work than they anticipated, 31 percent wish the home they bought was bigger and 21 percent thought they overpaid.

“Pandemic era buyers faced unprecedented conditions, they had far fewer homes to choose from, they had far more competition for the homes that were for sale,” said Amanda Pendleton, Zillow’s home trends expert. “A lot of buyers ended up in this home that was maybe not what they expected.”

Buyers stepping into the 2022 market have much to learn from those who shopped before them. Market forecasts predict that conditions won’t change significantly this spring. If anything, they might get tougher. At the end of December, inventory fell to a record low, according to the National Association of Realtors. Zillow projects that home prices will rise another 16 percent in 2022, on top of the 20 percent rise in 2021. Rising interest rates will likely push some buyers out of the market, but they could be replaced with others looking to escape rising rents or shoppers who sat on the sidelines last year, waiting for some stability.

Many successful buyers ended up with homes that they liked, and are happy to own a place. For some of them, that meant making an offer that managed to stand out in a bidding war. For others, it meant recalibrating their expectations during their search to avoid disappointment.

Recent buyers — those who are remorseful and others who are content with their homes — have some sage advice about how they would do it differently if they had to do it all over again.

Celeste Mohan and Zach Flynn did not set out to buy a farmhouse with a barn and two cows. But after they lost a bidding war for a rundown house in Boca Raton, Fla., the couple jumped on the 2,660-square-foot house in Lake Wales, a town of 16,000 about an hour from Orlando. They bought it last July for $349,000.

Ms. Mohan, 25, and Mr. Flynn, 29, a teacher, felt pressured to buy because the rent on their one-bedroom in Boca Raton was about to jump 22 percent, to $1,900 a month. With their $400,000 budget, their options were restricted to fixer-uppers, with fierce competition. After their bidding war defeat, the couple headed for the country. The farmhouse, set on five acres on a lake, seemed like an ideal alternative: quiet, pastoral, and charming.

“There really wasn’t much hesitation at that point. We’re defeated, we’re exhausted, we’re anxious,” said Ms. Mohan, a curriculum developer for an educational company. “We really just wanted to own a house.”

Almost immediately, the couple regretted their decision. The property felt eerily quiet and isolated, and maintaining five acres and two cows was more work than they anticipated. “You see these people on Instagram with their farm life,” Ms. Mohan said. “Nobody tells you what actual hard work that is and how time consuming it is.”

Before the summer ended, the couple had given the cows to the neighbor, had moved back to Boca Raton and rented a new apartment. Rather than try to sell the farmhouse, they hope to turn it into an Airbnb. “Right now we’re paying rent and a mortgage, which is really uncomfortable,” Ms. Mohan said. They married in December and are expecting a baby in March, adding to their financial stress.

What they wanted: A three-bedroom house in Boca Raton for under $400,000

What they bought: A three-bedroom farmhouse in Lake Wales for $349,000

What they learned: In hindsight, Ms. Mohan wishes she and Mr. Flynn had spent more time evaluating their goals before giving up on Boca Raton. If they had been more clear on what they wanted, they would have known that their wish list included staying in a younger, livelier community. “I also would’ve told myself and Zach to honestly try harder for a house in Boca and to not get so worried about the competition,” she said.

Three months into the pandemic, Stephanie DiSantis felt claustrophobic working from home in her 800-square-foot townhouse in the Queen Anne neighborhood of Seattle.

So, like millions of other Americans, she started looking for a bigger space. She set her maximum budget at $900,000, but soon realized that if she wanted to stay in the central neighborhood, she would have to pay more. She pushed her budget up to $1.3 million, reassessing her priorities.

“I decided, I’ve done a lot of traveling, I’ve had a lot of fun. I’ve done the thing where I’m like, ‘I’m hungry for pasta, I’m going to go to Rome for three days,’” said Ms. DiSantis, 47, who works for Amazon. “I can stop doing that. I can afford to be a little house poor.”

In October 2020, while she was in Massachusetts visiting family for a month, a 2,570-square-foot house dropped the list price to $1.45 million, over her maximum budget, but within reach. After her friends, her broker and an inspector vetted it in her absence, her offer at full asking price was accepted.

She returned to Seattle in November, seeing the house she’d only seen on video in person for the first time. “When I first saw it, I cried,” she said of the house with views of the Puget Sound. “I fell in love.”

The house gave her more space, but at a significant financial cost. In 2021, her priorities shifted, and she suddenly felt the burden of a huge mortgage. “I got super burned out at work,” she said. “I remember thinking, ‘Man, if I was still in that townhouse, I could just quit my job for a year and be fine.’ The mortgage was so low, I could take a year off, I could relax, I could refuel and now I really can’t. ”

What she wanted: A three-bedroom house in Seattle for $900,000.

What she bought: A three-bedroom house in Seattle for $1.45 million.

What she learned: When Ms. DiSantis calculated her budget, she did not anticipate how a large mortgage would limit her future options. “I wish that I would have been able to foresee a couple of years down the road and waited it out,” she said. “I could have taken a big break or been that person who’s like, ‘OK, I’ll move to Montana and get a house that is everything I want for half the price.’”

When Travis Parman got a new job in Lexington, Ky., he figured the housing market there would be more forgiving than the one in Nashville, where he had been living. “I thought it would be cheap and easy,” said Mr. Parman, 49, who started his job at AppHarvest, a tech start-up, in November 2020. “What I actually found out was that Lexington tends to be low on inventory.”

Mr. Parman started his search in November 2020. His husband, Andrew Kung, 43, a surgeon with the Navy, lives on a military base in Jacksonville, N.C., visiting on weekends. With a budget of $1 million, Mr. Parman imagined that he could find a picturesque historic property to be his forever home. Instead, he found extremely limited options. And the properties that were available were a far cry from the stately homes he envisioned.

“I walked into a lot of situations that were disasters,” he said.

Frustrated, he reset his expectations. Rather than look for the perfect home, he would find one that could work for the next five years. In a few years, when the market cooled, he could reassess. “The compromise that I made was really saying: ‘This is going to require a renovation, but it’s cosmetic,’” he said.

With a more measured goal in mind, he found a 3,600-square-foot four square style house in a historic neighborhood close enough to the office that he could bike to work. With canary yellow walls, dated track lighting and decorative kitchen tiles adorned with herbs, it seemed like a house that only needed modest upgrades, the types of improvements that let a homeowner put their own stamp on a space. He closed in January 2021, figuring the renovations would take three months.

But not all repairs are immediately visible, or caught during an inspection. By summer, the central air conditioning, which was 20 years old, failed. Replacing it cost $5,000. The spring revealed a dead 100-year-old pin oak on the property, another $5,000 bill, although the city shared in the cost of removal.

His list of simple upgrades to the décor collided with pandemic delays and cost increases. He struggled to find dining tables, light fixtures and wall coverings. “We wound up having to, in many cases, choose second, third or fourth options because materials or pieces just weren’t available,” he said. The three-month job has stretched to nearly a year.

What he wanted: A historic home in excellent condition in Lexington for under $1 million

What he bought: A four-bedroom home in need of repairs in Lexington for $653,000

What he learned: Mr. Parman learned that even minor improvements can take longer than expected, and not all larger problems are immediately apparent. In hindsight, he said he wished he’d researched the life span of the mechanicals, like the air conditioning, to avoid unexpected bills.

However, he found that by lowering his expectations for the kind of home he needed, he was able to find something that he could live with for the next few years.

“This does not have to be your forever home,” he said. “This does not have to be perfect.”

It just has to work for now.

After spending almost a year traveling through Mexico and Costa Rica, Steph Vaye returned to New York in September 2021 eager to buy an apartment. She had two requirements: the apartment had to be in Williamsburg, Brooklyn, and it could not be a studio.

Three days after Ms. Vaye, 29, started her search, an apartment came on the market that checked all her boxes. Listed for $599,000, it had an open kitchen and a large balcony. “This was a dream apartment,” she said.

She offered the full asking price, but with multiple offers already on the table, she bumped hers up to $655,000, over her $650,000 budget. Her offer was rejected anyway.

“I’m a single woman. I was competing against couples who might have double my income,” said Ms. Vaye, who works for nate, a shopping app.

The first rejection motivated her. “Once you start looking, it becomes an addiction and you just want to move,” she said.

Her broker, Molly Franklin, a saleswoman at Corcoran, showed her six more apartments in Williamsburg, and she bid on three. Two needed work. The third, at 484 square feet, was tiny, far smaller than any of the other options. But it had a balcony and was in a luxury building with an elevator, roof deck and a swimming pool.

“I had this expectation of the size of my apartment,” she said. “I thought it was going to be larger.”

Listed for $569,000, the apartment was well within her budget. Unlike the other options, it did not need work. She initially thought she’d be willing to renovate, but once the options were in front of her, she realized she wasn’t up for the work. “I was not prepared to remodel,” she said. “I needed something that was turnkey.”

She decided she could live with the tiny size because the apartment had an open floor plan, storage space and the amenities gave her options to entertain elsewhere. She closed on the apartment in November 2021.

What she wanted: A one-bedroom apartment in Williamsburg for under $650,000.

What she bought: A one-bedroom apartment in Williamsburg for $569,000.

What she learned: Ultimately, Ms. Vaye realized that staying well within her budget was a top priority, even if it meant she would have to pare down her belongings to live in a much smaller space. By choosing a home that didn’t need any repairs, she had the money to decorate immediately, adding new wallpaper and painting the space. “That was the really fun part,” she said. “I was really able to make it a home.”

For weekly email updates on residential real estate news, sign up here. Follow us on Twitter: @nytrealestate.

Financing for Japan residential investment property amid the pandemic

Financing for Japan residential investment property amid the pandemic

Due to the fact the onset of the pandemic, rumour experienced it that financial institutions throttled lending for unique investors hunting to get qualities in Japan.

With extra than 2 decades into the pandemic, it is useful to glimpse again and see what has really occurred to lending for the buy-to-permit segment for the duration of these unparalleled times. 

Ahead of we start off, remember to note that the facts outlined below refers specifically to retail buyers and not their institutional counterparts. 

Financial investment property bank loan amount trends

Based on the study done through Oct 2021 by Kenbiya, a property financial investment info web page, 50.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the borrowers explained their interest premiums were being among 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

As opposed with the benefits in former 2 yrs, the {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of borrowers with desire costs lower than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} experienced a noteworthy fall,  although the {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of debtors with fascination costs concerning 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} experienced a sizeable enhance.

This data indicates that while the lending is continue to out there, the banks are vulnerable to pricing in their higher chance of lending with bigger desire prices. 

Just one should notice the comparatively small sample size for Kenbiya’s facts.  200 respondents were surveyed, 59 of whom mentioned they have a property finance loan. Hence this data should really be dealt with as inconclusive but improved than very little. 

Pandemic affect on Japan’s investment property market 

In accordance to data from the Real Estate Economic Institute, 140 strengthened concrete multifamily expense houses were sold in Better Tokyo in 2020, an improve of 6.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Year-on-12 months (YoY) . 

The number of models offered was 6,260, up 4.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} YoY.

In the 1st 50 percent of 2021, income of reinforced concrete multifamily financial commitment qualities reached 76, a 1.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} YoY increase.  

The range of models sold rose 4.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} YoY to 3,650 in the exact same time body.

We may well will need to hold out until August 2022 to see the comprehensive revenue facts for 2021, nevertheless the 2021 to start with 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} outcomes suggest that inspite of the pandemic, there was not a detrimental impression on the need for expense qualities in the Greater Tokyo Spot.

Financing for investment residence

The Financial institution of Japan data display that the number of borrowers for expense houses arrived at 614,632 as at September 2021, up 2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from September 2019.

In conditions of excellent financial loans, it was all around 28 trillion yen as at September 2021, minor improved compared to the balance prior COVID-19.

The previously mentioned information indicates that the domestic lender home loan lending did not significantly abate.  Paired with the earlier mentioned desire data, a single can presume that lending need is still being fulfilled, albeit at larger curiosity costs to cost in the better perceived lending danger all through the pandemic.

For abroad prospective buyers, since most regional financial institutions involve the home finance loan contracts to be signed in Japan, lots of buyers are not able to borrow in the course of the pandemic as Japan’s borders have been closed to non-citizens.

In some situations, non-resident investors can receive yen financial loans from banking companies in their residence countries, presented that those people banks have branches and operations in Japan. 

This option nonetheless ordinarily comes with greater desire fees and greater down payments than individuals of local banks.

You can uncover the mortgage information for international nationals delivered by some of the banking companies shown beneath. 

Shinsei Investment decision and Finance
(For HKSAR or Japanese passport holders residing in Hong Kong)

Tokyo Star Lender
(For Taiwanese passport holders residing in Taiwan)

SMBC Have faith in Lender
(For foreign nationals residing in Japan) 

Orix Asia Limited
(For Hong Kong ID holders)

Bank of China
(For Chinese passport holders)

Lender of Communications
(For Chinese or Japanese passport holders residing in Japan)

Even further Looking through

Actual Estate Economic Institute Comprehensive 2020 and 2021 Initially Fifty percent Condominium and Multifamily Investment decision House Report (Japanese only August, 2021)

Dallas-Fort Worth’s retail real estate market has gained back its worst pandemic losses

Dallas-Fort Worth’s retail real estate market has gained back its worst pandemic losses

Dallas specialists say the excellent retail reset is in excess of.

At Wednesday morning’s annual Weitzman D-FW retail authentic estate meeting, the presenters stated Dallas-Fort Worth’s retail true estate current market scored a solid restoration past yr, reversing some of the worst of 2020, and is poised to keep on the rebound.

H-E-B’s grocery expansion is lifting new retail design, which is predicted to get to 2 million square feet this year. Very last year, there ended up only 640,000 square ft of new retail building, marking the initially time that range fell under 1 million sq. feet since 1990, stated Matthew Rosenfeld, executive vice president at Weitzman, at the brokerage firm’s on the web celebration Wednesday.

D-FW retail is at, or near to, pre-pandemic concentrations of 2019 soon after the “great retail reset” that restructured harmony sheets and closed revenue-shedding merchants, mentioned Michelle Caplan, govt vice president at Weitzman.

Even though very last 12 months was the worst year for retail design in a long time, 3.9 million square ft of retail room was leased, reversing 2020′s 4 million sq. ft of vacancies when a document amount of merchants closed nationwide.

Michelle Caplan, executive vice president at Dallas-based Weitzman.
Michelle Caplan, executive vice president at Dallas-dependent Weitzman.(Weitzman)

It was the 3rd-strongest leasing marketplace in 22 a long time for the region’s more than 1,400 purchasing facilities.

In Dallas-Fort Worth’s 200 million square feet of retail area, occupancy ranges have been up to 93.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2021 from 91.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2020 and are forecasted to increase to 95{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this calendar year, Rosenfeld explained. Last year’s occupancy was the strongest in 32 many years.

Retail and cafe operators progressed with new innovations for drive-up entry and in-keep fulfillment as the pandemic transformed searching behaviors, Caplan said. “The vast majority of vacancies have been filled by more robust concepts than the kinds they replaced.”

Which is not normally the scenario soon after a downturn, Caplan reported, but this time there had been stronger outlets of all dimensions, places to eat, clinical boutiques, and conditioning and elegance providers waiting to fill in.

That was also correct with anchor vacancies remaining by Stein Mart, Pier 1 and other individuals, Caplan stated, including that Sprouts Farmers Current market has 4 new shops in vacant anchor spaces in the is effective.

“So our vendors are much better. And our industry is more powerful. And our economy is much better,” Caplan mentioned. That is why Weitzman came up with a rosy forecast that involves new leasing to go on at a potent rate of 2.5 million square ft in 2022.

Matthew Rosenfeld, executive vice president and director of brokerage D-FW at Dallas-based Weitzman.
Matthew Rosenfeld, government vice president and director of brokerage D-FW at Dallas-centered Weitzman.

The market place has discovered some lessons from yrs of overbuilding.

The reduced development displays a ten years-lengthy craze in D-FW, Rosenfeld mentioned. In the 2000s, the industry included 50 million square toes of new retail house, but building totaled only about 18 million in the 2010s.

Of all the types of shopping facilities, malls, which occupy about 20 million sq. toes, or 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the D-FW region’s retail area, had the lowest occupancy charge of 89.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} past 12 months. The area’s most significant sort of center, local community facilities that are anchored by grocery and other huge box shops, experienced the optimum occupancy rate of 94.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Final year proved that “brick-and-mortar retail continues to be suitable,” Caplan claimed.

Noam Ben-Zvi, co-founder and CEO of place information analytics firm Placer.ai, mentioned the lion’s share of income invested — 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — nonetheless happens in bodily areas.

Ben-Zvi was the featured speaker at the Wednesday meeting and was interviewed by Weitzman main advertising and marketing officer Leisa Barger. He co-started Placer.ai in 2017 following recognizing that so a great deal of info analytics was focused on on the internet spending.

“We experienced an a-ha minute that by way of mobility info there is a wonderful deal of electric power in understanding what humanity is doing,” Ben-Zvi mentioned.

Noam Ben-Zvi, CEO and co-founder of Placer.ai

He had a sturdy technological innovation history, which involved providing a organization he started in Israel to Salesforce, but he didn’t know a lot about retail real estate. The 1st time he attended the Global Council of Shopping Centers once-a-year conference in Las Vegas, Ben-Zvi reported, he was “walking all around and Googling JLL and Brixmor.”

The agency uses anonymous tracking of cell gadgets, credit card details and other components, which includes retail building in the pipeline and criminal offense data, to response questions from merchants and developers. Ben-Zvi introduced at the convention that Placer.ai gained $100 million in a 3rd spherical of funding this 7 days.

Placer.ai’s facts displays that keep targeted traffic is rebounding and immediate-to-shopper models are finding achievement with suppliers. “Many will be scaled up and other folks will close.”

Barger questioned Ben-Zvi for the audience of 500 real estate industry experts whether he thinks bodily retail is a very good financial commitment.

“I believe I do based mostly on the details you just described,” he said, “and for the reason that persons want to go out and never want to sit at home to invest in everything.”

H-E-B is putting its first D-FW stores in suburban Collin County.
Rendering of the H-E-B store in Plano that's scheduled to open in fall 2022 on the southwest corner of Preston Road and Spring Creek Parkway.

Twitter: @MariaHalkias

Hunting for more retail coverage? Click in this article to read through all retail news and updates. Click on listed here to subscribe to D-FW Retail and more newsletters from The Dallas Morning Information.