Need to I wait for actual estate costs to crash prior to I buy a home? Here are 3 easy causes why this housing downturn is nothing at all like 2008
Two decades in, this 10 years has by now introduced a world pandemic, file-setting inflation, growing fascination charges and a region additional divided than at any time just before.
So why not a housing crash way too?
Americans who lived by means of the 2008 crisis may be looking at the crimson-incredibly hot sector beginning to awesome and receiving flashbacks. And for potential house owners, it may well be appealing to set your ideas on pause till the market bottoms out so you can snag a home at a good selling price.
But gurus say there are great causes to believe that that nonetheless this shakes out, it will not be a return to 2008 — which will no doubt be a reduction to any one whose apple bottom denims and boots with the fur have been lengthy place away in storage.
Really do not miss out on
1. Creditors stopped remaining so lax
Blame it on the banking companies. A enormous contributor to the housing crisis in 2008 was dicey lending methods inside the monetary business. Years of deregulation created it much easier — and more profitable — to hand out dangerous loans.
The Dodd-Frank Act, which was signed into legislation in 2010 aimed to stop that by rising oversight in the business.
Though the act’s effectiveness has been termed into concern over the many years, it has without doubt compelled lenders to be stricter about their lending methods, which indicates far much less borrowers are most likely to land in hot water.
The median credit history score of freshly originated home loans was 773 in the 2nd quarter of the year, according to the Federal Reserve Bank of New York. But 65{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of new house loan holders had a credit rating of 760 or a lot more.
The New York Fed extra in its quarterly examination that, “credit scores on newly originated mortgages stay incredibly significant and mirror continuing significant lending specifications.”
2. Homeowners are performing good
The onset of the pandemic could have been catastrophic for the housing market place if thousands and thousands of house owners had no choice but to default on their loans.
The good news is, mortgage forbearance programs allowed struggling debtors to pause their payments till they could get back on their feet. And it labored: by the conclusion of June, the share of home loan balances 90-furthermore days earlier due remained at .5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — a historic reduced.
And when compared to 2010, when delinquencies on solitary-spouse and children residences strike a 30-calendar year substantial of 11.36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, the level was just 2.13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the first quarter of 2022.
On leading of that, climbing residence prices has translated into enhanced fairness for homeowners. In whole, home finance loan holders now have $2.8 trillion additional in tappable fairness in contrast to a year in advance of, in accordance to Black Knight, a property finance loan engineering and info company. That is a 34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} maximize and much more than $207,000 in extra available equity for every borrower.
3. There’s even now plenty of supply
“It’s not normally as easy as supply and desire — but it pretty much always is,” host Dave Ramsey said on The Ramsey Present previous thirty day period.
Ramsey states the important issue in 2008 was there was a “tremendous oversupply for the reason that foreclosures went in all places and the sector just froze.” The crisis wasn’t down to the economic climate or curiosity rates, it was “a actual estate worry.”
In comparison, now, there’s a substantial need and a shortage of offer. But the Federal Reserve’s attempts to dampen demand by elevating fascination fees is beginning to function. And new housing is setting up to slowly but surely arrive on the marketplace as well.
What Ramsey says we’re seeing now is a softening in the rate of maximize of prices, but he doesn’t foresee they’ll go down like they did in 2008.
What to go through up coming
Signal up for our MoneyWise investing e-newsletter to acquire a continuous move of actionable concepts from Wall Street’s top companies.
If your retirement strategies have been thrown off by inflation, here’s a strain-free way to get again on observe
‘There’s generally a bull industry somewhere’: Jim Cramer’s well-known text counsel you can make money no make a difference what. In this article are 2 highly effective tailwinds to consider benefit of today
This posting provides facts only and must not be construed as suggestions. It is delivered without having warranty of any sort.
No matter if you happen to be on the hunt for a holiday property as journey reopens, or you want a keep for your funds as shares somersault, Europe can present a host of persuasive 2nd-dwelling destinations.
From accessibility to fine foods and rich lifestyle to stunning scenery, the continent has one thing for absolutely everyone — and house purchasers are getting in.
In the past year, Europe’s prime actual estate sector has developed 5.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} amid continued demand from customers, in accordance to new exploration from worldwide serious estate agency Knight Frank. In the meantime, rental returns in the region’s most in-need family vacation locations carry on to rise.
“For next property owners, Europe’s towns offer culture, connectivity and a good quality of life, even though for buyers they offer you potent tenant occupancy and rather minimal obtain fees,” Kate Everett-Allen, head of international residential investigate at Knight Frank, advised CNBC.
The growth comes as buyers lookup for secure-haven assets and money-generating investments as inflation soars — with fascination extending across the Atlantic.
Nonetheless, as with any investment, getting a residence is a major economical motivation, and being aware of where to get started can be tricky. Utilizing data from Knight Frank, here is CNBC’s rundown of the best spots to get started hunting for a 2nd property in Europe.
If you are in the sector for cash expansion, take into account casting your eye to the ever-alluring cities of Western Europe.
Rate development in Europe’s prime authentic estate markets — categorized as the best 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the current market in benefit phrases — has been among the best in the entire world in the past 12 months, in accordance to Knight Frank.
Berlin, Germany has found the strongest selling price advancement in the yr to June 2022, with substantial-end houses appreciating 12.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on ordinary.
Berlin residence prices have appreciated at the quickest click on throughout Europe’s prime actual estate marketplace, according to Knight Frank.
Nikada | Istock | Getty Visuals
The yearly uptick places the German capital’s expansion amount well forward that of other world wide cities like New York (7.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Hong Kong (3.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and London (2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
In other places, assets cost appreciation has been robust this calendar year across the significant-conclude genuine estate markets of Edinburgh (11.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Dublin (10.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Zurich (10.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Paris (8.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).
The slowdown will be felt most in reduced cost brackets and domestic-driven marketplaces.
The continued increase of the region’s leading cities arrives as expansion rates slow throughout the global house market amid growing desire rates and a darkening economic outlook. Even so, Knight Frank mentioned the slowdown has not still translated to home charges — with the luxury sector proving specifically resilient.
“Rising mortgage premiums and a weakening world economic outlook are cooling some of the ebullience of the very last two decades, but the slowdown will be felt most in lessen rate brackets and domestic-pushed markets,” the report pointed out.
Creating an abroad residence acquire is not devoid of its challenges, nevertheless. In advance of embarking on an overseas order, possible purchasers ought to think about foreign exchange fees, regional mortgages and taxes, ownership and sales expenditures, as well as any constraints on overseas owners.
If you are hunting for a purchase-to-allow home, Europe’s primary holiday vacation destinations may possibly just suit the invoice, with the Mediterranean coast an eternal favourite for holidaymakers.
On top of the earlier mentioned issues, there are a several other components to look at when buying a rental vacation residence. People involve area — the two in phrases of proximity to local amenities and accessibility to worldwide airports — calendar year-spherical demand to limit void periods, and market liquidity.
Italy’s Tuscany and Liguria areas, France’s south coastline and French Alps, and Spain’s Barcelona, Marbella and Balearic Islands are among some of the major places in Europe to invest in a buy-to-enable house based mostly on those people requirements, according to Knight Frank.
Tuscany, Italy, dwelling to rolling hills, glorious food stuff and one particular of the world’s best collections of Rennaissance artwork, is a perennial favorite for overseas residence purchasers.
The Tuscan metropolis of Lucca on the Serchio River is a notably well-liked choice, representing a quarter of customer requests in 2021 alongside Pisa and Bolgheri, and recording yearly price advancement of 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, according to Knight Frank.
The normal assets price sought by Knight Frank buyers in Lucca and Pisa now stands at all over 1.7 million euros ($1.8 million) — nicely underneath the Tuscany region’s 3.7 million euro average. Meantime, normal everyday rental rates stand at 471 euros.
The euro is currently trading at shut to parity with the greenback, meaning U.S. purchasers are taking pleasure in a 15-20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower price on home costs in any of the 19 euro zone member nations around the world when compared to July 2021.
We’re now seeing U.S. buyers target conventional sunbelt regions, which is a departure from the norm.
Mark Harvey
head of intercontinental, Knight Frank
“In the previous, U.S. desire has been concentrated on cities presenting lifestyle and connectivity from Rome to Paris and from Barcelona to Florence,” Mark Harvey, Knight Frank’s head of international, claimed.
“But we are now viewing U.S. customers target conventional sunbelt areas, which is a departure from the norm,” he ongoing, citing expanding interest in locations this sort of as Mallorca, Sardinia and the South of France.
With the U.S. Federal Reserve tightening monetary coverage at a speedier clip than the European Central Lender, that greenback rally could be set to continue, producing Europe a competitive expenditure place for some time to arrive.
“Further amount hikes by the Federal Reserve will see the greenback strengthen even further towards the euro leading to probably higher bargains for U.S. purchasers,” Everett-Allen extra.
I come from a family of genuine estate business owners and investors.
As a result, I have been in authentic estate virtually my complete lifetime and so when it arrived time to invest, it felt normal to get a rental house.
I bought my initially one at the age of 18 and I continue to don’t forget the quantities.
It was a condo in Germany. It was for sale at close to €38k, I managed to negotiate it down to about €33k, and its anticipated rent was about €400 per thirty day period. I also had access to low-priced credit card debt to improve the returns on equity.
On the floor, this was a no-brainer.
The returns on equity had been 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}+ for every 12 months and that was in advance of even accounting for any future appreciation.
I believed that even with conservative estimates the returns would be considerably far more desirable than what I could get paid in the inventory industry.
But I was incorrect!
Later on, I went on to work in private equity actual estate and I swiftly realized that my calculations ended up way off.
And I am not by itself to make these issues.
In truth, I would argue that the bulk of rental property investors vastly overstate their returns by miscalculating them. After you appropriately account for all costs, the returns might nevertheless be interesting, but most typically, they are inferior to all those of REITs (VNQ), and which is on leading of taking a lot better challenges.
Allow me demonstrate that to you:
Calculating the returns of rental attributes: 101
The easy math that every person is executing is the following.
Rents + appreciation – desire expense / down payment = return on equity
With this calculation, you can often get 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}+ once-a-year returns.
But even pretty new investors will fully grasp that this is commonly deceptive.
Taking it a move more, buyers will generally replace rental revenue with net functioning profits, which eliminates property expenditures like utilities, taxes, insurance policies, etcetera.
Web functioning earnings + appreciation – fascination price / downpayment = return on equity
Below already, the returns get started to decline substantially. The internet functioning cash flow is typically just 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the rental profits if you properly account for all property bills.
So let us say that the returns now fall to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}+ every year.
Even now really very good, proper?
Properly, we nevertheless haven’t accounted for the most essential charges… which are typically neglected by buyers.
Calculating the returns of rental attributes: Continued
Some buyers may possibly include a renovation reserve cost in the calculation of their web working profits, but most possible, it won’t address big restore expenses that happen not often, or at minimum, it is not going to thoroughly account for them.
As soon as in a although, you will have a terrible surprise. It is literally inevitable and it desires to be accounted for when calculating returns.
If you get again to my to start with rental property, a single repair monthly bill could have drained yrs of rental money. To get an instance, think about that the apartment flooded and endured important h2o harm. Your coverage may possibly cover some factors if you are fortunate, but most very likely not all the things. The repair service invoice could very easily be a couple a long time or rental money.
But you will also have other destructive surprises. It is not just residence repairs, but also other matters like a tenant who refuses to pay back the hire… or trashes your locations… or even sues you.
To acquire a different instance: let us presume that some mold experienced been growing in your rental property simply because of weak air flow, and your tenant decides to sue you right after he or she finds out that she formulated bronchial asthma.
You will have to employ the service of a law firm to protect oneself and this could drag into the courts for months or even yrs, costing you a whole lot of money (and time… far more on that later).
The issue below is that terrible surprises are inescapable, they are really highly-priced, and they want to be accounted for in your return calculations.
So let us revisit the past calculation:
Net operating income + appreciation – interest expense – reserve for bad surprises / downpayment = return on fairness
So now, your return drops to let’s say 15-20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} annually.
But this is where factors really get messy mainly because we even now have not accounted for the value of your have time and work.
Obtaining and taking care of a rental house is closer to operating a small business than creating a passive investment. It is a good deal of get the job done and your time is not absolutely free. You could just as well operate on one more work and make a income so we will need to account for this expenditure.
1st, we will need to estimate how lots of hrs for every thirty day period you will do the job on your house. This is dependent on several factors, but assuming you personal a number of properties that you control your self, it could be one thing like 15 several hours for each thirty day period. In this estimate, I incorporate also all the time put in on buying houses. Some months, you will work 30 several hours. Other months, you will only do the job 5. We are making use of 15 several hours as an typical.
Then, we will need to figure out what is actually the worth of your time. This will also depend on a person human being to another. If you operate a standard position, let’s say your worth is $25 per hour.
So the value of you functioning on your rental house (as an alternative of your common job) is $25 x 15 = $375 just about every month.
Internet running money + appreciation – desire expenditure – reserve for undesirable surprises – value of your function / downpayment = return on fairness
Now your returns may fall somewhere near 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for each yr.
Still, it really is not undesirable, but we are significantly from the 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}+ talked over early on, and our estimate is still fairly conservative.
Now assume that you are a lawyer and your time is worth is $300 for each hour.
Then the monthly expense of you placing several hours into your rental property is $4,500.
Are your returns large more than enough to justify this cost?
No, it is not. Your time is considerably better put in doing work your key task and investing that dollars in passive investments like REITs than functioning on a rental property, which at the finish of the day, is ordinarily a great deal much less fulfilling.
The better your profits potential, the worse your returns are going to be once you appropriately account for the value of your time.
Why REITs Make Bigger Returns Than Rental Qualities In Most Situations
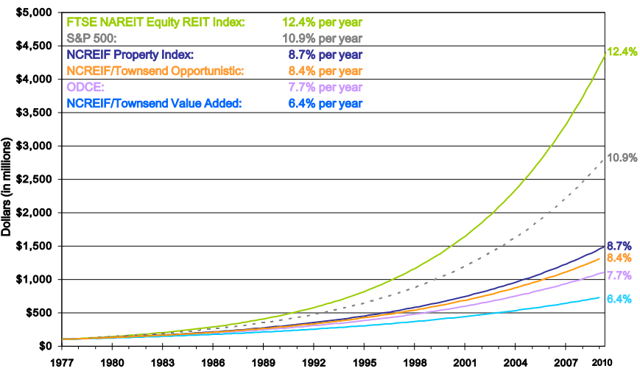
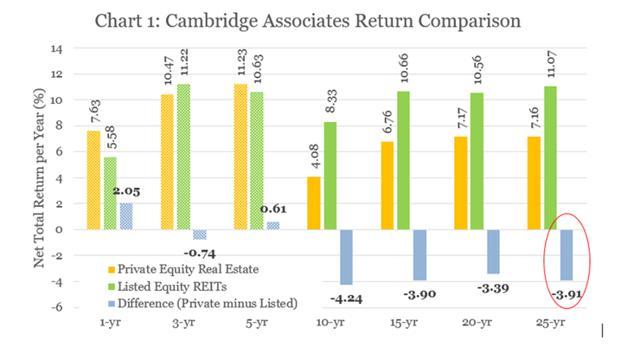
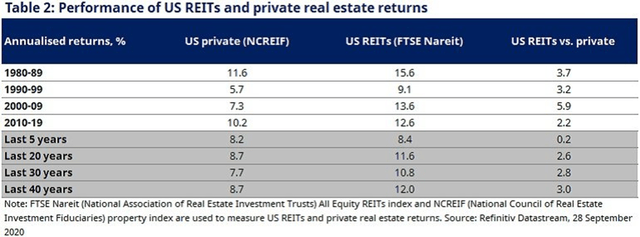
Various scientific tests have demonstrated that at the time you account for all bills, publicly mentioned REITs make better returns than personal real estate investments.
We shown 10 causes in a previous report that you can read by clicking here.
In limited:
1) REITs Do Unfold Investing to Compound Quicker
2) REITs Can Enter Real Estate Related Corporations to Raise Returns
3) REITs Can Develop Their Have Houses
4) REITs Can Do Sale & Leaseback
5) REITs Enjoy Important Economies of Scale
6) REITs Get pleasure from More powerful Bargaining Electrical power With Tenants
7) REITs Make use of The Best Expertise in Serious Estate
8) REITs Have a Overall Return Tactic
9) Most REIT Professionals Are Well-Aligned With Shareholders
10) REIT Traders Pay No Transaction Expenses
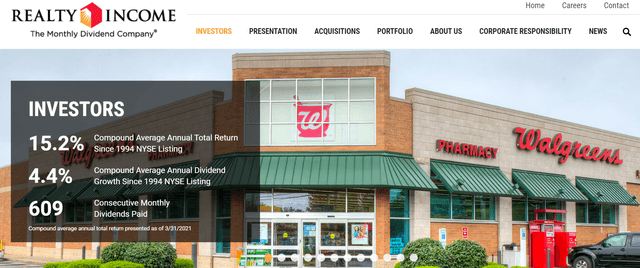
This points out how REITs like Realty Profits (O) have managed to provide 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}+ regular once-a-year returns given that its IPO in 1994:
And Realty Money is not an exception. Numerous other REITs like American Tower (AMT), Prologis (PLD), Community Storage (PSA), and so on. have obtained comparable final results in excess of time…
And if you are an energetic REIT trader who can cherry-choose the best alternatives and may possibly increase your returns even further.
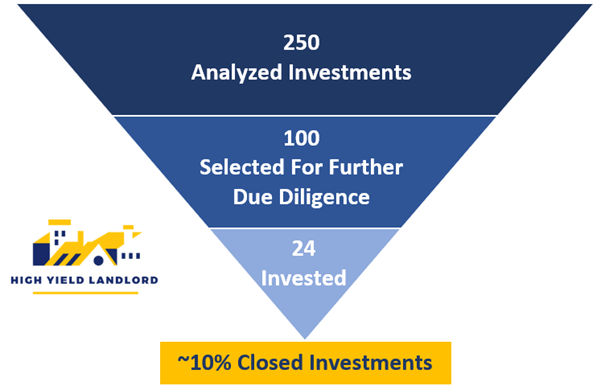
That is what we goal to do at Higher Generate Landlord. We only make investments in the finest REIT alternatives to increase returns:
Significant Produce Landlord assortment (High Produce Landlord)
This has traditionally resulted in even much better outcomes for us. We have managed to compound returns at 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}+ per calendar year and we also receive greater dividends with an normal produce of 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Finally, this is what led me to quit investing in rental qualities to make investments in REITs in its place.
They allow me to generate equivalent or better returns than rental houses, but importantly, I generate these returns with significantly reduced risk and very little hard work.
I set a ton of perform upfront to make the suitable choice, but outside of that, I just observe my investments, accumulate profits, and wait patiently for extensive-term appreciation.
When it arrives to investing in actual estate, there are various routes you can choose to make revenue. And a single choice is to purchase a home that you rent out to tenants.
Several genuine estate investors do pretty nicely for them selves possessing rental properties. And if you’re inclined to place in the perform, you could locate that possessing a rental is a economically satisfying experience.
But presented the point out of the housing marketplace, you may well be questioning if now is a good time to insert a rental home to your true estate portfolio. The reply? It relies upon.
Impression resource: Getty Visuals.
Why it is not the very best time to acquire
These days, dwelling charges are up on a national degree due to solid consumer need driven by a lack of stock. In point, as of late May, there was a mere 2.6-thirty day period provide of households on the serious estate current market, for every the Nationwide Association of Realtors (NAR). It would most likely consider a bare minimum of a four-month source of residences to considerably cool the marketplace off.
In fact, everyone who purchases a household nowadays must count on to spend top quality rates, and that extends to traders seeking to purchase qualities to hire out. The NAR studies that May’s median present property sale price tag arrived to $407,600, a 14.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} uptick from the preceding Could. It also marked 123 consecutive months of yr-in excess of-yr improves.
Compounding the difficulty of larger dwelling charges is high-priced mortgage rates. Just after sitting down at aggressive degrees from mid-2020 by means of late 2021, house loan charges have been on the rise this 12 months. And so if you are unable to shell out dollars for a rental home, you should really anticipate financing it to be high priced.
Why it is a great time to get
Whilst you may well spend a good deal a lot more cash these days to order and finance a residence, the upside of shopping for these days is that rental demand from customers is robust. Correct now, the U.S. occupation industry is good, and that means far more people can afford to pay for to hire a place of their have.
Also, properties have clearly gotten pretty expensive to buy, which suggests numerous folks have no decision but to rent in the absence of currently being capable to find the money for homeownership. As these, if you buy a rental house now, you may possibly handle to command a good deal of dollars in rent from your tenants — money that can assist you recoup your outlay.
What’s the proper simply call?
If you never have a whole lot of capital to function with, now may well not be the ideal time to buy a rental assets. But if you’re ready to be a little affected person, you may well do well purchasing a property you lease out at a time when tenants have no alternative but to fork out up. Feel about your private finances and ambitions to get there at the best choice for you.
If you happen to be hesitant to tie your cash up in an asset like a rental home, you may appear at purchasing REITs (serious estate financial commitment trusts) instead. The upside there is receiving to make investments in genuine estate without the need of obtaining to do the work of a landlord or plunk down a huge sum of dollars up entrance.
Even with house loan prices and acquiring fees on the rise, investing in authentic estate could be a lucrative venture. But in advance of diving in, you ought to figure out if it will make perception for you.
Do you have a timeline with an exit approach? How substantially money do you have and how much will you need to have? How high does your hard cash stream will need to be to make the juice well worth the squeeze?
These are the types of factors you need to inquire you forward of buying a home, according to home loan specialist Shivani Peterson. You can pay attention to the comprehensive extent of Peterson’s information on a latest episode of The Mortgage Experiences Podcast. Here’s what she experienced to say.
Listen to Shivani on The Home loan Reviews Podcast!
What’s your goal?
Investing in true estate takes time, effort, and cautious considered. “You can not jump into any kind of investing wondering you just want to make some funds, you have to be a lot more distinct than that,” Peterson claimed.
There is a record of factors to establish if authentic estate investing is ideal for you. To start with, you need to figure out how considerably cash you have to work with. That will tell you the variety of property you can pay for.
“You cannot bounce into any kind of investing considering you just want to make some dollars, you have to be extra certain than that.”
Up coming, you should really make a timeline for when you realistically want to get a return on your investment and for how prolonged you system to hold onto the home.
Is it an financial commitment to generate a passive income or to substitute your present earnings?
Will it be one thing to increase your nest egg for retirement?
Can you manage the home if it doesn’t develop dollars stream promptly?
True estate has customarily been an appreciating asset class — but it is a lot more of a lengthy-time period technique and most buyers aren’t flipping houses to make a quick revenue, Peterson adds. Whilst home values skyrocketed more than the past several a long time, appreciation is predicted to sluggish by most sector analysts, most likely which means fast gains aren’t in the playing cards.
Contemplate your dollars move
Several real estate investors take into account their dollars movement in advance of using the plunge. To figure out what your hard cash movement is, evaluate the variation involving how a great deal you’d be shelling out per month and how significantly rental income you’d have.
Of system, it’s more than just the buy cost of a house and the curiosity level you lock in. You also will need to component in fees, routine maintenance, and administration fees.
If it all provides up to a earnings, then it could be a very good thought to make investments — as extended as that profit is superior ample to make it worthy of your efforts. “You just can’t management the current market but you can make the most effective conclusion for you specified the data obtainable to you at the time,” Peterson explained.
>Related: Expense Property Bank loan Manual: Needs and Course of action
Know the policies for secondary homes
This year’s soaring property finance loan premiums include yet another layer to authentic estate investing mainly because creditors charge additional for non-principal residences.
How much higher your interest fee will be is dependent on the style of investment house, your down payment amount, and your credit rating rating.
The decrease your down payment, the increased the charge will very likely be. Creditors desire investors to place at least 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down and to have credit rating scores higher than 740, according to Jon Meyer, The House loan Experiences bank loan expert and accredited MLO.
Commonly, curiosity rates on secondary attributes are .5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to .75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} greater than regular conforming premiums. With all those increased home finance loan prices, it all will come back to earning certain you can nevertheless sustain a constructive dollars flow.
Is genuine estate investing proper for you?
Buying an financial investment residence to rent out can convey in a lot of revenue — as very long as you map it out ideal.
The final factor to ponder is your endgame. “When you’re considering providing an investment decision residence, you have to issue in selling charges, carrying charges, upkeep, cash gains tax, real estate agent fees,” Peterson concludes. You will need to figure out the timeline where by you can recoup these charges or you could close up consuming them.
For any person thinking of likely down the street of authentic estate investing, get started by mapping out your existing and potential expenses. When you are completely ready to get commenced, a house loan lender can help you operate the quantities and figure out if an expenditure assets obtain is possible.
The data contained on The Home loan Reports web page is for informational functions only and is not an advertisement for goods offered by Entire Beaker. The sights and thoughts expressed herein are those of the writer and do not replicate the coverage or situation of Whole Beaker, its officers, guardian, or affiliates.
With soaring lease and housing costs soaring, is it better to invest in a dwelling or pay back lease?
COLLIN COUNTY, Texas — As residence rates soar, lease just strike a new file higher.
The nationwide median rent was $1,827 in April. Review that from a year ago, it’s up 16.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
And hardly anywhere is the housing squeeze remaining felt additional than listed here in North Texas, in which facts this year showed that rent increased nearly 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in 2021.
In the meantime, Dallas-Fort Worth observed the premier spike in residence sales costs in the nation, in accordance to a Re/Max National Housing Report in Might. The report claimed residence selling prices right here had been up 39.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more than 2021, and the median residence price tag was $362,782 in April.
So with desire in both the rental and housing markets continuing to mature, a single of the major issues individuals are inquiring is, “Is it far better to lease or invest in appropriate now?”
We talked with Collin County realtor Terri Soussan to get her choose on the present point out of issues. She explained it can be a scenario-by-scenario scenario, with potential renters and prospective buyers both equally weighing a variety of variables.
Soussan is noticing residents make the conclusion centered on the sort of way of living they want. Also, people are re-assessing their funds to see which is the better healthy and if they’re in a financial posture to take into account paying for a house.
“So, it truly is both equally,” Soussan explained. “I’m viewing sellers deciding to rent, but I’m observing consumers that are selecting that they actually just cannot pay for to obtain ideal now since they are remaining priced out. And I’m observing renters also that are making an attempt to choose if paying for is a far better possibility for them.”
There are pros and negatives to both solutions.
There are some things to consider if you want to grow to be a home owner, such as mortgage loan curiosity fees heading up, just one-time costs, home value most likely dropping decreased than what you purchased it for and upkeep and repairs.
On the flip aspect, rent is at its optimum, and a landlord can adjust the price to your regular monthly rent at any time.
While renting, there is no upkeep or recurring expenses, there is more adaptability, renters insurance policies is substantially significantly less pricey, and there is no residence tax to get worried about.
“People are knowing that inflation is hitting all the things and they are hoping to make your mind up what their future stage is,” Soussan reported. “Trying to figure out how they can maximize their returns in this pretty uncommon market that we have not lived via right before, coming out of the pandemic, in modifications with the way persons are dwelling.”
One matter is for particular, however: Soussan reported it is no doubt harder to be a renter now than it was a calendar year in the past.
Far more genuine estate protection from Susanne Brunner: