How new US tax credits, rebates will work for clean energy home upgrades

How new US tax credits, rebates will work for clean energy home upgrades

US President Joe Biden signed the huge local weather bill – the Inflation Reduction Act (IRA) – earlier this 7 days. Electrek spoke with Dan Gayer, JD, CPA, a senior manager in the tax follow at Baker Newman Noyes, about how home owners can declare tax credits and rebates as they work to realize electrical power performance and lower their electrical power expenses.

Strength Effective Residence Improvement Credit history

Variations to the former Nonbusiness Strength Home credit, now renamed the Power Effective Residence Improvement Credit, will acquire impact on January 1, 2023.

The aged credit was really worth 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the expenditures of setting up insulation, windows, doorways, roofing, and other vitality-conserving improvements. The aged $500 life span limitation however applies for the relaxation of 2022. 

From 2023, a $1,200 once-a-year tax credit history restrict will replace the aged $500 lifetime limit. The tax credit history will be equal to 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the prices for all suitable residence enhancements designed for the duration of the calendar year. It has also been expanded to cover items this sort of as biomass stoves and boilers, electric powered panels, and dwelling energy audits.

Commencing in 2023, once-a-year limitations for distinct styles of qualifying alterations had been improved. For illustration, it is $250 for an exterior door, or $500 for all exterior doors $600 for exterior home windows and skylights and $2,000 for warmth pump and warmth pump scorching drinking water heaters for homeowners who do not qualify for the rebate owing to better residence profits – see under. (The latter $2,000 is the exception to the $1,200 annual limit.)

Household Clean Strength Credit

The Residential Cleanse Energy Credit, which is now extended by means of 2034, was beforehand called the Household Energy Productive Residence Credit.

The credit history sum for putting in clean domestic strength these as solar, wind, or geothermal has been elevated from 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 2022 to 2032. It then falls to 26{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for 2033 and 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for 2034.

Gayer suggests of the timing of residence solar tax credits:

On the solar credits, the two the residential credits and enterprise expense tax credits are back again to 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} productive for solar machines placed in provider any time right after January 1, 2022. 

Gayer went on to describe how house owners can secure tax credits for the two the Electricity Economical Property Improvement Credit rating and the Residential Thoroughly clean Power Credit under the IRA umbrella:

The mechanics of boasting this credit rating surface to be the identical in 2022 and 2023 as they have been in the past – the credit rating is claimed on the purchaser’s particular person income tax return. The purchaser does not need to have to submit specific documentation with the tax return, but should really retain documentation as component of their tax records so they can prove they acquired qualified residence in the party of an IRS audit. 

Suppliers must be ready to deliver purchasers with this type of documentation. In 2024 and long run many years, companies want to produce a unique product identification quantity for every single qualifying product or service they offer, and purchasers will have to incorporate this range on their tax returns to claim the credit.

Superior-Effectiveness Electric House Rebate Method

The IRA’s $4.28 billion Large-Performance Electric powered Household Rebate Application will provide an upfront rebate of up to $8,000 to set up heat pumps that can both of those heat and interesting properties. It also gives a rebate of up to $1,750 for heat pump water heaters.

There is also a rebate of up to $840 to offset the price of a warmth-pump clothing dryer or an electric powered stove, including induction ranges.

If a property desires an electrical panel up grade to help new electrical appliances, then there is up to a $4,000 rebate to aid with that. There is also a rebate of up to $2,500 for electrical wiring advancements. 

And for a person of the most cost-economical and quickest methods to make a residence more electrical power-successful – insulation and sealing – there’s a rebate of up to $1,600. 

House owners will be ready to collect a utmost of $14,000 total in rebates. Residence earnings can not exceed 150{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the area median money as calculated by the Office of Housing and Urban Progress in get to qualify. (Here’s an Space Median Income Lookup Instrument from Fannie Mae to see what your restrict is.) In accordance to the bill by itself, rebates start out immediately after December 31, 2022.

Gayer elaborated on the specifics of how the rebates will function:

The Inflation Reduction Act does not give specifics on how this rebate will be administered – the details here are remaining to the Treasury Section to challenge typical suggestions and then offer grants to state governments, who are the kinds charged with really employing the plan and giving out the rebates.

The intent listed here is to supply rebates to experienced purchasers at the place of sale, so this will be a direct lower price on the acquire selling price rather than a credit score claimed on a tax return.

Given how considerably even now wants to happen at equally the federal and condition amounts to generate more specific guidelines and get the required administrative strategies established up, it would seem unlikely that this rebate plan will be up and jogging till someday in 2023, and the actual details of the method might be diverse in just about every state.

The rebate method will run through September 30, 2031, and the Electricity Productive Household Improvement Credit score will operate via 2032.

Photo: “Three pigeons on a roof” by Dunnock_D is certified beneath CC BY-NC 2.

Examine more: If the huge US climate invoice passes, here’s how it could turbocharge photo voltaic and wind


UnderstandSolar is a free of charge company that one-way links you to prime-rated solar installers in your region for customized photo voltaic estimates. Tesla now presents price matching, so it is crucial to shop for the ideal estimates. Simply click here to study a lot more and get your quotes. — *advertisement.

FTC: We use income earning car affiliate inbound links. Much more.


Subscribe to Electrek on YouTube for exceptional movies and subscribe to the podcast.

https://www.youtube.com/check out?v=1DXOa0Kf-D0

U.S. Housing Market Just Hit a Speed Bump That Could Change Homebuying

U.S. Housing Market Just Hit a Speed Bump That Could Change Homebuying

How a lot of a variance does 5 days make? In today’s speedy-paced housing marketplace the place true estate listings get snapped up nearly right away, a complete whole lot.

Our weekly column “How’s the Housing Sector This Week?” delivers the most up-to-day data on the four big bellwethers of the housing sector: home prices, times on the marketplace, selection of new listings, and mortgage loan prices. And for the 7 days ending Aug. 13, a single essential alter is that the rate of dwelling income slowed substantially, with listings sitting five further times on the marketplace when compared with this time past year.

Residences normally linger on the sector just 34 days, so a 5-day upswing is big. Here’s what this and other current fluctuations signify, so that both homebuyers and sellers can continue to be on leading of the dynamic planet of serious estate currently.

Weekly housing report

(Real estate agent.com)

‘Homes are sitting down on the market’

“Last year’s compressed property sale timelines are lengthening,” notes Real estate agent.com® Main Economist Danielle Hale in her investigation of the information. “For a third 7 days in a row, properties are sitting down on the sector for a extended time than final year, and the gap has greater every single 7 days.”

In fact, previous months display time on the market inching up by one working day for the week ending July 30, and by 3 days for the week ending Aug. 6.

This new breather not only offers homebuyers much more time, but also paves the way to a significantly less frantic house-searching mindset in general.

“As both purchasers and sellers modify to the rebalancing current market, expectations shift, decreasing the sense of urgency in the current market and reinforcing the trend toward for a longer period sale timelines,” Hale clarifies.

In other terms, listings may linger even lengthier the moment homebuyers commence kicking back again and pondering, “What’s the rush?”

___

Observe: America’s Most popular ZIP Codes for Real Estate in 2022

___

Home rates are continue to likely robust

Even though properties may well be having more time to provide, homebuyers shouldn’t assume significant discount rates still. For the 7 days ending Aug. 13, median listing charges rose by 13.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a calendar year previously.

“The usual asking price of for-sale residences was up from final 12 months by double digits for a 35th 7 days,” suggests Hale.

But though household prices are however near history highs—clocking in presently at a nationwide median of $449,000—home value development has been tapering for 3 straight months, down from its 16.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} peak in July.

This indicates that dwelling sellers who are hoping for the good ol’ days of way-over-asking-price bidding wars may possibly be in for a impolite awakening.

“Even while inquiring price ranges are nevertheless climbing, July information display that much more sellers overreached what potential buyers have been willing to pay back, and experienced to cut down their asking value,” states Hale.

The variety of new listings dropped a good deal

Inspite of property prices still getting in the vicinity of history highs, for the 7 days ending Aug. 13, the variety of new listings on the industry plummeted by 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a year before.

“This week marks a sixth straight week of calendar year-more than-year declines in the amount of new listings coming up for sale,” suggests Hale. “The early 2022 enthusiasm that householders had towards offering is evaporating.”

As this sort of, household sellers who do checklist are still hot commodities.

“The housing marketplace is not unfriendly to sellers suitable now,” Hale suggests. “It’s critical to keep these shifts in perspective.” In short, we are continue to firmly in a seller’s marketplace.

“Homeowners who value their houses competitively are nonetheless very likely to see an present or additional in a sensible time frame,” she claims.

Home loan prices dipped

The average 30-calendar year set-amount house loan dropped to 5.13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the past week’s 5.22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, according to Freddie Mac, for the week ending Aug. 18.

This is no doubt welcome information to hard cash-strapped homebuyers who are hunting for any break economically, although this will count on exactly where they’re shopping.

“National traits might or might not match what is taking place in your current market at your cost level,” Hale details out. “As an illustration, the Realtor.com 2022 Most popular ZIP Codes report displays that even with a usually cooling housing current market nationwide, ZIPs in the Northeast, and specifically in historic New England, stay competitive, with homes selling swiftly and attracting more customers than in other areas of the place.”

Rising interest rates shouldn’t discourage income property owners

Rising interest rates shouldn’t discourage income property owners

The checklist of concerns can be very long when getting an revenue house in the Puget Seem area. Regardless of whether it is a multifamily, small professional or combined-applied home, earnings house buyers must realize the dangers and benefits that come with this precise kind of purchase. If that weren’t sufficient, the math on investments is transforming as The Federal Reserve proceeds to elevate fees in response to inflation and other financial inputs.  

There is no concern that as the premiums for conventional mortgages are on the rise, even the boldest profits assets investors are sensation cautious about the sector. 

Earnings assets traders will need not be fearful nonetheless, as the correct established of strategic resources can support make the very best of their investments. Especially for those in the sector to make investments in 1 – 4 household properties – single relatives residences, duplexes, triplexes and fourplexes – there are nevertheless competitive methods to finance your financial investment devoid of paying quality premiums.

A single consideration is the Adjustable-Amount Mortgage loan (ARM). As common rates continue on to increase, quite a few are turning to ARMs mainly because of the decreased fees they supply for a mounted time period of time – normally 5, 7 or 10 yrs – when compared to a standard 30-12 months fixed home finance loan.

Not all ARMs are designed equivalent, nevertheless, and earnings home buyers should really take into consideration some standard advice to get the most from their strategic investments.

3 key tactics for getting the most out of your ARM

Comprehend your lender’s curiosity level ceiling

A nicely-acknowledged hazard of ARMs is that at the end of the set-charge time period, ARM financial loans are matter to price changes, which can be significantly better than the first ARM level.

There is a large range of alternatives for how a loan provider will increase fascination premiums after the preliminary fastened period is full, in addition to how much the rate can change about the overall lifetime of the personal loan. Some banking companies let a modest raise at original adjustment, although some others may possibly default to an first maximize up to the lifetime cap. The life span cap is the utmost curiosity amount permitted on an adjustable-price home finance loan, which most lenders set at 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Appear for a bank that keeps the preliminary adjustable desire amount ceiling lower. For illustration, some creditors cap the optimum mortgage charge boost to 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} right after the original fixed period.

Get a obvious see of pre-payment penalties

Typically situations with an ARM, traders choose to pay off their home loan early to acquire advantage of small set desire fees. If a bank loan is paid out off or refinanced in the course of the prepayment penalty period of time, traders could owe extra expenses or a penalty, which is ordinarily a proportion of the remarkable personal loan equilibrium.

Some lenders provide pricing alternatives that do not incorporate prepayment penalties. Acquire the time to comprehend your bank’s approach to pre-payment penalties in their loan agreements. If they only offer prices with a pre-payment penalty, traders have alternatives and really should search for a lending establishment that has options for penalty-free pre-payment of their loan.  

Assess community and larger lending institutions

Huge, nationwide banking institutions and loan providers can contend in the consumer lending market with attractive fees. But neighborhood banking institutions, like Pacific Crest Financial savings Lender and others in our region, give a number of benefits further than charges alone for traders seeking to framework special funding deals – though also preserving the bank’s property in the area economy.

Buyers with elaborate conditions may perhaps uncover that with a community lender, the loan company may understand their clients’ desires more intuitively, and are equipped to close discounts much more speedily since determination-building occurs on a regional amount.

Local community banks also generally have flexibility to tailor their merchandise and companies to clients’ wants and are enthusiastic by working collaboratively to propel progress among smaller firms in the neighborhood region.

Even as the listing of issues for money home traders receives for a longer period, there’s nevertheless lots of possibility to be successful in the Pacific Northwest. From one spouse and children household to small business actual estate and everything in involving, there are financing alternatives that will fit both equally quick and very long-term requirements for community traders.

Master additional at www.paccrest.com.

Written content Resource: Johnny Smith, Pacific Crest Personal savings Financial institution, Vice President and Residential Financial loan Officer


Johnny Smith

Johnny Smith is a vice president and household loan officer at Pacific Crest Price savings Lender, a nearby and independently owned savings financial institution headquartered in Lynnwood, Washington, that has served Northwest organizations and individuals with personalized banking and lending solutions given that 1984.

With knowledge in equally serious estate lending and title insurance, he delivers a important blend of perception to assistance address clients’ exceptional difficulties and possibilities. As a vice president and residential mortgage officer, he delivers portfolio financial loans for residential qualities and floating houses, tailoring the bank’s remedies to meet up with his clients’ requires.

Outside of the lender, Johnny enjoys spending time outdoor – particularly tenting with his spouse, kids and grandkids.

Come to feel free to speak to Johnny Smith at (425) 670-9624 or jsmith@paccrest.com. Remember to do not incorporate sensitive or private information in your information.

Home Depot and Lowe’s cite strong demand, but softening could be ahead

Home Depot and Lowe’s cite strong demand, but softening could be ahead

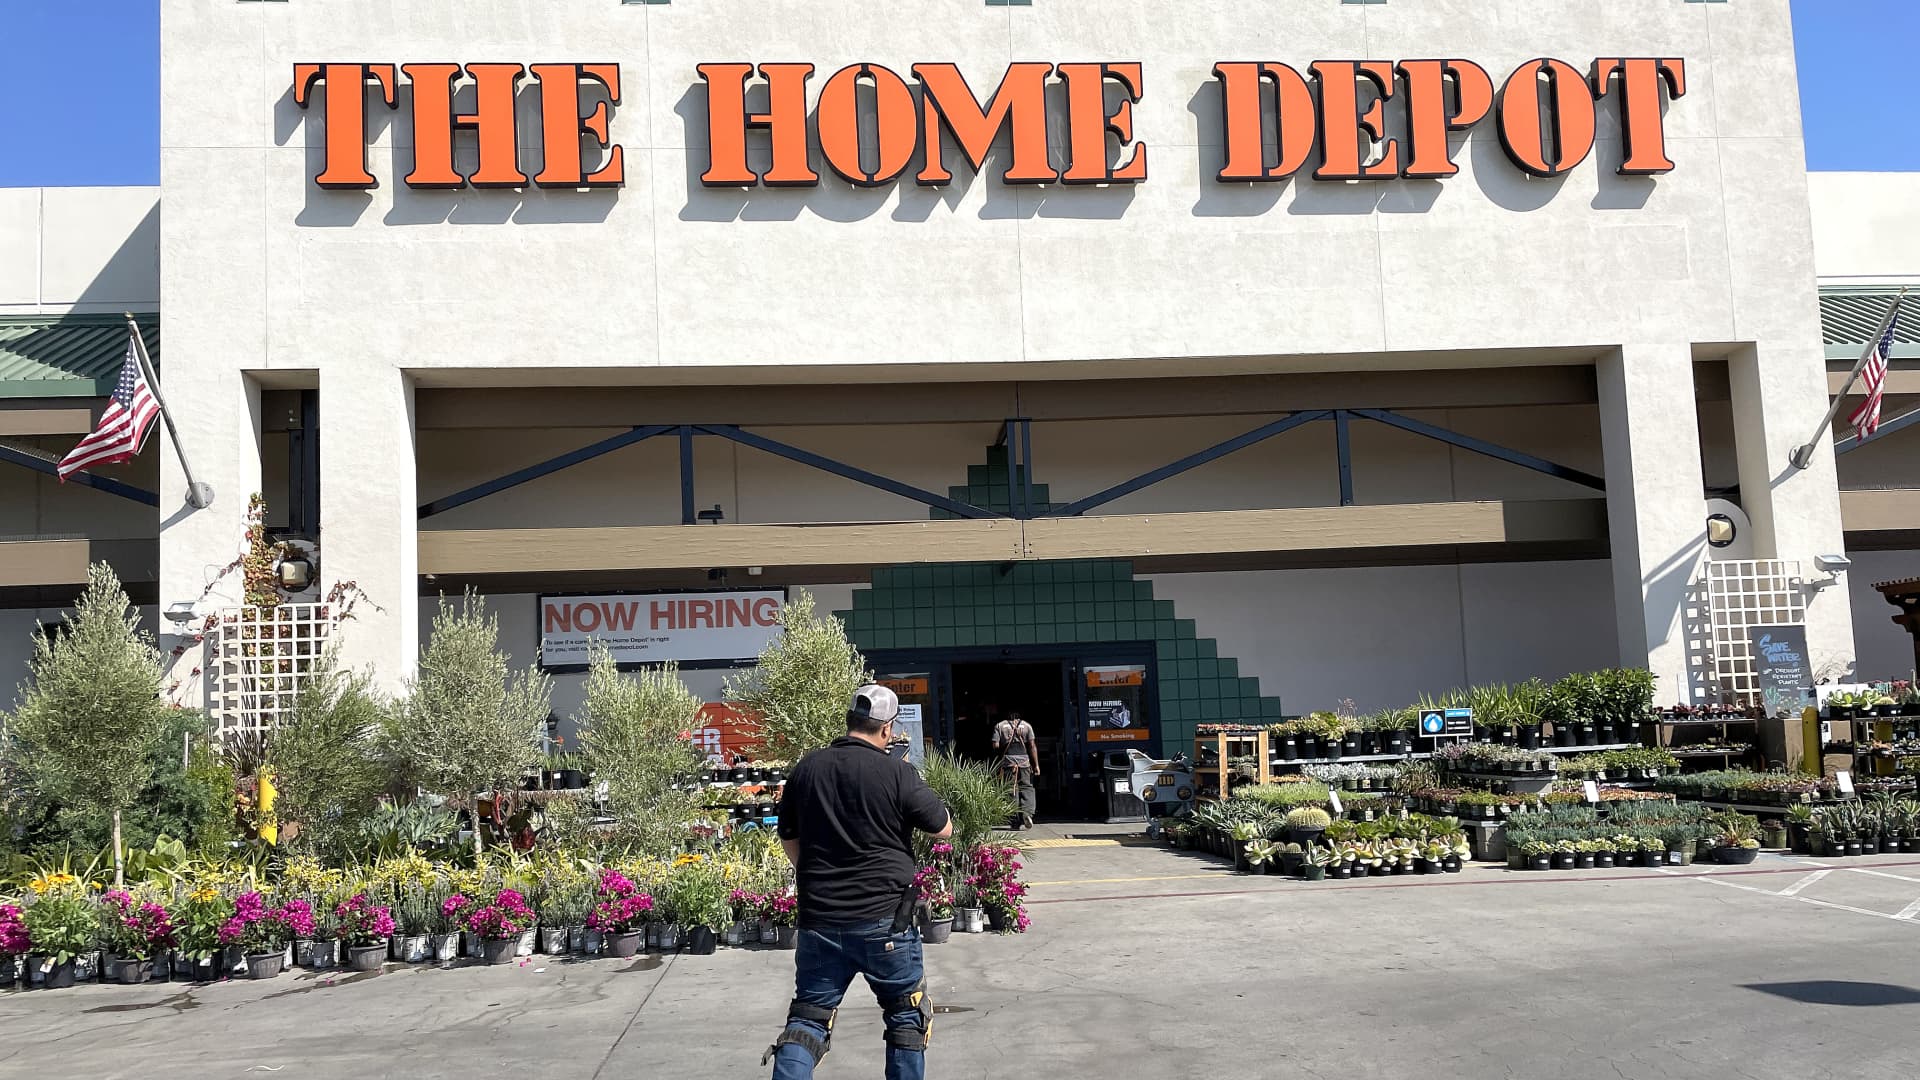
A buyer enters a House Depot shop on August 16, 2022 in San Rafael, California.

Justin Sullivan | Getty Photographs

Paying out on residence improvement isn’t going to appear to have taken a significant hit with the slowdown in the U.S. housing marketplace, but analysts say the power may not past.

House Depot and Lowe’s this 7 days cited solid next-quarter gross sales from professionals this sort of as contractors, plumbers and electricians. The stores explained all those consumers have a wholesome backlog of assignments and loads of pent-up demand for house improvement.

The businesses are chalking up the ongoing strength coming out of the top of the pandemic to housing sector situations for the reason that, they say, individuals remaining set in their homes more time could spur renovations. Considering the fact that the commence of this year, the ordinary price on the 30-year fastened home loan has practically doubled and housing commences have declined significantly. This thirty day period, the Countrywide Affiliation of Homebuilders/Wells Fargo Housing Marketplace Index dropped into the negative territory for the initially time since early in the pandemic.

“Quite often, what is negative for the house builder is not necessarily bad for the home advancement,” Lowe’s CEO Marvin Ellison advised CNBC.

Ellison stated reduced housing starts and large property finance loan prices could incentivize homeowners to continue to be exactly where they are and select to renovate their present-day properties. He observed much more than half of U.S. homes are above 40 yrs previous. 

Dwelling Depot’s main financial officer, Richard McPhail, also noted that the rise in household prices is “almost certainly the strongest underpinning” of property advancement demand from customers. 

“We have viewed dwelling charges respect by practically 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more than the very last two years, which has truly transformed the equilibrium sheet of the North American home owner,” McPhail explained to CNBC. “When you see your residence raise in price, you are much more probable to commit far more in it.”

Appreciating dwelling price ranges can also let for much larger household fairness financial loans, which owners use to fund renovations. KeyBanc analyst Bradley B. Thomas noted that Home Depot cites property prices as “one of the most significant top indicators of residence advancement demand.” The median rate for a household sold in July was $403,800, which is approximately 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} greater than through the similar thirty day period a calendar year earlier.

But with curiosity fees now bigger, residence equity financial loans are falling just after hitting their highest degree due to the fact 2007 in the very first quarter of the year, explained Piper Sandler analyst Peter Keith.

“There’s a bit of a lag effect,” Keith advised CNBC. “We do imagine this drop off in house fairness extraction will sooner or later show up in the pro investing.”

Keith explained the fall off could strike contractors and other residence improvement pros by the conclude of this calendar year or the beginning of up coming.

Bobby Griffin, an analyst from Raymond James, sees the danger to residence equity extraction, but similarly has most of his target on household price ranges.

“Premiums go up, it is really not as appealing to acquire income out of your household any longer,” Griffin advised CNBC. “But you however have that fairness, so it is nonetheless eye-catching to invest.”

Miami-Dade County’s median home prices retreat in July for first time since 2021

Miami-Dade County’s median home prices retreat in July for first time since 2021

Miami-Dade

Single-family home and condo prices retreated in July in Miami-Dade County, showing a housing market slowdown has begun. This is a file photo of the FTX Arena and several Miami high-rises, including Zaha Hadid’s One Thousand Museum.

/el Nuevo Herald

Home prices dipped in July for the first time in Miami-Dade County since fall of 2021, providing a silver lining for priced-out buyers desperately trying to catch a break in an ultra-competitive housing market finally losing steam.

Single-family houses last month came with a median price tag of $570,000, down 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from $579,000 in June, according to a monthly housing report released Thursday by the Miami Association of Realtors. Condominium prices, meanwhile, declined 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to $380,000 in July in Miami-Dade, from $410,000 the prior month.

The drop in median prices reverses the upward trend since September, when the median hit $485,000 for houses and increased monthly through June. Condos experienced a similar ascent starting in October, when prices vaulted each month from $326,790.

“It’s gotten to a point where buyers aren’t willing to pay an astronomical price,” said Jonathan Vega, a real estate broker with ONE Sotheby’s International Realty in Miami. “Some sellers think they can get whatever they want. Then you realize the market is not what it was. I am seeing price reductions and negotiations that were not happening before.”

Relief has yet to come for prospective buyers in Broward County. Last month, the median sales price hit $600,000 for single-family homes — up from $590,000 in June — and remained steady at $265,000 for condos.

After runaway home prices have left most South Florida buyers behind since shortly after the pandemic began in spring of 2020, a retreat in prices and total monthly sales is clearly underway. The big questions now are how low will prices go and how many months will it take for the market to stabilize for buyers and sellers.

Mariya Letdin, a business professor at Florida State University, said South Florida’s real estate market has hit headwinds and she predicted a “small price correction” over the next few months.

Still, median price tags are expected to remain greater than those seen in most of 2021. On an annual comparison, Miami-Dade’s $570,000 median price for houses last month jumped 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from $515,000 in July 2021, and by 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for condos to $380,000 last month from $340,000 in July 2021.

Broward’s single-family home sales midpoint price of $600,000 is 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more than $495,000 a year ago, and the condo sales price of $265,000 is 23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more than $215,000 in July 2021.

South Florida’s residential market remains out of reach for many local residents. An influx of wealthy transplants from across the country has led dramatic price growth during the pandemic, exacerbating a housing crisis that actually started in Miami-Dade years before the pandemic.

Regional home sales began declining in June following mortgage lenders increasing interest rates, following the lead of the Federal Reserve, which is expected to keep boosting its benchmark interest rate to thwart inflation.

However, the sales slowdown is somewhat muted in South Florida by the large number of people still paying cash for houses and condos. In July, 41.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of total home sales in Miami-Dade and 41.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of them in Broward were cash deals, far greater than the 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} national average.

Last month, Miami-Dade recorded 2,375 total home sales, a sharp drop from 3,632 sales in July 2021. Broward recorded 2,575 sales, also a steep decline from 3,679 in July 2021.

Lawyers Weston Finn and Diana Correa observed the slowdown in the real estate market, as they tried selling their condo in Lighthouse Point near Fort Lauderdale. When the husband and wife first listed their condo in May, the couple welcomed lines out the door for their open houses. The couple sold their condo for the list price of $565,000 in June, and then started searching for their next residence.

Before finally finishing their three-month search by purchasing a house in The Roads, Finn and Correa said they didn’t see as many prospective buyers or as much competition as they experienced vying to buy their Lighthouse Point home.

Also, house hunters are seeing more home options in the South Florida real estate market, with inventory increasing every month since February. Miami-Dade has 3.1 months of supply of houses available for sale and 3.3 months of condos. Broward has 2.4 months of houses and two months of condos. Those supply figures show South Florida is slowly moving closer to a what’s considered by real estate experts as a balanced market between buyers and sellers: 5 to 7 months of inventory.

While the volume of cash home buyers remains high in the region, the prime reason for that is changing. Cash was king to beat the competition the past couple of years. Now, area buyers are paying cash for houses and condos to save on increasing interest costs attached to 15-year and 30-year mortgages, Florida State’s Letdin said.

Profile Image of Rebecca San Juan

Rebecca San Juan writes about the real estate industry, covering news about industrial, commercial, office projects, construction contracts and the intersection of real estate and law for industry professionals. She studied at Mount Holyoke College and is proud to be reporting on her hometown.
Support my work with a digital subscription

Profile Image of Michael Butler

Michael Butler writes about the residential and commercial real estate industry and trends in the local housing market. Just like Miami’s diverse population, Butler, a Temple University graduate, has both local roots and a Panamanian heritage.

6 of the San Antonio area’s wildest luxury real estate listings

6 of the San Antonio area’s wildest luxury real estate listings

In San Antonio and its neighboring communities, the appetite for over-the-top luxury amenities is sure to raise some eyebrows. 

The Express-News compiled a list of some of the wildest real estate listings spotted in and around Alamo City so far this year. Among them are a private water park, a lazy river and a wine cellar built into a rock bluff. 

Tony Parker’s splashy mansion: The 53-acre estate near Boerne owned by the former Spurs player Tony has a waterpark. The mansion is still on the market for $19.5 million. 

The property, at 9 Rue Parker, includes 10 bedrooms, eight bathrooms, and four half-bathrooms. 

The home’s impressive amenities include a tennis court, a sand volleyball court, a greenhouse, an herb garden, a fruit orchard, and a tortoise enclosure. The private water park includes body slides, lazy rivers, grottos, and a diving platform. The property also features a 5,922-square-foot gym. 

Own a cave near George Strait: The $54.5 million, 2,269-acre Less Ranch in Kendall County is less than five minutes from Strait’s Tapatio Springs Hill Country Resort and borders the Kronkosky State Natural Area on the southwest.

The Less Ranch, a 2,269-acre tract of land just off Texas 46 comes with creeks, springs and a "dramatic cave" has hit the market for $54 million, according to a listing by Robert Dullnig of Dullnig Ranch Sales. 

The Less Ranch, a 2,269-acre tract of land just off Texas 46 comes with creeks, springs and a “dramatic cave” has hit the market for $54 million, according to a listing by Robert Dullnig of Dullnig Ranch Sales. 

Courtesy of Robert Dullnig of Dullnig Ranch Sales 

The Less Ranch, a 2,269-acre tract of land just off Texas 46 comes with creeks, springs and a "dramatic cave" has hit the market for $54 million, according to a listing by Robert Dullnig of Dullnig Ranch Sales. 

The Less Ranch, a 2,269-acre tract of land just off Texas 46 comes with creeks, springs and a “dramatic cave” has hit the market for $54 million, according to a listing by Robert Dullnig of Dullnig Ranch Sales. 

Courtesy of Robert Dullnig of Dullnig Ranch Sales 

Among the ranch’s most impressive features is its “dramatic” cave, with an Artesian-type water feature discharging an estimated 19,000 gallons of water a day and captured for decades in a 40,000-gallon cistern. Large lakes and creek tributaries are found throughout the property. 

A private runway: Famed architect Victor Hugo Salas Sr., who is known for his custom-made wood and iron constructions and precision millwork, is selling his Pleasanton mansion for $4.9 million. The 6,243-square-foot estate sits on 147 acres in the city of Pleasanton, just south of San Antonio. 

The property is so massive that it has its own runway for an airplane. 

Lazy River Ranch: About an hour from San Antonio and seven miles from downtown Boerne is the $7.3 million Lazy River Ranch. The name says it all. The ranch contains its own private lazy river, according to listing agent Kris Forks with Kuper Sotheby’s International Realty. 

The main house overlooks a canyon that has live water springs and a custom-built 1,400-square-foot pool house with one bedroom and one bath. 

To go along with the lazy river is an Olympic-sized swimming pool with a slide and waterfall. 

Wine cave built into rockbluff: A $1.9 million home billed as ‘truly one-of-a-kind’ in New Braunfels comes with a wine cave built into a rock bluff. 

A $1.9 million home billed as ‘truly one-of-a-kind’ in New Braunfels comes with a wine cave built into a rock bluff.

A $1.9 million home billed as ‘truly one-of-a-kind’ in New Braunfels comes with a wine cave built into a rock bluff.

San Antonio Board of Realtors

Situated on 14-acres, half of the 3,561-square-foot home is on stilts and hangs over the edge of a hill. The hot tub was also built into the rock bluff. 

A private view of the Tower of the Americas: The $1.5 million, three-bedroom, three-bath penthouse occupies the 33rd and 34th floors of the Grand Hyatt hotel in downtown San Antonio. The “breathtaking views” of the Tower of the Americas and downtown San Antonio can be seen through the floor-to-ceiling windows.There’s also a private balcony. 

Through the floor-to-ceiling windows at the penthouse of the Grand Hyatt hotel are “breathtaking views” of the Tower of the Americas and downtown San Antonio. There’s also a private balcony. 

Through the floor-to-ceiling windows at the penthouse of the Grand Hyatt hotel are “breathtaking views” of the Tower of the Americas and downtown San Antonio. There’s also a private balcony. 

Kuper Sotheby’s International Realty

timothy.fanning@express-news.net