Daily Push file photo
A Wise Gardening presentation is demonstrated at a earlier Kiwanis Household & Backyard garden Present. The celebration returns this weekend at the U.P. State Fairgrounds.

ESCANABA — Spring is listed here and with it arrives the Kiwanis Property & Backyard garden Clearly show. The yearly occasion promises to bring the hottest and best of house advancement and landscaping and, of study course, a heaping assisting of pancakes.
The three-working day event kicks off Friday at 5 p.m. In addition to homemade pancakes served by the Escanaba Midday Kiwanis from 5 p.m. right up until doorways shut at 8 p.m., visitors will be able to peruse booths from sellers and local community teams.
“We’re up to comprehensive ability, which is enjoyable for us,” explained Aaron Deiter, of the Escanaba Noon Kiwanis, adding the pandemic has constrained the number of sellers and booths at modern Household & Yard Displays.
Even though the majority of the booths are centered on sharing solutions, services and info linked to all facets of houses, gardens and local community businesses in Delta County, there will be a number of functions aimed at small children. Among 5 and 8 p.m., young children will be ready to take part in a scavenger hunt at the Kiwanis booth, paint flower pots and plant seeds at the Important Club booth, or make crafts at the Bonifas Art heart booth. These pursuits and steam motor rides close to the U.P. Point out Fairgrounds will be obtainable to friends all a few times of the clearly show.
The night also offers a opportunity for gardeners to hone their information. From 5:30 to 6 p.m., Michigan State College Extension’s Wise Gardening marketing campaign will current on priority invasive species in the Central Upper Peninsula. From 6:30 to 7 p.m., Smart Gardening will current on planning food stuff for preservation, which involves discussion on pressure canner lid tests, jar prep and other facets of residence canning.
Saturday is a distinctive day at this year’s Dwelling & Backyard Present, as it’s the working day the Escanaba Noon Kiwanis celebrates its 100th anniversary.
The working day kicks off at 9 a.m. and operates until eventually 7 p.m. Pancakes will be served from open up right up until 2 p.m.
MSU Extension Smart Gardening displays will include “What Are Valuable Bugs and How Do I Invite Them To My Garden” from 9 a.m. to 9:45 a.m. “Small Area Vegetable Gardening” from 10:15 to 11 a.m. a presentation on the Escanaba Community Backyard, the group’s activities and how to become a member from 12:15 to 1 p.m. “Bee Facts” from 2:15 to 3 p.m. and “Horticultural Mysteries” from 3 to 3:45 p.m.
From 2 to 7 p.m., local beer and wine will be served. Grownup company will be ready to delight in drinks from Higher Hand Brewery, Leigh’s Backyard Winery, Herford & Hops and Northern Sunlight Vineyard.
From 5 to 6 p.m., the Kiwanis will rejoice their 100th anniversary with the 1st at any time “Kids Olympics for Older people.” According to Deiter, the unique games that will be performed for the duration of the function are top key but will be similar to children’s playground game titles. The Kiwanis and their 6 strategic associates — Big Brothers Huge Sisters, Kid Advocacy Center, Escanaba General public Library, Northern Lights YMCA, Salvation Army, and Scouts — will struggle towards every other in the celebration, which aims to display the general public how the groups assist neighborhood kids and the local community.
From 5 to 7 p.m., new music will be supplied by Amp’d Enjoyment.
Sunday will spherical out the a few times of the celebration, with the exhibit continuing from 9 a.m. to 2 p.m. Pancakes will be served all over the day, and, in addition to sellers and functions for young children, MSU Extension will current two sessions: “Small House Vegetable Gardening” from 9:30 to 10:15 a.m. and “How To Prune Your Apple Tree” from 11:30 a.m. to 12:15 p.m.
for more information and facts about the Escanaba Noon Kiwanis or the Household and Garden Show, take a look at escanabakiwanis.org.
Landscape Management Network (LMN) and household improvement lender Acorn Finance have joined forces to start a new funding device for landscape contractors and their prospects, the firms said in a Friday (April 8) announcement.
LMN Lend Household Advancement Funding allows contractors who use LMN’s organization management software offer their buyers obtain to Acorn Finance’s marketplace for funding choices up to $100,000, according to the announcement.
“Consumers continue on to invest in their qualities,” claimed LMN CEO Mark Bradley in the announcement. “As a contractor, you want to be equipped to deliver the most effective practical experience probable for your buyers. Figuring out you can now conveniently walk them through financing alternatives as a aspect of the estimate delivers tremendous price to consumers and positions landscape operation owners as true associates in the renovations.”
The organization mentioned in the announcement that this funding option addresses a regimen agony stage for contractors and their consumers: how to simply access the correct funding at the correct time. Position-of-sale (POS) financing can give contractors on big positions enhanced hard cash flow when offering included usefulness to home owners through estimating and proposals.
LMN pointed to investigate showing that customers are more very likely to go forward with house enhancement undertaking when they know they have obtain to funding. The company mentioned its purchaser funding choices will be available to all LMN Pro end users and their clients in the United States.
“Through LMN Lend, when a contractor prepares an estimate for a yard renovation, pool or other main landscape advancements, they’ll be able to seamlessly offer you access to financing options from Acorn Finance’s community of lenders,” the business mentioned in the announcement. “Through an on line application method, property owners will receive funding gives (sum, prices and phrases) in just minutes. As soon as executed, resources are sent to the property owner in as very little as 24 hrs.”
Acorn Finance presents a network of 12 loan providers who bid to finance home improvement tasks. In 2021, the amount of prospects trying to get financial loans as a result of its system rose by 800{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Acorn explained.
Last month, the Sacramento, California, business introduced a partnership with Joist — an estimating and invoicing application for contractors — to embed funding gives into Joist’s system.
Read through more: Household Improvement Lender Acorn Teams up With Contracting System Joist
——————————
NEW PYMNTS Details: WHY Client PORTALS ARE Getting Table STAKES TO Individuals
About: Affected person portals are now a need to-have for vendors — so a lot so that 61{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of clients intrigued in using the tools say they would swap to a healthcare provider that delivers one particular. For Accessing Health care: Easing Digital Frictions In The Affected individual Journey, a PYMNTS and Experian Overall health collaboration, PYMNTS surveyed 2,333 consumers to understand how health care vendors can ease digital ache points to offer you enhanced client care and gratification.
Ludomir Wanot knew early on that he wanted to use real estate as a tool to build wealth.
He bought his first property with his brother in 2016. They used an FHA loan and put 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down.
His main revenue stream is wholesaling. On his first wholesale deal, he profited $160,000.
Ludomir Wanot tapped into his entrepreneurial spirit early on.
He started selling candy in elementary school. He’d buy jawbreakers with the couple of dollars his mom could afford to give him each day and sell them for a profit to his classmates.
When he was 15, he started buying and selling cars on Craigslist. He’d been working for his dad since he was 13 — mostly installing floors — and saved up enough money to buy his first car, a used Volkswagen Jetta, for $4,000. Less than two weeks later, he sold it for $5,500, he told Insider. “I was like, ‘Holy crap, I just made $1,500 in a week and a half. Can I do this again?'”
Wanot, who grew up in Federal Way, Washington, researched the car market in the area and found that Volkswagens were very popular and in high demand. So he started buying and reselling that specific car brand. He earned $1,000 on average per flip — and he barely did any work on the cars, he said. “I never fixed them up or anything. I’d just clean them and take professional photos.”
His key advantage was his ability to negotiate, he added: “I would buy directly from owners and I would just negotiate prices with them over the phone.” While he was not a licensed dealer, within two years, Wanot earned about $35,000 selling 35 cars. He says that he gave most of the money to his mom so she could visit family in Poland, where she’d emigrated from before he was born.
His business mentality emerged out of necessity. After his parents split up when he was seven, Wanot’s mom raised him and his two brothers. She worked three different jobs to provide for her sons, but still struggled to stay afloat and gradually accumulated a significant amount of credit card debt. Every two years or so, she had to move her family into a different apartment when the rent would inevitably go up. Wanot used the money he earned from his various businesses to pay for food on days his mom couldn’t afford to give him and his brothers money for breakfast.
“From a very young age, I knew that money could give me options, and I wanted more options in my life,” said Wanot, now 30. “So I started thinking about how to earn more money.”
A quick Google search piqued his interest in real estate investing: “I found online that 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all millionaires became so through owning real estate.” He was a teen at the time and didn’t have the means to invest, but after developing a knack for sales and understanding the principles of risk, he decided that real estate would one day be his path to wealth.
Buying his first property with his brother with less than $10,000 upfront
Wanot graduated from University of Washington’s Foster School of Business in 2014. His education was completely funded by scholarships and grants, he said. Plus, he worked all throughout college. He installed flooring and built a construction business, WA Flooring, out of it.
After graduating, Wanot tried to grow his company, but the income wasn’t as consistent as he wanted it to be. He still aspired to buy properties one day and knew that
mortgage lenders
would want to see a stable income history before offering him a loan, so he started thinking about transitioning into the corporate world. In the meantime, though, he was able to get his foot in the door by partnering with his older brother, Jan.
Jan, who’d been working at Boeing for about two years, qualified for a loan and the brothers started searching for properties in the Seattle area in 2016. Jan would be listed as the buyer but they agreed to split expenses and profits evenly.
“I knew from my Craigslist experience that there were so many opportunities out there at a discount,” said Wanot, who would specifically seek out properties listed for sale by their owner, which cut out agent commissions and typically meant a lower sale price. “So we just set up searches on Craigslist and, as soon as a property popped up that was for-sale-by-owner, we would call the homeowner and try to buy their property at a discount.”
They found a single-family, fixer-upper listed for $150,000. “I was able to negotiate her down to $138,000,” said Wanot, who was living in his mom’s apartment at the time to save on housing. “I knew that every dollar mattered for us.”
The first property Wanot invested in: a four-bedroom, single-family home.
Courtesy of Ludomir Wanot
The brothers financed it with an FHA loan, which is a government-backed mortgage that gives people the opportunity to buy a home with lower credit scores and down payments as low as 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. They ended up using what’s called an FHA 203(k) loan, which finances the purchase and renovation of a home.
Without this specific type of loan, they wouldn’t have been able to afford renovations, which ended up costing $30,000. But since they rolled the remodeling costs into the loan balance and put down 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, “we were in for no more than $10,000,” said Wanot.
They split the upfront costs, meaning they each paid less than $5,000, which Wanot had in savings from his flooring business.
A requirement of using an FHA loan is that you have to purchase a primary residence and live in it for at least a year before renting it out. After a three-month-long renovation process, Jan moved into one of the four bedrooms, while Wanot continued living in his mom’s apartment. They rented out the other three bedrooms to college students and collected $1,850 in rents each month, which more than covered their $1,100 monthly mortgage payment.
After deducting utilities, the brothers earned $600 per month in cash flow. That single-family home, which they still own today, was Wanot’s first passive income stream.
Taking a job at Amazon and saving up to continue buying real estate
After finding success in his first deal, Wanot wanted to continue expanding his real estate portfolio but he needed consistent income to qualify for a loan.
He started job searching and landed a gig at Amazon in 2016. Wanot, 24 at the time, wasn’t necessarily passionate about his work as a program manager, but it paid well — $120,000 a year, he said — and was a stepping stone to buying more properties.
He continued living with his mom and doing flooring jobs on the side, which allowed him to save his entire Amazon paycheck. “I could earn about $3,000 a month with flooring, and that would sustain my lifestyle,” he explained. “So, every dollar that I earned from Amazon, which was exactly $6,800 after taxes, I would save.”
Wanot (right) and his family.
Courtesy of Ludomir Wanot
After just a couple of months of diligent saving, he had earned enough to pay off his mom’s $25,000 worth of credit card debt. Once she was debt-free, all of his savings went into an account earmarked for his next property. He and his brother again decided to go in on it together. This time, they bought a $350,000 fourplex in 2017. It also needed renovations, and they financed it with another FHA 203(k) loan.
“We did a massive $180,000 remodel,” said Wanot. “So, our loan was for about $530,000.” They put 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down again, meaning they only had to come up with about $18,500 in cash upfront, which they split. The brothers then spent the next six months renovating the property. After completing the work, Wanot moved into one of the units and the brothers rented the other three. Rental income covered more than their monthly mortgage, meaning Wanot lived for free. Plus, he and Jan profited about $1,200 each from the property each month.
Shifting to wholesaling and earning $160,000 on his first deal
Despite earning six-figures at Amazon and pulling in side money from his real estate investments, Wanot continued thinking about other viable revenue streams.
“I knew that I could sell — I knew that I was good at flipping cars,” he said. “And I thought, ‘Okay, what’s the next biggest thing?'”
That’s when he started looking into wholesaling. The way the real estate wholesaling process works is the person acting as the wholesaler enters into a contract on a home or piece of land, finds a buyer willing to purchase it at a higher price, and then pockets the difference in price once the transaction closes.
Wanot decided to put his sales skills to the test once again. He pulled a list of about 350 landowners in Tacoma, used a public data platform called PropertyRadar to get their phone numbers, and started calling up every landowner, asking if they were interested in selling their property.
“I had a script written out and I just made call by call,” said Wanot. It was a tedious activity and, “a lot of them were really angry that I called, he added.” It took about 300 calls, but a landowner interested in selling his property in Bainbridge Island finally picked up the phone.
“I didn’t know what the heck I was doing,” recalled Wanot, who immediately went to visit the potential seller and started researching how to get a piece of land under contract. He managed to put together a contract to buy the property for $800,000 with a 90-day feasibility, meaning he could terminate the contract for any reason within that period.
“For the next 90 days, I called every single investor that I could possibly find using online sources, Facebook, and LinkedIn. I looked everywhere,” said Wanot. He found a buyer willing to pay $980,000 for the land and, after paying his designated broker $20,000, Wanot took home $160,000, he said. “I’d never made that kind of money before. I had just earned more than I did at Amazon in the year-and-a-half that I’d worked there on one transaction.”
Wanot says he achieved financial freedom at age 28.
Courtesy of Ludomir Wanot
That was in 2018, just as the US housing market was picking up steam again after a decade of
recession
. Shortly afterwards, Wanot decided to quit his job at Amazon to focus on wholesaling. He didn’t jump into it right away, though. “I spent the next 18 months reading every book I could about wholesaling, passive income, and investing,” he said. “I lived purely on my passive income. And I had saved up a lot from Amazon and my construction company.”
In August 2020, he co-founded a wholesaling business, Evergreen Housing Network with his business partner Vernie Gonzalo Dahl. Wholesaling remains his biggest revenue stream today. In 2021, Wanot and his partner earned nearly $1 million in profit, according to documents viewed by Insider.
“We find people that want to sell their homes without the headache of listing it on the MLS or waiting months for their house to sell,” explained Wanot. “Once we get a property under contract, we source a buyer from our list of investors or home buyers and sell them the property directly for a higher price. Our business earns an assignment fee for each deal that we close, similar to how real estate agents earn commission for selling a house.”
Wanot’s 11-person team does about sixty deals per year and averages $35,000 per deal in revenue, he said.
His other revenue stream is rental income. As he started earning more from wholesaling, Wanot continued expanding his real estate portfolio. Today, he profits about $50,000 each year in rents from the 13 units he owns throughout central and western Washington, he said. Plus, he estimates he’s built roughly a combined $500,000 in equity from all of his properties in the past year alone.
Living on $3,000 a month and achieving financial freedom through real estate investing
Wanot says that he achieved financial freedom about two years ago, even before his wholesaling business took off.
He’s learned that, “you don’t need to create a lot of wealth for yourself to be financially free.” The first step he took towards hitting financial freedom was understanding exactly how much money he needed to sustain his lifestyle.
“I wrote down everything that I spent on a monthly basis — rent, healthcare, insurance, transportation, food, clothing, and entertainment — and realized that I only needed about $3,000 to cover my essential living expenses,” he said.
Wanot lives with his girlfriend in Tacoma.
Courtesy of Ludomir Wanot
Once he had that number in mind, he set the goal of earning $3,000 a month in passive income through his cash-flowing investments. At that point, when his passive income could cover his living expenses completely, he’d consider himself financially free.
“When I picked up my third property, I finally surpassed the $3,000 mark,” he said. That was about two years ago, when he was only 28 years old.
Today, despite earning significantly more, he maintains a relatively frugal lifestyle and still spends about $3,000 a month on his living expenses. However, he now lives with his girlfriend in Tacoma and the two split their cost of living. All of his extra savings go into an account earmarked for future real estate investments.
“As long as you can live within your means, and you understand your basic necessities, then it’s very possible to create financial freedom,” said Wanot. “I’m there. And now, everything on top — it’s just like a fun game of Monopoly.”
Many of the most affluent of Massachusetts’ residents live outside the city in smaller towns like … [+] Dover, Sherborn and Carlisle.
getty
Massachusetts is a state of wealth—a wealth of history, education, and wealth itself.
According to the U.S. Census Bureau, Massachusetts is the second wealthiest state in the U.S., with a median household income of $85,843 compared to the national median of $65,712.
While much of the state’s most expensive properties are set in Boston, many of the most affluent of Massachusetts’ residents live outside the city in smaller towns like Dover, Sherborn and Carlisle.
One such town, Weston, is the wealthiest.
The Massachusetts suburb of Weston continues to draw more and more of American’s wealthiest families … [+] each year.
Bassick Real Estate Advisors
Located just 15 miles west of downtown Boston, Weston is not only one of the richest towns in Massachusetts but also in the nation, with a median household income of $206,250.
It’s no accident, however, that this small, New England suburb is largely unknown to those from out of state—residents pride themselves on their well-kept town but often brush off its moneyed reputation.
“Sure, the town is home to billionaires, but you see behavior so uncharacteristic of that,” says Catherine Bassick of Bassick Real Estate Advisors, one of Wall Street Journal’s top 100 agents in the U.S. and a resident of Weston. “People are putting out messages during snowstorms that say their kids can come shovel snow for the elderly. Someone even brought me chicken broth when I got a cold! There’s still a strong sense of community.”
MORE FROM FORBESBoston’s Luxury Single-Family Home And Condominium Market Ends 2021 Stronger Than EverBy Ellen Paris
With over 300 years of history, the town is currently at something of a crossroads. The pandemic-fueled urban migration has brought a new wave of interested buyers, straining a supply primarily consisting of long-established homes.
But while this demand may give rise to new construction, an array of building and zoning restrictions have kept over-development at bay, maintaining the town’s quiet and idyllic charm, Bassick shares. “People love it here because it’s an authentic community. Plus, the setting looks like a Hallmark movie.”
When it comes to the homes of Weston, prepare to be charmed inside and out. Most homes features … [+] character details and have been upgraded with top-tier amenities.
Bassick Real Estate Advisors
Homes In Weston
While the town may possess a certain rustic quaintness, the luxury homes are anything but.
Large estates reaching well above 10,000 square feet can be found about town, including stately manors of Colonial and Georgian designs dating back to the early 20th century.
Many of these sizable luxury homes feature classical rooms like libraries, ballrooms, and wine cellars and housing more modern spaces like gyms, movie theaters, and indoor spas.
MORE FROM FORBESBoston Area Estate Entwined In Local History Seeks $7.9 MillionBy Lauren Beale
Exterior space is also ample in Weston—the town’s population of about 11,800 is spread out over 17.3 square miles, meaning the density breaks down to roughly one acre per person—and many homes are located on multi-acre lots. Well-maintained gardens, walking paths and patches of forest are common on estate grounds.
Though the area may be famous for its more illustrious homes, a variety of residences can be found.
“Not everyone lives in a big mansion. There are people here who live in more modest homes,” Bassick says. “But the magnificent homes are truly magnificent.”
The Ridgehurst estate at 80 Orchard Avenue is situated on one of Weston’s private drives, abutting … [+] pastoral Weston Conservation land
Bassick Real Estate Advisors
Real Estate Prices In Weston
According to data from Redfin.com, the median sale price for homes in Weston was $2,453,000. In November 2021, the median was about $1.29 million. This disparity results from so few homes being on the market and thus few homes selling per month, meaning one sale can greater alter averages.
Lower price points in the area still hover around $1 million. For that price, buyers can expect single-family homes ranging from about 2,000-3,000 square feet in more densely populated neighborhoods.
Multi-acre estates make up the most expensive properties in the area, with prices reaching upwards of $15 million.
MORE FROM FORBES$3.6-Million Greater Boston New Build Draws On Colonial RootsBy Lauren Beale
The Vibe Of Weston
Given the town’s long history, notable historical landmarks are in abundance, including many structures that pre-date the American Revolution.
The area’s downtown recently underwent an $18-million face-lift, improving the town center’s look, function, and safety. These improvements ranged from new public spaces to installing four-way stop signs.
Although the downtown area is home to many businesses, you won’t find a bar, as Weston is a dry town. For bars and restaurants, many residents head to nearby Boston.
The population age in Weston is fairly evenly dispersed, with residents under the age of 18 making up 25.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and residents over the age of 65 making up 20.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, per the most recent data from the U.S. Census Bureau.
The Harvard University campus is located roughly 30 minutes from Weston.
getty
Schools in Weston
There are five schools in the Weston Public School District—three elementary, one middle and one high school. The district serves roughly 2,100 students. Nearly 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of students in Weston attend a private school.
Prominent institutions in the area include the Meadowbrook School of Weston, a pre-kindergarten through eight-grade co-ed school located on a 26-acre campus and the Cambridge School of Weston, a day and boarding school founded in 1886.
MORE FROM FORBESGreater Boston Continues To Be One Hot Market With Price Increases And Low InventoryBy Ellen Paris
Surrounding Weston
Roughly 100 miles south of Weston is Martha’s Vineyard, with another popular destination, Nantucket, located about 20 miles beyond. Boston Logan International Airport is 17 miles east or about a 30-minute drive.
Bassick Real Estate Advisors is an exclusive member of Forbes Global Properties, a consumer marketplace and membership network of elite brokerages selling the world’s most luxurious homes.
In this panel from OZ Pitch Day Spring 2022, a trio of experts discuss the various strategies that investors can use to optimize the tax efficiency of their portfolios.
Webinar Highlights
The ongoing disconnect between housing supply and demand that will likely persist for years to come, and how that creates an opportunity for high net worth investors.
The relative merits of 1031 exchanges compared to Qualified Opportunity Funds.
Scenarios where Opportunity Zones may be particularly attractive — and other scenarios where the clear preference may be for a 1031 exchange.
How depreciation can have a major impact on returns realized in OZ investments.
Live Q&A with webinar attendees.
Industry Spotlight: Cantor Fitzgerald
Cantor Fitzgerald is a leading global financial services firm, serving clients from over 30 offices around the world. Founded in 1945 as a securities brokerage and investment bank, the firm pioneered computer-based bond trading, built one of the broadest distribution networks in the industry and became the market’s premier dealer of government securities.
Investment Management. Jay is involved in overseeing the day-to-day operations of the business, providing direction and implementing strategic initiatives.
Realized is an end-to-end platform that lets investors exchange 1031-eligible properties for diversified portfolios of property interests, customized to your shifting income needs, risk appetite, and investment goals across generations.
In his role as Head of Wealth Management for Realized, Rob is responsible for overseeing the client’s Investment Property Wealth Management (IPWM) experience. In addition, Rob works with Registered Investment Advisors (RIA) and Broker Dealer networks throughout the United States in an effort to increase awareness of the 1031 exchange and Delaware Statutory Trusts (DSTs) to support client financial planning needs.
MultifamilyInvestor.com covers trends and opportunities in multifamily real estate investing. We help High Net Worth investors, family offices, RIAs & financial advisors, and industry service providers navigate the ins and outs of the multifamily landscape.
Jimmy: Well, today’s panel is Opportunity Zone investing or Opportunity Zone benefits for high-net-worth investors. My three panelists here today, I’m gonna introduce them very briefly. We only have 20 minutes, so it’s gonna be kind of rapid-fire. But Jay Frank, joining us from Santa Monica, California. He’s president of Cantor Fitzgerald capital and co-head of their real estate investment management business. Scott Hawksworth joining me here today from Chicago, Illinois. He’s co-founder of MultifamilyInvestor.com and host of the “Multifamily Investor” podcast, which is a resource for passive high-net-worth real estate investors. And Rob Johnson also joining us today. He’s here from Austin, Texas. Rob is head of wealth management for Realized. They’re a platform for investment property wealth management, and they specialize in 1031 DSTs and, of course, opportunity zones. So, gentlemen, I wanna start with Scott Hawksworth first.
And Scott, the reason why I wanna start with you is because multifamily is by far and away the most popular sector for Opportunity Zone investing. In fact, 9 of the 12 Qualified Opportunity Funds that are partnering with us on today’s event are multifamily funds, or at least have a very strong multifamily component. So, Scott, why do you like multifamily as an asset class for high-net-worth investors?
Scott: Yeah, thanks, Jimmy. I like multifamily as an asset class for a number of reasons, but I think the biggest reason is we have an ongoing housing shortage in this country. We are underbuilt, and that creates tremendous opportunity for high-net-worth accredited investors. And that kind of underlines what you were just mentioning about the number of funds that have multifamily. And there’s a statistic that I like to point out here, and I have it right here. And this is according to a recent report from the National Association of Realtors. We have an underbuilding gap of 5.5 to 6.8 million housing units. And that has been ongoing since about 2001. So, again, that’s a mismatch between supply and demand. And so there are these funds that are addressing this issue. But even with all of that activity, the demand is not going away, and the supply is just not meeting it. And you see this all over the country. So, I think when we’re talking about the opportunity for return, it’s really tremendous. And that’s why I like multifamily.
Jimmy: Good. Let’s turn to Rob next. A lot of real estate investors traditionally are very familiar with 1031. It’s been a traditional tax advantage vehicle for high-net-worth real estate investors for decades and decades and decades. Can you compare and contrast the section 1031 exchange with Opportunity Zones? What do investors need to know?
Rob: Yeah, no, that’s a great question. So, we get that frequently from clients who could go either way, and they’re gonna evaluate the considerations and upsides of doing one or the other. So, let’s talk about the eligible gains. With a QOZ Fund, any capital gain, regardless of the asset that generated, that gain can go into a QOZ Fund. For a 1031 exchange, it’s limited to gains from real property held for investment or used in a trade or business. So, it’s extremely clear. One is real estate-based. The other one is gonna be any capital gain. The reinvestment of proceeds. What’s nice about the QOZ Fund is you’re only going to reinvest the capital gain. You can reinvest the basis, but it’s not gonna receive the tax benefits. So, quite honestly, we discourage a client from doing that. In the 1031 exchange, you have to reinvest all proceeds, both your basis and the gains. And you have to have the same, or greater amount of debt through the 1031 exchange. So, there are some IRS policies that have to be followed.
The time to reinvestment with the QOZ Fund. You have 180 days, and the gain must be triggered on or before December 31st of 2026. With the 1031 exchange, the time constraints can be very onerous. You’ve got 45 days after the sale of that property to identify what your replacement is gonna be, and then 180 days to reinvest. But you are stuck with what you identify in that 45-day period. So, if you, you know, identify something you don’t close on, it’s gonna blow up your exchange. The replacement asset Qualified Opportunity Zone Funds. You’re gonna invest 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the assets in the QOZ property. Real property must be like-kind. So, the IRS is gonna keep a very close eye on what exactly you use to replace that property, and it has to be the real property designation underneath the IRS.
Location of replacement asset. Obviously, the QOZ is in an Opportunity Zone. It has to be designated by the census. With the 1031 exchange, you could pretty much go in any U.S. state and region that you want. Qualified intermediary, or QI, or an exchange accommodator is gonna be required for 1031 exchange. They have to hold the money. If you don’t pass the proceeds onto them from the sale of the property, you’ll blow up your 1031 exchange. You don’t need a QI in a QOZ transaction. Minimum holding period, the QOZ, at least 10 years to achieve the maximum tax benefit. With the 1031 exchange, it’s really gonna be when… You have to have it for a minimum, in most cases due to IRS policy in terms of a hold. But after that, you can exit when you find a potential buyer for the property. And the tax on the gain generated by the replacement asset for the QOZ, it’s eliminated if held for 10 years, maybe eliminated upon the investor’s death. With the 1031 exchange, it’s due upon the sale of the asset, but they also can qualify with the step-up basis. So, those are the main differences with the QOZ versus the 1031.
Jimmy: Yeah, no, that was a great breakdown, Rob, very, very in-depth, very detailed. Jay, kind of want you to kind of take that and keep going here, comparing and contrasting OZs with 1031s. Jay, Cantor Fitzgerald, I know you have a lot of high-net-worth accredited investors that you advise on this situation all the time as well. And, you know, just like Rob does. How often for you do you find that an Opportunity Zone investment is better than a 1031? And when should investors selling real estate really consider OZs as opposed to…or as a replacement for 1031?
Jay: Yeah. Great. And nice job, Rob. I’m happy to pick up where you left off there. Section 1031 in the tax code has a lot of complexities to it, right? And you should be talking to at first, at a minimum, your CPA or tax attorney, maybe your state planning attorney, and probably a financial advisor. Opportunity Zones to take that complexity to the next level. So, you know, to the nth degree, there should be that team involved in the process because when you are making a decision between one or the other, or don’t forget, you can also invest in both simultaneously. It’s not always opportune, but you can. There’s a lot of different considerations, not just in terms of the investment return, investment time period, horizon, you know, income versus growth when you’re gonna get the returns, etc., like Rob was touching on, but also it has to do with the client’s personal situation. What account that they’re holding it in? The estate planning needs. What tax bracket they’re in? What state do they live in? There’s a whole bunch of, you know, economic considerations, but then there’s a whole bunch of human considerations that go into this.
The general rule that we refer to when you’re kind of comparing a 1031 to an OZ, obviously, only for someone selling investment real estate is when they both are in play. If an OZ tends to be preferred when the client has a basis in the proper they’re selling and/or a little debt. So the more basis they have, the less amount of debt they have, the more the opportunity that it’ll be attractive. So, Jimmy, you bought some land in Dallas, a $ 1 million dollars, it’s land, so you don’t have depreciate it. So, your basis is a $1 million. A few years later, you sell it for a $1.5 million and you have no debt. If you do a 1031 exchange, all $1.5 million would need to go in the exchange to defer a 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your taxes. With an Opportunity Zone, you’d be able to take the million dollars of basis out tax-free, put it in your pocket, diversify it. And only the $500,000 of capital gain would need to go into the Opportunity Zone Fund to defer a 100{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your tax liability. So, in that situation, I’d say 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} plus of the time, an investor that’s informed and has good advice, would be looking at an Opportunity Zone.
On the flip side, the other bookend where a 1031 tends to be superior is when the lower the amount of basis the client has, often zero basis, and the more debt they have on the real estate property they’re selling tends to be when the 1031 is superior. And the reason why is, example, Jimmy, you bought a rental property in Dallas for a million bucks, you sold it for a $1.5 million. However, you owed it for 30 years, you’ve depreciated it to zero and you have a million-dollar loan on the property. If you were to put your money in 1031, you simply need to take the $1.5 million and complete the exchange. You defer all your taxes. To do an OZ and defer all your taxes, you’d have to first take your $1.5 million and pay off a million-dollar loan to the bank. You’d have a $500,000 left over to invest in the OZ. Then, you’d have to come up with another $1 million out of pocket to invest in the OZ to address your deferred and recapture depreciation tax. So, it really depends on the client situation, both economic considerations, but also human considerations. And it’s a small amount of time, but there are times when you can use a combination of 1031 exchanges and Opportunity Zones on the same transaction.
Jimmy: Great. I think that was an awesome breakdown that both you gentlemen gave. Jay and Rob, thank you so much for that. I think that’s helpful to a lot of investors on the call today who have familiar with 1031s, maybe they’re starting to learn about OZ. Always good to compare and contrast those two programs. I wanna pulse Scott back in, give him another question about multifamily. That’s his area of expertise. So, Scott, you know, just kind of looking at the world at large over the past 24 months or so, we’ve really been in a period of a lot of economic uncertainty with the COVID pandemic and the resulting recession, the imbalance in the labor market. And now the war in Ukraine is kind of making everybody a little jittery, a little bit more uncertain. Do you still like multifamily during this period of economic uncertainty?
Scott: Absolutely. I think it really gets down to the basic fact that everybody needs a home. They need to live somewhere. And multifamily really addresses this need. And then when you look at it at the real estate sector and where it fits traditionally, multifamily has been among the most resilient. So, does well in terms of generating returns in periods of economic expansion and in times of economic uncertainty, or even recession, multifamily has performed well. And I would also say, as you’re kind of looking back through it, we’re coming out of COVID-19, it’s also created a lot of shifts in lifestyle, and work from home, and all of that. And so that really is attractive to a lot of potential renters and has really driven up the need for that housing and for their expectations on amenities and having quality housing and really having folks really reevaluate the four walls that they’re spending their time in. So, I think, for me, even in a climate of economic uncertainty, multifamily is still something I’m very bullish on.
Jimmy: And regularly tying it back into Opportunity Zones and Opportunity Zone investing, multifamily is where it’s at typically for the types of real estate assets that we see, you know, I think, more than half. According to the most recent Novogradac survey, more than half of the capital raised, data’s been going into funds that have, at least some sort of strong residential or multifamily component. And, you know, bringing it into the Opportunity Zone communities really gives investors a chance to do well by doing good, not only are they providing much-needed housing for this country but also they’re doing it in the areas that need it most, these traditionally underserved economically downtrodden communities.
Jay, let’s bring you back in now. Just one more question for Jay and Rob. We gotta wrap things up here pretty quick. But, Jay, why are we seeing more real estate gains from investment properties going into Opportunity Zones? And in your experience, maybe I’m kind of giving away the answer, I’m leading the witness here a little bit, but does the average financial advisor know enough about Opportunity Zones to properly advise high-net-worth investors their clients on that option of OZ investing?
Jay: No, you got it. And it’s not just the financial advisor, it’s fill in the blank advisor, you know, legal advisor, tax advisor, financial advisor, you know, spousal advisor, whatever it is. Many people just are ignorant to the opportunity. I would also add that people miss one of the key elements that make Opportunity Zone viable for real estate changes, which is, it’s not just the capital gain from this sale of an investment property that can be invested in the OZ in realized the tax benefits. It is also the unrealized depreciation expense. At least the straight-line portion of it, is also eligible. And that key element is what… So, if you had, you know, again, a $500,000 gain and $700,000 depreciation recapture expense, most people think, “Well, I can invest a $500,000 million. I have to pay taxes on the $700,000.” They don’t realize that all $1.2 million could go to get all the tax benefits.
Another thing about depreciation is, remember you’re building brand new properties, which means you have a full depreciable schedule. You can be using, you know, multifamily as a shorter depreciable life than most, again, a bonus there. You can be using cost segregation, component depreciation to really accelerate depreciation, and you can be using bonus depreciation, which was also part of the same Tax Cuts and Jobs Act that created the OZ program. Meaning, said in another simple way is there is so much depreciation that can be passed through in the first 7, 10-year useful life of these assets that the amount of taxable rental income, the investors are gonna be received from these things are probably zero or very close to it. So, there’s two ways that people are unaware of how depreciation plays in and can benefit from the OZ program, A, can be invested in the program, but B, all the appreciation from the program is also gonna be tax-free, assuming you hold it for the required period of time.
Jimmy: Terrific. Yeah, no. Great points there, Jay. Thank you. That’s really interesting about the depreciation as well there. Rob, I’m gonna leave you at the final word here. We gotta cut you guys loose here in a couple minutes. I got my next presenter coming on at 35 after the hour here. But Rob, looking at the future here, I’m gonna turn to you. Opportunity Zones in 2022 and beyond. You know, we’ve gone through that expiration of the 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} basis step-up at the end of last year. So, we’re kind of looking forward to the future program over the next, you know, four-plus years when it is scheduled to sunset. How do you view that opportunity today and going forward, and any additional thoughts or insights you have on opportunity zones?
Rob: Yeah, I mean, I would say that it’s taken too long, in my opinion, for investors to make full use of the Qualified Opportunity Zone opportunity. It got off to a little bit of a slow start. We’re seeing a lot of investors utilize it now for the right reasons, not just for deferral but for planning, long-term planning, retirement, estate planning, things that we normally would use with more traditional investments. They’re benefiting from a Qualified Zone Fund and investment in that manner. So, I hope more individuals are aware of the opportunity that this provides. And my hope is also that the government, as the years go on, understands the benefit of reinvesting in challenged communities, challenged areas, and the benefit that can lead to our society, communities, education growth, you know, the ability to live in a community that’s safe and leads to, you know, better society. So, I hope that the opportunity continues from a legislative purpose.
Jimmy: Agreed. And with any hope, fingers crossed, we’ll get this thing extended at some point. Well, I’m gonna end this session there. Hopefully, that was helpful for you as a high-net-worth investor. Some of the options you have and some of the considerations you should make when contemplating an Opportunity Zone investment, especially with you’re comparing it with a section 1031 exchange, and especially if you’re a multifamily investor. This has been Jay Frank with Cantor Fitzgerald, Scott Hawksworth with multifamilyinvestor.com, and Rob Johnson with Realized. I’m gonna cut you gentlemen loose here and demote you to participants again, but thank you for attending today. Appreciate it.
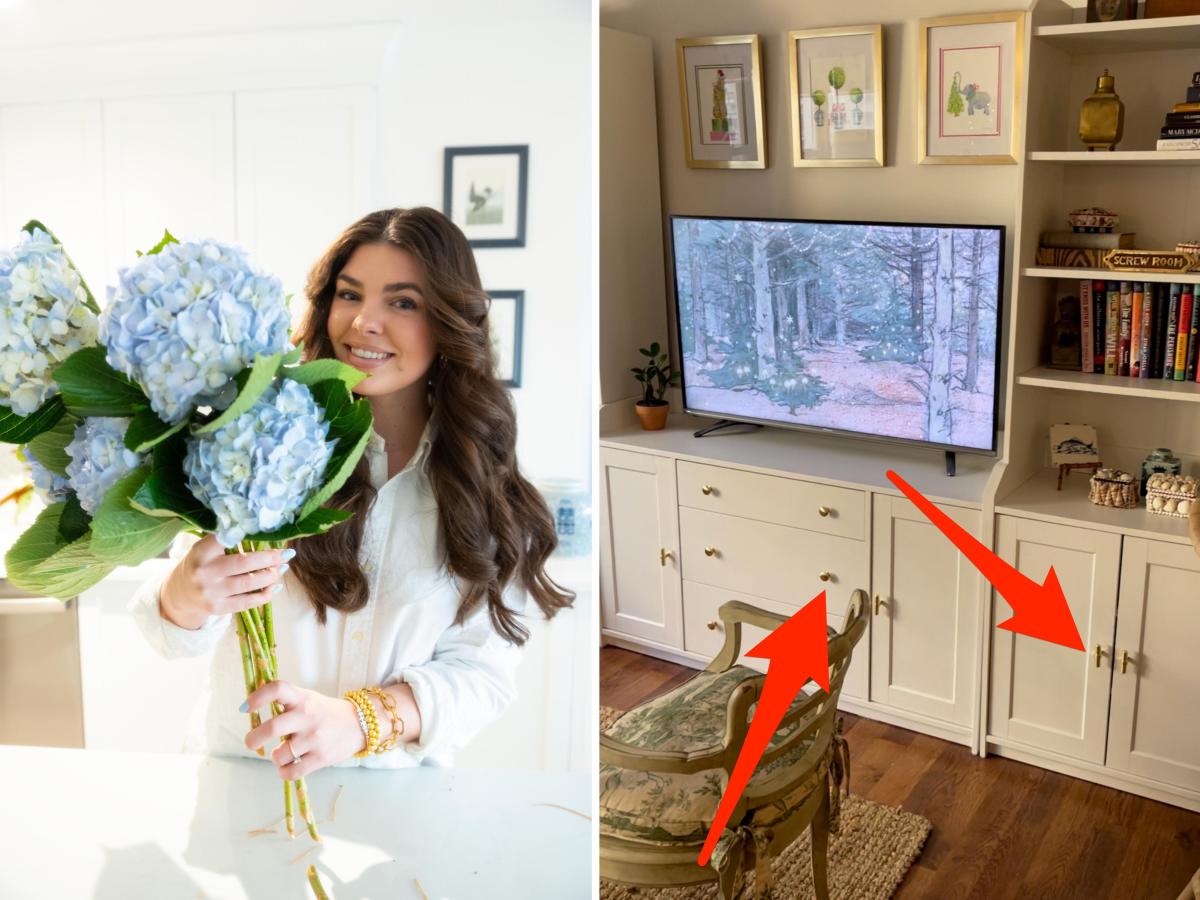
Clare McLaughlin, a TikTok home-advancement qualified, and her residing space.Clare McLaughlin
A TikTok household-advancement skilled who gives spending plan-luxurious strategies shared hacks she makes use of in her individual house.
Clare McLaughlin instructed Insider she kinds textbooks by color and employs picket dividers in drawers.
She also claimed people today ought to think extended-phrase when purchasing household furniture alternatively than adhering to traits.
A spending budget-luxurious expert can make viral TikTok films presenting affordable dwelling decor suggestions to her significant subsequent on the application.
Clare McLaughlin, a price range-luxurious specialist who shares house improvements on TikTok.Clare McLaughlin
Clare McLaughlin is a 28-yr-aged information creator with a track record in inside design and style, centered in New York Metropolis. She experimented with creating TikTok movies centered on her artwork in April 2020, ahead of tapping into a rising need for residence interiors hacks.
Considering the fact that then, her TikTok account has grown to a surplus of 998,000 followers, who can ordinarily expect lifestyle and house business hacks, with a “finances-luxury” concentrate. McLaughlin advised Insider that spending plan luxury is all about “being resourceful with your existing residing circumstance.”
“I required my property to come to feel deluxe but I didn’t want to go broke executing it,” McLaughlin said. Here are the minimal-work updates she produced to her dwelling to make it experience far more expensive without the need of breaking the lender.
Purchase much less highly-priced units and boost them with a lot more luxurious facts.
A before and immediately after shot of Clare McLaughlin’s modified drawers.Clare McLaughlin
“Occasionally the most pricey significant furniture retailers have almost everything made with questionable labor at a stunning portion of the conclude price,” McLaughlin mentioned. Instead, she explained potential buyers ought to break down what they value about a superior-stop piece, whether or not that’s brass components or door handles, and search for out these features for a lot less.
“Hold people matters in mind when searching for a fewer high-priced device,” McLaughlin claimed. “You can often swap out the existing, low cost hardware for nicer pulls and knobs.”
In her personal dwelling, McLaughlin mentioned she changed grey plastic knobs on her drawers with brass ones and it elevated the piece for a portion of the value. She also bought adjustable picket dividers for drawers which make them glance custom made-created.
Use antique indicators rather of modern-day decor with crafting on it.
Indicators reading through “Screw Space” and “bathroom” in TikToker Clare Mclaughlin’s dwelling.Clare Mclaughlin
Mclaughlin stated that people today must embellish their households in any way that can make them joyful but for these actively trying to get a luxury come to feel, prevent modern decor with words or phrases on.
“I am going to acknowledge that it is really surely uncomplicated to see a ‘French Laundry’ cursive font on a distressed wood signal and feel it’ll adjust the total vibe of your home, but these items cheapen the appear of your room,” she said.
If you’re definitely fully commited to the strategy of producing on homeware, Mclaughlin endorses antique signals as a good compromise due to the fact they assist your household appear curated and superior-conclude.
Mclaughlin has a navy-blue and white antique “bathroom” indicator exterior her toilet. “It really is little, subtle, and authentic — and it was only $5,” she explained. “Why invest in a little something new that is developed to search outdated when you can pay the very same selling price for the antique first?”
Sort guides by coloration or remove their sleeves to include fascination to your shelves.
Vibrant bookshelves in TikToker Clare McLaughlin’s home.Clare McLaughlin
Color-blocking bookshelves is a absolutely free hack that McLaughlin executed in her household to make it sense more coordinated. “If you evaluate all of your books, you’ll probably notice that they tumble into specified shade teams,” she stated. “I removed the e book jackets to expose far more solid spines, and the end final result looked good.”
The content material creator included that she’s viewed trends exactly where purchasers pay out hundreds of bucks for matching textbooks to make their dwelling search cohesive. She claimed she uncovered this fairly “unhappy” and encouraged persons to only decorate with issues they genuinely love as this will also help you save revenue invested on needless buys.
Spend in home furnishings that is timeless so it won’t go out of fashion.
A view of Clare McLaughlin’s bedroom interiors.Clare McLaughlin
A ultimate idea, and a person that McLaughlin individually life by, is not to observe structure traits and decide for evergreen furnishings. “Prior to you commit $7,o00 on a lime eco-friendly bubble boucle sofa, request you no matter if your 60-12 months-previous self will like it,” she instructed Insider, noting that decor can grow to be a major expenditure if you obtain seasonally.
For merchandise that stand the test of time, McLaughlin advisable shaker door panels on cupboards, home furnishings crafted with bamboo or wooden, and white or beige materials.
She added that most of the items she has gathered will occur with her to long run properties and even go to her little ones a single working day: “My home furniture is just not pricey by any means, but I have sourced items that are very well produced and significant top quality, by way of thrifting and picking out inexpensive things that were being developed with regard to background.”