Nationwide Affiliation of Dwelling Builders CEO Jerry Howard argues he’s ‘very worried’ for the housing market as pending house profits go on to decline.
National Affiliation of Residence Builders CEO Jerry Howard warned shoppers Friday the housing market place is at present “staring into the experience of a fantastic storm” and argued that is a “bad indication” for the American economy.
“Our very own Wells Fargo NAHB Housing Current market Index (HMI) declined a few factors this month since builders are indicating factors are going to ‘dry up.’ You have acquired a blend of the costs…regulatory compliance and now at the other finish of the pipeline, curiosity fees are likely up,” Howard instructed “Cavuto: Coastline to Coastline.”
The housing skilled created these feedback after pending household product sales declined for the fourth consecutive month in February. Howard claimed he’s “incredibly apprehensive” that the current market could “seriously sluggish down.”
Home Gross sales SEE Wide NATIONWIDE Drop
Cavuto questioned no matter whether customers walk absent if they’re preapproved for a mortgage loan and the cost transpires to maximize noticeably.
Rent and house costs have witnessed big boosts above the past yr and in some areas, they have hit report highs.
Howard stated shoppers have walked absent even before signing their housing contracts, and this has been an situation nationwide.
“What builders are performing to stay clear of that…is they are putting escalator clauses into their contracts,” he defined.
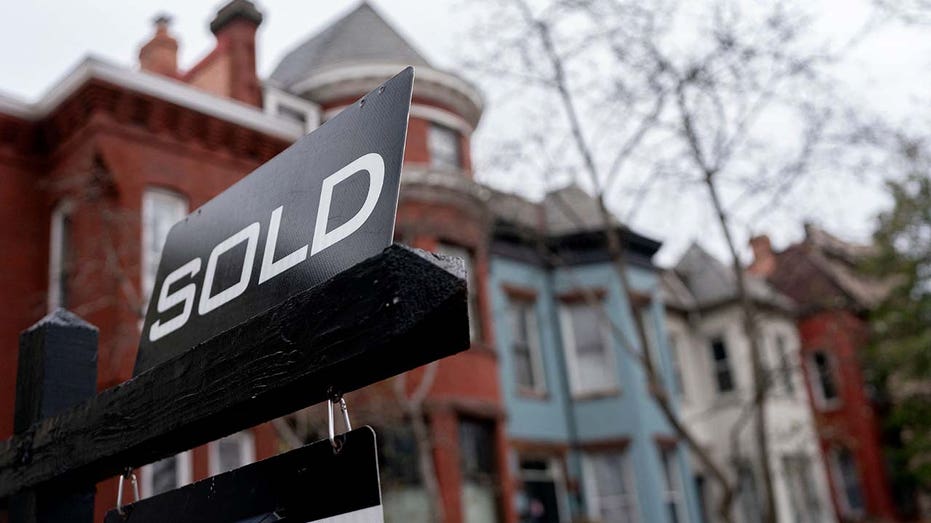
A offered indicator is posted in front of a home in Washington, DC. (Photograph by Stefani Reynolds / AFP) (Photograph by STEFANI REYNOLDS/AFP by using Getty Illustrations or photos) (Photo by STEFANI REYNOLDS/AFP via Getty Photographs / Getty Pictures)
“[Customers] appear in and say, ‘You want to build a dwelling?’ I’ll convey to you how substantially I imagine it really is heading to price, but I’ll also say ‘I can not be held to that. You are heading to be liable if it goes up,’” Howard pressured.
Home finance loan REFIS DOWN 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Compared to Year Ago
In accordance to a new review from Zillow, house prices are fast rising quicker than people today make in an entire year, projecting cost expansion to arrive at 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} calendar year-over-year in May well.
GET FOX Company ON THE GO BY CLICKING Right here
In the meantime, the Fed’s the latest charge hike has resulted in climbing borrowing charges, in addition to presently historic highs for property rates.
“I am very, pretty involved that we are likely to see the housing markets gradual down significantly, which is a poor indicator for the buyers, and it is an similarly undesirable signal for the American economy. We are very nervous right now,” Howard concluded.
The pandemic rocked downtown Los Angeles’ luxury household real estate market place. Simply because office environment towers have been vacant and nightlife shut down, the allure of urban core dwelling light noticeably. All over 2020 and into 2021, reductions and incentives ended up on offer you for luxurious rentals. Household profits slowed. The very visible challenge, and what was to be L.A.’s tallest residential tower at Oceanwide Plaza across from the Crypto.com Arena, absolutely stalled immediately after halting development in 2019.
Condominium enhancement did proceed apace, and several of all those jobs are now on the marketplace, this sort of as the 450-device Perla on Broadway and the Metropolis Tower, with far more in the pipeline. Residential towers are reshaping the skyline as vertical living gains traction from South Park to the historic core and throughout the Arts District. The coming launch of the 45-tale the Grand by Gehry from architect Frank Gehry and Similar is significantly predicted because it will deliver a signature household tower to Grand Avenue, along with retail, restaurants and the 305-area Conrad Los Angeles lodge.
“People wrote downtown off but it is a really resilient community,” says authentic estate agent Media Moussavy of the Agency, who’s an pro on downtown residential leasing and sales. For each the a number of listing support (MLS), there is been an uptick in household revenue (up 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} calendar year-over-yr), a 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} improve in median income cost and a 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} lower in time on the market for the duration of the same time period. The regular product sales price tag in January was $620,000 (for each Redfin) while in comparison to most of Southern California, downtown is a significantly less competitive market and has somewhat grounded house values.
Downtown household possession prospects have often been constrained Arts District lofts and historic core adaptive re-use structures have been the exception. The Perla on Broadway (at 400 S. Broadway) is one of the hottest additions to downtown’s saleable stock: the 35-tale building from developers SCG The usa, the 1st to be crafted on downtown’s most important artery in near to 100 years, provides studio, a person- and two-bed room layouts. Italian appliances, flooring-to-ceiling windows, an indoor gaming lounge and an out of doors 36th ground rooftop glass-walled lounging spot with unobstructed skyline views are a number of of the lavish comforts. The product sales procedure is underway and recent listing selling prices begin at $449,000.
Arts District lofts are always in demand from customers. Director Justin Lin a short while ago outlined his multi-degree, showplace penthouse at the landmark Biscuit Co. Lofts for $6 million. The are living/do the job loft has a storied history: a basic adaptive re-use of a former industrial house. The Biscuit Co. Lofts had been originally designed in 1925 as the West Coastline headquarters of Nabisco, built by E.J. Eckel for the — at the time — substantial sum of $2 million. Vincent Gallo is among the the previous proprietors.
“It may not sense like it, but downtown Los Angeles is in the midst of a increase,” says Tab Howard of the Alexander Team at Compass. He contends downtown’s true estate is underutilized, especially for industrial and producing works by using. Even so, the attraction to artists and creators trying to get a correct metropolitan experience is plain.
Lin’s two bedroom, 2½ tub, 4,300-sq.-ft. loft has remarkable cantilevered stairs and personal wrap-all over terrace. At 3,600 square-ft, the outside deck is greater than most homes.
“It is nearly 100 decades outdated and absolutely has that exposed brick New York Town/Soho vibe, which is tough to come across in Los Angeles,” says Howard, who contends potential buyers “get far more bang for their buck” in downtown L.A. The majority of downtown Los Angeles’ believed 85,000 inhabitants are renters and by much under 40. The norm for young renters is to live downtown somewhere around three a long time or so building hopping and chasing rental incentives is prevalent. Gleaming luxurious rental significant rises are the attraction for those who can find the money for them (on ordinary, a a single-bedroom apartment downtown rents for a lot more than $2,600/month to month).
Properties advertise their competitive set of amenities which include expansive views, rooftop swimming pools, high-fashion fitness centers, concierge companies and pet benefits. Facilities and stability are the differentials in these elevated communities.
1 rental flies over them all with each and every imaginable further and highest stop finishes: 825 Hill’s 6-bedroom, 11-tub, 19,300-sq.-ft. penthouse, atop 52 flooring. The palatial condominium holds the present file for priciest lease in the metropolis at $95,000 for each thirty day period for the 1st year. Compass’ Lee Mintz negotiated the offer on behalf of her consumer who sought a “wow” locale. The penthouse functions its own pool and elevator — and a rock-climbing wall. The building delivers a amount of security not achievable at a solitary-family household.
“It does not get far more private. … I think in the product or service,” says Mintz of downtown L.A.’s long term alternatives. Builders and town planners concur as new blended-use, predominantly residential initiatives are coming to traditional professional blocks. Etco Residences is powering Ato, an 8-story combined-use constructing with 77 residences now less than construction in historic Small Tokyo.
The condominiums will selection from 700- to 1,117 sq.-feet topped by a rooftop way of living deck with pool (and sights of Town Hall), various gathering locations and an out of doors theater. The new Metro Tiny Tokyo station is shut by. Product sales will start in April and shift-ins envisioned by late 2022.
“The household setting up boom in downtown Los Angeles has spurred a contemporary renaissance in Minor Tokyo, attracting home consumers in search of an energetic city natural environment in this traditionally Japanese neighborhood,” states Afshin Etebar, president of Etco Homes.
Whilst downtown has its grittier facet, residents can rely on vibrant avenue daily life, walkability and limitless dining, cultural and enjoyment possibilities.
As the Agency’s Moussavy suggests, an expenditure in downtown residing will make feeling for these who can remain five to 10 several years.
He notes, “The outlook is sturdy: If you put roots down right here, and you are in it to stick it out for the long time period, you won’t lose.”
We want to help you make more informed decisions. Some links on this page — clearly marked — may take you to a partner website and may result in us earning a referral commission. For more information, see How We Make Money.
The median price of a single-family home in the U.S. in February 2022 was $363,800, a 15.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} jump from February 2021, according to the National Association of Realtors. This increase in home prices across the country, spurred by low supply and high demand in the housing market, means many homeowners have gained substantial amounts of equity they can now borrow against for quick cash through a home equity line of credit (HELOC).
If you own an investment property and want to tap into funds for a home improvement project, to consolidate debt, or to purchase another property, you may be considering getting a HELOC on your investment property instead of putting your own house up as collateral.
While HELOCs on investment properties are available, they tend to be more expensive and are harder to get than if you were getting one on your primary residence. Before you decide whether getting a HELOC on your investment property is the right financial move for you, you’ll want to know the requirements to get one, the pros and cons, and how it stacks up against other financing options.
Can You Get a HELOC on an Investment or Rental Property?
While it is possible to get a HELOC on an investment or rental property, it’s more difficult to find and get approved for one. That’s because lenders usually see them as bearing higher risks than if you were getting one on your primary residence. There’s an assumption that there’s less incentive for you to stay on top of your payments because you don’t live in that home.
“With an owner-occupied property, the bank is assuming [that since] you live there, you’re going to make sure you pay for it so you don’t lose the house,” says Monick Halm, an investment property expert and founder of Real Estate Investor Goddesses. “They don’t feel that with a non-owner occupied [property] that there’s the same incentive.”
Not all lenders offer HELOCs for investment properties, says Mike Carpenter, a mortgage originator based in Kirkland, WA, and founder of Mike the Money Man. Even if your financial profile would qualify you for a HELOC on your investment property, you may still find your options limited simply because fewer lenders offer this type of product.
Requirements to Get a HELOC on an Investment property
The requirements to get a HELOC of any kind — whether on an investment property or principal residence — vary by lender, but there are some common factors lenders look for when evaluating an application:
Home equity and loan-to-value ratio: your home equity represents how much of your home you actually own. Loan-to-value ratio (LTV) is one way to measure your home equity, and is calculated by dividing your current mortgage balance by the appraised value of your home. HELOC lenders typically allow a maximum LTV of 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, meaning you’ll need to have at least 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity in your home.
Debt-to-income ratio (DTI): your debt-to-income ratio is calculated by dividing your total monthly debt obligations by your monthly gross income. The lower your DTI, the better you’ll look to lenders, since it shows that you’re less likely to overextend yourself if you take on new debt.
Credit score: Your credit score is calculated based on information in your credit report and helps a lender determine how likely you are to repay your debts — and how risky it is to lend you money. The higher your credit score, the more likely you’ll qualify for a HELOC, and the lower the rate you’ll likely get.
Cash reserves: Some lenders may require you to have a certain amount of cash in reserves before they’ll grant you a HELOC. This is to ensure you have adequate funds to cover any unexpected expenses and won’t immediately default on your loan if you have an emergency.
Typically, lenders will have more stringent requirements on all of these factors if you’re taking out a HELOC on an investment property instead of a principal residence. To get approved for a HELOC on an investment property, you may need to have a lower loan-to-value ratio (meaning more equity in your home), lower debt-to-income ratio, higher credit score, and more cash reserves. The exact thresholds required will vary by lender, and it may be difficult to find out that information until you apply.
Lenders might also look to see if you have a long-term tenant on your investment property, explains Halm. “They generally want to see a long-term lease versus a short-term one, and then they want [the property] to be occupied,” she says. “They’ll also want to see proof of income.”
The lender will also want information about your other properties, says Halm. “They want to make sure you’re not using [the HELOC] to pay debt down on other mortgages you owe,” she says.
Advantages and Disadvantages of a HELOC on an Investment Property
Pros
Less risk to your primary residence: All HELOCs are secured by a property, meaning that you’ll lose the property if you default on the loan. If you get a HELOC on your investment property instead of your primary residence, you won’t lose your own home if you default on the loan — although you could still lose the rental property and face other serious consequences.
Flexible line of credit: A HELOC offers you a flexible line of credit that you can continuously draw upon (up to the credit limit) for a long period of time, usually 10 years or more. This can make it good for ongoing expenses or projects where you don’t know the total cost at the onset. And, since you only pay interest on the amount you withdraw, you can have access to a large pool of potential funding without paying for extra money you don’t use.
Cons
Potentially higher interest rate: HELOCs on investment properties are considered riskier for the lender, says Carpenter. Because of this, they typically come with higher interest rates than HELOCs on primary residences, even if the borrower’s financial profile is the same in both cases.
Potentially more fees: HELOCs typically come with fees and closing costs that could add to the cost of your loan. While some lenders may waive these costs for a HELOC on a primary residence, says Halm, they generally won’t waive them for a HELOC on an investment property.
Harder to find: There are fewer lenders who offer HELOCs on investment properties compared to lenders who offer HELOCs on primary residences. Because of this, it may be harder to find a lender, and you’ll have fewer options to choose from when shopping around to get the best rate.
Is It a Good Idea to Get a HELOC for My Investment Property?
Whether it’s a good idea to get a HELOC for your investment property depends on your individual circumstances, financial goals, and intended use for the HELOC.
A HELOC in general could be a good fit if you want a flexible, ongoing source of financing that you can tap into for virtually any purpose. However, make sure you’re comfortable with the variable-rate structure of a HELOC, which can cause your rate — and monthly payment — to unexpectedly change in the future.
Pro Tip
HELOCs typically have a variable interest rate structure, meaning the interest rate could change at any time during the life of the HELOC. Some lenders offer a rate-lock option that lets you lock in a fixed interest rate, but that may come with additional fees or a higher starting interest rate.
One benefit of a HELOC is that you only need to pay interest on the balance you withdraw, not the amount of your entire credit line. “It’s a line of credit that you can tap into, or not tap into, as needed,” says Halm. “But if you’re not tapping into it, you’re not paying for it.”
Compared to a HELOC on a primary residence, a HELOC on an investment property will typically be both harder to get and more expensive. But, sometimes you may not feel comfortable putting your own house up as collateral, or you may be unable to get a HELOC on your primary residence — for example, if the loan-to-value ratio on your primary residence is too high. In that case, getting a HELOC on your investment property can be a viable alternative.
Experts don’t recommend using a HELOC — or any type of debt — to finance an unsustainable lifestyle, but a HELOC can be a good strategy if you use the money wisely. For example, you can use a HELOC to pay for renovations on your property to increase its value, or use it for a down payment on another rental property, says Halm. In both those cases, the money spent could be considered an investment that will pay off in the future, and a HELOC can be an affordable and accessible way to access the funding you need.
Alternatives to a HELOC for Your Investment Property
If you want to tap into your home equity or you need fast funding, here are some alternatives to getting a HELOC on your investment property:
A HELOC on your primary residence: HELOCs on an investment property are considered riskier for the lender because the borrower has less incentive to keep up with payments, since their own home isn’t at risk. Because of this, lenders typically set stricter borrower requirements and charge higher interest rates. HELOCs on a primary residence don’t have this issue, which is why they might be easier to qualify for and offer lower interest rates.
A home equity loan: a home equity loan works similarly to a HELOC, letting you borrow against your home equity. Home equity loans are fixed-rate installment loans with the full loan amount paid in a lump sum when you take out the loan, instead of the revolving credit line structure of HELOCs. Like with HELOCs, home equity loans on investment properties are possible, but you may be faced with fewer options, stricter borrower requirements, and higher interest rates.
A cash-out refinance: Unlike a HELOC or home equity loan, which acts as a separate loan on top of a primary mortgage, a cash-out refinance replaces your existing mortgage with another one in a larger amount. Then the difference is then doled out to you as cash. You can get a cash-out refinance on both investment properties and primary residences, but just like with a HELOC or home equity loan, a cash-out refinance on an investment property will typically come with stricter borrower requirements and higher interest rates.
A personal loan: If you need cash, you can also take out a personal loan from a bank or online lending company, suggests Carpenter. Personal loans are generally unsecured, meaning they don’t require your home as collateral like a HELOC or cash-out refinance. However, this means they’ll typically have a higher interest rate than HELOCs.
Best HELOC Lenders for Investment Properties
Fifth Third Bank
Fifth Third Bank offers HELOCs with line amounts ranging from $10,000 to $500,000. There are no closing costs, but there is an option to lock in a fixed interest rate on your HELOC for a $95 fee. HELOCs from Fifth Third Bank come with a draw period of 10 years with interest-only payments, followed by a 20-year repayment period. Fifth Third Bank offers HELOCs on condos, multi-unit, and non-owner occupied properties, but 0.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} will be added to your interest rate for each applicable factor. There may be additional benefits for customers with a Fifth Third Preferred Checking Account.
PenFed Credit Union
PenFed Credit Union offers HELOCs on non-owner occupied properties for line amounts ranging from $25,000 to $500,000. The maximum combined loan-to-value ratio (CTLV) is 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, meaning that the total value of all loans secured by the property (including HELOCs, home equity loans, and primary mortgages) cannot exceed 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the property’s value. Borrowers have a 10-year draw period, and the repayment period is 20 years. PenFed HELOCs feature the option to switch from a variable to a fixed interest rate.
TD Bank
TD Bank offers HELOCs on investment properties with a credit line between $25,000 and $500,000. Customers with a TD Bank personal checking account are eligible for an interest rate discount of 0.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. There is an origination fee of $99, an annual fee of $50 after the one-year anniversary, and an early termination fee of 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of outstanding principal balance ($450 max) if the line of credit is paid off and closed within 24 months of account opening. There may be additional closing costs on lines of credit greater than $500,000, investment properties, and co-ops.
It’s practically time! Give your dwelling a festive update with lights, lanterns, and cheery banners forward of Ramadan and Eid Al Fitr. From traditional themed décor, like the Arabian fanous (lantern), to up to date décor, like paper enthusiasts and fairy lights, we’ve obtained you coated as you discover what is on give. Choose edge of Amazon’s ongoing Ramadan sale and get these things shipped to you by means of free of charge 1-day supply from Amazon Key.
1. Green and Gold Ramadan Kareem Paper Fans
An Instagram-worthy backdrop, this paper supporter and honeycomb set is perfect for iftar parties or as a month-lengthy decorative set-up in your home. Uncomplicated, however classy, it quickly presents a festive experience. It is straightforward to assemble and will get the complete loved ones pumped up for the month forward.
2. Highland Ramadan Doorway Decorations
Searching for some thing a minor understated and elegant, nonetheless perfectly suited for Ramadan? These doorway decorations (you can even place it up on a wall indoors or across a window) aspect moons, stars, and lanterns, and welcome all site visitors to your household with a festive Ramadan greeting. Produced of environmentally welcoming and non-poisonous wooden, it can be packed up and reused in following several years.
3. Sworway Solar Lantern
Lights and hanging up the fanous or lantern is a 1,000-yr-previous tradition that commenced in Egypt and distribute about the planet throughout Ramadan. Bring this custom to your backyard or indoors, with photo voltaic-run lanterns that are wonderfully built and solid a heat, patterned gentle. The photo voltaic lamp is IP44 water-proof and just demands immediate daylight to function.
Reward: The manufacturer features 12-thirty day period excellent assurance for top quality linked issues, alongside with 30-day revenue again ensure for any cause.
4. Star Moon Curtain String Lights, 3.5m
Mild up your household for Ramadan and Eid with these uniquely intended curtain lights. They incorporate six compact stars and six massive moons with stars – fantastic for balconies, windows or curtains. Make a warm, inviting environment in your household with the eight brightness adjustment amounts provided in this set.
Maintain your kids fast paced and pleased with an activity that’ll get them thrilled for the thirty day period forward. This sticker established is manufactured of environmentally helpful vinyl – it’s non-toxic, water resistant and uncomplicated to get rid of, without having any hurt to partitions or home windows. It’s a great way to get youngsters to enable adorn the home in Ramadan. The stickers aspect illustrations or photos like lanterns, dates, prayer rugs, Islamic artwork, and much more.
6. PTFNY Ramadan Mubarak Fairy String Lights, 3m
Complete of Ramadan motifs, these fairy string lights aspect lanterns, moon palaces, lanterns, stars and greetings. Comprising 20 lights with 10 kinds of designs, the fairy string is 3m extended and will work effectively for both equally indoor and out of doors use. Straightforward to set up and dismantle, it can be made use of for years, and brighten up your dwelling through Ramadan.
Bring the bling with this decoration established that involves disposables for parties, much too. With 24 meal plates, dessert plates, napkins, cups, dessert toppers, and two table addresses, alongside with Ramadan and Eid Mubarak banners, it is ideal for iftar or Eid get-togethers.
Our recommendations are independently preferred by Gulf News editors. If you choose to store via inbound links on our web site, we might get paid an affiliate fee, as we are part of Amazon Companies LLC Associates System.
Spring flowers will be in bloom at the home and gardens of Isabelle Bowen Henderson when the historic Raleigh property will be open to the public on April 3, 2022.
Russ Stephenson
RALEIGH
In the late 1970s, the City of Raleigh tried to tear down and pave over the house and English-style gardens where for decades Isabelle Bowen Henderson raised daylilies, irises and roses near the N.C. State University bell tower.
A few years later, the city tried again.
Both times it wanted to replace a shaded, two-lane section of Oberlin Road with a five-lane thoroughfare that would run through Henderson’s property and line up neatly with Pullen Road, near the bell tower. As with most projects of this kind, the goal was to move more cars faster.
By then, Henderson had died and left the property to her sister, Phyllis Riley, who successfully fought off the city with the help of attorney Brian Howell. Riley also worked to get the 1.2-acre home and gardens added to the National Register of Historic Places in 1989.
Riley left the property to her grandson, Russ Stephenson, and his wife, Ellen Longino, in 1991. The couple set about restoring the home, outbuildings and gardens that Henderson started creating in the late 1930s.
On April 3, Stephenson and Longino will open their home and gardens to the public. The event will benefit the Raleigh Garden Club, which will provide guides and collect $5 at the gate.
It’s a chance to see an urban oasis, hidden by fences and greenery, that thousands pass unknowingly on Oberlin Road every day. Stephenson, a former member of the City Council, says inviting the public in is a way of showing respect for his great aunt’s creation and for his grandmother for keeping the city from destroying it.
“It’s an incredible story,” he said. “And people are amazed when they come here, and they say, ‘I never knew that this place was here.’“
The house and gardens began with a two-room home built by former slaves on Oberlin Road in about 1870 and expanded around 1900. In 1937, Henderson’s father, N.C. State College treasurer A.F. Bowen, bought the building and moved and reoriented it so it faced the back door of his home on Ferndell Lane.
She created a formal Elizabethan herb garden with beds arranged in geometric shapes in brick. She built a clapboard herb potting shed with an enormous brick fireplace at one end, inspired by the summer kitchens at Colonial Williamsburg. The giant fireplace served no practical purpose.
“According to my grandmother, that thing has never seen a fire,” Stephenson says.
Henderson’s bluebells bloom every year
The main garden behind the house served different purposes, depending on Henderson’s interests. During World War II, it was a large Victory garden, full of vegetables. At various times in the 1950s, she had 600 varieties of irises planted there and more than 500 types of daylilies. By the mid-60s, it was all in roses.
Isabelle Bowen Henderson in the mid-1950s with some of the hybrid irises she grew at her home off Oberlin Road in Raleigh. Her home and gardens will be open to the public from 1 to 4 p.m. on April 3, 2022.
A lot of what Henderson planted has survived, more than 50 years after she died in 1969. These include her camellias and the Spanish hyacinths or bluebells that will soon be in full bloom in the English perennial garden in front of the house.
Visitors also will see Henderson’s studio, with its soaring ceiling and abundant natural light, and the room where she painted a 1770 map of the Carolina colonies on the wall over the fireplace (the map pre-dates Raleigh, and shows nothing between “Tarrburgh” and “Hillsborough.”) The mural was featured in House and Garden Magazine in 1942 and again, along with the rest of the property, in Preservation Magazine in 2018.
While Henderson’s house and gardens look much like they did 80 years ago, the city is ever changing around them.
Over the back fence, the large homes on Maiden Lane, long rented to college students and fraternities, were recently replaced by three-story apartment buildings. And next door, just beyond the perennial garden, N.C. State University has replaced an old warehouse building with a gravel parking lot. Stephenson doesn’t know what the university’s long-term plans are, but he hopes it’s not a tall building that would shade the gardens.
And that points to another reason that Stephenson and Longino periodically open their home to the public.
“Part of what I’m doing is to keep people aware of the value of what’s here and the amazing story,” Stephenson said. “It’s all about raising that awareness so people will have an appreciation and respect and not have the city or other development people do things that will attempt to destroy it in the future.”
The open house at 213 Oberlin Road will take place from 1 to 4 p.m. on Sunday, April 3. Parking will be available in that gravel lot next door. For more information, go to www.raleigh-garden-club.org/garden-tours.
Related stories from Raleigh News & Observer
Richard Stradling covers transportation for The News & Observer. Planes, trains and automobiles, plus ferries, bicycles, scooters and just plain walking. Also, hospitals during the coronavirus outbreak. He’s been a reporter or editor for 34 years, including the last 22 at The N&O. 919-829-4739, rstradling@newsobserver.com.
Earlier this March StorageCafe named Denver the 10th-most active real estate performer in the country based on new construction in the 50 biggest metro areas across the U.S.
The good news: “Ever-growing interest in Denver makes it one of the best performing residential markets,” in the country, the report read. And in an attempt keep up with all the demand, residential building permits have increased 131{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the past decade.
Yes, but: We still need lots more.
For a view of a few homes up for grabs across Denver right now, have a look here:
Why we love it: Thischarming 1950s brick ranch residence has a big backyard with tidy landscaping, a patio and fireplace. The home is just blocks from Central Park and close to the light rail station, Stanley Marketplace, downtown Denver and more.
Notable features: Natural light thanks to large windows, classic kitchen with all-white cabinetry and expansive countertops. Primary bedroom features a walk-in closet with built-in shelving; secondary bedroom offers possibility for home office.
Why we love it: This listing boasts a cozy living room connected to a bright dining area — great space to mingle with guests beneath all beneath a contemporary light fixture.
Why we love it: This mid-century modern home is situated at the intersection of the Bonnie Brae, Wash Park, Old South Gaylord, University of Denver and Cherry Creek neighborhoods — making it central and easily accessible.
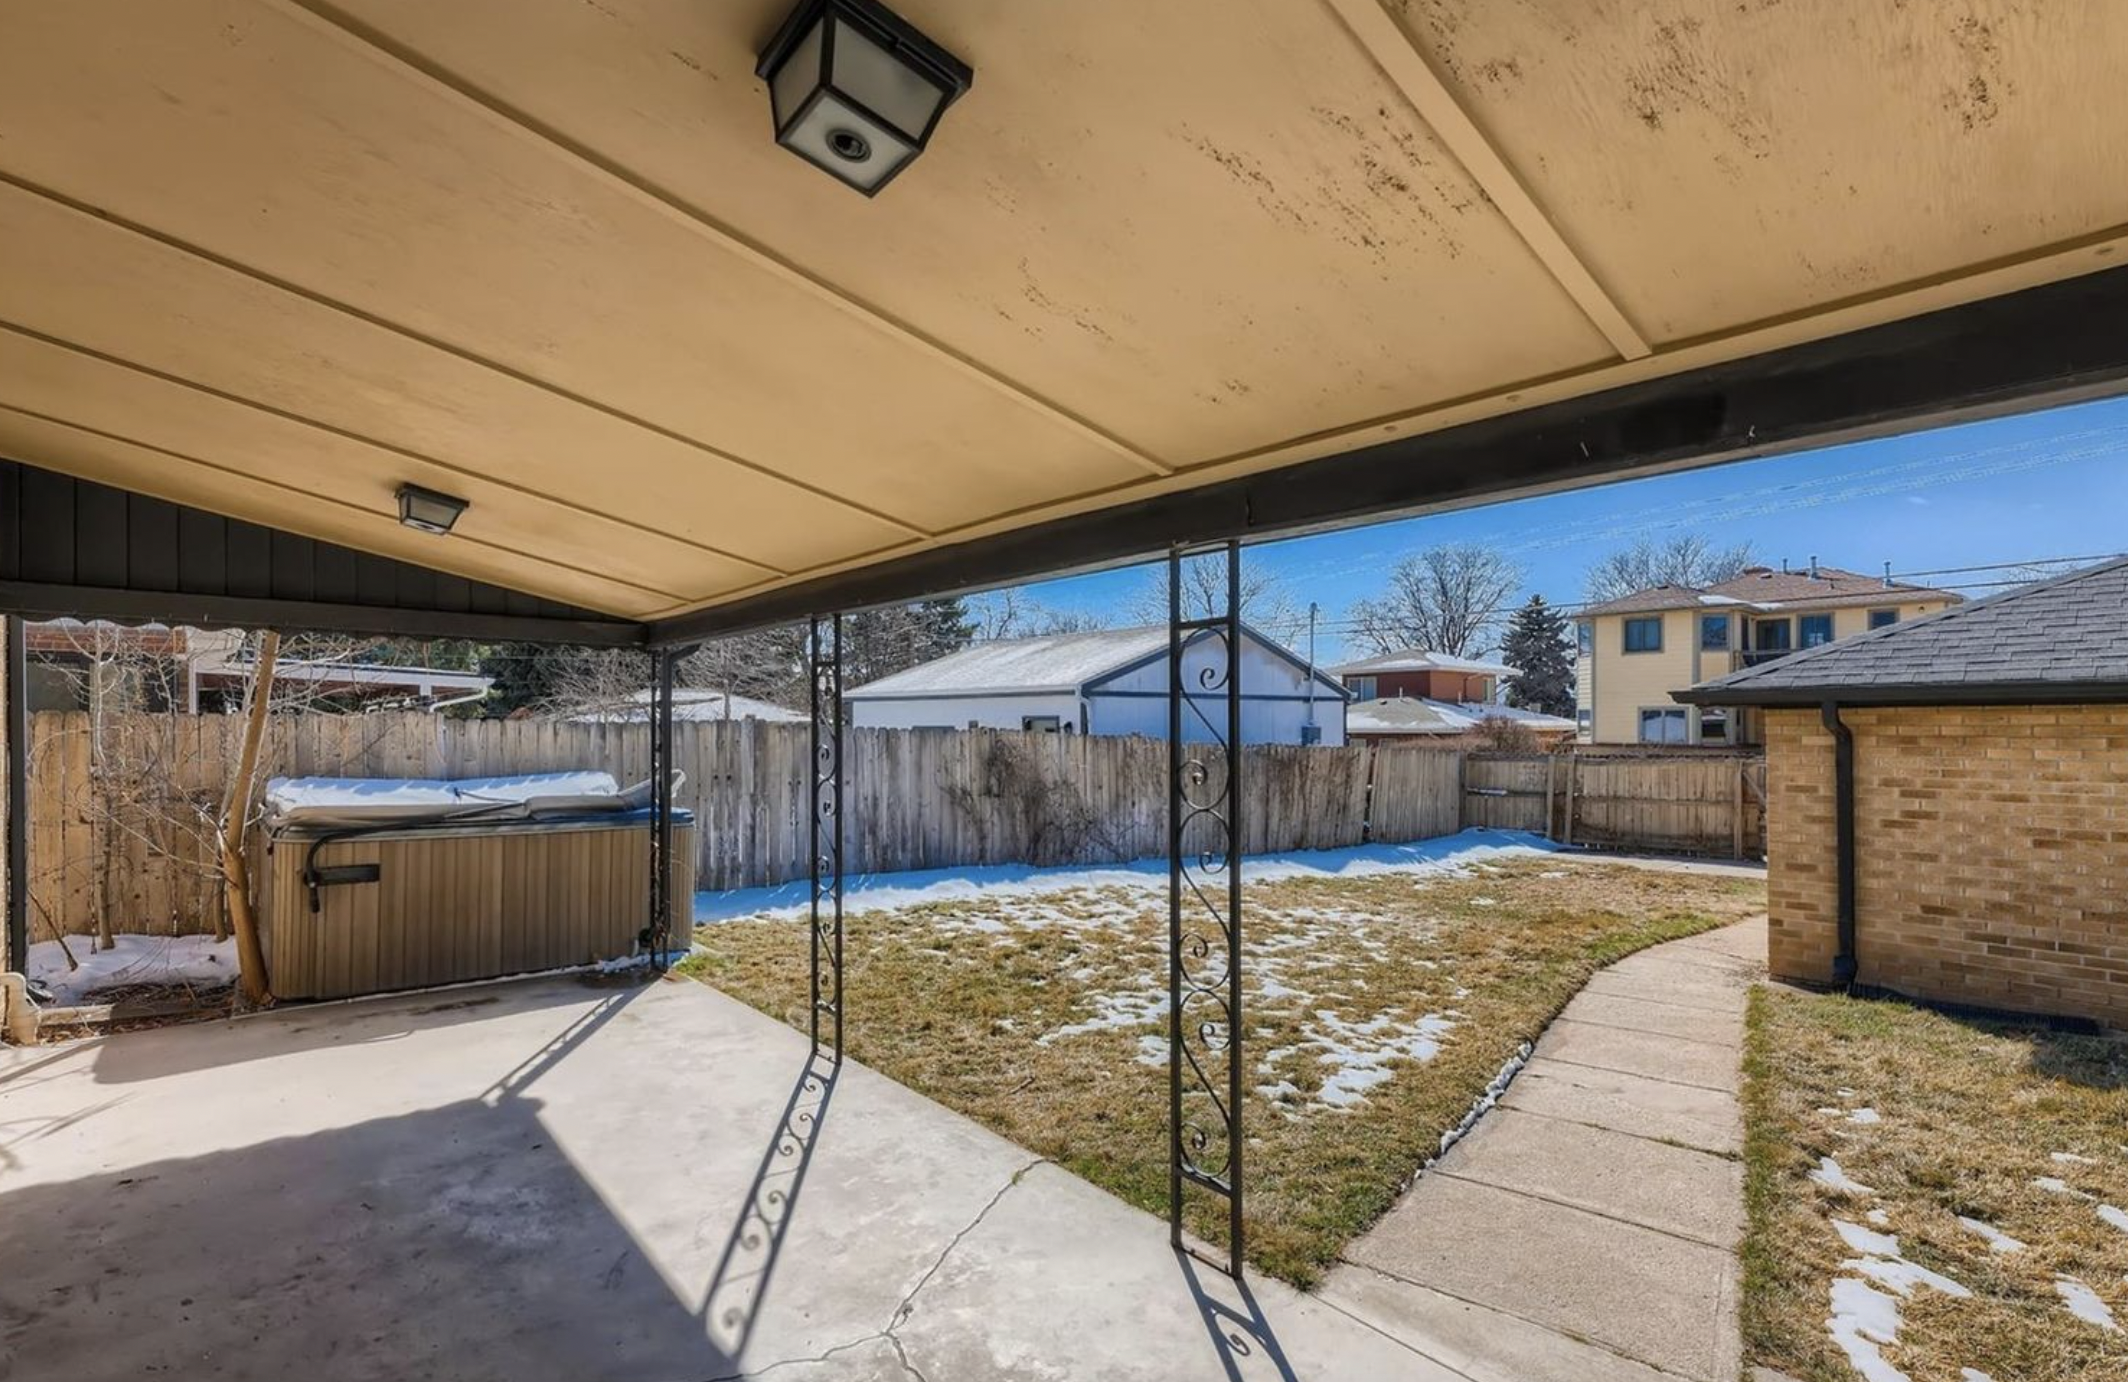
Notable features: Coved ceilings and bar seating in the kitchen. Recessing lighting. Finished basement. Covered patio, landscaped backyard and oversized two-car garage.
1429 S Jackson St. Photo courtesy of Corcoran Perry & Co1429 S Jackson St. Photo courtesy of Corcoran Perry & Co1429 S Jackson St. Photo courtesy of Corcoran Perry & Co
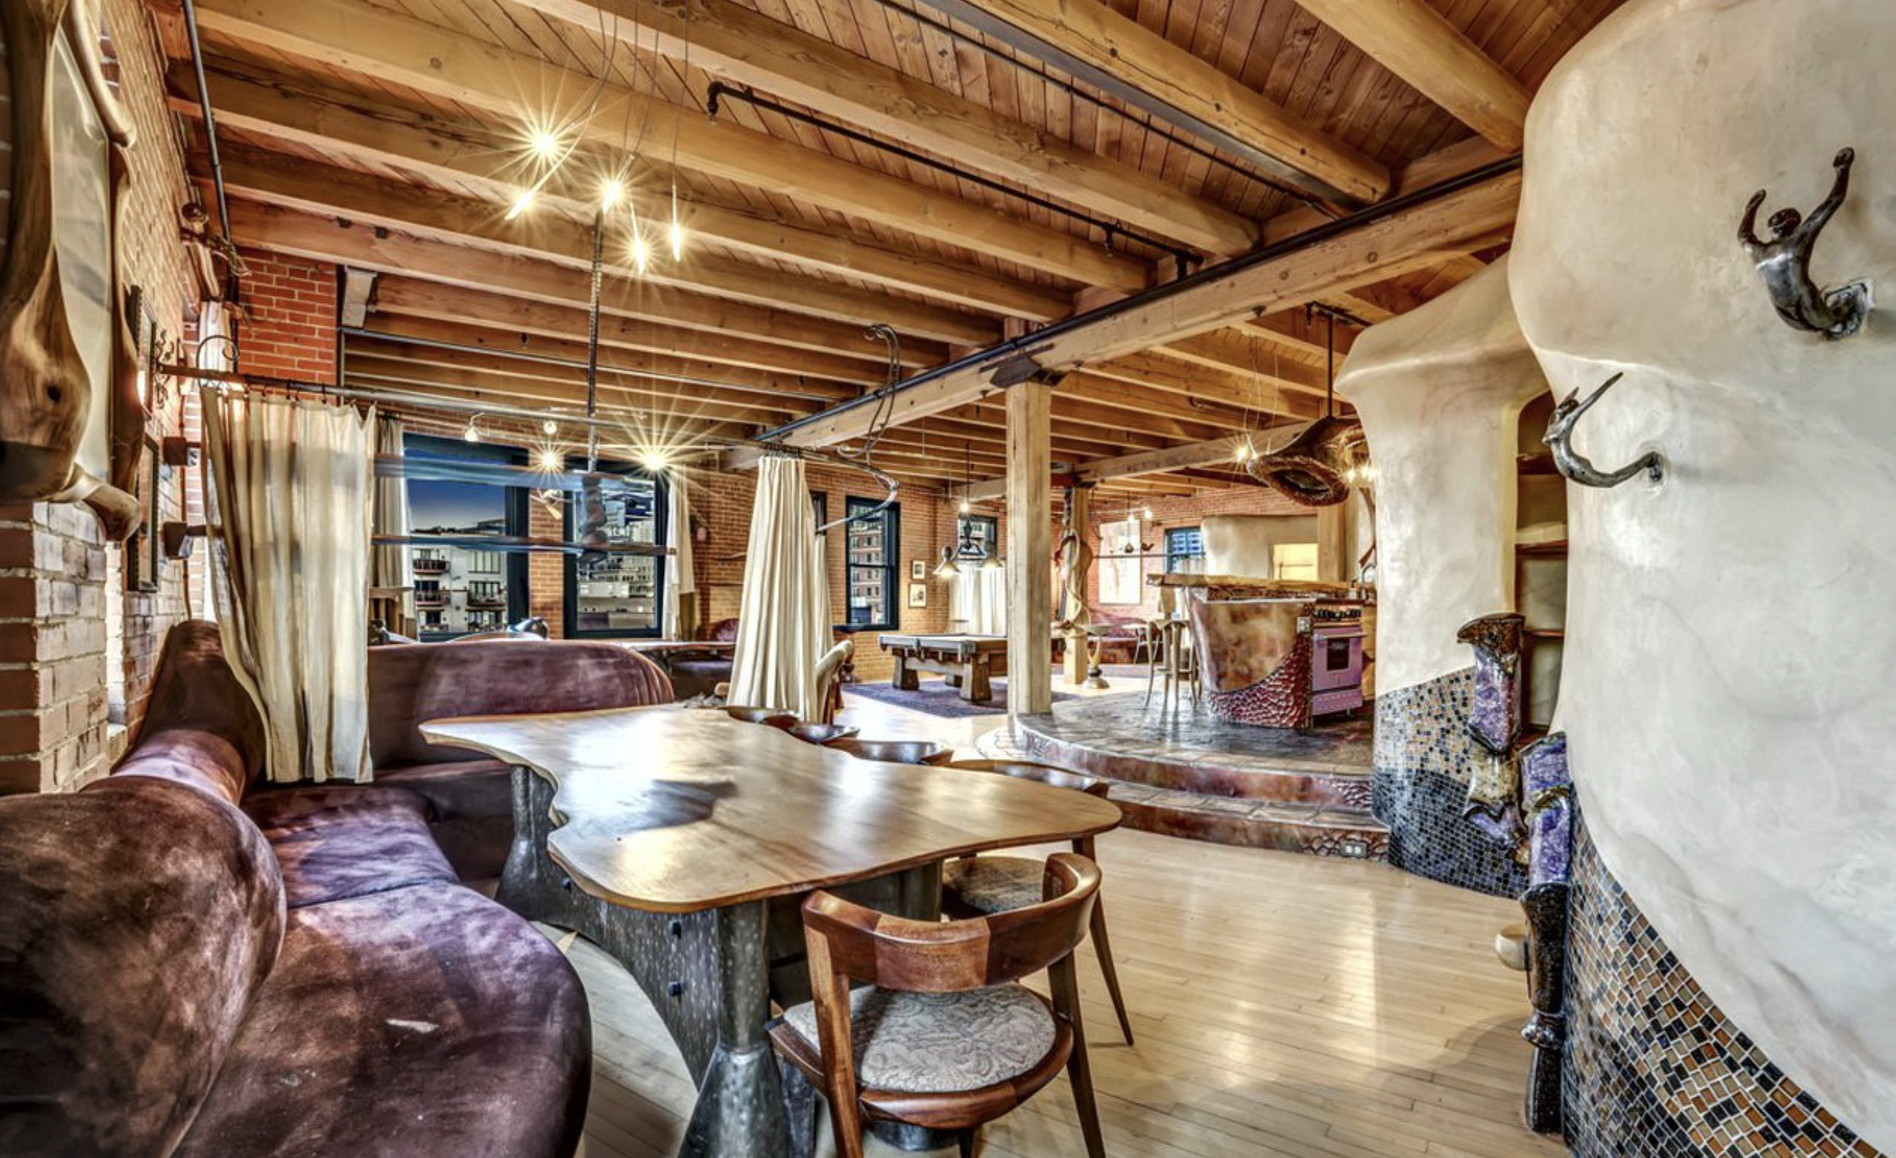
Why we love it: This modern, third-floor loft is inspired by visionary architect Antoni Gaudi. Custom-made art and furniture are offered for sale with property.
Why we love it: Welcome to the Rohe Home, featuring multi-level architecture with stunning woodwork, soaring ceilings and multi-generational living thanks to an ADU condo.
Realtor: Jenny Usaj and Kristina Casinelli — Usaj Realty
Notable features: Elevator, gas fireplace, built-in shelving, soaring windows. Five-piece bathroom, rooftop vista and lots of access to outdoor space. Sitting area and library. Heated garage can accommodate three vehicles.
1128 Cherokee St. Photo courtesy of USAJ Realty1128 Cherokee St. Photo courtesy of USAJ Realty1128 Cherokee St. Photo courtesy of USAJ Realty