Could Zillow or Redfin buy up all the homes — or the whole real estate market?

Could Zillow or Redfin buy up all the homes — or the whole real estate market?

Anything can be done online. Some tech companies, like Zillow and Redfin, think they can even buy and sell houses online, and are dreaming of becoming the Amazon of what has come to be known as ‘‘iBuying.” But they’re finding out that buying and selling assets worth hundreds of thousands of dollars is a bit harder as an online industry than buying and selling books.

Last week, Zillow made a startling announcement that it would stop buying homes for the rest of the year, self-reportedly due to a “backlog of renovations and operational capacity constraints” that it blamed on the supply chain issues plaguing the economy.

This news made a splash in the world of iBuying, a relatively new industry in which companies like Zillow, Redfin, OfferUp, and Opendoor allow homeowners to avoid the tedious process of listing and staging homes by selling directly (and quickly) to them. But it also caught traction on TikTok where Sean Gotcher, a Las Vegas real estate agent, posted a video with Zillow’s news laughing at the company’s troubles.

Gotcher had already achieved the sort of brief internet fame one can most easily get on TikTok when he posted a video in September that has now received more than 3 million views. In it, he insinuates that iBuyer companies are manipulating the market by intentionally overpaying for some homes in order to sell others that they’ve already bought in nearby areas for a higher price.

While some of Gotcher’s claims are far-fetched and verge on conspiracy theories (and since real estate agents directly compete with iBuyers, you should take claims either entity makes about the other with a grain of salt), the video went viral because it struck at the heart of a growing fear that housing is becoming less like shelter and more like a risky financial asset traded on Wall Street. This anxiety is not new but has become electrified over the course of the pandemic as a hot housing market and a historic undersupply of housing have locked out young and first-time homebuyers. Earlier this year, fears that BlackRock and other institutional investors were responsible for current market conditions were rampant despite a lack of evidence for the claim.

iBuyer companies make up a very small share of the market — roughly 1 percent of home sales in the second quarter of 2021, at what is their peak so far — but it’s important to take concerns about their growth seriously. While iBuyers contend that they are offering a clear solution to reducing the stress of the home-selling process, US policy has predicated financial security on homeownership, and the introduction of large firms into the space raises fears of potential anti-competitive and predatory behavior.

The Amazon of real estate?

The process of selling a house is stressful, to say the least. On top of the general concern —about getting the best price for the most expensive thing you have ever owned and in which you have likely already invested tens of thousands of dollars and countless hours — is all the logistical stuff. As a part of staging the house, sellers may have to do front yard work, repaint the interior and exterior, replace the carpets, hire a professional photographer for the listing, keep the interior clean in preparation for showings, figure out where to take the home’s dogs and children when there are showings, hire a real estate agent, the list goes on.

This doesn’t even include trying to time your home sale to coincide with the move-in date of your new home or city. Often, people will need to have sold their home in order to buy a new one, which means there can be additional transaction costs there too if you have to put all your things in storage and live at a family member’s place or a rental while you look for your new home.

This is the problem iBuyer companies say they are looking to solve. Instead of having to go through the hassle of this entire process and potentially incur some costs, homeowners can take an iBuyer’s offer — and then the company does the work of staging, listing, and selling the house to someone else.

There are are a couple of ways these companies can turn a profit: first, the difference between what they purchased the home for and what they are able to sell it for (minus any costs for renovations, upkeep, and selling), and second, the fees they charge homeowners to sell the property.

Whether any of them are actually turning a profit is a whole other matter.

iBuyers are growing quickly. According to University of Colorado Boulder’s scholar-in-residence Michael DelPrete, in 2018 iBuyer companies made up roughly 0.2 percent of the market; in 2019, his numbers show that iBuyers accounted for roughly 31,000 purchases or 0.5 percent of the U.S. market. According to research by Zillow, in Q2 of this year iBuyers’ market share reached 1 percent for the first time.


Two people stand in the side yard of a single-story house and look up at its roof.


Employees of Zillow Offers evaluate a home for possible purchase by Zillow in Lauderhill, Florida, in August 2019.
Joe Raedle/Getty Images


But according to research by DelPrete, the profit margins in this industry are narrow. Looking at this past quarter, Opendoor and Zillow were posting net losses (-$144 million and -$59 million, respectively). While Offerpad did post a profitable quarter ($9 million), DelPrete notes that “the overwhelming majority of profits are coming from record home price appreciation, which is temporary, and appears to be falling.”

Though these numbers are small in the context of the national housing market, iBuyers have historically been relatively concentrated in specific regions like the Sun Belt where there’s more new single-family construction, since it’s easier to accurately price new, relatively similar homes. In 2019, DelPrete’s research showed that in the largest iBuyer market, Phoenix, they’d reached a 5.5 percent market share. However, Zillow data from Q2 of this year indicates that that number hasn’t shifted much with market share at 5.7 percent in Phoenix. Other cities with a relatively high share include Atlanta (5.3 percent), Charlotte (5.3 percent), and Raleigh (5.0 percent).

Redfin, despite expanding its iBuying business, is still heavily committed to its traditional real estate model. In a statement, Jason Aleem, vice president of RedfinNow (the iBuying arm of Redfin) said: “Part of what makes RedfinNow different is our ability to educate sellers on all of their options in a single conversation. … Many are drawn to the certainty of our competitive cash offers, but those who still want to list on the open market for the lowest fee can do that with a local Redfin agent.”

But are these companies big enough to manipulate the market?

Taking concerns about market manipulation seriously

Despite Gotcher’s TikTok video claims, I’m very skeptical that iBuyers could manipulate the market to systematically undercut homeowners on the initial price of their homes and then set higher prices when they return to the market.

Take the first part of that plan — to systematically buy homes for less than they’re worth. There’s simply too much competition to be able to do that reliably. For one, there are other iBuyer companies that compete against one another. They find themselves in bidding wars with the other companies not infrequently, and some research indicates that the price they’re willing to pay is going up faster than the rest of market. And it’s not just iBuyers competing against one another — there are also thousands of real estate agents who would be happy to sell your home for you.

These companies simply don’t have the power to consistently drive up prices on homes they sell. Let’s break down exactly what would have to happen for an iBuyer to be able to do something like that. First, they would need to buy a significant number of homes within a given market. What a market is is up for debate, but you’d need to get enough market share to shift prices — courts have defined monopoly power as greater than 50 percent. To emphasize how far away iBuyers are from this, in the markets where they are most active that have achieved roughly 5 percent of sales, not even all the homes, just the ones that are selling. And that’s all iBuyers, not one specific company.

But that’s not even the hard part. The hard part would be that they’d need to hold onto the homes until they’d achieved a high enough market share. iBuyers are usually putting houses back on the market in a matter of a few months. They’d need instead to pay upkeep costs, property taxes, and take on the huge risk that all the homes that they are holding onto within a given area don’t tank in value because of something unrelated like an economic downturn or changing living preferences or a hurricane.

This strategy quite evidently has some major downside risks. There’s only so much that even a regionally monopolistic firm would be able to charge before people would choose to live elsewhere.

It would also require that these companies can accurately price homes. Failing to accurately build an algorithm is very costly — Bloomberg reported that when Zillow “tweaked the algorithms that power its home-flipping operation to make higher offers … it had to stop making new offers” after winning too many bids. The market is appreciating more slowly than earlier this year, which means when you take into account the renovation costs and selling costs, Zillow could end up selling those homes at a loss.

It seems as though iBuyers are not resting their business model on selling homes. Instead, as the Wall Street Journal reports, they’ve “been clear that their businesses are built to mostly make money off of ancillary services like mortgage, title insurance and escrow.”

But not all the worries about these firms’ power can be brushed away easily.

To start an iBuying company, you need to be able to raise a lot of money. That means it’s hard for new competitors to join the market. It costs hundreds of millions of dollars in order to be a serious competitor — you have to be able to buy a lot of homes, hire contractors to do the necessary renovations, and also have all of the employees and independent agents to sell the homes as well. That doesn’t even include all the work needed to accurately build an algorithm that prices the homes accurately.

It’s possible that iBuyers could have downstream effects not just on homebuyers, but renters too: They’re not just putting the homes on the market for regular people to buy; they are often selling directly to institutional investors (like private equity firms) instead. According to Desiree Fields, assistant professor at UC Berkeley, there is a “growing role for iBuyers” observed in institutional investor activity in the market. She cites reporting from Business Insider that one CEO expects that up to 20 percent of homes his firm is buying for an institutional investor will come from iBuyers.

While the impact of institutional investors is contested, Fields says that these firms are more likely to pursue eviction than smaller landlords and some even practice predatory “serial eviction filings,” a tactic that disempowers tenants from “reporting problems to their landlords and fosters housing insecurity by adding late fees, attorney fees, and other costs to rent arrears.”

The bottom line: iBuyers are providing a service. It’s not clear they’ve really figured out how to make money. Understanding it as a fledgling industry in need of oversight rather than a behemoth manipulating the housing market is important to understand where the power really lies: in the hands of regulators.

Whether iBuyers end up being an option for homeowners or usher in an institutional investor frenzy that harms renters too is a regulatory question.

First, the underlying reason that home prices have skyrocketed is because of historic undersupply. Experts are clear that issue is largely the result of exclusionary zoning laws that have made it impossible to build sufficient homes to meet demand, and in particular demand for starter homes for first-time homebuyers and lower-income homebuyers. Because there is artificially constrained supply, investors hungry for quickly appreciating assets have turned to the housing market.

Second, lack of protections for low-income tenants was an emergency long before iBuyers or institutional investors ever became a presence in the American housing market. While this past year has pushed governments to be more willing to enact tenant protection measures like eviction moratoria and rent relief, tenants often lack basic protections from landlords who openly flout even the few laws that are enacted, due to lack of consistent enforcement.

People aren’t irrational to fear what increased investor activity in housing could mean. But it’s important to accurately diagnose what’s going on here and the actual range of potential harms. If not, the policy solutions designed by the government could fail to protect the people who need it the most.
Real estate: US homeowners have lost .3 trillion since June: Redfin data

Real estate: US homeowners have lost $2.3 trillion since June: Redfin data

U.S. property owners have misplaced $2.3 trillion due to the fact June, in accordance to a new report from the true-estate brokerage Redfin. The full value of U.S. homes was $45.3 trillion at the finish of 2022, down 4.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a document superior of $47.7 trillion in June. That figure signifies the most significant June-to-December proportion decrease given that 2008.

The report arrives amid increased home loan charges as the Fed attempts to curb inflation. The 30-year fastened mortgage fee sat at 6.36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in December, about twice what it was at the commence of 2022. Even though charges fell in early February, they have since risen again to December amounts to the dismay of potential buyers.

Consequently, People in america locate on their own a lot more hesitant to buy homes and price ranges have dropped. The median U.S. property sale cost was $383,249 in January, which was up just 1.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the earlier calendar year, according to the report.

Redfin highlighted the Bay Place, noting that the location had viewed the largest fall in genuine-estate worth when compared to other pieces of the country. For instance, the overall benefit of San Francisco houses fell 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in December, to $517.5 billion, a $37.3 billion decline calendar year above calendar year.

“Three of my listings not too long ago went under deal right after sitting on the market for additional than a thirty day period,” stated Ali Mafi, a Redfin genuine estate agent in San Francisco showcased in the be aware. “They all experienced a number of showings listed here and there in the drop, but no customer required to pull the trigger. And then instantly in the new calendar year, we had 10 or 15 persons touring just about every house.”

Meanwhile, the report pointed out, the Florida housing sector has remained robust, with the most significant boost in true-estate worth compared to other elements of the place. The full value of homes in Miami rose 19.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months above 12 months ($77 billion) to $468.5 billion in December.

“Florida’s housing current market is being sustained by people relocating in from the North and as of not too long ago, the West Coastline,” claimed Elena Fleck, Florida serious estate agent highlighted in the report. “People are pouring in from New Jersey and New York, in huge component mainly because Florida has somewhat inexpensive properties and no profits tax. They can get a large amount more bang for their buck in this article.”

The report famous that U.S. towns are accomplishing a great deal worse than U.S. suburbs. While the price of urban residences amplified 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to $10.8 trillion year above 12 months, the price of suburban properties jumped 6.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months over 12 months, to $25.4 trillion, in December.

Although some gurus see “armageddon” in the serious estate market more broadly, other folks believe that the most demanding time for the current market has handed, pointing to information that the current market is displaying signs of restoration. For instance, self-confidence amid single-spouse and children household builders in January rose for the very first time in around a calendar year, in accordance to the Countrywide Association of House Builders/Wells Fargo. Also, pending residence profits increased 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in December, marking the end of a 6-thirty day period decrease.

“The housing market has drop some of its worth, but most owners will still experience large rewards from the pandemic housing growth. The total price of U.S. properties stays roughly $13 trillion better than it was in February 2020, the month prior to the coronavirus was declared a pandemic,” mentioned Redfin Economics Investigation Guide Chen Zhao in the report.

“Unfortunately, a great deal of men and women ended up remaining guiding. Several People couldn’t afford to get households even when mortgage rates strike rock base in 2021, which means they skipped out on a sizeable prosperity building opportunity,” Zhao additional.

Dylan Croll is a reporter and researcher at Yahoo Finance. Comply with him on Twitter at @CrollonPatrol.

Click in this article for the most recent trending inventory tickers of the Yahoo Finance system

Simply click right here for the most recent stock market place information and in-depth analysis, which include situations that shift stocks

Read through the newest financial and enterprise news from Yahoo Finance

Download the Yahoo Finance application for Apple or Android

Abide by Yahoo Finance on Twitter, Fb, Instagram, Flipboard, LinkedIn, andYouTube

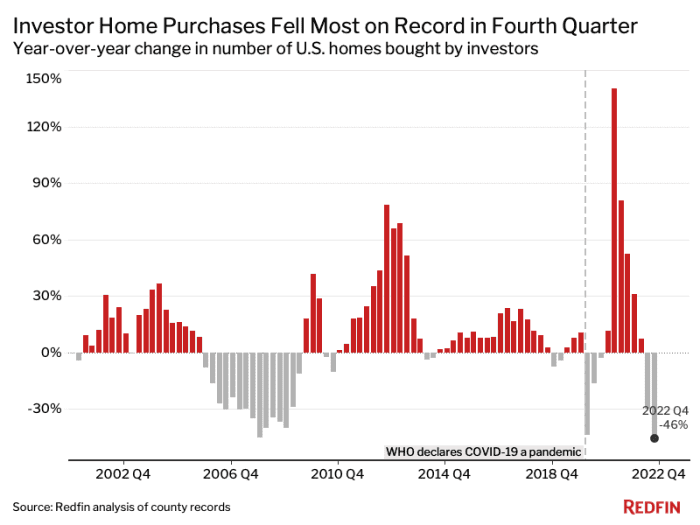
Investors are pulling back from the housing market, Redfin says

Investors are pulling back from the housing market, Redfin says

Traders are slinking away from the serious-estate current market as property-selling price growth slows and the possibility of value drops seems on the horizon.

The last time trader purchases dropped so considerably was in 2008, throughout the subprime house loan crisis, when they fell 45.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, Redfin explained.

In the fourth quarter of 2021, buyers acquired 89,396 houses in metropolitan regions tracked by Redfin. In the fourth quarter of 2022, investors only acquired 48,445 properties in those regions.

The overall drop in mortgage charges and a feasible bottoming-out of home prices may lure investors back again into the industry, but “it’s unlikely that investors will return with the exact same vigor they had in 2021,” said Sheharyar Bokhari, senior economist at Redfin.

“That’s fantastic information for personal consumers, who are nevertheless grappling with high housing fees but no more time shedding bidding war soon after bidding war to traders,” he extra.

Throughout the pandemic, many property purchasers were being outbid and overshadowed by traders who were being equipped to scoop up houses with all-income features. The issue above the plight of initially-time household customers prompted Democratic lawmakers to convene a panel to seem into achievable predatory actions by institutional investors.

In its study, Redfin appeared at residence income amongst January 2000 and December 2022.

Residence purchases by investors fell in 2022. The last time such purchases dropped as drastically was in 2008.


Redfin

For the study, an investor was described as a purchaser whose identify incorporated at the very least a person of these search phrases: LLC, Inc., Have faith in or Houses. Buyers were being also viewed as to be buyers if their possession code on a house deed integrated key terms like “association,” “corporate trustee” or “company.”

Though buyers have pulled back on purchasing homes, it does not imply their market share has dropped, due to the fact person household prospective buyers have also slowed their action. Home loan costs are nevertheless elevated and house charges have not however dropped drastically, which means that lots of men and women are acquiring it challenging to find the money for to buy a dwelling ideal now.

According to Redfin, investors’ share of the industry in all the metropolitan places tracked by Redfin was 17.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fourth quarter.

In other terms, traders acquired that proportion of all households bought in the 40 most populous U.S. metro locations, as tracked by Redfin. Past yr, buyers bought 19.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all homes in all those locations.

The cost of a usual property ordered by an investor was all around $425,926.

Investors flee pandemic boomtowns

In pandemic boomtowns like Las Vegas, Nev., and Phoenix, Ariz., buyers are operating for the hills, the info clearly show.

In accordance to Redfin, household purchases by buyers fell the most in Las Vegas, dropping 67{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the fourth quarter about the exact period of time of the past calendar year.

Las Vegas is also the metropolis that saw residence values fall the most amongst the prime 50 marketplaces tracked by Zillow Group
Z,
+.86{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9},
another true-estate tech enterprise. Household values there fell 1.23{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January as opposed with December.

Traders also hit the brakes in Phoenix, in which house purchases by investors dropped 66.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Nassau County, N.Y., where they fell 63{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Atlanta, where they fell 62.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and Charlotte, N.C., exactly where they dropped 61.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

“A large amount of traders are on hold since they even now see residence costs declining,” claimed Elena Fleck, a Redfin agent based mostly in Palm Beach, Fla.

The only metro place amid these analyzed by Redfin that observed an boost in trader purchases was Baltimore, Md.

Buyers still experienced the highest sector share in Miami Jacksonville, Fla. Atlanta Anaheim, Calif. and Charlotte, Redfin noted.

Home loan costs have crept again up as the current market weighs extra fascination-rate hikes from the U.S. Federal Reserve, which proceeds its struggle against inflation. In consequence, potential buyers have also pulled back again.

Redfin CEO predicts ‘terrible consolidation’ in the real-estate sector, but says it will ultimately be good for the industry

Redfin CEO predicts ‘terrible consolidation’ in the real-estate sector, but says it will ultimately be good for the industry

The actual-estate sector is in disaster amid the housing downturn. Be expecting additional agony to come prior to factors commence to normalize, one housing chief claims.

But he added a caveat: “I do believe it’ll be very good for the market.”

Through the pandemic a long time of 2020 and 2021, quite a few Americans jumped into the actual-estate field, Kelman recounted, so a lot of that “we experienced much more actual-estate brokers than listings by 2021.”

At this level, there are about million-and-a-fifty percent realtors striving to market around about five million households, meaning that they’re only doing five or six offers a year, which “isn’t a effective, fulfilling existence,” Kelman reported. 

Some of the excessive potential in the sector has been released. In 2022, Redfin went as a result of layoffs twice, responding to industry circumstances. Compass, a further brokerage, declared a third spherical of layoffs on Thursday, to lower fees. 

“I hope the sector is close to [becoming] ideal-sized and that issues can get much better from right here,” Kelman reported on Wednesday. “I really do not feel that’s occurred nevertheless.”

‘It’s just a roommate generation now’

But for quite a few Us residents, large housing prices and mortgage prices make homeownership unaffordable. The Redfin main government sympathized with youthful Us citizens priced out of the marketplace.

“It’s just a roommate generation now, wherever individuals are remaining with their mothers and fathers, dwelling in the basement or just shacking up with pals longer simply because property selling prices and rents have the two gotten so significantly out of hand,” Kelman said.

There is some reduction for these renters, as rents have fallen in excess of the earlier couple of months.

Rents dropped for the fourth thirty day period in a row in December, Condominium List claimed in its month to month countrywide lease report on Wednesday.

“Rents lessened in December in 90 of the nation’s biggest 100 cities,’ the report stated, “with rates down by 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} month-above-thirty day period.” 

And far more residences are coming online to support with rental tension.

But which is also restricting the quantity of residences that go on sale, Kelman noted. He stated that some of that supply arrived from home sellers who are withdrawing their listings from the industry, and renting them out alternatively.

Traders continue to on the prowl for deals

Investor buying was a large subject of conversation through the pandemic, as lots of possible customers received beat out by firms and landlords with massive pockets.

Kelman explained that investors are nonetheless on the prowl, and are scouring disaster zones for discounts.

In 2021, buyers acquired 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all solitary-loved ones houses bought nationwide, a Pew Trusts report said very last 12 months. 

Kelman explained that some out-of-town traders now are tracking damaged houses, this kind of as in Florida, to come across promotions.

When he a short while ago frequented a regional office in Florida, Kelman mentioned Redfin workforce in places afflicted by Hurricane Ian advised him that traders ended up contacting as the hurricane made landfall.

“We were being trying to tour properties that the National Guard experienced shut …that have been literally submerged. We would have had to check out the property by boat,” Kelman recounted.

“And these investors continue to wished us to do a digital tour in which we’re using our telephone to tutorial them as a result of the home,” he continued.

“Even as the typical residents of Florida are calling us, nearly in tears, because they’re standing on their next-floor balcony and they are up to their knees and drinking water …there’s one more group of persons coming from all over the earth who see this as an financial commitment option,” he stated.

While insurers and loan companies are turning into wary of coastal properties that come with challenges affiliated with local weather change, these as flooding, “what was ridiculous to me is that traders have been stepping in to fill that gap,” Kelman reported.

Canada banning foreign homebuyers was ‘a bold move’

In reaction to investors’ getting frenzy, Canada, which is also dealing with an unaffordable housing market place, decided to get a hard stance. Kelman reported he was amazed.

At the start out of 2023, the Canadian authorities enacted a ban on foreigners acquiring residences in Canada for two years. The law supplies exceptions for purchases created by immigrants and long lasting residents of Canada, CNN reported.

“I was impressed and stunned at what Canada did,” Kelman explained.

“At a single level, it is just a massive self-inflicted wound to the financial system,” he claimed. But on another degree it is “a authentic motivation to earning housing extra economical for Canadians,” he extra.

Although the United States frets around a shortage in the offer of homes available for keen consumers, “Canada just stated screw it. They pulled the twine,” Kelman explained.

“And now that housing industry is acquiring a actual correction and it’ll be awful for the authentic-estate business [and] for persons who are about to provide their property,” he additional. 

“But it will imply that a new technology of Canadians is heading to be in a position to afford to pay for a location, and so that was a pretty bold go,” he added.

Bought feelings on the housing current market? Create to MarketWatch reporter Aarthi Swaminathan at aarthi@marketwatch.com

Seattle is America’s fastest-cooling housing market, Redfin says

Seattle is America’s fastest-cooling housing market, Redfin says

The Seattle-place housing marketplace cooled faster in recent months than any other location in the place, highlighting the squeeze rising curiosity premiums are putting on an high priced marketplace.

That evaluation will come from Seattle-based mostly brokerage Redfin, which ranked U.S. metro places primarily based on how rapidly their housing markets are slowing down.

The 10 quickest-cooling markets include extensive-dear regions, these kinds of as Seattle and San Diego, as well as metropolitan areas like Phoenix that saw a big influx of new residents all through the pandemic. 

“These are all places wherever homebuyers are sensation the sting of mounting household rates, increased property finance loan premiums and inflation really sharply,” Redfin Main Economist Daryl Fairweather claimed in the report.

Redfin’s investigation in contrast an array of factors in the nation’s 100 greatest metro areas, like charges, gross sales, inventory and how numerous attributes dropped in cost while awaiting a buyer. The brokerage contains King and Snohomish counties in its evaluate of the Seattle metro place. The Tacoma spot, which ranked 10th, is involved in Pierce County. 

Just after two yrs of complete-tilt progress in residence prices, bidding wars and all-cash presents, the latest months have brought a placing turnaround.

Previous thirty day period in King County, pending sales were being down about 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in comparison with the exact time very last year, in accordance to independent info from the Northwest Various Listing Provider. While King County’s $899,999 median home price tag was nonetheless up from 2021, it dropped virtually 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from Might to August.

Driving the downturn: mounting curiosity fees, a lagging stock market place and basic uncertainty about the financial state. 

As the Federal Reserve seems to management inflation, growing property finance loan charges are right hitting buyers’ bottom strains — especially very first-time consumers. 

A 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} curiosity level enhance can decrease a residence shopper’s purchasing electric power by 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, said Curt Tiedeman, a loan guide at Caliber Home Financial loans in Issaquah. The average price on a 30-yr property finance loan passed 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} last 7 days for the initially time considering that late 2008, according to Freddie Mac. That level is up approximately three proportion details from the start of the calendar year.

“So people are losing 20, 25, 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} acquiring electricity,” Tiedeman mentioned.

On a $775,000 home in the Seattle region, the regular property finance loan payment would be about $3,300 with a 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} fascination fee and $4,400 at a 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} curiosity charge, according to Redfin. 

That is driving some consumers out of the market entirely.

“In the very first-time homebuyer sector, if they are scarcely qualifying for a residence in the space they are seeking for, a tiny little bit of a transform in desire price could just take a person out of the industry fully,” explained Sally Li, a broker with Beacon Hill Realty. 

Selling prices pushed one consumer exploring for new design in Everett “further and further more north” until eventually he at last made the decision to postpone his look for, Li said. 

“Even even though costs have been stagnant … just the desire amount alone modified his trajectory,” Li claimed.

Inflation and the stock market are hurting homebuyers’ budgets, as well, particularly in tech centers the place many prospective buyers count on stock choices from their businesses.

Redfin’s assessment tracks several indicators comparing the housing marketplace with the same time very last 12 months. 

To present how the current market cooled off, the report compares these indicators in August with the exact figures in February since in quite a few places, “that’s when the housing marketplace arrived at a peak in terms of demand from customers and competitors when the amount of properties for sale was at a minimal,” in accordance to Redfin. Additional residences usually strike the market in the spring. 

In Seattle, household charges were up 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year around 12 months in Seattle in February. In August, they ended up up just 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as opposed with a 12 months earlier. 

The variety of homes for sale was down 36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in February, indicating a competitive sector for buyers. In August, stock was up 78{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. In February, brokers dropped costs on 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of listings. In August: 48{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Individuals are all signals the market is cooling. 

Tacoma showed related symptoms of a slowdown. 

The median residence price tag was up 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months around 12 months in February and 7.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in August. Whilst 87{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of Tacoma-place homes had been off the market inside of two months in February, that figure was just 39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in August.

With fewer potential buyers competing for every single dwelling, properties are sitting on the market place extended. Sellers are dropping costs and chipping in on closing expenditures. Purchasers are capable to hold on to their right to an inspection and other contingencies.

That all signifies what Tiedeman named a “trade-off” for prospective buyers these days: greater rates, but additional leverage above sellers.

With desire rates nonetheless ticking up, even those people who can qualify for a personal loan may perhaps not be cozy with the price. “Just because you can afford to pay for a $4,500 payment,” Li mentioned, “doesn’t imply you genuinely require to go there.”

I’m the chief economist of Redfin. 5 things to know about the housing market now

I’m the chief economist of Redfin. 5 things to know about the housing market now

Redfin main economist Daryl Fairweather shares her feelings and predictions on the housing industry.

Peak dwelling-obtaining period is in full swing, and lots of aspiring consumers are asking yourself: What need to I know about the housing market place if want to buy? After all, interest fees have been soaring, with some pros declaring that pattern will go on (see the cheapest home loan fees you can qualify for below) household prices preserve climbing and there are not plenty of properties on the sector to meet buyers’ need. So we questioned Daryl Fairweather — Redfin’s main economist, who also labored at the Boston Fed studying why householders enter foreclosure — to share her projections and feelings for what potential buyers and sellers can count on in the coming months.

There are early symptoms that the sector, in some sites, is cooling a bit

Fairweather says we’re viewing early symptoms that the housing market place is setting up to neat, at the very least in pricey coastal metros. “Buyers in marketplaces like Los Angeles, San Francisco, Boston and Seattle who have missing out on many bidding wars may possibly find they’re experiencing a lot less level of competition from other purchasers than they had been a month or two in the past,” claims Fairweather.

Also see: This story is element of a series where we ask popular true-estate economists about the housing sector. Here’s what the senior economist for Real estate agent.com informed us about the housing current market now.

For this cause, if you’re a nearby property hunter in a well-known migration spot like Nashville, Tenn. Atlanta or Miami, you must expect levels of competition from California and New York buyers who are likely to have greater housing budgets. “In Nashville, the ordinary out-of-towner has a housing funds that is practically 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher than the ordinary spending budget for neighborhood customers,” states Fairweather.

Mortgage loan premiums could proceed to rise in the near expression

It’s no key that interest rates are climbing quickly — and, thanks to soaring premiums as effectively as increasing property charges, regular property finance loan payments are up 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a yr ago. “I hope fees will proceed to rise in the close to time period so potential buyers who never however have a home loan rate locked with a lender must variable that into their budget,” states Fairweather. (See the lowest home finance loan premiums you can qualify for below.)

House-selling price development could slow before long

As for residence-value expansion, she expects a slowdown shortly, provided growing property finance loan fees. “I really do not believe household charges will go down, but purchasers may be relieved to know that the double-digit yr about calendar year rate expansion we have been suffering from is very likely to fall into the one digits in the coming months,” suggests Fairweather.

But this will not be universal in every single market place: Preferred Solar Belt migration places are likely to be the most resilient, meaning value development will likely keep on, but, in common, house-rate progress will start off to harmony out, according to Fairweather

Rents are also quite superior, so this could possibly not be the most effective time to shift

Buyers who are at present renting must also beware that rental asking price ranges are soaring. “They were being up 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} nationwide in March and as substantially as about 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in places like Austin, Texas, and Portland, Ore. If you make your mind up to pause your residence lookup for any purpose, keeping in your present lease could be a much better choice than going to a new rental residence,” claims Fairweather. This is due to the fact, she says, landlords are usually much less likely to increase rents as aggressively for present tenants as they do on freshly vacant models.

Emphasis on what matters when shopping for a dwelling

In this difficult marketplace, Fairweather suggests household potential buyers not get hung up on beauty particulars that are comparatively simple to replace or repair like paint color, cabinet hardware, out-of-date appliances and mild fixtures. “It can guide to a lowball offer you on a residence that would otherwise check out all your boxes, and, in a market where about two-thirds of gives confront bidding wars, it can value you the property,” says Fairweather. Instead, focus on the matters that subject more, like spot, square footage and layout — you can make cosmetic improvements at any time as soon as you possess the household.