Investment Property Loan Guide | 2022 Guidelines and Process

Investment Property Loan Guide | 2022 Guidelines and Process

Guide to investment property loans

Investment property loans are a lot like ‘standard’ mortgages, provided you want to buy a home with 1–4 units.

The application and approval processes work the same way, and mortgage rates are usually less than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher than for a standard mortgage.

However, the rules are a little stricter for an investment property loan than for a mortgage on your primary home. For instance, you likely need 15–20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down instead of 3–5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. And your credit score will need to be in the high 600s or 700s.

If you’re planning to buy an investment property in the near future, here’s what you need to know.


In this article (Skip to…)


What is an investment property?

An investment property is a home that is not your primary residence, and that you buy with the intention to generate rental income or sell for profit. Most commonly, these include one– to four–unit rental homes or houses that you buy to fix and flip. For the purposes of this article, we are not including commercial investment properties like apartments or office buildings.

How are investment properties different from second homes?

It’s important to distinguish between investment properties and second homes because mortgage rules and interest rates are different for each type of property. The biggest difference between the two is that you must occupy a second home for at least part of the year, while you – the owner – don’t live in an investment property.

A second home or vacation home might count as an investment property if you intend to rent it out even for short periods. However, lender policies vary over this.

For example, Fannie Mae lets you rent out a second home provided you occupy it yourself for a period each year, retain exclusive control of the home, and don’t rely on your anticipated rental income when you apply. Lenders will also expect a second home to be in a tourist area for a vacation home or a certain distance from your main house if you plan to use it as an occasional residence.

>Related: Second home vs. investment property mortgage rates

Investment property loan options

There are three main loan types used to finance investment properties:

  • Conforming loans: By far the most common option
  • Jumbo loans: Used when the loan exceeds conforming loan limits
  • Government-backed loans: Used only when you occupy one unit yourself and rent out the others (not for ‘true’ investment properties)

Most of those seeking investment property loans will require conventional mortgages. The majority of these are ‘conforming mortgages,’ meaning they conform to lending rules set by Fannie Mae and Freddie Mac. (More information below.)

It’s a condition of all government–backed loans (FHA, VA, and USDA loans) that the borrower occupies the home as their primary residence. So these are not good sources for investment property loans.

However, there is one exception. You can use a government–backed FHA or VA loan to buy a multifamily dwelling with two, three, or four units. And, provided you live in one of those, you can rent out the other(s).

Other ways to finance an investment property

Many investment property buyers use one of the three mainstream mortgage programs listed above. But other options include:

  • Home equity: A home equity loan or home equity line of credit (HELOC) on your current home
  • Private loans: Real estate investors will sometimes fund a purchase of rental property
  • Seller financing: Occasionally, a seller who owns a home outright may trade the lump sum she would normally receive for a continuing income stream
  • “Hard money loans”: These short–term loans can sometimes work well for house flippers

But most buying investment properties turn to mainstream mortgage lenders, including banks. You can find some through our website using the Request a Quote service. You’ll soon find a question that asks whether you want the loan for investment purposes.

The investment property loan process

If you plan to finance your investment property with a mainstream home loan (likely a conforming loan), the process will look very similar to any other home purchase. You will:

  1. Get preapproved for financing
  2. Find a home and make an offer
  3. Apply for the loan
  4. Lock an interest rate
  5. Go through the underwriting process
  6. Sign final papers on closing day

As when buying a home for yourself, it’s a good idea to get preapproved for a mortgage before you begin house hunting. That way, you’ll know how much home you can afford. And, more importantly, the seller and seller’s real estate agent will know you’re making a serious offer.

Before you settle on a lender, make sure to comparison shop for the very best mortgage rate you can find. Investment property mortgage rates are often 0.50 to 0.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (sometimes 0.875{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) higher than those for standard mortgages. And the lower your rate, the higher your profit margin on the property will be.

Is it hard to find investment property loans?

As a rule, it gets easier to find an investment property mortgage when the economy’s doing well and more difficult when it’s struggling. That’s because lenders see investment property loans as riskier than primary home loans. And they may restrict access to moderate their risk level in tough times.

For example, when the Covid–19 pandemic choked the economy, many lenders made qualifying for one of these loans very tough.

So how easily you’re going to find the loan you want will depend on the economic environment when you apply. But, during normal and good times, there are usually plenty of lenders willing to help out.

Investment property mortgage requirements

Mortgage lenders get to set their own requirements. And the guidelines for investment property loans are usually stricter than for a primary residence.

Though rules vary by lender, here are the broad guidelines you can usually expect to see for an investment property mortgage.

  • Minimum down payment: Often 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of purchase price, though some still require 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Minimum credit score: 680 with a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment; 620 with 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down
  • Maximum DTI: This is your debt–to–income ratio. Typically, your non–housing debts should be no greater than 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your gross monthly income. And your total debts plus housing costs shouldn’t exceed 36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. But some lenders are less strict, often allowing 36{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} respectively
  • Cash reserves: Many lenders want you to have cash reserves (or easily liquefied assets) that are sufficient for you to cope for six months without rental income
  • Loan limits: Government–backed mortgages and conforming mortgages have limits on the amount you can borrow. These vary according to local home prices
  • Documentation: Expect lenders to request two years of tax returns, two years of W–2s, and two months of bank statements at a minimum

In addition to your finances, mortgage lenders will also evaluate the property you hope to buy.

Lenders will typically lend on any mainstream property: a condo, apartment, manufactured home, single–family house, or multifamily house. But there may be rules about condition, safeness, year–round habitability, accessibility, and so on. An appraiser will establish whether the home is mortgageable.

Investment property loan rates

Lenders know that investment property loans are riskier than loans for owner–occupied homes. That’s because if a borrower gets into financial trouble, they’ll prioritize paying their main mortgage over their investment property mortgage.

As a result, lenders charge a higher interest rate for investment property loans than for ordinary mortgages as well as setting higher barriers to qualifying.

As we’ve already mentioned, these rates are often 0.50 to 0.75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (sometimes 0.875{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) higher. That will vary by lender as well as your down payment, credit score, cash reserves, and DTI.

To find out more, read: Investment and rental property mortgage rates.

Special mortgage rules for investment properties

One of the advantages of buying an investment property is that you can typically add your anticipated rental income to your existing income when you apply. That will help you prove you can comfortably afford your new mortgage payments.

However, don’t assume your lender will count all that extra income, nor that it will take your word for how much it will be. Lenders typically allow 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the future rental income to count toward your qualifying income. And they require a rental schedule, which will use the appraiser’s view of your likely rental income based on local comparisons with similar rental properties.

You’ll likely need that extra income to qualify. Because your lender will want to be sure you can afford payments on your existing mortgage (assuming you have one) as well as your new loan.

When you’re budgeting, also keep in mind that investment properties typically offer much more generous tax breaks than owner–occupied ones. So speak to your professional tax adviser to discover what those might mean to you.

Investment property loan FAQ

Do you need 20 percent down on an investment property loan?

That depends on your lender’s rules and the type of mortgage you want. Often 15 percent down is enough for a conventional loan. And for multifamily dwellings where you occupy one unit, you could put down 3.5 percent (FHA loans), 3 percent (conforming loans), or even 0 percent (VA loans)

Can you put 3 percent down on an investment property?

You cannot put 3 percent down on a ‘true’ investment property. But, as discussed above, a mortgage from Fannie Mae or Freddie Mac has a minimum 3 percent down payment for a multifamily dwelling where you live in one unit. So you can buy with one of these loans and still generate rental income from the additional units in your home.

Can you get a 30-year loan on an investment property?

Absolutely! Most borrowers do.

What bank will loan me money for an investment property? 

Many banks, mortgage lenders, and other lenders are happy to lend on investment properties as long as you meet lending criteria, which are stricter than for your main home. In addition, investment property loans are easier to find when the economy’s doing well. You might have a harder time finding investment property loans during economic downturns, like when the Covid pandemic was at its peak.

Can I use my 401(k) to buy an investment property?

That depends on the rules of the program(s) of which you’re a member. But most financial advisers warn against touching your retirement funds for any investment that’s even a bit risky. A better way to fund your investment property purchase might be with equity from your current home, via a cash–out refinance or second mortgage.

Can I live in an investment property? 

A ‘true’ investment property is one you do not live in. But your home may be considered an investment property if you buy a multifamily property, live in one unit, and rent the other(s) out. Indeed, this can be one of the most affordable ways to buy a rental property and start earning income from it.

How much can I borrow for an investment property? 

That depends on whether your chosen mortgage has loan limits. In theory, you could borrow millions with a jumbo loan, providing you can afford the monthly payments, have a big down payment, and are highly creditworthy.

The information contained on The Mortgage Reports website is for informational purposes only and is not an advertisement for products offered by Full Beaker. The views and opinions expressed herein are those of the author and do not reflect the policy or position of Full Beaker, its officers, parent, or affiliates.
Why Buying A Rental Property In 2022 Could Be A Smart Investment

Why Buying A Rental Property In 2022 Could Be A Smart Investment

Why Buying A Rental Property In 2022 Could Be A Smart Investment

LifestyleVisuals/iStock by means of Getty Visuals

If you have followed my article content for a though, you most likely know that I am usually in opposition to the idea of buying rental attributes.

I feel that most investors undervalue risks, overestimate returns, and forget to take into consideration the destructive affect that owning a rental house can have on your lifestyle, occupation, and even your overall health.

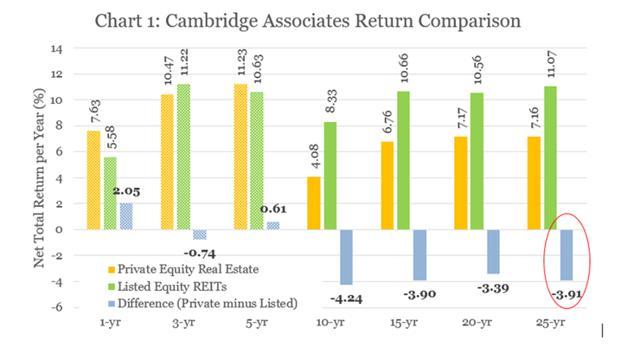
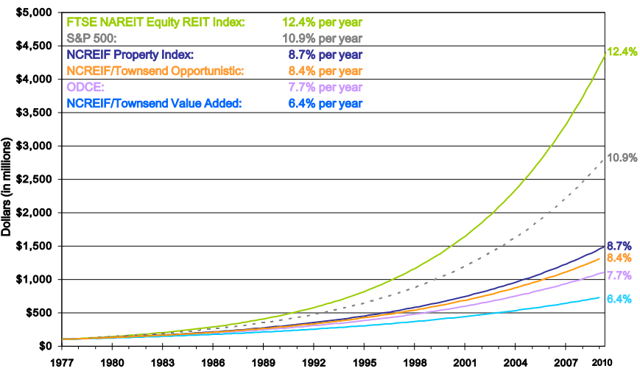
Over and above that, quite a few reports have shown that publicly mentioned REITs (VNQ) outperform non-public genuine estate more than multi-ten years time periods, and this makes perception when you look at that REITs appreciate significant economies of scale, are managed by the brightest in this business, have much better funds, interactions with tenants, and I move on numerous other reasons:

REITs outperform private real estate

REITs outperform non-public true estate (OTC:EPRA)

REITs outperform private real estate

REITs outperform private actual estate (Cambridge Investigate through NAREIT)

(To discover a lot more about why I frequently favor REITs in excess of rentals, you can click below to go through my hottest short article on this subject matter.)

But this does not imply that all rental property investments are poor for each se.

In fact, supplied the latest environment situations, I imagine that getting a rental residence may possibly even make a wonderful investment decision in 2022.

Lately, I even bought one particular myself. It is not just a rental home because I will use it as my most important home, but I manufactured the purchase mainly because of the similar rationale.

Below, I existing 3 explanations why you may perhaps want to acquire a rental property in 2022, and following that, I existing a few REIT solutions for people of you who you should not want to deal with the unpleasant 3 Ts: tenants, toilets, and trash.

Reason #1: Hugely Leveraged Bet on Inflation

These days, we have extremely low curiosity costs, but unusually substantial inflation.

This blend strongly favors highly leveraged, inflation-protected real asset investments like rental qualities.

This is the most effective form of surroundings to be a landlord/borrower simply because you are purchasing belongings that respect in benefit with personal debt that’s depreciating in price.

Let us look at a simple illustration:

  • You obtain a rental assets for $200,000.

  • You finance $160,000 (80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) of it with a 30-year mounted-level mortgage loan.

  • Your desire fee is 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and your regular rental money is $1,200.

In a very low inflation entire world, this investment decision wouldn’t be anything extraordinary. I would argue that this is a inadequate investment decision the moment you thoroughly account for all the bills and the worth of your time.

But in a significant inflation world, it is a really diverse story.

Today, inflation is at 7.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and housing is appreciating by even a lot more than that in most well known and rising metropolitan areas. Assuming your rental home gains 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in value, then you essentially attained a 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} return on fairness for the reason that of your mounted-charge property finance loan. The asset improves in serious value, but the debt is lowering in true price, resulting in exponential equity benefit advancement.

Now, your loan-to-benefit also drops from 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 73{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, which lowers threats and may perhaps allow you to refinance to pull equity out of the assets and reinvest it in other places.

In that feeling, getting a rental house with a fastened-price mortgage is basically a leveraged bet on inflation, and offered the present-day environment get, it is an expense that may make a whole lot of feeling. Even if you consider that inflationary pressures will neat down, it may perhaps make feeling as a hedge in your portfolio in scenario you are completely wrong and inflation stays elevated for decades to occur. As I reveal in a current short article, a rental house is a much greater inflation hedge than gold.

Purpose #2: War Or Not – People Have to have Housing

Russia’s invasion of Ukraine is causing excessive uncertainty.

It is not only a humanitarian crisis, but also an financial crisis, and the outcomes are nevertheless quite a lot unknown to most of us.

Companies around the world are now struggling the pain, and this could be just the beginning. To give a couple illustrations:

McDonald’s (MCD) experienced to quickly shut ~1,000 restaurants in Russia and Ukraine but will continue on to shell out its workforce. These outlets depict practically 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the company’s revenue so it is major.

MCD is not an isolated circumstance. KFC (YUM), Starbucks (SBUX), Coca-Cola (KO), PepsiCo (PEP), Fb (FB), Netflix (NFLX), Visa (V), Mastercard (MA), etcetera… are all using the very same techniques to protest versus Russia’s war crimes.

Russia is a major sector and so this is a good deal of dropped income and financial gain for these organizations. Past that, the disaster is creating a spike in the price tag of most organic means, which will also impact businesses.

Could this be ample for the inventory market to crash?

I will not know. I never assume that anyone appreciates.

But what I know is that housing is a safe and sound haven in this crisis due to the fact individuals even now have to have a roof above their heads and what’s happening in Eastern Europe has little effect on housing in the US.

In that feeling, shopping for a rental residence in the US might provide as a hedge in opposition to the war in Ukraine. You get to secure virtually-totally free money by means of a long-dated preset-fee home finance loan and obtain a defensive, inflation-protected asset that ought to go on to improve in benefit about time and throw off rental cash flow irrespective of the war.

Motive #3: The Diversification Advantages Are Starting to be Progressively Important

Now much more than at any time, buyers will need to make sure that they are properly diversified.

Bonds (LQD) and Treasuries (IEF) generate close to almost nothing even as inflation is surging and stocks (SPY) have become particularly risky. For superior or even worse, REITs have also come to be ever more volatile, which may well flip off several buyers.

Adding a rental assets to your portfolio may well assist you diversify pitfalls and sleep improved at evening realizing that you don’t have all your income at the risk of a stock sector crash.

To be crystal clear, it does not suggest that a rental really should be viewed as a safe investment. But having some belongings out of the inventory sector can lower your portfolio threat through times of extreme uncertainty like currently.

Obtaining a Rental vs. Buying REITs: Which is Better?

REITs are publicly detailed true estate financial commitment firms that permit you to make investments in genuine estate by buying shares. In that feeling, they take pleasure in all the exact rewards of leverage and inflation protection. You supply the equity by shopping for shares, and the REITs then include home loans on your equity to get qualities and share the monetary reward with you.

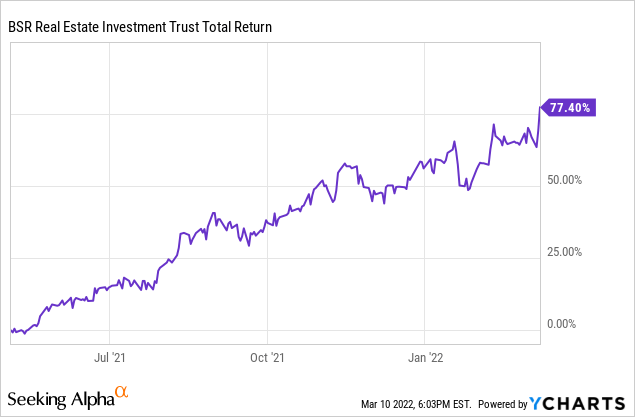
To illustrate this point, consider our current financial investment in BSR REIT (OTCPK:BSRTF), an apartment REIT that focuses on Texan marketplaces. We invested in the company in Might 2021, and in considerably less than a person calendar year, it has already produced a close to-80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} return:

BSR REIT (<a href=
Info by YCharts

It was so worthwhile since its equilibrium sheet is about 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} leveraged and its houses liked significant lease development and appreciation.

In that sense, REITs are not unique from rental homes, but in addition, you also get qualified management, diversification, liquidity, and very likely outstanding extensive-term returns. For this reason, I favor REITs in excess of rentals nine moments out of ten. They merely supply superior threat-and-trouble-modified returns in most scenarios.

Even then, supplied what is actually taking place in the planet appropriate now, there is a potent circumstance to be built for also investing in non-public real estate for the further diversification, control, and peace of intellect that can arrive with it.

It is not for every person, but if you have the capacity to borrow at a reduced fee in a secure way, then it can give you a great hedge against inflation and also the war in Ukraine.

You could of program also get this hedge by the REIT marketplace, but you won’t be able to be as well diversified in this sector. Russia’s invasion of Ukraine does not just effect Europe, but the entire earth and its REITs.

Generally, it is a excellent matter to be publicly stated because it enables you to easily and cheaply invest in/market investments. But for the duration of instances of extreme uncertainty like now, it is excellent to also have some assets that are not vulnerable to the mood of the inventory industry. That is wherever rental homes appear in.

Base Line

Get equally: REITs and rentals.

In most situations, I would favor REITs, but provided modern extreme uncertainty, I would suggest investing in non-public rental homes for extra diversification.

Now, I have 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of my web worth in REITs/Rentals and about 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of that is in REITs and 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in rentals. Which is the best combine for me.

FP Answers: Can I save tax by transferring an investment property to a corporation?

FP Answers: Can I save tax by transferring an investment property to a corporation?

The potential transfer of the property presents an opportunity to take back tax-free cash from your corporation

Article content

By Julie Cazzin with Andrew Dobson

Advertisement 2

Article content

Q: Are there tax consequences if I transfer my investment property — a duplex that I own 100 per cent of — into my incorporated company? If so, how can I minimize this tax? — Johnny L. 

FP Answers: If you transfer certain types of property to a corporation, you may be able to defer some or all of the income that may otherwise arise by simply making an election under Section 85 of the Income Tax Act.

A Section 85 rollover of your investment property to your corporation can be done on a tax-deferred basis. In some cases, a transferor may choose to trigger a partial capital gain, such as when you have a relatively low income for the year or if you have capital losses you can use to offset the gain. 

One requirement is you must receive “share consideration” — shares of the company — back from the corporation. You can also receive “non-share consideration,” such as a note receivable, but this will trigger a capital gain if it exceeds the tax cost of the property. 

Advertisement 3

Article content

As well, future rental income from the duplex will be taxed as passive income in your corporation, which will be a rate similar to the highest personal marginal tax rate. And if you withdraw this income from the corporation at a future date, factoring in the potential refundable tax to your corporation upon paying a dividend to you, the combined corporate and personal tax payable could be more than you would have paid to earn all the income personally in the first place.

If the goal of the transfer is to lower your tax payable on the rental income, depending on your income and province or territory of residence, this may not happen.

If you decide to sell the property in the future, the capital gain will be taxable to the corporation. It may pay tax at a higher rate than what you may have paid if you continued to hold it personally, given corporations pay tax rates on investment income similar to the top personal marginal tax rates. 

Advertisement 4

Article content

One of the primary benefits of this transfer strategy is that you may be able to get cash out from the corporation tax free.

For example, if you bought the property for $800,000 and it is now worth $1 million, you may be able to take back up to $800,000 of tax-free cash from the corporation in exchange for your transfer.

This may present an opportunity if you have a lot of cash or investments in the corporation that you want to access personally, or if you will have lots of cash flow in the future. 

Keep in mind that holding investments such as this rental property in your corporation may negate other tax benefits like the lifetime capital gains exemption.

If your business could be sold some day, you may not want to hold rental real estate, stocks or mutual funds there. Otherwise, you may not be able to claim the lifetime capital gains exemption on the sale of the business, which could exempt up to $913,630 of capital gains from being taxable. 

Advertisement 5

Article content

If this were a consideration, you could set up a separate holding company to hold assets such as the rental property and preserve access to the lifetime capital gains exemption.

Doing so may also be advisable if your business could be subject to creditor risk or other potential liability. If you hold the rental property in the same corporation as your active business and the latter gets sued, it may expose your rental property or other assets that could otherwise be insulated by owning them in a separate company. 

Advertisement 6

Article content

Holding your real estate in your corporation may also prevent you from accessing small-business tax rates due to the investment income the property generates.

If your investment income exceeds $50,000, your corporation may start to lose the benefit of the small-business deduction that allows the corporation to pay tax at lower rates on active business income. 

Furthermore, transferring real estate to a corporation may trigger land transfer taxes and legal fees. In a city such as Toronto that charges a municipal land transfer tax in addition to the provincial land transfer tax, a $1-million property could result in $32,950 of land transfer taxes. 

If the property is mortgaged, you would need to ensure the lender will allow the mortgage to be assumed by the corporation. You may need to refinance the mortgage and there could be penalties or other costs involved. Corporate borrowers may have to pay higher interest rates and face other restrictions. 

Advertisement 7

Article content

The potential transfer of the property presents an opportunity to take back tax-free cash from your corporation, now or in the future. However, there may not be tax savings on the rental income or the eventual capital gain. There could be immediate land transfer taxes and legal fees and longer-term costs due to higher mortgage interest rates. Seek legal and tax advice to assess the process, implications and cost/benefit of such a strategy.

Andrew Dobson is a fee-only/advice-only certified financial planner (CFP) and chartered investment manager (CIM) at Objective Financial Partners Inc.

_____________________________________________________________

 For more stories like this one, sign up for the FP Investor newsletter.

______________________________________________________________

Advertisement

Comments

Postmedia is committed to maintaining a lively but civil forum for discussion and encourage all readers to share their views on our articles. Comments may take up to an hour for moderation before appearing on the site. We ask you to keep your comments relevant and respectful. We have enabled email notifications—you will now receive an email if you receive a reply to your comment, there is an update to a comment thread you follow or if a user you follow comments. Visit our Community Guidelines for more information and details on how to adjust your email settings.

10 Investment Property Risks and How to Minimise Them

10 Investment Property Risks and How to Minimise Them

Cheapest desire premiums for 1-yr mounted household loans

The comparison desk under displays some of the 1 calendar year set amount expense residence bank loan solutions on Canstar’s database with back links to lenders’ web sites out there for a personal loan amount of money of $350,000 at 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} LVR in NSW, and offered for Principal and Fascination repayments. The outcomes are sorted by comparison charge (least expensive to best), then by provider name (alphabetically). Right before committing to a certain home personal loan products, test upfront with your loan provider and read through the applicable financial loan documentation to verify whether the conditions of the financial loan satisfy your needs and compensation capability. Use Canstar’s household financial loans comparison selector to view a wider assortment of house mortgage goods. Canstar might receive a rate for referrals.

*Comparison fee based on financial loan amount of $150,000. Study the Comparison Charge Warning.

Most affordable fascination rates for 3-year preset home loans

The comparison desk under displays some of the 3 calendar year fixed rate expenditure household loan items on Canstar’s database with hyperlinks to lenders’ sites readily available for a bank loan total of $350,000 at 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} LVR in NSW, and available for Principal and Desire repayments. The effects are sorted by comparison fee (least expensive to optimum), then by provider name (alphabetically).Ahead of committing to a unique property loan products, test upfront with your lender and study the relevant loan documentation to verify regardless of whether the phrases of the personal loan meet up with your demands and reimbursement capacity. Use Canstar’s house financial loans comparison selector to perspective a wider range of residence mortgage solutions. Canstar may well earn a cost for referrals.

*Comparison price dependent on personal loan amount of $150,000. Read through the Comparison Rate Warning.

Lowest fascination costs for 5-12 months fixed residence loans

The comparison tables down below shows some of the 5 calendar year preset rate expenditure home financial loan goods on Canstar’s databases with one-way links to lenders’ internet websites accessible for a bank loan sum of $350,000 at 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} LVR in NSW, and out there for Principal and Fascination repayments. The results are sorted by comparison level (most affordable to optimum), then by service provider title (alphabetically).Just before committing to a specific household bank loan solution, look at upfront with your financial institution and study the relevant personal loan documentation to validate regardless of whether the phrases of the personal loan meet up with your requires and reimbursement capability. Use Canstar’s house financial loans comparison selector to watch a broader selection of residence bank loan goods. Canstar may earn a charge for referrals.

*Comparison price dependent on mortgage sum of $150,000. Go through the Comparison Level Warning.


7. Funds circulation

Hard cash stream is the net revenue that the house trader earns after paying out off an financial commitment property’s bills, taxes and home loan repayments. Damaging funds circulation is experienced when the costs exceed the rent collected. In this sort of conditions, you have to have to use other income resources to pay back for the property. As a result, cash movement risk has the likelihood of producing a negative money move of a far more major magnitude than envisioned.

How to minimise this hazard

  • Forecast your earnings and costs and make it possible for for contingencies.
  • Create a sizeable home portfolio with enough hard cash stream to aid your requirements.
  • Talk to a residence strategist to support you plot your extended-term tactic and create your home portfolio in accordance to your circumstances and danger hunger.

8. Deficiency of liquidity

A major risk precise to true estate investing is that houses are illiquid, that is, they cannot be effortlessly converted into income. This hazard manifests when an trader is forced to provide a home at an unwanted selling price due to their money or individual situation.

How to minimise this threat

There is no quick remedy for handling this possibility, so you really should embrace it by preserving liquidity in your portfolio. Having said that, it would be better to stay away from it altogether by creating a buffer of liquid investments or income. When contemplating your acquisition, consider your will need for liquidity and commit wisely.

9. Own risk

Financial investment portfolios could be negatively impacted by various unforeseen elements, together with reduction of money thanks to personal injury, divorce or job loss. These are termed own dangers.

How to minimise this danger

To mitigate this threat, you should really consistently overview your lengthy-phrase technique and invest in building a positive cash circulation residence portfolio. In other phrases, you should really have a neutral-to-optimistic geared portfolio, making certain that your expenditure portfolio does not rely on your contributions. Nevertheless the particular person properties can chase growth or hard cash move, be certain that your in general investment portfolio does not have to have as well substantially of your cash to work.

A further successful way to mitigate the chance is to insure your self. All home traders should have life insurance policy and revenue security. 1 of the obligations of buyers is their potential to assistance their loans whilst growing their residence portfolio. In the same way, for unexpected instances this kind of as death or harm, you have to have to make certain your spouse and children will be able to maintain the financial commitment properties.

Consequently, it is significant to consult with a experienced insurance policy broker and an accountant to get tips on the style and level of covers essential.

10. Foreclosures danger

This danger manifests when an investor just cannot pay their mortgage payments on time for a extended period they default on their financial loan obligations so the loan provider forecloses.

How to minimise this risk

You can regulate the foreclosures threat by making sure all your repayments are designed on time. You need to also have an unexpected emergency fund to address a handful of months’ worthy of of repayments. Eventually, parking money in an offset account will decrease the interest you are billed and give you with liquidity and versatility at the exact time.

The Property Wealth Blueprint


This is an edited extract from The Home Wealth Blueprint by Rasti Vaibhav ($39.95) republished with permission.


Cover impression supply: Soho A Studio/Shutterstock.com


Rasti VaibhavAbout Rasti Vaibhav

Rasti Vaibhav (B.Arch, M.Comp, MBA, CFA) is the founder of prospective buyers company firm Get Uncommon Qualities. He is a licensed impartial buyer’s agent, house professional and long-term home trader, who specialises in assisting dwelling purchasers and buyers obtain the correct home at the appropriate price tag Australia-wide.


Thanks for going to Canstar, Australia’s major monetary comparison site*


5 ways to spot an investment property

5 ways to spot an investment property

&#13
&#13

5 ways to spot an investment property

&#13

Not all properties are really worth investing in – a residence pro reveals what to seem for and what to avoid

&#13
&#13
&#13
&#13

If you have been to consider just about every assets present you viewed, you’d assume investing in bricks and mortar is a confident-hearth way to increase your financial institution equilibrium. And whilst it surely can go away you with a wholesome revenue, you need to hurry the obtaining procedure at your peril. 

Browse More: How to renovate an outdated residence

Whether you intend to renovate, offer up and reinvest in another project property, or embark on a invest in-to-enable enterprise, it truly is critical to do your investigate before you sign on the dotted line.

Residence professional Thomas Goodman of MyJobQuote has shared his assistance on the 5 signals to seem out for when taking into consideration investment potential to assure you really do not waste your time and revenue on a residence that’s unlikely to enhance in worth.

1. Locale, location, place

It is been mentioned plenty of instances right before but that is due to the fact in which you get actually does issue. You may perhaps be tempted by a low cost assets in what you may take into account an up-and-coming location, but getting a pricier property in a locale with a powerful housing current market already may be fewer of a gamble.

Goodman states: “Do substantial investigation on the area, the demographic traits, and the houses that have recently been marketed, in addition to any prepared developments. These can all impact assets cost and come to a decision no matter whether your house will develop in price above the coming many years.”

2. Search for difficulties that can be solved

Goodman is a wonderful believer that there is a solution to every difficulty, it just is dependent on how considerably you might be keen to commit.

“Badly laid-out qualities can be reconfigured,” he says. “Unattractive attributes can be brightened with a new lick of paint, and you can upcycle or swap old pieces of furnishings for a brand name-new inside.”

If you’re doing work with a small budget and want to maximise your return with nominal anxiety, appear for properties that just demand cosmetic alterations – and be guaranteed to get a skilled study before you make an offer to test for any unpleasant surprises.

Image: HUSKReplacing kitchen cupboard doorways can make all the change to a weary area. Image: HUSK
Look at what minor alterations will make the space additional attractive. Often it can be as basic as updating worn out kitchen area cabinets.

3. Seem for eco-opportunity

Some buyers wrongly dismiss a put if it has weak energy functionality, but incorporating insulation and air flow can swiftly switch this close to – though the present-day performance ought to be viewed as when you come to make an offer you on the residence. 

Goodman suggests: “If you have the funds to renovate your property, you could call an engineer to incorporate in eco-friendly attributes, these types of as an energy-successful heating program or photo voltaic panels on the roof. This will promptly modernise any property and choose it into the 21st century, which is certain to raise its price in the long operate.”

4. Seem to the long run

If you might be willing to participate in the lengthy game, it truly is a very good plan to look at if the spot where you are property-hunting has any large advancement strategies in the pipeline. If so, then holding onto an investment house right until the sector catches up could be a shrewd shift.

Additions these kinds of as new faculties, new businesses and regeneration tasks will make the area more attractive and aid your expense mature.

Image: Oak Furniture LandChanging an unused attic is a good way to increase benefit to a home. Image: Oak Home furnishings Land
But Goodman claims it’s also critical to look to the long term with regards to how you build your house, far too.

He explains: “The down payment for a home finance loan may perhaps signify you are at this time unable to pay for a massive renovation. Having said that, maybe there is likely for a loft conversion or a driveway redesign in the future? Setting up forward, and conserving toward your plans, will direct you to enjoy the rewards of your financial commitment afterwards.”

5. Study nearby demand

Though you could know an location is sought right after, have you deemed what sort of home is most in demand? There is no place getting a a single-bed room flat if the place is preferred with family members, for instance, whilst on the flip facet, one particular-bedroom flats may possibly change a rapid profit in parts well-liked with youthful persons.

Goodman claims: “Monitor the housing costs in the area for a whilst ahead of acquire, so you can see if they fluctuate and will guide to an increase in your investment.”

Study A lot more: 24 wise strategies to flip a home for earnings

Picture: Ewelina W / Shutterstock

&#13
&#13
&#13

How to Succeed With Your First Rental Property Investment

How to Succeed With Your First Rental Property Investment

Source: fitsmallbusiness.com

Investing in rental attributes – especially, residential one- and multi-spouse and children rental homes – is a certain-hearth way to develop wealth. Some investors have far more achievements than some others, while.

Why is this? And how can a to start with-time trader boost his or her odds of hitting a bulls-eye the very first time out? We’ll include all you want to know listed here.

Why Do Rental Home Investments Fall short?

When you commit in a rental residence, either you make income or you eliminate it. If you examine the causes, there are actually only a pair of means this expenditure can are unsuccessful.

  • You’ve procured the wrong home. If you buy the mistaken just one, it’s likely not heading to matter what you do. You will never receive the revenue you need to make it a worthwhile investment. Everything is dependent on getting a appropriate assets.
  • You are running the property improperly. Good results does not transpire at the closing table. You have to control your holdings in a way that assures they continue being profitable for several years. This incorporates both how you tackle the physical property and constructing nutritious associations with your tenants.

Clearly, a number of facets will drop beneath one or the other of these types, but these two are mainly all there is to it. If you want to be prosperous, you just have to obtain the proper residence and handle it perfectly.

Six Approaches to Assurance Your Accomplishment

Source: mcgrawhillprofessionalbusinessblog.com

Instructing you to invest in the right residence and handle it nicely doesn’t make for a really useful report, so let us split this down and seem at some of the distinct means you can assurance achievements.

1. Know What You Want

It is critical that you know precisely what you want out of a home just before you commence wanting for a person to receive – absolutely in advance of you make any features. Hold both of those your small-term goals and your prolonged-time period vision in intellect.

Is your purpose to get paid a handful of hundred bucks in passive regular monthly earnings? Or do you hope to establish an full portfolio of homes?

Are you only interested in investing locally? Or are you keen to invest any where the numbers pencil out?

Would you like solitary-relatives attributes or multi-relatives properties? Or could you be open to anything at all?

By defining your objectives and anticipations on the entrance conclude, you are going to give by yourself the profit of a concentrated house research.

2. Run Conservative Figures

Source: medium.com

Real estate investing is principally a numbers video game. If they get the job done out on paper, it’s typically a fairly sturdy investment decision if they really do not, then you really should search elsewhere.

The query is, how do you operate the quantities so you are hardly ever (if at any time) completely wrong? The remedy to that problem is a two-parter: initially, you have to have the proper equations second, you need to have exact inputs.

To be a lot more exact, you have to use conservative quantities. There are too quite a few suitable equations to cite all of them in this posting – these types of as web running money, cap costs, dollars move, and money-on-money return – but you need to just identify that this section of the approach will get time.

Most of your time as an investor will be used crunching quantities. If you tumble into the behavior of using shortcuts in this article, you are going to spend for it afterwards.

To operate figures conservatively, often round up on fees and round down on money. For example, if it seems to be as if routine maintenance will price tag you $237 for each thirty day period, use $300 in your calculations. If you imagine you can get $1775 for lease, bank on $1,700.

On top rated of all that, generally anticipate at minimum one particular thirty day period of emptiness for each 12 months.

3. Clear away Thoughts from the Equation

There’s minimal room for emotion in genuine estate. If you’re obtaining a residence to dwell in, absolutely sure, you can permit your feelings play a role.

But a rental house is a pure company possibility. The figures both work or they really do not. If you uncover oneself building excuses to bend the quantities, that is a signal you are about to make a mistake. Retain it black and white.

4. Make Your Individual Staff

Source: noradarealestate.com

So a great deal of your achievements as a genuine estate investor will depend on the persons with whom you surround oneself. If you can assemble a strong staff of proficient and trustworthy colleagues, you should really have as considerably achievement in this industry as you’d like.

You must have a handful of folks in unique on your crew. The 1st is an seasoned true estate agent who can assist you find offers (especially off-sector kinds) and crunch the quantities.

The second is a skilled property manager like GreenResidential.com to manage all the working day-to-working day administration duties (like tenant screening, rent assortment, repairs and servicing, accounting, and so on.). The 3rd is a great authentic estate lawyer and/or CPA. This particular person will aid you optimize your defense and money move for bigger ROI.

5. Be a Meticulous Screener

Even the most conservative numbers can occur crashing down if you get bad tenants who don’t shell out and/or handle your assets inadequately. The important to finding superior tenants is to be a meticulous screener.

At moments, comprehensive screening could feel unwanted and intrusive, but you have to do it. Operate track record checks, validate profits, talk with prior landlords, chat with their employer – do anything you can!

Expending a few additional hrs to screen up front can preserve you countless numbers of bucks in the long run.

6. Conserve and Reinvest Gains

Resource: investbetter.co

As soon as the 1st hire examine settles into your lender account, you will possibly come to feel the temptation to begin upgrading your possess life-style. You are going to believe, “I did it!”

But don’t go ridiculous just yet. The most profitable serious estate buyers are the ones who strategically benefit from the funds they gain.

First off, you should really established aside at the very least 3 months’ well worth of fees for each individual house. If it prices you $1,500 a month to pay out the home loan, insurance coverage, taxes, and utilities, you should put at the very least $4,500 in a devoted checking account.

As soon as you have that emergency fund set up, we recommend putting just about every further dime toward a down payment on a next residence. Repeat this system with the 2nd house, and that will direct to compounding money. At that place, it may choose only a handful of months just before you’re equipped to invest in your 3rd house, and so on.

Incorporating it All Up

When everything is claimed and completed, rental home investing good results without a doubt is composed of almost nothing more than deciding on the correct properties and running them very well. If you do that continually, it’ll be a make any difference of only a couple years in advance of you have your very own mini genuine estate empire.

And all it can take is 5, 10, or 15 properties to start constructing considerable wealth. Excellent luck!