Homie layoffs: Utah real estate disruptor cuts staff due to housing market issues

Homie layoffs: Utah real estate disruptor cuts staff due to housing market issues

Utah actual estate market place disruptor Homie introduced companywide layoffs previous week as the tech startup lowered its workforce by some 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} amid unparalleled ailments for home customers and sellers in Utah and all-around the region.

Homie co-founder and CEO Johnny Hanna reported the team reductions impacted 119 workers across the company’s operations in Utah, Arizona, Colorado, Idaho and Nevada. Hanna, a veteran Utah entrepreneur, claimed a confluence of current market situations place the firm in a situation of needing to make vital variations he described as the hardest choice he’s had to make in his occupation.

“Record reduced inventories have completely played a function in this,” Hanna explained. “2021 was currently an amazingly aggressive 12 months and we commenced out this year with even much less households than the same time final yr. And it’s even a lot more aggressive.”

The shift in U.S. households-for-sale inventories was highlighted in a Nationwide Association of Realtors report issued previous week that found putting reductions in readily available properties considering that the get started of the COVID-19 pandemic.

In just one particular group, properties inexpensive to homes earning $75,000-$100,000 annually, the realtors’ assessment identified 400,000 much less reasonably priced homes offered for sale compared to the commence of the pandemic — 245,300 in December 2021 vs. 656,200 in December 2019.

For probable home consumers in that money classification, there was a single very affordable listing for just about every 65 homes at the close of last year, vs . the 2019 ratio of a single inexpensive listing for each individual 24 households.

Hanna observed other components are at engage in in the residential actual estate market, including big advancement in homeowners’ fairness amid skyrocketing values. The newfound property prosperity, Hanna mentioned, is lessening problem amid sellers about how much they are spending out in standard true estate agent contracts, which can operate as higher as 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the home’s sale rate. And, Hanna noted that in marketplace ailments in which most home sellers are entertaining various, and occasionally dozens, of features, these equipped to fork out in cash were being trumping financial institution-financed consumers.

Homie’s employees reduction represents a pivot for the firm that, just in advance of the COVID-19 pandemic began altering the environment, was celebrating a venture financial commitment milestone.

In February 2020, Homie introduced a $23 million Collection B funding spherical that, subsequent a $10 million Collection A in 2018, would help fuel the company’s designs to increase its present-day bases in Utah and Arizona into new arenas, such as Las Vegas, Boise, Idaho, and Colorado Springs, Colorado.

Homie has developed a residential real estate transaction technique that dispenses with the fee-based strategy utilized by legacy authentic estate brokers who typically charge a merged 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of a home’s sale cost. Instead, Homie employs a flat-rate method of $1,500 for sellers and features rebates on the customer aspect of the equation and uses a program method, together with agents and lawyers, to enhance efficiencies for a complex course of action that, for most persons, signifies the biggest monetary transaction of their lives.

Because its launch in 2016, the corporation has also extra Homie Financial loans, Homie Title and Homie Insurance in an energy to produce a one particular-prevent, “end-to-stop genuine estate knowledge.” Homie claimed in early 2020 it experienced saved clients some $55 million in commission charges and had $1 billion in authentic estate transactions in 2019. The company also reported it grew its revenues by some 150{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} that yr.

Adhering to the 2020 funding announcement, Hanna claimed the key to his company’s success has been obtaining the appropriate relationship of technology, providers and serious-earth experience.

“Buying or offering a house is high priced and time-consuming simply because of all the different providers you have to perform with,” Hanna stated in a statement at the time. “Communication will become a match of phone simply because of all the get-togethers involved. We are disrupting the classic design and conserving customers thousands of bucks by combining engineering, a group of industry experts and a just one-quit shop for genuine estate.

“Technology has improved all the things apart from the serious estate business enterprise model. That time has eventually arrive.”

On Monday, Hanna also highlighted yet another somewhat new Homie support alternative, in which the business helps buyers make a financial institution-backed income present, a method which is become progressively suitable in a marketplace in which potential consumers much outnumber sellers. Hanna reported the means for all those searching for a new house to contend with an all-dollars offer you was no lengthier a nicety, but virtually demanded, amid document opposition for each individual home that goes on the sector.

Hanna also pointed out how thankful he was for the do the job all of Homie’s current and previous staff members have accomplished in expanding the company and reported the reaction he obtained from a social media publishing about the layoffs gave him encouragement that the previous personnel would locate new possibilities.

“I posted on LinkedIn that we were going to enable go of pretty much 120 workers and requested the group to come jointly,” Hanna explained. “And I was blown away at the responses and the supportive setting that we have right here. Parting methods with men and women I adore is actually difficult but knowing they’re being attained out to is a consolation.”
5 economists and real estate pros share predictions for the 2022 housing market

5 economists and real estate pros share predictions for the 2022 housing market

What economists and other execs consider will materialize to the housing current market in 2022.


Getty Photographs

It’s been a wild experience for house potential buyers and aspiring property purchasers about the past calendar year, with bidding wars and soaring selling prices — as fascination premiums held in close proximity to historic lows (see the most affordable prices you could qualify for in this article). Here’s what 5 economists and actual estate pros advised us they considered would occur in 2022.

Prediction 1: Property finance loan rates will increase

“Mortgage charges snapped upward in January as mortgage investors understood what the Fed intends to do, which is raise fascination charges aggressively this 12 months,” says Holden Lewis, home and home loan qualified at NerdWallet. “Now, mortgage loan costs are increasing much more slowly as markets wait around for the Fed to clarify their timetable.”

“For point of view, the 30-12 months mortgage averaged 4.09{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 2010s and 12.71{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the 1980s, people today acquired a lot of houses in both of those eras,” claims Lewis. This thirty day period, Bankrate’s chief financial analyst Greg McBride says he expects 30-year set fee home loans to typical between 3.65{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 3.85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, with the 15-12 months mounted ranging concerning 2.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. “The bulk of these amount improve moves have been made in January as markets reset their expectations on the Federal Reserve. Moves in the up coming few months, nevertheless, ought to be a lot more subdued,” suggests McBride.

But with premiums growing for the earlier number of months, reaching their optimum concentrations considering that March 2020, Gregory Heym, main economist at Brown Harris Stevens, claims they are most likely to proceed to rise as the Federal Reserve tapers its bond purchases, which will guide to a charge hike most likely in March. Of program, home loans go up and down 7 days to 7 days, but Lewis claims: “Expect a lot more up months than down weeks in 2022.”  (See the most affordable rates you could qualify for listed here.)

Even while the Fed doesn’t straight control home loan premiums, the overall tightening plan of halting the order of mortgage-backed securities and elevating of the shorter-time period Fed funds charge will push house loan charges up. In simple fact, Lawrence Yun, chief economist at the Nationwide Affiliation of Realtors, says: “The typical fee on a 30-yr fixed amount home loan is probable to get to 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} by the fourth quarter.”

Prediction 2: Dwelling price advancement could ‘return to normalcy’

Heym states the industry is struggling from report-lower inventory concentrations, which has driven costs to new highs even as the amount of product sales has declined. “I don’t assume this to change in the upcoming few months as household builders simply cannot make properties speedy sufficient to aid the provide difficulty,” suggests Heym. Especially, Yun claims household selling prices are solidly higher by double-digit percentages compared to just one ago. “However, with mortgage premiums going up and some household potential buyers receiving priced out, residence selling price growth will return to normalcy, to all-around 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for all of 2022,” suggests Yun.

Prediction 3: Count on in close proximity to-expression bidding wars

The clock is also ticking as 2021 curiosity charge locks with 60-90 working day expirations are set to experienced any day. But what does this necessarily mean for consumers? Effectively, they’re speeding and overbidding on attributes in the hopes of securing a small fascination charge just before the upcoming Fed boost. “This is producing bidding war frenzies,” suggests Pierre Debbas, managing lover of serious estate legislation organization Romer Debbas LLP. 

Prediction 4: It will however be a hard market for purchasers though

Potential buyers will continue to have limited possibilities in most places as inventory will continue to be scarce, professionals say. “Prices will continue on to rise, which blended with increased property finance loan prices, will drive some prospective buyers out of the sector,” suggests Heym. That said, it will proceed to be a sturdy seller’s market, which signifies if you’ve been imagining about listing your home — there’s no time like the current. 

Even though energy will remain firmly in the arms of sellers this 12 months, in accordance to Nicole Bachaud, a Zillow economist, price ranges will rise considerably. “We’re viewing month-to-month growth accelerate earlier in the 12 months than regular, but we really don’t expect they’ll increase pretty as a lot as they did in 2021,” states Bachaud. In accordance to knowledge from Zillow, residence values in 2021 finished up 19.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the year and the forecast calls for 16.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} progress in 2022.

Prediction 5: But there are still wildcards

The huge wildcard is the permanency of work-from-home procedures or even hybrid versions of work. “That will lead to variations in household locational possibilities with far more households willing to obtain a home farther absent from job places and house price development hence will be stronger in small towns and exurbs in contrast to downtown spots,” suggests Yun.

Prediction 6: Spring will bring a lot more action

With the spring household purchasing year correct close to the corner, anticipate activity to heat up. “It’s very likely inventory and sales will choose up in excess of the future handful of months,” suggests Bachaud.

Opinion: These 2 numbers sum up why the housing market won’t get back to normal for a long time

Opinion: These 2 numbers sum up why the housing market won’t get back to normal for a long time

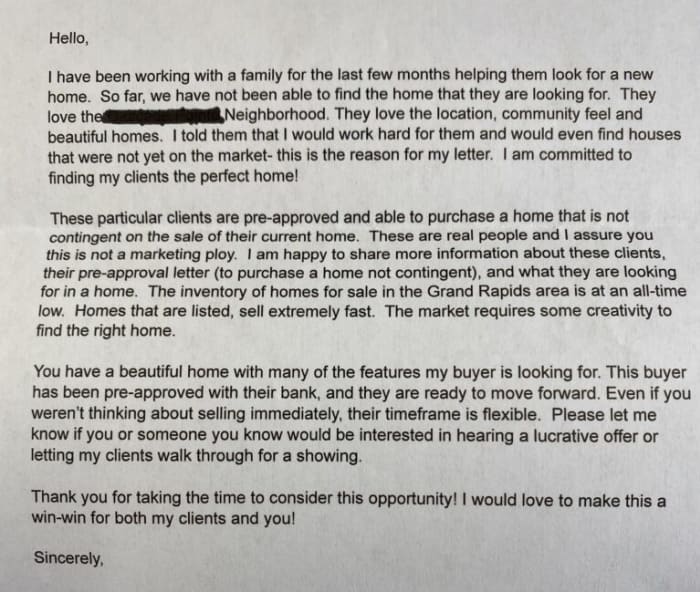
Final week I obtained a letter in the mail.

Like you, I’m stunned this still exists as a practice but determined moments phone for desperate actions:


Courtesy Ben Carlson

Now I would like to believe our property is just that beautiful, but I really don’t assume we’re the only ones who been given a letter from this Realtor. I’m positive there were numerous properties in numerous neighborhoods that received the exact same point.

I showed my spouse this letter and joked we should inquire for a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} quality in excess of the present benefit. It is a massive spherical number but it’s primarily useless.

Why?

We have to reside someplace!

Even if we were being capable to secure a much higher advertising selling price, it wouldn’t seriously aid us all that a great deal.

We presently have a 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} house loan amount locked in. We have a decent chunk of equity in the household. And as our desperate Real estate agent alluded in their letter, it would be almost unattainable to obtain a different property suitable now to buy.

The combination of rising dwelling charges, low mortgage loan rates that are locked in by current owners and low provide can make it unappealing to sell your property and seem for a further just one correct now.

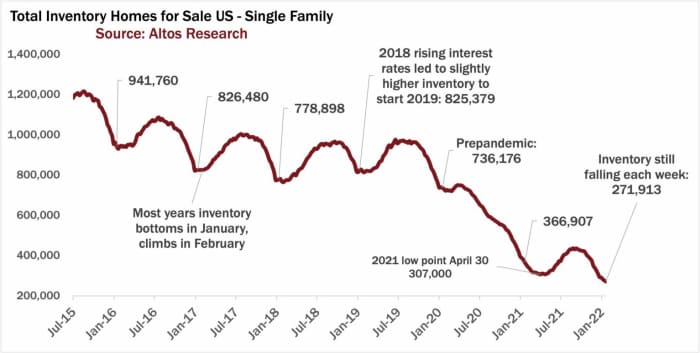
Mike Simonsen from Altos Research has a chart that demonstrates just how dire the housing provide condition is proper now:


Altos Research

That is 271,913 properties for sale in the full state proper now!

We’re in a housing marketplace in which we have document substantial demand and document small provide. If you want to know why rates are 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} greater than they have been a year back this is the simplest clarification.

But there’s extra likely on below.

Simonsen was lately on the Odd Tons podcast with Tracy Alloway and Joe Weisenthal where he explained how several owners are doubling up on their genuine-estate investments:

It’s like a doubling up. The house owner goes to purchase the subsequent dwelling, move up or shift down. And for the reason that mortgages are so low cost, it’s a actually very good time to keep the initial one particular as a rental unit. And so just about every 12 months I go to purchase a future just one and I continue to keep my to start with 1. And so which is one major phenomenon. And all of a sudden I’m a serious-estate trader. And at the very same time, institutional money’s been low cost. There is a ton of information about the major private-fairness funds getting up residences, but it is really the people today who are driving most of it. So in the past 10 years we have taken 8 million homes out of the resale cycle and moved them into the financial commitment rental component of the pool. And that’s, you know, 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all the solitary-relatives households.

I know anyone wants to complain about BlackRock buying all of the households in this state, but 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of residential rental models are owned by people today in the United States.

And this quantity is increasing for the reason that of an abundance of property fairness, the power of client harmony sheets and the prevailing minimal mortgage loan costs.

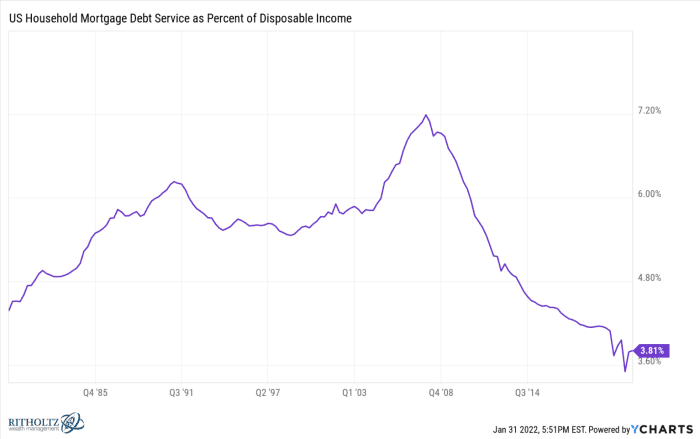
Small home loan costs have designed regular payments as cost-effective as they’ve ever been:

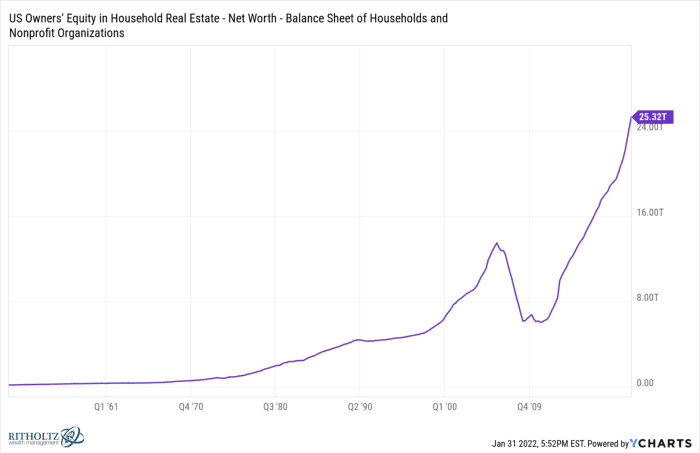
House fairness has skyrocketed from climbing housing rates:

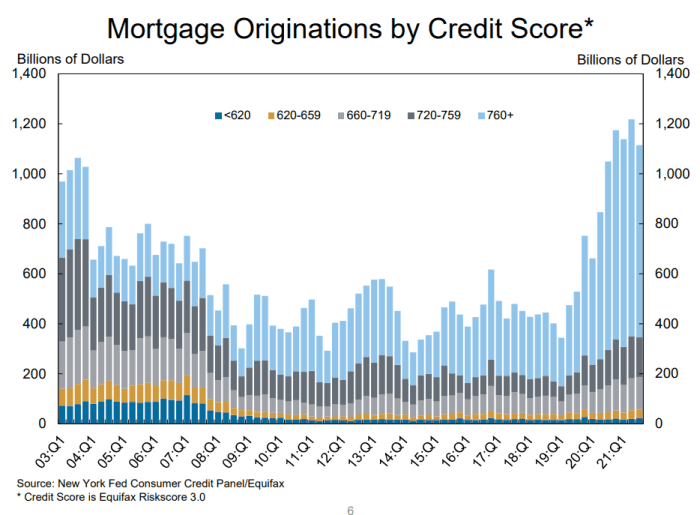
Plus search at the credit score-worthiness of homebuyers these days:

The individuals shopping for homes now have exceptional credit score scores. This was not the situation in the subprime boom of the early-to-mid aughts when the greater part of consumers came from persons with small credit score scores.

Just envision you’ve owned your property for 5 many years or additional. By now you’ve certainly refinanced at the very least two to three moments and very likely have a borrowing price of 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or fewer. You’re also sitting on some pleasant fairness as a result of a mixture of principal payments and growing selling prices.

It absolutely sure does not appear like housing selling prices are going to halt rising any time before long and rents are also on the rise, so it helps make feeling individuals are picking to hold on to their primary property even immediately after buying something new. They can basically demand ample lease to protect the home loan, insurance policy and taxes and however come out ahead by gradually paying out down a inexpensive mortgage loan and viewing their house go up in value.

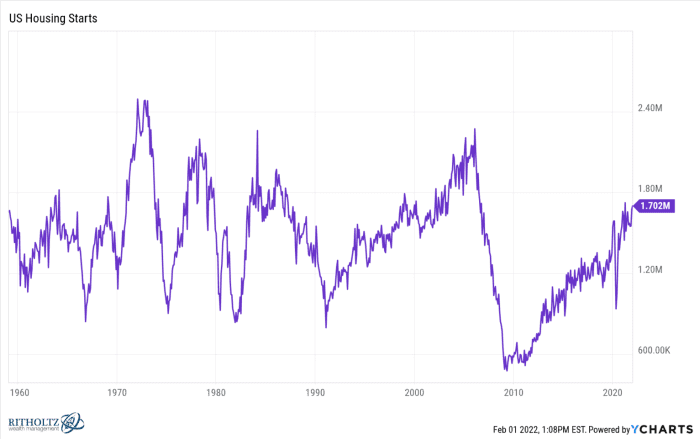
If I had to guess it’s heading to be a long time right up until we see anything at all approaching a “normal” housing market place. We simply just did not make adequate houses following the past housing crash to meet up with the need coming from millennials reaching their residence development yrs.

Points are last but not least buying up, but we have many years and many years of underbuilding to make up for. And it’s not like the provide-chain difficulties, federal government restrictions and COVID are generating it any simpler to make households any a lot quicker.

In the meantime, growing prices could sluggish issues a little bit if mortgage loan prices get higher enough. Rising housing costs and higher borrowing costs would at the pretty least make it not as appealing for individuals to keep onto their old houses and rent them out.

Nonetheless, rising costs would also very likely hold a lid on housing offer for the reason that so a lot of people have locked in minimal costs. Why provide to acquire a home for a larger cost with better borrowing prices?

Naturally, individuals will nevertheless go for new employment or family or a change of scenery or any of the other good reasons men and women determine to offer.

But it is probably likely to acquire a lengthy time till we see some kind of equilibrium amongst source and desire in the housing market.

Also from Ben Carlson: Really should I offer my shares so I can pay hard cash for a house?

Ben Carlson is the writer of the investing web site “A Prosperity of Frequent Feeling,” in which this was initial posted. It is reprinted with authorization. Follow him on Twitter @awealthofcs.

Gov. Whitmer Announces New Housing Development, Economic Investments for Three Detroit Neighborhoods

Gov. Whitmer Announces New Housing Development, Economic Investments for Three Detroit Neighborhoods

Gov. Whitmer Announces New Housing Development, Economic Investments for Three Detroit Neighborhoods

FOR IMMEDIATE RELEASE  

February 2, 2022                     

Contact: Kathleen Achtenberg, achtenbergk@michigan.org 


Gov. Whitmer Announces New Housing Development, Economic Investments for Three Detroit Neighborhoods 


LANSING, Mich. – Governor Gretchen Whitmer joined the Michigan Economic Development Corporation (MEDC) today to announce that the state will be supporting revitalization projects to bring new housing, economic growth and vibrancy to three neighborhoods in Detroit. The projects are expected to generate a total capital investment of $33 million. 


“These revitalization projects demonstrate our ongoing efforts to meet the housing needs of Michiganders and build a foundation for long-term economic opportunity in Michigan,” said Governor Whitmer. “Today’s investment is helping us put Michiganders first, creating good-paying jobs, and reinforcing Detroit neighborhoods as attractive places to live, work, and play by transforming underutilized properties into productive spaces.” 


 Gov. Whitmer Announces New Housing Development, Economic Investments for Three Detroit Neighborhoods


The Brush 8 Townhomes project will include the construction of a three-story multifamily building on two vacant sites in the Brush Park neighborhood of Detroit. When completed, the building will consist of eight for-sale residential townhomes and will feature a rooftop terrace, penthouse, garden, and alleyway improvements. The project also includes public infrastructure improvements including curbs, gutters and paving the public alleyway.  


The project is expected to generate a total capital investment of $4.8 million and will reactivate vacant property into a contextually appropriate building that will provide needed housing in the neighborhood.  


The City of Detroit Brownfield Redevelopment Authority has received MSF approval of $29,220 in state tax capture for the reimbursement of brownfield remediation activities. The city is supporting the project through the approval of the local tax capture, valued at $201,145. The development team is also seeking a Neighborhood Enterprise Zone tax abatement that would apply to future residents of the property. The city of Detroit is certified with MEDC’s Redevelopment Ready Communities program. 


“The Detroit Economic Growth Corporation is committed to supporting Detroit-based and minority-owned development firms. We’re excited to support City Growth Partners, and its Brush 8 Townhomes development,” said Detroit Economic Growth Corporation Executive Vice President of Economic Development & Investment Services Kenyetta Bridges. “The project will redevelop vacant and previously contaminated land to provide new, high-quality and design-forward residential opportunities for Detroit’s Brush Park neighborhood.” 


 1727 Merrick Redevelopment Project 


The 1727 Merrick Redevelopment Project will include the construction of three three-story townhome buildings in the Woodbridge neighborhood near downtown Detroit. When completed, the project will consist of 23 for-sale townhomes and public infrastructure improvements including sidewalks, a public pocket park, bike infrastructure, and onsite underground stormwater management system. 


The project is expected to generate a total capital investment of $7.1 million. In addition to bringing affordable housing options to the area, the project will transform unused land into a development that will drive economic activity and contribute to the vitality and density of the neighborhood. It will also move tax-reverted Detroit Land Bank property back to productive use that generates tax base for the community. 


The City of Detroit Brownfield Redevelopment Authority has received MSF approval of $81,739 in state tax capture for the reimbursement of brownfield remediation activities. Local support for the project includes approval of the local tax capture valued at $652,180 and a potential Neighborhood Enterprise Zone tax abatement that is anticipated to have a value of $2 million, helping to reduce property tax burdens for future homeowners. 


“The Detroit Economic Growth Corporation is proud to support the redevelopment of the vacant 1727 Merrick site in Detroit’s Woodbridge neighborhood,” Detroit Economic Growth Corporation Executive Vice President of Economic Development & Investment Services Kenyetta Bridges said. “The new construction will provide attainable homeownership opportunities for Detroit residents and families, which aligns with DEGC’s mission to provide inclusive economic opportunities within the communities we serve.” 


 3700 Trumbull Redevelopment Project


The 3700 Trumbull Redevelopment Project will include the construction of 65 new, for-sale market-rate townhomes on 11 parcels in the Woodbridge area of Detroit. The project will include public improvements such as storm water management features, installation of streetlights, sidewalks, landscaping, and creation of a community commons area connecting Scripps Park and Rose Dog Park that will be accessible to the public.  


The project is expected to generate a total capital investment of $20.9 million. It will also provide needed workforce housing options immediately adjacent to an employment center and serve as a catalyst for further economic growth in the surrounding commercial district. The project is expected to generate a total capital investment of $20.9 million. This project is another example of MEDC’s partnership with the Detroit Land Bank Authority in returning property owned by the Land Bank to productive use within the community.  


The City of Detroit Brownfield Redevelopment Authority has received MSF approval of $192,481 in state tax capture for the reimbursement of eligible activities. The city of Detroit is supporting the project through the approval of local tax capture, and it is anticipated that the city will approve a Neighborhood Enterprise Zone tax abatement valued at $6.4 million. 


“Reactivating blighted, vacant property is at the core of the Detroit Land Bank Authority’s mission and we work directly with residents and developers alike to make that happen,” said Detroit Land Bank Authority Interim Executive Director Tammy Daniels. “Projects like these aren’t just pretty to look at-they take vacant land and turn it into new, mixed-income housing opportunities for Detroiters and increase property values for neighbors.”  


The Detroit Land Bank Authority’s mission is to return the city’s blighted and vacant properties to productive use, utilizing a variety of sales programs to make homeownership and land purchases accessible to Detroiters. The Detroit Land Bank Authority works directly with individual buyers, as well as community partner organizations and developers for projects. 


“These three development projects reflect our continued focus on supporting innovative placemaking efforts in communities throughout the state that lays the foundation for long-term economic wins and greater opportunity for Michiganders,” said Quentin L. Messer, Jr., CEO of MEDC and President and Chair of the MSF Board. “By focusing on traditional neighborhoods and increasing much-needed housing options, we are working with our local partners in Detroit to establish vibrant, unique places that residents and visitors will enjoy.” 


About Michigan Economic Development Corporation (MEDC) 

The Michigan Economic Development Corporation is the state’s marketing arm and lead advocate for business development, job awareness and community development with the focus on growing Michigan’s economy. For more information on the MEDC and our initiatives, visit www.MichiganBusiness.org. For Pure Michigan® tourism information, your trip begins at www.michigan.org. Join the conversation on: Facebook, Instagram, LinkedIn, and Twitter. 


### 

What To Do With Your Rental Property Investments If The Housing Market Crashes

What To Do With Your Rental Property Investments If The Housing Market Crashes

The housing industry is regarded for its extensive-term security and consistency, but, like all financial commitment forms, it can fluctuate above time. On the brilliant side, home values have usually continued to increase all through the final 50 years, with average dwelling costs increasing over 16-fold throughout the identical time period, as shown by the Federal Reserve genuine estate sector investigation facts.

Serious estate tends to be a reputable investment decision, even even though no financial commitment is hazard-free of charge. But, what would materialize if the housing market drops even though you own rental home?

What Comes about to My Expense if the Market place Crashes?

All investments — regardless of whether in inventory, gold, mutual money or cryptocurrency — have hazard, and serious estate is no exception. However, Arrived Households, a system that permits retail traders to invest in shares of rental houses, strives to make these investment decision varieties as secure as possible by supplying a minimal maintain time period. 

This way, you never eliminate your cash to worry due to the fact house appreciation is statistically very likely to bounce back again when the market does, even if you can find some small-time period instability.

Of the myriad of investments attainable, single-household dwelling price ranges and rentals have surged around time, in accordance to related details. For that reason, experts recommend traders to look at very long-phrase true estate investments because they produce cash move and take pleasure in in thanks study course.

Need to I Offer or Keep?

Arrived Properties features some assistance for managing market fluctuations. 

As investments achieve the conclude of the hold period, Arrived evaluates the opportunity choices you have, figuring out what can make the most perception for your condition. Arrived Homes’ tips to buyers is to maintain qualities for as extensive as feasible, enabling the housing market place sufficient time to rebound the residence continues building hard cash stream in the interim.

Advertising through a sector slump hurts your investment, negatively influences other house values in the spot and eventually harms the sector further. To stay away from this, Arrived takes advantage of two essential tactics.

Good Use of Leverage

The 1st tactic will involve applying an volume of financial debt of 55{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on every house, which is safer than a increased property finance loan percentage. In addition, the firm’s estates have repayment conditions lengthier than seven a long time, making it possible for for flexibility in the expenditure maintain period of time.

In addition, Arrived properties’ loans are curiosity-only, meaning that the month-to-month payment is noticeably reduced than an amortized financial loan, but the funds move is bigger. The ordinary Arrived residence has a personal debt company coverage ratio of nearly 2. This implies that the estate’s running cash flow could reduce by 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, but it will nonetheless create more than enough profits to address the monthly fascination charges.

Income Reserves

When calculating how much income a residence demands to elevate from buyers, Arrived also incorporates a money reserve stability. In case of an extended vacancy, unexpected repairs or other troubles, the hard cash in the reserve balance can be utilised to protect the dividends and extra expenditures.

If the reserve depletes, Arrived can acquire out a business enterprise personal loan or elevate more money. Even in the worst-scenario marketplace situation, when the property’s worth would be down briefly, the firm’s objective is to distribute hard cash circulation created by the estate to buyers. So even if the market place is down significantly, investors nevertheless get their dividends.

When Should really I Commit in True Estate? 

The notion of any variety of investment decision is to purchase low and sell superior. Having said that, issues are a bit unique concerning actual estate because it really is smart to devote in it regardless of whether the industry is up or down.

Even though earlier efficiency is not a assure of potential achievement, with authentic estate, the probability for gain is sturdy since the trends indicate a significant, regular upward expansion. Also, mainly because true estate investments produce earnings from each dividends and appreciation, you continue to keep earning passive revenue irrespective of the property’s quick-term value.

Even if you never usually buy at the cheapest probable selling price, the long-time period gains and appreciation can be substantial. Likewise, investing when the industry is down can be a great shorter-expression approach due to the fact you can get homes at a wonderful offer and love even far more appreciation when the sector recovers.

Summary

Like other investments that guarantee rewards for trader possibility, the housing sector has its ups and downs even so, in the long operate, each hire advancement and all round home values have tended to enhance more than time.

Investing in serious estate shares as a result of Arrived makes it possible for you to benefit from some of this lengthy-time period get while averting brief-term difficulties such as vacancies or price declines. In addition, Arrived is organized for any contingency with intensive hold periods, income reserves, and the flexibility to prolong the investment decision.

Photo by todd kent on Unsplash

© 2022 Benzinga.com. Benzinga does not deliver financial investment tips. All rights reserved.

What to expect from the housing market now that the Fed has signaled rate hikes

What to expect from the housing market now that the Fed has signaled rate hikes

Program to obtain a household in 2022? The very good news is that ailments will not quickly get out of manage the way they did past year. The terrible news is that source stays tight and rates are nevertheless on an upswing — and the probability of greater mortgage prices looms on the horizon.

Actual estate pros say the true estate marketplace this year will not match the fever pitch it achieved in 2021, and the pace of property sales this 12 months will be significantly much less frenzied. “As we transfer via the 12 months, we will see slower revenue exercise,” explained Lawrence Yun, main economist at the Nationwide Affiliation of Realtors. “Intense several-provide times are over… persons can choose their time.”

“There’s no expectation that charges will drop, but our forecast suggests that cost appreciation will slow,” mentioned Doug Duncan, senior vice president and chief economist at Fannie Mae. Duncan predicted that even though prices will not repeat the meteoric 18 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase they sustained previous calendar year, they will nonetheless rise somewhere in the neighborhood of 7.5 per cent. “That’s not much of a breather, especially for the reason that fascination premiums will be mounting at the similar time,” he pointed out.

There’s no expectation that prices will slide, but our forecast suggests that price appreciation will sluggish.

Other gurus have a little bit reduced projection for rate appreciation, but no just one sees a reversal any time soon. “We haven’t witnessed the fundamentals transform to point out that rates are going to come down,” claimed Robert Frick, company economist for Navy Federal Credit score Union. “Prices are continue to going to go up this calendar year,” he mentioned, despite the fact that he also stated the fee of boost is possible to amazing immediately after very last year’s torrid double-digit jumps. 

As soaring need sent price ranges into the stratosphere last calendar year, would-be homebuyers generally found themselves in bidding wars, or were compelled to make a snap conclusion on the most important economical determination of their life. The success of a December study propose that home-hunters have tempered their optimism, or could possibly choose to remain on the sidelines for the around upcoming: The Fannie Mae Residence Purchase Sentiment Index discovered that while 76 p.c of all those surveyed reported the current is a very good time to market a house, just 26 p.c reported it is a superior time to get. By comparison, 52 percent of respondents experienced characterized the present-day market place as a fantastic time to invest in a property a calendar year before.

“There’s nonetheless a lack of houses for sale, so it is a seller’s current market, but the residences that are overpriced are tending not to transfer,” reported Ralph DiBugnara, CEO of Property Certified, an on the internet authentic estate details and lending useful resource.

“I believe for the property sellers, they need to understand the days of double-digit value appreciation are over,” Yun reported. If persons are mulling a sale, he additional, “They should do it based mostly on regular aspects somewhat than trying to speculate on large price gains.”

Residence sellers require to understand the times of double-digit rate appreciation are in excess of.

These changes are unfolding towards a backdrop of fascination charges rising as the Federal Reserve targets inflation in a major way. Earning it additional expensive to borrow tamps down demand in the combination and can assist rein in inflation, but what can be great for the economy on a macro level can be unpleasant for unique consumers, who will discover on their own paying out a lot more to provider their mortgage debt. 

As a end result, some experts have predicted that before the marketplace normally takes a breather this 12 months, there will be a sturdy 1st quarter as people test to lock in lessen house loan pricing. The charge for a conventional 30-year mortgage loan is currently hovering all over 3.5 percent. Many authentic estate professionals forecast that this will rise any where from a half to a entire proportion level by way of 2022. 

“It’s seriously dependent on what the Fed states and does,” Duncan said. The central bank’s contribution to greater mortgage charges is partially mainly because of a increased Federal Resources level, but extra importantly, it is a purpose of the Fed paring back its pandemic-period economic support. 

This support bundled getting billions of dollars in mortgage bonds every single month, purchases that will terminate by March. In a press convention final week, Fed Chair Jerome Powell explained officers expect to talk about before long how to shrink that part of the Fed’s portfolio. Marketplace members will be on the lookout to policymakers for extra guidance on regardless of whether the Fed elects to simply just not repurchase new house loan securities as the types on their balance sheet experienced, or actively seems to be to promote some of all those holdings — an acceleration of the sector exit that would be likely to have a additional abrupt impact on borrowing rates. 

“They could call for far more yield,” Duncan explained of the more bottom-line oriented home finance loan financial debt buyers that will continue being adhering to the Fed’s exit. “The Fed is a policy purchaser, not an financial consumer.” 

“From a property finance loan pricing perspective… I would say there is going to be a more robust effect from the exit of the bond purchases,” explained Steve Kaminski, head of residential lending at TD Financial institution. “We don’t know wherever prices will conclusion up, but we do have a clear indicator that the Fed intends to improve rates right here,” he stated.

As the Fed tempers its before prodigious appetite for property finance loan-linked personal debt, the current market will have to modify accordingly. “Their prepare is to exit the house loan-backed safety current market by March. I do assume the March-April time frame for that level boost to be a small extra obvious,” Kaminski reported. 

If there is a slowdown in homebuying exercise this yr, one particular silver lining for debtors is that the similar number of mortgage loan creditors will be hunting for business enterprise among the a lesser pool of consumers, Duncan mentioned. “A tiny little bit of a moderator on the charge rise will be the simple fact that house loan loan companies …. will compete and the profit spreads they’ll take will shrink,” he mentioned. 

But on equilibrium, professionals say the challenges remain acute for to start with-time customers. “The issue for first-time homebuyers is there are not more than enough residences for sale at competitive selling price factors. They’re seeing bidding wars on most houses. Very first-time homebuyers have to be eager to compromise,” DeBugnara explained, whether that indicates on square footage, spot or other characteristics.

Buyers — both of those first-timers as very well as people today in search of to downsize — will also continue to face levels of competition from institutional potential buyers, which have aggressively targeted the so-termed starter house market in purchase to hold individuals qualities and hire them out. And with house charges as effectively as rents increasing, it will become much more tricky for folks who want to possess and dwell in their personal households to split in to the marketplace.

“You have corporate entities shopping for homes to rent, which is further reducing the availability of homes… 17 percent of new residences are likely to be corporate-owned to hire,” Frick stated. “We’re obtaining shut to a stage where by 1 in 5 houses is essentially staying taken off the ownership marketplace for lease,” he stated.

We’re finding near to a position where a person in 5 residences is effectively becoming taken off the possession market place for lease.

“We’re going to see for confident the prices of rents expanding for the up coming handful of years. A great deal of these more substantial cash are scooping up solitary-relatives homes in bulk,” DiBugnara said. “I’m deciphering that as they believe there’s heading to be very large demand from customers for single-family members homes.”

When new residences are remaining designed, experts say it isn’t occurring speedy more than enough. Even ahead of the pandemic, new house development was failing to retain rate with demand from customers, and Covid-19 has saddled builders with a mix of shortages and climbing fees for the two supplies and labor. 

For a longer period time period, experts say the offer pipeline is improving. “We expect that in the new household house, begins will increase about 7 p.c,” Duncan stated. “The builders are accomplishing anything they can. If they can get the land, labor and lumber, they’ll build.” 

“I’m inspired that we’re heading to see numerous a lot more new homes designed in this year,” Frick stated. “Some of the source constraints are easing as significantly as materials go. The other matter which is essential is that builders are purchasing a whole lot of land,” he explained. But until the sector reverts to a point out that extra intently resembles historical norms, and right up until additional new stock is available at major scale, Frick warned that the desire of homeownership is fading for households on the margin. 

“We have to remember, for middle-income people, their most important way of accumulating prosperity is homeownership,” he reported. “Home rates are pushing homeownership absent from 1st-time and decrease-income homebuyers at an alarming rate.”