Single-relatives rental (SFR) houses go on to entice buyers as a scarcity of rental attributes on the sector proceeds to place tension on rates. In accordance to Corelogic, U.S. one-family hire progress rose by 14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months above calendar year, the 13th consecutive thirty day period of file-breaking annual gains.
As the SFR industry continues to heat up, extra investors are leaping into the blend and buying qualities in markets a major distance from their house base. This is because the total method of obtaining a single-loved ones rental house can now be finished from afar. But what is the most effective way for people to purchase SFR attributes remotely?
As a distant solitary-loved ones rental trader myself, I have acquired firsthand the greatest approaches to discover properties and markets ripe with prospect. I begun an SFR Fund together with 13 other traders, and we have acquired 28 attributes in Birmingham, Alabama, to day. All the properties have been bought sight unseen.
In this article are 5 tips for individuals searching to efficiently get SFR properties remotely.
Assemble Genuine Estate Marketplace Info
Men and women should entry and analyze real estate industry knowledge to decide a industry with fantastic cap rates and cash movement for SFR assets investments. Some good resources for authentic estate knowledge consist of Attom and Entera.
Another procedure for pinpointing a sound investment chance is to use the authentic estate investing 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule, which measures the cost of the expenditure property versus its generated gross money. For an financial commitment to go the 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rule, its month to month hire ought to equal to or get to no a lot less than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the order price tag. This is an indicator to the trader of no matter if they can at least break even on the house.
People must also contemplate searching at county information to assess and recognize where by institutional investors are obtaining. Though this is not a foolproof way of deciding a sound financial commitment market place, it does provide a great overview of the markets that greater buyers have discovered as potent for SFR residence expenditure. This info can be really telling and help advise your expense final decision.
Conduct Community Research
Prior to investing, folks must realize the rental legislation in every single condition and municipality. It is essential to have an understanding of your rights, secure your expenditure and run a successful enterprise. Look for metropolitan areas in which the charge of living and accomplishing business enterprise is reduced and the high quality of lifestyle is on the increase. Career growth in the spot is a critical element to take into consideration as nicely as reasonably priced property rates.
Discover A Neighborhood Rental Real Estate Agent
Serious estate is a nearby and specialised enterprise. Obtain a true estate agent who not only specializes in rental houses but who is also a area skilled and can support you locate the finest expenditure property. Regional brokers recognize the ins and outs of each and every neighborhood, similar properties, the average current market selling price for shopping for and offering and present place trends. They also typically know the agent on the other facet of the table which can be effective in having the deal completed. A nearby agent can assist information you by way of the assets acquiring journey and preserve you time and worry.
Leverage Home Know-how
The electricity of the online and modern-day technological innovation has endlessly modified the actual estate field. Actual estate investors can now research and view residences on the marketplace by means of on the net listing platforms these types of as Realtor.com and Zillow. These platforms can be very valuable throughout the lookup course of action to gauge pricing and see accessible stock, specially for distant investors. In addition, residence technology this sort of as 3-D tours and digital floor programs permit traders to watch and perform a virtual walk-by of a residence remotely.
Buyers can employ these tools to examine houses at their convenience and prior to building a buying conclusion. And when traders are prepared to acquire a residence, they can leverage electronic transaction products and services to assessment, indicator and notarize documents on the net.
Discover A Neighborhood Residence Administration Business
For remote traders, getting a area house administration organization that can aid assess your residence investment decision and take care of the property and the tenants’ wants on an ongoing foundation is critical. I are not able to emphasize this ample. I consider a fantastic residence administration organization can assist make or crack an SFR investment decision for remote buyers.
It has by no means been simpler to invest in SFR houses remotely than it is these days owing to the advancement of technological know-how and on line information. Folks that carry out comprehensive marketplace and neighborhood exploration, detect potent local associates and leverage house technologies and on the internet data will be improved positioned to spend in SFR attributes in several markets without at any time seeing the home in man or woman.
Forbes Company Council is the foremost development and networking corporation for business enterprise entrepreneurs and leaders. Do I qualify?
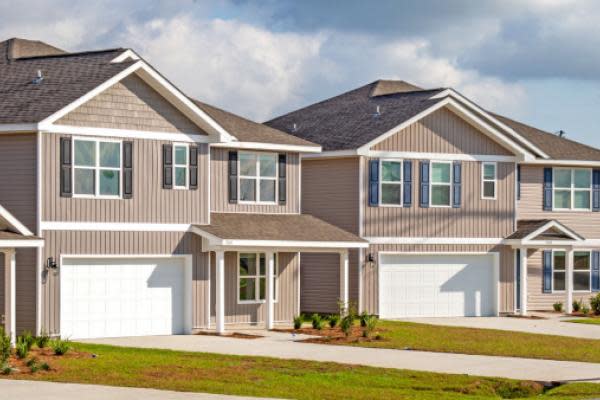
Genuine estate expense system Fundrise just lately obtained Sunset Village, a group of 233 detached, one-relatives rental properties in Panama Metropolis, Florida.
The obtain was created by a joint undertaking between two Fundrise-sponsored funds: the Flagship Genuine Estate Fund, which was backed by Goldman Sachs Team Inc. (NYSE: GS) past 12 months with a $300 million credit history facility, and the Progress eREIT VII.
The joint undertaking obtained the neighborhood for close to $110.2 million from a developer who completed development of the houses in February 2022. In accordance to Fundrise, approximately 52{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the houses have been occupied at the time of acquisition. The community is made up of 3-, four- and 5-bedroom properties.
A portfolio update posted on the Fundrise web page about the hottest acquisition states, “Our intent with this and other investments in solitary-loved ones rental house communities is to be a very long-phrase investor, building a scaled portfolio that generates dependable rental earnings, although at the identical time being positioned to capture what we consider will be outsized value appreciation many thanks to a confluence of demographic components driving need across the Sunbelt.”
According to information from Redfin, single-household properties in Panama Metropolis have improved in price by 53{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} calendar year-over-year.
The enterprise has invested intensely in the solitary-loved ones rental area, primarily in Sunbelt states such as Florida. The Flagship True Estate Fund now owns at the very least 650 one-family rentals and several multifamily houses in Florida.
As opposed to the Wall Street funds that have been getting massive portfolios of rental qualities through the state, the Flagship Serious Estate Fund was intended for retail investors — even permitting nonaccredited traders to participate with as very little as $10 through its Reg A choices.
While most publicly traded serious estate financial commitment trusts (REITs) have made adverse returns so much in 2022, the Flagship Serious Estate Fund is at present up 6.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} year-to-day (YTD) and posted constructive returns for the duration of the second quarter.
Invitation Properties Inc. (NYSE: INVH), the greatest operator of one-family members properties in the U.S., is at present down 20.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} YTD. An additional main player in the solitary-household rental area, American Houses 4 Rent (NYSE: AMH), is down 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Fundrise has made favourable returns for 22 consecutive quarters as of the stop of the second quarter of 2022.
Hunting for techniques to raise your returns? Look at out Benzinga’s coverage on Option True Estate Investments:
Or search present investment decision possibilities primarily based on your requirements with Benzinga’s Presenting Screener.
Longtime resident Joe Taylor likes the city of Lauderdale so much that he has spent the past six years becoming one of its biggest landlords.
During that time, Taylor has snapped up two duplexes and 25 single-family homes, which he has since converted to rental properties in this hamlet bordering Minneapolis and St. Paul.
Taylor’s spending spree has raised some alarms among the city’s 2,600 residents and city officials. In an already tight housing market, they fear the loss of so many homeownership opportunities for young families by Taylor and other potential investors will forever alter the character of their city.
“Lauderdale is a great place to live. Our housing is some of the most affordable in the metro,” said City Administrator Heather Butkowski. “Now, all of this naturally occurring affordable housing is being scooped up and rented at often unaffordable rents.”
Taylor defends his purchases, saying he’s investing in his own community, which, counting the 500 apartments in town, is already more than half renters.
“I’ve looked to acquire properties that needed repair and attention. That increases everyone’s value,” he said. “It’s helping to change the face of the community.”
A national trend
The dynamics in Lauderdale are playing out across the country, according to a 2022 report from the Joint Center for Housing Studies at Harvard University.
Investors bought 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of single-family homes sold in the first quarter of 2022, up from 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a year earlier and 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} averaged in 2017–2019, according to the report.
In the Twin Cities, neighborhoods from Minneapolis to suburbs such as Fridley and Hopkins are seeing dramatic increases in corporate ownership, according to a database developed by the Federal Reserve Bank of Minneapolis.
Business consultant Zak Knudson and his partner live near several of Taylor’s rental homes. He said it’s disheartening for owners who’ve invested time and energy into their homes to see some rental properties lacking general upkeep churn through tenants who never get established in the neighborhood.
“That’s the problem with rental properties. It’s a cash cow. There’s not a lot of incentive to improve the property,” said Craig Zbacnik, a retired contractor who moved to Lauderdale in 1984 and raised his family there. “Rather, it’s, ‘How can I increase my profit margins with as little investment as possible?’ It’s frustrating.”
Longtime Lauderdale resident Rev. Dave Greenlund said Taylor’s buying spree has left him with a sour taste in his mouth. Greenlund, the pastor at Peace Lutheran Church in St. Paul, said he recently lost out by $2,000 on a property that a different buyer snapped up and turned into a rental. Greenlund had hoped to downsize in town.
Now, Greenlund worries investors will continue to buy up affordable homes, finding it’s safer and more lucrative to park their wealth in quiet, tree-lined Twin Cities neighborhoods instead of tempestuous Wall Street.
“The problem is, Taylor says this is such a great neighborhood. But what is a neighborhood? It’s the relationships and the people,” Greenlund said. “I think he does like the neighborhood. He doesn’t see anything wrong with what he is doing.”
Lauderdale Mayor Mary Gaasch said she’s heard the concerns and is in talks with community partners about investing some of the county’s new housing and redevelopment levy dollars into helping prospective first-time homebuyers make successful offers in Lauderdale.
“We are deeply committed to keeping our naturally occurring affordable housing, ” she said.
Community investment
Taylor, who works full time managing his rental property business, is open about what he does.
Taylor bought a house in Lauderdale around 2000 and made the community his home. After the 2007 housing crash, he began investing heavily in single-family rentals, buying and fixing up homes on St. Paul’s East Side and in South St. Paul and Minneapolis.
About five years ago, Taylor said, he sold those properties and moved aggressively into the Lauderdale housing market. As a licensed real estate agent, he said, he has a keen understanding of the local market and inspects properties himself. There’s no question he has an advantage over first-time homebuyers, he said.
“I haven’t lost out too much. My offers are generous,” he said, noting that he is often bidding against other investors.
Despite the criticism, Taylor said he feels he has a good relationship with city leaders and neighbors and wants to maintain that. He doesn’t foresee a wave of new acquisitions.
“I don’t want residents to be uncomfortable with me,” he said. “I am not looking to buy up the whole town.”
Taylor said the community benefits from his local, hands-on management. He said he lives within two minutes of all his properties, responds to tenant concerns immediately and often does repairs himself.
“He has totally exceeded my expectations of what a landlord would be,” said renter Shauna Hendrie, 22, who relocated from New York to attend the University of Minnesota College of Veterinary Medicine. “I love being in such a nice neighborhood. I feel at home. It makes me want to stay here.”
Alexia Lythos and her sister rent a small, tidy one-story home from Taylor. A 24-year-old University of Minnesota student and U.S. Marine Corps veteran, Lythos said the house had been vacant and used for storage before Taylor refurbished it into a two-bed, two-bath rental complete with new appliances and a dark teal accent wall that the sisters have transformed into a gallery of their original artwork. They pay $1,600 a month in rent.
Lythos said neighbors stop her to compliment the renovations and even ask to take a peek inside.
“It’s a very safe and quiet suburban neighborhood,” she said. “I like it that way.”
Garron Houston originally rented a duplex from Taylor in St. Paul, and now rents one of Taylor’s homes in Lauderdale for $1,500 a month. Houston, 60, lives two doors down from Taylor’s own home and is able to walk to his job as a cashier at a local gas station. He calls his rented home a “blessing.”
“You can’t find a better guy around. He’s been great,” Houston said of Taylor.
Houston said he understands neighbors’ concerns about things changing — he, too, was once a homeowner.
“If I was able to own, I would buy in a heartbeat,” he said.
Doug Brien of Mynd and The Real Deal’s Hiten Samtani
“Do you have to live in Atlanta to invest in Coca-Cola?”
Doug Brien is making a point about how provincial single-family rental investing is, with people tending to buy within driving distance of where they live. That’s because the market, unlike those for stocks and bonds, is messy and opaque.
Things we take for granted in debt and equities — reliable data, smooth portfolio management — are hard to come by in single-family rentals. Brien speaks from experience: He first took on the sector as co-founder and CEO of Wall Street-backed Waypoint Homes, which he built into a $3 billion, 17,000-home behemoth that is now part of Invitation Homes.
His focus now is Mynd, a startup he founded in 2016 with his Waypoint partner Colin Weil to transform how such rentals are managed.
The startup operates close to 13,000 single-family rentals on behalf of both retail investors and institutions such as Invesco, which committed $5 billion to the firm last year for acquisitions. Mynd has also raised nearly $200 million in venture capital, including $57 million in September at a valuation north of $800 million.
Brien, who began real estate investing after a career as a Super Bowl-winning placekicker, sees property management as the fulcrum upon which single-family sits. He spoke with The Real Deal about how investor interest, cloud computing and more adventurous homebuilders are ushering in a creative era for the sector.
Companies like yours talk about “democratizing investment,” but often end up becoming a more efficient investment vehicle for the big guys.
We’re a management platform. We help others execute their investment strategies. And we started with retail investors. If you look at single-family, that really is the market. To your point, we did a deal with Invesco last summer. It’s funny, even some of our own team have raised the question: “We’re trying to democratize access to real estate for all. What are we doing with Invesco and other institutional partners?”
Part of what I had to explain to them is, if you think about Invesco or any of these other institutional investors, they’re deploying capital on behalf of endowments and pension funds. What does that mean? It’s teachers and firefighters and police, folks that work hard their whole lives and this is their savings that they’re going to get back in the form of a pension. And single-family rental is a really good asset class on a risk-adjusted basis. So yes, there’s professional investors in front of them, but really we are providing accessibility to an asset class that we know really well, that we believe there’s a 21st-century way to invest in, and we want to be the pioneers in making that happen.
Why is this happening now as opposed to 10 years ago?
It’s three things. One was the foreclosure crisis — that was the fire sale, the economic impetus to go take some risk. The other two components are the advent of cloud computing and mobile computing. Prior to those technologies, you had folks running around with yellow pads of paper, going out to a house, writing down some notes. As we started building our system, they had iPads and they could get whatever information they needed, not only about that house, but the portfolio, the area, and could input data into the system. All of a sudden the asset class became manageable.
You could argue that it wasn’t really a unified asset class before. Now I’ve heard numbers as high as $4 trillion.
$4.5 trillion is the number we show in our investment deck, which makes it the largest asset class in the world. What made it institutional was a 10- to 12-year track record of real operating data. And then the final straw was Covid. We want to see how an asset class behaves during an economic downturn, and single-family was a shining star. And so, in 2011 and 2012 the private equity firms were coming in, but 2020 and 2021 were the big years when the traditional commercial real estate investors came in. We were deploying capital for GI Partners, and I and one of their partners went up to Sacramento to pitch CalSTRS [California teachers’ pension fund]. And I think they literally thought about our talk for 10 years before they started buying anything. That’s just how that capital behaves.
They have been burned pretty badly on some more speculative investments, like Stuy Town.
Yes. So they are careful, but that type of an investor, they are now in. Invesco changed the name of their “multifamily” group to “residential” and their goal is to have as much single-family as they do multifamily.
We started with property management. This is an important point about single-family: In almost every asset class within real estate, property management is considered a commodity. It’s like, “We’ll find somebody to manage it, it doesn’t really make any difference” — except for single-family, where it’s actually property management PLUS logistics management. We used to always say, “We’re a property manager, plus we’re FedEx.” No single asset has enough revenue to support a full-time employee; you have to manage it portfolio style, which necessitates a lot more technology.
What does that look like in the field?
Unlike traditional real estate where people are assigned to a property, here they’re assigned to a portfolio, which is typically 200 to 400 properties and they can be spread out all over Atlanta. And so how they spend their day is something that needs to be well thought out so that they’re not just doing the things that need to be done, but also incorporating the idea of prioritization.
I just flew in from Houston, an absolutely massive market. One of the things we talked about was, “Should there be such a thing as a Houston vendor? We need to be breaking this down into submarkets.” These are the types of challenges that we have to grapple with in single-family, so what you end up with is a pretty big difference between a good manager who has the technology backbone to support the operation at a high-growth pace and at scale versus those that don’t.
A home is still the most emotional asset. When there are big investors involved, it can come with a lot of bad press often and that can lead to more regulation.
I’m sitting here in the San Francisco Bay Area, the epicenter of residential real estate regulation. I own properties myself here. Think of Maslow’s hierarchy: Shelter is one of the most basic necessities, and we take that responsibility seriously. Our job is to educate our investors on why taking care of their residents, making sure that they have a good home, is good business. They stay longer, they pay on time and they take care of the assets. [Small] investors can be very emotionally charged because in some cases it’s their life savings in that one rental house.
Having said that, yes, as you get big, there’s always going to be a target on your back. I do think a lot of the aggression aimed at institutional investors is somewhat misguided. I remember firsthand in 2009, 2010, 2011, the market stopped falling, but it was flat and you had nice neighborhoods that had turned into flat-out dangerous places to be, there were boarded-up homes everywhere, squatters living in them, dealing drugs out of them. And we at Waypoint would come in and were buying aggressively in some of these neighborhoods, but we were investing $30,000 into these homes. Making them nice, making them livable, making it so other families would move in and we would have the neighbors come up and want to give us hugs. And so you kind of have to take a little bit of a walk down memory lane to remind ourselves that institutional capital kind of saved the housing market to some extent.
Home prices year-over-year are up 20 percent. In some markets, 30 percent. Institutional ownership is still a drop in the bucket, but institutions do have access to cheap debt. Their ability to buy homes at scale is being fingered as one of the reasons for increasing unaffordability for average homeowners.
Some markets have more robust institutional investment than others. None of them are really more than 20 to 25 percent of the buying activity. But one thing to keep in mind is institutional investors are still economic buyers — there has to be some economic rationale. Can they typically get lower debt? Yes. But end-user homeowner buyers are not economic buyers. People will pay as much as they possibly can — it’s not an economically rational decision.
We have an affordability problem, both in terms of owning and in terms of renting. And I’d love to be a part of the conversation of how we build more supply. I live in the worst metro in the U.S. in terms of Nimbyism and you cannot build new supply. So guess what, you have an imbalance that’s driving both rents and prices. If we built enough homes there’d be plenty for renters and owners and pension funds via institutional buyers. Prices and rents could be set at reasonable levels that work for everybody.
Are you involved at all, directly or indirectly, in any lobbying related to the single-family rental sector?
Starwood Waypoint was one of the four companies that helped to form the National Rental Home Council, which Mynd is a member of. The NRHC is the tip of the spear for representing single-family rental. I’ve been involved with some discussions with the mayor of Oakland around ideas for affordable housing.
Read more from The REInterview
You recently called built-to-rent “a gateway drug” for large investors and have been actively courting landlords and developers in that space.
The reason that I jokingly refer to it as the gateway drug is because I’ve been in so many of these conversations over the last dozen-plus years, where most institutional investors are accustomed to large multifamily. So you explain to them that we’re going to invest in distributed single-family homes, and they’re like, “Hold on a second. I own an apartment building, 300 units, I got six people. They’re all there.” Their heads kind of explode around the idea of how do I do all these houses?
And so what you have with built-to-rent, purpose-built communities is you might have 200 to 400 houses. It’s the same asset. But it’s in one area. You can have that community front office with some amenities and a local team that does everything. So [investors] are doing single-family rental, but in a way that’s more familiar to them.
Our hypothesis is that you’re getting a lot of the big multifamily investors coming into single-family via built-to-rent communities. They’re going to get good returns. And then as those product types start to get more expensive and you get cap rate compression, they’re going to want to branch out and also own houses, which will require portfolio-style management, which is what we specialize in.
It’s almost like a geographic security blanket. I know Lennar and other big builders have dived into built-to-rent. You wouldn’t be co-developers with them – instead, you’d be at-scale property managers?
We’d charge a traditional property management fee, leasing fee, renewal fee. And then when we’re buying homes for investors, we get a brokerage-like commission.
On the retail side, most of what we sell is built-to-rent. Lennar is a big public company. They were the first builder to get it. We have seen a big opportunity with smaller regional builders who don’t have the kind of balance sheet that a Lennar or a Pulte has. And so we partner with them and we can take down parts of their communities and pay them as they go and make their business work better. So we’re not necessarily buying the entire community, but maybe we buy 10 or 15 homes out of 40. And for us, those are great individual homes to put into the hands of individual retail investors who want to get access to single-family.
Would you go, say, to some small to midscale developer that has a plot outside Scarsdale and wants to do a built-to-rent?
In fact, we have a 40-home community that we actually bought on our balance sheet and are reselling to another investor and we’re going to manage for them. So there’s different ways we can play. We can take down deals ourselves, we can resell them. But our whole model is you get the property management right — we didn’t do anything but property-manage and build all the associated technology for four years.
If you think about all the services that one needs to successfully deploy capital — brokerage, financing, insurance — they’re all transactional. The enduring relationship is the property manager. It’s also where the really valuable data lies. And so if you can earn trust in that enduring relationship, collect all the relevant data, it puts you in a pole position to be there and just say, “Okay, would you like to now thoughtfully grow your portfolio? We’re in 25 different markets. We can help you buy here. We can help you finance. We can help you make it really easy and get you institutional-type pricing.”
Property management is also probably the stickiest factor, right? If a home is well managed, it’s probably the reason to stay. Conversely, my home could be in a great location, but if I’m getting shitty maintenance, I am moving.
Taking it even one step further: The way that the industry works, which is not the way it should work, is you go to a broker because you’re trying to buy a house. You want to buy an investment property and they give you a pro-forma. And it’s like, “Okay, how do you know that repairs and maintenance is going to run me this much?”
The broker’s trying to sell the property. So they’re basically fabricating numbers. The beauty of having all this data is we can use actual operating data from our own business. We can have feedback loops and tell investors, “Look, if you have a 1980 home in this market of this square footage, this is the range at which it’s going to perform.”
The way that you invest in real estate is to understand your risk and reward. And you study various markets and you have a diversified portfolio that blends to those return criteria. The tools we are building are enabling Main Street and institutional investors to more thoughtfully deploy capital.
The stat that I get stuck on is 180 million Americans own stock and 10 million own [investment] real estate. Why is it that only 10 million own fee simple real estate? The reason is because it’s hard.
Mynd has raised close to $200 million in venture capital, with the latest disclosed valuation north of $800 million. What’s the next step in your evolution?
Geographic expansion is a necessity — becoming the platform that can be in all the most relevant single-family markets and allow investors to use one platform to deploy, finance and manage in 40 to 50 markets, that is a big competitive differentiator. We’re also looking at some financing products that can reinvent what it means to finance a property for retail investors. We call it one-click investing, where Mynd is basically the lender, and we’re not even looking at the individual — we’re just looking at the asset.
We control the dollars. And so we pay ourselves the financing costs first and we can set up an institutional-caliber facility that individuals can leverage. Helping retail investors more efficiently finance, including power buying, going out onto the market as an all-cash buyer to be more competitive, by virtue of the fact that we’re also an institutional investor. And then also looking at some other interesting synergies that we call, “sell with Mynd” or “sell to Mynd.” So think iBuyer in the investment world.
It’s possible for us to basically have an all-cash offer for every single retail home in our portfolio. And if you think about one of the biggest risks or challenges for most retail investors, it’s liquidity. So imagine if in 24 hours you could have all cash, you’re out. That’s a product that we’re working on.
Would the lending be from your own balance sheet?
Partnering with banks, but basically leveraging our balance sheet to secure a warehouse line. And then what we ultimately did with that warehouse line, we could securitize it, take more of an institutional approach to financing that individual investors could never do and offer that to them.
And then just to finish out “the sell with Mynd.” We have 4,500 individual investors, we have 10 institutional investors. So if you want to sell, we can take you out quickly, but we can also sell off-market through our platform. And because we have all the data on your property, we can very quickly list your property to folks that are going to want to buy it as an investment property, meaning you don’t have to go clean it up, you don’t have to vacate your property. And we can do that transaction for less than you would incur on the open market.
I saw that you were also buying through iBuyers. Are you partnered with any specific player?
We’re iBuyer-agnostic. There’s probably eight to 10 different iBuyer-alternatives, MLS bulk portfolios, as well as built-to-rent. We have teams out scouring the market, looking for those deals.
We are in an amazing marketplace with tons of rental demand, tons of investor demand. These are the things you like to see in your business. The flip side of that coin is it’s hard to buy — it’s competitive. And since we do it all ourselves, we don’t just go buy houses. We buy houses that we have to manage and, and, you know, turn into returns for Invesco and pension funds and retail investors.
Ballpark, what kind of returns are they looking for in this game?
Specific buy boxes is not something that I can talk about, but institutional capital is now buying in the mid-4 percent cap rate, depending on the market. It’s meaningfully compressed.
Colin and I just came out with a new book called “The Big Long.” I remember back in 2008, 2009, ’10, ’11, we would be looking at eight caps and be like, “Yeah, we’re gonna pass.” Now we’re trying to buy 4.5 caps! So the world has changed.
What are you trying to get at in the book?
It’s a story about our journey from Waypoint to Mynd and where we see proptech going. A lot of things we talk about are very central to our thesis, using smart home technology to create a better experience for residents. And then, eventually owning [the ecosystem]. I mean, Amazon is an extreme example, but if you think of their business, it started with books and now they’re literally being FedEx.
They own the rails, the undersea cables, God knows what else.
Our hypothesis is that once you earn the trust of the investor and the resident, there’s so many different services around housing that we are now uniquely positioned to offer. We kind of own the payment gateway. So residents pay us rent, we pay investors and it just puts us in a very good place to be able to add value throughout that value chain. And it started with buying houses one at a time back in 2009.
We’ve just always seen this as an emerging industry — why wouldn’t it be? Look at other industries, the institutionalization of coffee shops with Howard Schultz and Starbucks, or 7-Eleven with the corner grocery store. Once these asset classes go institutional, they just tend to never go back. And there are these amazing opportunities with modern technology to create highly differentiated game-changing experiences. The book just kind of takes you through that whole thought process and evolution.
The Big Long. If you made a movie about that, it’s just not as dramatic as The Big Short.
Read the book and then tell me. There are some hilarious stories. Think of what we were doing — it had never been done before. These were crazy times. We were buying houses and there were squatters in them. We were trying to buy houses in foreclosure on the courthouse steps and people were getting indicted and going to jail. This was the Wild, Wild West that we had to navigate.
This interview has been condensed and edited for clarity.
(Write to Hiten at [email protected] or @hitsamty on Twitter. To check out more of The Real Estate Interview, a series of in-depth conversations with real estate leaders and newsmakers hosted by Hiten Samtani, click here.)
The single-loved ones rental current market is booming, with additional and a lot more traders leaping into the sector. The need for solitary-family rental homes is exploding as consumers seek larger sized houses with extra out of doors place, and charges are reaching file highs. Rents for these spaces elevated 12.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yr-above-calendar year in January, compared to an boost of 3.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January 2021, in accordance to a press release by CoreLogic.
As CEO of PlanOmatic, I provide one-relatives rental traders and homeowners with images, 3-D and ground strategies with speed and at scale. Nevertheless, I not long ago made a decision to set my marketplace awareness to perform and individually make investments in one-spouse and children rental qualities. I launched a one-loved ones rental fund along with 13 other investors, and we have obtained 24 qualities to date. As a comparatively new single-family members rental investor, I’ve realized a lot of vital classes along the way. Below are 5 strategies I inspire persons to maintain in thoughts if they’re new to one-spouse and children rental investing.
Identify your expenditure requirements.
There are numerous components to contemplate prior to investing in a solitary-spouse and children rental residence. 1st, it’s essential to decide your financial investment requirements. Are you hunting for cash move or appreciation? Upcoming, decide how substantially funds you have to commit. And and finally, recognize the marketplaces you are familiar with and the types you want to spend in. Some markets will give better appreciation, and some will offer you far better income movement and cap premiums. Whatsoever you pick, emphasis is vital. To be profitable at the beginning of your investing journey, I suggest concentrating on a distinct products form and a unique market.
Evaluate your funds.
You will have to have an knowledge of your fiscal problem before investing. It is critical to very first test your credit score score and then ascertain if you qualify for a personal loan. Obtain outhow considerably your lender is equipped to leverage for you. My rule of thumb is to glimpse at loans with a seven-year amortization agenda for the reason that, in my expertise, that timeframe will get you by means of a usual genuine estate or economic cycle.
One more thing to consider when investing in a one-loved ones rental assets is no matter whether the residence already has leases and/or a tenant in spot. Your financial institution could possibly be more probably to approve you for a personal loan if there is already a tenant in place, as there is significantly less hazard.
Figure out markets and attributes ripe with potential.
Recall: area, location, site. No matter where you are on the lookout to invest, the area of the home is significant. Homes in fantastic locations commonly retain their rental costs and usually worth far superior than those in outlier spots. In addition, a major element of your investment decision is residence taxes, so it’s crucial to glance at the value of assets taxes prior to acquisition.
Once you have identified a strong solitary-loved ones rental expenditure opportunity, beware of what I connect with “analysis paralysis.” You are not buying this property to dwell in it, so you do not need to overanalyze each individual aspect of the house as if you would be. When you are investing in these homes, it’s important to glance at a couple of easy components. What’s the appreciation likely, what does the income movement glimpse like and what’s the likely for a renovation?
You certainly want to be informed and to do your evaluation right before the acquisition, but “analysis paralysis” can finally sluggish you down. This is a market that is moving immediately, so you have to be prepared to get. Try out not to get hung up on a couple of percentage details as you response the questions earlier mentioned, particularly if the expense is a more time-phrase perform.
Do your because of diligence.
In advance of buying a assets, buyers must embark on a comprehensive owing diligence procedure. For occasion, I usually advise checking the property’s roof affliction, sewer scope and foundation. Examining these a few issues can assist make certain you are not missing something large when it will come to estimating servicing expenses. A single large expense like that can genuinely devastate a complete year’s investment decision.
Additionally, when you are underneath agreement to acquire a rental assets, the title will only go so significantly as to check for any owed taxes. Verify to see if there are any municipality leans and taxes on the home that won’t demonstrate up in the title. You could quite perfectly be trapped with an unpaid tax monthly bill if you do not conduct extensive residence because of diligence.
I also advise examining regionally and regionally to study if the residence has a record of surprising pure disasters in the spot, this kind of as floods, hurricanes, fires and/or tornados. If so, you can make confident you are insured to stay clear of disastrous charges owing to these sorts of activities.
Verify h2o charges, electrical energy expenses and rent rolls as properly, and make certain the rent is reconciled with the lender and actually was deposited.
Past, look to see if nearly anything is envisioned to be designed all around the property, as a likely growth up coming doorway could make a large amount of noise, and a tall constructing, for illustration, could block your home sights.
Determine your residence administration strategy.
When you have acquired a residence, you can think about employing a trustworthy and seasoned assets management corporation. If this is the route you consider, identify a home supervisor that can onboard promptly, has the identical values as you in regard to how you want to take care of your tenants and has a system in put.
By operating with a dependable residence administration partner, the investing method can be a whole lot easier and let you to invest from anyplace across the place.
The information provided right here is not expenditure, tax, or monetary information. You ought to seek advice from with a accredited experienced for information relating to your particular situation.
One-household property product sales in Westchester for the initial quarter of 2022 ended up down 20.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the 1st quarter of 2021, while Putnam and Dutchess posted declines of 33{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 21.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, respectively, in accordance to a new report from serious estate brokerage firm Houlihan Lawrence.
Forcing the amount of home sales down was a absence of stock, with the variety of properties readily available in Westchester dropping 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, when Putnam noticed a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop and inventory was down 38{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Dutchess.
The lack resulted in a usual supply and desire reaction with median sale charges up 2.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Westchester, 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Putnam and 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Dutchess, according to the report.
Houlihan Lawrence identified that in Larchmont, 29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the purchasers in the initial quarter of 2022 arrived from New York Metropolis, while back in the initial quarter of 2020, the section of buyers that had appear up from the metropolis arrived at 50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Dutchess County also noticed a sharp drop in the number of consumers coming from New York Town as when compared with the 1st quarter two yrs ago, in 2020. Back then, 29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} came from New York Metropolis even though in the initially quarter of 2022 only 8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} had been from there.
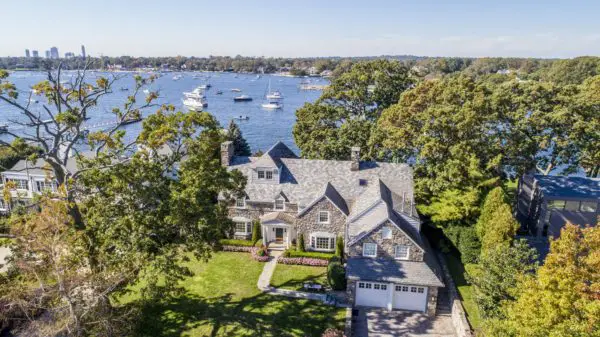
One of Houlihan’s luxurious houses at 1251 Flager Travel, Mamaroneck.
“Today’s offer and desire ratio reveal that the market place will continue to be a potent vendor sector for the foreseeable potential,” said Liz Nunan, president and CEO of Houlihan Lawrence. “If a house is lingering on the market below these ailments, it is quite probably (for the reason that of) the price tag.”
Provide and demand from customers ongoing to assist describe what happened in the luxury finish of the marketplace in Westchester, Putnam and Dutchess counties in New York and in Greenwich, Darien and New Canaan in Connecticut.
In Westchester, there was a 17.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} improve in the range of luxurious houses bought, from 84 in the initially quarter of 2021 to 99 in the initially quarter of 2022. The median selling price went up 3.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from $257,138,997 to $320,633,847. The number of luxurious product sales Putnam and Dutchess combined was unchanged at 41 in each the to start with quarters of 2021 and 2022, with the median sale cost dropping 21.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from $1,625,000 a calendar year in the past to $1,275,000 in the initial quarter of 2022.
In Greenwich, the median sale value in the luxury marketplace went up 6.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, from $3,975,000 a calendar year back to $4,225,000 in the initial quarter of 2022, with 60 homes marketed compared with 70 in the very first quarter final yr, a 14.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop.
Darien observed a 29.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} bounce in the median sale rate for luxury homes from $2,662,000 to $3,459,000 with 19 models bought, a 46.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} enhance from the 13 product sales in the initial quarter of 2021.
In New Canaan, the median sale price for luxury residences rose only 1.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from $2,260,000 in the 1st quarter of 2021 to $2,650,000 in the initially quarter of this calendar year. The selection of models offered dropped 33.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 30 in Q1 of 2021 to 20 in Q1 of 2022.
“The majority of Westchester’s initial quarter luxury income shut beneath the asking cost, demonstrating that price tag sensitivity is a reality,” mentioned Anthony P. Cutugno Sr., vice president and director of private brokerage at Houlihan Lawrence. “If a listing is languishing on the marketplace, it is frequently a signal that pricing ought to be revisited to capitalize on this strong, but not constantly euphoric, current market. On the lookout forward, the absence of inventory will not accurate itself soon. One particular of numerous things contributing to the provide deficit is sellers’ hesitancy to listing their property for sale. They are involved about securing a new home that meets their requirements in this ecosystem, perpetuating the shrinking provide of residences on the market place.”