Want to Invest in the Real Estate Market With Less Stress? Try This REIT.

Want to Invest in the Real Estate Market With Less Stress? Try This REIT.

Investing in rental authentic estate can be a financially rewarding venture, but it’s not necessarily the most available or passive way to produce profits. To commence, you will need a substantial sum of money for a down payment on a house. Then you have to take care of the house, accomplishing points like advertising and marketing the rental, screening tenants, coordinating repairs, communicating with tenants, keeping the assets, and dealing with evictions if they take place.

I have owned rentals and the past and am in no way discouraging traders from pursuing this avenue. Even so, if you don’t have tens of hundreds of pounds to commit in a rental home proper now or simply want publicity to the time-examined rental authentic estate sector with out the strain, here’s why you should take into account investing in Invitation Houses (NYSE: INVH).

The leading one-relatives rental REIT

Authentic estate investment trusts (REITs) were invented in the 1960s to support make the real estate sector much more accessible for everyday traders. These one of a kind shares are required to earn the bulk of their cash flow from real estate homes like rental homes or from real estate equities like home loans. They are also essential to shell out at least 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their taxable revenue to shareholders in the variety of dividends, building them a fantastic passive revenue expense devoid of the worry and trouble of owning or running authentic estate personally.

With fascination or possession in in excess of 80,000 properties, Invitation Houses is the greatest solitary-family members rental REIT in the industry today. The enterprise was started by option asset administration organization Blackstone in the aftermath of the Terrific Economic downturn when solitary-loved ones residences could be obtained cheap. The firm purchased tens of countless numbers of residences, renovating them and turning them into single-family members rental homes. Invitation Homes is no longer a element of Blackstone, but the REIT has made a title for by itself as a major company of single-relatives rental households considering the fact that its initial general public offering in 2017.

The firm’s portfolio of rentals is distribute throughout 16 markets largely in the southern section of the country, usually referred to as the Sunlight Belt. This includes key metro markets in Florida like Jacksonville, Tampa, and Orlando, as effectively as Houston and Dallas in Texas. But it also has a little but expanding range of properties in the Midwest. The markets Invitation Properties operates are some of the speediest growing in the state.

Very low housing provide and large need created best disorders for history rental advancement. About the earlier 12 months, Invitation Home’s rental level for new and renewing leases elevated by 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} compared to the 12 months prior. This may not feel like a massive bounce, but this fee of advancement is quite unheard of in the rental marketplace, significantly in these types of a brief period of time of time. Occupancy for its portfolio at the close of the yr was just more than 97{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, one more indication demand continues to be sturdy for its rental properties.

Why Invitation Properties is a fantastic buy right now

You can find a growing concern that the slowing financial system and weakening demand for rental housing will crush operators like Invitation Houses. Even so, I never assume it’s as major of a concern as lots of believe. To get started, Invitation Homes rents to primarily center-class and affluent earners who get paid more than 5 moments their lease. That signifies its tenants have sufficient coverage for their rental payments even in an inflationary ecosystem.

It also added benefits from owning a deeply diversified portfolio of rentals, which assists offset losses in the celebration sure markets knowledge a deeper slowdown or much more delinquencies than others. Additionally, its massive community of support companies (like contractors, plumbers, or handymen) allows it streamline the management course of action and limit charges for the business.

In spite of the modern slowdown in rental development, its whole-calendar year 2022 earnings were nonetheless unbelievably solid. Its net working money (NOI) grew by 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the year right before and its money from functions (FFO) — a important metric that is effective like earnings for each share for REITs — rose by nearly 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Invitation Homes year-over-year growth from 2021 to 2022 in a chart.

Info supply: Invitation Home’s Q4 2022 and total-12 months earnings. Chart by author.

Anticipating some effect from the slowing genuine estate marketplace, the business pre-paid its nearest debt obligation with no penalty. Now it has no major financial debt maturities right up until 2026, supplying it a good deal of flexibility to use its $1.2 billion to maintain dividends, shell out expenditures, and keep on escalating. If the authentic estate industry does see frustrated pricing you can find a good likelihood Invitation Houses will use it as a acquiring opportunity. It has expertise shopping for in down markets, which is a huge cause for its achievement nowadays.

Invitation Homes is down approximately 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from its recent significant and trading at about 19 occasions its FFO. This is somewhat large, but still very interesting pricing offered the high quality of the firm’s portfolio, financial place, and extensive-time period development options. Furthermore, its dividend yield of approximately 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} (near to double the ordinary of the S&P 500) makes it a trustworthy and beautiful money stream.

10 shares we like much better than Invitation Residences
When our award-winning analyst crew has a stock idea, it can pay out to listen. Following all, the newsletter they have run for in excess of a ten years, Motley Fool Stock Advisor, has tripled the market.*

They just exposed what they believe are the ten very best stocks for traders to buy suitable now… and Invitation Houses wasn’t one of them! That is appropriate — they think these 10 stocks are even far better purchases.

See the 10 stocks

*Inventory Advisor returns as of February 8, 2023

Liz Brumer-Smith has positions in Blackstone and Invitation Houses. The Motley Fool has positions in and suggests Blackstone and Invitation Residences. The Motley Fool has a disclosure plan.

The views and views expressed herein are the views and views of the creator and do not always mirror people of Nasdaq, Inc.

Want to Invest in the Housing Market? Try This REIT.

Want to Invest in the Housing Market? Try This REIT.

Owning a rental residence isn’t as quick as it could audio, even if you employ the service of a property supervisor. But which is not the only way to commit in the housing market.

One more choice to contemplate is obtaining shares in AMH (AMH 1.35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), formerly known as American Homes 4 Lease. This real estate expenditure trust (REIT) owns a huge and diversified portfolio of solitary-spouse and children residences. It’s not specifically like proudly owning your own rental property, but it gets you quite a few of the most critical gains whilst preserving you stress and danger. Here are some key info to take into account.

1. Diversification matters

Most little serious estate traders will only personal a several qualities, possibly only a single, in addition to their most important home. That indicates a vacancy at a one home can have a large affect on your income movement. Similarly, an surprising value at a property (like changing a broken furnace) will be a weighty load. AMH owns extra than 59,000 solitary-family members houses. No single house will have a discernible affect on its in general results or the revenue you acquire from the REIT’s dividends.

A sign in front of a home that says house for rent.

Image source: Getty Visuals.

On prime of that, with only a handful of belongings, most tiny serious estate traders are uncovered to just just one or two markets. AMH’s portfolio is spread across the Southeast, Midwest, Southwest, and Mountain West locations of the United States. It would be almost impossible for most scaled-down landlords to realize that type of diversification.

2. Responsible dividend

To be honest, AMH’s 2.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} dividend yield is just not specifically massive. That mentioned, it is notably larger than what you would get from an S&P 500 index exchange-traded fund (ETF), at this time all-around 1.65{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. But the true vital is that the dividend has been held constant or increased each and every 12 months due to the fact AMH commenced paying out dividends in 2014, the REIT’s 1st complete yr of daily life as a public company. In the meantime, in the third quarter of 2022, AMH’s altered funds from operations (FFO) was $.33 per share as opposed to a dividend of $.18 for each share. That prospects to an adjusted FFO payout ratio of all over 55{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, which is very conservative. 

3. Hire and appreciation

When it comes to REITs, dividends are a essential issue. On that score, lease advancement more than the previous pair of yrs has authorized AMH to maximize its quarterly payment to $.18 for each share for every quarter from $.05 for each share per quarter in 2020. In other words, buyers are benefiting specifically from the business’ powerful operating outcomes. 

Even so, that’s not the only story here. AMH began developing its portfolio in the aftermath of the Great Economic downturn, which was driven by a housing downturn. It was opportunistically purchasing residences on the inexpensive. The inventory has doubled due to the fact its IPO, reflecting the reality that housing price ranges have gone up because that place. Massive gains like that aren’t likely to come about again, but if home price ranges raise in excess of time, the improve is probable to be mirrored in a bigger stock cost just the same. In other phrases, if you are observing housing costs go up, AMH is an prospect to get in on.

Virtually like carrying out it you

AMH’s inventory rate has pulled back approximately 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} since the begin of 2022 as desire prices have headed better. So there is probable to be far more price volatility here than if you bought a rental assets on your own. And however, that fall has pushed the generate towards traditionally high stages. And you get the benefit of specialist management and diversification. AMH isn’t really an specific substitute for obtaining a rental residence, but if you are conservative, it could be worth a deep dive when you consider the complications and hazards of getting a landlord.

Alpine Income Property Trust: An Interesting Microcap Retail REIT (NYSE:PINE)

Alpine Income Property Trust: An Interesting Microcap Retail REIT (NYSE:PINE)

Alpine Income Property Trust: An Interesting Microcap Retail REIT (NYSE:PINE)

Lemon_tm/iStock via Getty Images

Written by Nick Ackerman. This article was originally published to members of Cash Builder Opportunities on August 11th, 2022.

Alpine Income Property Trust, Inc. (NYSE:PINE) immediately caught my attention when it appeared on our latest monthly dividend screening piece. Several interesting names show up with that screening article, and it gets some of the most readership. So, a good reason why I continue to produce that monthly piece.

For PINE, more specifically, the higher yield of nearly 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} at this time plus a growth trend initially stood out. After looking into it a bit more, some red flags should be addressed. All in all, though, it is an interesting name that is worth being put on the watchlist, or even perhaps a small initial position.

They describe themselves as:

“a publicly traded real estate investment trust that acquires, owns and operates a portfolio of high-quality net leased properties. The Company’s portfolio consists of 143 properties located in 35 states.”

They were considered a diversified real estate investment trust (“REIT”), but after selling off their Wells Fargo offices earlier this year, they have become a more pure-play retail REIT.

A Look At The Tenants And Size

There are risks to all investing. Some investments have additional risks that should be considered. I believe that PINE is one of those.

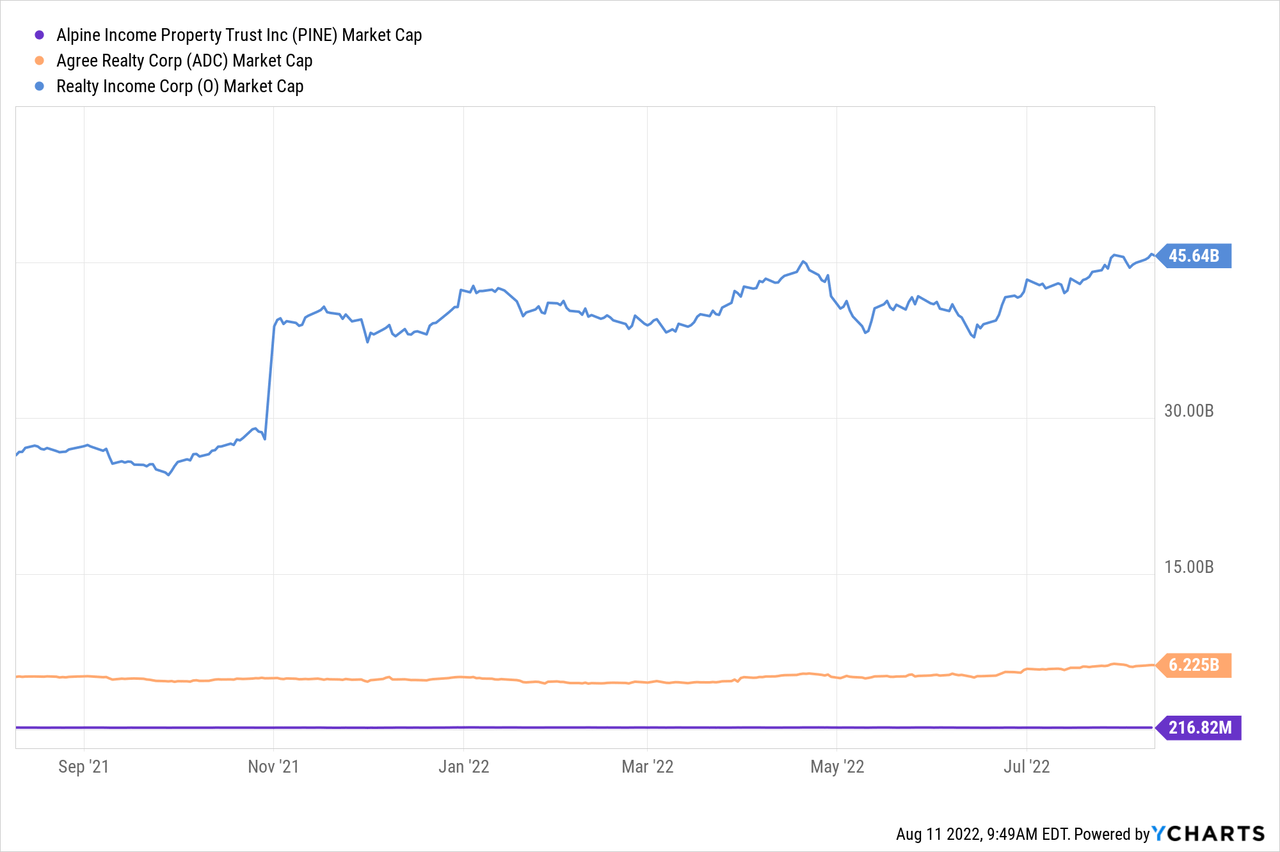
The first caution that I saw was the market cap and, subsequently, the size of the REIT. At only around a $217 million market cap, we are looking at a microcap. In total, they only have 143 properties. With only a few years of operation, that isn’t necessarily unexpected as they look to become bigger over time.

Other retail REITs such as Realty Income (O) and Agree Realty (ADC) weren’t built in a day.

Speaking of those names, here’s a comparison of those market caps for some context. Note how O had a spike in market cap after its merger with VAREIT.

Chart

YCharts

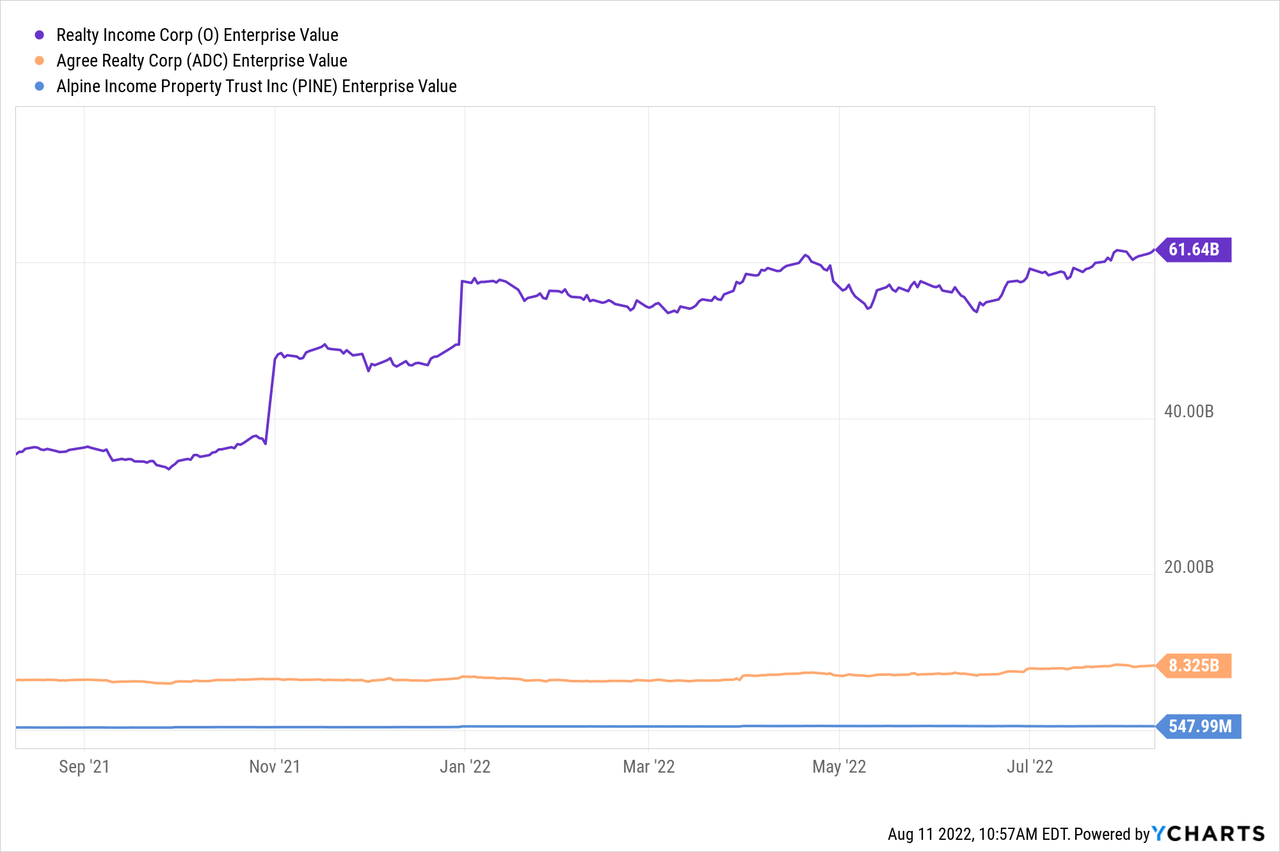
Enterprise value is often considered a better sizing metric for REITs, but we will obviously see a similar trend here too.

Chart

YCharts

A small company, or in this case, REIT, can offer higher growth potential going forward. However, it also means that a small speed bump in the economy could send things off track. Looking at the portfolio, despite being a small number of properties, it seems they hold some top-quality names for tenants.

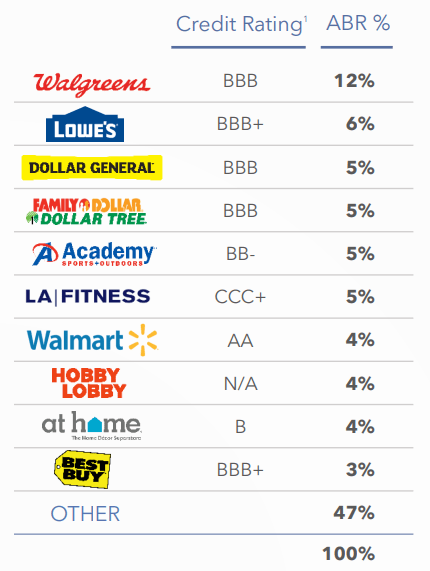
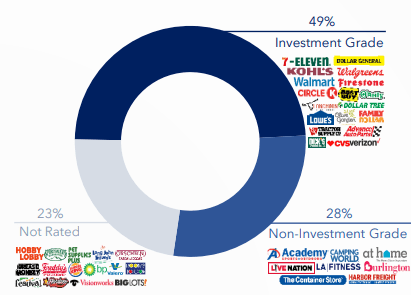
There are several recession-resistant names that won’t be impacted too considerably, such as Walgreens (WBA), Lowe’s (LOW), Dollar General (DG), Family Dollar/Dollar Tree (DLTR) and Walmart (WMT). That’s reinforced by the strong credit ratings of investment grades that these positions receive.

PINE Top Tenants

PINE Top Tenants (PINE Investor Presentation)

In fact, half their tenants are considered investment-grade. That should bode well during the next economic slowdown.

PINE Tenant Quality

PINE Tenant Quality (PINE Investor Presentation)

That’s where we go back to the size discussion, though. These top tenants make up half of their annualized base rent (“ABR”). That’s a fairly narrow selection of individual companies that can have their own individual issues pop up.

I’d also look back at their geographic exposure. Having a fairly small number of properties means that you will be fairly concentrated. In this case, 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their portfolio is in Houston, TX alone. They highlight that 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of ABR comes from metropolitan statistical areas with more than one million people.

They also highlight that 39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of ABR comes from the high-growth states of Texas, Florida, North Caroline, Arizona and Georgia. That highlights a strength while those places are growing. However, I view it as more of a concentration risk, too, having so much ABR tied up to a relatively limited number of cities within these states.

External Management

A second risk to consider before investing is that they are externally managed by CTO Realty Growth (CTO).

The Company has no employees and is externally managed by Alpine Income Property Manager, LLC, a Delaware limited liability company and a wholly owned subsidiary of CTO Realty Growth, Inc. (our “Manager”). CTO Realty Growth, Inc. (NYSE: CTO) is a Maryland corporation that is a publicly traded diversified real estate investment trust (“REIT”) and the sole member of our Manager (“CTO”).

That can create some potential conflicts of interest or values that don’t necessarily align with current shareholders. In their coverage of CTO, On The Pulse noted that they own a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} stake in PINE itself. That should help align the managers with shareholders.

As of the latest quarterly release from PINE, they continue to pick up shares in the open market. That continues to align their interest with current holders of PINE.

We are externally managed by the Manager, a wholly owned subsidiary of CTO. Subsequent to the IPO, CTO purchased an aggregate 107,866 shares of PINE common stock in the open market including (i) 99,778 shares purchased during the six months ended June 30, 2022 for $1.8 million, or an average price per share of $17.99 and (ii) 8,088 shares purchased during the year ended December 31, 2021 for $0.1 million, or an average price per share of $17.65. As of June 30, 2022, CTO owns, in the aggregate, 1,223,854 OP Units and 923,656 shares of PINE common stock, inclusive of (i) 394,737 shares of common stock totaling $7.5 million issued in connection with the CTO Private Placement, (ii) 421,053 shares of common stock totaling $8.0 million issued in connection with the IPO, and (iii) 107,866 shares of common stock totaling $1.9 million purchased by CTO subsequent to the IPO. The aggregate 1,223,854 OP Units and 923,656 shares of PINE common stock held by CTO represent an investment totaling $38.5 million, or 15.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of PINE’s outstanding equity, as of June 30, 2022.

Additionally, they intend to internalize the management of PINE. Their latest investor relation simply stated, “internalization of management for PINE is anticipated in the future when the Company approaches or exceeds critical mass.” That suggests they want to be a larger operation before internally taking a team. It, unfortunately, does not give us any solid metric to watch to see how close we may be to such a transition.

Growth Potential And Dividend

I believe those are the main risks that stood out to me, but now on why PINE can be quite attractive. The latest funds from operation (“FFO”) they provided for last quarter was $0.47. That was an increase from 2021’s $0.38 of 23.68{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That’s quite the leap. AFFO also increased 20.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the prior quarter.

ADC recently had its own earnings release. The results were fantastic, in my opinion. However, their FFO increased by 9.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and AFFO was up 10.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Fantastic results, but helps provide context on what size can do to the figures. That was after they invested $430 million on 121 properties. That’s nearly as many properties that PINE has combined.

Analysts expect that they will report $1.68 in FFO for the full year. Though that’s only a relatively smaller 6.24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth potential for the year, they have a history of easily beating analysts’ expectations thus far.

For the full 2022 year, they expect AFFO to come in at $1.58 to $1.63. That was a raise from their own prior guidance of $1.53 to $1.58. That was after they raised their guidance in the earlier quarter too. So at this point, it’s becoming a bit of a regular thing for PINE to beat and raise, which means that their expectations could still potentially be lower than what we ultimately see.

That’s part of why microcap stocks and REITs can have some strong appeal-being able to grow by larger percentages since they are growing from a smaller size in the first place. When they add 19 properties as they did in the latest quarter, that actually really adds up.

Though, net, it was a 14 property addition due to disposing of 5 office properties. Still, another 14 properties in the next quarter off of 143 properties is an almost 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} add to their portfolio. That can really contribute significantly to the FFO and AFFO growth through acquisitions alone.

For 2022 overall, they are expecting acquisitions of $215 million to $235 million. Dispositions for the year are anticipated to be $125 million to $175 million.

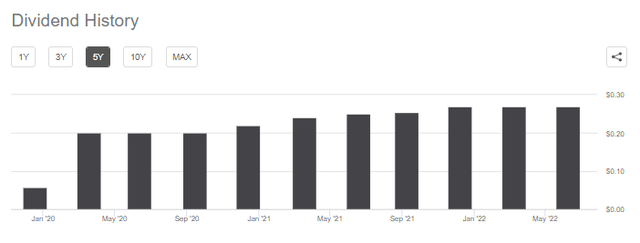
This all translates into the potential growth of the dividends for investors. Which is exactly what has been experienced so far. So far, it appears they haven’t had a predictable growth in the dividend. Instead, they appear to be raising rather sporadically but raising nonetheless. That doesn’t seem to be a bad thing until they have matured a bit more.

PINE Dividend History

PINE Dividend History (Seeking Alpha)

The latest $0.27 quarterly was a raise over last year’s $0.25 of 7.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. That also worked out to an increase of 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over the 2020 $0.20 quarterly payout.

Conclusion

I consider ADC to be “O-lite.” With PINE coming on my radar now, it would appear that a fitting description could be something like “O-ultra-lite” if I wanted to put a moniker on it. There is potential here, but due to its newness and being a small operation at this point, I think it would only be appropriate for a very high-risk portion of one’s portfolio. With the size can come the potential for a lot of growth. Even the potential to be an acquisition target. However, it also means that their economic sensitivity and lack of diversification leave them more vulnerable.

Fundrise vs. REIT: Real Estate Investment

Fundrise vs. REIT: Real Estate Investment

Man looking at toy houses with a magnifying glass

Male looking at toy homes with a magnifying glass

Incorporating serious estate to your expense portfolio can be an exceptional way to crank out potent returns and hedge from marketplace downturns or inflation. If you are not fascinated in getting and handling a property on your have, while, there are choices. Each REITs and platforms like Fundrise make true estate investing easier and additional obtainable to buyers. Even so, though Fundrise may perhaps appear to be pretty comparable to primary REITs, these two expense selections have significant dissimilarities to be aware. Here’s what you want to know.

With all the selections you have to invest in genuine estate assets, it’s only would make sense to function with a money advisor as you decide on this kind of securities.

What Is Fundrise?

Fundrise, which is a type of REIT, is an online platform that enables buyers to purchase shares of genuine estate interests. By way of Fundrise, buyers are ready to diversify their portfolio, including lower-cost true estate investments without the headache of acquiring, renovating or running people houses.

This also can make genuine estate investing feasible for a lot more persons. Rather than requiring the whole capital required to order a assets, Fundrise has decreased minimums that make serious estate investing obtainable to more recent or decrease-spending budget buyers.

Fundrise operates as a crowdfunded small business product. Buyers buy shares of preset portfolio tactics their money are then diversified across different resources in that approach. Fundrise uses this funds to invest in, renovate, market place and occupy a selection of assets styles, while charging buyers an yearly advisory price and a management charge.

About time, the investment decision houses held in just Fundrise’s portfolios may perhaps acquire value and provide profits. In change, buyers may see their very own portfolio’s price grow, and may perhaps even obtain quarterly dividends as a consequence.

How eREITs Do the job

One of the easiest ways for buyers to include serious estate to their portfolio is through a authentic estate investment have confidence in, or REIT. Acquiring shares of a REIT is identical to acquiring shares of other investments these as mutual funds, exchange-traded funds (ETFs) or even person stocks.

When investing by means of Fundrise, investors are buying shares of private equity REITs, or “eREITs,” which is a trademarked time period. These investments give funds for many residential and professional real estate tasks, presenting traders a return on the home as it increases in benefit.

Equity REITs can be privately or publicly traded in the case of Fundrise, their eREITs are open to all traders but are not traded on an trade. There are no brokers and no income fee for investors who obtain eREITS they are bought directly by Fundrise.

Fundrise vs. REIT Investing

"REIT" spelled out in block letters

“REIT” spelled out in block letters

Investing in REITs – primarily publicly traded REITs – is a beneficial selection for numerous traders. Not only do these investments usually accomplish well, but the greater part of the time they even boast a bigger return yield than the S&P 500. The eREITs offered as a result of Fundrise are privately traded investments, on the other hand. This implies that they might not boast the identical returns or have the similar rewards as community REITs acquired via a brokerage account.

With that reported, Fundrise REITs ordinarily address a vast selection of financial investment kinds. Because of this, they may perhaps enable hedge towards industry downturns much better than some specialised REITs or person authentic estate purchases.

Which is Superior?

So, involving investing via Fundrise or investing in general public REITs, which is greater? Properly, the big difference will actually rely on your goals and priorities as an investor.

Here’s a search at some of the important variations involving the two REIT financial investment strategies:

  • Fundrise delivers minimal expenditure minimums. To get started off investing through Fundrise, buyers are only expected to make a bare minimum financial investment of $10. Other REITs may well have noticeably bigger requirements – occasionally in the 4- or 5-figure selection – particularly when it will come to non-trade traded or private REITs.

  • Fees might be better with Fundrise eREITs. Fundrise costs traders a whole of 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in once-a-year costs. This consists of a .15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} advisory price and a .85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} asset administration price. The usual publicly traded REIT costs charges about 50 basis details, or .50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, on a yearly basis. This helps make Fundrise two times extra high-priced than community REITs, on typical.

  • Non-public REITs really do not present the exact same liquidity as public REITs. Commonly, REITs function greatest as a long-expression investment decision. However, if you at any time require to liquidate general public trade-traded REITs, you can often do so relatively immediately via your brokerage platform. Fundrise REITs, on the other hand, are personal and non-traded, which usually means that your shares could consider a lot for a longer time to provide.

  • The Fundrise platform can be simpler to use. There are quite a few distinctive REITs to opt for from, but locating the a person that functions finest for your objectives and financial investment timeline can be tough, dependent on the place and how you spend. Fundrise presents preset investment decision portfolios, enabling investors to choose the a single that suits their objectives. Any cash invested will be disbursed in accordance to that portfolio’s allocation, without the want to shop all over or do substantially digging.

All REITs are essential by the IRS to pay back out at the very least 90{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their taxable income to traders. These are disbursed in the form of dividends. While dividends (and over-all returns) are hardly ever assured, this prerequisite can make REITs an superb alternative for buyers searching for passive profits streams.

The Bottom Line

Two REIT investors

Two REIT traders

Normal REITs can be publicly traded, privately traded or public non-traded. Fundrise REITs are non-public, and so may well be considerably illiquid, might be easier for some buyers and only call for an original expenditure of $10. Investors can just choose the preset portfolio that ideal matches their ambitions. Fundrise system fees are 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yearly, which is increased than the common general public REIT rate. Though the Fundrise financial investment product is rather straightforward, return yields could be decrease than community REITs, relying on the portfolio you pick out.

Ideas for Investing

  • Consider functioning with a economical advisor as you weigh the execs and downsides of various actual estate assests. Acquiring a financial advisor doesn’t have to be challenging. SmartAsset matching software matches you, in just a couple of minutes, with experts in your place. If you’re prepared, get began now.

  • REITs can make a critical aspect of your retirement nest egg. Preparing for retirement involves understanding how a great deal you’ll need to have to maintain your way of living at the time you’re performed doing work. SmartAsset’s free of charge retirement calculator can give you an concept of how a lot revenue you want to save.

Image credit score: ©iStock.com/designer491, ©iStock.com/Kwarkot, ©iStock.com/calcassa

The submit Fundrise vs. REIT: Actual Estate Expense appeared initial on SmartAsset Blog.