Gangnam style falls out of favor as rising rates whack Korea’s luxury real estate sales

Gangnam style falls out of favor as rising rates whack Korea’s luxury real estate sales

House in Gangnam — a trio of exceptional districts in South Korea’s cash, Seoul — is commencing to buckle as the central bank’s yearlong tightening cycle weighs on the luxurious serious estate market place.

Apartment charges in all Gangnam districts have declined for 4 consecutive months, info from the Korea Real Estate Board present, portending the to start with regular drop considering the fact that the Lender of Korea commenced boosting its important price final August.

The strike to Gangnam signals the effects of plan tightening is now achieving into the upper stratum of Korea’s 51 million individuals. 

Whilst Governor Rhee Chang-yong told Bloomberg that a housing correction was unavoidable and has a attractive component, issue over the home industry and home credit card debt are among aspects that have prompted the BOK to return to smaller fee will increase.

Gangnam residences make up an overwhelming bulk of Seoul households factored into the Knight Frank Primary World-wide Cities Index, which has slowed soon after soaring final 12 months at the speediest tempo considering that 2008. 

The cooling momentum among the world’s most attractive and costly 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of houses coincides with the get started of the Federal Reserve’s amount improves and climbing worry about a world economic downturn.

“My expectation is that we will see the index’s price of advancement sluggish further in the 3rd quarter as economic headwinds mount,” mentioned Kate Everett-Allen, head of global residential analysis at Knight Frank. 

“But we anticipate our primary index to outperform our mainstream housing sector indices in which there is a bigger reliance on finance and as a result extra publicity to the charge rises.”

With Gangnam at its heart, Seoul’s key serious estate was Asia’s hottest in the previous 12 months, leaping 20.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and outpacing the two Tokyo and Taipei, according to Knight Frank.

Flats tracked by Knight Frank include Raemian Dogok County, which expenditures up to 3.8 billion gained ($2.8 million) per device, and Acro River Park, priced at as significantly as 22 billion received. Samsung Tower Palace 3rd traded for up to 7.5 billion received, according to Korean portal Naver.

South Korean singer and producer Psy performs his greatest strike music, Gangnam Model, through a live performance at an outside venue in the grounds of the Korea University in Seoul on May 27, 2022.

Anthony Wallace—AFP/Getty Photographs

Made internationally popular by Psy’s “Gangnam Style” music movie, the districts symbolize prosperity, standing and chic amid Koreans. Their cluster of prestigious large educational institutions and community of influential people make the community a Mecca for South Korea’s elite.

Compared with a year before, home selling prices in Gangnam even now grew in July, soaring about 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — the slowest tempo since the spring of 2021. It continues to be to be observed whether the downturn will final in the districts.

Nonetheless, when Gangnam falls, it tends to fall more challenging than many other places. For the duration of the 2012-2014 downturn, Gangnam declined even further than most of the relaxation of the nation. Related volatility was recorded through the 2008-09 worldwide money crisis.

Even more strain is very likely to come, way too, with central bankers such as Fed Chair Jerome Powell warning at final month’s Jackson Gap assembly that borrowing costs are headed even larger and will stay elevated for some time.

Gangnam, once rugged farmland, is now home to 2 million men and women, together with significant-level officials this sort of as President Yoon Suk Yeol, K-pop stars and an array of business enterprise and tech leaders.

Not everyone in the districts is rich and well known. When the heaviest rainstorm in 80 several years hit Seoul last thirty day period, at minimum four Gangnam residents drowned in the basement homes that arrived to symbolize Korea’s deep wealth inequality in the Oscar-successful movie “Parasite.”

The torrential rains also uncovered sudden gaps in some luxurious flats, submerging Lamborghinis, Porsches and hundreds of other luxury cars parked beneath them. 

Koreans as a rule want residences to standalone houses, in contrast to quite a few Western countries. The cookie-cutter structures just take up significantly less house in the densely-populated state and are considered as safer against theft, cheaper to control and simpler to trade simply because they are crafted to equivalent specs.

The incipient correction in luxury properties is not constrained to Gangnam, both. The 50 quality residences picked nationwide by Kookmin Financial institution have fallen for two months in a row, in accordance to facts produced past 7 days.

The cooling is a distinct indication that the central bank’s coverage tightening is flowing by to house. 

The BOK commenced its amount-hike cycle before than most formulated economies as it grew involved about financial imbalances. Korea’s widening prosperity divide, amplified by soaring house prices, fueled general public anger and drove an electoral wave that assisted Yoon oust Moon Jae-in in an election previously this yr.

Now, as residence price ranges begin to slide, the tables are turning. But likely purchasers aren’t dashing to brokers to test to safe a property.

The BOK’s fee rises and anticipations of further tightening, with each other with the low volume of offers, are fueling expectations the downturn will be protracted.

“With households starting up a deleveraging cycle, we assume housing charges to continue to be beneath force in coming yrs,”said Park Jeong Woo, an economist at Nomura Holdings Inc. 

Indication up for the Fortune Attributes email list so you do not miss our most important capabilities, exceptional interviews, and investigations.
What Inflation, Rates, Recession Mean for US Real Estate: Goldman Sachs

What Inflation, Rates, Recession Mean for US Real Estate: Goldman Sachs

  • Genuine estate is typically touted as a trusty hedge from significant inflation, but that may perhaps be transforming.
  • Soaring selling prices, rising fascination costs, and a opportunity recession are reshaping the US industry.
  • Two Goldman Sachs genuine-estate industry experts disclosed in which they see upside for investors, on a current podcast.

Actual estate is normally touted as a trusted hedge in opposition to inflation, presented landlords can elevate rents, and assets values tend to rise together with other selling prices.

Two of Goldman Sachs’ specialists on the sector, Jeff Fantastic and Nora Creedon, defined why that is not essentially accurate on a current episode of the Exchanges at Goldman Sachs podcast. They thorough how inflation, climbing desire premiums, and a possible economic downturn are transforming the true estate field, and uncovered where they see possibilities for investors.

In this article are High-quality and Creedon’s 8 very best quotations, lightly edited for length and clarity:

1. Nora Creedon: “True estate tends to be much less correlated to other investments that you have. It tends to be significantly less risky than quite a few other investments. It tends to have cash flow areas. And so, I imagine it requires to be a element of everyone’s portfolio.”

2. Jeff Good: “Simply because there is so substantially funds that is chasing investments, we have not viewed a substance reset in asset pricing yet. We think it will arrive over time.” (He was responding to Creedon indicating the Federal Reserve’s curiosity-amount hikes would reduce credit history availability, minimizing industry liquidity and house values.)

3. NC: “Target on property that has pricing energy. Assets with definitely excellent demand from persons who can pay back for all those assets. Indicating that they can pay the rents to possibly be in that multi-relatives group, or be at that lodge, or be in that excellent business developing at Major & Key.”

“Also, the kind of serious estate that is not contending with major new source. The intersect of that strong demand from customers and limited supply is actually the place you are going to see the pricing energy that can offset inflation.”

4. NC: “There’s definitely never ever been a period in history exactly where you could have inflation like this and not have significantly tighter fiscal problems, no matter if that will come in the form of higher costs or considerably less cash availability. That is not ordinarily friendly to actual estate.” (She added that extended lease agreements may well prohibit rapid rate hikes, and highlighted “offsetting charges” to charging better price ranges, this sort of as possessing to spend better wages to personnel a resort.)

5. NC: “The very last few months, we’ve had a remarkable spike in mortgage premiums to invest in a household. And that has induced a serious affordability disaster in the housing industry.” (She pointed out that larger monthly home loan expenses have served household landlords to increase rents, as the alternate solution of possessing a dwelling has become a lot less attractive or even infeasible for some persons.)

6. NC: “We are absolutely discovering parts in residential, which includes specialized niche locations of residential like college student housing and age-restricted and senior housing, the place we imagine there is certainly large skill to increase rents over time. And all those are sites that we’re likely to want to be in above the next five and 10 years.”

7. JF: “Our belief is people today are likely back again to get the job done. There may possibly be some variations to the perform patterns. There may well be much more flexibility designed in. There could be particular industries that care about in particular person, in business a whole lot fewer. But by and large, we even now believe that in the business office tenant current market.”

8. JF: “This is a truly interesting time period that we’re heading into. We never really like them supplied the destruction, in some cases, that it can induce to the broader marketplace. We talked about economic downturn. We talked about increasing fees. But as an investor, these are the times you wait around for. This is when the inefficiency generates prospect.”

Browse much more: 6 explanations why the US housing current market is nicely-positioned to take up a collection of corrections as selling prices slide quickly

Homeowners lose wealth as rising interest rates weigh on home values

Homeowners lose wealth as rising interest rates weigh on home values

A “For Sale” sign outside a home in Albany, California, on Tuesday, May perhaps 31, 2022.

David Paul Morris | Bloomberg | Getty Visuals

Some householders are dropping wealth as significant property finance loan prices weigh on property values, at least on paper, as the once pink-sizzling housing sector cools promptly.

Revenue have been slowing down for numerous months, with house loan costs now double what they ended up at the start of this 12 months.

House charges, similarly, dropped .77{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from June to July, according to a recent report from Black Knight, a computer software, details and analytics corporation. Although that may perhaps not sound like a ton, it was the major regular monthly drop because January 2011 and the very first regular monthly fall of any dimensions in 32 months.

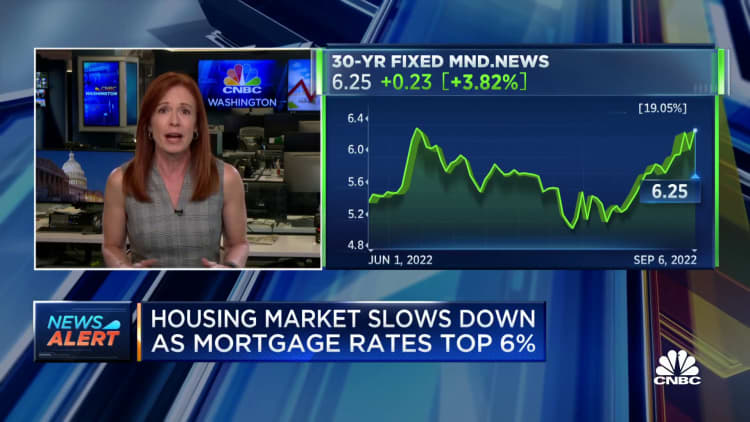
Housing market slows as mortgage rates hit 6.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}

“Yearly dwelling rate appreciation even now arrived in at about 14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, but in a sector characterized by as much volatility and quick improve as present day, this sort of backward-on the lookout metrics can be deceptive as they can mask far more existing, pressing realities,” wrote Ben Graboske, president of Black Knight Knowledge & Analytics.

Around 85{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of major marketplaces have noticed selling prices come off peaks by means of July, with just one-third coming down a lot more than 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and about 1 in 10 falling by 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or far more. As a final result, soon after gaining trillions of bucks in property equity collectively through the to start with two several years of the Covid pandemic, some house owners are now shedding fairness.

So-identified as tappable fairness, which Black Knight defines as the sum a homeowner can borrow versus even though trying to keep a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity stake in the assets, strike its 10th consecutive quarterly document high in the second quarter of this yr at $11.5 trillion. But data suggests it may well have peaked in May possibly.

Declining house values in June and July introduced the complete quantity of tappable equity down 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and offered the weakening in the housing market considering the fact that then, the third quarter of this calendar year will demonstrate a a lot more sizeable decrease.

“Some of the nation’s most equity-rich markets have viewed considerable pullbacks, most notably amid vital West Coast metros,” pointed out Graboske.

From April by way of July, San Jose, California, shed 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its tappable equity, followed by Seattle (-18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Diego (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), San Francisco (-14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}) and Los Angeles (-10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

House owners are nonetheless considerably a lot more flush than they have been the previous time the housing industry went by way of a big correction. All through the subprime mortgage crash, which began in 2007, and the subsequent Excellent Recession, dwelling values plummeted by virtually half in some significant marketplaces. Hundreds of thousands of debtors went underwater on their mortgages, owing a lot more than their households have been worthy of.

That is not the scenario right now. Latest debtors, on normal, owe just 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their home’s value on the two first and 2nd home loans. It is the most affordable leverage on record. Shedding some value on paper should not impact all those entrepreneurs at all.

There are, nonetheless, about 275,000 debtors who would tumble underwater if their households ended up to get rid of 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of their current benefit. A lot more than 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all those borrowers acquired their properties in the 1st six months of this calendar year, which was the top of the market.

Even with a common 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop in charges, destructive equity costs would continue to be nowhere close to the concentrations noticed throughout the monetary crisis, according to the report.

Rising interest rates shouldn’t discourage income property owners

Rising interest rates shouldn’t discourage income property owners

The checklist of concerns can be very long when getting an revenue house in the Puget Seem area. Regardless of whether it is a multifamily, small professional or combined-applied home, earnings house buyers must realize the dangers and benefits that come with this precise kind of purchase. If that weren’t sufficient, the math on investments is transforming as The Federal Reserve proceeds to elevate fees in response to inflation and other financial inputs.  

There is no concern that as the premiums for conventional mortgages are on the rise, even the boldest profits assets investors are sensation cautious about the sector. 

Earnings assets traders will need not be fearful nonetheless, as the correct established of strategic resources can support make the very best of their investments. Especially for those in the sector to make investments in 1 – 4 household properties – single relatives residences, duplexes, triplexes and fourplexes – there are nevertheless competitive methods to finance your financial investment devoid of paying quality premiums.

A single consideration is the Adjustable-Amount Mortgage loan (ARM). As common rates continue on to increase, quite a few are turning to ARMs mainly because of the decreased fees they supply for a mounted time period of time – normally 5, 7 or 10 yrs – when compared to a standard 30-12 months fixed home finance loan.

Not all ARMs are designed equivalent, nevertheless, and earnings home buyers should really take into consideration some standard advice to get the most from their strategic investments.

3 key tactics for getting the most out of your ARM

Comprehend your lender’s curiosity level ceiling

A nicely-acknowledged hazard of ARMs is that at the end of the set-charge time period, ARM financial loans are matter to price changes, which can be significantly better than the first ARM level.

There is a large range of alternatives for how a loan provider will increase fascination premiums after the preliminary fastened period is full, in addition to how much the rate can change about the overall lifetime of the personal loan. Some banking companies let a modest raise at original adjustment, although some others may possibly default to an first maximize up to the lifetime cap. The life span cap is the utmost curiosity amount permitted on an adjustable-price home finance loan, which most lenders set at 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Appear for a bank that keeps the preliminary adjustable desire amount ceiling lower. For illustration, some creditors cap the optimum mortgage charge boost to 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} right after the original fixed period.

Get a obvious see of pre-payment penalties

Typically situations with an ARM, traders choose to pay off their home loan early to acquire advantage of small set desire fees. If a bank loan is paid out off or refinanced in the course of the prepayment penalty period of time, traders could owe extra expenses or a penalty, which is ordinarily a proportion of the remarkable personal loan equilibrium.

Some lenders provide pricing alternatives that do not incorporate prepayment penalties. Acquire the time to comprehend your bank’s approach to pre-payment penalties in their loan agreements. If they only offer prices with a pre-payment penalty, traders have alternatives and really should search for a lending establishment that has options for penalty-free pre-payment of their loan.  

Assess community and larger lending institutions

Huge, nationwide banking institutions and loan providers can contend in the consumer lending market with attractive fees. But neighborhood banking institutions, like Pacific Crest Financial savings Lender and others in our region, give a number of benefits further than charges alone for traders seeking to framework special funding deals – though also preserving the bank’s property in the area economy.

Buyers with elaborate conditions may perhaps uncover that with a community lender, the loan company may understand their clients’ desires more intuitively, and are equipped to close discounts much more speedily since determination-building occurs on a regional amount.

Local community banks also generally have flexibility to tailor their merchandise and companies to clients’ wants and are enthusiastic by working collaboratively to propel progress among smaller firms in the neighborhood region.

Even as the listing of issues for money home traders receives for a longer period, there’s nevertheless lots of possibility to be successful in the Pacific Northwest. From one spouse and children household to small business actual estate and everything in involving, there are financing alternatives that will fit both equally quick and very long-term requirements for community traders.

Master additional at www.paccrest.com.

Written content Resource: Johnny Smith, Pacific Crest Personal savings Financial institution, Vice President and Residential Financial loan Officer


Johnny Smith

Johnny Smith is a vice president and household loan officer at Pacific Crest Price savings Lender, a nearby and independently owned savings financial institution headquartered in Lynnwood, Washington, that has served Northwest organizations and individuals with personalized banking and lending solutions given that 1984.

With knowledge in equally serious estate lending and title insurance, he delivers a important blend of perception to assistance address clients’ exceptional difficulties and possibilities. As a vice president and residential mortgage officer, he delivers portfolio financial loans for residential qualities and floating houses, tailoring the bank’s remedies to meet up with his clients’ requires.

Outside of the lender, Johnny enjoys spending time outdoor – particularly tenting with his spouse, kids and grandkids.

Come to feel free to speak to Johnny Smith at (425) 670-9624 or jsmith@paccrest.com. Remember to do not incorporate sensitive or private information in your information.

Housing market “pushed to the limit” as mortgage rates jump, sales slump

Housing market “pushed to the limit” as mortgage rates jump, sales slump

The housing slowdown we have been anticipating for months is here.

The big picture: House income are slowing down, and some of the pandemic era’s hottest “Zoomtowns” — sleepy places exactly where distant staff pushed up authentic-estate selling prices — are previously viewing selling price drops.

Why it matters: The plan of a real estate downturn may possibly appear scary, especially if you lived through the previous a single. But with home price ranges at record highs, this was a market place overdue for cooling off.

What is going on: “Activity in the housing sector has weakened,” is how Fed Chair Jerome Powell place it Wednesday, at a press convention asserting yet another .75 proportion position charge hike.

  • Agreement signings for residence purchases, or bargains signed but not however closed, fell 8.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in June from a thirty day period in the past, the Countrywide Association of Realtors documented yesterday. That was perfectly above what economists were being predicting, and a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop from previous 12 months.
  • It was also the slowest speed given that September 2011 — apart from for the first two months of the pandemic, notes CNBC.
  • Meanwhile, mortgage loan programs are at their most affordable degree of exercise given that February 2000.

Information: House loan Bankers Association Chart: Nicki Camberg/Axios

What is actually subsequent: Selling prices are coming down in some pockets, and analysts assume that to continue on.

  • 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders reduced selling prices on new households in July, in accordance to study data from housing market place study organization Zonda.
  • “Some of the metro areas that captivated out-of-condition consumers early in the housing boom are cooling off the swiftest,” writes Nicole Friedman in the WSJ. Boise, Denver, Salt Lake Metropolis and Tacoma, Clean. all noticed the most value cuts in June, in accordance to Redfin facts she cites.

What they are declaring: “Exercise is now in cost-free-slide, inventory is rocketing, and price ranges have begun to fall,” Ian Shepherdson, chief economist at Pantheon stated in a take note. He’s been contacting this slowdown for a although.

  • This was not a blip: “We can assume ongoing downturn as we head into the second fifty percent of the 12 months,” mentioned George Ratiu, senior economist & manager of economic analysis at Realtor.com.

Zoom out: This is how the actual globe is reacting to what is going on at the Fed — mortgage charges jumped, and quickly homes had been even fewer cost-effective. However persons would like to get, they can’t.

  • You could say that the Fed “crushed demand from customers” for households, except persons however truly want households. The U.S. is struggling from a very long-time period housing lack.

“The problem in the housing market is that numerous People in america so desperately continue to want to personal a home,” Ali Wolf, main economist at Zonda, mentioned in a concept to Axios. “But climbing house charges and higher interest prices have pushed them to the restrict.”

‘The pandemic boom in home sales is over’: Mortgage rates soar to highest level since 2009 as the Fed pressures the housing market

‘The pandemic boom in home sales is over’: Mortgage rates soar to highest level since 2009 as the Fed pressures the housing market

Home loan rates are skyrocketing thanks to the Fed, but potential buyers who can rough out this tough, altering market will be rewarded.

The 30-year fastened-rate mortgage averaged 5.27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the 7 days ending May possibly 5, in accordance to info unveiled by Freddie Mac 
FMCC,
-1.62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
on Thursday. That’s up 17 basis details from the earlier 7 days — one particular basis level is equal to 1 hundredth of a percentage level, or 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

This represents the maximum level for the benchmark 30-calendar year house loan products given that August 2009. To set that in context: The very last time mortgage loan rates ended up this substantial Barack Obama was just months into his initial phrase as president, the country was in the depths of the Good Recession and Instagram experienced still to be launched.

“The last time mortgage loan charges ended up this higher Barack Obama was just months into his initial phrase as president, the country was in the depths of the Terrific Economic downturn and Instagram had but to be launched.”

The common fee on the 15-12 months fixed-amount home loan rose 12 foundation points about the earlier week to 4.52{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The 5-yr Treasury-indexed hybrid adjustable-rate property finance loan averaged 3.96{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, up 18 foundation details from the prior 7 days.

Home finance loan premiums are roughly benchmarked to the generate on the 10-calendar year Treasury be aware
TMUBMUSD10Y,
3.127{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
But the change among the normal level on the 30-calendar year mortgage and the 10-yr Treasury has widened not long ago.

Considering the fact that the conclude of the Excellent Economic downturn, the spread involving the two has averaged 1.7 share details, but presently it hovers higher than 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If the spread had been closer to historical stages, the 30-calendar year set-fee mortgage loan would however be underneath 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

The Federal Reserve is mostly to blame for the point that mortgage costs enhanced at a more quickly speed than may possibly otherwise be envisioned, according to assessment from Odeta Kushi, deputy main economist at title insurance company Initially American
FAF,
+.29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Investors who purchase property finance loan-backed securities have previously factored in expectations that the Federal Reserve will carry on to raise prices in the course of this 12 months into their view on the mortgage loan current market.

Lenders, therefore, ought to hike the costs they provide customers so that they can carry on to sell their financial loans to traders — people sales are what generates the funds applied to deliver much more home loans.

“While some additional Fed tightening is previously baked into today’s regular house loan premiums, ongoing inflationary tension remains probable to force mortgage loan prices even bigger in the months to come,” Kushi claimed.

Hiking limited-phrase desire charges is not the only way the Fed influences the mortgage marketplace. The central financial institution by itself has been a purchaser of mortgage-backed securities considering that the start out of the pandemic. So now that the Fed will be shrinking its balance sheet of bonds, together with these securities, there could be an influence on liquidity in the mortgage loan market. Lenders would will need to make up the big difference by increasing fees.

Already current housing-market details has proven the massive outcome the surge in rates has experienced on residence prospective buyers. “The pandemic boom in house revenue is around, and exercise is again at pre-pandemic ranges,” Mizuho Securities U.S. economist Alex Pelle and main U.S. economist Steven Ricchiuto wrote in a study be aware.

It’s obvious that the affordability troubles posed by increasing fees and higher charges has cooled demand among property prospective buyers. Nonetheless, house listings continue being several and significantly amongst. That suggests that property selling prices probably will carry on to develop — albeit at a slower pace — due to the fact even with a reduced pool of customers there aren’t plenty of properties to grow all around, analysts say.

And there is the likely that growing interest charges could also put a damper on the provide of properties for sale. “Existing householders are amount locked-in when their existing mortgage rate is beneath the prevailing marketplace home finance loan level, mainly because there is a economical disincentive to offer their residences and purchase a new property at a larger mortgage fee,” Kushi said.

Most economists foresee that the housing market place is balancing out, meaning that bidding wars and contingencies could soon grow to be a issue of the earlier.