Want to Know How the Housing Market Is Doing? Follow Mortgage Rates.

Want to Know How the Housing Market Is Doing? Follow Mortgage Rates.

Textual content sizing
Current Investment Property Mortgage Rates Today

Current Investment Property Mortgage Rates Today

Our experts answer readers’ home-buying questions and write unbiased product reviews (here’s how we assess mortgages). In some cases, we receive a commission from our partners; however, our opinions are our own.

If you’re planning to buy an income-generating property, shopping around to find the best mortgage rates can help you make the most of your investment.

Check out today’s investment property mortgage rates and learn how these types of rates are determined.

Current investment property mortgage rates

In general, mortgage rates have been inching up this month, following several weeks of rapid decreases. But rates are expected to fall throughout 2023, and borrowers will likely be able to snag lower rates later this year.

As you explore rates, keep in mind that investment property mortgage rates are usually higher than mortgage rates on primary residences or second homes.

See how investment property mortgage rates compare

Check out today’s mortgage rates to see how rates are trending. These rates are for all mortgages, not just investment property mortgages.

Mortgage type Average rate today


This information has been provided by
Zillow. See more
mortgage rates on Zillow

Investment property definition

When using a mortgage to buy a property, buyers can choose from three types of occupancy: primary residence, second home, and investment property.

Your primary residence is your home, and the place where you live for the majority of the year. A second home is a home you occupy only some of the time, such as a vacation home.

Investment properties are properties purchased solely for the purpose of generating income, often by renting it out on a short- or long-term basis. Investment properties are not owner-occupied, meaning the owner doesn’t live in the home.

Are investment property mortgage rates higher?

The main reason investment property mortgage rates can be higher than other types of mortgages is that lenders consider investment property mortgages to be at a higher risk of default than other occupancy types.

Why are investment property mortgages riskier? If the borrower encounters a financial hardship, they’re more likely to make sure the costs on their primary residence are paid first. Investment properties also require a lot of work and money to maintain. If the owner has a hard time finding tenants or ends up putting more money into their investment than they’re getting out of it, they could decide to walk away.

Other factors that can impact your rate include how much you’re borrowing and where the property is located. If you’re buying a very high-cost property, you may pay more in interest. Some states also have higher average rates than others.

To help keep your rate as low as possible, you could work on boosting your credit score, improving your debt-to-income ratio (DTI), and saving for a larger down payment. You should also get preapproved with more than one lender so you can compare offers.

How to qualify for an investment property mortgage

Because the risks are higher, the requirements for an investment property mortgage are stricter. 

You’ll need to put down at least 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to purchase a single-unit investment property. If you’re buying a property with multiple units, you’ll need at least 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If you can put down more than the minimum, you’ll likely get a better rate.

“A homebuyer looking to purchase an investment property should account for a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment to get a competitive rate,” says Raul Hernandez, a mortgage broker with Competitive Home Lending.

Additionally, Hernandez says its possible to qualify for an investment property mortgage with a credit score as low as 620. But those with lower scores will need to make a larger down payment and pay more in interest, he says.

Mortgage calculator

Use Insider’s free mortgage calculator to see how different rates can impact your monthly payment and overall loan costs.

Mortgage Calculator

$1,161
Your estimated monthly payment

  • Paying a 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher down payment would save you $8,916.08 on interest charges
  • Lowering the interest rate by 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} would save you $51,562.03
  • Paying an additional $500 each month would reduce the loan length by 146 months

Investment property mortgage frequently asked questions

The amount you’ll need to purchase an investment property can vary depending on your lender — but typically you’ll need a minimum of 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down for a single unit, and 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down for a two to four-unit property.

However, if you’re considering purchasing a multi-unit property to rent out, you can make a lower down payment if you occupy one of the units full time. This is allowed because the property would be considered a primary residence rather than an investment property. With an FHA loan, you can purchase an owner-occupied property with up to four units with a 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment. With a VA loan, you won’t be required to put anything down. For conventional loans, you’ll need at least 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down for a two-unit property.

You’ll need a higher credit score and down payment to qualify for an investment property mortgage than you would with a primary residence mortgage. Keeping your DTI to an acceptable level may also be more difficult, since you’ll be adding a new mortgage to any existing loans you’re already paying.

If you’re having trouble coming up with a sufficient down payment for your investment property purchase, you might consider tapping into the money you have in your current home with a home equity loan or HELOC.

Housing market slump gives homebuilders no choice but to offer aggressive mortgage rate buydowns

Housing market slump gives homebuilders no choice but to offer aggressive mortgage rate buydowns

The 2nd 50 percent of 2022 noticed the crimson-incredibly hot U.S. housing current market thrust into an abrupt—and sharp— slowdown. That’ll occur when property finance loan prices spike from 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} just soon after U.S. household price ranges skyrocketed in excess of 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} all through the Pandemic Housing Increase.

Contrary to present house sellers who can just hold out out the storm, U.S. homebuilders—who have a historic amount of models in their backlog—have no choice but to sweeten the deal for new purchasers in 2023. Their incentive of selection? Intense mortgage loan fee buydowns. 

How do home loan amount buydowns operate? Fundamentally, builders pay back lenders a lump sum of revenue in order to decrease home finance loan prices for future customers. For case in point, a builder could possibly offer a 2-1 fee buydown, in which the mortgage level is diminished from say 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and primarily based on the arrangement, the level would maximize each yr immediately after by 1 proportion level until eventually it reaches 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

“If you seem back above time, there’s distinctive incentives that do the job all through various intervals of time—the explanation that amount buydown is operating proper now is because rates acquired so large,” Devyn Bachman, senior vice president of study at John Burns Authentic Estate Consulting, instructed Fortune. “It’s always been a thing, it’s just that it is the preferred preference in today’s sector.”

Although the 2-1 non permanent fee buydown is commonly made use of to make an give extra enticing, Bachman mentioned customers are favoring full-term buydowns. That implies they’re “buying down the rate for the entirety of that person’s home finance loan,” Bachman said.  

As of final month, 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of nationally surveyed homebuilders mentioned they are buying down buyers’ house loan costs to make payments far more affordable, according to John Burns Serious Estate Consulting. That very same survey found 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders are purchasing down the whole 30-year phrase, while 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} are only temporarily lessening the charge for the very first two years. 

Bachman informed Fortune that huge incentives bolstered by amount buydowns are encouraging far more people to take into consideration obtaining new residences as opposed to present houses because the resale industry just cannot contend with all those presents.

The company’s hottest builder survey identified new dwelling revenue rose 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from November to December, she said. And though there are several aspects at enjoy, the incentive of rate buydowns does carry some excess weight in deciphering the improvement. 

“There’s plenty of variables at engage in, but the price buydowns and the dimensions of them, is unquestionably a person of the levers that’s encouraging customers to order new homes,” Bachman claimed. 

As for the expense of home finance loan price buydowns for builders, every single .25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} reduction in the charge generally prices around 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the bank loan quantity. But with the industry scarcely commencing to see indications of depressurization, it is frequently the only incentive builders can offer you prospective buyers to press the sale through. 

Nevertheless the value of the price buydown differs and is dependent on a several variables, which include: household price and down payment—which in alone varies based on the marketplace remaining cost-effective or unaffordable—the type of bank loan, and the form of buydown. 

Find out how to navigate and improve believe in in your business with The Belief Variable, a weekly publication inspecting what leaders require to do well. Signal up listed here.

US home price gains fall sharply in November as rising mortgage rates cool housing market

US home price gains fall sharply in November as rising mortgage rates cool housing market

Household rates declined sharply in November as greater growing home loan premiums continued to sap demand from the housing market.

Rates in November greater 8.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the year-ago time period, the smallest attain in two yrs, according to new data posted on Tuesday by CoreLogic. 

On a month to month foundation, prices truly dropped .2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in November.

Prices are now about 2.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} beneath their spring 2022 peak and are envisioned to continue slipping this yr, at some point tumbling into negative territory right before rebounding to close to 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} or 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the spring. 

INFLATION EASES A lot more THAN Predicted IN NOVEMBER TO 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, BUT Buyer Costs Stay ELEVATED

home mortgage

A For Sale indication is posted in front of a home in Monterey Park, California on August 16, 2022.  (FREDERIC J. BROWN/AFP through Getty Photos / Getty Images)

“Despite the fact that house value development has been slowing quickly and will carry on to do so in 2023, sturdy gains in the very first 50 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of very last yr advise that total 2022 appreciation was only slightly reduce than that recorded in 2021,” reported Selma Hepp, deputy main economist at CoreLogic. “On the other hand, 2023 will present its possess problems, as people continue to be wary of both the housing current market and the in general financial outlook.”

The curiosity rate-delicate housing market has borne the brunt of the Federal Reserve’s aggressive campaign to tighten coverage and gradual the economic climate. Policymakers now lifted the benchmark federal resources fee 5 consecutive situations and have revealed no signal of pausing as they test to crush inflation that is nevertheless managing around a 40-calendar year substantial. 

Property finance loan fees have commenced to inch better in recent weeks: The regular amount for a 30-12 months fastened home loan hovered all around 6.42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} past week, in accordance to the most recent details from house loan loan provider Freddie Mac. While that is down from a peak of 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in September, it is still more than double just a person calendar year back, when prices stood at 3.10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

US housing market

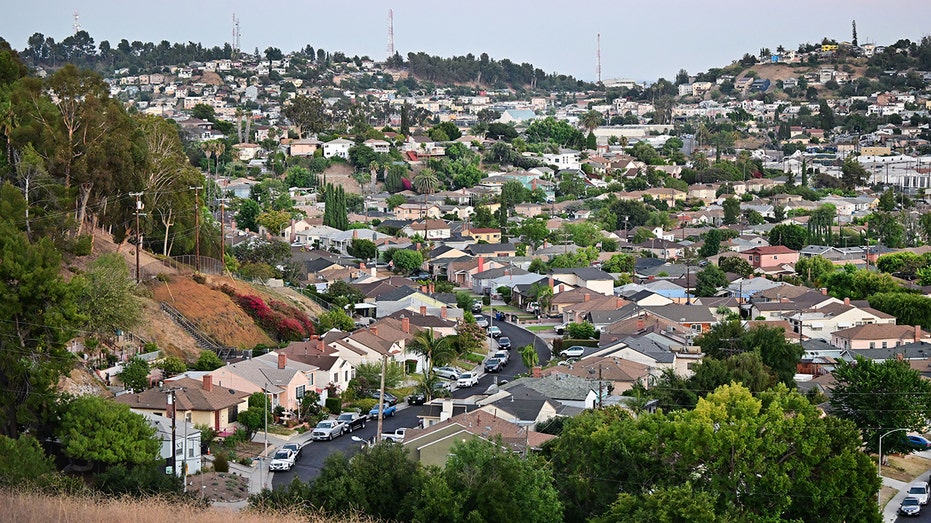
A look at of houses in a community in Los Angeles, California, on July 5, 2022.  (FREDERIC J. BROWN/AFP by way of Getty Photographs / Getty Images)

Merged with higher household rates, the rapid increase in borrowing expenses has pushed quite a few entry-stage homebuyers out of the marketplace.

A separate report introduced last month by the Nationwide Affiliation of Realtors (NAR) showed that U.S. present home profits slowed for the 10th straight month in November, tumbling 7.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from the prior month to an yearly rate of 4.09 million models. On an once-a-year basis, house profits plunged 35.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in November.

GET FOX Business ON THE GO BY CLICKING Below

“In essence, the household genuine estate current market was frozen in November, resembling the income exercise found all through the COVID-19 financial lockdowns in 2020,” explained Lawrence Yun, the main economist at NAR. “The principal component was the speedy enhance in mortgage loan rates, which hurt housing affordability and minimized incentives for house owners to listing their residences.”

Are home prices still going up? What’s happening with mortgage rates?

Are home prices still going up? What’s happening with mortgage rates?

Housing market “pushed to the limit” as mortgage rates jump, sales slump

Housing market “pushed to the limit” as mortgage rates jump, sales slump

The housing slowdown we have been anticipating for months is here.

The big picture: House income are slowing down, and some of the pandemic era’s hottest “Zoomtowns” — sleepy places exactly where distant staff pushed up authentic-estate selling prices — are previously viewing selling price drops.

Why it matters: The plan of a real estate downturn may possibly appear scary, especially if you lived through the previous a single. But with home price ranges at record highs, this was a market place overdue for cooling off.

What is going on: “Activity in the housing sector has weakened,” is how Fed Chair Jerome Powell place it Wednesday, at a press convention asserting yet another .75 proportion position charge hike.

  • Agreement signings for residence purchases, or bargains signed but not however closed, fell 8.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in June from a thirty day period in the past, the Countrywide Association of Realtors documented yesterday. That was perfectly above what economists were being predicting, and a 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} drop from previous 12 months.
  • It was also the slowest speed given that September 2011 — apart from for the first two months of the pandemic, notes CNBC.
  • Meanwhile, mortgage loan programs are at their most affordable degree of exercise given that February 2000.

Information: House loan Bankers Association Chart: Nicki Camberg/Axios

What is actually subsequent: Selling prices are coming down in some pockets, and analysts assume that to continue on.

  • 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders reduced selling prices on new households in July, in accordance to study data from housing market place study organization Zonda.
  • “Some of the metro areas that captivated out-of-condition consumers early in the housing boom are cooling off the swiftest,” writes Nicole Friedman in the WSJ. Boise, Denver, Salt Lake Metropolis and Tacoma, Clean. all noticed the most value cuts in June, in accordance to Redfin facts she cites.

What they are declaring: “Exercise is now in cost-free-slide, inventory is rocketing, and price ranges have begun to fall,” Ian Shepherdson, chief economist at Pantheon stated in a take note. He’s been contacting this slowdown for a although.

  • This was not a blip: “We can assume ongoing downturn as we head into the second fifty percent of the 12 months,” mentioned George Ratiu, senior economist & manager of economic analysis at Realtor.com.

Zoom out: This is how the actual globe is reacting to what is going on at the Fed — mortgage charges jumped, and quickly homes had been even fewer cost-effective. However persons would like to get, they can’t.

  • You could say that the Fed “crushed demand from customers” for households, except persons however truly want households. The U.S. is struggling from a very long-time period housing lack.

“The problem in the housing market is that numerous People in america so desperately continue to want to personal a home,” Ali Wolf, main economist at Zonda, mentioned in a concept to Axios. “But climbing house charges and higher interest prices have pushed them to the restrict.”