When to increase your house budget and when to stick to your plan

When to increase your house budget and when to stick to your plan

Mikolette | E+ | Getty Photos

Prior to the pandemic’s red-sizzling housing market place, there was a simple profile that constituted an “A” buyer, in accordance to Brian Copeland, a real estate agent in Nashville, Tennessee.

“Four yrs in the past, an ‘A’ purchaser was anyone who was pre-skilled for a financial loan, experienced 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down and could go out this weekend and obtain a property,” mentioned Copeland, who is also president of the business affiliation Better Nashville Realtors. “Now, an ‘A’ buyer has all dollars.”

In addition, the top rated consumers right now are ready to waive appraisals and inspections and, in some situations, really don’t even see the home they’re acquiring in particular person, he explained.

Extra from Invest in You:
The greatest retirement scheduling guidebook for 2022
Why you should really start spending off debt now — and how to get started off
Inflation is costing U.S. households virtually $300 far more a month

“Everybody is getting squeezed,” said Copeland, incorporating that center-course cost-effective housing is “definitely struggling.”

Costs are likely up

Individuals are knowledgeable of the struggles they deal with in shopping for a dwelling. Extra than 70{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of U.S. grown ups believe the housing sector is at present in a bubble, and a lot more than 50 percent say it is a undesirable time to acquire a household, according to a survey of extra than 7,000 grown ups from Momentive.

Cost is a main factor that’s holding possible prospective buyers on the sidelines – some 38{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} stated they have delayed or canceled programs to get a house due to inflation. Individuals of coloration had been also a lot more probable to push off a property obtain thanks to mounting expenses, the study identified.

“Much more scuttled or delayed plans to purchase amongst these teams threatens to exacerbate already huge gaps in homeownership charges along racial and ethnic lines,” stated Jon Cohen, main investigation officer at Momentive.

In February, the median profits cost for properties in the U.S. was $357,300, a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase from a yr previously, according to info from the Countrywide Association of Realtors.

At the same time, home finance loan costs are also escalating, which means purchasers that need loans will pay out a lot more for them as well, stated Danielle Hale, chief economist at Realtor.com.

That can harm youthful consumers, as nicely as initially-time prospective buyers, in accordance to Hale. It also signifies that homeownership as a path to creating wealth is now out of achieve for several.

“It truly is a extremely competitive current market for individuals who are buying at the prime of their budgets,” explained Peter Murray, a real estate agent and the principal broker at Murray & Co. Authentic Estate in Frederick, Maryland. “You can find a good deal of disappointments.”

The money math

Some house owners may be tempted to extend their budgets to acquire a household, primarily if they have had months of exploring and getting outbid.

It can make feeling in some scenarios to stretch your price range, according to Marguerita Cheng, a accredited fiscal planner and CEO of Blue Ocean World Wealth in Gaithersburg, Maryland.

“There are scenarios when I have explained to persons it is all right to stretch, but just comprehend the effects that is heading to have on other places of your existence,” she said.

For case in point, it could make sense to spend slightly much more if relocating will reduce other expenditures, or if you happen to be anticipating life-style adjustments that will free of charge up room in your monthly finances. This could contain going from two vehicles to a person, or possessing young children who will soon enter community university, that means you’re no longer paying as substantially for childcare.

If you’ve calculated your spending budget applying your foundation salary, not which includes any bonuses, you may well also be able to find the money for a lot more, she mentioned. And, if you never have shopper debt, are sufficiently conserving for retirement and have a solid emergency fund, there may be much more wiggle space than you feel at first.

The amount of money of time you expect to shell out in the property also matters. If you might be hunting to live in a household for more than 5 several years, it may well make sense to pay a little bit additional now.

When not to stretch

On the flip side, there are some cases where it does not make perception to improve your homebuying budget.

Cheng states stick with your original plan if having to pay extra would make it challenging to contribute to other money goals, these as preserving for retirement or having to pay down credit card debt.

“If the only way that extend is heading to occur is if they borrow from retirement revenue, I would in all probability say that does not make feeling,” she mentioned.

If the only way that stretch is likely to take place is if they borrow from retirement revenue, I would in all probability say that does not make feeling

Marguerita Cheng

CFP, CEO, Blue Ocean Global Wealth

She also cautioned towards wiping out all your hard cash savings to manage a much more expensive residence. You require to budget for variable charges this sort of as taxes, insurance and repairs.

It also won’t make perception to extend your spending plan to a issue the place you can only afford it with tax breaks, reported Cheng. If those gains go absent in the upcoming, you are going to be in trouble.

What to do if you won’t be able to pay much more

Buyers who cannot extend their budgets have a handful of options.

“They either pause their house look for or they require to readjust their search standards,” mentioned Murray.

Stepping out of the buying market could possibly make sense for some who need to have far more time to help save. It could also be a undesirable idea, having said that — if rates go on to increase, you could be more priced out of the market place, explained Copeland.

That usually means rethinking your have to-haves might make additional feeling. That contains searching at various neighborhoods, such as types that aren’t as popular or may possibly be farther absent from metropolis facilities. They may well also want to be adaptable on the dimension or situation of the home they purchase.

They should really also have all of their paperwork prepared to go so that when they do see a property they like, they can make an offer suitable away, claimed Hale.

“To be competitive in this market place, you could throw more dollars at the difficulty or you could be seriously geared up and on best of it,” she reported.

Doing work with a monetary planner or advisor can aid homebuyers recognize what they can seriously afford to pay for to spend on a property, mentioned Cheng.

“The personal loan officer is going to be seriously valuable in helping you composition your bank loan, the real estate agent is going to assist you uncover a home,” mentioned Cheng. “You might think getting a financial planner is more than the major, but they are likely to truly assistance you see how this has an effect on your problem.”

Sign UP: Funds 101 is an 8-week finding out course to fiscal independence, shipped weekly to your inbox. For the Spanish model Dinero 101, simply click here.

Look at OUT: 74-calendar year-outdated retiree is now a model: ‘You really don’t have to fade into the background’ with Acorns+CNBC

Disclosure: NBCUniversal and Comcast Ventures are traders in Acorns.

How to Increase Your Rental Property’s Value (and Justify Higher Rents)

How to Increase Your Rental Property’s Value (and Justify Higher Rents)

With any financial commitment assets, you’re seeking to raise your price and improve eventual return on financial commitment (ROI). But with rentals? It is not just the extensive-term returns you’re looking at.

Improving your property’s price can justify better rents, much too — rising those people monthly revenue and your passive money stream as well.

Are you wanting to elevate your rents this year or just make improvements to your property’s worth and marketability? In this article are 4 points to contemplate.

Person on phone in front of for sale or rent sign.

Image supply: Getty Photos.

1. Devote in appliances

Owning a excellent fridge, washer, dryer, and dishwasher on-internet site can all justify greater hire selling prices and make your home more worthwhile. These also open the doorway to a wider web of tenants, as not as well lots of will convey their personal appliances, nor will most have the cash to get these valuables on their personal. 

If you’re anxious about affording appliances for your location, you can look to alternate resources, like outlet merchants, surplus suppliers, or even ReStores, which are low-expense supply retailers presented by Habitat for Humanity. Estate product sales, product household auctions, and on the internet equipment like Nextdoor and regional Fb teams can also be useful resources.

2. Update the kitchen

The kitchen area is by considerably a single of the most important spaces in a house — specially since the pandemic. It really is the place we eat a few foods a working day, and in scaled-down units, it may possibly even be where by we work, review, or do our research. For a tenant, it also may possibly be the place that puts your home more than the edge.

If your kitchen space is dated or just looks worn and exhausted, you could possibly look at a transform. You will not have to go mad, possibly. Updating the counter tops, refacing the cupboards, and installing appliances (see higher than) is generally plenty of to make an influence. In reality, in accordance to Remodeling Magazine, a “minimal” kitchen area transform is one of the optimum-ROI renovations you can choose on as a assets operator. In the extensive operate, it recoups about 72{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your costs and adds an normal of practically $19,000 to your eventual resale worth.

3. Replace the floors

If your property has aged carpet or dated linoleum, it could possibly be truly worth a fast update — preferably to anything a minimal much more timeless and sturdy. Undertaking so can make your home extra photogenic (i.e., greater listing photos) and a lot more marketable (who will not want a fairly home that requires less cleaning and upkeep?). 

Your very best bets are vinyl, hardwood, or laminate, while it actually depends on your home’s fashion, site, and spending plan. Converse to a actual estate agent in your space to locate out what types of flooring might be well-known in your spot. A regional contractor can also support you opt for anything that is long lasting for your area’s local climate. 

4. Incorporate extra dwelling house

You can charge appreciably additional for hire with an extra bed room, as this expands how lots of individuals can stay in the home (not to point out how many roommates can split the lease). 

Though this would not imply you ought to necessarily construct a tailor made addition or add a second ground to your home, it must get you pondering. Could you near off that loft location and increase your livable sq. footage? Is there a way to make your attic, basement, garage, or dining area a bed room (or even a grasp suite)? If so, will get some quotations from a contractor. If you can improve your hire by hundreds for every month, it just could possibly be worthy of it.

Rents are on the rise

Even with no some selection upgrades, it could however be time to consider about escalating your rents. Nationwide, rents are on the increase, and with housing inventory down and need up, a lot of would-be purchasers are acquiring by themselves pressured back again to leasing — even if just temporarily. There’s also inflation to take into consideration, which warrants a lease bump by default. 

Acquire some time to do a swift comparative assessment of rents in your spot. Are you nevertheless on par with what very similar houses are leasing for currently? If not, it might be time to feel about a alter.

Greensboro-High Point Saw a 10.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Increase in Home Improvement Loans | Business

Greensboro-High Point Saw a 10.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} Increase in Home Improvement Loans | Business


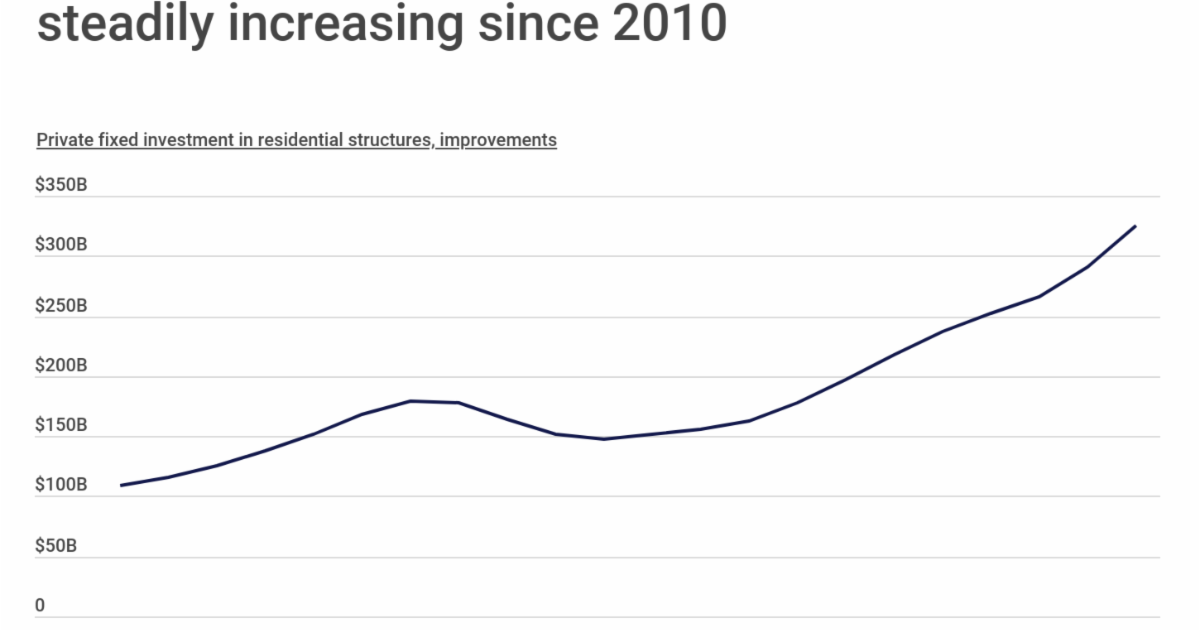
Chart1_Home improvement investments have been steadily increasing since 2010.png

As People hunkered down in their households in the early days of the COVID-19 pandemic—with remote function and university continuing into the foreseeable future—many started tackling dwelling improvement assignments. Demand for residence places of work, far more residing space, and nicer out of doors parts boomed. Interest charges also dropped to document lows, spurring lots of to get out home advancement loans. In accordance to bank loan-level mortgage loan facts from the Home Home loan Disclosure Act (HMDA), there have been virtually 480,000 regular, single-household property enhancement loans taken out in 2020 with a complete benefit of $54.5 billion.

Investments in property improvements commenced to fall through the housing crisis—and starting of the Good Recession—that started out in late 2007. Factors did not convert about right up until 2010, but house advancement expending has steadily enhanced given that then. The most the latest recession—the COVID-19 recession—lasted just two months, from February to April 2020, and differed markedly from the Fantastic Recession. Most notably, dwelling prices did not fall, but instead speedily enhanced in the aftermath. The mixture of growing home prices and file low curiosity charges gave homeowners accessibility to extra cash, as perfectly as the confidence that they would be able to recoup dwelling enhancement investments if they were to provide. In simple fact, residence enhancement spending attained file degrees in 2020. 

Home owners that took out loans to finance their property enhancement jobs in 2020 tended to expend additional on residence advancements for second residences and expense homes than on improvements to main residences. The median household enhancement mortgage total for principal residences was $65,000 in 2020, when compared to a median sum of $105,000 for the two 2nd residences and financial commitment houses. Residence enhancement investments in second households and financial commitment qualities can yield a larger return as a result of rental earnings or sale revenue when when compared to advancements to proprietor-occupied properties in which the proprietor does not intend to market.


Chart2_Homeowners tend to spend more on investment property improvements.png

Both equally the complete amount and price of property advancement loans fluctuate on a geographic basis. At the state amount, South Dakota house owners had the most significant increase in property advancement loans from 2019 to 2020, at +62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The median household improvement mortgage quantity in South Dakota in 2020 was $85,000, greater than the nationwide median of $75,000. Other states going through a sharp increase in home advancement loans include Idaho (+30.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Oregon (+30.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Utah (+24.{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

Interestingly, about fifty percent of states noted a decrease in dwelling enhancement loans from 2019 to 2020, probable due to huge quantities of self-financed property advancement jobs or property owners refinancing their existing mortgages to pay out for upgrades. Middle- and higher-income householders benefited massively from the stock and true estate market place booms, letting them to additional quickly find the money for household enhancement tasks without having to consider out household enhancement loans.


Chart3_South Dakota had the largest increase in home improvement loans.png

To establish the metropolitan regions with the greatest improve in household enhancement loans considering the fact that the COVID-19 pandemic commenced, scientists at Design Protection analyzed the most recent facts from the Residence Home loan Disclosure Act. The researchers ranked metros according to the share adjust in the full home advancement bank loan price from 2019 to 2020. Scientists also calculated the median financial loan total, the median curiosity fee, the median bank loan term, and the median residence worth. To improve relevance, only metropolitan regions with at least 100,000 people today were being involved in the examination.

The assessment found a 10.{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} boost in the complete home improvement financial loan value of Greensboro-Significant Stage metro residence advancement financial loans from 2019 to 2020. Right here is a summary of the knowledge for the Greensboro-Large Issue, NC metro spot:

  • Share adjust in the overall property advancement bank loan worth: +10.{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan quantity: $55,000
  • Median curiosity amount: 4.{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median mortgage term: 30
  • Median property benefit: $215,000

For more info, a comprehensive methodology, and finish results, you can uncover the unique report on Design Coverage’s site: https://constructioncoverage.com/exploration/towns-with-largest-maximize-in-residence-advancement-financial loans-2022

Cities With the Biggest Increase in Home Improvement Loans Since COVID-19

Cities With the Biggest Increase in Home Improvement Loans Since COVID-19

Photo Credit: Jaruwan Jaiyangyuen / Shutterstock

As Americans hunkered down in their homes in the early days of the COVID-19 pandemic—with remote work and school continuing into the foreseeable future—many began tackling home improvement projects. Demand for home offices, more living space, and nicer outdoor areas boomed. Interest rates also dropped to record lows, spurring many to take out home improvement loans. According to loan-level mortgage data from the Home Mortgage Disclosure Act (HMDA), there were nearly 480,000 conventional, single-family home improvement loans taken out in 2020 with a total value of $54.5 billion.

Investments in home improvements began to fall during the housing crisis—and beginning of the Great Recession—that started in late 2007. Things didn’t turn around until 2010, but home improvement spending has steadily increased since then. The most recent recession—the COVID-19 recession—lasted just two months, from February to April 2020, and differed markedly from the Great Recession. Most notably, home prices didn’t drop, but instead rapidly increased in the aftermath. The combination of increasing home prices and record low interest rates gave owners access to more capital, as well as the confidence that they would be able to recoup home improvement investments if they were to sell. In fact, home improvement spending reached record levels in 2020.

Homeowners that took out loans to finance their home improvement projects in 2020 tended to spend more on home improvements for second residences and investment properties than on improvements to primary residences. The median home improvement loan amount for principal residences was $65,000 in 2020, compared to a median amount of $105,000 for both second residences and investment properties. Home improvement investments in second homes and investment properties can yield a bigger return through rental income or sale profits when compared to improvements to owner-occupied homes in which the owner does not intend to sell.

Both the total number and value of home improvement loans vary on a geographic basis. At the state level, South Dakota homeowners had the biggest increase in home improvement loans from 2019 to 2020, at +62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The median home improvement loan amount in South Dakota in 2020 was $85,000, higher than the national median of $75,000. Other states experiencing a sharp rise in home improvement loans include Idaho (+30.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), Oregon (+30.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}), and Utah (+24.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}).

Interestingly, about half of states reported a decline in home improvement loans from 2019 to 2020, likely due to large numbers of self-financed home improvement projects or homeowners refinancing their existing mortgages to pay for upgrades. Middle- and upper-income homeowners benefited massively from the stock and real estate market booms, allowing them to more easily afford home improvement projects without having to take out home improvement loans.

To determine the metropolitan areas with the biggest increase in home improvement loans since the COVID-19 pandemic began, researchers at Construction Coverage analyzed the latest data from the Home Mortgage Disclosure Act. The researchers ranked metros according to the percentage change in the total home improvement loan value from 2019 to 2020. Researchers also calculated the median loan amount, the median interest rate, the median loan term, and the median property value. To improve relevance, only metropolitan areas with at least 100,000 people were included in the analysis.

Here are the metros with the biggest increase in home improvement loans.

Large Metros With the Biggest Increase in Home Improvement Loans

Photo Credit: Songquan Deng / Shutterstock

15. Orlando-Kissimmee-Sanford, FL

  • Percentage change in the total home improvement loan value: +4.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $85,000
  • Median interest rate: 4.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $335,000

Photo Credit: Henryk Sadura / Shutterstock

14. Grand Rapids-Kentwood, MI

  • Percentage change in the total home improvement loan value: +6.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $55,000
  • Median interest rate: 4.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 25
  • Median property value: $265,000

Photo Credit: Paul Brady Photography / Shutterstock

13. Milwaukee-Waukesha, WI

  • Percentage change in the total home improvement loan value: +6.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $55,000
  • Median interest rate: 3.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 25
  • Median property value: $305,000

Photo Credit: Sean Pavone / Shutterstock

12. San Antonio-New Braunfels, TX

  • Percentage change in the total home improvement loan value: +10.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $65,000
  • Median interest rate: 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 15
  • Median property value: $285,000

Photo Credit: Farid Sani / Shutterstock

11. Raleigh-Cary, NC

  • Percentage change in the total home improvement loan value: +11.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $65,000
  • Median interest rate: 4.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 25
  • Median property value: $365,000

Photo Credit: f11photo / Shutterstock

10. Dallas-Fort Worth-Arlington, TX

  • Percentage change in the total home improvement loan value: +11.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $95,000
  • Median interest rate: 4.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 20
  • Median property value: $385,000

Photo Credit: Chones / Shutterstock

9. Los Angeles-Long Beach-Anaheim, CA

  • Percentage change in the total home improvement loan value: +12.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $165,000
  • Median interest rate: 3.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $815,000

Photo Credit: photo.ua / Shutterstock

8. Salt Lake City, UT

  • Percentage change in the total home improvement loan value: +13.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $65,000
  • Median interest rate: 4.0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 20
  • Median property value: $435,000

Photo Credit: Lucky-photographer / Shutterstock

7. San Diego-Chula Vista-Carlsbad, CA

  • Percentage change in the total home improvement loan value: +13.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $125,000
  • Median interest rate: 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $755,000

Photo Credit: Steve Minkler / Shutterstock

6. Riverside-San Bernardino-Ontario, CA

  • Percentage change in the total home improvement loan value: +13.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $105,000
  • Median interest rate: 3.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $485,000

Photo Credit: Sean Pavone / Shutterstock

5. Phoenix-Mesa-Chandler, AZ

  • Percentage change in the total home improvement loan value: +17.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $75,000
  • Median interest rate: 4.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $385,000

Photo Credit: Jon Bilous / Shutterstock

4. Charlotte-Concord-Gastonia, NC-SC

  • Percentage change in the total home improvement loan value: +19.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $75,000
  • Median interest rate: 3.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $345,000

Photo Credit: LHBLLC / Shutterstock

3. Tucson, AZ

  • Percentage change in the total home improvement loan value: +23.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $85,000
  • Median interest rate: 4.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $275,000

Photo Credit: Roschetzky Photography / Shutterstock

2. Austin-Round Rock-Georgetown, TX

  • Percentage change in the total home improvement loan value: +33.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $95,000
  • Median interest rate: 3.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 20
  • Median property value: $455,000

Photo Credit: Bob Pool / Shutterstock

1. Portland-Vancouver-Hillsboro, OR-WA

  • Percentage change in the total home improvement loan value: +35.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan amount: $105,000
  • Median interest rate: 3.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
  • Median loan term: 30
  • Median property value: $465,000

Detailed Findings & Methodology

To determine the metropolitan areas with the biggest increase in home improvement loans since COVID-19 began, researchers at Construction Coverage analyzed the latest data from the Federal Financial Institutions Examination Council’s Home Mortgage Disclosure Act. The researchers ranked metros according to the percentage change in the total home improvement loan value from 2019 to 2020. In the event of a tie, the metro with the larger total number of home improvement loans in 2020 was ranked higher. Researchers also calculated the median loan amount, the median interest rate, the median loan term, and the median property value. To improve relevance, only metropolitan areas with at least 100,000 people were included in the analysis. Additionally, metro areas were grouped into the following cohorts based on population size: small metros: (100,000–349,999); midsize metros: (350,000–999,999); and large metros: (1,000,000 or more).


FOX28 Spokane©

Fishers mayor concerned about rental property increase

Fishers mayor concerned about rental property increase

FISHERS, Ind. — A increase in rental houses in Fishers has caught the interest of Mayor Scott Fadness who is worried about the impression of that boost.

Over the last five years, virtually 1 out of 10 properties obtained in the metropolis has been transformed in to a rental home.

“Of that one particular thousand just about 33{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of those people were being bought by entities that had been out of state,” Mayor Fadness stated.

Individuals numbers arrived from a modern analyze commissioned by the metropolis. Fadness mentioned all those companies are primarily based in locations like California, Georgia and New Jersey.

“What’s going on now is Wall Avenue is shifting in purchasing these residences at a rate that most folks can’t compete with and turning it into a rental,” Mayor Fadness reported. “The individuals that go into people homes now and shell out lease will never accomplish the opportunity to deliver or accumulate wealth.”

Fadness’ major fears are around the lack of economical housing this trend could make, as very well as the opportunities it could get away from 1st-time household customers.

“It produces an rigorous battle since folks who may possibly be low to reasonable profits are looking for starter households. To start with-time homebuyers essentially are competing towards financial investment companies,” mentioned Amy Nelson who serves as the govt director of the Honest Housing Middle of Central Indiana.

Nelson stated these substantial firms are capable to out-bid prospective consumers, leaving much less solutions.

“These financial investment firms are coming with all hard cash presents and a usual customer is not likely to be ready to contend with that,” Nelson said.

Nelson explained there has been a deficiency of funding dedicated to reasonably priced housing in Indiana. She’d like to see legislators raise the income circulation toward those people efforts.

“We have the cash to do it. COVID-19 pandemic cash is coming and our state has a really potent surplus,” Nelson claimed. “Why aren’t we utilizing that to ensure that folks have security in housing?”

Legal guidelines handed in new many years by the common assembly have designed it almost unattainable for municipalities to control landlords. Nevertheless, Mayor Fadness explained he’s confident the metropolis can get something completed.

“I still imagine there is another opportunity to operate with our point out legislature and think via what are some opportunity options to this,” Fadness stated.

Nelson inspired men and women to ask their elected associates about housing issues before casting a ballot in this year’s elections.

We did attempt to attain the Central Indiana True Estate Investor’s Association for remark but we’re however ready to hear again.

You can see a total duplicate of the examine below:

DoD’s average housing subsidy sees big increase as real estate continues to get pricier

DoD’s average housing subsidy sees big increase as real estate continues to get pricier

The average amount of housing subsidies the Defense Department will give out to service members in 2022 is increasing substantially compared to previous years.

The Pentagon says the mean increase of basic allowance for housing (BAH) will go up by 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, a wide jump from the past two years, which have averaged just below 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. DoD will spend $25.6 billion on BAH for 2022.

Depending on grade and dependency status, service members will see BAH go up by a range of $74 to $168. Allowances will not decrease.

“The department is committed to the preservation of a compensation and benefit structure that provides members with an adequate standard of living to sustain a trained, experienced, and ready force now and in the future,” DoD wrote in a Wednesday press release.

It’s important to note that the BAH increase is only an average. Some service members may not see the full 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase; others could see allowances even higher than that.

“The Department collects rental housing cost data annually for approximately 300 military housing areas in the United States, including Alaska and Hawaii,” the release states. “Median current market rent and average utilities (including electricity, heat, and water/sewer) comprise the total housing cost for each military housing area and are included in the BAH computation. Total housing costs are developed for six housing profiles (based on dwelling type and number of bedrooms) in each military housing area. BAH rates are then calculated for each pay grade, both with and without dependents.”

Part of the reason for the hefty increase in BAH may be because housing and rental prices rose in 2021 and 2020.

According to Redfin, a real estate brokerage firm, the median sales price for a house increased by 13.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} when comparing settlements from October 2020 to October 2021. Sales prices increased 14{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from October 2019 to October 2020.

Meanwhile, the number of homes for sale is down nearly 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 44.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of houses sold over their listing price.

The housing market became so competitive last year that DoD temporarily increased BAH in 56 areas for the last quarter of the year.

“Rental housing market data collected by the Department of Defense from March-August 2021 indicates that the COVID-19 pandemic has had a significant impact on rental housing costs in the 56 affected markets. Notably, low availability and turnover of rental housing stock during the spring and summer months led to rental cost increases in many locations,” a DoD September release read.

The 2022 BAH rate supersedes those temporary increases.

According to Redfin, some of the areas with the fastest growing sales prices are cities in Florida and Arizona, as well as Detroit. The military has multiple bases in all of those areas.

Lawmakers have recently had some concerns about BAH. The 2022 Defense Authorization Act requires a report from DoD on whether BAH is sufficient enough for an average military family.