U.S. genuine estate has gone through a extraordinary slowdown in transaction activity in the months considering that the Federal Reserve began jacking up desire fees.
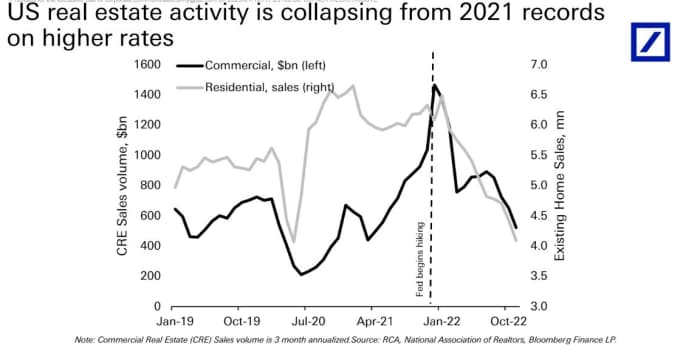
Income of present residences plunged from peak pandemic stages to about 4.1 million in November (see chart) from over 6 million units offered per calendar year in 2021 as the Fed has radically raised desire charges to tame inflation.
U.S. genuine estate transaction quantity has collapse with higher prices
Deutsche Lender, RCA, Nationwide Association of Realtors, Bloomberg Finance
Likewise, the chart demonstrates industrial real estate transactions dropping off a cliff after they rose 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increased than their prior peak in 2019, according to a new shopper be aware from Deutsche Bank investigation.
“Real estate is one particular of the crucial levers the Fed can use to slow the overall economy higher costs are significantly cutting down US authentic estate exercise,” a Deutsche analysis team led by Ed Reardon wrote in a weekly market place briefing.
They also mentioned that property finance loan premiums of about 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in both sectors will let the Fed “to unwind some exuberance” in the housing marketplace, exactly where charges climbed about 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} considering the fact that March 2020 and around 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in commercial actual estate.
Connected: The occasion is more than in professional genuine estate. Here’s what to expect in 2023.
The Fed started fast increasing its plan desire price from in close proximity to-zero in March to assist convey inflation that peaked above a 9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yearly rate this summer time nearer to its 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} goal. Its federal cash level was increased to a 4.25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 4.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} vary in December, the optimum given that 2007, with yet another level bump envisioned in February.
Before this week, San Francisco Fed President Mary Daly claimed she expects the central bank to raise desire costs earlier mentioned 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to get inflation down. A new monthly update on consumer inflation due Thursday is envisioned to clearly show inflation slipping for 6 months in a row to a 6.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yearly amount.
U.S. stocks have staged a modest rally to commence 2023 as some investors interpret retreating price pressures and moderating wage gains as indicators that the economic system may possibly nevertheless keep away from a economic downturn, even though central bankers hold expressing to hope high prices until finally inflation deeply recedes.
Examine: Inflation is slowing, CPI to show. But is it slowing quick sufficient for the Fed?
The S&P 500 index
SPX, +.34{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
was up .7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on Wednesday ahead of Thursday’s inflation reading through, when the Dow Jones Industrial Ordinary
DJIA, +.64{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
was up .4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and the rate-delicate Nasdaq Composite Index
COMP, +8.98{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
was 1.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} higher, in accordance to FactSet.
America’s house prices could plunge as a great deal as 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} due to the sharp rise in mortgage loan rates in 2022, which are greatly rising household ownership costs and “enhance the odds of a significant household cost correction,” in accordance to investigation from the Federal Reserve Financial institution of Dallas.
To be sure, the potential for the nation’s properties to drop as a great deal as a single-fifth of their price represents a “pessimistic state of affairs,” Dallas Fed economist Enrique Martinez-García noted in a report on Tuesday. But other economists have signaled equivalent fears, with Pantheon Macroeconomics Chief Economist Ian Shepherdson before this yr predicting a identical slump in household costs.
The pandemic made an unconventional elixir for the authentic estate sector, with record-small home finance loan fees and operate-from-home orders whipping up a surge in desire for home possession. At the peak of the industry, some customers even waived classic contingencies such as inspections and supplied tens of 1000’s of pounds in excess of asking price ranges in get to get their bids — a “concern of missing out” mentality that fed into a “bubble,” Martínez-García reported.
A steep drop in housing selling prices would probable have a ripple influence on the broader financial state as effectively as further undermine the real estate sector. If residence prices dropped 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, beneath Martínez-García’s pessimistic situation, personalized intake could fall by .5 to .7 a share point, he believed.
“These kinds of a negative prosperity effect on aggregate desire would further more restrain housing demand from customers, deepening the selling price correction and setting in movement a unfavorable suggestions loop,” he cautioned.
Large home loan premiums generate down household income
02:09
Home loan charges have jumped from about 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January to about 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} currently, moving in tandem with the Federal Reserve’s 6 amount hikes this yr. The central lender would like to tame the maximum inflation in 40 yrs by raising the charge of borrowing, which ought to temper demand from businesses and buyers.
Preferably, the Fed will “cautiously thread the needle of bringing inflation down with out placing off a downward property-cost spiral — a substantial housing offer-off that could irritate an economic downturn,” Martínez-García wrote.
Household charges rose a overall of about 61{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} among 2013 and 2022, following altering for inflation — a soar that outpaced the preceding housing bubble from 1998 to 2007, in accordance to his calculations.
Higher home finance loan costs must decrease the chance that the present-day “increase” in property price ranges will keep on, Martínez-García included.
Demand rises for adjustable-rate mortgages
04:15
For now, housing charges are nevertheless rising. The national median price tag for an current single-family dwelling rose 8.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the third quarter, reaching $398,500, according to the Nationwide Association of Realtors. Continue to, the charge of selling price increases is slowing, offered that home costs jumped 14.2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the second quarter, the industry group said previously this thirty day period.
Extra purchasers are having priced out of the market place since of the mixture of growing property rates and bigger mortgage loan prices. The median revenue now essential to purchase a usual dwelling is now $88,300, or about $40,000 much more than was needed prior to the pandemic in 2019, NAR claimed.
The industry is specially tough at the second for very first-time consumers. Mainly because of the spike in mortgage rates, a purchaser of a common starter residence value about $340,000 who set 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down would encounter a every month mortgage payment of $1,808 — about $600 far more than a yr ago, in accordance to the group’s calculations.
NAR Main Economist Lawrence Yun predicted previously this thirty day period that residence revenue will slip by 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} future 12 months as far more people are priced out of the market, but explained he expects the median residence value will increase 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. One particular cause he would not anticipate price ranges to slide: Stock continues to be limited, which means that customers are nevertheless competing for attractive attributes.
Home loan rates are skyrocketing thanks to the Fed, but potential buyers who can rough out this tough, altering market will be rewarded.
The 30-year fastened-rate mortgage averaged 5.27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for the 7 days ending May possibly 5, in accordance to info unveiled by Freddie Mac
FMCC, -1.62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}
on Thursday. That’s up 17 basis details from the earlier 7 days — one particular basis level is equal to 1 hundredth of a percentage level, or 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
This represents the maximum level for the benchmark 30-calendar year house loan products given that August 2009. To set that in context: The very last time mortgage loan rates ended up this substantial Barack Obama was just months into his initial phrase as president, the country was in the depths of the Good Recession and Instagram experienced still to be launched.
“The last time mortgage loan charges ended up this higher Barack Obama was just months into his initial phrase as president, the country was in the depths of the Terrific Economic downturn and Instagram had but to be launched.”
The common fee on the 15-12 months fixed-amount home loan rose 12 foundation points about the earlier week to 4.52{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. The 5-yr Treasury-indexed hybrid adjustable-rate property finance loan averaged 3.96{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, up 18 foundation details from the prior 7 days.
Home finance loan premiums are roughly benchmarked to the generate on the 10-calendar year Treasury be aware
TMUBMUSD10Y, 3.127{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
But the change among the normal level on the 30-calendar year mortgage and the 10-yr Treasury has widened not long ago.
Considering the fact that the conclude of the Excellent Economic downturn, the spread involving the two has averaged 1.7 share details, but presently it hovers higher than 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. If the spread had been closer to historical stages, the 30-calendar year set-fee mortgage loan would however be underneath 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
The Federal Reserve is mostly to blame for the point that mortgage costs enhanced at a more quickly speed than may possibly otherwise be envisioned, according to assessment from Odeta Kushi, deputy main economist at title insurance company Initially American
FAF, +.29{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
Investors who purchase property finance loan-backed securities have previously factored in expectations that the Federal Reserve will carry on to raise prices in the course of this 12 months into their view on the mortgage loan current market.
Lenders, therefore, ought to hike the costs they provide customers so that they can carry on to sell their financial loans to traders — people sales are what generates the funds applied to deliver much more home loans.
“While some additional Fed tightening is previously baked into today’s regular house loan premiums, ongoing inflationary tension remains probable to force mortgage loan prices even bigger in the months to come,” Kushi claimed.
Hiking limited-phrase desire charges is not the only way the Fed influences the mortgage marketplace. The central financial institution by itself has been a purchaser of mortgage-backed securities considering that the start out of the pandemic. So now that the Fed will be shrinking its balance sheet of bonds, together with these securities, there could be an influence on liquidity in the mortgage loan market. Lenders would will need to make up the big difference by increasing fees.
Already current housing-market details has proven the massive outcome the surge in rates has experienced on residence prospective buyers. “The pandemic boom in house revenue is around, and exercise is again at pre-pandemic ranges,” Mizuho Securities U.S. economist Alex Pelle and main U.S. economist Steven Ricchiuto wrote in a study be aware.
It’s obvious that the affordability troubles posed by increasing fees and higher charges has cooled demand among property prospective buyers. Nonetheless, house listings continue being several and significantly amongst. That suggests that property selling prices probably will carry on to develop — albeit at a slower pace — due to the fact even with a reduced pool of customers there aren’t plenty of properties to grow all around, analysts say.
And there is the likely that growing interest charges could also put a damper on the provide of properties for sale. “Existing householders are amount locked-in when their existing mortgage rate is beneath the prevailing marketplace home finance loan level, mainly because there is a economical disincentive to offer their residences and purchase a new property at a larger mortgage fee,” Kushi said.
Most economists foresee that the housing market place is balancing out, meaning that bidding wars and contingencies could soon grow to be a issue of the earlier.
Marcus & Millichap CEO Hessam Nadji joins Yahoo Finance Reside to talk about the outlook on the genuine estate marketplace, housing revenue expansion, anticipating the Fed’s desire amount hikes for renting and homebuying, and the most sought after true estate marketplaces.
Online video Transcript
EMILY MCCORMICK: As the broader industry carries on to languish in the red this afternoon, let’s get a check out of true estate shares. This early morning, existing house sales came in substantially greater than predicted, in simple fact, achieving the highest stage in a year at a seasonally altered annualized charge of $6 and 1/2 million. That was superior for a 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} month more than month raise. Now on the heels of that, the S&P 500 authentic estate sector, as you can see on the monitor, is even now reduce on the working day, but also off session lows and also outperforming the broader S&P 500.
Now for the 12 months-to-day, nevertheless, the sector is nonetheless the worst performer following communication companies, with potential clients of increased fascination premiums weighing on several actual estate stocks. But taking a search at two homebuilders specially, we are looking at shares of KB Dwelling, as well as Toll Brothers, coming effectively off session lows. Toll Brothers shares have really now turned good. So one particular aspect of the current market that we are continuing to observe intently is that real estate sector.
RACHELLE AKUFFO: Well, plenty of details there. We know that present house gross sales jumped 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in January to a seasonally altered once-a-year level of $6.5 million. Now this also arrives amid record lower stock, with houses typically receiving snatched up in a working day or two, and leaving a lot less affluent prospective buyers out in the chilly. Perfectly, to crack down what is actually happening with the housing sector, let’s welcome Hessam Nadji, Marcus & Millichap CEO. Thank you for joining me.
HESSAM NADJI: Thanks for acquiring me on the program.
RACHELLE AKUFFO: So I want to very first start by finding your reaction to some of this facts. Clearly, hunting at this 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} surge in present home product sales. Median present residence selling price is up 15.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on the calendar year to $350,000. In this competitive current market, though, what options do you see?
HESSAM NADJI: Very well, first of all, the amount is not shocking, given the developments that we’ve observed above the previous calendar year, in that the housing market place has experienced a offer lack. Compared with the 2008, 2009 disaster, in which overspeculation experienced in fact produced a wide vast majority of the credit challenges that led to that downturn and a recession, real estate on this aspect of the cycle has basically been a contributor. And you will find been no oversupply in housing or in business authentic estate.
And of system, the impact of the pandemic has produced so significantly demand from customers for people to get the job done from property, grow their residing areas, and so on. We’re viewing the same phenomenon have out in condominium rentals, which are also registering history demand from customers and hire advancement.
So the place does it go from here? We do have some problems in that affordability is turning out to be an issue. A lot less and much less people will be capable to afford the 15 and 1/2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 16{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} value maximize that you just outlined on a 12 months about yr foundation. On major of that, as curiosity rates go up, of system, that affordability becomes even far more acute.
But the source side of the equation is nonetheless constrained by the offer chain difficulties, labor expenses, and so on. So, yet again, supply-need is going to be quite balanced. We never count on price ranges to keep on growing for the for-sale market place at the exact rate they have been, so some cooling off of costs. But however, the market is relatively stable.
On the industrial true estate facet of the equation, simply because of minimal fascination costs and the reality that industrial true estate as an investment decision auto has always been viewed strongly as an inflation hedge, we keep on to see document demand from buyers wanting to commit in flats, place of work properties even, buying facilities, and in self-storage belongings, every group of professional serious estate.
RACHELLE AKUFFO: So then as we talk about the Fed below, you reported that a significant fast increase in desire costs by the Fed could weigh on professional serious estate financial commitment. What sectors are the most exposed? And how are you advising your clients to genuinely brace for probably four to 7 level hikes this calendar year?
HESSAM NADJI: Perfectly, to start with and foremost, you have to recall, the 10-year Treasury yield has previously ran up very a little bit this yr, and the sector has altered relatively very well. Loan provider spreads have occur in, and what is seriously crucial for commercial genuine estate investments and valuations is the pace by which desire fee raises are achieved with hire development increases. If the profits and occupancy of these belongings are wholesome and developing at, at least the identical rate, if not more rapidly, than the amount of improves in interest charges or the price of debt, valuations are well supported.
So much, which is what we are viewing. The major chance is if the Fed goes way too far too fast or has to respond even far more aggressively than anticipated to essentially struggle inflation. And I consider we need some time to see if that is heading to be needed or not. Let us not ignore that we’re coming off of a significant recovery in careers very last yr. Now the rate of work progress is slowing. Therefore wage progress really should in all probability start out to crest a bit. And the source chain at some position is going to start out easing again. So it is really not a foregone conclusion that the Fed will have to actually overplay its hand.
RACHELLE AKUFFO: Now I want to communicate far more about professional actual estate and, really, the file breaking total of expenditure, we observed very last yr. Buyers bought far more commercial genuine estate in 2021 than at any time ahead of and a record $335 billion just into flats throughout the United States last 12 months. But then you also have renters who want to turn into first-time potential buyers because the rents are rising and a whole lot of leases are coming to an stop. So what is your outlook for the condominium market place in 2022? And what are some of the headwinds that you’re looking at for?
HESSAM NADJI: The outlook for residences is very sturdy for the reason that as I pointed out earlier, the for-sale housing affordability situation is going to grow to be much more of a problem. If you look at some of the metros like Austin or Salt Lake Town, Phoenix, Los Angeles even, San Jose, the Inland Empire here in Southern California, they’ve registered price increases of this 19{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 28{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on a calendar year over yr foundation. A good deal of buyers are likely to get priced out of the for-sale housing market place and will have to proceed leasing.
And a ton of buyers, we’ve seen above the final five yrs, pre-pandemic, definitely were deciding upon to be renters, to have the versatility and the way of life that they have appreciated as renters. And the apartment improvement group has responded by creating products that the 30 somethings, 40 somethings, partners with out children or empty nesters truly want to rent. Individuals developments have captured extra renters than ever in advance of. And for all those factors, the outlook for flats is rather strong for 2022 and really– and outside of.
RACHELLE AKUFFO: And talking of traits, we are looking at obviously Omicron-similar COVID premiums continuing to drop in the US. We are looking at a return to both in-person operate or some kind of hybrid function from property, in-man or woman model. What are you watching for in the office environment market? And what are you seeing with the most effective and worst executing markets for vacancies?
HESSAM NADJI: The office environment market still has a ton of cloud in excess of it, specifically in city The united states, wherever the vacancy fees are continue to pretty substantial. And of training course, the pandemic impacted city markets a lot extra severely than suburban markets. And the outmigration that we have found was happening even in advance of the pandemic. The millennials that were being genuinely fueling the demand from customers for city housing and qualified services work opportunities, workplace employment, were being beginning to enter their 30s, forming people. 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of them are now in their 30s. And they were being presently moving to the suburbs before the pandemic, and the pandemic, of training course, accelerated that trend.
So the place of work outlook is considerably combined in that you even now have leases on regular in put wherever the tenant has to pay back the hire for an additional four decades. So we have loads of time for there to be a restoration in demand from customers. But public transportation, having persons comfy to come back again into the office environment is likely to consider some time. We believe that it’ll materialize around time, but the hybrid alternative, office solution is listed here to keep. We are encountering it. Just about every a person of our purchasers, in some approaches, is enduring it. So it will minimize workplace space demand.
But let us not overlook that spots like New York, Los Angeles, in which the foremost job creators in the last 12 months– 300,000 jobs in LA, 200 furthermore thousand positions in New York. Dallas was the third major task creator. So the city marketplaces are commencing to arrive back again. And I feel enterprise formations that we are viewing at history stages will finally bring new desire to the office environment current market. But it is heading to be a bit of a transition. And we’re viewing a large amount of opportunistic investors acquire advantage of office right now being the diamond in the rough.
RACHELLE AKUFFO: We are going to surely have to maintain an eye on that. We are going to have to depart it there. Thank you so much. Hessam Nadji there, Marcus & Millichap CEO, thank you so significantly.
Program to obtain a household in 2022? The very good news is that ailments will not quickly get out of manage the way they did past year. The terrible news is that source stays tight and rates are nevertheless on an upswing — and the probability of greater mortgage prices looms on the horizon.
Actual estate pros say the true estate marketplace this year will not match the fever pitch it achieved in 2021, and the pace of property sales this 12 months will be significantly much less frenzied. “As we transfer via the 12 months, we will see slower revenue exercise,” explained Lawrence Yun, main economist at the Nationwide Affiliation of Realtors. “Intense several-provide times are over… persons can choose their time.”
“There’s no expectation that charges will drop, but our forecast suggests that cost appreciation will slow,” mentioned Doug Duncan, senior vice president and chief economist at Fannie Mae. Duncan predicted that even though prices will not repeat the meteoric 18 {d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increase they sustained previous calendar year, they will nonetheless rise somewhere in the neighborhood of 7.5 per cent. “That’s not much of a breather, especially for the reason that fascination premiums will be mounting at the similar time,” he pointed out.
There’s no expectation that prices will slide, but our forecast suggests that price appreciation will sluggish.
Other gurus have a little bit reduced projection for rate appreciation, but no just one sees a reversal any time soon. “We haven’t witnessed the fundamentals transform to point out that rates are going to come down,” claimed Robert Frick, company economist for Navy Federal Credit score Union. “Prices are continue to going to go up this calendar year,” he mentioned, despite the fact that he also stated the fee of boost is possible to amazing immediately after very last year’s torrid double-digit jumps.
As soaring need sent price ranges into the stratosphere last calendar year, would-be homebuyers generally found themselves in bidding wars, or were compelled to make a snap conclusion on the most important economical determination of their life. The success of a December study propose that home-hunters have tempered their optimism, or could possibly choose to remain on the sidelines for the around upcoming: The Fannie Mae Residence Purchase Sentiment Index discovered that while 76 p.c of all those surveyed reported the current is a very good time to market a house, just 26 p.c reported it is a superior time to get. By comparison, 52 percent of respondents experienced characterized the present-day market place as a fantastic time to invest in a property a calendar year before.
“There’s nonetheless a lack of houses for sale, so it is a seller’s current market, but the residences that are overpriced are tending not to transfer,” reported Ralph DiBugnara, CEO of Property Certified, an on the internet authentic estate details and lending useful resource.
“I believe for the property sellers, they need to understand the days of double-digit value appreciation are over,” Yun reported. If persons are mulling a sale, he additional, “They should do it based mostly on regular aspects somewhat than trying to speculate on large price gains.”
Residence sellers require to understand the times of double-digit rate appreciation are in excess of.
These changes are unfolding towards a backdrop of fascination charges rising as the Federal Reserve targets inflation in a major way. Earning it additional expensive to borrow tamps down demand in the combination and can assist rein in inflation, but what can be great for the economy on a macro level can be unpleasant for unique consumers, who will discover on their own paying out a lot more to provider their mortgage debt.
As a end result, some experts have predicted that before the marketplace normally takes a breather this 12 months, there will be a sturdy 1st quarter as people test to lock in lessen house loan pricing. The charge for a conventional 30-year mortgage loan is currently hovering all over 3.5 percent. Many authentic estate professionals forecast that this will rise any where from a half to a entire proportion level by way of 2022.
“It’s seriously dependent on what the Fed states and does,” Duncan said. The central bank’s contribution to greater mortgage charges is partially mainly because of a increased Federal Resources level, but extra importantly, it is a purpose of the Fed paring back its pandemic-period economic support.
This support bundled getting billions of dollars in mortgage bonds every single month, purchases that will terminate by March. In a press convention final week, Fed Chair Jerome Powell explained officers expect to talk about before long how to shrink that part of the Fed’s portfolio. Marketplace members will be on the lookout to policymakers for extra guidance on regardless of whether the Fed elects to simply just not repurchase new house loan securities as the types on their balance sheet experienced, or actively seems to be to promote some of all those holdings — an acceleration of the sector exit that would be likely to have a additional abrupt impact on borrowing rates.
“They could call for far more yield,” Duncan explained of the more bottom-line oriented home finance loan financial debt buyers that will continue being adhering to the Fed’s exit. “The Fed is a policy purchaser, not an financial consumer.”
“From a property finance loan pricing perspective… I would say there is going to be a more robust effect from the exit of the bond purchases,” explained Steve Kaminski, head of residential lending at TD Financial institution. “We don’t know wherever prices will conclusion up, but we do have a clear indicator that the Fed intends to improve rates right here,” he stated.
As the Fed tempers its before prodigious appetite for property finance loan-linked personal debt, the current market will have to modify accordingly. “Their prepare is to exit the house loan-backed safety current market by March. I do assume the March-April time frame for that level boost to be a small extra obvious,” Kaminski reported.
If there is a slowdown in homebuying exercise this yr, one particular silver lining for debtors is that the similar number of mortgage loan creditors will be hunting for business enterprise among the a lesser pool of consumers, Duncan mentioned. “A tiny little bit of a moderator on the charge rise will be the simple fact that house loan loan companies …. will compete and the profit spreads they’ll take will shrink,” he mentioned.
But on equilibrium, professionals say the challenges remain acute for to start with-time customers. “The issue for first-time homebuyers is there are not more than enough residences for sale at competitive selling price factors. They’re seeing bidding wars on most houses. Very first-time homebuyers have to be eager to compromise,” DeBugnara explained, whether that indicates on square footage, spot or other characteristics.
Buyers — both of those first-timers as very well as people today in search of to downsize — will also continue to face levels of competition from institutional potential buyers, which have aggressively targeted the so-termed starter house market in purchase to hold individuals qualities and hire them out. And with house charges as effectively as rents increasing, it will become much more tricky for folks who want to possess and dwell in their personal households to split in to the marketplace.
“You have corporate entities shopping for homes to rent, which is further reducing the availability of homes… 17 percent of new residences are likely to be corporate-owned to hire,” Frick stated. “We’re obtaining shut to a stage where by 1 in 5 houses is essentially staying taken off the ownership marketplace for lease,” he stated.
We’re finding near to a position where a person in 5 residences is effectively becoming taken off the possession market place for lease.
“We’re going to see for confident the prices of rents expanding for the up coming handful of years. A great deal of these more substantial cash are scooping up solitary-relatives homes in bulk,” DiBugnara said. “I’m deciphering that as they believe there’s heading to be very large demand from customers for single-family members homes.”
When new residences are remaining designed, experts say it isn’t occurring speedy more than enough. Even ahead of the pandemic, new house development was failing to retain rate with demand from customers, and Covid-19 has saddled builders with a mix of shortages and climbing fees for the two supplies and labor.
For a longer period time period, experts say the offer pipeline is improving. “We expect that in the new household house, begins will increase about 7 p.c,” Duncan stated. “The builders are accomplishing anything they can. If they can get the land, labor and lumber, they’ll build.”
“I’m inspired that we’re heading to see numerous a lot more new homes designed in this year,” Frick stated. “Some of the source constraints are easing as significantly as materials go. The other matter which is essential is that builders are purchasing a whole lot of land,” he explained. But until the sector reverts to a point out that extra intently resembles historical norms, and right up until additional new stock is available at major scale, Frick warned that the desire of homeownership is fading for households on the margin.
“We have to remember, for middle-income people, their most important way of accumulating prosperity is homeownership,” he reported. “Home rates are pushing homeownership absent from 1st-time and decrease-income homebuyers at an alarming rate.”
A mall giant and a nursing home REIT could benefit from more public spending, two Fools parse out residential iBuying, why UWM stock surged today, outer space commercial real estate, and don’t sleep on the pandemic.
Two REITs that would benefit from the government putting more money into the economy
With an infrastructure bill now signed into law and a huge package addressing social spending and climate change passed by the House today, now might be a good time to look at real estate investment trusts (REITs) that could benefit from more government money going into the economy.
Motley Fool contributor Reuben Gregg Brewer picks out mall giant Simon Property Group(NYSE:SPG) and senior housing specialist Omega Healthcare Investors(NYSE:OHI) as beneficiaries of more cash flow to consumers in general and the hard-hit nursing home niche. There certainly could be more.
(Image source: Getty Images.)
Two major red flags with Zillow’s iBuying failure
Zillow(NASDAQ:ZG)(NASDAQ:Z) recently surprised investors by announcing that it plans to exit the iBuying business entirely, despite having promoted it as the biggest future growth driver of the company. In this Fool Live clip, Fool.com contributors Matt Frankel and Tyler Crowe discuss two of the biggest red flags they see with this move.
Matt and Tyler parse out what happened, as the company with perhaps the most residential real estate data of all couldn’t do better with its number-crunching, and how rivals Opendoor and Offerpad could do better with this new way of buying.
Why shares of UWM stock surged today
Shares of mortgage originator UWM Holdings(NYSE:UWMC) had jumped more than 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} as of 2:40 p.m. ET after the company said it had decided not to go through with a planned secondary offering. UWM also said that it would “accelerate” its previously announced share repurchase program.
Motley Fool contributor Bram Berkowitz says it seems a bit wonky to announce a secondary offering and then reverse course two days later. But market conditions have not been easy this week, and at the end of the day the accelerated repurchase plan will make existing shares more valuable, so shareholders are not complaining.
Bezos planning “Space Business Park”: Is this the next real estate investing frontier?
Jeff Bezos’ Blue Origin has partnered with several aerospace interests to create the first commercial business park in space: Orbital Reef. They plan to have it up and running by the end of the 2020s, just in time to replace the soon-to-be decommissioned International Space Station (ISS).
Motley Fool contributor Kristi Waterworth also notes here that as futuristic and far-fetched as a business park in space may sound, Bezos’ team isn’t the only one determined to create the world’s longest commute. Lockheed Martin(NYSE:LMT) has teamed with other space hopefuls to race Blue Origins to space with its Starlab.
Pandemic resurgence may be slipping under the radar here but shouldn’t be
Nations across Europe are ramping up their fight against COVID-19, up to full lockdowns, as the delta variant drives up cases and casualties. Bloomberg points out in a post today that the word “lockdown” doesn’t appear at all in Goldman Sachs’(NYSE:GS) and Morgan Stanley‘s (NYSE:MS) outlooks for Europe now out for 2022, and a survey of fund managers by Bank of America(NYSE:BAC) places the virus fifth on its list of risks to markets.
The holidays and flu season are here, and COVID-19 doesn’t appear to be as threatening to many right now as inflation, but real estate investors need to be alert to changes that could send people back home from stores, restaurants, and offices.
This article represents the opinion of the writer, who may disagree with the “official” recommendation position of a Motley Fool premium advisory service. We’re motley! Questioning an investing thesis — even one of our own — helps us all think critically about investing and make decisions that help us become smarter, happier, and richer.