Real estate private equity fund managers are typically accustomed to obtaining financial statement audits of the fund, and it is important to know that stand-alone audits of the lower-level property investments can be just as relevant and important.
In a typical real estate private equity fund structure, each investment property is commonly held in an LLC governed by its own operating agreement. These LLCs are may also hold the related mortgages on the properties. The most common reasons for obtaining a property audit are as follows:
Requirement in the operating agreement of the LLC
Requirement by the lender in the mortgage loan agreement
Fund manager wants a level of assurance related to:
Accuracy of property management’s accounting records
Financial records used for comparability across the portfolio
Net operating income used in fund valuations
Unlike the specialized accounting and reporting requirements for investment companies under Accounting Standards Codification Topic 946 Financial Services – Investment Companies, property level financial statements often have more flexibility in selecting the basis of accounting. When an entity’s accounting method is not dictated by a governing body, the fund manager should consider which basis is a more beneficial financial management reporting tool and the impact this basis has on the property’s financial results and presentation. Some of the different financial reporting method include:
Generally accepted accounting principles (GAAP)
Income tax basis
International financial reporting standards (IFRS)
Special purpose basis of accounting
There are different accounting requirements under each basis that should be considered before choosing which basis to select.
There are several things a fund manager can do to prepare for and facilitate a successful property level audit:
Designate an audit point person from your team.
Understand the significant accounting cycles and obtain and/or prepare a write-up of the major business processes and internal controls at the property.
Evaluate whether the internal controls are effectively designed and implemented.
Obtain and/or develop and prepare a financial reporting and close checklist.
Review the complete financial reporting package of schedules and relevant documents that will be provided to the auditors to determine whether supporting schedules agree to the general ledger and sufficient documentation and evidence exist that support those schedules
Review the financial statements, whether prepared by property management or another external party to determine whether they appear reasonable and complete based on your understanding of the property, as well as understanding of any significant fluctuations.
Property level audits can be a relevant and useful tool for fund managers and, when properly planned, can be performed efficiently and effectively.
Expensive Liz: My siblings and I are considering providing a triplex. It was bequeathed to us by our mother when she died in 2007. There is no mortgage loan and it is fully occupied. If we promote, my wife and I (equally more than 50) would get roughly $200,000, and we’d like to lessen the tax effect. We individual our property no cost and clear and have no personal debt. We’d like to use this windfall to assistance our son obtain a house. We’d also give our daughter a hard cash gift. We have no curiosity in purchasing one more expenditure property making use of a 1031 exchange. Any strategies to minimize our tax bill offered our conditions?
Remedy: Speak to a tax pro, because marketing a rental house is much more sophisticated than offering your individual residence.
You are not suitable for the $250,000-for every-man or woman home sale profit exclusion, and in addition to spending funds gains tax you also confront a depreciation recapture tax of 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. (Depreciation is the quantity of don-and-tear you wrote off during your ownership of the residence the IRS calls for you to repay that tax split when you offer.)
A massive funds achieve could impact other regions of your finances, these as Medicare premiums, and the pro can help you strategy for that as effectively.
A 1031 exchange would allow you to defer taxes on a rental house by purchasing a very similar alternative house.
One more option would be to hang on to the house, carry on to love the rental money and bequeath your part of it to your little ones when you die. Your portion will acquire a favorable action-up in tax foundation so that your heirs won’t owe taxes on the funds gains that transpired for the duration of your ownership. They also won’t deal with the tax on depreciation recapture you would usually owe.
But that naturally is not a superior remedy if you no for a longer time want to be a landlord or want the hard cash rather. In that situation, the tax professional can enable you thoroughly account for selling charges, legal charges and improvement bills that could minimize the tax hit and may perhaps be equipped to advise other methods to take care of your tax invoice.
Opening an IRA for a retired husband or wife
Dear Liz: Are spousal IRAs a great idea for a pair when a person spouse is retired but the other is working? I’m 63 and operate total time. My partner is 76 and retired. I have a Roth IRA he does not. I lead the utmost amount of money to my IRA. If we produce a spousal IRA for him, would we be ready to contribute as if it were a common Roth IRA?
Respond to: Certainly. Ordinarily individuals have to have earned revenue — these kinds of as wages, salary, commissions, strategies or self-work earnings — to add to an IRA or a Roth IRA. If you’re married and doing work, however, you can lead up to the highest amount of money on behalf of a nonworking wife or husband. In 2023, the maximum contribution for individuals 50 and more mature is $7,500. As lengthy as you make at minimum $15,000 ($7,500 instances two), you can max out equally accounts.
There is no particular “spousal IRA” account, by the way. Just open a common IRA or Roth IRA in his title.
Ins and outs of HELOCs
Dear Liz: We have a dwelling equity line of credit score as a result of our credit rating union. I have been paying out it down very aggressively and it will be compensated off in two months. That is our only credit card debt. I was considering leaving a modest ($100) balance. It would value $7.50 a 12 months to have the mortgage out there but we would have fast entry to $200,000 with no paperwork, etc. Your ideas?
Solution: Call your credit union and ask if it’s necessary to keep a harmony to maintain the line of credit history open, simply because ordinarily that’s not the situation.
You need to know, even so, that HELOCs normally have two phases: a five- to 10-calendar year “draw” time period, for the duration of which you can borrow and repay the line considerably as you would a credit card, adopted by a compensation period of time of 10 to 20 a long time for the duration of which you pay out down any total still owed. You normally just cannot attract out more revenue during the reimbursement time period.
If your HELOC is nearing its compensation stage, you can replace it with a new HELOC that you go away open up and unused for emergencies. Closing prices often array from 2{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the financial loan volume, while some loan providers price cut these expenses.
Liz Weston, Licensed Money Planner, is a individual finance columnist for NerdWallet. Issues may well be sent to her at 3940 Laurel Canyon, No. 238, Studio Metropolis, CA 91604, or by making use of the “Contact” form at asklizweston.com.
If you happen to be all set to action into the waters of financial commitment house financing, this guide is here to assist. You want to have your income and credit history in buy and know what your options are for loans. Soon after all, obtaining an expense home is a major action. You want to know what to anticipate and techniques you can make it far more economical.
A economic advisor could aid you generate a money approach for your economical requirements and objectives.
What’s an Expenditure House?
An expenditure residence is a piece of authentic estate you acquire with the sole motive of profiting off of it. These can be qualities you hold for a brief period of time, like you’re household flipping, or they can be lengthy-held, like with rental attributes.
Expense houses make income by balancing the obtain price tag and additional expense though protecting money move. This can be with a distinct purpose in sight, like with flipping a property, or it could be with numerous more compact plans, this sort of as creating enhancements though maintaining renters.
How to Prepare for Expense Home Funding
As with any serious estate obtain, you have to have to have your finances in purchase. That is primarily accurate with financing expense properties. Loan companies have bigger specifications for buyers than they do for those hunting to fund their principal residence. Right here are a handful of methods you can be geared up.
1. Construct Your Credit rating
Many creditors are going to have to have you to have very good or fantastic credit score to finance an financial investment home. In common, be expecting loan companies to call for a credit score score of 680 or superior. There are some approaches around this (more on that later on). But, the far better your credit score score, the a lot more probable your bank loan software is accepted and you are supplied a far more favorable fascination fee.
2. Have a Sizable Down Payment
Funding an expenditure house needs you to previously have a fantastic chunk of funds towards the buy. This can vary based on the personal loan variety, but for a standard property finance loan, you are going to probable need to have 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down.
3. Have Added Money Reserves
Together with your down payment, you can need to have extra dollars in reserve. This may perhaps or could not be necessary by your loan company. However, if you are buying an expense residence, you are going to have to have to place income into the home. Even the most turnkey of rental homes will need funding in situation of a significant appliance failure or to address things like landscaping.
4 Expenditure House Financing Procedures
There are four principal expense residence financing approaches that you can get edge of.
1. Making use of Your Individual Property Equity
If you personal your latest house or have a significant chunk of fairness, you can use the equity in it to finance your financial investment property invest in. There are three ways to do this:
Dollars-out refinance: With this product or service, you dip into your equity, changing your outdated mortgage, or, if you very own the household outright, starting off a new home finance loan. You can get up to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your fairness as a lump sum.
Property equity bank loan: Identical to a money-out refinance, you will need to have to go away some equity in the residence and you are going to be compensated in a lump sum. But, a home equity bank loan allows you keep your authentic home finance loan (if you even now have it) and get started a next mortgage. This can be valuable if your first mortgage has a reduced fee.
Household fairness line of credit score (HELOC): A HELOC is a line of credit score, like a credit card, that taps into your residence equity. It will work on two time durations: a draw and a compensation interval. People frequently use HELOCs when they never know how considerably they have to have specifically and would instead not consider out a lump sum.
Let us go around how you can use your house equity. For case in point, let’s say you own a home appraised at $350,000. You choose to just take out a house fairness bank loan for 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of your fairness. Which is $280,000. You can then use that lump sum to obtain and update an expense property.
2. Receiving a Home loan
There are a several ways you can get investment house funding with a home loan. The primary way is by way of a conventional mortgage loan. Typical mortgages usually are not element of a govt-sponsored system, which can make them tougher to get, specially for expenditure qualities. For a standard home loan on an financial investment house, you may most likely require a credit rating rating of 680+ with at minimum a 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} down payment.
Yet another way you could get a house loan for an financial commitment residence is by means of a authorities-sponsored home finance loan, like an FHA financial loan. FHA loans can be attained with decrease credit rating scores and down payments, making them much much more versatile. You may perhaps have to soar as a result of other hoops, although. For occasion, you can get a multifamily house with up to 4 models with an FHA loan, but you will want to reside in 1 of the units as your principal home for at least a yr. FHA also provides funding for non-proprietor-occupied properties, but they come with distinct needs close to the issue and age of the property.
3. Private Revenue Financial loans
Personal revenue loans are especially popular in serious estate financial investment. They are what they sound like: loans from rich people today or companies manufactured to other people. Typically moments they are from a relatives member or close friend. If they are from an group, it’s not an accredited a single, like a lender or credit history union.
If you know the financial institution properly, you might get a reduced fascination level. Having said that, if the bank loan is coming from a person you you should not know, private dollars loans are likely to have increased fees. The reimbursement terms are generally considerably shorter than with a typical house loan much too.
4. Hard Money Financial loans
Hard funds loans are comparable to personal cash loans in that they’re small-term mortgages made available at a higher fascination price. The change here is that tricky funds financial loans typically come with greater service fees. You achieve a single by means of a tough income loan company and they’re typically funded by investors.
The Base Line
Acquiring the right financial investment assets financing is a significant piece of the puzzle when it comes to buying an expenditure home. Ahead of you make a conclusion, you want to be informed of your funds and your choices. Analysis creditors in advance of speaking to them and examine meticulously over the phrases of their loan offer you. Potent funding can be the foundation for your authentic estate expense.
True Estate Investing Strategies
Investing in serious estate signifies you can have to do a lot of juggling. Owning a economic advisor in your corner offers you just one less thing to get worried about. Obtaining a skilled financial advisor will not have to be tricky. SmartAsset’s totally free resource matches you with up to a few vetted financial advisors who serve your location, and you can job interview your advisor matches at no cost to make a decision which just one is proper for you. If you happen to be all set to come across an advisor who can support you obtain your economical plans, get begun now.
You require the whole photograph of your home loan payment. Estimate your month to month payment with our free mortgage calculator, where you can contain information like taxes, costs and coverage.
Discover the best financial institution for your demands. Review mortgage loan rates from major loan providers utilizing SmartAsset’s home loan comparison device.
The firm’s hottest update retains its concentrate on rental residences, condos, and multifamily qualities, even though incorporating higher use of mobile systems. Revisions to the tenant and landlord portal allow for for real-time checking of expenditure attributes in any locale, and on most gadgets, whilst extra digital payment possibilities are created to increase lease selection premiums.
TCS Property Administration states that the Philadelphia region has captivated much more interstate buyers, and the firm’s increased technologies had been designed in guidance of those people clients. The organization states that tenants are also provided the means to talk with help staff and/or report problems, contributing to increased pleasure and retention in a aggressive sector.
In accordance to a recent report from Maxwell Realty, Philadelphia supports a younger and developing inhabitants, which is contributing to a vivid rental industry. Each new and nicely-recognized home traders are acquiring far more households in the area, partly thanks to the very affordable pricing when in contrast to spots this sort of as New York.
As TCS Property Administration details out, controlling rental homes from a distance can pose numerous one of a kind problems, and the firm’s newest remedies have been developed as a additional economical and helpful way to maintain stakeholders informed. Landlords can now accessibility a variety of studies on just about every property, together with rental collection prices and maintenance requests.
Tenants are also provided a array of on-line and digital payment mechanisms, like ACH, credit card, and ‘Pay In the vicinity of Me’. The portal can be utilized to submit report concerns, request upkeep, and chat with the company’s reps, allowing for for decreased reaction times.
Winner of the Experience.com ‘Best Home Management Organizations in Philadelphia’ award for 2022, TCS Assets Administration is one particular of the region’s primary companies of household companies. The firm has also opened workplaces in New Jersey, New York, Delaware, Maryland, and Tennessee, and its systems are now accessible to landlords in all those areas.
A corporation agent a short while ago mentioned: “TCS Management specializes in residential property management precisely made for you, the landlord. We embrace old-fashioned principles of provider whilst utilizing point out-of-the-artwork instruments. Solitary-family households, person condominium rental units and small multifamily dwellings are our core aim, and what we excel at.”
Picking the right area to invest in real estate is hard enough. But add numerous unprecedented developments to the mix—a pandemic, high interest rates, and Americans fleeing to secondary cities at historical rates—and the risk of leveraging wealth to a mortgage in the wrong location feels especially greater than buying a share of a REIT investment.
Here, we take a closer look at geographic risk’s impact on direct real estate investments.
Why REITs Have Lower Risk Than Direct Real Estate
REIT management teams often invest in hundreds of properties across various sectors and markets, ensuring that investors take on lower geographical risks and higher diversification.
Additionally, REITs tend to come with fewer risks than rental properties because they:
Develop their own properties.
Are managed by real estate experts.
Offer fewer options to choose from than investment properties.
Can expand externally by raising capital through the public equity market.
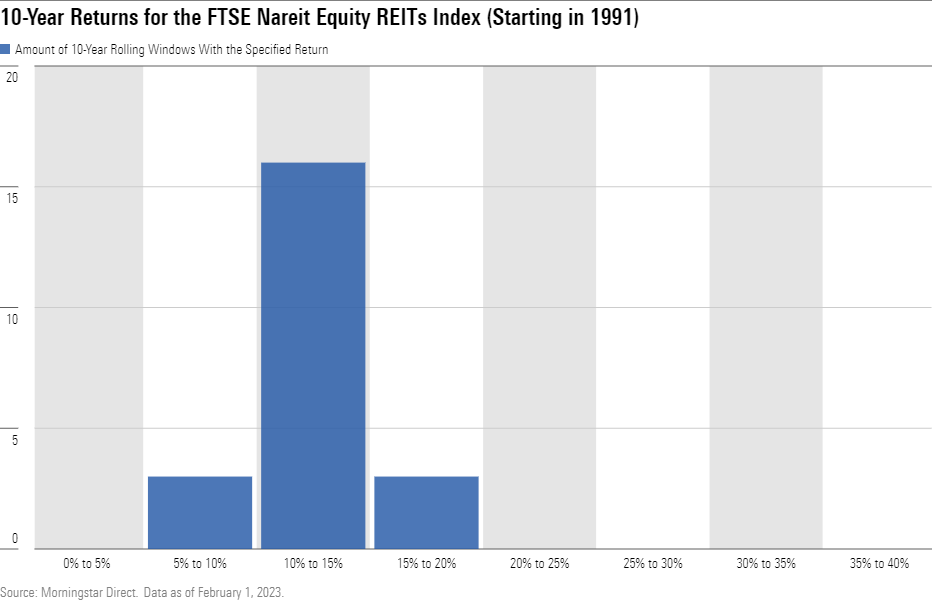
Historically provide a tight range of returns.
The chart below highlights the consistency and predictability of the annualized return from investing in a REIT index for a decade, starting anytime between 1991 and 2012.
What Are the Risks of Investing in Real Estate Directly vs. REITs?
Buying and owning property is rarely easy, especially because it’s hard to predict if a neighborhood will start to trend downward, lowering the resale value and rental prices to attract long-term tenants.
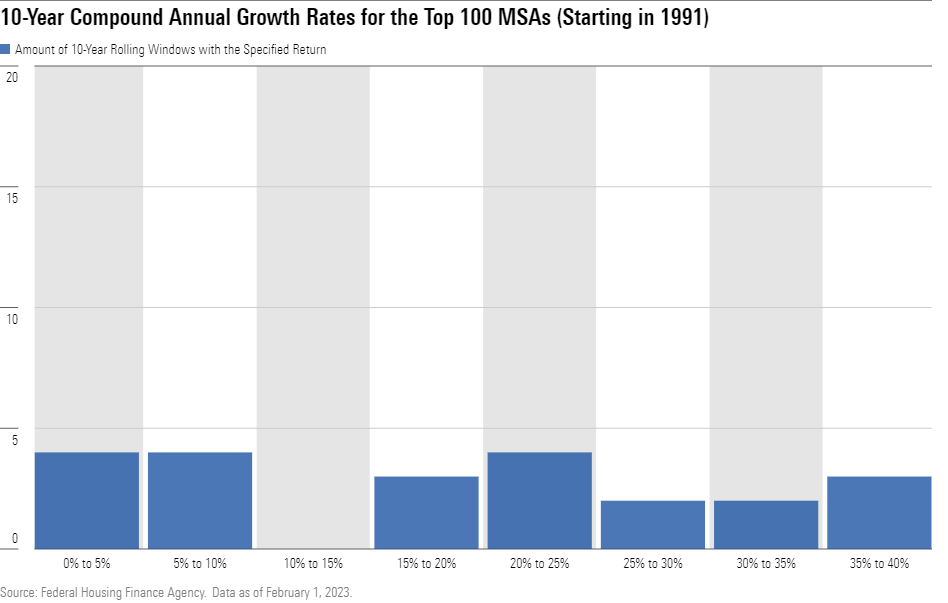
For example, consider direct real estate investors who owned a rental property (leveraged at 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} equity) for at least 10 years, starting anytime between 1991 and 2012 in any of the 100 biggest metropolitan statistical areas, or MSAs. They would have experienced inconsistent and sporadic compound annual growth rates based on the investment time window and property location, as shown in the chart below.
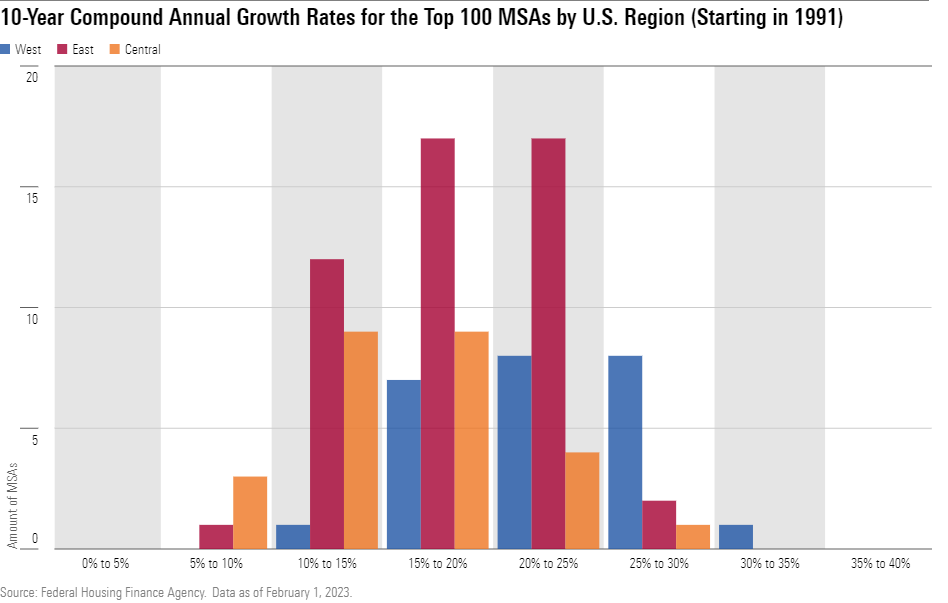
This inconsistency happens because investing in physical real estate can have significant geographical risks. For example, our analyses indicate that while property price returns often ranged between 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} across the Central, East, and West regions in the United States in the past 32 years, it was more likely to fall below that range when investing in the Central and East regions.
On the other hand, you were more likely to reach peak returns in the West, as early investors in West Coast cities saw their properties appreciate faster than homes in any other region. That said, you had to get into that market at the right time: Investors today are likely to pay a hefty price to enter the market and need to make a sizable down payment to see immediate positive cash flow on a rental property.
Meanwhile, despite more modest returns, the housing markets in the Central and East tend to be more affordable, allowing home prices to cool down slowly after a housing boom.
Even within the same market, the range of potential return outcomes can be broad and complex to navigate.
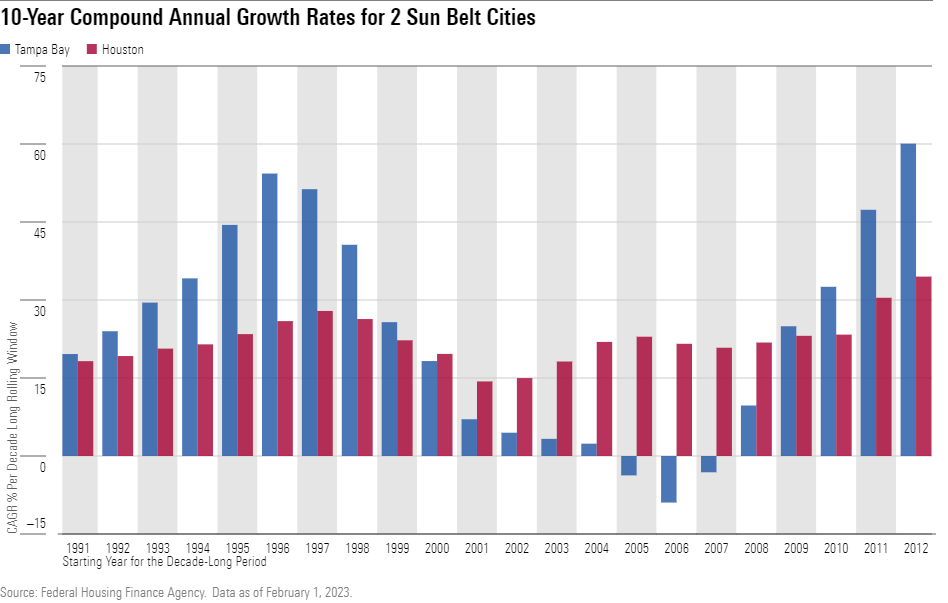
For example, take Tampa Bay and Houston—two comparable Sun Belt cities. Your real estate returns in these two cities would have varied substantially depending on the decade when you bought your property. If you made your investment 1) in the 1990s, you would have seen greater long-term returns in Tampa Bay; 2)between 2000 and 2008, you would have withstood the effects of the housing crisis better in Houston; or 3) after 2009, you would have seen positive growth for both cities, especially in Tampa Bay.
The highs and lows of Tampa Bay and the long run of mediocre returns from Houston may make it surprising that they currently are among the most thriving areas in the real estate game.
Early investors who capitalized on the low costs of real estate development in the South now enjoy the fastest-growing home sales prices. While it may make sense that cities with warm weather, affordable housing, and low tax rates are good areas to invest in, it’s harder to know when you should invest and how long you should hold.
The Complexities of Predicting Real Estate Winners
In hindsight, the benefits of investing in the Sun Belt cities after the housing crisis seem obvious. However, property markets quickly rise and fall, so picking the right time and location for an investment is easier said than done.
If you’re newer to real estate, reviewing historical trends can be a helpful guide. So, let’s turn back the clock about 20 years, to 2001. Despite being in the midst of an economic recession, there was unexpectedly high performance in the housing sector.
There were new annual records for home sales and homeownership.
Mortgage rates were at near all-time lows.
Housing affordability was the most favorable in the past 28 years.
Real estate professionals around the country anticipated that the increase in home supply would make early 2002 a good time to buy, even if interest rates were slowly beginning to rise—defying an economy in recession.
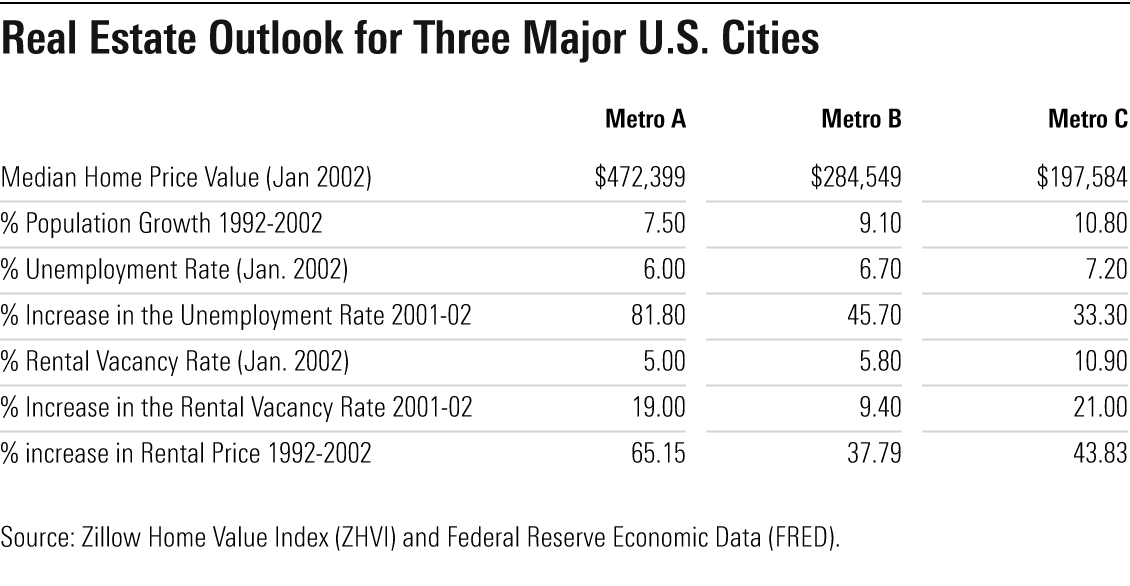
Let’s say you had the ability to purchase a property in a large metro area at the beginning of 2002 for $500,000 and hold it for 20 years. Which area would you pick? Below you’ll find more information to help guide your decision.
Metro A faced a downward spiraling disaster after the dot-com bubble left many people unemployed and forced them to leave the area, causing vacancy rates to climb. While the market was considered a real estate gold mine in the late 1990s, its heavy dependence on the troubled technology sector led economists to anticipate a slow economic recovery and an uncertain future.
Metro B faced a more mixed picture. In 2001 alone, more than 25 companies relocated out of the area, increasing unemployment rates and reducing the number of building permits. On the other hand, sales of existing single-family homes and sales prices were up from the previous year despite an economic slowdown.
Metro C had another excellent year in residential construction and home sales as property prices remained relatively low compared with the national average. In addition, despite relatively high unemployment rates, there were plans for an automotive-supplier project that would introduce hundreds of manufacturing jobs to the area.
Still undecided on which metro area would have been the best long-term investment? You’re not alone.
Real estate investing was much murkier in the early 2000s, as the current top housing markets weren’t necessarily the prime locations from 2002 to 2012. In fact, since 2002, more than 300 of the top 500 metro areas appreciated less than the U.S. average, including 28 of the largest 50.
Here’s how each of those investments would have fared:
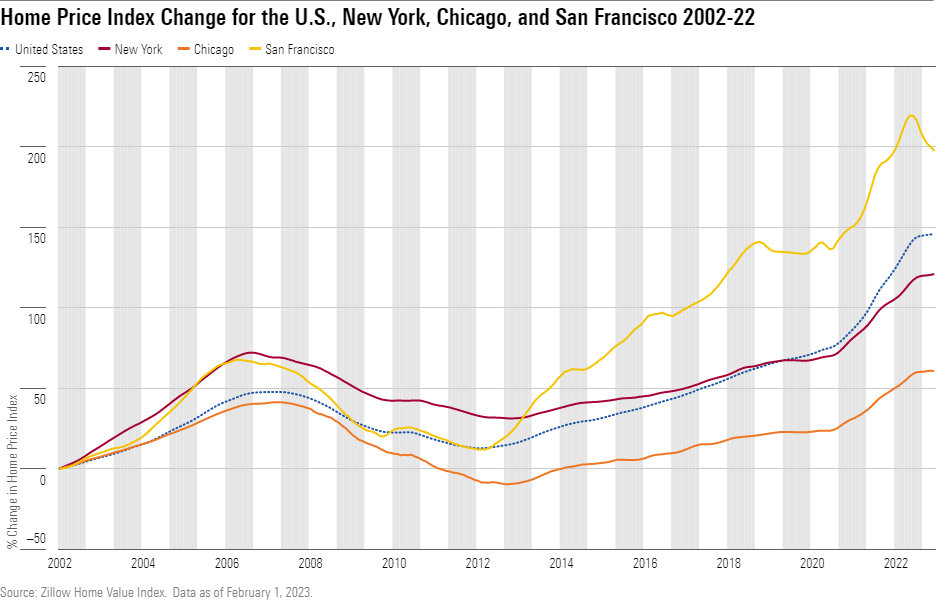
An investment in Metro C (Chicago) would have seen your capital appreciation grow at a lower rate than the national average. Yes, your property value would have increased to $800,000 by 2022, but that falls $400,000 short of the U.S. average due to a relatively low annual home growth rate after 2006. Since then, income and property taxes have gradually risen, and the lack of employment opportunities has caused residents to leave the city at unprecedented rates.
An investment property in Metro B (New York) would have performed around the national average, with your home value rising to $1.1 million by 2022. New York City’s recovery after the 2008 housing crisis was particularly strong as people continued to flock to the area and residents were more likely than average to keep their jobs and avoid foreclosure. However, strengthened rent controls and low capitalization rates have made New York a complex property investment choice unless you are focusing on the luxury marketplace, which is still one of the most expensive housing markets in the world.
Metro A (San Francisco) would have seen the best returns of these three options. Your investment property would have experienced an eye-popping 300{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} growth in its value, turning that $500,000 investment property into $1.5 million. In 2002, it would have been hard to believe that one of the best future housing markets would be led by the development of internet-related companies, considering that the industry had just lost more than 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of its market value during the dot-com bust.
But then again, these strong returns highly depend on when you invested.
As many big technology companies weathered the storm in California, Silicon Valley became home to the hottest residential bidding wars, reaching a peak in 2012.
Strict zoning laws combined with the limited amount of land have made real estate scarce in San Francisco compared with other California areas. However, high property prices, strict rent-control regulations, and tenancy rights make it extremely difficult to be a successful new real estate investor in San Francisco unless you are willing to provide a significant down payment for immediate positive cash flow.
Picking Real Estate Winners Is Only Simple in Hindsight
While home appreciation can be compelling for rental properties, finding the location that will grow a property’s value the fastest with the greatest return can be highly speculative. The stakes are especially high for homeowners who borrow up to 80{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the home price value. On the other hand, REIT management teams strategically finance their investment properties with 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} to 40{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} leverage, allowing for higher liquidity during economic distress.
Even those who invest a significant amount of their wealth in a property are exposed to unprecedented outside risks. Each market is unique, regardless of the location you decide to invest in, and some secular dynamics are harder to identify than others. For example, the Chicagoland counties accounted for some of the largest numbers of homeowners with underwater mortgages, as lackluster job and pay growth pushed residents to move out of the area.
Unless you have a time machine, factors like these may be beyond your ability to forecast. That said, for those who get the timing right, the rewards can be great when investing directly in real estate.
SmartAsset: Capital gains tax on real estate investment property
Real estate investments can be lucrative assets. However, they can also incur capital gains taxes that weaken your profits. Fortunately, you can implement tactics that reduce capital gains taxes so you can keep more of your money. Although the IRS taxes short-term and long-term gains differently, you can combat high tax rates on both. We’ll explain short-term and long-term capital gains and how to keep the associated taxes from costing you an arm and a leg.
You pay capital gains taxes when you profit from selling assets. You can incur two types of capital gains taxes: short-term and long-term. Short-term capital gains are from selling assets you’ve held for less than a year. On the other hand, long-term capital gains come from selling assets after holding them for a year or more. So, if you sell an investment property, the time you owned it before selling it will determine what kind of capital gains taxes you pay.
How Are Capital Gains Taxed?
The IRS taxes short-term capital gains as standard income, meaning your income tax bracket will determine your tax rate. Income tax brackets are as follows: 10{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 12{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 22{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 32{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 37{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Your income determines your capital gains tax rates.
For example, say you make $85,000 from your day job. You sell an investment property nine months after purchasing it and make a $30,000 profit. The sale results in a short-term capital gain, and your income is $115,000 when you file taxes. In addition, you’re a single filer, putting a portion of your income in the 24{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} tax bracket.
Conversely, long-term capital gains have different tax rates than short-term gains: 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, and 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, depending on your income level and filing status. For 2023, single filers making up to $44,625 receive the 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate. Single filers with income between $44,626 and $492,300 will pay 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Finally, single filers with income above $492,300 will pay 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} long-term capital gains taxes. In addition, single filers making $125,000 or more annually will pay a net investment income tax of 3.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on capital gains from real estate.
A married couple filing 2023 taxes jointly will pay 0{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} if they earn up to $89,250. The 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate applies if the couple earns $89,251 to $553,850. The 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} rate applies if they earn more than $553,850.
How to Limit Capital Gains on Real Estate Investment Properties
SmartAsset: Capital gains tax on real estate investment property
You can use a variety of strategies to avoid capital gains on real estate properties:
Use Tax-Deferred Funds
You don’t have to invest in real estate with dollars from your bank account. Instead, you can use your individual retirement account (IRA) or 401(k). Depositing investment profits in your investment account allows your money to grow tax-free. Plus, your IRA contributions can garner you another tax deduction.
Make the Property Your Primary Residence
The internal revenue service (IRS) exempts primary residence sales from capital gains taxes up to $500,000 for married joint filers and $250,000 for single filers. You can also avoid paying taxes on depreciation deductions this way. Using this option means fulfilling the following requirements:
Owning the home for two or more of the last five years
Living in the home as the primary residence for two or more of the last five years
You haven’t taken a primary residence exemption in two years
Tax-Loss Harvesting
Tax-loss harvesting means deliberately selling an asset for a loss to mitigate profits from another asset. Therefore, you can sell a property for less than you bought it, reducing your taxes.
For instance, say you sell one property and make $30,000. You don’t want to pay taxes on this gain, so you sell another property for $25,000 less than what you paid. As a result, you pay taxes on $5,000 of capital gains.
1031 Exchange
The depreciation deduction for rental properties has one major drawback: when you sell a rental property, you owe taxes on the depreciation amount (if you received any). Fortunately, the 1031 exchange allows you to circumvent this rule.
The 1031 exchange means using the income from the sale of an investment property to purchase another investment property of equal or greater value. Then, you don’t have to pay taxes on prior depreciation deductions. This caveat allows you to avoid income taxes on depreciation into perpetuity if you buy another property of equal or greater value.
How to Minimize Your Capital Gains Tax
Even if you can’t altogether avoid capital gains taxes, the following tactics will minimize your capital gains taxes:
Depreciation Deduction
The IRS allows rental property owners to deduct an annual depreciation amount from their income. The deduction comes from the expected lifespan of rental property, which the IRS defines as 27.5 years. As a result, you can calculate your depreciation deduction by dividing your rental property value by 27.5 (commercial real estate uses the lifespan figure of 39 years).
For instance, say you have a $250,000 residential investment property. Dividing this figure by the depreciation deduction lifespan of 27.5 gives you an annual deduction of $9,090.
Itemized Deductions
Generally, you can deduct the costs of managing property, lowering your tax burden. Running your real estate investment business incurs costs such as travel, legal fees, and business equipment. These expenses can add up – but instead of hurting your wallet, they can create a tax benefit.
In addition, you can deduct mortgage interest and the costs of repairing or maintaining a property. Therefore, keeping detailed records and saving every receipt is vital to claiming as many deductions as possible.
Methods to Boost Property Basis
SmartAsset: Capital gains tax on real estate investment property
Improving your property gives two financial advantages: the costs of doing so can shrink your capital gains taxes, and the improvements can bolster your property value. Here’s how you can boost property basis:
Closing costs, including title search, escrow, and taxes
Bottom Line
Capital gains taxes can curb your profits from real estate investments. Fortunately, multiple deductions and tax strategies can lower your tax burden. For example, you can deduct depreciation and make a home your primary residence before you sell it. In addition, upgrading your home can boost your property basis and lower your capital gains taxes. So, it’s essential to be thorough in your research and record keeping to ensure you minimize capital gains taxes on real estate investments.
Tips on Capital Gains Tax on Real Estate Investment Property
You can make the most of your real estate investments by familiarizing yourself with relevant tax laws. A financial advisor can help you understand your financial position and make the most of your tax return. Finding a qualified financial advisor doesn’t have to be hard. SmartAsset’s free tool matches you with up to three vetted financial advisors who serve your area, and you can interview your advisor matches at no cost to decide which one is right for you. If you’re ready to find an advisor who can help you achieve your financial goals, get started now.