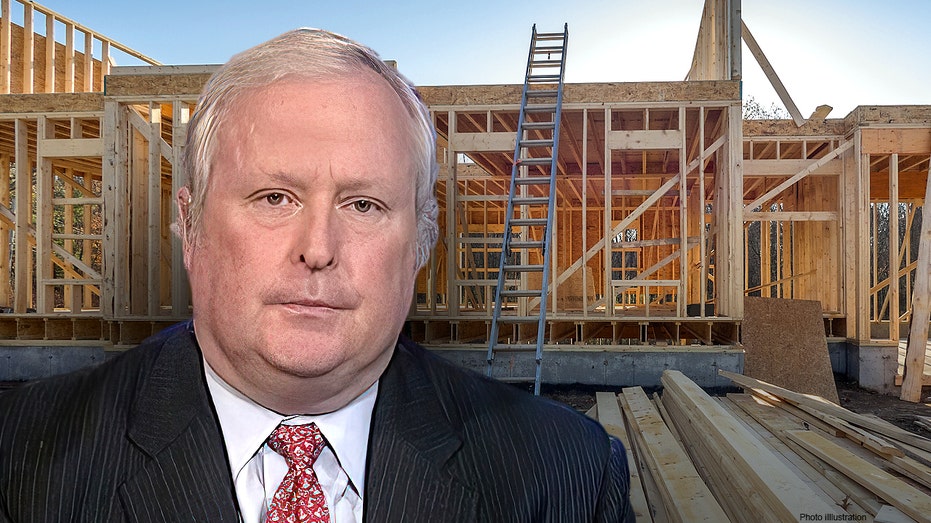
Nationwide Affiliation of Household Builders CEO Jerry Howard addresses the ‘huge drop’ in the homebuilder sentiment index on ‘Varney & Co.’
Countrywide Association of House Builders CEO Jerry Howard warned on “Varney & Co.” Monday of “a tricky time” in advance for the industry as facts uncovered the housing market has been slowing down.
Howard presented the perception on the very same day it was discovered that builder confidence plunged in July amid soaring inflation and amplified curiosity rates, which stalled the housing marketplace by radically slowing income and targeted traffic from potential buyers, in accordance to the association.
Property builder self-confidence in the market place for newly-created one-relatives properties dropped 12 points lessen to 55 in July, its seventh consecutive regular decrease according to the NAHB/Wells Fargo Housing Industry Index (HMI) unveiled on Monday.
The index can range in between and 100 with any print around 50 indicating positive sentiment. Any reading through above 80 indicators robust demand from customers.
HOW THE FEDERAL RESERVE Skipped THE MARK ON SURGING INFLATION
The information introduced Monday marks the most affordable HMI studying considering the fact that May perhaps 2020 and the greatest one-month fall in the history of the index, with the exception of the 42-stage drop in April 2020, the affiliation pointed out.
Talking on “Varney & Co.” on Monday, Howard stressed that there is no doubt that the data offers a crystal clear indicator that the housing industry is slowing.
“For the previous seven straight months it has been likely down and this is a huge fall – and I assume all it states is, ‘Somebody do something or we’re going to go into a recession,’” Howard reported.
National Association of Home Builders CEO Jerry Howard warns of “a tough time” forward for the sector. (Fox News | iStock)
He then argued that the “only way to convey down housing costs is to convey down the value of setting up materials, fix the supply chain, negotiate a lumber offer with Canada, [and] deregulate some of the regulations that are unnecessary.”
“We hope that policymakers will take this as sort of a previous cry for help,” he included.
The Federal Reserve has been mountaineering rates in an effort to tame inflation, which now sits at a refreshing 40-year superior, and the moves have been impacting the housing industry in the variety of bigger home loan rates.
Though mortgage rates do not adhere to the federal cash amount, they do typically adhere to the produce on the 10-12 months Treasury.
Jason Haber discusses the change in the housing current market telling ‘The Claman Countdown’ large fascination costs are triggering homebuyers to walk absent from buys.
NAHB Chairman Jerry Konter, who is a household builder and developer from Georgia, pointed out in a information launch that “production bottlenecks, rising home making charges and superior inflation are causing a lot of builders to halt building simply because the price tag of land, construction and financing exceeds the market place value of the house.”
“In one more indicator of a softening market place, 13{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders in the HMI survey documented reducing house selling prices in the earlier month to bolster sales and/or restrict cancellations,” he ongoing.
Howard famous on Monday that “we’re commencing to see slowdowns” as it pertains to demand from customers.
GET FOX Small business ON THE GO BY CLICKING Here
“All across the country, builders are telling me now that traffic is slowing down. They are telling me that they’re having people today chat about canceling present contracts,” he ongoing. “It is a pretty grim outlook suitable now from where I sit.”
As the US housing industry starts to neat, scientists say these towns are primed for a rate fall
If you’ve been squeezed out of the restricted housing industry above the past couple of a long time waiting for the prospect to purchase, you may last but not least be obtaining your probability – and some sites are now on the lookout much more desirable for potential buyers.
The housing marketplace is commencing to neat and cities that have viewed an “influx of affluence” as Rick Palacios, Jr. calls it, may possibly see charges drop the farthest.
Palacios is the director of investigation at John Burns Real Estate Consulting, which provides investigation on the housing market to clientele this sort of as builders, realtors and investors.
He’s predicting a considerable downturn in the housing industry in Boise, Austin, Nashville, Phoenix, Sacramento and other metropolitan areas where prices climbed in the course of the COVID-19 pandemic as much more men and women moved to them.
“These are some of the marketplaces the place we ended up anticipating the steepest cost declines in 2023,” says Palacios.
Do not pass up
The moment tight marketplaces will be primary the way down
They’re the towns people flocked to during the pandemic, garnering them the nickname “Zoom towns”. They have a substantial quality of lifestyle and ordinarily reduce housing prices than the key centers.
And given that the commencing of the pandemic, men and women who could function remotely have relocated to these parts, nabbed the comparatively low-priced homes and drove up prices.
But Palacios is predicting a steep drop in housing selling prices in these cities, with Boise primary the way.
Boise turned just one of the the very least cost-effective towns to buy in the course of the pandemic as an inflow of people bought house in the area. Residence selling prices reached 72{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} over what a center-revenue loved ones can afford very last year, according to Oxford Economics.
“Boise is 1 of those people markets that generally rides the bubble wave. When factors are fantastic, I necessarily mean, it just – it catches that wave,” states Palacios.
But the similar can be claimed for when points start off heading downhill.
“Just wanting at the advancement price in residence appreciation, [Boise] has reversed wholly. And it is, I think, the single market place that we foresee truly having to value declines in 2022.”
And while this may possibly be tricky news for men and women who have acquired in Boise and equivalent metropolitan areas in the earlier couple of decades, it is excellent information for anybody seeking to purchase property — although it may possibly just take numerous months or even years in advance of rates level out.
Investors are pumping the breaks
Home values in Phoenix went up 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} above the past calendar year, in accordance to Zillow’s worth index.
“As of the 1st quarter of this year… investor transactions are 45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of the total housing market,” says Palacios.
That includes people obtaining 2nd residences, investment decision properties and properties to flip.
“That’s a large offer,” suggests Palacios. “And you can find a large amount of marketplaces throughout the region the place trader transactions are now 30-40-45{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of all household purchases.”
Marketplaces that count on financial investment things to do do perfectly on the upside, claims Palacios, but they can turn immediately.
“That’s why we’ve bought some fairly adverse forecasts, particularly on a relative foundation to much more kind of slow, continual markets.”
In accordance to Redfin, trader buys in Nashville ended up down nearly 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the initially quarter of 2022, 17{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Las Vegas, and 21{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in Sacramento.
Stock on the increase
From February 2020, just before the housing current market went haywire, to right now, housing costs in Boise are up 58{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, claims Palacios. In Austin, they’re up 75{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and in Nashville, it is up 56{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.
“We look at affordability as possibly just one of the most, if not the most, important indicator for how sustainable factors are in a marketplace,” suggests Palacios.
And as fascination fees started to rise — the national level on a 30-12 months home finance loan is now 5.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, according to Freddie Mac — it grew to become distinct how unsustainable those selling prices had come to be.
“The regular payment is up 40-50{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} 12 months above yr,” says Palacios. “And that is a enormous shock to that consumer, which tells you why these markets have pulled back again so quick.”
Organizations are also starting off to carry persons back again to the office, which has played some portion in more folks placing their households up for sale and a progress in stock.
June observed an 18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} maximize in housing inventory nationally calendar year more than 12 months, according to Realtor.com.
Ratiu suggests stock is rising in Austin, Raleigh, Nashville, Sacramento and other people – all over again, cities that noticed a surge in populace above the previous two many years.
“These markets have, in quite a few techniques, captivated folks from coastal, considerably much more costly markets,” Ratiu suggests.
“Austin has been a magnet for a good deal of tech employees from San Francisco, Silicon Valley, Seattle, Los Angeles, most of them really captivated to the relative affordability. It is really not surprising to see that, in change, these markets are type of foremost the shift in the sector.”
Austin saw some of the most significant progress in stock, in accordance to Redfin. The variety of properties for sale in the metropolis rose by 27{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in June, in comparison with past 12 months.
But as much more households arrive on the industry, sellers are even now hoping for those top of the marketplace prices, says Ratiu.
“Markets have adjusted considerably in the very last 3 months. And what we are viewing pricing sensible, we’re still observing a great deal of owners listing properties centered on the current market from 6 months ago.”
And selling price cuts for listings are on the increase. In June, 11{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of listings nationally lower their price ranges, in comparison with 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in June the 12 months prior to.
More than 60{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of sellers in Boise experienced to minimize their costs in June, according to Redfin.
What ought to customers do now?
Palacios states all signs level to a housing gradual down, and while it could take a number of months or extra for price ranges to occur down, if you can wait around, you ought to.
“We haven’t been in a slowing setting for many years,” says Palacios.
“The possibilities are heading to be out there. And I really don’t feel it is the worst decision in the planet to be a little bit additional affected individual now than you would have been when charges were being 3-4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.”
What to read through upcoming
What do Ashton Kutcher and a Nobel Prize-successful economist have in prevalent? An investing application that turns spare change into a diversified portfolio
‘There’s constantly a bull current market somewhere’: Jim Cramer’s famous terms suggest you can make cash no make any difference what. Right here are 2 highly effective tailwinds to consider advantage of right now
This report delivers facts only and should really not be construed as information. It is offered with no guarantee of any form.
Housing in the 1950s is characterized by homogeneous model and publish-Globe War II sensibilities, affluence and family dimensions. Broker Gerard Splendore presents perception into the historical and architectural roots of the decade’s dwelling models as section of his Circa collection
Wanting for a lot more new agent assistance? Sign up for The Fundamentals, a weekly newsletter with every thing you will need to start your serious estate enterprise.
American housing kinds have improved, and keep on to transform, all through the nation and as homeowners’ preferences and life have advanced. As the nation has been through industrial and financial alterations, each superior and not so very good, housing types have tailored out of necessity.
In this new collection, I will walk you via the predominant housing models of the past 12 many years, beginning in 1900. A standard being familiar with of each architectural design that defines a 10 years will placement you as a professional agent with your shoppers and make looking for a household with your potential buyers less difficult for everyone.
True estate brokers who can identify a property designed in the 1950s when they look at an exterior listing photo, or as before long as they arrive at the property with their potential buyers, have an gain in excess of brokers who are not as visually astute.
This interval of architecture and house furnishings has come to be even additional really sought after given that it turned regarded as “mid-century modern” in Cara Greenberg’s 1984 e book Mid-Century Present day: Home furnishings of the 1950s. The tv sequence Mad Males popularized this time period of architecture and style. Very preferred by millennials, any agent effectively-versed in this fashion will be thriving.
When urban 1950s architecture is characterized by glass curtain partitions and exposed steel, apartment properties in the town showcased remarkable lobbies with various amounts, amoeba, area-age-formed seating and ceiling cutouts. American properties of this interval were largely designed in the Colonial Revival and Cape Cod kinds. The gross countrywide merchandise of our nation grew significantly throughout the 1950s, and housing measurements grew in proportion to America’s prosperity.
This period of time spawned a new vocabulary to explain the capabilities and forms of residences that turned obtainable. Ranch residences, or houses without basements or second stories, grew to become acknowledged as ramblers.
Open up sheds to home autos, connected to the property, have been recognized as carports. Dwelling rooms showcased photograph windows, even if the sights were only of the yard. And the decrease level perform spaces or basements in these residences had been referred to as “rec rooms,” limited for recreation rooms.
The 1950s have been known for meticulously planned properties catering to modern day sensibilities, neither much too huge nor also tiny, neither far too official nor as well everyday. The residences have been constructed for two-mother or father people with children and area for entertaining was a provided. Patios and porches ended up added to the floorplans.
Girls, who had entered the workforce in record numbers during the Second Earth War, ended up now stay-at-property moms and homemakers, with a number of exceptions. The final result was the colourful, present day kitchen, no for a longer period sterile and all white, in which the lady of the dwelling employed all of her contemporary appliances to acquire care of her relatives.
Not only did kitchen area appliances develop into obtainable in a rainbow of colors, but bathroom fixtures and tiles as properly. Paper products, together with paper towels and rest room tissue, shortly followed, with multiple colours and styles out there.
Pent-up desire and the surging economic system for the duration of the 1950s motivated housing styles. They provided sufficient closets and household rooms, recreation rooms and recreation areas that housed the television (which turned a common in practically every home). Some affluent homeowners experienced additional than one tv, far more than a person phone and a number of autos parked outside the house.
Housing developments grew throughout the country as an growing network of thruways led to the growth of suburbs. The Federal-Help Highway Act of 1956 aided to acquire extra housing alternatives in many spots. Railways were being no for a longer period necessary to ship solutions from the farm and manufacturing facility to the marketplace, as vehicles became the decided on standard of transportation.
An additional element triggering suburban sprawl and more elaborate housing was the regular development of loved ones profits, which was at the highest degree in American background. Billions of federal pounds grew to become available for housing as Fannie Mae and the Federal Housing Authority (FHA) took off.
Variety of housing model was neither valued nor encouraged. When arriving at a suburban housing advancement, as handful of as two diverse solutions of facade and floorplan and as numerous as 5 may be available to the homebuyer. This homogenization enabled the contractors and builders to rapidly erect properties constructed on typical modules.
Sheets of drywall replaced damp plaster, which took time to combine, utilize and dry. Preconstructed trusses for roof and stairway, as properly as regular-sized windows and doors, expedited development in all parts of the country.
Crawl areas less than homes were an cheap and well-known substitute to the basement or cellar, which necessary pricey and time-consuming excavation. Lacking a basement, furnaces and hot drinking water heaters moved earlier mentioned ground in a further freshly added and named area in the 1950s house, the utility place. This area also housed electrical panels and h2o shut-off valves.
Contributing to the uniformity, television courses portrayed, virtually without exception, two-mum or dad families in suburban homes adorned just about identically. The 4 million toddlers born in 1954 (surpassed by the peak of 4.3 million babies in 1957), all aspired to live like the families they observed on tv.
Housing from the 1950s is even now very a lot offered throughout the nation and incredibly very desired. A interval of prosperity and hope, submit-war American housing sends a good concept to customers who are nostalgic for an period that took spot ahead of their delivery and that they may possibly have skilled only in flicks and on late-night television. The Real estate agent who can figure out this fashion and enchantment to his buyer’s innate wants will be certain accomplishment in the market.
As component of our sequence where by we check with prominent economists and genuine estate professionals their choose on the housing industry now, we talked to Nadia Evangelou, senior economist and director of forecasting at the National Affiliation of Realtors.
Countrywide Association of Realtors
The housing affordability crunch is right here — with house loan premiums continuing to rise (see the cheapest charges you can qualify for in this article) at the very same time that housing costs do. So – as section of our series in which we check with popular economists and actual estate professionals their get on the housing sector now – we talked to Nadia Evangelou. She’s the senior economist and director of forecasting at the Countrywide Affiliation of Realtors (NAR), and focuses on regional and local sector trends, like the results of changing demographic and migration patterns. She also specializes in study and investigation on area housing affordability ailments and solutions to enhance housing stock. In this article are her feelings on the housing sector now.
The outlook is for home loan prices to increase even even more
Home finance loan fees for 30-12 months set loans strike approximately 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in June, up from a minimal over 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a year back, according to Bankrate facts. The upward climb will carry on, suggests Evangelou, just not at that similar fast tempo: “I really don’t hope to see the exact sharp will increase that the market place expert in March and April. It appears that home finance loan fees have by now priced in some of the results of the future Fed’s rate hikes,” claims Evangelou.
Some consumers may possibly want to think about an ARM
Offered the recent industry, Evangelou suggests some prospective buyers really should take into account getting an adjustable-charge mortgage instead of a preset-rate house loan. “If they strategy to offer or refinance in the upcoming 5 decades, a 5/1-yr ARM might make more feeling simply because the amount on these is continue to under 4.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}. Thus, for a median-priced house, the every month home loan payment is about $300 reduce than the payment for a 30-yr home finance loan,” says Evangelou. You can see the lowest property finance loan prices you can qualify for listed here.
There are indications that the industry is cooling
Both of those growing home loan premiums and dwelling prices hurt affordability for lots of purchasers. “As a result, present property gross sales have dropped for the previous 4 months. I anticipate a bigger reduction of the house revenue activity in the next months, specifically right after summer time months,” says Evangelou.
And prospective buyers are having priced out of the marketplace. Nevertheless, not all home customers can afford to get these additional homes. In accordance to Evangelou, potential buyers earning $75,000 can find the money for about 25,000 much less listings now in comparison to January.
Institutional potential buyers might maximize competition for 1st-time purchasers
With rising mortgage loan charges hurting affordability, a lot more folks are leasing and because of to very low inventory, rents are increasing sharply. “For institutional potential buyers, this interprets to larger sized profits. Nonetheless, a much larger marketplace presence of institutional purchasers will increase current market competitors for initial-time property customers. Study has shown that institutional buyers may perhaps be having a considerable portion of homes that would usually be offered to first-time and decrease-earnings consumers,” says Evanagelou.
Residence selling prices will go on to rise but at a slower rate
“Due to a housing scarcity, home charges won’t fall in 2022. Keep in mind that when there is a housing lack, home costs don’t drop, in fact, household prices rose about 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in May well, despite the fact that house loan charges were about two share factors better than a year earlier,” says Evangelou.
Inventory is increasing
There are about 20,000 extra properties readily available for sale for prospective buyers earning $200,000. “While it is promising to see much more houses obtainable in the market, extra entry-level houses are required,” states Evangelou.
Some real estate markets are extra susceptible to a downturn than others.
Getty Photographs
6 of the 10 counties most susceptible to a downturn are in New Jersey, in accordance to a Unique Housing Chance Report — which looked at the best concentrations of the most at-threat marketplaces in the very first quarter of 2022 — introduced by ATTOM, a real estate knowledge analytics business. (You can see the lowest mortgage loan costs you could qualify for here.)
Counties are found as vulnerable depending on the percentage of homes dealing with foreclosures, the portion with house loan balances that exceeded approximated house values, the share of common community wages expected to pay back for big household ownership expenses on median-priced single-family members households, and area unemployment fees. “Housing marketplaces with lousy affordability and comparatively large charges of unemployment, underwater financial loans, and foreclosures action could be at hazard if we enter a recession or even deal with a extra modest downturn,” discussed Rick Sharga, executive vice president of market place intelligence at ATTOM, in a assertion.
Most susceptible to a downturn
Minimum vulnerable to a downturn
Passaic, NJ
Chittenden, VT
Essex, NJ
Benton, AR
Atlantic, NJ
Davidson, TN
Sussex, DE
King, WA
Kent, DE
Shelby, AL
DeKalb, IL
Durham, NC
Sussex, NJ
Tippecanoe, IN
Cumberland, NJ
Olmstead, MN
Will, IL
Williamson, TN
Union, NJ
Rutherford, TN
Sharga clarifies that a number of New Jersey counties land on this list, as the point out “endemically is vulnerable to some chance things, notably high price ranges which usually means a higher proportion of home profits is necessary to maintain ownership” and is surrounded by New York City and Philadelphia, “whose economies were impacted by the pandemic and there’s a spillover into NJ simply because of that.”
New Jersey isn’t the only state with a cluster of susceptible counties. Certainly, these three states housed 34 of the 50 counties most susceptible to a probable decline, the report located. And of the 50 most at-possibility counties, 8 have been in the Chicago metropolitan space (Cook dinner, De Kalb, Kane, Kendall, Lake, McHenry and Will), 6 have been in New Jersey, in close proximity to New York City (Bergen, Essex, Ocean, Passaic, Sussex and Union, which are in New Jersey) and 10 were sprinkled all through California (Butte, San Joaquin, Shasta, Solano, Fresno, Kings, Madera, Merced, Stanislaus and Kern).
This smattering of locales may well seem to be geographically random due to the fact “rural northern California and the spots about NYC and Chicago never have much in typical, but they do share slower residence-cost development than the Sunbelt mainly because their populations are rising extra slowly but surely,” states Holden Lewis, dwelling and mortgage pro at NerdWallet. Provides Jacob Channel, senior economist at LendingTree: “Homes in the Chicago and NYC parts, as properly as households scattered throughout lots of components of California, are often rather pricey in comparison to residences in other areas of the region, and, simply because of this, men and women in these areas may require to stretch their budgets a little bit extra in order to be ready to pay for a house.” (You can see the most affordable fees you may well qualify for listed here.)
This, mixed with an uncertain outlook for how the economies in individuals regions will fare in the confront of ongoing large inflation and a opportunity recession, signifies that housing markets could be additional susceptible than typical, pros say. “Of training course, parts with significant property rates can even now have pretty sturdy housing marketplaces, assuming that other elements of their overall economy like unemployment are reduced. It is significant to retain in mind that just due to the fact there are some indicators that one area’s housing industry could possibly be extra vulnerable than yet another, doesn’t mean people area’s markets are on the precipice of a main collapse,” states Channel.
The report reveals that big residence ownership charges like home loan payments, home taxes and coverage on median-priced solitary-household properties consumed additional than 30{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of typical local wages in 25 of the 50 counties most susceptible to market issues. The best percentages in these marketplaces were being in San Joaquin County, CA with 48.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of normal nearby wages necessary for major possession expenditures, Bergen County, NJ with 48.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of average neighborhood wages needed and Solano County, CA with 46.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of typical area wages needed for significant possession costs. To put that in standpoint, the report indicates that nationwide, significant fees on regular homes offered in the initial quarter of 2022 demanded 26.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of common regional wages. (You can see the most affordable premiums you may well qualify for right here.)
So what could this all mean for the housing marketplace as a full, and customers in susceptible counties?
Channel points out that the housing sector as a entire does not look to be at a significantly heightened chance of collapse. “As of now, most knowledge, like the nation’s small mortgage loan delinquency rate or the document amount of money of equity that homeowners are sitting on, still suggests that the the vast majority of property owners throughout the place are in a fantastic place to retain up with their payments and aren’t at severe chance of defaulting on their financial loans,” says Channel.
But if you are seeking to invest in or provide in a susceptible county, professionals say it is achievable you could see heightened rate cuts on properties and sellers more keen to negotiate with purchasers. “This could direct to some great offers for individuals on the lookout to get a dwelling, but keep in thoughts that provided how a great deal rates in lots of parts elevated in 2020 and 2021, prospective buyers may perhaps nevertheless have to have to offer with significant home rates, even if they do fall a small little bit,” claims Channel.
A large amount can alter in just 6 months. Russia invaded Ukraine. The latest time of “Stranger Things” dropped on Netflix. And the housing market, which acquired a turbo strengthen from the COVID-19 pandemic, has begun to change.
Surging mortgage loan desire costs are rippling by the housing industry, threatening to upend authentic estate’s unprecedented tear. These improvements led the Realtor.com® economic analysis group to revisit its 2022 housing forecast, issued in December, and make some adjustments. The current midyear forecast variables in these better rates—and the disruptions they’ve presently started to bring about.
Realtor.com expects house costs and property finance loan costs will continue on to rise, property sales will drop as buyers are priced out of homeownership, and the housing current market will keep on to cool. However, in a vibrant spot for discouraged homebuyers, the variety of houses on the market place is envisioned to shoot up.
“The quantity of homes for sale proper now is so reduced that it is developing these ultracompetitive ailments for purchasers, which are so challenging,” suggests Real estate agent.com Main Economist Danielle Hale. “More residences for sale will assist convey again far more harmony and sanity to the marketplace.”
Mortgage fees are now anticipated to hit 5.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} by the finish of the year—a rate predicted to proceed sidelining prospective buyers previously grappling with record-high dwelling selling prices. At first, the Realtor.com economists predicted they would hit only 3.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} for 30-12 months set-charge loans. Having said that, premiums strike a higher of 5.3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} final thirty day period prior to settling in at about 5.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, in accordance to Freddie Mac information.
The reduced projection was designed ahead of persistent inflation turned a thorn in the aspect of the U.S. Federal Reserve. The Fed is now hellbent on taming all those runaway selling prices by mountaineering desire rates—causing historically reduced home loan prices to soar.
“Rising fascination charges have shifted the basis of the financial state as properly as the housing sector. So numerous homebuyers take out home loans so that mounting charges have an impact on how pricey homeownership is,” says Hale. “It’s causing customers to make challenging trade-offs and disrupting the housing industry.”
The just about 2 share level distinction in between the preliminary very low prediction and the genuine mortgage loan fee enhance is a recreation changer for the housing market place
A median-priced home of $447,000 with a 3.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} home loan rate would command a roughly $1,626 every month mortgage payment. (This is for purchasers who set down 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and doesn’t incorporate residence taxes or dwelling insurance policy.) Boosting the home loan fee to 5.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} translates into consumers paying about $400 far more a month—nearly $5,000 additional a calendar year, and roughly $45,000 above the 30-year lifetime of their financial loans.
Potential buyers have descended on to the housing marketplace, scrambling to acquire bidding wars in advance of charges surge even greater. The Realtor.com economists imagine prices will be 6.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} better by year’s finish. Though that’s even now a conservative estimate specified the latest spike in home prices, which rose 17.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} yr more than yr in Might, the increase is much more than double the 2.9{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} appreciation economists experienced foreseen in their primary forecast.
“Our dwelling value projection is going up as we’re looking at a ton of sticking electricity in prices and selling price advancement,” says Hale. “We do however be expecting property costs to cool, but we’re starting at a higher price issue.”
Those price range-busting costs and rates are anticipated to gradual dwelling product sales. Alternatively of the variety of home purchases ticking up, the Real estate agent.com economists now predict income will drop 6.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} when compared with previous yr. (These are for current households rather of newly constructed kinds.)
Nevertheless, no a person really should panic. Even if sales do tumble, the authentic estate market is nevertheless on keep track of for a historically fantastic calendar year. Final 12 months was an anomaly with the highest number of closings considering that 2007. Furthermore, much less income could give inventory levels a boost in a earn for purchasers who are not finding lots of qualities for sale.
“Were it not for very last year’s extraordinary profits quantities, this would be a pretty good year,” states Hale. “We’re a prolonged way from a crash.”
In some welcome information for buyers, all of these forces at play are expected to give the quantity of properties for sale a large raise. Inventory is expected to increase by 15{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} this year. That is a game changer for the marketplace and is a significant bounce from an before estimate of just a .3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} bump.
Development of all those poorly needed new households is anticipated to continue to be 5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} increased than past yr. That is simply because builders have identified methods to conquer a myriad of worries, from supply chain woes making it difficult—and expensive—to supply supplies and appliances to building employee shortages.
The Realtor.com economists now expect housing begins, which is development which is started on new households, to hit a 16-calendar year superior this yr.
“We have a genuinely significant making deficit to climb out of. In excess of the very last 10 years, we have not crafted sufficient homes,” states Hale. “So we’ve received a long way to go to capture up. That’s why we could still see construction improve even if house profits sluggish.”
Residence sellers will also very likely want to modify their expectations as they may well not acquire the windfall they anticipated. The bidding wars they anticipated, presents of tens of hundreds of pounds about their asking costs, and legions of purchasers prepared to waive just about just about every contingency could possibly not materialize. Though it’s predicted to continue being a seller’s sector, potential buyers are now struggling with larger selling prices and property finance loan premiums. So they may possibly have fewer cash to place toward a household than they would have just a calendar year previously.
“The sector is going as a result of a changeover,” claims Hale. “The housing marketplace more than the previous handful of decades has continued to develop more and extra aggressive. [Now] it is heading to sense a very little like whiplash. The market place is even now competitive, but the tide is shifting.”