How to know when housing bottom is in

How to know when housing bottom is in

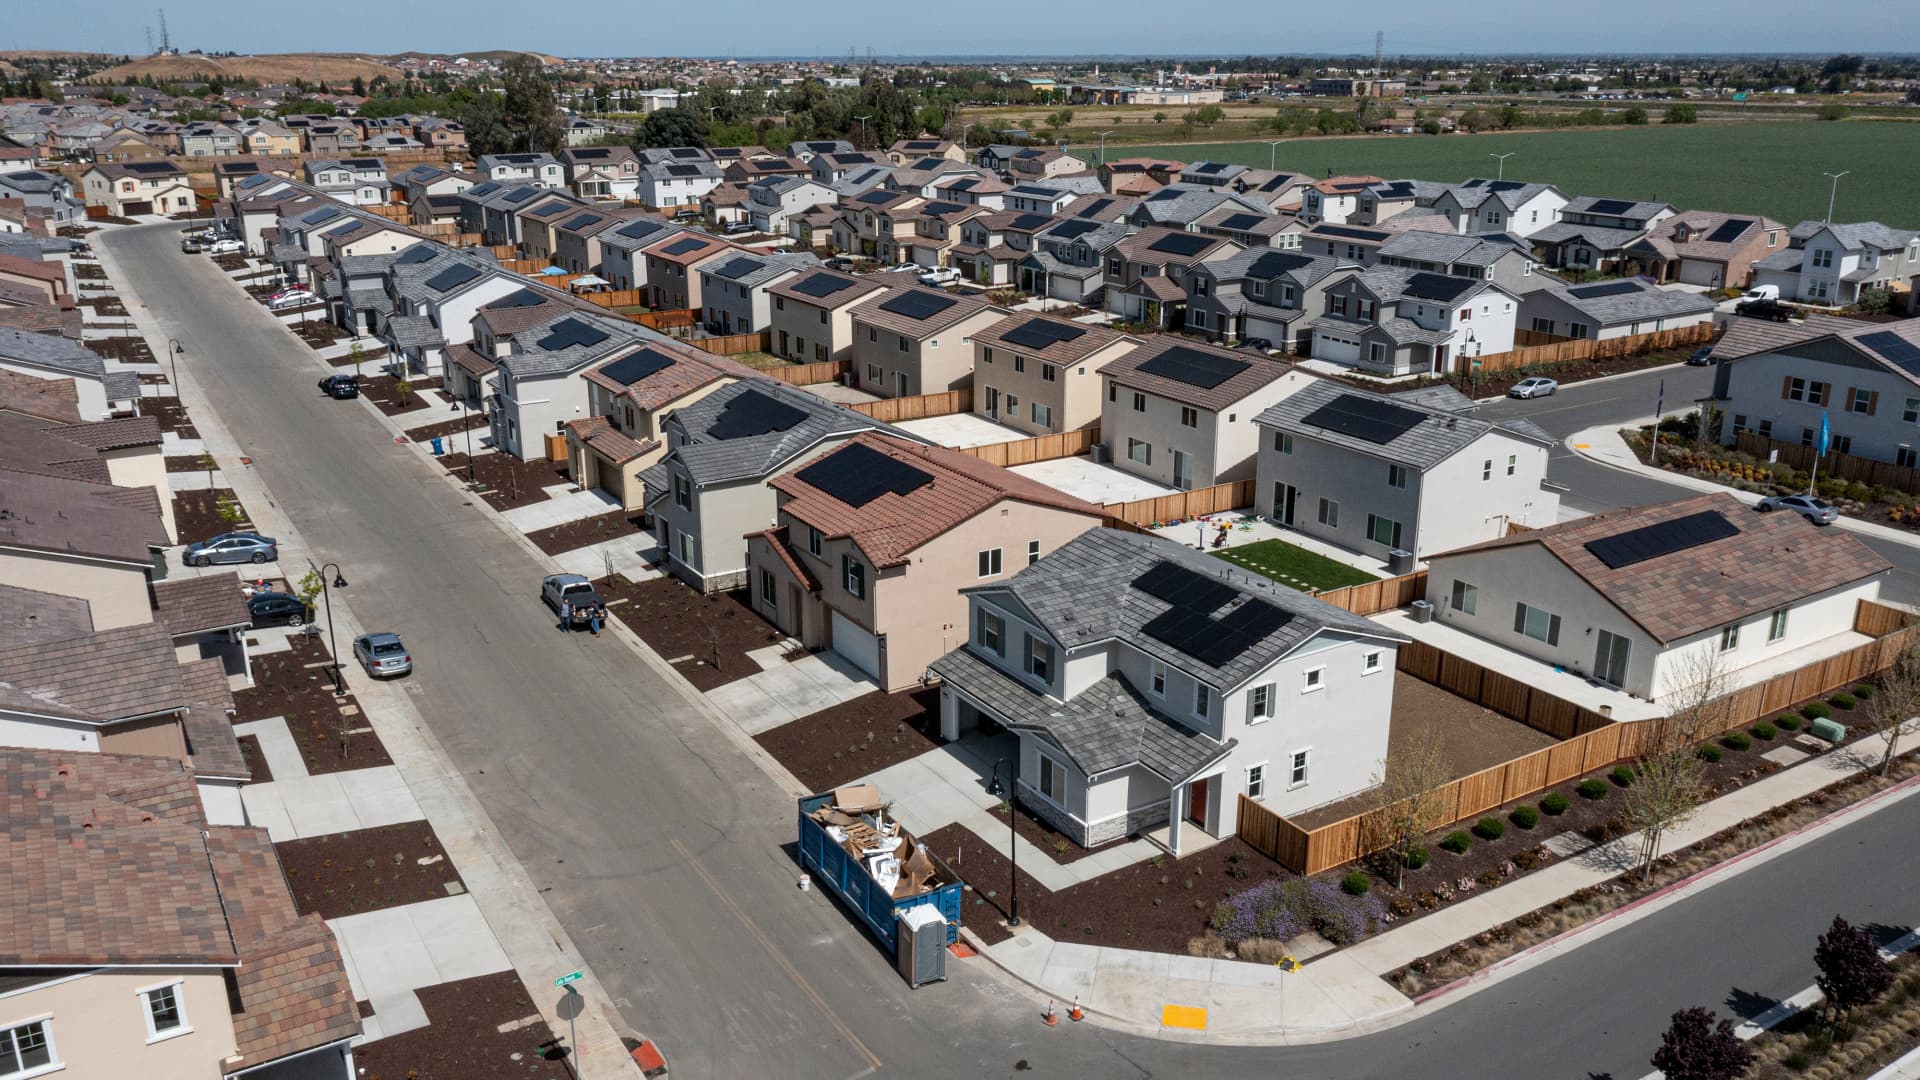
New homes at the Cielo at Sand Creek by Century Communities housing development in Antioch, California, U.S., on Thursday, March 31, 2022.

David Paul Morris | Bloomberg | Getty Images

Chicago realtor Jeremy Fisher headed to Florida after Christmas counting on five mostly-relaxed weeks, after a slow second half of 2022 left him with a bunch of unsold listings exiting the year.

Instead, the Compass broker ended up flying back to the Windy City three times during his low season, as seven homes went into contract and his husband ended up driving their baby home from Florida alone. The great real estate bust, it seems, has found something like a floor.

“For somebody, it’s always the right time to buy a house,” Fisher said. “People for the most part have come to terms with interest rates.”

After only a few months in the tank, is the U.S. housing market close enough to a bottom that it’s time for those on the sidelines to at least start thinking about buying as spring shopping season nears?

Signs are accumulating that the big price bust — and mortgage-rate relief — that buyers wanted isn’t materializing, at least not soon.

Goldman Sachs trimmed its estimate of peak-to-trough declines in nationwide home prices to 6 percent from 10 percent in late January. Online housing marketplace Zillow now expects prices to rise slightly in 2023. Existing home sales, which were running at a 6.5 million annual pace in early 2021, have begun to stabilize around 4 million, with the National Association of Realtors forecasting 4.8 million for the year. Meanwhile, mortgage rates, which dipped under a 6 percent national average on Feb. 2 after more than doubling since mid-2021 to almost 7.4 percent, have jumped back to 6.75 percent, driven by a scorching January jobs report.

No bust, but a standoff between buyers and sellers

Instead of a price bust a la the one after the mid-2000s housing bubble, what’s developing is a standoff, says Logan Mohtashami, lead analyst for HousingWire in Irvine, Calif. On the one hand are buyers who would like homes to be as affordable as in 2019. But a big share of them either have to move or can afford to despite higher prices and rates. On the other are sellers, under no pressure to move since they have cheap mortgages and plenty of equity for now. So far, sellers are hanging tough in most cities. Even small increases in demand can keep prices firm, or move them higher, because inventory is so tight, Mohtashami said.

The recipe for 2023’s housing market is shaping up as prices that are roughly stable nationally, but with ongoing drops in some regional markets, interest rates that decline but not hugely, and buyers’ incomes that rise. Experts think they will combine to make affordability improve, maybe to near-normal historical levels, but still fall well short of where home buyers stood when mortgage rates were 3 percent or even lower.

“Households have two incomes, and you have to earn about $100,000 to buy a house,” Mohtashami said. “There are lots of dual-income couples that can do that. It gives you more buying power than people know about.” 

No return of 2008, or 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} mortgage rate

The biggest reason why housing prices aren’t plunging like they did after 2008? Because the market isn’t being flooded with homes that drive down prices, as happened then.

Capital-rich banks aren’t under pressure as they were then, with foreclosure rates less than a tenth of those from the housing bust. Neither are households, with debt payment burdens near historic lows and few homeowners owing more on their mortgage than the house is worth. Serious delinquency rates, which skyrocketed after 2006 and led to 6 million foreclosures, have fallen by nearly half in the last year, to less than 0.7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of mortgages, according to Fannie Mae. Unemployment is the lowest in 54 years, letting homeowners either trade up or hang on to their current homes easily – and if they are among the 85 percent of owners whose mortgages carry interest rates below 5 percent, many will stay put rather than buy a more expensive house with a costlier loan. 

All that means the supply of homes for sale is likely to stay tight, which limits price declines.
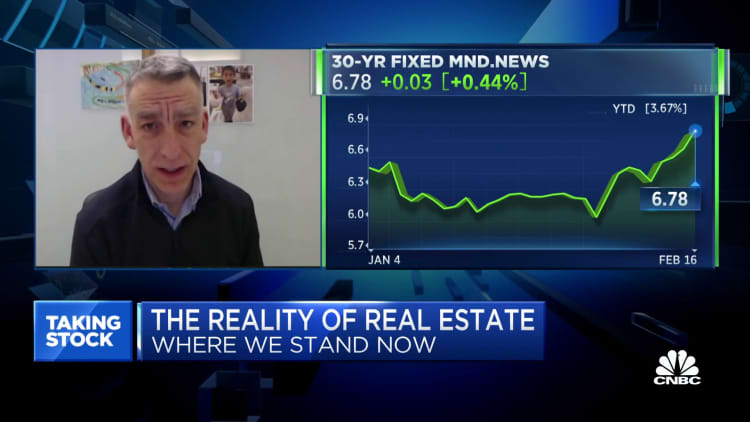
We're still at half the housing inventory of 2016 through 2019, says Redfin's Glenn Kelman

Affordability is bad now, after rate hikes and Covid-driven price increases, but it has been worse. And we’ve all been spoiled by recent history: After the financial crisis, housing affordability nationally literally doubled as interest rates collapsed and prices fell, reaching all-time highs. It had retained most of those gains up until the Covid price surge, even as home values recovered.

“Rates will be dropping in the second quarter, but we don’t see a drastic drop that should make people wait,” said Nadia Evangelou, director of real estate research at the NAR. She predicted that 30-year mortgages will decline to around 5.75 percent. “Buyers realize 3 percent rates are not coming back.”

Housing affordability is stretched

The NAR’s closely-watched affordability index, which considers prices, rates and buyers’ incomes, is much lower than in 2019, but is still in line with the late 1980s and early 1990s. At current levels, the Housing Affordability Index says the median buyer can afford the median U.S. home — but barely. In 2020, the median buyer could afford the median home with a 70 percent cushion, which was the product of 3{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} loans, Covid-driven income support and the residual impact of big home price drops between 2006 and 2011. Since 1980, the average is that median home buyers have about 20{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} more income than they need for the median home, Evangelou said.

So why is anyone buying homes that are suddenly less affordable?

For Maggie Neuder, a client of Fisher’s in Chicago, the answer boiled down to wanting a new place and being able to afford one. Having seen 6 percent interest rates when she bought her first place in 2007, she’s not daunted by today’s rates, she said. The 41-year old finance executive bought a bigger home than she needed during Covid to ride out quarantines, and now wants a smaller place in the city’s Lincoln Park neighborhood, so she executed a flip.

To calm her buyer’s interest rate fears, she is giving a closing credit big enough to buy down the mortgage rate on the buyer’s loan for the first two years, by two percentage points in year one and one percentage point in year two – a move many builders are also using to sell new homes. To make back the money, she extracted a similar concession from the seller of the home she expects to buy in April.

“People look at refinancing like it’s a bad thing,” she said, figuring she can likely lower her payment within a couple of years. “I don’t think we’re going back to the sub-threes, but somewhere in the fours. Even if rates don’t fall below 6, I’m in a comfortable place with my mortgage.” 
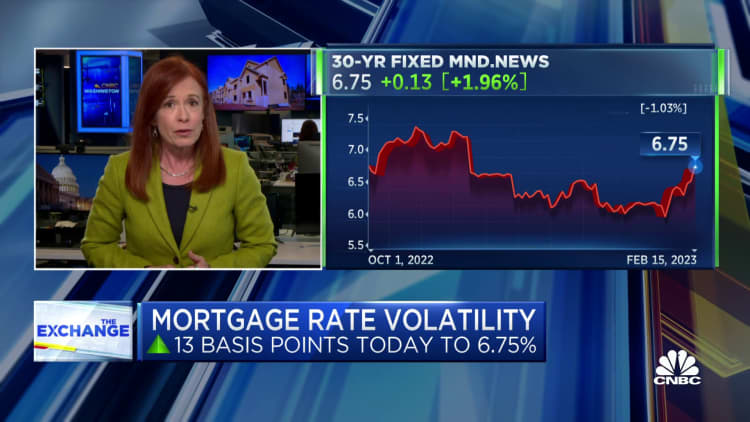
Mortgage rates move higher, along with homebuilder sentiment

Fisher says his recent buyers fall into three camps. At either end are first-time buyers who have never had a 3 percent loan, and older buyers who are paying cash. Neither is much bothered by rates around 6 percent, he said. In the middle are move-up buyers who initially worried about rates more. But they are making work-arounds like Neuder’s to get what they want, Fisher said. These buyers likely drove the increase in applications for new mortgages that happened as rates fell earlier this winter.

“People have wrapped their heads around where interest rates are, and they have adapted,” Fisher said. 

Indeed, combining the wage gains of the last few years with the deflation that has begun to show in market-based housing data in the last six months, and the most flagrant cases of distorted regional markets have begun to correct already. Another boost comes from solid rates of new household formation, said Daryl Fairweather, chief economist at Redfin.

Where home prices are now

The average house price is down 6 percent since the June peak, according to the S&P Case-Shiller index of prices in 20 major metro areas, and 3.5{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} in the index for the whole country. 

Recently-hot markets have taken bigger hits, as expected. In San Francisco, the Case-Shiller index is down 12 percent, in Phoenix 8 percent. In Sacramento, home prices have given back almost half of their Covid-era gains, said Ryan Lundquist, a local appraiser who blogs about the market in California’s capital. In metro Tampa, where prices rose 69 percent during Covid, according to Case-Shiller, prices are down only 3 percent.

Add in wage growth — wages rose about 5 percent last year, according to data from Zillow — and the effective price of housing has come down sharply in some places, while remaining well above pre-Covid levels, Zillow chief economist Skylar Olsen said. 

“Even with values down a bit since August, if you bought the average house in February 2020 you have annual gains of 11 percent,” Olsen said.

Wage growth is one reason why even in some recently-hot markets, buyers are still out there, said St. Petersburg, Fla. broker Jeffrey Clarke. Indeed, he recently talked one client with a home in another city out of selling their place in St. Petersburg, convincing them that the crash they feared was not coming.

By the NAR’s numbers, affordability is now poor in metro Tampa, with the median buyer only earning 80 percent of what’s needed to buy the median home. But Tampa is close enough to equilibrium that Clarke doesn’t see anything coming like 2008-2011, when the average Tampa house lost half of its value.

“With nothing falling yet, no one is freaking out,” he said. 

The math on mortgage rates and wage growth

The big flaw in the thesis that only minor price drops are coming is that so many large regional markets like Tampa remain out of line with local incomes, and many of them were in much better balance as recently as two years ago. Another is that San Francisco, Phoenix and Las Vegas all saw more than a 1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} price drop in January alone, according to Zillow, making forecasts for relatively-stable prices look shakier.

Much of Florida and Texas, and markets like Asheville N.C. and Denver, had relatively-affordable housing until 2020 but median homes are now 20 percent to 30 percent too expensive for median local incomes, according to NAR data released in October. In much of California, NAR affordability indexes are at 50 or below, indicating homes cost twice as much as local incomes can support. But much of California has always been less affordable.

Nationally, to get back to the average affordability since 1980, meaning median houses are about 20 percent cheaper than the median family can afford, mortgage rates would have to come down to about 4.6 percent, while wages would need to rise 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} and prices stay stable, the NAR’s Evangelou said. Wage growth has recently cooled a little, but remains above 4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} — in the recent nonfarm payrolls report, wages were up 4.4{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from a year ago, though a bit below the December gain of 4.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}.

Mortgage rates remain volatile, and the market hopes that began 2023 — that the Fed would be cutting its benchmark interest rates before year-end — have recently dimmed as the labor market and consumer remain too strong to provide confidence that the current rates hikes are doing enough to slow inflation. After falling for five weeks, the average contract interest rate for 30-year fixed-rate mortgages increased to 6.39{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from 6.18{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} last week, and was as high as 6.8{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} on Friday. The rate was 4.05{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} one year ago.

How fast could affordability get better? On a $300,000 loan, a drop in fixed rates to 4.5 percent from today’s 6.75 percent, with no change in prices, would change the monthly payment by about $425 on a 30-year loan, about a 23 percent drop. Going to 6 percent cuts a payment by about $150, or 8 percent. A 5 percent income gain this year for the median buyer would add about another $400 a month.

“If rates come down to 5 percent, it gets radically better very fast,” Olsen said.

In a place like Tampa where prices grew rapidly during Covid, the affordability fix will probably blend near-stagnant prices for a year or two, pay raises and lower interest rates, Clarke said. But hotter markets like Tampa may need more price cuts to get affordability all the way back to historical averages, Evangelou said.

The market’s standstill is likely to last for months, at least, because its main underpinnings aren’t going anywhere. Sellers will continue to have the advantage of being equity-rich and sitting on a low interest rate from 2021 or before, Mohtashami says. Some buyers will remain priced out of the market, or able to afford less house than they want. And some will use work-arounds like mortgage buydowns or parental support to buy houses until affordability recovers. Sellers of new homes will do buydowns and have been using incentives since last summer to limit cuts to list prices. 

“It has become kind of the norm,” Neuder said. 

In some markets, affordability is likely to remain a problem for long enough that policy solutions will be needed, Olsen said. She mentioned solutions like building more dense housing, or letting more homeowners add additional dwelling units such as basement or attic apartments to let families share costs. 

In most places, the likely outcome is affordability that falls somewhere between today’s market, where many prospective buyers are stretched and demand is light, and the buyer’s delight that prevailed for close to a decade. The path to that is rising wages, declining inflation that lets interest rates fall, and home prices that give back a still-to-be-determined chunk of the 2021-22 gains – a share that so far is small in most places.

“I want it to be flat the next two years,” said Clarke, the Florida broker. “You can’t rise 20 percent a year for a decade. You end up with a $5 million dollar two-bedroom, two-bath.”
‘A real estate bottom?’ More homebuyers jump back in as the year kicks off

‘A real estate bottom?’ More homebuyers jump back in as the year kicks off

Authentic estate agents verify what housing details is starting to exhibit: Much more homebuyers are rising from their self-imposed hibernation.

The volume of mortgage loan apps for dwelling buys rose 25{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} week over week, the House loan Bankers Affiliation (MBA) survey for the week ending Jan. 13 identified. Housing sentiment ticked bigger at the finish of last year, for each Fannie Mae. And household builders are reporting an raise in consumer website traffic in January, the first uptick since December 2021, according to an market survey.

These buyers are hoping to enjoy the benefits from a a lot more favorable market place, bagging vendor incentives along with a marginally lessen mortgage loan price, ahead of the spring-shopping for season draws in a lot more level of competition.

“I experienced one particular of my consumers at Meta and yet another from Microsoft who have been active up until September of previous yr access out to me past weekend,” Jeff Reynolds, a broker at Compass and founder of UrbanCondoSpaces.com, explained to Yahoo Finance. “They had wanted to see what the current market would do, and because it looks to have stabilized and costs are down, they are hoping to get a move ahead of what would inevitably be a true estate bottom.”

Home sellers are more likely to offer buyers concessions, a Redfin report found. At least 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homes sold during the fourth quarter of 2022 included an incentive. (Credit: Getty Creative).

Dwelling sellers are extra likely to offer potential buyers concessions, a Redfin report observed. At minimum 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of households sold through the fourth quarter of 2022 provided an incentive. (Credit history: Getty Artistic).

‘Bringing people back again in’

The dip in home loan fees in recent weeks has taken some of the edge off of the document-setting ascent costs clocked in previous year. Past 7 days, the ordinary rate on the 30-year fastened mortgage — the most generally applied property personal loan for a invest in — settled closer to 6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} than 7{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9}, fitting into extra buyers’ budgets.

“Interest costs are greater for initially-time customers. I consider naturally it’s just bringing folks back again in,” John Downs, senior vice president at Vellum Property finance loan, instructed Yahoo Finance.

At the similar time, dwelling selling prices have also softened, with the median record rate falling to $400,000 in December, in accordance to Redfin, down 11.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} from June’s peak of $449,000.

“The vast majority of exercise is from new purchasers,” Reynolds said. “In our microclimate in downtown Seattle, the the vast majority of action has strike definitely reasonably priced cost details. That’s pushed primarily by that millennial buyer, that younger consumer, or initial-time purchaser eventually taking benefit of market place disorders — probably for the to start with time.”

‘Picking for deals’

The buyers who are coming back again are also finding gutsy, knowing that the sellers who continue being in the sector are open to negotiation.

“In 2022, prospective buyers set the market by bidding up, which led to escalating price ranges and primarily possessing to spend to acquire,” Downs reported. “Now, rather of waiting for listing rates to drop, customers submit features with major bargains and make the vendor make a selection. And that seems to be performing.”

At the very least 16.6{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of homes bought in December experienced a selling price slice, Real estate agent.com info found, an increase from 7.1{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} a 12 months ago. Even home builders are squishy on cost.

A person of Monte Miner’s shoppers obtained $15,000 off a recently created household initially priced at $409,000, in accordance to the serious estate agent at Ironwood Fantastic Homes in Arizona.

Rick Nazarro of Colonial Manor Realty talks with a pair of interested buyers in the driveway as a couple waits to enter a property he is trying to sell during an open house in Revere, MA. (Credit: Blake Nissen for The Boston Globe via Getty Images)

Rick Nazarro of Colonial Manor Realty talks with a pair of interested customers in the driveway as a few waits to enter a residence he is hoping to provide in the course of an open up residence in Revere, MA. (Credit: Blake Nissen for The Boston World by using Getty Pictures)

“Buyers are coming back again, but they are choosing for offers. Let’s say a household is listed for $400,000 — a whole lot of the provides coming in are below that range,” Miner mentioned. “Some sellers’ pricing anticipations are trapped in the earlier, like three months in the past. It’s various now.”

Not only are some people receiving large cost reductions, they are also snagging vendor concessions to further ease the stress of nevertheless-significant residence prices.

For instance, at least 35{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders reduced their dwelling rates in December, information from the Countrywide Affiliation of Homebuilders identified. A further 62{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of builders continued to use incentives to catch the attention of customers, like charge invest in-downs and shelling out factors. According to Redfin, about 42{d4d1dfc03659490934346f23c59135b993ced5bc8cc26281e129c43fe68630c9} of properties marketed in the closing three months of 2022 incorporated a vendor concession, these types of as funds for repairs or closing expenditures.

“If you don’t have not enough dollars for closing expenses,” Downs said, “sellers are supplying to fork out it for you,”

A sign is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit: Mario Tama/Getty Images)

A indication is posted in front of new condominiums for sale on December 19, 2022 in Los Angeles, California. (Credit: Mario Tama/Getty Images)

Timing is anything

With rates finally inching down, now could be an opportune time to invest in a property prior to the spring season is in entire swing, Downs explained. But you need to be well prepared. Having a pre-qualification completely ready, setting a spending budget, and conversing to a authentic estate specialist can raise your chances of negotiating a far better deal at closing.

According to Miner, stepping into the marketplace just before it will get flooded by competitiveness could be a excellent go if you want to negotiate terms.

“From what I’m looking at,” Miner explained, “I sense like the bottom is right here.”

Gabriella is a personalized finance reporter at Yahoo Finance. Stick to her on Twitter @__gabriellacruz.

Click right here for the newest financial news and economic indicators to assistance you in your investing decisions

Examine the most current economical and company news from Yahoo Finance

Download the Yahoo Finance application for Apple or Android

Comply with Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, and YouTube.

Brokerage Reminder: Know the bottom line for investment properties

Brokerage Reminder: Know the bottom line for investment properties

Buyers all want to know the similar point: “Is this assets heading to spend off?”

Any agent can present an authoritative and information-driven response applying two uncomplicated formulation:

    &#13
  • the capitalization price (cap price) and
  • &#13
  • the web earnings multiplier (NIM).
  • &#13

Related posting:

Capitalization costs, spelled out

The cap charge is pure earnings — the amount of money of revenue remaining after all of the owner’s house costs are deducted from the gross cash flow generated by the home — expressed as a rate, or proportion. Most authentic estate investors will have a certain cap amount in head when searching for income-making property. This charge may perhaps be real looking or not, based on the current sector. [See RPI e-book Income Property Brokerage Chapter 4]&#13 &#13 &#13 &#13

To uncover a property’s cap fee, a buyer’s agent desires the following knowledge:

    &#13
  • gross functioning profits (GOI) from the property (the hire amounts compensated by the building’s existing tenants and the scheduled lease amounts for vacant models)
  • &#13
  • home working expenses (taxes, routine maintenance and repairs expense, etc.) and
  • &#13
  • the buy selling price for the property.
  • &#13

Possessing attained the above facts, the agent calculates the net functioning profits (NOI) of the home by subtracting all assets expenses from the GOI:

GOI – working bills = NOI

Up coming, the agent establishes the cap fee by dividing the NOI by the invest in selling price:

NOI ÷ purchase selling price = cap amount

Once the agent has located the cap rate and introduced it to their customer, the customer can choose if it is superior enough and irrespective of whether the price of purchasing the assets will meeting their aims in possessing an earnings creating house. If the cap fee from the listing price would seem as well lower, the buyer’s agent can use the inverse of the cap amount system to locate a order cost much more constant with their buyer’s preferred cap price.

First, come across the NIM — this is the reciprocal of the cap level. Since a cap amount is expressed as a percentage, or fraction of 100, this can be accomplished by dividing 1 by the cap rate:

1 ÷ cap amount = NIM

Upcoming, come across the buyer’s wanted purchase rate by multiplying the NOI by the NIM:

NOI × NIM = buy value

What the consumer wishes the profit created from the assets to be and what can realistically be anticipated  may be two various items. However, an agent who understands how to locate a property’s cap fee and NIM can reduce via a jungle of costs and variables to exhibit their buyer an expense property’s bottom line – in true numbers – in mere minutes.

Keep in mind: expertise is the crucial to achievements in today’s actual estate sector!

&#13

&#13

Similar Video: A few Appraisal Methods: Income Approach

Simply click below for far more information and facts on this matter.

Other consumer issues

The cap level does not reflect each and every component an trader customer needs to contemplate when location the highest cost they will pay back. Software of a cap charge formula by itself does not account for:

    &#13
  • required renovation and rehabilitation of the residence (which requires additional cash over and above the obtain value to get rid of the obsolescence)
  • &#13
  • the price tag of employing a assets manager and of other products and services necessary to operate the property (when not integrated as an running price)
  • &#13
  • a house loan with an interest rate exceeding the blended charge of inflation and genuine return on financial investment utilised to established the cap amount and
  • &#13
  • a ultimate/balloon payment in a home finance loan.
  • &#13

Therefore, a consumer getting an earnings-producing assets subject matter to an current home loan or funded by a new property finance loan demands to set the cap level higher than the interest amount on the mortgage to justify the risk of reduction. This distribute addresses objects these kinds of as restoration of the expenditure or reserves for alternative, and threats offered by adjustments in demographic (tenant) calls for.

Editor’s note — Any adjustable level property finance loan (ARM) or owing-day financing provides a especially troublesome danger of reduction because of exclusively to potential will increase in interest charges — which of class minimize house values.

Even further, the main resource of resources for the owner’s payment of a buy-help property finance loan is the property’s NOI. The NOI remaining following deducting the desire paid out on the home finance loan signifies the earnings attributable to the buyer’s cash equity financial commitment.

Thus, this remaining part of NOI requires to create a substantially higher share generate on the buyer’s leveraged equity expenditure (hard cash) to offset the threat of the buyer’s income remaining subordinate to house loan funding.

Pitfalls inherent in the residence: the principal group of hazard

As is the circumstance with any investment decision, acquiring earnings-manufacturing home contains an quantity of possibility that some or all the funds (hard cash and borrowed home loan funds) will be shed.

Hence, the prudent trader asks: how do you contain this hazard (called a risk high quality) in the cap level, in addition to the true level of return and the inflation amount?

There are two kinds of chance to take into account when deciding the risk high quality amount to be integrated in cap premiums:

    &#13
  • challenges inherent in the residence (the key classification of possibility) and
  • &#13
  • hazards owing to human and other exterior activity (the secondary class of risk).
  • &#13

The principal class of danger considers the physical advancements on the residence, such as their deterioration and declining usefulness as a result of aging, identified as actual physical obsolescence.

Actual physical obsolescence is also labeled depreciation for tax accounting needs. Depreciation supplies for a return of capital (funds recovery) more than the remaining economic daily life of the advancements ahead of the land worth exceeds the value of the property’s money, identified as financial obsolescence.

Pitfalls because of to human and exterior exercise: the secondary classification of chance

The secondary category of risk contains the “human” and exterior influences on the property’s value. These hazards consist of:

    &#13
  • the creditworthiness and stage of work range in recent tenants, an employer situation
  • &#13
  • the coming expiration of latest leases, which are ideally staggered, a management issue [See RPI Form 352-1]
  • &#13
  • opposition from nearby, identical properties (present and long term development), a sector problem
  • &#13
  • a background of crime fully commited on or close to the property, a safety problem [See RPI Form 321]
  • &#13
  • extended-term money and prosperity changes in the place bordering the assets, a demographic challenge and
  • &#13
  • variations in zoning, retrofitting, habitability and fire ordinances or restrictions, a political issue. [See RPI Form 185]
  • &#13

Want to understand more about this matter? Simply click an image underneath to down load the RPI book cited in this article.

Brokerage Reminder: Know the bottom line for investment properties


This short article was originally posted [August, 2012 of Know the bottom line for investment properties], and has been current.